Small Cap Value Report (Mon 19 Aug 2024) - IGP, PLUS, BVC

Good morning from Paul & Graham!
Very quiet for news today, so we'll leave it there.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
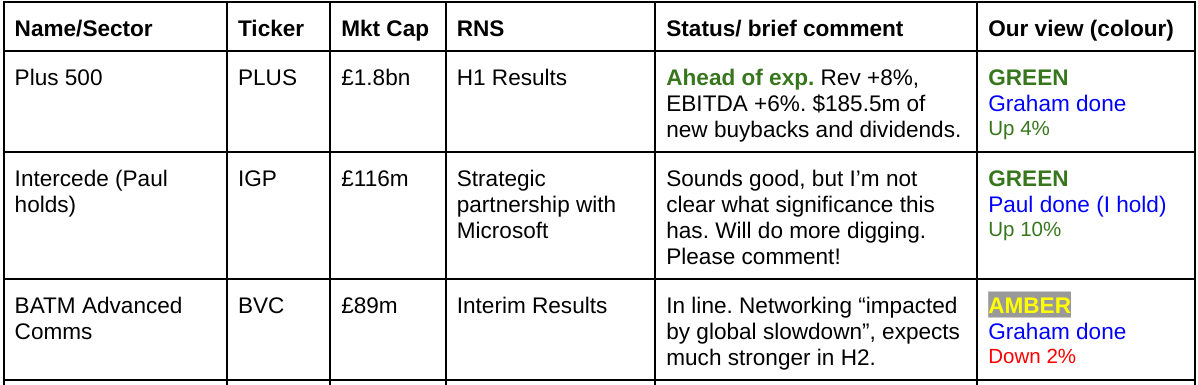
Intercede (LON:IGP) (Paul holds) - up 14% to 197p (£116m) - Strategic partnership with Microsoft - Paul - GREEN
Today's partnership with Microsoft sounds impressive, but doesn't alter the broker forecasts. Hence at this stage I don't know what the financial significance or structure of this deal is likely to be. I've reached out to the company asking for more colour, so at this stage all we can do is discuss amongst ourselves in the comments below - sector experts please help guide us!
Plus500 (LON:PLUS) - up 5% to £25.52 (£1.93 billion / $2.5 billion) - Interim Results - Graham - GREEN
This CFD provider issues an ahead of expectations update. Perhaps it could have already done this in July (at the H1 trading trading) but there is no harm in delaying the good news for a month. I’m staying positive on this one. There are still some important risk factors to be aware of - in particular around customer churn and profits on customer losses - but the track record of excellent profitability stretches over several years now, and I think it needs to be respected.
Batm Advanced Communications (LON:BVC) - down 4% to 19.75p (£86m / $111m) - Interim Results - Graham - AMBER
BATM says it is on track to deliver full-year results in line with expectations, but this is predicated on a recovery in the Networking division (whose performance collapsed in H1) and a large H2 weighting for group revenues. This is a stock I would treat with caution as it seems much more complex than other small companies we analyse and its market cap already prices in a step-change in profitability.
Paul’s Section:
Intercede (LON:IGP) (Paul holds)
Uup 14% to 197p (£116m) - Strategic partnership with Microsoft - Paul - GREEN
Intercede and Microsoft Join Forces to Streamline FIDO Passkey Management for the Enterprise
Intercede, the leading cybersecurity software company specialising in digital identities and strong authentication, announces a strategic partnership between Microsoft and the Company that will bring cutting-edge FIDO Passkey management to the Enterprise.
This sounds exciting, but I’m left scratching my head after reading this announcement several times. It doesn’t give any indication of the likely financial benefit from this “strategic partnership”.
Broker update - house broker Cavendish helps us out with a brief update today, with the key bit saying -
“ While there are no changes to forecasts, the partnership reiterates the world-class quality and reach of Intercede’s technology”
What does this deal actually entail? It’s not clear to me, but this bit below seems to suggest IGP’s software is somehow to be used in conjunction with Microsoft’s Entra ID cloud-based identity & access software -
“This collaboration combines Intercede's expertise in Credential Management Systems with Microsoft Entra ID to allow administrators to create and register FIDO Passkeys on behalf of users on devices such as the Yubikey family of devices or smart phones. This development allows FIDO Passkeys to be managed in a similar way to PKI based devices through MyID CMS and then passed to Microsoft Entra ID for use during user authentication. Importantly, this enables organisations to comply with US federal government security legislation including FIPS 201/SP 800-63 at the highest levels of assurance.”
That’s quite intriguing. Perhaps naively, I would have expected a software giant like Microsoft just to write its own code, and not have any need to involve Intercede.
What are FIDO passkeys? Details are on an industry website here. Briefly, it’s a secure method of logging into online services. An example would be when you’ve registered with internet banking, and subsequently login to your banking app using your fingerprint on your smartphone. It’s much more secure than ordinary passwords.
Quote from Microsoft in today’s RNS - it seems that Intercede is one of several vendors, so this isn’t an exclusive deal -
"Microsoft is committed to realising the full promise of passkeys to help accelerate adoption within enterprise organisations. Our new FIDO2 provisioning APIs, and our collaboration with leading vendors like Intercede, represent a big step forward in helping organisations create fast, easy and secure authentication journeys from day one," said Natee Pretikul, Principal Product Management Lead at Microsoft Security.”
Quote from Intercede -
“Until now, the lack of ability to integrate credential management systems with Entra ID for passkeys has been a barrier to adoption. I am delighted that by working with Microsoft this barrier has now been removed and organisations can benefit from stronger, managed authentication." added Allen Storey, CPO at Intercede.
What's Next: We're moving quickly to bring this partnership to life. A first version of the implementation will be ready for demonstration within the next two weeks.”
Paul’s opinion - with no indication of financial terms of this deal, I’m completely in the dark! Whilst obviously recognising that this sounds a very interesting development. Let’s see if we can draw out any industry experts within our community here to explain what this deal might mean, and help us understand its significance.
I’ve already reached out to Intercede this morning, asking for more colour. I’ll see if they want to do another CEO interview, where I can ask our questions, to hopefully better understand today’s deal.
I remain a bull on IGP shares, which is why I hold personally. It’s been a successful multi-year turnaround, and the company is now well-financed, following a bumper year boosted by a large one-off contract win in FY 3/2024. Now it has established successful routes to market through third party IT groups, and has an astonishing existing client list, I believe it has very considerable growth potential, and this isn’t blue sky - it’s an established (over 20 years) expert in an increasingly vital niche. It’s difficult to put numbers on it, so I tend not to focus very much on broker forecasts or conventional valuation metrics. My view is that there’s a genuine opportunity here, but I don’t know how large it is.
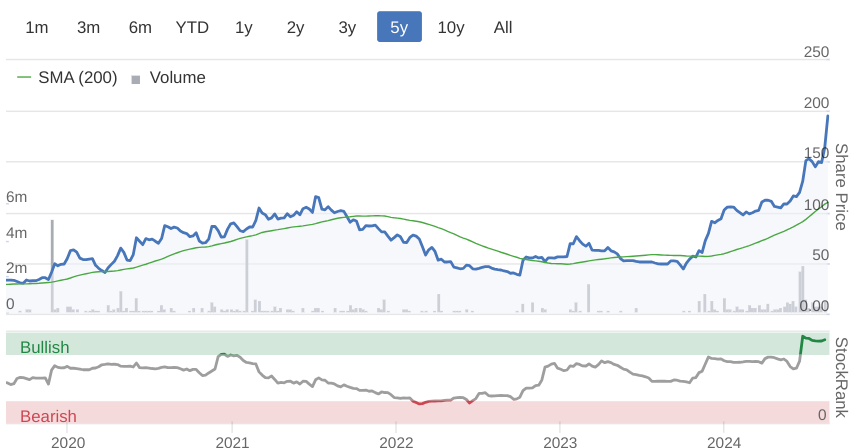
Shares now going exponential is both exciting and scary! Hence I'm expecting considerable volatility -
Graham’s Section:
Plus500 (LON:PLUS)
Up 5% to £25.52 (£1.93 billion / $2.5 billion) - Graham - GREEN
We have an ahead of expectations update from Plus500:
FY 2024 results expected to be ahead of current market expectations
Significant additional shareholder returns of $185.5m announced today
Strong financial and operational results for H1 2024
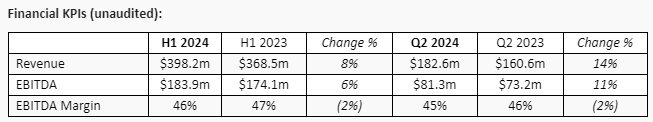
Existing full-year expectations for FY24, according to the company, were for revenue of $697.8m and EBITDA of $314.6m.
But the company has already achieved revenue of nearly $400m, and EBITDA of $180m+, in the first six months of the year:
Note that we covered this stock in July at the time of the H1 trading update. The market seemed to be disappointed with the “in line” outlook published that day, but I observed that PLUS still had a great chance of beating full-year expectations for FY 2024. So today’s “ahead of expectations” update does not come as a huge surprise.
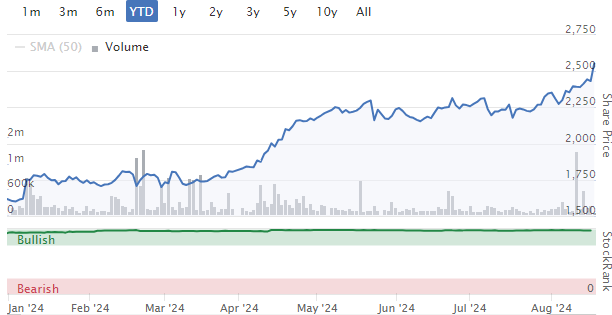
Increasingly good news has been priced in:
Cash exceeds $1 billion for the first time.
Buybacks and dividends of $185.5m are announced, comprising share buybacks of $110m and dividends of $75.5m. This brings total buybacks and dividends year-to-date up to $360.5m.
Valuation multiples for PLUS tend to be cheap, making buybacks attractive:
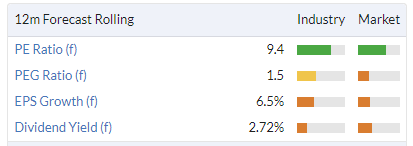
The PER shown above is before making any adjustment for the company’s cash balance; deduct $1 billion from the market cap to adjust for this and the PER is reduced by about 40%, i.e. to less than 6x.
That would be an optimistic way of valuing the company, as the company’s cash balance is partly needed to insure PLUS against the risk of customers trading profitably as a collective. But still, PLUS evidently does not need $1 billion+ and some large portion of it is surplus.
Operational KPIs
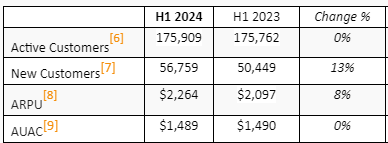
Customer churn seems worse than before as nearly 57,000 customers joined in H1, vs 50,000 in H1 last year, and yet there is no increase in active customers. Active customers are unchanged year-on-year at c. 176,000.
The driver of revenue growth is therefore the 8% increase in average revenue per user, not growth in the user base. Combine that with zero growth in the cost of customer acquisition, and PLUS had the foundations for a very profitable H1.
Outlook is ahead of expectations:
Plus500 remains strategically well positioned to capitalise on both short-term market conditions and the medium to long-term growth trends in its end markets. In the short-term, its increasingly diversified offering and intuitive trading platforms allow customers to access a wide variety of products, services and features across multiple markets.
These initiatives are designed to position the Group for key growth opportunities, including new products, services and markets, the expansion of its OTC, futures and share dealing offerings and the deepening of its customer engagement and retention initiatives…
Over the medium to long-term, the opportunity to drive growth, scale and compounding value creation is significant. Plus500 has strong fundamentals underpinning its business and is attracting and retaining more customers while putting greater focus on customer longevity…
I’ve emphasised some parts of the outlook statement where I think PLUS is acknowledging that customer churn could be improved. Most of the bear arguments against this stock have been defeated by the passage of time but I think customer churn remains a point where the company could improve and where I think that even shareholders of the company might agree that it has a weakness.
Perhaps this will never change, but it is a fundamental challenge for PLUS that it needs to replace a huge portion of its active customer base every 12 months. This means that it is always vulnerable to customer acquisition costs, which are largely beyond its control.
Graham’s view
Despite the cautious tone that I’ve taken to PLUS over the years, I turned positive on it as its ability to generate cash has become undeniable, as its successful track record has lengthened, and as its product/geographic diversification has improved.
One of the points which worried me greatly before was the company’s hedging practices. I still think it’s worth worrying about them, but at least we have several years’ worth of data from the company now around how much of their revenue has been generated from customer losses as opposed to spreads and commissions.
Today, for example, we learned that customer trading performance (i.e. customer losses or wins) contributed $39.7m of revenue in H1. This is a little less than last year and is about 10% of total revenue. I still think it’s important to know that this is a source of risk and could be very volatile, but I no longer think that it defeats the bullish arguments in favour of PLUS.
So I’m happy to retain my positive stance on this one.
Batm Advanced Communications (LON:BVC)
Down 4% to 19.75p (£86m / $111m) - Interim Results - Graham - AMBER
We don’t cover this one too often. The last time was in August 2023
Profits tend to be unpredictable and usually seem too low compared to the market cap:
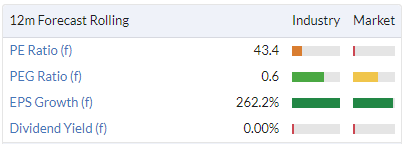
Here are the key points from today’s interim results, with the company on track to deliver full-year results in line with expectations.:
H1 revenue approximately unchanged at $60m
Gross margin falls and gross profit reduces by 11% to $18.7m.
Operating profit and EBITDA both increase, regardless of whether or not you include the company’s adjustments. Adj. operating up slightly to $2.3m.
Business review
This is more difficult to analyse than most stocks we cover because a) it’s based in Israel, and b) it has multiple divisions/activities.
These divisions are Cyber (hardware and software for government agencies), Networking (connectivity), Diagnostics (in vitro reagents and instruments) and “Secondary Activities” that generate nearly half of its revenues.
Few of the divisions stand out as being particularly profitable at this stage of their evolution, except for the Cyber division that generated $2.6m of EBITDA from $8.3m of revenue in H1.
The Networking division suffered a revenue collapse of nearly 50% (down to $6m) and was unprofitable in H1.
Outlook suggests that H2 will be much better in the Networking division, and mentions the potential for M&A:
BATM remains on track to deliver strong growth for FY 2024, in line with market expectations. In the Networking division, the Group expects performance in the second half to be much stronger than the first, with new orders expected for its carrier ethernet and Edgility solutions. The Cyber division continues to perform well as it delivers its large backlog as well as new orders. In the Diagnostics division, further growth is being driven by the continued expansion of the customer base.
Looking further ahead, the Group is eagerly anticipating the launch of its cyber solution into commercial markets, which represents a substantial increase in the addressable market. The Board is also continuing to actively pursue M&A and disposal opportunities that will enable the Group to accelerate execution on its growth strategy in its core divisions. As a result, the Board continues to look to the future with confidence.
Balance sheet: net assets are an impressive $117m, including only $21m of goodwill. So the market cap (c. $111m) is only a small premium to tangible net assets ($96m).
Cash and short-term investments finished the period at $32.6m. As noted previously by Paul, however, there isn’t any sign of dividend payments. While BATM has been publicly listed for a long time, large cash balances at foreign LSE-listed companies can arguably be viewed as a red flag - if the cash is real, what is it doing?
Graham’s view
I’m inclined to leave this stock in the “too difficult” tray. So I’ll take a neutral stance on it, as I wouldn’t have any conviction in a bearish or a bullish stance on it.
In the short-term (six months), I would worry that the expected H2 recovery in Networking may take longer to materialise than expected. A large H2 weighting is often the prelude to a profit warning, and the full-year group revenue forecast is $143m (vs. only $60m in H1).
Looking further ahead, there is clearly the potential for BATM to start converting incremental revenues into real profits, and for the large cash balance to provide optionality in the form of M&A or other opportunities.
However, I expect that a great deal of research would be needed to gain conviction in the bull case.
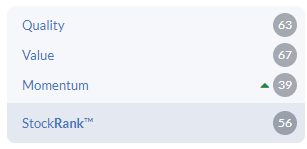
Stockopedia’s algorithms are neutral, too:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Tracsis (LON:TRCS) Unusually large volumes in Tracsis today, don't know if the seller has finished yet but it's very tempting at £6 given where the share price has spent the last few years....and if you believe the last miss was more of a speed bump as oppose to a 'derailment' of the business.
Completely off topic...... Sky News are reporting that the UK Yacht that sank of Sicily this morning belonged to Mike Lynch of Autonomy & Darktrace fame.
It's reporting that his wife was rescued and that he is one of 6 missing
Terrible tragedy. The US government put Mike Lynch through hell but he defended his case vigorously and won. One of UK's best technology entrepreneurs.
Wish I could give you 10 thumbs up - just thinking the same.
As he said - I only won because I was wealthy - he should never have been extradited - it was obvious HP had made a bad decision but got the US government to prosecute him as a criminal. The CFO pleaded guilty because he wasn't wealthy. Tells you all you need to know about the US legal system.
Hope he's found alive, although unlikely, after going through that he should have been allowed many happy twilight years.
It has just been announced that Mike Lynch's co-defendant in the US trial, Stephen Chamberlain, was killed in a car accident whilst out jogging on Saturday. Barely believable!
I only just noticed today that the CFO of Pennant International (LON:PEN) is scarpering (announced last Wednesday). Harwood / Rockwood appear to be a 10% holder so perhaps he left before getting pushed to be replaced with a Harwood pick maybe? I've been listening to some of the excellent interviews lately with Chris and Nick Mills as well as Richard Staveley (thanks to Paul Hill / Vox for these really useful interviews / podcasts) but I don't recall them mentioning Pennant at all although 10% of Pennant wouldn't make for a sizeable portion of any of their funds so perhaps not surprising. One to watch maybe for the announcement of the new CFO pick.
Pennant
Dont think anything untoward with CFO going .
I asked CEO and hes just moving on naturally I think .
New chairman is a Rockwood guy for sure .
I think Rockwood would like to see some corporate activity which I think was a Reverse takeover of a larger company.
There was a failed corporate activity charge of 300k in last half year but I doubt this is completely off the table .
Issue at pennant is the super long runway for their customers so always tendering for work .
The plus is its a hot sector .
Dowgate also hold .
Some smart investors on the register .
Windward (LON:WNWD) 5.73% stake reported sold down to 0% by Maritime Invest Scandinavia AB.
SD,
There must have been a matched buyer as it didn’t adversely affect the SP?
Graham.
Share price seemed supressed for a while and last trading update was decent imo.So i'm guessing they were sold in the market.They sold down from circa 7% earlier in July as well.Good growth and product traction both in government lumpier contracts and growing commercial, high margin software business.Right sector commercially especially with the houthi attacks highlighting the value of the product.Could be a Beeks Financial Cloud (LON:BKS) for the sailors?!Right team, right time, right place.I half wondered why the sp was drifting downwards.. but then again i'm not a great sharepicker admittedly.
Big volume Friday with HY results tomorrow. Pretty exciting stuff.
Anyone holding these?
Presentation and results tomorrow at 09:00 through LSE. Register through notification in RNS news. Hopefully results will be good with today’s SP and volume increase!
Graham
Windward (LON:WNWD)
Another poster wrote a great write up on Windward (LON:WNWD) a few days agoon SCVR.They've also been mentioned in a couple of Paul Hill's interviews with fund managers too.
Plus500 (LON:PLUS)
It may be worth pointing out to the risk averse that PLUS500’s head office (etc.) is in Haifa, Israel, c. 20 miles from the Lebanese border. I have assumed from this page - https://careers.plus500.com/ that Haifa isn’t just an administrative office. The city of Haifa is a major port which has seen some action. https://www.reuters.com/world/... There are also significant offices in Tel Aviv.
I haven't done any research on Intercede (LON:IGP) but I guess there's no broker upgrade because this partnership doesn't mean they are getting more profits. However this will be another product to sell as there are many big organisations using Microsoft Azure as their main IT platform and they might be targeting those organisations to sell them their secure authentication products. So I believe this partnership is just opening the doors for more potential clients and earnings upgrades will come then
Zotefoams (LON:ZTF)
A pal just alerted me to an ad in this week's Grocer magazine for Combibloc's version of a recyclable board. Removes the aluminium layer, apparently. Called Terra Alu-free Full barrier. Snappy! Forest based polymers.
Swiss based SIG (not to be confused with our insulations materials crowd in Sheffield) own Combibloc and together with TetraPak from Sweden dominate the market for board drinks packaging currently. Guess it is no surprise to see them being active in defending their territory and makes the ReZorce link with Refresco much more valuable IMO.
Guess it is no surprise to see them being active in defending their territory and makes the ReZorce link with Refresco much more valuable IMO.
Doesn’t it highlight the level of far better funded competition that faces Zotefoams (LON:ZTF) ?
Zotefoams (LON:ZTF) The "Terra Alu-free Full barrier" is still 2 materials, that need separating , being paper board and plastic film before they can be recycled (they have removed the aluminium foil).
ReZorce is one material HDPE, so I believe recycling should be easier and cheaper.
Good discussion on Intercede (LON:IGP) this morning. I have two issues with the name. How do I reconcile its plodding medium term performance to a reasonable valuation? And bear in mind that I own a lot of US tech: PERs of 50x don’t scare me off as long as they are accompanied by a consistent record of strong revenue growth greater than 20% pa. And, if the tech has far wider-reaching applications, why haven’t Microsoft or its competitors just gone and bought it for what would be pennies down the back of the sofa? Nevertheless, I’m feeling a little FOMO here, but I mostly stay away from market caps under £100m, especially in tech, where they tend to be more blue sky than, say, a manufacturer of drains and gutters!
in tech, where they tend to be more blue sky than, say, a manufacturer of drains and gutters!
Drains and Gutters is more Brown Field perhaps!
Plus500. It is a mistake to look too much at the detail. Instead focus on the continuous large cash profits and the relentless share buy backs. Then check out the 11 year share price appreciation……
Plus500 (LON:PLUS) looking forward to Graham's take on today's results - in the meantime this snippet caught my eye
"Since the Company's IPO on the London Stock Exchange in 2013, Plus500 has distributed $2.3bn in shareholder returns, including those declared today, positioning it as the best performing company on the FTSE All-Share on a total return basis over that time frame"
Cash generated from those of us foolish enough to try trading on the Plus500 (LON:PLUS) platform (albeit briefly!). Essentially a gambling site where the house wins c. 80% of the time. Undoubtedly much better to own the shares. Sadly I sold my holding c. 10 years ago for a small profit so missed out on a lucrative multi bagger.
That's the popular perception, but customer trading losses make up a relatively small part of their revenues.
Well that depends on what you count as customer losses really Bouden54
Although I haven’t looked in a while my understanding is that Plus500 (LON:PLUS) sell lots of short dated CFDs which have a large spread and high funding cost. So someone taking out the CFD either needs to hold a very short term trading position (which many retail investors are poor at managing) or they need to roll often. In reality the roll costs are significant and contribute a lot to the overall losses generated by the customer but are not counted as customer losses by the company in the accounts.
It’s a sleight of hand in my view but allows the company to show income is commission based rather than customer trading losses though the economic effect on the customer is the same.
less sophisticated investors will take a while to switch on to that effect in their accounts which also means they stay around longer funding those charges.
I tried it a few years back and was staggered at how much they were taking from me over a month even for fairly small tester positions before the actual underlying price even moved. So I closed my account and bought the shares instead, though sold those ages ago too albeit with a decent profit.
Microsoft sells thru channels.
IGP -MyID® software and services are available through integrator and reseller partners worldwide.
A strategic partnership with MSFT and deployment tools could make MyID the FIDO2 product of choice for the Microsoft reseller. Accelerating sales.
I would not be surprised if Matt or a cyber security player acquires IGP before Google makes an offer.
I hold IGP since 2019 and have added more today.
Cornwall Insight have released our final October-December 2024 price cap forecast. We are forecasting energy bills will be £1,714 a year for a typical dual fuel consumer.
This would represent a 9% increase compared to the July price cap.
https://x.com/CornwallInsight/...
Should be good for Yu (LON:YU.) and others imo.
Sharecast's morning news included this snippet on Serica Energy (LON:SQZ) (I hold)
One of the North Sea’s biggest gas producers is threatening to end
investment in Britain because the tax regime has become too unstable to
support offshore energy producers. Serica Energy, which produces 5pc of
the UK’s gas supply and around 600,000 barrels of oil a day, is
preparing to shift future investment to Norway instead. - Telegraph
Diaceutics (LON:DXRX) announcement sounds like it could be a significant next step in their development. Contract with new major pharma customer initially worth 10% of current sales revenue for the licence through end 2025 with success fees of 75% more possible. Expect to extend the contract if hit success targets. Sp has responded nicely first thing.
I only have a small holding as this is at the blue sky end of my portfolio. Plan to buy in stages as it demonstrates real world success. Is it as good as it looks?
Hi sevenc
I think Diaceutics (LON:DXRX) is 'as good as it looks'. I have been invested for approx 2 years and my confidence has increased during this time. Diaceutics (LON:DXRX) are approaching the end of a 2 year period of investment which they have funded from their own cash. They have maintained their cash position of approx £16m (no debt) which growing rev 25% CAGR for a number of years whilst simultaneously moving to a SaaS model. Most companies struggle to maintain revenue growth when moving to SaaS. Recurring revs were 55% end June, expected to reach 60% by year end. I have spoken to management many times. They are passionate, do what they say and are well invested owning about 25% of the MCap. Gross margin is 85%.
Diaceutics (LON:DXRX) are thought leaders in precision medicine. Almost all the top pharma companies are clients, so embedded in their strategy. Medicine is moving from a 'try this and if it doesn't work, try that' strategy to pinpointing the precise medicine for each individual. This is great for patients and also pharma as they can commercialise their drugs much more effectively. Diaceutics (LON:DXRX) is perfectly placed and starting to deliver.
I have a large position.
Peel Hunt: ‘Add’ Osb (LON:OSB) Group
OSB Group (OSB) has disappointed the market with its first-half results but Peel Hunt has faith in its balance sheet and buybacks.
Analyst Robert Sage retained his ‘add’ recommendation and target price of 420p after the specialist lender, which is Citywire Elite Companies AA-rated, saw its shares plunge 15% to 408p on the back of a 28% underlying profit fall. At the end of the week, the shares had fallen a further 3% to 396.6p.
‘A further net interest margin downgrade is clearly disappointing, and challenges confidence in future financial performance,’ said Sage.
‘While we expect a period of share price weakness, the return on equity is likely to remain at mid-teens levels and the balance sheet remains strong, as seen in the future £50m buyback announced.’
Over the longer-term, Sage said that ‘the prospects for OSB are attractive, but that the group needs to instil confidence in net interest margin and establish a stable and rising net interest margin trajectory before the shares are likely to realise their medium-term potential’.
Also:
*BERENBERG CUTS OSB GROUP PRICE TARGET TO 580 (660) PENCE - 'BUY
The Times review of Osb (LON:OSB) update ends with:
"Shares in OSB Group shares fell by 91¼p, or 18.8 per cent, to 393p in afternoon trading, a decline that leaves the business valued at about £1.5 billion and could make it vulnerable to a takeover. There has been a big increase in deal activity among British banks and mutuals this year, including Nationwide’s £2.9 billion acquisition of Virgin Money UK and Coventry Building Society’s purchase of The Co-operative Bank for as much as £780 million."
https://archive.ph/uUzg6
Ramsdens Holdings (LON:RFX)
The gold price continues to rise, albeit nothing goes up indefinitely; however the value of gold and the dollar historically have operated inversely and with the Fed likely to reduce interest rates, gold should benefit. That's my reasoning, which of course could be flawed. I don't invest in miners because I don't understand them, Ramsdens Holdings (LON:RFX) for me is much easier to get my head around and so have recently added a few more.
I have funded the purchase by exiting Bloomsbury Publishing (LON:BMY) at a handsome profit. A great company but as I posted previously the share price is I feel up with events. I may regret the sale but can always buy back in.
Just my view.
All the best
Ramsdens Holdings (LON:RFX) gives a very roundabout expsore to gold, plus a lot of other unrelated income streams. I hold but wouldn't use it as my main gold exposure. For those that don't like investing in individual mining companies, like myself, Golden Prospect Precious Metals (LON:GPM) might be worth a look - it's an investment trust with a diversified portfolio of junior mining companies. Trading on quite a wide discount. Pretty volatile as you'd expect, but should do well if gold continues to rise.
An ETF for gold miners is VanEck Gold Miners UCITS ETF USD A (LON:GDGB) which I hold alongside Wisdomtree Metal Securities (LON:PHGP) and Ishares Physical Metals (LON:SSLN).
Hi jonno, you are onto something with Ramsdens Holdings (LON:RFX) simply because , unlike gold miners it will never run out of gold while it just toddles along. My experience in gold miner shares has been won at top dollar price. I learned that it is better to invest in those actually getting gold out of the ground but the trouble with these is that they will place exploration for the next gold mine before the dividend if there's not enough profit to go round. As for gold prospectors one needs deep pockets to keep up with share dilution and a long-term expectation of a successful investment and that's being brave. Of the gold miners I hold, Centamin (LON:CEY) and Pan African Resources (LON:PAF) are of proven value.
Edit: going back just 2 years when gold was at 1700 dollars an ounce one could expect todays price of 2500 dollars to soak through into share prices. Hopefully anyway.
Silver
A diversified portfolio needs some gold. A simple gold etf like Ishares Physical Metals (LON:SSLN) does the trick.
I think you'll find Ishares Physical Metals (LON:SSLN) is for Silver, Ishares Physical Metals (LON:SGLN) is for Gold.
Intercede (LON:IGP) Beeks Financial Cloud (LON:BKS)
Wish I'd paid attention on both of those two. I feel there is too much risk on both of them to buy at the current prices. Both linked to big names but we don't know how much revenue this will generate, when the hype cools off they could come back down a bit, I'll wait and see.
Note to self - take time to read the daily SCVR every day!
LON: IGP
A quick search...
Microsoft’s (MSFT) earnings report may have signaled a continued slowdown in cloud growth and a steep drop in PC sales, but it also provided more insight into its growing security arm. According to the tech giant, its security offerings are now a $20 billion per year business.
Double previous years
The FIDO Authentication Market size was USD 1.3 billion in 2022 and is expected to Reach USD 6.72 billion by 2030 and grow at a CAGR of 22.8 % over the forecast period of 2023-2030
Van Elle Holdings (LON:VANL)
Interesting announcement regarding inclusion in Network Rails Southern Renewals Enterprise programme. As the work will be reactivate there is understandably no revenue figures quoted, but interestingly it appears that the company will operate independently rather than riding on the coat tails of a principal contractor. The shares which appear to be gaining some traction are cheap on a variety of metrics and Van Elle Holdings (LON:VANL) is in a net cash position.
I have a reasonable position, as does Richard Staveley manager of Rockwood Strategic (LON:RKW) , although I suspect somewhat larger!
"Van Elle Holdings plc (AIM: VANL), the UK's largest ground engineering contractor, has been confirmed as one of the delivery partners in Southern Renewals Enterprise's £1.4bn 10-year building and civils minor works framework programme for Network Rail's Southern region.
The Company will be allocated reactive, planned maintenance and small renewals projects across the Kent, Sussex, and Wessex routes covering control periods 7 and 8.
Van Elle's award under the civils portfolio covers earthworks and drainage, with a specific emphasis on slope stability in response to climate change related infrastructure investment. Van Elle's involvement in the framework has the potential to run for the full 10 years, depending on performance.
Chief Executive Officer, Mark Cutler commented. 'We are delighted to be announced as one of the framework's specialist partners for CP7 and CP8 in the Southern region. This is an important milestone for Van Elle; we typically deliver our services through tier 1 principal contractors with whom we enjoy high levels of repeat business, but as part of the Southern Renewals Enterprise model in this framework for Network Rail, we will be involved earlier, with much greater workload visibility. This will enable us to collaborate with other framework partners and assist in the early development of efficient solutions using our breadth of specialist geotechnical and rail engineering capabilities."
My morning smallcap tweet: Morning news light
Diaceutics (LON:DXRX) Libertine Holdings (LON:LIB) RM Infrastructure Income (LON:RMII), Batm Advanced Communications (LON:BVC)
◄Diaceutics (DXRX)► agreement with a leading biotech to become its primary promotional partner for the launch of a breakthrough oncology precision medicine in the US using PMx (, a suite of data-driven services built for the promotion and commercialisation of precision medicines). It's not only a milestone but 'the start of a new era'. [SP=123 Cap=105m]
◄Libertine (LIB)► hasn't received first £110k tranche of the bridging loan by 16 Aug. Only has cash to end Aug. Seeking asset sale. [SP=1.17 Cap=2m]
◄RM Infrastructure Income (RMII)► H1-June. Expects return of capital to accelerate in H2. [SP=74.4 Cap=87m]
In line: BVC
Exciting news from Intercede (LON:IGP) this morning; Intercede and Microsoft Join Forces to Streamline FIDO Passkey Management for the Enterprise.
Hard to imagine anything bigger.
And yet the Intercede (LON:IGP) announcement was an RCS not an RNS.
It's an RCS because there's no money involved. However, FIDO is extremely important for Intercede (LON:IGP) broadening their market. It is the next step down from PKI on the authentication pyramid, and is easier for enterprises to implement. It's also included in the new FIPS (US) government regulations as an option for moderately sensitive (as opposed to highly sensitive) government departments and suppliers, a market where Intercede (LON:IGP) are market leaders.
It's clear from the company that most enterprise adoption of credential management depends on ease of use as well as level of security. Microsoft have had several embarassing cases of lax credentials being exploited. By combining the impeccable reputation (see the client list) of MyID with the ease of use of FIDO in Microsoft's IDMS, you remove one of the main barriers of entry to enterprise adoption.
Agreed that people are getting more excited than they should be on this announcement by Intercede (LON:IGP) ?
So basically, Intercede will be one of many providers of FIDO passkey authentication solutions, that MS clients can choose that will work with MS products?
It seems like an analogy would be if a games developer goes live with a games app on the Apple App Store, and claims it is a "partnership with Apple to bring a game to iPhone customers"
Am I missing something here?
Actually it could be quite a big deal. It's not the FIDO authentication which is important - as you say is open-source (and has been part of Intercede (LON:IGP) MyID CMS since last year) - but the first integration of it with Entra ID.
Entra ID is used to sign on to any Microsoft Cloud services (365, Azure etc.). There have been lots of cyberincidents with Azure (usually password mismanagement, old credentials that have not been removed etc.) including Microsoft themselves and the US government. MyID is the now the only CMS that incorporates all the authentication methods (PKI, FIDO, TFA, Passwords) and provides a one stop shop for enterprises (99.9% of which still use passwords) to beef up their security and today's announcement means any enterprise using Microsoft services (almost all) can now use MyID for seamless credential management.
Will they be the only CMS doing this? Of course not, although I doubt many others will incorporate PKI (as it's expensive and complex to do and Intercede (LON:IGP) seem to have cornered the market).
Will it move the dial on the numbers this year? No.
But what it does do is open the door for Intercede (LON:IGP) to a vast market of enterprises using Microsoft who wouldn't have considered adopting a proper CMS because it didn't fulfil all their needs.
Imagine you're an enterprise looking to move away from passwords for important users and an IT integrator presents you with several options. If they can say the US Department of Defence, White House, Department of State and Department of Homeland Security together with Boeing and most of the US defence industry use exactly the same product you're being offered and it works with all the sign ons you need - well I'd certainly be interested....
But your logic here assumes that there are many enterprises that need to deploy the full range of authentication across their entire user base. PKI + FIDO + MFA/TFA + etc etc...
How many corporates need PKI and FIDO across their user base? FIDO I get; and that's why Intercede have been trying to go "down the pyramid" to FIDO, to get itself out of the PKI niche.
PKI is very cumbersome. That's why in the past, Intercede had only luck selling PKI based solutions to organisations with the highest security concerns, where security trumps ease and usability.
Therefore, on the Entra ID platform, Intercede will be one of many FIDO providers.... and not super unique...
Agreed. But Intercede (LON:IGP) appear to have first mover advantage.
Also, while PKI is cumbersome and won't be used unless mandated by a government, the fact that MyID is the only CMS (and likely to be one of the very few) to incorporate the whole authentication pyramid allows employees to move up the pyramid within the same CMS as opposed to having to adopt two systems with all the potential pitfalls of credentials falling between the cracks.
If you're an enterprise likely to be bidding for government contracts at some point which may require higher security then do you think you'd choose a CMS that gave you that flexibility or one which doesn't?
Anyway, I agree it has no immediate impact on their numbers. Time will tell if it accelerates the demand for MyID MFA or not.
I should add that the rise of Intercede (LON:IGP) this year means it’s become my largest holding so clearly I’m biased.
Also I think the SP has clearly got ahead of itself in the short term but in my experience, it’s very difficult to trade any dip when you can get significant announcements at any time stopping you from buying buy back in any volume.
What's also important is that Microsoft have last week decreed that MFA (Multi-Factor Authentication) will be mandatory for all Azure accounts from the near future - this means everybody will HAVE to use some form of PKI / FIDO etc...