Small Cap Value Report (Mon 2 Aug 2021) - PHTM, DIA, ESC, RCDO, GETB

Good morning, it's just Paul here with the SCVR for Monday. As it's a quiet day for news, Jack is doing other things today.
Timing - today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Photo-me International (LON:PHTM) - another upgrade to guidance. Shares still look good value, although the long-term outlook for the business is opaque, hence a lowish PER is to be expected.
Dialight (LON:DIA) - interim results show a return to just above breakeven. Outlook comments point to an improving performance in H2. Difficult to value, so I'm neutral on this one.
Escape Hunt (LON:ESC) - positive sounding re-opening trading, but no meaningful numbers provided. Not much cash. Speculative, unproven business model. It's not for me.
Ricardo (LON:RCDO) (I hold) - a straggler left over from last week. Trading update is in line, with lots of detail provided. Seems to be recovering from the pandemic, and valuation looks cheap. I like it.
Getbusy (LON:GETB) - Brief thoughts on today's InvestorMeetCompany webinar.
Photo-me International (LON:PHTM)
75p (Friday’s close) - mkt cap £290m
Photo-Me International plc (PHTM.L), the instant-service equipment group, announces an update on the Group's trading position.
The company has a 31 October year end.
I’ve reported on this company 3 times so far this year, and have had a quick look back (our summaries at the top of each report are so useful for a snapshot view!), as follows:
11 March - guidance for £9.0m PBT in FY 10/2021
23 April - Surge in activity in Japan drives increase in guidance to £15-19m PBT
12 July - Good interim results, driven by restructuring rather than top line growth.
2 August - Q3 better than expected. Guidance raised to PBT £25-30m (previously £21-24m)
Today’s update - it’s more good news for shareholders.
Stronger-than-anticipated recovery of photobooth activity, mainly in Continental Europe.
New guidance - revenues £210m (old: £200m), profit before tax (PBT) £25-30m (old: £21-24m)
Outlook - generic comments tell us nothing really -
Nevertheless, economic uncertainty remains across many of the Group's operating markets due to the COVID-19 pandemic. The Board continues to closely monitor activity across all its end markets.
Valuation - an update from Finncap this morning (many thanks) shows 5.6p adj EPS for FY 10/2021, and 8.2p next year.
The big question is what PER should we apply, for an opaque business (it doesn’t disclose the split of profits between various activities), with a structurally challenged main activity (will photobooths be needed in the future?), which also seems to be geographically concentrated (most of the profit coming from mainland Europe, which I think is France mainly)?
It also doesn’t tell us what profit is being generated by the newer products (e.g. launderettes). So it’s impossible to value, as I’ve mentioned before.
As a guess, I think a PER of 10 looks about right, which would value the shares at 82p based on next year’s forecast EPS of 8.2p.
The current price is 75p (likely to rise today when the market opens, I’m writing this at 07:35), so the current valuation looks reasonable to me.
My opinion - a tremendous recovery in performance this year - it just shows the benefits of restructuring (unprofitable machines were withdrawn, and other costs cut). This is one of many businesses that have emerged stronger from the pandemic, which forced them to take an axe to poorly performing areas of the business, which might have been tolerated in the good times.
PHTM looks a good business, and reasonably priced, so I can see why some investors like it. The lack of visibility about what the future holds, and the opaque reporting of segmental profits, mean that it’s not something I would be able to value with any certainty, hence that rules it out for me. I like as little guesswork as possible when assessing shares.
However, people who anticipated a recovery in performance, have been well rewarded, and it looks like today should see a further rise, so well done to holders. Nothing is said about dividends today, but with this strong performance, it seems likely that divis might resume at some point.
Note the consistently high StockRank too.

.
Takeovers
There’s a bumper 800p agreed cash takeover bid today for Meggitt (LON:MGGT) - valuing it at £6.25bn. Not a small cap obviously, but it’s the latest in many takeover approaches for UK listed companies. The premium is an astonishing 70.5% on Friday’s close.
The buyer, Parker-Hannifin is a large American corporation. So many bids for UK companies seem to be coming from across the pond - suggesting that in places, the UK market looks cheap to Americans.
Wm Morrison Supermarkets P L C (LON:MRW) - Sunday papers suggested that there might be a bidding war for this property-rich supermarket, which is already in play. I wonder if other supermarkets might also receive bid approaches? I’ve taken positions in J Sainsbury (LON:SBRY) and Tesco (LON:TSCO) on that basis, but they also look good value on fundamentals. Although logistical problems are widely reported, with a particular shortage of HGV drivers at the moment, which is pushing up wages.
Let’s hope some bid approaches come through for small caps as well.
Dialight (LON:DIA)
327p (up c.4% at 09:!4) - mkt cap £109m
Board changes - don’t look particularly important - the Chairman steps down to a NED, and another NED steps up to become Chairman. A different NED leaves after 9 years.
Dialight plc (LSE: DIA.L), the global leader in sustainable LED lighting for industrial applications, announces its half year results for the period ended 30 June 2021.
This is a nice touch - a results video, including some pictures of its factories & staff, which I like, because it helps to visualise what the business is like in reality.
.
Key numbers -
Revenue H1 up 9% to £60.2m - prior year comps are not representative of normal performance, for all companies, since we’re comparing against the prior year period which was worst impacted by the pandemic, in the most stringent lockdown 1. So I’ve checked back to the 2019 interims, and this showed £76.1m revenues. Today’s reported revenues are 21% below the pre-pandemic level, so not very good.
Profit before tax - breakeven, at £0.1m profit in H1. The company identifies £0.7m of non underlying items (litigation costs) in note 3, so the adjusted PBT is £0.8m. I don’t like litigation, so would not buy this share without first fully investigating that issue.
Balance sheet - NAV of £56.8m, less intangible assets of £21.9m, gives NTAV of a healthy £34.9m.
Note the £1.1m pension scheme asset - which could indicate a liability, because of the crazy way pension scheme accounting works.
Inventories stand out as very high, at £36.0m. That strikes me as inefficient, because cost of sales for the half year is £39.0m, indicating that the company holds inventories of almost 6 months sales - way too high. There could be slow-moving stocks held there, or maybe the company has too wide a product range? It’s tying up capital unproductively, and raises the risk of a future exceptional item to write down stock, possibly.
Receivables look fine at £19.3m, so there doesn’t seem to be a problem collecting in the cash from customers.
Net debt of £12.0m doesn’t look problematic.
Overall, the balance sheet looks OK to me. I’m not worried about solvency, or dilution risk, which are the key things to look for.
Cashflow statement - the stand out item is £1.6m development spending capitalised in H1. So that renders EBITDA meaningless.
Note also the £1.2m repayment of lease liabilities in H1, near the bottom of the cashflow statement, that should be manually moved up, in my opinion.
Overall there is slightly negative free cashflow.
Outlook - the H1 results are nothing to write home about - a company that’s nowhere near to recovering in full to pre-pandemic revenues. Operating around breakeven, in profit and cashflow terms. Therefore, the key question is what does the future hold? Can it improve on these numbers, I would hope so!
H2 2021 has started well with substantial order book
· Expectations for full year currently unchanged
The first half of 2021 has been encouraging with a significant improvement in order intake, revenue and a return to profit combined with ongoing cash flow discipline. We expect our markets to continue to recover at varying rates, while acknowledging that there are potential headwinds including currency, inflation, and supply chain constraints. We have made good progress in the first half with order intake ahead of revenue and a good pipeline of projects for the second half of the year. Our expectations remain unchanged at this stage.
Longer term the sales pipeline, product development, team strengthening, and operational actions will help ensure we are strongly positioned to sustain significant growth as end market conditions normalise. We are also seeing the increasing requirement of our customers for more environmentally friendly products that help them to meet their net zero commitments and as market leader we are at the forefront of supporting this.
That’s not very helpful - saying expectations are unchanged, but no indication provided of what those expectations are! How ridiculous. I can’t find any broker research to help either, so we’re left in the dark. Hence I won’t be buying any shares, due to inadequate information.
My opinion - it sounds as if the company is expecting an improvement in trading in H2.
As mentioned above, I don’t have enough information to form a view on this company. Who are its competitors? How do Dialight products compare with them re price & quality? I’ve got no idea on that, do any readers have experience of the company? We love “scuttlebutt” from readers if you’ve worked for, or dealt with any company, then do post anything you can to share your experiences.
With the order book growing, it sounds like Dialight is set up to report better H2 figures, so that’s positive. The balance sheet looks OK. How to value it? I don’t really know, as it depends on how strong the future recovery is. I can’t see any serious negatives in the numbers. Therefore overall I’m neutral on Dialight.
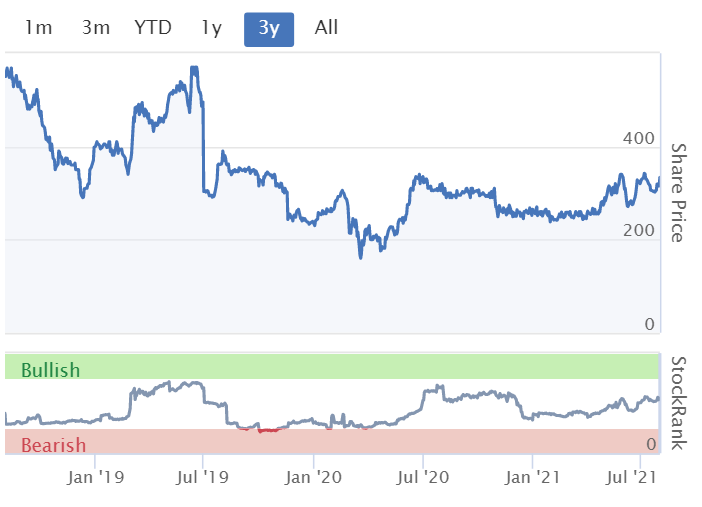
Middling StockRank. The chart looks interesting, that shape tends to attract charting/momentum traders, so there could be a short term trade here maybe?
.
.
Escape Hunt (LON:ESC)
38.5p (up 10%, at 10:53) - mkt cap £36.0m
Escape Hunt, a leading international operator of escape rooms in the fast-growing experiential leisure sector, is pleased to provide an update on trading since the re-opening of its UK sites and for the six months to June 2021 ahead of the release of its unaudited interim results due to be announced in September 2021.
Main points -
- Uk sites re-opened on 17 May 2021
- Trading in 10 weeks to 25 July 2021 “ahead of management’s expectations”
- Total revenue (NB not LFL revenue) up 58% on 2019 pre-pandemic comp
- Like-for-like (LFL) revenues (8 sites) down 5% on 2019
- LFL has improved, and turned positive (+2%) in the last 5 weeks
- EBITDA at site level up 185%, or 83% on a LFL basis - good percentage increases, but with no base numbers provided, that doesn’t tell me much
- Cash balance of £2.4m at 30 June 2021, plus an undrawn £1m convertible loan note facility - seems low for a £36m market cap company with an unproven business model.
- Revenue only £1.1m in H1, due to sites being closed until 17 May 2021. That’s 6 weeks and 3 days of trading, or 45 days. That annualises to a run rate of £8.9m
- New sites - 18th and 19th UK sites are in the pipeline
- “Property market conditions will continue to be favourable, in short & medium term”
- Demand expected to improve in the autumn, as office workers return
Forecasts - thanks to Zeus for putting out a short note today. This shows an unusual, but useful approach to forecasting - giving a run rate, at end 2022, with 3 cases (optimistic, base case, and pessimistic). That’s by far the best way to forecast, in my view, and it’s what a lot of companies do internally. Let's hope other brokers switch to doing 3 scenario forecasts.
The 3 figures for ESC are EBITDA of £2.3m, £1.2m, and £0.6m. as that's the Q4 run rate, it's effectively forecasts for calendar 2023.
My opinion - there’s not enough information in this update for me to form a view.
In my view it’s far too early to decide whether ESC has a viable (long-term) business model or not.
I can see how escape rooms might be a fun, albeit niche, experience, but the trouble is that the sites would have to be changed frequently, requiring continuous capex, to refresh them. Hence I imagine a surge of initial demand is likely when they open, then a long tail of declining sales, or at least increasing marketing costs to drum up business from a declining group of people that have not experienced it yet.
The valuation of £36m, for what is really a speculative concept, that’s very easy to copy, strikes me as highly optimistic. So it’s not for me, as risk:reward looks unfavourable at this stage, and I’m trying to get out of the habit of speculative buying of unproven business models, as they rarely work out as planned. So it's really a complete punt, in my view. Maybe the re-opening trade has overshot on the upside?
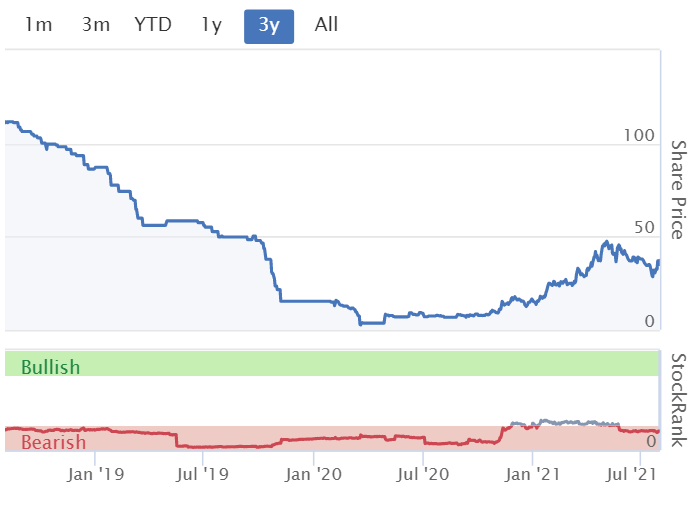
It floated in 2016, and was a dismal performer well before covid hit. The initial placing was at 135p, when it reversed into a shell called Dorcaster. Looking at the Admission Document the initial share count was 10m. It's now 88.6m, which tells me everything I need to know about this share! I'd say the recent big surge in share price could be providing a favourable exit point.
.
.
Ricardo (LON:RCDO)
(I hold)
390p - mkt cap £245m
Ricardo plc ("Ricardo") is a world class global engineering, technical, environmental and strategic consultancy business, which also manufactures and assembles niche, high-quality and high-performance products.
Ricardo is today providing a trading update ahead of its full year results in respect of the year ended 30 June 2021. Ricardo plans to announce its full year results in September 2021. The results in this trading update are subject to audit.
This somehow slipped through the net, in last week’s deluge of reports. There’s lots of information in the update, here is my summary of the highlights (I’ve omitted the detail on divisional performance, for brevity) -
- FY 06/2021 - Ricardo continued to recover from the pandemic
- Sequential half year improvements in revenue & operating profit
- All division improved “activity” and “revenue” (what about profit?!)
- Order intake for the year of £350m, down on £369m in prior year
- Revenue of £350m, same as last year
- Net debt - £47m at June 2021, £50m at Dec 2020, and £74m at June 2020
- Placing of £28.2m main reason for drop in net debt
- Liquidity looks ample, with a £200m bank RCF available
- CEO leaving, previously announced 25 Jan 2021, but he’s still in situ as heis named in the trading update as CEO
Most important bit - underlying profit before tax (PBT) is in line with market consensus forecast. Yes there’s a footnote, thankyou!
[1] Based on company compiled analysts' consensus of £18.0m, with a range of £15.1m to £19.6m
Valuation - grateful thanks to Liberum for crunching the numbers - analyst Daniel Cunliffe has converted the trading update into 28.3p EPS for FY 06/2021, 31.8p the following year, and 40.4p after that.
At 390p per share, the PERs are: 13.8 (historic), 12.3 (current year just started), and 9.7 the following year. Looks cheap to me, even after we adjust for net debt (not excessive).
My opinion - I opened a standard size starter position in this share recently at a rather ill-timed 441p. That broke my usual rule of only buying after a recent reassuring trading update or results, to eliminate the short-term guesswork. Sometimes you have to break your own rules, to be reminded of why you have them, and get back on track!
I’ve always had a positive impression of Ricardo, but it’s been too expensive in the past.
It’s now looking decent value, so it’s moving into my “need to buy more when funds permit” tray.
To be completely open, I’m not that au fait with the various parts of the business, it seems quite diversified. What do subscribers think?
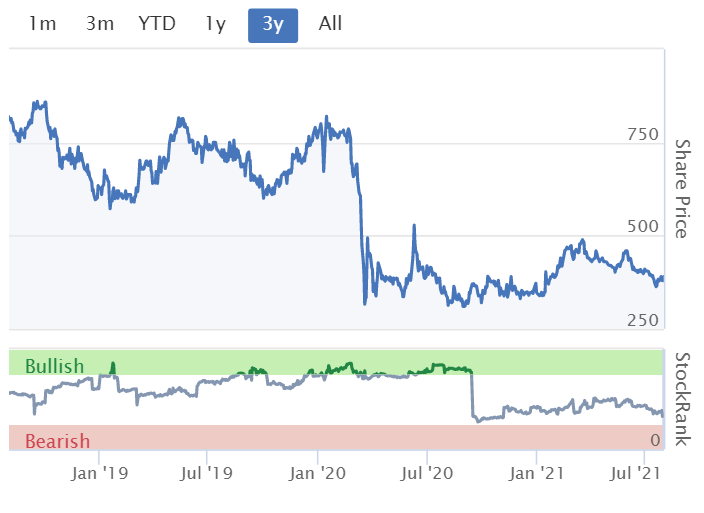
This is an unusual chart, the share price is not that much above pandemic lows. Surprising, considering performance is recovering. An opportunity maybe? Or is there something nasty lurking that I haven't spotted?
.
.
Getbusy (LON:GETB)
82.5p - market cap £41m
Brief thoughts on results webinar today
I tuned in to this at 11am, and thought management presented well - the CFO seems a much more confident presenter than the CEO, just as an aside.
I'm reasonably familiar with the company, and quite like it, so there wasn't really anything new in the presentation. A few points I did jot down though -
- Well-used niche product - 30% of UK's top 100 firms of accountants use Virtual Cabinet - so it must be a very good product
- Very sticky recurring revenues, and low customer churn
- Talked us through the productivity benefits of using their software, which sounds convincing (e.g. eliminating lost files, confusion over which version of file is latest, etc)
- Annual recurring revenues: Virtual Cabinet 56%, Smart Vault 44%
- Strong visibility, as reliable recurring revenues
- Development spend fully expensed
- My view the £1.1m corporate/shared overheads seems a lot, and arguably could be unrealistically boosting the Virtual Cabinet profit line of £2.1m (mentioned before in SCVRs)
Overall - lots of other things were mentioned. My main worry is that the main products could be mature, and hence post-growth? (even though markets are very large). New products haven't gained enough traction yet to be exciting. On balance then, I remain neutral, although leaning slightly towards positive.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
News late afternoon (but pre market close) that the bid for Meggitt (LON:MGGT) has been called in for review as a matter of potential public interest. CMA is required to review and submit a report to the SS T&I by March 22nd next year.
https://www.investegate.co.uk/...
At the very least this creates quite a lengthy delay and potentially calls the whole deal into question. Given the very high original bid premium that could be in jeopardy surprised there was barely a flicker in the Meggitt (LON:MGGT) share price.
Gus.
Hi abtan.
Thanks for posting the link. I’m no lawyer but a layman‘s read of the judgement suggests Augean (LON:AUG) have a pretty strong case/judgement in their favour. Gist of the argument appears to be that in seeking to clarify whether a company is liable to pay a standard rate or lower rate tax on landfill deposits, HMRC in effect extended its powers in the original legislation to levy a higher rate of tax that was not prescribed in the original law. The judge’s view is that HMRC is not clarifying the position but making new law. As it’s Parliament rather than HMRC that makes laws in the U.K. this is outside HMRC‘s authority so they are not allowed to do this, hence the ruling in favour of Augean (LON:AUG) . No doubt HMRC legal counsel could try and pick holes in the argument but at face value the judgement seems pretty definitive.
Gus.
Going back a few decades, the main speciality of Ricardo (LON:RCDO) was R&D on engines, for which they had a very good reputation.
They now seem more diversified, although if I understand correctly, the Performance Powertrains business is developing and selling engines to McLaren (road cars, not racing, obviously).
According to the last presentation on their site, Automotive, Industrial and Performance Powertrains was just over 50% of revenue.
When the share price gets cheap enough to think about it more, my first task would be to work out how this business adapts to electrification, alternative fuels etc
I don’t hold Versarien (LON:VRS) but note that it is up over 9% today.
This has been a perennial jam tomorrow business. Such a farce one wonders if someone was having a bet with the company management to see how many RNS they could issue about their collaborations with potential customers before the whole thing collapses.
Well there’s no RNS today, so, given their predilection for issuing these at the drop of a hat, there cannot be anything too dramatic/material happening. However, an article in the Times talks about HS2 using graphene enhanced concrete printed with a 3D printer in situ rather than traditional reinforced concrete parts brought to site. And a press release from HS2 themselves confirms it and that the graphene is from Versarien.
https://mediacentre.hs2.org.uk/news/3d-concrete-printing-and-graphene-combined-on-hs2-set-to-cut-carbon-content-by-up-to-50-percent
So, what to conclude? Either the company is very dozy at present, perhaps they are all isolating, or it is not material to their numbers. I had thought that the problem with their product was that it may cost too much, but could the issue here be that the quantities of the magic carbon dust are just so small it doesn’t move the dial. Or perhaps it is just a trial and even if successful HS2 will only do very minor work this way. (So, more a bit of PR from HS2 than something of significance).
Just shows how difficult it is to know with any certainty when new tech will actually gain traction.
RNS seem to have dried up at Versarien (LON:VRS) . Adding graphene to concrete has been in the public domain - https://www.graphene-info.com/...
On Photo-me International (LON:PHTM) I actually think the story is terrible for H2.
Adjusted PBT was £12.9m in H1.
Now they're guiding £25-30m FY, say £27.5m midpoint. That's £14.6m PBT for H2. Looks good on paper, sequential HY improvement in PBT.
However, if you look back at prior years, H2 PBT is significantly higher than H1! Its all over the place, but its been as high as +100% and as low as +60%. Seasonality is high in this business.
So it looks like, potentially, H1 was a bumper half. H2 is going to be a reversal.
So it'll be a red herring to take FY21 EPS and assume that FY22 would do better, as the H1 bumper profits look it really was a one-off. The extra profits from the Japan photo booths.
Off the back of the envelope I think I can see 5.8p EPS next year, which is below the current broker forecast of 7.6p.
Always thought there's potential here, what with the chairman buying loads in 2020-2021. But I just can't justify going in at the current 77p price. It doesn't look like lots of potential; and in fact looks like a lot of the growth next year is already baked into the price.
Photo-me International (LON:PHTM) (no position)
The main issue for me with this one is that the CEO owns too much of the company. He can literally do anything he wants and given how long he's ran the business there's nothing to stop him delisting. That's a risk too far for me
Saloon bar theory why Photo Me CEO has bought so many shares over the last year is to enable the CEO's job to go to his daughter
Getbusy (LON: GETB) / Checkit (LON:CKT).
I also watched the Getbusy webinar agree that the CFO gave a much better impression than the CEO. I'm pretty sure I watched him present at Mello. I like the recurring revs and the products appear to be good and sticky and the growth story sounded compelling. I watched as I wanted to compare Getbusy to Checkit (LON:CKT) where I am long.
I recently went to Checkit CMD who provide operations management software for deskless workers as opposed to Getbusy who provide a software for accountancy. The figures according to Stockopedia appear similar except that Checkit has the benefit of £11m in cash to fund its growth. Checkit have made an acquisition in the US to assist with this growth and have made some recent appointments also. BP is a client of Checkit in the UK with the potential to go global and their chairman and largest shareholder is the successful and impressive Keith Daley. Whilst I like the little I know of Getbusy, I feel happy with my investment in Checkit.
The big risk with small, one-trick software like Getbusy (LON:GETB) is that the larger software vendors who supply the same clients, decide to start offering this, and initially give it away for free/cheaply to squeeze out competition.
Think Slack in the USA in 2019/2020, and how Microsoft invested in Teams, gave it away for free, and caused huge headaches for Slack.
What's to say MSFT or any of the large software vendors to accountancy firms don't do the same? Strategically they will do this because they might lose money replicating SmartVault / document signing, but then have deeper tentacles in their clients and make them more sticky for their core, cash-cow software.
The flip side, of course, is that one of the larger software vendors might buy GETB at a premium to do exactly the strategy I've described, rather than develop it from scratch in-house.
But they won't have to buy GETB on the public markets and have the hassle of take-private; I'm sure there are a few PE owned, similar platforms to GETB that they could acquire much more easily.
Saga (LON:SAGA) (I hold) There's a nice write up in the Mail on the Saga's Spirit of Adventure https://www.dailymail.co.uk/tr...
RajanP Saga (LON:SAGA) thanks for posting the DM link - at last, something positive
Re Saga (LON:SAGA) - just spent the day doing covid testing/screening to get Virgin cruises going ex Portsmouth. All passengers double jabbed and keen to go; no sign of an issue on demand side and ability to supply "safely" steadily improving.
I agree Ricardo (LON:RCDO) looks interesting Paul, especially when you compare the current price against historic P/E ratios it has achieved (often 14-20x).
My main nervousness is whether it's going a bit ex-growth? If you read the FY19 commentary the company warned that it was facing increased headwinds in the automotive part of its business due to Brexit, tariff actions, and 'uncertainty in outsourcing trends'. So this segment had encountered problems pre-pandemic and maybe the pandemic has obscured whether there is a more fundamental issue here? I don't know enough about outsourcing trends to know if this is in longer-term decline in the automotive sector or if this is just a temporary issue. If anything I would have thought the shift to electric vehicles would increase the need for outside engineering expertise?
On the other hand, the growth in the environmental division looks interesting.
I don't hold but thinking about it.
I sold my holding in 2017 at about 750p. I notice that every instution named as major shareholder here has bought more this year so they must agree with the Liberum note which has a TP of 570 based on £20mn net in 2 years time. That puts them on a foward p/e of around x10 for June 23 and the current ev/ebitda is already well below 10 which feels cheap by current inflated standards. Possible value tob target? I actually hope not as too many good companues being snapped up by vultures from the US.
My small concern is whether they may be negatively affected by the move to more electric vehicles. But on the other hand Ricardo seems to be pretty active in very important project work on lowering emissions, especially I note work in the Mexico heavy transport sector and the hydrogen aeroplane initiative in the UK. Perhaps it is a (relatively) safe route into important future sectors without the glitz, a bit like Johnson Matthey?
June 21 (figures out next month) adjusted est PBT of £18mn but reported PBT of only £4mn due to some exceptional costs (writedowns I assume) though this should normalise next year to June 22.
I am a bit surprised the share has come back so much from the year high but perhaps the resurgence of covid, well pubilcised problems (chip shortages, factory closures etc) in the automotive sector have been the root cause. Plus they are still looking for a new CEO. Standard Life has been a quite argse seller but they are (imo) useless.
Any comments on Augean (LON:AUG) ? - the bid price of 280p plus a note for up to 20p depending on the outcome of the dispute with HMRC came at 16 30 on Friday.
Since the shares closed at 285/290 on Friday this was a little underwhelming but they have 46% acceptances in the bag.
I sold this morning at 280.5p. This gives me the cash bid but I risk losing up to 20p from the HMRC part, but this is unknown at present. I also risk a counterbid, but this bid, other than the price, has been known about for two months and so I think that is less of a risk than if this was the first announcement.
So - a gain of 29.2% over 18 months compared to 29.4% on the AIM All-share index. I have you all to thank for this! In January last year I researched the top 10 picks chosen by subscribers in the Stocko Challenge and bought this and one other - Volex (LON:VLX) - now up 113% and holding!
I (still) hold and am very disappointed with the price agreed for Augean (LON:AUG)
The contingent entitlement is annoying, unnecessarily complex and will probably take an age.
Praying for a counter-offer...
FR
Augean (LON:AUG) (I hold)
If HMRC do not appeal by the end of this month, don't we just get the extra 20p now?
In which case, is it not better to just hold for a few more weeks?
I can't imagine a delisting will happen this month, but I'm happy to be corrected if I missed that detail.
And of course there is still that minimal chance of a counter-offer, whilst 280p is on the table.
In my mind there was always a risk that if HMRC won the case, Augean would need to pay the higher landfill tax for 2018-2021 as well (an extra c£25m by my estimates), so I'm happy to take the win, which is only just below my target price anyway, and move on.
A
That would be wonderful!
Augean (LON:AUG)
For any interested here is the latest Augean vs HMRC court ruling, which looks like it's finally been published:
https://www.casemine.com/judge...
I've only glanced through parts of it, but it seems quite conclusive that HMRC have no grounds to ask for high rate of landfill tax retrospectively.
Paragraph 48 in particular seemed quite positive (sorry, it won't let me copy and paste.)
It's 56 days from 22nd June 2021 to appeal. That's August 17th by my understanding. Hopefully there will be no appeal by this date therefore releasing the extra 20p from the recent bid.
Here's hoping.
A
re. Augean (LON:AUG) , August 17th hypothetical deadline for the HMRC appeal has come and gone. Haven’t seen any news either way although schare price is staying stubbornly close to the 280p level suggesting the market isn’t too confident the extra 20p is coming. Hopefully some clarity next week.
Gus.
Augean (LON:AUG)
Hi Gus
I've been away for a few days with terrible internet, so my apologies for posting this so late.
Mark Fryer, the CFO, emailed me a few days ago to confirm that HMRC have asked for an extension to the appeal deadline.
He further added:
"There is no reality of payout pre completion though as this is only one aspect of the case (out of around 6) and only the Lower Tier. There is still the Upper Tier, Court of Appeal and High Court for whoever loses and seeks to challenge up to the next level. This means that we will be in this process for the next 3-5 possibly 10 years. I appreciate this is hugely frustrating for shareholders."
So it looks like nothing is going to happen pre-delisting.
Given the current share price of 281p, there doesn't seem to be much point in selling right now anyway so I personally will be holding on.
The extra 20p/share next month would have been nice though...
Cheers
I note that the FT today published a survey run by BDO of medium sized businesses in the UK.
Only 58 per cent expect to return to pre-Covid revenues in the next 12 months.
However, BDO’s survey of 500 medium-sized firms across the UK also identified potential challenges.
Over half, or 58 per cent, of surveyed organisations have open roles that they cannot fill and 34 per cent cannot find people with the appropriate skills, BDO said.
In addition, 99 per cent of businesses said they were concerned about the potential impact of rising inflation.
-----
The risk with inflation is that it can runaway if everyone expects and plans for it (ie stock up, raise prices proactively). So not good if all businesses are starting to plan for it.
Then there is the fact that only just above half of businesses will return to pre-Covid revenue levels over the next 12 months!
"The risk with inflation is that it can runaway if everyone expects and plans for it ..."
Yes and undoubtedly there is inflation around at the moment. But if these companies were able to pass input inflation along to their customers via output inflation, then they wouldn't be so worried about it. That would just result in bigger nominal profits.
The problem for them is that they are unlikely to be able to fully pass inflation along. You say that "only 58 per cent expect to return to pre-Covid revenues in the next 12 months." That suggests an economy still running well below capacity, which is not an environment conducive to rising prices.
It's this kind of thing that suggests why market chatter has shifted away from inflation concerns, towards an oncoming profit squeeze, and so why government bond yields have fallen significantly over the last 2 months.
One has to be very careful with surveys because the answers depend entirely on how the question is phrased. The inflation question may have been “If inflation went and remained above 5% would you be concerned about the potential impact?”
it also depends on what sectors were polled.
Thanks Paul for your comments on Dialight (LON:DIA)
You say "Inventories stand out as very high" - this is happening a lot now as component stocks are increased against supply problems. The report says "The increase in inventory during the period was driven by a decision to increase the holdings of raw materials given current world-wide shortages of certain products and delays in shipping". XP Power (LON:XPP) also announced interims this morning - inventories are up from £44m to £56m for a similar reason.
You also say that "I don’t like litigation, so would not buy this share without first fully investigating that issue". Well, previous management of Dialight (LON:DIA) , or Direshite as Mr. C used to call it, thought it would be a jolly good idea to outsource all the production. That turned out to be an utter disaster. There was a profit warning on 14/12/17 when the CEO stated "The performance of our manufacturing partner is a significant disappointment". He was given the boot on 8/1/18 and the new management brought the production back in house.
The litigation is with Sanmina to which production had been outsourced. The last annual results stated:
"We have sought to reach a negotiated conclusion on various outstanding matters following the termination of the manufacturing services agreement with our former outsourced manufacturing partner, Sanmina Corporation. On Friday, 20th December 2019, both parties issued legal proceedings against the other, with Sanmina claiming up to £8m against Dialight and Dialight counter claiming up to £190m against Sanmina. The basis of the claim filed by Sanmina Corporation relates to outstanding invoices and residual inventory they allege they purchased for Dialight. The claim filed by Dialight is more complex in nature and relates to significant costs and losses suffered as a direct consequence of Sanmina Corporation not performing in accordance with the terms of the manufacturing services agreement. In the unlikely event that Sanmina's claim is successful, the range of outcomes could be £0 - £8m. Management have assessed the claim in conjunction with external legal advice and the judgement is that we are confident of the merits of our legal position. In the view of management, it is not probable that the group will have to make a payment. Therefore, no provision is required and the matter is disclosed as a contingent liability".
That the company survived this says only one thing - they have a very competitive product.
Just worth noting not entirely new management - current CEO was CFO from late 2014. But she has clearly introduced a break from the outsourced manufacturing strategy that her predecessor and former boss had instigated.
(Just for transparency, I am a former employee. My opinion is terrific, class-leading products, market fundamentals are terrific, a lot of own-IP, some highly capable people, let down by devastating strategic decision 5 years ago that current management team are trying to recover from).
Hi. Might I ask you to just clarify which Company you are talking about please?
Dialight (LON:DIA)
After doing some work for a civil engineering company that was installing national LED lighting, I thought that a UK supplier would be a good investment. But, like Versarian, a good product killed by lousy management.
Interesting article about Cenkos Securities (LON:CNKS) over the weekend noting the company has already raised more money for its clients so far in 2021 than in the whole of 2020. That bodes well given 2020 was 3.3p diluted EPS.
Thanks, Patrick,
Seems like they experiencing good business flow.
Let hope the second half is successful also.
BSV
Maybe Paul and Jack (whoever makes the thread), you guys could put things like the Meggitt stuff as different posts rather than an "extra" in the SCVR to help with the discussion board being so useless because everybody just posts in the SCVR thread and nowhere else? Its the perfect topic to start a separate thread for surely?
Hi Liquidium.
I respectfully disagree that commenting on larger companies or topical issues outside the strict definition of a small cap value company should go on a separate thread. While Meggitt (LON:MGGT) is clearly not a small cap it is in a clearly defined sector (Defence and Aerospace) and if it’s attracting a 70% bid premium that has a clear read across to other companies in the sector, several of which such as Senior (LON:SNR) , Chemring (LON:CHG) , Qinetiq (LON:QQ.) and Avon Protection (LON:AVON) could well be of interest to small cap market followers, especially with another in the sector Ultra Electronics Holdings (LON:ULE) already being in the midst of a bid from Cobham. All of these are up between 2-6% today on this news.
Gus.
Hi gus,
Yes that's right, I only mention takeovers or macro things, because of the potential read-across for small caps, and market sentiment as a whole, which are relevant for here.
I've been chatting with Jack about how we improve discussions, because the SCVR does tend to become a vortex for all discussion of topical issues!
We like it when readers start your own threads to discuss larger companies, and then provide a link in the comments here. Michael did that for Boohoo (LON:BOO) (I hold) which we like a lot, so more of that from readers please, if you feel so inclined!
Regards, Paul.
I appreciate the topical comments. It’s good to get some views on the things that are relevant on the day. Perhaps when certain topics start to take over people need to start a new thread but otherwise I find it a welcome part of the SCVR.
Re: different Company discussion boards. If Stocko is prepared to become much more of a Company discussion boards site then I think we need a Board Index. This then becomes a whole different ball game because Boards need moderating IMO to stop them from becoming full of idiots and profanity (I'm thinking some of the ADVFN and LSE boards). Motley fool was a good example for those of us that enjoyed it until the discussion boards section demise. Really depends on the way Stocko wants the site to go as it requires quite a bit of work to do it well.
Gus
Entirely agree. I would be happy to see any size and sector of company discussed here but I get a sense that the majority want it restricted to small caps.
With the exception of a few companies (Boohoo (LON:BOO) for example) I don't think it would drown out other companies in the comments section but there we go.
Regards
Michael
MichaelFBS - I'm with you re having all companies mentioned here. All I'm interested in is information that leads me to making money. However, there will always be the self-appointed 'Board Police' who can sometimes monopolise the board with objections to something. Check one or two of The Lemon Fool boards if you want to see this in operation. I hasten to add that beyond one or two Boards there the rest are very good.
But why does "here" have to be the SCVR topic every day, why can't "here" be the stockopedia discussion board as a whole. Its a vicious circle where everybody wants everything mentioned in the SCVR because its the most active place and the circle repeats, its just a spam fest.
I think if people dont put the effort in to try and make the message board as a whole become more active then it may as well just be binned and simply have a single posting thread each day for the SCVR and 100% of posting all spammed in there. At the moment 95% of stocko users are in SCVR and then 5% are posting stuff outside and just getting ignored.
Angle (LON:AGL)
Interesting article published from Institute of Oncology Ljubljana, Slovenia. They ran tests to determine which CTC separation technique / equipment would best be suited to their labs. Their results (again) proved Parsortix outperformed other systems by some way.
https://radioloncol.com/index.php/ro/article/view/3731/4923
Thanks again JimMcLad for that snippet of more extensive success in research for the Parsortix process owned and heavily patented by Angle (LON:AGL) . All good news but the best will be FDA approval. We eagerly 'some time in the second half of Calendar 2021' for that.
£mmgt surely one that should be considered as a company of national importance? one I don’t think should be allowed to fall into foreign hands (though if I held I might feel differently).
Meggitt (LON:MGGT) can’t edit.
Re. Meggitt (LON:MGGT) , when it’s Uncle Sam doing the buying I suspect national security considerations may be less of a priority than if, for example, it were a Chinese company. This said, the Meggitt share price this morning is less than 750p compared to an 800p cash bid so there must be some uncertainty in the background.
Gus.
similar to the Ultra Electronics Holdings (LON:ULE) bid, where the sp hasn’t yet matched the proposed takeover price.
I assume where there is some relevance to the defence sector, the takeover will be subject to greater scrutiny from the government and hence higher risk of it not going through.
I just bought some Meggitt (LON:MGGT) at 727p as a bet that the deal will go through.
I can’t see how the bid can be blocked on national security grounds when the customers are primarily US companies like Boeing?
The undertakings being made about protecting jobs and investment in the U.K. seem pretty thorough and make me think there may have already been discussions before the bid was announced.
For any investors in Thinksmart (LON:TSL) it's notable that Afterpay were bid for by Stripe overnight, which presumably (although I can't actually find the underlying agreement) will trigger the option to buy out Thinksmart's remaining 7% stake in Clearpay. For those unfamilar with the situation Thinksmart sold 90% of Clearpay to Afterpay with options on both sides to sell to Afterpay.
Since Afterpay and Thinksmart appear to quite a way apart on valuation it'll be interesting to see how this plays out.
timarr
The Afterpay buyer is £SQ not Stripe
The Afterpay buyer is £SQ not Stripe
Yep: https://www.theguardian.com/au...
timarr
I am (luckily) a holder of Thinksmart (LON:TSL) but I cannot understand the likely value of the Afterpay takeover by Square to Thinksmart.
Currently the 10% holding in Afterpay is conservatively valued at £106.6m in Thinksmarts' accounts. BUT todays Afterpay takeover valuation is $29bn (circa £20.8bn) so 10% = c. £2bn......
Am I making a massive mistake with my sums here? Admittedly the valuation may be determined by the agreement between Thinksmart and Afterpay.
Am I making a massive mistake with my sums here? Admittedly the valuation may be determined by the agreement between Thinksmart and Afterpay
Hi Nick
Unfortunately yes, you are making a mistake.
The 10% in question is 10% of Clearpay not 10% of Afterpay. So it depends on what weight Clearpay has within Afterpay - but obviously that's a function of the Afterpay market cap, so the higher the Afterpay share price the higher the valuation of Clearpay.
On the basis of the discounted valuation Thinksmart (LON:TSL) put forward last December (which is close to the offer from Square) that valued their 6.5% stake at £106.6 million:
https://www.thinksmartworld.co...
At the same time Afterpay were holding Clearpay on their books at £36 million, so quite a gap.
timarr
That makes more sense - thanks for the input!
That makes more sense - thanks for the input!
No worries.
Even after the rise today the price is still about 40% discounted from the Thinksmart (LON:TSL) valuation - presumably because of nervousness about how Afterpay will value the stake and potential arbitration. However, in the context of Square's £21 billion takeover price will they really want to quibble over a few tens of millions to get outright ownership of Clearpay?
Thinksmart announcement on the subject:
https://www.stockopedia.com/po...
Brings forward the exercise data of Afterpay's option (currently at 23rd August 2023) and means that any exercise will be in cash.
timarr
Yes still heavily discounted compared to value. I have just re read the Simon Thompson article, he has a target of 109.5p and this was before todays news about Afterpay. I expect he will issue an updated article with an updated target price in the next 24 - 48 hours.
Simon Thompson has issued a new article and has a sum of parts valuation of 140p so continues his BUY rating
Not just a Buy but a Strong Buy recommendation from ST (who wrote the article when the share price was around 87p, i.e. post-rally) on £TSL.
I guess the Clearpay valuation can go down as well as up though, so there is still some risk until that put/call option is exercised in 22/23. I do wonder whether Square have paid a lofty valuation and I worry about competition from Paypal, Affirm, Klarna, Apple etc.
Having said that, there is still a decent margin of safety with the current c.35% discount to the 140p sum-of-the-parts valuation.
You are confusing Afterpay with Clearpay
My morning smallcap tweet:
Totally (LON:TLY) Photo-Me International (LON:PHTM) Camellia (LON:CAM) Escape Hunt (LON:ESC) Cyanconnode Holdings (LON:CYAN) Tribal (LON:TRB) U.K. SPAC (LON:SPC) Sensyne Health (LON:SENS)
Totally (TLY) wins 3 year contact worth £4m PA. Also contract extensins worth total c. £2.5m. [SP=38 Cap=69m]
Photo-Me International (PHTM) hikes FY(Oct) rev guidance by £10m to £210m and pretax £25-30m from £21-24m. Cites stronger-than-anticipated photobooth activity, mainly in Continental Europe. [SP=75 Cap=284m]
Camellia (CAM) buys 80% of Bardsley England, a major fruit farming business, for £15.7m. Expected to be earnings enhancing in 2022. [SP=6800 Cap=188m]
Escape Hunt (ESC) last 10 weeks rev and site level EBITDA from the UK owner-operated estate ahead of mgmt expectations. UK rev up 58% on 2019. Group rev in H1(June) £1.1m, (£1.3m). [SP=35.5 Cap=31m]
CyanConnode (CYAN) wins contract for 152k Omnimesh Modules and related hardware, S/W and services. No £££. [SP=9.7 Cap=22m]
Tribal (TRB) cloud contract wins worth £7.1m. Will add £1.2m to ARR by the end of 2022. [SP=102.15 Cap=214m]
U.K. SPAC (SPC) the Pound-shop version of US's SPAC fad agrees RTO of Hellenic Dynamics, a European medical cannabis cultivation co, for £45.2m in paper. "The proposed transaction is expected to value UK SPAC at a minimum of £11.76 million at the Issue Price, assuming the minimum net cash balance of £3.92 million on completion is achieved." Shares suspended. [SP=0.21 Cap=4m]
Sensyne Health (SENS) medical research dataset now 60m patients. [SP=150 Cap=249m]
In line: £
Not a small cap but another U.K. defence sector company Meggitt (LON:MGGT) being acquired for cash, in this case at 800p per share, over a 70% premium to previous close. Hot sector at the moment. I hold.
https://www.investegate.co.uk/...
Gus.