Small Cap Value Report (Mon 2 Oct 2023) - THRU, ACSO, XPP, BKS, PEEL

Good morning from Paul & Graham!
Now fully recovered from covid, I'm pleased to say that my summary spreadsheet is updated, and episodes 38 and 39 of my podcasts went out on Sat & Sun. So we're fully up-to-date, and raring to go!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
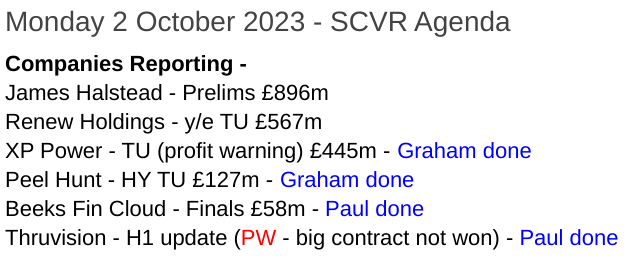
Thruvision (LON:THRU) - 29p (pre market) £43m - H1 Trading Update - Paul - AMBER/RED
A big disappointment today, I'm afraid. The large anticipated order from US Customs has fallen through. This blows a big hole in the revised forecasts, now showing another loss for FY 3/2024. Progressive reckons cash should be OK, if it can unwind some inventories & receivables, but risk of another placing has probably risen. Pity, as this company and its products look quite good, but it's too expensive now.
accesso Technology (LON:ACSO) - up 6% to 659p (£261m) - Share repurchase - Paul - AMBER/RED
I've just realised that I mis-read this announcement, thinking that it was announcing a large share buyback of 4m shares (total is 42m). However, it's actually a repurchase of £4m worth of shares, less than 2% of the total, so not as significant as I thought when I started writing this! I looked at ACSO on 20 Sept, and dislike that the company has spent its cash pile on acquisitions - when I don't see any evidence that its previous acquisitions have added value. Also I think there's a risk that companies making acquisitions might have run out of organic growth opportunities, possibly? [no section below]
XP Power (LON:XPP) - down 46% at 1286p (£250m) - Trading update (profit warning) - Graham – RED
A nasty profit warning from this provider of power supply products, whose awfulness is enhanced by likely debt covenant breaches. The company is “initiating dialogue” with its lenders. I am forced to take a negative stance on this today due to solvency concerns.
Beeks Financial Cloud (LON:BKS) (Paul holds) - Up 3% to 93p (£61m) - Final Results FY 6/2023 - Paul - GREEN
Results as expected. I like the outlook comments, dangling "potentially transformational" contracts at advanced stage of negotiations. That's enough to keep me interested, even though the existing business is only really trading around breakeven, once you adjust staff share options cost back in.
Peel Hunt (LON:PEEL) - up 2% at 85p (£104m) - Half Year Trading Update (in line) - Graham – GREEN
H1 revenue is in line at Peel Hunt: up 3.2% year-on-year. They have been involved in a large IPO (for “CAB Payments”) and should hopefully produce at least a breakeven result for 2023. The balance sheet should provide downside protection for investors here.
Paul’s Section:
Thruvision (LON:THRU)
29p (pre market) £43m - H1 Trading Update - Paul - AMBER/RED
The current financial year is FY 3/2024.
Thruvision (AIM:THRU, "Thruvision" or the "Group"), the leading provider of walk-through security technology, today publishes a trading update for the six months to 30 September 2023 ("H1 2024").
It’s bad news I’m afraid, so holders will need to brace for a potentially difficult day.
…the anticipated order from US Customs and Border Protection (CBP) did not get awarded in September, due to US Federal Government and Departmental budget challenges. Without the CBP order there will be a material impact on the Group's performance in the second half and for the current financial year as a whole.
With an encouraging pipeline of opportunities, it is anticipated that second half revenue will exceed that of the first half. However, without a CBP equipment order this year, it is unlikely that full year revenue will meet current market expectations.
Pity, as the rest of the update mentions some quite encouraging snippets -
H1 revenue £3.5m (up 27%)
Cash £2.3m at end Sept 2023
Major contract win with a new Asian customer (customs agency), and a new Central American customs agency - good validation of the products I think.
H2 revenues expected to exceed H1’s £3.5m, but less than expected due to not winning the anticipated big US contract.
Revised forecasts - have been put out via Progressive, and I’m afraid this is a big miss. Revenues for FY 3/2024 are slashed from £13.6m, to £8.1m. This results in a much bigger loss than expected of adj PBT £(3.2)m.
I would imagine that’s likely to put cash under pressure, so I think the risk of a placing just got a lot higher. Although Progressive reckons cash would be unchanged at £2.8m, which doesn’t tie together well with a loss of £(3.2)m. However, looking at the FY 3/2023 balance sheet, there’s clear scope to reduce inventories and receivables, which might allow THRU to absorb this year’s losses without needing more cash. Maybe.
Progressive suggests the US orders may now be deferred for a year.
Paul’s opinion - unfortunately I think this does a lot of damage to the bull case. FY 3/2024 was forecast to be breakeven at EBITDA level, but performance has now effectively gone backwards to similar to FY 3/2022.
Given this backward step, and the fact that it’s getting a bit tight for cash, then I don’t see how the £43m market cap can be justified any more. Pity, as THRU looks quite a promising company, with good products (that detect concealed objects as people walk through a scanner).
Last time I looked at THRU on 21 July, I was AMBER, and mentioned the dependence on US Customs as a risk factor. Today’s disappointment means we don’t have a lot of choice than to go down to AMBER/RED. It would need to at least halve in price to tempt me to have a punt on this, given the failure to win a key contract.
Beeks Financial Cloud (LON:BKS) (Paul holds)
Up 3% to 93p (£61m) - Final Results FY 6/2023 - Paul - GREEN
I last looked at this cloud SaaS specialist for financial markets here on 6 Sept 2023, when it issued a rather annoying FY 6/2023 trading update which tried to gloss over the reality that it had missed forecast revenue by about 10%. Canaccord clarified that underlying PBT of £2.3m was short of its forecast of £3.1m. It did however come with more upbeat commentary on the new financial year, which seems to have started well, and in line with exps for FY 6/2024.
Moving on to today’s FY 6/2023 numbers, here are my notes -
Revenue £22.4m (up 22%), roughly what was expected.
Underlying PBT £2.33m, again roughly as expected.
NB. Note that they adjust out £2.3m cost of shares based payments (for staff, not mgt), which I regard as a payroll cost, so I see underlying profit as being about breakeven.
Big contract in Johannesburg stock market has just gone live.
Record pipeline, some at advanced stage - potentially transformational contracts, which take time to deliver, as we’ve been told before.
Growth acceleration forecast for FY 6/2024 - Progressive note shows revenue rising from £22.4m to £29.1m - if achieved I think that could trigger a re-rating.
Paul’s opinion - this has been quite a painful long-term hold for me, but with a lower valuation, and encouraging outlook today (of growth accelerating, and potentially transformational contracts at a late stage of negotiation), I think there’s a catalyst here for a re-rating. So I’ll stick my neck out and say that, based on the facts, figures & forecasts we have available today (which will of course change in future), then this share looks quite attractive to me. So I’ll probably be adding to my position, when funds permit.
The balance sheet looks OK-ish, but this is quite a capex-hungry business, so I think it needs to focus new contracts on getting more cash up-front from customers, something we’ve discussed before.
It’s not the finished article, but Beeks looks to have good potential I reckon, and so far broadly speaking, so good. Very impressive organic growth has been achieved over the years, and in a bull market I think the market cap would be multiples of the current £61m. So good upside I reckon, but we’re having to be patient! The outlook comments seem to be saying we could see some nice big contract wins, which I think would be a nice catalyst for an opening bell jump. Hence why I want to be in this share ahead of possible announcements of that kind.
The main downside risk for me, is if revenues stop growing, and it just gets stuck being around breakeven.
Graham’s Section:
XP Power (LON:XPP)
Share price: 1286p (-46%)
Market cap: £250m
This Q3 trading update is a stark profit warning:
XP Power, one of the world's leading developers and manufacturers of critical power control components to the electronics industry, is today issuing a trading update.
The share price has taken a huge dive:

Key points:
“Weaker end-market demand resulted in some customers deferring shipments into 2024.”
“The economic uncertainty in China has also led to a reduction in demand in that market.”
Presumably using adjusted numbers, operating profit for 2023 should be “broadly similar to last year”.
Last year, adjusted operating profit was £42.9m (before exceptional costs relating to a lawsuit in the United States).
Checking recent forecasts from commissioned researchers, I see that the analysts were previously pencilling in an operating profit of £49.3m in the current financial year.
So we could be looking at a c. 15% reduction in forecasts. It has all materialised in H2, implying a serious deterioration in trading over the last few months.
One bright spot might be that hopefully the adjustments/legal costs will be less severe this time around. H1 results did not include too many adjustments.
Q3 revenues: down 2% year-on-year at constant currencies. That’s a sharp reduction from the revenue performance in H1 this year (plus 24%).
Order book shrinks further from where it was at the end of H1, from £250m to £225m.
The “book to bill” ratio (orders received vs. units shipped) was only 0.6x, as new orders failed to replace orders fulfilled.
A declining order book has been a trend since the industry’s supply chain problems eased, and it was not a worry at first. It was just the reversal of an unusual situation. But it’s becoming more persistent, implying a real slowdown. The company says:
While we have yet to see a recovery in orders from the Semiconductor Manufacturing Equipment sector, our customers’ outlook for 2024 and 2025 is encouraging, although the timing of the overall economic recovery remains uncertain.
Net debt rose last year after the loss of that US legal case. XPP had to pay large damages based on “unjust enrichment”, plus punitive damages. Net debt was £151m at the end of 2022, and fell slightly in the first six months of 2023.
Today we learn that net debt has risen again, to £163m, not helped by adverse foreign exchange movements. When it rains, it pours!
We now expect net debt to rise further by the year-end, reflecting a combination of the higher than planned capital expenditure on the Californian site relocation which will take place in late December, lower than expected revenue and profitability and a less than expected working capital reduction. In order to conserve cash, we have temporarily suspended the build for the new Malaysian plant, which will restart when the market outlook becomes clearer.
Banking covenants: current covenants could be breached in the near-term, so XPP is initiating dialogue with its lenders, to ask for flexibility (it does not say that it has been granted this flexibility yet). They are also exploring “other near-term options to strengthen the balance sheet”.
Dividends have been paid to shareholders on a quarterly basis; no more dividends will be paid this year.
Graham’s view
Checking the archives, I remember that XPP already received covenant flexibility from its lenders back in January of this year. So it’s not as if the company has suddenly started to struggle with the debt load; this has been an ongoing issue.
I took a neutral stance on the shares then, saying that investors could “probably” still have faith in XPP, but that deleveraging needed to be its top priority.
Roland also looked at the stock in August, coming to similar conclusions.
Unfortunately, and it may not be entirely the company’s fault, they haven’t pulled through with the required deleveraging this year. Net debt is up year-to-date, despite what looked like a decent profit performance in H1. The wheels have sadly come off in Q3.
It troubles me that the company didn’t say that it has already received covenant flexibility with its lenders. Typically, when we learn that a company is breaching its covenants, they immediately follow up with the news that the bank is cutting them some slack. That’s not the case here, so we are left with that uncertainty.
In a similar vein, they say that they are “taking appropriate actions to reduce costs and conserve cash”, but they don’t elaborate on the “other near-term options” they are exploring. Does that mean an equity raise?
I don’t like to switch from neutral to red after a severe share price decline, but sadly I am left with little choice here as this update leaves me with a question mark over the company’s solvency; if they need to recapitalise, then we could be looking at some serious shareholder dilution.
I also have to say that the size of this profit warning comes as a shock to me, and I find it hard to trust the explanation that macro conditions are entirely to blame.
For context, here is the total return for the Semiconductor Index (3-year chart):
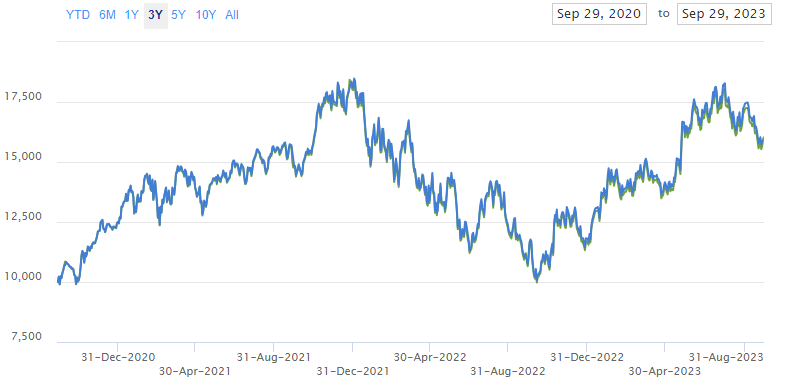
It’s true that this index has taken a dip over the last few months, but it was much lower last year.
So I’m concerned that there could be more to the story at XPP, as I was not aware that macro conditions were so severe.
While I still think there is a decent business at XPP, the fact is that they have flown too close to the sun when it comes to their balance sheet. The dividends, it turns out, were unsustainable (nearly £20m paid in both 2021 and 2022). Cash may now need to go in the other direction: from shareholders back to the company.
Peel Hunt (LON:PEEL)
Share price: 85p (+2%)
Market cap: £104m
Peel Hunt, a leading UK investment bank, today issues a trading update in respect of the six-month period ended 30 September 2023.
H1 revenues are expected at £42.4m, in line with guidance and up 3.2% year-on-year.
They refer to their “strong balance sheet” - as of March 2023, they had £27m of cash and £102m of total liquid assets.
Net assets at that time were £93m (compare vs. market cap of £104m).
The company also has access to a £30m RCF but it’s undrawn.
Like most small investment banks, the balance sheet here is rock solid.
Investment banking - they were joint bookrunner on the largest UK IPO of the year so far: Cab Payments Holdings (LON:CABP) which raised £335m. Revenues in this division are “significantly ahead” of H1 last year, but “overall deal activity remains subdued”.
Trade execution - revenues are “above pre-Covid levels”, but it sounds like business has been fairly quiet.
Retailbook - gradual progress with this joint venture. Peel Hunt is “hopeful of receiving regulatory approval for RetailBook to operate as a standalone entity in the coming months”.
Copenhagen office - will be operational shortly.
Outlook
Whilst exact timing of recovery cannot be predicted, there are encouraging signs that interest rate rises are bringing inflation under control, and we may be nearing the end of the current tightening cycle. We have the balance sheet strength and regulatory capital to weather the remainder of this cyclical downturn and are well positioned to benefit from the strength of our platform and considerable operational gearing as market conditions normalise.
Graham’s view
Only two years ago, this floated at 228p per share. That’s the difference between a bull market and a bear market: utterly different rates of profitability, and utterly different perceptions of the value of investment bank shares.
I’m going to continue to give this one the green light on the basis that it’s trading not far off its book value, providing downside protection, and there will be a bull market again, some day!
For 2023, I’d like to see Peel Hunt minimise the financial damage and grind out a breakeven result at a minimum. It looks like a marginal profit is currently in the forecasts. Given the lack of activity in the markets, that would be a fine result in my view.
We’ve already seen a good deal of corporate action in this sector: Numis getting bought out, and finnCap/Cenkos merging and changing name. We might see competition between banks continuing to weaken, the longer that these conditions go on, eventually setting them up for some bumper years when circumstances improve.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
ME International (LON:MEGP) Added Fujifilm's Japan Photo Booth business for $6.4M
Stock down 3.5% atm - I guess investors do not see this as good news?
momentary sell - now back on track -
XP Power (LON:XPP) XPP - 30-40 years ago it was always the thought that if a manufacturing Company ended up with an Accountant at the head, the best you could hope for was stagnation. You need some-one who understands the product and the processes involved in its manufacture. Without a change at the head, things can only get worse.
Zoo Digital (LON:ZOO) Stuart Green made a £50,000 purchase September 28th at £0.40 for what it is worth
Card Factory (LON:CARD) Telios still have 11.7% and Stuart Middleton, the former Creative Director (not sure if he still is but not on the Board), down to 2.6%. This is half the holding listed on current holdings on Stocko and I can't see any substantial shareholder list on the Card Factory site - or am I missing something?
XP Power (LON:XPP)
A horrendous 50% drop on today's profit warning. Without wishing to sound smug I have Stocko to thank for not getting caught up in it. After seeing the PW study my action changed from a previous "reaction is overdone, they will recover" stance to a much tougher one, although that has been difficult to do - no-one likes booking a loss. So, on 1/8/22 I sold XPP at 2500 on a PW - not easy as it had been trading at 5000 at the beginning of that year. Similar action getting out of Gear4music (HOLDINGS) (LON:G4M) on the 21/4/22 PW at 250 was something I had to force myself to do but looking back it was right.
So, for those who are newer here and have not yet come across it, this is what I recommend viewing:
A question for Ed and the team. Is it possible for PW to be traffic lighted on the individual company page?
Many thanks for uploading the webinar and as SC120 asks below it would be very useful if PW's can be flagged on the company page. Also a follow up webinar as several years have passed would be interesting
XP Power (LON:XPP) finishes down more than 50% at around £11.50. Definitely one to press the sell button on before the open and hopefully catch a bid around £14. Graham put out his report just as the shares hit their mid-morning bounce so some relief for holders who followed his advice promptly - thanks Graham. Probably big gains for those that catch the eventual bottom but a painful equity raise is surely already on the table in discussions with the bank - especially after this vote of no confidence from the market.
Any opinions/comments on YU.?
Happy customers make for sustainable profit
But have you seen the reviews for all the other energy suppliers?
You might find that Yu (LON:YU.) has the best rating out of all them, even at 1.8 stars!
Gulf Keystone Petroleum (LON:GKP) up 25% today on new of pipeline re-opening ...expect them to drop back tomorrow.For O&G fans worth trading this (long and short)
MS International (LON:MSI) (I hold) Contract announcement -
Another Day another RNS. Another DoD/USNavy contract.
The third USNavy contract within a month.
The first a 5 year support contract for the Mark38 mod4 weapon system over 5 years.
The second for the first production delivery of 15 MSI mounts for the mark38 mod4 system.
and today- a $15.8m for the Mark48 mod2 Electro Optic Sight (EOS) system.
I flagged in my post on Friday that i expected a separate annoucement for the EOS contract. It's come quickly. In my view the contracts for support, mount and EOS complete the current set - I don't expect further contracts to be rns'd under mark38 mod4 programme until the next production order - probably in at least 12 months time.
Does what it says on the tin? Very well done MSI!
cheers
Mark
Very undervalued for me, share price only about 5% up before last two RNS
MS International (LON:MSI) will be getting a nosebleed with all these RNSs
Step change indeed.
MS International (LON:MSI) have real momentum. You have to think that with the US navy giving them so many contracts the references and credibility they will get selling into other countries should be enormous.
This is starting to look more exciting than I’d hoped. Maybe I’m getting carried away but I would imagine eps is going to explode upwards. Minimal analyst coverage alas.
Hold £MSI. Seems to have an extremely well regarded product at the right tme. Unfortunately conflict does seem to be a part of human nature and more orders will be forthcoming to be used as defence against asymmetrical drone warfare.
Hi Paul,
Great Podcasts over the weekend. Well done for catching up, there's no gap now.
Avation (LON:AVAP) it’s not without risk particularly around interest rates but it’s been a mystery to a lot of us who follow this company whats keep it down and the recent announcement has let even one understand. There’s a general feeling it will move up now and some of the huge discount will close. That’s probably driving it today so far
Huge trade of some 15m shares late on Friday though. Suggest an overhang cleared
Who bought the stake Oceanwood sold ?
Dunno. It’s a big stake - about 20%. Clearly been holding the stock back so you’d hope that helps the share price move north if a new more supportive shareholder in the register
Avation (LON:AVAP)
I hold and the risk for me is the debt and capital repayments over the next 1-2 of years. As far as I can see they don't generate enough cash to pay this.
There are loads of assets though so they'll be able to sell something. That's clearly not an ideal business model,but they should pull through.
For me most of the upside probably won't come for a few years, unless someone buys them sooner. Either way, it looks like a cheap safe bet with lots of upside.
A
Avation (LON:AVAP) noticed over the weekend that a big overhang seems to have cleared. Share price up today so wondering if that’s on the back of that. Would be good if large stale holders have gone as share price should trend closer to NAV
Beeks Financial Cloud (LON:BKS) Looking forward to your thoughts on this Paul. I know a couple of years ago you thought it was one of the best opportunities in the UK market. Fast forward and clearly the heat has come off the shares (down over 50% from high) and there's clearly a mix bag. Revenue growth is good but not spectacular for a company in this market, the continue to cite an exciting pipeline but continue to struggle to convert them. Profitability is non existent and they continue to flag needing to invest in infrastructure and people although this announcement says a lot of this is now done and they can now start to scale into the profitable growth.
For me I have held this for five years now and am 7% down on my initial investment so obviously disappointing but not disastrous. I continue to believe as a very sticky cloud company this could in the end give me a very positive return. I continue to be happy sacrificing profit for growth but would be much more excited if this was 30%+ growth given the market and the opportunity. It'll get bought out one day I suspect and hopefully it'll be a few years time when revenue is up at 40-50m a year and should get a nice multiple on that. They might need another funding round before that.
I am holding and ok to continue
Hi Brookeda,
I hold Beeks Financial Cloud (LON:BKS) too. Loss before tax for the year of £620k. I'm not sure about these Share based payments of nearly £2.3m, thats 38% up on last year. I understand that it's to attract and retain staff (as per the Interview Paul did with management) but why not pay the going rate for the required expertise. Does the company need to charge more for its solutions to ever be profitable. If investements and expenditure, along with share based payments have to increase at FY 23 rates for each new exchange customer will they ever be profitable. I'm sure at the Interims meeting they said this was the year of profit. Looks like its now FY24. Will be on the FY Investor meeting.
I still hold as I believe the narrative for now.
I work in a SAAS company and large share options are normal. The reality is for the people you want to hire such as engineers you have to find a way of keeping them in and they work well when you lock people in for four years. Simply paying more cash would still leave them vulnerable to someone else coming along and offering 10% more. In this business people are hot commodities
Macfarlane (LON:MACF) (I hold) - Small bolt on acquisition of B & D 2010 group based in Southampton and supplying the defence and aerospace industries with protective packaging for £3.3m (x-earnout of 0.55m) on sales of £2.6m and adj EBITDA of 0.5m.
Looks to be another good bolt-on (third this year) and with 15% adj ebitda mgn is probably immediately earnings enhancing.
We are not told anything about the assets acquired and the FY22 accounts for B&D 2010 group are overdue (by 1 day so far) at Companies House. But the 2021 accounts reveal no long term liabilities. Hopefullly thats not changed and most of cash will likely have been taken out of the business prior to acquisition.
Although its a small acquisition in sales volume we're told its growing strongly. So MACF will likely pay the full £3,85m.
Ok. So far so good. But it's tiny. So whats got me interested here? Time for a little bit more of a deep dive into this acquisition.
https://barumanddewar.com/
Well it's not exactly your local supplier of bubblewrap and gaffer tape? It appears to be a hybrid one-stop shop for reselling quality protective cases, customising containers (anti-vibration, shock mounts and environmental monitoring) and bespoke container design and manufacturing for the defence and aerospace sector.
I have some experience in this area as a customer. Can be a very sticky business. When you are shipping out space hardware you don't tend to get 3 quotes and go with the cheapest one. It's a long term relationship with a lot of trust in it, and often calling for a quick turnaround of bespoke containers. with good margins to match if you establish a good reputation,
Right at the moment the aerospace/defence export market is booming. Looks like it will be for some years to come. And a lot of the kit being exported includes sensors, comms, demining equipment, test equipment etc. All of which needs the right packaging when in use not just for delivery, MACF already have some aerospace exposure through their manufacturing division - and Barum and Dewar looks to be an excellent operation to accelerate MACF sales in this sector globally as well as in the UK. I see from the website that B&D attended the recent DSEI 2023 expo - a good indication that they already have brand recognition in this sector. An interesting picks and shovels approach?
I continue to be extremely impressed by long term MACF managements ability to grow their business both organically and through acquisitions which integrate well.
It also seems that they very good at thinking out of their boxes ? If you'll excuse the pun?
Macfarlane (LON:MACF) is my second largest holding (I've held for many years and slowly increased my holding) and this acquisition is perhaps the best pointer yet to why I believe the company is differentiating itself from its peers and will - eventually - be rated accordingly. If I had cash to spare I'd be buying, but then I seem to be surrounded by so many other good opportunities right now!
cheers
Mark
Macfarlane (LON:MACF) has been a frustrating share for me to own so far.
Seems a nice stable business though, and they've been improving their margins. Dividends have been compounding at 10% pa over the last few years. Good return on capital. FCF yield is about 17%. Seems that patience is required.
Gulf Keystone Petroleum (LON:GKP) up nearly 30% this a.m. I hold. There is an RNS but it is unreadable, the implication is there is some insider buying or an update on a legal dispute. Anyone know the reason? As background this is a high risk but value share that produces oil in Iraqi Kurdistan. Their pipeline to Turkey was closed after a legal dispute with the Iraqi Govt.
A Turkish chap has said that the pipeline will reopen this week.
https://www.jpost.com/breaking...
Maybe! My default position on this is that I trust none of these, frequent, announcements that the pipeline is "about" to resume exports. So far that's clearly been the correct position to take. Is it different this time? Perhaps, perhaps not. The attractions for anyone trying to manipulate the news and share prices are obvious. When GENL or GKP issue an RNS I'll take note. Until then ...
Genel Energy (LON:GENL) also up 11%
It is to do with Turkey saying they will reopen the Iraq / Turkey pipeline this week. Obviously has a material impact on both companies particularly as there is also agreement between Iraq govt and Kurds.
Of the two companies I have a slight preference for Genel Energy (LON:GENL). Don’t hold either at the moment but if the pipeline reopens could be an interesting play as dividends alone should exceed 10%
Gulf Keystone Petroleum (LON:GKP) Genel Energy (LON:GENL)
“The problem you’re going to have is if the pipeline opens and there is no commercial solution on how to repay the IOCs that are producing that oil, then you’re going to have an empty pipeline and we’re not going to put oil into that pipeline,” from: https://www.rudaw.net/english/interview/01102023
The pipeline through Turkey is only part of the problem that oil companies face in Iraqi Kurdistan. Iraqi courts invalidated contracts between Kurdistan and IOCs (e.g. Gulf Keystone, Genel) in 2022. https://www.reuters.com/world/middle-east/iraqi-federal-court-deems-kurdish-oil-gas-law-unconstitutional-2022-02-15/ For Iraq, there is no existing legally enforceable contract that enshrines the rights (to the oil, to a specific level of payment, etc.) of international oil companies.
If there are no major contractual changes, GKP appears to be a bargain. At the moment there is a temporary agreement between Iraq and Kurdistan which provides for oil revenues to be paid into an account both governments control until the Iraqi parliament passes new oil laws. https://www.aljazeera.com/news/2023/4/4/iraqs-govt-signs-deal-with-krg-to-resume-oil-exports and https://www.al-monitor.com/originals/2023/04/iraq-kurdish-region-sign-accord-resume-oil-exports
The Turks say that the pipeline was damaged in the earthquake. I am under the impression that the repairs needed are minor but I have not found a reliable source for this.
Some background info previously posted: https://moram.eu/oil-companies-kurdistan/
disclosure: No relevant companies are currently owned.
Anyone have access to the Liberum note on Yu (LON:YU.) post results last week? What numbers are they forecasting for this and next year? SP has responded positively since the update.
Re Hostmore (LON:MORE) turnaround following update last week. I hold.
A year of change incl. all the board etc... where covenant test on debt had to be waived and debt extended....whilst reorganisation of the business took place. Initially received well due to cost cutting measures announced but then, following a trading update on 7 June, the shares tanked because revenue performance had deteriorated. Revenues in the first 16 weeks were up 2% adjusted for VAT changes on a LFL of -1%. For 22 weeks these numbers were reported as -1% and -3% and the market freaked out because of the implied 6 week week performance looking like -8%.
In the interim nos the LFL Revenue improved a little to -2% from -3% but still a bad number. Clearly the numbers are pinging around a fair bit if they can add 1% in 4 weeks. Importantly though, H2 to date is running at +2%. So total implosion of business would NOT appear to be happening. A small tick esp given the CFO resigned a few weeks ago justifiably prompting fears of further weakness.
Cost reduction plans have improved from £5.9m to £8.2m. In 2023 £5.8m will be delivered. So +£2.4m in 2024. The losses from the bottom 20 bars have reduced to £1.5m from £4.2m.
CRUCIALLY net debt came in at £31.3m versus £32.2m expected which includes an additional £0.3m cost to achieve the savings. For a company failing to meet prior covenant tests and looking to renegotiate debt levels this is fairly important. Some further adjustments have been made to covenants to align the facility with group forecasts....I guess positive but let's face it, they are not out of the woods here by any stretch.
So what does all this mean...new openings are on hold saving them £15m Capex per year. H1 should be the nadir. H2 last year was also bad...feeling the real brunt of inflation etc....and therefore my expectation is an improvement on H1 last year. I get this by taking H2 EBITDA numbers and adding £4.3 stated cost improvement plus £0.5 Edinburgh and Manchester losses that won't be suffered following closure. So £18.1m EBITDA and £9m EBITDA after leases. Hmmm we haven't got a net debt forecast for the year end so not sure what that might mean cash flow wise.... but better, in the 20s..lets hope under £25m. Looking to 2024... with little for Revenue just adding the additional costs coming through I think you are back just under £200m of revenue.... with EBITDA £38.9m and EBITDA after leases £19.1m....which is basically adding £2.4m costs and removing losses from Edinburgh and Manchester and using H1 22 as a benchmark not H123. That might be a stretch BUT if this is where forecasts lie ( I haven't seen any notes) then I would argue the cashflow projections have credibility and they could pull off the debt reduction they are going for.
So apologies, a lot of proforma in there...but then thats what you would expect and have been guided to. The shares are on their knees, in technical breach of covenant. BUT they could trade at a very low multiple of EBITDA and be paying down debt rather quickly. The quality of the business model re Franchise agreements now massively helped by the waiver of new openings. New openings are a normal part of rent negotiation for all restaurant groups.
The point to the recovery is Free Cash Flow and since that goes to pay down debt....it is all accretive to equity. Not wasted on expansion that may or may not work. So if the business achieves its target of £10m FCF then the equity market cap can rise by at least this per year....which is an amazing return. That's why recovery can be interesting.
Obviously they are not out of the woods as I have said but the largest shareholder is Chairman. I think they will be supportive and therefore I don't see a huge deficit of funding on the register. This means contrary to some views that a huge discount will NOT be needed should additional equity be needed. Why? Normally such large discounts are demanded by new shareholders who don't care about existing holders dilution. It's an automatic transfer of value to the new funders. I don't think this is the situation here.... so it's a misunderstanding to suggest a huge discount might be on offer.
My last point would be if you have held this stock its no doubt a small part of your portfolio, almost riskless. If you buy it here it would in a small amount to reflect the risk. You can see how it goes calmly because you have most likely suffered all the pain. Contrary to media coverage institutions rarely sell the bottom draw stuff because it has so much optionality, they don't care about losses they have already suffered. If a share that has fallen 90% goes to zero you have only lost 10% of your initial investment. If it recovers you could reduce those losses significantly. Thats just the maths.
Good luck to all of you.
Frankly I got as far as "Refinancing process commenced with existing and potential new lenders, expected to be concluded by end of Q1 2024" in the interims. Not sure why anyone would even consider it until this is completed.
"Contrary to media coverage institutions rarely sell the bottom draw stuff because it has so much optionality, they don't care about losses they have already suffered. If a share that has fallen 90% goes to zero you have only lost 10% of your initial investment. If it recovers you could reduce those losses significantly. Thats just the maths."
That may be the mindset of institutions who're using other people's money, but private investors who think like that are training their brain to be losers. Any half decent private investor should easily beat these sloth like small cap funds. They're trapped, we should sell early. If it goes to zero everyone loses 100%.
Whilst true it's not really pertinent because the shares are where they are. Sometimes things deteriorate so quickly you never really get a chance to sell. Or you just make a mistake.
I question a decision to sell here that's all, when you have already lost 90%. The risk reward here is actually more akin to a call option.... and massively positive. I don't think you are training your brain to do anything apart from an analysis of the current situation rather than one that doesn't exist. I would suggest not selling and/or a position size 10-20% of normal is appropriate at this stage to reflect obvious risks.
Apart from a brief blip in July I'd say the whole of last year was screaming sell. Any number of of new lows made, price couldn't get close to trend for much of the first half. Even the gap down was surely a point to sell.
Everyone makes mistakes, I had several of these in the dot-com meltdown. Best thing to do for any pi is promise yourself to never allow it to happen again.
Never the less this only tells one what one should have done...not what one should do...which is the name of the game. Turnarounds start before the trend.
Indeed. Hope it does well for you.
XP Power (LON:XPP)
I don’t really mind the profit warning. These things happen. What I mind is that, only 2 months ago, management was confident of meeting forecasts. It can only be incompetence or self-deception - I’m stopping short of accusing them of deceiving investors and financiers, others wouldn’t be so generous.
I mind the 45% drop!
I mind the 45% drop!
Well, yes. I share your pain. Sold for a 40% drop and a 25% loss this morning.
Yes, it's hard not to wonder if there isn't more to this morning's profit warning and fall off in orders.
With the 45% share price fall I'd be tempted to take a punt were it not for the debt position. As it is, too risky until further information comes forward Best of all, would be an equity raise, though this would be bad for existing investors.
I've had XP Power (LON:XPP) on my watchlist for ages. Just liked the good ROCE and cashflow figures. Assumed this was a manufacturer of a vital product with reasonably steady demand. Today's TU makes me wonder if I was wrong about the character of XPP's markets.
Today's TU makes me wonder if I was wrong about the character of XPP's markets.
Looks far more commodity-like than management would have us believe. I’m accustomed to the cyclicality of the semiconductor market. But the IP inherent in OEM’S products tend to ensure a 150% bounce off a 50% fall. Not so for XPP which might bounce 400% some day in the future. But who knows from what low base? And only if the company survives, which must be in question. I’m out as management clearly can’t be trusted.
My morning smallcap tweet: The Stung Ones
Peel Hunt (LON:PEEL) Thruvision (LON:THRU) EFG Holding (LON:EFGD) Versarien (LON:VRS) XP Power (LON:XPP) Beeks Financial Cloud (LON:BKS) Taylor Maritime Investments (LON:TMIP) Proteome Sciences (LON:PRM) Arecor Therapeutics (LON:AREC) Futura Medical (LON:FUM)
◄Peel Hunt (PEEL)► guides H1-Sept rev up 3.2%, in line. Costs have increased broadly in line with inflation, so profit down I guess. [SP=81.2 Cap=102m]
◄Thruvision (THRU)► H1-Sep rev up 27% but warns FY rev unlikely to meet market expectations. Expected order from US Customs and Border Protection did not get placed in September, due to US Federal Government and Departmental budget challenges. [SP=29 Cap=43m]
◄EFG Holding (EFGD)► Valu (Buy-Now, Pay-Later service) to launch in Jordan in Early 2024. [SP=NA Cap=NA]
◄Versarien (VRS)► throws holders some straws to clutch at. [SP=1.17 Cap=4m]
◄XP Power (XPP)► warns FY-Dec below expectations with op profit broadly flat. Q3 rev c.£75 down 2% due to weak Chinese demand. Expects covenant breach in the near-term. Exploring options to strengthen the balance sheet. Placing?. No further divs. [SP=2360 Cap=466m]
◄Beeks Financial Cloud (BKS)► FY-June rev up 22% and U/L pretax up 13%, better than guided.. Guides FY24 in line with mgmt expectations. [SP=90 Cap=59m]
◄Taylor Maritime Investments (TMIP)► to get $32.44m from subsidiary reduce debt and for general corporate purposes. [SP=73 Cap=297m]
◄Proteome Sciences (PRM)► launches SysQuant SCP, a commercial service for single cell proteomics. It "can identify more than 1,000 proteins in each study of 576 single cells and provides novel insights into individual cell biology and heterogeneity". [SP=6 Cap=19m]
◄Arecor Therapeutics (AREC)► increases the number of subjects in its Phase I clinical study of ultra-rapid, ultra-concentrated insulin candidate AT278. [SP=195 Cap=59m]
◄Futura Medical (FUM)► European patent for MED3000 aka Eroxon to 2040. [SP=42.5 Cap=128m]
Card Factory (LON:CARD) Only noticed this morning that RNS on Friday showing top shareholder, Teleios is still reducing their stake. Explains why share price hasn't really reacted to last week's good news yet.
Great podcasts at the weekend Paul, thanks for continuing to give up your time for these invaluable round-ups.
I did some research on Card Factory (LON:CARD) over the weekend after the comments from Paul and others on here. With impeccable timing I then had a read of Cockney Rebels exceptionally detailed analysis of CARD in his weekend blog. I know Rebel is a big holder and bullish but numbers are numbers and he put across an excellent investment case so thankyou Rebel for taking the time to share your thoughts - much appreciated. Aside from Teleios selling down, I really can't see anything else that is holding back the SP. That will, at some point, stop and when it does I can only see the chart going in one direction. (I held...as of this morning, I hold more).
Hi Ben Hazzard,
Yes I agree with all of that re Card Factory (LON:CARD) (I hold). I'd actually also be interested to hear from anyone who takes a more bearish stance on this share, because everyone seems to bullish (including me!) that we could be in danger of creating an echo chamber, and miss something important on the negative side.
As you say, the only negative is that big shareholder Teleios is constantly selling. Once they've finished, and the overhang has cleared, it stands to reason that the share should re-rate upwards. My target is 150p, which I think is reasonable.
Value hiding in plain sight, I'd say. Richard Crow's analysis is spot-on I think.
Regards, Paul.
Hi Paul - whilst I don’t necessarily disagree with the analysis I think the share price reflects a couple of things
1) physical retail is not commanding reasonable multiple in todays market. So a PER of 7 today isn’t far away from comparators.
2) throw in net debt and that becomes riskier and implies higher than 7
3) poor history means stale bulls
I don’t hold but am looking for an entry sub 100p if I can get it. I think Teleios will continue to sell, but in reality the 150p plus target is dependent on continuation of strong lfl performance, paying down debt quickly and reintroducing dividends. Those may well all come true but are also in the future so uncertain.
Different business obv but compare against Ten Entertainment (LON:TEG) which is growing lfl has a net cash position, already pays good dividends but is trading around the same multiples.
So I don’t think the Card Factory (LON:CARD) story is a bad one by any stretch from a bear perspective but in the current market just faces headwinds to a re-rating much like some other quality businesses out there.
Hi Paul . I did own Card Factory Shares a few years ago but I reasoned that they were fighting a strong headwind of continual postage price increases.
Mortimer - Re Card Factory (LON:CARD) and a "strong headwind of continual postage price increases." Really good point we should ask of management: what % of cards are hand delivered vs posted vs online. Previously, I have focused only on the shop bought vs online split.
Not sure management will have a clue once you walk out the shop with your card.
In our household, most are hand delivered, and for those who live ooop north, they are sent "en block" when someone is visiting .
Very rare one actually gets a postage stamp.
As the Global Head of Birthday Card Procurement in my household I think the on line offering is very poor compared to moonpig/funky pigeon/etsy. In addition it's been poor for some time which suggests to me either they haven't got the wherewithal to improve the offering or its not perceived as valuable enough to justify the investment (perhaps due to low prices/basket value), which is an interesting data point on its own.
I was also disappointed to see Card Factory (LON:CARD) invest in South Africa in one of its first forays into overseas growth. I struggle to see the attraction of investing shareholder money in a country with currency controls/repatriation taxes as well as currency and geopolitical instability (e.g. the cost of insuring a shop must be much higher than in the UK). If there were no better options for overseas expansion, I think that raises a question about the overseas growth potential of the business.
In summary, it's been a cracking turnaround story but for me questions remain about growth potential beyond physical retailing cards and gifts in the UK. In my opinion though that home market is probably enough for £1.50 at some point in the not too distant future.
I hold.
Hi Paul, thanks for the podcasts thumbs up. You mentioned game developers, I haven't seen it mentioned here but I wonder whether recent share price falls have been linked to the announcements by Unity, a pretty widely used game engine used by lots of the 'indy' developers. They retroactively changed their pricing structure recently, where fees can be charged to games that have already been sold regardless of the license agreement that was in place when they were developed. There has been quite alot of noise in the industry and Unity have 'clarified' (watered down) their position - but still it could be quite a material (and unexpected) cost for developers.
Morning cheeky_minnows,
Yes, actually we have picked up on the general theme that games streaming companies seem too have worsened their payments to games developers. I recall at least 2 of the poorly performing games companies mentioning that as a factor, but not the specifics of which platform(s) had done this. So interesting that you mention Unity, thanks for that. As I mention in the podcast, there does seem to be an industry headwind impacting the smaller games developers, another reason to steer clear, as it looks like some of them are only really hoping to get to breakeven or a small profit. I really dislike the business model too - heavy up-front capex on intangibles, then a relatively short burst of sales, with no idea how well a new game is going to sell! Couldn't be a lot worse actually. I suppose the attraction is for larger games companies that have "franchises" that they can repeatedly milk with updates?
Regards, Paul.
Re: smaller developers, this year has also been a bumper year for AAA+ titles (i.e. the very biggest and best) which, combined with large companies cutting back on investing in their platforms/catalog of games (XBOX game pass, PlayStation Plus) and generally higher costs (staffing, the Unity news) has just meant it's a really tough trading environment for the smaller devs who don't have the cash surplus to buffer against poor performing titles.
I think this will unwind, particularly for companies who do produce better quality games, but I am coming to terms with what Paul has mentioned in his comment - the business model isn't great. Large upfront capex which gets hidden in the balance sheet with really varying and hard-to-predict returns. This annoys me, as it's one of the few industries I know more about, thanks to being a bit of a nerd!
Great podcasts thanks. Glad you’re better Paul.
Absolutely classic weekend podcasts Paul, particularly the first where you reflect on the tiny déclassé minority among the reader community and their facile attempts to undermine you and civilised debate - “eff ‘em” indeed!
LOL yes my podcasts are not scripted, so anything can happen (and often does!!) :-D