Small Cap Value Report (Mon 20 April 2020) - Covid-19 update, DFS, AML, PFD

Good morning! Graham here.
Covid-19 update
I've already written lots about this subject. It's the topic right now.
Since I last wrote about it in the SCVR, the most important news stories and things I have noticed are:
- The UK lockdown was extended for 3 weeks, to the first week in May. The PM continues his recovery.
- We can look forward to a staggered reopening of the European economies. It is likely that schools will open first in most countries, and the hospitality industry will open last. See the most recent proposal by UCL economists.
- New cases and deaths with the virus are falling pretty much everywhere, according to official data - see Worldometer.
- The capacity of the healthcare system has not been exceeded in the UK, nor in most other countries (but patients with other conditions have not received their scheduled, elective treatments).
- Localised studies show high levels of asymptomatic infection and the buildup of antibodies in local populations.
- Demonstrations against the lockdown policy have started taking place in the USA, Germany, Israel, and India. The severe economic consequences of lockdown are causing millions of people to go hungry, including in the UK.
After all of this, the FTSE has roared ahead to c. 5800.
I was very bullish around 5000, and I still have a long trade on the index (opened a few months ago), but I'm currently neutral in the short-term.
Even if the policy of near-total lockdown ends soon, I don't believe that we will get the pre-Coronavirus economy back straight away.
For a start, there are likely to be social distancing rules and guidelines for a long time. These could be a major drag on the retail, leisure and hospitality sectors if they limit customer numbers or if they cause some people to deliberately avoid places where crowds may gather or where irritating rules have to be followed.
Secondly, I don't see how the unemployed and furloughed masses will be able to start spending again soon. For those living from paycheck to paycheck, even a 20% pay cut (if they are on the UK government's job retention scheme, for example) is a major blow to their spending power.
A severe financial shock can have long-lasting effects both on an individual, and on the wider economy. We have just witnessed a financial shock like no other.
In the US, 5.2 million more people filed for unemployment last week, bringing the total jobless to 22 million.
It is now thought by economists, in advance of the official numbers, that the US unemployment rate may be in the region of 15% already - the highest unemployment rate since World War 2. The longer that lockdown persists, the higher this number will rocket.
The US labour market is generally more flexible, and so it is possible that many of the unemployed could be hired again quickly once the lockdown is over.
But as I keep saying, many of these people, and their counterparts in Europe, will need to repair their personal balance sheets:
- they will be behind on their mortgage or rent, and their credit cards/overdraft.
- their employers (particularly in travel, leisure and hospitality) will be restarting from a position of weakness and in no mood to pay high salaries.
- people might also worry about lockdown coming back, if there is a "second peak".
Against all of that, we have the prospect of very high money-printing by central banks. Which makes it rather difficult to hold cash.
One company which does hold lots of cash is Berkshire Hathaway ($BRK.B) (in which I have a long position). There are no signs yet that Berkshire is making any major investments at the present time - which is interesting, to say the least.
I'm still holding all of the shares I did before this crisis kicked off, and have no plans to sell anything. I do expect that lockdown will end soon, perhaps when the data around the virus becomes more widely understood but (more likely) when most people can't bear the economic consequences of this any longer, and start putting pressure on politicians for change.
If you're not comfortable with all of this uncertainty, there is no shame in heading for the exits and holding cash instead, until this is over.
A popular tweet from yesterday:
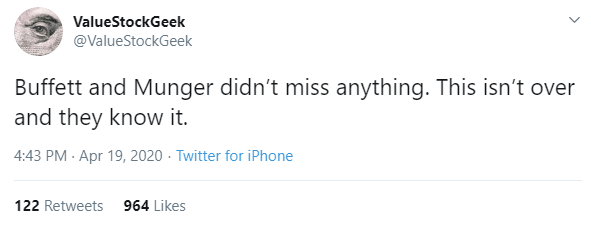
Right, onto some small-caps...
- DFS Furniture (LON:DFS)
- Aston Martin Lagonda Global Holdings (LON:AML)
- Premier Foods (LON:PFD)
Finished at 3pm. Not covered: NAHL, PHD.
DFS Furniture (LON:DFS)
- Share price: 147.19p (+12.5%)
- No. of shares: 213 million
- Market cap: £313 million
Paul looked at this furniture company in January. He ruled it out, because of its "absolutely diabolical balance sheet". Good call!
Net debt was last seen at £160 million (interim results).
In a March CV-19 update, DFS said it had headroom of £70 million, implying that it had used up around £180 million of its £250 million debt facility.
In that update, it highlighted the potential of a cash crunch, since a large supplier book (£100 million) needed to be settled. Deliveries to customer are suspended, so DFS is not getting paid for outstanding orders.
Today's RNS
DFS confirms that it is negotiating a new £60 million - £70 million facility, which is basically to let it pay its suppliers ("near-term working capital unwind").
It also wants to dilute shareholders by up to 19.9%, with an equity issue.
At the current share price, that would raise £62 million.
In combination with the new debt facility, that means DFS would be able to pay its suppliers and plug the near-term hole in its finances.
Cash burn is reduced to £14 million/month following discussions with suppliers and landlords. Showrooms, manufacturing and distribution remain closed.
Trading - the website is still open and taking orders, and some warehouse activity is taking place.
Online orders are up 20% but of course there are zero purchases taking place in-store at the moment.
At the interims, online sales were less than 20% of the total. So the increase in online orders does not come closed to replacing the large quantity of lost in-store orders.
Outlook
The combination of the proposed additional financing together with the operating cost mitigation measures is expected to, when agreed, give the Group significant liquidity to see through an extended lock-down.
My view
If you liked DFS before this crisis, then you might like it even more at current levels, after the share price has halved.
And from the point of view of the banks, if they see shareholder support for an equity raise, then I imagine they'll be comfortable extending a short-term loan.
The equity is superficially cheap vs. normalised earnings and, like other retailing shares, could prove to be a multi-bagger in time.
But it doesn't interest me at all. For the reasons outlined in my macro update, I'm gloomy on consumer spending, especially big-ticket items.
This company could spend years focusing on the management of its debt load, during which time profits could easily be de minimis or negative (remember that it's an operationally leveraged, low-operating margin business).
I think it's likely that this will have to be run on behalf of its lenders.
Aston Martin Lagonda Global Holdings (LON:AML)
- Share price: 55.775p (-4%)
- No. of shares: 1,520 million
- Market cap: £850 million
Statement from Executive Chairman, Lawrence Stroll
Aston Martin has been recapitalised with a huge fundraising: 1.2 billion new shares following a 4 for 1 rights issue. This means 4 new shares were offered for every share that was previously outstanding.
The pricing for the 1.2 billion new shares was just 30p, ensuring that the rights would be taken up.
A large new consortium of investors has taken control, headed by the billionaire Lawrence Stroll. He is taking Aston Martin back to Formula 1 for the first time since 1960.
The total new equity that has been raised is £536 million, as announced at the end of March.
Net debt as of the end of 2019 was £876 million. Without the capital raise, there would have been an "immediate liquidity shortfall", and AML could have been forced into administration or liquidation "shortly thereafter" (1st Supplementary Prospectus, p. 6).
Working capital
The following statement appears in the 2nd Supplementary Prospectus (p. 1). The bold is mine:
Taking into account the proceeds of the Capital Raise, the Company is of the opinion that the Group does not have sufficient working capital to meet its requirements for 12 months following the publication of the Original Prospectus. This is due to the increased impact, since the Company published the First Supplementary Prospectus on 13 March 2020, of COVID-19 and the ongoing and unquantifiable uncertainty it has created and continues to create.
They go on to say that they do have sufficient funding, because of various other options and facilities they have - such as inventory repurchase arrangements and possible support packages from government.
What I think this means is that the £536 million capital raise alone is insufficient to ensure survival, but in combination with other measures, the company will be able to survive another 12 months.
My view
Aston Martin has gone bust seven times in its history. It would almost certainly have done so again, if not for this rescue package.
I understand the attraction of these shares as trading counters, but what are the odds that AML won't go bust an eighth, ninth and tenth time?
I would treat these shares in the same way that I do the shares of Manchester United ($MANU). They are a luxurious holding of the super-wealthy, and are unlikely to make anyone rich who wasn't there already.
Premier Foods (LON:PFD)
- Share price: 39.85p (+22%)
- No. of shares: 848 million
- Market cap: £337 million
Strategic review, pensions and trading update
I've just checked the archives, as I always do, to see the most recent comments on this share.
Funnily enough, Premier shows up in a November 2011 article by Ben, titled "How to avoid investing in distressed stocks". Not investing in Premier would be a good start, apparently!
Today, it announces the conclusion of a strategic review which began over a year ago.
The main idea is that it is merging all of its defined benefit pension schemes together, so that the surplus of one of them ("RHM") can fund the deficits in the other schemes, after a buyout.
There is the potential for "significant reduction in future pension deficit contributions".
Premier thinks that future annual deficit contributions, from FY 2024, could be between £17 million and £30 million (down from the current £38 million).
There are also immediate savings on expenses from the plan, worth £4 million p.a.
If I'm reading it right, the total annual savings will reach between £12 million and £25 million, by FY 2024.
Trading update - FY March 2020 will be at the top end of expectations.
This is the first update from Premier since the C-19 crisis began, and perhaps it's to be expected that it had a good year? Its brand portfolio looks perfect for the eat-at-home, cost-conscious culture we are currently living in: Ambrosia, Batchelors, Bisto, Oxo, Sharwood's, Mr. Kipling, etc.
Sales in March were up 10.5% year-on-year (up 15.1% in the UK).
As an essential service, Premier's manufacturing and distribution operations are working "at maximum capacity".
While the initial bulk-buying panic is over, Premier expects to see continued strong demand - everybody has to eat at home, so home cooking ingredients are needed more than ever.
Leverage has reduced - trailing net debt/EBITDA is "comfortably lower than the previous 3.0x target". The cash balance is £177 million, after drawing down nearly half of its RCF.
My view
It's an excellent update. Great news on the pension schemes, on trading and on liquidity.
The September 2019 balance sheet showed an accounting surplus of nearly £600 million (pre-tax) in the aggregate, across its various pension schemes.
Management signalled that they might start to have breathing room soon:
Looking a little further ahead, the Group is starting to see options regarding its future cash deployment, especially in light of its disciplined and consistent track record of Net debt reduction.
But the net debt position was still very large at £470 million (versus adjusted EBITA of £51 million). It will be good to know what the latest figure is.
Overall, I'm neutral on Premier. It's working through its balance sheet challenges, and has the potential to come through on the other side.
That's it for today - back tomorrow!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
Graham
Thank you for your write up on £PFD. I agree the net debt are BS are complete disaster areas but do think yesterday's RNS mean its wrongly priced.
Cheers, Martin
For posterity may I record that May oil finished at minus 37.63 dollars a barrel. First time negative in history. Will not be the last I guess.
The negative rate reminds me of a story at the bottom of the recent dip. Buy shares in oil tanker and oil storage companies as capacity will run out. Another idea I didn’t follow
You are not alone ezlifeme, I too saw people discuss buying tankers/storage plays but completely ignored it, due to multiple rules/biases (don’t invest in O&G, don’t invest outside my circle of competence, don’t invest directly in US holdings). All sensible rules that generally keep me out of trouble but on this occasion, a clear opportunity missed. Hey ho! Hindsight investing is always the easiest.
Cheers
Simon
Also for posterity, this is a chart I am going to forget any time soon.
Very good article on AML - Small investors should be careful
Paul has explained in simple English
As we seem to be having another virus focus day today, here’s an interesting one for the data crunchers amongst us. Please move on if you don’t enjoy data-mining ! But like-minded, data-driven souls may too find this intriguing, and it may help with pass a couple of lockdown hours….
I believe I am right in thinking that the press and TV report “daily COVID-19 deaths”. And there follows much debate about approaching, being at or past the peak, although focus now seems to have moved to a 2nd peak – interesting in itself. All of this informs debate on lockdown duration and restarting the economy.
It is now clarified that the data is hospitals only, and is drawn from NHS statistics in which England numbers dominate the total, and are freely available at https://www.england.nhs.uk/statistics/statistical-work-areas/covid-19-daily-deaths/
But this data is not daily death data – rather it is daily released data showing which deaths have been coded as COVID-19 over preceding days, as far back as the earliest change.
So the data released yesterday shows the total deaths coded / re-coded as COVID-19 spanning back to March 20th, data released on 18th April shows coded deaths spanning back to March 14th etc. A very different statistic to “Daily Deaths”, and nowhere close to being a sexy headline in the media.
This attracted my interest so (as I am bored today) I collated all the daily data available on the links, and arranged it by calendar day, to see how long it takes to form a (mostly) complete daily total – about 14 days in fact – and what this cut of the data shows. My view is that “real” daily deaths for 19th April will not be known (at least unless the “lag” which keeps being discussed is removed) until about the 3rd May, and consequently, and by manual totalling, 4th April is likely the most recent accurate total.
However, as the data appears surprisingly consistent, at least in terms of an 80:20 build of the total, it is possible with a bit of trend analysis and extrapolation to form a view on the likely daily counts, and on the peak. Check it out and see what you conclude. I’m all set to check my assumptions daily now, as each new day’s data is released.
I am not qualified to make public pronouncements or predictions, and am in no way trying to dilute the impact, seriousness etc. of the situation and its impact. But I like accurate facts and data, and do think that the press and TV should be giving the nation a true and balanced view to help us all rationalise things, and ultimately make decisions – exactly as the good folks here on Stockopedia do for companies, and apparently the Swedish do for their citizens.
Apologies to those expecting a bombshell conclusion, but I did say at the start to move on if not data mining inclined! Just as with analysing companies, this kind of exercise helps me better understand the changing narratives and actions, and form my own views as to likely outcomes - and whilst we all agree doing that on companies is futile at the moment I like to keep my brain sharp.
Would love to see your chart/sheet!
(From Mr C this morning): "Easyhotel (EZH) to cancel listing on 19 May because listing costs are disproportionate to any potential benefits.
Is this a harbinger of things to come. Several of my small caps are now VERY small and if they do see a way to raise new capital by exploiting AIM (and still see a future), then their listing must be in doubt.
Hi Rhodie Jonners,
I have no knowledge of Warpaint per se but a large spread is usually a function of illiquidity. It tends to happen with micro/small caps where there is low volume and will be exaggerated when there is a small free float of shares. 25% is pretty bonkers though for a £30m company, are trades going through within the spread?
Hope this helps,
Simon
Re Warpaint London (LON:W7L) spread- perhaps the below helps explain (see Accounts Tab, Major Shareholders) 2 Individuals hold 25.34% each, 4 other listed major holders. Thats 79% tied up
That’s interesting because stock report says 48.49% is free float, which tallies, but the 4 institutional can sell at any time and so can the 20% remaining outside the institutional holders, so sort of 60% is free? I still think with average daily volume of in excess of 100,000 shares per day, there should be enough liquidity for the spread to be far lower than it is. Perhaps they need to have more than 1 broker? Really appreciate your input, it does explain a lot.
Rhodie you are most welcome - One newish area of the Stocko data set I always refer to when DMOR
Warpaint London (LON:W7L) trades on a spread of 25%, average volumes are over 100,000 shares and it’s a £30million Company. I would buy it at a spread of 5% or under but can anyone more enlightened than me, explain why the spread for this share is so incredibly high?
actual spread appears to be more like 10-12.5%, today's trades below
We all have our view regarding the virus.Media is reporting deaths in hospitals only.A lot of people have also died in nursing homes and also at home.The reason why we have slack in icu is because 111 tell people to stay at home and not come to the hospital as the condition is not that serious as yet.Some healthcare workers who had covid and recovered say it is the most harrowing experience ,a lot of doctors have also died.The virus attacks old and young depending on the exposure to the virus(extreme to mild).
Therefore the most important thing is to protect yourself and others by social distancing and other necessary measures.
Regarding DFS Furniture (LON:DFS) I would think that a not insignificant part of their business is related to the turnover of housing. When people move house they re-evaluate what furniture they’ve got and that triggers them to buy some new stuff. While I expect that the housing market will be one of the first parts of the economy to reopen, I think it could be a long time before transaction volumes get back to normal as people will simply lack the confidence to move house and potentially take on extra debt when the jobs market is depressed. So, it’s a long wait for DFS to pick up in my view.
On the more general point of Covid-19, I find it surprising that we are focused so much on the fatality rates. Whatever the calculated rates is it not clear that the number of deaths occurring in a short time has increased significantly in certain hotspots? If that is not the case how come Lombardy brought in the army to move coffins because local facilities ran out of capacity, how come Spain felt it necessary to turn an ice rink into a morgue? Release the lockdown immediately if you like, over the course of the year the death count may not look all that much worse than a particularly bad flu season. But a large number of deaths will come very quickly and you had better start building emergency crematoria. As we have the Nightingale hospitals perhaps you would like some jaunty name for these incinerators.
Sorry, for the cynicism! I must have got out of the wrong side of the bed this morning!
Hi all,
Apart from Stanford, there are other examples (2 x Boston; Diamond Princess, the village of Vo; the French aircraft carrier; and a Dutch submarine) that all point to a much higher percentage of asymptomatic already-infected.
Re Sweden, there's some suggestion that BAME are more vulnerable /susceptible and it's at least possible that Sweden's higher death rate vs its Scandinavian neighbours is that it has a much higher recent immigrant population.
See www.lockdownsceptics.org (blog yesterday and today) for link to sources.
ATB
"British households will have £43bn less cash available for essential spending between April and June, as the UK slides into its deepest recession in decades...according to the CEBR".
A lot of people (and the press) are saying we cannot in the future have a situation where a company pays vast amounts to its directors, pays dividends and does buybacks....and yet within a few weeks of the virus has to rush to the taxpayer to ask for emergency funds. Why have companies not put aside large amounts of cash to cope with such unexpected events?
Hard to explain and understand that. I wonder if there will be much tougher rules in the future to stop company buybacks etc until and unless there is substantial cash held.
The start of the virus job retention scheme today has also been received with very mixed feelings. Right to support low paid employees but why should the taxpayer bail out the very rich (including celebrities and directors paid fortunes) ? There does not seem a rush by the wealthy to put much of their fortunes back seems to be a very common view...you took out fortunes in the good times and stripped the company. Now in the bad times its a matter for the government? Any suggestion that there need to be higher taxes on the poor or another period of austerity is likely to be met by fury. As a landlord I am not exactly a left winger but I have some sympathy for some of this. I can certainly see major changes being introduced that will affect companies and their ability to operate just on debt. It is probably time to change things not to allow companies to operate on a "abolutely diabolical balance sheet".
Coldnt agree more. Why should we bail out some of these shoddy building companies who manipulate house prices, build starter homes below the recommended minimum square meterage, and some of them start to fall down after less than six months after 'completion', not to mention entrapping supposed freeholders in unreasonable service charges which the governments have been looking into for about 20 years! Bail out the workers by all means, but nationalise the companie's land banks as compensation to the tax payer.
I think thats the point . He's not buying or selling, but he is invested. The rules remain the same. Value and diversification of assets.
The Swedes reckon up to 50% of their population may have already had the virus without feeling ill effects.
Their policy is to prefer to lock down the old and vulnerable. They recognise that they may have started later than they should in locking down care homes etc.
They expect later waves of infection, and this is a timing issue, with regard to Health resources available.
Obviously they are a highly educated population with good resources.
The true statistical lessons will only be learned in the rear view mirror. It could be quite embarrassing for some of the more lurid media commentators. But no doubt they will have moved onto another doom-laden scenario by then.
A study in Stockholm of random tests found around 2.5% were infected, that was a about 2 weeks ago so could have changed but 50% looks too high, need to check the daily reports.
They had 563 new cases yesterday but I don't know how many tests they did, will check later.
According to https://www.ovulation-calculator/coronavirus the Swedes have done over 7,500 tests per million of population (UK 6,783). Switzerland has tested 25,000 per million; Spain, Portugal, Italy, Germany and Austria have tested over 20,000. Of all the countries with over 15,000 cases of Covid-19, only Iran, Brazil and India have tested a smaller proportion of their population than the UK.
I really don't see the relevance apart from it's shows that Sweden has done a low number of tests. France has the same number as the UK.
Obviously they are a highly educated population with good resources.
I'm not sure what being highly educated has to do with anything? For me, the only amusing thing about this crisis is the number of highly educated people I am watching and reading that are making total plonkers of themselves on a daily basis.
Why is it so embarrassing to be honest and admit you don't know something?
All the best, Si
Here is an example of how education helps.
Sweden - I understand the science and I trust my government and health authorities. I respect distance from others and realise the importance of protecting those at risk and can continue without a lockdown but alter my behaviours.
USA - I don't understand and distrust the science I trust my president and distrust my local government and health authorities and I don't want to continue with lockdown or change my behaviours. (MAGA crowd.)
Well if you need to set up a straw man and then add in gross generalisations and ridiculous biases... However, this doesn't stand up to scrutiny. Your description of the US in no way relates to California, for instance, a state with a population 4x that of Sweden with world class Universities that blow anything in Sweden clean out the water when it comes to education. Last time I looked California had far less virus deaths than Sweden as well.
But let's not let facts get in the way of a good rant.
Si
Si...
I was in no way inferring that US citizens are not well educated, hence stating (MAGA crowd) not US citizens or for that matter Californians. It is not bias as I have heard them interviewed and this is their believe although I understand that they also need to get back to earning a living.
Si...
I was in no way inferring that US citizens are not well educated, hence stating (MAGA crowd) not US citizens or for that matter Californians. It is not bias as I have heard them interviewed and this is their believe although I understand that they also need to get back to earning a living.
Sorry, I'm not great at acronyms and had no idea what MAGA stood for. It's very easy to use the US as a whipping boy because they have a cretin for a president and some newsworthy rednecks, aided by Jon Sopel's constant anti-Trump bias on the BBC, but it sadly does not paint a true picture of the country.
The point I was really trying to make is that we shouldn't be listening to experts from Sweden explaining how they've got it right and everyone else is wrong - it's too early and they are just talking their own book. In particular, my understanding is that it is the scientific community making the decisions and not the Swedish government. That's great because at the end when it turns out horribly they can all keep their jobs and fire a few scientists who can just go back to their day job.
California has handled the virus far better than Sweden, where the approach seems little more than scientifically sanctioned euthanasia. If that is how a highly educated civilised society operates, I'm glad I don't bloody live there!
All the best, Si
Interview with adviser to Chief Swedish Epidemiologist (used to be Chief himself but now retired) fwiw
https://www.youtube.com/watch?v=bfN2JWifLCY&feature=emb_title
Late addition:
This video may have been posted earlier by another contributor
how do you lock down a care home when the staff come in from outside?
The media commentators will suffer no embarrassment or shame.
If one prediction of doom doesn't come to pass, the media pack will have already moved onto the next hot topic.
Many of them constantly criticise performance, decisions and so on, without ever collecting data to support. A fine example is ventilator procurement. Despite all the media indignation over us not joining the EU ventilator scheme, the UK has not been short of ventilators, whilst the EU has been short of ventilators.
I remain unimpressed by the majority of mass media journalists. Reporting supported by evidence is in short supply.
"Despite all the media indignation over us not joining the EU ventilator scheme, the UK has not been short of ventilators, whilst the EU has been short of ventilators."
Did the EU scheme ever actually deliver any ventilators? Or is it still at the draft discussion stage.
Dear Mr Buffett I know that I should be greedy when others are fearful and fearful when others are greedy but right now I can't work out whether others are being fearful or greedy....please advise.
Love this Saxman. My view and I am no Buffet....
Greedy people are using the fact that Central Banks are holding up the market and greedy people follow greedy people into the market.
Fearful people are staying out as they may fear that we are not out of the woods yet. There are so many unanswered questions.
If the fearful people are right then the Greedy people will run for the hills!
I guess... Be Greedy but not quite yet!
Wonderful! Thanks for brightening my day!
The point Graham makes about Buffett is a valid one. His strength as an investor has always been to step back and invest according to his perception of long term trends. Buffet invested heavily in January 2009, which at the time seemed bonkers. The markets went down in February. Then in March they started taking off. The Berkshire Hathaway reticence to step in so far speaks volumes.
Excellent!!!!
This is my current thinking. The markets are still depressed therefore there is plenty of fear. The greedy believe that sooner or later lockdown will have to be lifted to avoid total economic collapse so are buying well capitalised companies that they think can weather the storm.
I think the question to ask is is there enough fear at the moment to be greedy?
I think the question to ask is is there enough fear at the moment to be greedy?
The problem is that you're dealing with proper uncertainty. If, when lockdown is lifted, the economy restarts reasonably smoothly and there's no spike in infections then many (although not all) share prices will recover from here. If, on the other hand, there's a second wave of coronavirus then we're into another lockdown and markets will crater.
The problem is ... nobody knows. Because nobody can know.
But people - and markets (which are just lots of people) - don't handle true uncertainty very well, so they seesaw between fear and greed, take random variation in market movements as meaningful, desperately analyse bits of data - which they mostly don't understand - for enlightenment and listen to people who aren't really experts, but are persuasively confident, for advice.
With hindsight what we should do will have been obvious, but anyone who thinks now that they know for certain what will happen is deluding themselves. The best we can do is take the few things we do know, try to think through the likely impacts and decide how best to hedge our bets.
Oh - and remember - although markets always recover that's not true of all of the companies in them and while cash is a option in uncertain times, if inflation kicks in it's lousy place to keep your money. Ultimately both greed and fear can see you in the poorhouse, although greed will get you there faster if you make the wrong decisions.
Welcome to the madhouse.timarr
I can recommend a podcast called This week in Virology (TwiV) for a deep dive into Covid issues, led by medical academics and virologists.
The latest takeaway was emerging data, tentatively supporting the idea that there may be largish numbers of asymptomatic people infected with Covid. They referred to a New York study where all maternity cases were screened i.e. no selection bias. In this case if I remember right, the 2% of expectant mothers with fever tested positive, but there were a further 13% positive without. (They might have be pre-symptomatic, though)
- The Stanford study (I think) was problematic as self selecting.
- Interesting data emerging in coming months
- some evidence that Covid infection fatality rate could be .1% to .2%
By way of counterargument, Ambrose Evans Pritchard (Telegraph columnist) pointed out that in Bergamo, monthly deaths recently are way up and inconsistent with the hypothesis that covid is largely non-serious. I wonder if this could be due to that city having a large cohort of very elderly. Amongst the Covid deaths, reported average age was 79.
Back home, the NHS currently seems at capacity. Not due to beds or ventilators but for lack of PPE.
Recently I am changing my view from accepting the government made a good job responding to the crisis, to that is making serious mis-steps. The bland re-assurances on PPE rather than getting to grips with the shortage being one issue. Another is the low take-up and scaling of Covid testing. Surely essential to a successful unlock strategy.
In fact treating the public as quasi children, and therefore unable to think about the unlock strategy until it happens: it's seriously annoying. Fortunately, Scotland's Government are going to kick of discussions this week for Scotland. So our own government will probably be embarrassed into following suit.
So the situation is mildly positive, but I'm surprised how well some consumer facing business shares prices are holding up. Greggs for example. Or Games Workshop. How long before people will be allowed and feel comfortable walking down the street again, eating a hot baked snack with unwashed hands in public?
How does one get to grips with PPE shortages? Its either there or it isn't. I guess the Mayor of London has the answer. Create even more demand by telling everyone to wear a mask. Every mask and pair of surgical gloves I see wondering around deserted streets is one less mask and pair of gloves for a frontline worker. Wash hands, maintain social distancing and smile! works just as well as masks for most social settings in a lockdown situation. Masks may have a role to play when exiting lockdown but not during lockdown.
I suspect Mr Khan is aware of a tsunami of masks coming on line and wants to take credit for when the Government advises the appropriate use in social settings (probably on Public transport) as part of a coordinated strategy. (Its Political point scoring not leadership or insight)
Is 100k antigen tests a day really helpful to an unlock strategy? I can see the merit for large scale reliable antibody testing but how can you criticise a government when the tests have not yet been developed. I personally would have preferred that all efforts were focused in this area. Instead the baying wolves demanded 100k a day antigen tests so I guess that's what we will get and we can continue to tell people what they already know. Bit like baying wolves demanding the ventilators that were never required.
I wouldn't hold your breath on Nicola! Why does she have to wait a week if she has all the answers? In reality, she will continue to attend the Cobra meetings and at an opportune moment brief the press in advance of a formal announcement. Same way she has done throughout the Covid crisis. (Its Political point scoring not leadership or insight)
I will of course check out your recommended podcast.
https://www.wired.com/story/covid-19-immunity/
useful short video that answers some of the questions we are going to have to deal with in the next few months
Graham,
I'm struggling to see how this degree of damage to economic supply and demand and to government, corporate and personal balance sheets can be repaired within a few years, even if a vaccine were to become available quickly and to stay effective for a long time. Yet the focus of financial commentators seems to be on identifying the shares to buy for recovery, whilst the economy has taken a huge hit and scientists and WHO are saying that the most likely outcome is that the virus will remain a recurrent threat for many years.
Then there's the impact of the money injected into the financial systems worlwide. I read in the FT on Saturday that the new economic theorists argue that worrying about national debts and deficits is "a language problem, not an economic problem" and that they believe that an independent central bank can create money with no negative effects. But I find that hard to accept and, if it becomes the UK Government's position, there will be a large number of very angry people who were hurt by ten years of austerity, and a huge clamour to print much more money to repair all the damege those policies caused to local government services, the NHS, the schools and society.
So, as a medium term investor, why are you still holding your long position on the FT100 and why are you even neutral on the index currently, in view of the economic
damage that is already baked in from the actions that world governments have taken, and the seeming certainty that further economic damage will become evident over the next many months?
Martyn
"Then there's the impact of the money injected into the financial systems worlwide. I read in the FT on Saturday that the new economic theorists argue that worrying about national debts and deficits is "a language problem, not an economic problem" and that they believe that an independent central bank can create money with no negative effects. But I find that hard to accept and, if it becomes the UK Government's position, there will be a large number of very angry people who were hurt by ten years of austerity, and a huge clamour to print much more money to repair all the damege those policies caused to local government services, the NHS, the schools and society."
Doesn't take a new economic theorist to believe that there will (probably) be no negative effects. This time.
The fundamental issues are around money supply, currency and interest rate levels and the level of economic activity. And what other countries are doing. Wouldn't have been possible in the austerity years without substantial negative effects. We actually did quite a lot, less than the US but much more than the EU despite having a proportionately bigger financial sector. The currency took a big hit and only gradually inched up again. It's like a global jigsaw puzzle with each piece having it's flexibility constrained by the other linked pieces.
Martyn, thanks for your comment!
I haven't got the time to write a detailed response. I would merely remind everyone what the biggest components of the FTSE are:
I agree with you about the economic damage that is coming. The relevant questions for me are:
Same goes for BHP, Rio, Diageo, BP, Reckitt, etc.
Regards
Graham
I have been a shareholder of HSBC for many years. Know many of the bank executive and Mark Tucker is a personal friend . They have a long history of looking after shareholders very well and this is unlikely to change in the future. Expect a substantial dividend in the final quarter 2020 ( assuming they are allowed to !!). At a price of about £4.10 they are a bargain for any with a long term perspective.
I think many will agree that there will be a staged reopening of the economy.
It is worthy of note that the Irish Health Minister said yesterday that he didn’t expect pubs to reopen until a vaccine is found. https://www.dailymail.co.uk/ne...
Where does that leave a lot of the leisure industry?
"Where does that leave a lot of the leisure industry?"
In the slurry tank, along with all the milk that the dairy farmers can't now sell and that coffee shops used to buy.
Politicians and the WHO really need to start asking whether the cure is worse than the disease.
Life is not priceless - organisations like NICE put a value on it every day.
My thoughts exactly for some time , I really worry what this is going to do to the economy in the long term. Is all this money printing really going to work or can we be heading towards the mother of all recessions ? I add that I am normally a very glass half full sort of person just not over this.
A Stanford University study on COVID mortality rates suggests death rates assumed by governments and public bodies are an order of magnitude too high.
The study used an antibody blood test to estimate how many people had been infected with COVID-19 in the past, in a sample of some 3000 individuals.
The Stanford study inferred that the infection fatality rate is between 0.12pc and 0.2pc, far lower than the rates of 1pc or more as assumed by most health authorities.
If 50 times more people have had the infection, the death rate could drop by that same factor, putting it "somewhere between 'little worse than the flu' to 'twice as bad as the flu' in terms of case fatality rate," Jay Bhattacharya MD PHD said.
If Bhattacharya is right, it probably means that many of the harsh COVID measures currently in place are over the top. Perhaps this will vindicate the approach taken by the Swedes.
To balance this report, there are claims that his study has suffered from selection bias. And it has yet to be peer-reviewed. Some question the sample size as being statistically too small to allow reliable inferences.
Similar studies are being undertaken in several parts of the world. Results should trickle into the public domain, in the next weeks rather than months.
A longish interview with Bhattacharya can be found here .
A Daily Telegraph article is also worth a read.
If Bhattacharya is right, it probably means that many of the harsh COVID measures currently in place are over the top. Perhaps this will vindicate the approach taken by the Swedes.
Not really, because Sweden is operating on the same data as the rest of us. Its decision making isn't based on assuming lower mortality rates but on its high levels of social cohesion, relatively low population density and extremely good healthcare provision. Even so it's seeing significantly higher death rates than Denmark and Finland, which did impose lockdowns.
But overall mortality rates aren't really the point - we can see by the excess death rates in the UK alone that it's more dangerous than flu to a certain section of the population. You only need enough very ill people overwhelming healthcare capabity and you start to see other people not getting treated.
It'll take a long time to fully understand the issues but the immediate problem, based on the data that we've got, is how to break the lockdown. We have a signficant majority of working age people who are at little risk who need to get back to work - somehow we have to figure out how to keep the remainder of the population safe as they do so.
timarr
Hi timarr
Even so it's seeing significantly higher death rates than Denmark and Finland, which did impose lockdown.
Why choose Denmark and Finland? Sweden's death rate/ 1m pop is significantly lower than Italy, Spain, France and UK, all of which have imposed draconian measures. (Worldometer).
We need to find a balance between loosening the lockdown and not allowing the economy to fall into a death spiral. That's the 64K$ question. If one of our key assumptions such as the expected death rate is wildly out, then that is material, in my opinion.
Let's assume Bhattacharya is right and his study is confirmed by others, then living in a world where COVID death rates are the same or marginally more than the flu rates should be equally manageable without shutting down the economy. If that means more hospital beds and ICU units and more hospital staff, then that should be the new norm. If it is OK to tolerate the current rate of flu deaths, then it should be OK to tolerate similar levels of COVID deaths. Not an indefinite lockdown. It sounds callous, I know.
Denmark, Finland and Norway are neighbours to Sweden so it's to be expected to compare them.
Bhattacharya also said:
“It is absolutely critical that similar studies be done all around the country,” said Jayanta Bhattacharya, a professor at Stanford and author on the study. “It’s very clear that the virus is more prevalent in some areas than in others, and understanding the prevalence of viruses in each region is is a critical step forward to making some policy.”
I thought Sweden's approach was partly based on their belief that their health system can cope. Therefore no need to 'flatten the curve' and spread the illness over a longer period of time. So we won't know until much later if there has been any impact on the death rates compared to other countries. It could simply be the same numbers as other countries but over a much shorter timescale
Not really, because Sweden is operating on the same data as the rest of us. Its decision making isn't based on assuming lower mortality rates
Are you sure?
"Professor Johan Giesecke, one of the world’s most senior epidemiologists, advisor to the Swedish Government (he hired Anders Tegnell who is currently directing Swedish strategy), the first Chief Scientist of the European Centre for Disease Prevention and Control, and an advisor to the director general of the WHO, lays out with typically Swedish bluntness why he thinks:
The actual fatality rate of Covid-19 is the region of 0.1%"
https://unherd.com/thepost/coming-up-epidemiologist-prof-johan-giesecke-shares-lessons-from-sweden/
If the COVID-19 is a mild disease similar to flu why are we seeing so many more deaths? Last week we already saw record numbers and that was based on figures 2 weeks ago when Covid-19 deaths were lower. That is also in a country that is isolating, without that the rates would be higher as the spread would be quicker. Many in Sweden are now having doubts, here is a different view: https://www.theguardian.com/world/2020/mar/30/catastrophe-sweden-coronavirus-stoicism-lockdown-europe
As ever, it pays to look at what the data says and not opinions in isolation.
It looks consistent with a much higher infection and lower mortality rate as claimed.
Let's hope that study stands up to scrutiny, but it seems very much an outlier at the moment.
For now, I would put more faith in the data from Iceland for example. They have gone for strong testing / contact tracing with no lockdown. After testing 5% of the population, they found 1% of tests were positive and 50% of positive tests were asymptomatic. Their death rate is about 0.5% but based on low numbers and comprehensive care.
How can they calculate the death rate when so many cases are on going still? Deaths is some places are doubling every 7-8 days. 0.1% (based on total population) does seem to be the mortality rate in New York state but it could be 0.2% next week as 200,000 cases still ongoing and 6,000 new cases everyday, if only 10% infected then the mortality rate would be 1%. We don't know how long this will be around for and whether it will come back. We also don't know about immunity, there are cases now where people who have recovered have been reinfected.
It is a small sample and not sure have reliable those antigen tests are. I think it is premature to calculate any mortality rate, even the researchers stress this.
This sort of study comes against many that have others that have come to different conclusions.
The fact is that there are so many variables so taking a small number of people as a sample and coming to a conclusion is far from accurate.
An important factor is that the R rate of Covid is approx 3 when left to propagate normally. This produces and exponential growth rate. Once the amount of current infections in a country goes past the capabilities of the healthcare system to cope then deaths will rise at an alarming rate.
I would expect that it is precisely because this study was done in a lockdown scenario that it has produced these results.
Sweden is a different situation from others. They have a country with a highly educated population that have relatively low densities. This solution which fits Sweden doesn't fit UK or India for example.
Hi Graham,
I cannot remember what the top end Mkt Cap limit is for this report, but would be very interested in your thoughts on the Premier Foods (LON:PFD) announcement today. Looks potentially transformative to me.
Thank you, Martin
The problem with Premier Foods (LON:PFD) as I see it is that it is a small producer owning second rank brands whose customers are in the main significantly bigger than it and have all the economic power. It operates on tiny margins and any improvement in that will be chiselled away by its customers.
Shanklin, top end is £400 million. PFD fits - I might have a look.
Best
Graham
Why can't I see this?
I don't know.
Hi Jesse,
I see you recently joined Stockopedia. Paul and Graham just put out a placeholder first thing in the morning and then add to the report during the day. It just allows people to add comments and discuss the latest company updates.
Cerillion (LON:CER) are interesting. No slowdown, even in their sales pipeline, £4.8 million in cash on the books. Growth rates a bit flattered by the fact that some contracts last year were delayed into the second half but, still, 46% growth is fair going.
Their main customers are telecos who are seeing unprecendent demand, so probably no surprise that they're resilient.
timarr
Hi timarr -
I had a good look at CER in terms of fundamentals and recent history. It is a good stock but not outstanding by a long chalk.
Which makes me suspect that today's market values COVID resilience above anything else.
To me, a good clue as to where I should be looking to park my cash, when the time comes.
I had a good look at CER in terms of fundamentals and recent history. It is a good stock but not outstanding by a long chalk ... Which makes me suspect that today's market values COVID resilience above anything else.
Hi Ramridge
I agree, although Cerillion (LON:CER) is potentially a bit better than just good. I've been following them since they listed when John Lee bought into them. It's not just the decent metrics but also the broad customer base and a good management team. Remember most of this growth was pre-crisis.
When thinking about resilience I'm trying to figure out whether we're looking at windfall profits or not. With supermarkets, for instance, I think we'll see them revert to more normal earnings levels when the crisis passes. But some changes will be more sticky - home working and less travel for example. Picks and shovels to the telecoms industry will see a lot of growth, even if we enter a recession - people won't give up their mobile phones, no matter what. 5G (when idiots stop burning down the masts) will boost that trend.
Overall, the crisis is driving businesses of all kind online and while there'll be some reversion after the event I doubt things will ever be the same again. But if any of us think we can predict the new normal with any certainty we're kidding ourselves.
timarr
Morning Graham, any thoughts on the £nahl update greatly appreciated. Their critical care business is still trading ok and is arguably worth much more than the current EV on its own, on my calculations. Thanks
Xpediator (LON:XPD) results today seem to read very well, revenue up 19%
My morning smallcap tweet:
IXICO (LON:IXI) Cerillion (LON:CER) Yourgene Health (LON:YGEN) Maestrano (LON:MNO) Totally (LON:TLY) Premier Foods (LON:PFD) SysGroup (LON:SYS) NAHL (LON:NAH) Proactis Holdings (LON:PHD) Gresham Technologies (LON:GHT) Wameja (LON:WJA) Midatech Pharma (LON:MTPH) DFS Furniture (LON:DFS) Feedback (LON:FDBK) Genedrive (LON:GDR) Be Heard (LON:BHRD) Omega Diagnostics (LON:ODX) easyHotel (LON:EZH)
IXICO (IXI) H1(March) rev up 33%. "A strong order book and cash position together with a backlog of revenue generating projects which are being undertaken during the COVID-19 "lock down" underpin the Company's confidence that it is well-placed."
Cerillion (CER) has not experienced any slowdown in trading due to lockdown. H1(March) in line with rev up 46%. Co "has added further resource, and its sales pipeline remains encouraging."
Yourgene Health (YGEN) FY(March) rev up 86%. Customers in Europe are continuing to operate as normal apart from some slight timing delays. "The Group remains well funded to achieve its objectives."
Maestrano Group (MNO) recent Q rev up 20% or 28% at constant currency. Expenses down 49%. ""Whilst the revenue reflects the change from the Company's previous core business to the new Airsight business, it is very encouraging to see improved results as the Company has transitioned to a lower overhead structure that complements the Airsight business model....based on current contracts and carefully considered opportunities, with no requirement for additional capital in our considered outlook."
Totally (TLY) guides FY(March) EBITDA ahead of consensus on lower than expected revenue. Rev miss due to due to NHS delays in awarding new tenders primarily as a result of Brexit and the general election. £8.9m net cash. I hold.
Premier Foods (PFD) concludes strategic review. Cuts pension contribs. "NPV of pension deficit contributions could reduce from current £300-320m by up to approximately 45% to £175-185m." Has moved closer to a scheme buyout by a specialist insurance provider. Guides FY(March) trading profit' at the top end of market expectations. Volumes have started to reduce from the exceptional levels seen in March, although are still expected to continue to be higher than average patterns of demand.
SysGroup (SYS) guides FY(March) in line with mgmt expectations. Rev up 53%, adj EBITDA up 99%. No covid impact yet but may see order delays.
NAHL Group (NAH) suspends guidance. "Since mid-March, the Group's Critical Care business has remained resilient with only a modest level of impact to date. However, the Group's Personal Injury division has suffered a more significant reduction in enquiries and its Residential Property division has suffered in line with the UK property market. Net debt £21m, "we believe that the Group will be able to manage net debt within the current headroom." I hold.
PROACTIS Holdings (PHD) rev, profitability, cash flow and net debt in line with mgmt expectations, not materially affected by COVID. Group remains comfortably within its existing facilities.
Gresham Technologies (GHT) rev committed or 'confidently expected' are 84% of of planned FY rev. New business activity has slowed. Cash at hand of £6.8m. No further FY guidance.
Wameja (WJA) invests €3.6m in Homesend to keep same share as Mastercard injects cash. Q1 Average Transaction Value up 6% and 30% QoQ.
Midatech Pharma (MTPH) strategic review update: has received initial enquiries but not in discussions with any potential offeror. Appoints Noble investment bank and Panmure as advisors.
DFS Furniture (DFS) advanced stages of negotiating additional debt facility of £60m-£70m to cover the near-term working capital unwind until sofa deliveries can resume. Also placing. Cuts op C/F to £14m pcm. These "should give the Group significant liquidity to see through an extended lock-down." I'm short.
Feedback (FDBK) Pennine Acute Hospitals NHS Trust to roll out co's Bleepa imaging-based communication platform.
Genedrive (GDR) agreement with Cytiva for development of Genedrive covid-19 assay for use on lab-based PCR instruments.
Be Heard Group (BHRD) expects rev hit from covid but the full impact is impossible to assess.
Omega Diagnostics (ODX) formalise a partnership to mfr Mologic's COVID-19 first generation ELISA diagnostics test.
Easyhotel (EZH) to cancel listing on 19 May because listing costs are disproportionate to any potential benefits.
Report posted at 9 am. Magnificent effort. Don’t know how you do it.
9am? That would be slacking. It was 7:52.
I see your tweets at this time Mr. C but for some reason your post on this site always seem to be delayed until later.
The post here is always a minute or so before the Tweet. Don't know why it doesn't show for you. Try a hard refresh of the site - click in the url and hit Enter.
Mr C - your report is timestamped 07 52 by Stocko and was there when I looked around 07 55.
Keep up the good work - it is much appreciated.
And Stocko is showing me that you posted at 8:52am. The exact 1 hour difference suggests that somewhere a clock is set to European time or maybe Grenwich Mean Time (would that be the same as Central European summer time?)
And regardless of that your daily post is a must read. I especially like the dry sense of humour.
Says 8.52am for me too !