Small Cap Value Report (Mon 20 Feb 2017) - HAYT, PHD, FISH

Good morning!
Today I intend reporting on;
Hayward Tyler (LON:HAYT) - profit warning, but strong pipeline. Issue with bank funding?
Proactis Holdings (LON:PHD) - in line H1 update, and upbeat commentary (I hold this stock personally)
Graham has emailed me a section on:
Fishing Republic (LON:FISH) - in line 2016 update.
Hayward Tyler (LON:HAYT)
Share price: 43p (down 11.3% at the time of writing, 08:30)
No. shares: 55.4m
Market cap: £23.8m
Update on trading & continued bank support - that's the exact title of the RNS, which would be enough to make me hit the sell button on the opening bell, and ask questions later.
This company manufactures heavy-duty electric motors, pumps, etc.
Reviewing the last few RNSs, it looks an interesting situation where the company has been raising loan funding from investors, to take the pressure off its bank borrowings. I reported in Mar 2016 here, on a property sale & leaseback, noting that the finances looked stretched.
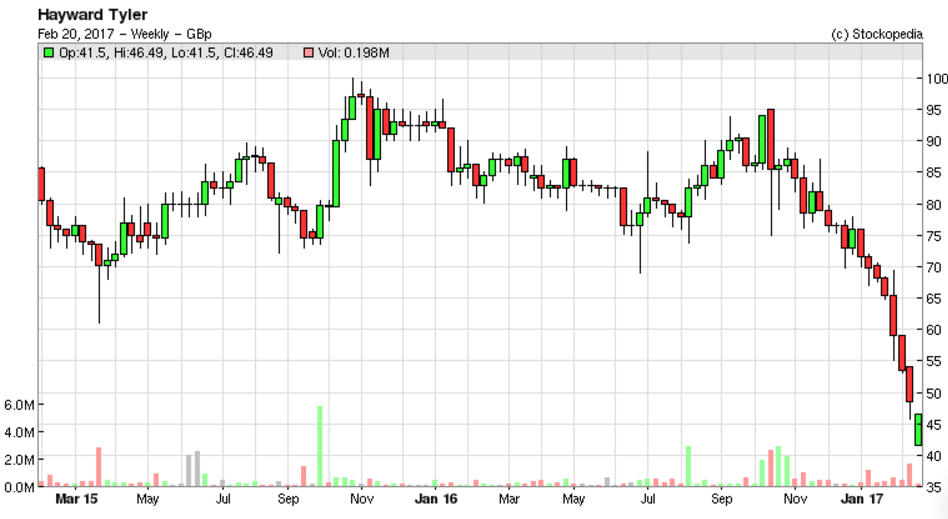
The share price had been around 80-90p until Nov 2016, when these funding issues emerged, and has since halved. Clearly the best course of action for small shareholders would have been to exit promptly, as soon as funding issues emerged in Dec 2016, as is so often the case.
Anyway, let's look at today's update. It's rather confusingly worded, as the first paragraph seems to be saying that things are going well, with a strong order book;
The Board indicated in its interim results statement that the current financial year would be very much second half weighted.
This is, as expected, proving to be the case with aggregate order intake1 of £24.3 million secured in the four months to 31 January 2017, giving order intake for the 10 months to that date of £49.7 million and a significant increase in the order book2 to £52.2 million.
However, the next paragraph seems to be saying that the increase in H2 order intake isn't enough, with a considerable (£30m) amount of delayed orders;
The Board's revenue3 expectations for 2H2017 relied on a number of additional contracts being secured across both Hayward Tyler and Peter Brotherhood in 4Q2017, however, to date there has been a delay in securing a number of these contracts to later in the quarter or FY2018, amounting to over £30 million in aggregate.
As a result, the Board now anticipates reporting lower revenue for the financial year ending 31 March 2017.
This revised revenue is expected to be £60-65 million, generating Trading4 EBITDA of £4-5 million in 2H2017 and around breakeven Trading4 EBITDA for the full year.
I think it's fantastic that the company has given the market specific guidance as to what level of EBITDA to expect for the full year. I reckon this is probably why the share price has only fallen a relatively modest amount today. When companies report clearly like this, giving investors specific numbers, then we can make informed decisions.
FinnCap says this morning that breakeven EBITDA translates into about a £4m adjusted pre-tax loss for the year, so it's far from a good result. Although as the broker points out, the bad news seems to have been anticipated by the market, hence the modest fall in share price today. Either that, or big shareholders happen to be sitting tight. With an illiquid share like this, it only takes one big shareholder to start dumping indiscriminately, and the share price can collapse.
Note that, yet again, the old chestnut of an H2-weighted year being expected, has turned out to be a deferred profit warning.
Pipeline/order book - the company makes very positive noises about future prospects;
Looking ahead to the next financial year, the Group's pipeline of new business opportunities is very strong, presently amounting to over £500 million through to FY2019 with short-term prospects of over £40 million.
Subject to securing further orders that are currently being tendered, the Board anticipates entering FY2018 with a record high order book.
Optimistic shareholders may therefore be looking through a poor 2016/17, and anticipating a recovery into profit in 2017/18.
Financing - I really don't like this bit at all;
The Group is operating within its current borrowing facilities and it continues to have constructive discussions with its bank, Royal Bank of Scotland, with respect to the repayment of £2.4 million of short term banking facilities, currently extended to 28 February 2017, and to ensure a suitable long term financing structure is in place to support the longer term prospects of the business.
This sounds as if the company only has 8 days to come up with £2.4m in repayment of debt to the bank. Maybe the bank is willing to extend that again, or maybe the company might be able to tap its investors for more loan notes?
It all sounds way too precarious for my liking though. If other options fail, and the bank get more jittery, then a deeply discounted emergency placing could be the only remaining option. It's got to be a serious risk anyway.
On the plus side, one of the main advantages of being a listed company, is that banks tend to be much more supportive than they are of private companies. This is because banks dislike the negative publicity of withdrawing funding in the full glare of publicity of the stock market. Also, banks know that, in extremis, companies can tap their shareholders in a way which may not necessarily be possible for private companies.
My opinion - this is a good example of the type of company that I try my best to avoid. Here's a list of things I don't like about this share;
- Capital-intensive business model
- Lumpy, unpredictable orders
- Financial performance is therefore erratic
- Worst of all, it's got a wobbly balance sheet.
- Broker forecasts are falling
- Quite a bad profit warning today
- The company is paying dividends that it can't afford
- Equity fundraising to shore up balance sheet looks long overdue.
On the upside, if the company can resolve its funding issues without diluting shareholders, and if the pipeline does turn into lucrative orders, then this share could perhaps recover. Although in my opinion, if you have to use the word "if" to justify any investment, then it's probably not going to be a good investment!
Overall then, it has no appeal to me whatsoever. I can't see the point in taking unnecessary risks.
Proactis Holdings (LON:PHD)
Share price: 168p (up 0.3% today)
No. shares: 50.2m
Market cap: £84.3m
(at the time of writing, I hold a long position in this share)
Trading update - this generally reads quite well I think. Although clearly not enough to have triggered any significant buying interest today. I'm quite surprised at that actually, because the organic growth is pretty good;
The Group confirms that results are expected to be in line with expectations, with revenues for the six months ended 31 January 2017 up 36.3% to approximately £11.8m (2016: £8.66m). This includes strong organic growth (excluding the part period impact of the Group's acquisitions) of 13.4%.
The Group signed 27 new names (2016: 23) and the initial contract value, order book and pipeline remain encouraging.
Proactis has made a series of acquisitions, building up a group of companies with complementary software & services offerings. I was pleased to see that, for the most recent acquisition, the company did a £12.5m placing. An unusual (and positive) feature of that fundraising is that it was done at a 9.3% premium to the previous day's share price. That shows strong demand from institutions, so could also be a pointer to follow-on buying in the open market.
The most interesting aspect of Proactis shares, is its supplier networking software. If this really takes off, then we could have a multibagger on our hands. It's a bit like Tungsten's idea of automating supplier relationships, and offering early payment discounts. Although Proactis is doing things at the opposite end of the scale - with the fee being only £50 per supplier - low enough to (hopefully) sign up many thousands of its clients' suppliers.
What I like about this share, is that you can justify the valuation on existing business. So there's no leap of faith in having to believe crazy forecasts, as was the case with Tungsten's bungled attempt to crack the higher end market in this space.
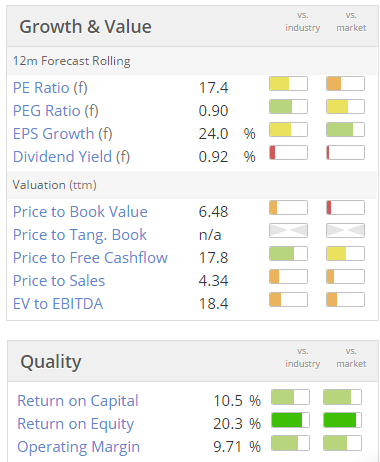
As you can see above, the forward PER is fairly reasonable for a growth company, in an expensive market at least. There's even a modest divi too. Quality scores look quite good, and the overall StockRank is acceptable, at 67 - which is mostly based on high quality & momentum scores:
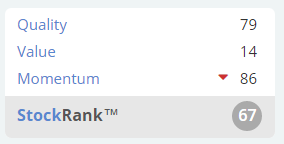
Thinking about momentum score (which incorporates share price movement & broker forecast movements), I think we need to be a bit careful with acquisitive groups. If a company keeps bolting on acquisitions, then the broker forecasts will of course keep rising. Care needs to be taken to ensure that an acquisition spree is not obscuring weakening underlying performance.
That doesn't seem to be the case here though, as the organic growth of +13.4% looks like a healthy underlying business exists.
My opinion - I've held this share for quite a while now, and whilst I do like the company & management, have not had sufficient confidence to buy in any real size. So it's one of the smaller positions in my portfolio.
Today's update gives me more confidence, so I'll give some thought to possibly increasing my position size here - but will probably wait to go through the numbers in more detail. They are due out on 26 April 2017, so I'll cover in more detail then.
The Directorspeak today sounds encouraging. I like the management here - have met them a couple of times, and they seem grounded, sensible people, as far as I can tell.
"The Group continues to develop its supplier networking solution. The realisation of this concept is on-going and the progress made has been substantial.
We believe there is great value in the solution and I look forward to providing an update on further progress in due course.
This, on the foundation of the Group's organic growth and strategic M&A, positions the Group well for the period ahead and we look forward to continuing to deliver growth and shareholder value."
I have to jump on a train now, so will hand over to Graham, who I believe is going to add 1 or 2 more sections, on Fishing Republic (LON:FISH) .
I may chip in with my own thoughts on FISH later once I'm back online.
Regards, Paul.
This next section was written by Graham Neary;
Fishing Republic (LON:FISH)
Share price: 39.75p
(+2%)
No. shares: 37.8m
Market
cap: £15m
It’s a short, calming RNS this morning, as Fishing Republic confirms that performance for the year to 31 December 2016 was in line with expectations.
Key points:
- Revenues up 40% (new stores, like-for-like store growth, and web sales)
- Total online sales down but gross margin improved due to greater mix (40%) of own website sales.
- Three new stores opened in H1 are in line with management forecasts. Five other stores opened or about to open (before the end of Q1).
This share has attracted some controversy/debate over its large inventories figure (£3.3 million at the H1 results, versus £1.25 million in cost of goods sold).
Maybe it’s a bit more
reasonable than it appears at first glance. After all, the gross
margin here is 50%. If a company makes good margins on sales, it can
potentially afford to turn its assets/inventories a bit slower, since
the end result is that overall returns on investment will be the
same.
That does require a good operating margin, however, and Fishing Republic hasn’t achieved that yet – not in 2015 and not in H1 2016. And its stock turn is particularly slow.
But from 10 stores at the end of H1 2016, to 15 at the end of Q1 2017, and with more planned after that, perhaps some operating leverage and some other economies of scale can kick in, and this could still work out well for investors?
Another consideration
with the inventories number is that it might be to do with having a
very large number of SKUs relative to total sales – that’s not a
good thing, of course, but it might be a reasonable explanation for
holding such a large amount of stock around the year. Opening new
stores might also require a lot of up-front stock purchases. It would
be good to hear from the company, unless I’ve missed their
explanation for this.
Paul's comments on Fishing Republic (LON:FISH)
Thanks for the above, Graham. I can't resist adding my own thoughts on the company too!
Online retailers have been fantastic investments for my family in the last 2 years - especially Boohoo.Com (LON:BOO) and £G4M which have both been multibaggers. Therefore I look carefully at all up & coming online retailers, trying to find the next multibaggers.
FISH doesn't cut the mustard for me, for these reasons;
1) Inventories are way too high. This inflates operating profit (i.e. provisions not being made against slow-moving lines). However, with non-perishable stock, this can perhaps be justified, as Graham mentions above. One additional negative is that lots of slow-moving stock makes the business cash-hungry as it expands. Whereas the opposite (e.g. BooHoo), where stock is turned much more quickly, meant that the business actually generated cash as it expanded - because stock had been sold before the supplier had to be paid.
2) 70% of sales come from physical shops - so I don't see FISH getting a proper internet stock rating until it becomes clear that it's an internet business, which it isn't at the moment.
3) Is it scaleable, especially internationally? If you look at Asos, BOO & G4M, their share prices really exploded upwards when it became clear their format was working internationally, as well as in UK. That's the point to buy, in my view, not when a company is a tiny UK operation.
4) FISH is too small currently - it has years of growth to achieve before it's likely to get a big mkt cap.
5) Development spend on website hasn't been done yet. They've been using 3rd parties mainly. So lots of expense required now, hence recent placing - will that be enough?
6) Heavy marketing spend needed to get critical mass for any eCommerce company. I don't think FISH has enough cash to do this.
7) Too early stage - e.g. G4M spent 13 years getting to a size where things really started to take off last year. FISH is a long way behind - it could take 5-10 years for FISH to get where G4M currently is. So people expecting a roaring share price could be disappointed, especially when the next bear market kicks in, and the froth disappears from valuations.
8) Shares ridiculously illiquid.
9) Celebrity shareholders - so what? They get it wrong just as often as we do.
Having said all the above, I will definitely be monitoring FISH in the coming years, and if online sales really start to take off, then I would consider a purchase.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
re Proactis Holdings (LON:PHD), having met the management Paul, how strong a leader do you think Jones was, and how hard will it be to replace him?
I sold Proactis on this release after working through figures and making very tentative forward estimates. I think it is too expensive on an ev/ebitda of (what I reckon) is over x12. The company has pretty much grown entirely on a load of acquisitions of which by far the largest was in Nov 16 of Millstream. I suspespect the US business is doing badly. It is terribly difficult to pin down valuations given the constant addition of new businesses - adjusted p/es are pretty meaningless, statutory makes it look miles overpriced but I accept these are distorted by amortisation schedules etc. I agree it COULD be a very good company but the CEO has recently left and I suspect there is a large share overhang to be cleared to boot. So too much uncertainty for me.
I think you are bang on the money Rhomboid.
Fishing Republic, I'm a fisherman and know and use a number of shops and online retailers. I don't see anything special in the FISH offering. I don't see why people will use them instead of established firms like
http://www.tedcarter.co.uk/
http://www.anglingdirect.co.uk/
Both are well established names with a good reputation.
The fishing tackle market depends on new products being released regularly. Big ticket items are redesigned annually and previous models have to be discounted to sell. It's capital intensive and short product life.
There's no reason they can't be profitable but this doesn't strike me as a roll out situation.
I might be wrong but I won't be buying.
Hi sg31 -
As Graham has pointed out they do seem to carry a lot of inventory. Items are in inventory roughly 365 days.
If as you point out big ticket items are redesigned and previous models are heavily discounted, why carry a large inventory when the shelf life and hence value of goods declines so rapidly?
I agree with you, there is nothing in this company that justifies a high multiple.
Regards, Ram
Hi sg31,
That's great info on Fishing Republic (LON:FISH) - many thanks.
I've checked the Alexa (estimated web traffic rankings), and they look like this;
TedCarter.co.uk (Alexa ranking 1,314,128)
AnglingDirect.co.uk (Alexa ranking 157,000, and ranked 16,145 in UK)
FishingRepublic.net (Alexa ranking 748,000, and ranked 61,772 in UK)
The lower the ranking, the better - because 1 would be the most popular website in the world.
So clearly AnglingDirect is well ahead of FishingRepublic, and the only way to catch up, is to spend heavily on marketing. As one eCommerce entrepreneur said to me recently, "There are few barriers to entry, but huge barriers to achieving scale".
Also, I've just done a Google search for "fishing tackle", and there are absolutely loads of companies selling online. Fishing Republic appeared on page 3 of my search - so nowhere near where it needs to be, basically.
Regards, Paul.
sg31 / Paul
Good to see some discussion on here re: Fishing Republic (LON:FISH). I have been an investor since just after the IPO.
The issue of stock / inventory levels is consistently raised by investors (for good reason when measured against other retailers etc). I have discussed this personally with management and being an angler myself (and having visited their operations) tackle retailers have to carry a vast array of stock to meet anglers demand. FISH are not unique here other than their very high stock levels are compounded by the need to stock the ongoing new store roll-out; each requiring around £200k of stock.
I understand that stock is often discounted (as it does become outdated due to constant new product launches), however, very little discounted stock is sold at cost or less due to the decent margins. These margins are improving all the time as economies of scale kick in due to FISH's size / buying power especially as they are the only UK listed tackle retailer. I understand that once a store is established stock turn is around 4 times /yr.
A bigger issue for tackle retailers is NOT having stock as the angler / customer will just go elsewhere and Angling Direct are a major (online) competitor. FISH do have an advantage over online only retailers namely that anglers / customers can 'try before they buy' or otherwise look at the item they want to buy in any of the stores and can then purchase it for the same price as online.
I have bought from Angling Direct on a number of occasions (prior to being a FISH investor) and they do have a good site and good stock levels. The company is run / owned by some savvy accountants and they are certainly competition.
Glad to see that FISH are launching a new website as it did need work and was a bit clunky.
There has been some M&A activity (PE / VC) over recent years and I understand management ambition is to grow FISH to at least a £30m business and then look for a US or other major player to acquire them. I would expect to see 30+ stores (min) over the coming years.
I went to FISH presentation last year put on by Share Soc in Leeds.
I am a retailer rather than a fisherman but I was very unimpressed with the management and their shops and website.
I could not believe the share price then or now - it's about double what I would have expected.
I am often wrong but I really don't see this one going anywhere against capable competition.
Hayward Tyler (LON:HAYT) should be a significant beneficiary of the sterling depreciation, the fact that it is not indicates the problems that it is having integrating Peter Brotherhood, where business has been particularly weak. Today's announcement does not really contain much new news, as previous statement that the RBS loan needed to be rolled over indicated second half cash flow was flat. What I find difficult to read is why RBS is continually giving such short-term extensions to the debt rollover (RNSs on 14 Nov and 1 Feb). Is management indicating that cash flow just about to improve (so far without result) or has the bank little faith in management (despite management saying RBS is being supportive and RBS apparently demanding little in return for the debt rollovers)?
I think it's more likely that RBS are "inside" on the progress of a capital raise by Hayward Tyler (LON:HAYT), that's obviously not going too smoothly as the best rights issues are the ones done early before the share price halves..
Thanks. Sounds logical.
Hi Paul, did you publish your research on Next and Pets over the weekend? Just in case I missed it...
Cheers. Mark
Hi Mark,
No, it takes too long to do reports on all the companies I research.
FWIW here's the conclusion I've come to;
Pets at Home (LON:PETS) - looks potentially interesting on the numbers (huge disparity between valuation of this, and £CVS although they do have different business models.
A friend raised some concerns about ethics/risks about PETS operations, which put me off rather (e.g. unsold animals being disposed of to be killed & used as food at zoos, etc. Risk of spreading diseases, relatively inexperienced & poorly trained staff dealing with animals).
Next (LON:NXT) - I've taken the plunge here, and bought some. Although the sector is struggling, I feel this is now reflected in the valuation (fwd PER of 9.5 is the cheapest I can remember it).
Regards, Paul.
An interesting (and detailed) article has been posted about Next (LON:NXT) on the discussion forum: http://www.stockopedia.com/content/does-nexts-share-price-offering-at-50-off-present-a-value-buying-opportunity-171697/
Paul, how does this compare with your own analysis?
Paul
With regard to Proactis: PHD I am particularly fascinated with the idea that they have the theoretical ability to earn fees from allowing their software into a Customer's supplier base (with the Customer's permission) producing savings to the Customer, and to the Customer's supplier.
However, this strategy which is always hinted at, and which could theoretically generate significant revenues to PHD never had any metric attached to it, to measure progress. They can't keep trailing it as they do, and not report on it IMO. It maybe a slower cross-sell than they anticipated, but there is a danger of hype over substance, which is not a typical feature of a generally sensible company. I shall be looking for some info on this in the detailed next report of results.
It's a fair question, but my understanding is that they have pilot projects with three clients underway.
Given that no plan survives contact with the enemy, I am not expecting them to report marvellous progress on all fronts when do update us. My faith comes from believing that what they are proposing is both commercially sensible for the parties involved, and technically unchallenging.
Proactis has been a long-term commitment share for me, and recent price growth makes it my biggest single holding.
Jon
Fishing Republic were in dire need of a new Website re online sales and I note that this is being delivered 1/3/17.
This may increase trade but you have to be in for the long term for this one.
When you look at other large retailers, many of whom trade at a multiple of well under 10, the valuation attached to Fishing Republic (LON:FISH) just looks crazy.
I sold Hayward Tyler (LON:HAYT) when it breached my stoploss at 70p.
I recall that it was often said that appearing on Tomorrow's World was an warning of future commercial trouble. Other awards and celebrity visits may have the same predictive effect.
Another consideration to add to our checklists, perhaps.
I was v enthusiastic about the company for a long time as I love the engineering expertise and the fact they are global mkt leaders in their niche. Unfortunately the CEO seemed to be more motivated by awards & royal visits than securing the orders they needed. I sold out at a small loss when they issued their first warning, Thankfully there was a big buyer, the Edinburgh fund manager I assume, so I was able to extricate myself at a modest loss. I think the fantastic rebuilt plant, great technology and compelling moat will attract an industry buyer. The CEO needs to go and a sizeable equity raise needs to occur before I entertain investment again if it remains listed. A fascinating situation and an object lesson for me to put the story after the numbers rather than the other way round!
Unfortunately the CEO seemed to be more motivated by awards & royal visits than securing the orders they needed.
I completely agree and would add "questionable management quality" to Paul's list. In the cold light of day given the state of the balance sheet, spending £10m on the acquisition of Peter Brotherhood and another £10m on a new development centre to be opened by the Duke and Duchess of Cambridge looks poor decision making and financial control.
All the best, Si
I was invested in Hayward Tyler (LON:HAYT) but bailed out when they said a few months back that sales would be materially higher in the second half as it didn't read that way to me. I had been holding them for a couple of years on the promise of increased profits from the Luton Development Centre and the integration of Brotherhood but it always seemed jam tomorrow. Took a small loss but which would have been much bigger now. This was at about 80p and after this a fund manager started buying in his own name which was strange but initially reassuring. Moral of that story - don't trust anyone even if they are a professional. Definitely a case of do your own research..
Brilliant summary of the situation at HT. I was in these much higher and traded them for a modest profit so keep a weather eye on what's going on. With the benefit of hindsight I'm sure this could have all been handled much better. The broker gets zero marks though whatever they advised may have been overruled by a strong ceo. Peter B may work out well in the longer term but it has put considerable strain on the balance sheet. Some nettles have not been grasped here and the decision to keep the dividend looks unwise.