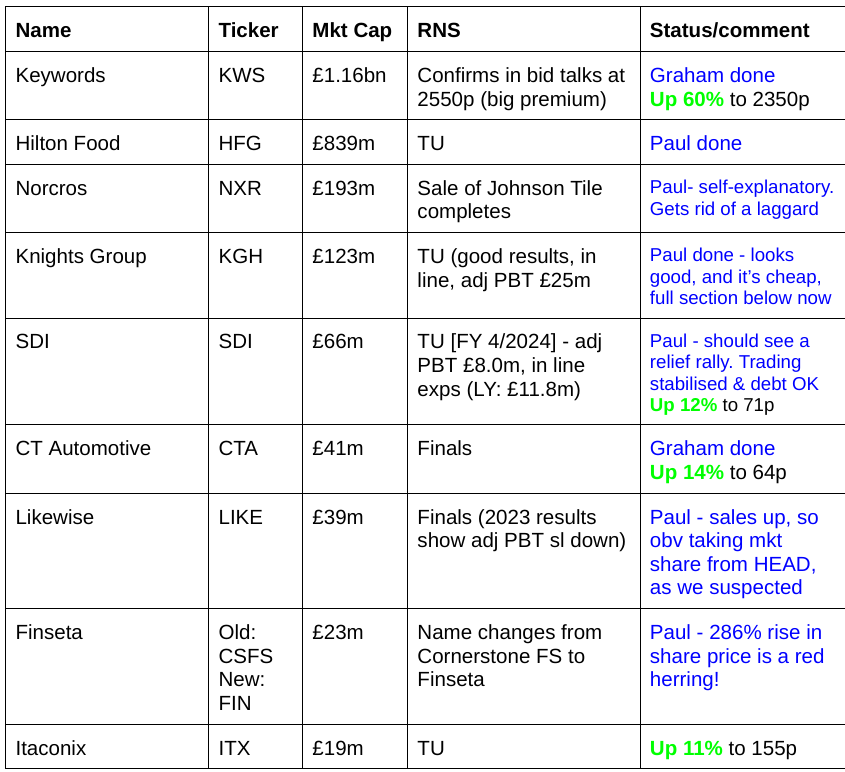
Small Cap Value Report (Mon 20 May 2024) - KWS, KNOS, VIC, KGH, CTA, HFG. Quick: SDI

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
List of Companies Reporting
Other mid-morning movers (with news)
Kainos (LON:KNOS) - up 11% to 1179p (£1.49bn) - Results FY 3/2024 - Paul - AMBER/GREEN
Impressively prompt reporting of FY 3/2024 results. Market clearly likes the figures & outlook. Adj PBT up 14% on 2% revenue rise. Adj EPS up 9% to 46.5p = historical PER 25.4x (should fall with further growth). Good outlook, and backlog up 11%. Dividend: 27.3p. Note that c.9% of profit goes on share options charges, and is adjusted out, which seems questionable. Healthy, ungeared balance sheet. Looks a good company, with excellent long-term track record, and further growth expected. I’m not sure of the colour, but AMBER/GREEN feels only fair, just based on a quick review.
Victorian Plumbing (LON:VIC) - up 7% to 91.6p (£299m) - Acquisition of Victoria Plum - Paul - AMBER
Acquisition - AHK Designs Ltd, trading as Victoria Plum - an online-only competitor in the bathroom fitting market. Price is £22.5m, funded from VIC’s cash reserves. As a reader questions below, I also wonder if VIC has overpaid for a failed competitor? -
“The Company's expectation is that Victoria Plum will be broadly break even in the second half of 2024. Given that Victoria Plum has recently been through an administration and there is already a cost reduction programme in progress, the Company intends to continue to trade the business as normal initially, pending finalisation of our integration plan.”... For the six months ended 31 March 2024, unaudited management accounts indicate that Victoria Plum had book value gross assets of £15.8m and losses of £3.3m.
Administrators are usually desperate to sell businesses as a going concern as fast as they can, so the price does surprise me. Maybe there were other parties with deep pockets sniffing around? Rules seem to require reporting gross assets, which of course is meaningless! It’s net assets that matter.
The only information at Companies House about AHK Designs, shows what looks like an almost dormant shell company, which only filed micro company accounts up to 9/2022, which seems odd.
Paul’s view - I quite like VIC, as it’s profitable and has a sound balance sheet. It can afford this acquisition, although I am curious as to why they’ve paid so much for a bust competitor? We need more information to explain the rationale for the deal. Management know their sector far better than any of us, so we have to trust they’ve made the right move. I was amber/green on 22/11/2023, and Graham was amber (but sounded quite positive in his remarks) on 27/2/2024. Since I’m not certain this deal is a good use of the cash, I think it’s safe to go with AMBER for the time being, until we have better information. It would be good if they do a webinar to discuss this deal.
Summaries of Main Sections
Keywords Studios (LON:KWS) - up 60% to 2350.8p (£1.86bn) - Statement re Possible Offer - Graham - PINK (takeover approach) - AMBER on fundamentals
Shareholders wake up to what seems (in my opinion) a generous potential offer from an enormous private equity company. By my sums, the earnings multiple on current year forecasts is around 24x. Not only would I sell KWS at that price, I’d even consider selling out today at a discount, to lock in some gains.
Knights group (LON:KGH) - up 4% to 147p (£126m) - FY 4/2024 Trading Update - Paul - AMBER/GREEN
An in line year end update looks pretty good, and shares look attractively cheap. Digging further I do find some less pleasing aspects in the numbers, but overall I think bull points outweigh bear points. So AMBER/GREEN today.
CT Automotive (LON:CTA) - up 23% to 69p (£51m) - Final Results - Graham - AMBER/GREEN
Excellent results from this supplier of vehicle components, manufacturing out of China, Mexico and Turkey for most of the world’s largest vehicle producers. I study the financial performance in some detail and do have some concerns, but there is little doubt that the company is now in a vastly improved position.
Hilton Food (LON:HFG) - up 1% to 945p (£846m) - AGM Trading Update - Paul - AMBER
In line with expectations. I struggle to see why this share has strongly recovered from last autumn's lows, when it seems an unattractive, low margin business. Are buyers expecting it to beat forecasts, perhaps? It hasn't done today. Recently reviewed Premier Foods (LON:PFD) looks a far better quality business, if you have to own a food company, in my view.
Paul’s Section:
Knights group (LON:KGH)
Up 4% to 147p (£126m) - FY 4/2024 Trading Update - Paul - AMBER/GREEN
Knights, the legal and professional services business, today provides a trading update for the year ended 30 April 2024.
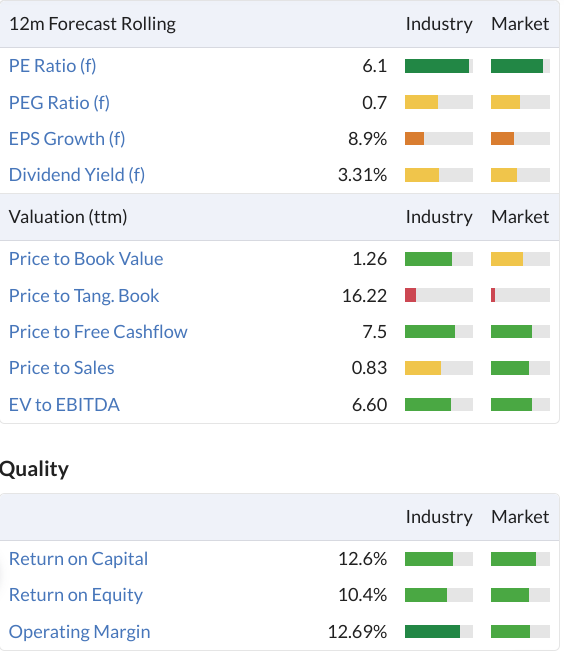
Going back through our archive, and looking at the share price, this was a fully valued firm of lawyers until 22/3/2022, when it plunged 50% to 186p on a profit warning which blamed the pandemic, and a fall in general business confidence. Here we are just over 2 years later, and the share price has still not recovered all of its losses, as just 147p. However, on the StockReport metrics, it’s now looking cheap, and has respectable quality measures too -
Today’s news, key points (for FY 4/2024) -
Revenue £150m (double H1), up 6% vs LY
Good underlying PBT of £25.0m+ (up 16%), usefully up on £11.6m in H1, so looks like margins improved in H2.
Profit is “within range of market expectations”, but no footnote.
Debtor days claimed to be 28 days (down from 30 days LY), but I challenge this number as it looks like only relates to invoices billed. The H1 balance sheet showed a larger number of unbilled receivables. So this looks a little bit like a positive spin to me, that collapses under scrutiny!
Net bank debt of £35.2m is well within its £70m facility. It’s stated after absorbing £11m of acquisition-related payments including buying Convex Capital off RBG Holdings (LON:RBGP) (I hold). I feel the debt is a little warm, and would like to see it come down somewhat.
More acquisitions being planned.
Outlook - vaguely positive, saying “well positioned for further growth” in 2025.
Valuation - no broker notes available to us, which the company should address. Stockopedia shows consensus PAT of £19.0m, which is consistent with the company’s latest guidance of underlying PBT of £25.0m. That ties in almost exactly, if we take a standard 25% corporation tax off PBT. Forecast EPS of 21.5p therefore looks reliable, giving an attractively low PER of 6.8x
Although bear in mind net bank debt is about 28% of the market cap, so I would adjust this up to a PER of ballpark 8-9x accounting for debt, still an undemanding valuation I’d say.
Although note KGH is keen on adjusting out “non-underlying operating costs” in its headline numbers, which are hefty at £2.8m in H1, and £6.8m LY. So this is a key point you need to get comfortable on before buying this share, I suggest.
Balance sheet - fairly threadbare, due to KGH liking repeated acquisitions. Although NTAV still positive at c.£7m, and net debt whilst large, is not dangerously large (but could become so if trading falls off a cliff again).
It’s not unusual for listed firms of lawyers and accountants to get into trouble from doing too many acquisitions on bank debt. In fact it’s worryingly frequent!
Paul’s opinion - I’m impressed by the growth, strong H2, high PBT margins, and of course a low PER.
Less keen on - thin balance sheet, a bit too much debt, lots of adjustments every year.
Owner/manager David Beech stands out as a shrewd man who knows how to sell high (in huge size), and buy back low (in much smaller, but still significant size!).
Overall, I think the positives outweigh the negatives, so I’m comfortable at AMBER/GREEN, based on the information available today. I keep having to stress this to a handful of readers - that I’m not able to time travel into the future, and tell you what happens next! My friend Gina is a clairvoyant though, so I'll ask her what she thinks the share price here will do! Probably along the lines of, "I see a chart bottoming out, which might be gooooood" -
Hilton Food (LON:HFG)
Up 1% to 945p (£846m) - AGM Trading Update - Paul - AMBER
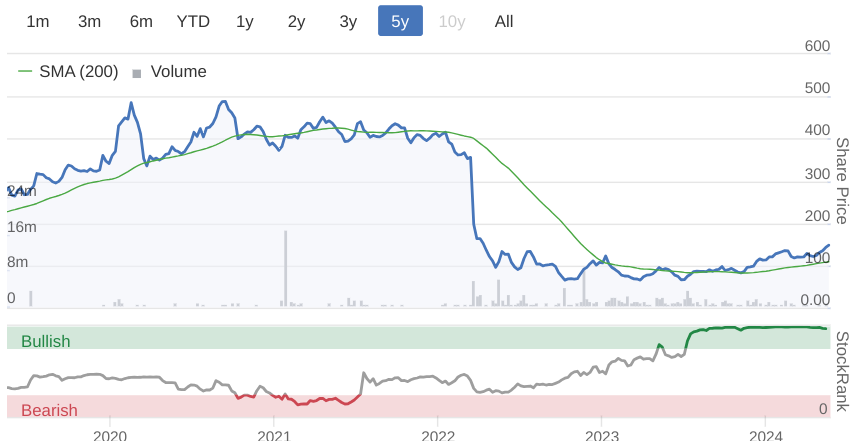
This very low margin food producer has never interested me, but we always look at each share with fresh eyes, and change our minds when the facts change here at the SCVR. The share price has put in an impressive c.50% rise since the autumn 2023 lows, so buyers must see something interesting here. Let’s see if I can figure out what it is!
Hilton Food Group plc ("Hilton Foods" or the "Group"), the leading international multi-protein food business, today provides a trading update for the period from 1st January 2024 to date, ahead of its Annual General Meeting to be held at noon today.
Trading in line with expectations; volumes and sales ahead of last year
More granular detail is provided, but I’m only interested in the overview, which is in line.
Outlook -
Hilton Foods' trading performance since the start of 2024 has been in line with the Board's expectations. The business remains well-positioned for the year ahead despite the continued challenging market environment and economic conditions.
Our short and medium-term growth prospects are underpinned by the strength of our multi-category offer and continued progress in our UK Seafood business. We are well placed to deliver long-term value to all stakeholders through our customer partnerships and with our strong financial position we continue to explore further growth opportunities and wider geographic expansion.
Paul’s opinion - there’s not really a lot to add to my AMBER view of the FY 12/2023 results here on 3/4/2024. HFG makes a tiny profit margin, and a lot of that is absorbed by finance charges, leaving a paltry 1.5% PBT margin.
The bull case must rely on people thinking that margins can be increased significantly - so it’s easy to see how even small margin improvements on £4bn pa revenues, could transform the profit numbers. So maybe that’s the key area to research?
I looked recently at Premier Foods (LON:PFD) - a food manufacturer with brands, and decent pricing power, making vastly superior margins compared with HFG. There’s no contest in the quality of the businesses (compare their gross and net margins!) , PFD wipes the floor with HFG in my view.
Do any readers hold HFG? If so, why? I’d be interested to hear what the bull case is.
Graham’s Section:
Keywords Studios (LON:KWS)
Up 60% to 2350.8p (£1.86bn) - Statement re Possible Offer - Graham - AMBER
Bombshell news from Keywords as they confirm that the company:
…is in advanced discussions with a fund which is part of the EQT Group ("EQT"), a purpose-driven global investment organisation, regarding a possible cash offer of 2,550 pence per share
Interestingly, there were four previous unsolicited proposals from EQT in recent months, all of which were rejected by the Keywords Board.
However, they “would be minded to recommend” the latest possible offer.
It’s important to emphasise that the offer has not materialised yet - it sounds like they are still early in the process.
As usual, the potential buyer has 28 days to announce a firm intention to make an offer, or to walk away. That gives EQT until 15th June.
About EQT: EQT is described as a “purpose-driven global investment organisation” in today’s RNS. It’s one of the top 10 PE firms in the world, originally from Sweden and listed on the Stockholm stock exchange. Of course it’s a huge thumbs up for Keywords that it caught the attention of such an outfit.
Graham’s view
We’ve not been huge fans of this share in the SCVR, believing at times that it was overpriced. But when I covered it in December 2023, I thought that it had arguably grown into its valuation during the post-Covid era, with the PE Ratio having fallen to 13.5x, and I took a neutral stance.
Coincidentally, that’s about the same as the multiple it was trading at last night, before this potential offer was announced:
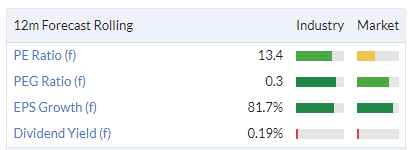
Paul also checked it out in March, upgrading to AMBER/GREEN (well done), on the back of good full-year results which included revenue growth of 13%, or 5.6% organic growth, and a very strong outlook statement.
If they do the deal at 2550p per share, EQT will be paying 24x the EPS estimate for the current year (using the estimates on the StockReport, and converting Euro cents to pence).
Granted that I’ve been a little sceptical of Keywords in the past, but personally I would be satisfied to cash in on Keywords at this price. The results have tended to be very heavy in adjustments, so the company isn’t posting “clean” profits and therefore cashing in at a PER of 24x would be attractive to me.
Organic growth is expected to improve in the current year, but from a modest level.
And the balance sheet is not a fortress: the company has used some borrowings to fund acquisitions (net debt last seen at €68m), and has negative NTAV.
EQT might very well have a successful investment at 2550p, but I’d rather be the seller at the price. I’d even consider cashing in some KWS shares today at a discount to that level, in case the deal falls through.
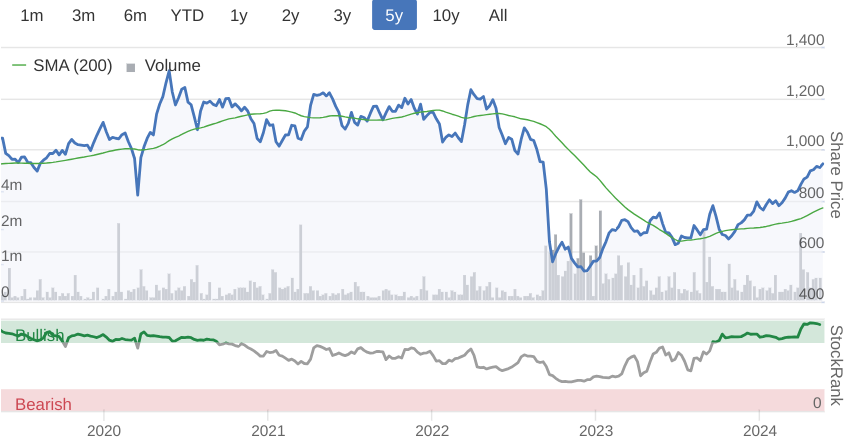
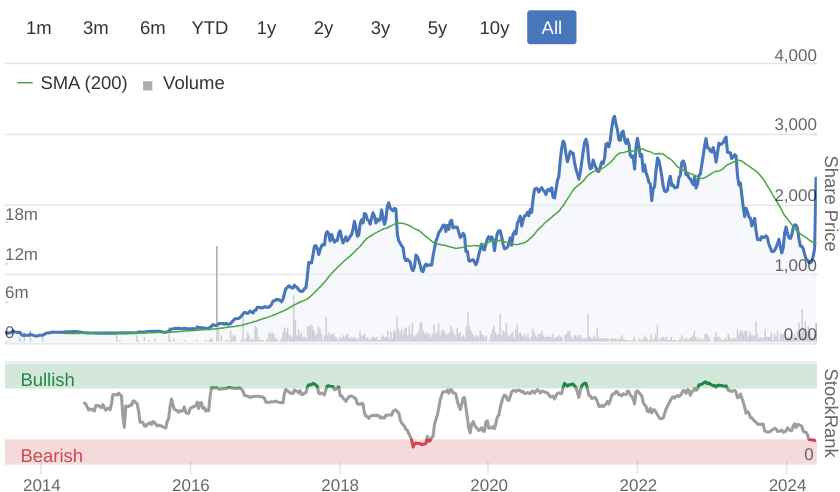
Paul adds: major multibagger from 2014 to 2018 - here's the chart since it floated -
CT Automotive (LON:CTA)
Up 23% to 69p (£51m) - Final Results - Graham - AMBER/GREEN
CT Automotive, a leading designer, developer and supplier of interior components to the global automotive industry, today announces its results for the year ended 31 December 2023 ("FY23").
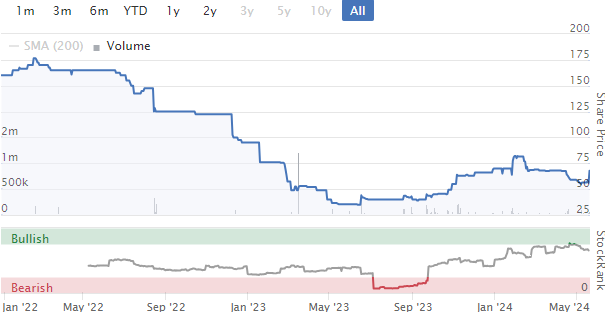
This is a 2021 float; after a terrible beginning to life as a listed company it has more recently been on the rebound. Paul turned GREEN on it in June 2023, and the shares have approximately doubled since then:
It supplies components to nearly all (22 out of 23) of the biggest vehicle manufacturers in the world, spanning both premium and mainstream brands, and ICE/BEV/PHEV. 57 car models are currently receiving components from CT Automotive.
(For context, major car manufacturers have thousands of suppliers each - I’ve seen an estimate that a large manufacturer could have as many as 18,000 suppliers!)
The company manufactures out of China for the most part, but also Turkey and Mexico.
Today’s results for 2023 are quite late, aren’t they? But here they are:
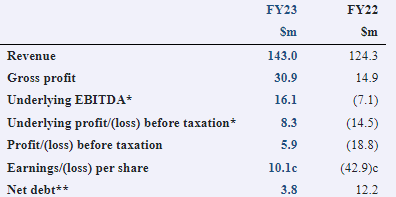
As flagged, these are terrific results: revenues up 15%, an enormous swing from losses into profitability, and a big reduction in debt. But remember that the company raised $9.6m in new equity, and so it would be shocking if they didn’t succeed in reducing its debt.
Profits in 2023 were greatly boosted by an improvement in gross margins, so let’s hone in on this for a moment:
Improvement in gross margin is a key ongoing focus. In 2023, our gross margin grew from 12% to 22%, an excellent achievement due to the hard work of all employees across the Group. This expansion came from measures taken to reduce unit labour costs as volumes recovered, as well as from a significant improvement in raw material costs. Whilst undoubtedly, margins benefitted naturally from volume improvement in a more normal market environment, a significant proportion of the recovery came from internal actions to improve production efficiencies, the full impact of which is still coming through in 2024.
So a combination of both internal factors (efficiency/cost-cutting) and external factors (higher demand) enabled the company’s success last year.
As we are already nearly halfway through 2024, let’s now skip ahead to the outlook section.
The company is currently trading in line with expectations for 2024 (emphasis added):
In line with our expectations demand volumes have moderated as OEMs align inventory levels with normal market conditions
This will be partially offset by our new business pipeline, building on wins with Ford, Marelli and Rivian
Margin improvement initiatives made in FY23 will annualise in FY24 with ongoing cost programmes expected to further benefit profitability in the current year
We are currently in advanced negotiations to secure a new debt facility
In summary: the Covid era saw exceptionally slow demand, then 2023 saw a surge in catch-up orders, and now 2024 is a more “normal” year.
Balance sheet
CTA has net assets of $17m, almost fully tangible. Inventories ($26m) and receivables ($31m) are substantial: both are much larger than PPE ($7m) but I would say they are at reasonable levels given the revenue they are supporting.
Cash flow
The cash performance was vastly improved in 2023: $8m generated from operating activities, with only $3m spent on capex, leaving a positive margin of $5m (last year: only $5.5m generated from operating activities, with $3.5m spent on capex).
However, overall, I still don’t think the cash performance was all that good in 2023.
According to the company’s own calculations, its conversion of EBITDA (a fairly pointless metric for a manufacturer) to cash was 59%.
When I look at the cash flow statement, I’m drawn to the interest bill ($2.5m) and lease payments (of which $3m are included in “cash flow from financing activities”).
When I include these items in the calculations, I’m left with the conclusion that the business generated very little cash during the year.
I also note that very little or no corporate income tax seems to have been paid, which is giving the company a temporary boost.
Net debt: the company finished the year with a low net debt figure but it was still carrying $9m of trade loans and $4m+ in invoice financing, even after applying some of the money it raised to reduce its invoice financing facility.
Graham’s view
It won’t come as a surprise that I think CTA should be trading at a cheap earnings multiple, given the industry we are dealing with and some of my concerns around its cash performance mentioned above.
But perhaps the market was pricing this too cheaply last night, given that the company is enjoying positive momentum in revenues and profitability. Hence we had another pop in the share price this morning:
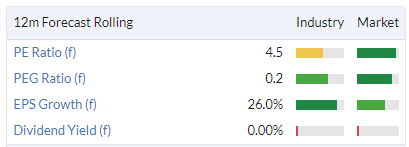
I’d like to see the company generate real cash by itself this year, without a further equity injection from investors. If I saw that, I’d happily go GREEN at the current valuation. However, for now I’m much more comfortable with Paul’s AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

86 comments
Kier (LON:KIE) has dumped housing for govt infrastructure which sorry is a positive in investment terms.
No insights just noise sorry ..
The group has four main divisions – Construction, Transportation, Natural Resources, Nuclear & Networks, and Property.
Construction – Delivers public and private sector projects around the UK, across sectors including education, healthcare, custodial and defence.
Clients include – Department for Education, Ministry of Justice, Department of Health & Social Care, Ministry of Defence, and the Crown Commercial Service.
Transportation – It is a leading provider of sustainable transport infrastructure solutions designing, building and maintaining infrastructure for the highways, rail, aviation and ports sectors.
Clients include – Network Rail, National Highways, HS2, Transport for London, Local authorities, and Combined authorities.
Picks and shovels. Or if you prefer bites and bits.
The weekly base is in methinks as a silly tea leaf chartist.
Kier (LON:KIE)
Windward (LON:WNWD) The shipping software, tech company.Not sure what kinda sales multiple this should trade on and any other competition or the total tam (so not much ha!).But the software seems to still be in demand (sold down a bit after a good run and on a director reducing a while back.They still have 6.5% of the company though).Hopefully the growth continues to continue after the pirate shipping attacks in the middle east, as the software seems to target a few different capabilities.And i assume it isn't easily and quickly replicable and the company's brand/reputation/penetration only increases.All fingers and toes crossed!
AGM Statement : 'The Board is pleased to report on a period of strong trading and execution against our strategy in FY24 to date, in line with our expectations. We have made further progress in growing our commercial revenues, and renewals for our government segment also remain on track.' Government contracts were the lumpier, although bigger ones, ones which were harder to predict i think.Good to see their focus on increasing commercial is penetrating.'Looking ahead, we are confident in achieving our stated goal of reaching an EBITDA break-even run rate during FY24'.
Tricky one, Windward (LON:WNWD) - as we've mentioned before here, it sounds intriguing, but it's loss-making, and quite small and niche. Has enough cash for now though. £87m mkt cap seems enough to me, until they can prove up a viable business model.
One of so many small companies claiming to use AI.
Fine - make some money from it then. EBITDA isn't profit remember.
I'll keep an open mind, but it's currently more a speculation than an investment. Speculations do well in bull markets though, so could be good, who knows?
One competitor is Norwegian company Kongsberg Gruppen ASA (STO:KOGo) which is listed on Stockholm and Oslo. I have held for 7 years. The Norwegian Government hold a 50% stake and, as well as marine security and tracking, they are also involved in aerospace and defence and have a satellite systems business.
thank you to Megan Boxall for highlighting Keywords Studios (LON:KWS) as a quality company at reasonable price a few months ago, which I then researched and analyzed and bought half position just a week ago. My extensive analysis has resulted in an intrinsic valuation of (rounded) 3,000p per share, so the bid offer is an opportunistic offer imho. Shame i did not have enough time to complete my position.
Great!
Just as an aside, Graham and I have reviewed 473 unique companies in the SCVRs so far in 2024, including an AMBER/GREEN for KWS here on 13/3/2024.
Pity none of those caught your eye.
Keywords Studios (LON:KWS) was a no brainer for the gaming industry but then the AI hype kicked in. Seems private equity can read the room better than others.
I hold underwater. Work tomorrow so what will be will be.
Hilton Food (LON:HFG)
Given Paul's comment "I looked recently at Premier Foods (LON:PFD) - a food manufacturer with brands, and decent pricing power, making vastly superior margins compared with HFG. There’s no contest in the quality of the businesses (compare their gross and net margins!) , PFD wipes the floor with HFG in my view." My question is: so why do they both have the same Quality Rank of 90 then?
Cranswick (LON:CWK, the UK's largest pork business, is also worth a look. They are working closely with Aldi to expand production. They have decent quality metrics: ROCE 16.2% albeit tight margins of 7.02%; a strong balance sheet backed by hard assets (farms and abattoirs) with low gearing, and good cash conversion. I hold and have held them for many years.
Knights group (LON:KGH) What on Earth is an unbilled receivable. There is no receivable until an invoice has been delivered to the client. Work in progress would be the correct terminology.
Or work done but not billed yet?
Hi Sharewallah,
"Knights group (LON:KGH) What on Earth is an unbilled receivable. There is no receivable until an invoice has been delivered to the client. Work in progress would be the correct terminology."
To clarify, this is what I'm referring to - "Contract assets" being their terminology - this is unbilled receivables I think - from KGH's Oct 2023 balance sheet - or Work-in-progress could be another description -
My point was solely that KGH claiming 28 day debtor days is clearly nonsense.
Thanks, Paul.
Knights group (LON:KGH)
What on Earth is an unbilled receivable
To be fair to Paul the company themselves call this unbilled revenue in the annual report rather than directly calling it work in progress as such - they then blur the lines by mentioning work in progress just to add the the fun and games.
Ref the true debtor days this is the "lock up days" as this factors in the unbilled revenue - to be fair to the company they do quote the lock in days stat next to the debtors day stat on page 60 of the annual report - an that stat is reasonably consistent for last 3 years. Heck if they are quoting this stat why not go the whole hog and call it what it is - an "unbilled receivable"
YouGov (LON:YOU) - YOU are not serious, are YOU? Could it be something's cooking?
Very lucky timing with my decision to purchase a couple of weeks ago
"Very lucky timing with my decision to purchase a couple of weeks ago"
Great, thanks Thomas. I was wondering when you might have bought.
Thanks for the sarcastic comment, Paul. I only commented because I posted here about YouGov 2 weeks ago and I did indeed get lucky timing.
Beautifully clarified, thank you.
In hindsight, it was a pointless comment and apologies for taking away from the discussion. I shared without much thought and, as I said, I was surprised by the movement and attributed it to complete luck. Keep up the great work. Good night.
Nothing marked as green today! Didn't have any of the companies covered today on my watchlist and seems like it will stay that way!
If I was holding Keywords Studios (LON:KWS) I'd sell straight away, seems like a huge premium compared to the closing SP
REF - Mello
Anyone going ?
I was going to go but have been struck down the dreaded CBA virus .
If anyone going would it be possible to make some notes and share on
- posh bloke Christopher mills presentation (22nd 11 am)
- Rockwood / staveley (Thursday )
bit cheeky I know but CBA virus is hard to shake off plus it’s my birthday 22nd
Any volunteers or do I have to drag myself out of my stupor and make the effort ?
Is CBA 'can't be A'd' or the rare one that affects mice?
Not the mouse one
looks like I’m finding my mojo so might make it
Come on PlanetX, you're better than this -
" posh bloke Christopher mills presentation"
And I thought that was a compliment .
Hole... digging...
Not at all
Keywords Studios (LON:KWS) had almost 4% short interest as of Friday. What would the strategy of those caught short be this morning? I assume close as soon as they can?
Keywords Studios (LON:KWS)
What would the strategy of those caught short be this morning?
A change of underpants?
I have not been invested in this company £KWS all that long but the bit of turn around plus the potential bid premium made this a sell according to my investing rules
My main reason for adding a comment is regarding the trading platform that I have been using “II Investors” The only reason that I have been using them is because “Selftrade” dumped me there when they got tied of small investors
I tried to sell my KWS and was unable to trade them on line with II Investors
I have many other moans about II Investors and was wondering if anyone else has any opinions on them or is it just me?
I have had occasional issues with ii. Whenever I have had any problems I phone them and speak to a real person. All problems sorted very quickly.
I wanted to buy EBOX, but their system wouldn’t let me. I could only buy the Euro version, BOXE. I called them, they explained why this was the case, and then traded for me over the phone at online rates. I have always found the staff to be excellent.
Keywords Studios (LON:KWS)
i suspect todays specific news might caused any provider to have issues providing firm quote online - material price change news shoud be expected to cause temporary issues with regard to getting firm prices - particulalry online . I have used ii and found that normally they are fine overall for my purposes - even when they dont provide firm price the other options available tend to do the job.
Note i think the price quickly trended down from 2450p ish first thing to 2350p ish sometime before 10 - so with price trending down quickly thats the exact time i would expect online firm quotes to be unavailable. so i expect if you wanted to sell in that window you wopuld have had to expect to take a lower than advertised price if it was continually updating in downward direction. Due to swings they may also be over cautious now even perhaps ?
Unfortunately for me as a newish holder i was awol first thing so i missed the chance to sell up at the opening price - slightly annoying as perhaps there are more uncertainties here than would not normally be the case - albeit who knows if this news might perhaps trigger someone else to come along so it could go eitehr way - the price offered does seem a fair premium compared to where the market has valued the company for the last 9 months or so - so fair play to board for getting the offer to fair and reasonable value from my point of view. Was feeling slightly left out with regard to takeovers ref my holdings until recently thats up to 4 for now in 6 months though so at least i feel like i havent totally missed the boat with this one and other recent similar ones.
I have had a letter from them showing a small investment and current value. However I never opened an account with them and was not even aware this company existed. I called them on their expensive 0345 number and after speaking to someone was asked to hold, however, gave up after 20 minutes. Does anyone have an email for them by any chance?
SDI (LON:SDI
Bull Case: SDI looks cheap vs its historic valuation and the shenannigans of Covid trading / overstocking & destocking by clients seems to be behind them.
Bear Case: Their recent acquisitions have been on an EBIT multiple of about seven times, so a PER of about 9.3x. This is similar to SDI's current rating so without a rerating the shares are not a useful acquisition currency. Nonetheless the company has some leverage at it disposal (though more expensive now!) and is generating cash so acquisitions can continue for the moment, they just need to be good uns done at the right price!
If their companies trade reasonably well from here (I hope) there is likely to be a rerating and the upside could still be substantial. Meanwhile, in the absence of any future profit warnings, the shares look moderatly rated. I hold (its been painful, one of my worst holdings ) and have bought more this morning.
Victorian Plumbing (LON:VIC)
I just wondered if the purchase is about taking out a (failed) competitor with a slightly similar name. May have been slightly confusing for retail customers. Also, I assume the sales of Victoria Plum will now all go through the new Leyland warehouse .
Given Keywords Studios (LON:KWS) have told us there were 4 unsolicited offers in recent "months", the chairman must have been chuffed to bits to get this share purchase through only a couple of weeks ago. Non-discretionary but extremely smelly in my view!
https://newsfile.refinitiv.com...
Keywords Studios (LON:KWS) He has bought similar amounts roughly every quarter, over the last year. This is his fourth purchase.
Keywords Studios (LON:KWS)
could it be that he has prior agreement to buy shares at specified times all setup in advance ? i know they certainly allow that stuff in the usa - so wouldnt surprise me if stuff like that booked in advance was allowed?
Yes - you can set up non discretionary purchases. That means an independent entity who has no inside information buys either at certain regular intervals or based on certain price criteria. The ultimate beneficiary has no ability either to revoke the order to purchase or sell unless they are in an open period, where they are then subject to insider rules (MAR).
So looks like the Keywords Studios (LON:KWS) Chairman has had such a purchase order in place for some time. The CEO at Hostmore (LON:MORE) has a similar arrangement. It is often used when a board member is contracted to spend a certain amount on owning shares.
It’s not smelly at all. It is actually a very good way of allowing directors to buy/sell shares without constantly trying to time a window. Of course it means the order is irrevocable so can be quite a good indicator of how confident a director is.
I like them less for sales as sometimes it means directors get cheap or free shares that are also sold in the market at regular intervals effectively creating a cash out for them - or a variable cash bonus. Of course that is diluting shareholders at the directors expense and I much prefer to see a direct bonus to compensation so shareholders can easily decide whether said bonus is fair or otherwise.
When I say smelly, my issue was more to do with the fact that as chairman he had a lot of influence over the timing of the release of price sensitive information to the market. It was in his interest to delay it as long as possible.
No doubting that legally there's no way to challenge his purchase - just taking a step back with 4 bids now disclosed there's been something of a false market for a while now.
In another scenario where a profit warning was on the cards, there'd be an incentive to get the bad news out quickly.
These non-discretionary arrangements can be dressed up as not open to abuse, but as insiders directors and especially the chair still have one over the rest of us.
Assuming he had the regular purchase in before the bidding started, what do you propose he did?
Request to cancel his share purchases, knowing that there was a bid coming, during an open window? Was there even an open window for him once the bidding started? And what would you have said if he had done that, the market had taken it badly, then he had realised a lower bid value for the company because the share price fell?
I am just struggling to see what you think he could have done better here.
Fair question CautiousValue. Also rmillaree makes fair points. Ultimately it seems there was a choice to disclose something to the market earlier in the process, or not to, and the company chose the latter route. I’ll just have to accept as a quirk of current rules.
Keywords Studios (LON:KWS)
When I say smelly, my issue was more to do with the fact that as chairman he had a lot of influence over the timing of the release of price sensitive information to the market. It was in his interest to delay it as long as possible.
its easy to throw conspiracy theories about here and sling mud.
facts are
He doesnt make up the rules he just follows them.
this is clearly a bit of an outlier of an event type - can everything be covered by existing rules perfectly i suggests not.
proof of the pudding - the proof of the pudding is that they seem to have extracted full value here by playing hard ball** , was he to know that playing hardball would work? it may very well have not worked and shareprice might never have risen had the other party walked away. If the agreed deal is only agreed now "ish" i would suggest he probably hasnt dictated the pace the other party has been increasing their offers at that up to the other party when they increase their offer.
** note i suspect its quite common for firms to "chance their arm" when making non binding offers for a company - who knows what their motives are if they are trying to "look at the books" without being forced to make an offer. So whilst agreeing very much with Paul and others who thing there should be lower bar for publishing news to the market- its probably no unusual for companies to receive derisory offers than may waste their time if they have to be over officiuous in being seen to keep the market involved.
I appluad the board here for sticking to their guns and ensuring the agreed price is one that seems acceptable and reaosnable to most small investors - so i am sure some can see value outing anyway imho here the board seem to have donen their jobs diligently.
Note the board are often well looked after when a company is taken over so - imho the main danger here is them accepting lowball offer and being rewarded of book for proposing something that may not suit shareholders.
Finally i would prseume there are certain standard that are expected when one is listed company director - so its entirely possible this issue is covered either in the detail of his contract or his qualifications to hold this post or something similar.
In some repects it suggests good practice by the board that this news seems not to have leaked till there was an agreed price made - at which time if the news is in the papers over the weekend practicably speaking thats an acceptable time for that info to leak out.
Just as a reminder about tickets for the two day Mello show this week in Chiswick, London where you can meet all your Stockopedia favourites....Ed Croft is on stage and the two BASH sessions with Damian, Mark, Leon and many more...
Mello2024 Line Up – Mello Events
Mark Simpson has a code for 50% off so you can thank him for a discounted ticket. It is Simpson50
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24
Cavendish Financial (LON:CAV)
Price 13p
Market Cap £50m
SP seems too low to be ignored.
Last update Cavendish Financial (LON:CAV) had £20m in cash up from £12m. This makes the EV only around £30m and probably a lot lower by 2025 year end. Also, cost savings (after the merger) are too high compared to the current market cap.
Can afford to pay big dividends and initiate extensive buybacks at current levels based on its cash flow generation.
All the best
I think there may have been an overhang from the merger for a while, it's up 30% this Month and 16% this week alone, still going strong.. Perfectly placed for the imminent bull market imo
Cavendish Financial (LON:CAV)
I agree again yiannos about Cavendish Financial (LON:CAV) and bought last October. I had previously held Cenkos. Cavendish is up a lot since then but still looks cheap.
What excellent comment that was on Cavendish Financial (LON:CAV) from Graham Neary last September. As Graham pointed out it looked in an excellent competitive position for the next bull market, and there are clear signs now that it has started. Here’s that comment:-
Cavendish Financial (LON:CAV)
7.9p (unchanged) (£29m) - AGM Trading Statement - Graham - GREEN
The combination of investment banks finnCap and Cenkos now has the unfamiliar name “Cavendish Financial”. The merger completed earlier this month, creating a business with nearly 200 staff and 220 quoted clients - making it a heavy hitter in the markets we cover here.
Staff have moved offices, trading has moved to a single platform, and there is “substantial progress” with IT integration.
I share their belief that the synergies should be significant and that the combined group should be stronger than the sum of its parts. In difficult market conditions, I think it makes sense for companies in this sector to consolidate and create a stronger group that should hopefully be very profitable in the next bull market.
Speaking of market conditions:
Graham’s view
As of March 2023, finnCap had tangible equity of £12.5m.
As of December 2022, Cenkos has equity of £22m.
The combination now has a market cap of £29m (there are 362 million shares outstanding, at about 8p each).
I am waiting to see a financial statement from Cavendish but I’ll tentatively give it the thumbs up on the basis that it will be in an excellent competitive position in the next bull market (if there is another bull market!) and there is a good chance that the market cap is offering a discount to tangible equity.
Nice to see people catching up on Cavendish Financial (LON:CAV) (I hold).
Graham is our resident expert on this sector, and was bullish on this at a much lower price. Pleased that I managed to slip a few into my personal portfolio too.
We're going to (collectively) enjoy this bull market, as we all look like geniuses now!
Pesky useless UK small caps? Damned to under-perform forever? Don't you believe it. Value attracts buyers, hence all the US bids. I'm up 25%, and Graham's up 27% - in under 5 months. Performance stats.
The worm has turned! I aim for 20% pa, which compounds stunningly. 2024 gains already in the bag, and we're only warming up.
Yes, I've had a drink.
Morning all,
Knights group (LON:KGH) solid update, 16% profit growth on a PE of around 6. Mcap 120M PBT 25M looks way undervalued to me!
Hi Paul, if you are open to a Monday challenge, and have some time today, could I ask you to take a fresh look at Nexxen International (LON:NEXN) as several key aspects have changed since your review last August.
The company is seeing early signs of an upswing in demand after a bruising downturn in the advertising industry over the past couple of years. It has fully repaid debts (seemingly taken on to bolster acquisition plans), and it is generating real and sustained cashflows which have enabled multiple buybacks over recent years.
The interesting point today as the broker notes is that any upside on revenues would lead to strong operational gearing and high drop through rates to profitability and cash flow.
While there are factors that detract (high director remuneration, murky company history, hard to understand sector), if this goes into another upgrade cycle, it could do very well once again.
My lesson from holding through the past few years is to step off at the right point this time!
Hi 1James1n1
Nexxen International (LON:NEXN) results looked good to me. They’ve done the sensible thing and paid down debt in entirety and using free cash flow to buy back shares. First time in a while that they’ve not only slightly beaten expectations for a quarter but also articulated that Q2 momentum is giving them confidence ion the full year. Given the increasing business confidence I think the ad market has just started to turn and I think a beat could be on the cards this year.
If that proves to be the case then I think that says that even in a nasty downturn Nexxen International (LON:NEXN) should be highly cash generative and in an upturn can take advantage of the enriched pickings. At that point I expect the market to re-rate it from a boom and bust rating to a more cyclically smoothed version. CTV is core to their forward looking strategy so they do need to see this organically growing at a good clip. Whilst Q1 in that regard wasn’t great it appears as though Q2 has seen a positive upturn so let’s see how that progresses.
I’m long - I think in a bull market this could have a long way to run from here.
Hi james,
No I'm sorry I can't be coaxed to look again at Nexxen International (LON:NEXN)
There are just too many red flags for me, and concerns over the sustainability of the business model. I'd rather focus my energies on companies where the business model makes more sense to me, and seems easily understandable and sustainable.
Good luck with it, and I have no opinion on what the share price might do, seems to be rising, so happy days for you hopefully! Just don't think I can add anything to the debate, so would rather focus on other things, with limited time, and on a mission to exceed last year's 609 total companies!
Best wishes, Paul.
#SQZ got permission from the North Sea Transition Authority to develop the Belinda oil field. 2P reserves estimated at 5m BoE per day and production should start Q1 2026 Serica Energy (LON:SQZ)
Microlise Group (LON:SAAS) new contact wins. Good growth to me? Seems under radar as no interest this morning despite good gas in the tank.
.
Iran news could cheer up the markets safer world? more Conduit Holdings (LON:CRE) big rise this morning
Well done to holders of Keywords Studios (LON:KWS) Stockopedia rankings are 13 for Value 19 for Momentum and a Stock Rank of 22. Very strange but not a share I have any knowledge of.
I've held it for a while and it's always come across as a well-run company. I think the constant acquisitions, and goodwill payments from that, constantly skewed the Stockrank figures. It's a growth share so Value ranking has been low for as long as I've held it.
Me neither portugull, but Keywords Studios (LON:KWS) was discussed here on this forum a few weeks back as being undervalued and a potential recovery stock. I did some subsequent research and was able to see it's heady past (value wise) and it's apparent potential. I bought a position. It rose about 25% recently and now today it's clearly shot up just as i was thinking about adding to it. The value of this community as well as our esteemed analysts give us a head start in investing. Thank you all.
Harworth (LON:HWG)
One of the two property companies in the family portfolios, the other being Palace Capital (LON:PCA) .
This morning's AGM statement from the former reads very well. Lots of detail in the statement; conservatively financed with LTV of 8.4% and trading at a significant discount to NAV. Similarly Palace Capital (LON:PCA) is in a net cash position and also trades at a deep discount to NAV., with a tender offer pending!
Have held both for a long time and expect their share prices to appreciate further as and when rates decline.
Given they are property companies no comment expected from Paul/Graham.
All the best
Palace Capital (LON:PCA) - Per RNS 18/4/24 - "We expect to announce a significant return of capital to shareholders, likely through a tender offer, in due course and ahead of the Company's preliminary results for the year ended 31 March 2024 which are scheduled to be reported in June."
Prelims were mid-June last year. I hold.
Surely the market has taken the proposed tender offer into account and has decided it is no big deal ? Why has there not been a significant increase in the price since the announcement ? Just curious as on the face of it, the share does look interesting.Palace Capital (LON:PCA)
AFC Energy (LON:AFC) taken a first commercial orders
AFC Energy (LON:AFC) A horrendous jam tomorrow stock. Do not touch with a barge pole.
Victorian Plumbing (LON:VIC) Canny acquisition of its #1 competitor Victoria Plum for £22.5m just as we’re seeing early signs of recovery in their respective markets
“purchase price represents c.0.5x Victoria Plum's estimated annual revenue and reflects the significant strategic value to the Company of the Victoria Plum brand and its associated intellectual property”
Having recently been through an administration process let’s hope that the cost cutting has already happened. It seemed a reasonable price to pay but a fellow investor said it looked expensive (at anything more than £1 ;-). Let’s see how the share price responds (as I hold a few VIC)
I also own VIC -share price was up 5% on Friday - knowledge of the deal?
Me too but I am underwater still and will not be doubling down in my holding of Victorian Plumbing (LON:VIC) as there are more attractive prospects elsewhere today.
Underwater with Victorian plumbing? - sadly appropriate turn of phrase.
Is the high level of director ownership in Victorian Plumbing (LON:VIC) a delisting risk?
Victorian Plumbing (LON:VIC)
Paul- Try this link for Victoria Plum at Companies House: https://find-and-update.company-information.service.gov.uk/company/04177694/filing-history?page=1 You will find the info about VIC’s acquisition there. I’m still mystified as to the size of the price paid for the acquisition but my reading hasn’t been exhaustive. Nice website here: https://victoriaplum.com/
disclosure: no position
Thanks laurie,
That looks more like it, in terms of the Victoria Plum acquisition. However, the RNS from VIC specifically mentioned acquiring the shell company that I followed up on, not the company you have tracked down. Maybe the shell company is topco, and I didn't spot it?
As we agree though, the question remains why VIC has paid £22m for a loss-making, and now insolvent competitor? Normally if you're quick, you can grab the assets off the receiver for peanuts - I worked on a deal like that in the 1990s, we paid next-to-nothing to buy a bust competitor as a going concern which had multiple millions of revenue, and we had to TUPE over staff, etc, a right pain in the ass, but it saved lots of jobs, and only cost us about £140k in total. Yes that was a long time ago, but even so, £22m seems a helluva lot to buy a failed business.
P.
Victorian Plumbing (LON:VIC)
As we agree though, the question remains why VIC has paid £22m for a loss-making, and now insolvent competitor? Normally if you're quick, you can grab the assets off the receiver for peanuts
It looks like AHK have already done that nifty bit of business in that regard dealing with the administrators - perhaps this business is fully stocked up now - it went from having £9 mill stock in 2022 to a fraction of that when adminstrator turned up - maybe they found the missing £17 mill of stock at the back of the warehouse perhaps ? - or that was standard administrator discount ? reminds me of a mfi kitchen i purchased in the 90's and didnt get around to installing it for 25 years - was surprisingly decent when the job was done!
Ignoring the price paid taking ownership of the similar sounding brand name makes a lot of sense. Found the two confusing when looking for taps in the past! Of course they could have just purchased the IP/brand name, but one hopes the Directors know what they are doing.
The broader implication of the Keywords Studios (LON:KWS) bid derives from the fact that its SP is a major victim of market fears about the impact of AI. Now, some very smart people have looked under the hood and concluded those fears are less well grounded, to say the least. Which other AI casualties are unjustly mispriced and which soundly re-rated? RWS Holdings (LON:RWS) is an obvious example to contemplate and I remain determinedly cautious but stubbornly intrigued.
I got £24.35 nice start to the day and first bag of the year
That'll do me, as Paul says what's the point waiting around for the extra 5%
Keywords Studios (LON:KWS)
Hi NewInvestor1972,
Just to be clear, I don't advocate any particular approach when takeover bids happen, as each situation is unique.
Things to consider might include -
Whenever I'm lucky enough to get a takeover bid for a share I hold, I often sell some in the market straight away, to bank some of the gains, and to give me time to think through all the circumstances.
Congratulations to holders of KWS, this looks an excellent bid, so you were right that the company had value beyond its pre-bid prices. This situation again highlights how poor the disclosure rules are. KWS has been negotiating for a while, with a credible bidder, for a bid at a significant premium, yet there was no requirement for them to inform the market, thus creating a false market. These takeover rules have got to be changed!
Let's see what Graham thinks, he's working on a proper section on KWS as I type this.
Any readers holding KWS, what's your view? I know it's customary to complain that the bid price is too cheap, but I don't think anyone can credibly complain at a price that's well over double the recent lows!!
Regards, Paul.
PS. Just realised that I reviewed KWS here on 13/3/2024 and quite liked it, concluding AMBER/GREEN, and "worth a closer look". Phew!
Hi Paul, Of course, personally I am very happy with 5% discount to the offer price and a 110% gain in a very short time period, a bird in the hand is worth two in the bush and all that.
As Shopping said they advised in the RNS for shareholders to take no action which makes you think there may be other suitors. If there is a bidding war I won't mind at all. Happy with my gains. Keywords Studios (LON:KWS)
Keywords Studios (LON:KWS)
My 2 cents - I'll be disappointed to see KWS leave the UK market. I think they may have come against some headwinds re: their localisation business (surely translation services is going to be one of the things AI absolutely nails?) but in their recent investor meet presentation I got a strong sense of how important they are to the games market. They've partnered with 24 of the 25 biggest games development companies. Some of those will recommend KWS puts the slide rule over what they think are potential acquisition targets so the tech stays with a trusted partner (rather than being bought by a competitor) and I think the games market suits an aggregator - lots of very smart people will develop coding skills in their bedroom, start a company full of talented people and then KWS can snap them up, look after the boring parts of running a business and put them to good use.
A huge amount of trust is required to partner on big titles given the IP and I think games development companies of all sizes got a big wake up call re: what happens in a quieter market when you've taken on lots of staff during a boom (i.e. the trend of outsourcing a percentage of the work would surely have continued, including the 'live service' requirements after a title has been launched, and KWS is already an established go-to partner.)
I bought a small started position last week with the view that a £1bn mcap for what seems like such an important company to the industry was good value. Will be interesting to see what happens next, but either way I don't think it'd be good for the market to have a company liked this snapped up.
Well played buying last week,I don't know much about Keywords Studios (LON:KWS) 's business in any detail or the gaming sector to be honest but the services to a large tam industry aggregator sounds like the very successful model used by Infosys (NYQ:INFY) (Sunak and his wife are £122 million richer on paper this year!) and EPAM Systems (NYQ:EPAM) buying up smaller, successful IT services companies and using their already achieved brand, size, reputation, reliability to sell new and more services to existing customers in a sector with large TAM.Wish i had bought some now, as although we all know loads about Chat GPT now, AI clearly isn't going to steamroll every commercial industry overnight, even law and accountancy firms, as well as translation, which have been talked about being ripe such for a long time.Much easier to say that once the the market has clearly agreed with you however!
Funnily enough Lord Lee is a big campaigner for change in those takeover rules and feels many investors lose out by not knowing that a company they own is being bid for. It is very good timing as he is a speaker at the Mello2024 conference this week Mello2024 Line Up – Mello Events
Keywords Studios (LON:KWS)
I think the reduction in share price has as much to do with the Hollywood strikes as with the AI fears. I was intrigued by this part of the RNS “The Possible Offer is subject to satisfaction or waiver (by EQT) of customary pre-conditions, including completion of confirmatory due diligence by EQT. The Board will issue a further statement as and when appropriate. In the meantime, Keywords Studios shareholders are strongly advised to take no action.” Does this imply that others may be sniffing around and considering making an offer?
Hmm ‘ the reduction in share price has as much to do with the Hollywood strikes as with the AI fears’ wonder if that might be the case for some other Hollywood service providers !!
Keywords Studios (LON:KWS) set to be next takeover according to the FT and reported in the Times this morning. https://www.thetimes.co.uk/art... Private Equity EQT set to offer £2.2 bn or £25.50 a share a nice 70% lift. I hold.
Obviously its a great takeover premium but like other UK takeovers you can't help feeling the bidder has timed it very well (right at the beginning of the company turnaround and at the start of UK SMID finally turning).
But the bid price is over 2x the share price of last month. Other bids such as IQGeo (LON:IQG) and Anglo American (LON:AAL) were nowhere near that level.
And the share price has been well above that bid price not so long ago.