Small Cap Value Report (Mon 21 Dec 2020) - FUL, BOO, SDG, ANG, UNG

Good morning! It's Paul here with Monday's SCVR.
Timing - today's report is now finished.
** Newsflash! Reminder that Ed will be doing a presentation at 18:15 tonight at Mello Monday. The other speakers & company ( Gaming Realms (LON:GMR) ) are all really interesting, so this one is probably the best so far. I've been roped into the panel discussion (again, I hear you sigh!!) at the end. I'm going to focus mainly on investing ideas & themes for 2021, so it's not duplicating my recent PIWorld chat **
I'm hoping it might be a bit quieter for company news this week, as I need to take some time out to buy the food for Xmas Day from ASDA. Reports of logjams at channel ports, mean we could run out of parsnips any time soon. Obviously completely unconnected with Brexit negotiations! ;-)
Covid - we're getting bad news about case numbers & deaths, but good news on the vaccine. My mother had her first vaccine dose yesterday. She reported back that it was very well organised, quick, and completely painless - she didn't feel a thing. No side effects. The booster jab is scheduled for 3 weeks. You might like to pass that on to your relatives & friends, to reassure them that it's not at all daunting. Mum came out of the health centre a little later (they make people sit for 15 minutes, to ensure there's no adverse reaction), got into my car, and commented, "Everyone in there was decrepit! They must be doing the over-90's today!"
To start off on companies, here’s one I prepared earlier (!!!)
Fulham Shore (LON:FUL)
9.5p - mkt cap £58m
Half-year Report (published 18 Dec 2020)
The operator of Franco Manca pizza restaurants, and the smaller chain “The Real Greek”, both being casual dining formats. Both are excellent, popular, and nicely differentiated, i.e. not just copy-cat pizza restaurants like all the others.
Investors generally should look at least 6 months ahead, therefore we really should now be focused on how businesses are likely to trade post-covid. That’s why so many cyclical shares have rallied strongly in recent weeks. Therefore, FUL’s interim results during the covid period are only of passing interest. I’m more interested in balance sheet strength, liquidity, and the outlook.
The Directors of The Fulham Shore PLC ("Fulham Shore", the "Company" or the "Group") are pleased to announce unaudited interim results for the six months ended 27 September 2020.
During this period we saw lockdown 1, then re-opening, and the big boost in August from EOTHO scheme, and reduced VAT. H2 will see continued disruption from lockdown 2 (and 3 possibly, the way things are going currently?). So this financial year, FY 03/2021 is likely to be grim, but that’s information the market already knows, so should be baked into the price.
Funding - FUL only raised a small amount from shareholders, a £2.25m placing at 6.25p, in August. Enlarged bank facilities were also put in place. FUL has unusually large debt facilities for a company of its size, in my opinion. The latest picture is this;
As at 17 December 2020, the Group had net debt (excluding lease liabilities) of £3.7m with undrawn debt facility of £11.5m out of total facilities of £25.75m
H1 revenue was £19.9m, down 45% on LY, obviously due to covid/lockdown enforced closures
Loss before tax was £4.3m, although there are numerous alternative profit measures given, so take your pick!
Net debt - fell from £9.5m at 29 March 2020, to only £3.3m at 27 Sept 2020 - which suggests to me there must be considerable creditor stretch.
Headline EBITDA - this number looks meaningless now, because IFRS 16 inflates it by stripping out a lot of the rental cost of properties. So I am ignoring this artificially high figure of £3.7m positive headline EBITDA. More meaningful is the old (IAS 17) headline EBITDA figure, which is exactly breakeven. It may seem off that the company has managed to perform at breakeven EBITDA in a period when its restaurants were closed for a considerable time. Bear in mind that these figures are boosted by Govt support schemes;
We have, during the Half Year, benefited from certain UK Government support schemes including, amongst others, the Coronavirus Job Retention Scheme ("CJRS"), Coronavirus Large Business Interruption Loan Scheme ("CLBILS"), VAT deferral, hospitality business rates relief at applicable locations and the Eat Out to Help Out Scheme.
Balance sheet - NAV: £37.0m, less £24.6m intangibles, and eliminating £1.77m of deferred tax liabilities, gets me to NTAV of £14.2m.
Lease assets and liabilities should be shown separately on the balance sheet, instead they are lumped together with fixed assets, and “borrowings”, which is poor presentation.
I feel that FUL should have done a larger placing, and relied less on debt.
Expansion - this is a wonderful time to be opening new restaurants, as the deals on offer from landlords are very attractive;
The ongoing damage to the property and restaurant sectors will allow us to prospect for new sites at much reduced rents and with lower capital costs per site. The two restaurants we have recently opened cost us less than half of the typical outlay of a year ago.
As such, over the next few years and once normal trading conditions return, we will target a higher return on capital than we have historically achieved.
Therefore, investors who look beyond covid, to a world (currently indicated by Govt to be from April/May 2021) where consumers can return to normal, then the future could be bright for popular restaurants to once again prosper, and with less competition. This sector has been over-supplied for years, so we are now seeing a much-needed reduction in capacity, as other restaurants close their doors. Sad for everyone involved, but we have to be realistic, that we need fewer restaurants, so that the survivors can prosper.
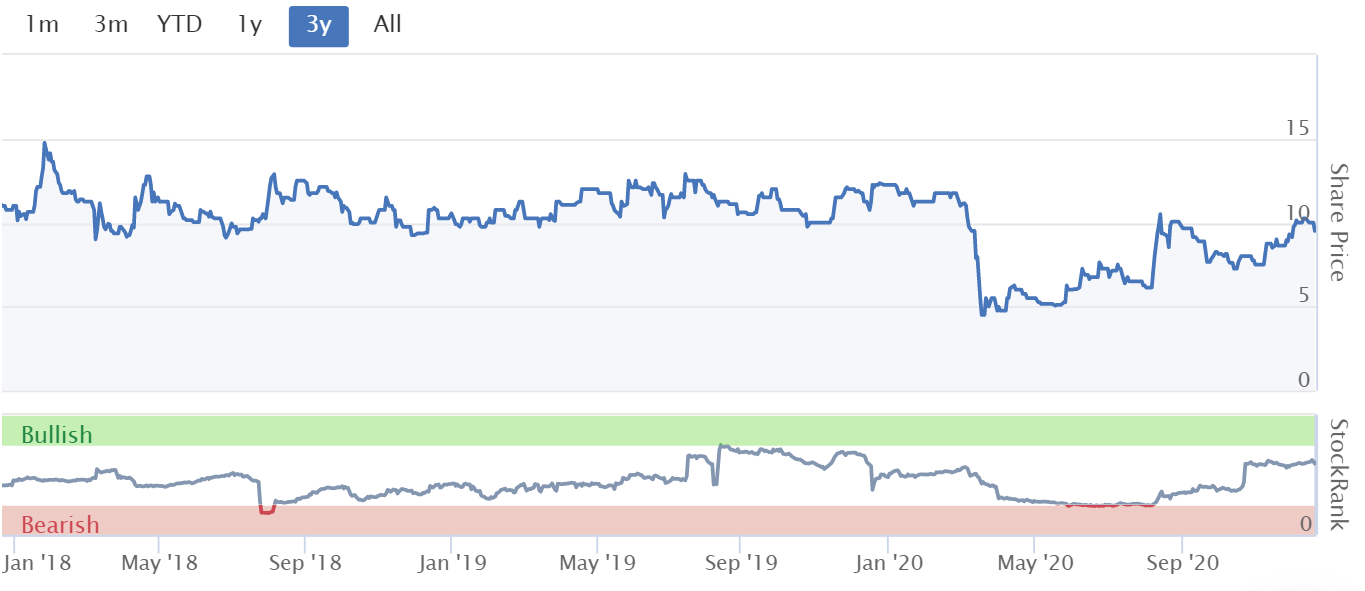
My opinion - the share price has now recovered back up to the lower range of where it was before covid. So where is the upside from here onwards going to come from? New site openings, on lower rents maybe, but why would I want to pay for that up-front?
By remaining solvent, and performing relatively well, you could argue that FUL is at a disadvantage. Competitors can do CVAs to force down their existing rents, and exit under-performing sites, but what can FUL do? It seems to be stuck with pre-covid rents, making it potentially less competitive.
To my mind, there’s probably better recovery upside on other shares right now. I'd want a significantly lower share price to tempt me into this share.
.
.
Boohoo (LON:BOO)
(I hold)
New auditor appointed
As expected, it looks a mid-tier firm, PKF Littlejohn. Its website says PKF is the 7th ranked auditor of listed companies in the UK, and has more than 21,000 partners and staff globally (of which 2,030 in the UK). So it's not a mickey mouse outfit. I don't really care who audits the accounts, as long as it's a reasonable-sized firm with a good reputation (which this is), and not some local backstreet outfit.
Audit work always used to be the entree, with little profit, to get a foot in the door for more lucrative tax & deal advisory fees.
KPMG is helping Sir Brian Leveson, in cleaning up & follow-up reporting on the extensive supply chain measures that have been taken. Once everything is sorted out there, maybe KPMG could become the auditors in future? Does it really matter? The auditing sector seem to be frequently engulfed in their own scandals & failures, so I find it a bit rich that they're reported as being sniffy about not wanting to audit BooHoo!
It will be interesting to see what happens to the Arcadia brands. Newspapers are reporting that BOO is seen as the front-runner to acquire the jewel in the crown, TopShop. That would certainly be an exciting move, but Mike Ashley is also sniffing around apparently. With 9 existing brands, BOO has plenty to be getting on with.
Over the weekend, I thought it would be interesting to compare the number of Instagram followers that BOO's brands have, and this was the result;
| PrettyLittleThing | 12.9m | |
| BooHoo | 7.0m | |
| NastyGal | 4.9m | |
| MissPap | 2.5m | |
| BooHooMan | 1.4m | |
I didn't look at the smaller, more recently acquired brands (Oasis, Warehouse, Karen Millen, and Coast), as they're probably not significant at this stage (e.g. Oasis was only 355k).
In the table above, the numbers that really surprised me are PLT, which seems to be smashing it, at 12.9m followers, and NastyGal doing surprisingly well - which could be behind the very strong growth in American revenues reported in recent interims. If BOO brands continue growing strongly in America, then a listing in New York would make a lot of sense & could trigger a serious re-rating - look at FarFetch for example.
By way of comparison, Manchester fast fashion competitor MissGuided has the same number of Instagram followers as BooHoo, at 7.0m. Press reports say it is having a big resurgence, with sales up 45% (same as BOO group) this year, to c.£300m annualised, according to recent press reports, and is considering a stock market flotation.
Did you see the TV mini-series about MissGuided? It almost went bust in 2018, but has since managed to recover, but is still loss-making, in both 2019 & 2020. How do they manage to lose money in a booming sector? The TV series suggests they're not very good at managing stock intake & ended up with a lot of terminal stock (buying the wrong things basically). The whole point of test & repeat is that that shouldn't be able to happen. The foul-mouthed narrator/creative woman at Missguided was really rubbing me up the wrong way by episode 3. How is it empowering for women to shout & swear all the time? Maybe I'm just getting old, but I prefer it when all people act with a bit of decorum in the workplace.
EDIT: Evans, the plus-sized brand of Arcadia has been sold for £23m - details here. End of edit.
.
Sanderson Design (LON:SDG)
(I hold)
Trading update
Sanderson Design is the new name for Walker Greenbank, a purveyor of fine wallcoverings & furnishings.
Very positive update, we should be in for a good day today.
Trading has been "substantially ahead" of management previous expectations. Pity there's no footnote to give us some guidance. But I won't quibble over that, given that the share price should rise today.
The improvement in sales during October and November 2020 was also reflected in profitability, which has also benefited from the programme of cost reduction measures implemented by management in the current and last financial years.
Outlook -
The Company's balance sheet remains robust, with improved cash levels and a stronger liquidity position, as compared with 31 July 2020. This further improvement in the Company's financial position prepares the business for a very uncertain trading outlook in the remainder of the current financial year and in the next financial year.
My opinion - an encouraging update.
.
Angling Direct (LON:ANG)
Share price: 76.5p(down c.3%, at 12:15)
No. shares: 77.3m
Market cap: £59.1m
Update re. Tier 4 Restrictions
Angling Direct plc (AIM: ANG), the largest specialist fishing tackle and equipment retailer in the UK, provides an update on its operations in relation to the UK government's enforced closure of non-essential retail stores in England's Tier 4 areas from Sunday 20th December.
Here are my notes from 14 Oct 2020, when I looked at ANG’s interim results - not bad in the circumstances was my conclusion, and I very much liked its cash-rich balance sheet.
Today it says -
- 12 stores are closed but still doing call-and-collect service
- 26 other stores & websites remain fully operational
- Positive sales momentum reported in Dec has continued
- Remains on track to deliver FY 01/2021 adj EBITDA of at least £3.8m - NB before IFRS 16, i.e. this is a reliable figure for our purposes
- Balance sheet & liquidity remain strong
- Angling is a health & wellbeing activity, which can safely continue
Broker update - many thanks for N+1 Singer for making available an update today, see Research Tree. Forecasts are unchanged, but note they were raised not long ago.
Adj EBITDA of £3.8m sounds good, but that only translates into 2.8p adj EPS, so a PER of 27.3 times - not cheap, but I wouldn’t expect it to be cheap in such a chaotic year.
Matthew, the N+1 analyst suggests EV/EBITDA as a valuation metric, and it looks to be rated at 11.9 times on that metric for the current (nearly ended) year.
Nobody knows how next year is likely to progress of course, but it’s good to see that N+1 has at least put some cautious-looking numbers out.
Having a mix of physical stores and websites hedges ANG’s bets either way.
My opinion - I don’t have a strong view either way on this one. I do like its strong balance sheet, and cash pile. That could allow it more acquisition opportunities, to roll up Mom & Pop type operators, if they want to exit, e.g. for retirement.
The balance sheet strength, and solid trading despite covid, combined with a market cap that’s still quite low, make me probably lean more towards being positive on this share.
.
Universe (LON:UNG)
3.75p (down 12%) - mkt cap £10m
This supplier of EPoS and loyalty systems has been listed for donkey’s years, but never seems to go anywhere. So I really can’t see the point in it being listed. Hence the de-listing risk (instant 50% loss if it announces an intention to de-list) is too big a risk for me.
Today it updates on FY 12/2020.
This reads as a profit warning - a project delay means costs are in 2020, but revenue now deferred into 2021. That sort of thing happens with micro caps, and in a covid year, we can’t really blame management.
Despite this delay, the costs of maintaining COVID-19 resilience, and an increased level of investment, the Company still expects to report a modest level of adjusted EBITDA profitability for the full year.
It says a small and temporary net debt position will exist at the year end.
My opinion - the only reason I would invest in this company, is if it launched a new, game-changing product, that was in very strong demand. Otherwise, why put your money into something that could be a lobster pot, i.e. difficult to exit from?
.
Here's Leon's end of year update from PIWorld - as always with Leon, some stand-out comments (e.g. that formal sales processes usually don't end with a bid). I hadn't thought about that before, but he's right!
.
.
That's it for today! Now I have to prepare something sensible-sounding to say at Mello Monday this evening.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
Paul,
Otherwise, why put your money into something that could be a lobster pot, i.e. difficult to exit from?
i like the term 'Lobster Pot', a new one to me.
Just back from ASDA, well I sat in the car while the good lady did battle.
Shelves fully stocked including Turkeys, so it sounds like more fear mongering in the red tops.
While sat in the car, did some spring cleaning off the portfolio, sold GYM (LON:GYM), and bought back into Revolution Bars (LON:RBG) for the 4th time, yet to lost money on this one, also topped up on Saga (LON:SAGA).
Then whizzed through a Mello session (my wife likes to shop) and I must say Paul, you do look a lot younger than I imagined and the picture on this page does not do you justice.
G Bob
I was thinking the same thing, a lot younger. has he cut his hair or what, something has changed, I no not what.
Saga movement looks to me to be a buying opportunity today. Temporary border closure surely has no real effect on Vaccination , financing, and recovery ...does it ?
I agree re Saga (LON:SAGA) and have been buying more. The current valuation doesn't make any sense at all to me, given that it has already refinanced, and the 2 new cruise ships are scheduled to resume cruising in April, which is in line with Govt guidance.
We should be told on 26 Jan 2021 that cruise bookings are booming, which is what Saga's head of travel said in a recent Telegraph interview. I also checked on Saga's website over the weekend, and saw that there's not much availability for the 2 cruises scheduled for April, for one of the ships, Spirit of Discovery.
I think this share could rebound really strongly, if the AstraZeneca/Oxford vaccine is approved, as expected, late next week. This one is easier to store & distribute, so could be rolled out much more quickly than the Pfizer vaccine, so I am told.
We saw a lot of kneejerk, irrational , large share price movements this morning. I think it's traders taking advantage of lower liquidity at a seasonally quiet week, to push prices around. It's always a good idea to keep a bit of cash on hand at this time of year, so you can take advantage of bizarre price movements when many market participants are resting.
Regards, Paul.
SAGA C-19 updates here:
https://travel.saga.co.uk/trav...
For what is is worth.
My thoughts on Angling Direct (LON:ANG) are more cautious. The placing in 6/20 raised £5.5m and i think most of this is still cash on the balance sheet as they've not been able to buy enough stock. Stock supply will continue to be a big drag on sales going into the Spring/Summer season and although their sales benefitted hugely from Angling being one of the few pastimes people were allowed, if and when we are allowed to do the things that we have been starved of Angling will probably take a back seat in peoples priorities.
As a newcomer to Stockopedia , this is my first post , I’d like to take the opportunity to thank the great Stockopedia community , who share their views and research selflessly. My thanks to those members (too many to name ) whose great posts I’ve read.
Paul did an excellent review on De La Rue (LON:DLAR) on the 30th Nov in the SCVR . The main points I took from that was the substantial share dilution and the share price (probably high at 166) but please read the report yourself .
In any investing decisions I look at the fundamentals of the company rather than technical type analysis, however I just felt it may be interesting to include the following chart for those who may not have noticed that De La Rue (LON:DLAR) appears to be trading in a slight upward channel at the moment. Whether it will continue ? Who knows ? Certainly not me . However I took a small punt today at a price of 144 and may add more if the price drops to approach the bottom line of the channel, but please DYOR I’ve no idea where the share price is going.
Please note the prices shown on the above chart were read from the chart itself for convenience rather than looking up the actual closing price history so may show a slight inaccuracy.
Neil
Hi neilt,
Welcome to Stockopedia, and thank you for an interesting first comment here, very interesting. I must take a look again at De La Rue (LON:DLAR) as I got bumped out of it on a margin call not long ago (story of my life!)
Regards, Paul.
Just want to give a big thank you to Tamzin at PI Word for a fabulous series of interviews and presentations this year and all the private investors and companies who have participated. I have just been watching the end of year reviews with a number of private investors, including Paul, who share their thoughts as to failures and successes during 2020 and views on investing in 2021. For me it provides a fabulous insight. PI World is great free resource for the private investor.
Also a big thank you to Ed and the Team at Stockopedia for the quality of information and service provided and in particular Paul and Jack and previously Graham for the in depth analysis of small cap companies. As one reader commented it is worth the subscription fee on its own.
To all, keep well and enjoy Christmas and New Year as best you can in what are difficult circumstances, which will eventually pass.
All the best
Jonno
Hi Paul, concur with your experience of your mother with the vaccine. My 91 year old father had it on Friday - very well organised, painless, and no after effects. Next one on the 8th Jan. It's a good start.
Just for awareness - I'm reading that the side effects are more likely after the second Pfizer jab so you might want to take more care of your relatives after that. Don't be complacent because they felt nothing first time. It's a normal sign of the immune system reacting.
My parents both in their 80s had theirs yesterday and reported it going very smoothly and said it was very well organised.
Next one on the 10th Jan but good to see them working through the highly impacted people quickly.
Some over 90s, in my area have been told, they won't get for some time, depends where you live.
There are around 12m people, who are over 65, in the UK.
.
12 million over 65 in the UK according to the ONS. What is your source for 12 m over 50?
12m over 50 yo.
As of last year it was about 25 million over 50, 20 million over 55, 16 million over 60.
I know CV-19 has killed a lot of old people but it's not that bad surely?
Based on the omnicalculator vaccine calculator there are about 21 million in the top 7 vaccine priority groups (60 to 90 and everyone with an underlying health condition). The current estimate is everyone in that group will be done by end of May, but you'd hope they can improve on that.
https://www.statista.com/stati...
timarr
Timarr,
Thanks for link to the https://www.omnicalculator.com... Very neat except I didn't see if the estimates were for first of second jab per person.
You always seem to have good data sources. Do you have anything solid tool for the expected SUPPLY of vaccines as this seems to me the critical variable . I read initially 4-5mn doses of Moderna by end of year with Jeremy Hunt saying that runs out at end Jan. After again I read that Oxford has pre-made stockpile of 10+Mn but how much for UK by when, assuming it is approved in next 2 weeks and what is the ongoing approval rate. I leave out other vaccines as upside.
Combing, in hand we would have 14mn doses - enough vaccinate 7mn people ie roughly first 4 groups - over 75s, care homes and all front line NHS/Care Home workers. Remaining deaths would be v small and probably on a declining trend.
Putting when someone aged 65 can expect their injection, it projects between 28/2 and 17/3 for getting a jab - so ready to cruise or go out to pub from 1/4
From Times 11/11 "A million people a week could be vaccinated against coronavirus under NHS plans to ensure a jab can be administered as quickly as it is manufactured.
All over-65s may be able to get the Pfizer jab before Easter if it is approved, with officials hopeful that the Oxford vaccine could allow a wider programme during the winter if it is also successful."
(For what must be the UK's no 1 priority, I would hope we could surely administer not 1Mn/wk but 2, or even 3mn if we really set up to do it (bring out that April 20 NHS army of volunteers, commander polling stations etc. Surely taking screening info and giving an injection is not so hard - my Dad had diabetes and did it to himself twice a day so with say 1 day of training, supervised by skilled staff to check filled in forms and cope with any adverse reactions......)
Do you have anything solid tool for the expected SUPPLY of vaccines as this seems to me the critical variable . I read initially 4-5mn doses of Moderna by end of year with Jeremy Hunt saying that runs out at end Jan
Sadly not. The variables involved in this are significant and there's global competition for access to vaccines. Allegedly the UK will have 10 million doses of the Pfizer vaccine by year end. Because it's manufactured in Belgium that's possible despite the delivery challenges.
Beyond that a lot relies on the Oxford vaccine - if it's effective then it can be rolled out quickly. Overall the UK has over 300 million vaccine doses on order, but not all may get approval. Where we are is a miracle of medical research. But 1 million a week looks realistic.
Delivering more than the 1 million doses a week will be a challenge. I doubt most people would want it to be admistered by anyone other than a heathcare professional and we're going into January and February, the worst two months of the year for general illness and hospital load. Healthcare staff are tired and rundown and they know the worst is yet to come.
This was always going to be the hardest part of the pandemic. It's going to be a tough few weeks.
timarr
My father had the vaccine last week and also came away with a positive opinion of the process. My mother would have had it too but as she has a history of anaphylatic shock - she has been told to wait for alternative vaccine. One of my daughter’s friends (a junior doctor on a maternity ward) was due to be vaccinated yesterday, but came down with symptoms the day before and has subsequently tested positive.
Here are my heat maps for today (prices as at ~9:15am). Lots of big movers!
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR world filtered to 'interesting' instruments ('interesting' means: reporting soon or recently; trending; breaking out; increased volatility - volume / ATR up; moving more than a 20d EMA of the ATR):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Big movers today (not restricted to small caps):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments. I define Small Cap using the Stockopedia Small Cap Size Group definition: Market Capitalisation between GBP 50 million and GBP 350 million.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many (from my own application and database) to help focus my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria (a 'T' in the top-right of the heatmap tile, meaning: profitable; low-debt; reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the identified instruments in more depth using the Stockopedia StockReports.
How (or indeed if) you use these heatmaps is up to you, I contribute these SCVR related ones here in the hope that others may also find them interesting or useful. I aim to post sometime in the morning when I can, but sometimes work / family and other priorities get in the way.
greensiax
Sorry, forgot to watch the news today (prices as at ~1:15pm).
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Has anyone come across Powerhouse Energy Group PLC? (LON:PHE)
It's very early stage, barely making revenues and its market cap is ~£100m
It's extremely underreported and its only blue-chip investor is Investec, which could pose as a potential opportunity.
I like the idea and it's in a great sector.
TIA!
I personally wouldn't take a position in a company that looks very much a newcomer to the renewables and waste-to-energy development scene in the UK - the sector is not particularly straightforward, lots dependency on external parties and factors outside of your control. Have worked in this sector for over 10 years so have some understanding of just how complex it is! It looks like Powerhouse sell proprietary waste-to-energy tech to project developers together with services contracts but they are not an owner-operator of WtE plants in their own right so their main source of revenue is from sales and support, they aren't getting steady revenue from electricity or hydrogen offtake. I can't tell from their website if they are involved in site construction. They only appear to have a partnership with one developer (Peel Energy), so all of their eggs are in one basket. They are reliant on Peel to raise enough debt and equity to develop a site, Peel to manage the planning permission and land acquisition process, Peel to negotiate an electricity/hydrogen offtake contract (this is ultimately what determines how much Powerhouse will get paid), Peel to develop the site and achieve commercial operations on time etc. Does Peel have a pipeline of WtE sites to develop, and do Powerhouse have exclusivity to supply Peel with their WtE tech? I'd be quite surprised if they do. Powerhouse need more than a single client, IMO. I've only given their interim results a cursory glance, and just think Powerhouse's business is still very early stage in terms of being able to scale their business with Peel and get paid those licensing fees and service contract fees, and also cultivate other clients. You might have more info than I do though!
Thank you for this. I have shot over those questions to their investor relations as it wasn't clear from their accounts. Will keep you posted
On a pretty quiet news flow day i've written up my notes from the Mirriad webinar last week following their successful fundraise and they can be found on the discussion tab of Mirriad Advertising (LON:MIRI) company page in Stockopedia.
It was a fascinating update and outlined some great revenue opportunities going forward, with live sport being worked on for 2021 in response to interest from one of their existing content partners. A recording of the webinar is also available here.
Re the vaccine, on the news they said only 350,000 have had it so far, at this rate will summer before all the vulnerable will be vaccinated.
I’m also hearing some surgeries have been advised, they will have to wait for the AstraZenica vaccine.
The UK got 800,000 of the vaccine and each person needs two doses so 400,000 is all that can be done. Given other countries have approved the vaccine now I doubt if we will get more doses for some time. Mass vaccination will probably have to wait for the AstraZenica vaccine to be approved.
Pfizer has said supplies will continue into January.
Unless the AZ one is approved soon, this vaccination is going to take a long time.
Unless the AZ one is approved soon, this vaccination is going to take a long time.
The omnicalculator vaccine queue calculator gives you an idea, but it's base assumption is a million doses a week and about 70% take-up:
https://www.omnicalculator.com...
At that rate the vulnerable groups down to Priority 7 (over 60's) would be done by mid-May. It roughly looks like the most vulnerable groups would be protected by the end of February.
However, realistically that doesn't end the need to take precautions. The effectiveness rates seen in the trials might be lower in the real world and older people are likely to be less protected because their immune systems won't respond as well. Just because someone has been vaccinated it doesn't mean they're protected.
So: you still need to take precautions around someone who has been vaccinated but is vulnerable.
At 90% effectiveness we need about 70% take-up to achieve herd immunity. Basically, until everyone is done, no one is safe.
timarr
Rumour is that the AstraZeneca final data was sent today and it might be approved by the end of the year by the MHRA.
I believe that 350,000 number refers to those who have had the initial dose, not the full vaccine.
I am impressed so far with all the work on the vaccines including the roll out, but I think you are right to be cautious. We will probably be delayed by vaccine availability, even if the vaccine that is available is as effective as we hope. There are still several unknowns e.g. the virus has demonstrated that it evolves rapidly. There have been 1 to 2 mutations each month. The new variant causing the current concern (B 1.1.7) is reported as showing 17 new mutations all at once. This has never been seen before in virus research. The point being, what we have here is a moving target.
Boris told us there would be a significant return to normaility by Christmas. Paul talks above about normal consumer behaviour by April/May. You suggest summer and the inventor of the Pfizer vaccine says next winter. Your guess is as good as mine, but I think we can safely ignore any forecasts from Boris.
Just to emphasise, my suggestion of April/May 2021 for things to be getting back to normal (i.e. retail, hospitality & travel able to function at close to normal), is not a guess from me. It's based on various companies I've spoken to, and what they have been told by the authorities, plus what I've read & been told by credible sources.
If we get news of AstraZeneca/Oxford vaccine being approved in the next fortnight, which has been mooted, then the pace of vaccinations could rapidly accelerate, and likely turn stock market sentiment positive again.
Downside risks seem to be if AZ/Oxford vaccine is not approved, covid mutates into a form which vaccines are not able to protect against, or worst case scenario is if it mutates into something far more deadly. There's no evidence of any of those happening as yet.
I had an interesting chat with mgt of Revolution Bars (LON:RBG) (I hold) last week, and it's important to note that there's very little downside now from their base case scenario, and also their downside scenario (terrible but plausible, or something like that). The reason is that their base case assumes very little revenues from Jan-Mar 2021, due to continued restrictions, and seasonally quiet trading even if they are allowed to open. That makes many sites, at best marginal.
Hence if forced to close all sites, zero revenues, for Jan-Mar 2021, it hardly makes any difference, because they're not paying business rates, and can furlough staff again. In some cases that will actually incur lower losses, than opening up for trade, but hardly any customers turning up.
They've been prudent with their cashflow forecasting, and basically they're well set up now to tread water until end March. Bank highly supportive - e.g. waived an £8.5m loan amortisation in 2021, so that RBG could get its FY 06/2020 accounts signed off. Management thinking is that, by the time they get to end March, bars should be about to open, therefore a little flexibility (if needed) should not be a problem as a short-term bridging issue.
They're not in crisis mode, but are actually salivating at potential opportunities, for acquisitions of good sites, and even buying smaller competitors from administrators, and bolting them onto RBG's existing infrastructure.
The mood music is actually quite positive - confident they can get through to re-opening some time around or after Easter. Forecasts suggest a slow resumption of trading in spring 2021, but I think it's likely to be the opposite - roaring trade likely, once people are allowed to party in the small hours again on Fri & Sat nights.
There will be large tax losses, so not likely to pay any corp tax for a couple of years, and debt could be reduced considerably, quite quickly, if you crunch the numbers.
Profits should be well above pre-covid level, because they've ditched all but 1 loss-making site, and reduced rents (consensual, and in CVA) on many others. HO overheads also reduced, so a leaner, fitter business.
My conclusion after digging into the detail at RBG - risk is very much lower than some investors seem to think. Risk of another placing to prop up the business looks minimal. Once it re-opens, the business should be a goldmine. Hence I reckon a fairly good chance of doubling our money from 20p level currently, and not much downside risk.
DYOR as usual. I think some people are putting out strident opinions without having done the number crunching properly! the really big news last week was the bank waiving the £8.5m loan repayment. This demonstrates they're being super-supportive. They could have insisted on another placing, but didn't. Remember that the bank & shareholders have seen that, when allowed to trade without serious restrictions, RBG actually did OK over the summer. This is evidence that, once allowed to, the customers return keenly. It was the imposition of 10pm closing that really clobbered them. Once that's gone, then we're off!
My position remains the same, I'm happy to hold until re-opening, so 6 months, and would be happy to exit somewhere in the 40-50p range based on what we know now, but I'm hoping it could be nearer 60p, if the post-covid boom in business happens as I suspect it might. In my view there's tremendous pent-up demand for partying, holidaying, etc. So my feeling is that a "roaring twenties" type of scenario could well happen.
Regards, Paul.
Paul, Whatever your personal political views, there are also definitely political dimensions to consider which will affect the timing of resumption of normal-ish UK life and thus investing - viz the important local elections in May plus Scottish elections etc. The govt and the PM in particular will be desperate to have lifted restrictions by Easter and thus able to be positive and be forward focused ie trying to draw a line under Brexit ("done") and Covid ("over") and "Build back Better" the new mantra.
With the death rate likely falling fast by then and the population desperate for release, what better time for PM to announce major relaxation than from Easter - queue resurrection themes. Good Friday is April 1st in 2021
So I think laws relaxed by Easter but everyone still exhorted to be careful is a reasonable best guess. Those still concerned (unvaccinated 60+ or vulnerable) will still choose to stay at home. The rest will party like its 1999, using enforced savings (majority including students and the majority of young adults who stayed employed) or debt. How long the boom lasts will depend on how the economy is doing more fundamentally by then............
I dont know Peter, I've heard that in Jan we will all be put in tier 5.
Tier 5 is when you have to go to your bedroom and youre not allowed out till they say you can come out
And no phones because 5G spread covid!
According to the British Medical Journal (see link) this new variant was discovered in September. A friend of mine has just come back from Spain and said in the Spanish newspapers they already knew about this, they have it in Spain, and it suggested it might even have come from Spanish farmers.
https://www.bmj.com/content/37...
Hi Marigold,
A friend of mine has just come back from Spain and said in the Spanish newspapers they already knew about this, they have it in Spain, and it suggested it might even have come from Spanish farmers.
That's muddling two stories. The majority of the cases in the UK were seeded from Spain in the summer (but summer holidays are so important, right?). That's variant 20A.EU1.
The new variant is VUI-202012/01 (Variant Under Investigation). It probably originated in the UK - basically the closer you are geographically to the point of origin the more cases you'll have in the early stages.
This article discusses both: https://www.sciencefocus.com/n...
This is the problem with the UK's approach of managing the number of cases as opposed to going for elimination. The more cases you have the greater the risk of something like this happening.
timarr
The Germans aren't happy with the EU process - https://www.spiegel.de/interna...
It may not be true, but it "feels" right that the French vetoed buying more from a German company until the French company was ready to sell an equivalent amount.
Hi paul, just a quick note to say that Instagram follower counts are very easily manipulated with fake followers etc and definitely can’t be trusted. The first thing any new upstart company will do is buy fake followers to look more impressive.
Have a nice Christmas everyone, as much as possible.
Good point, thanks!
Watched Andrew Marr, and in particular Prof. Susan Hopkins (PHE) and Dr Kerkhove the head epidemiologist at WHO, who both said they do not believe the new variant is a game changer to the vaccine due to the 23 variations.
It is 1 of 7 mutations already detected of Covid-19 (another one detected in South Africa recently) and this particular UK variant has already been detected in the Netherlands, Denmark and they believe several more European countries.
Prof. Hopkins also said the 70% increased infection estimate will be updated this week (could go up or down) but that it doesn't seem to have increased the rate of hospitalisations because it was first noted in October from a September sample. Matt Hancock later clarified they knew about this but didn't know of any causation to a statistical increase in transmission until last week.
What does this mean for shares?
If a vaccine still works, this will be short-term issues - could be a big "IF" but current knowledge is slightly positive.
Seems why shares are fighting back this morning (International Consolidated Airlines Sa (LON:IAG) was 19% down on open, now -8% or so at time of writing).
One thing I feel more comfortable about is sitting in online stocks, food delivery, video game developers. (particularly Just Eat Takeaway.com Nv (LON:JET) ,Boohoo (LON:BOO) ,$AMZN , Thg Holdings (LON:THG) and $EA )
I can at least sleep at night in them!
And also this on the vaccine and the new variant.
https://www.moneycontrol.com/n...
Good article, thanks.
Why has THG Holdings (LON:THG) got a StockRank of 0?
Recently IPO'd.
Is it, THG Holdings (LON:THG) well the share chart goes back to September?
Not sure that would help me sleep.
I don't have a problem sleeping at night, I don't really get some of the comments. But I tend to avoid companies with a lot of debt.
The data on Stockopedia comes from Refinitiv, they do take a while to properly update. If you look at any of the recently IPO'd companies this year, the data isn't as comprehensive. I wouldn't read anything in to it being 0, it certainly isn't 0, it just hasn't been updated.
High debt? It has a low gearing of around 40% even when excluding intangibles.
I should correct myself because I believe net debt is even much lower as I'm looking at their balance sheet at end of year which doesn't include proceeds from the IPO.
Net debt/(Cash) is around (163mio) post-IPO.
Significant positive net cash position of c. £420m as at 30 September 2020, with over £900m of liquidity available to the Group.
I think gearing is only about 20% actually!
A list of one more wafer thin mint stocks?
There is no such thing as a sleep easy stock. If you feel zero risk, you have zero opportunity...and in the reflexive world of stocks zero risk complacency likely finds that bad downside angst and risk with time.
Who knows why stocks are down but it is probably more a sense of disappointment with US stimulus than new variant covid. In addition there have been emergent signs of stress in eurodollar markets with US 12 mth yield trading under 6mth....but expect a very large Fed corrective response very quickly. The greatest thing to learn from March 2020 is that the Fed is very very sensitive to the liquidity and pricing of US govt debt market as foreigners are no longer knee jerk buyers of US paper under duress due to the US's woeful net international investment position (approx -60%)...foreigners sell US assets for dollars in sustained periods of duress risking US govt debt market 'failure'. So the Fed had to step in...and the stock market rebounded. This routine is likely to play out even quicker this time reinforcing the focus through to recovery positioning by investors
That gold flipped from up 1% to down 0.5% as early US originated activity starts to kick in tells us that we are having a real risk-off moment driven by stresses in repo/eurodollar markets. Left unattended this can snowball very significantly
There is a risk the variant has an impact but but it seems a tail risk for now based on what the scientists are saying and the hospitalisation numbers haven't increased much considering this has been in the UK since at least October, so I wouldn't use it as my base-case.
That gold has firmed back up is a positive sign for risk. Not anything intrinsic to gold (ie I'm not making a gold bug type statement) just that when collateral stress happens in repo/eurodollar gold is often sold to meet margin as its the second cleanest collateral after US govt paper (so if you're a leveraged hedge fund and you can't post treasuries to meet margin calls, gold is next...and as it is a much smaller market that creates volatility).
I'm removed from the blow by blow of these markets so I'm guessing re what's going on and will only truly find out after the event...but I take some comfort that the gold price firmed up for market structure rather than gold reasons.
To me its a hint that the Fed has been very active very early this morning....we'll find out from news later
TBC the above is tea leaf reading by me...so take with a pinch of salt
Stimulus was agreed, stocks would normally be up. It will have little impact on the UK anyway.
Selling US assets for US cash is USD neutral. US banks are buying US paper like never before because they need HQLA and are required to. The Fed will accommodate buying of any part of the curve which needs it, because they can. There isn't a significant risk to the Fed or the banking system at the moment as they provisioned hundreds of billions between them already this year and capital adequacy is at or above 15% for most banks - which is the strongest for 10 years or so. JP Morgan are even buying back $30bn of stock.
With Brexit and increased infection rates and harsher measures it was obvious traditional or 'non-covid' or value stocks would drop.
I mean I can sleep when I remove risk, I see much less downside risk in Just Eat Takeaway.com Nv (LON:JET) than I do Gold or Gold miners or banks etc.
Just Eat Takeaway.com Nv (LON:JET) is likely to triple revenue from 2019 to 2021-end and it is only 20% up on pre-covid. The infrastructure of restaurants which have been added to their market place since covid is in the hundreds of thousands all over Europe. The rest of europe has also gone in to an even greater lockdown and are slower at rolling out the vaccine.
Even post-covid, there is the Euro 2021 tournament and the Olympics which are famously boom times for takeaway, not to mention the vast social gatherings which will take place once this is all over.
Nothing is obvious. Its a dangerous mindset.
My view is that if this dual shock of lower than desired (by market) stimulus and variant covid is suppressed/modest then the likely groove of markets is back into the reflation/recovery stocks. The post wobble rally could be very powerful given seasonality and the likelihood of a lot of repositioning into the new year. If the long Amazon short the rest trade doesn't accelerate like a ludicrous mode Tesla then the margin selling of this sort of sure fire covid stock could be large. This is not a forecast just a comment on how markets work and surprise the tendency for rearview mirror investing.
I own gold miners that are low single digit multiples of EBITDA and even allowing for ongoing investment needs they are below 5x CF. Operating margins are very high. They also have production growth and they may benefit further from high gold prices (note the benefit of high gold prices is not really recognised in many of these stocks as many gold miners were operationally hit by covid). Obviously if the gold price falls a lot then its less rosey. However, some degree of price fall is implied in stock pricing IMO. I don't recommend gold miners to anyone as they are a rough and volatile ride....DYOR and brace...sometimes they price on 'fundamentals' but other times they just swing like macro counters pushed around by risk and ETF flows. I am not a gold bug
Just Eat Takeaway.com Nv (LON:JET) have a lot to prove. Throw a lot of capital at something and you can always generate revenue.... foodtech looks like a classic over investment and hype mania https://themargins.substack.co...
Thg Holdings (LON:THG) has a lot to prove with regard to its valuation and 'platform tech' credentials. We talked about it last week and it seems to me you did not really know it beyond the hot story. Again today you show lack of knowledge in your recommendation as THG is net cash (based on the v cursory work I did last week). I cannot see that the actual platform tech piece they promote so heavily is more than approx 1% of external revenue. The company trades on 4.5x revenue as beauty and health product plus gym/hotel biz. I feel you need to make a much stronger argument than merely its a good vibe. There is evidence in their RNS of feeding hype IMO...for example the statement re in Q1 they secured over £200m of future revenue for their Ingenuity (ie platform tech) product. It may prove a great investment but the odds are that it will be worth much less than now before it is worth much more than now. My bet of a pint that Lloyds Banking (LON:LLOY) beats it in 2021 stands. Its not that I think Lloyds is great, I'm just using it to make a point (and it is probably the least liked of the UK banks too which is why I used it)
Amazon is a great businesses. But what price?
Boohoo (LON:BOO) and Electronic Arts are respectively potentially great and great businesses. Neither are cheap but they might be worth the price...not for me as I'm very rarely clever enough to see the value in such valuation levels particularly when I know that a lot of people already see the greatness.
"Just Eat Takeaway.com Nv (LON:JET) have a lot to prove. Throw a lot of capital at something and you can always generate revenue.... foodtech looks like a classic over investment and hype mania https://themargins.substack.co..."
We certainly disagree on this every time because everything with a whiff of technology is a 'hype' to you - I've lost count of how many times I've read you say it.
This article specifically is about DoorDash which is operationally very different to Just Eat Takeaway.com Nv (LON:JET), they don't have a 'marketplace' business model - they are like Deliveroo where they just deliver everything and anything, even at a loss. I encourage you to dig in to this, they are very different business models.
Do the math, go take the Market Cap of £11bn, add $7.3bn they paid for Grubhub, add the combined revenue and projected EBITDA ($5-6bn by the end of 2021, and over 500mio respectively), then scale that in whatever estimate of growth you wish to use above a conservative estimate of 20% growth - which is well below pre-covid growth, scale it down over time and see where you end up.
The Grubhub deal was a stroke of genius and was purchased at 30% of the actual value back in April. There will be a significant re-rating once it become part of the combined company because it is currently capped at the deal price of $75. The US market only has 3 main players and has a huge market size est. 100+bn.
Technology isn't automatically a hype, it is a productivity gain in industries which are particularly bad at leveraging operations, that is why they grow so strongly.
You have at least changed your mind on Boohoo (LON:BOO) but I'm actually more bullish Just Eat Takeaway.com Nv (LON:JET) than Boohoo (LON:BOO) personally.
There are some over hyped stories like £SNOW (Snowflake etc.) but doesn't mean all companies with some technology focus are hype.
In banks, I don't see any catalyst for earnings growth other than some increased volume for loans, everything else is against them, which is why they are so cheap. I worked in banking for a long time and it was on a downtrend and has been since 2007.
Let me pose a question to you:
Once covid is over and there are only 2 or 3 players in food delivery with all the restaurants, which restaurants are going to move anywhere but the main one or two players with all the users and restaurants?
That is a duopoly waiting to happen and great for shareholders.
"Thg Holdings (LON:THG) has a lot to prove with regard to its valuation and 'platform tech' credentials. We talked about it last week and it seems to me you did not really know it beyond the hot story. Again today you show lack of knowledge in your recommendation as THG is net cash (based on the v cursory work I did last week)."
I didn't even read this when I first read your post because I tuned out when you resorted to your usual 'it is hype' criticism.
I sent you about 5 pages worth of explain of the Thg Holdings (LON:THG) business, the model, infrastructure, how, why and by how much margins are increasing by and you say I only know the 'hot story'..................
If you don't agree then don't buy, you don't need to keep up with these poor arguments that everything is over-hyped because you clearly just ignore all the facts I say anyway even though there is no justification for buying gold at this price and you have no real reason for it other than 'gold price is high and inflation', therefore buy. What is more hyped?
I remember back in 2010 having a discussion with an Asset Manager (sales) who worked at the company I worked and he just kept going on about how great gold was and he put all his clients in it and I told him how it is not the hedge you think it is, it is speculatively priced depending on risk like anything else and centralises risk on one exposure.....a few months later it tanked...
you didn’t send 5 pages and what you did had no real detail other than copy and paste. You still haven’t shown you understand the nature of revenues in the all important THG Ingenuity (platform tech bit).
Everything thing can tank. I didn’t own miners in 2010. I’d held cash, gold, yen, Japanese equity and short financials going into 2008 and made money. In late 2008 I started buying (early but after the massive Chinese stimulus and credit easing.) particularly with EM bias.
2010 was a different time tho so why would I do same thing today?
Technologies great and so are platforms. I own some, I’m just not a relentless unquestioning fanboy. Just Eat Takeaway.com Nv (LON:JET) may be as good and obvious as you say but curious that such a stock is not valued at more than 2x visible ebitda in current environment. Investors are usually quite observant of stuff like that for things that are defo on trend...as your maths is so good how do you explain? If you are correct and ebitda proxies cash flow then you’ve got a 25-50x bagger on your hands. Is that your expectations based on your knowledge of the ‘maths’? maths is certain stuff -right? - so this is astounding.
I haven’t looked at Just Eat myself ...do you want me to do that for you? Or will it be above your head like THG and you just return to spinning narrative from company?
"you didn’t send 5 pages and what you did had no real detail other than copy and paste. You still haven’t shown you understand the nature of revenues in the all important THG Ingenuity (platform tech bit)."
Copy and paste from where? You have gone from baseless to just lying. I sent you information on every segment and how the distribution has evolved to leverage margins.
"Everything thing can tank. I didn’t own miners in 2010. I’d held cash, gold, yen, Japanese equity and short financials going into 2008 and made money. In late 2008 I started buying (early but after the massive Chinese stimulus and credit easing.) particularly with EM bias."
You are now claiming you were part of the cast of the big short? How hilarious. Japanese equity has been poor over 10 years and much of EM excluding China has been quite poor when including covid. The only market which has really outperformed is US consumer tech,
You stick to your Gold Gold Gold mantra to get some likes on here and I'll keep analysing growing companies and we shall see which one outperforms because growth and consumer technology has only outperformed massively for the past 10 years so far!
Safe to say we can agree to disagree. If you have nothing worthwhile to add I appreciate if you stop replying to all of my comments.
Gold miners up, US banks up strongly. Its a day, not proof by a long shot, but just FYI. But they are not platform tech rarara so probably just a dumb luck day for me (I don't have many banks actually as there's better growth with margin and value elsewhere in financials and I agree its hard to see through the capital cycle long bottom banks are experiencing....but history says that is the time to take risk in a sector so I have taken some).
This is great analysis that you may relate to:
Anyway, I think we are all bored of each other and I am about to be smothered in red thumbs for arrogance etc....behind the veneer there is doubt and humility....but I've done markets for a long time (admittedly more macro historically) and like a shark I know you got to keep moving and playing as you see....and lunch is better if you haven't arrived at the same spot as everyone else.
Bye!
I'll engage on Thg Holdings (LON:THG) since I've looked at it now. Best to put it in separate post so as we don't crowd this...obvs needs a lot of space for Boohoo (LON:BOO) ;-) ...and if I look at Just Eat Takeaway.com Nv (LON:JET) I might come back to you. I'm happy to learn
Thg Holdings (LON:THG) is up, Just Eat Takeaway.com Nv (LON:JET) is up, Boohoo (LON:BOO) is flat, Lloyds Banking (LON:LLOY) is down, £TSLA is down but US banks are up because of US stimulus and they have been allowed to buy back shares.
US banks are a very different beast to UK banks though, they have less competition from incumbents and half of their revenue comes from services (AWM/CIB), not commercial banking and NII.
I didn't say Lloyds Banking (LON:LLOY) was great...I just said I bet you a pint it outperforms Thg Holdings (LON:THG) in 2021. I push against you as you post ra ra stuff saying things are obvious and I think its dangerous and you've called me out in some dumb ways IMO...
...you might be a market genius but TBH not many are. I've met and interviewed/analysed some that are claimed to be by onlookers such as Nick Train, Joel Greenblatt, Bill Ackman, Jim Chanos, Steve Eisman, John Paulson, many ex SAC but never Stevie and I'd only consider it for Greenblatt of the famed investors I've met. Paulson is perhaps the most lauded in his moment of glory of the bunch I've mentioned and IMO he was a 'lucky fool' (he's not alone in that though...and he was very good at raising assets so got very rich!)... he doubled down so hard on credit default swaps during 2008 that he could have easily had volatility blow the implicit leverage in his fund (it was an insanity bet IMO)....but the market and leverage went his way and he was the guy that got famous for minting it in the crisis (before The Big Short made Michael Burry famous).
I consider myself a student of stock picking in that I have not done directly for myself with earnest focus for very long (I've made some howlers doing if for myself). So I often doubt myself (as well as others). But I do have other market knowledge and experience. In 2008 before the credit crisis peaked I seeded (with c.$75m) a large cap quality growth fund management business (very tech biased)...it did superbly as it was the time...that money came from taking away from a momentum-EM managed in early 2008. In 2012 I seeded small cap biotech business and it went on to make c.700% over a few years (nice!)...at the same time I also seeded an Argentine equity mandate (which also did very well...and very different from tech) and invested heavily in Japanese smid (a lot of tech). In 1999 as a whipper snapper investment consultant I did what I could to prevent my partners from sacking 'old and finished value investors' PDFM and GMO for UK pension funds and moving to large cap growth or even Amerindo (look them up they are 2000 equivalent of ARK...absolute effing nonsense, make ARK look respectable).
This time may be different...but that is not the low risk perspective. Today many are running on the fumes of a great mega bull run. Its like addiction...comforting whilst high on it.
Anyway, best you stop speaking to me now. Bragging rights over a day in markets is a bit silly so take my 2021 bet...then you can ridicule me in 2022 with justification. I really wont mind.
Like I've said, its not that Lloyds is in any way great...but you recommend THG (and other fashionable high valuation things) as surefire safe for 2021 and I'm putting up the junkiest of the junk no hoper against that to say that your rearview mirror investing certainty is bad timing and risk management. My experience tells me that markets tend to flow the way I'm playing it. I do have a small position in Lloyds (its in a basket of 5 comventional-ish banks that make up 5% of my portfolio...so equivalent to one full position). I feel nervous about it but instinct and experience tells me its time to look for those narrative 'unclean' risks.
Bye now. We really got stop talking for a bit. We are boring people. Take it to another separate post if you want to debate...I've put it here just in case https://www.stockopedia.com/co...
I have never, ever, said I am or will be right or gloated. I have discussed promising companies and pointed out the market has a good impression of them now and it is increasing, you are the one who has levelled a number of assumptions at me (hyped, copy and paste etc.)
I want people to discuss Thg Holdings (LON:THG) Boohoo (LON:BOO) Just Eat Takeaway.com Nv (LON:JET) and others, so that if they do have information which I don't it will be good to know.
I don't want my every topic knit-picked as being BS hype because from my long experience of investing (which we all have and I don't claim exclusivity on) strong growing companies compound and outperform over many years. Whether they are a drinks company or a tech company, I just particularly like consumer tech.
Personally I have bought some cheap companies (like £BT. which I told you about) and that didn't go well so I realised what I was doing was wrong and cheap just got cheaper.
Now I buy growth at a reasonable price where I think they are solid and there is more upside risk for surprises in performance due to quality management, than potential skeletons in the closet.
That is not to say I never buy 'value', I bought 'value' (Barclays (LON:BARC) £EZY Taylor Wimpey (LON:TW.)) twice this year and sold again, just because I get uneasy in them and I don't see them as long term winners. That is just my personal view and experience.
FYI (and as you mis-sell your recommendations as conservative) GARP may stretch to Boohoo (LON:BOO) - but that would be quite a modernist unorthodox redefinition of growth at a reasonable price. Boo is high growth and high valuation, its got to execute on high sales and earnings growth or there will be no reasonableness in the price. Its shown it can do that so far for sure so with Hindsight Capital goggles on expectations of it growth has been reasonable.
Electronic Arts is the only stock you've promoted that could fit into a GARP investor's portfolio without them choking on their hobnob.
If you believe that Just Eat Takeaway.com Nv (LON:JET) , Amazon, Thg Holdings (LON:THG) are safe-ish GARP like stocks then you are in a cohort of one (other than mad commentator on Bubble TV)....now such contrariness can pay but one should recognise one's hubris in being so unique and dissonant. I always feel hubristic when I take contrary positions....but I do it though rarely with super high expectation stocks (as implied by valuations) as the landing strip for my dissonant expectations is narrow and very high.
I get confused as to whether you are a trader or an investor (as you mention being in an out of stocks a couple of times in short period). I don't trade much and look for things that I believe can at least double over a few years with embedded optionality that can take me higher and longer if I'm lucky. Optionality is never a certainty so it is always partially luck if I get it... Tremor International (LON:TRMR) is my current (nervous) example.
If you are trader then by all means just play the narrative flow and to hell with the long term always bounded possibilities.
mojo out
Mojo, that tweet is pure gold. I’m off to buy Tesla
Phuntt, he's a good follow on Twitter. Quite inane but in very current way for financial markets. Who knew finance was so good for humour!
"Just Eat Takeaway.com Nv (LON:JET) is likely to triple revenue from 2019 to 2021-end and it is only 20% up on pre-covid."
True, but the trebling of revenue is a consensus forecast, and hence already embedded in the share price.
Going forwards, the share price will be determined by how expectations change.
Just Eat Takeaway.com Nv (LON:JET) has exprerienced persistent downgrades this year, so it has been re-rated to be up "20% up on pre-covid."
Needless to say, this is a risky share price if those downgrades continue.
It is priced in now or priced in when it was at 10,000p recently?
Let me pose a question to you. Once covid is over and there are only 2 or 3 players in food delivery with all the restaurants, which restaurants are going to move anywhere but the main one or two players with all the users and restaurants?
That is a duopoly waiting to happen and great for shareholders.
The consensus is actually for EUR 2.6bn and 380mio EBITDA in 2021 for Just Eat Takeaway alone. It seems like Q4 2020 will be 45% growth on a conservative estimate to assume EUR 250mio per Q, the same as Q3. That would put 2020 revenue just above 2bn. This put the company on track to hit EUR 2.6bn to EUR 3bn in 2021 even on a slow down in growth from that point to 20% for the year. Q1 2021 will also see strong growth with Europe locked down but let's assume it is the same as Q3 and Q4 and revenue is flat across the three quarters.
That puts expectations of revenue at $5bn (~$3bn Just Eat Takeaway and 2bn Grubhub) in 2021 and potentially 5.7bn in 2022. This has also been estimated by several of the biggest analysts with EBITDA of near 600mio 2021 and 860mio in 2022 and nearly 2bn in net cash.
Just Eat Takeaway.com Nv (LON:JET) + £GRUB would have a current combined market cap of ~$20bn.
That is a EV/Sales of ~3.5-3.8 and EV/EBITDA of 34-40 for 2021 numbers.
You can factor in what ever forward growth and guidance you want beyond that date to give all forward cashflows but it's not high for a company growing at even 20% p.a. and is not even particularly looking out far into the future or into what new markets they could stretch to.
"How is it empowering for women to shout & swear all the time? Maybe I'm just getting old, but I prefer it when all people act with a bit of decorum in the workplace."
I know I am getting old and completely agree though I would have written:
".....but I prefer it when all people act with a bit of decorum".
Merry Christmas Paul in case I don't post a comment again and very much liked the short wrap up interview with Tamzin at PI world.
Just watching the one with Leon Boros. He was down 23% in March but is now up 33%. Extraordiary. (For context I was down 38% in March and am now down 4.4%)
Regards
Michael
Great Interview. I like Leon.. talks a lot of sense.
Anyone else think he looks like Jim Levensteins dad from American Pie?
Yes!
Hi Paul, Fully endorse your comments on the Covid Jab. My Mother had hers last Wednesday. Swift contact, seamless process and no after effects.
piworld 2020 round up interviews.
We published Paul's wonderful round up on Saturday, most reading here will be aware of Paul's year. Fantastic returns from hedging. On-going learnings, cheap stocks can get cheaper! And as we know Paul is very bullish about Boohoo (LON:BOO) for 2021. Watch/listen to the full interview here: video & podcast.
Today we've published Leon Boros summarising his year. YTD up 37%. Top contributor: Best Of The Best (LON:BOTB), which he continues to hold. Detractor: £GAW. Bullish for 2021: £WEY. Watch/listen to the full interview here: video & podcast.
Earlier interviews in the series with Cockney Rebel & Richard Leonard can be found here. There are another four interviews forthcoming! Happy Christmas from piworld!
Excellent Tamzin. These round ups are very informative. Thank you and a Merry Christmas.
Anyone else having problems getting quotes on AJ Bell / Youinvest this morning?
Hi - had no problem wit AJB first thing, but looking at early share and exchange movements, it looks like it may well be another "interesting" day in respect of price volality - so it may well be that delays aren't only going to be on the roads around Kent, but also on-line with the brokers.
Have a mince pie while you wait !
Yes.
I finally managed to buy some Avon Rubber at about the 10th attempt.
Avon Rubber (LON:AVON) - hope support at 3000 and should move to 3700 during the week. Novacyt Sa (LON:NCYT) may pick up as detects the new strain and I think testing is still going to be around for a long time and the tech is not just covid related so building a wide moat, but a competitive space.
Ok with them late morning.I previously made a complaint after poor service (site down and rubbish phone response) They offered me £250 to not pursue further
I received the same £250 from AJ Bell to not pursue further. I have not accepted their offer yet.
Re Boohoo (LON:BOO) in the US, I had heard (where I cannot remember) that they satisfy all their sales by air-freight out of the UK warehouse. If true, this must put them at a disadvantage against US home suppliers. However this does not really ring true as NastyGal is an acquired US brand. Anyone any better info than I ?
(BOO hold but only medium sized position)
The flight from New York to LA is 5 hours.
Heathrow to LA is 10 hours.
So they don’t lose that much relatively. The US is so big and, on the whole, not very densely populated thus it’s near impossible, until you scale to the size of Amazon, to have enough distribution centres. The US market is used to that and more tolerant of 2 day delivery timeframes.
IGPJ - Thanks. Helpful perspective
Its probably a bit out of date but I posted this a few years ago:
"I did a little bit of research earlier and found the following estimated delivery times in the US:
Boohoo – 6 days (standard) 8-10 days Supersaver
Charlotterusse – 5-10
Forever21 – 3-5 days standard
H&M – 3-5 days
Lulus – 7-10 + 2-3 dispatch
It is worth noting that there are next day delivery option also but they cost a fair bit more.
My take from this was that customers do in fact have a lower expectation of delivery times as you speculate but I do know amazon amongst others are at the very cutting edge of minimising delivery times so expectations will most certainly change.
It’s far from clear cut but I think that management have made the right decision keeping everything under their noses as they expand into the US but like you I can see a real need for significant warehouse expansion both locally and abroad in the near future."
I would like to see it updated with Shein and Fashion Nova but unfortunately don't have the time these days due to a 6 month old.
Merry Christmas and Happy New Year everyone.
Interesting, thanks.
Remember that eCommerce businesses can expand rapidly using managed distribution. E.g. Sosandar (LON:SOS) always talk very highly of Clipper Logistics (LON:CLG) , saying how good they are. It removes a massive headache from management time, freeing them up to concentrate on what they do best, so I'm a big fan of outsourced distribution, especially for smaller companies.
Joules (LON:JOUL) is a bigger company than SOS, but they really messed up distribution a while back, and sensibly decided to outsource it to Clipper.
In my Pilot days, we used to have constant headaches with logistics. It must have taken up at least a quarter of the CEO's time, which was wasted time. I saw the business noticeably improve its performance during phases where he concentrated his time elsewhere, mainly on product & store operations.
The other big drain of his time was new store openings. He enjoyed the process so much, that opening new shops became almost an obsession. The trouble is, many of them didn't deliver anything like the forecast sales. Hence why I think companies which are rolling out a retail/hospitality format really need close scrutiny. It only takes one disastrous new store, to wipe out the profits from half a dozen others. Hence why it needs a highly disciplined financial process.
Previous mgt at RBG made a big mistake with Torquay - it did well over the summer, but then was dead the rest of the time. New mgt have fixed this one recently I believe, with revised arrangements with the landlord.
Paul.
Re Fulham Shore (LON:FUL), there was a piece in the Sunday Times yesterday quoting David Page saying they had recently opened a new site where the landlord had paid all the fit it costs, and he therefore anticipated a high ROI in due course (and other similar deals).
My morning smallcap tweet:
Avacta (LON:AVCT) Sanderson Design (LON:SDG) Windar Photonics (LON:WPHO) Novacyt SA (LON:NCYT) Universe (LON:UNG) Symphony Environmental Technologies (LON:SYM) Deltex Medical (LON:DEMG) Dev Clever Holdings (LON:DEV), Surgical Innovations (LON:SUN)
Avacta (AVCT) license agreement with Astrea Bioseparations for the use of the Affimer platform in affinity purification applications. £0.5m upfront payment. [SP=135.5 Cap=342m]
Sanderson Design Group (SDG) guides FY(Jan) pretax substantially ahead of management's previous expectations due to demand in home improvement and furnishings mkt. [SP=78.25 Cap=56m]
Windar Photonics (WPHO) guides FY(Dec) up 21% after strong H2. £495k placing at 11.25p, nil discount. [SP=20 Cap=10m]
Novacyt (NCYT) computer simulation predicts co's test will be able to detect the new covid strain with the same accuracy. [SP=870 Cap=675m]. I hold.
Universe (UNG) rev from roll-out of a material project for an existing customer won't be booked this FY but related costs will be. Guides H2 rev similar to H1 and modest adjusted EBITDA 'profitability'. [SP=5.5 Cap=14m]
Symphony Environmental Technology (SYM) launches case against EU for a directive banning oxo-degradable products that do not properly biodegrade and are not recyclable with ordinary plastics. Co "continues to explain the difference between oxo-degradable and oxo-BIOdegradable plastic" but the Directive has not made this clear. " [SP=22.04 Cap=39m]
Deltex Medical (DEMG) considering ways of simplifying its year-end balance sheet. Update on commercial activities. [SP=1.5 Cap=8m]
Dev Clever (DEV) five-year exclusive partnership agreement with Veative Labs and the National Independent Schools Alliance, India's largest governing body for budget private educational institutions. Dev Clever's Launchyourcareer will be platform-of-choice to deliver a career guidance across NISA affiliated schools which have c.13m students. [SP=7.5 Cap=35m]
In line: Surgical Innovations (LON:SUN)