Small Cap Value Report (Mon 21 Sept 2020) - SDRY, CRW, AUG, FCAP

Good morning, it's Paul here with the SCVR for Monday.
Timings - after a leisurely start today, I'll be writing here until about 3pm. Sorry, I was too tired to write any more, after watching the Beeks Financial Cloud (LON:BKS) results webinar after lunch. See tomorrow's report for a catch-up session. Today's report is now finished.
Today's agenda
Superdry (LON:SDRY) - ridiculously late results, which have taken 5 months to be published. Covering the 52 weeks to 25 April 2020
Craneware (LON:CRW) - Final Results for FY 06/2020
Augean (LON:AUG) - Interim results to 30 June 2020 - see tomorrow's report
Finncap (LON:FCAP) - AGM trading update - see tomorrow's report
For general interest - initial report from the FRC on the collapse of Carillion.
.
Superdry (LON:SDRY)
Share price: 137p (down 10% today)
No. shares: 82.0m
Market cap: £112.3m
I've been itching to see some numbers from this fashion brand retail/wholesaler, and have been having a vigorous debate with a friend who is bullish on it, and me being bearish. My view is that SDRY was only trading around breakeven before covid struck, so with a lot of expensive flagship stores, it's probably been losing money hand over fist in recent months during the shutdown. Also, will its wholesale customers be willing or able to pay their invoices?
The founder, Julian Dunkerton, returned as CEO, in an attempt to restore the brand to previous glory, after a period of poor management by hired hands. It's interesting how brands often lose their way, once the founder exits, and no longer has that oversight of everything.
The statement today is headed;
Performance materially impacted by Covid-19 disruption. Cash and liquidity remain strong
Brand reset continues with the launch of AW20 collection
The company has certainly been unlucky with timing. Not only is it having to deal with covid/lockdown, but also it's trying to "reset" its brand by focusing the product ranges (getting rid of things like kidswear which devalue the brand), and trying to re-establish full price sales instead of heavy discounting. Brand resets are very difficult to pull off successfully, because once a brand is damaged, it tends to remain damaged because the sparkle has gone, and the brand has become old hat. To resurrect a brand, it needs outstandingly good new products, that become must-haves for customers. Otherwise, they just wait until the prices are reduced in the sales.
The numbers look bad, and remember this only includes about 1 month of impact from covid lockdowns, which started in the UK in late March 2020.
Revenue down 19.2% vs LY at £704.4m
Gross margin also down, 150 bps to 53.6% - although remember that is a mixture of retail (higher margin) and wholesale (lower margin)
Underlying loss before tax of £(41.8)m (LY: a profit of £38.0m)
Huge exceptional costs, of £125.1m - mainly a charge to write down the value of the leasehold stores, which are now a financial millstone, rather than an asset - because traditional rents are now far too high. The trend is for retailers to do a CVA or pre-pack administration, and secure much cheaper turnover rents. I wouldn't invest in any company like this unless & until they have got rid of the problem leases in that way. Otherwise shareholders are just likely to be pouring in fresh money, in order to bankroll the landlords. What's the attraction of that?!
It's useful when companies estimate the financial impact of covid/lockdown, which Superdry does here;
We estimate that the profit impact of Covid-19 across all of our operations, including lost sales and additional costs experienced in FY20, amounted to ~£62m. This has been calculated as the gross margin miss to forecast in March and April, the increase in bad debt for the same period as well as the Covid-19 stock obsolescence provision at the year end, less the impact of the furlough benefits and UK rates holiday in April.
Bear in mind that £62m lost profit is only up to end April 2020. Therefore it's likely to be the thin end of the wedge, with far higher losses in FY 2021 being likely. My worry is that this profit impact could overwhelm the company.
Net cash is slightly up, at £36.7m - cash conservation measures taken - I wonder how much VAT/payroll taxes have been deferred? I'll be looking for signs of creditor stretch on the balance sheet
Having established that performance is weak, the key question is whether it is at risk of going bust? The balance sheet strength is key when any company is trading at a loss, so I'll focus on this next.
Balance Sheet - note that the results include a £19.7m charge for inventory & debtor provisions. There could be more provisions necessary in the new financial year.
I've checked the last Annual Report, and it only seems to have £4.8m in freehold property. The stores, and fixtures & fittings seem to be leased, hence have little to nothing in resale value, and I doubt any stores have any leasehold premium valuation any more.
NAV is £112.7m, less intangibles of £48.4m, gives NTAV of £64.3m - still a reasonably solvent position. Although looking forwards, the company must be losing money heavily in the new financial year FY 04/2021, therefore I would expect this balance sheet to be deteriorating quite rapidly.
Unusual cash position - note that the group has £307.4m cash, but £270.7m in current liabilities marked "borrowings". Although these are shown separately, the notes explain that these are pooled cash & overdrafts, i.e. different parts of the group bank with the same bank, which nets off the surplus and negative balances. I think the accounting treatment is misleading here, in that by showing them separately, it is not reflecting the commercial reality that SDRY could not withdraw the £307.4m cash, and spend it on something like an acquisition. It's tied to the overdrafts. I don't know why they do it like that, maybe it's to avoid triggering tax liabilities by moving money abroad, I have no idea. The key point to understand, is that SDRY is not cash rich, most of that cash is spoken for, in overdrafts.
Leases - under IFRS 16 the Right of Use Asset is £118.0m, which is dwarfed by the lease liabilities: £80.1m current, plus £240.8m long term. Thus we have a £202.9m deficit on the leases, if we net off the theoretical asset, and the actual future years' rental liabilities. That's a big problem. Although some rent reductions have been achieved, and some leases might be capable of being restructured, landlords normally won't consider any negotiations until the lease is nearing expiry or break clause. So I cannot see any way around these horrible lease liabilities. It's just going to be a constant drain on the company's resources, having to pay now uneconomic rents. This is the company's biggest problem, and the solution is clearly a CVA or a pre-pack. I consider this share uninvestable until that is done.
Bank facilities - this is interesting, and could be a good way for struggling retailers to refinance. Note that French Connection (LON:FCCN) (which I hold) has also recently refinanced with an asset-backed loan (secured on the receivables book, and inventories, I assume, which are the main assets for these type of businesses).
Post year-end, completed the refinancing of our facilities to an Asset Backed Lending facility of up to £70m due to expire in January 2023, with amended covenants
Going concern - these are always an interesting read. Remember it's the auditors who require these disclosures, and although auditors are frequently criticised (often with good cause), they're earning their fees at the moment, with useful going concern notes.
The narrative frequently uses the phrase "material uncertainty" over going concern, so shareholders have been warned. If you choose to ignore this, then it's your risk. The risk is obviously that the company has to raise more equity in future, and dilutes existig holders heavily. Or, worst case, it ends up going bust once funding has dried up.
If the turnaround plan doesn't work as expected, then the business is in trouble;
However, a sustained downturn as a result of the new strategy not turning the business around, and a failure to renew the ABL in January 2023, would threaten the viability of the business over this four year assessment period.
Current trading - unfortunately, we're only given sales figures, not any indication of profitability.
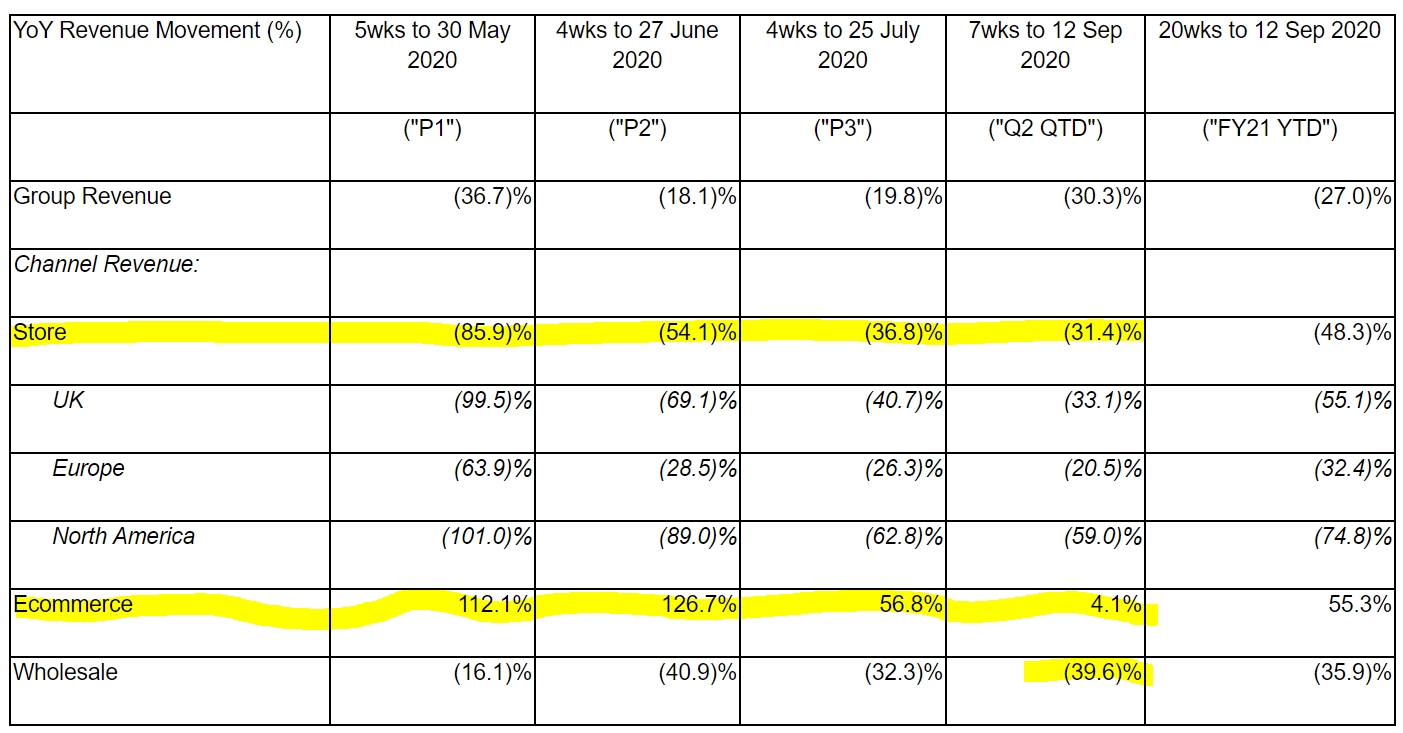
The table below shows revenues by channel, initially for the first individual months (periods 1,2 and 3 which together are Q1), then it shows the most recent figures for Q2 to date (7 weeks), then the grand totals.
.
.
As you can see from my highlighting, the stores revenues are in a recovering trend, but the most recent figures are still (31.4)% down on last year, which will have disastrous impact on the bottom line. Although it isn't paying business rates this year, which is a useful profit boost, helping to blunt the damage.
Online grew strongly when the shops were shut, but the most recent column shows that the growth has since stalled.
Wholesale is also heavily down, and has deteriorated again in the most recent column.
My estimate of losses - to put these numbers above into perspective, if we work on annualised numbers, then £704m starting revenue, then (30)% fall is £211m lost sales. On a 53% gross margin, that is £112m lost gross profit. There might be some cost reductions too, but most costs are largely fixed. So I reckon at least half of that lost gross margin would fall through to the bottom line, which means that full year PBT performance would be down maybe c.£60m on FY 04/2020 (a loss of £(41.8)m underlying), so I'm estimating a FY 04/2021 loss of over £100m. That's before thinking about any further write-offs of receivables, inventories, and stores fixed assets.
It's difficult to see how lenders would want to continue offering borrowing facilities, if actual performance is that bad. They could insist on an equity fundraising being done, as the price for covenants being eased & facilities extended.
My opinion - it's very clear to me that my earlier caution on this share was justified.
With greatly increased losses in the current year FY 04/2021 looking likely, I think time is running out for this group. The one hope is that its new season range might wow customers in such a way that it starts reporting revenues up on last year. There's no sign of that yet, with the most recent sales figures still looking poor, even online.
As things stand, this share looks very high risk, and I'd say a refinancing with dilution to existing holders, is probably only a matter of time. It needs a spectacularly good turnaround in performance to reverse the decline that has set in. How likely is that? Not very, in my view, but I'll keep an eye on future trading updates, in the hope of spotting a turnaround, if one appears. The founder's reputation, and life's work is on the line here, so he couldn't be more motivated to get this right, and is likely to be highly tenacious in attempting to stop the rot.
It's not a risk I would want to take though. There are better opportunities elsewhere, with homewares retailers that are rapidly recouping lost sales (e.g. Scs (LON:SCS) - I'm long). I think that's a much better spot, than heavily loss-making, tired brands like Superdry (LON:SDRY) or Ted Baker (LON:TED) , chasing after their former glories, but laden down with uneconomic property rents.
I can't find any up-to-date broker forecasts unfortunately, so have no idea how they see things at the moment. If any subscribers have got recent (i.e. based on today's results) forecasts on SDRY, maybe you could kindly post a comment below with their estimate of losses in FY 04/2021? That would be really helpful. Isn't it crazy that forecasts estimates are so elusive?
EDIT: another thought just occurred to me. Retailers are currently benefiting from the suspension of business rates. What happens when they are reinstated in April 2021? It's going to cripple many retailers which just about survived the current crisis. Superdry says this is a £16m benefit, most of which is assisting FY 04/2021. However, what happens when this benefit disappears? The company's underlying losses will then be even worse, in FY 04/2022. End of edit.
.
Craneware (LON:CRW)
Share price: 1600p (up 2.6% today)
No. shares: 26.83m
Market cap: £429.3m
Craneware (AIM: CRW.L), the market leader in Value Cycle software solutions for the US healthcare market, announces its audited results for the year ended 30 June 2020.
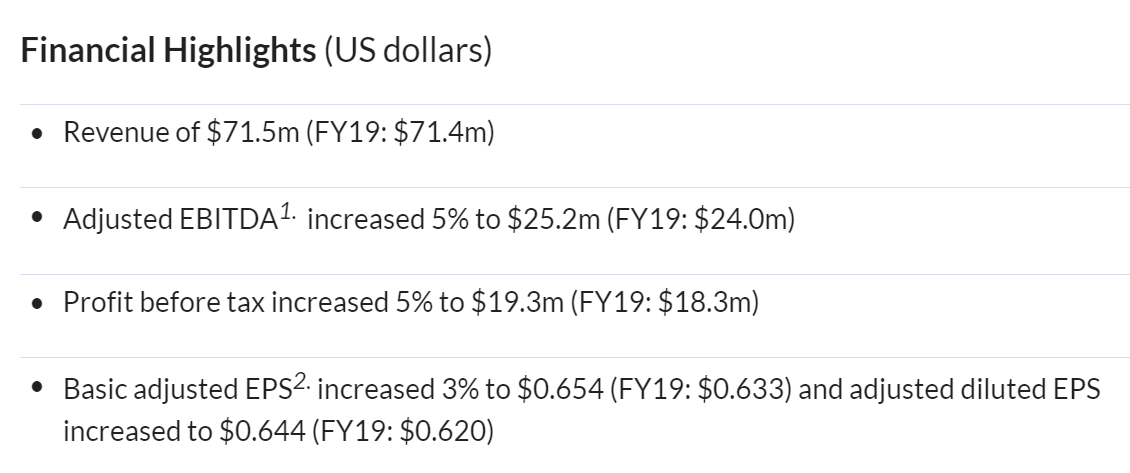
Growth seems to have stalled, although it depends how much of that is due to covid, and how much is underlying?
.
Using the last bullet point above, adj earnings of 65.4 US cents is 51 pence, so the PER is 31.4, which seems expensive if the business is now ex-growth?
There seems to have been a sharp slowdown in Q4 (April-June), which I'm struggling to reconcile with the supposed high level of recurring revenues;
Total Sales to 31 March 2020 tracking 30% ahead of same period in FY19, impacted in the final quarter by COVID-19
.
Outlook - it sounds as if things are improving now;
"We have experienced strong sales momentum in Q1 and continue to have sales discussions with hospitals across the US. We are cautiously optimistic we are seeing the first signs of sales cycles slowly normalising; however, we remain cognisant of the ongoing macro uncertainties.
"We continue to benefit from a strong balance sheet and high levels of recurring revenue, entering the new financial year with an annuity revenue base of over $65m, providing us with a strong foundation for future growth."
Balance sheet - is quite good. Note that about three quarters of the $48m cash pile has come from customers paying up-front (deferred income), which might fluctuate during the year. Companies often set their year ends to coincide with cash being at a peak (that's the sensible thing to do, anyway!)
My opinion - this is a strongly profitable, cash generative business. I've always found it remarkable that a relatively small UK company is a significant player in the USA health system. Rather impressive.
The only question is, how to value it? The share price has roughly halved from a peak 2 years ago, but it still doesn't look cheap, on quite a high PER, and divis are less than a 2% yield.
I've always liked this business, but am still not convinced that the share price is a bargain. So I'll conclude that I'm neutral on it.
.
That's it for today. See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
good discussion on RNS, genuinely excited by the suggestions given that similar to Gromley, I have done a bit of work in this space and have been doing a lot lately given the opportunities offered by the volatility of recent markets
I have been interested in the opening price action as a function of RNS for a good few years and aggregate these daily. I tend to focus more on the quantitative response of price to the catalyst rather than attempt to interpret the qualitative value of that catalyst (on a simple premise that price is truth .. or at least .most of the time)
I've been doing a lot of work lately to aggregate and integrate different catalytic data sources such as RNS, FCA daily short interest etc and relating this to the opening price action . I've also been characterising the gaps that result and then looking at how they perform over time to simplify some quantitative rules on trades to take as a function of volume, gap size and technicals (moving averages , volatility breakouts etc) as well as providing a basis for deciding the best execution mechanisms given liquidity, volatility and spread (CFD, versus SB versus shares). Data can be queried by MCAP, Index, Sector, Volume , ATR , MAs etc
It is still work in progress but given the richness of the above discussion, thought I would gauge interest as I intend to offer something live in the coming weeks and will provision a trial to anyone interested.
Below are a few visuals from one of these reports: the actual reports are relational and interactive so can be queried, analysed and structured. They are not really fit for mobile and don't reproduce well here as JPEGS so apologies for the formats below but hopefully you get the gist.
visit my website at https://runprofits.com and sign up if you are interested ....
Augean (LON:AUG)
This might now be smallest holding, but I am minded to top up. Some thoughts:
There is a supposed 2nd half weighting (as per last year) so let's assume this year will generate +£20m of cash after Capital Expenditure.
With a Market Cap / EV of £168m this is impressive.
What might be less obvious is that the company has not been paying the same tax for 2018 and 2019. If HMRC chase them for this, then the company will need to pay up.
By my calculation, based on tonnes of waste produced and included in the annual reports, this amounts to an underpayment of £17.5m over these 2 years.
So debt is sort of gone, unless you include this potential liability.
(for reference, this reduces the £20m annual cash generation I mentioned in 1. to c £14.5m by my calculation)
There seem to be a lot of potential surprises here, so why am I interested in topping up?
Well, in my mind there are 4 different scenarios:
SCENARIO 1 - HMRC WIN, THINGS DON'T RETURN TO NORMAL
The company will still be generating c £15m a year in cash.
For me this is still reasonable for a growing company with an EV of £168m + £17.5m = £186m.
SCENARIO 2 - HRMC WIN, THINGS RETURN TO NORMAL
The company will be generating >£20m a year in cash and be in growth mode.
For me this is cheap for a growing company company with an EV of £168m + £17.5m = £186m.
SCENARIO 3 - HRMC LOSE, THINGS DON'T RETURN TO NORMAL
The company will get back their £40m and be generating >£20m a year.
For me this is now very cheap for a growing company with an EV of £128m.
SCENARIO 4 - HRMC LOSE, THINGS RETURN TO NORMAL
The company will get back their £40m, so have an EV of £128m, and be generating >£20m a year in cash after capex. This would make the company super duper cheap at current levels.
I'm comfortable with all the above eventualities at the current price.
For reference I personally believe #4 will be the likely outcome.
If there is one thing putting me off, it's the lack of company updates, as someone else pointed out in the comments today. It's quite ridiculous how little information has been provided by the company this year and the longer the periods of silence, the more wary I become.
It would be interesting to hear the thoughts of other holders on my thoughts above.
Cheers
A
An excellent piece of analysis Abtan, thanks. Have owned LON:AUG* since 2013 and have traded in and out and am left with a decent size holding that has a negative in price which always makes me a bit bolder than usual. I'm with you in that I think the downside has been fully priced in. One thing I'd add is that North Sea Oil is going to have a very substantial clean up/decommissioning bill and these guys are very well positioned in this regard. Was already getting my interest and you've kindled that further, may well make a move over the next couple of days.
Was tipped AUG by a chap called Paul Hill from Money Week. He left suddenly and I never had the time to thank him for his excellent work. If anyone knows him please pass on my regards and tell him a bottle of something nice awaits!
Hi Berksbee,
You can find Paul Hill on twitter @CapitalPmh Apologies as I don't know how to make this a live link through to Twitter as still learning.
Regards,
Andrew
Hi Abtan
Have you written directly to the company and asked them why they are not updating as a PI?
If not, it is an easy start to send an email off.
Then possibly use this to say can anyone else who holds also send something of on the lines of. #Shareholder Activism?
Just thinking that in my old job when I got one letter "to the CEO" it was a quick reply and issued out, but when he got 10 or 20 letters on the same issue, I was called into his office "to explain WTF was going on" and all the responses went out with my personal email and mobile number on saying contact me in the first instance...e.g. do not let this happen again.
Just a thought
Tommy (I do not hold)
Re Craneware (LON:CRW) FY results ending June 2020, capitalised intangibles amount to $9.5M vs amortisation of $2.5M charged against these items arguably over-stating earnings by $7M. Not as profitable and cash generative as it pretends?
(No position.)
Did you give up on Augean and Finncap?
Hi
Boohoo (LON:BOO)
Hope somebody can enlighten me. I received an invite from Research Tree:
"Zeus Capital is organising the following Roadshow Meeting for the following company(s): boohoo group Plc"
I cannot attend because it is only for institutional investors. (though I only discover that once I have clicked through!)
I am a shareholder in Boohoo (LON:BOO) and while only a minute portion of the company it is a 10% holding for me.
How can some information be available to certain shareholders and not to others. Surely the information should be either insider information and not for release or not and available to all.
Otherwise it means that certain individuals are trading at an advantage to others and I cannot see how that can be right.
I know it is legal but I do not understand why.
Searching for enlightenment!
Regards
Michael
As if worrying about downward share price movements is not enough for one day, for those who have not picked it up there is equally bad news on the savings front: https://citywire.co.uk/funds-insider/news/blow-for-savers-as-nsandi-cuts-rates-and-premium-bond-prizes/a1403272?ref=citywire-money-latest-news-list - some of which is drastic - market leading instant access a/c goes from 1.16% to 0.01%. This will undoubtedly lead to a downward spiral as few building societies want to be top of the 'best buy' list or they would be swamped.
Perhaps there is a good read-across to shares with reliable, well-covered dividends. I have twice profited quite well setting up a yield portfolio when interest rates were sliding.
It's sad to see Superdry (LON:SDRY) in this state. I had the same Oh, Superdry t-shirts are everywhere prejudice until I was given a t-shirt as a present and realised there's a reason why the t-shirts are seen everywhere: the product is actually good. Softer, heavier cotton. Quality materials with real design input.
Just goes to show that's it's not enough to have a good product - you also need effective management. They made simple mistakes over the years, especially overseas. e.g. opening stores on the west coast of America, where it's hot and no one wants to buy hoodies and jackets; similar story in Italy, where the heavyweight t-shirts didn't suit that climate; opening stores in China and not understanding the market...everyone sees the potential in China, but does anyone go there and make money? [serious question...please leave an answer in the comments]
I hope they turn this around.
Hi Paul, Would appreciate you having a quick look at LON:FIF Finsbury Food if you have time. At first glance they look pretty solid and the balance sheet seems to have strengthened.
If you missed the Checkit (LON:CKT) webinar last week there is a write up on the stockopedia discussion page and a recording can be viewed here
Big market falls this morning and A J Bell site crashed. Are we seeing another big Covid fall? Any thoughts/experiences?
What seems a bit different this time is in March everything was pretty much falling due to uncertainty. It seems this time its a more selective fall as its clearer now which companies will suffer most and which might actually benefit. Added to that the bubble better known as tech looks like its popping and banks seem to be in trouble again with legislators.
Really? 4 FTSE 100 risers and 10 FTSE 250 is selective?
The government has lost control of the situation and we are now having to predict the next set of largely unnecessary restrictions which could be catastrophic for small and large companies.
I was listening to Grant Shapps - how did he end up in charge of anything? - and he just did not understand the significance of false positives. Just a 1% false positive rate would mean that the entire increase in 'cases' could be invalid. This has been written up by many scientists but is being ignored by the government.
Really good article in money week on the subject of false positives. 1982 Research by Paul Eddy on Breast cancer posed the following question to doctors. Women aged 40 participate in routine screening for breast cancer, with a prevalence of 1%. The MM test has a false negative of 20% and a false positive of 10% what is the probability of a woman with a positive test having breast cancer? 95/100 Doctors gave an answer of between 70-80%. (and what was the negative impact of the FPs?!!!!) The correct answer is just 7.5%.!!! This is the challenge we have with the current covid results.
Thank you Berksbee for bringing that article to my attention. I think it is the most important thing I have learnt about the virus since it all started.
I have been arguing with my doctor over whether or not I should get a PSA test. He says, too high a FPR, but I wanted one anyway. I'm beginning to think he may be right after all!
Additionally you have to look at the changes, most of the companies getting hit the hardest are airlines, restaurants, bars and then in the middle you have the insurance companies and then some companies who benefit or are largely un-impacted aren't moving much. I have 6 risers today all of which might benefit from further lockdowns.
Which companies? The ones I have going up are Japanese investment trusts. Of the 14 FTSE 350 you have six? Well done.
The PCR test was never designed to test for this.
David Crowe- Canadian researcher, with a degree in biology and mathematics, host of The Infectious Myth podcast, and President of the think-tank Rethinking AIDS. He broke down the problems with the PCR based Corona test in great detail, revealing a world of unimaginable complexity, as well as trickery.
"The first thing to know is that the test is not binary," he said. "In fact, I don't think there are any tests for infectious disease that are positive or negative."
The next part of his explanation is lengthy and detailed, but let's push through:
"What they do is they take some kind of a continuum and they arbitrarily say this point is the difference between positive and negative."
"Wow," I said. "That's so important. I think people envision it as one of two things: Positive or negative, like a pregnancy test. You "have it" or you don't."
"PCR is really a manufacturing technique," Crowe explained. "You start with one molecule. You start with a small amount of DNA and on each cycle the amount doubles, which doesn't sound like that much, but if you, if you double 30 times, you get approximately a billion times more material than you started with. So as a manufacturing technique, it's great. What they do is they attach a fluorescent molecule to the RNA as they produce it. You shine a light at one wavelength, and you get a response, you get light sent back at a different wavelength. So, they measure the amount of light that comes back and that's their surrogate for how much DNA there is. I'm using the word DNA. There's a step in RT- PCR test which is where you convert the RNA to DNA. So, the PCR test is actually not using the viral RNA. It's using DNA, but it's like the complimentary RNA. So logically it's the same thing, but it can be confusing. Like why am I suddenly talking about DNA? Basically, there's a certain number of cycles."
This is where it gets wild.
"In one paper," Crowe says, "I found 37 cycles. If you didn't get enough fluorescence by 37 cycles, you are considered negative. In another, paper, the cutoff was 36. Thirty-seven to 40 were considered "indeterminate." And if you got in that range, then you did more testing. I've only seen two papers that described what the limit was. So, it's quite possible that different hospitals, different States, Canada versus the US, Italy versus France are all using different cutoff sensitivity standards of the Covid test. So, if you cut off at 20, everybody would be negative. If you cut off a 50, you might have everybody positive."
Pretty much everyting is down in my pf and it looks pretty indescriminent. Everything from a gold miner (Anglo Asian Mining (LON:AAZ)) to online retailer (Boohoo (LON:BOO)) or to Games Workshop (LON:GAW) to Avacta (LON:AVCT) . Only things marginally up are Best Of The Best (LON:BOTB) and Novacyt Sa (LON:NCYT) .
Sometimes wonder if the people (or is it mainly computers nowadays) selling or buying stocks even know what the underlying company even does.
Sigh........................
Its the usual indiscriminate panic selling. Even companies that have very recently announced ahead of expectations updates are being battered, such as Chemring (LON:CHG) and Spectra Systems (LON:SPSY)
Part of me looks at the crash and thinks it's a great buying opportunity. The other part looks at the portfolio and hopes the pain stops...
Over time, we'll be fine. No need to panic :)
AJ Bell site still not functioning properly, very slow to login and to get quotes.
Interactive Investors instead is as fast as ever.
These guys are starting to get on my T*ts - and Ive told them so - they have so much down time or you cannot get an online quote.My ISA and SIPP with this lot.Can anyone recc. a good reliable platform ?
Well, reliable is Charles Stanley Telephone Execution, which I still think is available to new customers (I have been with them for decades now). Yes, you pay a little more, but there's always someone there if you want a dealer, or you email, and they advise on spreads on offer, do multiple day triggers etc.
Cheers JTG
gush
Yes indeed. Ftse100 below 5800 as I write. I notice the banks falling sharply. £Barc below 90p etc; partly on suggestions of a number of the European banks under investigation on "money laundering" issues. It looks to me that there are plenty of nervy sellers around today; especially in the usual hospitality areas. Plus housing...Taylor Wimpey (LON:TW.) hit a 52 week low today below 100p. They placed at 145p in June so the discount is getting bigger and bigger. There is a leasehold investigation here but firmly on my watchlist.
A Covid vaccine ; there is a real expectation that one will be ready in early 2021. That would see the markets soar I think but no guarantees ....so I am a selective buyer of stocks that are fully funded with strong balance sheets and a solid business.
I think it's the markets catching up with economic reality. Regardless of the reason though, I've taken some money off the table and am waiting to jump back in.
Hi Paul what do you think of Supply@me Capital (LON:SYME) is it true good to be true, up today 35/45%
I like this share for a spreadbet as it's like a binary option, if it goes to zero only a small loss due to <1p sp. If it starts to make headway, good R/R to the upside.
Hi Forbsy
Are you trading Binary Opinions? All that I read about them, seem to indicate that you should stay well away from them. Am I missing something here? Maybe there is a positive side to them. Look forward to your reply.
I could be wrong but think Forbsy is speaking in terms of it is an 'all or nothing' type play (binary being 1 or 0) and that as the SP is so low it was unequal weighting of positive potential vs negative and this is done as a spreadbet.
Whereas i do not think he/she is referring to 'Binary Options' in terms of the Fixed Return Option.
OK, thanks for that. I have just reread it and now understand with your explanation - Thank again
Does anyone have any information about NETW (Network Intl Hldgs) which are in freefall today and have crashed over 50% in a week?
Its on my watchlist but never bought in as I thought it was overpriced. Without being an expert on it I assume the over market sentiment, the general push to down price tech and some of the more major holders have decided to dump. I am not wanting to put any more money to work at the moment (I am about 20% cash after selling out of AMZN at 2520) but will continue to watch this and others from the sidelines
This has been on my watchlist as well its a very strange drop without any news and company said trading is good. Looks like everyone is scratching their head on the drop, 50% in two days seems big much if just overall market sentiment. The only reason I didn't take a position as covid still seems a major issue across the Middle-East.
Something seems off here watching from sidelines.
agreed. Its suspicious but likely just herd mentality
They have just released an RNS saying they don't know why there's a drop and business is improving. I have opened up a small stake.
Robbie Burns announced he sold his holding on Thursday afternoon (the day before the drop) but I struggle to see how that could have influenced such a huge drop. I held this in the early days of its listing so have kept a close eye on this share.
Bearing in mind it raised £205m @ 410p about six weeks ago, I think this is a big buying opportunity and I'm going to dip my toe back in.
Which share are you talking about?
Network International Holdings (LON:NETW)
Cause seems to be increasing short interest in £NETW. Not sure why short interest is increasing but might be some bad news or shorting report going to emerge?
Short positions are tiny and have barely changed in months.
It's been said before but I'll add it again...
Please put the £ sign in front of the ticker :)
Network International Holdings (LON:NETW)
Eps * PE would suggest that before the recent falls this share was over priced.
Good Morning Paul,
Would love your thoughts on the contract win for Billington Holdings (LON:BILN), long a share that pops up on my custom screens but was just not enough information (certainly since COVID) to jump in.
Still seems on the cheap side to me if they can sustain their growth but capacity issues concern me.
On Go-ahead (LON:GOG), note media reports: Rail franchising ‘ended’ as government extends emergency support
I came across this on my twitter feed (others might have done as well of course) as I follow both MC2 and Alta Fox Capital and thought that as it focuses on micro/nano caps it would of interest here.
Multibagger Interview with Alta Fox Capital on Microcap Club (MC2).
https://www.youtube.com/watch?v=D7mSv0G2ZzA&
It is well worth a watch.
The report discussed can be downloaded at:
https://static1.squarespace.com/static/5aaacb57506fbe4636414126/t/5f5ba8c6bba8c27b79d66af7/1599842551653/Conclusion+Deck-+Makings+of+a+MultiBagger_compressed+%281%29.pdf
I am yet to study it in full but It looks to be a great (well more than great!?) piece of research.
On the U.K. side 15.4% (16 in total) of the stocks were U.K. listed.
I was pleased to see that I owned four of those stocks
Games Workshop (LON:GAW) - 8th since Jan 2018
Boohoo (LON:BOO) - 14th since Nov 2015
Fevertree Drinks (LON:FEVR) - 44th bought Oct 2015 sold Jan 2020
Bioventix (LON:BVXP) - 52nd bought Oct 2015
(NB the first two I sold in my March meltdown but have since repurchased at slightly higher prices but not much in the case of Boohoo).
There are other SCVR favourites such as Keywords Studios (LON:KWS) Future (LON:FUTR) and Ab Dynamics (LON:ABDP) to name three.
It is thought provoking because the companies are drawn from 15 different markets and of course some of them may be still be good investments and the document might prompt thoughts about how to find the next £ZYXI, which is up 9,119% in the period covered by the paper.
@AltaFoxCapital and @MicroCapClub are well worth following in twitter, if you don’t already.
Hope people find it of interest.
Regards
Michael
Today Augean (LON:AUG) finally deigns to inform the market of the impact of Corona virus on the business.
How can sitting market sensitive information like this be compliant with stock exchange rules?
Are we really to believe that harwood capital will eagerly be devouring this report so it can finally update it's valuation models to reflect 'the new normal'?
This situation is totally unacceptable.
?? really not sure I follow your ire. I am also a holder and pretty happy with the update. They say they will be broadly in line with full year expectations unless there are any more unexpected lockdowns. That's not really sitting on sensitive information is it?
I didn't expect Q2 to be great but they are clearly comfortable that outside of the lockdown they are performing ahead of expectations, thus the in-line.
Agree. I'm conscious that companies reporting June H1 results in late September, the old finance/ accounting heuristic: bad numbers take longer to add up.
Regarding Augean (LON:AUG) I agree - to have no trading update between the prelims on Feb. 26th and today is very poor. Looking at the investor section of their website the amount of information is poor - I cannot find the full annual report.
On the other hand the current -12% looks harsh given the full year "broadly" in line and the substantial reduction in net debt - Paul, your views on the balance sheet would be appreciated.
I bought this and a couple of others in a sort of mini NAPS portfolio following Ed's webinar on the Challenge entries - it was one of the top ten by number of Stocko subscribers and had a SR of 88 at the time. I have just run a rough YTD comparison of those top ten so here they are by share price % change:
Sylvania Platinum (LON:SLP) 69.2
Games Workshop (LON:GAW) 63.9
Volex (LON:VLX) 13.5
RockRose Energy (LON:RRE) -0.0
Somero Enterprises Inc (LON:SOM) -5.2
SDI (LON:SDI) -20.5
Augean (LON:AUG) -23.4
Sosandar (LON:SOS) -44.4
Redrow (LON:RDW) -49.4
Reach (LON:RCH) -52.9
Average -5% cf ASX -23%
"Broadly inline" = profit warning. https://brucepackard.com/signa...
disappointing trading statements often use the phrase “broadly inline” which translates into simple English as “profit warning”. The logic goes that if trading was inline, or better than expected, companies would spell this out clearly. When trading is disappointing, they don’t want to use the word “disappointing” so they just say “broadly inline”. Which in effect means “disappointing”. Market makers and professional investors almost always notice, and the share price falls anyway. Management are not fooling anyone; or perhaps only themselves
Management don't appear to be trying to fool anyone. If you read the statement you will see they've been pretty clear.
Q1 made 2/3rds profit of H1 and Q2 was poor due to lockdowns.Despite this annual result should be broadly in-line with expectations (so within a few %). That means H2 is back to growth. Caveat no more stringent lock downs.
Even if you take the view that profit comes in at -9% for the year it is an EPS of 16p and net debt eliminated.
In my view people are inanely focusing on a single quarter that was impacted by specific lockdowns and ignoring the forward looking view which is far more important.
Re. "Broadly inline" = profit warning.
"Management are not fooling anyone; or perhaps only themselves."
What about The Remuneration Committee?
Annual and interim reports are here https://www.augeanplc.com/financial-reports/
MrSmallCaps - thanks for the link to the Augean (LON:AUG) annual report. It does prove my point - I was looking for it in the Investors section of the website. Silly me! I should have known that it was in the 'Information Centre' subsection of the 'Duty of Care' section!
There are a number of other things required by AIM rule 26 such as details of board members and committees or list of key advisors that I cannot find.
Paul, Can you cover Record (LON:REC) today?
My morning smallcap tweet:
Go-Ahead (LON:GOG) Finncap (LON:FCAP) Urban Logistics Reit (LON:SHED) Kin and Carta (LON:KCT) Nakama (LON:NAK) STM (LON:STM) Billington Holdings (LON:BILN) Record (LON:REC) John Lewis of Hungerford (LON:JLH) Deltex Medical (LON:DEMG) Verona Pharma (LON:VRP) Universe (LON:UNG)
Go-Ahead Group (GOG) GTR franchise Emergency Measures Agreement extended for a year. Margin up to 1.5%. [SP=651.5 Cap=281m]
finnCap (FCAP) guides H1 rev up 37% with a 'significant uplift in profitability'. "Although trading for the last few months has been exceptionally strong, we remain mindful of the overall social and economic backdrop to the current operating environment. However, our pipeline for Q3 2021 is good..." [SP=22 Cap=38m]
Urban Logistics REIT (SHED) £100m placing and OO at 139p, a 5% discount. [SP=146.05 Cap=277m]
Kin and Carta (KCT) guides FY rev and profit slightly ahead of July expectations. [SP=62.4 Cap=105m]
Nakama (NAK) guides FY(Mar) rev down 28%. This FY: "UK businesses of Highams and Nakama have seen business volumes reduce due to the initial, albeit revised, changes to IR35 and then the onset of COVID...Hong Kong and Singapore has been broadly similar to the UK due to COVID...As the various government support schemes are ended the Group will face a number of trading and cashflow challenges and without access to additional capital the Group's working capital situation may deteriorate." [SP=0.57 Cap=1m]
STM (STM) as expected, Carey case (which STM won) goes to appeal. [SP=38.3 Cap=23m]
Billington (BILN) wins 3 contracts worth £21m for delivery in Q4 2020 and throughout 2021. [SP=310 Cap=40m]
Record (REC) has, subject to contract, been selected for a dynamic hedging mandate of approximately $8bn. "Assuming contract negotiations conclude successfully, this mandate will build up over time and will be revenue-generating by the end of this calendar year." [SP=32 Cap=64m]
John Lewis Of Hungerford (JLH) guides FY(June) rev down 34%, pretax -£850-£900k (-£229k). Recent 3 months dispatched sales and forward order book up 23%. [SP=0.48 Cap=1m]
Deltex Medical (DEMG) H1(June) rev down 40% as guided, pretax -£578k (-£307k). "We are confident that as the number of elective surgical procedures starts to climb, in part due to increasing pressure to reduce waiting lists, so the financial performance of the Group will improve." [SP=1.5 Cap=8m]
Verona Pharma (VRP) proposed AIM delisting to leave only US trading because "only a small proportion of trading in the Company's shares is conducted on AIM". [SP=70.5 Cap=286m]
Universe Group (UNG) to leave 'to pursue a new career opportunity' after replacement found. He is thanked. [SP=5.5 Cap=14m]
Looks like my old code hasn’t aged well - painfully slow to download and picked up a lot of crap along the way. Regret publishing it, so will work on it more before it sees light of day again. :) Cheers
It's a brave effort, so much gen to mount and for me to read.
Thanks HollandSmith, welcome back!
Is it possible to rerun the code say at 9am, and add a column with the % movement in price of that stock? and then re-publishing it?
Thank you for the idea, always like fresh ones!
It’s not a bad idea, but the limitations of uploading to this forum means I only have time period in which to edit the post until it’s locked and unable to modify. 9am would mean reposting twice, but that option doesn't tick any boxes. I believe a way around this would be to post my own discussion blog where there’s no time limit, but then price % movement would be out of date within moments of re-publishing.
It doesn’t fit the full request but I could include a plain tickers list, which your able to copy and batch upload to a portfolio to then monitor live prices?
Step 1: Copy and Paste this list,
INF, MNTN, FGP, CRW, IGR, KGH, RAV, GOG, MXCT, CMCL, AUG, SYME, YGEN, KCT, SDRY, CRS, REC, FIF, DNE, RLE, TOWN, BILN, FCAP, DRV, GRC, TERN, UKOG, LND, LND, SECG, OVB, PEN, LFI, LFI, ING, POW, DEMG, THAL, PET, KAV, NTOG, JLH, NAK
Step 2: into, the “Add multiple stocks at once…” box and price the add stocks button
Step 3: Monitor prices and enjoy.
Thanks!!
I found investigate was very slow this morning so maybe not all the problems are with your code?
Really useful snippets HollandSmith - please keep it coming.
I think you are using the old site which allows the "add multiple stocks" (the new site doesn't) - either way the process needs the exchange info in front of the ticker (e.g. LSE, NYSE) otherwise weird and wonderful international stocks are picked up.
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
2021 Cashflow Positive: Strength of B2B brands and focus on cash management reflected in customer commitment to forward bookings, with refunds less than 15% of Events gross cash collections.
Elsewhere, this is reflected in the continuing commitment to forward bookings and cash deposits as events are rescheduled to 2021, with refund requests currently running at less than 15% of Events gross cash collections..
The disruption to our physical events portfolio led to a decrease in statutory revenue of 42.1% to £814.4m.
Statutory net finance costs fell 2% to £57.3m, comprising of £62.1m of finance costs and £4.8m of investment income.
In H1 2020, the effective tax rate (as defined in the glossary) was 13.0% (H1 2019: 19.0%).
Adjusted diluted earnings per share (EPS) decreased by 78.4% to 5.0p (H1 2019: 23.1p).
This reflects a 77.1% decrease in adjusted earnings to £66.9m (H1 2019: £291.8m), combined with a 6.2% increase in the weighted average number of shares. In H1 2020, approximately
The six months to 31 July 2020, the Company's NAV increased by 4.3%.. As of the end of July, 62% of the capital raised in Schiehallion had been invested in high growth private companies. Under the terms of the Investment Management Agreement, the Investment Manager will be entitled to an annual fee (exclusive of VAT, which shall be added where applicable) of: 0.9% on the net asset value excluding cash or cash equivalent assets up to and including US$650 million; 0.8% on the net asset value excluding cash or cash equivalent assets exceeding US$650 million up to and including US$1.3 billion; and 0.7% on the net asset value excluding cash or cash equivalent assets exceeding US$1.3 billion. By way of an ordinary resolution passed on 19 May 2020 the Directors of the Company have general authority to m
The overall fee potential is a maximum of 1.5% of the cost base of each franchise prior to the pandemic. We are now operating around 90% of the rail services we were prior to the pandemic. Notes Passenger volumes on our First Rail operations have increased modestly from the lows of c.95% below pre-pandemic levels on average in late March and April, but still remain c.70% below across our operations.
Basic EPS increased 12% to $0.628 (FY19: $0.561) and diluted EPS increased 13% to $0.619 (FY19: $0.550).
Total Sales to 31 March 2020 tracking 30% ahead of same period in FY19, impacted in the final quarter by COVID-19. Sales of Trisus Enterprise Value Platform products represented 14% of New Sales in the year (FY19: 13%). Healthy sales mix, with 90% of sales being to existing customers or new hospitals within existing healthcare system customers, demonstrating the successful execution of our land and expand strategy.
In the first nine months of the year to 31 March 2020, Total Sales were tracking over 30% higher than in the prior year, demonstrating a considerably improved performance and strong sales of both our existing and newly developed cloud-based Trisus applications. Although it is clear COVID-19 held back the Group's financial growth in the final quarter of the year, there are ma
Following the strong start to the new financial year, which was announced on 28th July 2020, the Group has maintained good trading momentum with revenue and adjusted profit before tax on track to meet full year market expectations.. The business has begun delivering, on schedule, its pipeline of over $500 million orders and is building upon this with additional orders as expected.. The Directors remain optimistic about the Company's outlook, with revenue expected to increase year on year, including the impact of the CSS acquisition.
As previously reported, the Group experienced a circa 20% decline in new business in the early weeks of the current financial year.
The Group is currently operating at a run rate equivalent to a circa 10% decline in new business compared to pre-COVID 19 levels and the Board expects this ongoing improvement to continue over the remainder of the year..
Strong revenue growth of 30%, generating positive EBITDA (before CARMA investment). · Revenue grew substantially in the first half of 2020, increasing 30.1% to $10.9m compared to $8.4m in H1 2019, an acceleration of the year-on-year growth rate seen in H1 2019. · Increase in clinical milestone revenues drove significant (2.4%) improvement in gross margin to 89.7%. Financial performance in the first half of the year remained strong, with first-half revenues increasing significantly, approximately 30% year-on-year, to $10.9m (2019: $8.4m). Operating expenses fell by 4.2% during the period as a result of the COVID-19 pandemic restricting life sciences spending to $15.6m compared to $16.4m in 2019. During the six months ended 30 June 2020, two customers represented 28% of revenue, in part due to certain one-time milestone events. During the six months ended 30 June 2019, no single customer represented more than 10% of net revenues. No customer represented over 10% of net accounts receiva
Adjusted revenue1 before landfill tax decreased by 6% to £41.4m (2019: £44.2m).
· Adjusted profit1 before taxation decreased 11% to £8.5m (2019: £9.6m).
· Adjusted basic earnings per share decreased by 12% to 6.70 pence (2019: 7.61p). · Return on capital of 42.0% compared with 37.8% at December 20193.
· Sales growth of 14% in North Sea due to successful completion of Curlew decommissioning contract.
· Treatment & Disposal sales reduced by 16% due to the impact of Covid-19.
The distribution agreement initially includes the Elucigene® DPYD assay, which tests whether cancer patients can be at risk of significant and potentially lethal side effects caused by the 5FU chemotherapy treatment. In the US, there are approximately 500,0001 5FU chemotherapy treatments carried out per annum. Following the launch of the CE marked Elucigene DPYD in Europe, Yourgene now has over 20 hospitals and cancer centre customers routinely using the DPYD assay. As announced on 14 February 2020, the Company also has approval from the Therapeutic Goods Administ
Total revenue down 19.2% to £704.4m, reflecting a planned move away from persistent discounting and latterly the impact of Covid-19 on Q4, with our entire store estate closed from 22 March until year end.
announces today that it has, subject to contract, been selected for a dynamic hedging mandate of approximately $8 billion in size (with AuME quoted by convention in US Dollars).
The total return in the half year to 30 June 2020 was -13.4% and -29.4% in terms of net asset value per share and share price respectively. The share price of 263p at 30 June 2020 represented a discount of 30.6% to the net asset value of 378.9p per share.
· Revenue up by 1.2% to £8.2 million (H1 2019: £8.1 million). · 2.4% increase in underlying profits before tax* £4.1 million (H1 2019: £4.0 million). · Pre-tax loss of £3.8 million (H1 2019: £1.7 million profit) allowing for a 3% reduction in property values and interest hedging costs (both non-cash items). · Occupancy 93.45% (FY 2019: 96.3%) due to known lease event expiries. ·
announces that it has sold four retail properties in Scotland and London for a total sum of £35.2m.. The units sold comprise of two Waitrose stores in Milngavie and Glasgow; an Aldi/Home Bargains store in Milngavie; and a high street retail store in Chiswick, London. ·
announce that its structural steel division, Billington Structures, has recently been awarded three contracts with a combined value of £21 million. One of these three contracts have been secured with a global multi-national corporation for a value of £12 million.. The three contracts are respectively within the power, manufacturing and commercial office sectors and are currently scheduled to be delivered in Q4 2020 and throughout 2021.
With our preliminary results in July, we reported record Q1 results, a strong pipeline for Q2 and a substantial increase in the group's cash resources. Q2's pipeline has been executed with a significant contribution from the equity capital markets team, where significant corporate fundraising continued.. As a result, we expect to report Group revenue for the six months ending 30 September 2020 of not less than £19.5m, up c.37 per cent. Given the level of operational gearing in the business there will be a significant uplift in profitability on the prior period. Costs have remained under control and our cash position has further improved. At the close of business on 18 September 2020, net cash was £12.4m(1).. Although trading for the last few months has been exceptionally strong, we remain mindful of the overall social
announces that it has concluded a strategic partnership with Africa's leading claims and dispute resolution consultancy,
• Revenues and billings 1 down 11% to £14.1 million (FY19: £15.8 million) and £14.0 million (FY19: £15.8 million) despite H2 including seeing the early impact COVID-19 pandemic..
• Strong growth in consultancy revenues of 19% to £8.6 million (FY19: £7.2 million). • Increase in gross profit margin to 57% (FY19: 54%), despite a 6% decrease in gross profit to £8.1 million (FY19: £8.6 million).
• High quality recurring revenue services now account for 29% of monthly billings 1 (FY19: 10%).
entered into an agreement with Stares Contracting Corp, Stephen Stares, Michael Stares and James Dawson (together, the "Vendors") through which Landore Canada purchased the remaining 20% stake in the Lamaune Lake Property from the Vendors.
announce the acquisition of a 50% interest in a 2,680 km2 portfolio of base and strategic metal project interests in Botswana (the "Acquisition") to be held in a new strategic joint venture holding company further details of which are provided below..
33% reduction in like-for-like revenues: £1.2 million (2019: £1.8 million).
25% reduction in overhead costs to £1.3 million (2019: £1.7 million).
In 2019 we negotiated the termination of a third-party distribution agreement, which included revenues of £0.2 million in the first half of 2019, accordingly the like-for-like H1 2019 revenues were £1.8 million, meaning that the H1 2020 revenues of £1.2 million declined by 33% on a like-for-like basis.
announce it has signed non-binding Heads of Agreement with Leadway Group Ltd to acquire a 70% legal and beneficial interest in a greenfield mining project in Uganda.
great that you are back. Missed your posts!
Thank you Michael, but looks like its a one day special sadly unless i get my finger out and fix the problems.
Can i ask, does anyone use any more RNS websites other than?
https://www.londonstockexchange.com/news?tab=news-explorer
https://www.investegate.co.uk/
https://www.lse.co.uk/rns/
Cheers
https://www.voxmarkets.co.uk/r...
Seems all right to me! What am I missing!!
I get alert from research tree but now I tend to use the news on Stockopedia front page and just wish that they would prioritise improving the news service :-)
HI Michael
Please can you copy and paste this comment into the Green Face button at the bottom left, the more feedback direct to the team the better chance we will get this within the next wave, or two of updates.
Thanks
Tommy
I have already contacted them about this:
- I would like to see a separate link on the left (on dekstop) to news
- News item on left panel news "article" on right so one can scroll through
- Tabs for portfolio news and all news and then custom filters for news on stocks below # mkt cap excluding y sector(s) (say resources).
If I had the money drive etc I would start my on RNS site because none of the sites that I can find Vox Research Tree Sharepad, LSE Investegate etc are IMO useless and trawling through RNS's from companies in which I don't have the slightess interest makes it a real chore!!.
Regards
Michael
It may not fit your criteria but the front page of ADVFN with the free subscription lets you see RNS'. Also I think the Shares magazine website does too but you might need a login for that.
Personally I use the portfolio/watchlist tools in ADVFN and on here to track RNS' for the stocks I watch.
Thx yes I get that from here and Sharepad but I wish there was a site that allowed you to filter RNS's by, as a minimum:
- Mkt Cap
- Sector (i.e. exclude sectors)
- Subject
I havent come across one but maybe there isnt the demand?
Regards
Michael
Re RNS/news
Yes, I agree, surely it can't be too difficult for the developers to add a screening rule option for "last RNS = within 'x' days" (where 'x' is the number of days you want to include)
Research tree Ipad app has a filter setting. Can filter market cap/sector.
I would certainly value such a facility, which is why I have written one myself! It's certainly not that hard so to include such in one of the existing commercial packages would not seem to me to be a major task.
I had considered possibly commercialising my tool , but from something MrContrarian said recently, it sounds as though the LSE would demand a hefty pound of flesh for using "their data".
I haven't looked into whether that would make in unviable, but providers that are already providing RNSes are already paying, so no extra cost?
Hi Gromley,
Thats something I don’t fully understand.
Do the LSE own the documents published by each company on the LSE? As far as I know, most companies publish their documents on their own websites, so are they still property of the LSE?
If not, could gathering these releases from all their own sites get around this?
Cheers
"I would certainly value such a facility, which is why I have written one myself"
That is very clever and beyond me, I wouldn't even know where to start.
But exactly if there are paying for the data a few simple filters would be child's play.
Research Tree has a filters but:
I can't exclude filters
Mkt Capare in bands so I cannot filter for all companies below x Mkt Cap
Will write to research tree and see if they are open to improving their filters.
Regards
Michael
Michael,
Out of courtesy to the Stockopedia management I wouldn’t normally sing the praises of another data supplier, but you’re doing SharePad a massive disservice by claiming that it can’t handle news filtering by sector, market cap or subject (it can filter for a great deal more, but those were the criteria you gave).
SharePad’s newsfeed is first class in my opinion – split pane view, instantaneous response from the server over a fast broadband connection, customisable coloured subject highlighting, inclusion/exclusion text and news code filtering, plus filtering by numerous metrics in a similar manner to Stocko’s screening tools.
Invaluable as they may be to Stockopedia subscribers, the daily SCVR posts from MrContrarian and HollandSmith don’t impart anything that I’ve not already quickly and efficiently absorbed from SharePad’s newsfeed first thing in the morning. I’d happily pay the subscription for the news service alone.
Thank you Lutheran.
No disservice intend. I will investigate further.
I like Sharepad a lot but nothing on the interface seems intuitive. It is almost as though they like hiding their abilities under a bushel! I just don’t see how you would come across the abilities of Sharepad without taking a degree in it.
Thank you.
Regards
Michael.
“I like Sharepad a lot but nothing on the interface seems intuitive. It is almost as though they like hiding their abilities under a bushel! I just don’t see how you would come across the abilities of Sharepad without taking a degree in it.”
I’m not going to argue with that, Michael. It’s the age-old problem that with power comes complexity (3D modelling software is the quintessential example).
Stockopedia’s visual data presentation is far superior to SharePad’s in my view and it’s the reason I would always recommend this platform over SharePad’s for new private investors seeking a quality share data and screening service (the discussion forum is an extremely valuable bonus).
Nevertheless, as subscriber driven features are added to Stockopedia it will become increasingly difficult for the developers to avoid the inevitable interface layering that will leave new users with a steep learning curve if they want to take full advantage of the site’s data mining power.
All I can say is that I see the two services as complementary, not rivals, and I know that in the absence of either of them my equity returns would suffer.
Agree with all you say including your last paragraph, though the cost has to considered in relation to porfolio size.
Anyway going to dig around the help/support section on news
Regards
Michael
Morning Paul, any thoughts on GOG generally? Announcement this morning confirming the extension of emergency measures for train contracts.
Approximately 90 per cent of total Group revenues are generated through contracts where there is no direct revenue risk from changes in passenger demand so largely unaffected by drop in passages demand due to Covid.
The company will make an operating profit of £60M (minimum) year end to June and has £200m cash in the bank vs a Mcap of 300M! Transport will likely recover in the medium to long term one would hope once a vaccine is found or Covid risk reduces.
Looks like an interesting recovery play.