Small Cap Value Report (Mon 22 June 2020) - MNZS, GDWN, SAGA, SCE, MTC

Good evening/morning, it's Paul here with the preamble for Monday's SCVR.
Estimated timings - it's a quiet news day, so I should be finished by 1pm.
Update at 12:57 - we're mostly done, but I've got 2 more sections to add, so revised finish time now 2pm.
Update at 15:08 - today's report is now finished.
Subscribers seem to like me preparing some general macro thoughts on Sunday evenings, and then feeding it out gradually during the week's SCVRs. I've tried out this idea, and it's worked well for me too, taking off a bit of the pressure on weekday mornings, so let's carry on with that.
PIWorld podcast about corporate bonds
I really enjoy the weekly podcasts or videos from PIWorld. Tamzin has such a natural interviewing style, asking concise, intelligent questions, and letting the interviewee reply without being interrupted.
The most recent interview was fantastic, I enjoyed it immensely. Paul Hawkins gives a masterclass in corporate bonds, and is successful in making potentially dry material very interesting.
I’ve been meaning to branch out into corporate bonds for a while, and this superb podcast explains everything very clearly. Well worth a listen. With stock markets generally so expensive, and lots of downside risk around, it could be a good time to shift some of my portfolio into safe, decent yielding corporate bonds, possibly?
Remember that bondholders rank ahead of equity, so if there is a deep recession, then it's divis that get cut, but bondholders normally get paid interest without fail (unless the company goes bust of course). Hence owning bonds can be a good way to protect capital in a market downturn.
Here’s the link - very highly recommended. Remember I only flag things that I genuinely think are excellent. That link is for the video, but personally I prefer to listen to the audio on podcast on my earphones, so I can go for a brisk walk at the same time.
.
Wirecard
I recall in 2016 seeing a damning shorting dossier on Wirecard, a German finance company. It seemed highly convincing. If I remember correctly, the main accusation was that Wirecard seemed to be facilitating online gambling transactions in countries where such gambling was supposed to be banned. It's a long time ago, so I might have mis-remembered, in which case I'll happily correct this.
The kerfuffle all seemed to die down, and the share price recovered from its spike down. Shorters had no choice but to buy back, tails between legs.
Here we are, 4 years later, and the thing has really blown up, with apparently a huge amount of money having disappeared.
It just goes to show, 2 things;
- Dodgy companies can take years to finally unravel, so for shorters there really needs to be a short-term catalyst. This reminds me of Globo, where I was certain the whole thing was a fraud, explaining precisely why in 29 articles here, but it took several years for the collapse to happen, and me (and other bears) to be proven correct.
- If there’s a bad smell around a company, then there’s usually something wrong. Sooner or later things usually turn sour.
I completely understand why some investors hate these shorting dossiers that are issued from time to time, designed to create maximum mayhem, to enable short sellers to make a profit. But, the track record of many such shorting outfits, can often be pretty good. Also, what is the difference between a shorter publishing his negative research, and brokers publishing almost universally positive research? Which side is being more dishonest? Answers on a postcard please.
If shorters attack a decent company, and cause a short-term spike down in price, then nobody should complain - it’s creating a buying opportunity! As happened with the bungled attacks on Learning Technologies (LON:LTG) and more recently Boohoo (LON:BOO) .
.
The re-opening trade
To a certain extent, I’m getting cold feet about this. As mentioned in last week’s reports, I decided to bank my profits on property REITs Hammerson (LON:HMSO) and Newriver Reit (LON:NRR) . For what it’s worth, I haven’t suddenly gone all bearish on either. I just mulled the situation, and decided it probably isn’t as bullish as I originally thought - so if in doubt, I’d rather sit on the sidelines and give it some further thought. We can always buy back in at any time. Selling half is sometimes a good idea too, if in doubt, I find.
NRR produced an absolutely excellent investor webinar last week, which I covered in detail. I’ve forgiven the subscriber here who fired off an abusive comment to me, without having read my report in full. These things happen, we all have off days, it really doesn’t matter :-) Apologies are always nice, but quite rare. I’ve never understood why people sometimes find it so difficult to say sorry? I find apologies are remarkably effective at resolving my minor misdemeanours from time to time - highly recommended.
Are High Streets coming alive again, now that shops can open again? I’m reading mixed reports. One paper today indicated that footfall was 50% down overall in the UK on prior year. To my mind, that’s not a bad start, considering only some shops have re-opened. None of the cafes/bars/restaurants can open yet (but will do shortly), and that’s a big reason to go into town centres, or rather part of the package for customers. Hence I’m reserving judgement until the week commencing 4 July - that should give us a clearer picture.
What concerns me particularly, is that many smaller shops have not re-opened. Why would they, if they’re getting staff paid on furlough until end October, have a business rates holiday, and landlords can’t currently do anything about unpaid rent? It’s going to cost more to re-open, than to remain closed, at least in the short term.
Restaurants/bars - it seems that the UK Govt could be about to reduce the 2 metre distancing rule/guidelines to 1 metre. There’s been extensive lobbying from the hospitality sector, saying that business would not be viable at the drastically reduced customer numbers needed to keep 2m apart. However, they reckon revenues would be only about 30% down, if this were reduced to 1m - a level where the best operators could perhaps just about breakeven.
I’m not sure this is likely to give the hospitality sector share prices a boost or not, because it’s been widely anticipated already. So likely to be already in the price perhaps? Anyway, time will tell.
.
Re-closures?
I recently listened to a very interesting interview on CNBC with a restaurateur who owned some restaurants in Napa Valley called Gran Electrica.
He explained how his company had re-opened one restaurant for a week, but found it was not viable at 50% reduced revenues. Hence they switched to more of a takeaway model, with some success at plugging the shortfall.
Interestingly he said there was little incentive for staff to come back. They’re paid the same or more to stay at home. Staff asked why they would want to put themselves at risk of catching covid-19 (it’s rising in some US states now), for no extra money? Diners apparently come in wearing masks, but obviously take them off whilst eating.
The company is also experimenting with “private patio parties”.
It seems very clear that restaurants can probably only survive by pivoting to takeaway food, outside dining, and somehow figuring out how to evenly spread business throughout the week, rather than relying on exceptionally busy periods at weekends.
I don’t know what will happen, but the survivors, who innovate, are probably going to end up with a ton more market share. As I’ve seen in previous recessions, it’s often a time of great opportunity, where innovative entrepreneurs start or expand the next wave of successful businesses, and others fall by the wayside.
On the point of re-closures, the market didn’t like Apple indicating that it has decided to close a small number of recently re-opened stores in areas of the USA where covid cases are rising again. I think one was Miami, and a few other places. Florida, Texas, California, and a few other states are reporting quite a big rise in new cases, but not a rise in deaths. Maybe it’d down to more testing, maybe it’s not? Who knows - even the experts seem to disagree.
I feel that few retail/hospitality companies can make a profit with such reduced footfall, so why would then re-open? Some might re-open, then re-close, when they see how heavy the losses are? It’s not clear-cut either way. So all I can say is, I’m watching & listening, and will adjust my view based on the facts. At the moment though, I’m more sceptical than I was.
If we get a breakthrough in treatment, or hopefully a vaccine, then of course everything would be resolved, after a time lag.
.
That's everything from Sunday night. On to Monday's RNS results, trading updates, and fundraisings...
Please see the article header for the 4 shares which have caught my eye with trading updates today.
.
John Menzies (LON:MNZS)
Share price: 158p (up 9% today, at 08:14)
No. shares: 84.3m
Market cap: £133.2m
John Menzies plc, the global aviation services business, today provides an update regarding current trading and its financing position.
Liquidity - says it has enough cash to last into 2021, after cutting costs & getting Govt support. Headroom will peak at £180m towards the end of June, before reducing.
Trading - surprisingly perhaps, it says Q2 to date has been ahead of mgt expectations. However, later in the announcement it says that "very challenging" conditions in Q1 have continued into Q2, with most flights grounded. That sounds contradictory, but seems to be due to cost cutting stripping out more costs than expected. Revenues down 64% below budget.
Bank covenants - "constructive discussions on necessary revisions"
Bad debts - no material bad debts (yet) from airline customers - most of whom are adhering to payment terms.
Outlook - no guidance given, other than to say business is expected to improve from July onwards. Could benefit from market share gains if competitors fail.
Funding position - this sounds encouraging, at least in the short term;
During April and May, the Group has been cash generative as a result of unwinding its working capital and achieving good cash collection from customers, whilst also benefiting from reduced cash costs and the material benefits of government support and payroll schemes. These schemes covering many countries have helped to mitigate a large proportion of our direct payroll costs, the Group's largest cost, accounting for in excess of 60% of our revenue.
That's fine for now, but as business ramps up again, then pressure is going to be felt on working capital again.
Fundraising? I think this is telling us that an equity fundraising is going to be necessary, which is glaringly obvious;
... the Board remains focused on ensuring the Group's financial position continues to be robust in all circumstances and will continue to review all options available as required to achieve this.
My opinion - this looks an awful share to me. It's got a terrible balance sheet (with negative NTAV), is completely dependent on bank debt, and only ekes out a low profit margin in the good times. Serving the aviation industry, it's obviously having a very bad year so far.
In my experience, supportive banks are only supportive because that's in their best interests - i.e. keep the business going with short-term support, in return for an agreement that the company raises equity to plug the gap. Therefore shareholders assume the brace position, because I'd say a big equity fundraising is a virtual certainty. That could mean heavy dilution, which would lead to a high PER (since more shares in issue), and a lower dividend yield.
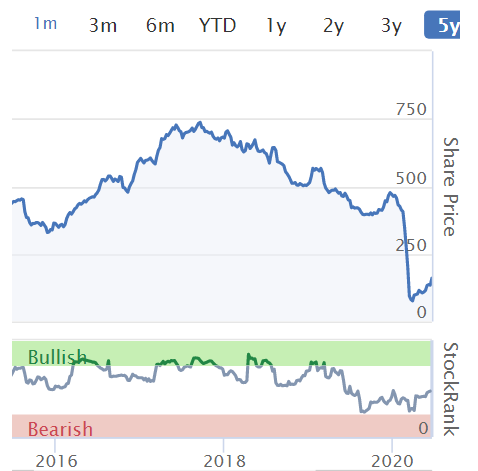
This is a good example of a company which paid out overly generous divis in the good times, leaving it with a weak balance sheet when this downturn hit. The shares get an emphatic thumbs down from me, due to the likelihood of dilution, and no divis for a while. Plus it's really not very profitable even when the aviation sector is busy, so what's the point? Deeply unappealing as a potential investment. Here's the 5-year chart;
.
.
Goodwin (LON:GDWN)
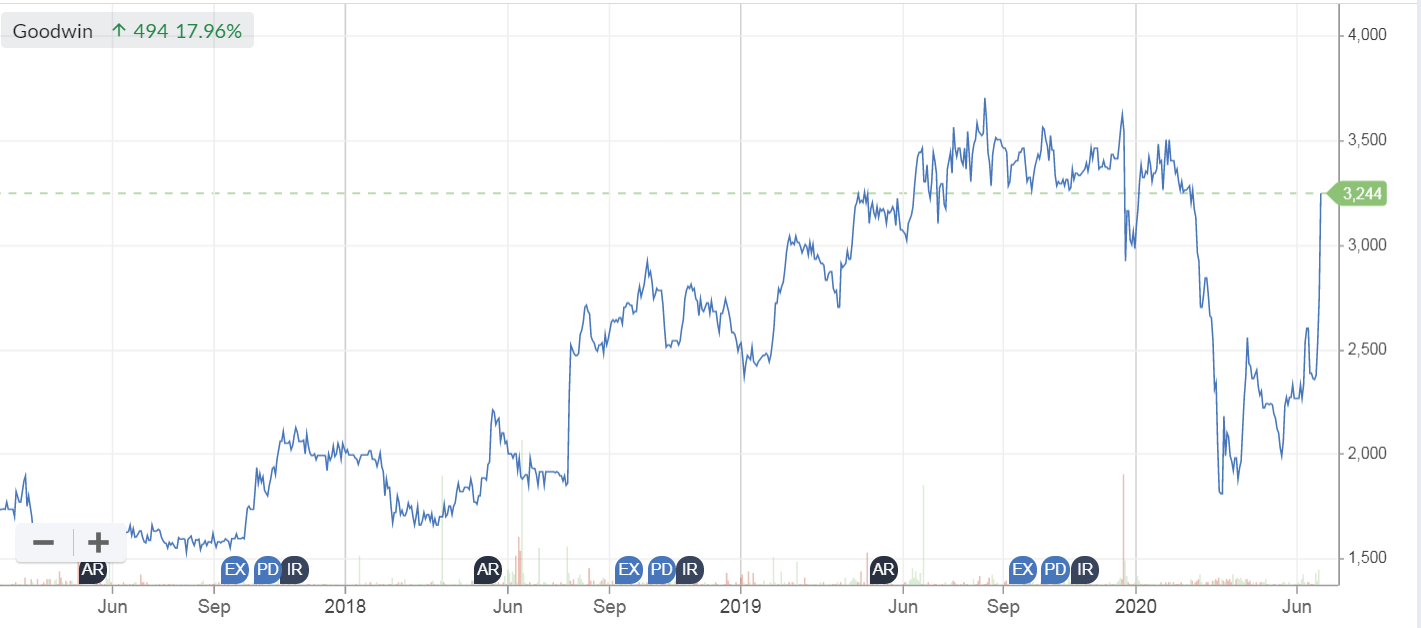
A reader has asked me to look at the "Supply Agreement" (i.e. contract win) announced today, from this engineering company. It's to make metal boxes for nuclear waste.
It sounds very good, and has triggered a 26% share price rise this morning.
Unfortunately, financial details are sparse, and no comment is made on how this affects market expectations (which don't seem to be in issue anyway). I would direct you to broker research, but there doesn't seem to be anything available.
So I cannot take this any further, other than to say it sounds positive, which has been reflected in the share price rise.
.
.
Saga (LON:SAGA)
Share price: 18.8p (up 2% today, at 11:32)
No. shares: 1,122.0m
Market cap: £210.9m
Trading Update (AGM)
Saga plc, the UK's specialist in products and services for people aged 50 and over, announces a trading update for the period from 1 February to 21 June 2020...
I always check our archive here, to see what I've previously written about each company, to quickly refresh my memory. In this case, there's nothing from me in the archive, and just one (year-old) article from Graham. That's probably because Saga has only recently become a small cap (by my definition of sub £400m mkt cap - that's not set in stone, it's just an arbitrary cut-off point I tend to use sometimes).
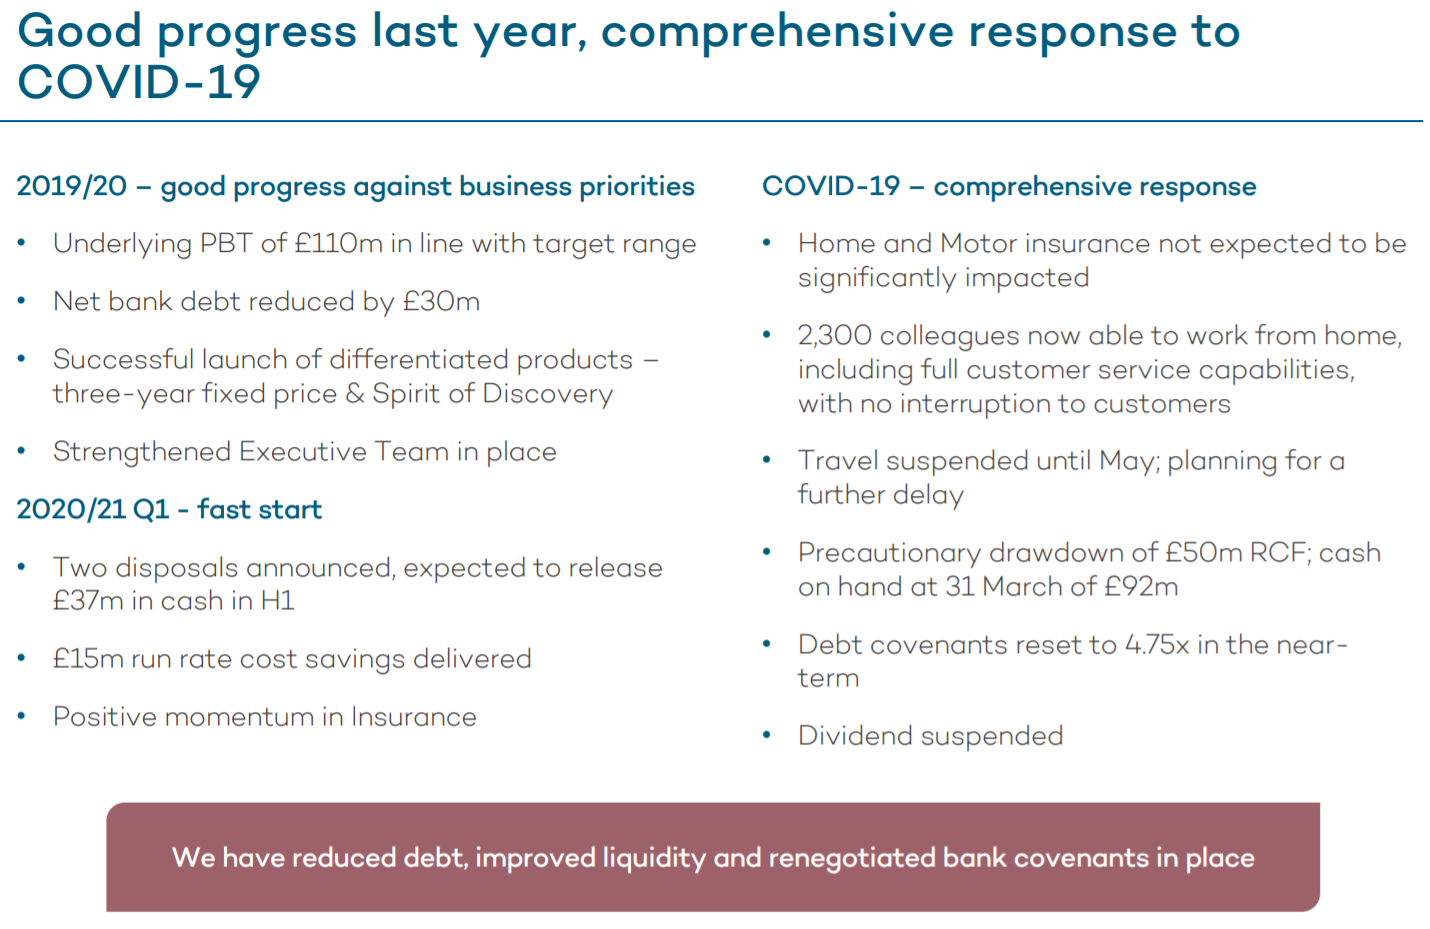
However, I do recall looking into Saga not long ago, to see if it was a recovery play, but didn't get round to writing up my notes unfortunately, sorry about that. It has an unusual 31 January year end. Results for FY 01/2020 are on its website here, including a results presentation, which I'm skimming through now. Slide 3 sets the scene;
.
.
To summarise, this was a highly profitable business pre-covid, but will obviously now be struggling because its travel operations (e.g. cruise ships) are mothballed.
Balance sheet is terrible - NAV is £588.2m, but that turns negative when goodwill is removed, with NTAV of £(247.3m). It's one of these situations where financial engineers came along, decided its income was annuity like, and its negative working capital (feeding off customer deposits) meant that the balance sheet could be geared up. As usual, that's ended up being a disaster. I think the Govt needs to consider making it illegal to excessively gear up balance sheets, since it now turns out there was an implicit taxpayer backstop for many companies which paid out excessive divis & took on too much debt in the good times. One idea I had was to offer differential rates of corporation tax, dependent on financial strength - i.e. lower taxes for the most strongly financed companies. That probably wouldn't work, because people always find a way of gaming the system.
The crux now seems to be whether the company can remain solvent until it's able to resume its cruise ship operations.
Today's update - here are my notes;
insurance business "resilient". Stand-out feature is success of 3-year fixed rate policies.
Covid insurance cover - this is quite surprising. I hope they have re-insured the risks, as this sounds like it could be very costly in the event of a second wave of covid;
The Group continues to innovate its Insurance offering and has announced that treatment abroad for COVID-19 and repatriation to the UK has been included as standard as part of its travel insurance policies for all trips from 1 June. Saga has added the cover to help customers feel more comfortable travelling once the Government advice changes to say that it is safe to do so.
Motor claims "much reduced" as people driving less, due to lockdown.
Travel business still "on pause" since mid-March. Some activities to resume this year. Retentions (presumably this means cash deposits from customers?) "continue to be high". £44m cash returned to customers. Cruise advance receipts higher than expected retained over 70%. New bookings for next year have been very positive.
Disposed of one ship. A new ship is expected to be delivered end Oct.
Healthcare division has been disposed of fully.
Liquidity - "remains strong" it says. Cash is down from £92m at end March, to £30m at end May. That looks rather alarming to me, but is said to be in line with assumptions in stress tests (which scenario though?!). It's mainly due to cash burn in the travel division. A disposal is pending that should raise £23m. Debt holiday & covenant waiver agreed on its two ship borrowing facilities. No divis can be paid to shareholders while this debt is outstanding. There is also an undrawn £50m RCF.
I'm struggling to see how the company can describe this positions as "strong". It looks dicey to me.
Cost-cutting has been done, as you would expect.
Outlook - sounds like there's no immediate crisis, but certainly not a comfortable position;
The Group remains able to resume traveling as soon as restrictions have been removed but has continued to run stress tests based on a wide range of outcomes for the COVID-19 crisis, including a further delay to the resumption of travel until next year. Based on this analysis the Group continues to expect to remain in compliance with key banking covenants at the next two half-yearly testing dates, although further actions may be needed to stay ahead given potential uncertain long-term impacts of COVID-19 on the business and the maturity of bank facilities in May 2022 and May 2023.
My opinion - this is clearly a high risk situation. I'm trying to weigh up whether the upside potential (from a resumption of cruise ships) is enough to risk a possible 100% wipe-out, if things implode. How likely is that to happen?
Overall, I think this is probably too complex for me to want to bet either way on it, My hunch is that the company probably should survive, and will then almost certainly need to do a fresh equity fundraising, thus diluting the upside.
It's either something to have a punt on, as positive news on covid treatment and/or vaccines, would unlock pent-up demand for cruises. The news today on buoyant future bookings shows that customers seem to have an undiminished desire to return to cruise ships.
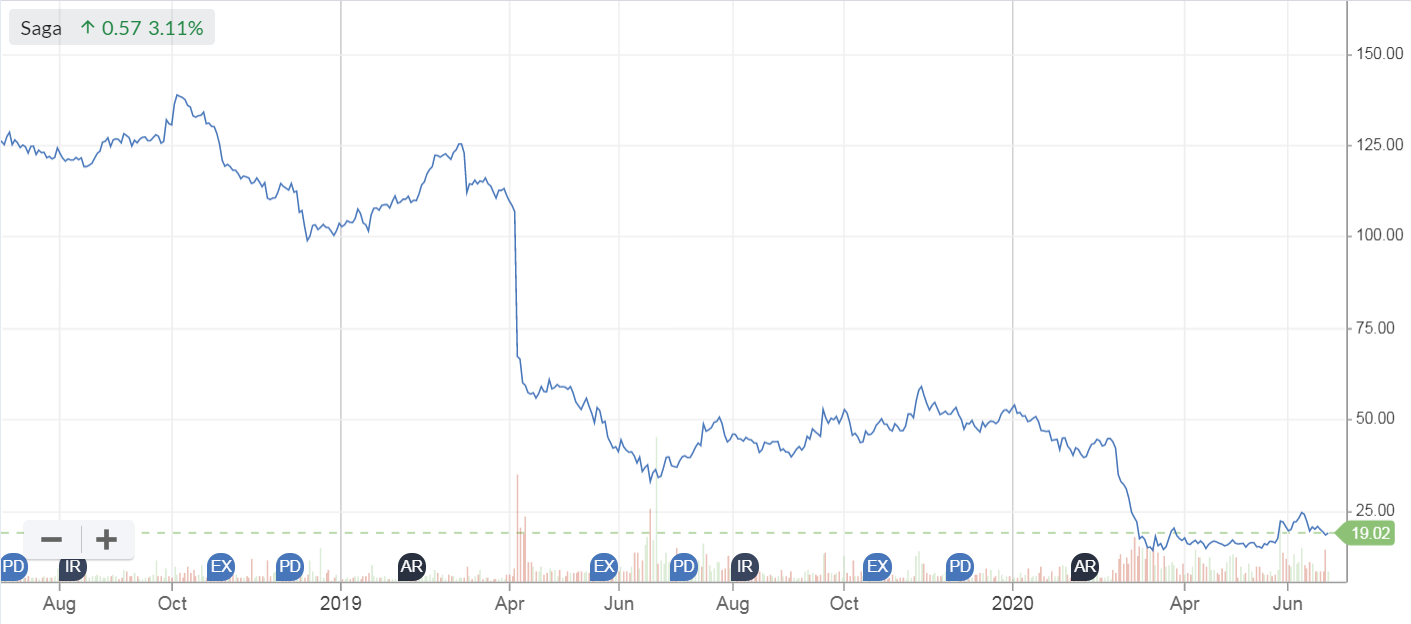
Must admit, I'm tempted to just dip my toe in with a very small punt on this. I wouldn't want to risk any significant money on it though. I'll give it some more thought. What do readers think? It's either a good recovery share, or a dead duck, I'm just not sure which! Note that there has only be a modest share price recovery so far from the March lows.
.
.
Surface Transforms (LON:SCE)
Share price: 20.6p (flat today, at 13:06)
No. shares: 149.2m
Market cap: £30.7m
This company makes special brakes for vehicles, and seems to have been around, and promising jam tomorrow, for most of my career. I wonder how much the costs of listing, and Directors remuneration has cost over the last 18 years?
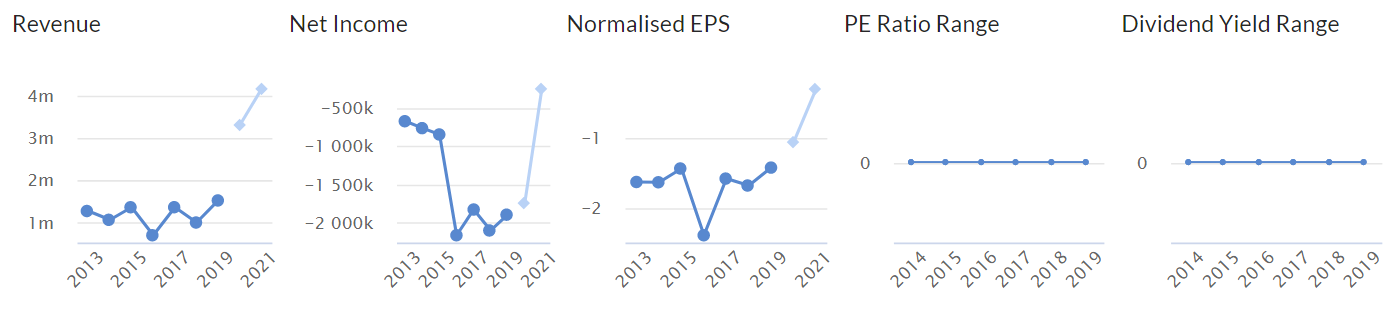
As you can see below, in recent years it has bumped along with £1-2m revenues each year, and losses every year. Forecasts suggest its time might be coming, but they always do. There are no profits or divis, hence the flat lines there.
.
.
Results for FY 12/2019 seem to be more of the same - revenues of £1.45m, and a £1.3m loss after tax (important because that includes the benefit of R&D tax credits).
Is it going to run out of cash? Not imminently, because it boosted cash by £2.25m after fees in a placing/open offer. That adds to the £770k cash as at end Dec 2019.
Operational highlights - this is where it starts to get more interesting. Details are given of some hefty contract wins. These must have been previously announced, as the share price has not moved today. An E11.8m contract with a major German OEM is shown, and a >£5m contract to provide brakes for Koenigsegg - I remember their cars from Top Gear, pretty damn sexy! This new model with SCE brakes looks utterly insane! Here it is. 1,700 bhp - have I read that right?!
It's a hybrid with mainly electric power, but also a 600bhp petrol engine, with 3 cylinders LOL! I'm not making this up.
.
Outlook - it does indeed seem that SCE is finally on track to deliver something like commercial viability;
The Company is still on progress to reach positive Adjusted EBITDA in 2021 and profit before tax in 2022.
My opinion - there's lots of interesting stuff in the commentary today, see the RNS for more details.
I think it looks potentially interesting. The crux here is whether the company can achieve scale, with decent profitability, or not? I would also need to find out what technical advantages the company has, and whether it has patents, etc, on its products, or whether there's a risk of competitors under-cutting them?
Overall, it's possibly worth a closer look maybe?
SCE certainly likes using TLA (three letter abbreviations). There have been delays to SOP (start of production). Anyway I'm off to HSL (have some lunch).
.
Mothercare (LON:MTC)
Share price: 7.38p (down 8% today, at 14:44)
No. shares: 341.7m
Market cap: £25.2m
The UK stores were put into administration last year. It seems to just be the international franchises now.
As set out most recently in our announcement of 30 March 2020, we remain on track to become a profitable international franchise operation, generating revenues through an asset-light model, operating in around 40 international territories.
The big question is whether the international business is viable long-term, or whether it is also doomed to eventual failure? I see that Mothercare's Ireland franchisee recently went bust.
Constructive discussions are ongoing with ourexisting franchise partners (to establish a more sustainable and less capital-intensive business going forward with effect from the A/W20 season) and with Boots (to finalise the contractual arrangements for their appointment as our UK franchise partner as contemplated by the binding heads of terms signed in December 2019).
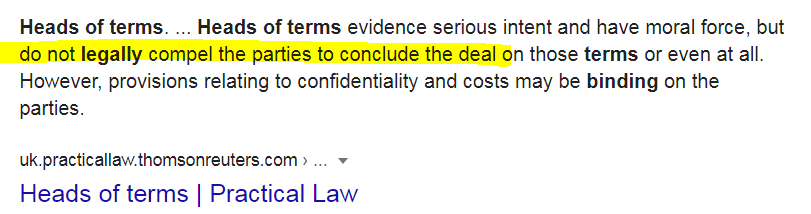
Are heads of terms actually legally binding? This is what google says on this question;
.
I don't know specifically what the Mothercare-Boots deal says.
Debt - it's looking to refinance, but without issuing new equity. Good luck with that.
Relocating head office to smaller premises, to save money.
Interim CEO is moving on. "At shortlist stage" for recruiting new CEO.
My opinion - neutral. The international business was previously highly profitable, so ditching the failed UK business was a sensible move. My worry is that Mothercare's franchisees may not survive. That could lead to a series of bad debts, and reduced scale.
Probably like many other investors, I just see this business as a relic from the past. So the shares don't interest me at any price really.
That's me done for today! See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
Apologies if I've already posted this, or words to this effect before, regarding re-opening (I think I must be suffering from lockdown fever).
So much talk about the 2m rule and it’s impact on the hospitality sector in particular.
But in reality it’s only guidance. Everyone has already admitted that it’s not a “rule” or a “law” that is enforceable by the police so what would happen if pubs/bars were to open with no enforcement by the licensed premises operator?
As it’s not a law, what could be the comeback?
Could the licensing authority revoke the license and if so on what basis?
Could the business insurer cancel cover and if so on what basis?
The police have already said that they could not become involved?
OK, the clientele might decide that they don’t want to enter a premises without social distancing but that’s a risk many operators might be prepared to take and in a way this would be good as it would help keep numbers below capacity..
Looking at what’s happening generally. I think a lot of people, especially the younger generation, don’t care all that much, they just want to go out and have a good time.
Even a 1m “rule” is going to be a joke once premises do open – give it five minutes and nobody’s going to take much notice and if it was enforceable then a lot of licensed premises are going to go out of business.
Below is a link to an article showing my local city centre re-opening to shoppers in Newport, Wales for the first time. It is a stark contrast to the images of frenetic shoppers trying to get in the nike store last week.
Draw your own conclusions what the consequences will be on high streets that are not destination shopping venues and the knock on effect for landlords etc.
https://www.southwalesargus.co.uk/news/18533956.scene-newport-shops-re-opened-today/
I've gone long on Newriver Reit (LON:NRR) today as it seems likely the govt will soon announce significant measures to help shops e.g. social distance reduction to 1-1.5m, VAT reduction, extension of business rates relief and employers NI reductions etc.
The shops don't need to make bumper profits, just to break even and pay the rents.
On the pub side of things I think there is significant pent up demand for people to visit pubs and the staycation theme of this summer will help. I cynically suspect that our mad travel quarantine policy is actually a domestic consumption stimulus policy in disguise.
“I cynically suspect that our mad travel quarantine policy is actually a domestic consumption stimulus policy in disguise. “
I thought this. I think our outbound tourism spend is about 48 billion versus 28 billion inbound. Theoretically we would be a lot better off if more people did staycation. This doesn’t however consider negative factors like loss of aviation revenue and jobs etc.
Not convinced about retail rents. Whilst there is an imbalance in supply and demand rents should fall. Our local Shoezone has moved at least once with its old site now a charity shop. I would expect landlords of both sites suffered reductions in rent.
Now we know why Paul has put off replacing his car. He has been waiting for the right time to buy a Koenigsegg Gemera.
Regarding excessive gearing, why not reduce or eliminate the ability of companies to deduct interest payments from corporation tax?
There is a restriction for companies paying more than £2M in interest where they are restricted to a deduction of 30% of the company's or groups UK taxable profits before interest, taxes and capital allowances. Whether this is much of a disadvantage depends on the level of profits but I suppose it could hit some of those currently not trading who have high interest payments.
£SAGA I think there must be question marks over the CEO appointed in January. He seems to be pretty"unlucky" . Euan Sutherland halved the share price at Superdry & stormed out of the Coop ..also some concerns to do with his roles at B&Q. So not for me.
Hi Paul,
Maybe there's a play on Saga (LON:SAGA) bonds instead...
Yes, good point. I started googling for SAGA bonds, but got distracted. If anyone has a link to prices & yields on saga's corporate bonds, then I'd be keen to see it.
Paul with regards to Saga (LON:SAGA), good point about the balance sheet and likely capital raise. The plus side for this share is in my mind the insurance business - which has a good brand and in itself you could argue is worth the market cap. Therefore you get the travel and cruise ships for "free". I think mid-size cruise holidays will recover pretty quickly - the British appetite for this type of holiday is undimmed - and come a vaccine (or the ability to test people easily before they go on board) they will take place with decent occupancy. I also think there is value in the constituent parts of Saga, and wonder whether hedge funds might in the future start getting involved in a break-up play. I hold and think balance is to the upside on this one - but agree balance sheet is imperfect - and don't yet have a view on management.
re Saga (LON:SAGA) :
"The plus side for this share is in my mind the insurance business - which has a good brand.."
Sorry, but as someone who held both house and car insurance with them I disagree. They used to be competitive but then a couple of years ago there were some ridiculous hikes in renewal quotes and I was forced to shop around (something I tend not to do as often as I should). I ended saving hundreds by moving to rival over 50s insurer AgeUK leaving a nasty taste in the mouth on how Saga treated loyal customers. It looks as if I am not the only one to appreciate AgeUK:
https://www.ageco.co.uk/viewpo...
Elliot Mgmt, an activist hedge fund owned just over 5% bought June/July last year. According to filing on 9 April they have now gone below 5%.
Hi Paul/all,
Re: buying bonds - which online platforms can be used to buy them?
In the PI World video interview Paul linked to above, Paul Hawkins said you have to phone your stockbroker. (He also said that whilst stockbrokers say they are experts in the bond market, in reality they are not).
IMHO, It's a really informative interview for anyone who invests in corporate bonds.
On corporate bonds
Yes, the return has been better than the index over the last 20 years or so, and a lot more constant
... that stat does depend on where you count from.
Disclaimer - I am a customer :
https://www.wisealpha.com/
Hi andrewdb,
Couple of questions re this wisealpha site which I haven't come across before:
Their site also states: "Our investments are only available to registered investors who qualify. To qualify and view this content, you need to be a High Net Worth Investor, Self-certified Sophisticated Investor, Advised investor or an Investment Profession". Consequently not sure it would be suitable for all investors (though I know anyone can self-certify!) and guess any bond purchases would be be outside ISAs or SIPPs. The investment platform I use (AJ Bell) will buy/sell corporate bonds over the telephone and charge the same commission (max £9.95 depending on your trading volumes). As Paul Hawkins alluded to in his excellent presentation bond trading involves some very large volumes and outside the Retail bond market the minimum denominations are probably beyond the means of most private investors. In the Q & A I asked a question about the minimum volumes but I'm not sure I got an entirely satisfactory answer other than looking at sites like http://cbonds.com. However, unless you subscribe there is a limited amount of information you can get for free on there.
1
yes. Note that any ytm > ~7 implies the bond market thinks you are one or more of a) risky b) unsecured c) the assets used for security are not that great.
2
that is the amount you can buy. The min is £1 I think.
3
not tried selling and disinvesting yet.
Basically (disclaimer I may be wrong) it seems bonds are issued at 100,000 face, they buy one and sell it on in fractions. The bond lives with an asset custodian. They cannot run off with it.
They charge ~1% of AUM.
They offer a normal account, an IFISA (Innovative Finance ISA) and you can get a SIPP to put money in here (I do not know how that works).
They do offer some basic info on the company - some ratios / accounts / credit ratings.
The warnings are there because it is a bit different, and you can lose all your money.
From memory I had £200 in New look bonds and now have £70 and £40 in new look shares
Some of the yields are amazing, the ytm of pizza express august '21 bonds was > 100% recently and that tells you something about the bond market's view on their survival chances.
Interestingly looking wider there is (according to Alphaville last week) a link between the bond price and equity returns - seems if the price > 90, returns are positive and otherwise negative.
andrewdb,
Think I just answered my own question with a bit of DYOR reading on another site. An investor doesn't actually own a complete bond but rather 'fractional bonds' in much lower denominations. I think I would rather own the bond per se though I recognise that this precludes a lot of the market due to minimum denominations, or the risk of a hefty investment in one companies bonds
Hi Paul
What are you’re thoughts on BIGDISH now that they are introducing the delivery service on top of the existing discount dine in/yield management platform?
Is this a sleeping giant? This seems to offer a better platform than the likes of DoorDash but at a minute fraction of they’re market cap!
Interesting times
All the best
Really appreciate your endorsement Paul. In truth all credit should go to Tamzin. She encouraged me to do it despite my apprehension that there would be little interest in the subject. She also gently guided me to make it relevant to the audience. I just talked about something I know and love.
You have taught me much about small cap investing over my years of reading your reports, so its nice to know that I have put something back.
Always happy to chat bonds!
Best wishes,
Paul
Hi Paul ,
Excellent nicely explained made a dry subject interesting !!
Catch up soon
@hawkipa
Thanks for the really informative interview Paul,
I'd welcome your views on the current prospects for index linked corporate bonds. I think you said you had been buying them this year.
Hi @FREng,
I haven't traded in any index linked bonds this year. If I was looking at them I'd probably want corporate index linked. If you think inflation is coming down the line, then it makes sense to almost hold your nose, forget valuation and buy.
The reality I always found is that there aren't enough linkers to satisfy demand, so the market is always extremely well bid. I never ever once shorted a linker as I knew I had 5 buyers lined up for every issue. Quite a few utilities issued them as they have inflationary liabilities and that might be a good place to start with something like that. But in all honesty its an esoteric market at the best of times.
That takes you back to government index linked. I'm afraid I have no view on breakevens there. All I know as of today, is that you will pay a high price for that protection, so its worth having a very strong view on inflation before pulling the trigger.
Regards
Paul
Hi Paul, having read your review on John Menzies would you say that this share might be a good shorting opportunity when you take into account that the airlines are about to get going again.
I have put this on my short sell watchlist.
Keep up the good work and stay safe.
Terry
I have shorted Menzies following the update. Coming into this year with £300m in gross debt and current market cap of £120m a massive rights issue must be on the cards, maybe soon following the share price pop today. The business was performing poorly pre Covid and will face severe headwinds going forward even as tourist flights start to rebuild. Having airlines and airports as customers must be concerning for collecting receivables.
HB
What are peoples thoughts on the potential of a technology bubble? Its clear to see that at this time we're using technology more and more. However does that justify the comeback of tech stocks after the COVID drop. Will we see continued growth or are these stocks being overbought at an overprice?
In my opinion I think it is but I'm unsure what the effects of a recession will have I haven't seen that many stories on it so will be keen to see what other peoples thoughts are.
I saw this tweet by Michael Taylor earlier and it is worth thinking about in the context of whether we are in a technology bubble: https://twitter.com/shiftingsh...
Amazing to think that MSFT only regained 2000 highs in 2016. It shows both how buy and hold is a terrible tactic if you are in a bubble, but also, that while MSFT has done very well for the last 7/8 years, on a longer term perspective it doesn't look too stretched.
Hi Paul, I held a decent size position in Wirecard until a few days ago narrowly avoiding the meltdown. I sold up after reading your musings on how you steer well clear of any companies with any hint of fraud. Totally agree with you, why take the unquantifiable risk, plenty of other fish in the sea.
Hi Paul, a personal thank you for sharing your notes on Globo. I'd been trying to find them for about 2 years but they never appeared on the Stockopedia search function.
I am a shareholder victim of Globo which I'm sad to report. This was before I read your reports and had I been a reader of your reports I'm sure I would have been more cautious in evaluating my position to potentially avoid the 100% loss. At that time I was more influenced by not focusing as strongly on the cash numbers and the capitalisation process and swayed through ADVFN bulletin boards and the posters resentment of shorters like EK.
Thankfully I've learned a bit from this mistake and whilst I don't claim to be a genius investor I am better read and also enjoy holding some very profitable, long term positions.
Re Amigo Holdings (LON:AMGO) : Profit warning RNS out today stating "The additional cost of complaints received subsequent to 31 March 2020 is expected to be material, as a result of the substantial increase in the rate of complaints received." Price down 20% today to 7.8p
Amigo is now in a legal/financial tailspin, down 95% in a year. Complex situation and Board dispute may mean it ends up de-listing in my view. If it is to be saved, it may be best sorted out away from public markets. However, demand/pricing for Guaranteed Lending (ie lower loan rates for high risk individuals if backed by someone more creditworthy) which is its only product, must surely be rising fast. At one point this product generated a valuation of £1,3bn
So big opportunity for segment's no 2, Non-standard Finance (LON:NSF) (if they can ride out their own problems!!) since Amigo had a 70%+ market share to NSF's +/-15% or for someone else like Morses Club (LON:MCL) to enter the market. Brokers will not like the uncertainty. (Disc. I hold NSF and MCL).
I know not everyone likes the sector from an ethical standpoint but paying 49% interest on a guaranteed loan and being able to buy/repair a car to keep your job is a lot better than paying >100% or no loan for a lot of people.
And being able to recover thousands in compensation for mis-selling because no-one made it clear enough to the guarantors that they might have to honour their guarantees is even better!
It's a business model that the FCA hates and I wouldn't want to fight them.
Re COVID.
Is the situation today significantly different from the situation in February? According to the scientists, most of the population is just as vulnerable to the virus today as they were in Feb and the virus is still in widespread circulation. Is the UK able to manage new outbreaks swiftly and effectively now? It doesn't feel that way to me.
It would appear that the lockdowns were a success in lowering transmission rates & that this gain is now being given up as lockdowns are eased. Economic concerns now appear to be the primary focus of governments.
The data from the US illustrates this.
Two months ago (when all States were locked down) just SIX States had an 'R' factor of one or higher:
Today, TWENTY-FIVE States have an 'R' factor of one or higher:
https://rt.live/
And to add to the COVID gloom, research reported last week suggests that people who had mild COVID symptoms developed lower antibody levels that those who had severe symptoms and the antibodies declined more rapidly. The Imperial College epidemiology prof is quoted as saying that it adds weight to the view that recovering from COVID-19 may not provide lasting immunity.
This might imply that it will be difficult to develop an effective vaccine.
If they showed more mild symptoms surely they dont need more antibodies for next time.
The top italian virologist also said the viral load of the virus is now much weaker and 'clinically not present.
The top italian virologist also said the viral load of the virus is now much weaker and 'clinically not present.
And a whole host of other experts have said that's not true or not relevant. In general if there's less prevalence of the virus in the community people will be getting lower doses anyway. If R rises again it's likely so will the viral load.
https://www.healthline.com/hea...
Health experts say it doesn’t look like the virus has mutated to be weaker. Rather, this observation is likely a result of amplified testing capabilities and increased physical distancing measures
timarrYes, Prof Massetti also suggests it may be mutating to a weaker form, from Tiger to Wild Cat
https://www.mirror.co.uk/news/world-news/doctor-says-coronavirus-now-wild-22227292
I'm also cautiously optimistic of no 2nd wave, at least in UK. After all, we've had these massive BLM gatherings in major cities with presumably long exposure and little physical distancing for 4 weekends now, yet I've not heard of any upsurge in cases related to these. Perhaps I'm looking in the wrong place? To me this suggests overall levels of folk infected here are now pretty low (I've seen 1 in 1,000 suggested) and/or risk of transmission outside is low.
Coupled with our tracing system, I'd hope that any localised outbreaks can be stamped out quickly.
I read that the majority of track and trace work now is "complex cases" being handled by health professionals rather than the newly recruited army of call centre staff. This implies for me that the spread is in healthcare or community care settings.
That's still an issue clearly because those settings are not isolated from the wider community. But it does enable efforts to be targetted.
The Astra Zeneca boss says the Oxford vaccine they are co-developing will last "about a year". That would be good enough if at all goes to plan. It's cheap enough to give annual boosters.
GSK think these novel vaccines will be a stop-gap and are working on a traditional vaccine as a follow up.
Edit - That's over simplistic as GSK are working on a number of different projects.
My ignorance may be culpable, but I would be interested in understanding the distinction between the novel vaccines and traditional vaccines.
This was written last year but explains the different technologies better than I would. The Oxford vaccine uses a genetically re-programmed adenovirus incorporating the spike protein from the coronavirus to trigger the immune reaction in the body.
https://www.niaid.nih.gov/research/vaccine-types
Thank you.
Hello OsullivanB. This is in In answer to your question about the difference between traditional and novel vaccines. Most traditional vaccines are made by growing the disease-causing organism in culture and then killing, inactivating or attenuating it so that it can be used in a vaccine to elicit an immune response without causing significant symptoms. Novel vaccines are more difficult to exactly define as there are so many different approaches being used, but any vaccine which uses a genetically engineered adenoviral vector, such as the COVID-19 vaccine being developed by the Oxford group, would certainly be regarded as novel as it is at the forefront of vaccine technology. However, it is not the first vaccine to be made in this way. The Oxford group developed a vaccine against MERS using a similar approach.
Thank you.
Thanks for your COVID-19 comments FREng. AstraZeneca's CEO, Pascal Soriot, suggested that the vaccine being developed in collaboration with a group from Oxford University may be effective for a year. He will have seen initial results from clinical trial results in the UK and, just as importantly, the experimental analysis of bloods from some of the recipients of this vaccine so I would suggest that he is in a good position to make this comment. It is possible for a good vaccine to induce a longer lasting protective immune response than some actual viral infections so his comments are not necessarily inconsistent with the research report you quote. Yes, you are right that the situation with COVID-19 is not much different from February with the important exception that the number of cases is stable or falling gradually rather than rising. The government has decided that the number of additional cases and deaths resulting from reducing social distancing to one metre is acceptable, because of the economic benefit it provides.
Many Government decisions can be analysed to calculate an implicit value that is being placed on a life (or sometimes a Quality Adjusted Life Year, QALY). I really wish they would use the same value consistently.
I think the US with its Federal and individual State measures gives very useful indications as to what works – and what doesn’t. Clearly the lockdown does save lives.
An interesting canary in the mine is Arizona. Arguably, it had a weakish stance on lockdown which was allowed to expire on May 15th. Governor Greg Ducie was confident that a light touch was the way to go and seemed to measure containment by spare capacity in ICU beds.
Now there are reports of a crisis developing and it will be interesting to see if Arizona can put the genie back in the bottle without re-imposing shutdowns.
FREEng
Is the situation today significantly different from the situation in February? According to the scientists, most of the population is just as vulnerable to the virus today as they were in Feb and the virus is still in widespread circulation. Is the UK able to manage new outbreaks swiftly and effectively now? It doesn't feel that way to me.
I would say today is significantly different to feb.
Public more aware
Public taking active measures
Business taking active measures
More testing
some sort of track and trace implemented
No/less mass participation events taking place now and for forseeable future
In theory we will take more active measures if needs be (if you belive the gov bods)
Is the UK able to manage new outbreaks swiftly and effectively now?
Thats the key unknown - i am confident that we are better placed to cope with spike back up than we were previously - is that enough to stop a material spike back up happening - unknown and anyone sho says they know is probably just guessing. I am presuming (90% confidence) it won't ever get as bad as it did first time round - at least the testing is ramped up now so we should at least be aware of any spikes taking place - and if we start from a low enough level there is the time lag it takes to get bad IF we start from a low enough background level - that should give us time to act. I could easily be wrong in my presumption though (i certainly didn't have an inplay bet on Joelinton to score yesterday - and he did)
Current practices in germany and china and the like where there are proactive measures in place will at least give us a roadmap of what need to be done with any spike back up. If the germans can't keep a lid on it though i would say our chances of doing better than the them are close to zero.
As regards retail re-opening.
I would think that pubs and clubs are hoping to reduce social distancing to 1 metre so that they might just carry on as before. Unless somewhere is really packed, it would be very difficult to monitor.
In our town, the local Marstons seemed to have been struggling pre virus for a good while with a steady turnover of Tenant Landlords. The local joke is that it was so quiet there you could make social distancing 3 metres and it wouldn’t affect their business. The main beneficiary appears to be Wetherspoons.
Prior to the virus, I would guess that the best shop in our town with footfall per square metre was Card Factory. A very small shop which was always absolutely packed. I thought it might struggle upon re-opening but on Thursday the queue to get in was about 30 metres in length
Was very pleased to see our local Hays Travel agents opening again – although the windows mainly seemed to be offering 2021 holidays.
Overall, I am more positive for retail – but see many pubs and bars having problems.
Disclosure – hold none of the above.
Paul I totally agree with your comments about shorters, who sometimes seem the best placed (financially motivated) people to hunt out fraud at companies. While shorters are not angels - their poor reputation is I think a pity. I was disappointed (but not surprised) at a talk given by one of the big 4 accountants a couple of years, when they said that they would not pay more attention to an area of the accounts, if they had been informed by a short fund (either publicly or informally) that there was a potential fraud there.
On Wirecard, I think the specific stories about the reliability of the cash on the balance sheet came from the FT last year. It seems that Wirecard’s auditors have focused on this area now (no doubt seeing the FT as a credible source).
I was disappointed (but not surprised) at a talk given by one of the big 4 accountants a couple of years, when they said that they would not pay more attention to an area of the accounts, if they had been informed by a short fund (either publicly or informally) that there was a potential fraud there.
Not surprised
1
If you were told that some was wrong, looked, found nothing, there was nothing to find:
You spent extra time (i.e. money) that the client (the company) will be footing.
That will not help customer retention
2
If you were told that some was wrong, looked, found nothing, there was something to find:
Your PII insurer will not be pleased as you accepted the job of looking and failed.
... no win.
This is more a comment on the structure / scope / function of Audit.
Given what is expected and who pays, nearly impossible.
No, i am not an auditor :)
Great work Paul. Always enjoy reading your macro musings and personal investing thoughts. Keep it up please.
Hi Paul
There were some news reports over the weekend that Go Outdoors is going to collapse into administration. Apparently they were struggling even before the covid outbreak.
They are owned by JD Sports Fashion (LON:JD.) so shouldn’t have been short of good management input. Perhaps that shows that if your offering is relatively undifferentiated you’re going to struggle even with good management.
I still hold JD but am wondering whether physical retailers are just too risky to hold right now.
Are you still in French Connection?
Press speculation largely confirmed by RNS this morning.
Yes I'm still in French Connection (LON:FCCN) - but that's more a special situation than a retailer.
Also, it's probably losing less money closed, than it did open! ;-)
Re French Connection (LON:FCCN) : "it's probably losing less money closed, than it did open! ;-)"
I wondered the same - and surely this will be the trigger to finally accelerate the rapid wind down the remaining retail operations! At worst, now there is a genuine risk it may go under (stock obsolescence and bad debt on top of store losses), it may be better able to negotiate rent reductions. It's an ill wind that blows no good! Previously its strong financial position probably worked against this as landlords knew ultimately it could pay.
However, its weak online operations will have been counting against it during lockdown and the consequent big shift online. Also its good historic links to Dept stores esp in the US ties it to a very weak sales channel going forward. I still hold as a kind of option since it is now so low but I am not optimistic. Marks must regret not selling out last year.
I saw a report at the weekend that Boohoo (LON:BOO) have a £200m war chest to spend on distressed retail brands. I wonder if French Connection (LON:FCCN) is on their radar at all.
This is the article - it was in the Telegraph. I believe it is subscription only:
https://www.telegraph.co.uk/business/2020/06/21/boohoo-goes-spending-spree-snap-retailers-distress/
V interesting pre-amble Paul.
Cheers
Hi Paul,
Can you look into Goodwin £GDWN nice sounding contract win which is “expected to result in significant turnover for the business from the next financial year onwards”
Thanks,
TA
Perhaps the good news for Goodwin is bad news for Avingtrans, as they had what looked like a continuing long term major contract building presumably the same nuclear waste boxes at their works in Chatteris.
Don't think they can be the same - I thought £AVG's business was stainless steel fabrications, and Goodwin (LON:GDWN) specialises in large castings. Anyone know better?
Hi muckshifter,
Regards Goodwin (LON:GDWN), Avingtrans (LON:AVG)
Been pondering this. As you'll be aware Darchem and Metalcraft (AVG subs) picked up the original Tranche A contracts. AVG stated in the interims that any further tenders had been delayed until late 2021 whilst what I believe to be this contract had an projected announcement date of 30th June 2020 so i'm not sure they were in the running for this one.
When I spoke to AVG at an agm a couple of years ago they suggested at least 1 other participant would be involved in producing the 3m3 boxes due to the large size of the contract.
Grc International (LON:GRC)
o The majority of our previously office-based staff in all our geographic locations are now permanently home-based.
https://www.investegate.co.uk/...
My morning smallcap tweet:
Fireangel Safety Technology (LON:FA.) Angle (LON:AGL) Integumen (LON:SKIN) John Menzies (LON:MNZS) Goodwin (LON:GDWN) Mycelx Technologies (LON:MYX) Mothercare (LON:MTC) GRC International (LON:GRC) Active Energy (LON:AEG) Amigo Holdings (LON:AMGO) Saga (LON:SAGA) Nuformix (LON:NFX) Bonhill (LON:BONH)
FireAngel (FA.) gets £3.2m covid loan to tide them over.
Angle (AGL) blood donations have recommenced for FDA analytical studies and patient enrolment in its pivotal ovarian cancer study.
Integumen (SKIN) Material Transfer agreement to develop and manufacture aptamers to detect SARS-CoV-2 in wastewater.
John Menzies (MNZS) Q2 ahead of management expectations, with a recovery in flight activity anticipated to begin from early July. No FY guidance. Cost cutting extends liquidity runway to 2021.
Goodwin (GDWN) wins contract to make storage boxes to assist with nuclear waste clean-up. Expected to ramp up over a 12 month period, and is anticipated to continue for many years. Sounds a big deal for co.
MyCelx (MYX) $1.8m extension of a purchase order from SABIC for a leased water treatment system in the Middle East.
Mothercare (MTC) substantially completed transition to refocus on brand management and the design, development and sourcing of product. 2/3 of partners' global retail locations are now open. Loan talks. Cutting warehouse & HQ lease costs by downsizing.
GRC (GRC) Billings almost 20% ahead of mgmt expectations, costs lower than anticipated. Wins 3 relatively large longer term contracts worth £400k this FY.
Active Energy Group (AEG) issues convertibles to raise £800k to accelerate development and increase production at Lumberton factory to meet demand. Additional saw-log export contract signed with a new South East Asian customer.
Amigo (AMGO) high-interest lender sees substantial increase in the rate of complaints, asks AFC for even more time to process them.
Saga (SAGA) continues to expect compliance with key covenants at the next two half-yearly testing dates, although further actions may be needed to 'stay ahead' due to potential uncertain long-term impacts of covid.
Nuformix (NFX) CEO resigns, will stay to end June for handover. He is thanked.
Bonhill (BONH) CFO resigns, will remain NED for handover. He is thanked.
Results out of Polar Capital (POLR) this morning. I hold and continue to hold.
Earnings down due to lower performance fees and higher costs. Divi held at same level as last year, still covered by earnings. Markets now higher, so fees will grow again, assuming that markets don't fall straight back down again. Well positioned.
Really enjoy reading your thoughts Paul, keep up the good work
Me too. Thanks Paul. I also found Paul Hawkins PI world interview incredibly informative. Really worth a listen.
Thanks Jon. Really appreciate you saying so.
Regards
Paul