Small Cap Value Report (Mon 22 Nov 2021) - ANG, CER, FDEV, CNIC, EMAN

Good morning! It's Paul & Jack here with the SCVR for Monday.
Mello - details of tonight's show are here. Cerillion (LON:CER) is certainly an impressive company.
Agenda -
Paul's Section -
Angling Direct (LON:ANG) - 2 more updates re cybersecurity incident were issued last week, so I recap on the situation, which now looks under control.
Cerillion (LON:CER) - tremendously impressive results from this telecoms billing software company. Profits are soaring, and the order book is strong, suggesting another good year is in the pipeline. Broker forecasts are up, but still look too cautious. Superb balance sheet & cashflows. This is a really impressive business, not without risk though. I think the valuation seems justified, there's a lot to like here.
Frontier Developments (LON:FDEV) - profit warning slams this computer games company down about 37%. This is due to disappointing sales of 2 games, but the company doesn't know if it can recoup this over the festive season. Lack of revenue & profit visibility worries me. Might be a buying opportunity, if you know more than I do about the company, and you like it?
Everyman Media (LON:EMAN) - trading ahead of expectations, helped by James Bond, which has led to a broker forecast increase today. I've heard good things from friends who have visited Everyman cinemas, with a differentiated offering. But is it a viable business model? That's not been proven yet, in my view.
Jack's Section -
Centralnic (LON:CNIC) - growing, acquisitive company dealing in domain name services and online marketing. Organic growth is picking up after a burst of acquisitions. The result could be an inflection point as a more complete platform drives further growth and margin expansion. Results remain adjusted and the situation requires a certain time investment due to the acquisitions, business operations, and growing markets.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Angling Direct (LON:ANG)
59.5p (Friday’s close) - mkt cap £46m
Both Jack and I think this company looks potentially interesting, so this section is to get us fully up-to-date. Delving through the archive;
13 Oct 2021 - Jack reviewed ANG’s interim results, and sounded positive about the numbers & potential. I agree with his cautious optimism.
8 Nov 2021 - I (Paul) commented on ANG’s announcement of a cyber attack, where hackers had taken down its transactional website (about half its business), and redirected it to PornHub.
Since then, there have been 2 more updates on the cybersecurity issue, so let’s get up-to-date.
10 Nov 2021 - Cybersecurity incident update - sounds like things have been resolved -
... the Company is confident it has now eradicated any threat from its systems. It has also regained control of its websites and social media channels.
Website may be slower to load
Investigations ongoing to determine if any personal data has been affected
No financial data is held for customers, as payments are processed by third parties - this strikes me as an important point
39 retail stores unaffected
Board currently believes this incident won’t hurt underlying trading (underlying being the key word, because of course there are likely to be exceptional costs relating to this incident)
Security measures have been increased.
12 Nov 2021 - Further update -
Websites trading normally now, and warehouse is working through the order backlog.
Reiterates that this incident should not affect underlying trading.
Talking to insurance company.
My opinion - we don’t yet have the full facts, but it seems to me this has been quickly resolved.
The main questions I have are;
- What is the total cost likely to be? It’s not cheap to bring in cybersecurity experts
- Are there likely to be regulatory fines? If so, how much?
- Who pays for the above? I.e. will insurance cover some or all of the costs?
So there’s still some uncertainty here, but given the company had almost £20m in net cash at the interim results, then I imagine this incident is not likely to come close to threatening the solvency of ANG. Therefore, unless some new, more damaging information is revealed, shareholders probably don’t need to worry too much about this cybersecurity incident.
Overall, I think ANG shares seem good value. It’s sitting on a ton of cash, over 40% of the market cap, and is now profitable.
It therefore seems odd that the share price really just gone sideways over the last 3 years, despite the business making considerable progress over that time.
.

.
Cerillion (LON:CER)
900p (up 4% at 08:40) - mkt cap £265m
Cerillion plc, the billing, charging and customer relationship management software solutions provider, presents its annual results for the 12 months ended 30 September 2021.
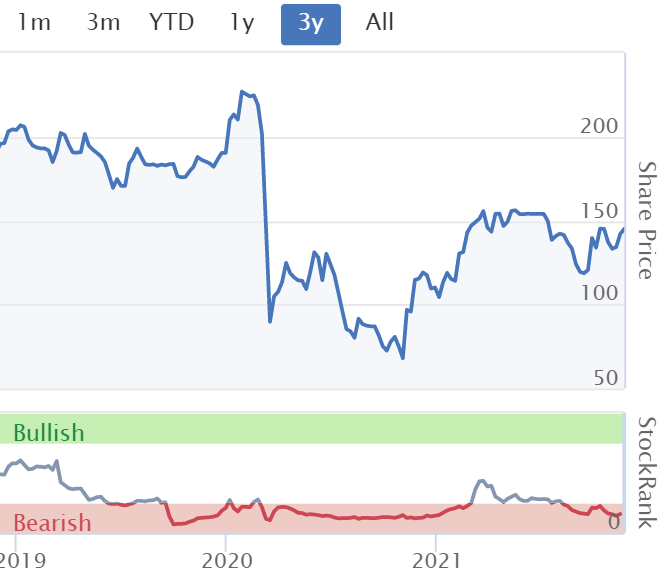
Very impressive results from this interesting software company, but of course strong performance has already been reflected in a stellar share price & re-rating. Note from the 3-year chart below, how CER shares have remained buoyant, despite market conditions for small caps feeling distinctly bearish in the last few months -

.
Summarising a few key numbers , with my comments added -
Performance is at record highs
Modest revenues of £26.1m (up 25%), but it’s a very high margin business
Adj profit before tax up 131% to £8.5m (statutory PBT is £7.4m, so not a huge difference)
Adj EPS up 105% to 25.5p - giving a PER of 35.3 - not outrageous given the stellar growth in profits, but obviously leaves no room for disappointments in future. There are plenty of other less impressive, slower growing software companies on higher ratings than this.
Adjustments look reasonable to me, and are the usual things like acquired intangibles amortisation, share based payments, and exceptional items (see footnotes 5 & 6)
Dividends small but growing, under 1% yield, people are not buying this share for income, more for capital gains, so that’s fine
Strong balance sheet with £13.2m net cash
Impressive cashflow statement, with no funnies, and lots of genuine cash generation
Only £970k capitalised intangibles, which suggests fairly prudent accounting to me
Impressive order book - up 36% to £42.1m
Largely unaffected by pandemic - e.g. staff working from home/hybrid model (2 days per week in office)
Broker consensus is showing as 20.3p on the StockReport, so actual of 25.5p for FY 09/2021 is a significant beat, although the 2 broker notes I’ve seen seem to have been far too conservative in their forecasts, which are raised to more realistic levels this morning in update notes.
Today, FY 09/2022 forecasts are raised considerably (from way too low levels) to c.27.0p - only 6% higher than FY 09/2021 actuals. I’m not sure why brokers are being so cautious, which I don’t think is particularly helpful - why can’t we just have realistic forecasts, instead of irrationally low forecasts? Although the under-promise, over-deliver mantra is quite good I suppose, so it depends how you view things.
The way things are set up, Cerillion should be putting out ahead of expectations updates in future, because the bar is set quite low, and the high valuation demands that it continues to beat expectations. The forward PER is 33.3 times forecast of 27.0p, which is too high for just 6% earnings growth, so it needs to out-perform, and probably will, judging by the year end order book being up 36% on a year earlier, and positive outlook comments -
Outlook -
The Company delivered a record set of results, and our products are gaining greater visibility in the marketplace. In addition, Cerillion's financial position is very strong, supported by a growing base of recurring income, increased cash flows, and no debt.
We believe that Cerillion remains well-positioned to deliver another strong performance over the new financial year. The back-order book stands at a record level, providing strong visibility of revenues, and the pipeline of new business is strong. In addition to these strong organic growth prospects, we also continue to assess a range of inorganic growth opportunities as they arise.
The market backdrop is favourable, with increasing investment by telecom companies in their networks and in digital transformation, and this long-term trend should continue to benefit Cerillion's growth prospects.
My opinion - terrific numbers here, and if growth continues, then the valuation looks justified.
The new financial year looks set to be another strong performance, since the order book & pipeline are so strong.
One particular phrase caught my eye - “the trend for bigger contracts & larger customers” - that suggests to me that something structurally good seems to be going on at Cerillion, i.e. a step change in size & profitability of the company. Customers seem to be very sticky too.
Although only 33% of revenues are recurring, which could be a big problem if new orders dry up, since the bumper profitability is mainly being fuelled by licence wins, which of course are one-offs. We’ve seen before how some software companies have a wave of big contract wins, profits soar, but then they dry up & profits crash. Let’s hope that doesn’t happen here, but it is a risk when two thirds of revenues are non-recurring, and very high margin. That risk has to be considered, but on balance I think the strong momentum of contract wins & big order book probably outweigh any such worries for me anyway.
Overall - very impressive indeed, and it is tempting to pick up a few shares in CER for my SIPP as a long-term holding (no position currently).
A reminder that Cerillion are on first at tonight's Mello Monday online investor event. I spoke to management a couple of years ago, and remember thinking how smart they sounded, and thinking I should invest in this management team, but sadly didn't stay in the share for long, can't remember why. Which reminds me that sometimes it can be better to back good management long-term, and not pay too much attention to valuation, something I still find quite difficult, but am trying to do more of it.
Frontier Developments (LON:FDEV)
1596p (down 36% at 10:39) - mkt cap £615m
Ouch, bad luck to any FDEV shareholders here. This is not a sector I understand well, and find valuations too difficult to fathom. So this section is really just to take a look at what’s gone wrong, rather than to impart any insights - reader comments might do so, so please let us know your view, if it’s a share you’ve researched.
Frontier Developments plc (AIM: FDEV, "Frontier" or the "Company"), a leading developer and publisher of videogames based in Cambridge, UK, provides an update on trading for the current financial year FY22, the 12 months ending 31 May 2022.
My summary of this update -
Well established titles continue to perform well
Elite Dangerous: Odyssey - sales have been “more muted”
Jurassic World Evolution II - expected to be this year’s largest revenue earner, but initial PC sales have disappointed, possibly a short-term issue.
Revenue guidance revised (from?) to £100-130m for FY 5/2022 - wide range is due to unpredictability of peak trading over holiday season
Next trading update in early 2022
Info given on other new product releases
Broker update - many thanks to Liberum for making available to us (via Research Tree) commentary and revised numbers.
The latest EPS estimate for FY 5/2022 is 34.7p, down from 60.9p last year, rising to 87.2p next year.
Stockopedia is showing 72.1p consensus EPS (before today’s profit warning), so today’s update is for earnings (at 34.7p) to be just under half what was previously thought. That’s a pretty bad downwards revision. However, maybe the broker is being too pessimistic, and this revised forecast could be too low, if Xmas sales surprise on the upside?
My opinion - what this is shouting out to me, is that there doesn’t seem much earnings visibility with this company. I understand the point that computer games are “franchises” now, or the best ones are, and eagerly-awaited updated versions can be lucrative (for a year or so), with operationally geared sales. So there must be considerable value in established hit games.
How on earth do we value the shares though? With earnings so volatile, a PER basis looks problematic.
Do you try to work out a value for each “franchise” instead, and do a sum-of-the-parts valuation?
There’s been takeover activity in this sector, so that might be another way to value this share.
Overall, it’s all too uncertain for my tastes, but I can see why some people might see this as a possible buying opportunity - if you think the problems are temporary (which they might be). It doesn’t sound as if anything has gone permanently, or drastically wrong.
Personally, I don’t know enough about the company or sector to form a view on this. Good luck whatever you decide.
.

.
Everyman Media (LON:EMAN)
148.5p (up 4% at 12:10) - mkt cap £134m
Everyman Media Group PLC, the independent, premium cinema group is pleased to announce a trading update for the financial year ending 30 December 2021.
What a refreshingly clear update, top marks for this -
Admissions have been ahead of expectations since publishing its interim results in September 2021. Therefore, Group revenues and EBITDA for the financial year ending 30 December 2021 will exceed current market expectations.
On the basis of no further COVID-19 restrictions in 2021, the Group expects to report turnover of not less than £46.3m and EBITDA of not less than £7.0m.
This type of business has obviously seen a lot of disruption to trading, and also received Govt support (e.g. furlough, business rates relief, etc), so we have to be very careful interpreting figures, because in future years, revenues should recover, but costs are also going to rise as Govt support measures disappear.
Broker update - many thanks to Canaccord Genuity for an update note, which they have helpfully made available on Research Tree. It’s great to see them joining the RT platform, as I’ve always liked Canaccord research notes, but often previously struggled to get hold of them.
There’s a big upgrade in EBITDA, from £4.8m to £7.0m.
However, that still results in a hefty adj loss before tax of £(6.7)m.
Large increases in revenues forecast for FY 12/2022 and FY 12/2023, result in more losses in 2022, and only just above breakeven in 2023. That doesn’t strike me as very good, for a company valued at £134m.
The forecast EBITDA numbers look impressive, but it’s nearly all wiped out by depreciation charges on the heavy capex to fit out each site.
My opinion - it’s not clear that Everyman has a viable business model yet.
James Bond has come to the rescue recently, boosting the figures.
The format is certainly differentiated, but I worry that the company might be rolling out a format that doesn’t really make any money. That’s not attractive to me, but maybe it could beat forecasts as audiences return?
It seems to me that there are probably other, much better re-opening, or roll out concepts in other sectors - e.g. restaurants or bars groups where they can clearly demonstrate favourable economics, with each site already being profitable, hence opening new ones results in more profits. That's far from clear what we're getting at EMAN, and I worry it needs to spend a lot on capex for new sites.
Although I see it was profitable pre-covid, in 2017, 2018, and 2019, so maybe there could be a decently profitable business here in future? There's too much guesswork involved for my liking, so I'll pass on this one.
Maybe it's the sort of share that people buy because they enjoy the concept as a customer? That can be a good strategy sometimes, a bit like the Peter Lynch approach.
.
.
Jack’s section
Centralnic (LON:CNIC)
Share price: 152.2p (+1.47%)
Shares in issue: 251,160,084
Market cap: £382.3m
This is an interesting developing situation, albeit one that can be hard to wrap your head around: CentralNic is a global vendor of online services (around 12% of domains globally use at least one of CentralNic’s platforms), supplying the tools needed for businesses to develop their online presence.
Such activities include the provision of domain names and domain monetisation services using a proprietary technology stack and its millions of registered domains.
CNIC now reports as two divisions:
- Online Presence: selling domain name subscriptions required for operating email and websites. Sometimes companies buy these to use, or buy them so others can’t use them (brand protection). Domain investors also own domain name portfolios and monetise the traffic they generate.
- Online Marketing: internet traffic monetisation is the group’s second core activity, established in 2019 with the acquisition of Team Internet, and growing to represent the majority (59%) of gross revenue in 9M21.
It’s arguably the latter segment that might warrant a racier multiple in time, although both markets are attractive.
In 2020, c$400bn was spent acquiring internet traffic by online marketers, with demand growing at over 20% annually (this is Online Marketing). Management estimates the size of the domain name market to be around $5bn with 3% growth, while the value-added services related to and bundled with domains has annual revenues of an additional $25bn, growing at 6% annually (Online Presence).
Each of these markets is highly fragmented, with a large number of small and mid-sized companies addressing specific market niches or territories.
The central idea is that, similar to Tremor International (LON:TRMR) before it, CentralNic is reaching an important inflection point having hit a certain scale as a result of acquisitions and internal investment. The market has recently rerated the company and it is attracting interest from the community.


The group has attractive recurring revenue and cash generation characteristics, and the $36m acquisition of Codewise makes CNIC ‘full stack’, selling directly to publishers and buying directly from domain owners, in a similar manner to Tremor.
Key acquisitions include:
- KeyDrive (August 18),
- GlobeHosting (September 18),
- TPP (May 19),
- Hexonet (July 19),
- Ideegeo (Aug 19),
- Team Internet (Nov 2019),
- Verisign (2020),
- Codewise (Jan 2021),
- Wando (Feb 2021)
- SafeBrands (Feb 2021).
Trading update - nine months to 30 September 2021
Significant investment in new management, staff and systems accelerated organic growth to record levels and positions the Group well for continued growth
Highlights:
- Net revenue +60% to $85.5m; organic revenue growth up from +9% to +29%,
- Adjusted EBITDA +46% to $32.3m,
- Operating profit up from $0.7m to $8.9m,
- Adjusted operating cash conversion up from 93% to 113%,
- Net debt down from $85m to $78.6m despite $13m spent on acquisitions,
- Adjusted EPS +5% to 7.73 cents.
‘Now more than 45m domains use at least one of CentralNic’s platforms (12% of domains worldwide).... As CentralNic consolidates, it is taking out costs, deploying technology to automate process and so is increasing EBITDA.’
Post period-end acquisition - a publishing network of revenue generating websites for $6.5m in cash and assumed working capital liabilities, completed on 15 November 2021. This is expected to generate at least $2.0m in annualised revenue and $1.5m in annualised EBITDA.
Outlook - The company expects to trade comfortably at the upper end of market expectations for the year for both revenue and adjusted EBITDA. Analyst expectations currently range from $349.0m to $384.1m and $41.8m to $43.0m respectively.
The accelerated organic growth seen during Q3 2021 YTD is expected to be sustained for the full year following the investment in new management, staff and systems
Ben Crawford, CEO, commented:
A virtually pure play recurring revenue business with cash conversion of over 100%, CentralNic continues to improve its cash position, interest coverage and net debt to EBITDA ratio as it grows. As our investment levels plateau moving forward, we expect future periods to benefit from increasing operational leverage.
These robust results reflect CentralNic's continued success in sourcing, completing and integrating transformative acquisitions and driving the organic growth of our businesses. The pipeline of future acquisition targets remains strong, and we are confident in continuing our trajectory towards joining the ranks of the global leaders in our industry.
Conclusion
The company's market consolidation strategy continues in what is a large, globally fragmented market. That said, this remains a fast-moving, acquisitive situation with quite heavily adjusted results. Note how the strong revenue growth does not yet translate into significant profit growth. That, plus the fact that the group’s businesses can be hard to understand, might make some wary.
But there are some more universal investment concepts to hold onto here. The recurring revenue and strong cash conversion in growing, fragmented target markets for example. CNIC says the online presence market is worth $40bn and the online marketing market is worth $400bn, so there is ample runway for growth.
Both divisions share characteristics including high recurring revenues, c 100% operating cash conversion and attractive customer stickiness, with significant opportunities for upselling and cross-selling across its c45m domains.
The result of its aggressive strategy is an impressive revenue compound annual growth rate.

This has so far come at the expense of profits but, with the group shifting its focus, the market expects quick progress here.
Operationally, management’s strategy is to benefit from structural market growth, building its marketing business as well as on the group’s underlying domain registry customer base, diversifying the group’s revenues through the cross-selling and upselling of services. Growth is supplemented by acquisitions in a fragmented market.
Margins should improve as the business scales, and management expects the strong organic growth seen in the first nine months to continue at least for the remainder of the year.
In the medium term, investment levels should plateau and management expects the recurring revenue model and strong cash generation to provide operating leverage as the business scales. All in all, an interesting growth situation, albeit one that takes some effort to understand. Its markets remain new and high growth - an opportunity, but there’s always scope for technological disruption as well in these areas.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Thank you johnsmith and shamusj for responding. My 1st purchase of TM17 was Oct 20 and my 2nd was July 21, so it is not 'doing it' for me but I will be patient. When I look at the data it is good which is why I have hung on so long. I will bide my time a little longer. Thanks again for helping. Charles
Seeing Machines (LON:SEE) announced a placing as an exceptional amount of RFQs in the pipeline. Results on Wednesday might be worth a look for the scvr.
I recall someone saying in the comments some time ago, saying that EveryMan Media generated decent cash per site. Obviously not currently the position, but that seems a sensible way to begin a review of its future performance, perhaps?
Everyman Media (LON:EMAN) (I hold)
Hi Trident
That comment on cinema venue profitability might have come from me.
Pre-covid:
It costs £0.6m-£1.0m to kit out a new cinema venue, after which maintenance capex is then quite minimal, so the Pay Back period is probably around 1.0-1.5 years, with future year profit flowing straight to the bottom line.
---
Today's trading update was better than even I expected.
I agree with Paul that the company is benefitting from short term support, such as reduced VAT on tickets and food. However, in my opinion, Everyman Media (LON:EMAN) is a luxury good and it's much easier for the company to raise their prices in future years, without it resulting in a loss of business.
I have no idea what updated forecasts look like for FY22 after today, but after the last update in September my general feeling was that 2022 revenue forecasts would actually be missed.
Nonetheless I continued to hold. The company makes plenty of cash, is able to use this to expand without taking on debt, and cinemas do well whatever the state of the economy.
It's undervalued in my opinion, but as a holder of course I would say that.
Cheers
A
Re Angling Direct (LON:ANG) - thank you for flagging a potential opportunity there Paul. Do you or anyone else understand why brokers via the Stockopedia EPS figures suggest that EPS will fall from 3.45p this year to 2.6p in FY23? I have done no research here and couldn't see that flagged up previously, but I'd want to understand why profitability is expected to fall.
Angling Direct (LON:ANG) . (No position)
Probably because of the withdrawal of Covid support. They have/had 35-40 retail units receiving Covid grants during a period when people could still go fishing so their website was incredibly busy, this is high unlikely to be replicated .
Richard
Hi
As an alternative to some of the not so great share price moves today. This is Boris's speech to the CBI (live as I type).
Irrespective of your views of him or his party. I think as investors it's useful to note where government policies, investments and significant supportive actions are playing out.
Also, of some interest are some of the stats he is quoting e.g. 70% annual growth rate of EV sales in the UK, growth rates of charging technologies and several other green-related industry sectors. Adding to these insights are the converse insights about sectors which will clearly be diminishing.
This post is not meant as either an endorsement nor a criticism (I am not trying to encourage politics onto this thread, that can ne dealt with elsewhere), rather I think it's useful context as it effects us all and in particular our investments.
Regards
Howard
All
Warning. The speech was extremely badly delivered (I posted it as it streamed live). But, as investors we can still look into the content which is the important part of the speech.
Regards
Howard
Without getting political, I don't think that speech belongs here. We know that you can't rely on anything Boris Johnstone says - he speaks for the moment and is likely to change track tomorrow.
My goodness that speech was a shambles. I expect toe-curling from him but there's something really not right about him there.
A bit off piste, but does anyone know why Team 17 Group Team17 (LON:TM17) is failing to perform in terms of share price and why down 5.52% today? Any comments gratefully received.
If a doubling in share price over a 2 year time frame is "failing to perform" then I hope that all of my investments fail similarly!
As for today's fall, it's off less than 4% on the same day that £FDEV (see main article and threads below) has fallen by over 33% on a profit warning so I imagine that Team17 (LON:TM17) is just collateral damage.
I would think that the read across from Frontier Developments (LON:FDEV) to Team17 (LON:TM17) is a buying opportunity as their strategy is much less risky than that of FDEV. i.e. Team17 produce 30 or so indie titles per year with a few bigger budget ones, as opposed to a one or two mega budget titles.
LON:AMYT. I hold in my ISA. Have seen the news that AMYT is to delist from the AIM and trade only on the NASDAQ. Has anyone been on a similar journey before? Can I still hold the ADRs in my ISA?
No proof, just a hunch, but it feels to me that popular PI stocks may be getting sold at moment. Stocks where there has been an element of follow the crowd (regardless of whether they are good or bad). Profit taking as uncertainty following the rush up from covid lows and last 6 months been choppy
Some of the sell-off seems random. Braemar Shipping Services (LON:BMS) (I hold) is now down to 9x earning even though you'd think it should be able to take advantage of some of the issues with shipping right now and the most recent update didn't provide any cause for concern.
Its generally pretty random...if possible to analyse it probably relates to the number of PIs (not the $$$ amount but number) who bought in as stocks shot up in the past on little work or follow the leader sort of thing and are selling out at a perhaps accumulating pace as prices carry on down. I've got no view on Braemar Shipping Services (LON:BMS) but would suggest it could apply.
I think some nice opps opening up. I think general negativity is overdone (I mean this at a global and macro level). It seems that only negative things are visible at the moment. My guess is that we are still early in a recovery cycle...tho that cycle is an odd one due to the covid V and the re-emergence of inflationary pressures (whilst not all transitory I think there is a high transitory element...we will have higher inflation than the 2010s...but we ain't taking off to mega inflation). I don't have a short term forecast for you as its possible sell off gathers a bit more pace...the market is made to do what you think it shouldn't and will surprise the most people so maybe Santa wont come this year. I dunno
Haha. Crazy price action IMO is Tremor International (LON:TRMR) (yeah I know...marmite stock so won't say more). When I wrote the above that was one of the 'nice opps opening up' I had in mind. Somewhat arbitrarily I'd set myself a buy sub 550p action point. Its cheap IMO before then (given margin, positioning within their industry and growth) but I wasn't rushing. Today its gone down 8% and then reversed to up a touch. Insane...IMO just price action driving price action
Does anyone have any insight in to what might be occurring with the Somero Enterprises Inc (LON:SOM) share price at the moment? Can't see any negative catalysts that are congruent with its fall.
Somero Enterprises Inc (LON:SOM)
Somero has rarely traded at much of premium price due to their sales partly being down to what market forces dictate - add in overseas company and chances of their current taliwinds starting to reverse at some and mention of teh next recession then blah. So in some respects i never really expected this would rise much above 600p anyway - that being the case the fact that is back in "cheapo" territory does not surprise me. Add in the potential for supply constraint issues and thats enough for there to be as many if not more buyers than sellers. IMHO its not really a share you should ever expect to be shooting the lights out return wise. I hold at present and i am happy to do so - i might have sold though had price spiked above 600p, befdore we get the next set of good news. Note as other companies are at more reasonable values now too compared to 3-6 months ago there is more choice on offer where too invest to. I would say up to now Somero seem to have avoided the reversal of tailwinds/supply issues that have plagued others up to now so i can see why you might be miffed price isnt higher.
Thanks for the interesting thoughts..
"Add in the potential for supply constraint issues and thats enough for there to be as many if not more buyers than sellers." Not sure if you meant more sellers than buyers?
Thinking about mitigating factors for Somero Enterprises Inc (LON:SOM) on the potential supply constraint issues:
- On the chip front, Jack Cooney confirmed at 27:00 on PIWorld that Somero was not directly affected by chip issue, this being more pronounced for other industries.
https://www.piworld.co.uk/comp...
- On a labour shortage front, Jack Cooney also mentions that whilst this is nothing particularly new - it plays into their obvious value proposition - a reduction in manpower and time.
On something like a 10x Cash adjusted earnings, the disparity with current growth and potential future adoption seems too good to ignore. Hopefully a future (and current) growth share still being priced as a value share.
Somero Enterprises Inc (LON:SOM) (I hold) is now sitting on its 200dMA which might act as support.
On many metrics Somero Enterprises Inc (LON:SOM) is ranked very highly by stockopedia so it’s hard to understand the logic behind such a sharp price move. However Mr Market is not rational in the short term (but is over the longer term) so maybe this is a buying opportunity?
Somero Enterprises Inc (LON:SOM) was one of the highly ranked AIM growth shares discussed in a previous thread. It also qualifies for the Greenblatt screen. These 2 combined lead me to believe this is a buying opportunity.
On Somero Enterprises Inc (LON:SOM), I think its just reflective of the current status of the smaller cap market. These have been selling off for the last month, and it appears pretty indiscriminate across almost all sectors. Most that I own, or are on my watch list, are down 20-30% from their highs.
Morning all,
I see the sell off in some small caps is still ongoing, Rbg Holdings (LON:RBGP) and Somero Enterprises Inc (LON:SOM) two to fall for seemingly no apparent reason. Looking decent value now...
I don't hold either.
Indeed, some steep sell offs that IMO isn't justified. Topped up on Time Finance (LON:TIME) today. TNAV at c30p and just released in a press release that invoice financing side of business is booming.
Revolution Bars (LON:RBG) is on my list as well to top up.
Last week bought into Fulcrum Utility Services (LON:FCRM) where they issued a solid update due to the share price collapse. And it hasn't recovered yet.
Many shares now just above my buy target price and I've got about 35% cash so as much as it pains me to see the rest of my portfolio take a clobbering, I'm going to take the opportunity to go more fully invested this week.
Just looking at Time Finance (LON:TIME) myself and scratching my head as to the share price. Looks very decent value.
Polar Capital Holdings (LON:POLR): Results look decent 65% increase in core profits, assets under management up tad over 12%, Interim dividend increased from 9p to 14p,
They are gradually branching away into other areas from their flagship technology and healthcare funds, Richard Leonard was keen a while back on this in one of his interviews on PI world.
There is also a huge amount of mergers and take overs going on in this sector and they will probably make a good fit for one of the larger players at some point in the future.
Be interesting to get Jack or Paul's thoughts if they have time seem to remember both have been positive on the stock in the past.
Although it has grown at H1, Equity Development today still expecting a fall in EPS from 65p last year to 58p last year which I think reflects higher performance fees benefits last year.
I like Polar Capital Holdings (LON:POLR) but am a bit nervous about its high US tech stock exposure as I think that market is looking a bit frothy (although it has for some years now). I think this exposure makes the market a bit nervous in giving Polar Capital Holdings (LON:POLR) a higher rating.
Polar Capital Holdings (LON:POLR) does have a lot of cash so some nice acquisitions could help add more shareholder value.
After its TS, Frontier Developments (LON:FDEV) is now in your Mkt Cap range of up to £700m.
Frontier Developments (LON:FDEV) on sale at 30% off this morning!
Frontier Developments (LON:FDEV), 37% now, looks overdone to me. Will it bounce back like Avon Protection (LON:AVON) and Naked Wines (LON:WINE) did?
Re: Frontier Developments (LON:FDEV)
Price drop is being driven by small retail trades but there are some very big institutional purchases this morning at levels well above current low - perhaps more to come when the price stabilises. One slow game release on PC - while performing fine on console - does not a bad company make.
Stupidly, I slept past the news and market open this morning so am bag-holding at these lower levels instead of trading out higher and going back in at the lows. You snooze, you lose.
Well the future release of Warhammer is going to create stonking cash flow for years.
for Frontier or GAW, or both?
Both
Frontier Developments (LON:FDEV) on sale at 30% off this morning!
Or: Overinlated Frontier Developments (LON:FDEV) falls due to missing revenue targets and downbeat forecasts?
Revenue now forecast at £100m to £130m, down from £130m to £150m due to lower than expected sales of Jurassic World Evolution 2 and Elite Dangerous: Odyssey.
Games developers found remote working problematic during the pandemic, so we now have a backlog of games which has started to come to market just as people are starting to go out more. So lower demand spread among more products = lower earnings.
Good company, but it'll take time for this to unwind across the sector.
timarr
Frontier Developments (LON:FDEV)
With this company i am probably more interested about the future than this year. So will be interesting to see if the hatchet stretches into 2023 FY ref broker forecasts? (i suspect this may be the case)
Note they are advising today they are being prudent ref downgrades - fair play to the company if they are now ensuring a line is drawn in the sand here - perhaps there is hope that the outcome may not be so savage as the news now may be if they his the low number?
Based on the lower initial PC sales noted above and the under-performance of Odyssey
in the financial year to date, we are prudently updating our revenue guidance
for FY22 to £100 million to £130 million
I missed the runup on Frontier shares from the pre 1000p days - as i didn't quite have the confidence that their stream of projects was guaranteed to provide at least one big payday each year. I would say what they have added is probably now sufficient base for me to be confident to invest here - if we say they now have 5 streams being Jurassic World Evolution, Planet Zoo, Planet Coaster , F1 management and Warhammer: Age of Sigmar. I would still like to see them pushing forward reference brands though as i would much rather they have 10 than 5 - presumably economies of scale applies. Perhaps they are doing quality over quantity - which i guess can't be all bad.
I suspect the time to buy in here may be when the news is at its worst - that might be today if they are just being over prudnet with downgrades now ? I think though personally i am in no hurry to jump in now. Note shares are now over 50% off the peak so certainly starting to look interesting.
Frontier Developments (LON:FDEV) could be a takeover target, we have already seen two UK game developers, taken over in the last year, must be looking cheap compared to US companies.
Warhammer 40K Daemon Hunters game is likely to have more interest than the Age of Sigmar game. It's a bit of a 1990s/early 2000s command and conquer style game though so may have limited appeal.
Frontier Developments (LON:FDEV)
With this company i am probably more interested about the future than this year. So will be interesting to see if the hatchet stretches into 2023 FY ref broker forecasts? (i suspect this may be the case)
And I suspect not, but it takes two to make a market. I held both Codemasters and Sumo when they were bid for and remain very interested in the sector as a long-term proposition- but the pipeline of new games is bulging. Look at any developer and they'll list an exciting new lineup. There's only so much money to go around, and if it's spread thinner we'll see quite a few more warnings.
This is yet another case of a company that did brilliantly out of the pandemic seeing a fall-off afterwards - Boohoo (LON:BOO), Cmc Markets (LON:CMCX), Purplebricks (LON:PURP), £ASOS, Ao World (LON:AO.), Best Of The Best (LON:BOTB). The list goes on and on.
Despite this most of these companies are in a much better position than they were two years ago - but investors do like to predict current earnings rises infinitely into the future.
timarr
I do wonder how much of the sales issue is down to the imposition of maximum 3 hours gaming per week by the Chinese government? Tencent is a large shareholder and reseller.
Frontier Developments (LON:FDEV)
Thats a pretty good point neils - it seems like they are running into a few headwinds at present. Probably doesnt help that there has also been a general selloff of software related stocks (do they qualify??) - think that is inflation related worries- don't quite get how that hits software stocks particularly but hey ho. Certainly dropbox is coming back on my buying radar in that area - shame i can't buy as many dollars as i could do a month ago.
Like clockwork from £FDEV. Investors Chronicle tipped them four days ago.
What do you think of the shocking announcement from HOC (Hochschild Mining Plc) today?
Re. Hochschild Mining (LON:HOC) , other than being nationalised/confiscated without compensation, the threatened action by the Peruvian government is about as bad as it gets for their two mines there (of three in total with another in Argentina), hence the 50% fall in the company’s share price. Even if they have a watertight legal case it will take time and money to fight their corner so unless this is cleared up quickly by the politicians involved back tracking its a pretty mortal blow to the company’s prospects. Peruvians shooting themselves in the foot maybe (45,000 jobs potentially affected) but no succour for shareholders. Ugly. No position.
https://www.stockopedia.com/sh...
Gus.
Re Hochschild Mining (LON:HOC) - this kind of out-of-the-blue news is a perfect example of why portfolio diversification is important. I have a small holding in this (rather smaller now than yesterday, although it has bounced quite a bit since this morning). A similar thing happened to Acacia Mining (LON:ACA) a few years ago getting hit with a ludicrous tax bill in Tanzania. In this sector, it's sensible not to have too much invested in any single-country operation...
My honest opinion if you want it is that I think it was always going to come to a head with an incoming Communist Government. The Civil Service anywhere has been an ideal home for Communists to slumber at while awaiting the chance to come out and wreck.
I expect Hochschild Mining (LON:HOC) mines will reopen in the fullness of time under Chinese control.
https://worldcrunch.com/world-...
Hochschild Mining (LON:HOC) it would help if you gave us a bit more than just 'what are your views on it'.
Check https://uk.advfn.com/stock-mar...
Hi Paul. I seem to remember a comment from some time ago that you were intending to go on a Saga cruise. Is that correct, and if so when might you be going? If it is indeed the case would be very interested in your feedback given the recent Saga weekends. Regards.
Hi Tango99,
I decided to defer my SAGA Rhine cruise at the last minute, because I've been doing so much travel in Sept & Oct, that decided I really wasn't in the mood for another trip, so rang them up and asked if I could defer it.
Yes, absolutely no problem, even though I was meant to be setting off just 2 hours later on the Eurostar, to travel to Amsterdam. They asked for a £100 cancellation fee, which I thought was perfectly reasonable in the circumstances.
Also, the resurgence of covid in Europe irked me a bit, as I like exploring places on my own, which you can't do at the moment - it's organised tours only, or you have to remain on the boat, which doesn't appeal to me that much. I'd rather wait until the spring, when hopefully we should be in a better position.
As regards SAGA shares, as a long-term investment, I'm happy with progress. H1 results were fine in the circumstances, and the second refinancing recently now means it's sitting on a massive cash pile, with all the debt on long maturities. So I don't see any funding risk at all. As we saw in previous lockdowns, the insurance division continues to generate enough profit & cash to offset the losses in travel division, so it's far lower risk than the market seems to believe.
Sir Roger has just bought £1m of shares too, clearly intended as a signal to the market. The share price is ludicrously volatile, but that really doesn't matter to me, as the fundamentals look fine. But as we know, the market is full of traders, who buy & sell stuff on a very short-term horizon, so the latest wave of covid in Europe is bound to panic a few traders.
Regards, Paul.
Saw their star holiday for the week emailed to me was 4 weeks in Madeira for the price of 3. Thought you might still be there, taking advantage of everything included in a Saga holiday on land, including the 24 hour free bar, including international brands.
Hi Tango, i have just returned from a 5 day cruise on Spirit of Adventure and will make some comments.
This was my first ever cruise I am 63, single, male and interested in trying a cruise.
I had booked a Superior Single which was very comfortable and a great balcony .
The ship seemed pretty full rumour was around 800, the ship interior is new and well laid out it does not take to long to get a grip of the layout.
As a shareholder I felt concerns about profitability as the cost of Covid protections must be
epic, truly epic, but this would be the same for most cruise lines sailing out of Southampton.
I paid £2300 for a 5 day cruise to 3 ports Amsterdam, Bruge, Cherbourg and one day at sea
I was surprised at how much was included in the price as when i disembarked I did not have to pay any extras . All house wine is included, some tours, some Spa facilities,Wifi, gratuities, coffee, hot chocolates, tea help yourself. I highlight these as people on board were telling me that on other lines these can be charged for depending on your deal.
I felt too that Saga onboard should stop wasteful spending, the amount of letters sent to my cabin over 5 days amounted to 15, each with an envelope which went in the bin x 400 cabins
thats a lot of waste.
Saga have an onboard cruise desk and as I have had trouble contacting Saga direct I went to see the desk to ask about future booking , possible single tours, river trips ocean cruises etc
and was surprised that the desk only dealt with Ocean Cruising and did not have access to other Saga products. When i said that I might be interested in this Xmas New Year river trip
the desk went on the normal website?
Overall the cruise was very good, Cabin 10/10 Food 7/10 i tried all 5 restaurants,
Entertainment 4/10 Facilities 9/10 the Promenade deck is great.
Would I return to cruising? not sure I prefer touring being confined was odd.
Hope this helps
Paul
Paul (Scott) and Manbre (Paul), many thanks for the SAGA feedback.
manbre, I've been told the European river cruises are very regimented - more like a floating coach trip. So if you don't like being confined then they might not be for you.
Oxford Metrics (LON:OMG) CEO, Nick Bolton, outlines their accelerated growth strategy at their recent Capital Markets Day (19.10.21). A superb overview of what they've achieved to date, with annual shareholder return of 21% pa over 5 years; and, their strategy going forward to grow their total addressable market from £150m to £650m, to grow revenue 2.5x by FY26, with 15% pa net profit growth over time.
Fascinating tech, today, used in healthcare, entertainment, defence, and engineering. Here they outline their growth ambitions to roll out to wider markets, through both organic growth and acquisition and through partnerships. Video & podcast.
Nextenergy Solar Fund (LON:NESF) interim results November 2021. NAV £607m (20:£584m); cumulative total return since IPO 46.4%; gearing 44%; 7.16p divi target; divi yield 7%. Video & podcast.
Separately, interim results tomorrow for £IGR. Register here for the webinar with Paul Fineman, CEO & Giles Wilits, CFO on Tuesday 23rd November, 1pm.
Next week we have Tpximpact Holdings (LON:TPX) interim results. Register here for the webinar with Neal Gandhi, CEO & Oliver Rigby, CFO, on Thursday 2nd December, 11am.
Finally, we've bought forward the next Stockopedia/PIWORLD StockSlam to Wednesday 19th January, 6pm. Register here to hear 10 private investors each share their best investment idea in a quick 3-minute pitch.
Ahead of the Hostmore (LON:MORE) IMC meeting tomorrow. I thought I would share some historic news - the TGIF where Charles Dickens worked, so to speak, has closed.
Hostmore will be featured on MelloMonday tonight as we are looking at the demerger in detail https://melloevents.com/mellom...
Haha, love it! I should point out that the closure of the Covent Garden branch of TGIs (or Fridays as they like to be known now) was flagged in an investor presentation some time ago. It was loss-making, and cannibalised sales from the flagship branch in Leicester Square, so this is a positive move, and was planned, so not a surprise.
After this, there are hardly any loss-making sites left, and the ones that are left are either pending disposal, or are new sites that are building up business from opening. Fridays has got a remarkably clean store portfolio actually. Maybe they'll show this slide in the IMC presentation tomorrow?
Regards, Paul.
Presumably most know this and I should have done, but I’ve just discovered that a wide range of TGI Fridays food is being sold in Iceland stores. Some of it is described as “NEW.” Guess margins are fairly tight? Maybe this side of their business will get covered in their Investor Presentation tomorrow.
Signs now that the falls for ELTA and MORE shares might have hit bottom?
Angling Direct (LON:ANG), likely that the ICO will be issuing a fine of some sort if the customer data was not held in accordance with data compliance policies like GDPR.
Only time will tell, but the payment data being held by a third party positive, but also potentially highlights an opportunity for Angling Direct (LON:ANG) to improve margins if they modernise their existing payment processing stack.
Gut feeling from me is that the ICO wont come down hard on small businesses that genuinely attempt to protect their customers data, there are much bigger players with little or no control and the £20M cash is a solid position.
There will of course be increase IT spend over the next period to remedy and enhance IT defences against this kind of attack, possibly including the purchase of Bitcoin as a risk mitigation activity.
Seems like most of the bad news is out on this topic.
re £ANG There will of course be increase IT spend over the next period to remedy and enhance IT defences against this kind of attack, possibly including the purchase of Bitcoin as a risk mitigation activity.
This puzzles me - are you saying they would buy Bitcoin so they have some on hand ready to pay future ransomware extortionists? Or is there another reason I am missing?
If you have time would love to read your thoughts on CNIC. I hold.