Small Cap Value Report (Mon 22 Oct 2018) - FCCN, SDRY, SFE, D4T4, IGP, Share Options, CER, GFIN, CML, CSSG

Good evening/morning, it's Paul here.
I'll be writing this week's SCVRs, with Graham also chipping in some extra sections on Tuesday.
Book recommendation
I hope everyone enjoyed the wonderful, mild & sunny weather over the weekend. I've been sunbathing on my terrace (in late October, this is madness!) whilst immersed in a great book, "Open Secret", by Stella Rimington, the retired Director General of MI5. It's a fascinating, and at times highly entertaining book - I recommend it to you.
Clothing retailers
This very mild weather won't be helping the embattled clothing retailers though. They really do need a cold snap in Sept/Oct, to get the sales moving of heavy & more expensive winter ranges.
As we know the whole sector is struggling, apart from online-only operators such as ASOS (LON:ASC) and Boohoo (LON:BOO) , both of which have reported excellent trading & growth this year.
Shares in Superdry (LON:SDRY) hit an all-time-high of £20/share in Jan 2018, but have since plunged to only 733p. I had a look at the figures & profit warning last week, and came close to dipping my toe in with an initial purchase. However, a forward PER of only 7.4 tells me that the market is expecting a further downgrade. It does look as if it may have another profit warning in it.
SDRY's profit warning here on 15 Oct 2018, blamed forex hedges, and warm weather for a lowering of profit expectations, saying;
... the summer and autumn to date has seen unseasonably hot weather conditions in the UK, Continental Europe and on the East Coast of the USA. Critically, these conditions have continued through into September and the first half of October and have significantly affected demand for autumn/winter product, particularly sweats and jackets, which account for around 45% of Superdry's annual sales.
The Sunday Times reported that the co-founder, Julian Dunkerton, wants to return to sort out the business, which he sees as on "a completely wrong path". I wonder if there might be some activism in the offing, to oust existing management?
I'll be keeping an eye on this.
(this section was written on Sunday evening)
French Connection (LON:FCCN)
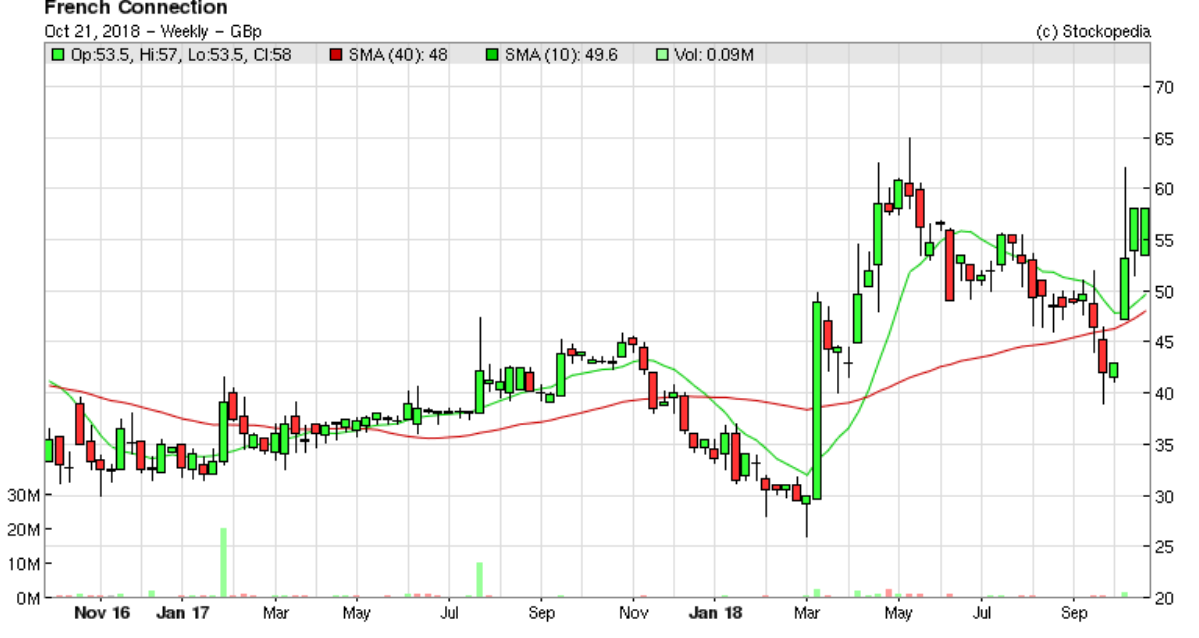
Share price: 58p (up 10% on Friday)
No. shares: 96.4m
Market cap: £55.9m
(at the time of writing, I hold a long position in this share)
Strategic review update - formal sale process
This announcement was issued after hours, at 4:45pm on Friday. I think it's likely to stimulate more interest in the shares in the coming week. The "for sale" sign went up, which I reported here on 8 Oct 2018.
The latest update said;
Since the announcement of 8 October 2018, the Company has commenced preliminary discussions with four interested parties and has had conversations with several other interested parties regarding the Company's plans...
The Takeover Panel has relaxed some of the rules to allow interested parties to remain private.
My opinion - I like the competitive nature of a formal sale process. FCCN received an unsolicited approach from an American bidder last year, but that fell through ( we were not told why). So I imagine they're likely to be back. I speculate that another interested party could be BestSeller, a large European fashion group, which bought Toast from FCCN recently, for a healthy price.
In my view this is a very nice each-way bet. FCCN's own working capital supports most of the market cap. Plus it is on track to move into profit this full year. Plus, it apparently has 3 heavily loss-making shops, which will disappear in the next 2-3 years on lease expiry.
By my calculations, this should mean (together with some cost-cutting), that FCCN could be a £5-10m p.a. profit business in 2-3 years time. Bidders may well have other ideas to focus on developing more lucrative licensing revenues. Plus FCCN's wholesale division is doing well.
The downside risk is that the share price goes too high, and bidding interest comes to nothing. Any business is only worth what someone is prepared to pay for it. Personally, I'm hoping for 100-200p as the final outcome here, but there are a lot of uncertainties. So it's little more than guesswork at this stage, until one or more bidder reveals their hand (or walks away).
Safestyle UK (LON:SFE)
Share price: 73.75p (up 31% today, at 08:34)
No. shares: 82.8m
Market cap: £61.1m
This double-glazing group is today's top percentage riser, hence why it has caught my eye.
If you recall, previously Safestyle had a dispute with some renegade former management, who set up on their own as SafeGlaze. Or, "Pat Butcher's lot", as one witty reader here quipped (because Safeglaze employed the former Eastenders actress Pam St Clement in its TV adverts). Although quite why anyone would be influenced in their home improvement decisions by an actress playing a big-hearted former prostitute, is beyond me.
A very unusual deal is announced today - a 5-year non-compete agreement with Mr M Misra. He will also be providing unspecificed services to Safestyle, and will be handsomely rewarded if targets are met;
Subject to satisfying the strict terms of the agreement the consideration will take the form of an allotment by Safestyle to Mr Misra of four million ordinary shares of 1 pence each in the capital of the Company (conditional on admission to trading on AIM of such shares) (the "Shares") and a payment of cash consideration of between £nil and £2.0 million (the "Cash Fees").Both the allotment of Shares and payment of the Cash Fees, if any, would only be made in Q4 2020.
NB this seems to be an agreement with one individual, and not with Safeglaze as a company. On checking Companies House, Mr Misra resigned as a Director of Safeglaze on 3 Oct 2018.
My opinion - clearly Safestyle regard Mr Misra very highly, to offer him a potentially lucrative deal. Perhaps he's bringing a team of successful salespeople with him? I don't know, that's pure speculation on my part.
It seems a pragmatic solution, to bring back (presumably) high performing staff, with a generous, performance-related pay deal. However, this also reinforces the lack of competitive moat for double-glazing companies. It's pretty easy for anyone to set up in competition, and eat your lunch, if you're making good money in double-glazing.
Safestyle appears to be on the mend, although whether it can get back to its former high levels of profitability, I'm sceptical. After debacles with this share, and with Entu (which went bust), personally I wouldn't touch any double-glazing company share ever again. There's no moat, it's highly cyclical, and often selling practices can be questionable. It's pretty obvious from events here that key staff are not likely to be loyal either - therefore good profits may not be sustainable. That's a fairly horrible combination of features for investors.
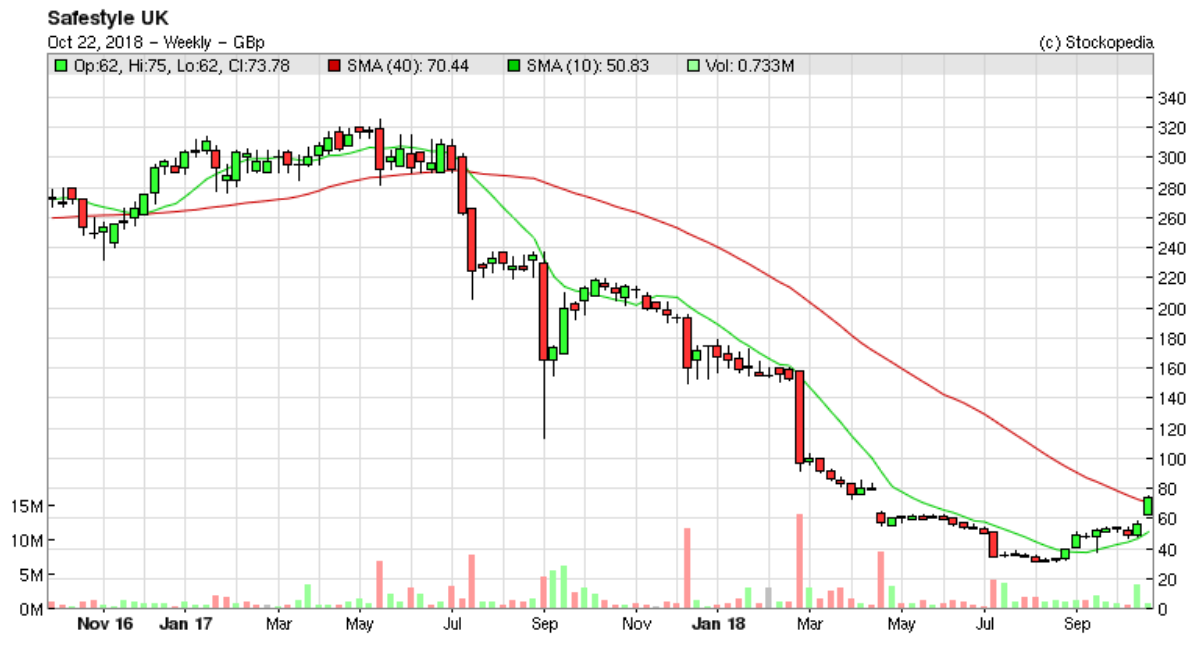
As you can see from the 2-year chart below, there were about 6 stages downwards in the collapse from 320p to a low of about 32p a couple of months ago. Anyone who managed to time their purchase at the lows was just lucky, in reality. How can anyone possibly predict at what level a falling knife will bottom out at? They usually bottom out at a level far below what people initially imagine. Hence why I try to avoid falling knives these days, having got so many wrong in the past!
D4T4
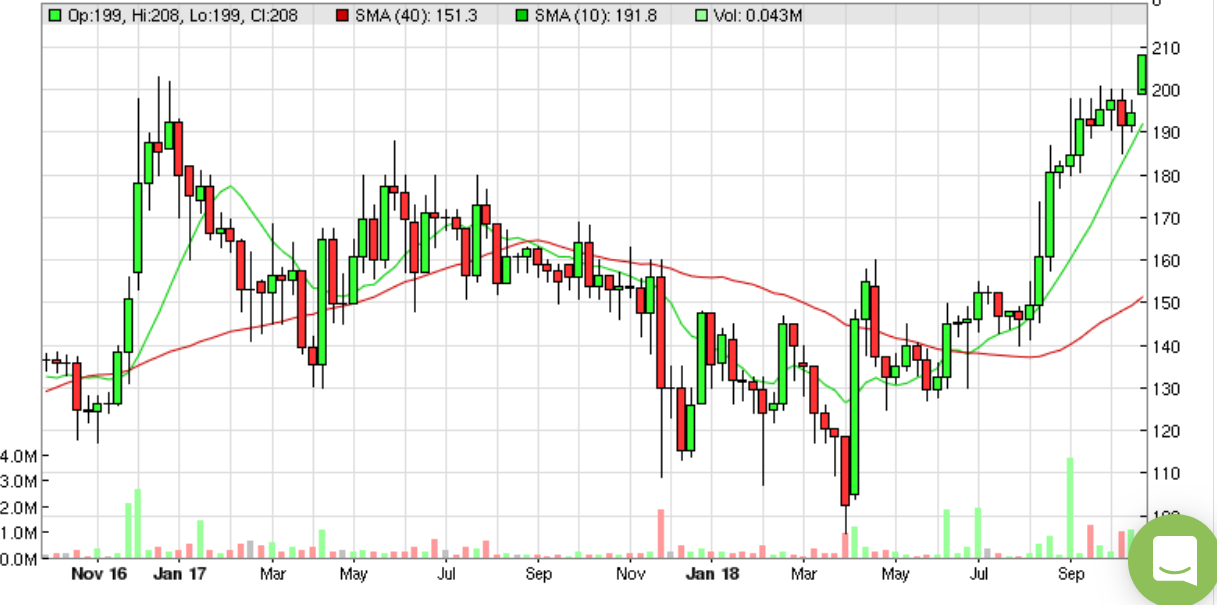
Share price: 207.5p (up 6.7% today, at 09:15)
No. shares: 38.1m
Market cap: £79.1m
This company describes itself as being;
specialists in data platform solutions
I've not got the foggiest idea what that is. Something to do with software, I think?
The company has a 31 March year end, so today's update covers H1, to 30 Sept 2018.
This (below) sounds pretty good, slightly above expectations, to translate from PR RNS speak, into plain English!
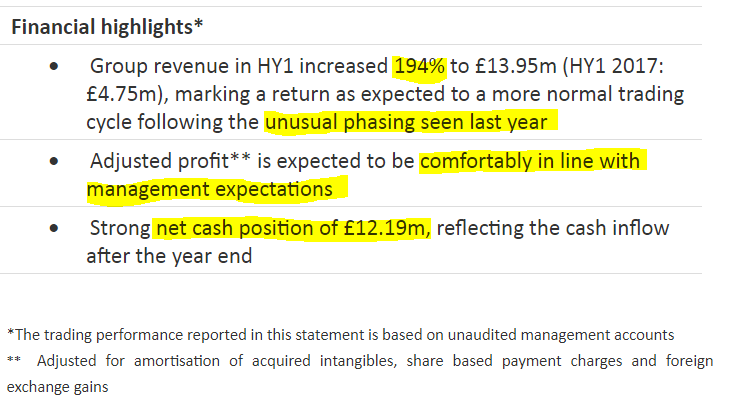
The net cash position sounds very strong - with it being material compared with the market cap.
Outlook comments are upbeat;
Based on our organic business, recent business wins and the depth and quality of the pipeline we remain confident about our prospects...
...Overall, our business is in a good position and together with a strong pipeline of opportunities makes this an exciting time for the business. Combine these with the people, skill set, and the flexibility to keep moving forward, we remain confident of delivering on management expectations for the financial year."
Valuation - there's an update out this morning from FinnCap, the house broker. The tone suggests that an upgrade could be on the cards, as the company has already achieved 60% of full year forecast revenue.
Adjusted EPS of 11.9p is forecast for this year. With the potential for forecasts to be raised, then we should probably see this as a conservative number. A strong H2 could see it achieve maybe 13-15p EPS? I'm inclined to use that sort of range to value the share, which would imply a PER range of 14-17. I like to use a range of forecasts, since predicting future earnings is imprecise. The probability of forecasts being raised, or lowered, is also a key point to consider with all shares. Things look tilted towards the positive side here.
My opinion - I need to do some more research on what the company's product is, to understand it better.
Performance has been very lumpy in the past, giving rise to a volatile share price. It is also rather illiquid.
On the back of today's update, this share looks to me as if could be worth a closer look perhaps?
Intercede (LON:IGP)
Share price: 26p (unchanged today)
No. shares: 50.5m
Market cap: £13.1m
(at the time of writing, I hold a long position in this share)
I wouldn't normally comment on this type of thing here in the SCVR. However, executive remuneration is a hot topic at the moment. Especially since the appalling greed displayed at Persimmon (LON:PSN) , where the CEO got a £75m bonus - basically for being in the right place, at the right time. A booming housing market, fuelled by Government policy (Help To Buy scheme), resulted in a bonus scheme paying out far more than intended.
This is incredibly damaging for social cohesion, in my view. The major shareholders are to blame. The golden rule for all bonus schemes, is that there has to be a cap, to limit the maximum payout to what is reasonable. Otherwise, unforeseen consequences can kick in.
The obscene Persimmon bonuses, essentially funded via the taxpayer, are even more galling, given that the share price has been practically in freefall lately. So Persimmon is probably the worst recent example of a poorly designed, and inappropriate bonus scheme for Directors.
Today I'm highlighting below what to me, is the opposite - a really good incentive/reward scheme for Directors, from Intercede (IGP).
Strike price - Intercede has granted share options to its CEO & CFO, with a strike price of 27p - being roughly in line with the current share price. This is as it should be. Options should reward for creating upside on the share price. Therefore the only fair and reasonable way to do this, is to make the strike price at or above the current share price. Nil cost options, in particular, are appalling - why should management get free shares?!
Long-term - the exercise date should be at least 3 years from now. In this case, the exercsie dates are from 3 to 10 years. This is justified, since it's locking in (hopefully) good management. Therefore the dilution from the options can be justified, as it prevents good management from jumping ship to a competitor.
Stretch targets - this is the bit I really like. Bear in mind that Intercede's share price is currently only 26p. Look at these share price thresholds for the options to kick in;
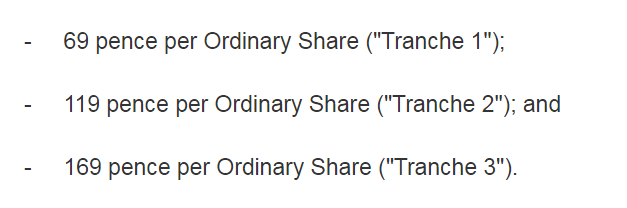
I'd be delighted if just tranche 1 is achieved. If tranche 2, let alone tranche 3 kick in, then I'll be on my stepladder putting out the bunting, and shouting "champagne for everyone!"
What's interesting is that management must think these share price targets are achievable. Otherwise there would be no point in signing up to this scheme. Although a word of caution, in that this type of scheme can be used as a publicity stunt, to ramp the share price - Elon Musk and Tesla springs to mind as an example.
A more positive example is Geoff Wilding at Victoria (LON:VCP) who has benefited hugely from a similar scheme of stretch targets for the share price. This handed him a large percentage of the company. However, I imagine other shareholders were more than happy with the arrangement, as it enriched all shareholders overall, despite the big dilution.
Funnily enough, I was asked recently by a listed company Director, what sort of management incentive scheme I favoured. My answer was that I like stretch targets for the share price, based around options, set at the current market price. Although such schemes do carry the risk of management doing something reckless, e.g. taking on excessive gearing, to try to achieve a higher share price, and blowing up the company in the process.
Modest dilution - I think there need to be very special circumstances to justify over 10% dilution from share options. Personally, I'm not really happy with potential dilution of over 5%. As in many cases, I see management incentive schemes as being double payment, for just doing their job (that is usually handsomely rewarded already). Do bonus schemes really incentivise & trigger out-performance? I doubt it very much. I think they just tend to pay out randomly, depending on where we are in the economic cycle.
For this reason, if we have to have share option schemes, then I'd like to see them be relatively modest. Intercede ticks this box for me also;
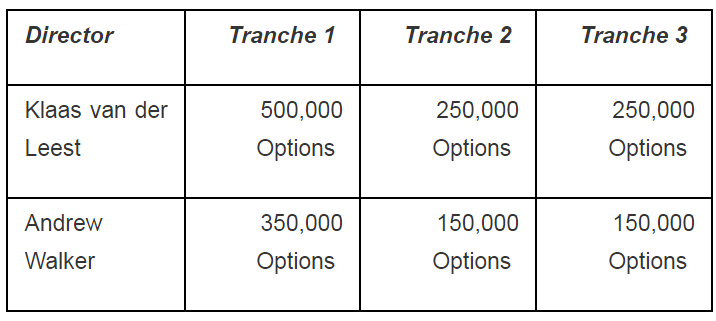
Today's announcement confirms that total potential dilution is still reasonable;
Following this grant, there are a total of 2,062,500 Options outstanding, representing approximately 4.1 per cent. of the current issued share capital of the Company.
Overall then, I think the above points are a good test to decide whether a bonus/share options scheme is reasonable, or whether the Directors simply have their snouts in the trough?
So my key tests for management incentive schemes are;
1. Strike price of options should be at, or above, the current share price
2. Options should reward good long-term performance, and lock in key Directors
3. Vesting should be dependent on achieving stretch targets, ideally based on the share price (with safeguards to prevent management wrecking the balance sheet)
4. Maximum dilution should be modest - ideally no more than 5%. Or, in special cases (where management is genuinely indispensable) then possibly higher
5. There must always be a cap on the maximum possible payout, if a cash bonus scheme is put in place
If readers can think of any other useful points on this topic, then please add a comment below.
A few snippets to finish off with;
Gfinity (LON:GFIN) - diabolical figures are revealed in a trading update for the year ended 30 Jun 2018.
- Revenues of £4.3m (up 82% Y-on-Y)
- Adjusted EBITDA loss of £12.6m! (H1: £7.4m loss, H2: £5.2m loss)
- Cash of £3.7m at 30 Jun 2018, down to £2m as of today.
Good job then that another placing is announced today - to raise £6m (before expenses) at 8p per share. This doesn't look anywhere near enough to be safe, given the high cash burn.
My opinion - it's not a sector I understand. The figures are so bad, and the cash worryingly little (even including the placing today) that this looks extremely high risk to me. Good luck to shareholders, I hope you know what you're doing.
Cerillion (LON:CER) - in line update, for y/e 30 Sep 2018.
Outlook comments are upbeat;
Trading in the second half of the financial year has been very encouraging, well supported by new orders. The Company is advancing with contract negotiations with major potential new customers, and its new business pipeline, including the range and quality of opportunities, remains very positive.
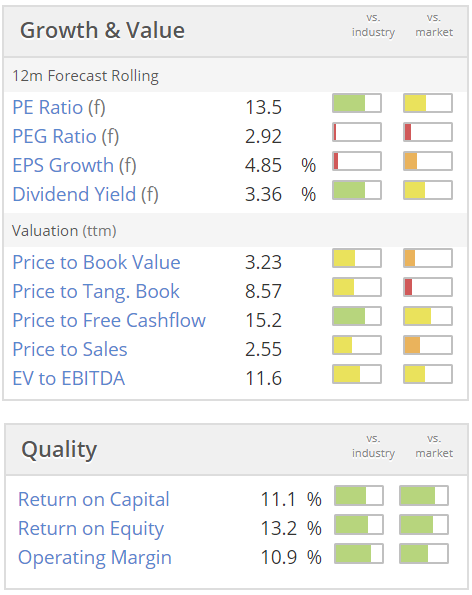
A quick look at the Stockopedia valuation section makes this look good value. I seem to recall that Graham likes or liked this one. Could be worth a closer look perhaps?
CML Microsystems (LON:CML) - trading update for the 6m to 30 Sep 2018.
It's in line with management expectations.
The Board expects to report unaudited half year results comprising Group revenue of £15m, pre-tax profit of approximately £2.3m, and adjusted EBITDA of approximately £5.1m. The Group had net cash of £13.5m at 30 September 2018 following the dividend payment in August.
Like many other small caps, it's come off about 20% from the highs earlier this year.
The valuation looks about right to me (based on the StockReport), but this is not a sector I understand, so I could be wrong!
Croma Security Solutions (LON:CSSG) - cracking figures issued today. The share price is unmoved, probably because the commentary says that the year benefited from some large, exceptional projects that are unlikely to be repeated.
At £15m, it's too small for me - am trying to avoid very small, illiquid stocks, unless it's something absolutely outstanding. The problem is, you can't sell them when you want to, very often, unless it's a tiny position size. With all the political & economic uncertainty out there, I think it's better to stick to more liquid stocks, so that there's an exit route available, if necessary.
OK, all done for today!
See you again in the morning.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
re. safeglaze. pauls comment If you recall, previously Safestyle had a dispute with some renegade former management, who set up on their own as SafeGlaze. Or, "Pat Butcher's lot",. my dad was fortunate to cancel cheques with them as company has gone into administration. https://www.thetelegraphandargus.co.uk/news/17191282.more-than-130-jobs-lost-as-bradford-double-glazing-firm-ceases-trading/
"How can anyone possibly predict at what level a falling knife will bottom out at? They usually bottom out at a level far below what people initially imagine." Couldn't agree more.
Re - Share Options - Many sensible ideas mentioned here.
As Graham recently found out (or struggled to !), the option targets etc. should be more readily available - see Tristel (LON:TSTL) on Wed 17th Oct SCVR. Ideally with examples on what would be needed for the beneficiaries to receive some (25% ? 50% ?) and the full amount of any incentive.
One annoyance, I recently came across was why/how option and warrant details can apparently change without any notification or shareholder agreement :
From this 31st July RNS:
https://investegate.co.uk/evr-holdings-plc--evrh-/rns/exercise-of-warrants-and-issue-of-shares/201807311646123725W/
To this correction 3 days later:
https://investegate.co.uk/evr-holdings-plc--evrh-/rns/exercise-of-warrants---issue-of-shares-correction/201808031640038359W/
Somehow 51m warrants have been extended by 7 years !
Thanks Paul, as always an interesting read.
Here's a Cerillion (LON:CER) investor presentation from Mello earlier this year. (I think they'll be at Mello London too.)
Helps to get an insight to management and their business model.
https://www.piworld.co.uk/2018/06/27/cerillion-cer-investor-presentation-at-mello-south-june-2018/
Hi Paul, thanks for a great report. I too thought the options announcement at Intercede was good news and if I understood it properly, I think those targets have to be hit within three years although the holders can exercise the options for some time afterwards. I also get the impression that new management are playing things cautiously in terms of their communications and revenue guidance so I think this tells us that management are confident.
I’ve been a shareholder a long time here. Intercede started off working with smartcards but it’s their ability to put the credentials, including the authentication and cryptographic keys, onto smart phones and to reside within the chipsets that may be important in them being able to reach a much wider customer base. I think they’ve also been working hard to build the key partnerships to go to market in wider areas.
Here’s hoping.
Best wishes, Andrew
For Croma Security Solutions (LON:CSSG) holders, the company also posted its report and financial statements on its website. Always worth looking at the notes IMO.
Great post on Management share options Paul.
Personally, I'm almost always against them. For me they are little more than management giving themselves another slice of the pie. They already get a very generous pay packet as well as a bonus, I'm not quite sure why they should deserve more. If the first two don't motivate them, why will the share options?
I would add the caveat that I have no objections to share options if management are truly exceptional or the company/SP have been on a great run.
But, all too often they are given out to all and sundry at incredibly generous strike prices, or even nil cost, and management then just sell them. That in itself is hardly a vote of confidence in the company's long term prospects or managements motivation. It just screams greed.
Then to round it off it seems to be the fashion of the day the exclude these payments from profit figures. Effectively management help themselves to an extra slice of the pie and would like us to just agree to pretend it didn't happen.
The Intercede (LON:IGP) options do seem very fair but almost every other example I can think of is overly generous to management and often based on KPI's that are all too easy to manipulate or meet.
I do like management who have a stake in the company they work for, but why should they be given it rather than having to buy it like the rest of us do!?
I may be alone here, but it's just snouts in the trough for me.
£D4t4
Surprisingly little discussion on this one. We had some debate here, maybe 6 months ago at around the 120p level, so the share has done well since then. It seemed to be a bit of a "marmite" stock as for some reason last year they had the dreaded 2nd half weighted skew that makes even the most ardent supporter nervous!
I bought some around there following full year results and had pencilled in 190-200p as a target but am revising that upwards after todays update.
Data analysis (or end to end lifecycle management) is a big component of todays digital world and something many companies do not do well, or even really understand the mechanics. Hence, it is a space I can see growing and doing well for a while to come yet. Probably with some consolidation thrown in at some point so I'm not ruling them out as a bid target either.
Trading update today was excellent. As Paul says looks like it is warming us up for an earnings beat of some 10-15% whilst retaining optionality for an in-line if things tailed off towards y/e. That would put it on 13-14p eps. However, it has almost 20% of market cap in cash, so if you strip that out it is really trading on 11-12* PE multiple. Feels a bit miserly for a business with 15-20% eps compounding growth. I'd have thought a fairer rating was 15-18 * cash adjusted? What's that, somewhere between 235p & 290p?
Anyone else have any context or views?
David - I like £D4T4 to, not least because it was one of the few shares that held up during the recent sell off, leading me to think that it is still good value. I topped up this morning and with an 5% lift today it seems others have too..
Safestyle UK (LON:SFE) - I held this some time ago so watch with interest. I don't get it how they can let the former owner snatch the business, then correctly take at least partially successful legal action against the new company but then go back to the former owner and offer him up to 4 million shares and £2M cash to help them sort out their problems. I wouldn't touch it with a barge pole although had I done so a short while ago I could evidently have doubled my money!
Great commentary on remuneration.
I always struggle to know how to vote on this so your guidelines will help a bit. To be honest I almost just feel like voting against all of them. Almost all policies look generous to me because I just can't believe that half decent people need these incentives to do their job when loads of people make a good effort just for their salary.
One practice I'd like to see would be holding the newly awarded shares in trust for maybe 10 years, with any dividends paid out possibly, with the ability to reclaim the shares in the face of a major setback in price. You could argue for it to be a company specific set back but frankly if price falls are not the fault of management, are price rises to their credit? This system based on EPS would be better, and it would stop directors just selling their shares which most of them seem to do.
So, in summary:
Less generous
Much longer term
Make them have more of their wealth tied up in the company for longer - should focus the mind a bit!
I second that re your very good review of what management incentives should be based on, remembering they are also getting significant salaries for doing a good job in the first place, something that is frequently forgotten! You should be offering a bespoke service to many BOD Remuneration Committees.
As I think you say re social unrest etc, it is particularly important that remuneration is regarded as FAIR and FAIRNESS is critically important to the future of this country as never before. The opposite of/alternative to a fair Tory run economy which most of us are convinced is the best,/least undesirable system of management of the economy is socialism and frustration may well drive the UK into the hands of Labour and JC. For example, I hear reasonable people say 'nationalise the railways' out of frustration, not because they have thought it through and KNOW that it will be better - cheaper, better service - under Labour nationalisation, just that anything must be better than what they are having to put up with - whether it is largely the fault of the current government-owned element of the railways - Railtrack - and their disproportionate contribution to the recent timetable fiasco - or the union-driven cancellations using safety as a job-supporting mechanism on Southern and Northern, even though the industry bodies say guard-less trains are safe. As always, the 'anything must be better than this' is so frequently proven to be a fallacy.
I have been the subject of a significant loss in SP for Playtech (LON:PTEC) over the last two years, where it was one of my most profitable shares, and has become one of my worst performing. Over this time, the Remuneration Committee have blatantly ignored the shareholders at 2 consecutive AGMs. The latest AGM in May,18 those shareholders started to put their foot down but they are very reluctant to hit the red pedal and go above the 50%. The first in May 17 was a one-off payment for the CEO of £1m. The latest in May 18 was a backdoor rise of £60k a year for a Chairman who has presided over a SP fall of 55% in the last year and 45% since that AGM. Oh dear. Whilst this isn't the most publicised company versus the likes of Persimmon (LON:PSN), it reflects the same malaise - in this case, rewards for failure, versus £PSN's CEO's unwarranted 'reward' for success he has only partially contributed to.
At the risk of being accused of spreading fake news, I would like to make the following comments on Safestyle UK (LON:SFE). I did spend quite a lot of time talking to a significant employee who has since left the company after a string of unfulfilled 'promises' probably not unrelated to the recent decline of the company, changes in management etc.
(By the way, this person is not one who bears grudges; he has been in this business with various companies all his working life, accepts it is a really nasty industry with extremely unpleasant, sometimes dangerous competitive practices - 'cutthroat' is used advisedly - with little or no company loyalty, and that is the way it is. that person had a job to go to the following week at a higher salary than he was being paid so he left and is getting on with his life after Safestyle UK (LON:SFE), personally disappointed with the person who attracted him to the company, but as I say not bearing any grudges.
Mr Misra was the largest shareholder and founder of Safestyle UK (LON:SFE) which came to the market in 2013. Mr Misra immediately sold out of his share of the business as part of the IPO process and left the business. My source told me that there appears to have been an agreement between Mr Misra and the company (probably through Mr Birmingham whose reputation has most recently been tarnished by admitting late last year that at the time of the IPO he bought shares in the company with an undisclosed loan from Mr Misra, but with strings attached. That loan and its implications were admitted by Mr Birmingham at the end of last year, who I understand has since left the company.)
My source says that the agreement would be that Mr Misra would not compete with Safestyle UK (LON:SFE) for an agreed period of time following the IPO. Surprise, surprise then - Safeglaze was set up at round about that time with the aggressive marketing (to say the least) since then which has hit £SFE's operations so hard. Within the company, it appears that the aggressive competition went far beyond marketing, with the stealing of IT records - customer records etc - and that they were used to get business. Significant numbers of staff were poached (or fired?) at that time too. The data were also used to undercut and 'slag off' £SFE's offering and service. When the new management came into Safestyle UK (LON:SFE) recently and injunctions etc started to fly around, Mr Misra appears to have departed stage left (ie left the country) to pursue other interests. Now he reappears as the guy who can really pull the strings at Safeglaze and be handsomely paid for taking the heat off Safestyle UK (LON:SFE). All of this is of course unofficial - the official bit came out in the court cases - but as the journalist often says, I have considerable faith in my source. I leave it up to the contributors on this site to come to their own conclusions; make comments; and hopefully add content of relevance to this sorry tale.
The thing that puts me off French Connection (LON:FCCN) is I don't see its products for sale anywhere. For a while at the start of the millennium FCUK was everywhere, though the joke wore out there must be millions of moderately rich middle age males who see that and smile about the memories of nights out etc. I tend to buy clothes from brands like Ted Baker, Meyer, Tommy Bahama, Superdry - not cheap but not too expensive for everyday work and social wear. So, shops like John Lewis and HoF and other men's outfitters are where I tend to get my threads. I cannot remember the last time I saw FCCN products on their racks. Is the style wrong, the price wrong - why aren't they capitalising on their brand recognition? Seriously, how can they fail this hard?
This mini rant inspired me to look at their website. There was literally nothing I would want to buy. It seems they're targeting expensive clothes at a demographic with limited funds - the complete opposite of BooHoo, who target cheap clothes at young people, and the opposite of brands like Joules who target expensive clothes at 30+ middle class people.
Any purchase of FCCN shares would purely be a play on gambling on the takeover. I'm going to watch this one with interest from the sidelines..
Hi Igotpoesjacket,
French Connection (LON:FCCN) isn't really about menswear, which is only a small part of its sales.
The womenswear is much more successful. So you need to ask women what they think of FCCN product. I've done that a lot, and they usually react positively about the styles, and brand image, but think it's too expensive.
Although interestingly, it's because the product is seen as expensive, and aspirational, that the company is able to make good profits from its brand licensing division.
Anyway, it doesn't really matter what any of us think about the product, as it's the numbers that matter!
Onerous lease expiries in the pipeline, mean that the company is set to move into profit shortly. So even if bidding interest comes to nothing, patient investors should do alright whatever happens. If it remains independent, then a resumption of divis is on the cards.
Regards, Paul.
French Connection (LON:FCCN)
Thanks for the insightful reply Paul. Interesting point about the womenswear. On reflection, in a vacuum you would want the menswear division to play on its brand power but I can see an argument where targeting clothes at "dads" destroys the desirability of the brand in the core young female market.
I note that their products are significantly more expensive than Sosandar (LON:SOS) , which gives me more confidence that the criticism some people have of them having no sizeable market is completely flawed (especially as I think Sos customers are female me, bit of spending power and like nice things)..
It's an interesting story - good luck with the holding, hope the PIs get a nice outcome :)
Paul,
Re French Connection (LON:FCCN) I am a happy holder but disagree with you when you say
"patient investors should do alright whatever happens. If it remains independent, then a resumption of divis is on the cards"
I think it needs to sell to change the management decision maker (ie Marks). Without him gone, yes divis will resume but at low levels and the brand will likely slowly fade away as eventually his energy/vision will fade but there are no signs he can work without being completely dominant. The share price will follow so NOW is the moment.
That said, my model says the business can be worth 140-180p /share on a 10-12 PER within a couple of years to someone who can chop central overheads by 30%, exit all/most retail leases and concessions (some may be very profitable or worth it for awareness/branding ie as an advertising cost) and drive the wholesale/ecommerce business.
As previous commentator, Ashley with a 27% share has a spoiler role but a big enough offer will tempt him (or ALL other shareholders) to sell out or to see enough to make a winning bid himself.
I hope and believe Marks (and Ashley) will get a big payday north of 100p by mid-2019
Croma Security Solutions (LON:CSSG) results were out today, look very good. Rev. up 59%, PBT up over 500%, EPS up over 400%, shares initially up 9% but now down 4%, am I missing something here?
Herbie, I wonder whether the outlook is too guarded - they do indicate that recurring revenue is very good, but there is some emphasis on the one-off contracts in the year just ended which, by implication, may not be repeated. I hold small number of these... but I'd probably want to wait for an AGM update before accumulating any more.
Andrea
Thanks Andrea, Yes there does seem to be some large one-off contracts. Outlook a bit reserved. I am tempted having missed out before, shares are now less than in February, yet EPS is about twice the forecast.
Croma Security Solutions (LON:CSSG) i think it is also perhaps the nature of the business - where they just provide ex-forces security to businesses - therefore its perhaps not a very exciting or scalable business. I could be wrong here - just trying to understand the lack of follow-through on the share price, also due to illiquidity, limited institutional trading, low volume.
financially - it looks great, its performing well, numbers are good, management seem competent, working capital is being well managed. I think two things might help - more analyst coverage, perhaps also a targeted acquisition if they have aspirations of becoming a larger group.
i hold - but cautiously.
Hi Paul
Will you get a chance to discuss the meeting you had with MYSL management a week or so ago?
All your insights as welcome as ever!
Best regards
Hi Ajay,
Unfortunately, I couldn't make it to the MySale (LON:MYSL) meeting in the end. Sorry about that.
I got positive feedback from a friend who did attend the meeting though.
Regards, Paul. (disclosure: long position in MYSL)
Two announcements this morning from Gfinity (LON:GFIN) which I read in reverse order.
The second was the announcement of placing and subscription.
75m new shares (26% increase) @ 8p. Although this was first announced today it has clearly been “in the price” for a few days.
My initial reaction was that this is probably a signal to close my small short. (Continually dilution is a key factor in the underperformance of these “pre-profitability” situations).
But then I saw the earlier announcement : Trading Update.
Revenue up 82% at £4.3m, although as MrC points out this is a big miss vs the forecast £6.9m and with £1.8m in the first half, this doesn’t look a particularly aggressive ramp up.
LBITDA improved in the second half from £7.4m in H1 to £5.2m in H2 (so LBITDA of £12.6m for the year).
This is before the positive impacts of various new deals etc kick in (these new deals all sound quite “shiny” – but I don’t believe there has been any financial disclosure on any of them).
So what is the outlook?
That is a very woolly phrase, but suggests to me : not this new FY, not next FY, but at the earliest FY ending June-2021!!
If that is so then I believe that there is a substantial risk that still do not have enough cash to get them to break-even. The placing was “to support the next phase of development” - no reassuring words there about being now fully funded to break-even.
I honestly have no idea about the viability of this business, but I think It very much still deserves the label “sucker stock” and I will keep my small short running.
If the business succeeds, I suspect that the key beneficiaries will be those investors participating in the NEXT fundraising, less so existing shareholders.
Any thoughts Graham on PCF ? The target of £350m loan book by 2020 must be redundant now as they should hit the target many months before. Azure alone would get them a good way towards that figure. With the loan book well ahead of forecast, what about the eps forecasts ? Surely time for an upgrade ?
As mentioned before, the Oxford Street lease is to be surrendered in January 2019. What are the other two large stores that are such a drain on income?
Re French Connection (LON:FCCN), although I am a holder, I do wonder if the current ownership acts as a brake on a sale for 'full' value. Anyone who wants to buy Mr Mark's holding of 41% must bid for the whole company. However with Mr Ashley's 26%, a bidder must in effect negotiate with Mr Ashley at the same time. Does this in practical terms mean that Mr Ashley is the only potential successful bidder ? It depends, I guess, whether Mr Ashley regards his holding as a tradeable investment or down payment on ownership.
Just musing
The way I see Mr. Ashley's stake is that he has a win win. If he can get the company for a good price, he'll buy it and already got a significant portion of it even cheaper.
If he can't get the company for a good price, it means he's able to sell his 26% stake for far more than he believes its worth.
In either case, he wins and the rest of the shareholders win.
Or so I think, but of course. I could be wrong and It'll be interesting to see how this pans out in the end.
Safestyle could be worth some coverage. The market likes the update.
Is this basically a backdoor acquisition of Safeglaze? On current trends if business does not increase they might have trouble paying this £2m. And it seems to be not much barrier for someone else to compete...
I used to own based on the Stockrank but felt their tactics were a bit shady and potentially ripe for regulation.
My morning smallcap tweet:
Safestyle UK (LON:SFE), Forbidden Technologies (LON:FBT), Gfinity (LON:GFIN)
Safestyle UK (SFE) bungs Mr Misra, who started rival Safeglaze, 4m shares and up to £2m to not compete with SFE for 5 years. It's subject to performance conditions by Mr Misra to Q4 2020 and Safestyle's trading performance in 2019 being above existing market expectations.
Forbidden Tech (FBT) FD leaving. He is generously thanked.
Gfinity (GFIN) Guides FY rev up 82% at £4.3m They don't admit it but that a hge miss of £6.9m F/C.
I got into FCCN at 62p. Hitting damn near close to the peak. It's been quite the journey since then. My position is very small (currently valued at a mere 988 pounds). As my name signifies, I'm new to stocks and educating myself with a few small positions.
The way I see it, this process is either going to significantly boost the share as you predict Paul or absolutely collapse it. If they have four bidders and all the bids fall through, given that one bid already fell through during due diligence a while back people are going to ask why. The most obvious answer to being, there's something rotten under the bonnet.
So here's hoping there's nothing rotten under the bonnet. Accounting is after all a very creative occupation!
Personally, I'm inclined to think you're correct in your valuations Paul. I don't know much about the retail industry but I read your research (all of it) and I read up on your background. You clearly know the industry well and you clearly did your research. I suspect your valuation will match well with whoever is doing the same job in the take over.
If there are any surprises, I suspect they will be on the upside and come from you under valuing the brand value.
In short. We're either going within or above your valuation (if above, likely due to brand names being highly subjective to value, there's also the FCUK marketing value to consider) or we're going to see one hell of a flash crash when it all falls through.
Either way we're in for an exciting ride.