Small Cap Value Report (Mon 23 Sept 2019) - TCG, OTB, SOS, XLM, BILN, BRY

Good morning, it's Paul here.
Many thanks to Graham for covering last week's reports, which gave me the opportunity to grab a relaxing & enjoyable week in the sun, in Malta - highly recommended by the way, if you've not been there before (sunny, friendly people, low crime, food & accommodation much cheaper than Greek islands, mosquitoes not too bad, interesting history/culture, everyone speaks English, and they drive on the left).
Estimated completion time of today's report - I'm starting early today, so should be finished by lunchtime. EDIT at 13:12 - it's taking longer than expected, so I'll carry on writing this afternoon. Revised completion time, 5 pm. Actual completion time: 23:39 - there we go. Does it actually matter?
Today's report is now finished.
Thomas Cook
Talking of which, the really big story today seems to be that Thomas Cook appears to have gone bust, according to press reports. The BBC is saying it's gone into liquidation (i.e. ceased trading), rather than the more usual administration process (where an insolvent business continues trading for a while, as a buyer is sought for its viable parts).
It's been obvious for several years that the shares were worthless, because the group was very clearly insolvent, with vast, unrepayable debt. However, its day-to-day operations were supposed to have been in the process of being rescued by a bail-out from its major Chinese shareholders.
Press reports this morning are saying that the group has ceased trading with immediate effect, leaving huge numbers of holidaymakers stranded. What a mess. The Government, CAA, etc, are apparently hiring large numbers of charter planes to repatriate massive numbers of stranded holidaymakers. That sounds like a gigantic undertaking, difficult to manage due to its sheer scale.
Here's the 7 am RNS, confirming liquidation.
Let's hope the repatriation process is not too gruelling for its customers. Although I did read an article in the Telegraph yesterday, claiming that Thomas Cook customers in a Tunisian hotel were essentially taken hostage - locked in by security guards, if they refused to pay the hotel directly for holidays they had already paid for through Thomas Cook.
What read-across might there be for other shares? I imagine that TUI AG (LON:TUI) could see positive sentiment, as a major competitor goes bust. Although it depends if any parts of Thomas Cook might continue trading in some form? Sometimes it's possible to save the viable parts of a large group.
Dart (LON:DTG) could be a possible beneficiary for the same reason, as its relatively new packaged holiday business has been growing fast. DTG is on my watchlist as looking attractively good value, for a decently growing business, that appears to be well managed. It's more attractive today, now that Thomas Cook is out of the frame. That's over £9bn of revenues to be re-allocated amongst competitors, if no parts of Thomas Cook are rescued.
On The Beach (LON:OTB)
Share price: 403p (up 6% today, at 13:14)
No. shares: 131.2m
Market cap: 528.7m
Statement re Thomas Cook (profit warning)
... the UK's leading online retailer for beach holidays
I would have thought that OTB would benefit from the disappearance of a large competitor. However, from this announcement today, it sounds as if OTB must be re-selling Thomas Cook holidays, hence is going to suffer some financial fallout from its collapse over the weekend.
... The Board anticipates that there will be a one-off exceptional cost associated with helping customers to organise alternative travel arrangements, and lost margin on cancelled bookings.
The Group expects to be able to recover the costs of the cancelled flights via chargeback claim (as was the case for the Monarch failure in 2017).
This one-off exceptional will be booked in the current financial year.
The Board is currently evaluating the potential effects of the failure on its forecasted performance for the year ending 30 September 2020, and a further update will be provided when appropriate.
That's not terribly helpful, as it doesn't give us anything to go on, in terms of the size of the financial impact on OTB.
My opinion - none, as I don't have any figures to work on.
All we can do is to await broker updates, and a further update from the company in due course.
EDIT: note that the share price initially fell, but has now moved into positive territory. It must be that investors are seeing through the one-off costs of Thomas Cook going bust, and instead seeing a bigger market opportunity for OnTheBeach to grab some extra business longer term.
Sosandar (LON:SOS)
Share price: 17.0p (up 5% today, at 13:16)
No. shares: 162.9m
Market cap: £27.7m
(at the time of writing, I hold a long position in this share)
AGM Statement (trading update)
... Sosandar plc, the online women's fashion brand ...
This is a pleasing update today, if a little over-the-top in how it's phrased.
Shareholders and commentators might be understandably sceptical about gushing prose, because the last trading update on 7 July 2019 sounded so positive, but delivered a bombshell that Q1 sales were only up 23% year-on-year. Whereas the forecasts for this year needed over 100% growth for FY 03/2020. This smashed the share price over the summer.
However, it sounds as if things are back on track. The most important bit is this, which shareholders should find reassuring;
We are pleased with the recent performance of the business, which has been in line with management expectations...
The current house broker forecast is for £9.5m revenues this year, up 116% on last year's actual of £4.4m. Earlier this year, I asked management if their expectations are the same as the broker's, and they confirmed yes this is the case.
Other points made in today's update;
Increased marketing spend, following £7m recent placing (at 15p). Note that Sosandar now has more cash than at any point in the past, so it can afford to really go for it, in terms of increased product ranges & broadening the marketing spend in to new areas like local TV, and tube stations (escalator digital panels)
Autumn season has started well;
The important Autumn period has only just begun but results for the first half of September have been very strong, and midway through September revenue has already exceeded that achieved in September last year.
This is so important. The company has heavy seasonality towards Sept-Dec inclusive. Given that it had a disappointing Q1 (Apr-Jun 2019), partly weather-related, it absolutely has to deliver a really strong autumn/winter season, to stand any chance of hitting the full year forecast numbers.
Management was absolutely adamant in the summer that the ambitious growth forecasts could be achieved, and gave good reasons to justify that optimism - mainly a big expansion of product ranges (in particular new buyers having been recruited to specialise in denim, footwear & accessories). These categories are favourable because they have lower customer returns rates than e.g. dresses, which have high returns due to the more complex fit on different shaped bodies.
We've seen before, e.g. with Asos and BooHoo, that during the early stage growth, expansion of product ranges fed through directly to increased sales growth. So the much wider product range (number of styles is being roughly doubled) for this year's autumn/winter season, should feed straight through to greatly increased sales.
Add in a bigger than ever marketing budget, and I'm reasonably hopeful that forecast growth for this year ending 03/2020 is achievable.
Third party platforms - Sosandar's original intention was to just sell through its own website. However, this year it has decided to sell through third party websites too. That's an extra avenue of growth, albeit lower margin, and makes complete sense.
The increasing product range has also contributed to third party platform interest. Sosandar is now successfully trading with Silk Fred and opportunities are presenting themselves to work with other interested parties...
Watch this space then. Joining one of the big online platforms (e.g. Next), could prove lucrative in the longer term.
My opinion - I'm pleased with this update. I've mentioned this before, but it's a critical point - the initial customer reaction to new autumn/winter products launched in September tends to be a key indicator of how the whole season is likely to pan out. That was my experience from my 8 years working in this sector. If the new product in Sept sold well initially, then I bumped up my full year forecasts. Repeat orders can be quickly placed, for the best-selling lines, meaning that you get two bites of the cake. Sosandar has greatly improved its speed to market, and can get repeat product in very quickly, e.g. 4 weeks, when needed.
Overall, today's update reassures me that things seem to be getting back on track, after a not-so-good spring/summer season. Bear in mind that the interim results (Apr-Sep 2019) are likely to look fairly poor, when they're released. It's the full year figures that matter, as they will include the key Oct-Dec trading period, with a big range, backed by big marketing spend.
The company is still loss-making at this stage, so remains speculative. Although it now has plenty of cash to push for fast growth. As the Chairman of Boohoo (LON:BOO) once said to me - there are no barriers to entry in online fashion, but there are huge barriers to achieving scale. If SOS does reach scale, and moves into profit, then the upside could be very exciting. I'm more confident that is possible after reading today's update.
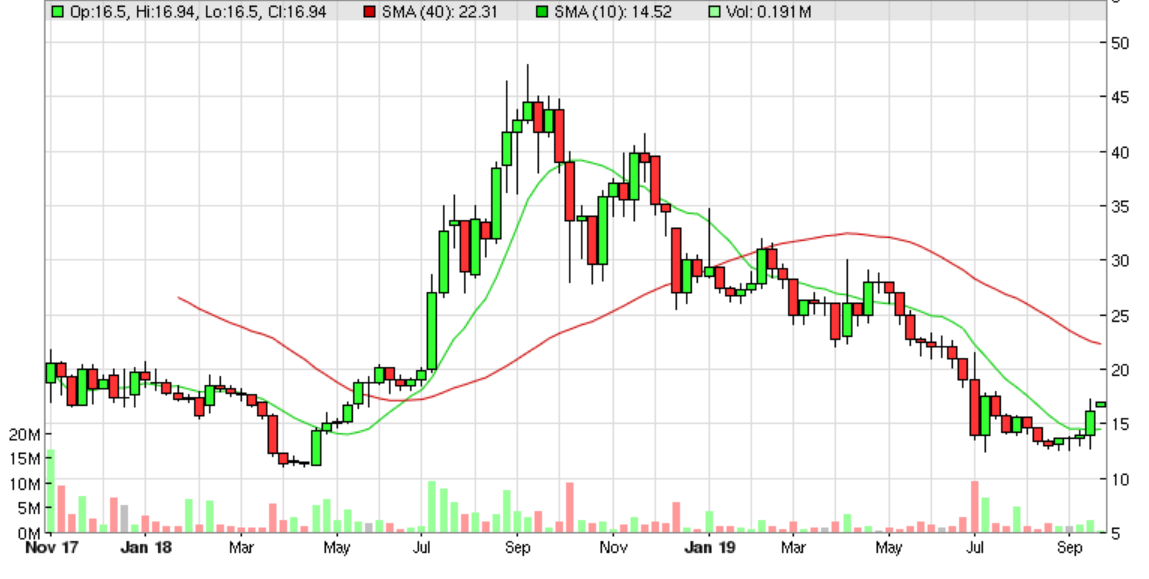
As you can see, it's been a roller coaster ride for shareholders to date, as is often the case for loss-making growth companies. The valuation of such shares is notoriously tricky, as it's based on investor sentiment & expectations of the future. Like a lot of speculative shares, this one tends to overshoot on the upside and the downside, depending on newsflow and market sentiment (which has been diabolical for small caps over the summer this year).
I'm in London today, so will try to get to King's Cross tube station, to take some pictures (assuming that my iPhone is still working - it's acting funny after taking a brief plunge into the bath in a weekend accident) to post here, of Sosandar's adverts on the digital displays flanking the escalators. I could see that working well, given that there are so many professional women going to & from work, that are perfect target customers. Given that one of Sosandar's key strengths is high quality, eye-catching photography (due to the joint CEOs' background in fashion magazine publishing), then this strikes me as a good new route to reach new customers. Tube adverts worked well for BooHoo.
XLMedia (LON:XLM)
Share price: 60p (down 20% today, at 13:25)
No. shares: 206.8m
Market cap: £124.1m
Interim results & full year update (profit warning)
XLMedia (AIM: XLM), a leading provider of digital performance marketing services, announces its unaudited interim results for the six months ended 30 June 2019.
Revenues in H1 are $42.5m, with full year guidance reduced to $80m (implying a further fall to $37.5m in H2). This is about 14% down on the $93.4m forecast for FY 12/2019 shown on Stockopedia (sourced from Thomson Reuters data).
Note this $80m forecast for 2019 revenue is down 32% on 2018 actual revenue, and 42% down on 2017 actual revenues. Clearly something is going wrong, what is it?
Regulation - XLM makes its money mainly from websites that drive customers to gambling websites, i.e. online casinos. The commentary with today's numbers gives a fair bit of detail over adverse regulatory changes in various countries, which have hurt its profitability.
Profitability - despite the large drop in revenues, this remains a highly profitable & cash generative business. The revised guidance today is for $34m EBITDA for FY 12/2019. Note that is a huge EBITDA profit margin, of 42% of revenues.
The key question is whether the still-high profits are sustainable, given the tightening regulatory backdrop?
Dividends - the profit & cashflows are real (whether sustainable, is the key question?), and are evidenced by generous dividends & share buybacks. Despite the profit warning, the interim dividend is actually being raised 5% to 3.1584 US cents per share. Although note that last year's interim dividend was cut by 25% on the prior year. So a 5% rise this year still leaves it well below that of 2 years ago.
Still, the dividend yield (if maintained at say 7 US cents) would be around 9% - very attractive, and the main reason to buy this share.
Balance sheet - this is dominated with intangible assets, so NAV of $161.5m drops to NTAV of $35.1m once we strip out intangibles (Goodwill: $23.65m, Domains & websites: $92.2m, and Other intangibles of $10.57m).
Cash of $40.27m at 30 June 2019 will have dropped by about half due to the £15.7m tender offer buying back 19.7m shares at 80p post interim period end, in August 2019.
At £1 = $1.24, I make that $19.5m to pay for the tender offer, using up almost half the 30 June 2019 cash pile.
With a large cash pile, why does the group also have bank debt of $4.2m?
A new lease liability of $8.76m has popped up in longer term liabilities.
Cashflow statement - looks very healthy. Operating cashflow was a whopping $23.8m in H1, benefiting from the reversal of c.$4m in adverse working capital movements compared with H1 of last year.
The strong cashflows generated are being used to pay generous dividends, and to fund share buybacks.
New CEO starts on 2 Oct 2019.
My opinion - this share peaked at just over 200p in late 2017. It's now only 60p, so disappointing performance has been thoroughly reflected in a reduced valuation.
Despite falling revenue, XLM remains a high margin cash cow, paying a generous dividend yield.
If you think the business has stabilised at lower revenues, or could even recover, then the shares are a bargain.
If you think the regulatory situation is doing lasting damage to the business, then the shares may not recover.
Personally, I've never been particularly attracted to this share, despite the impressive numbers. The reason being that it is one of several Israeli marketing/tech companies where things looked too good to be true. Thus raising the question of how sustainable the high levels of profitability & cashflow would be, in rapidly changing sectors?
The commentary today is open & detailed about the regulatory problems in the online gambling sector. That's the crux of the matter. I think that, in order to form an accurate view on the value of this share, one would really need to do detailed work on the regulatory threats & possible opportunities.
I quite like the fact that XLM has made hay whilst the sun shined re online gaming promotion, hence it must have learned some useful expertise which possibly could be applied to other sectors?
Sosandar (LON:SOS) - advertising on the tube - I couldn't resist the urge to nip to Euston & Kings Cross underground stations this afternoon (as I was in London anyway) to see if I could take some photos for you, of the Sosandar advertising on the escalator digital displays at selected London underground stations.
Incidentally, if you like cycling in central London, which I do, then the relatively new "Jump" bikes from Uber are an absolutely brilliant way to get around. They give an excellent electric assist (much stronger than the competing "Lime" electric assist bikes, which are feeble). Hence one can nip around London fairly easily at 15 mph, avoiding the traditional pitfall of cycling - i.e. turning up at meetings drenched in sweat, which is what tends to happen with normal bikes, especially in summer.
You do have to remember to lock the Jump bike after using it though. I forgot to do this the other day, and was charged £87 by Uber for a 5 minute ride. Some naughty person must have noticed that I inadvertently left the electric Jump bike unlocked, and I later saw from the App that a person unknown went on a 9 hour joyride around several estates in Stoke Newington, at my expense. Uber were very good, and refunded £86 of it to me once I had apologised to them.
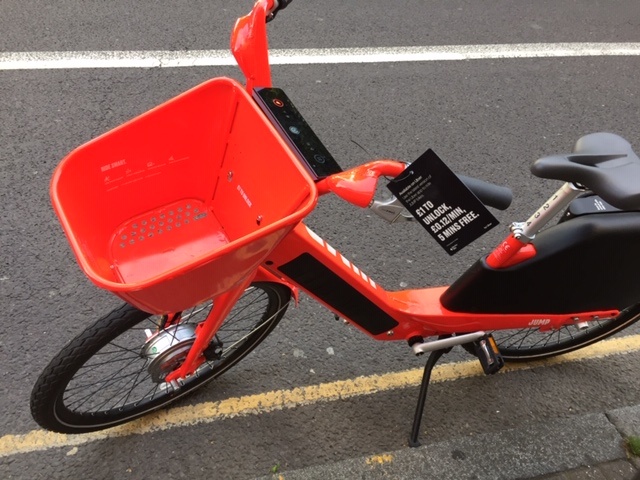
Well anyway, I rocked up at Kings Cross station today, and abandoned my Jump bike (after locking it this time) on a traffic island just opposite the station. Then it was time to take some pictures of the digital advertising displays, and hopefully find some Sosandar adverts. This is how it looked - note how good the new digital displays are, compared with the traditional old style adverts;

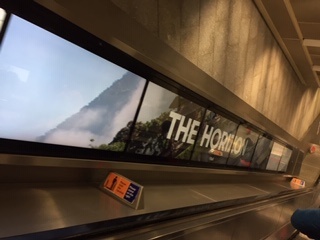

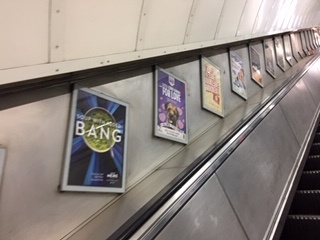
This was all a bit of an anti-climax, as unfortunately there didn't seem to be any Sosandar ads playing (I took these photos at around 15:30). So after several trips up & down the escalators, and starting to get funny looks from security, I decided to visit Euston underground station too, but no Sosandar there either.
A friend did message me recently to say that he'd seen a Sosandar ad playing on the digital displays at Bond Street underground.
Anyway, after a rather fruitless trip out, I needed a lie-down when I arrived home. Hence why this update is a bit late.
I've just emailed Sosandar's PR person, to ask for some pictures of the Sosandar tube ads, as I'm interested in seeing them, and some readers who take an interest in the company might also be.
Anyway, that's 5 minutes of your life you won't get back, so I'd better make up for it by covering another reader request.
Billington Holdings (LON:BILN)
Share price: 333p (up 5% today, at market close)
No. shares: 12.9m
Market cap: £43.0m
Billington Holdings Plc (AIM: BILN), one of the UK's leading structural steel and construction safety solutions specialists, is pleased to announce its unaudited interim results for the six months ended 30 June 2019.
It's over 2 years since I last looked at this company, so am a little rusty on it (geddit?!)
Stockopedia ranks it as a "Super Stock", and a very high StockRank - which are a good start, although obviously not a guarantee of success for an individual share. StockRanks work best for a portfolio of shares, where the results have been superb - hence why a lot of us like the system to help our investing process.
Check out these Stockopedia graphs too, for Billington - everything moving in the right direction, over several years - performance up, but value improving;
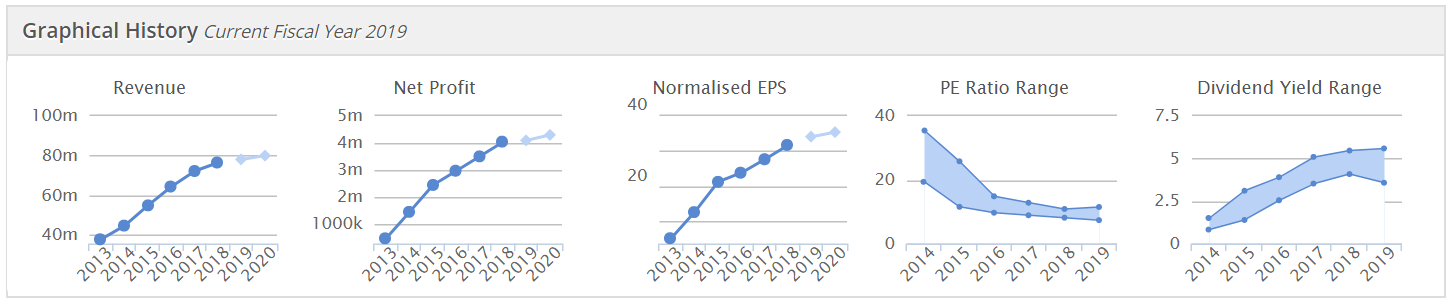
Economic cyclicality is something we need to be very careful about right now. If the economy is turning down (press reports seem to be indicating that business & individual confidence is falling right now), then this could be a bad time to buy apparently cheap cyclical companies, maybe, or maybe not. Nobody really knows for sure.
The financial, and summary highlights to today's H1 results look really good;

(apologies for wonky highlighting - am using my left hand for the mouse these days (am right-handed), in order to reduce RSI)
Outlook - sounds good too;
Prospects and Outlook
The Group has had a very busy and successful first half of the year. Whilst the overall market continues to be uncertain, the outlook for Billington remains positive, particularly given the Group's ability to target both the largest and medium contracts, insulating us, in part, from any temporary disruption in the market.
The Group has gained further large contracts during the first half that will be executed in the second half and into 2020. Our order book remains at strong levels and we continue to see a number of significant prospects and coupled with a healthy balance sheet we are well positioned for the future and remain cautiously optimistic.
In closing I would like to thank Billington's Board, employees, shareholders and stakeholders for their continued support, and I look forward to a busy and bright second half of the year.
Economic cyclicality - the above positive outlook is all great. However, previous economic cycles have taught me that when the economy as a whole rolls over into a downturn, then sooner or later, it affects all cyclical businesses. A strong order book can dry up, if the economy shudders to a halt. Therefore I think readers need to think long & hard about this crucial issue.
Over the last 20+ years, I've bought (and/or not sold) cyclical businesses, at the wrong point in the cycle, believing that they would weather the downturn, only to be caught out by disastrous share price falls some time later, when reality hit home, as order books failed to replenish once the economy really tanked. Hence I'm very wary of cyclicals right now, in a time of considerable uncertainty.
Balance sheet - looks fairly good, but not massively strong.
The £10m in cash is partially offset with £1.6m in borrowings, so that's net cash of £8.4m - good for a company with a £43m market cap.
The current ratio is 1.42 - that's a sound position, but not particularly strong, the way I look at things.
My opinion - if the economy pans out fine, then this share could continue to do well.
The PER of about 9, and dividend yield of about 4% look quite attractive, providing those profits & pay outs are sustainable.
This share can also be very illiquid, hence difficult to exit if something goes wrong.
On balance, I'm not tempted to go near anything this cyclical right now.
A couple of quick snippets to finish off with;
Brady (LON:BRY) - I hadn't spotted the profit warning in August. That's mainly because I formed the view some time ago that it just isn't a very good company, making losses in most recent years.
Interim figures today look pretty awful, as does the commentary about carrying out a strategic review.
The balance sheet looks very weak indeed, with a current ratio of only 0.52 - very low indeed. Although software companies do benefit from favourable cashflows - receiving money up-front from customers, which can enable them to operate with apparently very weak balance sheets.
It still seems to be in a net cash position of about £1.0m - so no apparent risk of the bank pulling the plug.
NAV of £17.2m, less intangibles of £25.8m, means NTAV is negative at -£8.6m is weak, but not necessarily disastrous if the company was profitable. The trouble is, that the company is loss-making, hence it's difficult to see how it can avoid a fundraising, or putting itself up for sale.
My opinion - way too risky.
I'll leave it there for today.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
Re: Sosandar (LON:SOS) So they are losing an extra £1.5Mn this year to generate the (original) sales target of £9.5Mn in FY19/20. Sosandar (LON:SOS) do not break out Marketing spend but I presume the majority of this increased loss is extra Marketing (plus a bit of extra headcount). I estimate they are therefore spending >£3mn on Marketing in total or >30% Revenue. Enough to start to build a brand moat and get out of the no-name competitive swamp.
They do have good evidence the Marketing is working (Sales already >£1Mn in Oct). This starts to imply the newly offered product categories are also interesting to the same target audience . If the stles/skus have doubled, they really ought to be reaching>100% Y-on-Y revenue growth for the next 6-9months which will restore the growth story. The decision to push for growth is thus certainly the right one.
HO costs are relatively low and fixed whilst scale up costs (distribution etc) are outsourced and proportional to sales – so driving absolute GM is the key. With a good margin structure this means driving sales. If they can reach >£25Mn turnover, they will rapidly become very interesting indeed.
However, the period of slower growth without the Marketing support also says that the styling is good but not so compelling or distinctive that word of mouth is bringing in lots of new customers organically ie we are not going to a spike from a sales fad but more a steady build as the Marketing works to bring in (and retain) new users.
Overall then, to me this update says they are back on track towards long term success but that it will be a while before I get my investment back! (I hold – for the long term)
Paul you should ask them for a touchscreen to help in the RSI. Of course, this will mean no greasy chips etc. But, does help and nowaday the screen cost is small.
I switched to a trackball. Seems much better for the wrist. Don't think I'd go back!
I saw the Sosander ads at Waterloo tube station last week and I agree - very striking & appealing. They definitely seem to be spending their increased marketing budget well.
I agree with you that Jump bikes are brilliant. Also I saw the Sosander ads last week at Kings Cross. They were very striking and appealing
Any technical traders here? Be good to get some advice. I have been researching a share and the share price is being suppressed although OBV has increased significantly in the last few weeks and MACD indicator showing upward trajectory after buy crossed the sell couple of weeks ago. The OBV seems disproportionate, I believe the company is a takeover target and don't know if Market Makers are keeping the price down or something else is going on. I normally invest based on business strategy / positioning and P&L - so I normally just look at technical indicators as an added value versus main view. But think this is telling me something interesting. Be good to understand what the above means and if it is just normal.
I would recommend regressing the flimflam against the whippyscotch and only buying once the hopdoodle finally turns a sunward gaze
Thanks for that. I hope you feel all big man now.
Phil - it would be good in future if you gave the name of the company. Clicking on your name and seeing recent posts it may be IGG, If so why do you think market makers are keeping the price down. It has gone up by about a third over the past three or four months. Would the market makers please keep the prices of my shares down in a similar way! In my opinion charts should only be used to support a decision made based on other factors. The chart is now at a resistance point. Will it carry on going up or drift down. Who knows!
thanks for your response. It’s Staffline, and it’s been on my list for a while as Paul mentioned the 29.9% which I knew before it was posted on here. But I’ve been biding my time as normally suppress the share price further to 1) Buy it cheaply / make the bid price more attractive to get a slam dunk or 2) get in when it’s in distress. Like I said I only look a technical analysis as an add on. Trying to think if there’s something fundamental happening underneath via the volume of trades...
1 Mines are outside my circle of competence and there are other sectors I need to learn about first.
2 I perceive a problem with incentives. If a mining company has a very large capex project which may take years, with marginal economics, there might just be a temptation to underestimate the costs to get the initial round of funding away. Then everyone is on the gravy train for a few years and with some luck, the economics for the incremental funding look better when production is nearer. Of course, I could not say if any company does this, but it is difficult to believe there is not an incentive to get the ball rolling in this way.
rwalford - are you on the "new" site and could this be the reason why Burford Capital (LON:BUR) doesn't show as you expected (I'm sticking to the old version).
Currently ploughing through the 46 pages of Fair Value Accounting "explanation".
I think you're spot on with mining incentives. There is a lot of institutional drive to underestimate costs and get projects going.
Interesting paper by £BUR about their Fair Value Accounting principles on their website. Worth a look.
Edit - I mean Burford Capital - no idea why that has not shown up as it is meant to.
I know this is a bit off piste but what about Sirius Minerals. Is 4p a buying opportunity? I think so and have bought a modest holding to hold for a few years. All that stuff won't be left in the ground!
https://www.standard.co.uk/business/business-news/after-sirius-minerals-how-to-avoid-the-next-disaster-a4241221.html
All that stuff won't be left in the ground!
That maybe so but that doesn't mean Sirius will be the one's to extract it, or for that matter, that shares in Sirius are worth more than 0p.
Si
cafcash.
You could well be right that the Sirius mine will get built, BUT very high chance current shareholders will be wiped out. So anyone buying Sirius’s shares now should be prepared to risk total wipe out. There is a chance of a very dilutive equity fund raising, but surely a strategic partner is more likely?
Most likely could be a strategic partner with deep pockets. e.g a sovereign wealth fund (Qatar sovereign wealth fund already an investor).
But that would mean future gains from their project (Sirius ambitious estimate is $30 billion by 2030) will end up in foreign hands, instead of U.K. getting the full benefits. This happens so often with brilliant UK projects.
from what I can determine on Sirius Minerals (LON:SXX) the principle lender concern is around certain higher risk capital items. This is broadly the sinking of the mine shaft and certain aspects of the tunnel. Reading between the lines (and I could be wildly inaccurate here) my suspicion is that the JPM facility for $2.5bn was predicated on the bondholders taking the risk on the capital items. ie that the terms of the facility were structured in such a way that they could only be drawn on certain development milestones being achieved, in this case the mine shaft and tunnel. I am therefore a little circumspect that market conditions were the excuse rather than the cause.
However, on the plus side, if that is correct, then some of the broker notes I have seen suggesting that a £500m raise is needed to unlock the full finance package might well be right. I suspect a strategic investor and/or an equity raise might well achieve this as there are a number of very well capitalised and incentivised parties involved.
There is no guarantee of that of course. This failure has damaged management credibility and the government flip flopping between support doesn't help either.
On Thomas Cook read across...I notice that £AIR is up +6% today. They do aircraft chartering - so perhaps not a coincidence. Air Partner could benefiting from Government, CAA, etc, hiring large numbers of charter planes to repatriate massive numbers of stranded holidaymakers. I hold £AIR :-)
Now back to reading 50 pages on £BUR Fair Value accounting!
One thing that irritates me about Thomas Cook (LON:TCG) is the management. Harriet Green did a great job of turning around the company. Since she was ousted this incumbent lot have been in place for around 5 years. In that time they have presided over a company that has gone from a positive net cash position to bust, whilst at the same time having the benefit of operating a very strong airline business. They have persistently talked up the strength of the business, which feels misleading. I remember watching a recent results presentation where the CFO talked about how much experience the CEO had etc and how the airline was attracting very strong bids!! Heavens above, really?!
Most importantly though, the directors compensation for such abject failure has been huge! Tell that to employees at risk or holiday makers and it's bad enough. Tell that to shareholders who have seen huge value destruction over that 5 years and it must feel borderline criminal. Worse still, what jumped out at me in his apology was that he appears to have apologised to pretty much everyone apart from the shareholders who trusted him to run their company, unless I missed something! That would show an unbelievable arrogance in my view. Company directors are only in that position as a steward employed to run the business to the benefit of the shareholders. They should not be well rewarded for screwing it up. I feel as though too many directors, especially those in "management roles" (ie no real shareholding %age in the business) now appear to have forgotten their real function and this case just highlights a requirement for some level of change in shareholder approach around remuneration.
(for disclosure I have held in the past on a few occasions and to be fair have lost more money in this share than I've made)
Paul - any chance you could comment on French Connection and Staffline.
Hi myayield,
Paul - any chance you could comment on French Connection and Staffline.
Disclosure: I hold long positions in both these shares.
French Connection (LON:FCCN) interim results - I was hoping for more of an improvement in H1 trading, but the explanation given (phasing of wholesale orders into H2 this year) is perfectly reasonable. Mgt commentary is very straightforward here, Mr Marks tends to tell it how it is. Good outlook for the full year, and it's a heavily H2-weighted seasonal bias every year. Bulletproof balance sheet remains, and valuation continues to be nonsensical, given that it should be modestly profitable for the full year despite £10m in retail losses. The sale process - at a guess, it sounds like there must be some interest, but possibly not at the sort of price Mr Marks wants to achieve?
I think waiting 6 months could be a nice 100% profit from the current price, so am very happy to hold, and buy more when funds permit. 30p or lower is an absolute steal, in my view.
Staffline (LON:STAF) - profit warning is obviously annoying, but my main reason for holding this share is the high likelihood of a takeover bid from its 29.9% Singapore shareholder, which paid 160p & 180p recently for the bulk of that stake. Hence my money is on a 180p full takeover bid in the not too distant future. The profit warning might help in that regard, by making a 180p bid appear more generous compared with a new, lower, 112p share price post profit warning.
As always, DYOR, this is just my current view, which is subject to change at any time.
Regards, Paul.
PIER - Trading for the Group during the important first two months of the current financial year - July and August 2019 - met budget. Consequently, we remain confident of our prospects.
Stocko says "Brighton Pier has an Z2-Score of 0.74. This indicates a serious risk of financial distress within the next 2 years."
Luje Johnson is Chairman with a 22.6% holding.
XLMedia (LON:XLM)
One extra piece of information ref this company is that the main man Ory Weihs seems to have stepped aside as CEO (July) and is now reduced to performing a non exec role. I am not sure exactly to what extent he has cashed his chips in over the years but the fact that he is loosening his ties with the business around the time it is struggling most is probably not a good sign.
XLMedia (LON:XLM)
This is a share I have paid attention to over recent years having twice made a lot of money on the run up from below 100p to 200p and then recently on the increase from 50p to 78p. I don't hold at present. I was a bit sceptical a few year's ago when Ory sold a very substantial holding through another entity he was connected with. He then made some re-investments but nothing like the amount he had cashed and the company then raised money from institutions at I think around 180p.
The company are suffering because of regulatory issues in Europe but are hoping that a very substantial opportunity for business in the US will more than cover this. I would have thought that there would be any number of tech companies in the US who could get in on this field if they saw there was money to be made. I don't know what web names they use to attract business but unless they are names that punters are likely to be easily able to search and find they are at some risk from how Google rate their sites. You can be top of the list for searches one day and then unexpectedly relegated! Paid adverts on Google can be prohibitive.
Looking at their balance sheet out of total equity of $161M they have domains and websites $92M, goodwill $23M and other intangibles $10. Websites need continual updating and a smaller company would be required to amortise the cost over a period.
If you were to buy this you would be hoping for an eventual share price of far more than double what it is today. I would wait until it was back up in the 70's following better news. I don't think it is going to go far for now.
According to H.L. Ory Weihs owns 5.6M shares with a couple recent purchases
07 Jun 2019Weihs, Ory CEO Regular purchase transaction421,052.00 £0.46 £193,683.92
07 May 2019Weihs, OryCEORegular purchase transaction 392,156.00 £0.51 £199,607.405
02 May 2019Weihs, OryCEORegular purchase transaction 297,029.00 £0.50 £148,514.50
19 Nov 2018Weihs, OryCEORegular purchase transaction 84,761.00 £1.04 £88,151.44
XLMedia (LON:XLM)
The recent purchases are true and one of the reasons I re-bought at around 50p. I thought a gain of 28p in a few weeks was enough for a trade for which I would not have allowed any downside. It is also true that Ory has made many other purchases over the past couple of years in addition to those you list.
My comment regarding sales goes back in time to 02.02.17 for £3,973,333 and 28.03.18 for £3,821,407 both incidentally at low prices to where it subsequently went. At least one of these sales was put down to a disposal by I think a partnership in which he had an interest.
Perhaps I am being unfair to Ory as he had no need to reinvest anything. For myself it is not the time to re-enter. For me better news is required in the future to make me reinvest.
Yes, I also bought in a couple of months at around 51/53p level and did very nicely selling out at the time of the 80p share buy-back. The stock was featured in the SCSW newsletter before the buy-back, which helped to accelerate the share price northwards.
I bought in today for two reasons 1) the fundamentals, cash-backed, good divi at this price level. 2) as a longer term play on the potential of the US betting market. (The other share racing ahead in this niche is GAN - I don't hold.)
You're correct to sound caution, as I notice a subsidiary CEO sold his entire share holding of 500K during July/Aug this year.
The subsidiary CEO you refer to, is that Inbal Levi? She was relieved of her duties and maybe that affected her judgement in selling out???
XLMedia (LON:XLM)
According to H.L. Ory Weihs owns 5.6M shares with a couple recent purchases
I guess the relevant question here is how much of the company did he own at his peak holding? - i would pay a lot less attention to £0.6 million share purchase if he had sold £50 million worth of shares previously than i would do if he has always had a smaller holding. I think he previously did have a much higher shareholding (indirectly perhaps) but i don't know for sure.
If he knew he was resigning as CEO some token repurchase of shares to show faith in the company might be seen to be a tactical ploy perhaps ? to say "look i still have faith in the company prospects"
XLMedia (LON:XLM)
Well he sold £7.8M of shares and has subsequently re-bought getting on for £2.4M in 22 (!) separate purchases over the past 18 months. He probably does think it is very cheap at the current price but many of his past dealings do not seem to indicate that he has much idea of which way the price is heading! As I have indicated why would anyone rush to buy until there is better news than the last two months being a bit difficult.
Paul - Billington Holdings (LON:BILN) if you get time please. Useful profit increase and almost a quarter of its Market Cap as cash.
XLMedia (LON:XLM)
I have been keeping an eye on this since it entered the bargain bucket category a while back, its difficult so estimate how this company will trade going forward , their marketplace is pretty opaque and subject to regulatory and other external issues that seem able to turn of the profits tap.
I was pretty dubious as to whether they could manage anything like their previous profit highs going forward ignoring newly acquired profit streams.
The draw here though is the rock solid balance sheet and the cheap p/e and the fact this business is still expected to make decent profits.
Up to today they seem to have limited the current future damage to the poor trading previously announced around the turn of the year - however todays news is they are expecting further reduction in profits due to poor recent trading.
Last years EBITDA was $43.8 with adjusted profit before tax of $35.1 mill.
They are expecting EBITDA to be $34 mill now - they previous dowgraded i think by $7 mill Feb.
So if i had to guess that looks like its a downgrade of another $3 mill - so something just below 10%.
current year forecasts before today were showing $27.5 mill profit - so lets say $25 mill profit this year - market cap - lets say 60p share price and shares in issue (very estimated) something around 185 mill - = market cap of $140 mill ish. Thats very estimated due to sharebuybacks tender offer etc etc - so pe of about 5.6. That's cheap as chips with strong balance sheet - if you believe profit decline will end - but probably very similar to how the company looked back in January/February?
I am slightly more positive on this share than i was 6 months ago (i knew very little about company then) - as the profit decline has been manageable compared to the worst fears suggested by the bombed out shareprice- although the newly announced drop in profits does somewhat leave us back where we started asking where will the downward trend end - so i will probably sit on the sidelines for now despite the fact that share price could easily add 50% or double or more if the company returns to growth - up to today rebound in shareprice from lows earlier in the year had been very good.
Any chance of a ramble on XLMedia (LON:XLM) Paul another profit warning this morning and outlook statement is cautious would be more interesting from your red flags point of view as i know you have been saying avoid for last 18 months or so.
Thanks
Morning clarea,
Sure, I'll take a look at XLMedia (LON:XLM) later this morning.
Regards, Paul.
Thanks for the write up Paul good to see French Connection (LON:FCCN) ticking up a bit today near the close.
Hi clarea,
Daily movements on small caps don't mean a thing, especially at the moment, with terrible sentiment & hardly any liquidity.
The prices are set by tiny and occasional trades. Bigger investors cannot buy or sell at the moment, in many small caps, so we're really in a largely false market.
All that matters is our eventual exit price. What happens in between buying & selling, doesn't really matter, the way I look at things.
Regards, Paul.
My morning smallcap tweet: Journey's end for Thos. Cook
Thomas Cook (LON:TCG), Sosandar (LON:SOS), XLMedia (LON:XLM), Omega Diagnostics (LON:ODX), Goals Soccer Centres (LON:GOAL), Osirium Technologies (LON:OSI), Escape Hunt (LON:ESC), Seeing Machines (LON:SEE), Keystone Law (LON:KEYS), Telford Homes (LON:TEF)
Thomas Cook (TCG) enters liquidation. I'm short.
Sosandar (SOS) AGM stmt: trading n line with management expectations. Increased investment in marketing and product producing "very good results". Sept rev to date better than whole Sept 18. I hold.
XLMedia (XLM) H1 rev down 0.9. Trading: weaker-than-expected performance in July and August. Blames regulatory headwinds. Guides FY rev ~$80m, adj EBITDA $34m.
Omega Diagnostics (ODX) £1.7m keep-the-lights-on placing at 10p, a 15% discount.
Goals Soccer Centres (GOAL) possible offer of 5p from Sports Direct. Was suspended in March at 27p.
Osirium Technologies (OSI) contract win: license for 2,600 devices over 3 yrs with major UK provider of software and IT services. No £££.
Escape Hunt (ESC) has now signed the contract (see April RNS) with its US franchising partner for USA & Canada.
Seeing Machines (SEE) FY rev up 4% to A$31.9m. F/C was 29.5m. FY20 rev guidance A$45-50m. F/C is 45.7m.
Keystone Law (KEYS) H1 rev and adj pretax up 15%, ahead of expectations.
Telford Homes (TEF) merger cleared with EU, Will delist 1 Oct.
Welcome back Paul. I expect you’ll comment on the upbeat AGM statement from SOS. Could you also look at the results from Keystone Law please? They include a special dividend.