Small Cap Value Report (Mon 24 Feb 2020) - CWD, RCH, CALL, JDG, LOOP, TSTL, AXS, RTC

Good morning, it's Paul here.
Please see the header for the company announcements that I'm covering today.
Estimated time of completion - 1pm mainly, but I might add extra bits after that.
Edit at 13:25 - it's cold & rainy, and I have nothing else to do, so will carry on writing - revised completion time: 4pm
Edit at 15:03 - today's report is now finished.
Worsening coronavirus spread
It looks like we're entering a choppier phase, with futures down heavily overnight. Hardly surprising, given the coronavirus is not being contained, and a global pandemic now looks a distinct possibility, or is already starting.
For this reason, I remain very cautious, and am not thinking about opening any new long positions right now - unless the buying case is compelling. Still, we need to keep up with the newsflow, to keep the archive up-to-date, so it's business as usual.
I think we need to be braced for further share price falls (and possibly some buying opportunities), as the coronavirus spread worsens. Although buyers can only buy if they have cash on hand. It's all very well people saying that it kills fewer people than normal flu, but just look at the economic impact of counter-measures in China - they all but halted economic activity in affected areas. We don't yet know whether the resumption of economic activity which is underway now, is likely to cause infections to increase - but that seems likely to me, based on common sense.
For anyone who missed it, I published a very interesting audio interview last week, with Andy Gossage, MD of Up Global Sourcing Holdings (LON:UPGS) - here. It's a non-commercial thing, with no fees or ads. I just did it for general interest, and to help inform readers on a topical subject. The conclusion seems to be that there will be disruption to China supply chains, but that this can be mitigated. Also, it's temporary.
Another aspect to consider, is that I imagine companies needing re-financing might possibly find it harder to do so, if this situation continues to worsen. It's essential to look more closely than ever at balance sheets, for companies which might be affected by coronavirus-related economic problems. I wouldn't want to be holding highly geared transport or holiday companies right now, for example - how would they service their debt, without any customers?
Let's start with some non-results snippets;
Countrywide (LON:CWD)
Confirms press reports that it is in discussions with Lsl Property Services (LON:LSL) regarding an all-share merger. All mergers are really takeovers, you just have to work out who is the dominant party.
LSL: market cap £350m (at 341p per share)
CWD: market cap £111m (at 340p per share)
In revenue terms, CWD it's the other way round, with CWD (£599m) being about twice the size of LSL (£313m).
In the all-important profitability terms, CWD is forecast to make barely above breakeven for 2019, whereas LSL remains strongly profitable. I'm scratching my head to work out why such similar businesses have such wildly different levels of performance. The only conclusion is that CWD must have been incredibly badly managed, and LSL well managed. There's no other explanation for the gulf in performance.
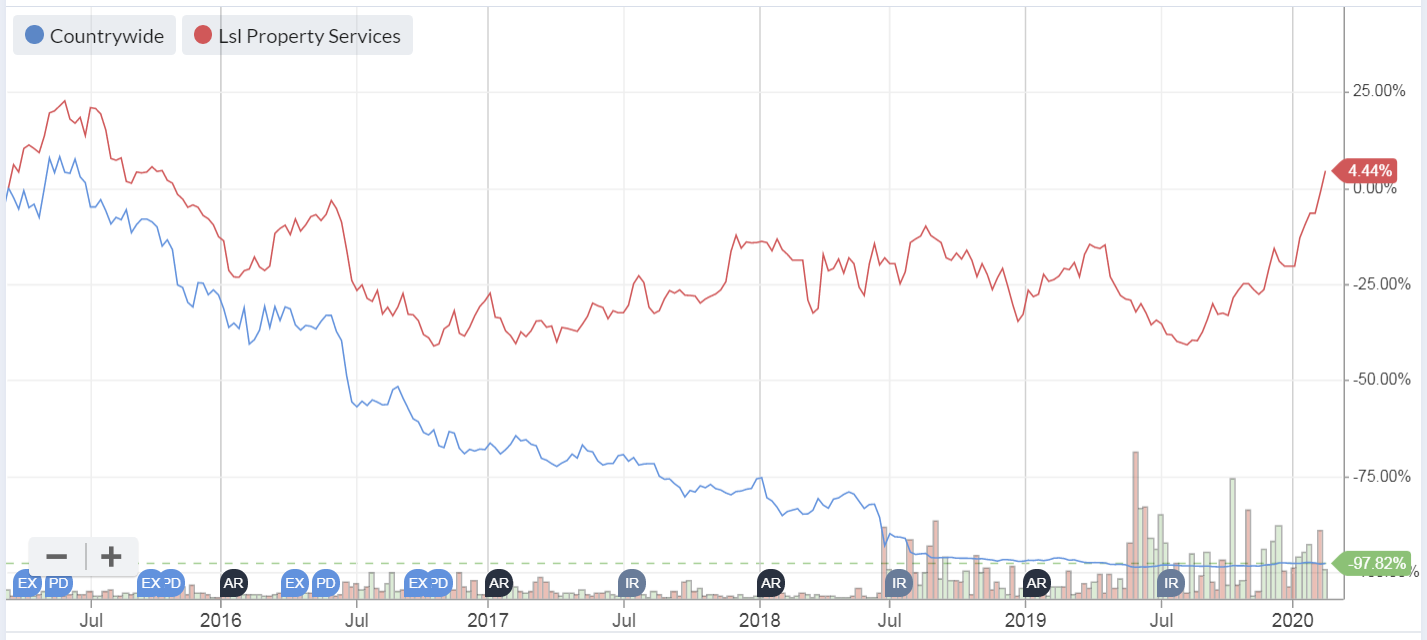
LSL has been the much better investment over the long-term. Look how, on the 5-year chart, CWD's began to diverge on the downside from LSL in mid-2016, and it's been a disaster for CWD shareholders ever since, being almost 98% down no the price 5 years earlier. Previous management at CWD all but destroying shareholder value.
.
.
Bear in mind that CWD paid about 46p in divis over the timescale of the above chart, which is about a 14% gain on the current share price. Therefore, the total shareholder return (divis + a small capital gain) has been about 18% for LSL shareholders over 5 years - not very good really. But a million miles better than the calamitous result for CWD shareholders over the same period.
I wonder if the competition watchdog might take an interest in this merger, since the combined group would be close to £1bn revenues?
Interestingly, both companies have weak balance sheets (which I define as having negative NTAV). Although CWD's finances are far worse, of the two.
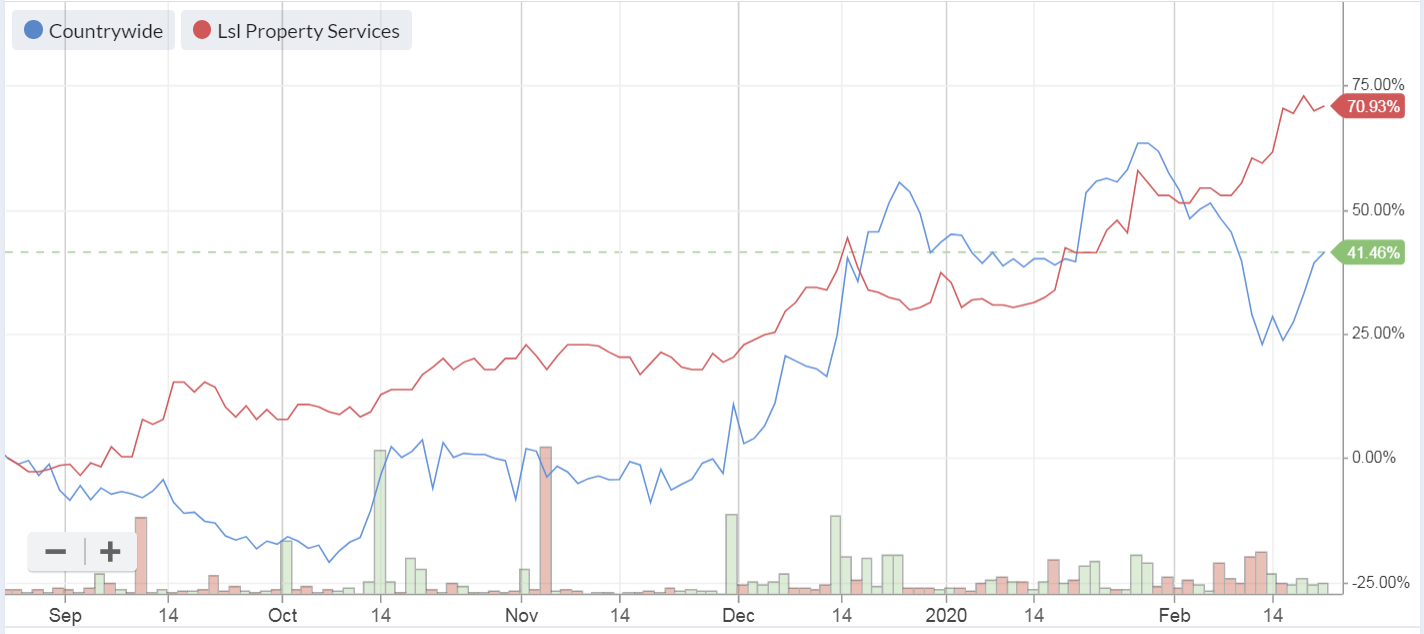
Recent positive newsflow about an improving property market, since political worries of an extreme-left Government have disappeared, has made this sector very strong in the last 6 months or so. Both have recovered well, but LSL pulling ahead strongly in recent weeks;
.
Incidentally, I'm using the new Stockopedia site now, and the charts are much clearer than on the old site, so worth checking out. It takes a little time to grasp how to use the various features, but I'm getting there!
Reach (LON:RCH)
Share price: 181p (up c.4% at 08:22)
No. shares: 299.3m
Market cap: £541.7m
Reach plc ('Reach', 'the Company', 'the Group'), the largest commercial national and regional news publisher in the UK, today announces its preliminary audited results for the 52-week period ended 29 December 2019.
Formerly called Trinity Mirror, of course.
This newspaper business remains staggeringly profitable & cash generative, as I always say when reviewing it. Acquisitions & cost-cutting have preserved, actually improved, the operating profit margin of a remarkably high 21.4% - that's far better than many companies in growing, hot sectors.
Adjusted EPS today of 41.1p looks a beat against forecast of 39.2p broker consensus. Although I think some of the adjustments look questionable.
Core revenues are still falling each year, but note the LFL decrease in revenues was 5.3%, which is improved from the drop of 6.6% in 2018. This holds out the tantalising possibility that newspapers might reach a plateau at some stage, where some are still financially viable? Maybe people buy newspapers when their smartphone batteries go flat?
Pension deficit is still large, but at least is falling, down by £52.7m to £295.9m (or £242.9m net of deferred tax). Those are the accounting figures. The actuarial figures (on which deficit recovery payments are based, so arguably more realistic),
Balance sheet - looks weak, with NTAV negative, at -£216.8m (calculated as NAV, less goodwill & other intangibles). However, the pension deficit (which is a manageable liability) is the cause of making the balance sheet weak. If we park that to one side, the rest of the balance sheet is fine. Combined with prodigious ongoing cashflows, I don't see any problem here. The business should last long enough to sort out the pension deficit completely.
Net cash is £20.4m (improved by £61.2m in the year) - as a result of very impressive cash generation.
Cashflow statement - very impressive, and worth a look. To summarise, it generated £147.4m in cash from operations (up from £137.8m last year). A third of this went into the pension schemes. The rest paid tax & dividends, with £60.0m left over to eliminate the remaining debt. It's absolutely staggering how cash generative this business is, for a supposedly dying sector (newspapers).
Outlook - continues to trade in line with expectations in 2020 so far.
Dividends - total divis for 2019 are up 6.7% to 6.55p - giving a historic yield of 3.6% - the yield has been much higher than this, but a strongly rising share price has brought it back down again.
My opinion - this group has performed a lot better than people thought it would. Going back a few years, everyone (including the then Chairman!) thought it was a dying business. However, with a mixture of relentless cost-cutting, and mopping up competitors (and stripping out duplicated costs) has proven a remarkably successful strategy so far.
Sir Martin Sorrell has been utterly dismissive of old media/advertising, but it's striking to note that his rapidly expanding digital advertising business S4 Capital (LON:SFOR) doesn't actually make any significant profit or cashflow yet, despite being valued at almost double what Reach (LON:RCH) is worth. RCH's cashflows & profits dwarf those of Sir Martin, so who's laughing now?
I note that Reach generated an impressive £107m in digital revenues in 2019. This is over 15% of total revenues. I wonder how much its digital division would be valued at, if floated separately on a racy rating? It looks to me as if there is a good market for newspaper and digital advertising to be sold side-by-side.
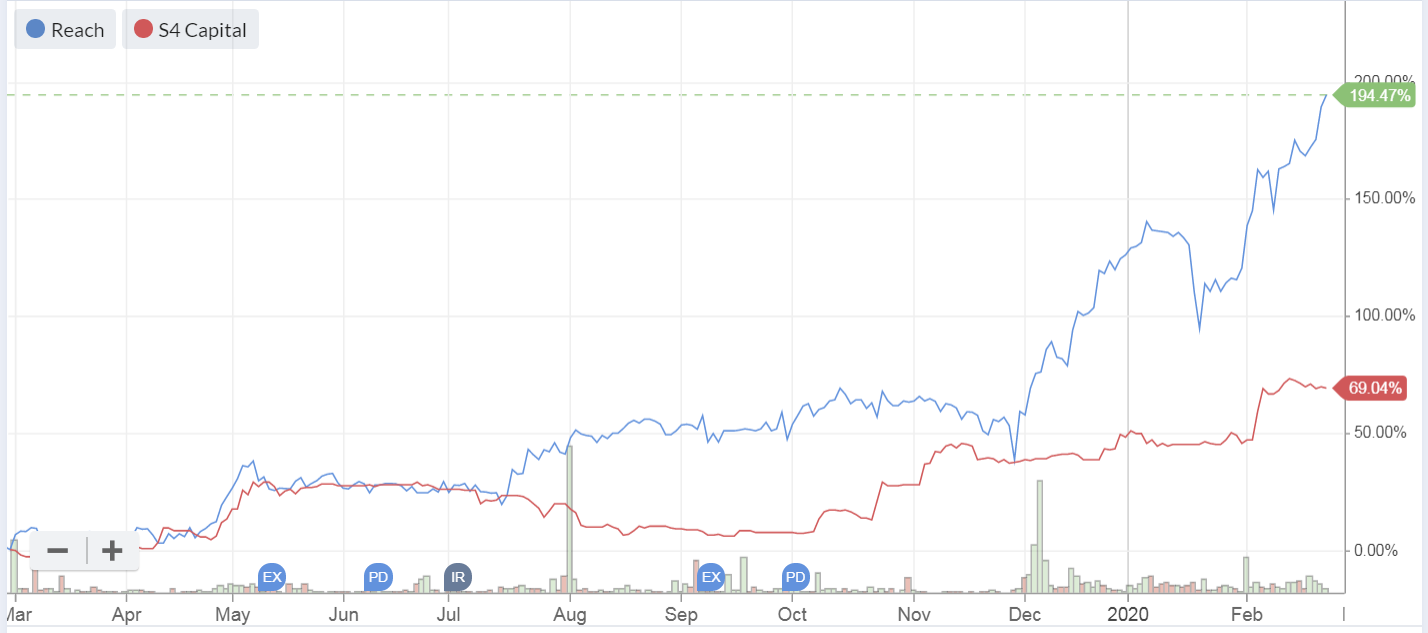
Looking at the 12-month chart below, RCH shareholders can also thumb a nose at Sir Martin, in that whilst his fancy S4 Capital (LON:SFOR) vehicle has delivered a decent 69% gain for shareholders, this has been left gasping in the dust kicked up by Reach's wheel-spinning +194% share price gain in the last year.
.
.
Even after this superb share price gain, RCH is still ultra-cheap on conventional metrics, especially the PER of 4.7
Therefore, if the market is now re-rating RCH as a media company with a good future, then this could have further to run perhaps?
Overall, I think the combination of good figures, low valuation, and interesting future potential from digital, make this share worthy of a closer look. I don't have time to plough through all the narrative & detail, as I've got lots of other companies to review today. So over to you, if the above has piqued your interest.
Cloudcall (LON:CALL)
Share price: 94.5p (up 1%, at 09:30)
No. shares: 38.7m
Market cap: £36.6m
(at the time of writing, I hold a long position in this share)
Contract win (and trading update)
It's always worth checking every update, as sometimes (as in this case) a more general trading update is slipped in.
CloudCall (AIM: CALL), the integrated communications company that provides unified communications and contact centre software that integrates with Customer Relationship Management ("CRM") platforms, are pleased to announce a major contract win with Vaco
CloudCall has previously told us that it's been targeting larger customers, so it's pleasing to see one come through.
Vaco is a global talent & solutions firm with annual revenues of more than $750 million. The three-year contract will see CloudCall providing its integrated telephony service to Vaco's thousand plus employees in quarterly tranches over the coming 18 months. The extended implementation period for this contract means that the resulting revenues will be spread throughout 2020 and into 2021.
Once again, CALL's close relationship with Bullhorn (software for recruitment sector) is mentioned.
Outlook - nice to see 2020 expectations confirmed;
... the Board remains confident in achieving its FY20 outlook.
My opinion - to put this into context, CALL ended 2019 with 42k users. Therefore, today's news of adding 1k new users, over 18 months, is pleasing, but not forecast-busting. Still, winning larger individual clients was a key aim, so it's good to see CALL delivering results, and confirming full year guidance.
With rapid organic growth coming from the US in particular (revenues up 55% in 2019), at high gross margins, I think CloudCall looks very cheap compared with how this type of company is valued in the US. This is further evidenced by the appearance of several US shareholders. Therefore, I'm quietly hoping for a US takeover approach. IF the price is right (over 200p for me), then I'd be happy to sell up.
Repeated cash calls of the past should be over now, because the last fundraise was big, and should leave CALL fully funded (how many times have we been told that in the past?!). But this time it does look different, as the cash pile is so much larger now.
It's taken years longer than expected, and cost far more, as with practically all growth companies, but CALL is clearly now getting there, in my opinion. That's likely to lead to a re-rating in due course, I reckon.
Loopup (LON:LOOP)
Share price: 60p (down 27%, at 11:13)
No. shares: 55.2m
Market cap: £33.1m
(I no longer have any position in this share)
LoopUp Group plc (AIM: LOOP), the premium remote meetings company announces a trading update for its financial year ended 31 December 2019.
Today's 27% price drop looks harsh, given that 2019 trading was only slightly below forecast. The trouble is, the market generally us selling-off heavily today, so we don't know how much of the 27% fall in LOOP shares is market-related, or company-specific. With illiquid small caps it only takes a few small sells to move prices a lot, at this end of the market;
The Group expects to report revenue and EBITDA broadly in line with market expectations at £42.5 million (FY2018: £34.2 million) and £6.4 million (FY2018: £7.7 million) respectively.
LOOP capitalises so much development expenditure into intangible assets, that EBITDA is completely meaningless. It provides a misleading, exaggerated view of profitability. It capitalised £2.44m of development spend in H1, therefore c.£5m looks likely for FY 12/2019 - consuming c.78% of EBITDA.
Adjusted EBITDA was £3.5m in H1, which implies it fell to £2.9m in H2.
Cash/debt - this sounds as if LOOP has cleared its debt, which sounds very good;
The Group's cash balance at 31 December 2019 was £3.0 million (net debt: £11.5 million).
I can't find any fundraisings since the interim results were published, back in Sept 2019. In those interims, this was the position (as at 30 June 2019);
Cash of £3.8m
Debt of £15.3m
Net debt £11.5m
Today's update ignores the debt completely, and just gives us the cash balance, now reduced to £3.0m. Not only do they ignore the debt, they also give a false comparative, of net debt of £11.5m, thus implying a dramatic improvement, where there hasn't been one. This is outrageously misleading! The cash figure may be technically correct, but showing a different comparative, is unbelievable, literally! Can we trust anything this company says? Based on this egregious attempt to deceive readers of the announcement, I'd say a resounding no.
The company blamed macro factors for a decline in user spending last time it reported. A number of us here didn't buy that explanation. Today it trots out the same reason for a worsening in USA of customer usage, from -2% in H1, to -8% in H2. It links this to a decline in US M&A activity. Again, I don't buy that explanation.
Intermittent service issues - this is the one thing that a telecoms service provider cannot allow to happen, as it's the quickest way to destroy the business - having a service that doesn't work.
... the Group experienced subsequent intermittent service issues during November and early December 2019, which gives rise to the potential for higher than normal churn in H1 2020.
All service issues have now been resolved and normal high-quality service levels have been resumed. We are focused on mitigating any potential impact.
If I was paying a lot for a premium service, and it doesn't work properly, then I'd be inclined to find an alternative that does work. Also, having many firms of solicitors as your clients, makes LOOP vulnerable to them demanding refunds, even damages, for poor service.
Cuts to sales pods - the previous expansion here looked excessive. 24 people have been cut from sales pods in Jan 2020. If they're on, say £30-40k each, that's a saving of approaching £1m p.a. - which is being spent on increased capitalised development spending, which is going up from £5.0m in FY 12/2019, to £6.0m in FY 12/2020. That seems extremely high - making me wonder if it is all genuine development spending, or might in part be a convenient place to dump operating costs, possibly?
Outlook - this sounds contradictory to me - demand is strong, but growth is only in the medium-term (i.e. code for demand being weak in the short-term). Previously in the RNS, they had told us that demand was falling!
While immediate business and forex conditions remain challenging, we continue to see strong demand for the LoopUp product and are confident in our ability to deliver medium-term growth. We continue to monitor market and financial conditions closely.
My opinion - my biggest problem here is management - based on their track record to date, of destroying shareholder value, I don't rate them. Also I don't trust them either, give the misleading elements of today's update.
I've previously held this share, because the product worked very well, when a friend and myself tested it out, prior to originally buying some shares a few years ago. Then more recently, I caught the falling knife, shortly before a profit warning unfortunately. What induced me to sell a few weeks ago were these factors;
- Portfolio clean-up, ditching small, low conviction holdings, when the coronavirus issue began
- Worries about LOOP's lack of cashflow generation, and the debt (trying to mislead us about debt today, just reinforces that it is a potential problem)
- A reader comment here, a few weeks ago, alerting me to the competitive threat from Microsoft Teams
- I spoke to a LoopUp client at Xmas, who indicated that the product seems basic, and they were not even aware of its sophisticated features & don't use them
- Poor management, who have made multiple mistakes, and destroyed shareholder value
On the upside, LOOP's client list is very impressive, and with a market cap of only £33m, it might attract bidding interest. It could also be a beneficiary from coronavirus - making people more likely to want to use remote meetings software, instead of traveling to physical meetings.
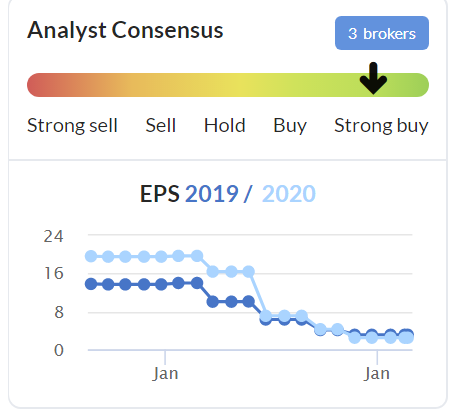
Expectations of profitability have collapsed for now;
Judges Scientific (LON:JDG)
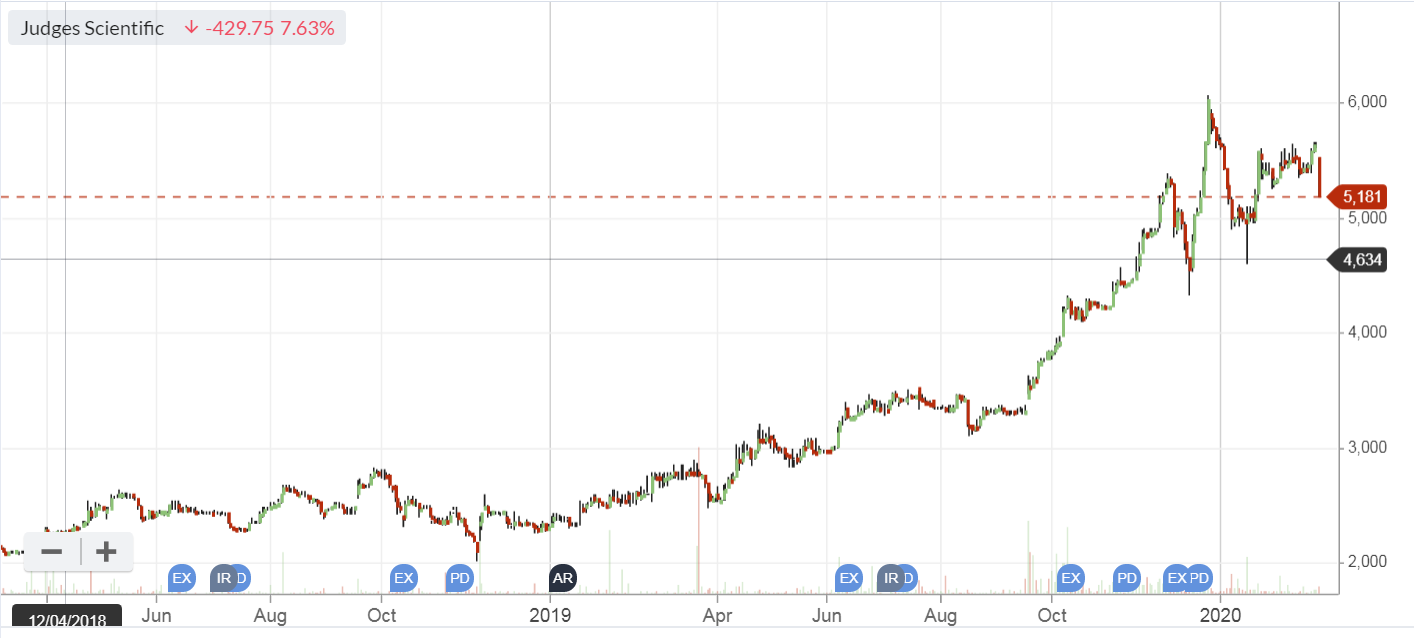
Share price: 5220p (down 7%, at 12:20)
No. shares: 6.25m
Market cap: £326.3m
As it's fairly short, here is the announcement in full;
The Board of Judges continues to closely monitor developments in China and the potential effect of the COVID-19 epidemic on its business.
With the current scale of the outbreak, and provided it does not last more than three months and remains largely contained within China, it is not expected that there will be a significant impact to the Group's 2020 trading.
The Group operates with an average 3-month order book, so in the near term the current travel restrictions are expected to only have a temporary impact, deferring rather than reducing revenue. Unaudited revenues for China/Hong Kong represented £9.5 million in 2019.
In relation to Judges' supply chain, direct and indirect supply from China varies from business to business in the Group, with only one subsidiary having significant supply chain exposure. The Board is monitoring developments closely and at this stage of the outbreak, currently considers that supply chain disruptions will be manageable.
The situation remains under active review by the Board.
There are quite a few "if's" in the above - in particular, the one about it largely being confined to China is already starting to look out-of-date - given the sudden surge in cases in S.Korea and Italy.
Deferred orders are fair enough, but that still means a likely miss against planned performance in H1 2020, and that would hit the share price - because some investors would decide that an H1 miss and H2 catch-up may not happen.
My opinion - JDG has a fantastic long-term track record. However, that's baked into the price now, which is a lofty PER of 24 times. Given that there's a question mark over performance in 2020, if coronavirus gets worse, then I can see the sense in selling up now, and watching from the sidelines.
Or, if you're a long-term, ungeared investor who is no good at market timing, then I can also see the sense in sitting tight, and riding out the uncertainties.
Given the high valuation, and superb share price performance in recent years, then banking some profits might make sense for some investors, but as always that's your call - every investor has to make up your own mind & own the decision.
.
Tristel (LON:TSTL)
Share price: 428p (up 8%, at 12:47)
No. shares: 44.8m
Market cap: £191.7m
Tristel plc (AIM: TSTL), the manufacturer of infection prevention and contamination control products utilising proprietary chlorine dioxide chemistry, announces its interim results for the six months ended 31 December 2019, ahead of guidance at the December AGM.
Strange wording there. It should have had the words "which are" inserted in front of "ahead of guidance...", and the word "given" inserted in front of "at the December...". I do sometimes wonder if companies have anyone review their RNSs before they release them, to sense-check the wording? Maybe I should start a consultancy business, to improve reporting?!
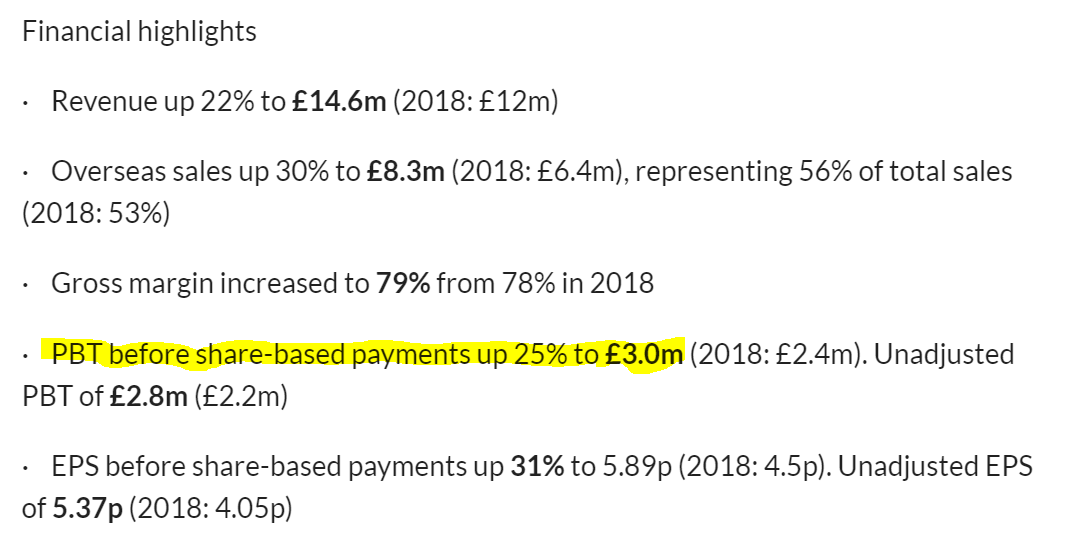
Interim results look pretty good. It always strikes me how small the numbers are, when I look at the geographic breakdown of sales for Tristel. Its overseas sales have been boosted by buying in distributors. Nevertheless, put it all together, and the company delivers a decent profit, on modest revenues, in the first 6 months;
.
It also flags how coronavirus might be helpful, in driving increased sales of its disinfecting products.
Outlook - describes process for entering USA market as "extraordinarily protracted".
Progress of a new product called "Rinse Assure" is explained, which sounds interesting.
No-deal Brexit risk mitigated by transfering permissions to the Netherlands.
Coronavirus - no significant exposure to China for supply chain.
Overall;
The prospects for the Company remain very encouraging and we look forward to further progress in the second half of the year and beyond.
Balance sheet - looks fine to me.
My opinion - it's a nice little company. Is it worth £200m mkt cap though? That's really the only issue - valuation. How do you value something like this, which has a good niche product, selling is small quantities, in lots of markets?
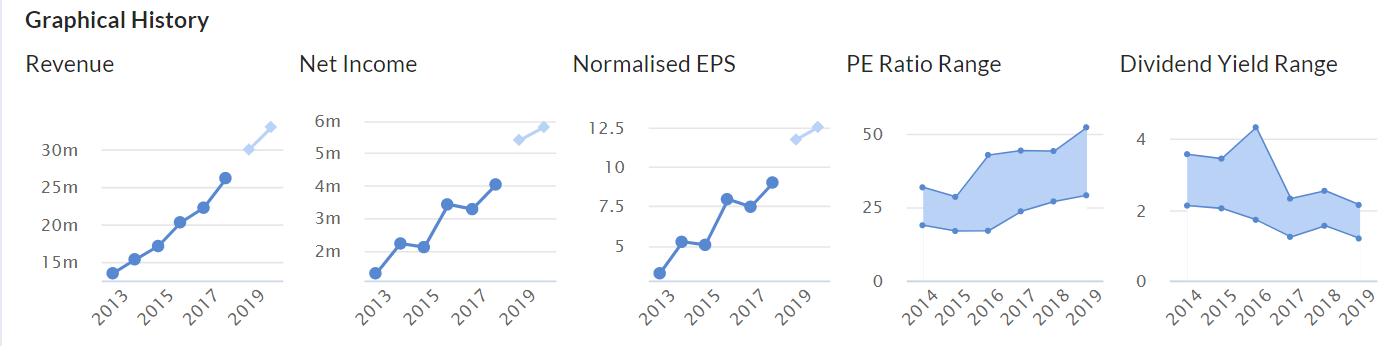
EPS for 2020 is forecast at 11.7p (confirmed today), hence a share price of 428p means you're being asked to pay a PER of nearly 37 times - that seems expensive for growth that's steady, but not exciting. As you can see below, the PER is getting more expensive over time, and the yield falling.
I like the company, but I'm really struggling to understand the valuation. Maybe people think the USA is a slam-dunk, and could raise future earnings considerably?
.
Accsys Technologies (LON:AXS)
Share price: 102p (down 1%, at 14:02)
No. shares: 162.3m
Market cap: £165.5m
I was about to delete this section, because the announcement today is too complicated for me to unravel.
Thankfully however it concludes with something I can understand;
Accsys confirms that trading is in-line with the Board's expectations and no changes are being made to the Board's expectations for the full year.
My opinion - neutral. The product looks very interesting, but I concluded some time ago that its development was taking too long, and too capital-intensive, to be of interest to me as an investment.
Rtc (LON:RTC)
Share price: 72.5p (down 4% at 14:17)
No. shares: 14.6m
Market cap: £10.6m
Results for FY 12/2019, from this minnow staffing group.
Given how many staffing businesses have been struggling of late, these results look respectable.
Revenue £94.9m, up 8%
Profit before tax of £1,758k is down 5.4% on LY, due to a higher finance expense line (operating profit is only down 1%)
EPS of 9.6p gives a PER of 7.6 - I can't see any reason as to why the PER should be higher than this.
Balance sheet looks OK to me - note that borrowings have come down a lot, at £3.57m, and this is quite low relative to the receivables book of £15.8m
Outlook - there's an interesting section about IR35;
The second predominant risk causing sleepless nights for CEO's is IR35. The IR35 cloud has been firmly on the horizon for twenty years as the initial legislation was first passed in the 2000 Finance Bill. Whilst the implementation date has been postponed on many occasions, HMRC is adamant it is not going to kick the can down the road anymore and the government is firmly committed to implementing its policy in April 2020. It is worth outlining that the legislation designed to combat tax avoidance by workers supplying services to clients through intermediaries is highly complex and with employment law relying on caselaw to determine the legal status of individuals, the complexity of the issue will be challenging for all concerned for the foreseeable future. Presently a significant contingent of workers deployed by the Group across its client base have been determined as residing outside the scope of the legislation as they are employed by the Government through Network Rail and the Government is responsible for determining the status of all workers engaged under their auspices. The status of workers engaged by Group within the private sector are subject to review by our various clients and we are working closely with all our clients to establish the most appropriate route to keeping the individuals engaged on their work programmes from April 2020.
My opinion - neutral. The valuation looks about right.
It's not clear to me why this company has a stock market listing, there's no obvious reason why the expense & hassle is justified.
A focus on engineering & infrastructure projects looks to have worked out well, given the major focus on this area of spending, from the new UK Government.
All done for today, see you tomorrow. Keep those hard hats on, and the hatches battened down!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
There was recent comment here about the financial problems at the family-run Cordant Group, and comparison was made with Staffline (LON:STAF) . I have received an e-mail telling me Cordant has just been taken over by Twenty20 Capital, a private equity crowd. Read into that what you will. (Posted this elsewhere on Friday)
By the way, for what it's worth I think RTC is a good business that operates in a quality niche with management that can be trusted. I know Andy Pendlebury a little bit (that is to say we've met several times to discuss the rail industry) and I like the quy and how he presents RTC. He is a no nonsense, straight talking CEO and not out to mislead investors.
I won't comment on valuation other than to say the market cap seems low when you consider the myriad companies on AIM which are absolute basket cases and yet continue to command market caps ranging from £30 - 250M whilst destroying shareholder value by consistently raising new money and/or cooking the books.
When looking at AIM companies I add a significant discount or premium based on management track record versus market expecation i.e. did they do what they said they were going to do?
RTC has consistently grown its top line in a meaningful way for many years with negligible dilution and pay a respectable dividend. How many other AIM companies get that badge? IMHO at some point it is bound to get bought by a larger player and the current market cap is so small that even a >50% premium to the prevailing share price would be relatively 'cheap' given the strategic position they hold with key clients.
(PS - I hold a long position in this company albeit very small!)
Anybody aware as to why SDI (LON:SDI) dropped 11.5% to 72.5 today. I don't think it has a connection to China that would cause such concern?
Possibly investors reading the the £jdg announcement today and just selling up anything else in that sphere
Hi Ted,
At times like this, you cannot make sense of small caps price movements.
It's supply & demand for the shares, in very low volumes, and prices can go all over the place.
If someone is desperate to sell, then the price falls to whatever level attracts buyers. But often in tiny volume, so the published prices are often completely illusory.
Regards, Paul.
Snoo don't you mean "way into five figures".
Best to view P&L as %, 4,5 or 6 figures will just drive you to insanity .
Wonder if some psychology wisdom could be apt for today, how to mentally deal with it?
On paper anyway there must be investors whose losses in one day are way into the four figures. And the futures market looked benign for much of Sunday in the day.
Easy to be upset and chase some stupid trades to try and make some money back. Probably going to not look at the market for the rest of today.
The outlook seems scary at the moment but the probability seems overwhelming that it will not get out of control and this time next year (or even in a few months) it will be largely forgotten.
Irritatingly while many of my shares have plunged nearly 10% like Ramsdens Holdings (LON:RFX), some on my shortlist that I would buy if they fell 10% which you would think may have supply chain issues somewhere ie (£SCS) have not budged at all.
I find the best source of dispassionate information about COVID-19 is the WHO's site at https://www.who.int/emergencies/diseases/novel-coronavirus-2019
There is excellent information and advice for the lay public.
But I also find the documents for a professional audience in the "Technical Guidance" section very useful. There are sections on detailed swabbing to take during early investigations (1 metre from patient, 2 metres from patient, various locations in the ambulance, etc) which are clearly used to find out how far from the patient the virus particles can typically get. There are sections on how the trace contacts and how deep to go. How to treat a patient in a home setting. And so on. Much of the data collection is very clearly aimed at being able to use statistical techniques like Bayesian inference to calculate risk factors for various situations.
They also have an app ( https://www.who.int/godata ) which is used by the workers in the field to do much of the data reporting and probably explains why there is so much detail available about how many are infected and which country they came from, etc.
So the short version is that when you peer into the world behind the superficial newspaper reporting you find very clear headed, focussed activity. A big part of the strategy is obviously contact tracing and self-isolation. When the virus runs out of people to infect that particular outbreak is stopped. Clearly the recent big jump in numbers in Italy is because they missed the patient zero in that case. But if they isolate around the cluster they will get it back under control again.
The papers like to imply that nothing short of a full hazmat suit can stop it and everyone from an infected country is a high risk. This is just knee-jerk nonsense though and it is a bit of a relief to see how much more sophisticated the behind-the-scenes response is.
That's all very sciencey & impressive-sounding, but to be fair, I don't think the press coverage has been misleading or alarmist at all. Everything I've read on e.g. BBC, Telegraph, websites has just been reporting the facts.
The facts are that this is highly contagious, and that attempts to control its spread are clearly not working well enough. That's why stock markets have now started to react in earnest.
Hi Paul - I'm not sure that's strictly fair. one major London newspaper led with a massive bold headline on front page at one point of "Killer Virus - Spreads!" : I'd say that's alarming when it's being read by millions of Londoners. I do think there is a lot of scaremongering out there.
That said you're not wrong that the virility aspect and thus containment attempts are troubling.
Fair point david, I hadn't seen any alarmist reporting, but I only read the BBC, and the Daily Telegraph. I take your point that other papers might be over-stepping the line.
The reason the markets have reacted is the surge in numbers outside China, as in South Korea, Italy and Iran. I don't think it is highly contagious, if it was why have not more people been infected, Chinese carriers have visited other countries and hardly anyone seems to have caught it, Thailand has had only 35 cases most of those were Chinese that have recovered and gone back to China. If in confined spaces such as a cruise liner or a meeting hall then yes it does seem to highly contagious.
I agree about running out of people to infect however millions of people are travelling on flights all over the world, even the Chinese are not restricted by many countries. Just been to Bangkok and there are millions going through there. Trying to isolate everyone that is infected would be almost impossible due to incubation periods and carriers showing no symptoms. Fortunately this virus does not seem to be passed on that easily otherwise people on flights would be infected more frequently. How can it be passed on from people with no symptoms if you need within a certain area and if they are not coughing or squeezing?
Not keen on the WHO site, I prefer this one: https://www.worldometers.info/coronavirus/coronavirus-symptoms/
Personally, looking at the WHO information I'd suggest that it is no longer containable.
For the outbreaks to have spread to different countries means that infected individuals have been through transport hubs resulting in the virus being spread internationally.
I'm sure we'll have a better idea in a couple of weeks as individuals become symptomatic.
I'd ask how many of you know the symptoms?
How do you know whether you have a cold or something more sinister?
I'm sure the WHO have great procedures for testing and isolating individuals but first you need to identify infected individuals.
No wonder some of the Uk citizens on the Diamond Princess refused to travel home with other UK citizens. Travelling back on an aircraft and in coaches breathing the same air as potentially infected travellers. They were right to refuse as two have since tested positive.
Looking at the figures it seems the mortality rate is between 2 - 3%
Yes 52 new cases on the Diamond Princess were asymptomatic.
Some cases have a longer than 14 day incubation period. 14 days may catch most but not all.
Not many seem to be catching it on flights. Maybe the air conditioning systems and filters are stopping it spreading?
I'll use some of Herbie's questions to illustrate the kind of data they collect.
What is the probability that an individual has COVID-19 given that they travelled from China? (Looking at the most recent situation report the probability is still low unless you came from Hubei itself.) There are protocols to manage points of entry.
There are a set of protocols to collect the data to understand the key epidemiological features. This data would be used to calculate the infection rate, the incubation period and different methods of spread (such as "do air conditioning filters stop the spread?").
There is also a short video on the main page which covers transmission, groups most at risk, symptoms, diagnosis, treatment, and prevention which is aimed at the lay audience.
Some were from Hubei and were infected, there were still 224,000 chinese visiting Thailand this year, numbers about half due to restrictions imposed by China. There are no restrictions entering Thailand apart from some airports have a thermal imaging camera to check temperatures, even that only seems to be the largest airports. I was very surprised there was no checks when I arrived at Heathrow.
Tristel has been thought overvalued for a long time now, but the shares, driven by Company performance, continue to rise!
In light of the much commented problems at Staffline (LON:STAF) I thought is was relevant to point out the news of the problems at unlisted Cordant (banks reportedly refusing to refinance a debt facility), one of the largest recruitment agencies in the UK, which also supplies staff to Tesco and Amazon.
I am not sure how direct competitors Staffline and Cordant are, but maybe not all Staffline’s problems are as self-inflicted as they seem.
https://www.google.co.uk/amp/s...
Just for info, I have worked for Cordant and Staffline (LON:STAF) . The set ups are very similar. I wouldn't put money into either.
Trading update from Ethernity Networks (LON:ENET) This is one of those 'failed IPOs' which didn't deliver as quickly as the market was expecting but now seems to be in recovery mode. Management have large shareholdings here, market cap is only £15m and yet the company seems to be in a good position to benefit from the rollout of 5G networks. I hold.
Paul - I've long argued on here that Reach (LON:RCH) is capable of producing prodigious cashflows for much much longer than the market was giving it credit for and a PE of 2, even accounting for pension deficit, was way too low. Hence, I was buying down in the 60p range. Whilst that discount has significantly narrowed now it appears management are growing digital at mid teen growth rates too and have got their act together on this as well. That makes the stock very interesting indeed.
With cash at £20m at y/e you can expect it to be above £80m at next y/e or 15% of market cap and pension deficit should be below £200m (with tax credit). That's less than 4 years to elimination, or a net -£120m if you include cash. To put into perspective that's less than 1 years worth of cashflow.
As you rightly point out the digital business is now over £100m revenues and growing mid teens and capable of churning out decent content given the number of journalists it employs. That could be interesting in its own right. I wonder what sum of the parts valuation would be.
Hi David Hill,
Re Reach (LON:RCH) Tom Winnifrith highlights thats they still have outstanding legal issues from phone hacking, i think, that could be £100s millions. Do you have a view on this from your previous research, something is likely to be holding back the share price to this magnitude?
I think they have a contingent liability of c£20m to cover these claims.
Your figure seems way in excess of what has been paid out to date, iirc, what would be the reasons for a massive ramp up in these payments?
Well, the company itself regularly addresses this point and updates the market and currently has a £21.1m contingent liability up £11m yoy, which reflects its expected risk based liability. Why Winnifrith and Co. are conjecturing something a magnitude above that I have no idea, but you'd imagine if there were any real substance to that the company would be obliged to say something about it, especially since the final results RNS come after these allegations.
What has historically held the shares back is nothing to do with this. Essentially threefold.
Firstly everyone thought the print business would very quickly become unprofitable and the company would be in a spiral of declining revenues and profitability. That hasn't turned out to be anywhere near the case, though I'd say management strategy has had a lot to do with that.
Secondly the pension deficit. If you assume profits are going to fall off a cliff and there is £300m+ of pension liability that wouldn't make for a good investment case.
Thirdly the lack of compound growth in digital to offset (1). However, this has also now started ramping up with revenues exceeding £100m and growth in mid teens.
In reality this business is a big cash machine that if managed properly can throw off large chunks of cash for years to come. Because of that the company can make big inroads to its pension deficit whilst at the same time moving from net debt to positive net cash and paying a decent dividend.
wrt Reach (LON:RCH) and the potential further phone tapping liabilities.
A couple of weeks ago Simon Cawkwell was apparently peddling some rumours about having "a paper" indicating that there were £100s of millions of liabilities yet to arise.
He still seems to have something of a reputation with his 'Evil Kineviil' but when I had an online interaction with a couple of years ago regarding a share which he was trying to ramp that I knew something about and was cautiously positive; I found him to be quite clueless. (But maybe that was part of the carefully crafted persona?)
Anyway it is probably therefore no surprise to find Tom Winnifrith two weeks later peddling exactly the same rumoured risk for Reach.
I very much doubt that they have any information of substance here.
However, it might have been three years ago when I commented on their latest increase to historical legal provisions and said something along the lines that I hoped they had now provided enough. They have increased the provision several times since. This has been in the single digit or low double digits each time,; so scarcely material when compared against profits and cash-flow. Nevertheless, it remains a risk factor that will and should continue to drag on the share-price until they can really draw a line under the issue.
Anyone that strays into dangerous territories might observe that the rampers are out in force, suggesting that Reach (LON:RCH) should be viewed as digital media stock on a PE of x20-30. Much as I would love that to be right (it would be a 10-bagger over a comparatively short period), it is utter-nonsense.
I do think there is more upside to come here, but one needs to recognise that Reach (LON:RCH) has been seriously Marmite to investors over the last decade and we a definitely at a phase where the market has lost it's hate for Reach, so there is definite downside risk here.
I should just point out that the high point PE ratio in that chart arises from taking the current share-price [P] against the 2018 earnings [E] which were not typical, the 2019 EPS is nearly 4x 2018 so Reach (LON:RCH) is still not expensive on earnings (and importantly cash-flow) .
Personally, I still think there is substantial value here and I continue to hold, but we are now in a place where there is ample ammunition for both the rampers and the derampers - perhaps though today's presentation can deliver renewed II interest to deliver renewed share-price stability.
I am oversized here as a result of the gains over the last year, but totally disinclined to "top-slice" - I'm almost inclined to regard this as one of my "safer" investments now.
V useful comments for a relatively newish investor in Reach. Thanks.
The death rate for closed cases is currently 9%, the WHO estimate is 2% but too early to tell, Wuhan 4.9%
I found this site over the weekend (I think from a link on another Stockopedia thread) which is very useful for up to date Coronavirus info and stats https://www.worldometers.info/coronavirus/
“ It's all very well people saying that it kills fewer people than normal flu”
Hi Paul
I think that this needs some clarification. The death rate of Corvid-19 appears to be around 2% but <0.1% for seasonal flu. So, of the people that catch it, Corvid-19 appears to kill many more. The next question then is how many will catch it? This is partly about containment and it seems like the probability that it will be contained is diminishing rapidly and a pandemic is on the way.
Unfortunately, there is nothing so far to indicate that it is significantly less contagious than seasonal flu.
So, if that pandemic happens, the substantially higher death rate for Covid-19 means than many more people will be killed by it than seasonal flu. Hopefully, we will get lucky somehow. Perhaps it may soon mutate to a less lethal form. But as someone once said, Hope is not a strategy.
Yes, from the CDC web site - last year CDC estimate 35 million "Symptomatic Illnesses" of influenza in the USA resulting in an estimated 34 thousand deaths. If Corona inflected 35m people with a 2% mortality rate that's 700 thousand deaths. Hence the various government reactions on containment.
The most recent estimated infection-fatality rate of corona virus that I can find suggests that it is less than 1%. This is more severe than the 1957 H2N2 influenza pandemic (0.1 - 0.3%) and less severe than the 1918 H1N1 influenza pandemic (2.04%).
Graham - you are better off looking at the death rate by age group. It's only in the over 70's with underlying problems where the death rate compared to flu is that much higher. I think over 80's is something like 14.5%, which dramatically skews the overall averages.
In the under 9's I think the death rate is zero for example, or at least it was last I looked.
The problem is not the death rate (other than for those that are affected of course). The problem appears to be the virility. it is clearly a lot more contagious than flu (though whether that is related to the fact it is a new human virus or not is unknown). This means containment is both necessary and much harder and unlike flu leads to shut downs of towns and cities and factories to minimise its effects, so the economic effect is greater.
As winter conditions end the virus is expected to become much less contagious as it will be unable to survive in the air for very long like most viruses (however, there is also an unknown element here) and if this happens containment will be easier. That though relies on the countries with current outbreaks keeping it at bay until then.
Also I don't think we look for the virus to mutate to a less lethal form, I think we hope it does not mutate to a more lethal form! That would be problematic to say the least.
Either way it's not a great situation!
Yes I agree and the death rate could be well over 2%, it may fall as the virus dies out but now it is properly somewhat higher. Deaths/over number of cases is not a true calculation as some of those may well die, many are in a serious condition. Number of cases is lower than actual as well as it takes about 14 days from infection to showing up as a case. Many seem to be carrying it but showing no symptoms, 52/57 mostly crew on the cruise liner for example.
Maybe it will disappear as the temperatures rise.
looking at PE ratios and forwards earnings growth, I think stocks are expensive and the corona virus is the catalyst for a correction.
i didn't get up early enough to buy the VIX (VILX) its up 28%.
Looks brutal out there today.
Perhaps a 200-point fall in the FTSE if fear picks up.
I do think there will be some quite severe knock-on effects that were not on the table at the initial outbreak. Companies with seemingly no connection to China for instance may end up seeing disruption because of things further down the supply chain.
What type of shares do people have on their watchlist if the bigger falls do come? I am interested in Royal Dutch Shell (LON:RDSB) but am waiting a bit longer. Carnival (LON:CCL) appears quite exposed here. Once the virus is dealt with it may be easy to see that people will resume flying again. But is that the same for cruises, which are almost wholly discretionary choices and may have reputational damage (the virus seemed to spread very quickly on Diamond Princess).
Their debt load appears quite big and their assets (big cruise liner ships) may not be worth as much if there is reduced demand for cruising in general.
I have just returned from a 10 day cruise on a relatively small ship - 900 all adult - in the West Indies. We had a noro virus outbreak on board almost from day 1. Good precautions taken, and unlike Princess Cruises event in same area in mid Feb (not same as Japan event on another ship of same cruise line) we were not barred from any ports en route. However, it did affect some of the facilities on board and also our health on a couple of days. Will it affect future cruise bookings? You bet! If it can happen to the best cruise line in the world, small boats etc, then I really wouldnt like to be on a 4000-5000 monster with kids!
Yes I agree this will have an effect for quite some time, I did have some long term Carnival (LON:CCL) shares, I got rid of the last of them about 10 days ago. I think airlines will also get hit but should bounced back more quickly, have sold my Wizz Air Holdings (LON:WIZZ) as well.
For anyone who likes pharma, the FT is reporting an interesting angle on this.
To date in this virus story, overall the pharma sector has been seen as a buy because a vaccine maybe developed. But the FT is saying today 'The price of many pharmaceutical ingredients has spiked for Indian drugmakers following panic buying and Chinese raw material shortages caused by the coronavirus lockdown.'
Increase in raw materials will be a headwind for the sector.
Morning Paul,
Tristel (LON:TSTL) has reported today, your comments on them would be most welcome. I am a long-term holder.
Many thanks
Me too Newbe. A big holding of mine and some strong results out today. Interestingly some hints that corona virus will accelerate their performance - and hopefully their US certification.
It's on the list!
Hi Paul, I know you can't do everything, but I for one would also appreciate your view of Finsbury Food (LON:FIF) Finsbury Foods, who've also reported today. It's on my new "blame Stockopedia portfolio" - which I only started at the beginning of the month and as a whole is roaring along!
Innovaderma (LON:IDP) announces the launch of its new brand "Nuthing". A new range of products for hair removal. To be stocked in all 800 superdrug stores from 11 March as well as being sold through DTC channel. Superdrug has committed to a major store activation plan to support the launch.
Half year results are announced tomorrow.
A key issue tomorrow for Innovaderma (LON:IDP) will be to what degree they are continuing to capitalise customer acquisition costs – especially as little amortisation is occurring. This is the main reason the share price looks superificially cheap in my opinion. As Graham previously commented on its 2019 results 'Profit before tax was £1.4 million, but it would only have been £500k if they had expensed their product development costs and purchase of
intangibles.'
Stockopedia labels the earnings manipulation risk at Innovaderma (LON:IDP) as 'high'.
My morning smallcap tweet:
Judges Scientific (LON:JDG) Countrywide (LON:CWD) Batm Advanced Communications (LON:BVC) US Solar Fund (LON:USF) Warehouse REIT (LON:WHR) Cloudcall (LON:CALL)
Judges Scientific (JDG) covir-19: does not expect a significant impact to the Group's 2020 sales provided it does not last more than three months and remains largely contained within China.
Countrywide (CWD) confirms report that it's talking to rival LSL re a possible all-share combination.
BATM Advanced Communications (BVC) wins $4m cyber security contract from its long-standing government defence department customer for deliver in H2 2020.
US Solar Fund (USF) gets back a further $2.7m of defrauded cash. Only $0.6m not recovered, not significant for NAV.
Warehouse REIT (WHR) portfolio valuation up 6.3p/sh since Sept. SP is 115.5p.
Cloudcall Group (CALL) wins 3y contract to co with a 1000+ staff. "The extended implementation period for this contract means that the resulting revenues will be spread throughout 2020 and into 2021." Outlook in line.
Not exactly a reassuring statement from JDG.
They had to be truthful.
Tristel (LON:TSTL) again quote results "before share based payments".
Since shareholders get the "AFTER share-based payments" results, stating the "before" result is very unhelpful.
It only makes sense if the directors are committing to take a smaller percentage in future. I'm not aware of such a commitment. No position.
I sold this a year ago at £2.9/2.9 as I felt the directors were being excessively greedy and the ratings excessively high. A quick glance at yesterday's release suggested the latter still to be true but perhaps the former has eased?
Reach (LON:RCH) and Countrywide (LON:CWD) please