Small Cap Value Report (Mon 24 June 2024) - SHI, THG. Briefs: PRU, BVIC, BELL, SUP, TPX, DWHT

Good morning from Paul!
It's quiet again for news today, so hopefully I might be able to enjoy some sunshine later! Isn't it strange how the media today see a heatwave as a desperate threat, and give us alarmist warnings - keep in the shade, drink plenty of fluids (what else would I drink, gas?!), and the weather charts are angry shades of red. Whereas back in the 1970s, the weather charts were shiny, happy bright yellow, and the forecasters told us to get out and enjoy ourselves. What went wrong? When (and why?) did common sense disappear?
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
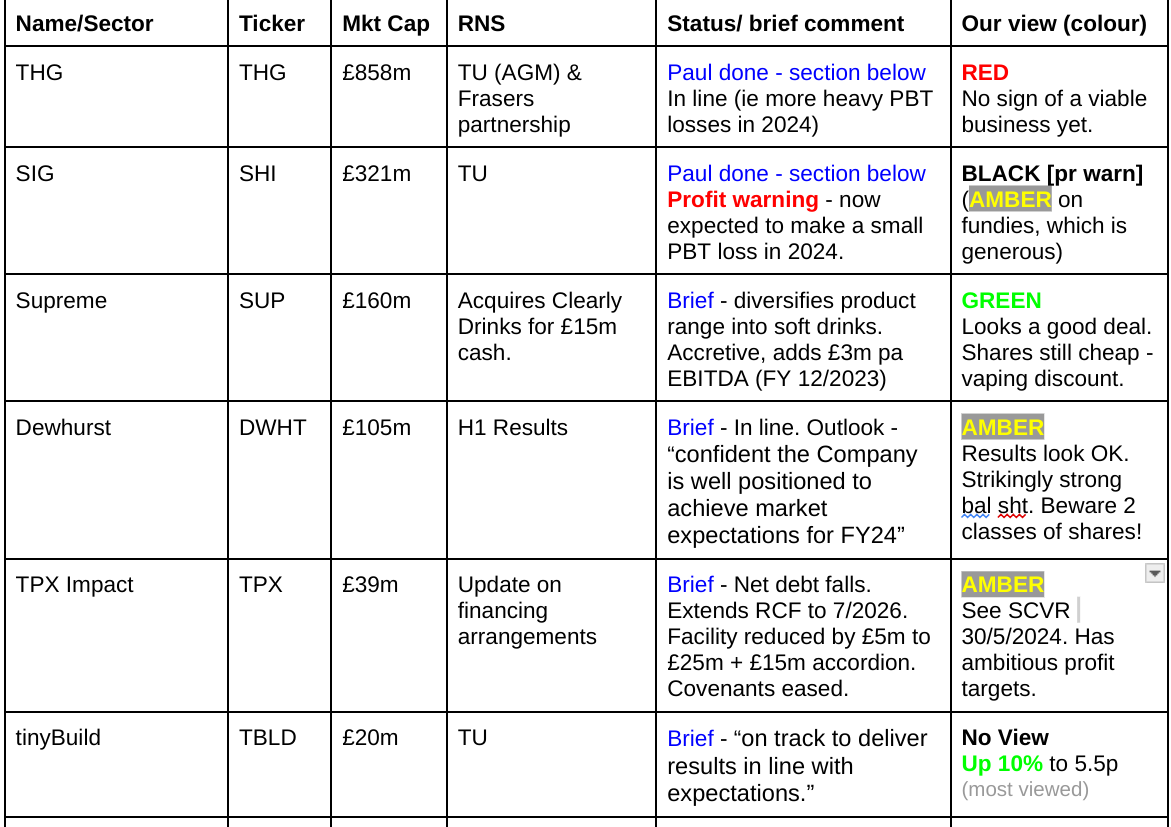
Other mid-morning movers (with news)
Britvic (LON:BVIC) - up 8% to 1,178p - Statement by Carlsberg re Britvic - Paul - PINK
We covered the bid approaches (1200p and 1250p) announcement last week. Carlsberg says this today -
“Further to the speculation in the weekend press, Carlsberg confirms that it has reached agreement with PepsiCo, Inc. ("PepsiCo") whereby PepsiCo has agreed to waive the change of control clause in the bottling arrangements it has with Britvic. This waiver will come into effect should an acquisition of Britvic by Carlsberg, which has the recommendation of Britvic's board, proceed to completion. Carlsberg is considering its position. There can be no certainty that any offer will be made.”
The newswire says that the market is interpreting this as meaning a takeover deal is becoming more likely. Interesting point about change of control clauses in commercial contracts, I hadn’t thought about that before, but it could be why some other takeover deals fall through perhaps?
Prudential (LON:PRU) - up 6% to 751p - Capital Management Update - Paul - NO COLOUR
Announces a bumper $2bn share buyback, although could be up to 2 years (complete by mid-2026). Also says there’s potential for further shareholder returns. Says it has “significant growth opportunity ahead”.
Buybacks sound good, but the dividend yield is only 2.6%, so arguably this buyback is just in lieu of divis, to get to a similar % shareholder return as, say the 7.6% dividend yield from Aviva (LON:AV.) ). Note that forecast earnings, and the share price at PRU have been in a downtrend for c.18 months.
No opinion from me, as I’ve not properly researched it, just flagging an interesting announcement and an unusual % up move in shares today. Could this be a low for the shares, who knows?!
Belluscura (LON:BELL) - up 8% to 16.25p - Update re convertible loan notes - Paul - AMBER/RED
Tiny equity raise of £300k announced from an investor at 15p. Says it will soon be able to give more details on its proposed convertible loan notes.
I’m wary of this company, under-funded, and a jam tomorrow story for a supposedly revolutionary new product. It sounds financially distressed, and who knows what the terms of the dilution might be for the convertible loans? I’ll be happy to move up to a more positive view once the risks are lower, with proper funding in place, and real profits and cashflows are flowing. I don’t mind missing out on the occasional multibagger, when the vast majority of similar companies are dismal failures and destroy shareholder value. Why take the risk?
Summaries
SIG (LON:SHI) - down 15% to 23.3p (£275m) - Trading Update [profit warning] - Paul - BLACK (AMBER on fundamentals)
More bad news from this low margin building products supplier. It's now expected to trade at a PBT loss in FY 12/2024, conveniently concealed by quoting adj operating profit instead (which ignores its hefty finance costs from a 300m Euros bond). A weakish balance sheet, no divis, and no signs (yet) of any trading recovery, mean this looks weak. However, optimists might be factoring in potential upside once its markets recover. I'm being generous with AMBER.
THG (LON:THG) - up 2% to 63.2p (£875m) - Trading Update (AGM) - Paul - RED
An in line with expectations update. THG likes to focus on EBITDA only, but I reiterate below how misleading these numbers are here. It's actually still loss-making, and with a dangerously weak balance sheet. The valuation looks nuts to me for such a poorly performing business. Deal with Frasers - not enough info to assess it.
Paul’s Section:
SIG (LON:SHI)
Down 15% to 23.3p (£275m) - Trading Update [profit warning] - Paul - BLACK (AMBER on fundamentals)
SIG plc ("SIG", or "the Group"), a leading supplier of specialist insulation and building products across Europe, issues a trading update for the year ending 31 December 2024 to date.
What’s gone wrong? No improvement in demand, with sales in May & June continuing at -7% vs LY (on a like-for-like [LFL] basis).
Reduced profit guidance -
“Given the weaker than expected trading in recent weeks and a consequently more cautious view of the timing of any potential market improvements during H2, the Board now expects our 2024 full year underlying operating profit2 to be in the range £20m-£30m, which is below the current analyst range.3”
3. Company collated analyst expectations is for Full Year 2024 underlying operating profit (EBIT) of £41.1m, within a range of £36.7m to £43.0m, as at 21 June 2024.
Good clarity in the footnote above, which is much better than the nonsense we had to deal with last week from YouGov (LON:YOU) , spending ages trying to find out what the old guidance was, and what the new broker forecasts are. It’s bad news from SHI, but is at least presented clearly.
Forecast revenue for FY 12/2024 is c.£2.7bn, so it’s barely above breakeven now, with an operating margin that looks to be c.1%.
An annoyance with SIG is that its name is just 3 letters, and the ticker is a different 3 letters. Let’s hope companies will go back to having proper names, not just some seemingly random collection of 3 letters.
Checking our previous notes, neither Graham nor I like this company. It’s a low margin, long-term disappointer, selling lots of stuff from many locations, but not really making any money. So what’s the point in it existing? Why would anyone want to own shares in this? I suppose hopes for a cyclical recovery would be the main reason. To be fair, we’re not yet seeing any significant cyclical recovery starting in other companies we’ve looked at in the building supplies space. Although it seems reasonable to anticipate some recovery maybe later this year, or in 2025. Housebuilders are making positive sounds about a recovery next year, for example.
Outlook - going back to today’s profit warning, it provides the expected split between H1 (to June 2024) and the full year (to Dec 2024) -
H1 -
“Based on the performance in the year to date, the Board now expects the Group to report an H1 2024 LFL sales decline of c7%, and an underlying operating profit in the range of £10m-£12m.”
FY - this bit below sounds to me as if there’s plenty of scope for the figures to change again, up or down -
“Given the weaker than expected trading in recent weeks and a consequently more cautious view of the timing of any potential market improvements during H2, the Board now expects our full year 2024 underlying operating profit to be in the range of £20m-£30m, which is below the current analyst range. The increasing benefit from productivity and cost initiatives underpins our continued expectation of a stronger second half. The extent of this improvement is subject to the evolution of demand conditions, particularly given market uncertainties in France and Germany, and recognising the sensitivity of operating profit to relatively small movements in sales.
Whilst market conditions remaining challenging in a majority of areas, the Board continues to expect its strategic and commercial initiatives to benefit medium term margin and profit growth, also supported by meaningful operating leverage when market volumes recover.”
Any broker updates? - nothing I can find, but since the company itself has given revised profit guidance, then we don’t really need any more information from brokers.
Going through the numbers myself, the previous years adj operating profit was £53.1m (on £2,761m revenues) for FY 12/2023, and £80.2m in FY 12/20222. So with £20-30m now expected for FY 12/2024, there’s a worryingly negative 3-year trend of profit falling.
Worse still, the infuriating recent trend for companies/PRs to quote operating profit, conceals the full picture, which of course is why they do it, quoting misleading EBITDA or operating profit measures. SHI has large finance costs in its P&L. Eg FY 12/2023 saw £53.1m adj operating profit, but only £17.4m adj PBT. There were also £49m of additional costs adjusted out (mostly £34m goodwill impairment charges). So it was loss-making at a statutory level in 2023.
2024 results - it’s guiding £20-30m adj operating profit, so if net finance charges are unchanged on 2023, that means c.£35m to come off, hence I make the adj PBT for 2024 being a loss of £(5)m to £(15)m.
Balance sheet & cashflow - the 2023 results show that free cashflow was only £4.2m, and in 2022 it was £10.6m. Both poor. I imagine given the lower profits, that 2024 could see a cash outflow, unless they can massage working capital positively.
The Dec 2023 balance sheet showed £82m NTAV. However, it has large inventories & receivables, which has to be financed with substantial gross debt. Hence why the finance charges are so high on the P&L. It seems to me that SIG is basically a bank for its customers, giving them credit on sales, and having to fund the hefty finance costs of that through bank borrowings.
Paul’s opinion - this looks a lousy business. It’s not making any profit or cashflow. However, maybe this is bottom of the cycle earnings, and a recovery might kick in at some point in the future?
It’s financed mainly with a 300m euros 5.25% bond, which matures in Nov 2026. So no immediate crisis there, but if recovery is slower than expected, then refinancing this in 2026 might become an issue. The last results said the bonds had incurrence based covenants only, which I had to look up -
“Incurrence Covenant means a covenant by the borrower to comply with one or more financial covenants only upon the occurrence of certain actions of the borrower including, but not limited to, a debt issuance, dividend payment, share purchase, merger, acquisition or divestiture.”
So that looks OK for the time being re debt.
Overall, with too much debt, no divis in prospect, a series of disappointing trading updates over the last year resulting in it now being loss-making at the PBT level, I can find nothing of any interest in this share other than hoping for a trading recovery which may or may not happen.
The advantage of large revenues (c.£2.7bn pa here) is that a rise in demand can drop through nicely to the bottom line. Hence I don’t want to colour code this negatively, just in case a trading recovery begins and sees the shares recover.
So I’ll just sit on the fence with AMBER, but that’s being generous for what just looks a poor quality business. Maybe it needs new management to do a massive restructuring to strip out tons of cost, and focus on higher margin products? That would be expensive though. Definitely not for me, but good luck to anyone here holding SIG.
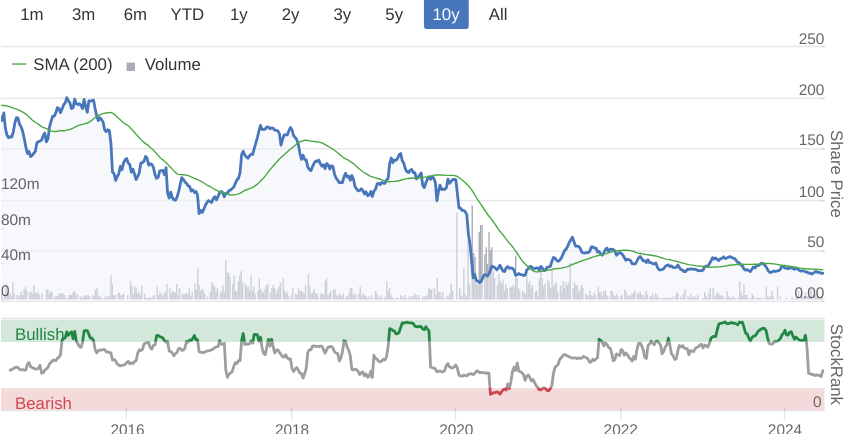
The 10-year chart below shows a dismal picture, with the current price at/near the 2020 pandemic lows again -
THG (LON:THG)
Up 2% to 63.2p (£875m) - Trading Update (AGM) - Paul - RED
THG PLC operates three distinct businesses in Beauty, Nutrition and Ingenuity, each scaled from the UK to hold global leading positions in their respective sectors.
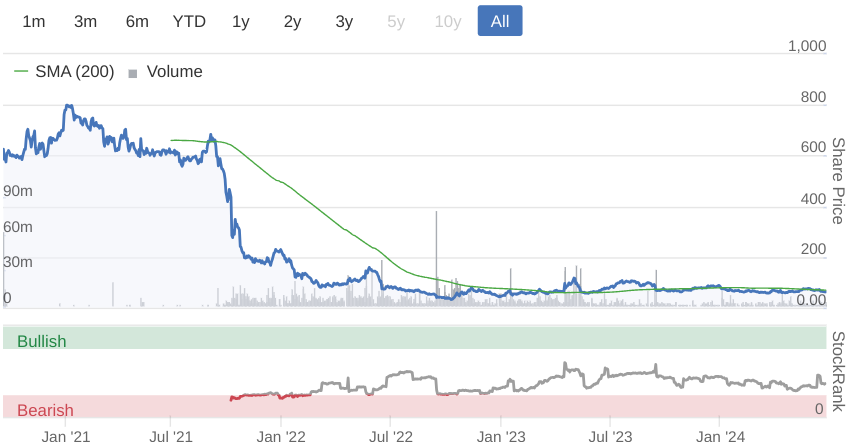
I see THG as a dismal, over-priced, over-hyped float in the pandemic. The share price now is >90% down on the Jan 2021 high of c.800p.
See my review here on 10/4/2024 for a whizz through its (bad) numbers for FY 12/2023 and why I think this share could end up at zero. The upside case is that on £2bn pa revenues, a significant improvement in margins could transform it into a profitable business in the future, maybe?
Today’s trading update sounds in line -
“Group performance on track, FY 2024 guidance unchanged”
For context, that means more losses in both 2024 and 2025, albeit shrinking.
At least revenue seems to be rising now, but I’m more interested in the size of the losses -
“Q2 will represent the third consecutive quarter of year-on-year (YoY) revenue growth. The Group's performance is underpinned by positive trading within the Beauty, external Ingenuity and offline Nutrition businesses, which have helped offset continuing FX headwinds within Asia. Guidance for FY 2024 remains unchanged[1].
THG shows its calculation of analyst consensus on its website, which is really helpful. Less helpful is that it only discloses fantasy EBITDA profits, which bear no similarity with commercial reality, since it capitalises about £79m of development spend, and EBITDA also ignored the heavy physical assets depreciation charge, heavy finance costs (£80m LY!) on its large debt pile, and other adjustments. Put all the real world costs into the pot, and THG remains loss-making. It’s a great example of how misleading & dangerous EBITDA-based valuations can be.

The StockReport thankfully uses PAT, and here we see below the lighter blobs (forecasts) are still losses of £(108)m in 2024, and £(76)m in 2025.
As I always ask, why is this company still valued at £875m, when there’s hardly any growth, and it’s bumping along generating losses every year? With a weak balance sheet that was heading towards NTAV of £(200)m negative when last reported?

There’s some additional upbeat-sounding commentary about each of the 3 divisions, see the RNS.
Deal with Frasers - various elements to this, including THG selling its luxury websites to FRAS, price undisclosed. Given that they generated sales of £43m, and were only “broadly breakeven” in 2023, then I’d be surprised if the proceeds were anything other than very modest, maybe £5-10m at a complete guess? So this is nothing to get excited about.
Other elements include FRAS using THG’s services in Australia, and FRAS stocking some of THG’s products in-store. As there are no financial details, I can’t judge if any of this is significant or not.
Paul’s view - as always, I’m not trying to predict the future. That’s your job! All we do is review the facts, figures, and forecasts on today’s date. And they remain very poor with THG. The market seems convinced that it can execute a turnaround, so we’ll just have to wait and see. I don’t see any sign of this yet being a viable business at all. Happy to revise that view once the facts change. As things stand though, it remains a clear RED.
Since IPO -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

93 comments
Prudential (LON:PRU) Held stock for some while nearly at a 10yr low getting despondent with the stock but reluctant to cut losses, liabilities reducing and thinking there has to be only upside from here. Divi yield not inspiring. Expected to grow EV by 50% over 3 years. SWS has them 63% BFV. Comments welcomed.
Supreme
Seem to have paid a high price for their acquisition .
They bought a company with 3 million assets losing circa 300k a year for 15 million .
Not saying it’s a bad deal As they will absorb a lot of the operating costs .
But definitely a great exit for Clearly directors / shareholders who will be breathing a sigh of relief having managed to exit a loss making / break even company for a tidy sum.
Supreme have overpaid in my opinion but if the numbers add up for them then probably an ok deal .
SIG (LON:SHI) trading update had a bit of an interesting nugget.
I don't know enough about the company to exactly know what the two phrases means in terms of products....
But they were clear to point out that why "UK Interiors" had a disappointing performance, "UK exteriors" had a good performance.
Given the context (SIG makes insulation and other building products?) it seems like maybe new construction rates/volumes are recovering nicely. However, renovation activity on existing homes, as well as the final renovation of new homes (last stage of the build) has not yet recovered.
Which could have all sorts of interesting read-across to other "interior" and "exterior" companies.
Eurocell (LON:ECEL) , Topps Tiles (LON:TPT) , Headlam (LON:HEAD) , Likewise (LON:LIKE) , DFS Furniture (LON:DFS)
Supreme (LON:SUP)
Some interesting detail of the deal announced today in this talk between CEO Sandy Chadha and Paul H:
Supreme (LON:SUP)
Not unexpectedly an announcement about mineral water has brought on a fierce debate here on vaping.
Whatever your views on vaping, Supreme is an industry leader in terms of responsibility. Please read this before you say otherwise:
https://www.stockopedia.com/sh...
Supreme (LON:SUP)
Whatever your views on vaping, Supreme is an industry leader in terms of responsibility.
Yeah right - thats a pretty low yardstick - and are they even meeting their own yardsticks?
on 18/10/2023 they said
Age-appropriate flavours only: The naming conventions of all flavours across the 88vape range will be simplified, for example "Peach Dream" will be become "Peach" and "Sweet Strawberry" will become "Strawberry" to reduce the shelf appeal for underage vapers. Any flavours which are likely to be more appealing to underage vapers will be removed entirely from the range.
As of today those very same names they agree are targetted at kids and will be removed are still front and center on the website i linked . Clearly they are not even actioning their own promises here - so i take point with them being industry leading ref responsibilty - clearly they dont mind still using the names that kids love still judging by their website. Note if they were responsible they would have given wide berth to stuff like this targetted at kids from day 1 ! not some lip service reponse while taking no action.
Note they say they recommend vapes are not kept near confectionary - they could demand and refuse to supply retailers who use such tactics.
IMHO clearly that release from October 2023 appears to be appeasement related guff to gain time for tougher measures to be avoided that would have hit them harder. Ie sound like you are doing something to minimise harsher rules being introduced.
Paul if you get a chance could you take a look at CMCX from last week
thanks
Hi alex,
Yes I'm intending to circle back to CMC Markets (LON:CMCX) at some point this week, sorry for the delay. I got a bit bogged down in a half-written section last week, and I find it's best to just let it settle and then come back to it fresh a few days later, when that happens. Sorry about that.
Regards, Paul.
Pets at Home (LON:PETS) Useful analysis here from a respected investment writer. I like the shares at this price, bearing in mind that they carry and are priced for an overhang from the CMA inquiry, so could move either way in due course.
SIG (LON:SHI)
Paul: "An annoyance with SIG is that its name is just 3 letters, and the ticker is a different 3 letters. Let’s hope companies will go back to having proper names, not just some seemingly random collection of 3 letters".
Not completely random. It was once Sheffield Insulations Group but then, no doubt, some consultants came along and charged a silly amount to change the name to initials.
Maybe the next set of consultants will see fit to shorten it further in exchange for a 6 figure engagement fee.... SG maybe?
Like what happened at abrdn....
Kier (LON:KIE)
Have been adding to my position the last 2-3 weeks as I believe infrastructure will play a major role the next 5 years in the British economy (especially with a Labour government on the way).
Kier (LON:KIE) dividend will climb to 7.50p in 2026 and with a FCF of at least £110m pa this looks a great investment. Cash balance will increase to £150m in 2026 leaving room for plenty of buybacks.
All the best
Kier (LON:KIE) Hi Yannios
I suspect you're correct re infrastructure spend increasing considerably. I'm just nervous that history is littered with projects that overran dramatically & contractors that underestimated equally dramatically...... I'm in Scotland and a couple of examples spring to mind:
Aberdeen Western Peripheral - a straightforward (to the layman's eye) road over a greenfield route. Original estimate £295m - £395m; final cost £1bn+. Carillion went bust & the other JV partners were Joint & severally liable.....
Edinburgh Trams - pretty old technology and existing underground services shouldn't have been a shock. Costs faily hard to pin down, but around £500m at time of proceeding; £836m for a truncated scheme.
Big contractors have me nervous......!
According to Balfour Beatty’s most recent annual report, only 10 per cent of UK construction work is carried out under a fixed-price contract, compared with 50 per cent in 2018.
A lot has changed since the demise of Carillion and Interserve in this sector hence the opportunity in the likes of Kier (LON:KIE) and Costain (LON:COST) (I hold both) as their share prices don't reflect the reduced risk imo.
Thanks for clarifying this. We have covered this before as the change in these contracts has made most companies in this sector great investment opportunities.
All the best
Fair enough not for you , but I don’t understand what all these have to do with Kier (LON:KIE) , it’s mew management and the forward numbers I have provided.
All the best
The water industry's next 5-year investment period announcement was delayed from 12th June to 11th July due to the election.
This will be the draft determination and will sign-post the water companies likely scale of investment over the following 5-years. Whilst things can still change between July and the final determination in December it will certainly be pretty close the final outcome.
I suspect that all contractors working for water companies will get significantly more work over that period as the level of investment is huge compared to all previous periods.
I suspect that there will be a number of winners with the likes of Kier (LON:KIE) Costain (LON:COST) Galliford Try Holdings (LON:GFRD) and many others all benefiting.
Have you looked at any of these as well Yiannos? I'd be interested in your thoughts. I am still looking at some of the others, so haven't completely come to a conclusion yet, but I agree with your thoughts on Kier.
Have looked at them briefly Costain (LON:COST) and Galliford Try Holdings (LON:GFRD)-nothing wrong with them.
Went for Kier (LON:KIE) for its biggest revenues , has rejoined the FTSE250 so obviously more established funds will be involved and better covered by biggest institutions. Also Kier (LON:KIE) FCF’s over the next 3 years make more appeal to me.
All the best
I agree on the infrastructure theme, Yiannos1. But how about playing the theme via the plant and equipment hire companies? To my mind, they are less risky and offer higher margins and returns. VP (LON:VP.) and Speedy Hire (LON:SDY) are still not far off lows despite recent strength. Interest rates are more of an issue today for equipment hire firms, but could provide more upside if they start to drop.
Kier (LON:KIE) is the theme!
BnB ,
What’s your opinion on the Bitcoin miners and the role they will play in AI and the use of their data centres?
Core Scientific (NSQ:CORZ) was a takeover target from NVIDIA (NSQ:NVDA) but they have rejected it. Then an announcement was made that they have signed an agreement with AI hyperscaler CoreWeave expected to generate more than $3.5B in revenues over the 12 year contract.
Today there seems to be aggressive buying on the $15 and $20 January 2025 calls.
All the best
Yiannis1
I never go near anything bitcoin-focused - more fool me, perhaps - so I can’t offer an opinion.
Yiannos1 BTC mining is all over the place. Best given a wide berth. Proof of Work moved over to Proof of Stake over at Ethereum (greener than youtube now) Layer2's promised but undelivered too - but PoW is still poor with no BTC roadmap out. As a previous maximalist (BTC since 2016) And having waited for the killer app; I now realise the killer app is us. As they say - if you don't know what the product is YOU are the product. (Or now horror of horror. BTC Eth ETF investors). Buy Gold instead. Or anything. Best of luck
Just seen this and to be honest I haven’t got a clue on what exactly are you on about and personally not interested about sentiment opinions about different products (unless backed by numbers and/or fundamentals).
I am interested about the data centres of these Bitcoin miners and not the mining itself. Mining on its own at the moment is not profitable -But the mining data centres WILL play a crucial role on the AI development/advancement. That’s why NVIDIA (NSQ:NVDA) tried to acquire Core Scientific (NSQ:CORZ) recently.
All the best
Interesting read and I work for one of the companies mentioned in the replies. The pipeline of work and opportunities is massive, especially the infrastructure work. The contracting world compared to 10 years ago is very different, especially for the tier 1 contractors mentioned here. Certainly the company I work for is trying to rebrand as a specialist infrastructure company rather than a builder, and hopefully a premium share price will follow. Hope the investment pays off.
Gas is a fluid. Just sayin'
obviously someone else who has had to sit through Navier Stokes lectures... I didn't want to point it out.
CMC Markets (LON:CMCX) Following up on my comments last Thursday I see stocko current year 25 forecast has increased from 17.1p to 18.2p! So a decrease on 2024 (20p), makes zero sense noting the H2 run-rate and guidance, won't be helping the screening outputs.
Paul. Don't you know this is a 'Heat Bomb'.?
Climate dread has infected everything. I am just surprised someone hasn't blamed it on Brexit.
You are so right, my garden is growing at an unbelievable rate, this is being replicated around the globe. The climate fanatics need a serious fact check the world is getting greener all because of CO2 the fertiliser in the air.
This is a misunderstanding. Of course it's well known that CO2 makes plants grow. It's necessary but not sufficient for growth. They also require optimal temperature, humidity & moisture. And so we see the forests of the Amazon starting to die off because the temperature is too high, and rainfalls tarts decreasing.
Temperature rises nearer the tropics will, and do, mean that daytime wet bulb temperatures (ie including evaporation effects) will exceed that at which humans can live. The first signs are arguably increasing kidney disease in such workers. Despite CO2 causing plants to grow then, the result in large parts of the globe will be reduced crop yields due to lack of water or excess heat.
In case there's any doubt, the basic physics of this was discovered 150 years ago back in the 19th century.
https://www.imperial.ac.uk/new....
And that's not getting to ocean acidification due to the dissolving of higher amounts of CO2, which is bad for any organism with an exoskeleton, from diatoms to corals, because more acidic water makes it hard to make their exoskeletons, or they even literally dissolve.
I could continue to the effects of rising sea levels caused by 1) the thermal expansion of oceans and 2) melting of land-based ice, which continues apace.
martinc
This is a misunderstanding.
is it really a misunderstanding or are you trying to spin your own narrative here.
basically JohnLa said the world is getting greener - are you denying that is factually correct?
i dont take point with your specific points raised but you seem to be missing then main thrust of the JohnLa's simple point and going of on some tangential point scoring exercise.
This is a dangerous subject for a share analysis website given the blindness of many to the problem. The idea that there is some solace in plants growing faster (because there is more carbon in the atmosphere) is as ridiculous as building cities in the desert and using air conditioning!!
This is a dangerous subject for a share analysis website given the blindness of many to the problem
100% agree - if the world is getting greener though lets not pretend it isnt or criticise someone for starting facts that are not ibeing disputed.
The fact that we as humans may not want to move people around the world to areas that will be more beneficial for a "warming world" (for political and perosonal reasons) doesnt alter the fact that is probably exactly what we should be doing (as we have done for all of human history since before manmande warming was a thing) if we want to ensure the majority of the world has conditions that are fit for humans to live. Warming aint gonna gonna go away soon based on current projections and its fairly obvious people will have to cope with the realities of that whatever they think should be done in an ideal world.
is as ridiculous as building cities in the desert and using air conditioning!!
I aint for one aint going to tell people that they cant live where they want in their own country - so if people want to live there and go down that route it is what it is however ridiculous you may think it is. Hopefully with solar and battery improvements even that can be done in sustainable fashion?
Nature tells us what we are going to do in the long term. Anyway not interested in arguing with you......
The forests (jungle?) of the Amazon is dying off at a faster rate by way of chain saw. Under a vast canopy a micro-climate is maintained, once this is lost the ground dries out so basically if it's not bust don't mess with it.
Isn’t this supposed to be a place to talk about the markets and not a forum for climate change discussions?
SIG (LON:SHI) Can someone update me on what the colour coding BLACK means on Paul's reports? Thanks in advance.
Morning dfs12,
"SIG (LON:SHI) Can someone update me on what the colour coding BLACK means on Paul's reports? Thanks in advance."
It's what I use to flag up profit warnings, useful for my summary spreadsheet, as profit warnings over several months can be quickly seen at a glance.
Then we also give a colour for the fundamentals. I know it's a bit confusing, sorry about that.
Regards, Paul.
Brilliant thanks
Morning Paul.
Since you have expanded the info in the header, it would make sense to list the supplementary colour key, ie PINK, GREY, BLACK
On a general note to all contributors, please remember to use the @ ticker lookup, as it makes it easier to understand posts, especially in unthreaded catch-ups later in the day.
Black is Profit Warning.
Renold (LON:RNO) has been trending downward this month down around 15%. Any reason to worry or do we reckon people just taking profits.
Hi Ugochukwu
There has been no news posts for Renold (LON:RNO) so it is all speculation following an amazing run up.
So it is probably a number of people exiting to move on to the next exciting thing (call them traders if you wish), people banking profits on the retreat, remember this was 30p not a long time ago so there are those sat on a good gain, and then people who bought at the high and now are sat on a loss and cutting and going.
I suspect there are folks who would see a precipitous chart so cutting now for a reentry later potentially if there is a stimulus to create another bounce, they look for the rise, a small retreat, and then rise again (someone can explain better than me the moving average lines, and price support lines they are looking for on breakouts, I know they exist but I am not that wise on these).
I will be honest I chose to sell and bank the profit and see what happens, like the company, happy to own, but a profit is a profit no matter how small.
No wrong answers, good luck!
Tommy
Same here
AJ Bell refusing to sell for private investors today as the institutions are selling too much volume.
Updated AJ Bell still refusing sales, Stop Loss finally allowed but they aren't actioning them today!
I noticed a lot of large trades today, quite a lot of100k share sales going through. As always the question here is - does someone know something that we don't, or is it just an institution taking profit after a good run up in SP. Of course it is just a gut feeling but I believe the latter and hence am happy to hold my position as it is still 70% up (tough to take when it was 110% up a few weeks ago though!) and I don't want to realise the gains on the position yet for tax reasons. The SP has remained constant all day, lots of people are buying up the shares.
Renold (LON:RNO) are down to 52.18 to buy now.
Tpximpact Holdings (LON:TPX) There's some negative comments on TPX today regarding their refinancing, but to me it looks quite positive. Am I missing something?
Hi planetx,
If you're looking in here do you have any updates on rise in freight costs you wrote about in the SCVR on June 5th? Would a company like Luceco (LON:LUCE) be impacted seeing they have a manufacturing base in China? Happy for others to enlighten if you have views. tia.
Freight rates now 10k a container .
Freight rates are now 10k a container from China with shortages of actual containers .
That’s going to be a direct hit to importers shipping low value bulky items .
Wynnstay (LON:WYN) H124 results webinar this Friday 28.6.24, 1pm, following the publication of results tomorrow (25th). Steve Ellwood, Exec Chair and Rob Thomas Gp FD will present followed by Q&A. Always interesting to hear what's going on in farming even if not invested here. I gather from R4 this morning it's not good for potatoes this year - too much wet weather again. WYN flagged an increase in milk prices & a return of fertiliser sales in March's AGM statement, which will be beneficial. Register here.
Some farmers were planting this year's potato crop before they had finished harvesting the previous year's crop. We have UK farmer friends farming in the South who have struggled to drill grain crops this year due to the sodden nature of the ground. It has been so wet, you cannot even get machinery on the ground.
We have Dutch friends staying with us this week who are farmers. She is also a senior executive with agricultural specialist Rabobank ABN, so she has a good overview. The situation in the Netherlands is dire due to climate change, and they have similar issues to the UK with wet weather. We are about 4 weeks behind where I farm in Scotland but fortunately, we have other sources of income.
To sum up, I think farmers across Europe will have sad looking accounts in 2024 and we will not have much spare cash to splash which will have an impact on agricultural stocks in the supply sector, like Wynnstay (LON:WYN). Your tatties and bread will cost more as the year progresses as well.
Coupled this with other climate change extremes globally, as well as declining yields from reduced fertiliser (from Ukraine) usage 1-2 years ago...
And potentially it's plausible to see food prices keep going up later this year, fueling continued inflation globally
Fertiliser prices have actually fallen a good way. The two key determinants of N-fertiliser prices are the price of natural gas (the source of H2 in the Haber process, which fixes atmospheric Nitrogen) and the cost of energy.
Fertiliser prices (europa.eu)
and the level of CO2 in the atmosphere which is free for those farmers who can't afford fertilisers
Still need N atoms to build proteins and P atoms to build DNA.
Thanks for the link!
Do you have more insight into the time lag between fertiliser application and yields?
My knowledge of this is based on just one or two Bloomberg/FT articles during the time of the crisis in 2021-2022, where I remember reading that it greatly impacts future year's crops rather than current year.
Hi Boon
Quite a bit ... I am an agricultural chemist by training and a member of the Royal Society of Chemists, so it is kind of my area.
The majority of applied N has disappeared from soils within 60 days, either by uptake by the crop, leaching into river systems (causing eutrophication), or soil microbial uptake. Obviously, anything not taken up by the crop is expensive on the farmer's pocket and the environment which is why we have nitrate free zones around the UK.
This means that the timing of NPK application is critical. It depends on the crop and whether it was Spring or Autumn drilled.
Here are a couple of links if you are interested:
Wheat nutrient application timing | Yara UK
Agronomy | Free Full-Text | The Effect of N Fertilizer Application Timing on Wheat Yield on Chernozem Soil (mdpi.com)
Incidentally, Yara International ASA (OSL:YAR) , a Norwegian fertiliser company has not been this cheap for 10 years. I don't hold it. My trade, when it became clear that Gazprom would no longer have the European gas market, was to short European N-fertiliser stocks and go long USA N-fertiliser. N requires natural gas as the source of the H2 required in the Haber process, and it seemed an uncomplicated way to arbitrage the US and European gas market at the time.
I think the Bloomfield/FT articles you refer to must be talking about wheat sown in the Autumn and harvested the following year.
I am curious Boon why you are interested. It must be a quiet day when we are all talking about agriculture which, let's be honest, does not normally get the pulse racing.
Thanks for the links and the detailed reply! I'm going to dig and read more.
It definitely has been a quiet day for me... nothing notable in the RNS for my portfolio or watchlists. In fact, its been that way for 2-3 weeks now... eerily quiet on the news front (at least when it comes to my portfolio and watchlist).
Nevertheless, I have a passing interest as I have a whole bunch of fixed rate savings maturing in the next month or so. Been taking more of a (casual) interest in UK inflation.
Quiet day on the RNS front for me to, however, my stocks all over place.
Metals Exploration (LON:MTL) digging deep and up 10%, chains come off at Renold (LON:RNO) down 6, CMC Markets (LON:CMCX) good bet on this one, up 4 then fell to ONLY 2, and even Card Factory (LON:CARD) had something to celebrate up 4% at the close, funny old day.
As a farmer we have coped with bad weather often but now it is much worse because of the shortage of staff/ contractors/tractor drivers etc (Brexit) crops could never get planted or harvested
Finding reliable qualified staff is now a nightmare and we are an ageing industry. I did a consultancy contract quite a few years ago for the Scottish Executive (i.e. pre devolution) when I worked for SAOS.org looking at the labour market in agriculture. The average age then was over 45, and today it is 59. I am 60. The result of that work was we set up the machinery ring network which today in Scotland consists of nine farmer-owned companies turning over £90 million a year.
The labour issue and climate change are throwing up huge risks and opportunities in agriculture, and there is a lot of clever and highly investable stuff going on in precision agriculture, robotics, genetics and plant breeding. My Rabobank friends told me yesterday over dinner that a lot of the high-end technology utilised in the Dutch glasshouse sector was now moving into the field.
in my view, for anyone interested in agricultural exposure in the UK, I would take a look at vertically integrated Cranswick (LON:CWK). I hold.
I was born in a tied cottage, rent fixed by law at 6 shillings a week. When the law changed, freeing these cottages, their occuppying farm labourers were encouraged to shift to Council housing. This led, along with the mechanisation of tractors and labour redundancies, to the staff shortage we now experience, what with the Poles who were homed in old caravans returning home after Brexit. The answers have always been in the hands of politicians most of which have never held a spade.
In reply to jamesalastair.
Thank you for the contributions today - it is the sort of tangential expertise that I love discovering on this forum.
Cranswick (LON:CWK) is one of my long-term core holdings. I'm aware they're still dealing with one cessation of pork exports to China, but the Spain/China situation shows the geopolitical angle isn't really improving.
One part (and only part) of my rationale is that our beef consumption needs to moderate, and pork/chicken are the obvious beneficiaries of this. Would be interested to hear more of your thoughts on the stock.
Thank you ... I always learn something, whether from Paul's analysis, or the entrepreneurs like PlanetX. I'll maybe approach stock and do a stock pitch for Cranswick (LON:CWK); maybe a whole sectoral review might be of some interest? So little of quality is available for retail investment across European bourses. Cranswick (LON:CWK) stands out.
I always get my El Nino's and La Nina's mixed up, but I think El Nino is due to end this year. This typically means increased disruption of the jet stream, producing generally warmer and wetter periods (warmer air holds more water vapour). This buffers any climate change factors, so if temperatures naturally increase (say due to Sun activity?) El Nino will amplify them. FWIW
Climate_the_movie of interest unless the elites have taken it down.
Hi James,
some farmers were planting this year's potato crop before they had finished harvesting the previous year's crop.
Do you not have a winter where you are? I wouldn't put my seed potatoes in before April in Wiltshire. Other than this, canny farmers always have Plan B, this year instead of the Autumm planting of winter wheat where impossible they were quick to sow spring barley in early Spring.
This recent weather, wet winter/spring and hot summers, reminds me so much of 1975/6. Same scenario of tractors bogged down in mud, inability to harvest spuds hence very high prices after a wet spring. This was followed by one of the worst droughts I can remember with empty reservoirs and water tankers moving it around. Not a heat wave by current standards as far as I remember but extended lack of rain until .gov appointed a minister for drought which promptly made it rain soon after. This does seem definitely more serious. :-(
Farming discussion maybe off topic but I have enjoyed reading the posts.. My husband was a vet (sadly he died last year) but the ways and wyles of the weather dry, hor, rainfall or lack of gas a massive bearing on herd/flock health and therefore marketability.... As for the Amazon the more trees cut down the more soil will erode into the rivers, the fewer trees the less moisture will evaporate from the trees into the atmosphere... Result less daily convectional rainfall... So drier remaining forest and lower Amazon rivervlevel... That leads to less fresh water entering the South Atlantic mixing with the sea water which in turn affects the production of the ocean currents which rule the weather systems.... This is just my take but gosh I find it interesting.....
Speedy Hire (LON:SDY) - "Focused on delivery" (link to note: https://www.equitydevelopment....)
Headline FY24 results were behind the prior year as expected but the underlying core hire and services performance was solid in a tough market. There is more to come from the Velocity strategy but material new business wins, enhanced financial control and the company’s growing position in clean energy equipment all augur well for future progress. Management expectations are unchanged and Speedy is trading ahead of FY24 in the first two months of FY25.
Velocity is one year into its five-year strategic plan. This is still very much an enabling phase – though the capacity for growth already exists – and investment in operational and customer-facing workstreams are evident and planned. This holistic approach is intuitively appealing and seeks to build on Speedy’s very strong technology position. The execution appears to be on plan and delivering improvements in margins and returns will be the measure of progress in due course.
Supreme (LON:SUP) - Acquisition of Clearly Drinks - link to research note here: https://www.equitydevelopment....
Supreme has announced the acquisition of Clearly Drinks Ltd., for a total net cash (debt free) consideration of £15m, funded from cash. Clearly Drinks is a manufacturer of specialised canned and bottled-at-source spring water and soft drinks with FY23 annual turnover of £22m and EBITDA of £3.0m. This is a significant diversification, which increases the FY25E contribution from non-vaping revenue streams from £85m (38% of total) to £100m (42%).
The acquisition of Clearly creates a new Supreme Business Category. We estimate that the immediately earnings enhancing acquisition should add £14.7m to our FY25 revenue outlook based on estimated 5%YoY Clearly Drinks growth (pro rata), and (adj.) EBITDA by £2.0m (13.6% margin). FY25E (adj. dil.) EPS increases from 18.5p to 19.8p (+6.7%). Supreme reports full year FY24 results on 2 July offering the opportunity to review estimates and add the medium-term impact on earnings.
I think there is a tendency to see SUP as a vaping stock and people forget about the other sides of the business. No doubt there is risk with vaping regulation but think this is more than priced in. I am long.
Agree Michael on Supreme (LON:SUP)
This takes their non vaping business to 40% of revenues and with recovery in lighting profitability should be much less heavily weighted to vapes.
What I think investors misunderstand on this stock is the companies distribution network. They are becoming a key supplier for major brands and that is valuable. They’ve been very astute in purchasing verticals that are both accretive in nature but that have extra capacity - think of how much they’ve paid for some very good plant capacity compared to the level previous owners invested in that plant. It’s a super return.
Vaping isn’t going anywhere and Supreme (LON:SUP) are the most responsible supplier out there irrespective of what people think about vaping per se. Profits are unlikely to keep growing though as it has probably reached peak maturity so the switch to growth in other areas is vital.
The energy drinks market is huge and they’ve just bought capability and capacity in that space so watch out for that.
Far too cheap imo. I am also long.
Using vaping to get smokers off cigarettes is arguably justifiable but promoting vaping as cool to kids is immoral & dangerous. Deserves a very low multiple.
It's illegal to sell vapes to anyone under the age of 18. I don't know why Supreme would promote vaping to children?
To the best of my knowledge it doesn't but I can always be wrong, so if you have any evidence please share it.
I think Buyandverify is refering to the fact that vapes are available in flavours such as "Strawberry....Dripping CustardA classic, creamy custard blended with caramel and vanilla." These are flavours likely to appeal to children.
Having seen the problem of vaping at my son's school, I. personally, am sympathetic to Buyandverify's point of view.
I am still staggered that vapes are available other than on prescription to aid quitting smoking rather than on the high street at supermarkets.
I am sure that potentially Supreme (LON:SUP) might make a good investment as has Altria (NYQ:MO, which has been the 7th best performing stock in the US over the past 30 years but it doesn't mean I am going to buy the stock. And by the by Altria's web site makes my skin crawl.
https://www.altria.com/moving-...
Regards
Michael
Supreme (LON:SUP)
I think Buyandverify is refering to the fact that vapes are available in flavours such as "Strawberry....Dripping CustardA classic, creamy custard blended with caramel and vanilla." These are flavours likely to appeal to children.
well said MichaelFBS - its pretty clear kids are target market here front and central even if the company wont publically say that. I might be convinced otherwise if they have taken some proactive measures to ensure their products are not targetted at kids - i suspect its exactly the opposite though with kids being core target. If you go to front page of 88vape website (one of their brands) front and centre is lemon sherbert / pink lemonade / rainbow burst and cherry sherbert shortfills being promoted - about as unsubtle an attempt at targetting kids with product type as you can get imho.
https://www.88vape.com/
Note i am not saying the company are doing anything wrong here - its up to the powers that be to stop companies from targetting kids in such a manner by have sufficiently robust rules - Supreme will justify themselves by saying the retailers should be doing the job of ensuring minors dont buy these items.
Supreme (LON:SUP) vape products definitely skew sweeter in flavour than would seem sensible given the prevalence of vaping in children…
I’d assume these flavours might appeal to quite a few adults smokers too and might help persuade them to vape rather than smoke?
And that just shows you know absolutely nothing about the Supreme (LON:SUP) business or the level of care and responsibility they take in their vaping and manufacture. You’ve made a high horse moral judgement with little to no facts or research. I hope you don’t apply that to your general investing strategy.
As investors we can make choices where we invest
I choose not to invest in tobacco or vaping stocks- I may miss out on profits but that’s my choice & I sleep better at night. Supreme (LON:SUP) seems a well run business but its choice to be involved with vaping makes it a no go for me- each to their own
Well said Rebecca
Like you, I do not invest in tobacco or vaping stocks on moral grounds. There is no benefit from tobacco. It only serves to kill people and raise taxes. Vaping is not much different. Nobody can reasonably say they are not aware of the dangers of smoking. There are many other stocks to choose from.
One and only beneficial affect of smoking is helps prevent flare ups of Ulcerative Colitis and keeps it in remission. Vaping dosn't seem to have an effect.
Exactly AG. If people choose to invest in the likes of Supreme (LON:SUP) or Altria (NYQ:MO) then that is there call, it is up to them and I'm not going to go around throwing orange powder over ancient rocks.
Face to face I might have a discussion about whether this is the best place to allocate capital, as I see no societal good in vapes as marketed at the moment. Besides there are another 46,999 (or so) other stocks in the world in to which one can put money to work.
Buffett and Munger had the opportunity to buy a chewing tobacco company a while back and turned it down on the grounds that they did like the product even though it made sense from an investing perspective.
Regards
Michael
Michael, ‘the societal goods’ that come from vaping is a persons better overall health compared to smoking plus far less cancer / breathing complications thus less NHS spend treating smoking related diseases - that’s quite some societal good IMO
on flavours - plenty of adults have a sweet tooth too, however my favourite flavour and extremely popular is Red Astaire (cherry menthol) made by a company Supreme (LON:SUP) acquired - a very savvy move.
Michael, ‘the societal goods’ that come from vaping is a persons better overall health compared to smoking
For anyone who has swapped from smoking to vaping that’s brilliant - we are at a point where the vast majority of newer regular high use vapers would not have been long term smokers - the long term decline in smoking rates is clear and waaaay pre dates the vast explosion in vapers.
So if 80% of younger vapers had no material long term smoking issues and only vape because they can we are creating a national long term addiction and health issue that would have not existed to anything like the degree we have had vsoing been limited to prescription only.
these so called responsible companies all take advantage of our lack of planning. Perhaps it’s too late now to get the masses to stop but it’s all also sad when the % of long term smokers was always going to decline further.
My morning smallcap tweet: Pride comes before a crawl
SIG (LON:SHI) R&Q Insurance Holdings (LON:RQIH) Belluscura (LON:BELL) Supreme (LON:SUP) Aptamer (LON:APTA) Woodbois (LON:WBI) Tpximpact Holdings (LON:TPX), tinyBuild (LON:TBLD), Dewhurst (LON:DWHT)
◄SIG (SHI)► warns FY-Dec24 U/L op profit only £20m-£30m cf F/C £41.1m due to continued subdued trading. [SP=27.35 Cap=323m]
◄R&Q Insurance (RQIH)► sells Inceptum for £11.25m. Also filed application to appoint Joint Provisional Liquidators as expected. [SP=0.1 Cap=m]
◄Belluscura (BELL)► £300k subscription at 15p, an 8% discount, to keep the lights on. [SP=15 Cap=25m]
◄Supreme (SUP)► buys the parent company of Clearly Drinks Limited for £15m. Immediately earnings enhancing. [SP=137.5 Cap=160m]
◄Aptamer (APTA)► wins contracts worth £235k. [SP=0.72 Cap=3m]
◄Woodbois (WBI)► has entered into a $5m trade finance facility, as mooted. 9.5% PA. [SP=0.45 Cap=18m]
◄TPXimpact (TPX)► maturity of the RCF by one year to July 2026, but reduced to £30m from £35m due to a significant improvement in the debt position. [SP=41 Cap=39m]
In line: TBLD, DWHT
Hi Paul I am unable to see anything on company reporting or summaries... Is that my computer?? Not sure, thank you
Hello Pad. Paul and Graham put up a placeholder to allow everyone to start commenting on the days news. The article itself will build throughout the morning so check back later to see more. The day's report is normally completed by 2pm.
Thank you
Morning Pad, and welcome to Stockopedia! :-) You'll get the hang of it - see 1MCF's helpful reply above. Best wishes, Paul.
Thank you