Small Cap Value Report (Mon 24 Oct 2022) - BVXP, CER, FCRM, D4T4, AFRN

Good morning from Paul & Graham! Today's report is now finished.
Weekend podcast - went up on Saturday, as usual. Here is the direct link. I thought it might be helpful to subscribers if I also type up the podcast, so there's a separate podcast summary post here on Stockopedia. Lots of bargains are cropping up, but the stability of the financial system worries me a lot. If people find a written summary of the week helpful, I'll keep doing them, even though it takes a chunk out of my weekend!
This looks a particularly interesting (online) show, with all 3 companies presenting having cropped up on my radar :
Warpaint London (LON:W7L)
Quixant (LON:QXT)
Galliford Try Holdings (LON:GFRD)
Agenda
Paul's Section:
Cerillion (LON:CER) - another positive update from this software company. Its track record is absolutely superb. No issues with the previous accounts - balance sheet & cashflow are strong. It's a bit stingy with the divis, which is helping grow the cash pile, up to £20m now. Shares are expensive on a PER basis, but I can see why, given the outstanding performance since 2020. Thumbs up from me. I'll be interviewing the CEO next week, we're just setting that up.
Fulcrum Utility Services (LON:FCRM) (I hold) [no section below] - profit warning, shares down 26% to 4.4p. A series of problems mean it’s now guiding an adj EBITDA loss of £3m, in each of H1 and H2. It’s taking longer than expected to resolve onerous contracts. “Unprecedented cost increases”. Net cash down to £4.8m at end Sept. “In discussions with its substantial shareholders to ensure that the Group remains adequately funded” - this last sentence is the killer for me, so I’ve decided to sell my small position here, and take a c.30% loss on the chin. I don’t like holding shares that need to raise more cash - the risk of small shareholders being heavily diluted in another fundraising is too high for me. I’ll keep an eye on it though in future. It’s a turnaround situation, that is not going so well, so far. [no section below].
Aferian (LON:AFRN) down 38% on a profit warning, caused by customers de-stocking (an issue that I've been flagging in my podcasts lately). Guidance is revised down, and I look through reduced forecasts from Progressive. Balance sheet has nothing in NTAV. Overall, I can't get excited about this, and reckon there are probably better opportunities elsewhere.
Graham's Section:
Bioventix (LON:BVXP) (£179m) - another strong financial performance, including a huge operating margin, as we always expect to see from this high-quality biotech stock. I’ve just reviewed my last comments on this share, from 2019, and it’s amazing how little has changed. One difference is that currency movements have helped in recent times by adding on a few percentage points of growth to the current year. Shareholders will benefit from a special dividend on top of an increased regular dividend. I remain neutral, despite the stunning financial performance, simply because it is a biotech share that is outside my circle of competence. The revenue growth does look a bit slow, and I think there are significant medium-term uncertainties relating to competition. But it’s hard to argue against a company that has performed so well for so long.
D4t4 Solutions (LON:D4T4) (£98m) (-2%) [no section below] - H1 revenues are up 8% to £8.1 million, at this data solutions company. The adjusted pre-tax loss is £1.3m, but results are always very much weighted to H2. The key ARR metric (annualised recurring revenue) is up nearly 13% to £15.8m, however the lion’s share of this is due to currency movements. The underlying increase in ARR is only around 3%. It sounds like the strong US dollar could keep boosting results for some time, as “a large part of reported revenues” in H1 are derived from contracts signed during previous periods.
With “an increasing number of sales opportunities in the final stages of the funnel”, there is “good visibility” and confidence that full-year results will be in line with expectations. The forecast net income is £3.5m, according to the StockReport, and there is a healthy cash balance of £26m. Deduct that from the market cap and you get an enterprise value of £72m, which is 4.5x the company’s ARR. By the standards of SaaS that is not an excessive multiple, but I think you still need quite a lot of conviction in the growth trajectory to justify it. D4T4 does have a terrific track record of posting consecutive annual profits for nearly 20 years. Along with the hefty cash balance, that helps to offset the demanding valuation multiples here. [no section below].
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Cerillion (LON:CER)
1144p (up 10% at 08:23)
Market cap £337m
Cerillion, the billing, charging and customer relationship management software solutions provider, is pleased to announce an update on trading for the financial year ended 30 September 2022.
Strong trading has continued -
Cerillion entered the second half of the financial year with a strong back-order book* and continued to trade very well throughout the period, including securing the Company's largest contract to date in the fourth quarter.
During the period, the Company benefitted significantly from favourable foreign exchange rates and higher resource utilisation, as well as lower net finance costs and lower depreciation and amortisation than anticipated.
As a consequence, whilst revenue is expected to be marginally ahead of market expectations, adjusted profit before tax for the financial year is now expected to be materially ahead of the consensus market forecast of £10.1m.
*Back-order book consists of sales contracted but not yet recognised as revenue at the end of the reporting period plus annualised support and maintenance revenue.
Clearly that’s good news, although those are mainly one-off factors, or happy coincidences, rather than underlying trading being much different from plan, with revenue only marginally ahead of expectations.
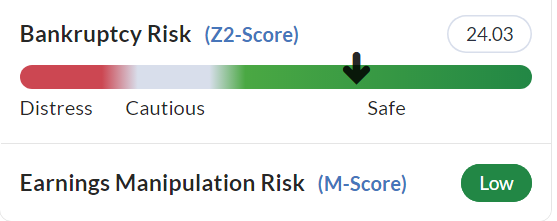
Balance sheet - cash has gone up nicely, to £20.0m, up from £13.2m a year earlier. It was £16.5m at the interim results, so looks to be growing at a steady pace. There’s only a small dividend yield though, of about 1%, so I would expect cash to be growing. Overall, the balance sheet is smashing, I’ve just checked the last one, as at 3/2022, and it’s strong. Hence little to no risk of dilution/insolvency. This is confirmed on the StockReport with good scores below - I find it’s important to check these two items for every company I look at -
Pipeline of new business “remains buoyant”.
FY 9/2022 results will be published in late November, along with another trading update.
Broker forecasts - there are 2 updates today available on Research Tree, many thanks to Liberum and Singers, who both put out great quality research notes, which are easy for us to access, this is so helpful to private investors.
Liberum upgrades FY 9/2022 forecast profit by 19%, which raises FD (fully diluted, for share options) EPS to 33.1p - at 1144p/share that’s a hefty PER of 34.6
My opinion - what a superb company! The growth track record now is tremendous.
As you can see below, something positive happened in 2020, and since then the company’s performance has really taken off.
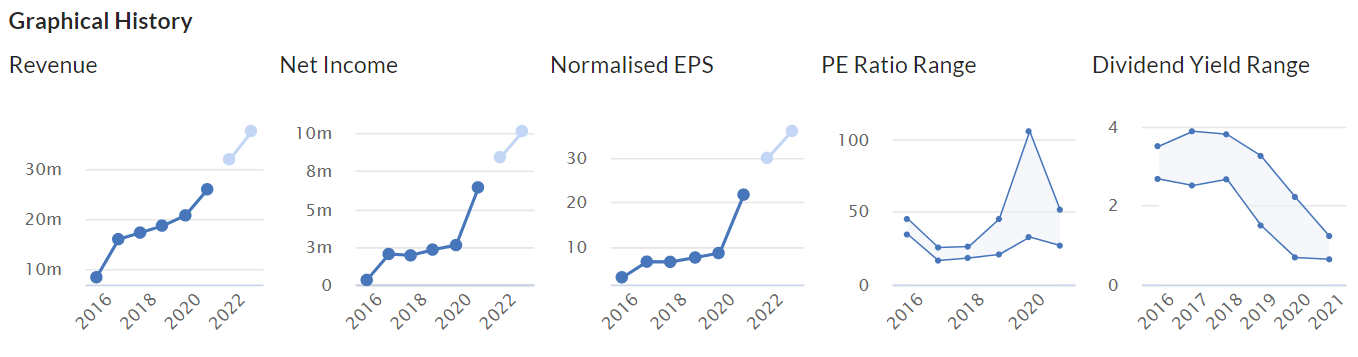
The valuation looks toppy, but when a company is growing like this, there’s a strong case to throw caution to the wind, and pay up for the shares. Obviously the risk is that something might then go wrong, growth slows, causing the high rating to be slashed.
Overall though, providing nothing goes wrong, this share looks expensive, but with a good justification for that.
I’ve reached out to the company this morning, to invite the CER to do an audio interview with me, as it meets my criteria of being a strongly performing company, with an attractive business model, and a sound balance sheet. Update - good news - I'll be interviewing the CEO next week, we're just sorting out date/time, TBC.
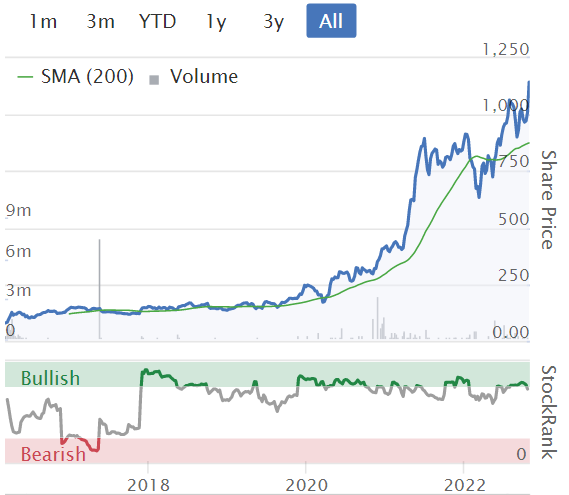
Long-term holders have had a multi-bagger here.
Consistently high StockRank too.
.
Aferian (LON:AFRN)
80p (down 38% at 10:52)
Market cap £69m
Aferian plc (LSE AIM: AFRN), the B2B video streaming solutions company, today announces the following trading update.
FY 11/2022.
I've summarised the key points -
- De-stocking by customers means that device revenues will be 10% less than expected.
- De-stocking also expected to impact FY 11/2023.
- Recurring & software revenues are growing, in line with management expectations.
Updated guidance -
In the light of these facts, the Board now expects Group adjusted operating profit for the year ending 30 November 2022 to be in the range of $7.8m to $8.8m.
When companies change guidance, I wish they would specify the previous guidance, so we can quickly see the change in amount & percent. That isn’t done here.
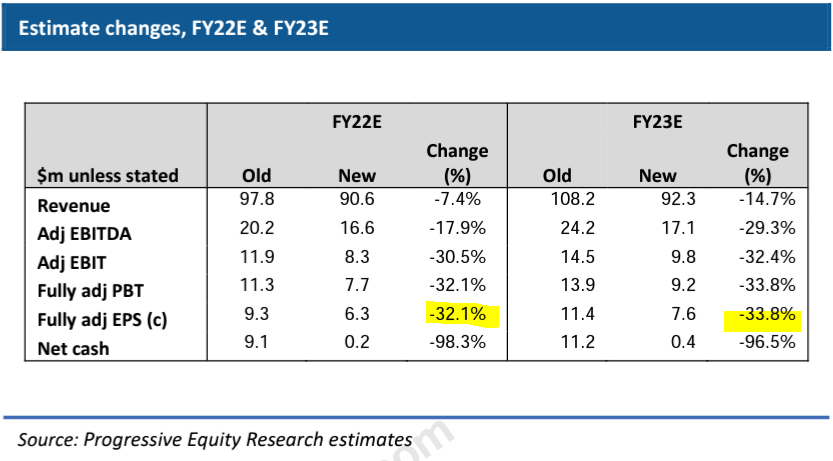
Research update - Progressive is retained to produce research notes, and the table below is their changes today to forecasts. I don’t normally copy anything from broker notes into these reports, because I assume it’s not allowed. However, since Progressive is a commissioned researcher, and publishes these notes available to all, then I’m hoping nobody will mind me showing this table -
.
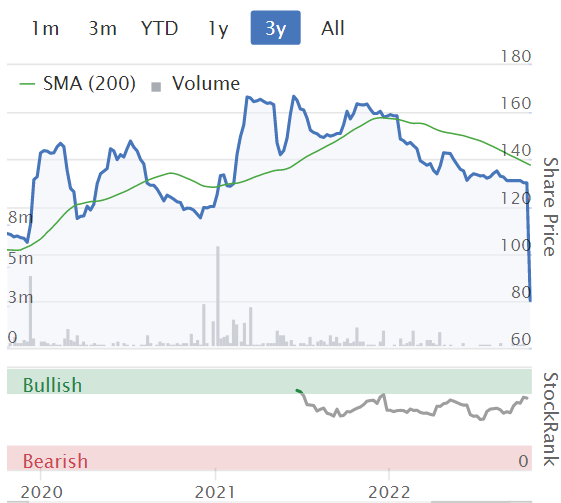
Quite hefty reductions in earnings then, down by about a third. The share price is down a bit more, at -38% - does that make sense? It implies that the market thinks this is a permanent reduction in earnings, but if it’s down to de-stocking, then it could just be a blip, with subsequent years’ earnings going back up possibly?
Note that AFRN reports in US dollars, so the EPS (fd) convert at £1:$1.13 to -
FY 11/2022: 5.6p, PER of 14.3 (at 80p/share)
FY 11/2023: 6.7p, PER of 11.9
Given the uncertain macro outlook, I’m not placing a lot of reliance on 2023 forecasts generally. We just have to accept that we don’t know.
It doesn’t look particularly cheap, even after the 38% fall in share price today. But if earnings subsequently recover, once the customer de-stocking has ended, then the valuation would look quite attractive now.
Aborted acquisition - this is a bit of a shocker. Management has managed to blow $5.5m in costs in fees for an aborted major acquisition. That’s most of this year’s profits, which seems crazy to me.
Cash forecasted to be in the range from $2m net cash, to $2m net debt at 11/2022 year end. That looks fine for a profitable company.
My opinion - all rather disappointing. I just can’t get excited about this company. There’s nothing in the numbers to indicate to me that it’s an exciting growth opportunity. Revenues & profits go up & down, with no obvious trend over the last 6 years.
The balance sheet has been hollowed out with an acquisition spree that leaves nothing in NTAV, once the £97m intangible assets are written off. It looks like a lot of costs are being capitalised into intangible assets on the balance sheet (£4.2m in the interim results), so be sure to ignore EBITDA.
It’s not obvious to me that the various acquisitions have created any shareholder value here.
Overall, I think this share would probably only be of interest if something exciting for the future could be ascertained about its products - e.g. if they bring out some new product that is brilliant, and trounces the competition, then the shares and results could improve. That requires sector knowledge, and a lot of work, and I can’t motivate myself to dig any deeper, given the disappointing update, and a valuation that doesn’t look especially cheap.
Have any readers looked at this one in more detail? If so, what do you think?
It's now halved from last year's peak, which is not especially bad in this horrible bear market for small caps.
Note the StockRank is middle-high, which is now likely to take a tumble, as the momentum score is likely to take a hit from both reduced forecasts, and the lower share price.
My commiserations to holders, profit warnings are horrible, but they just happen sometimes. It's then a tough decision as to whether to ditch the shares, or stick with them for a hopeful recovery in due course. Your money - your decision!
Graham’s Section:
Bioventix (LON:BVXP)
Share price: £34.33 (+4%)
Market cap: £179m
This is a highly successful biotech company that many of you will be familiar with.
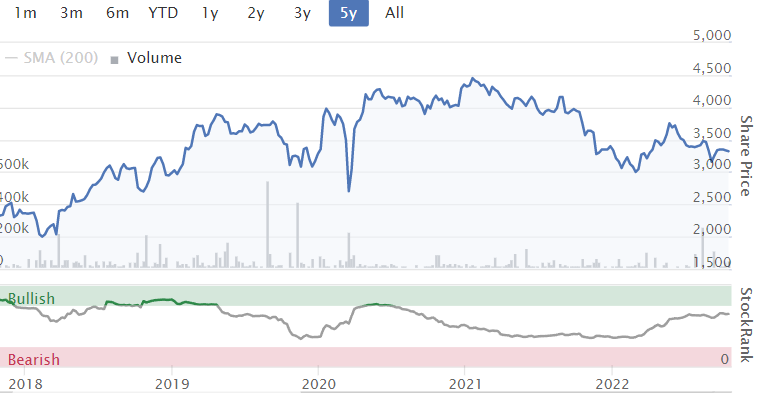
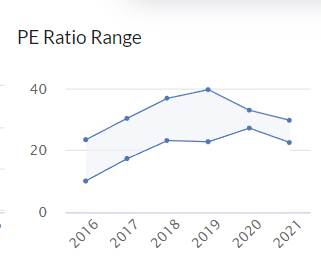
After so many years of producing excellent results, it became common knowledge within the investor community that this was a high-quality company. Focus shifted to valuation: who was willing to pay a PE multiple that was often in the 30s?
This chart goes all the way back to October 2017. You can see that since around 2019, the situation has stabilised and the share price has traded within a range:
The PE multiple has accordingly calmed down a little:
Let’s dig into these results for FY June 2022 and see how the latest numbers stack up:
- Revenue +7% to £11.7m (last year: £10.9m)
- Without currency gains, revenues would have increased only to £11.3m.
- PBT +14% to £9.3m
- Year-end cash £6.1m
As an unhedged exporter, whose sales are mostly in US dollars, Bioventix enjoyed a nice tailwind from dollar strength during the year.
Here’s a company description to help refresh our understanding of what the company does. It creates, manufactures and supplies “sheep monoclonal antibodies” (SMAs):
Most of our antibodies are used on blood-testing machines installed in hospitals and other laboratories around the world. Bioventix makes antibodies using our SMA technology for supply to diagnostic companies for subsequent manufacture into reagent packs used on blood-testing machines. These blood-testing machines are supplied by large multinational in vitro diagnostics (IVD) companies such as Roche Diagnostics, Siemens Healthineers, Abbott Diagnostics & Beckman Coulter. Antibody-based blood tests are used to help diagnose many different conditions including, amongst others, heart disease, thyroid function, fertility, infectious disease and cancer.
There is a long lead time between research and commercialisation - the company mentions today that its current research work “is more likely to influence sales in the period 2026-2036”.
Note that about 70% of revenues are derived from royalties on the sale of devices that use Bioventix technology. Royalties are always something I look out for - they prove the existence of valuable IP!
Another thing I look out for is revenue per employee. According to the company’s StockReport, Bioventix has 17 employees. This implies revenue per employee of almost £700k: excellent!
Indeed, today’s RNS says that “the Bioventix team” consists of just 12 full-time equivalents. If that number represents the current workforce, then revenues per employee are closer to £1 million!
There is an interesting section on China:
Our shipments of physical antibody to China continued to increase. Some sales are made directly but the majority are made through five appointed distributors. Regulatory approvals for domestic Chinese customers have considerable lead times but we are now seeing modest increases in royalty payments flowing from these customers. The prospects for further growth in China are good though we recognise that continued antibody technology development in China and elsewhere does constitute a longer-term threat.
I’ve noted before the difficulties involved in selling Western technology in China (see Somero).
It’s impressive that Bioventix is getting any royalty payments out of China, but again I wouldn’t bank on this being a long and fruitful venture. At some point, I would expect Chinese companies to figure out how to make this product for themselves.
In that regard, the reference to “continued antibody technology development in China” as a “longer-term threat” is certainly worth remembering.
Cash - the company says it only needs a cash balance of £5m. Therefore, on top of the raised ordinary dividend, there is a special dividend of 26p per share.
Outlook
We are pleased with our financial results for the year which we believe reflect both the growth in the use of our products and of course some relief from the global pandemic. In particular the continued roll-out of the high sensitivity troponin assays and the royalties associated with them have combined to help replace revenues from NT-proBNP which ceased from August 2021. After stripping out the impact of these 2 significant changes the growth in our underlying business over the year is in the range 8-10% which we believe is sustainable for the immediate future as our sales mix continues to change.
Excellent technical progress has been made with our research projects and we anticipate that our pipeline of opportunities will create additional shareholder value in the period 2026 to 2036.
My view
This is always a tricky one for me. I can’t say how likely it is that the current research projects at Bioventix will succeed, or how valuable they could be. There are good reasons I don’t cover most biotech shares!
I can say that I think the revenue growth reported here, before currency gains, is underwhelming (only around 4%).
They say that they can sustain underlying sales growth of 8%-10% “for the immediate future”, and based on their credibility, we can have some faith in that prediction.
But looking further out, I would have some concerns about the prospects here, especially considering that the stock continues to trade at a stretching valuation.
Even if growth of 10% is achieved, that is not normally the pace of expansion that you’d expect from a highly-rated share.
From a currency perspective, if you think that GBP is overdue for a recovery against the dollar, then the company’s forex tailwind could reverse. This could wipe out a significant chunk of nominal growth.
Before concluding, we should remind ourselves again that the quality metrics here are stunning - I have little doubt about the quality of the financial performance.
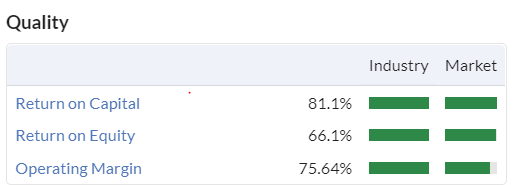
When you see such high quality metrics, it feels easy to justify paying a premium valuation for the company producing them. But personally, I lack the specific expertise needed to have confidence in this company’s prospects, and I would like to see a higher rate of growth, so this is not something I’d personally invest in. Life is easier when we stay inside our circle of competence!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
Superdry (LON:SDRY) (I hold) for anyone that cares their Auditor (Deloitte) has resigned - The reasons are as follows:
" The reasons for our ceasing to hold office relate to deficiencies in internal financial controls which are set out in our Independent Auditor’s Report in the Annual Report and Accounts for the 53 weeks ended 30 April 2022. In summary, the Group’s control environment requires significant improvement, particularly related to management review controls, balance sheet reconciliations and transactional processing controls (particularly in accounts payable and inventory). In addition, general IT control deficiencies relating to access and change management controls also need to be addressed."
Doesn't sound great...
*MELLO LONDON PRIZE DRAW*
Purchase a ticket for tonight's MelloMonday and you will be entered into a draw to win a FREE ticket to MelloLondon! TWO lucky winners will be drawn LIVE during the MelloBASH this evening! Don’t miss out! Use code TwitMM50 for half price tickets
https://melloevents.com/mellom...
Programme for tonight...
5.00 pm Mello Bliss update
5.10 pm Presentation by Galliford Try
5.50 pm Alan Charlton & David Stredder on ‘Irrational Markets Create Bargains!’
6.10 pm Warpaint
6.50 pm Delta Application Services
7.05 pm Quixant
7.45 pm Karin Shulte
8.00 pm Mello BASH
I know it goes the whole point of these articles but is anyone else looking at the metrics across the indexes and finding them hard to beat given the downside protection afforded by the sheer numbers of companies held within them? e.g. the FTSE 250 above. Yes, earnings are reducing next year but corporation tax is more than likely to be increasing next year* (*this may change next week & then change back the week after though :D). I think I'd be content with that income and the (distant prospect) of an attempt at the ath last year (c.39% above where it is now).
I know it goes the whole point of these articles but is anyone else looking at the metrics across the indexes and finding them hard to beat given the downside protection afforded by the sheer numbers of companies held within them? e.g. the FTSE 250 above. Yes, earnings are reducing next year but corporation tax is more than likely to be increasing next year* (*this may change next week & then change back the week after though :D). I think I'd be content with that income and the (distant prospect) of an attempt at the ath last year (c.39% above where it is now).
I guess the reason indices like the FTSE250 are not discussed here is because any metrics for them are meaningless and can only involve high level hand waving type analysis, instead of the low level detailed analysis this forum is best at. Who on earth would invest based on the median value of an index? Only an investor who is very wet behind the ears.
The FTSE250 in particular is a stupid index. Have you looked at the constituents? It is a market weighted index of which 40% are financials and 9% is REITs. Of the financials about 30% are Investment Trusts, so nearly 40% of the index is made up of investment companies for whom the measure of EPS (and hence P/E ratio and EPS growth) is meaningless and never used for valuations purposes.
Thats withering the say the least. :D I actually hunted about for mean ratios but couldn't seem to find them on stocko (though I do recall seeing an ability to toggle between them some years ago when a friend first showed me the platform.) I vaguely recall the median wasn't a million miles away from the mean but yes I take your point.
Relating to the constituents that's quite interesting actually & destabilises my rationale quite considerably. When your currency is floundering, your money is held in a s&s isa and you want to be slightly more risk adverse it is natural to look towards the local index. The FTSE 100 hasn't felt much pain this year so in simple terms I liked the look of the FTSE 250 for an ability to rise & provide an income over the next 5 years say.
Relating to the constituents that's quite interesting actually & destabilises my rationale quite considerably. When your currency is floundering, your money is held in a s&s isa and you want to be slightly more risk adverse it is natural to look towards the local index. The FTSE 100 hasn't felt much pain this year so in simple terms I liked the look of the FTSE 250 for an ability to rise & provide an income over the next 5 years say.
If it is any help, the TTM dividend yield you displayed must be wrong. You shouldn't take these things at face value and need to know how it is calculated. A better indication would be to look at the TTM total distributions of the iShares FTSE 250 ETF (MIDD) which equates to something more like 2.9% using the latest NAV.
Thanks. It is as a median average of all yields as collated by stockopedia in the FTSE 250 I assumed it was as good as any measure out there as you can go through the list it is calculated from line by line. Whenever I've explored dividend yields for individual companies on Stockopedia it has been accurate.
Thanks. It is as a median average of all yields as collated by stockopedia in the FTSE 250 I assumed it was as good as any measure out there as you can go through the list it is calculated from line by line. Whenever I've explored dividend yields for individual companies on Stockopedia it has been accurate.
Well I don't think the median value for the index as shown is accurate. I think it's just very misleading and how it is calculated totally opaque. All that matters is the TTM dividend yield of the ETF you are going to buy to gain exposure to the FTSE250. That will vary somewhat as the index changes but if you buy the iShares ETF today the TTM yield is 2.9% based on the current NAV. Given that only about 150 members are operating companies and the rest Investment Trusts, Infrastructure funds and REITs, I personally don't see the point. Best to buy the individual constituents yourself because there are some good companies in the index
Actually, scrap the above... having looked at the iShares fund it is an optimised fund and does not hold all shares in the weighting of the index. So the Vanguard fund (VMID) looks a better representation. Currently yield for the Vanguard fund is 3.48%.
Stupid . adjective - having or showing a great lack of intelligence or common sense.
Yes I suppose the FTSE250 could be defined as being as stupid, same as a brick wall is thick!
SDI (LON:SDI) another acquisition today, this time of Fraser Anti-Static Techniques and the largest to date, and is expected to be immediately EPS enhancing. Frasers appears to be well run company in its own right and opens up further export possibilities for SDI as Frasers has sales offices in Germany and China.
SP looks to be rerating and can see £2.00 being feasible even with the current depressed market state (Broker TP 275).
Its not a cheap company and the spread can be a bit of a pain, but management continue to delivering solid results year on year and I remain a happy holder of this one. Both revenue and profit forecasts 23/24 look like a significant jump if met.
Paul
Not small cap, but I have a question which I think this very knowledgeable base of investors will know the answer to!
I'm struggling to find an etf or etp that:
I've done a thorough search on Google and various etf databases, but can't find any. Any suggestions?
£SOIL may be what you are looking for, a Wisdom Tree ETF to Short Oil
£SOIL and £SBRT almost fit the bill... Except they are both still in USD and thus incur fx conversion (iny situation) for buy and sell as well as the GBPUSD risk.
It looks like there is a gap in the market!
Cerillion (LON:CER) I looked several years ago at much lower price and thought it expensive and that some of the accounting was a bit dodgy (around revenue recognition and accruals etc I think) and that the business had a weak moat and competitive offering -> so had it more as a short than a long -> that view has not been proven out by the market obvs! I'm probably just very mistaken. I note its not cheap so got to be sure of what you have going forward.
Out of curiosity can someone summarise why the various profitability measures on here for it have really exploded up in the last few years?
Billing system vendor has a weak moat? Do you know how long it typically takes to replace a telecoms billing system? Or the chances of a successful replacement? There are many problems, so very hard to put into a few paragraphs, but basically companies tend to build their business processes around their billing system, so when you go to change it the billing system has to be very configurable (they always fall far short of what are usual wildly unrealistic expectations) and easily customisable (costs a fortune - way more than any number anyone first thought of) or the business has to completely change their processes and make sure everyone adopts them (never happens). So anyone who has a product that is just a bit easier to get working and a bit more flexible than the competitors and produces a delivery that is better than more or less OK has a competitive advantage
Cerillion (LON:CER) is very high quality, but is expensive so they could suffer a correction. However, the Oct H2 update is very strong and showing material operational gearing. Gervais Williams said in Nov 20 podcast that CER has new contracts and significantly that its, “Customers love it”. Cerillion’s offices are located in London, India and more recently in Bulgaria, so it has cheap overseas talent. – The big question in my mind is: What exactly do their customer love and what is their Moat?
Thanks...I think my original comment showed I didn't have a good handle on Cerillion (LON:CER) rather than I was claiming it to be a wrong un!
That said...beyond your offended incredulity at my dumbness (no doubt you are a holder) you didn't really answer my question: "Out of curiosity can someone summarise why the various profitability measures on here for it have really exploded up in the last few years?"
Also, obvs I don't know how long it takes to replace a telecom billing system! Maybe it takes a long time as telecos are riddled with old, sh1tty, cobbled together tech...like the tech in the back office at financials (an area I am much more familiar with)...very hard to replace, essential, needs to be foolproof and a graveyard for service providers if they try to provide anything holistic and integrated rather than periphary and not in need of much integration...
Is Cerillion a good buy today? Why?
Apologies for the late reply. I'm not actually a holder of £CER. I try to avoid investing in anything too close to my day job - partly avoiding having too many eggs in one basket and partly avoiding potential conflicts of interest. I occasionally miss good opportunities like £CER.
And apologies for the incredulity which was pehaps a wee bit overdone. Still, unwanted legacy billing systems do persist far longer than any beseiged medieval castle with a good moat would. The money is made by changes and customisations over the lifetime of the system rather than the original contract, so once a sale is made there really is a good moat. It normally takes several years to replace one and can typically cost the operator in the order of £100million. I know of one that has taken 20 years. I know of another that didn't issue a bill to their customers for 12 months (it was OK they were state owned). The last figure I heard was that about 60% of replacement projects fail. A very plausible figure from my own observations.
Some incumbents are just old cobbled together systems from the early days but most are just older products that have been heavily customised. There's a thing called the Christmas Tree model which means people get stuck on old versions. Imagine a company that had spent £50m customising Windows XP to suit their business. They would not want to upgrade to Windows 10 or 11. So they keep going until it just becomes too painful to stay on the old stuff. It's silly to do this when we think of Windows but it is pretty much impossible to avoid for telecoms billing systems.
So what I'm saying is that if Cerillion (LON:CER) make a sale and successfully complete the migration to their product they will be the incumbent for many years to come and will get the revenue stream from that.
There's always a product or two that gets a reputation as being easier and simpler and better than their competition so they become favoured. Cerillion seem to have hit a sweet spot.
How long that will last is another question. I'm not working with the product at the moment so don't know. But they will not fade away quickly. They are expensive and I don't feel a strong temptation to jump in now myself - but as I mentioned there are other factors there
And yes, I didn't answer your question on the figures. I'm not a holder so haven't put in the right amount of work. Hopefully someone else can answer that.
PS The main reason the replacements take so long is that the telecoms company has built it processes around the old system and with the best will in the world attempts to change the processes to match the new system meet immense resistance. so many more customisations than are expected turn out to be unavoidable. The idea of installing a billing system out-of-the-box and re-building the processes around it is a fallacy only believed by CEOs.
Paul - great Podcast thanks. I think if you are pushed for time you could drop the write up -after all, everything is in the individual SCVRs if people are interested. I also subscribe to Sharepad and I continue with Stocko as well primarily because of your content.
Smashing, thanks Bert, much appreciated! :-)
Superb podcast Paul, very balanced, very honest, very informative and great to see you doing this at a time when many who like to lord their gains have closed the bunker doors.
Thank you, and I for one won't forget your hard work in these dark times.
Cerillion (LON:CER)
Long-term holders have had a multi-bagger here.
Paul, searching for the Golden Grail I'm forever widening the circle and here I look at share ownership. I see that Individual Insiders hold 30.8% of the company, General Public 1.4%. I would like to buy the Dip but since it seems there will be jam tomorrow I doubt very much if I'll see one but thanks very much for your findings and excellent write-up anyway.
p.s. As a rule i generally don't vote at AGM's any more, the PI hardly ever counts in the proceedings.
Bioventix (LON:BVXP) – some encouraging commentary from the often understated and cautious Peter Harrison in today’s results for the year ended 30 June 2022.
Revenue up 7% to £11.72 million (£11.3m at CCY), PBT up 14% to £9.28 million and diluted EPS of £145.90 against £127.94 in 2021.
2nd interim plus special dividend giving £1.00 per share in total.
The most notable figure really was the troponin antibody sales which doubled again to £1.23 million having already doubled in 2021 to £0.68 million. It’s worth bearing in mind however that this royalty stream will expire in 2032.
The results are impressive considering the loss of NT-proBNP revenues (royalty stream terminated in August 2021.)
Also impressive was the increase across the board of the lesser revenue generating antobidoes: T3 (tri-iodothyronine) increased 25% to £0.93 million, biotins and biotin blockers were up 67% to £0.90 million, progesterone up 14% to £0.62 million, estradiol up 34% to £0.59 million and testosterone up 7% to £0.47 million. The only detractor was drug-testing antibodies which fell 7% to £0.38 million.
Each year, the results contain a useful table showing the potential success and revenue contributions of their current research products (to understand this business, it’s imperative to understand that current revenue is derived from antibodies created many years ago, revenue growth will come from research work already carried out many years ago and current research work will influence sales beyond 2026.)
The Tau (Alzheimer’s research) project, which shows a High Potential Value has now moved from the Low to Medium column of “Increasing probability of success” with some fairly positive associated commentary.
Notably, however the Industrial biomonitoring and Pyrene biomonitoring projects have both been relegated to the lower rank of “Increasing potential value”.
It’s always difficult to assess the future potential of this company because there are so many unknown variables but I thought that the commentary today sounded an optimistic note on many fronts. The exceptional track record, pristine accounts, incredible flow of dividends, fabulous margins and the fantastic moat all contribute to making this an incredibly exciting investment. It remains a core holding for me.
Bioventix (LON:BVXP)
Very pleasing results this morning - revenue and EPS beating forecast by over 10% - although this could be inferred from the previous update.
More interesting is to look at H2 in isolation in comparison to H1 . Revenue has gone up from £4.7m to £7m and PAT from £3.0m to £4.7m.
On this basis FinnCap's marginal increases in Revenue and EPS for FY2023 look pretty cautious.
Pondering a top-up.
Phil
(Edit: Looking at the past there doesn't appear to be seasonality between H1 : H2 and I can't think of a reason why there should be)
BVXP (I hold). Agreed, I have topped-up - these do look excellent results, after adjusting for the loss of revenue from NT-proBNP, underlying sales up by 21.5%, (£2.07m) of which just £0.4m is from currency strength. Look forward to seeing updated FinnCap forecast.
Supreme (LON:SUP) - "Resilient and generating cash" (link to note: https://www.equitydevelopment....)
In a Trading Update for the six months to 30 September, Supreme reports that Group performance remains in line with market expectations for the full year, reiterating the positive message of the 15th September AGM.
In particular, the Vaping division, which we estimate to comprise 46% of FY23 revenue and 71% of FY23 gross profit, is reported to have continued on a strong growth trajectory, with organic growth boosted by the acquisition of Liberty Flights, and latterly, Cuts Ice Ltd., and Flavour Core Ltd.
Notwithstanding the headwinds buffeting the UK political and economic outlook, this is a positive Trading Update. Supreme occupies a market niche which emphasises value for money in its product lines whilst representing a positive alternative to the threats to health represented by cigarette smoking - as backed by the government’s Smokefree 2030 initiative.
Based on our outlook, Supreme currently trades on a FY23E EV/EBITDA of 4.6x and offers a yield of 6.4%. We include a valuation update based on sector-specific peers in the Distribution, Consumer Staples and Tobacco markets cross-referenced against the relevant divisional contributions to Supreme’s gross profits. Our Fair Value remains 190p/share.
Supreme (LON:SUP)
There is a useful note from Equity Dev which refers to the recent slowdown in the lighting division as apparently only a temporary hiatus. If that proves to be the case then that makes Supreme of interest to me once more. ED are hosting a zoom featuring the interims on 29th Nov.
In passing, I cannot help but notice the number of new hole-in-the-wall shops springing up in this part of outer West London selling all sorts of vapes (I don’t indulge!).
Mark
Trackwise Designs (LON:TWD)
Friday afternoon is traditionally a time for sneaking in a profit warning, but the reverse with this company at 14 16 last Friday as a result of which the sp went up 150% :
For those of you who missed it: https://www.londonstockexchang...
It has reached a new agreement for the supply of flexible printed circuit boards to its UK EV OEM customer. This involves a cash sum upfront but even with that "additional funding is required and Trackwise is reviewing a number of options for additional funding with its advisers and will provide further updates in due course".
In view of that maybe a rise of this magnitude is a little premature.
Graham any observations? You last wrote "I consider this stock uninvestable" here: https://www.stockopedia.com/co... and Paul added "I was warming to TWD as a speculative punt, but your update today has put me off. Looks more risky than I suspected when I looked at it here in June. Interesting new products, but I'd like to see more secure finances before investing here".
Note: the forecast shown on the Stock Report was withdrawn some time ago. The last time I moaned to Stocko about this (on a different share) I was told that it would not be removed but that "As we go forward, we plan to handle stale estimates differently, for example, by highlighting them in a different colour - eg. a light shade of amber. Removing them completely may be jarring for users".
It was priced to go bust. It isn't. The correction will likely continue this week.
I did look at the big price movement on Friday in Trackwise Designs (LON:TWD) and was left scratching my head at the market reaction to an announcement that didn't strike me as particularly positive, if at all.
For me, the dilution/insolvency risk is currently way too high for me to entertain buying any TWD shares, other than as a pure punt for fun money that I would be prepared to lose.
I see it's slipped back a bit, down 19% today, so maybe day traders were having some fun with it on Friday, and banking their profits now?
I did look into the products, and it looks very interesting, but there must be other companies in the same area? Also, the US customer looks a bit flaky - they're NASDAQ listed, so I read up their accounts, and wasn't impressed - burning cash, and already retrenching on costs as conditions worsen. I can't remember the name of the customer, can anyone remind me, and I'll check on their current position.
There are really 2 hurdles for TWD -
I need proof that both can be achieved, before I would add any of these to my portfolio. Potentially interesting though, if it can jump the 2 hurdles, so I'll keep an eye on it.
Regards, Paul.
Trackwise Designs (LON:TWD) 's large EV customer is Arrival who announced recently a move of some production to the US (they have developed micro-factories which they claim will allow them to set up shop close to where the demand is for the vehicles) . The possibly now greater opportunity lies in producing the wiring harnesses that will allow the massive array of battery cells in a large battery to be monitored and controlled. A painful holding so far but their unlimited length technology does seem so far to be unique and have taken many years to develop.
Hi Paul I believe that Trackwise Designs (LON:TWD) technology is still unique. "In 2010, it developed the globally unique capability of producing multi layer, flexible printed circuit boards of any length. This process is called Improved Harness Technology™ (IHT). " As I understand it, no one else can produce length unlimited circuit boards like this. The cost saving for the airline industry if they would put this in new aircraft is huge - lighter planes means less fuel which means greener. Whether they go bump and somebody else other than current shareholders make the big bucks is yet to be seen of course.
Paul, just to say thank you for your podcasts...I really enjoy them. You have the perfect balance of information and entertainment, love the fact you didn't try to edit out your mum calling.
45 minutes fly by and in truth I could easily listen to another 45.
Also just discovered Graham's YouTube videos this weekend which are also excellent.
After a week staring at a screen it's great to just chill out and listen without having to read anything.
Hi gringo,
What a lovely message, thank you! Although you do sound a glutton for punishment LOL!! ;-)
Yes, I've just discovered Graham's Youtube channel too. I'll ask him if he plans to also publish them as podcasts (which PI World do) which I find better than having to remember to log in to youtube. Also playing on mobile on Youtube is really annoying, as it switches off the sound when you switch off your phone screen.
I've listened to, and quickly deleted some other shares podcasts. E.g. Justin Waite spent over 20 minutes rambling on about his half-baked political views this weekend. What a waste of time! Sometimes he comes across as not being that bright! Although his company interviews are good somtimes (e.g. an excellent recent one with XP Factory (LON:XPF) [I hold]). Shares podcast/videos should be about shares, nobody's interested in people just regurgitating politics that they've seen on the TV news, or on Twitter. Insights are rare, and non-experts in any field have nothing to add of any value, I find. So why waste everyone's time with politics?!
If readers here find any good podcasts, do flag them up, as I love listening to podcasts especially when shopping , driving, or exercising, it's a great use of otherwise wasted time.
Regards, Paul.
Morning all,
Very positive update from Cerillion (LON:CER) this morning, PBT "materially ahead". Shares are pricey, but the company has been doing very well. Chart looks very good also...
Any views welcome!
This link is from a FT article last week. I found it quite educational - its the slides and transcript from a recent speech by Ben Broadbent of the BoE. It explains why the B0E has not raised rates as fast as the US and how they consider FX rates and Government spending (including energy subsidies) when it comes to evaluating interest rate rises. It's a bit theoretical from an economics perspective but good if you can hack through the first page or so.
https://www.bankofengland.co.uk/-/media/boe/files/speech/2022/october/the-inflationary-consequences-of-real-shocksspeech-by-ben-broadbent.pdf?la=en&hash=40EE6F0A7FE902A87B1349A71B04FF37A2D62C74
It's beyond me Cuddlesticks but I do my best with the FT online everyday.
This is excellent - thank you. Wouldn't it be great if the media tried to educate us and help everyone understand how difficult it is to draw immediate policy conclusions from the combination of shocks the economy is experiencing.
For me, it illustrates that trying to guess who is winning or losing in the current economy without reported evidence is at best a guess. It doesn't mean I don't want not try bit it limits risk taking ... until things become clearer. So equity risk premiums rise...makes sense...