Small Cap Value Report - Mon 25 July 2022 - EQLS, CARD, WINE, JDG, EBQ, VLG

Good morning!
Agenda -
Paul's Section:
Equals (LON:EQLS) - finally! Guilt overcame me on Sunday, so I prepared some notes on this interesting growth company. Looks good to me, but I don't understand the sector.
Card Factory (LON:CARD) - is ditching its CFO, after 5 years service, which is bound to worry some investors. An in line with expectations trading update is buried in today's news. It's a potentially interesting turnaround, but the weak balance sheet still puts me off, despite a bank funding agreement that has greatly reduced the risk of an emergency placing. Could be good, we'll keep an eye on it.
Naked Wines (LON:WINE) [no section below] - another CFO leaving, "by mutual agreement", effective last Friday, so no transition period. Although the RNS strangely says there has been a "smooth transition" - I wonder if that just means, here are the passwords, bye!? This one sounds like a falling out, since it's happened with immediate effect. The old CFO (2015-2020) is resuming that role on an interim basis. I've never been keen on this share, and think wine subscription services are not a good place to be right now. I was unimpressed with the FY 3/2022 results, reviewed here.
Graham's Section:
Judges Scientific (LON:JDG) (£467m) - today’s H1 update is in line with expectations. Order intake was up 4%, with very different trends seen in different geographies. Economic conditions remain “challenging”, and revenue growth is held back by supply chain/recruitment issues, and by staff needing to self-isolate. I provide some analysis of the £80m deal announced by Judges in May, the largest deal ever made by this highly successful buy-and-build operator.
Ebiquity (LON:EBQ) (£67m) (+10%) [no section below] - this media consultancy made over £20m of acquisitions in March, raising equity to do so. Today’s H1 trading update shows organic revenue growth of 10%, and total revenue for the six-month period of £37m. That’s half of the full-year revenue estimate shown on the Stock Report, but only includes three months of contribution from the acquired businesses.
Underlying operating profit in H1 has more than doubled compared to last year: margin improved due to “growth in higher margin digital products and improved operating efficiencies”. Net debt is £12.9m.
Historically, there have been huge discrepancies between underlying profits and actual profits (i.e. losses) at this company. Consultancies are a difficult place to invest and I would preserve a cautious attitude to this share.
Venture Life (LON:VLG) (£43m) (+6%) [no section below] - this consumer self-care company is “confident” it will meet market expectations this year. Organic revenue growth is approximately zero at VLG’s existing businesses, but newly-acquired businesses help the overall group to achieve 36% revenue growth compared to last year.
“There are signs that the supply chain issues have plateaued”, according to the outlook statement, and profit margins are being maintained through cost control and passing on price rises to customers where possible.
These shares are lowly-rated on a single-digit PE ratio but I suspect that this is fair, given the lack of meaningful organic growth.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Equals (LON:EQLS)
95p
Market cap £171m
H1-2022 Trading Update
I couldn’t put this off any longer, as have been promising to review this share for a while now! I briefly reviewed its in line with expectations trading update here in Jan 2021 - which mentioned an expected recovery in travel money FX transactions, and high development spending which was expected to moderate in 2023 - both seemingly good drivers for profits.
The current financial year is FY 12/2022.
Reviewing the StockReport here for EQLS, I made the following notes -
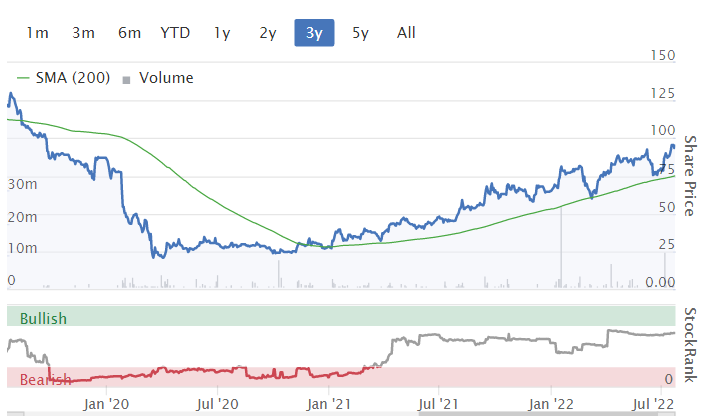
High relative strength of +11% in the past year, and +23% in the last 6 months - so something positive is happening with this share, given this strong share price performance, when most small caps have wilted.
EQLS appears in a top momentum screen here, which throws up some interesting companies that are bucking the downward market trend - so could be fertile ground for future winners, maybe?
Loss-making from 2019-21, so the bullishness must be driven by high expectations for the future, not its historic track record.
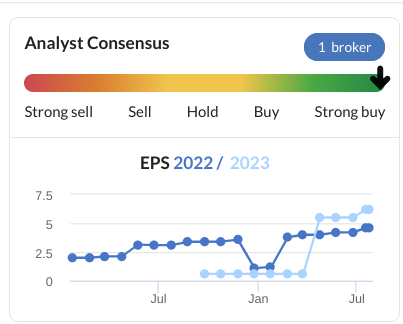
Valuation is 20.7x forecast earnings this year FY 12/2022, moving down to 15.3x FY 12/2023 earnings, and as you can see below, earnings forecasts have been rising, despite macro headwinds, reinforcing the view that positive things seem to be happening at Equals -
.
.
Some Director buying in recent years, but nothing huge.
P/TBV 17.2, so little asset backing.
Poor value rank of 13.
No dividends.
Listed competitors that Jack referred to here previously, are Alpha FX (LON:AFX) and Argentex (LON:AGFX)
Major shareholders - overhang from Crystal Amber selling is now small, with latest holding being 5.8% (down from 10.0%). Ameriprise looks like the buyer, increasing from 5.0% to 11.2%.
H1 Trading Update - was issued on 5 July 2022.
Key points -
H1 revenues up 84% to £31.3m - highly impressive growth.
Big increase in large enterprise solutions division, up from £0.2m revenues in H1 LY to £6.2m this time - is this sustainable, and what is driving it, I wonder?
Estimated gross profit is up strongly at £15.0m (up 47% - very good, but not as big an increase as revenue growth)
Cash has risen to £15.1m (June 2021: £10.1m)
Adj EBITDA for FY 12/2022 anticipated to be ahead of market expectations (no numbers given)
Business model is “highly inflation-resistant” - interesting point. As it takes a tiny cut of FX transactions, then those transactions would naturally rise with higher inflation.
Canaccord (many thanks) published an updated note, raising forecast FY 12/2022 adj PBT from £9.3m to £10.3m.
Adj EPS is forecast at 4.6p for 2022, rising to 6.2p in 2023 - PERs of 20.7, and 15.3 respectively, which looks a sensible valuation to me.
No divis forecast.
Bear case is noted by Canaccord as being execution & regulatory risks.
My opinion - I wouldn’t normally be interested in a forex dealer, because margins are so tiny, and there’s always the risk of catastrophe when huge amounts of money (£ billions) are being moved around, from system failures, or fraud.
It’s also such a competitive space, where customers shop around for the best deal.
On the upside, EQLS is clearly performing very well, with stellar growth in H1, and a valuation that looks reasonable still, despite a strong share price.
I’m not familiar with the company, but would like to learn more about it - management should get some webinars up, to inform more people about what the company does, etc.
I’ve just found an audio interview with management here on Vox Markets, hosted by my friend Paul Hill. I would certainly benefit from a simpler webinar, explaining the basics of what the company does, and its competitive position, etc. The key message from the CEO seems to be that the company is in a sweet spot, and enjoying the strong growth it’s generating.
At this stage, I’m not sure what to make of EQLS, because I don’t properly understand the business model, or competitive position. Although the very impressive growth, and strongly rising forecast profits, together with a valuation that still looks reasonable, sounds interesting, and makes me lean towards viewing it positively.
.
.
Card Factory (LON:CARD)
50.6p (down 2.5% at 08:34)
Market cap £174m
It’s worth reading this type of announcement, because sometimes companies put other information in it, like a brief trading update, as in this case. Not ideal really, because trading updates should be clearly marked as a trading update, otherwise investors can miss them.
This is a bit strange - the CFO is being sacked (as is usual, no proper reason is given) but staying on until they find a successor -
Card Factory announces that the Board and Kris Lee, Chief Financial Officer have agreed that Kris will leave the Company following a transition period…
…the Board and Kris have agreed that now is the right time for change.
The Company will commence a process to identify his successor. Kris will remain in role for the transition period, working with the Company to assist in this process and help ensure an orderly succession.
The RNS profusely thanks him, including that -
“he has worked tirelessly to deliver a successful refinancing in recent times and leaves the Company with a solid platform to move forwards”.
The reward for 5 years’ work, described today as a “significant contribution”? Being shown the door, and getting a £40k termination payment! I’d be mortified if that happened to me, and would tell them to stuff it, whilst walking out of the door for the last time! Wouldn’t you?
It doesn’t sound like a bad leaver situation, as bonus & share options are being honoured.
The Company will commence a process to identify his successor. Kris will remain in role for the transition period, working with the Company to assist in this process and help ensure an orderly succession.
Trading update - partially reassures me -
The Group's trading performance for the year to date is in line with the Board's previous expectations. The Group will publish its interim results on 27 September 2022.
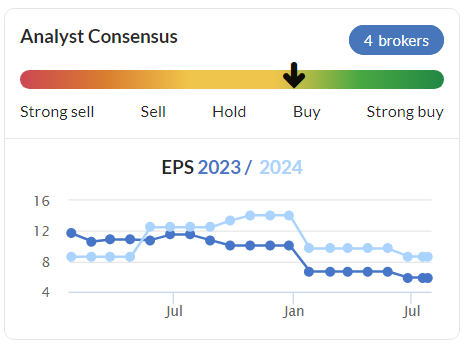
In line is good, but that's in the context of forecasts which have been lowered a fair bit this year -
My opinion - I’m a bit unsettled by the unexpected departure of a CFO, as they usually stay put when things are going well.
Has there been a falling out in the Board room? Or did the rest of the Board not think he was up to the job? Or maybe just a culture change under the CEO who joined in Mar 2021? I think the outgoing CFO worked wonders, maintaining the support of the bank, when the business was seriously under-capitalised during the pandemic. Who knows. It’s frustrating when Directors depart, because the culture in the UK often seems to be to cover up the real reason, and leave small investors guessing, whilst the big shareholders often know what’s really going on behind the scenes.
Renowned investor Richard Crow (@RebelHQ on Twitter), talked positively about the turnaround under new management at CARD on Friday, when I interviewed him here - well worth a listen, Richard is always full of common sense investing wisdom, and interesting stock ideas.
The forward PER looks reasonable, at 7.2 on the StockReport, although the weak balance sheet still worries me - NTAV was negative £(101)m when last reported.
I’ll keep an open mind on CARD shares, for a potential turnaround. Although I think Moonpig (LON:MOON) probably attracts me more, and seems to have eaten CARD’s lunch online. If CARD can catch up online, then it might get interesting. That’s a tall order though, with MOON (and others) now so well established, and able to fund big marketing budgets from strong cashflow.
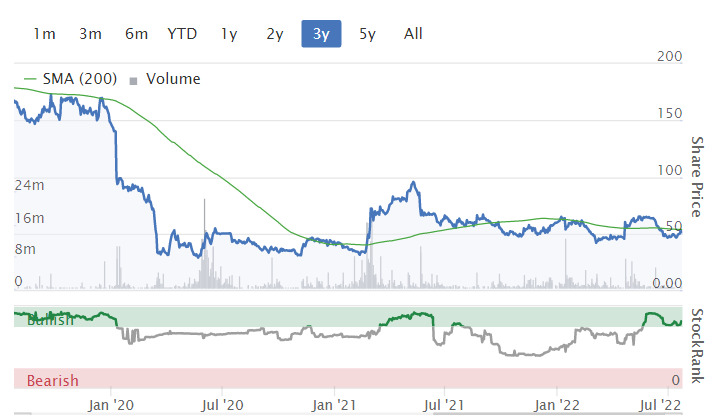
Note that the share count has barely changed, at 342m in the last 6 years, so theoretically, there's no reason why the share price couldn't get back to pre-pandemic levels, if performance improves -
.
Graham’s Section:
Judges Scientific (LON:JDG)
- Share price: £73 (-4%)
- Market cap: £467
This buy-and-build operator in the scientific instruments sector provides a half-year trading update.
As many of you will know, Judges has been a successful long-term compounder thanks to an efficient approach to acquisitions. It bought many small, founder-led businesses at very cheap multiples, used some debt to fund the deal, and then paid off the debt (along with any contingent consideration) using the profits of the acquired business..
Geotek
Earlier this year, Judges announced a large (up to £80m) acquisition.
The website for the newly-acquired business, Geotek, can be viewed here. It specialises in the analysis of geological samples.
Judges agreed to pay a multiple of 7x Geotek’s operating profit in 2022, with a lower limit of £45 million (paid upfront) and an upper limit of £80 million (£35m of contingent consideration). The lower limit was based on Geotek’s average performance over the three years prior to Covid.
Bonus payment - non-execs at Judges are entitled to a bonus worth 1% of the enterprise value of any acquired business they introduce.
As a result, one of Judges’ non-execs will receive up to £800k (in a mixture of cash and shares), for suggesting the Geotek acquisition. Judges argues that this 1% fee is “materially lower” than the fees charged by brokers.
I acknowledge that setting remuneration is a difficult task, but will always issue caution when incentives are geared towards size rather than profitability. This bonus scheme at Judges seems a bit too heavily geared towards the former.
Quality of earnings? - I note the following disclosure by Judges, regarding Geotek:
This is the first acquisition by the Group that derives a substantial proportion of revenues from services. It will provide the Group with greater medium-term visibility but also reliance on a small number of large contracts.
In connection with this, I also note the disclosure by Judges regarding Geotek’s Service Director and its Chairman, who are the founders of Geotek and are involved in selling it to Judges. These two individuals will continue in their roles on one-year contracts.
These are helpful disclosures, to help investors understand the risks involved in the deal. It’s certainly not without risk - and hopefully Judges are ready for the challenge of managing this larger business!
Today’s H1 2022 update.
Let’s get into this. It’s in line with expectations but the key points are:
- Organic revenues (i.e. excluding Geotek) +7%.
Revenues would have done even better if not for supply chain issues, recruitment difficulties and staff being required to self-isolate.
- Order intake +4% organically in H1 2022, after achieving a 25.1% gain in H1 2021.
- The order book measured in weeks reaches an all-time high, but this partially reflects the “ongoing supply chain difficulties”. So I perhaps wouldn’t read too much into this.
Despite the growing order intake, Judges argues that it still hasn’t caught up with the “pre-Covid growth trajectory”.
And while other regions were more positive, I note that China/Hong Kong and the UK both saw reductions in order intake, compared to H1 2021.
My view
The topic of scalability often came up with respect to Judges. While the strategy worked well with very small, founder-led businesses, would it continue to work when Judges had much larger funds to invest?
My view was that I would have more trust in Judges when it came to larger deals, than I would with most other management teams. After all, it had proven its ability at the smaller end of the spectrum, and therefore had earned the right to employ larger amounts.
However, I did have a concern in November 2019, when Judges announced a £12m special dividend. Its cash balance at the time was only around £20m. I wondered if this meant that Judges were not looking for larger deals, and if it meant that the era of rapid growth was over.
Obviously I’ve been proven wrong by the £80 million deal for Geotek, a couple of years later.
But I still think the jury is out (forgive the pun) when it comes to the success of Judges at this larger scale.
I don’t think we can completely take it for granted that Judges will be able to successfully execute eight-figure and nine-figure deals. And it probably needs to do that, if it’s going to kick on from its current scale. Small deals don’t move the needle anymore.
As with Berkshire Hathaway (in which I hold a long position), there’s also some key man risk in the form of the Judges CEO David Cicurel.
However, Warren Buffett is c. 20 years older than Mr. Cicurel, and still doesn’t want to retire, so maybe I’m overthinking it?
Personally, I agree with the StockReport and I find these shares more than fully valued at current levels.

That’s always a dangerous thing to say about any long-term compounder. But this share does provide very decent buying opportunities from time to time, and I don’t believe that this is one of those times.
As a long-term hold, however, I’m sure that its shareholders are feeling very comfortable indeed - congratulations, if you are one of them!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
The £104m "net debt" for Works co uk (LON:WRKS) shown by stocko consists of:
Lease liabilities 122.423
less cash 17.783
less Unamortised debt issue costs 0.262
IFRS16 = Utter pain
Thanks, very misleading on Stockopedia then. I will have another look.
Sanderson Design (LON:SDG) and Portmeirion (LON:PMP)
I know how popular these two shares are in the SCVR and I thought there will be many who find this article informative
https://knowledge.sharescope.c...
The Market has refused me a Quote and Deal request and I'm not sure why. So as not to take up space on the SCVR, I've created a separate post here - any wisdom from the Stocko community would be welcome.
Another decent contract win for Crimson Tide (LON:TIDE) . I was pretty miffed when they crumpled the share price to do the raise, but it seems the cash did go where they said, on winning bigger contracts with bigger customers. Let's hope they can keep it up.
on Naked Wines (LON:WINE)
Easy to forget this is Majestic + Naked Wines.
Majestic is in long term decline, full credit to it, as I think it is the last large mainstream national chain wine merchant that has a mostly physical presence - that market is now held by supermarkets and "bargain booze".
NW has the opposite problem, the 'wine over the internet' thing is doing well. The trouble is that it is _really_ hard to scale your business when it is basically selling exclusivity to a mass market.
I subscribed to NW 2003-9. At the beginning they would advertise 50-100 cases of something nice from a small producer and about 80% of the time I got the wine and it was pretty good. At the end they would advertise ~600 cases and if you did not order within an hour you had no chance. So I stopped trying.
There are a lot of small independent merchants who are starting to move towards the NW model (selling small batches, not the subscription - I think the costs of doing that are quite high). In Bristol, DBM wines, I am sure there are many more I do not know of and because they are small, can sell exclusivity to their local market.
I think there is a good business in there, just not one that is suited to the stock market.
Naked Wines (LON:WINE) sold off Majestic Wines back in August 2019 to Fortress
A real shame imo as their physical stores are great with young enthusiastic staff
Naked wines subscription based model imo is not attractive, the wines I tried were over priced for the quality (I previously worked on the wine business so have tasted a few over the years ;-))
Agree re Majestic but i would add knowledgeable to young and enthusiastic.
When you were working in the wine trade was your 'handle' AstiGirl ? ;-0
Agreed. Always found Majestic staff to be excellent in all regards.
If you want to get your weekly shopping bill down, a great way to do it is to swap out for a cheaper wine. I think the inflation squeeze will effect these companies, as 'Middle England' is getting hit.
Since Aldi stopped throwing your shopping at you through the tills, I see a steady change in clientele of late, and why not, as the quality of products and wine is very good.
Aldi wines have gone up in price quite a bit in the last few weeks, nothing under £5 anymore.
Some food prices are going up by silly amounts, not shopping in Morrisons anymore.
Thank you.
I first bought £EQLS at about 117p (partly as a result of experiencing excellent service from the holiday cash offering, FairFX). and somehow kept the faith while averaging down to just under 30p! Every time I reviewed the position the underlying position was improving at about the same rate the share price was falling! My suspicion is what Paul notes is right, people find it hard to understand the business model so as soon as there is a hiccough in the price they bail.
I stayed with it because
Now they are producing cash and profitable. They have a plausible offering that could compete in the SME space with the major banks; this could be seriously attractive for those companies with a significant amount of foreign business and related currency requirements.
Can they continue their phenomenal recent, profitable, growth? Following the pain of investing in tech based small caps over the last year I am nervous to say this but, given the growth achieved during what I would have expected to have been a very difficult market for them during the pandemic, the answer should surely be a resounding yes!
A small acquisition today by Begbies Traynor (LON:BEG) of Mantra. They are looking to build out their finance brokering operations, having dipped their toes into this area last year with the acquisition of MAF.
No update on current trading given, but the £4.0m of initial consideration cash payable wipes out their net cash position as of FY Apr22. So they must be bullish on current trading to sign off on this acquisition, IMO.
Mantra is already profitable, looks like it might be c5% earnings accretive immediately, with possibly more to come once duplicate costs are stripped out.
I'm always nervous about acquisitive groups, that do multiple acquisitions a year. But they have been doing that for a few years now, and seemingly successful (albeit earnings are still messy adjusted because they keep acquiring! So there's never been a clean set of accounts without acquisition costs being adjusted).
(I hold in the Boon Fund)
After last weeks placing debacle and associated negative comment around Unbound (LON:UBG) received this newsletter this morning. Marketing seems to have caught up with the business launch under the Unbound name. Sadly it is full of the usual hyperbole and totally detached from reality!! https://newsletter.hottershoes...
Card Factory (LON:CARD) having listened to the interview with Richard Crow, I am more with Paul on this one. Apart from the weak balance sheet, I think they will see sales gradually fade as business moves online - think they were too late to establish an online presence and will struggle to compete with Moonpig.
In terms of their high street stores, I think there is limited brand loyalty and plenty of competition from hosts of generic retailers (discounters, supermarkets, etc). The company looks cheap admittedly, but there are so many bargains around right now I just think there are much better opportunities.
Card Factory (LON:CARD) has a shop in Tunbridge Wells, directly opposite Works co uk (LON:WRKS) . Whenever I walk past, I think that there are too few customers in either to cover their overheads. Maybe I just don't understand the business model for such shops.
I went into the Works co uk (LON:WRKS) shop in Kingston yesterday and it was very busy indeed. Spoke to the charming sales person who claimed that the shop was always quite busy . After listening to Richard Crow, and doing my own research, have decided to invest .
Not looked into Works, but just as a high level observation I think they are in a much better niche than Card Factory - always seems to be plenty of demand for cheap books/games/stationary and don't see this changing.
I looked at Works co uk (LON:WRKS) but too much debt for me.
They have no debt last time I looked at it ( and it was last week or so ).
Really, so the figures on Stockopedia are incorrect?
I never look at those ( I mean the figures on Stockopedia ) as they are most of the times not correct.
You must be referring to the IFRS 16 lease liabilities that are definitely not debt.
You really need to go to the source (company accounts) and cannot rely on Stocko figures - these are good for a quick scan but for a more detailed analysis you need to go through the accounts.
Thanks , this is what I have been doing for the last 25 years but these can be misleading as well!
It’s not exactly stockopedias fault that lease liabilities are classed as debt it’s just a fact of life - nowt misleading here as you say financials could be out of date if there has been recent acquisition but still it’s a much better starting place the most recent results than what is shown on stocky as those figures always need to be checked for sanity purposes
Apart from it looks like the company is almost bankrupt, this will probably affect the the scores on the Stockreport and exclude it from some screens.
Card Factory (LON:CARD)
I like the shops, I can go in with my girls and can give them total freedom of choice to buy a handful of cards at a reasonable price, so cover the various friends birthday parties, seemingly endless needs for cards for my wife, then friends, family and all that. Basically once every month or so go in and buy £20-30 worth of cards, put them in a draw and go again when they run out.
Reasonable quality cards, very good price what more can you need?
If there is something specific (e.g. wants a more expensive card) my wife will walk round to the Co-op and get something.
I guess that I am also going into the world of trying to shop local more, it keeps people employed locally, it keeps things on the High Street, at a time when what do those who leave school with not a lot of qualifications do, or those who have full/part-time caring responsibilities and just want two/three shifts per week to keep above water?
They have to compete against a Clinton's across the road, a local department store (family owned) which tailors for the £4+ per card, and Waterstones next door seem to do a reasonable amount of quality cards too. Or you can walk to the various charity stores, or Tesco at the end of the road. So it is always going to be a very competitive niche, they are never going to rule the world, but I guess can they defend their margin, pay down debt and get better deals each time the shop leases come up?
So yes I did lose a lot of money going into lockdown holding.
I do not hold any more and whilst I like the shop and will continue to use, I do not personally feel this is something I want to invest in right now.
Cheers
Tommy
(I do not hold)
Card Factory (LON:CARD)
Paul
Would be interested to know how you know for certain the CFO is being sacked i.e. its not an amicable parting of the ways. I can see why it looks like he has been sacked but are we certain this is the case ?
Idle speculation but i wander if the banks may have indicated they would not enter into negotions ref future refinancing with current cfo if they (the banks) have spat their dummy out ref the cfo playing hardball - or have concerns with that persons conduct?. I suspscet the banks may not like not being the dominant player when they are having discussions ref "re-financing the business" - if this is the case whether the banks have overstapped the line or not i doubt we will find out.
Has anyone come across this situation before where the banks/financiers have refuse to deal with the relevant nominated individual in future if they feel they "have lost faith" and requested they be replaced forthwith if they want to be able to "roll over financing in the future"?
Card Factory (LON:CARD)
No, the Banks would dare not demand the resignation of a director ! (unless the business was going into insolvency etc - like a McColl's situation).
Even if he was viewed as highly incompetent, they have no right to interfere with the day-to-day running of the business whilst their debt is not impaired. It may impact their views on providing further facilities / flexibility to the business in future though.
My take on what's happening at Naked Wines (LON:WINE):
The CFO has been pretty unimpressive generally on calls. He is steeped in business school speak/MBA terminology. It often felt like Nick (CEO) was picking up the slack/having to translate for him. That wasn't great, but then the recent debacle over the late announcement of their inventory backed lending facility, and the subsequent concern raised in the Going Concern opinion really raised the blood of shareholders. I think pressure was put on Nick to act, and it appears as though he has. James Crawford is a very safe pair of hands, who knows the business very well. IMO this is a positive development.
Science (LON:SAG) H1 (end June) I hold
Mcap £179m at sp 397p
International science, technology and consulting business, primarily in food sciences, environmental consulting with a DAB radio chip designer and a 28% associated interest in quoted TP (LON:TPG) – currently being restructured under the guiding hand of Science (LON:SAG)
Headline revenue up 10% to £44.8m (assisted by the strong US dollar) and then a pile of adjusted measures Adjusted operating profit up 22% to £8.8m, Adjusted profit before tax £8.5m up 23% and adjusted eps 14.6p up 10%. So far so good. Very good under current circumstances.
You have to dig a lot deeper to find the unadjusted figures. Primarily in the financial statements. Reversing the adjustments for amortisation of acquisition related intangibles and share based payments – operating profit comes out at £6.231m up by around 8.7% but still up healthily, though a lot of that might well be due to the tailwind of the US dollar.
Ploughing on - with the unadjustments - profit after tax is up 0% after a more realistic tax charge of £1.28m and diluted eps is down 9% at 9.9p. You can see why they might want to lead with adjusted figures, which admittedly do give a better insight into the operating performance. Shareholder return not so much.
But overall its not bad. The figures look to be well in-line with FY forecasts. At this stage they have delivered more than 50% of the forecast FY22 revenue of £82.7m and £8.67m net profit (according to stocko). So there is reason for cautious optimism as well as room to accommodate some slow down on the DAB chip side as consumers rein in spending and still meet or exeed FY expectations.
But there are a couple of things to bear in mind. I am not surprised or disappointed at the unadjustments – it’s business as usual for SAG – I note it more to highlight how this company operates. A lot of the shareholder total return comes from their long term ability to acquire businesses and bolt on to build scale in the group. The dip in eps is explained by the raising of £18.5m fresh funds in a 10% raise at 450p – which now looks like a well timed move – providing a war chest for acquisitions. So far unutilised, with cash of around £39m sitting on the side.
The use for the cash is likely to be in two parts. Firstly fresh acquisitions to increase the scale of the activities – I suspect that management sees potential acquisitions getting cheaper right now and is in no great hurry to splash the cash.
And then there is the special situation at TP (LON:TPG) where SAG is the largest shareholder with 28% of the shares and in the driving seat with 2 board seats including chairman after disposing of the capital-destroying previous board of directors. For this reason TPG shares are now an associate. The question is how SAG intends to exit this process without destruction of its own capital? TP Group is currently expecting to report a loss of around £18m for 2021 – the results are delayed in auditing – primarily due to restucturing of ‘legacy contracts’ at its maritime defence subsidiary and disposal of various loss-making subsidiaries – which should leave a leaner and cleaner company focused upon defence and aerospace consultancy. Presumably the end interest of SAG in this affair - as these businesses are growing and well regarded by their customers. over many years and would give SAG a position in the defence market that they can't achieve just by poaching consultants. Pro-forma associate loss for SAG from TPG will be around a further £3.4m (they already wrote down £1.1m in their 2021 FY results) though this won’t affect the ‘headline’ figures. The endgame with TPG remains obscured – and will be down to the main institutional shareholders in TPG (some of which are also shareholders in SAG) and the price they need to agree the deal – I think it most likely that SAG will acquire the consultancy businesses once the rest of the outfit is ‘cleaned up’. It will be interesting to see how this plays out.
Overall I’m happy with the results and operating performance – but I regard it as a ‘work in progress’ with continued high shareholder returns closely linked to futher acquisitions and the successful resolution of the TP Group saga to continue the build the scale of theirconsultancy businesses.
Cheers
Mark
As per IG Market Call this morning :£SThree (STEM ) I hold enjoyed an impressive H1, with pre-tax profits rising up 64% like-for-like to £44.3 million. The staffing firm posted record net fees, which were 25% higher year-on-year. Operating profit was £44.6 million for the period, representing a 62% like-for-like increase for the firm. Surely one of the best value shares at the moment with Stocko showing a PE of 10.5 alongside an impressive 33.5% ROC and 29.5% ROE. Worth a look
SThree (LON:STEM) - ”Surely one of the best value shares at the moment with Stocko showing a PE of 10.5 alongside an impressive 33.5% ROC and 29.5% ROE.”
I’ve grown tired of championing this one on account of the market’s complete indifference, hence the short comment. But I have a decent sized position and consider current levels very attractive. The key datapoint is the growth in contractor numbers - now 78% of turnover - that will bridge any recession-induced hiatus in hiring trends. Not that there is any evidence of a drop in demand showing in the numbers. More pertinently, if there is no material fall in orders, the enhanced contractor book forms the platform for accelerated growth.
If I hadn’t spent much of my professional life with my assets bound up in the IT consultancy sector and consequently enjoy investing in newer (to me) sectors* nowadays, I would back up the truck. Likewise for DX providers, which nevertheless are also well represented in my portfolio.
*Automation
Energy Transition
Cybersecurity
Luxury Goods
Life Sciences
I note investors are selling into strength this morning perhaps encouraged by a PT cut from Jefferies’ clueless analyst. That may be a sensible call on market conditions but it is a wrong one on the company.
The results appear very impressive, however, I am unclear as to why cash conversion of profits is not better?
The results appear very impressive, however, I am unclear as to why cash conversion of profits is not better?
When contractor numbers increase, the demands on cash flow accelerate rapidly - contractors have to be paid at least a month before corresponding fees are collected, which is to say that, for each new contractor, two months of their costs need to be allocated afresh from cash. You can see buried in the commentary an acknowledgement that the emphasis on growing contractors is incompatible with the KPI of improving cash flow and they have dropped the latter as a target. With an objective of further growth this is entirely reasonable.
A number of agencies make use of factoring to reduce the immediate demands on cash flow - the factoring company pays the contractor his rate, then gives the agency a smaller amount than they eventually collect from the client company.
Many do. Although it doesn’t work as you describe. The bank remits directly to the agency on notification of an authenticated invoice to the customer. The agency pays the worker out of this sum and often from reserves, depending on the margin on the contract. Thus each additional contractor still adds to the drain on cash if the factoring doesn’t cover the whole cash demand.
Factoring also increases average debtor days and bad debt as credit control gets lazy when the bank keeps the current account afloat.
I think that a large increase in receivables could be the answer here. Not adding VAT (or it's equivalent overseas) I calculate that if it's all trading debtors then it equates to 39 days worth of sales. Am I in the right ballpark?
I hold - and regret not buying more more a month or so ago
CFO bought £20k worth of shares this morning ...
In line but somewhat downbeat update from perennial favourite Judges Scientific (LON:JDG) . I've held before and I've been waiting to get back in but the valuation has always managed to stay out of my reach even throughout the recent market turmoil. I've struggled to make sense of the valuation in the light of the market's general marking down of growth shares and I wonder if the price might start to drift downwards on the back of today's update:
Organic order intake up 4.2% (25.1% gain in H1 2021) - 7.8% progress compared to H1 2019 - "cannot be considered a full recovery to the pre-Covid growth trajectory."
"Rest of Europe was flat (after 34% growth in H1 last year) reflecting varied performances across the region"
"UK, which had progressed 26% in H1 2021, was down 9.4%" (my bold)
"modest increase in order intake"... "ongoing supply chain difficulties"
"progress was hindered by supply chain issues, by staff shortages caused both by recruitment difficulties and by numerous colleagues having to isolate."
"general market conditions remain challenging."
Overall they remain confident of meeting expectations but whilst I've selectively extracted the most negative parts of the update, I was struck by the unusually downbeat tone for such a highly rated performer - it'll be interesting to see how the market responds to this and if the share price can continue its bulletproof run - I suspect not and hopefully it may present a buying opportunity in the months ahead.
Reading between the lines on Judges Scientific (LON:JDG) I have to wonder about dilution. I hold.
Good morning all,
Science (LON:SAG) record first half results this morning. Some softness expected in some of their markets going forward, but they are well diversified in terms of revenue streams and remain "quietly confident" for full year.
Large cash pile and freehold property two big positives also. Will you cover today Paul?
They're not record results though are they ? Revenue yes, but profit is lower and they've used some adjusting items to create the illusion of growth. Still a great business though...
Morning JohnDoe2378,
Re Science (LON:SAG) -
Will you cover today Paul?
Yes, I'm planning to cover SAG, and also £STEM today.
Graham is looking at Judges Scientific (LON:JDG) and possibly 1 or 2 others.
Regards, Paul.