Small Cap Value Report (Mon 25 Nov 2019) - CER, IGP, D4T4, BRCK

Good morning, it's Paul here. I hope you enjoyed the weekend. I'm possibly a little behind the curve here, but have this weekend enjoyed binge-watching The Crown - isn't it marvellous!
Also, I had to chuckle when my mobile went off at 12:30 am on Saturday morning, from a friend who happened to bump into a Stockopedia subscriber in what sounded like a busy bar or nightclub! They just wanted to say hello, and how much they like the SCVRs! So hello to DavidF and Davidj128 - who subscribed here 3 months ago - good man! They signed off by quipping that, seeing as it was me, with my reputation, they guessed I wouldn't mind them calling me past midnight to have a friendly chat. Absolutely correct!
Timings - I've got a call booked in with Cerillion (LON:CER) management just after 11 am, to discuss its results. These calls tend to take up quite a lot of time beforehand, to prepare (i.e. thinking up some intelligent-sounding questions, in order to avoid appearing clueless!), and afterwards, to digest and write about it.
I've mentioned here before that CER looks quite an interesting company. So when an adviser got in touch to see if I'd like to talk to management, I replied yes please. (it's not a share I currently hold, but is on my watchlist).
So that's likely to dominate most of my morning. After that, I'll try to cover everything else of interest in the trading updates/ results statements from small caps within my remit.
Therefore, we're probably looking at an all-day job, with completion estimated at 5pm.
Update at 17:33 - today's article is now finished.
My initial sweep of the RNS has thrown up these items which I'll tackle today;
Cerillion (LON:CER) - final results, FY 09/2019
Intercede (LON:IGP) (in which I hold a long position) - interim results, 6m to 30 Sep 2019
D4T4 - interim results, 6m to 30 Sep 2019
BRCK - interim results, 6m to 30 Sep 2019. This is a recent IPO.
Cerillion (LON:CER)
Share price: 192p (up 3% today, at 09:31)
No. shares: 29.5m
Market cap: £56.6m
Cerillion plc, the billing, charging and customer relationship management software solutions provider, presents its annual results for the 12 months ended 30 September 2019.
These figures look good;
- Revenue up 8% to £18.8m, although only 27% of this is recurring
- Big increase in order book - up 69% to £22.0m
- Adj PBT up 12% to £3.5m
- Tax - note that it pays very little corporation tax, due to R&D tax relief - that's fine, but worth bearing in mind if this valuable benefit is ever withdrawn by Govt, then it would whack the share price (as with other companies which also benefit from this policy)
- Adj EPS is 11.3p, giving a PER of 17.0 - this valuation looks reasonable, given the decent performance, and strong outlook comments. Note that 11.3p EPS is a beat against forecast of 11.0p, a good thing
- Total divis for the year of 4.9p, up 9%, giving a yield of 2.6% - not huge, but it's well-covered, and rising, so perfectly acceptable
Balance sheet - looks good, including £5.0m of net cash. Although receivables look unusually high, and there is £2.4m receivables within long term assets, which is very unusual. I shall ask management about this on my call later this morning.
Outlook comments - are upbeat. I particularly like the bit about winning major new contracts, but this section below is stuffed full of positives;
"Cerillion has delivered a strong performance with revenue, pre-tax profits and new orders all achieving record highs. The four major new customer wins continued a trend towards larger deal sizes with larger customers and stand us in good stead for further new wins. Three of the four were signed in the second half, increasing our back-order book to a new high. With a further major new win secured in October, we start the new financial year with greater revenue visibility than at the beginning of any previous financial year."
"Industry trends in our core telecoms market mean that demand for our solutions remains strong and with recent sales success, a strong new customer pipeline, the ability to rollout new and enhanced product modules, and ongoing recognition by industry analysts, the Company is very well placed for continued progress."
Broker forecasts for FY2020 and beyond have been increased today by about 7%.
We're now looking at 12.6p for FY09/2020, with comments that this could be increased again. If we say that 13.0p looks possible, then the PER would be 14.8
That looks good value to me.
EBITDA - is largely meaningless, as £833k in development spend was capitalised.
My opinion - I'm impressed with the numbers, and positive outlook, combined with a valuation that still looks reasonable, even after having had a good run this year.
Management is long-serving, and hold about 40% of the company - plenty of skin in the game there. I agree with Tim Martin (of Wetherspoons), in his recent comments that it's far better to have long-serving, experienced Directors, than to change the composition of the Board in response to box-ticking regulatory ideas.
Cerillion seems to be on a roll. I particularly like situations like this, where companies are winning large, multiple contracts. That usually tells us that the product is very good. Contract wins can then become reference sites, to give other new customers confidence, thus creating a snowball effect.
On the downside, the company seems to need a constant pipeline of new contract wins, almost running to stand still perhaps? The main risk in future is if it has a lean patch of new contract wins, which could cause a profit warning.
With a strong order book, the outlook seems good. Overall, this share gets a thumbs up from me.
Stockopedia awards it the coveted "High Flyer" classification. The StockRank is positive, and I bet this is likely to rise, once the upgraded broker forecasts feed through into the data, which should push up the momentum part of the StockRank;
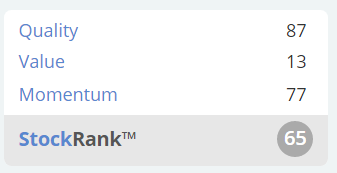
Call with management - I've just come off the phone to the CEO & CFO of Cerillion. The tone was upbeat, as is the RNS. It looks like a business that's on a roll. I asked some fairly dry accounting questions, and got reasonable-sounding answers. In particular, the long-term receivables balance of £2.4m relates to extended payment terms for customers, which they see as a useful differentiator. Keen to keep a strong balance sheet with plenty of cash, as customers expect a mission-critical software provider to have decent financial strength.
A subscriber here, Phil Dunfy, put forward 3 good questions in the comments below (no. 5), which I managed to get answers to, as follows;
1) What's your competitive moat? Standardised product set, straight out of the box, so quick to set up. Being a small & agile company, Cerillion can serve its customers better than large software companies, who can take years to write complex software.
2) How much reliance on a few key customers? Largest customer was about 20% of revenues, top 5 are 55% of revenues. But the top clients list changes each year. Lots of follow-on revenues, over many years, from new customers. So revenue much more predictable than 27% recurring revs figure suggests.
3. Growth plans? Yes most customers are tier 2 or 3, but it's modular software, so some larger customers take partial product. Size of customer wins is increasing, augurs well. Mgt want to grow the business faster, and scale it up. Possible acquisitions, but has to be complementary, and accretive to earnings. Private Equity are possibly over-paying, making it difficult to find sensible deals. There has been a reduction in competitors, e.g. Chinese & others withdrawing from the market - good for Cerillion.
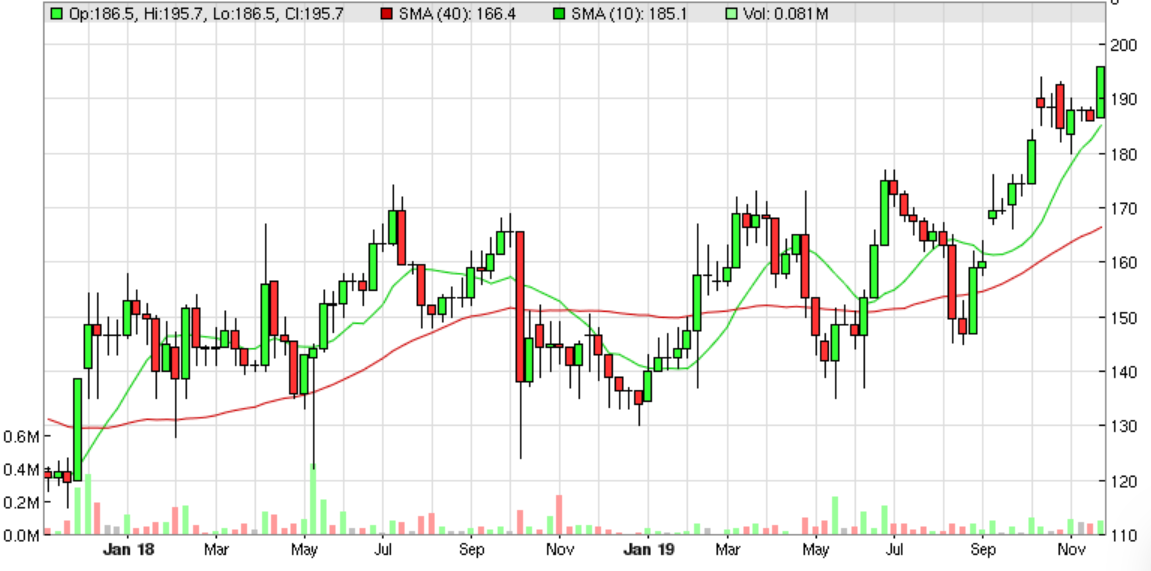
Intercede (LON:IGP)
Share price: 34.5p (up 4% today, at 12:05)
No. shares: 50.5m
Market cap: £17.4m
(at the time of writing, I hold a long position in this share)
Intercede, the leading specialist in digital identity, credential management and secure mobility, today announces its interim results for the six months ended 30 September 2019.
On the face of it, these figures look unremarkable - a tiny company, producing only £4.4m revenues (up 5% vs H1 LY), and eking out an operating profit of £25k, a loss before tax (after the heavy finance charges) of -£263k, and a profit after tax (benefiting from R&D tax credits) of £184k (this last figure of £184k is the most meaningful number, in my view, as it takes into account everything).
What's the excitement then? Two things;
- Client list - is astonishing for a small AIM company. We're talking Government agencies (especially in USA), and some of the world's largest companies.
- Turnaround under new management, which is much more commercially focused than before.
Customers are very sticky, typically once signed up, remaining clients for 10-15 years, or even longer. It's high margin business, therefore the potential is for operationally geared growth, and potentially a takeover bid from across the pond (about 70% of revenues come from America) .
Set against that, Intercede has been around for a long time, with several false dawns under old management, therefore I can understand why UK investors want to see proof of progress before chasing up the share price.
I had a good meeting with Intercede's new management earlier this year, and came away with the impression that they know what they're doing. The strategy makes sense, they've stabilised the business, now the big question is whether they can accelerate the growth. If they can, then we could have a multi-bagger on our hands. That's why I'm holding this share. Or, it might disappoint again, we don't know.
Balance sheet - is a little unusual, in that Intercede has £4.8m of expensive, convertible debt. It has also accumulated a cash pile of £5.2m (+£460k tax credit received after the period end). Therefore, my hope is that the company could soon pay off the expensive debt, and thereby boost the future P&L by eliminating the finance charges. Management are tight-lipped on their plans, just saying they're considering all options.
Intercede has had to raise fresh equity in the past, thus diluting shareholders. It's looking a lot more positive now that the company is cash-generative, and I hope it should not need to dilute shareholders again.
Customers - this bit in the commentary caught my eye, as it sounds encouraging;
As outlined below in the Financial Results section, we have received some significant follow on orders from existing customers, which provides tangible evidence our secure credential management software continues to deliver measurable business value.
We have sold three new deployments to the US Navy, US Airforce and one of the largest US wireless network operators. All of these deals were for our traditional smartcard solution although it should also be noted that we are continuing to see orders, along with strong interest and bid activity, for Derived PIV solutions...
Channel partners - this is the chosen sales strategy. No specific news, but positive noises are made;
Good progress has been made in the past six months working closely with technology as well as channel partners on new opportunity generation in our chosen markets.
Outlook - H2 weighting, which is unavoidable because a large client renews its contract at the end of March each year;
The actions taken to refocus the Group's strategy continue to drive improvements throughout the business. As in previous years, revenue is expected to be weighted towards the second half of the year
Whilst the nature of Intercede's business and customer profile is such that the precise timing of orders is difficult to predict, the current sales pipeline and levels of bid activity continue to support management's revenue and profitability targets.
Forecasts - FinnCap has put out a short note today, confirming its £11.0m revenue target for this year.
My opinion - the main risk is large, lumpy contracts. There's nothing that can be done about that, in the short term anyway. The good news it that contracts are very sticky, and a lot of revenue is recurring, or at least repeat.
If new management is successful in driving more rapid sales growth, then things could get exciting here. We'll just have to wait and see what happens. Obviously, as I hold this share, then I think risk:reward could be good. But it is clearly quite speculative at this stage.
D4T4
Share price: 205p (down c.5% today, at 14:57)
No. shares: 40.2m
Market cap: £82.4m
Specialists in Data solutions, D4t4 Solutions plc (AIM: D4T4) announces its unaudited interim results for the six months ended 30 September 2019.
A theme is developing today - this is the third software company with lumpy revenues that I'm reviewing.
As readers have already commented below, the headline figures for H1 reported today look poor. My notes here from the trading update on 23 Aug 2019 are quite helpful in getting up to speed - the company advised the market then that it expected an H2 weighting to this year's results - a message which is repeated today. Hence why poor H1 results have only hit the share price by 5% today.
Also bear in mind that the same thing happened last year, in an even more pronounced way - i.e. awful H1 figures, but they recouped it in H2. Hence management assurances about this year do have credibility.
I've just spotted that there was another trading update here on 21 Oct 2019, which disclosed the anticipated H1 revenues & net cash position (which are the same as in the actual results today). Although that update withheld the H1 profit figure, saying only that it was in line with full year expectations.
Today's interim results are just a short summary, with a link here to the full H1 results. I can see that D4T4 is definitely a company that specialises in managing data!
You can see how volatile H1 profit has been in the last 3 years;
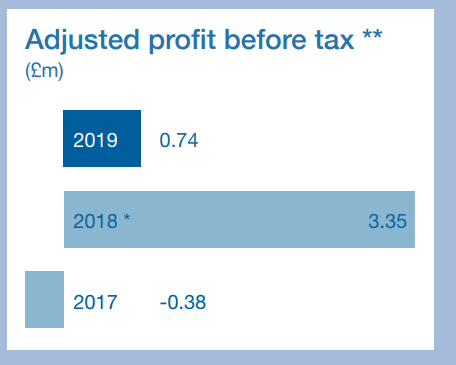
Outlook - this is emphatic;
The Board remains confident in delivering a solid finish to FY20, in line with market expectations.
Therefore should investors be worried about the poor H1? Who knows.
The company does give sensible reasons as to why it thinks the full year should be OK;
Our prospects for H2 are strongly underpinned by a high level of contract renewals from new licences signed during the second half of last year and
strong visibility on new contracts due to initiate during H2.
This, combined with a significant pipeline of new business in negotiation with existing clients wishing either to increase the footprint of our software or to extend the use of our Hybrid Cloud Data Platform solution...
Given previous performance, I'm inclined to give the company the benefit of the doubt, although would want to price the increased risk into my valuation, just in case.
Balance sheet - absolutely bulletproof, including £11.2m in cash. The smallish divis look safe, given that the company has so much cash on its balance sheet.
Valuation - I've got an earnings forecast of 14.2p for this year. H1 achieved only 1.76p, so H2 needs to really delivery, to hit the full year forecasts. Management reckon they can do that.
My opinion - has to be neutral, as D4T4 has such wild swings in half-year performance, that we probably can't glean too much from today's figures. If it hits the full year numbers, then the valuation would look reasonably attractive at the current level. Especially when we take into account the lovely, cash-filled balance sheet.
Managing data seems to be a good growth area.
Overall quite interesting, although buying them at this stage is a leap of faith to a certain extent, relying on H2 being very strong.
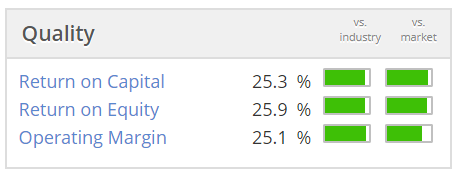
Stockopedia particularly flags very high quality scores;
Brickability (LON:BRCK)
Share price: 65p (up 6% today, at 16:15)
No. shares: 230.5m
Market cap: 149.8m
This is a new one for the SCVRs. It floated on AIM at 65p, 29 Aug 2019.
As the name suggests, it's a brick wholesaler, also selling other things to the regional & local housebuilding sector;
Brickability Group plc, the leading construction materials distributor, today announces its unaudited Interim results for the six months ended 30 September 2019 showing steady delivery of the objectives it set out at IPO.
The highlights show a good improvement in profit for its maiden interims;
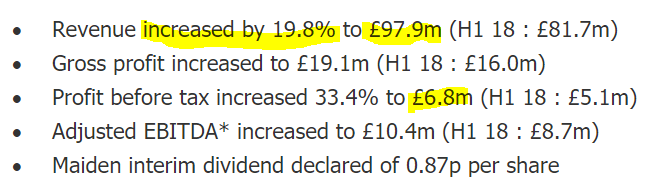
The net profit margin is just under 7%, which looks about right for a distributor.
Outlook comments are positive, and note that some of the growth seems to have come from acquisitions;
We are confident of building on a strong first half and the acquisitions made during the period are performing in line with expectations. We have a healthy acquisition pipeline, the outlook for our markets is positive and the board remains confident of meeting full year expectations.
Looking ahead, the longer-term outlook for our markets remains encouraging and we are pleased to see that all the main political parties have made substantial commitments to build more houses. Overall, the fundamentals for the housebuilding sector remain strong which gives us confidence that we will make further progress in the future.
I'm a little wary of groups which grow by acquisition. Whilst some have worked out brilliantly (e.g. Tracsis (LON:TRCS) and Judges Scientific (LON:JDG) ), others have run aground from stretching their balance sheets, and having incompetent management (Conviviality springs to mind). Let's have a look what this one is like.
Balance sheet - NAV is £78.9m. As you would expect, it's top-heavy with £74.8m intangibles, which will almost certainly be acquisition-related stuff. Writing off intangibles:
NTAV is only £4.1m - a little threadbare for my taste.
Another item that jumps out at me as looking extremely low, is inventories of only £7.36m. This is tiny, compared with receivables of £39.6m. How can the business operate with annualised revenues of about £200m (ex. VAT), with only £7.36m inventories? The only answer I can imagine is that perhaps it drop-ships products, direct from suppliers, instead of holding its own inventories? Or, the period end dates happen to coincide with drastic de-stocking?
I've had a rummage through the AIM Admission Document, and my question is answered on page 18, which says;
In the opinion of the Directors this has provided an opportunity for distributors like Brickability Group to build up an understanding of the products available from manufacturers, both in the UK and in Europe and to discuss and negotiate a wider range of options for the type, volume, price and timing of bricks needed by customers.
There is generally a cost advantage for the customer when sourcing product through a factor, as customers benefit from the factor’s scale of orders. Such sales often do not require the Group to take physical possession of the bricks and, instead, they are sent directly to the building site of the customer.
So my hunch was right, BRCK is acting as an intermediary, and not necessarily taking delivery of the bricks itself. Hence why inventories are so low. That's a nice business model, as it means that BRCK only ties up significant capital into receivables, and not the more usual combination of receivables + inventories. Therefore, I can see why BRCK doesn't actually need much NTAV for its particular business model.
Although I do wonder if the brick manufacturers might, at some point, decide to cut out the middleman, and sell direct to smaller housebuilders?
Valuation - the house broker is forecasting 6.2p EPS this year, and 7.4p next year. Therefore the PER is about 9-10, which looks about right to me. I can't see why you would want to pay more than that, for a distributor.
My opinion - it looks an OK business, but I wouldn't want to own shares in it, due to the risk of it being cut out of the supply chain by brick companies selling direct.
Also there is a question mark over all new floats. We've been caught out so many times by companies floating, and then it turning out that the stock market float was an opportunistic sale, at an inflated price, based on unsustainable profits. For that reason, I'm very wary of new floats.
Housebuilding in the UK is at a cyclical high, so maybe that has boosted profit margins for intermediaries like BRCK?
On the upside, this company has been around for a while, and the major shareholder list shows Directors owning about 28% - lots of skin in the game, which I like.
Overall, it's just not the type of sector that interests me at all.
That's it for today. See you tomorrow morning.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
testing..
Hi Paul, thanks for the shout out and being a good sport when Dave and I pestered you Saturday night / Sunday morning. Really enjoying the small cap blog as I start to find ny feet as a beginner. Keep up the good work!
Friday / Saturday morning even. It is a bit of a hazy memory ;)
Cake Box (CBOX) might be interesting to look at. Interim results and CFO just bought £150,000 worth of shares. 100,000 shares at £1.50. I haven't looked at the results closely yet.
Hi Andrew,
Re Cake Box Holdings (LON:CBOX) - that's certainly a conviction buy, an FD buying £150k worth of shares. Although judging by his total holding of 3.67m shares, he's an unusually wealthy small cap FD!
I'm having a quick look at the interims from CBOX today, and don't see anything very interesting - adjusted profit being down 12%
I recall that, earlier this year, I dug quite deep into this company's accounts (unfortunately it's not coming up on the search here), and came to the conclusion that a lot of the profit was probably coming from selling franchises, rather than from actual trading. Since the company doesn't disclose the split, then it's very difficult/impossible to value.
Members here were also sceptical - with some pointing out that there are lots of egg-free cake shops around, in areas where there is demand for that. Falling footfall is another issue - how credible is it that any retailer can prosper long-term, when so many High Streets are struggling with declining footfall?
For those reasons, I'm not keen on Cake Box.
Regards, paul.
Thanks Paul,
Good point on selling franchises. I read your previous piece and that did raise some question marks.
The IPO prospectus has the split for where the revenue in the business comes from in the year to March 2018. See P15:
https://investors.eggfreecake.co.uk/wp-content/uploads/2018/06/Cake-Box-Holdings-plc-Admission-Document.pdf
But it doesn't split it for the profit I don't think. For what it is worth the importance of selling franchises will decline over time as overall revenue increases. They aim to open 24 stores a year with a target of 250 versus 122 at the end of September 2019.
I was sceptical about their proposition but the store near me seems good. Very strong like-for-like sales growth over the last 3 and a half years.
The proposition is distinguished I think through the rapid cake personalisation and online ordering. Also the cakes are attractively priced. I have had one and it was nice.
Patisserie Valerie going bust may have helped reduce the competition. But I agree it is a niche consumer offering and so how it will do over the long term is hard to say.
I think the high street decline isn't really an issue as they are a destination store. They are also considering opening sites next to transportation hubs/stations .
One to watch anyway.
Thanks, Andrew
BTW my mistake the Finance Director bought £225,000 worth of shares - 150,000 bought at £1.50.
Thanks Andrew,
Interesting follow-on points from you.
Regards, Paul.
Hi Paul,
I think the write you are talking about was the 14th of October. Link below.
https://www.stockopedia.com/content/small-cap-value-report-mon-14-oct-2019-cbox-sys1-rno-ygen-spa-520881/
Not sure why it is not showing up in searches, one for Ed and the team.
Paul,
You might want to have a look at MTI Wireless Edge (LON:MWE) which had Q3 results this morning. They made a V interesting presentation at Mello (which I don't think you attended. But today's numbers look rather strong.
I have been an happy holder of £mwe over the last 2 years and have seen it appreciate very pleasantly this year. It has three separate businesses which are all growing and have a lot more room to grow in my opinion. Whilst not an expert on their technology my understanding is a lot of it is leading edge and so it wouldn't suprise me at some point to see a bid come in at a considerable premium to its current price.
Personally I hope though it doesn't and it continues to grow.
Hi grumpy5,
Sorry I didn't get round to looking at £MWE
Skimming through its results today, the figures do indeed look pretty good, and with an upbeat commentary too.
I try to avoid overseas small caps, listed in the UK, as so often there's something wrong with them. Although in this case, MWE has been around for a long time, and it pays decent dividends, which are both good signs.
Could be worth a closer look maybe?
Regards, Paul.
I am as confused as everyone with regard to D4t4 Solutions (LON:D4T4) - you could read these interims and go either way depending on wheter you are glass half full or empty.Would appreciate your views
Re £D4T4 could it be that management see no icebergs because they are holding their telescope to their glass eye?
(Disclosure: I have a small shareholding.)
simoan, I totally agree with the challenges of transitioning from license revenues to SaaS. It’s one of those situations where you have to take the original time estimate and double it. I worked for a listed US software company going through this process and as you say, the share price fell out of bed before private equity stepped in to snap us up (on the cheap?). The re-IPO was planned for 2018, then 2019, now ???
This said, companies that are SaaS from the beginning and achieving decent penetration or more mature companies that have crossed the 75/80% of recurring revenue threshold, then they become interesting, especially if they have a high renewal rate from their SaaS customers. At this point, they also become attractive as takeover targets, being cheaper/smaller than US rivals and in combination with weak sterling - it would not surprise me to see a few takeovers in this space over the coming months. Intuit to buy Sage anyone?
Cheers
Simon
I looked at Cerillion (LON:CER) earlier in the year with a mind it could be interesting. I was put off for a number of reasons and believe this is a business that has a high probability of having a problem moment:
1) Low recurring revenues...but I feel the valuation and vibe on company implies higher recurring amount
2) I suspect its a fairly vanilla product, no great shakes, so established relationships etc and companies sticking to the status quo important
3) I don't like that capitalise software development spend to the tune of £830k (in 2019 this has been nearly all covered by amortisation but in 2018 there was a net £500k boost to earnings from it, only c.£60k in 2019)
4) Why don't I like 3? Number or reasons. a) Only comfortable with it on recurring revenue stuff which is c.25% of revenues...-> not too bad then you are thinking > b) they ain't involved in any rocket science and they the cost they are paying for software engineers is low at approx £50k I estimate (figure from memory so best to check out yourself) -> now you say that the coders are in Pune India so are cheaper and then that leaves me uncomfortable about the genuine barriers and specialness of product and back to whether they should capitalise
(note, amortisation is bigger as they write down about £1m in IP and purchased contracts)
5) Working capital is messy...if you want to be cynical then all of the cash growth can be accounted for in movements in working capital....this again hints at perhaps a creaky rather than healthy growing business. Some points re WC...
6) £10.5m of receivables....of which £2.4m is for non-current accrued income...so earned income but not yet billed or received!? It was £577k in 2018 which was fishy enough! All and more of revenue and gross profit growth covered by this £1.8m increase
7) Payables up by £2.4m too. Trade payables are actually down from £960k to £500k the increase is mainly combo of increase of £1.65m deferred income and £0.85m accruals. Deferred income good perhaps (but still has risks around it and significant in context of revenues) nevertheless the point is that the cash gain in cash flow statement has a lot to with this increase in payables
Altogether I feel that Cerillion is a company with a high propensity to negatively surprise. I can't see what is specifically wrong and I don't know their business but based on numbers they look a short and not a long
"if you want to be cynical then all of the revenue and cash growth can be accounted for in movements in working capital".
That would be very cynical - movements in working capital shouldn't have any revenue impact.
True...so I corrected it...the dangers of quick thinking and writing is the blurring of points...
But the points re Cerillion (LON:CER) overall hold?...or have you got a counter? I do not know the company. I started looking earlier in the year and the financials put me off diving into the operations. Feels like a company stretching to look better than it is with a shakier revenue/growth path that is implied in the price
Morning all,
Re reader requests above, yes, I'll be happy to look at £IGP and D4T4 results later today.
Regards, Paul.
Hi thanks Paul and everyone who commented on £D4T4
D4t4
I am non the wiser really as the arguments here reflect my internal thoughts. If they miss H2 they will be hammered but a growing business in data management with a load of cash, it’s not expensive. As there are some interested parties holding, or thinking of buying, or selling (sounds suspiciously like a market :) - here is my response from the CEO a couple of months ago.
Q&A's
What are the options to make Celebrus a PAAS service where recurring revenues become a bigger part rather than the lumpy license fees. If Celebrus is to become PAAS type platform could you please comment on the roadmap ?
We supply our software in any form that the customer requires. Many of our customers are large financial services companies who will use our software on premise for many years and as a result want to purchase perpetual licences that they will depreciate as a capital purchase over a 4 or 5 year period. As a result we are currently weighted to perpetual, however if you look in the last full year’s results page 6 you will see reference to a number of multi-year annual recognisable contracts closed in H2 last year. This will hopefully provide us with more of a balance between recurring and perpetual licence revenue in the future.
Are there any KPI’s on the number of customers you have for Celebrus & what like for like up-lift there has been over previous periods?
Read the previous reports and presentations on the investor section of our web site and you will see the uplift for Celebrus clearly shown on page 2 of (2018/19) full year presentation shows 43% growth in Celebrus revenues
You do not seem to split out recurring revenue from software maintenance. Could you please provide the % split and explain what the recurring is for?
We split out support and maintenance as can be seen on page 11 of the (2018/19) full year presentation
Could you please provide the split of revenue received from direct sales compared to partner produced revenue?
We do not provide this number but you can see from our annual report page 76 the revenues from our two largest customers (customers over 10% of revenue) which are both partners and therefore indirect sales. This gives a good indication of the split…
Are you looking to keep the chief data officer role now Matthew Tod has resigned?
As reported in the announcement we have re-allocated the function internally to our expanded team and will not be replacing the role
Could you please comment on the large director share sales recently, I would have thought purchases rather than sales given the confident outlook & relatively low financial ratios D$T$ are on?
The sales by directors were for various reasons, One is one of our non execs reducing his holding prior to his eventual retirement, another was reducing his risk of investment in one stock as the price increased, another was selling some stock for personal reasons, the rest were to pay for the options exercised. All stock went to institutions as there was sufficient demand.
Our main interest really is where are D4T4 on the journey to PAAS/SAAS and if possible given the nature of the software and its use.
We will continue to supply our software and our data platforms in any way the customer requires them in either on premise, paas or saas versions. If we restrict the customers to paas or saas we limit the use of our products considerably.
The market is driving towards “as a service” and we are experiencing a gradual shift. We will not pressure the rate of shift to our present and future customers at this time.
Hi Paul it would be great for you to ask Cerillion (LON:CER) mgmt:
1. What they believe their competitive moat is? Industry word is their offering is 'vanilla'. I'm not close enough to their product set to understand..
2. How much reliance / % revenue is focused on a few key customers. Billing once won is relatively sticky, although when lost it has a big impact, new customers are also 'lumpy'
3. I understand they only have tier 2/3 customers, what are their growth plans here to either improve/diversify
Just my two pennies, good luck for later.
Thanks Phil,
Those were really good questions you came up with, for my call with Cerillion (LON:CER) - thanks!
Please see the updated article above, where I've published the answers to your questions.
Best wishes, Paul.
Hi Paul,
Would you be able to look at £D4T4 (I can’t get the ticker to work) the ‘all about the data’ bunch. The half year results are a little hard to read because of the huge h1/2 weighting they had last time. For once the H2 came through last time but I am not really sure here.
My other concerns are they have the real-time application celebrus, the star product. They call it a platform but it seems to me it’s a software product & they refer to recurring revenues as though they are subscription revenues when they appear to be maintenance & support. They speak of an industry growing at 19% but if they have a killer application, which they say they do, I’d expect much more growth. The client list looks a bit week too.
I’ve had an email conversation a few months ago and they say the clients want the product on a license basis ‘So that’s what we do’ , they were quite blunt on this point. But.....if it’s killer they will pay SaaS/subscription. Now I read clients are increasingly wanting SaaS.
These are founder/owners with good shareholding ceo 5%, but I’m not sure if just a bit old school.
Anyway, those are my thoughts and I’m partly verbalising my thinking as I’m now thinking of selling my non-conviction holding.
Anyone with a view on £D4t4 much appreciated.
D4t4 Solutions (LON:D4T4) Hi John652, another vote for D4T4. H1 results are down significantly on H1 '18 so H2 will need to be very good although the words are encouraging.
I've had a quick look at D4T4 and not convinced by the narrative. The below shows a breakdown of revenue 2019 v 2018. Looking at the 2018 1H results, the narrative stated the £13.9m total revenue reflected a return to a "more normal trading cycle following the unusual business phasing seen last year."
Also, if there was an increase in revenues in 1H 18, then contract renewals should be reflected in 1H 19. Does this imply customers take on the product and after a year they are not renewing?
Perhaps the new contract wins will come through in 2H along upsales to existing clients, but seems like there is a mountain to climb.
D4t4 Solutions (LON:D4T4) cash adjusted PE of 12 is very low for a decent technology company and their product is good. We had the same H2 weight a couple of years ago when everyone was panicking they wouldn't make it and came in bang on where they said they would. My sense is that management have a decent ability to forecast. EPS forecasts have actually risen during the year so they've been upgraded. Gross margins are rising as. Balance sheet is very strong with good levels of net cash and no debt.
Not sure what you mean re SAAS. If you read page 4 of the interim report you will see that they recognise this as a marketplace change and are in active discussions with partners and clients to move to this model. Growth in Cerberus is strong, services revenue was what, up 46% in H1?
A data analytics business with a good product and growing client list on 14* earnings and 12* net of cash. Looks cheap to me
A data analytics business with a good product and growing client list on 14* earnings and 12* net of cash. Looks cheap to me
IMHO companies that go from feast to famine every 6 months because they rely on lumpy license revenues deserve to be cheap. I'd say 12x adjusted earnings is no better than fair value for such a company. And as for holding a software company that is transitioning from up-front license revenues to a subscription based SaaS model... let's not even go there! Recent history shows you really don't want to be holding during this period unless you can handle the subsequent share price falls. Even real quality companies like Sage (LON:SGE) have suffered.
All the best, Si
To be fair to management they guide on an annual basis and have a strong track record of hitting the expectations they set. If they "missed" or had a poor track record then I could understand the market scepticism (Cloudcall spring to mind), but so far they've been consistent. Why should we judge a company on an arbitrary set of quarter or semi-annual if the business isn't set up that way! The core problem is that some companies use "weighting" disingenuously which then tars everything with the same brush. Commentators then push towards a "regular revenue" saas model as being the holy grail but woe betide you if you actually move to effect that model.
Against peer group they are cheap. You could argue the peer group is expensive of course, in which case they may be fair value. I can see them growing at a CAGR of 15% p/a for the next 3+ years so for me undervalued, but we shall see. I'm happy to hold unless the narrative changes.
To be fair to management they guide on an annual basis and have a strong track record of hitting the expectations they set. If they "missed" or had a poor track record then I could understand the market scepticism (Cloudcall spring to mind), but so far they've been consistent.
Yes, but I work in a business with lumpy revenues and so know how very difficult it is to estimate if/when a sales pipeline will turn into revenue. It's good that they have a track record of getting it right, but eventually they will get it wrong. What today's RNS really highlights is the operational gearing in this business. If things go wrong it will not be profitable, and particularly in light of the change of business model, the risk of that is being heightened during the transition to SaaS. None of us have to hold a share working on this basis, other companies with higher quality (i.e. more predictable) revenue streams are available...
As I said before, it's very easy to see why the rating is low.
All the best, Si
Is a low rating for a company a good or a bad thing, it depends if you're a buyer or a seller.
As I'm a buyer, I'm quite happy that D4t4 Solutions (LON:D4T4) has a low rating (happy enough that I topped up a little bit this morning). I understand that people would prefer steady revenues and earnings. For me, as the share price will eventually reflect the discounted future cashflows, I don't mind if these cashflows jump up and down, so long as the general (longterm) trend is for them to grow.
As I'm a buyer, I'm quite happy that D4t4 Solutions (LON:D4T4) has a low rating (happy enough that I topped up a little bit this morning). I understand that people would prefer steady revenues and earnings. For me, as the share price will eventually reflect the discounted future cashflows, I don't mind if these cashflows jump up and down, so long as the general (longterm) trend is for them to grow.
The trouble is the market does not view things this way. Particularly with small caps we know how short-sighted it can be. And the free cashflow generation of the company is nothing to write home about. Although it goes from positive to negative like a yo-yo, if you take a 5 year average it is on a FCF yield of approx. 4% - not what I would call cheap.
All the best, Si
Be interested in your thoughts on Intercede 6 months Paul. Pretty much teed up by their trading update in October. But cash looking good with further 1/2m from research rebate still to come. Some good names added. In profit but feels it will take something significant to move this share price.
Northern Bear (LON:NTBR)
Ticking over interims out today , not as good as last years but acceptable based on the comparatives being exceptionally good. Pretty much as flagged up per the trading update back in October.
Price seems to have stabilised around the level the new large shareholder (just under 30%) bought at give or take.
Cash flow somewhat negative due to natural fluctuation in working capital (and not helped by dividend payment)- they had well over 100% cash conversion ye 31/3/2019 so nothing to specifically worry about there mee-thinks. I would say balance sheet isn't the strongest for this company due to the large payables totals and large receivables - always slightly dangerous if they ever have large customer not pay up.
Outlook seems fine but next to no actual visibility ref profits as is always the case with this company :) - old fashioned wait for full time before one celebrates (lesson for man u fans there?). And then repeat with next outlook statement.
Time for a bit of Whey Aye soon perhaps? (£100 mill potential investment in the toon if that project goes ahead - hopefully they could grab a piece of that construction pie)
As ever p/e still under 6 for this company - will it ever revalue to p/e of 10? - at current level of ticking over they should have money for modest acquisitions or to improve the balance sheet somewhat so it's everything trending in the right direction if you ignore the recession threat. Note ignoring intangible w/offs this company has delivered 10 consecutive years of profits (i think)- that's not bad even if there has now been no recession for that long.
My morning smallcap tweet: Dull
Sportech (LON:SPO) Nuformix (LON:NFX) Corero Network Security (LON:CNS) Zoetic International (LON:ZOE) WANdisco (LON:WAND), Idox (LON:IDOX), SysGroup (LON:SYS), Gateley Holdings (LON:GTLY)
Sportech (SPO) guides FY adj EBITDA, excluding Sports Betting investments (why?), ahead of mgmt expectations, rev in line.
Nuformix (NFX) £1.25m placing at 7p, a 17% discount. Described as a 'tactical' placing (that's a new one) "to strengthen its overall position during negotiations in Asia for NXP002 and accelerate progress within two promising programmes."
Corero Network Security (CNS) £3.25m placing at 3.5p, an 11% premium! Will keep the lights on and fund SmartWall. If co doesnt get the placing away it will have to immediately secure alternative financing.
Zoetic (ZOE) trading: busy with lots of stuff but no financials at all.
Wandisco (WAND) keep the lights on $16.5m placing at at 425p, a 22% premium!
Wandisco (LON:WAND) not sure this is a "keep the lights on" placing MrContrarian, they had plenty of cash before this, but they obviously see the need to continue developing and spending.
Interesting that both last raise and this raise were done at quite large premiums (though last raise is now underwater) and taken up by decent institutions. The stock is illiquid so I guess if you wanted to buy in size directly in the market you couldn't anyway. I must admit to having an affection for Wandisco (LON:WAND) mainly because I made good money on it a while back and having sold out much higher did buy back around this level.
I think it has a world class product and see it at an inflection point. My concern is that revenue growth doesn't appear to be anywhere near what I thought they'd manage but my rationale for owning is that I am expecting someone big to buy it like Amazon AWS or Microsoft at a big premium. They have serious partnerships with both so it's not a stretch that one of them would want to take them out and embed into their cloud offerings. I believe they have the highest level of partner accreditation currently, which adds weight to that possibility. Personally I think they'd be better off on a US exchange for that reason and US investors.