Small Cap Value Report (Fri 23 Aug 2019) - GDWN, ESL, ETO, STL, D4T4, SPE

Good morning, it's Paul here.
I had a few technical problems getting yesterday's article to update, so have decided to start with a new article today, with the backlog from yesterday.
Timings for today - I'm not sure at the moment. In all likelihood the remaining backlog from yesterday might have to wait until this evening, or tomorrow morning.
Goodwin (GDWN)
Share price: 3480p (up 1.5% at close yesterday)
No. shares: 7.2m
Market cap: £250.6m
This is an engineering group. Several readers asked me to look at it yesterday. Unfortunately, the section I wrote yesterday disappeared when I updated the article, so am having to write it up again now.
Results for FY 04/2019 look solid:
- Revenue up 1.8% to £127m
- Pre-tax profit up 11% to £14.7m - note the decent profit margin of 11.6%
- Diluted EPS of 150p - giving a PER of 23.2 - that looks very pricey compared with Castings, which I looked at yesterday, on a PER of about half this level.
Outlook - this is the exciting bit. There's been a huge increase in the order book, with more in the pipeline:
Furthermore, I am also delighted to confirm that we have seen a significant rise in the level of sales order input within our Mechanical Engineering Division. Whilst some individual elements would not be notifiable the aggregation is significant for the Group. With this exceptional input, I am able to confirm that, at the time of writing, the Group order input since the start of the new financial year stands at £93 million and the total forward order book stands at a record £165 million (July 2018: £85 million), a 94% increase from this time last year, with yet more large long-term contracts, that we have been targeting over the past few years, still to be placed.
That sounds tremendously positive. I wonder what's driving it? At a guess, cheap sterling must be boosting things. Weak sterling is reported on the news as being something terrible, but of course it's positive for UK producers & exporters, making them more competitive.
Here are my notes from reviewing the results today;
- Very positive commentary & outlook
- Capex heavy
- Capitalised development spend of £1.5m - not very much
- High inventories - but £5m due to unwind. Still high though
- Balance sheet OK, but weaker than Castings (CGS)
- Big fall in cash generation compared with last year
- Reduced reliance on petrochemical industry
- Some debt on balance sheet, but looks OK relative to profits/cashflow
My opinion - I can see why readers like this, and asked me to review it - because the outlook comments, and large increase in order book, suggest that profits could rise strongly in future.
Which is better, Castings, or Goodwin? On balance, I'm more drawn to Castings, as it's much cheaper & has such a strong balance sheet. Although Goodwins seems to have much more exciting potential for growth - which is priced into the shares.
Weak sterling means that these UK businesses have quietly been getting a lot more competitive of late.
Eddie Stobart Logistics (ESL)
Share price: 71p at close yesterday - suspended from 07:30 today
No. shares: 379.3m
Market cap: £269.3m
Directorate change, company update & suspension
Eddie Stobart Logistics plc, a leading UK end-to-end supply chain, transport and logistics group...
EDIT: NB. please note that this announcement relates to ESL. There is another UK listed company called Stobart (STOB), which owns 11.78% of ESL, according to ESL's website here. So it's a bit confusing.
Sounds like very bad news. To summarise:
- CEO standing down with immediate effect
- Replacement CEO being promoted internally
- Accounting problems have emerged;
As part of the Group's review carried out in conjunction with the Group's auditors in relation to the interim results, the Board is applying a more prudent approach to revenue recognition, re-assessing the recoverability of certain receivables, as well as considering the appropriateness of certain provisions.
While revenue expectations for the first half are broadly in line with previous guidance, the full impact of these items on Adjusted EBIT is unclear, but it is likely to be significantly lower than anticipated at the time of the Half Year Trading Update on 9 July 2019.
As a result, the Board also intends to review the Group's current dividend policy.
Suspension - normally an announcement like this would probably hit the share price by perhaps 50-75%, in my experience. That's not possible in this case, as the shares are being suspended, pending clarification of the financial impact.
Accounts delayed - but not by much. Interims (6m to 31 May 2019) were due out on 29 Aug 2019. This will be delayed until "early September".
Outlook - management say they are confident:
The Board has full confidence in the ability of Eddie Stobart's management team to deliver an improved performance for the Group going forward, and remains confident in the strength of the underlying business.
My opinion - I've not looked at this share before. Looking back, its trading update on 9 July mentions accounting adjustments being required, but unrelated to what has been disclosed today.
I've had a quick look at the last reported accounts, and don't like what I see. The balance sheet is weak, with £312m intangible assets. Eliminate those, and NAV of £236m becomes NTAV of minus £76m.
Net debt was last reported at £154m, at 31 May 2019.
We've seen before (e.g. Staffline), how companies with stretched balance sheets (i.e. too much debt, and negative NTAV), which uncover accounting problems, may not have any safety margin to ride out the problems. That might trigger the bank losing confidence, possible breach of covenants, and an emergency fundraising being required.
This looks pretty grim to me. I hope none of our subscribers here hold this share.
Entertainment One (ETO)
This is getting ridiculous! Yet another takeover bid.
US-listed Hasbro is buying ETO for £3.3bn, or 560p per share. That's a 26% premium to last night's close.
With so many bids occurring, for decent-sized companies, it's difficult to avoid concluding that UK listed shares might be too cheap. Or at least some of them.
Stilo (STL)
This is de-listing after many years on the UK stock market.
It's absolutely tiny, both in terms of mkt cap (£1.65m), and revenues/profit. So a listing never made sense. It's looking at doing a tender offer for some shares are 1p.
It mentions lack of liquidity in the shares, and costs of "at least" £120k p.a. Clearly that is money wasted.
I think this is a good opportunity to review any micro caps which we might have languishing in our portfolios. Does it make sense for them to remain listed? If not, then a de-listing announcement could clobber the share price.
D4t4 Solutions
Share price: 230p
No. shares: 40.24m
Market cap: £92.6m
AGM Statement (trading update)
This update relates to trading for the year to date, FY 03/2020. I wish the company would explain its activities more clearly. As far as I can tell, it sells software & services relating to data management.
I last reported on D4T4 here in June, with a quick look at its results for FY 03/2019 (Financial Year ended 31 March 2019, for anyone not familiar with my abbreviations!). These figures were excellent, and I liked the share, concluding that it was good, and reasonably priced given the strong profit growth.
The update yesterday seems to be in line;
D4T4 entered the current financial year (ending March 2020) in robust shape, and I am pleased to say that the business is continuing to trade well and in line with our expectations ...
H2 weighting - a bit of a fly in the ointment here;
Reflecting the timing of anticipated contract wins, we are expecting some second half bias to the year overall though this is not expected to be as pronounced as that experienced in the year to 31 March 2018...
Taking a look back, this was how FY 03/2018 turned out;
H1: Rev £4.8m Adj PBT -£0.4m
H2: Rev £13.6m Adj PBT £4.5m
As you can see, that was a massive differential between H1 & H2 trading. Actually, I would have expected a considerably greater difference in H1/H2 profits, on that very weak revenue in H1, so I suspect the CFO might have done some smoothing of the numbers to be able to report only a small loss in H1.
Last year, the seasonality actually reversed, with H1 being the stronger half at £3.4m adj PBT, and H2 softer at £2.6m adj PBT.
Therefore, there does not appear to be a seasonal pattern, but a more random result dependent on what contracts they happen to win, and when. This makes it difficult to predict how future results might pan out, and therefore increases risk of an unexpected profit warning.
Healthy pipeline - this is reassuring;
However, with a growing and healthy pipeline of new business opportunities together with a range of opportunities with existing clients, the Board remains confident regarding progress during the rest of FY20 and beyond."...
"We continue to remain positive about the outlook and look forward to providing updates on contract wins and at the time of the interim results in late November."
Brexit/forex risk seems low, even favourable;
A large proportion (greater than 80 per cent.) of our business is dollar-derived and this gives us some protection from current Sterling weakness."
Surely it gives more than "some protection", but should be actively boosting margins, if revenues are in dollars, and costs in sterling?
My opinion - lumpy contract wins seem to be an unavoidable part of the business model with this company. Therefore the risk of missing forecasts because large contracts may not be signed by the year end, is just something shareholders have to live with.
On the upside, the problems in FY 03/2018 of a very weak H1, with management assurances that H2 would be much stronger, turned out to be fine. Therefore I feel that management gained credibility from that episode - i.e. by giving an accurate steer in the past, I'm now more prepared to rely on management assurances now & in the future.
The quality scores look great;
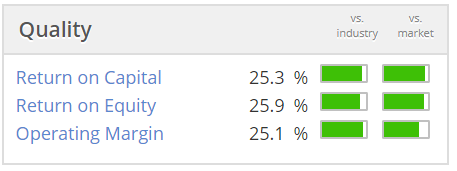
The forward PER of 16 looks reasonable, especially considering that there's plenty of cash on the lovely balance sheet. Shareholders get a modest, but well-covered dividend too. I reckon there's plenty of scope for divis to be increased in future too. Or maybe some bolt on acquisitions using the surplus cash pile? There are lots of small companies in this space that might make a good fit.
Current forecasts are for only modest earnings growth, given last year's large increase. There's a 1-pager update note, available on Research Tree. That shows 14.2p EPS for this year - a PER of 16.2 .
Coincidentally, I went to a briefing last week on digital marketing. It really dawned on me that data is now incredibly important for companies, large and small. Therefore, I feel D4t4 operates in a sector that it makes a lot of sense for investors to have some exposure to. Therefore, whilst accepting there is some risk over the H2 weighting, this share gets a thumbs up from me as a potential long-term buy & hold - I'd categorise this share as QARP (quality at reasonable price).
It's the sort of share that I could see rising maybe 10-25% once we have some clarity on Brexit.
Sopheon (SPE)
Share price: 815p
No. shares: 10.16m
Market cap: £82.8m
Sopheon plc, the international provider of software and services for Enterprise Innovation Management solutions, announces its unaudited half-yearly financial report for the six months ended 30 June 2019 together with a business review and outlook statement for the second half of the year.
Background - Sopheon issued a profit warning, which I covered here on 24 July 2019 here. Delayed contract wins meant that H1 figures were anticipated being down 14% on H1 LY, at $13.7m revenues, and EBITDA roughly halving on H1 LY to $2m. (note the Sopheon reports in US dollars).
The reason for the anticipated poor H1, was down to contract delays. The outlook comments were very positive for the full year.
H1 results - revenue is indeed $13.7m, and EBITDA has come in better than expected at $2.5m.
Outlook comments - the latest commentary remains very upbeat;
The underlying market and commercial momentum is increasing. Expanded sales resources have contributed to a 48 percent growth in sales pipeline value between January and June, expected to drive a strong second half weighted revenue profile.
Both the volume of deals and the number of larger deals in the pipeline have risen to all-time highs.
Revenue visibility - is still down on last year, but this should rise as more contracts are won in H2;
The proportion of SaaS business in the expanded pipeline has risen sharply, potentially accelerating our desired transition to a higher recurring revenue model and greater lifetime customer revenue.
Revenue visibility2 for full-year 2019 is now at $25.4m (2018: $27.2m).
This is the same quandary that many software companies are experiencing now. SaaS, recurring revenues are great longer term, but the transition is painful in that it suppresses short term revenues & profits compared with licence deals (that are all up-front profit, but one-off in nature).
Outlook comments remain very upbeat;
Sopheon's Chairman, Barry Mence said:
"The future prospects of the business have never been brighter, and we do not believe this first half pause in the impressive financial performance of the past several years has a bearing on Sopheon's unique potential and growth opportunity.
The business remains profitable and cash generative, and our balance sheet is stronger than ever.
With unprecedented activity and higher value in our sales funnel, we continue to anticipate rising deal flow and traction through the balance of the year.
We see the shift to SaaS as reflective of a change in procurement behavior, and not a change in commercial momentum, which is rising.
The Board believes that this development will drive shareholder value and remains confident that Sopheon is well positioned to build on its leadership position in the new and exciting space of Strategy Execution management."
Balance sheet - very good, including $18.7m in cash. No issues at all, this looks a soundly-financed business.
Valuation - current forecast for FY 12/2019 is EPS of 42.7 US cents per share, which is a big all on last year's 61.2 cents. Converting the 2019 forecast into sterling (at $1.23 = £1) gives 34.7p EPS, for a PER of 23.5.
Why would we rate a share on a high PER of 23.5, when earnings are forecast to fall by 30% against last year? Clearly the reason is that investors believe that the 2019 forecast is a blip, and that earnings should rise strongly in future.
Forecast for FY 2020 is for strong recovery in EPS to 59.6 US cents. that's 48.5p, for a 2020 PER of 16.8 - much more reasonable.
My opinion - I remain neutral on this share.
I'm impressed with the company's performance in recent years, and on the balance of probabilities, the weak H1 this year does sound like a blip, rather than a more permanent downturn. So I completely understand why a lot of shareholders are happy to give the company the benefit of the doubt - which is what the current share price is saying. It would be a lot lower if investors thought the company had a more serious problem.
The balance sheet is very secure, so there's no solvency risk.
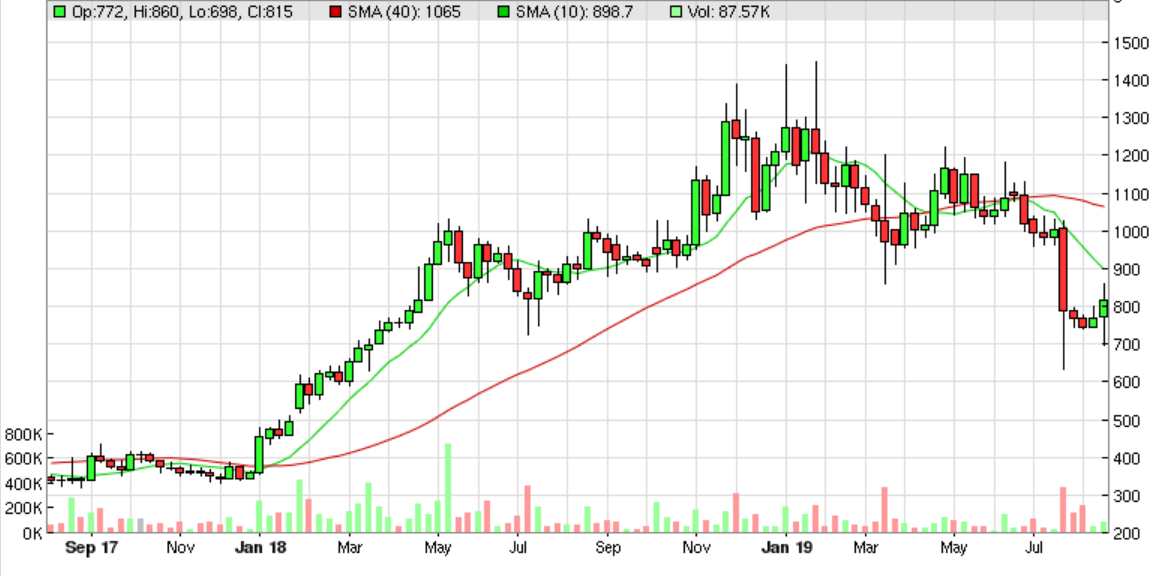
Recovery already looks priced-in, therefore I don't personally want to take a position here. If H2 goes well, and the strong pipeline delivers good contract wins, then the share price would probably be back up into 4 digits (over 1000p). If H2 disappoints, then I think it could be going back down to 400p. A recovery in H2 looks more likely than a further deterioration, therefore the market is probably pricing risk:reward here about right, at 815p per share.
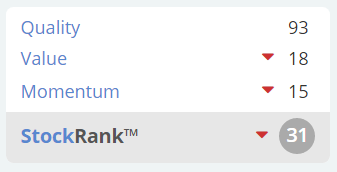
The Stockopedia StockRank system is warning us to be careful;
To finish off, here are some brief comments on the 2 remaining stocks outstanding from last week;
Macfarlane (LON:MACF) -
(I'll do this later on Saturday, or possibly Sunday. Markets are shut anyway, so there's no rush)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
By freak chance, I had a look at Eddie Stobart last week. One thing that stuck out was how the companies cash generation dropped off a cliff in 2018. Operating Cash Flows/Net Operating Cash flows (before CAPEX) were:
2014: 37.1m/30.2m
2015: 32m/16.0m
2016: 29.7m/17.7m
2017: 29.2m/18.9m
2018: 7.5m/-3.3m
This is despite operating profit and EBITDA increasing over the period. Debtor days also took a significant jump with trade receivables going from 149m to 231m having grown steadily and roughly in line with revenue in previous years. Made no sense to me at the time but I didn't investigate any further. Without further research, it looked like a smoking gun.
I have Eddie Stobart, and fingers crossed. I was keeping them as good dividends and balanced risk rating. The share price was recovering too.
SPE …. was on your list for Thursday … what are your thoughts on SPE
“With so many bids occurring, for decent-sized companies, it's difficult to avoid concluding that UK listed shares might be too cheap. Or at least some of them.”
In Dollars or Euros but probably not in pounds!
Hi Paul... SPE was on yesterdays to do list for reporting but NO COMMENT so far any chance we may hear from you on SPE.
Barrie,
My comments on SPE are now in today's article.
I got locked out of Thursday's report due to some unknown technical glitch, and I lost all my updates. So am having to reconstitute them in Friday's report. I was busy doing some charity fundraising on Friday afternoon, hence catching up Saturday morning.
Both Graham & I are part-time, freelance writers, so we have to fit things around doing other stuff.
Regards, Paul.
CCT - Peppa Pig 21% of sales in 2018.
Hi Glaws - what is your source for that please? I've been trying to find out myself.
CCT - it was their presentation at Mello in April
Paul,
Thanks for the Goodwin (LON:GDWN) analysis, whose outlook does seem to be transformational. There appears to be a differentiator with Castings linked to production of larger castings and US orders. This overview from the end of last year, by Richard Bennard.....
....Goodwin took the opportunity to install bigger and more sophisticated plant capable of casting even larger products weighing up to 35 tonnes – a size that relatively few foundries around the world can match. Goodwin completed the lengthy approval process required to supply the US Navy last year, and has secured the first of what the company believes will be many orders supplying its shipbuilding programme. It is also targeting the US civilian and military nuclear industries, which also require huge high-integrity castings for nuclear reprocessing and propulsion systems.
Positive results from Henry Boot (LON:BOOT). A conservatively managed and underappreciated business. The shares are trading at around NAV, It will be debt free by the end of the year and yields in excess of 4%.with dividend cover approaching 3 times. Understandably the spectre of Brexit continues to dampen enthusiasm for UK shares, especially those of a cyclical nature.
It may never shoot the lights out and some may view Henry Boot (LON:BOOT) as boring, but I am happy to remain invested in profitable boring companies with an easily understood business model, especially those where the founding family continue to have an involvement.
Henry Boot (LON:BOOT)
I share your positive vibes here jonno.
Other than construction and brexit this share ticks all the boxes , i think their decent landbank pipeline of projects and conservative accounting (no Burford style booking of profits based on notional increases in value) - should seem them fine unless land prices take a material knock - i just can't see that happening with the lack of housing in this country.
Character (LON:CCT) interesting drop this morning. I can only attribute it to some nervousness around the implications of the takeover of Entertainment One (LON:ETO) since Character (LON:CCT) have own branded Peppa Pig toy products. However, they have had these for 15 years and I'd be surprised if there is an implication for their licences as I would imagine they are locked in long term on an exclusive arrangement. Only 22k volume traded so next to nothing. Would imagine there will be a statement in due course.
Agree very odd, no news and unclear downside. Thin vols but now 11% off
I read on Twitter re Character (LON:CCT) that the Peppa Pig licenses will be up for renewal in two years, and the fear/assumption is that they won't be. Price now down over 20%, 400-416.
So the big question is how reliant is Character (LON:CCT) on the Peppa Pig licence? Does anyone know?
Character (LON:CCT) two years is a long time to be able to pivot so the fall is overdone in my opinion. It is also not a particularly long period to develop a new set of toys given that none of that work would start until after completion of the deal. Large organisations have to plan well in advance, so even if licence wasn't extended I'd expect a run off period.
Anything from Co yet? % exposed would be useful.
Held Character (LON:CCT) until this morning.
Whilst I agree with you that it will take a long time for Hasbro to make their own Pepper Pig, Paw Patrol, etc... toys, they probably will make them eventually.
Long term I agree that Cattles (LON:CTT) will be fine and it is one that I will keep a close eye on, but market sentiment will, IMHO, most likely push the share price further down in the short-term on the expectation of reduced revenues.
So why stay in? Why risk anything when you can sell, wait until the dust has settled and then buy back in when things look rosier?
A
You seem to be saying that Hasbro can't develop and launch new toys in two years, but that Character can even though they start now from behind without a replacement franchise? There aren't a whole lot of Peppa Pig equivalents out there.
I would say Hasbro are much larger with greater resources and are more aggressive.
????? I'm saying nothing of the sort. Character (LON:CCT) already have the products and the licence and will continue to sell them exclusively for at least the next 2 years.
Hasbro first need to complete the deal which will take several months and it is unlikely that they will spend the time from now to deal completion on what would be relatively low level merchandising plans and development.
Once the deal is complete then they will need to decide whether to bring the licence in-house or leave it with Character (LON:CCT) ; they get royalties on it either way. Assuming they decide to bring it in-house it is unlikely that Character (LON:CCT) would then give them the product they develop in-house. Thus Hasbro will need to stick that into their design team, toy manufacturing plans and marketing/distribution. Again for a big company like Hasbro that takes time. All of that whilst integrating Entertainment One (LON:ETO)
My point is that whilst long term I agree that it is likely that the Peppa toy merchandising goes in-house it is relatively small fry to Hasbro and probably nowhere near top of the list of their priorities, especially as Character (LON:CCT) does a good job of distribution and Hasbro will receive royalties anyway. Therefore it is not beyond comprehension that actually the licence gets extended.
Peppa accounts for approx 20% of Character (LON:CCT) sales and the share price has fallen 20%. Thus the market is saying it is nailed on guaranteed that the Peppa licence is lost. Not only that but it is saying that it is lost today and not in 2 years time. Further, it is saying that Character (LON:CCT) cannot replace any of that revenue with something else ever in the future..........really ??? They have a pretty good track record of diversification over the years. Whilst for Hasbro Peppa toy merchandise isn't going to be top priority for Character (LON:CCT) replacement of Peppa is. Therefore management focus will be different.
Lastly I note that Entertainment One (LON:ETO) is trading above the offer price. That also says market potentially expects another bidder, so not guaranteed that Hasbro will even win the race to take over
Hi David - I mostly agree with all your caveats re Character (LON:CCT) and the licence implications.
However for me the starting point is that Pippa Pig is 23% of sales but that the impact on profits would be much larger - prob 30% to 35%. Of course CCT can take cost cutting if their business is smaller but that is possibly a CASH cost. Just a negative to offset the facts you present.
I think also that Peppa Pig gave CCT a gravitas which enabled them to add other global brands around that. If the future scenario is without PP , it does make the whole group profits slightly more volatile, and the medium term profit growth slightly less attractive, both of which means I would attribute a lower rating to whatever level of profits CCT has.
Thus for me a c.20% fall is a reasonable market reaction being a mixture of 30% profit loss in 2 years on a lower rating if the licence is removed, and the much more likely scenario that the excellent mgt team at CCT are able to mitigate the impact.
I am a long term holder but not adding yet
CCT is in my top5 hldgs
Weekend viewing!
Here's the latest piworld investor interview with Lord Lee. Where he discusses his new book: Yummi Yoghurt - A Taste of Stock Market Investing! Aimed to introduce teenagers to investing. Further, he discusses pearls of wisdom from his 60 years of investing. This is the first of two parts.
This of course follows on, from the tremendously popular interview with Ryan, last week. Who is (a very successful) teenage investor. Achieving returns of around 100% pa, since his debut at 11 yrs!
The statement from £D4T4 yesterday was an AGM statement, a lot about the company's good prospects, but no numbers. So I am not sure there is much Paul could usefully have said. I have the impression of a business where sales are "lumpy", so both management and broker forecasts are likely more than usually guesswork. I hold because of a belief that the product is good, combined with the good cashflow, but like you I am a bit nervous.
Yes please, don't forget to comment on D4T4 and Macfarlane!
I was so looking forwards to your comments on D4T4 yesterday. The company's EPS growth for 2019 was 98%, but forecasted EPS growth for 2020 is 2%, and only 3.5% for 2021. So why the big slowdown?
Did they make any acquisitions in 2019 or late FY2018? That would account for a sudden 1-off jump in EPS.
My morning smallcap tweet: Eddie Stobart CEO naughty boy, shares suspended
Eddie Stobart Logistics (LON:ESL), Stilo International (LON:STL), Real Good Food (LON:RGD)
Eddie Stobart (ESL) auditors finger aggresive accounting: writedowns, new rev recognition policy. Rev expectation for H1 broadly in line but full impact on adj EBIT 'unclear', likely to be significantly lower than anticipated. CEO sacked. Shares suspended.
Stilo International (STL) stilletos holders with proposed delisting. They kindly intend to buyback shares and make a tender at 1p, a 31% discount.
Real Good Food (RGD) new loan will repay shareholder loans. No int rate but will but int payments by £0.25m PA.
Hi Paul
Thanks for reviewing Goodwin (LON:GDWN) I hold rather a lot of the shares and know the business reasonably well
Firstly lower Sterling is helpful but emphatically not the reason for the increased activity, that is being driven by a multi-year strategy of upskilling their facilities, back in 2012/3 they realised they were overly depended on O&G and also felt that the bulk casting business would migrate eastwards where labour was cheaper & energy costs lower.
They decided to move to the very top of the market where they believed they could earn good margins & secure workflow over many different sectors that were either less cyclical or in different cycles to O&G , key to this was huge Capex on the latest & most advanced machinery but most important was they extended a summer close down to install a newly designed (to their specification) casting facility that could cast items up to 35 tonnes or more in finished weight. to put that in context Castings can cast items up to 30kg or so.
This Foundry is one of only c.5 globally with that size capability and they added to their advantage by installing a massive industrial x ray facility alongside ( well underneath) that is unique in the U.K. , this allows them to create & document MRI scans of the components they produce which is an essential feature for nuclear validation especially
Accordingly they started the process of pre-qualification for a vast number of Nuclear/Defence & other programs that unlike O&G offered v long visibility of up to 20 yrs + ...this process will start to see results from 2020 onwards
Additionally their core pump/valve business continues unabated so all the above activity is supplemental hence the 94% increase in order bank
Separate to this part of the business is the refractory products business that generates half the profits and is now by far the global market leader in the highly technical area of casting powders ..primarily for jewellery manufacturers worldwide..again non cyclical
Finally unlike Castings there is no client concentration risk at Goodwin...they supply pretty much globally, they also manufacture globally but keep IP in the U.K., they have major facilities in Brazil,Finland,Germany,S Africa,Australia,China,Thailand,India so are v much a global player at the top end of their various markets
As such I’d say they’re a cheap Renishaw rather than an expensive Castings but with far far better growth prospects