Small Cap Value Report (Mon 26 June 2023) - BMS, DWHT, LOOK, CINE, POLR, AML, CBOX, DEMG

Good morning from Paul & Roland, raring to go!
Today's report is now finished.
Gorgeous weather continued over the weekend here in Bournemouth, so it feels like I'm on holiday!
I've got into a good routine each weekend now - Saturday morning is to go through the week's SCVRs, replace any missing tags, update my quick reference spreadsheet summary, then I record the weeks' podcast. Sunday morning is for recording my macro/markets podcast, having done some digging around for relevant data and articles. Sorry part 2 was so lengthy this week, but there was masses of information, and I reviewed the Bank of England MPC summary/minutes, which was useful in better understanding the Bank's rationale for increasing rates aggressively again to 5.0% (due to inflation & labour market running hotter than expected), despite admitting that it didn't yet know what impact the previous 12 interest rate rises would have.
Brief macro thoughts
I'm actually a little less bearish than last week though, as I explain in the podcast. This is because consumer confidence data from GfK has been consistently improving since last autumn, and the interest rate hikes mainly shift money from borrowers to savers. Yet mortgages are something like 85% fixed, so that impact will only occur gradually, and impact a relatively small number of people. Whereas savers are benefiting already from higher interest rates, and there are many more people saving, than borrowing (only about half owner-occupiers have mortgages at all). Plus many people got a 10% pay rise from April, boosting spending, as Next (LON:NXT) pointed out in its upbeat statement last week.
I suspect some sectors might slow down (e.g. business-to-business, capital goods, construction, etc), but others might perform better than the current gloomy mood suggests. I don't know, we'll see. All up for debate, and I always remind myself that no matter how expert anyone is, and how emphatic their language, and certainty in their own opinions, we're all just guessing! That's why it's better to keep an open mind, rather than to become rigidly wedded to some theory about what the future holds.
I've noticed that in the past, lots of sceptical bears miss out on the best part of a recovery, because they're still denying that it is a recovery (seeing it as a bear market bounce). Similarly, people who sit in cash, often miss the recovery, as they're too timid to put the money to work in cheap shares. Although things are much more favourable for cash now that interest rates have risen. So I think cash, and bonds, are actually pretty good places to be right now. But as always, that's for each investor to decide for ourselves.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
Braemar (LON:BMS) - down 19% to 223p (£75m) - TU & Investigation - Paul - AMBER
Confirms previous guidance for FY 2/2023. However, it also confirms a Sky report yesterday that shares will be suspended because it won't be able to meet 30 June deadline for publishing its accounts. This is due to an investigation over historic transactions of $3m. Looks like I was too sanguine with my relaxed view (written before 8am)!
Dewhurst (LON:DWHT) - down 3% to 1,015p (£85m) - HY 3/2023 results - Roland - GREEN
Today’s half-year results seem to have prompted a mild downgrade, but this industrial group needs to be looked at through a long-term lens. I think the current valuation looks reasonable, given solid profitability and a bulletproof balance sheet.
Polar Capital Holdings (LON:POLR) - unch. at 495p (£500m) - FY 3/2023 results - Roland - GREEN
Performance at this specialist fund manager appears to have stabilised during the second half of the year, after a difficult H1. The dividend has been held unchanged and while the timing of a recovery remains uncertain, I think the shares probably offer good value.
Quick Comments
Aston Martin Lagonda Global Holdings (LON:AML)
Up 10% to 360p (£2.6bn) - Deal with Lucid - Paul - AMBER
This luxury carmaker fell into our sub-£1bn briefly, both at the height of the pandemic, and again in the second half of 2022, when it looked very precariously financed & overwhelmed with debt. However, I remember commenting previously that whilst it looked very high risk, and almost a basket case financially (heavy losses every year), the brand value must be immense, and I also mentioned the massive valuation of Ferrari, which has achieved scale and hence become highly profitable.
Aston Martin has not only survived, but the shares have now 4-bagged from the lows, which is great to see. It has deep-pocketed financial backers, including Mercedes.
A deal announced today is with Lucid, a cash-rich, massively loss-making luxury US electric vehicle maker (a copycat Tesla it seems), valued at c. £8bn, despite its shares being down almost 90% from speculative spikes in 2021! The American market is just a different world, isn’t it! Tesla is currently valued at c.£640bn, or $813bn! Tesla has achieved substantial scale, and profitability though, so fair play to Elon.
Key points -
- Lucid will supply Aston Martin (AM) with EV (electric vehicle) powertrain components.
- AM seems to be offering to pay using a mixture of shares and cash.
- Minimum spend by AM £177m of Lucid products.
- Lucid could end up owning 3.7% of AM, with a 1-year lockin.
Paul’s view - clearly AM shares are outside the scope of a value/GARP report, but I’m always happy to look at anything interesting. Low volume, high end car makers like AM have always bought components from larger companies, and this is an innovative twist on that theme, paying partly in shares.
Aston Martin shares look terrible on conventional valuation methods, but that’s missing the point. It’s all about the brand, and scaling-up potential.
Deltex Medical (LON:DEMG)
Shares suspended at 1.2p (£8.5m)
I dropped coverage here of this medical device jam tomorrow share in 2014, because it wasn’t really getting anywhere, and there’s been nothing since to re-engage our interest. Revenues never got off the ground really, and in recent years have been dwindling. Repeated equity raises saw the share price wither away almost to zero.
Today it’s reached the end of the road, shares suspended with the dreaded (and nearly always terminal) “pending clarification of its financial position”.
It’s set to run out cash in just over a fortnight, with loans fully drawn down, and negotiations for fresh funding have failed.
That’s it I’m afraid, the shares are now worth zero. Bad luck to any holders. At least the company tried to make a success of its products, but it’s so difficult (and expensive, and time-consuming) to commercialise innovative healthcare products.
Deepverge (LON:DVRG)
Shares suspended at 0.15p (£1m)
Similar sort of thing, AIM announces that the shares have been suspended at the request of the company, again with the ominous words “pending clarification of the Company’s financial position”. So you might say Deepverge is in Deepmerde.
Deepverge itself put out an update at 07:00 today. It’s been trying to dispose of operations, to raise cash to keep going, but says today none of the offers look likely to conclude on a timely basis. Hence -
The Board's current expectation is that this process will result in the sale, closure or administration of all Group subsidiaries.
The group topco plc has net liabilities of £0.2m, with more expected (eg for audit fees).
There’s nothing shareholders can do now, other than hope for a miracle. If a subsidiary can be sold quickly, then that might generate some value for topco, who knows? But I would say it’s safest to assume the shares are a zero.
So this is another share certificate/contract note to print off and stick on the wall in the downstairs loo, to remind yourself not to buy any junk like this again! (we’ve all done it, you can barely see the tiles in my loo!)
Paul’s Main Sections:
Braemar (LON:BMS)
279p (pre market) £92m - TU & Investigation - Paul - AMBER
(Update at 08:58 - shares down 16% to 233p)
Sky News (which seems to be the place to go for tip-offs of deals and scandals) reported yesterday that BMS “has been told by its auditor that its accounts will not be signed off before a deadline this week”, and is “plunged into crisis” by this, which would see its shares suspended. Although I would say that late accounts are quite commonplace these days, with the effects of the pandemic still being felt by understaffed auditors.
More worryingly, Sky says that auditors BDO are unhappy about unspecified elements of the accounts, and that FRP Advisory (a restructuring/insolvency/investigations) firm had been brought in. That sounds a lot more serious than just a slight delay to signing off the numbers.
Braemar issues a statement this morning -
Update on trading, FY23 results & investigation
Braemar (LSE: BMS), a provider of expert investment, chartering, and risk management advice to the shipping and energy markets, provides an update on its annual results for the 12 months ended 28 February 2023 ("FY23") together with details of an on-going investigation into a historic transaction.
Trading update - this all sounds fine, no changes apparently, and 33% increased divi (yield is a useful 4.3%) -
As announced on 22 March 2023, Braemar is pleased to reconfirm its expectation of reporting record revenue and record profitability for FY23, with revenue for the year of not less than £150m (2022: £101.3m), underlying operating profit of not less than £20m (2022: £10.1m) and net cash of £6.9m at the year end.
It remains the board's intention to recommend a final dividend of 8 pence per share (2022: 7 pence) to shareholders for approval at the forthcoming annual general meeting, representing a dividend for the year of 12 pence per share, a 33% increase over the previous year (2022: 9 pence).
Accounts investigation - this doesn’t look material, at c.$3m, and is historic from 2013-17.
It confirms Sky’s report that FRP Advisory to assist the investigation (that won’t come cheap).
As a result, FY 2/2023 audited accounts will indeed be delayed, and not published by the 30 June 2023 deadline. Note the deadline is 4 months for fully listed companies, whereas AIM is 6 months (rule 19). Braemar is fully listed, so 4 months applies.
Shares suspension - BMS doesn’t expect to meet the 30 June deadline for accounts publication, so its shares will be temporarily suspended.
Paul’s opinion - Braemar is a decent company, and trading well - I reviewed it positively (with a GREEN overall view) here on 22 Mar 2023, but wanted to see the full accounts before being completely happy. One issue I flagged was the apparently huge potential dilution (23%) from share options. Not unlike sector peer Clarkson, where the company seems to be mainly run for the benefit of its management & staff (who are ear-marked to get most of its cash pile, in bonuses!)
The accounting problems seem odd considering they’re historic, and only $3m. Why get in expensive advisers, and suspend the shares, over an issue that is small? I wonder if fraud might be involved? (EDIT: this point is also mentioned by M48 in the comments below. I should emphasise we're only speculating here, not making any accusations).
Shareholders have this week to decide whether to bail out ahead of temporary suspension, or to sit tight (and maybe even buy more, if it plunges). Based on what we’ve been told so far, this issue doesn’t look significant or material, so personally I’d be inclined to ignore it. But as always in this type of situation, we never know what else might come out of the woodwork. Overall though, Braemar looks a good, sound business, so I’d be inclined to give it the benefit of the doubt over a small, historic accounting problem.
Lookers (LON:LOOK)
118.6p (£453m) - Update re takeover - Paul - AMBER
As mentioned in my weekend podcast, I’m uneasy about this 120p cash takeover bid.
The reason being that J O Hambro held 8.0% of the company, and gave a letter of intent to support the 120p takeover. But it’s since been selling in the market, having reduced its position by over a third, to 5.2% of Lookers. I don’t recall having seen that before. Normally instis give an undertaking to support a deal, and then hold until the deal completes. So why is Hambro selling in the market? The only reasons I can think of, is that they consider there’s risk of the deal falling through, or they need the money for redemptions, or to buy something else they think is better.
Furthermore, we’re told today that Artemis (holder of 40.5m Lookers shares, 10.6% of the company) has done the same thing! It’s now reduced down to 8.8%.
As a result Lookers now has only 37.4% of the company that has confirmed an intention to support the deal. Does this mean it could fall through? In that case, I would have expected the share price to have fallen to a say 10%+ discount to the bid price of 120p. But it hasn’t - the share price of 118.6p is so close to the takeover bid of 120p, that it seems the market expects this deal to happen, or even that there’s a chance of a higher bid - after all, someone seems to be hoovering up big blocks of shares in the market I wonder who the buyer was for Hambros and Artemis’s shares? (I've not ploughed through all the disclosures, due to time constraints, so do leave a comment if you have).
So it’s looking quite interesting. Personally, I would follow the instis, and sell in the market, or maybe sell half, and keep the other half in case of a higher competing offer for the company? But wouldn’t the instis be holding too, if they thought a higher offer likely?
Paul’s opinion - the above is all guesswork really, but interesting to ponder. I’ve not seen instis giving support to a deal before, then selling in the market before it’s completed. So something unusual seems to be happening here. We’ve seen several other takeover deals fall through lately, hence I’m leaning towards playing it safe, and selling in the market to lock in the profit, if I held the shares personally.
I’d love to hear from any actual shareholders, and how you see things with this takeover deal?
The whole sector is ripe for consolidation, as we’ve been saying here for ages, so I’ve picked up some Vertu Motors (LON:VTU) and Pendragon (LON:PDG) shares recently.
Cineworld (LON:CINE)
Share suspension imminent & insolvency
I've given it my own title above.
This large, international cinemas chain once again confirms that its restructuring won’t provide for any value to existing shareholders. This is the latest in a long series of announcements confirming that its shares were worth nothing, yet for some bizarre reason unknown to me, the shares continued trading on the London stock market. Does anyone know why? (at the time of writing, they're still trading at 0.5p, with a market cap of £8m! Why would anyone be buying? Probably shorts covering their positions, to avoid a lengthy delay in getting paid once it's suspended).
The latest development today is that it has decided to place the UK plc into administration. It’s only the plc going bust, not the operating subsidiaries, which continue trading as usual. The US operations are already in Chapter 11 bankruptcy protection.
An intermediate holding company Crown UK Holdco Ltd will then own the operating subsidiaries, and will become wholly owned by a newco controlled by the lenders.
This is an important point to grasp for newer investors - that when a company becomes insolvent, the equity becomes worthless, and instead lenders end up seizing control. This is because debt ranks higher than equity in law.
Meanwhile the actual operating business itself has continued trading as usual. It’s just a transfer of ownership, from equity, to debt holders. That happens quite often. This is why it’s usually a mistake to buy shares in quite big companies where the shares look insanely cheap. They’re “cheap” because equity is being squeezed out by debt, and equity is probably already worth nothing, but speculators in the shares either don’t understand this, or are hoping for a miracle.
Anyway, I’m sure no SCVR readers got caught on CINE, because we’ve been telling you for a long time here that the equity was worth nothing.
Shares are going to be suspended shortly, and are worth nothing.
Thank goodness that’s over, we’ve wasted a lot of time covering this share, but I thought it was important to try to protect readers from stumbling into something that was a guaranteed 100% loss.
Cake Box Holdings (LON:CBOX)
Up 8% to 137p (£55m) - Final Results - Paul - AMBER/GREEN
Cake Box Holdings plc, the specialist retailer of fresh cream cakes, today announces its audited full year results for the twelve months ended 31 March 2023.
Adj Pre-tax profit is down 23% to £5.4m
No adjustments this year, so numbers are clean.
Diluted EPS is 10.6p (PER 12.9x), down 33% on LY.
Gross profit was up 8% on LY, but the reason profits are down is because admin exps rose 32% to £11.6m, so I need to better understand why costs rose so much.
Franchise model, so revenues are smaller than if the 205 shops traded within the group.
Decent rate of expansion still, with +20 new sites in the year.
Supermarket kiosks also expanding, now with 18 - has anyone tried them? I found this image online -

Here's a full store -
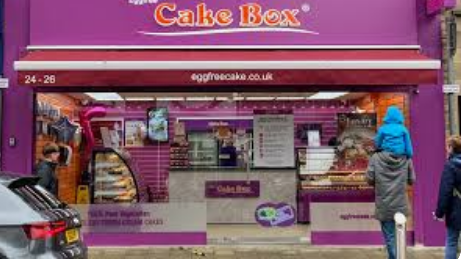
Cake Box's niche is egg-free cakes. But they still have cream on some of them. So I'm not entirely sure exactly the dietary requirements this appeals to. Doing some googling, it says that some Hindus and Sikh vegetarians don't eat eggs, which would rule out conventional cakes I suppose. It looks as if CBOX is targeting that particular niche, which is a nice positive for the investment angle - ie. targeting a specific, under-served niche, is the sort of thing I look for, in preference to competing head-on with everybody else, with generic products. If you know more about this question, then do please enlighten us with a comment below!
I am worried that franchisees might be struggling, as LFL franchise store sales were only up +1% in FY 3/2023 - which means franchisees are bound to be less profitable, since their costs will have risen a lot more than that. Although performance has improved more recently -

Dividends - total is 8.125p (LY: 7.6p), yielding a very impressive 5.9%
Balance sheet - is very solid. NTAV is £17.3m, which includes £8.7m freehold property (3 central sites), and £7.4m cash, less £1.3m mortgage debt, gives net cash of £6.1m.
Cashflow statement - looks fine to me, no concerns.
About a third of the £6m cash generation, £2m, was spent on capex - expanding central baking/warehouse facilities.
Most of the remaining cashflow was paid out in divis, costing £3.1m.
As it’s net cash, the finance income line should grow by a few hundred £k maybe in the new financial year, given interest rate rises, which is helpful.
Note 3 gives a useful breakdown of revenues - so the business model for CBOX is all about supplying the ingredients (at a mark-up). This is not what I imagined, as I thought they would generate revenue from charging franchise fees. It would be interesting to know how the contracts are set up, in terms of what ability CBOX has to force franchisees to buy from them, and what pricing power CBOX has, and how it detects whether franchisees cheat the system to buy cheaper ingredients elsewhere maybe? Do they reconcile what sales are versus ingredient purchases? These would be good questions for a future webinar.

Note 4 shows individual expenses. I’ve queried the high cost of “Travel and entertaining goods”, which has risen again, to £599k - seems a lot. Another good question to ask management. Let’s hope it doesn’t include any jollies!
“Professional costs” of £1.7m is double last year, again that seems a lot. What’s in it?
Paul’s opinion - I still can’t shake off my mistrust of this company after the accounting scandal in 2022, and heavy Director selling just before it. It’s a pity because, apart from that, there’s a lot I like about this share.
As some wholesale food ingredients may be coming down in price now, there could be margin improvements here possibly? Plus of course, it’s a successful franchise/roll-out model, which are usually priced at a premium, whereas CBOX looks quite cheap.
The founder owns 25% still - about the right amount to be motivated, but not overly dominant. The dodgy former FD has gone, and taken his ill-gotten loot with him, so good riddance there.
It’s quite tempting to take a small position here. Providing nothing goes wrong again, then I could see this share being a steady riser in the coming years, as more stores are rolled out. And you get nice divis along the way, since most of the cashflow is available to pay divis.
I’ll go AMBER/GREEN on this.
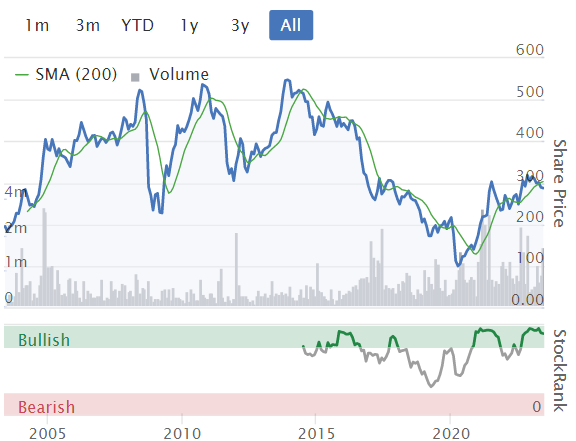
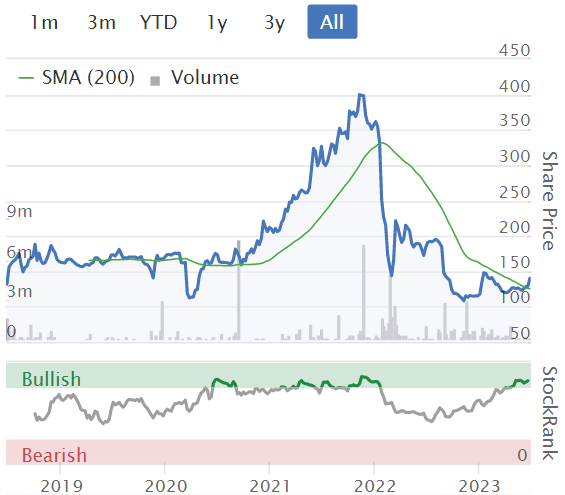
The chart since it listed on AIM in 2018 shows the rollercoaster ride investors have had, and the big impact of accounting troubles (see our archive for lots of details) in 2022. Although I'd say it's looking like the chart may have formed a base now, and the StockRanks have also recovered. Interesting!
Roland’s Section:
Dewhurst (LON:DWHT)
Dewhurst (LON:DWHT) - 1,015p (-4%, 08.30)
Dewhurst (LON:DWHA) - 590p (-5%, 08.30)
Market cap: £85m
Wonderfully simple and straightforward accounts from this family-controlled maker of lift controls, keypads and traffic control equipment.
Dewhurst is not the most liquid stock and suffers from a big spread. But the shares have delivered very steady progress over a long period.
Note that shareholders can choose to buy the non-voting but higher-yielding Dewhurst (LON:DWHA) shares. These are what I’d buy, given that the Dewhurst family controls more than 50% of voting rights. I can’t see any reason to pay more for an (effectively) worthless vote.
The A-class shares have eight-bagged over the last 20 years:

Results summary: today’s interim results cover the six months to 31 March. Refreshingly, there’s no PR puffery or talk of adjusted EBITDA here!
More generally, there’s not that much detail at all – management commentary is quite limited from this business. Investors wanting more detail have no choice but to plough through the annual reports, although there is an updated note available from Singers on Research Tree today, that provides an overview.
Here’s a summary of the main numbers:
H1 revenue rose by 12% to £30.4m
Pre-tax profit up 8% to £4.0m
Earnings per share up 13% to 32.1p
Interim dividend up 5.6% to 4.75p per share
Net cash of £22.6m (H1 22: £19.9m) - that’s a quarter of the market cap!
Trading commentary: I think the main takeaway here is that Dewhurst is suffering the impact of inflation. The group’s operating margin fell by 1% to 13% compared to the same period last year.
Dewhurst has now been able to push through some price increases, but these have lagged higher costs and not all increases have been passed on.
Overall, price increases haven’t (yet) fully compensated for the impact of inflation, although there has been a welcome reduction in stock levels as material availability has improved. Recruitment difficulties are also said to have eased a little.
Management says that sales in the Lift Division saw sales growth “in most regions”, led by Canada and the UK. However, “a lull in major projects in Sydney” is still ongoing.
Keypad sales saw a modest recovery, but these remain “volatile and unpredictable from month to month”.
Overall, Transport sales were “fairly similar” to the previous year, with rail infrastructure spending down, but highways products up.
Outlook: Today’s outlook statement seems quite measured, perhaps even a little downbeat. Management appears to be expecting the second half of this year (April-September) to be more difficult across all of its markets:
In North America:
there are signs that the second half of this financial year may be impacted by a slowing of orders and customer approvals to proceed.
In Australia, order levels are said to be “reasonable”, but:
continuing customer labour constraints are leading to some project delays
In the UK, Dewhurst’s management think:
The UK has remained surprisingly steady given the economic backdrop, but may tail off later in the year as the impact of interest rate rises start to bite on the economy
My reading of today’s outlook is that it’s probably a mild downgrade to forecasts. The market seems to have taken that view, with the A-class shares c.5% down in early trade.
Roland’s view
Dewhurst’s profit margins look quite attractive to me for a company operating in this sector. The long-term average return on capital employed of 12.7% shown on the StockReport would be higher, if the company didn’t carry so much cash on its balance sheet.
My impression is that Dewhurst’s products probably have some degree of competitive advantage.
Cash generation improved during the half year as the group was able to unwind some inventories and reduce outstanding receivables.
Dewhurst’s final salary pension scheme remains a drag on cash, with deficit reduction contributions expected to total £1.4m this year. That’s significant, against a pre-tax profit of c.£8m.
However, the deficit is visibly reducing and the numbers in last year’s annual report suggest to me that this scheme might become self-sufficient over the next few years, given the benefit of rising interest rates. That could improve free cash flow and dividend payment capacity.
Although the outlook for this year suggests some risk of disappointment, Dewhurst’s balance sheet looks extremely strong, with c.25% of the share price covered by net cash of £22m.
On balance, I think the shares look quite reasonably priced for a business with such a strong balance sheet and attractive profitability. I reckon the A-class shares trade on about eight times forecast earnings with a 2.5% dividend yield, after today’s results.
The size of the spread here means that this is a buy-and-hold stock only. But the dividend hasn’t been cut for over 30 years, reflecting a very steady long-term performance:

In my view, the balance of risk and reward looks quite favourable at this level. I’m going to give Dewhurst a thumbs up.
Polar Capital Holdings (LON:POLR)
Share price: 495p (unch)
Market cap: £500m
"Total dividend per share for the year has been maintained at 46.0p."
Graham last covered fund manager Polar Capital in November, after its interim results.
It’s been a turbulent year for Polar, which is heavily exposed to tech stocks. But comparing Graham’s notes with today’s full-year numbers suggests to me that Polar’s performance may have stabilised or even improved slightly during the second half of the year.
With the dividend held unchanged, this unloved stock offers a 9%+ yield today. Is there value on offer here?

Financial summary: today’s full-year numbers do not seem to contain any nasty surprises and show profits broadly flat on H1 numbers:
Assets under Management (AuM) down 13% to £19.2bn (H1 ‘23: £18.8bn)
Average AuM for the year down 14% to £19.6bn
Pre-tax profit down 27% to £45.2m (H1 ‘23: £23.0m)
Adjusted earnings per share of 44.3p (FY22: 56p)
Second interim dividend of 32p per share leaves the full-year payout unchanged at 46p per share
Dividend: is Polar’s 9% dividend yield sustainable? I estimate last year’s payout cost about £47m, compared to net profit for the year of £35.6m.
The payout clearly wasn’t covered by earnings and required some support from the balance sheet. But Polar still had surplus capital of £57.7m at the end of the year, after subtracting regulatory capital and the July dividend payment.
Fund managers’ profits can bounce back quickly with modest inflows and a more supportive market. The yield of 9% reflects some risk here, but also negative market sentiment.
If profits are broadly flat this year, as suggested by consensus forecasts, then I think the dividend still has some breathing room and may survive without a cut.

Trading commentary: Polar’s technology fund saw net outflows of nearly £1.2bn last year.
This chart from a new Equity Development note today highlights the outsized impact of technology on Polar’s fund flows last year. But we can also see inflows in some areas:

This chart from today’s results shows how AuM weightings have changed over the last year. Healthcare, insurance and emerging markets have all gained weight, helping to offset Technology outflows:

Understandably, chief executive Gavin Rochussen is keen to stress that Polar was by no means the worst performer in the fund management sector.
He says that 88% of Polar’s UCITs AuM (closed-ended funds) has been in the first quartile of performance against its Lipper peer group since inception. That seems quite positive to me. Lipper is a fund performance ranking scheme.
Perhaps more usefully, net outflows have eased during the final half of the year.
During the fourth quarter, Polar’s AuM actually rose by £0.8bn (+4%), thanks to £1.2bn of investment gains.
A net outflow of £0.4bn dampened this result slightly, but this was said to be due to profit-taking in the Global Insurance fund, rather than continued weakness in Technology.
Outlook: the company believes the outlook is positive, “with global inflation abating and the peak interest rate cycle within medium term sight”.
Rochussen says he believes Polar’s specialist focus and balance sheet leave the group well positioned for a return to growth.
Roland’s view - I think the company’s outlook statement leaves some wiggle room, but it seems like a reasonable viewpoint to me.
Although I think inflation will remain a feature of the economic landscape, most companies seem to be reporting a degree of moderation and have now factored in necessary price increases.
Polar’s share price is down by nearly 50% from its 2021 peak. If the company’s growth can resume its long-term trend, I think the chart suggests this could be a good cyclical buying point:

Of course, there are no guarantees. Risks remain and a dividend cut may still be needed if market sentiment does not continue to improve.
But on balance, I think Polar Capital looks in good health and affordably valued. In my view, the stock has the potential to offer attractive returns from current levels. For these reasons, I’m going to go green on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Reading Pauls report that Polar Capital Holdings (LON:POLR) has started to shift more of its assets towards Emerging Markets. Is it possible that this could have a positive read across for Ashmore (LON:ASHM)? They took a nasty dip over the past week like many stocks and currently trade at 195p, this is roughly a 30% decline since Graham rated the stock 'green' back in February (277p). I bought into ASHM on Friday so probably clutching at straws to vindicate the purchase!
I am also a suffering Ashmore (LON:ASHM) shareholder, but I am in it for the 1-2 year horizon at a minimum. The solace I take is the tasty dividend on offer, and a solid balance sheet to weather the storm.
Long term, I think high inflation and high interest rates are going to squeeze growth in developed world, and developed stock markets will struggle for gains in the next few years. Meanwhile, some of the drivers of inflation (high commodity costs, increasing labour costs) should benefit emerging markets in general, given that they export quite a bit of commodities, and also will benefit from more labour intensive work shifting to emerging markets. Don't forget that demographically, emerging markets should see good structural GDP growth vs developed markets. This was not the case 2008-2022 due to cheap credit in developed economies, as well as COVID impacting developing markets more.
But now, investors in general have this view that developing markets are always going to lag developed markets in growth. This is where I take a contrarian view. The leveraged bet is investing in an emerging markets fund specialist, because when the tide changes, they will see a huge surge in AUM due to more allocation to emerging markets among investors.
(I hold in the Boon Fund)
Hi Boon,
Thanks for your detailed summary on Ashmore (LON:ASHM) above but also for your detailed write-ups that you put together regarding the Boon fund, always a good read. I had actually only read your summary on Ashmore a few days ago and when my alert went off at 200p I decided to buy in.
Another factor I think will benefit Ashmore in the mid-term timeframe is the current perception around onshoring compared to the reality. A lot of companies have talked up moving business onto home soil which would reduce FDI inflows. Whilst I believe this will happen in the long term, in the short term companies will be looking for any way to save money in the moment, which if anything might actually result in increased EM investment to get companies through the upcoming downturn.
Lets hope the dividend is maintained for this year and next year. If that happens then at the very least we should walk away with 15% upside... if only it was that easy!
Ben
Inspiration Healthcare (LON:IHC) has an AGM statement tomorrow I think
Just scanning for shares which have risen in the past 7 days, and its one of only a handful of smallcaps to have rallied strongly.. After earnings forecasts were slashed in November things were looking better Q4 + Q1 this year so will be interesting to see if positive trading has continued.
Thanks Paul for the write up on Cake Box Holdings (LON:CBOX. (I hold but a small position).
I think that you are spot on with the list of questions for mgt. That said, the underlying business does now look quite firm with past probs hopefully gone with the last FD.
I do like the franchise model and with the StockRank hike and the good divi in mind, I need to do a mystery shop before thinking about increasing my exposure. The last time I visited my nearest store (Tolworth, West London), the display looked great and two families ahead of me were spending freely. Good service from the staff who appeared cheerful which, IMHO, is always a reassuring sign.
Mark
With Cake Box Holdings (LON:CBOX), being egg free, it seems strange they don't have a selection of cakes which are also dairy free. This would cater towards people who are vegan and/or lactose intolerant.
Not sure this is much help Paul/anyone but I sold Lookers (LON:LOOK) last week as it looked a done deal and immediately put some of the proceeds in to Pendragon (LON:PDG) after your prompt about doing that. And I’ve already got a full stake in Vertu Motors (LON:VTU) luckily bought in the 40s. All three buys and an incredibly lucky wild punt in SERAPHIM which tripled on a bid just days after I bought were thanks to your excellent commentary here. ZANE is a beneficiary as I’ve broken my only give to UK charities rule as you’re so keen and it does seem such a worthwhile charity, and worth monthly payments in to it with a bit of the profits.
With bids I nearly always sell quickly unless the share price goes above the bidders price. Markets are often the best guide for us with bids and are so often right when the share goes above the bidder price as it is then followed by other bidders or the original bidder paying more, And when the share price stays well under the bidders price it’s so often proved right and the bid fails.
And Lookers (LON:LOOK) has been just below 120p throughout so far. It’s not worth hanging on for an extra penny or two. Also imo unless the share price suggests a higher bid quite likely it’s not worth holding on in case the bid fails. And there’s just a hint of that now with Lookers.
Thanks for the kind comments Ken. And particularly thank you for supporting ZANE too. I attended online the annual ZANE conference recently, and things are predictably dire out in Zimbabwe. I think about it every day, the hundreds of lovely people I met out there, who are scratching around just trying to survive from one day to the next, in a completely dysfunctional country. They are incredibly grateful to us for helping them with the basics - food, basic medicines, and the other projects (club foot, pop-up schools in townships, womens refuges & rehabilitation for victims of brutality. But obviously it's not the right time to be tapping anyone here for money to ZANE, as the bear market has been so savage for small cap investors. So I'm delighted you're finding some to send to ZANE, thank you :-)
It was nice to hear Paul being a bit more cheerful about the macro world in the podcast. I'm feeling a little bit pessimistic at the moment, but I'm mostly involved in the startup world.
Anecdotally, I'm hearing a lot of issues around raising funds and there being no money out there. I'd be the first to admit that there was a period where raising money was way too easy and ideas without any proof points would be able to raise stupid amounts.
That tap has definitely been turned off. This is going to have quite a bit effect on the ecosystem as there are lots of companies providing services to startups that have gotten used to being able to charge a lot of money.
I went through the dot com bust and it feels like there are some similarities. Money suddenly became very difficult to come by. Many companies failed and many companies reduced their spending significantly.
Just reading in the Times something similar.
"Nine out of ten businesses are halting growth plans because of problems accessing capital, forcing almost a quarter to scale back expansion or make redundancies. In a survey of 500 mid-sized businesses by BDO, the business advisory and accountancy firm, more than half cited inflation and increasing operating costs as the biggest challenges in the next six months. As a result, businesses were considering new sources of financing, notably private equity, as they called on the government to help to improve their access to cash. The survey found that 24 per cent were being forced to make cuts, including reducing employee numbers, with 22 per cent unable to finance expansion plans. Another 20 per cent were struggling to invest in new technology or software. Even if companies manage to avoid job losses, 20 per cent said they were unable to raise salaries and 24 per cent were struggling to invest in benefits or schemes to retain existing staff.The survey highlights this as a big concern, given that 24 per cent of businesses cite staff and skills shortages as one of their biggest challenges over the next six months."
Just wanted to warn people on PROCOOK (LON:PROC) I'm getting offers daily now - desperate to hit targets perhaps?
Just wanted to warn people on PROCOOK (LON:PROC) I'm getting offers daily now - desperate to hit targets perhaps?
Interesting, thanks. With hindsight, this was a warning sign with Joules. In the last 6 months before that went bust, I got daily half-price offers by email, I remember we discussed it here, agreeing that they were trashing their own brand in a desperate plight to offload excess inventories. Even the broker, Liberum I think, said in a note that Joules was being run for cash, not margin. That's why, rather belatedly, I jumped ship and sold my shares, turning bearish here, but only after the big losses had already occurred unfortunately. Still, salvaging something is better than nothing.
Roland reviewed PROCOOK (LON:PROC) last here in April 2023, saying he thought the balance sheet looked risky without a return to profitability.
It's family-controlled I seem to recall, so de-listing might be more of a risk than insolvency perhaps? Or they might buy it back for peanuts from an administrator, minus the leases?
Last TU for FY 3/2023 indicated a breakeven result, not a disaster. It's got 58 stores though, so fixed overheads on those mean it's geared to a further downturn (unlike online, where costs are mostly variable).
Looking at its last balance sheet at 16 Oct 2022, there's not really any support there. If we write off worthless fixed assets (which will mainly be historic shop fit-out costs I imagine), then NTAV is only about £4m.
I could do with some new kitchen knives actually, as I've been struggling with a tiny "kitchen devil" for many years. So I might have to mystery shop Procook! Also of course more wine glasses, where I've broken thousands of them over the years, and always only seem to have 2 mismatching ones left from the many original boxes of six.
(Never take the seat opposite me at a long lunch, because a wild gesticulation or two usually launches a glass of red into orbit, and you'll go home drenched & discoloured, as many of my friends will confirm!)
Regards, Paul.
PROCOOK (LON:PROC)
Once upon a time there was a brilliant shop near me called Kitchens. It stocked for the basic amateur and high end professional equally.
Then along came Procook and took over Kitchens and all its branches and drastically cut the stock that appealed to the amateur leaving only the 'pro' end of things. No more Mary Berry cookbooks!
Result - closed
They have just opened a new headquarters by me, and it is says
"The new site will bring all of ProCook's stock back under one roof, improving product availability and operational efficiency and further supporting the customer experience both in store and online."
So they must be doing something right, not sure about giving food away!!
ProCook new Headquarters
*** Paper is under the Daily Mail, so expect a bit of sea sickeness as the pages refresh all over the place.
On Braemar (LON:BMS) its interesting to note that results were originally due by the end of May and then put back (by RNS) to end of June. CFO replacement annnouncement on 20 June with new CFO coming in on 1 August. Pretty obvious that the board have lost confidence in the leaving CFO, who hasn't been able to get his accounts out on time. Whether the new CFO will want to take responsibility for last year's accounts in August is questionable. I suspect BDO risk management requested management to request a third party review of the historic transactions as part of their final audit processes. Auditors don't really care about hitting deadlines if there is something not fully resolved. It all reflects badly on the CFO for not managing and resolving the issue on a timely basis, hence he is walking the plank....2 years of missed deadlines!
May I just comment on the post by Colin1862 on Friday about Mortgagees.
The Mortgagee is the lender not the borrower. The Mortgageor is the borrower. The Press often get this wrong. The best way to remember which is which is Mortgagee rymes with Society as in Building Society and Mortgagor rhymes with borrower.
Thank you for pointing that out - the spelling actually crossed my mind as I wrote it but I thought if it's good enough for the Daily Mail it's good enough for me. I've spent the last 5 mins trying to get Mortgageor to rhyme with borrower but failed. Maybe Eyeore would be more appropriate? I did, however, succeed in rhyming Mortgagee with Society - could be the basis for an advertising jingle?
I still hold a small position in Braemar (LON:BMS) . Rather frustrating today. Last year's accounts were published late as well at the end of August with historical restatements. Difficult to tell whether this is all cleaning-up the mess of the past or new management aren't really that great either. It does sound like the historical payments might be somewhat irregular, but time will tell. US$3m might not sound like a lot but it was 10x the audtors materiality limit last year and so I suspect, even with a higher limit this year, BDO will want it satisfactorily resolved. I am not selling as the shipbroking business is worth > £100m on its own so value will be realised at some point. Unfortunately, its not been a good investment up to now really, and I have held from ACM Shipping days. There are some good institutional holders on board who haven't done that well either. Clarkson is better, so I should have picked that one!
Quick review of some charts
Froth starting to come off the S&P a little, fear and greed index was over 80 last week. Im bullish S&P so long as it stays above moving averages, lots of support below so even a 5% pullback would be above 50d ma.
MACD triggered a short term sell signal. No idea where it goes but bias is probably down/sideways next few weeks.
FTSE 250. A picture is worth a thousand words. October uptrend didnt hold. Rolling over and MACD is on a sell signal. Starting to look a little oversold short term tho.
AIM All share. October lows breached, moving averages turning lower.
China 50. Looking weak again. I suspect they'll have to turn on the printing press again soon?
Dollar trying to find a base. Maybe short term headwind to equities. Longer term Id have a bearish bias tho unless it breaks 105
To be polite, its a stockpickers market for now.
I’m not sure I see the issue at Braemar (LON:BMS) as an accounting problem. Given a relatively small amount (relative to the size of the company) has caused quite drastic action, it does read as if it could be fraud (or some other dodgy related party transaction). Often these are later found to be with directors/management but then you’d think there might have been a comment about someone being suspended or something. What if it’s a key group of employees/traders? Often in companies like this, a relatively small number of people drive a lot of the profit - what if it’s such a group and they leave ultimately. It’s impossible to know what’s really going on, but ignore it at your peril.
edit: I’m neither long nor short.
Re Braemar (LON:BMS) - could this possibly be a bribe that has been uncovered which might expose the company to punitive damages that exceed the value stated? The FCPA can also apply to non-US listed companies - see here
https://www.pwc.co.uk/assets/p...
Good points, thanks M48 and mammyoko.
With BMS shares down 21% at 09:02, it looks like some investors (209k shares printed so far) have taken fright, possibly for the worries you both mention (and I wondered in the main report if fraud might be involved).
This will certainly be an interesting one to watch.
I've found before when shares are suspended for this kind of thing, the suspension often lasts much longer than expected. It's almost as if mgt breath a sigh of relief once the clock stops ticking. Then it's anybody's guess if they gap up, or gap down, when trading in the shares resume.
Regards, Paul.
P.S. Must admit I'm tempted to buy a small amount, just for a fun punt. It's fundamentally a good, profitable company, trading well, and cheap. But as you both say, there could be (currently unknown) consequences from the accounting issue being investigated. So we're in the dark really. The company should have given more details.
If your interested in some exposure to O&G then take a look at Trinity Exploration and Production (LON:TRIN)
Currently market cap of just £32m, EV of £24m and Cenkos are predicting $5.6m profit for this year. Broker target is 178% above current price.
Trading update today says spudding for Jacobin well pay zones which have exceeded pre-drill estimates.
Been in a downtrend for a long time but recently moved above the 50 ma and possible a cup and handle pattern has formed.
Not the usual SCVR company to report on, but I would be interested if Paul or Graham had a look at it. I have a small holding in this.
Polar Capital Holdings (LON:POLR) - just a reminder that following results this morning, we host the Polar Capital management team this Wednesday at 10.30am for an investor presentation with Q&A - sign up to register here if you'd like to join: https://www.equitydevelopment....
Hi Paul. Will you be looking at Braemar (LON:BMS) I hold? Excellent results but a mysterious historical investigation that will not affect results but will require shares to be suspended from July 3rd.
Normally I’d expect the SP to jump on such good results and growth but the investigation might spook investors. I’d be interested in your thoughts.
Morning Revs8,
We crossed in the post! I was writing up my thoughts on Braemar (LON:BMS) when you posted, now published.
It wasn't actually results today though. They just reiterated the previous guidance provided in March.
Plus telling us that the shares are about to be suspended, since an accounting investigation over $3m transactions 2013-17 is not going to complete in time.
Regards, Paul.
Thanks Paul. I take the view that there is something unpleasant in the history else why take such measures. I no longer hold.
Morning all. Wanted to highlight the staff expenses for Polar Capital Holdings (LON:POLR) which actually fell. This model is quite different to other asset managers which have high fixed costs, so will be suffering. The non staff was only slightly higher, so management have a real control on costs.
Polar Capital Holdings (LON:POLR) - Tough FY23, outlook improving for flows & returns (new research report here: https://www.equitydevelopment....)
In FY23 (to 31 Mar 23), market conditions created strong headwinds for asset managers, especially those with a growth equities bias like Polar. AUM declined 13% from £22.1bn to £19.2bn, with net outflows of - £1.6bn (FY22: + £0.4bn), investment performance of - £0.9bn (FY22: +£0.9bn); and fund closures of - £0.5bn. However, the story of the year was certainly not entirely negative, but mixed, with an improving picture towards year-end and also post-year-end (although we caution that economic and market conditions remain uncertain).
The strength of FY22, buoyed by the bull market of calender-2021, makes FY23 results look comparatively weak. Gross income fell 18% from £226m to £186m. However, performance-tilted variable pay structures resulted in operating costs reducing by 16% from £141m to £119m, which limited margin impact. So, while core operating profit* fell 31% y-o-y from £69m to £45m, core margin fell from 37% to 31%. Statutory PBT fell from £62m to £48m, and PBT margin fell from 28% to 24%.
Polar maintains a strong balance sheet, with cash of £107m (down from £121m), and no debt. This strength has given the board confidence to maintain a full-year dividend of 46p, a yield of 9.3%.
We forecast AUM growth in FY24 based on an improving outlook, although revenues are expected to fall in FY24 (lower ave. AUM), before recovering in FY25. Our fundamental value is 625p per share, 26% above the share price, and we see potential for a company and sector re-rating.
Regarding interest rate rise and mortgages, if you have a mortgage that is due for renewal in the next 6 months, look for a new deal now. Do not wait until it expires. You can lock in a new mortgage up to 6 months in advance and if a better mortgage comes along you can simply change it before your old mortgage expires. Look for a mortgage that does not have any expenses charged. This is what I did and as better mortgage deals became available to me I changed my deal. In fact, I changed my deal 3 times and have ended on a 5 year fixed deal of 4% which gave a £250 cashback with Lloyds. I had 14 years left on the mortgage and as I was able to pay more I set my new term to just 10 years. I can also pay an extra 10% per year which I will try to do for the next 5 years. Providing I do pay that extra 10%, then I should be nearly mortgage free by the end of the 5 years. Another thing you can do, is delay paying the extra 10% until just before the end of the first year and open up a savings account to pay that extra into, then pay off the 10% before the first year ends. First direct offer a monthly saver at 7% which you can pay up to £300 per month. As you can see, this is higher interest than is charged for current mortgages.
The important thing though is to sort out a new mortgage and it does not need to start until the current one ends. I hope this is helpful to someone.
Hi gmtrader. Your comment about First Direct's monthly saver account struck a bell about an article I read in The Times a few months back. As it's behind a pay wall, I reproduce the salient bits here - "Regular savings accounts are offering some of the market’s best rates: First Direct’s pays 7 per cent interest and NatWest’s 6 per cent. They’re not as generous as you think, however. You only get the full advertised rate of 7 or 6 per cent on your first month’s savings. If you saved the maximum £3,600 over a year into First Direct’s regular saver you would earn £136.50 interest — an overall rate of 3.79 per cent. With NatWest you would earn £59.83 if you paid in the maximum £1,800 over 12 months — a rate of 3.32 per cent."
I didn't realise this was the case until I read the article. Hope you find this info useful.
Here's the link to the original article - https://www.thetimes.co.uk/art...
It's true, but that is because you are saving monthly. It makes sense they would not pay interest on the money before it is saved.
If you have the full £3600 to save then you would be better off putting it in a Raisin account that offers 5.75% or an ISA which I believe offers 5% with Lloyds. In the case of saving to pay extra of a mortgage, if you have £3600 already you'd probably be better off taking out a smaller mortgage to start with and then you still have the option to pay 10% extra. Most people who want to pay that 10% extra will probably not have £3600 savings and will want to make monthly payments, which in that case the monthly saver could be the better option. Also, you can save and not pay tax on the first £1000 in interest, so in that case a normal savings account can some times be better than a cash ISA.
Also, I mainly use the monthly saver as a way to pay my tax as I am self employed. I pay tax twice a year, January and July. I open up two monthly savers. One in January and one in July, so they both mature just before I need to pay my tax.
One last point, to open up a monthly saver you do need to have a basic account with the bank. The great thing is, a lot of banks are offering money to open up an account with them, or at least they were doing a couple of months ago. What I did was open up a second bank acc with my regular bank and used that dummy account to do a bank switch. I was given £175 for opening up an account with Halifax. First direct kindly gave me £200 and NatWest also gave me £200.
For enthusiasts in Oakley Capital Investments (LON:OCI) , and I am a substantial holder, the levels of director buying are pretty high, including today. I do like to see directors spending £1m of their own money....
£VOLEX stockrank has gone from 76 to 96
Interesting, thanks CamRaid. I wonder if the broker forecasts for Volex (LON:VLX) (I hold) might also increase? There doesn't seem to be any extra earnings in for the latest acquisition. Although the placing resulted in c.13% dilution, this was only for part of the acquisition cost, and it was valued on a low multiple of earnings, so should be earnings enhacing. Hence I'm expecting to see forecasts for VLX increase soon too.
FWIW, Volex was my mystery share in this weekend's podcast - i.e. the most interesting-looking share that I spotted during the week. I only call them "mystery shares" so that Stockopedia subscribers get some added value (hopefully!) compared with free listeners to the podcasts.
Regards, Paul.
In the offer document Volex said this: "Expected to be mid-teens earnings enhancing in the first full year of ownership with ROIC exceeding Group cost of capital in year one"
So first full year is to April 2025. Current forecasts are for 33.6p of earnings.
So 38.6p?
At 280p, a p/e of about 7.2x
Seems ok to me.
Volex reports in dollars Chris, have you converted into sterling?
EDIT: FYI, any subscriber can edit your own reader comments within the first hour of posting it. I've just done that with this post, using this button -
It's good etiquette to make it clear what things you've edited/corrected I think.
Woops!
So call it 31p.
P/E of 9x
Still good.
It’s a shame you’ve discontinued deployment of the ethereal jingle to signal the pending Mystery Share announcement.
It eerily had something of the Twilight Zone about it, for those of us old enough to have watched endless repeats of the show (late BBC2 and later C4) well into the 80s.
Volex (LON:VLX) I think that the leap in the Stockrank may be because the figure for the number of shares has not yet been updated to include the new shares recently issued. The figure shown for this near the bottom of the Stockreport is about 159m, which is same number that it was showing weeks ago.
That's a great point, thanks WarrantStar.
This reminds me that we had some complaints a while ago, about the data provider being slow to update no.shares issued. But their response was that they will only update when the shares are actually issued, which can be a little while after the deal has been announced, which is fair enough.
Although as you point out, in the intervening period, shares to be issued but not yet issued could distort the numbers on the StockReport. I've never thought of that before, so very useful to flag it, thank you :-)
Regards, Paul.
Good morning Paul and Graham. Paul, you gave Braemar a green on March 22nd (we hold), I wonder if you'd have time to bring your experience to bear on this morning's curate's egg statement from them? They reiterate all the good forecasts you'd noted but are going to suspend the shares from the 3rd July. This is due to a so far, unresolved to the board's satisfaction, transaction and payments running from 2013 to 2017. They will miss the 30th June deadline for publishing their accounts so are suspending until resolved.
As a dividend-seeker my returns are being short-changed by corporation tax and firms buying their own shares back so I think you are right Paul in saying that for the time being it is better to be in cash.
Morning Silver Moon,
you are right Paul in saying that for the time being it is better to be in cash.
That wasn't actually what I said!
Just to clarify, I think there's a good case for holding cash, and fixed interest investments, since they are generating a decent income now, compared with the 15 years of zero interest rates. But I'm not saying that is necessarily better than being invested in shares. That's up to each investor to decide for yourselves. I can see merit in both, or maybe a mix of both? Personally I like to be fully invested in small caps.
Best wishes, Paul.
Sorry about that Paul, I do tend to read through and jump to conclusions....
Not sure. If you count real returns the story is different.
1% interest when inflation is 0.5% = +0.5%
7% interest when inflation is 8.5% = -1.5%
But what the right thing to do is is not clear to me.
Personally shifted to larger 500m+ cos that pay reasonable divis that have lots of cash or assets last year. With hindsight would have done better just buying really big cos