Small Cap Value Report (Mon 26 Nov 2018) - FLYB, SND, CER, KNOS, IGP, CBOX

Good morning, it's Paul here!
Today's report will be earlier, and briefer than usual, as I have to head over to Chiswick, to attend and speak at Mello London - David Stredder's team's latest investor event. I'm looking forward to catching up with many Stockopedia subscribers at the event.
Flybe (LON:FLYB)
Share price: 16.6p (pre market open)
No. shares: 216.7m
Market cap: £36.0m
(at the time of writing, I hold a long position in this share)
Takeover bid(s)?
There's lots of excitement surrounding this regional airline. It put itself up for sale recently, after concerns about it future viability emerged. On Friday we had 2 RNSs, one from FLYB confirming that it is having talks with several parties over a possible bid, or increased co-operation (e.g. code-sharing). Virgin Atlantic also issued an RNS confirming its possible interest.
An article over the weekend in the Telegraph suggests that British Airways is in pole position to buy Flybe, raising the spectre of a potential bidding war. That could be lucrative for shareholders, so I'm rather excited about this one.
It's quite high risk though, as if the bid interest comes to nothing, who knows where things will end up?
EDIT: The very low market cap means that buying Flybe would be pocket change for the bigger airlines. It could bring cost synergies, and act as a feeder for the more profitable transatlantic flights operating from Heathrow and Gatwick. I think there's also an opportunity to be denied to a competitor, which given the bad blood going back to the 1980s between BA and Virgin, could be an interesting factor.
The volume traded on Friday and today is huge, so we should see some "Holding in company" RNSs this week. End of edit.
Sanderson (LON:SND)
Share price: 85p (pre market open)
No. shares: 60.0m
Market cap: £51.0m
Sanderson Group plc ('Sanderson' or 'the Group'), the specialist provider of digital technology solutions, innovative software and managed services for the retail, wholesale, supply chain logistics, food and drink processing and manufacturing market sectors, announces Preliminary Results for the year ended 30 September 2018.
These results look good, with the summary saying;
The Group trading results for the year ended 30 September 2018 are significantly ahead of the prior year and also ahead of market expectations.
Revenue has increased by 49% to £32.05 million (2017: £21.56 million) and operating profit* by 33% to £5.18 million (2017: £3.90 million)
Note that most of the revenue growth has come from acquisitions.
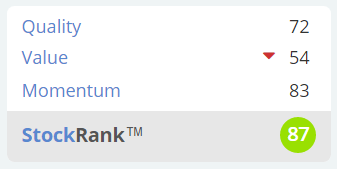
Adjusted EPS of 7.9p means that the PER is only 10.8
This is a significant beat against broker consensus of 6.4p adj EPS, so the share price is likely to rise strongly today. It could be a good one to buy on the opening bell, although the market makers have already marked it up, and the spread looks wide.
Outlook - also sounds good;
The Group has a clear growth strategy. Organic growth is planned from the fast expanding Digital Retail division and renewed growth impetus from the enlarged Enterprise division. There is an ongoing plan to accelerate the Group's growth with selective acquisitions.
Sanderson has a good reputation having built-up a strong track record of delivering customer-centric solutions. Whilst the Board is mindful of potential ongoing uncertainty surrounding economic conditions post the Brexit outcome, the Board believes that Sanderson is well positioned in its target markets and has good sales prospects, backed by a healthy order book.
This provides a good level of confidence that, at this relatively early stage of the new financial year, the Group will make further progress and once again deliver trading results which are, at least, in line with market expectations for the year ending 30 September 2019.
Bear in mind that current market expectations are for only 6.9 adj EPS in 09/2019, so clearly that bar is currently set very low. Expect brokers to increase their forecasts, I imagine to at least 8.0p EPS for the new financial year.
EDIT - I've just seen new forecasts (available on Research Tree) suggesting 8.1p adjusted EPS for the new year 09/2019, which is similar to what I guessed at above. End of edit.
Balance sheet - this is overall, weaker than I would like. NTAV is negative, at -£8.9m, this doesn't seem to be a problem - because the group receives cash up-front from customers - the debit entry is within cash, and the credit entry is in deferred income.
I'd like to know what the average cash/debt position is throughout the year, as the year end snapshot can often be unusually positive at many companies.
The pension deficit has come down from £6.2m to £3.8m, which is a trend we're seeing with many pension deficits, as bond yields rise.
My opinion - this looks an excellent share. Sanderson has a very good track record of profit growth. The figures today are way ahead of broker forecasts by the looks of it, and the outlook comments sound positive too.
Unless I've missed something, this share looks outstanding value, and I'm tempted to buy some. I'd see this being 100p+ very soon. It's a good example of a share which has drifted down generally with the market in recent months, of no good reason. Hence this looks a clear buying opportunity, in my view. As always, that's just my opinion, it's up to individual readers to do your own research, and not rely on my view.
EDIT - the house broker points out in a note this morning (available on Research Tree) that EPS benefited from a lower than expected tax charge.
Cerillion (LON:CER)
Share price: 145p (pre market open)
No. shares: 29.5m
Market cap: £42.8m
Cerillion plc, the billing, charging and customer relationship management software solutions provider, presents its annual results for the 12 months ended 30 September 2018.
Another software company, which reports figures today that look to be ahead of forecast.
Adjusted EPS is 10.9p, up from 10.2p in the prior year.
Note that the Thomson Reuters data on normalised EPS often does not tally with the figures published by many companies. I have queried this, and apparently it's because TR adjust figures to make them consistent with other companies. So I find it's always best to check the source RNS, and to see what adjustments the company is making, and checking that for reasonableness.
Outlook - I like the sound of this;
Prospects for continuing growth remain positive. We have a strong new customer pipeline, including two potential large near-term orders, where we anticipate a decision being made over the coming months, and our pilot work for another new enterprise customer is also very encouraging.
This could be laying the groundwork for an out-perform update, if the 2 large potential orders are signed.
Balance sheet - pretty solid. Receivables look a tad high.
My opinion - I bought some of these shares some time ago, after Graham commented favourably on the company, and of course DMOR! However, it didn't survive my portfolio cull over the summer, for several reasons. Firstly, the profit growth seems lacklustre (hence justifying the low PER). Secondly, the market for this share is so illiquid, that you can't get in or out in decent size. So what's the point in holding a tiny position, which won't move the dial even if the company performs well?
With so much uncertainty around, I think it makes sense to focus on more liquid shares, so that there's an exit route available if needed. It's a double-edged sword though, as often panic selling is the worst thing to do. So being locked in, can be a blessing in disguise, if you're good at picking long-term winners.
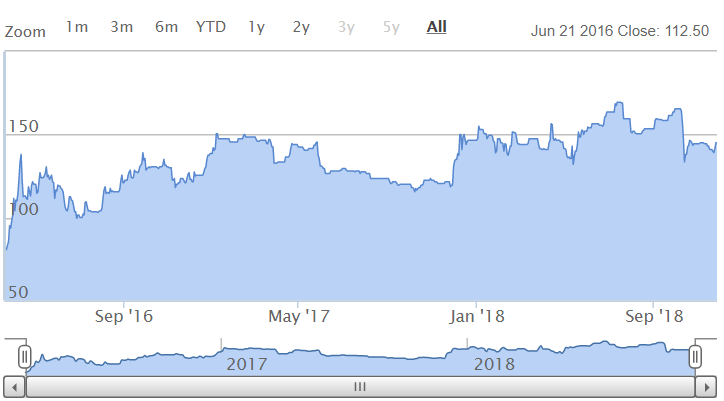
The lacklustre chart (during a roaring bull market) is unimpressive. There's an opportunity cost to holding shares that quietly go nowhere. Although bear in mind that the divis are quite good, at about 3.4% yield.
Kainos (LON:KNOS) - excellent interims are out today. The company (which is an IT contractor, especially to public sector bodies) says performance is in line with upgraded market expectations.
I lost interest in writing any more about it when I saw that the forward PER is about 28. I'm not interested in paying that sort of multiple for this type of business. Although performance is impressive, and public sector work can be very lucrative.
Intercede (LON:IGP) (I hold a long position in this share) - interim results show a great improvement against last year, due to 14% revenue growth, combined with greatly reduced overheads. This is as anticipated - see the archive here for my previous comments on the turnaround story under new management, which is what attracted me to pick up a position here earlier this year.
Note that the UK's generous tax credit system for R&D actually moved the company into profit at the after tax level. The cash position looks fine - no need for more equity fundraisings, if this level of performance is maintained.
Encouraging outlook comments, in particular sales opportunities to US Federal organisations.
See my previous reports for more information on the convertible loan notes. I don't see this as a problem for now. Although opinions differ on this.
Overall, this share is looking potentially interesting. It's so illiquid that you can't buy in any decent size. I find it astonishing that a c.£16m market cap company is providing important cybersecurity products to Governments, and some of the biggest companies in the world. I imagine it might attract takeover bidding interest at some point.
It's riskier than usual for me, but if things go well, then this could be a multi-bagger. It's been a serial disappointer in the past though. New management seem more focused and commercial, which is encouraging.
Cake Box Holdings (LON:CBOX) - impressive maiden results today from this cake maker. I don't know anything about the business, which recently floated. So I'm just flagging that the good results out today look worthy of further investigation by readers (and me, when I have more time).
The business model seems to operate through franchisees. The products look excellent, but are expensive! Gross margins on these products must be very high - hence providing enough profit for both the company, and its franchisees.
It's a pity I don't have more time today, as this share does look quite interesting.
All a bit of a rush, but I have to leave it there for today.
I'll be running through this report live, at Mello London, around lunchtime today.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
.. oops
As it's out-of-hours, I hope you don't mind me posting a general-ism which appears to have been popping up quite a lot recently, unless I'm just noticing it more. Let me (try to) explain ... (disclaimer: I read other share BBs as well as the SCVR ! - sorry)
Post the Patisserie Holdings (LON:CAKE) fiasco (or whatever it is now), I noted the bears saying they were right etc. The more reasoned were providing details why (wished they'd done so beforehand !), and one of those was the turnover per shop per hour. I can't recall the exact figures, but using approx. figures from their last finals:
Revenue (£114m) / 200 shops = £570k per shop
Hours open = 50 weeks x 6 days x 10 hours = 3000 hours per annum
£190 revenue per hour per shop.
Average spend £9.50(? - mainly to make following calc. easy ! lol) ... If so, then one customer every 3 minutes in every shop at all open times.
Is that feasible from just selling cakes/drinks? I don't know, but makes you think. Comparisons were made with other similar companies (Costa, starbucks etc. I think) to show how high the Patisserie Holdings (LON:CAKE) figures were.
I've seen similar from Aston Martin Lagonda Global Holdings (LON:AML) being:
£3b market cap. / 6,000 car sales p.a. = £500k per car
By way of a comparison, Tesla figures are:
$60b market cap. / 250,000 cars p.a. = $240k per car
I've even seen one about Paul's favourite, Sosandar (LON:SOS) :
£48m market cap. / 84,500 customers on database = £568 per customer
I know we all DYOR, but I wonder how far investors go with micro-analysing each figure and/or ratio, and THEN compare all these against competitors. I 'play' about with various figures, and suppose, in hindsight, if I'd noticed the Patisserie Holdings (LON:CAKE) scenario above, may have paused, or at least discussed it before investing.
On my main holdings, I have various scenarios for HY and YE results etc. Although pleasing IF my figures are close to the actuals, I learn more when they're not, as I have to then see where I've gone wrong ! lol
Apologies for the ramble, and hope those attending Mello are enjoying themselves :o)
Interesting but the so called bears were not shorting Patisserie Holdings (LON:CAKE) prior to the discovery of the ‘accounting irregularities’! Hindsight is clearly a wonderful thing - the bears are just trying to justify the problems in retrospect. Had they had any prior knowledge and were confident in their analysis they would surely have ‘put their money where there mouth is’! I suspect they were as clueless as the rest of shareholders who are still waiting for a sensible explanation.
Interesting point - it's always good to do a sense check. But I make the Patisserie Valerie opening hours rather higher. The ones I looked up (Reading, Hammersmith, York McArthurGlen) are open 7 days a week and average 77.5 hours open per week. So I get to around 4,000 trading hours per annum and £142.50 per hour spend. Still seems high but not impossibly so to me.
Interesting to see Paul's brief overview of Cake Box Holdings (LON:CBOX).
IT looks like a promising model, but I didn't quite get why the vegetarian society has endorsed it, just because of the eggless element. It still provides product with milk and cream ingredients.
I am not a vegetarian, or a vegan, so I don't know all the subtle nuances of difference as to why chickens get saved, but baby cows etc do not?
Grateful if anyone can point to me the logic of this.
I am long of being a carnivore.
Congratulations on being long FlyBe, Paul. I remember you said the other week that it didn't deserve to be trading so low given its finances and you were correct!
I would also just like to flag up Palace Capital (LON:PCA) half-year results today. I hold this and topped up again this morning as I think it looks good value for a number of reasons:
- NAV per share is now up to 421p a share even though the share price is currently sat at around 300p. A near 30% discount to the NAV per share looks bonkers to me.
- Palace Capital (LON:PCA) management are conservative and rarely buy properties unless they are confident they will be able to deliver good returns on it. Their track record is excellent - look at the long-term share price growth and past RNS'. For me, management is a key reason for investing
- The share has probably been affected by concerns on the high street and property prices post-Brexit. However, if you look at their portfolio they are not very exposed to high street retailers. Its mainly offices and industrial units.
- Its portfolio is outside of London which over the last year seems to have better weathered property prices. More info here: https://www.palacecapitalplc.com/wp-content/uploads/Palace-Capital-Investor-Presentation-June-2018-FINAL.pdf
- Loan to value is 30%, relatively low for a property company.
- Dividend is 19p or 6.3% at current share price.
- Directors focused on growth.
On the negative side:
- Obviously it can't fully escape wider factors affecting commercial property prices and the economy. But a 30% discount more than factors that in I think and you can milk the 6.3% dividend while you wait for the SP to go up.
- The 6.3% dividend is not fully covered at the moment. The company say this is because they've been too conservative with purchases during the current year but that 'we have every intention of maintaining the dividend.'
- It won't set your portfolio alight like Sosandar (LON:SOS).
- It has always traded at a discount to NAV per share for as long as I have held. However, this has usually been c.10% not approaching 30%.
- Thinly traded although there hasn't usually been a big spread in price.
Do shout if I have missed any other reason why this is trading at such a large discount.
I agree. One I've held for a long while. Sensibly run but un-loved at the moment. A 6%+ dividend is strong enough to keep me happy whilst I wait for it to re-rate. There is development upside to NAV as well as increasing rental income potential so dividend should be covered again in short order.
Would be good to see Sanderson (LON:SND) back to a 100p as Paul suggests though given that it was that level at start of July when I bought today’s price rise is just reducing my losses! Having said that results do look good and Paul’s enthusiasm gives considerable hope for further improvements in share performance.
Hi Paul, any thoughts on the FinnCap IPO just announced via PrimaryBid? Does your rule that if an IPO filters down to plebs like us it's not worth considering apply to this one?
Worth reading this article in the Evening Standard.
"Broking is broken" by MIFID 2 regulations. There's a lot of consolidation underway. The danger is that people pay up based on past performance, not the future.
https://www.standard.co.uk/business/liberum-in-100-million-sale-talks-as-rules-leave-broking-broken-a4000176.html
Thank you John for the article. Mot bejng a city person reading these bits are invaluable especially as I hold Cenkos Securities (LON:CNKS) and Jarvis Securities (LON:JIM)
Steve
There's a follow up article in today's Evening Standard for you Steve,
Simon English: Despite the brokers’ wails, the sell-off of the Old City may be no bad thing
https://www.standard.co.uk/business/simon-english-despite-the-brokers-wails-the-selloff-of-the-old-city-may-be-no-bad-thing-a4001386.html
I quite like Cake Box - I think there is a hell of a lot of potential there considering the massive increase in dietary requirements. Lactose-free, gluten-free, could be on the agenda if cross-contamination can be ruled out.
Different formats could be tried - for instance a PatVal/Greggs type for single servings. Neither cater for groups with food intolerance, and I think the gap in the takeaway market could be significant in certain areas.
One downside for me is the management here, not enough diversity, outside experience or depth. I could see them being resistant to change.
Cake Box Holdings (LON:CBOX) results look good but the reviews of the cakes online are quite poor - lots of complaints that they are dry / stale, so I would be concerned that the level of repeat purchases will be low and growth will be difficult once stores mature
Hi Paul. It's going to be a very exciting week for Flybe (LON:FLYB) holders. There's been plenty of discussion over on the LSE board's re: the Heathrow slots. It appears that the slot pairs held by Flybe will be "grandfathered" to the airline after 3 years on the route, meaning they can then be traded on the secondary market. They are restricted to certain European destinations, so not as valuable as unrestricted slots, but, an existing Heathrow operator could swap them around with their existing European operations, thus freeing them up for use as international slots. Some crazy figures being thrown around as to the value of these slots, many multiples of the company's market cap. Exciting times indeed.s
Paul if you get any time I would be very interested in your thoughts on Intercede interims. Cost savings 29% and revs up 14% lead to reduced operating loss of 0.6m which with R&D tax refund moves to a small profit. Cash at 3.6m Chairman says he expects company to return to op profit in next financial year. All quite promising as far as I can see for a sucker stock let's hope it isn't!
My 2p on Cake Box Holdings (LON:CBOX) is that if they started a vegan range sales could go mad. Questions is whether management are happy catering just to the Indian 'pure vegetarian' demographic or if they have ambition to expand outside of it.
Seeing Machines (LON:SEE) news - 25 years contract with RAAF, but no numbers, not enought to get me back in here
Kainos (LON:KNOS) - Profit up 42%, Cash up the same, EPS 24%, Div up 40%, justifies its highish PER better and enough to make me wish I'd not sold out at about 280p, certainly! Do any other readers have a view on this NI-based digital medical records services provider?
Well done to Flybe shareholders but may be a bit risky to get in now given we don't know whether a bid or a merger will go ahead?
Positive sounding RNS with no numbers from Seeing Machines (LON:SEE) I am shocked, I've never seen them do that before! ;-)
Ex-holder who got tired of rampy jam tomorrow BS and sold out. Good to see they haven't changed.
Would appreciate any views on Cake Box Holdings (LON:CBOX) debut set of results since listing.
Defying the high street with 15 new franchise openings (H! 2018: 10)
Revenue up 44%
Gross profit up 47%
Adjusted eps up 36% (adjusted for IPO costs)
Biggest concern is how big the total market for egg free cakes is but performance suggests there is strong demand. I understand this is mainly from Hindus that avoid eggs for religious reasons but I have seen a lot of positive reviews of the products.
Some general doubt over figures following recent accounting surprises but owners still have a big slice (sorry) and results seem clear and frank. I hold.
The cakes are delicious if a tad on the expensive side at around £3 a slice.
The odd occasion when I treat myself I do notice that there is usually a large number of birthday (and other special occasion) cakes waiting to be collected.
The product deserves to do well.
My morning smallcap tweet from Mello London:
MedaPhor (LON:MED), Seeing Machines (LON:SEE), Cohort (LON:CHRT), Fusion Antibodies (LON:FAB), Sanderson (LON:SND)
Medaphor Group (MED) placing and open offer at 8.5p, nil discount.
Seeing Machines (SEE) Aviation division wins small first order. Operator monitoring technology will initially be installed in two flight training simulators for the Australian Air Force. "This initial engagement will enable Seeing Machines to demonstrate its core capability."
Cohort (CHRT) wins Electronic Warfare Operational Support software and services contract worth £20m.
Fusion Antibodies (FAB) H1 poor as previously announced but strong recovery in order levels seen in October and November.
Sanderson Group (SND) FY rev up 49%, adj EPS 7.9p (6.4p), ahead of mkt expectations. Guides 2019 at least in line with market expectations.
thanks for these comments, they are a great daily addition
Preliminary results out from Sanderson (LON:SND) this morning.
https://www.investegate.co.uk/sanderson-group-plc--snd-/rns/2018-preliminary-results/201811260700074086I/
Decent looking numbers ahead of market expectations.
Gus.