Small Cap Value Report (Mon 27 July 2020) - RBG, HEAD, VANL, CPC, KBT, BOO, KNOS

Good morning, it's Paul here with the placeholder for Monday's SCVR, put up so that members can post comments from the 7am RNS.
Please see the header for the company announcements which have caught my eye today.
Estimated timings - the morning went by in a flash, so I'm having another go at adding some more sections after lunch. Looking to finish about 4pm.
Update at 15:54 - today's report is now finished.
Tourism shares (e.g. airlines) are down sharply today, as a resurgence of covid-19 has led to the UK Govt re-imposing a 14-day quarantine on tourists coming back from Spain (apart from Canary & Balearic islands). Sod's Law kicked in for me, as I booked a trip to Malaga for September, so am hoping the quarantine restrictions might be lifted by then. Although for me personally, I've worked from home for the last 18 years, so quarantine at home would be little different to normal life. In any case, who's policing it? The only practical difficulty would be buying groceries.
Gyms - I've seen some alarming stats about the willingness of clients to return to gyms. CNBC reported last week that a massive 59% of gym clients say they do not intend to return, instead intending to cancel gym memberships post-lockdown. That's a staggeringly high figure, which if people do what they say they intend to do (not always the same thing), then it would cripple the sector. The argument is that people have found other ways of exercising during lockdown.
There's an interesting article here about attitudes towards gyms in the UK. Attitudes might change as we go back into colder weather in the autumn/winter, where exercising outdoors becomes even more unpleasant than now. The problem is surely heavy breathing when exercising, which you can often see in strong sunlight projects saliva far & wide, and profuse sweating. All in an enclosed environment. That's surely a deeply unattractive proposition to visit a gym, with a nasty virus still in circulation, and likely to remain so for some time? Hence I'm keeping well away from Gym (LON:GYM) and Pure Gym (LON:PGYM) shares.
.
Revolution Bars (LON:RBG)
Share price: 18.5p
No. shares: 125.0m (after placing shares admitted today)
Market cap: £23.1m
(I'm long)
Admission to AIM, Director shareholding
This is just a formality, but the RNS confirms that RBG shares are now listed on AIM, having moved from the main list.
Increased Director shareholdings are also confirmed.
I was wondering if the move to AIM might have possibly forced out some institutional shareholders? There might possibly be some holders with a mandate to only hold fully listed shares? I'm surprised to see the share price dip below the 20p placing/open offer price.
A reader emailed me, asking for my current opinion on this share. Nothing has changed from my last post here about it. I see this as a binary situation, dependent on how covid develops. If things get back to normal over (say) the next 6 months, then RBG shares could conceivably double from here (maybe more?), since there was a nice turnaround underway before covid struck, and the bars were highly cash generative. People who say otherwise haven't done their research properly!
On the downside, we've seen how bars and nightclubs seem to be problem areas in other countries, in terms of spikes of covid. Therefore I can see why many investors may want to avoid this sector altogether, seeing it as too risky.
RBG should now have enough cash/facilities to survive well into 2021, so it's a nail-biting time for shareholders in bars generally, to see how things develop. We should get updates in the coming weeks, over how the gradual bars re-opening programme is going. RBG seems to be very cautious in re-opening slowly. Does anyone know which bars have re-opened? I'd quite like to visit one, to see how it's looking.
Clearly this share is high risk, and entirely dependent on what happens with covid. But it's got enough cash to keep going well into 2021, so we'll see what happens in due course.
Thinking more widely about sectors, it's clear now that all the assumptions that investors & management had about business models in the travel, retail & hospitality sectors, were completely wrong. The main assumption is that business would always continue uninterrupted. We now know this was wrong. Lockdown has changed everything. From now on, leases will have to be drafted differently, with clauses to allow for what happens in the event of more shutdowns in future. Someone will have to bear the risk, or take out insurance to cover it (if anyone is prepared to offer such insurance at a reasonable price?). Many businesses are carrying far more risk than we realised. Negative working capital (e.g. airlines funding their operations from customer deposits) is no longer viable, so that will have to be changed too. Plus, many companies that relied on debt, will need to re-think their risk. Companies need to bolster balance sheets, and pay less out in divis. How long before all this is forgotten, and everyone starts making the same mistakes again? 2 years probably!
.
Headlam (LON:HEAD)
Share price: 279p (up 9% today, at 08:29)
No. shares: 84.9m
Market cap: £236.9m
(I'm long)
Trading Update & New Distribution Centre
Headlam Group plc (LSE: HEAD), Europe's leading floorcoverings distributor, today announces a trading update in respect of the six months ended 30 June 2020 (the 'Period') ahead of announcing its interim results on Thursday, 3 September 2020.
Trading was OK until lockdown began on 24 March.
H1 revenue of £242.1 million was 30.6% below the comparative period in 2019.
Trading is recovering now, which is probably what has stimulated today's share price bounce;
UK revenue profile recovered strongly during June 2020 following the reopening of all of the Company's principal distribution centres by late May 2020 and the reopening of retail businesses in mid-June 2020.....
... trading to-date in July has seen a continuation in revenue growth back towards 2019 revenue levels. Currently, July 2020 UK revenue is running ahead of July 2019's UK revenue.
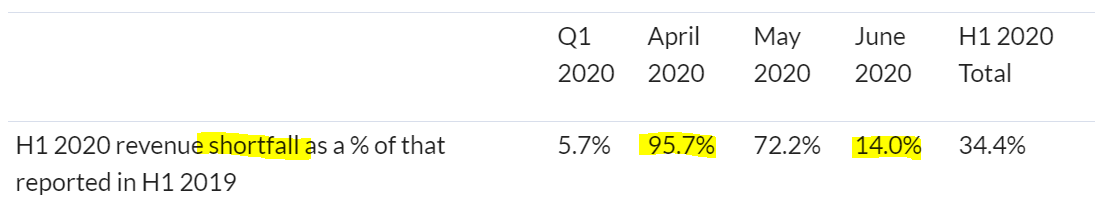
I like this table below. It's much easier to understand when companies provide a table like this, instead of sometimes ambiguous text;
.
.
That's a very striking recovery in June, and even better in July - possibly pent-up demand. Domestic demand must have been helped by lockdown - people spending months at home, with children charging about, must have worn out a lot of carpets! Although laminate flooring is popular these days too.
Outlook - limited visibility. H2 is seasonally stronger usually. Fear of another lockdown.
Whilst the current revenue performance is pleasing, it is still not possible given both COVID-19 and the economic backdrop to provide guidance at this stage on the expected outturn for the financial year ending 31 December 2020.
Liquidity - this sounds OK, although shareholders will sleep more easily once the Dec 2020 covenants have also been eased. Hopefully the banks won't force Headlam to do an equity raise. Although even if they do, the dilution would probably be only 10-20%, so not a panic situation for shareholders.
The Company announced in May 2020 that it had agreed revised covenant tests with its banks, Barclays Bank PLC and HSBC Bank Plc, for 30 June 2020 on the existing facilities which run to 30 April 2023.
The Company is currently in discussions with its banks regarding the extension of these covenant amendments for 31 December 2020.
As at 30 June 2020, net debt was £22.5 million, with banking facilities available to the Company of £110.7 million and headroom of £88.2 million. The Company remains confident it can manage the business and cash flows within these facilities.
Dividends - no interim divi will be paid. Makes sense. Wants to resume divis in future.
Profit guidance for H1 - this is very helpful;
... underlying loss before tax for the Period [Paul: i.e. H1: Jan-Jun 2020] of approximately £2 million.
Goodwill writedown of £20.9m - doesn't matter to me, as I always write off all goodwill anyway, and ignore the amortisation charge too, which is standard practice with most analysts & investors.
Cost-savings, efficiency gains, new £26m distribution centre, expected to improve future profitability.
My opinion - I'm pleased with this update, and will be looking to increase my position size here, when funds permit.
This looks a classic case of a business which has suffered a temporary, one-off impact from covid-19, which is now righting itself. Therefore, I think people who hold this share throughout the crisis, should come out the other side with a decent restored dividend yield.
I don't see any solvency risk, with a last reported balance sheet of nearly £100m NTAV. The modest bank debt is covered multiple times by liquid assets (inventories and receivables), and the bank should be fairly relaxed, given the rapid recovery of revenues.
Overall then, this gets a thumbs up from me.
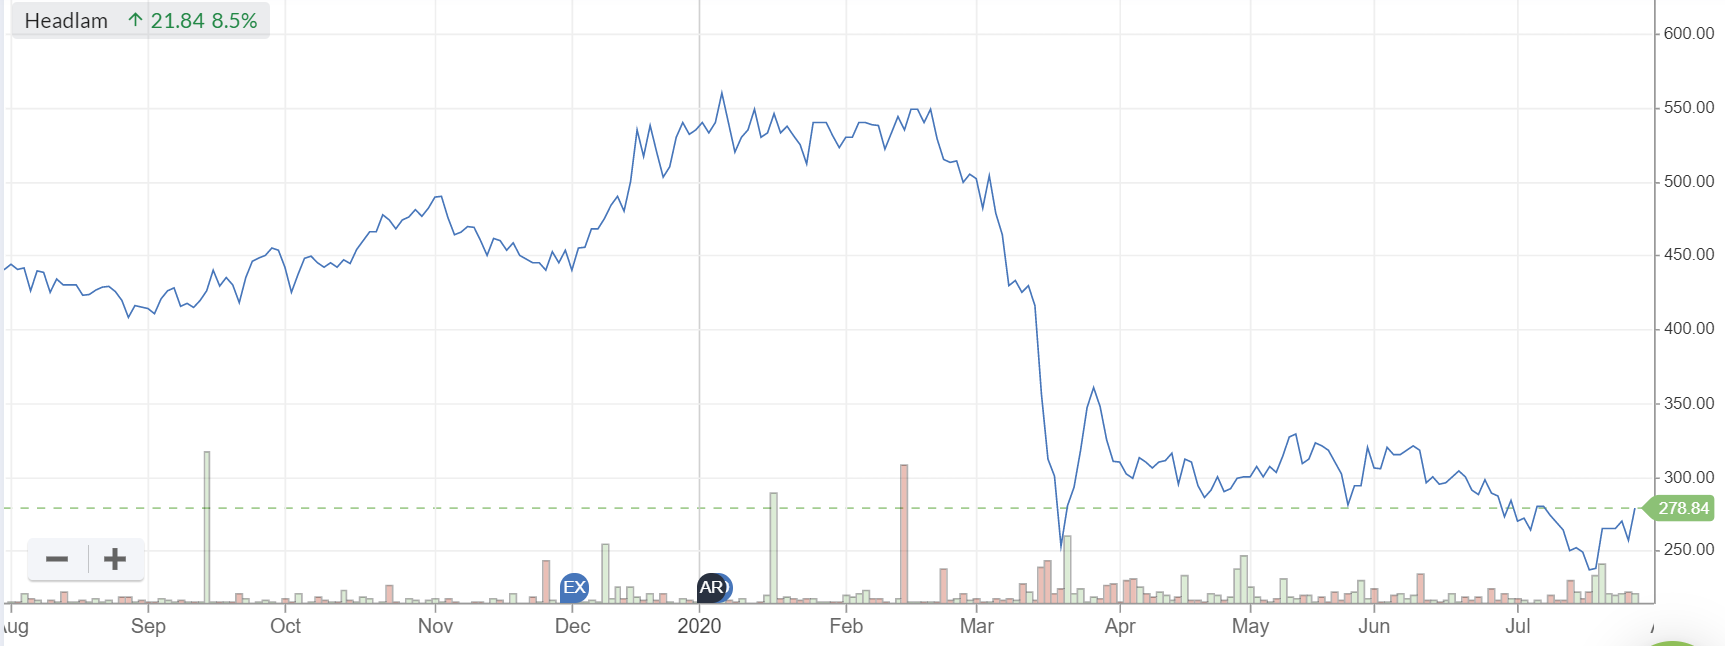
Looking at the 2 year chart below, I don't understand why the price has failed to recover much from the recent lows. I would have thought the newsflow justifies a stronger rebound, if we accept that 2020 results are a write-off, but should still be profitable given the H2 seasonality. Looking to 2021 & beyond, I think the share price should recover. Buying now could lock in a low future PER, and high future dividend yield, for investors taking a long-term view. That's assuming nothing else goes wrong, of course. There are always risks, with every share.
.
.
Van Elle Holdings (LON:VANL)
Share price: 30.6p (down 3% today, at 11:15)
No. shares: 106.7m
Market cap: £32.7m
I last looked at this groundworks contractor here in Dec 2019, when it was already doing badly, before covid struck this year.
This is what it says today;
Van Elle Holdings plc, the UK's largest ground engineering contractor, announces that since its most recent update on 4 June 2020, the Group continues to trade slightly ahead of the mid-case scenario outlined in the announcement of its equity fundraising on 9 April 2020.
Group liquidity remains strong and its cash position as at 24 July was c. £10.0m having paid £2.0m of deferred PAYE payments to HMRC.
It doesn't say whether other taxes have been deferred, e.g. VAT, which could be a large amount. Hence we only have incomplete information, which isn't good. Companies need to be very specific about deferred taxes - i.e. confirming either way whether, and how much, they have benefited from tax deferrals. Otherwise we're not seeing the full picture, which could be misleading. The thing that concerns me, is VAT could be deferred until March 2021, resulting in a cashflow cliff-edge. That's a general point, which could could affect lots of companies. I'll need to pay particular attention to balance sheets in the coming months, when interim figures are published, to spot stretched creditors, in particular VAT.
Fundraising - it raised £6.7m in April 2020, at 25p per share - at the time this was a 21% discount, suggesting that there wasn't much appetite for the deal from investors. The mid-case scenario (referred to above) is this;
In order to assess the potential impact of the COVID 19 situation on the Group, the Board has modelled a series of scenarios to reflect what it believes to be the range of potential outcomes for financial performance in FY21. Based on its current assessment of the short-term outlook and informed by customer discussions, the Board's mid-case assumptions envisage that Group revenue would be approximately 25% below its plan for FY21. This assumes that Group revenue levels reduce to 40% of plan in May 2020 before recovering to approximately 80% in September 2020 and being maintained at around this level for the remainder of the year.
My opinion - I can't find any brokers notes, and am not interested in buying this share, as I rarely touch contractors's shares. Hence it's not a worthwhile use of time putting the above scenario through a spreadsheet.
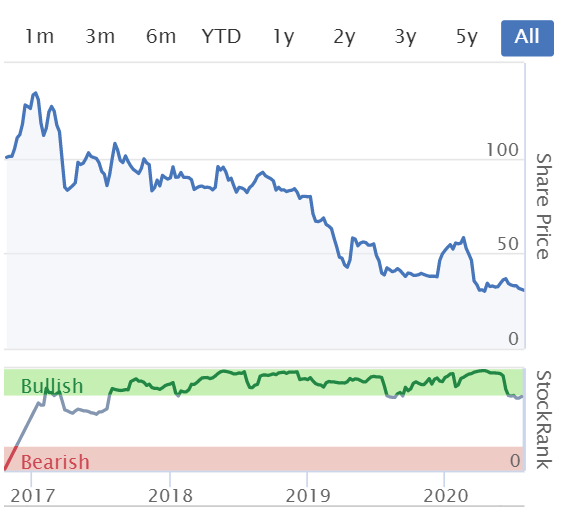
With so many better quality companies out there in other sectors, I cannot see why anyone would want to own this share in preference. That doesn't make sense to me. The track record since floating on AIM in Oct 2016 has been lacklustre. Although to be fair, it has paid 8.3p in divis, so the total shareholder return isn't quite as bad as the chart suggests. Maybe profitability might return in 2021 or 2022?
.
.
City Pub (LON:CPC)
Share price: 69.6p (flat on the day, at 13:45)
No. shares: 103.8m
Market cap: £72.2m
This is a (mainly) freehold pubs company, with sites in London & Southern England. Here's a list of its pubs.
Ahead of the Annual General Meeting to be held later today, the City Pub Group updates on trading for the three weeks since 4 July, when pubs were permitted to reopen in England following the easing of social distancing restrictions.
Some pubs have reopened;
On 4 July, the Group reopened 24 of its 48 pubs, with a further 8 pubs reopening over the last two weeks, taking the total number of pubs open and trading to 32.
It is our intention to open the remaining pubs over the course of the next two months, or earlier if social distancing measures are relaxed further.
.
Like-for-like ("LFL") sales are down 37%. The company says if finds this "encouraging". Hmmm, I'm not so sure about that. Pubs operate at very high gross margins, so any fall in LFL sales would have a punishing impact on profitability. I'd be very surprised is the company is profitable at this level of sales. Still, it's a start, I suppose.
No, I was wrong, it goes on to say;
Following thorough work during lockdown, significant reductions have been made across our cost base, including payroll costs, consumables, satellite TV, entertainment, recruitment, and these together with operational efficiencies from our streamlined offering, have allowed the Company to trade profitably and generate cash during the 3 week period.
That is surprising! Although bear in mind that freehold pubs don't have any rent (nor business rates at present), but instead pay interest on borrowings in lieu of rent. It's not clear whether this announcement includes interest charges or not, in reporting profitability.
Outlook - sounds promising;
The Board remains confident it will be able to rebuild its sales to previous levels on a much lower cost base.
Fundraising - it raised £22m in a placing/open offer at 50p in April 2020. That should have repaid a lot of the £30.0m net debt last reported at 30 Dec 2019.
Balance sheet - the end 2019 balance sheet shows NTAV of £74.8m, being mostly freeholds less some debt. Given that much of the debt was repaid in the subsequent placing, then the current balance sheet should look really strong. Even taking into account likely losses during lockdown, the market cap should be well below current NTAV. Therefore this company looks very financially secure.
My opinion - this must be one of the lowest risk ways to buy into the pubs sector. The share is basically a minimally geared property company, that also operates its freehold pubs portfolio.
Long-term, once we've got through covid, whenever that may be, this share could be usefully higher, perhaps. And in the meantime, it's not going bust, because of the value of the freeholds. So quite attractive risk:reward, I would say.
.
K3 Business Technology (LON:KBT)
70p (up 4%) - mkt cap £29.9m
Very late results for FY 11/2019 are out today.
There's a fairly worrying Going Concern note, which the auditors also draw attention to in their report.
A subsidiary was placed into administration.
The balance sheet shows negative NTAV.
I think this has to be seen as a special situation, to determine whether it could become a turnaround/recovery situation, or whether the future is more grim? It's not for me.
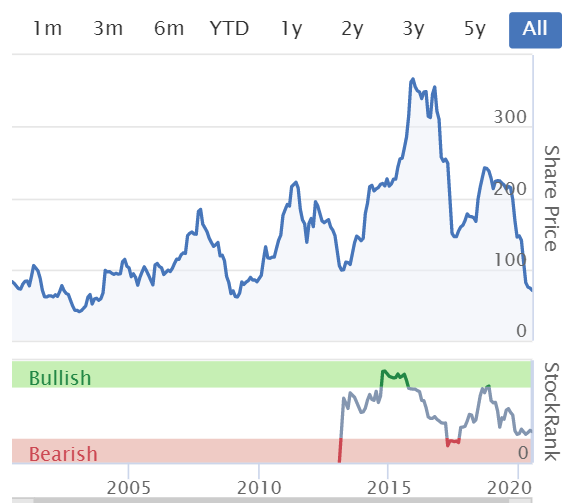
As you can see from the long term chart, it's back down to where it was 15 years ago. Maybe just not a very good business?
.
.
Boohoo (LON:BOO)
(I'm long)
Own factory - an interesting development here. Very clever, I think. BooHoo has decided to set up its own "model" factory in Leicester, making clothes directly for its own websites, and demonstrating best practice. This is great PR I think - as if anyone criticises BooHoo for using suppliers which operate sweatshops, then it will be able to point to its own impeccable factory.
The other aspect of this, is that it cuts out the wholesaler's typical 20-30% profit margin. In doing so, that could make UK production economically viable, even if paying full minimum wage. There might be opportunities to automate some processes too.
My opinion - an interesting development. I see the current depressed share price as a terrific buying opportunity, as there have been numerous allegations against many brands, for either exploiting warehouse, or subcontractors. As long as they're seen to do something about it, then these things quickly blow over.
.
Kainos (LON:KNOS)
1036p (up 25%) - mkt cap £1,266m
Much bigger than I normally look at, but a strikingly good trading update caught my eye;
Despite the impacts of Covid-19, trading in the period has been strong and we expect revenue to be well ahead and adjusted profit to be substantially ahead of current consensus forecasts for the full year ending 31 March 2021.
That's great, but look how forecasts had previously been lowered;
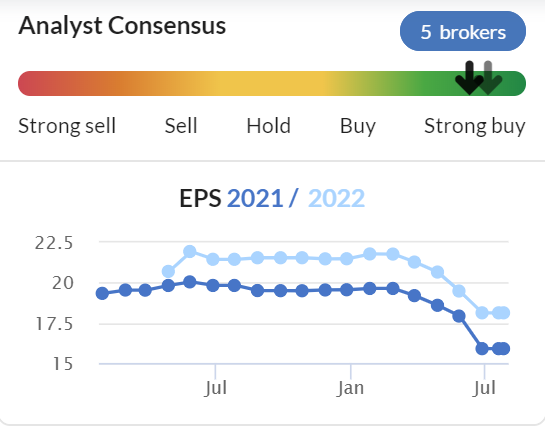
.
If it gets to say 20-25p EPS, then the PER would be 40-50 - that looks crackers to me, especially as the narrative says some cost-savings are one-offs.
My opinion - makes the FAANG stocks look cheap!
That's me done for today. See you tomorrow.
As always, thanks for the interesting comments.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
With regards to Revolution Bars (LON:RBG), an asset manager has just gone from zero to its largest shareholder with nearly 9% last Thursday, so someone far cleverer than me thinks its a good buy
Thanks Paul for your (as always) excellent updates today.
I seem to be in a minority here and elsewhere in strongly agreeing with your views on BOO, and think current price is very good buying opportunity and a good chance of a second bite after that great run up from 35p. I would never have bought then but for your brilliant posts basesd on such detailed knowledge of the sector.
Short term BOO share price might be volatile if ethical investors sell, but I can’t fathom how any fund manager could not have known about how and where clothing retailers source their clothes. And some seem to be disgusted at iffy practices in the UK while turning a blind eye or ignorant about far worse conditions in sweat shop suppliers for many clothes retailers elsewhere like Bangladesh. Have they forgotten about that terrible factory fire there years ago where no fire regulations or ignored. In an ideal world working conditions and in the food sector (slum labour in the Fens) would be much better, but to single out BOO as the only such example seems ludicrous.
Think you will find that many of us share the same opinion,but tend not to go on about it as much as the naysayers
Re, 14 day quarantine when returning from Spain... Less people spending on holidays abroad, more people spending within the UK economy? Call me cynical!
Re observation in RBG comments Many businesses are carrying far more risk than we realised.
Paul, you have often railed against the capitalisation of leased property costs on the Balance Sheet but have recent events made you reconsider your opinion on IFRS 16 as it shows the worst case and if you wish you can adjust the figures to suit your analysis?
Regards
Gyms - Been back in the gym everyday since Saturday (well you got to catch up somehow).
So the below is subjective and just from within my experience bubble.
Generally felt very quiet, staff say spin and boot camp classes are half full or less. Cardio and weights areas were like a ghost town, staff say regular users 3 times a week plus were all in (but less prequent users absent) - they said they had a flurry of cancellations at the weekend. Staff have returned on reduced hours.
One other gym in town is laying off 6 of the 25 staff they had in their gym and spa.
I have noticed the boot camp clubs that use the disused local bowling green in the morning only have 5-6 people attending, where as in the past it was upwards of 15-20.
Normal is going to be some time off for now.
Re Gyms - reported that gym equipment sales have boomed since March so I wonder if many have realised that there is a lot of money to be saved by having your own set up at home? Also a lot of time saved in not having to travel to and from gym.
Obviously can't work for everyone - you need some available space to set things up.
Quite a few in the WhatsApp lifting group have done just this , the cost of a decent set of weights, squat rack and bench is around £1K + - so I can't see them coming back after spending that much. Shame most of the decent equipment manufacturers are private eg. Rogue, York Barbell etc..
Gyms were bug ridden airless under ventilated filthy drama-filled torture chambers before the lockdown... I go back to mine tonight to see what's there.
You have to book in, the classes/spin sessions are halved at capacity which means most customers will be disappointed, and the puke/sweat fests like HIITs and BodyCombat for now has disappeared.
A buddy of mine specialising in Online Coaching however says he's seen a surge in client bookings.
Re Gym (LON:GYM) - Note sure how we got here today as no RNS etc but...although they are high risk of an open/close/open /cycle over next 6-12 months, long term I am sure they will be back.
My son and his friends still want a Love Island body and will not be spending £1K on equipment. They have neither the capital nor the space. Politically, it also looks as if there may be a sustained push to get everybody fitter - Boris in shorts anyone!. At least some of this will translate to gym visits (which are cheap/visit if you x2/wk = 8+ visits/mnth for say £15-20/mnth. Compare that to a cinema or pub visit for cash-strapped 20&30 year olds!). Same is true for personal trainers /outside boot camps. These work fine outside when the sun is shining, they will be less attractive at a drizzly 5C
What will likely be hit very hard are local authority gyms, often surprisingly expensive and dragged down by expensive attached swimming pools plus other mid- to upmarket gyms. At the other end small, financially weak gyms without good digital systems and advertising may go bust. So medium to long term you can see a case for market polarising and the biggest part going to low-cost chain gyms like Pure Gym and Gym Group with good Marketing budgets. The latter at least has cash to survive (following 41Mn equity raise in April at 150p, 9p over current price).
So my only concern on re £GYM group is that they have been paying premiums to get long leases on sites near transport hubs - hubs that will be much less valuable in the short run with high unemployment and/or lots of working from home and potentially a drap long term. However, on the upside they (and new competitors?) will be able to expand more cheaply - new leases on retail parks will be dirt cheap! But with a national brand and small box formats established & rolling out, I think they are well placed.
I hold, bought more in the crisis and expect to hold for 3 or 4 years so obviously believe in the upside case in the long run.
I don't think PureGym are in great shape financially - IIRC their parent had a large bond outstanding. I think they may be vulnerable in future.
I kinda of disagree that local authority gyms are expensive, at least the one under the Better brand. In fact I think Better have done a terrific job. They are a 'charitable social enterprise' so I don't even think they would even come under financial pressure. It could be even the reverse, as if government wanted to get more people fit, it could use the Better network to dish out free vouchers for activities.
For example, the Better gym in Stratford is £36.25 a month. TheGym prices are sneaking up - seen very few at under £19.99 now for London, and the Central London ones are quite pricey now (ie. Angel £31.99).
The Stratford Better gym is £16 a month more expensive but also comes with more modern equipment, discounted pool entry, and a superior range of classes. It isn't 24 hours but I feel this aspect is of little value unless you really need it.
I don't view this as bad value at all, for a user of the pool or spinning/pilates/yoga it's actually better value (you have to pay extra at GYM for those classes).
Been rather disappointed with GYM as a member. Their website basically fell over on the first day. An app which was supposed to show how busy a gym was and allow contactless entry also failed, and still hasn't been fixed. It also doesn't seem to run on the same database as the membership site, so you need a separate membership for it.
They have also seemed to price themselves out of the one-day membership, which doubled in price at my gym.
On this front, I think a centre like Better could have an advantage, especially for the casual user who just wants to pay as you go.
Mate of mine works in a Royal Mail sorting office. For the first three months of lockdown, he says he only moved boxes of wine or gym equipment.
So presumably he doesn't need to visit the gym!
Here is the cnbc article I think Paul was referring to. It suggests people are now looking for cheaper alternatives. So one could argue people cancelling their expensive memberships may look for cheaper no contract alternatives. Pure gym and Gym (LON:GYM) could be a beneficiary of that https://www.cnbc.com/2020/07/2...
There is an interesting article/interview with Oxford Professor Sunetra Gupta giving an alternative perspective on Covid and immunity/treatment, which people may find interesting:
https://reaction.life/we-may-a...
I am not saying I agree or disagree with her opinions (I still think there is still not enough data to form a hard view) but I certainly find it interesting.
I would also add that Avacta (LON:AVCT) has developed an Affimer which blocks the ACE2 receptor. To quote:
“...shown that Affimer reagents which bind to the SARS-COV-2 virus spike protein prevent infection of human cells by a SARS-COV-2 model virus and therefore provide a potential therapy for COVID-19 infection.”
Full update at:
https://avacta.com/update-on-affimer-therapy-for-covid-19-infection/
So a vaccine may not be the only hope.
I hold Avacta with a 4.75% of holding.
Regards
Michael
On thing I do agree with is lauding New Zealand for its lockdown (or should that be lockout) seems very premature.
Of course in headline terms it delivers glowing reports in the short term.
In fairness Revolution Bars was not really a star performer before the crisis so it’s difficult to see how Covid 19 might have improved things. The company seemed to be relying on cost cutting and closures to consolidate its position and perhaps the bigger question for investors is if a small pure bar operator has a successful business model as a quoted company?
I can’t recall many success stories in this niche sector. Many years ago one of Jim Slater’s popular picks was Luminar. I was struck by a conversation I had with another investor who was also a former law enforcement man and his reply was quite insightful. He said that one problem Luminar had as a legitimate quoted operator was that it was competing with privately held bars/clubs whose principal reason for existence was not to sell alcohol at a profit.
It’s obviously difficult to see what effect fake bars have on legitimate operators such as Revolution and indeed other legitimate privately held bars. It may not be much – but it’s another headwind.
As a slight read across – it’s not been that well reported in the UK but readers may have noticed that Police across Europe manged to crack EncroChat – the encryption communication system which was allegedly used by Europe’s organised crime network. It was a huge success for much maligned Police and for anyone interested, an account appears in Wikipedia.
https://en.wikipedia.org/wiki/EncroChat
One interesting point was that in the UK alone Police recovered £54 million in cash at various locations. It may be a coincidence that the story broke a couple of days before pubs and bars were scheduled to re-open in the UK.
Hopefully there is a similarly successful outcome for Revolution shareholders
Thanks for flagging Headlam (LON:HEAD) as I hadn't come across them before. At a quick glance this looks like the sort of boring (by that I mean consistent, reliable and honest) business that I'm attracted to. Worth further investigation...
I visited my local Cafe Nero yesterday, for a Sunday afternoon catchup with a friend. My first visit to a favourite local hauntsince lockdown.
There was evidence of precautions against infection, hand sanitisers on entry, perspex screens between customers and staff, paper cupsm and removal of some tables. A slightly sterile atmosphere compared to before but all available tables were taken. (It's a place where you typically get people stationed with a coffee, working on a laptop for an hour or so.)
A fair flow of people coming for takeouts, and other potential customers who came and left due to lack of seating. In normal times it's a very busy weekend venue, with constant streams of customers ones and small groups often spending surprisingl large amounts for a small place. Actually there used to be the staff sales target just by the till. I think it was something like £1500 (per day? per week?). Wish I'd asked!
After 15 minutes we gave up and had coffee and an unheathy sandwich at an independent coffee place.
It got me thinking whether places like Cafe Nero would be viable if these trading terms persist. I suspect they might still be just about OK as is, and likely would be fine if rents and business rates were permanently lower.
I wouldn't want to anywhere near commercial property firms as an investment right now, as estates might permanently have to live with lower rents. I've never really understood why rents are apparently so sticky and landlords of estates would rather keep places empty than rebase rentals to make units viable.
They say an effect of a crisis like Corona is too accelerate pre-existing trends such as home-working, zoom meetings etc. So perhaps retailer and hospitality will do OK where they can survive given lower rents. I guess the really strong players in the sector might do pretty well longer term. I'd guess Wetherspoons is one example, not sure who'd be candidates among general retailers.
Agree on Gym (LON:GYM) group, it’s definitely one to avoid in short term. I just cancelled my membership of Pure Gym as I am not comfortable going back straight away and can easily decide later on to start it up again as there is no cost of doing so. I imagine a lot of others will be doing the same. That means the member figures of Gym (LON:GYM) could look very bad when they next have to report and market will take no prisoners if that is the case (even though a lot of people may be thinking to start up again later, the market won’t factor in that intricacy). If that happens, then is the time to consider investing rather than now.
Paul, glad to see that you’ve moved on a bit from your view earlier in the crisis that once the lockdown ends people will party like it’s 1999 and the outlook for bars will be rosy. As we can see more clearly now it is a very complex picture and hard to predict where or when restrictions or minor lockdowns will strike next and which bars may be viable or not.
Regarding sectors, I am not sure if LOFBI is an acronym yet but perhaps it should be. That is Last Out First Back In, meaning that the sectors that were allowed out of lockdown last will be the first back in to a future lockdown. This is coming to pass in international tourism with the quarantine restrictions on Spain. So, it really does make me very wary of any sectors or businesses that could be shut down again quickly. So, although I was reluctant to sell GYM (LON:GYM) earlier in the crisis as I think it had very good growth potential I’m glad to have taken that decision as the gym sector could be another just too exposed to LOFBI at present.
But on Headlam (LON:HEAD), a past holding but not at present, I am wondering whether the Stamp Duty holiday will push up the number of housing transactions, even if house prices may be subdued, and hence drive volumes in the floor coverings business for the next 9 months. I think that could be a bigger driver for them than anything else right now. However, it’s not a business that has captured the imagination of investors in the past so perhaps even if their future is good that may not be reflected in the share price.
Hi Graham,
Paul, glad to see that you’ve moved on a bit from your view earlier in the crisis that once the lockdown ends people will party like it’s 1999 and the outlook for bars will be rosy.
You're putting words into my mouth there, to some extent. I try not to use words like this will happen, and that will happen. Nobody can have that level of certainty. Social distancing rules have been key as well - clearly the 2m rule made it impossible for bars to trade sensibly. The 1m flexible rule makes it a bit easier, but capacity constraints clearly restrict the potential for bars to trade profitably, or at all, as we've discussed here before.
The situation is constantly changing, so we have to adapt our thinking. Actually, I still think that a lot of young people do want to party like it's 1999. Just look at Bournemouth beach when the sun comes out, for the clear evidence! The question is purely whether they're allowed to go clubbing, or not. The social distancing rules currently make it a fairly sterile & atmosphere-less environment to go to pubs, for example. I didn't really enjoy my trips to various pubs, with anxious staff bossing customers around. I'd rather drink a 4-pack of Carling on the beach.
Roll things forward a few months, and we could have much better treatments, and at some point after that maybe a vaccine? The pent-up demand to return to bars/clubs/restaurants is clearly there. So at some point, things are likely to return to normal. The only question is whether companies can survive long enough to benefit from that return to normal - which nobody knows when it's going to happen.
Regards, Paul.
Hi Paul,
I think something to be wary of is the recent reports in the spanish papers (Thankyou google translate) is they are finding outbreaks relate to family gatherings an nightclub/nightlife venues, and the authorities are closing them.
Given the, in my view, highly suspect quarantine decision for Spain (for me a political decision to show how on the ball the uk government is, not! ) but given the huge impact to tourism and hospitality this will have, the government wont think twice about banning the opening of nightclubs. There is no reason the number of infections in spain wont follow elsewhere & in particular the UK, why wouldnt they (spain is quite obsessive with is covid rules) , if and when they do, shutting nightclubs & Revolution Bars (LON:RBG) business would be a logical step (not that logic is in abundance) so there is a very real risk to Revolution Bars (LON:RBG) and the like that i am not sure is priced in.
yes, but they won’t shut every bar across the whole country, surely. There has to be some balance or there will be other issues. We’re already started on a path to local lockdowns
That's right, I mentioned in the main article that nightclubs/bars were proving problematic overseas.
Although one thing to consider, is that RBG is not operating its re-opened bars as nightclubs. It has shifted to a standard 11pm closing time, therefore operating as a standard bar. They are mainly large sites, where social distancing measures can be applied more effectively.
Therefore I think investors are perhaps missing the point, in seeing RBG as nightclubs, when they're not.
The big issue, is whether RBG can trade at breakeven or above after re-opening? That's a tough call, and nobody knows at this stage. They're prioritising re-opening sites with the most outside space. The most profitable sites pre-covid will not necessarily be profitable with social distancing measures.
Therefore it's an uncertain situation. All shareholders need, as with all bar companies, is that they can survive into next year, and hopefully come out the other side (with a lot less competition remember). The placing & extended bank facilities do seem to give RNG headroom well into 2021, according to a Peel Hunt note.
Another option that could be considered, if things get really ugly in the autumn, is doing a pre-pack administration, although I've not heard anything about that, it's just my idea.
There's a resurgence in the rave scene with illegal gatherings that are too large for the police to be able to break them up. I think teenagers are no more able to socially distance than toddlers for any length of time.
So better in my view to open the bars and get people to check in so that track and trace people have some clues to work with if there is an outbreak. But that may be a bit of a stretch for our world class PM's boss to explain to his focus groups.
RBG have a great and very large site right on the Thames in Richmond,but it’s the only bar in the area that’s yet to open. Trade appears to have been very good in the area ,considering all the noise,broken bottles and rubbish left behind on the banks of the river !!
Frankly,I am very surprised they have not opened yet.
Minor anecdote on Pubs.
OH works in a micropub. Was furloughed. Just been told that it will not be re-opening as just not economic.
(It was capacity ~25 when completely jammed - so not too surprising, but sad)
It was owned by a brewery that supplies the local area (n. somerset)
They also had to reduce the brewery staff. Orders are running at about 25% of what they were in jan / feb 2020.
This says to me that the pubs may well be open and selling beer but until everything is back to normal, profits will probably not be normal.
Yes, similar experience here. As soon as the Amstel was back on tap, I returned to the Lord Clyde (in N1), and chatted to the landlord;
"I'm glad to see you've survived"
"Well, we haven't really. We're only here for another 5 weeks, then that's it"
"Oh no, I'm sorry to hear that"
"I'm not. Time for a change of career"
I didn't like to ask why they're leaving, but it must be due to not seeing the business as viable, and maybe not being able to pay the rent, I don't know.
The trouble with pubs, is that so many people think they're fun, lifestyle businesses, and get sucked into signing uneconomic leases, giving personal guarantees, and lose their life savings and experience utter misery from running a business that isn't viable. I got into a terrible mess with 5 pubs & a restaurant, which cost me hundreds of thousands of pounds to extricate myself from, a couple of years ago. Total nightmare. Hence memo to all readers: never, ever sign a lease with a personal guarantee.
Regards, Paul.
Maybe a ramble at some point on your days serving Stella to the masses Paul fair play you have certainly had an interesting life
Tell me about it, I've certainly made every mistake in the book. But you recover, and learn from those mistakes (sometimes!)
Agreed on you last comment Paul, although I have done that and survived! ALSO never sign as a guarantor for a family member either. If they default the lender will just come for you not the borrower. Harsh, but one has to protect one's capital for retirement. (I have never done it. I have given money to assist a project but will never act as a guarantor as I have heard too many horror stories. The worst one involved grand-parents losing their own house!!) Great article as always.
Couldn't agree more Paul. The secret of personal guarantees is not to have any assets to back them up. My wife and I opened a small group or restaurants in the 80s and 90s and at one point were in for about 600k of bank debt and a similar amount of annual rents. We decided to sell our flats and put the money into the business to fund another restaurant. About the same time our very friendly bank manager was promoted and replaced by an obnoxious young turk. He insisted on doing a review of the business to include a schedule of our personal assets and liabilities.
The look on his face when we told him that we were renting and had total assets of about £16 was a wonder to behold.
Story has a happy ending as we found a greater fool in a greedy PLC.
I am not sure if this is the right thread to discuss gold , but to add to the discussion that's already in place - Lynn Alden has some interesting analysis here which values gold versus various ratios.
https://www.lynalden.com/reasons-to-buy-gold/
The article is a few weeks old but probably still worth a read.
Thanks intuitive. Even if not the right thread that was an interesting read even though only yesterday I thought I must spend less time reading investment articles and more time getting on with work! With the amount of money being thrown about by governments they simply have to keep interest rates at a minimum and that will surely lead eventually to an uptick in inflation and that combination can only help gold.
One little candle light in the dark of my portfolio performance is my Gold 'hedge'. Perhaps less of a hedge more of a bush. Pan African Resources (LON:PAF) has taken another leap up this am.
The argument is that with money being constantly devalued (discuss!) Gold is a store of relative value.
Pan African Resources (LON:PAF) lay in the doldrums for a long time, and is hitting new highs now. I wonder what the consensus is on Gold value going forward?
I held a relatively small holding of Pan African Resources (LON:PAF) in my portfolio for 14+ years (I did manage to take some profit along the way when spiked to c. 20p at some point) but as you say it ‘lay in the doldrums for a long time’. I finally lost patience and decided to tidy up my portfolio a little on 6th April selling , no doubt to some smart gold bug, at 9.66p only to see the share price virtually triple since!!! I put the proceeds into a physically backed gold ETF which has shown some gain but nothing like £PAF. I guess the lesson here is that Gold miners are a leveraged play on the gold price and are likely to see much larger % increases than something linked directly to the bullion price. A lesson learned but very frustrating nevertheless.
One of the historical problems with LON:PAF has been their debt. But at the current gold price they could be debt free by end FY 20/21. FY 19/20 results show debt down from USD 124 million to USD 62.5 million.
Stockopedia is also showing a very decent forward dividend for PAF. I have some in my portfolio and it's done well recently. But, I've also bought it numerous times in the past and it has done nothing, and I've sold it usually at a small loss (in frustration).
They have decent reserves, and new projects like Evander Egoli are likely to produce an increase in output (potentially 60,000 - 80,000 oz with an 8/9 year mine life). PAF is currently producing about 180,000 oz a year.
The current Peel Hunt target is 24p , but debt free, paying a dividend and with the prospect of production increases, shouldn't it be nearer 50p? It's certainly unloved which is probably in part down to political risk because its operations are in South Africa.
As if to prove the error of my ways I wish I had read this article before baling out of £PAF!!
https://www.youinvest.co.uk/ar...
Paul, interested in your thoughts on Bilby who came out with excellent figures today and have really turned the business around.
Hi Chris,
I had a quick look at the numbers for Bilby, but too tired to write it up, and it's tiny mkt cap.
The PER looks very low, based on adjusted EPS.
Regards, Paul.
If you have time Paul could you cast your eye over dev Clev it’s online education a sector I know you feel there is growth in, these have 4 bagged for me but there seems to be mixed feelings with them - your input would be interesting
Revolution Bars (LON:RBG) Hi Paul, Revolutions website has the answer:https://www.revolution-bars.co.uk/blog/coronavirus-update.
Maybe a trip to Southampton is in order, after the 27th? :)
"Last updated 21/07/20
We’re so excited to announce that a further six bars have had their opening date confirmed today. The bars due to open in the next couple of weeks are:
Monday 27th July
Monday 3rd August
Yesterday, we welcomed back Cambridge, Clapham Junction and Durham. This brings the total number of Revolution bars currently open up to seven and those are as follows:
This list doesn't include Aberdeen and Belfast which i think are also open.
An hour with Mark Slater - the piworld interview from Friday's webinar. Mark, Chairman and CIO at Slater Investments talks about CV19, and more detail on his investing style, how he views companies, and much more. I could have talked to him for hours, and certainly didn't get through all my questions!
Companies mentioned: Hollywood Bowl (LON:BOWL) Codemasters Group (LON:CDM) Future (LON:FUTR) Venture Life (LON:VLG) Strix (LON:KETL) Tesco (LON:TSCO) Hutchison China Meditech (LON:HCM)
Video or podcast - enjoy and share!
Forthcoming webinars:
Friday 31st July, 12.30: Ig Design (LON:IGR) FY20 results presentation by Paul Fineman, CEO & Giles Willits, CFO, followed by Q&A. Register here.
Wednesday 5th August, 10.30am: Imimobile (LON:IMO) FY20 results presentation by Jay Patel, CEO & Mike Jefferies, CFO, followed by Q&A. Register here.
Thursday 6th August, 1pm Investor & Trader: Life in a Family Office. Continuing with the piworld educational webinar series, Richard Leonard will discuss how he manages money in a Family Office. Drawing on a long history in the City. What he learned from his mentors, and how he manages money to generate exceptional returns. Register here.
Thanks Tamzin! I listened to the Mark Slater podcast over the weekend, and as usual, thought he was excellent!
Hi Tamzin..I listened to you and Mark on Friday and as usual found your interview excellent.So sorry that you ran out of time.Would you consider an extra interview as a follow on where you could ask Mark the outstanding questions? Also I cant find the recording of your interview with Mr Hoare re investment trusts which again was very helpful
https://www.youtube.com/watch?v=624gxM5F0gA&t=2267s
Thanks for the link much appreciated
It was great Tamzin, I'm now catching up on the others. Thank you for making them available. They are an education!
Bloomberg's Jojn Authers has a very interesting analysis of the gold price in today's article. If he's right, it could have important consequences for equities too.
Does the heading sum up what he has to say? I would not have thought enough people could be short on gold to contribute to a short squeeze. When I try to look at this it is asking for payment and it is not just really that there is a limit to what I want to pay for but even more so what I have time to read on a daily basis even if it were free.
doublelutz - I think you must be reading it wrong. I signed up recently and receive the daily email. No charge. Only problem is that, for me, the formatting is not great meaning I have to constantly scroll to be able to read across the page (if that makes any sense).
Technically there are intermediaries - the swap dealers run by the banks who make a market in gold who are short and having to scramble to buy gold because investors are choosing to take physical delivery of gold to an unprecedented extent. I'm thinking of it as a melt-up in the price.
I have just been unsuccessful in my attempt to find out who the major players are among the gold swap dealers. Can anyone point me in the right direction?
doublelutz
You can sign up to receive John Authers daily email for free:
http://link.mail.bloombergbusiness.com/join/4wm/opinion-authers-signup&hash=b9b2681361bede0e1069ca238efb1ec2
Thanks Howard. Actually whatever I do I keep coming back to where Bloomberg wants to charge me but not to worry!
Hi doublelutz
If you go to
https://www.bloomberg.com/acco...
You can receive email in your inbox for free.
Hope that works.
Regards
Michael
PS You have to scroll down a ways to get to the John Authers tickbox. His newsletter is well worth getting.
I read everyday and insights into his musical taste is wonderful.
Michael
Thanks Michael. I did scroll down and ticked on it and I could access a sample article but not the one on gold we are talking about today. I looks like I would have to pay at the moment. Not unreasonably for such long reports.
Sorry another comment put in wrong place.
Thanks, FREng,
Nice article.
BSV
Last week the Dollar continued to feel the pressure, falling 2% against most other currencies. In isolation this would be positive, but.... CRB index managed a gain of 1.6% which is actually a net negative in local currency. Oil, Copper, Lumber all struggled not reflecting anything positive about the cycle. Gold and silver were the stars... up 6% and 20% respectively. Bond yields ticked down. So not a good result for value as a style but equity markets were weak... FTSE 100 was down -2.6%, DAX -0.6%, S&P -0.7% and Nasdaq -3.6%. Weakness in Nasdaq outweighing all others in driving sentiment over the week which was deflationary and risk off. Naturally VIX ticked higher.
Tesla reported nos, achieved a profit for the 4th Q in a row, which most likely gets them in the S&P .... but the stock sold off 8.4%. The All Share Index was down 1.5% and my random list of an equally weighted, BP, Barclays, Rio, BT and IMB fell 2.5%.
So the macro drivers of value were weak but markets were also weak -- which hurt tech and Nasdaq most --- and the poster child of recent strength fell most of all.
My morning smallcap tweet:
Headlam (LON:HEAD) Supply@Me Capital (LON:SYME) Maestrano (LON:MNO) Zinc Media (LON:ZIN) Midatech Pharma (LON:MTPH) Sabien Technology (LON:SNT) Novacyt SA (LON:NCYT) City Pub (LON:CPC) Oncimmune Holdings (LON:ONC) River and Mercantile (LON:RIV) Regional REIT (LON:RGL) Location Sciences (LON:LSAI) K3 Business Technology (LON:KBT)
Headlam (HEAD) guides H1(June) rev down 31%. July up YoY. Talks on extension of covenant amendments. No FY guidance.
Supply @ME Capital (SYME) progressing two funding routes to achieve Inventory Monetisation. 1. Securitisation note programme. 2. Potential partnerships are progressing with two leading Italian banking institutions that intend to use the SYME platform to service their existing customers. Also Discussions with a large UK financial institution relating to a UK inventory monetisation pilot programme are progressing. Co working with a large, UK financial institution to arrange a first UK inventory monetisation pilot (up to 10 UK client companies) by the end of 2020.
Maestrano (MNO) Drone division appoints first North American distributor. Also client for Machine Learning platform in Japanese rail has approved progression to a new Phase 3 with an increased scope and term.
Zinc Media (ZIN) resuming previously paused production faster than forecast, wins £2.7m of new business. Closes loss making CSR business, which accounts for a substantial amount of the Group's losses. Increasingly likely revenues in July to December 2020 will be better than May guidance.
Midatech Pharma (MTPH) £5m placing and Broker Option for £0.75m at 27p, a 32% discount. Cash needed to progress Q-Sphera products. Expects to have cash to last to Q4 2021.
Sabien Technology (SNT) gives 6 month extension to Jan to complete RTO. Remains suspended.
Novacyt (NCYT) Significant new opportunities for growth. Launches mobile testing of covid. Study shows co's saliva test more sensetive than nasal swab. Has developed a testing panel (whats that?) covering the differential diagnosis of influenza A&B, respiratory syncytial virus (RSV) and covid. Finalising development of a two gene target test (as required by some countries) and expects to launch this by September..
City Pub Group (CPC) pleased with "encouraging performance" since reopening. LFL sales down 27% since 4 July.Traded profitably and generated cash due to cost cuts.
Oncimmune (ONC) Roche has exercised its option to increase the scope and value of the cornerstone contract announced in May. Value increase 'substantial'. End date still Nov.
River and Mercantile (RIV) Q4(June) fee earning AUM/NUM up 9.3%. FY is up 11%. Confident.
Regional REIT (RGL) Q2 Rent Collection Rises to 91.4%.
Location Sciences (LSAI) guides H1(June) rev up 43%. Has cash to until Q2 2021. Outlook "expect advertising revenues to return, albeit perhaps not to 2019 levels, however, with a renewed focus on local marketing, something which Location Sciences is ideally positioned to benefit from."
K3 Bus Technology (KBT) FY(Nov). Outlook "Despite the material uncertainty of the existing banking facilities expiring in March 2021, the Board is confident that the business will be in a position to obtain any necessary funding to support its working capital requirements...views prospects positively beyond the current period of uncertainty."
FTSE100 opens UP 8.0pts (0.13%) High: 6145.8 Low: 6084.0
Outputs down but cost efficiencies up
Cash Up, Net debt reduced, earnings per share increased 11%
Doubling EBITDA year on year to £13.3m with
Margins of 25%
No numbers attached
Could you look at HEAD if possible Paul? Thanks
Sure, will do.