Small Cap Value Report (Mon 28 Sept 2020) - FUL, GETB, RCH, VANL, BAR

Good morning, it's Paul here with the SCVR for Monday.
Here are the company updates which have caught my eye this morning;
Fulham Shore (LON:FUL) - casual dining chains - trading update
Getbusy (LON:GETB) - Trading update & completion of loan facility
Christie (LON:CTG) - AGM statement - sorry, I ran out of time to look at this, but it doesn't look very good, from a quick glance, so we're not missing anything.
Van Elle Holdings (LON:VANL) - AGM statement
Reach (LON:RCH) - Half yearly financial report
Brand Architekts (LON:BAR) - Final results
.
Timings - I need to be finished by early afternoon today, in order to prepare for the Mello Virtual online shares event this evening. They want me to discuss a few small cap shares with other investors.
Update at 13:56 - today's report is now finished.
.
Fulham Shore (LON:FUL)
Share price: 8.25p (up 4%, at 08:07)
No. shares: 609.6m
Market cap: £50.3m
Publication of audited accounts for y/e 29 March 2020 is extended from end Sept, to c. 15 October. It says that both AIM and Companies House have extended the deadline for filing accounts to end Dec 2020, so there's nothing to get worried about here. Other than that it's a bit slow to produce accounts, even allowing for covid disruption.
Here's a summary of today's update, with my comments;
FY 03/2020: revenues up 7.2% to £68.6m - this only clips the start of the covid lockdown, so not a terribly impressive growth rate. There should be many more opportunities to open new sites on low rents in the current situation.
Current net debt (at 25 Sept 2020) is low, at £3.52m. It says £7.46m undrawn on £25.75m, which suggests the gross positions must be as follows (my workings);
Cash: £14.77m
Debt: £(18.29)m
Net debt: £(3.52)m
Couldn't they have just provided a table with those numbers in, instead of the confusing text? Note to everyone who writes or edits RNSs: tables are always the simplest, clearest way to present figures.
It looks as if FUL has drawn down heavily on its bank facilities, and is sitting on a big cash pile, as a comfort blanket. I understand why some companies are doing this, but it usually does waste money on interest costs. Unless there's an offset agreement between credit & overdrawn balances, which there might be, I don't know.
10pm curfew - interestingly, FUL says this is not likely to have a material impact, because most customers eat before 10pm anyway. That's a useful point, as this measure is probably confined to hurting bars, rather than restaurants, maybe?
Eat Out to Help Out scheme - confirmed what we already knew, that it boosted business strongly in August.
Sites - 68 out of 70 are currently trading. If forced to close again, will once again pivot to delivery & takeaways.
FUL sees itself as a "successful survivor", which I think is fair comment, I agree.
My opinion - interesting points, but this trading update doesn't actually tell us anything about current trading! No LFL sales figures, not even an indication if they're still trading ahead of last year now that EOtHO has ended. I'm not at all keen on this selective type of disclosure. Trading updates should be in a standard format, and released on a reliable schedule (quarterly is fine, I think). Not ad hoc announcements of whatever snippets management & the PR company decide we can be told about.
Since it says nothing about trading vs market expectations, I can't go any further with this, which is rather disappointing, as this share is in my "looks interesting, but probably too expensive" tray. I've no doubt FUL is likely to be a successful survivor, but the mkt cap of £50m, for 70 restaurants, works out at £714k per site - that's far too high, in my opinion, given that a lot of the sites are smallish, and probably now on rents that are too high. However, both Franco Manca, and The Real Greek, are good formats, and well-managed, in my view.
Who wants to buy shares in a restaurant chain right now though? I would if it was dirt cheap, but it isn't.
Paradoxically, it's a successful chain like FUL that will soon be suffering, up against weaker competitors that are now doing CVAs in their droves, and hence securing lower rents than FUL. Hence I would rather look at chains that have restructured, and ditched all their onerous leases. Revolution Bars (LON:RBG) (I hold) is the latest to be looking into that option. Set against that, is the reality that covid looks to be weighing on the hospitality sector well into next year (Govt talking about 6 months restrictions), which is bound to hurt. Those operators which can survive, and restructure their leases through a CVA or pre-pack, could emerge very strong & highly profitable businesses with much reduced competition (temporarily anyway), once covid is over.
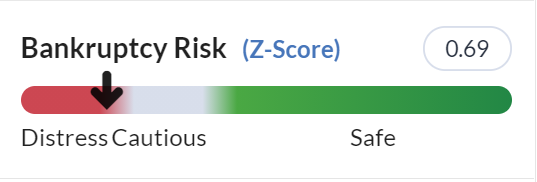
I note that FUL says it has a strong balance sheet. I often think this is management trying to convince themselves, as much as the market. Altman disagrees, saying there is some solvency risk;
.
.
If Altman is flashing a warning signal, I always check the last balance sheet. FUL did a small placing in August, so that would slightly improve things once it comes into the interim results in late 2020 or early 2021. FUL does have positive NTAV, but it's dominated by the fit-out costs of its restaurants. In reality, those fit-outs have little to no resale value, so are not saleable assets. If you write off those substantial costs, you're left with a threadbare balance sheet with too much debt for the size of business, in my view.
If we have a further, extended lockdown, then FUL wouldn't be the safest share to hold. If it can continue trading, then it should be fine. Don't bite my head off, I'm only flagging the risk.
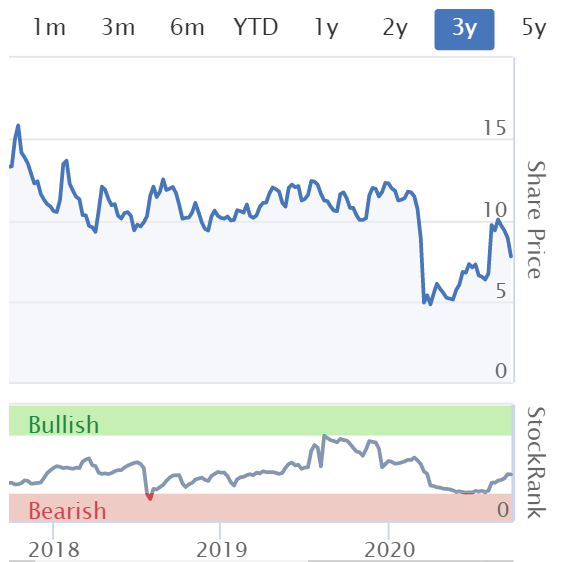
The other thing to consider, is that this share is thinly traded, and tends to go sideways for long periods. Would you have the patience to sit tight for years, with nothing happening? There is an opportunity cost to doing that, especially as FUL doesn't pay divis.
.
.
Getbusy (LON:GETB)
Share price: 77.5p (up 7%, at 09:58)
No. shares: 49.4m
Market cap: £38.3m
... and completion of loan facility - a £2m loan from Silicon Valley Bank. A lot of small tech businesses tell me that they cannot borrow money, because banks aren't interested. Well here we go, clearly you need to call Silicon Valley Bank, as they've funded this small tech business. I've heard that Barclays are also active in lending to small tech businesses with recurring revenues, on the basis that the facility could be repaid, in extremis, by slashing costs and letting the recurring revenues roll in to repay debt. Hence not as high risk lending as it might at first appear.
This is a 3-year facility, secured, with covenants, at a reasonable cost of 3.25-3.75% above LIBOR, plus arrangement fee. The key terms section doesn't seem to tell us what the repayment terms are, which is probably more key than anything else! Is it repayable by instalments, or all at the end?
I like GETB, it looks an interesting growth company, with 3 products, which all sound relevant to the circumstances we're in;
- Virtual Cabinet - the biggest division, and a cash cow, with very high profit margins. This funds the other parts of the business.
- SmartVault - making a small loss at the last interims
- GetBusy - looks to be a largely pre-revenue, blue sky project, which is currently loss-making.
I reviewed its interim results (6m to 30 June 2020) here on 23 July - impressively rapid reporting of the numbers, let's hope they're right!
Today's update -
The Group's performance has remained robust since the half-year.
It's all a bit vague.
SmartVault's annual contract value from new customers remains around 40% ahead of last year. We have started the investments announced in July in SmartVault product capabilities and growth to drive sustained increase in shareholder value over the coming years.
Is that the same as revenues being 40% up? It sounds ambiguous. At the interims, we were given a figure of 35% growth for total SmartVault revenues. I wish the company had given the same measure today, instead of apparently switching to a slightly different metric, or using ambiguous wording anyway.
Moving on to the biggest, most profitable division, we're told;
New business for Virtual Cabinet has also recovered and we are delighted to have secured an order from another Top 10 UK accounting firm.
Sounds positive, but I'd prefer some numbers.
GetBusy division - growing, but still small, so I think we can disregard this division for now.
Outlook - completely vague;
We continue to look to the future with confidence.
My opinion - today is turning into a frustrating day. Both companies I've looked at so far, seem to think it's OK to give shareholders vague, waffly updates, instead of what we should get - which is an indication of how the company is performing versus market expectations.
How are we supposed to value shares, and hence decide whether to buy/hold/sell?
Anyway, the update today seems to have reassured, as the share price is up 7%.
Overall, I still like this share, but currently don't know how to value it. The main value is clearly in the VirtualCabinet division, with nice recurring revenues & profits. Arguably we're getting the other 2 divisions in for free, so some speculative upside there. Quite interesting. I could be tempted to have a dabble here at some stage, because it has a decently profitable core division. That lowers the investment risk compared with a completely jam tomorrow, cash burning proposition, which is more normal with micro caps.
.
Reach (LON:RCH)
Share price: 76p (up 17% today, at 11:30)
No. shares: 299.3m
Market cap: £227.5m
This group used to be called Trinity Mirror.
Reach plc ('Reach', 'the Company', 'the Group'), the largest commercial national and regional news publisher in the UK, today announces its half-yearly results for the 26-week period ended 28 June 2020.
It's got a heading to tell us that profits are ahead of expectations. I like this. It's not waffle, it's telling us the most important performance measure - notably absent from the trading updates covered above.
Performing materially ahead of 2020 market expectations
There's lots to digest here, I'll just mention the key points;
Revenue down heavily, down 17.5% to £290.8m - to be expected, given the covid/lockdown situation
Note that Reach is making acquisitions, and growing digital, so there's an even steeper underlying decline
Amazingly, despite this, adjusted PBT has been robust, at £54.9m (H1 LY: £71.3m), down 23%
Are the adjustments reasonable? They seem to be genuine one-offs, e.g. a disastrous contract error on a property conversion, which has cost £15.5m
More restructuring, streamlining, cost-cutting. They look to be cutting to the bone now, as staff have had to take a 10% pay cut, which you can't keep doing, or there'll be nobody decent left after a while
Dividends - bit of a try-on here, with no cash divis, but a bonus issue - they must think shareholders are daft! If everyone gets bonus shares, then the share price just falls to reflect the increased share count, so nobody is any better off.
Balance sheet - still dominated by goodwill at the top, and pension deficit at the bottom
Pension scheme - is sucking out a lot of cash, and with interest rates now permanently low, the liabilities could be revised up again at the next actuarial valuation in March 2021. Asset values are also likely to rise too.
Digital revenues - are significant now. The dream scenario for shareholders, is if Reach shares become fashionable amongst tech investors, as a growth digital marketing business attached to a newspaper business, and a huge pension scheme. How likely is that? It's possible, but I'm not sure I'd attach much more than a 0-20% probability to it happening, but who knows?
My opinion - the low PER isn't very relevant, because it ignores pension scheme cashflows, and reflects the rapid decline of the print business. This year's covid impact could be next year's soft comparatives, so that might be a catalyst for some moderate excitement in spring 2021?
For me, this has to be filed in the "too uncertain" tray, and hence almost impossible to value.
It is surprising though, how strongly profitable it has remained, despite massive headwinds.
.
Brand Architekts (LON:BAR)
120.5p (unch) - mkt cap £21m
Small and illiquid, so I'll keep this brief.
Brand Architekts Group plc announces its final results for the 52 weeks ended 27 June 2020.
The key numbers are "continuing operations", because the main business was sold.
The numbers look lacklustre, with underlying trading c. breakeven. But note the large exceptional costs too. A bit messy.
Of most interest is the cash pile - net cash of £18.0m, so this share is really all about what is done with the cash. If management make a brilliant acquisition or two, then things could get exciting. If they squander the cash pile on something rubbish, then not so exciting.
Pension deficit - oh dear, I'd forgotten about this. There's a whacking great deficit, on the balance sheet at £13.2m, so that (over time) could erode a lot of the cash pile, and/or profits. The narrative says that the next triennial valuation is due, and could result in an increase in recovery payments. Given that the accounting deficit is very large for the size of the company, then the actuarial deficit would usually be larger still.
I think this rules it out for me. The pension scheme looks such a large potential liability, that I'd need to see up-to-date actuarial figures before knowing how to value the company.
My opinion - I'll park this to one side, and wait to see how new management performs, and what they do with the cash pile. Plus I'd need to see the updated pension deficit figures, which have the potential to be nasty, given the size of the accounting deficit.
Therefore, at this stage, it doesn't interest me, but will keep it on my radar and follow the future newsflow.
.
Van Elle Holdings (LON:VANL)
36.5p (up 3%) - mkt cap £39m
See my notes here from 21 Aug 2020, where I concluded this looks a nice asset-backed potential recovery share.
This sounds quite good;
Operations have continued to improve since the market update in our results announced on 20 August 2020, following the trend established from the low point in April 2020. Revenue in August was approximately 80% of normal pre-Covid levels, with further progress in all the Group's end markets except Rail, which we expect to show improvement in the second half as previously advised.
The Group's cash position remains strong at c. £12m. The Group is in the advanced stages of finalising an asset-based lending facility, which is expected to provide additional balance sheet strength and flexibility to enable the Group to support its growth strategy.
I've run out of time today, but I quite liked this share last time, so a reassuring update today certainly helps. One that readers might like to take a closer look at, if you like this type of business?
.
Sorry, I've run out of time now, because there's a webinar from Portmeirion (LON:PMP) (I hold) that I need to watch next.
See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
I recommend Phil Oakley's "How to pick Quality Shares" book. It's possible a good way to pick value shares in a depressed market but not a quick fix to a profit.
Pedant alert Getbusy (LON:GETB) the loan is with Silicon Valley Bank. They specialize lending to tech companies and are based as the named implies in Silicon Valley. They specilaize in lending to tech companies and have done since the mid 80's. So they have been around the block a couple of times. They issue quarterly reports on the industry which are worth reading if only for context about the tech industry. They certainly see something they like in Getbusy (LON:GETB) . A slight positive sign for the company though not necessarily a reason to buy.
SVB specialise in hardware not software businesses historically as they like to lend against assets....like a regular bank. Once upon a time they were really quite strict about the asset backing...I know first hand having approached them for loan for software businesses.
It would arguably be a more positive sign to have a loan from, say, dull old Natwest and on more favourable terms. That would mean they had persuaded Mr Boring that their business is exciting.
Getbusy (LON:GETB) is a great business, well run, good eye on how to grow etc ....but I'm still mystified why punters see today's news as a positive signal when clearly what it signals is that they are going to invest beyond cash on balance sheet and op cash flow produced. They just released a RNS saying that the risk has gone up but they provide no corresponding news on extra revenue sauce...if anything they deflate that by saying GetBusy product is going slow.
Like I said, investors lost their senses with some vibe-y stuff....
SVB have no compunction to lending to software business. There isn't that many hardware startups in Silicon Valley now a days. I just checked their quarterly FS in the loans that they extend under the "technology " umbrella 80% is to software companies.
I haven't looked a Getbusy all that closely so I can't really comment on the business perspective.
Hi mojo,
I'm enjoying your input of late, thanks.
Regards, Paul.
Hi arfournier,
Many thanks for pointing out my error, I've now corrected the article to say Silicon Valley Bank, not Silicon Bank. My handwritten notes have the correct name, but I clearly had a minor brainstorm when typing!
I very much encourage people to point out factual errors such as this, as I want to get things right. So you're not pedantic at all, your comment is actually very helpful. Thanks!
Regards, Paul.
I hold Getbusy (LON:GETB) from sub 30p.
I'm surprised that the share price is up today on fairly meh update that says steady as she goes in two established divisions (with the tone being slightly down in the most cash generative division Virtual Cabinet and up in the rapid going but heavy investment SmartVault) and things moving slowly in its cash consuming new eponymously named GetBusy division. The £2m loan from Silicon Valley Bank really just tells you that they are going to burn more cash short term as they chase growth on two fronts (SmartVault and now GetBusy!
Shows the insanity of investors at the moment whereby anything right vibe-y is bid. Perhaps some people like that SVB are providing the finance...as its a vibe-y bank.
I won't have time for a proper look until later, but the report from Reach (LON:RCH) looks encouraging (I hold - although less than I once did)
Still profitable in H1 (underlying) and nearly at a statutory level. Strongly cash generative too, as ever.
As a note of caution however, the exceptionals include yet more provision for phone hacking (£5m) which seems to continually grow.
in Q3 print declined by 20% YoY which is not that much worse than the underlying trend and digitial returned to growth at 12.9% (still not fast enough, but not bad under the circumstances of advertising still been suppressed).
At face value plenty of reasons to be cheerful; the market agrees +20% at the time of writing.
There is a results presentation webcast available and these are usually pretty informative so will take a look later.
I hold Reach also, results better than i expected. P/E still somewhere around 3, so all risks priced in and then some, in my opinion.
Thanks Gromley & DVB99, interesting comments on Reach (LON:RCH) and I note the share price is up strongly today, so I'll move that up the agenda, and look at it next.
P.
Hi Paul,
Thanks for covering Reach (LON:RCH) , always interested in your views. Even if we'll have to agree to disagree on the conclusions ;-)
Just a couple of clarifications :
1. The year on year figures are not influenced by acquisition as the last was more than 2 years ago.
2. Cash generation.
True but the cash generation is still pretty prodigious :
Those figures might be slightly flattered by the Covid schemes (or perhaps rather the PBT suppressed) , I will have to check. They do though reflect the continued impressive cash-flow from the business.
As you say, perhaps they will begin to be considered as a sexy digital business.
Good points, thanks Gromley.
Just to clarify, I really don't have a strong opinion either way on Reach (LON:RCH) - I can see merit in the bull case, so don't think we're particularly disagreeing on anything :-)
Best wishes, Paul.
Looking forward to seeing you tonight Paul at the Mello Monday, especially in the BASH as I hold SCS and Spectra which are two of the companies listed for your panel to discuss https://melloevents.com/
Paul, thoroughly enjoy reading SCVR every morning.
Any comment on the potential impact of this article on Boohoo (LON:BOO) relating to a $100m lawsuit in California over allegations it offered "fake" bargains i.e. heavy discounts based on inflated original prices?
"One of the three court claims was filed in April but was not disclosed to investors ahead of a £197m fundraising in May."
https://www.telegraph.co.uk/business/2020/09/26/boohoo-asks-dismissal-100m-pricing-case/
Am sure Paul will comment if time allows, but when I read the below I can not get very excited about it personally. Smacks of at best sour grapes, and worst desparation to attempt to discredit and de-ramp.
"A prominent short-seller accused the retailer of deflecting from the substance of the claim.Matthew Earl, managing partner of ShadowFall, which has bet on Boohoo’s share price falling, said: blah blah"
Bring on the Wed results....
Hi cdm1,
I saw that article about Boohoo (LON:BOO) in the Telegraph too. It's re-hashing of a previous story, so nothing new.
No, I don't have a view on it. Marking prices up, then marking them down again, is something retailers often do, and it's important to be on the right side of the law with that kind of thing.
Regards, Paul.
The fact that a short seller has a prominent quote in the article makes me think the entire story is a plant designed by frustrated short sellers to try and drive the price down. The entire class action suit might be (although this thought might be caused by my rampant paranoia and binge watching too many episodes of Billions over the weekend).
The market seems to be ignoring it for now - focused on the results due out Wednesday. If they hit their numbers, it will have another nice boost.
EDIT: Should have noted here - I don't hold Boohoo (LON:BOO) anymore - sold out on Friday as once it hit £3.60 it was above my personal valuation so no more margin of safety for me. Thanks to Paul and all here for the great information and pointing me to it - wishing you all the best with it going forward.
Nice trading update from Numis (LON:NUM): not unexpected given the amount of capital raisings since March that they had a hand in given price reaction this morning would appear Mr Market thinks they are priced about right.
Morning Paul, any thoughts on Brand Architekts (LON:BAR) would be welcome this morning after the release of their finals. Disappointing performance from the company, having reported a 17% decline in revenues, (-16% UK, -24%) internationally, with international sales being particularly affected by Lira depreciation and trade tariffs between the US and China. The latter is particularly concerning if the giant wotsit gets a second term in November. The big hope here is that new Execs can use the cash pile to pick up some good brands on the cheap, although it looks like Brand Architekts (LON:BAR) did not pick up on the hand sanitiser trend like Venture Life (LON:VLG)
The share itself is a special situation following the sale of the manufacturing business last year and has a net cash balance of around £18m (105p/shr). My stressed value of the balance sheet values the business at a break up value of £1.07, down from £1.36 at the interims, principally due to a 50% rise in the pension deficit, which is now £13.2m. I have also increased the haircut on the intangible assets to 20% from 15% due to the poor performance of the business and the review they are conducting on the brands, as well as writing inventories down by 25% to account for likely discounting to reduce stock. I have also written off the deferred tax asset.
The share price is deservedly down this morning and I continue to hold, but will look to pick up more sub-100p.
Just heard someone from the hospitality sector saying sales are down 33% since the 10pm curfew introduced. This when the sector had got revenues back to 75% following ‘eat out’ . If further restrictions are brought in in London and elsewhere it’s likely to be fatal for some businesses.
This comment needs a reference, unfortunately even if this is true, without some kind of supporting evidence this comments doesnt hold up.
I know the assistant manager of my local Wagamma (part of Restaurant (LON:RTN) ) and they have certainly been hit by the 10pm closure as they do have quite a lot of late eaters (haven't got a view on numbers at this stage). They also have contingency plans in place for the potential move back to delivery only, so clearly the mood music is not great.
Probably different for different types of venue / clientele though.
Odd that some would think effective closure at 9.30 - and total closure in some parts - would not impact revenues.
Kate Nichols, CEO of UK Hospitality, the trade body for the sector.
Thanks kgb1953, I read all sorts of forums and social media and its difficult to know what is factual, a bit of exuberance, or just made up. Because of that any comments which I can't validate, with figures or a reliable source, aren't much use, however helpful the poster might think they are.
Friends of mine run a small restaurant in the Highlands - v popular tourist area, especially this year.
They see a significant impact from the 10pm curfew - essentially they have to be 100% sure of locking the doors, with no remaining diners, by 10pm. So they are taking their last bookings for 7.30pm to be certain of complying.
As they are v busy, they are having to call their future bookings and try to shuffle everyone forward - so much so that evening bookings are now starting at 4.30pm, and are not so popular.
I suspect the issue for many pubs/restaurants is not the reduced hour of trading but the message it sends about going out to restaurants generally. My wife has decided that she doesn't want to go to any pubs/restaurants for a few weeks. We are not in a high risk category and we live in C London and traditionally eat out quite a lot.
HI paul, are you going to cover Brand Architekts (LON:BAR) today please? thanks!
Yes!
Hi everyone,
I would appreciate some thoughts on £VAL. Mr C has commented on trial success but the metrics on Stocko look terrible at 8!!
Also Bigdish (LON:DISH)?
A brief comment on the latest update from Bigdish (LON:DISH) - what it seems to be saying is that the (highly conditional) $5m investment from an unnamed Central European ultra-high net worth individual, will result in them owning 20% of a new SPV (special purpose vehicle, i.e. company) which will operate the BigDish platform in certain unnamed countries. All a bit vague still. However, it does sound interesting that this effectively seems to value the SPV at $25m, or £19.5m, which is almost 3-times DISH current market cap of c.£7m.
It's true that DISH has to pass a technology audit (although a lot of its tech has existed for several years already, based in the Philippines), and come up with a marketing plan. It says today that "restaurant acceptance" is not precisely defined, which sounds a potential problem. I haven't seen any of the detail of the Letter of Intent, but the way I look at situations like this, is that it sounds as if the investor could easily pull out, if they change their mind. So I'm not sure how much reliance we should place on this deal just yet?
The main thing is that we don't seem to be at risk of imminent dilution, which is my main concern with my shareholding in DISH.
Remain highly speculative, but interesting! (I hold)
Regards, Paul.
Hi Sunny 1978,
Valirx (LON:VAL) is what I class as a 'Jam Tomorrow' company. It might promise to offer you something sweet and tasty in the future but there are no guarantees. In my opinion, there is nothing supporting its share price, only fresh air.
Regarding Bigdish (LON:DISH), I personally wouldn't buy shares in this company because I want to be able to sleep at night. Some people can get by on an hours sleep, I like eight hours.
Hi Paul,
I’m really enjoying reading your daily reports – very insightful and all with a nice touch of humour. I joined Stockopedia a few months ago, having dabbled in the markets for a long time but with limited success. My small business is now so small as to be invisible, so I can spend a lot more time on investing. The postings by other contributors are also very interesting.
DYOR we see everywhere but it’s not that easy…Having ploughed through a few company reports and lacking accountancy expertise, I find I am both not much wiser and also in need of a drink. Thus, it is so useful to get your views on companies.
Does anyone have any thoughts on which small caps might go up significantly if/when an EU trade deal is concluded soon?
Rogerh,
Maybe I could offer some advice having spent several years trying to find a process that worked and I could understand. Yes DYOR is very difficult when you don't know how and it will take time to build your own process. which will continue to evolve as you learn. I personally base my investment on the principal of "companies that start to outperform tend to continue to outperform". Like you, I am no accountant. I struggled with understanding them and then gave up. When I look at a company, I always look to see if Paul has reviewed it at any time in the past. What I want to know from Paul is are the accounts honest. Paul really adds value in his ability to spot accounts that superficially look good but have hidden issues. I have no hope of doing this. I don't follow his tips or follow his buys. You can but he is not always right. I like companies beating expectations, paying down debt rapidly, growing cash pile, paying maiden or special dividends, paying off pension liabilities and with the right hand side of a daily chart higher than the left hand side. Read Robbie Burns (Naked Trader) book to get started. There are some good basic ground rules you can follow.
What I never do is take binary bets on things like Brexit negotiations. You cant know what is going on from reading mainstream media. I am mostly cash or invest in companies that wont see much effect. Red or Black type bets like this are not a good strategy.
Re: Analysing company accounts:
Roger,
I recommend Phil Oakley's free series of articles on analysing accounts: https://knowledge.sharescope.c...
I hope Stockopedia will forgive my posting a link to a rival website.
Phil Okley is a genius!
I have some accounting background and I think with investing it is important to have some understanding of accounts otherwise it is going to be difficult to get a proper understanding of the company. That said I have not read the last five years of reports and accounts of every company in which I am invested. Heresy if heresies .
I think there are courses, I believe Graham Neary who used to write here runs a one.
My main source of learning has been reading and my list is at:
https://investing4value.wordpr...
I have read most but not all.
I would start with Intelligent Investor, Zulu Principle, Naked Trader, Buffett Letters and go from there.
I wouldn’t worry about macro calls like Brexit/US election etc, just too hard. Try find companies you understand, that are wonderful companies and buy them at a reasonable price. Finding them of course is the tricky part!
Many thanks to jht76, Ed_miller and MichaelFBS for the helpful feedback
Hi Paul
As it seems so quiet out there today - perhaps interesting to see the news update from Kenmare Resources (LON:KMR) this morning - just successfully moved a giant 'mining machine' 23 k to a new site!
bohenie, Paul doesn't cover resource stocks since he has no specialist knowledge on the sectors and feels he cannot provide a fair assessment. A former writer on this site, Graham Neary runs a commentary website called Cube Investments and on there is Joel's Resource Report which might serve your interest? Otherwise feel free to initiate a discussion with other readers by asking for comments or maybe creating your own post in the "Discuss" tab?
#INS.
Morning Paul,
My tweet this morning regarding interims:
Board are considering a number of M&A opportunities.
Rev up 20%
PBT 1.9m (H119 0.4m)
Resilient thru C19
Cashed for M&A
Highly scaleable well-run biz
Top 5 holding
https://www.investegate.co.uk/instem-plc--ins-/rns/half-year-report/202009280700062155A/
Michael
I also hold Instem (LON:INS) - The interims look positive with good revenue and profit growth, plus £15 million in the bank to fund potential acquisitions. Particularly interesting is the 338% increase (from a very low base) in the Informatics division, which management seems to believe is the strand of the business with greatest potential.
The CEO says, A number of bolt-on acquisitions and more substantial targets have already been identified and are now being progressed - aided by the impact of Covid-19 on certain business valuations.
Agreed @sturat1.
I am pleased with these results too.
My morning smallcap tweet:
Supply@Me Capital (LON:SYME) ULS Technology (LON:ULS) BigDish (LON:DISH) Fulham Shore (LON:FUL) Angle (LON:AGL) Open Orphan (LON:ORPH) Mears (LON:MER) Genedrive (LON:GDR) Van Elle Holdings (LON:VANL) ValiRx (LON:VAL) GetBusy (LON:GETB) Surface Transforms (LON:SCE), Christie (LON:CTG)
Supply@ME Capital (SYME) Guides FY(Sept) rev £2.3m and no of Client companies 142 (H1:97). Guides FY21 rev £27m. [SP=0.49 Cap=167m]
ULS Technology (ULS) CEO scarpers, immediate effect. He is thanked. Co has found a replacement but name is a secret. So when did CEO resign? Trading: "current volumes underpinning management's confidence of continued improvement in Q3." [SP=52.97 Cap=34m]
BigDish (DISH) clarifies possible funding RNS. "SPV would be the recipient of the $5m of funding. The SPV would be a separately incorporated company that would operate the BigDish platform in certain international markets. BigDish would own 80% of the SPV." [SP=1.87 Cap=7m]
Fulham Shore (FUL) delays FY by 2 weeks to mid Oct. Guides FY rev up 7%, net debt £3.52m. 68 out of 70 restaurants are open. Believes 10pm curfew will not have a material effect on dine-in business. [SP=8 Cap=49m]
Angle (AGL) completes FDA submission for Parsortix PC1 system for use with metastatic breast cancer. Uncertainty over the timing of the process and its ultimate success. [SP=53 Cap=92m]
Open Orphan (ORPH) wins £4.3m contract to conduct a human viral challenge study. [SP=17.03 Cap=114m]
Mears (MER) completes exit from domiciliary care, with the disposal of its Scotland Domiciliary Care for £2m + £0.5m deferred. [SP=112.7 Cap=125m]
Genedrive (GDR) £1m loan note conversion at 1.5p. [SP=118 Cap=61m]
Van Elle (VANL) AGM stmt: Aug rev down 20% on normal level "with further progress in all the Group's end markets except Rail, which we expect to show improvement in the second half as previously advised." [SP=34 Cap=36m]
ValiRx (VAL) Phase 1/2 trial of its lead asset VAL201 cancer drug "shows it has potential to be a safe and well-tolerated drug" but does not comment on the 54.5% response rate. [SP=53.5 Cap=31m]
GetBusy (GETB) trading 'robust'. SmartVault's annual contract value from new customers remains around 40% up. Gets £2m loan facility with Silicon Valley Bank. [SP=75 Cap=37m]
Surface Transforms (SCE) H1(June) rev up 55% (as guided) to £902k. Pretax -£1.45m (-£1.52m). Guides FY rev £2m. Notes recently RNSd large win. [SP=42.22 Cap=65m]. I hold.
In line: Christie (LON:CTG)
Old Site - The Early Morning News - Monday 28 September 2020
New Site - The Early Morning News - Monday 28 September 2020
This is a great resource and one I look forward to seeing each morning. Great work.
Bryan, if you look at Paul's commentary on Revolution Bars (LON:RBG) over the past week, he does explain it.
explain Paul RBG and how a CVA works
Check out Robert Goodwin post on Fridays report, posted Sunday.
Even this numpty understands it.
@GloucesterBob I thought you meant that I was numpty - you would probably have been right! Thank you for mentioning Sunday's post, I thought no-one would see it as I wrote it quite late!
Explain Bryan cannot be ar5ed to complete a coherent sentence / polite question?
Hi Bryan,
If you click on the 'Discuss' tab and scroll down to Fridays SCVR you will find Paul explains very well how a CVA works and the effect it will have on Revolution Bars (LON:RBG) and its shareholder's holdings. I don't hold RBG because I like to sleep at night. However, what would be interesting to hear from Paul is..... What would happen if RBG, or any company for that matter, went down a Pre-Pack Administration route, how would that affect shareholders??
Would shareholders get wiped out, whereas with a CVA shareholder's holdings remain in tact??
It would probably wipe shareholders out if the whole plc went in to Administration.
They might be able to put an operating subsidiary into administration and buy it back if they have a limited company within the corporate structure.
Hi Richard,
Thank you for your response. When I posted my 9:11am comment today the previous links from your good-self, GloucesterBob and johnsmith68 hadn't appeared. It was only after I had clicked on 'Add Reply' that the 3 links materialised. I have since read your excellent Sunday post and it makes for very good factual reading. Furthermore, it perfectly answered my question. Keep up the informative posts.