Small Cap Value Report (Mon 29 July 2024) - QTX, TRI, DOTD Movers: SHI, TRAK, PFC, RKT

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
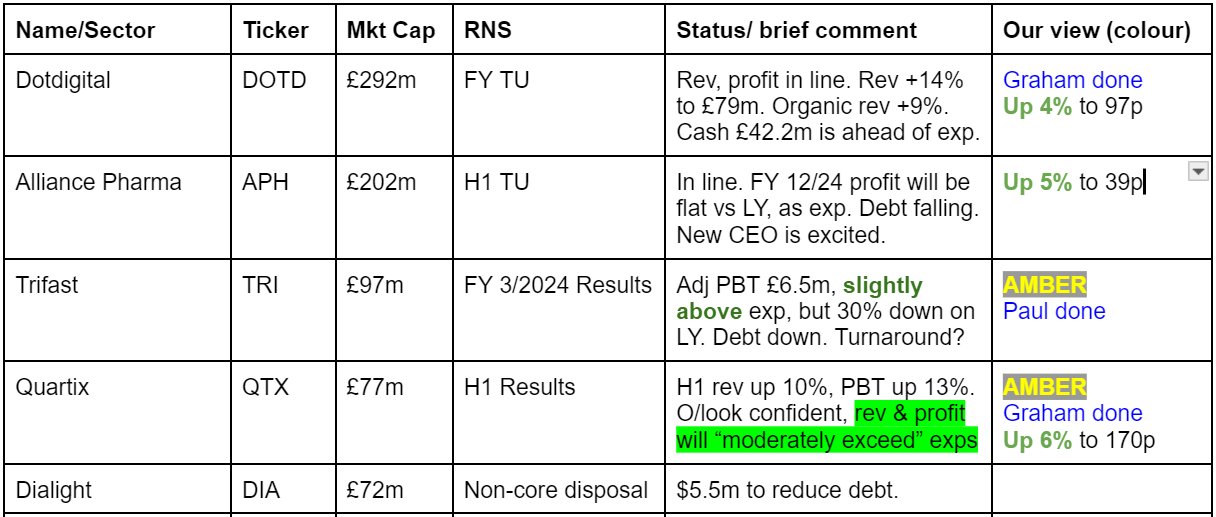
Companies Reporting
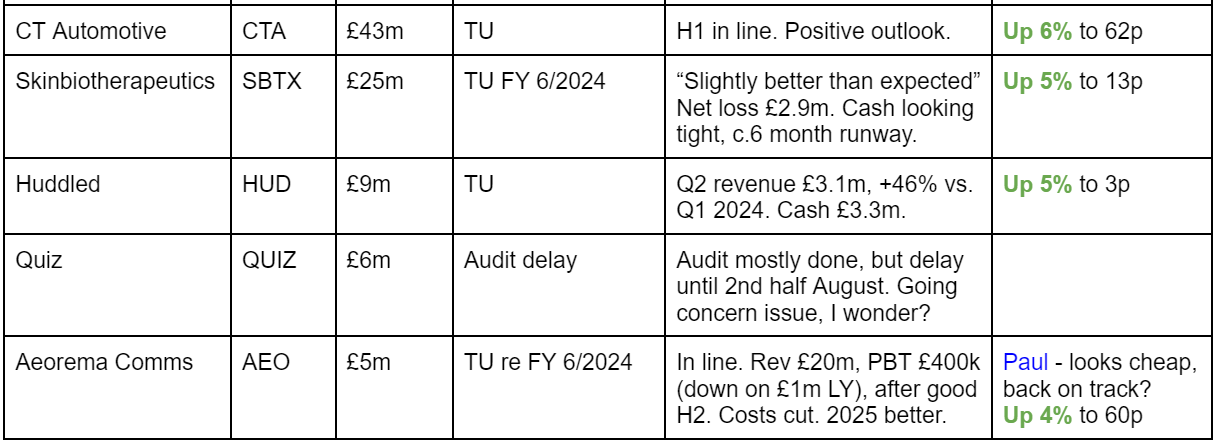
Other mid-morning movers (with news)
SIG (LON:SHI) - down 7% to 24.5p (£290m) - Sky News says this building materials group is lining up a substantial equity raise. Paul - AMBER/RED
We covered its profit warning here on 24/6/2024, concluding that with soft trading, a weak balance sheet, and no divis, the shares had little appeal. With the risk of discounted placing (on unknown terms) now added into the mix, I will definitely be avoiding this one for now.
Trakm8 Holdings (LON:TRAK) - down 12% to 7.5p (£4m) - FY 3/2024 Results - Paul - RED
Serial under-performing telematics minnow.
Revenue down 20%, and moved from £0.3m adj PBT last year, to £(1.3)m this time. Outlook comments sound mixed. Board says they’re confident revenues & profits can improve. Good job, as they’re probably going bust if they don’t show an improvement. Balance sheet looks horrible, with NTAV negative c.£(6)m.
Paul’s view - is the equity worth anything? I’m struggling to value this above nil. Heavy dilution or insolvency look the most likely outcome, based on these lousy numbers.
Petrofac (LON:PFC) - down 18% to 18.2p (£95m) - Guarantees & loan forbearance - Paul - RED
Petrofac shot up 67% on Fri afternoon on news of deals with a big customer over guarantees, and extension of forbearance agreement with bondholders. We already knew PFC was dangling by a thread, in serious financial difficulties. So this is a high risk special situation, which could end up with a debt for equity swap, or even insolvency. Or the upside case could see equity multibag. One for specialists only, you really need to know what you’re doing with this type of share. I have to mark it RED due to the high risk, but I have no idea what the outcome is likely to be.
Reckitt Benckiser (LON:RKT) - down 8% to 4,109p (£28.6bn) - Legal action - Paul - No view.
Large cap consumer goods group. Shares are taking a battering this year, down a lot to a 10-year low apparently. The problem seems to be large numbers of legal claims in the US over problems caused by baby milk products, and an adverse judgement recently. I wonder if the 4.6% dividend yield might come under threat, if legal costs escalate? Let’s move on, I’m only briefly flagging a large % mover, not doing any analysis.
Summaries
Quartix Technologies (LON:QTX) - up 9% to 175p (£85m) - Interim Results - Graham - AMBER
This telematics company has achieved some upgrades to its earnings expectations for this year and next year, thanks to solid growth in annualised recurring revenue and good cost control. I can see bull and bear arguments here - can motivated, previously successful management justify a high earnings multiple?
Trifast (LON:TRI) - up 2% to 72.5p (£98m) - FY 3/2024 Results - Paul - AMBER
Some useful improvements here compared with my last review after a profit warning in January. A turnaround plan seems to have only stabilised things so far, with more progress expected medium term, hence nothing much of interest to grab my attention shorter term. Debt & inventories are usefully down. I've upped my view from amber/red to AMBER, given the progress so far. We'll keep an eye on it, but nothing has excited me as yet.
dotDigital (LON:DOTD) - unch. at 93.2p (£286m) - Trading Update - Graham - AMBER/GREEN
A solid update from this provider of online marketing tools to businesses. Last year’s acquisition has performed well, and the company continues to benefit from a large cash pile and repeat revenues from a wide variety of corporate customers. However, I’m inclined to think the attractions could be priced in here.
Paul’s Section:
Trifast (LON:TRI)
Up 2% to 72.5p (£98m) - FY 3/2024 Results - Paul - AMBER
I’m happy to look at this fastenings group with fresh eyes today. I took a dim view of its profit warning here on 22/1/2024, concluding amber/red, since forecast profit for FY 3/2024 was almost cut in half. I also noted that inventories seemed excessive, and the outlook weak. Although the balance sheet protected the downside, being quite strong. Let’s see if things have improved since?
Note from our archive here, that there are 4 fund manager interviews from Paul Hill which mention Trifast, including the effective turnaround specialists Harwood. I can remember walking around ASDA and listening to the podcast version of Richard Staveley, where he explained the turnaround potential. Although I’m still not clear what has actually gone wrong to begin with. Competitive pressures, presumably? I wouldn’t imagine that a fastenings maker has much pricing power, but could be wrong. The main reason for the profit warning seems to have just been reduced demand. The inventories were much too high, at £83m (as at 30/9/2023), c.6 months cost of sales, which could contain slow-moving or obsolete items possibly?
FY 3/2024 Results - which were delayed by the audit almost a month, something that seems fairly common these days.
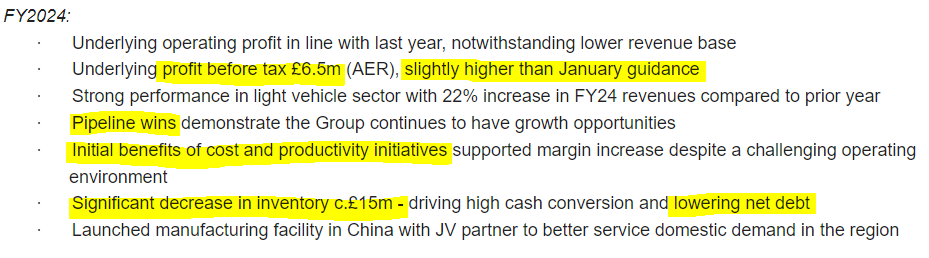
This looks OK, in particular inventories coming down -
Outlook - I like the format of bullet points here, but there’s nothing particularly exciting here - it sounds more like sorting out basics that shouldn’t have deteriorated in the first place -
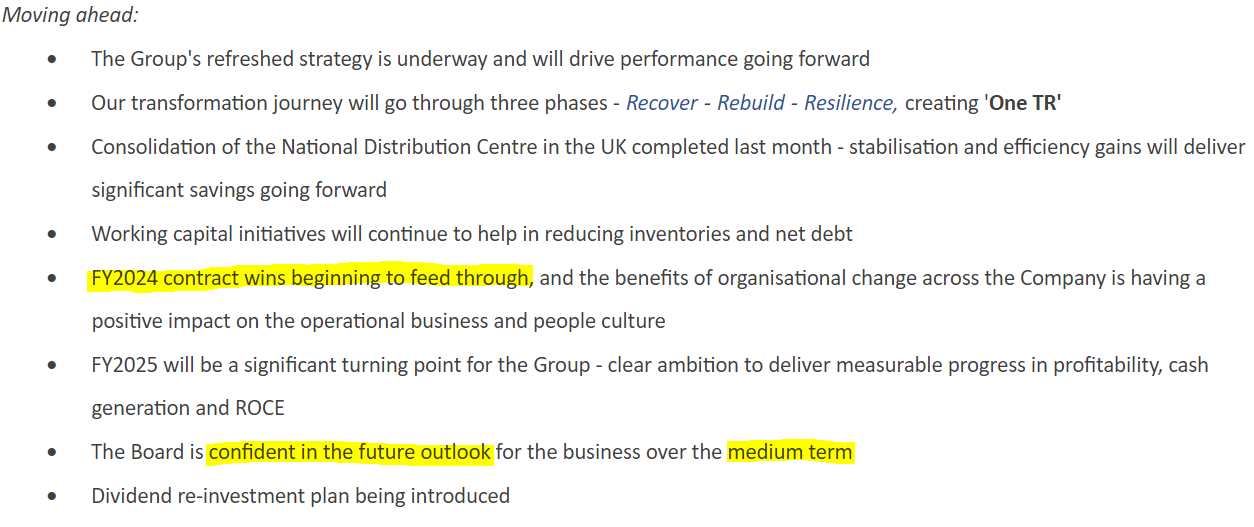
Medium term is usually code for nothing much good happening in the short term.
More outlook comments -
“Whilst the macroeconomic environment continues to present short-term challenges, current trading remains in line with management expectations. We continue to have a strong focus on cash generation to reduce net debt and working capital and are driving EBIT improvement through margin management, focused growth, organisational effectiveness and operational efficiency.
Operationally, we have been setting ourselves up for growth when the market recovers by rightsizing the business through a restructuring programme, the completion of the Atlas Project and the consolidation of the NDC…
We believe there is significant scope for improvement in the mid-term and are confident we will be more profitable, effective and efficient in FY25.
The macroeconomic and geopolitical environment remains volatile, and we continue to be challenged by inflationary pressures. We are confident we have the right strategy to capture margin upside and deliver sustained growth. We believe there is significant opportunity to return performance to historic levels.
Trifast has made strong progress in managing working capital to reduce its net debt through working capital initiatives and remains focused on driving profit initiatives to improve our margins.”
A big fall in net debt by £17m to £21m should mean that finance costs reduce, as PBT dropped 30% mainly due to higher finance costs in FY 3/2024 vs LY. Assuming it’s a permanent step down, and not just year end window-dressing that quickly reverses.
Balance sheet - this is looking good. NAV £124m, less intangible assets of £36m, gives NTAV £88m, getting close to the £98m market cap.
Overall I think shareholders probably have little to worry about re dilution or insolvency. Although it would be worth checking the terms, covenants, etc of the bank facilities. I’ve just had a quick look in the Annual Report, and there’s quite a bit of detail about bank covenants, which look as if they’ve been amended, so there could be an issue here to at least check the detail properly and make sure you’re comfortable with downside risk if trading were to deteriorate further.
Going concern - you have to click through to the full Annual Report, on Trifast’s website, and I confirm it gives a clean going concern statement, which the auditors have signed off.
Paul’s opinion - I can’t shake off the view that this just doesn’t look a particularly good business, so why would I want to own part of it?
Turnaround efforts sound like they may have some potential, but why did it get into this position where turnaround efforts are needed? Is it a badly run business that’s slowly turning into a better run business? Getting back to previous higher profit margins isn’t likely to be easy - those margins have clearly fallen due to competitors squeezing TRI. What other explanation is there?
If I invest in industrials, I want something with pricing power, and something unique. There’s not any evidence of that with Trifast, so it has to execute perfectly, which doesn’t seem to have happened.
Harwood have bet big on it, with 14.1%, plus Slater (13.3%) and Schroders (9.8%) are also big holders. So who am I to disagree? Maybe there’s a trade here for a recovery, but I wouldn’t want to own this share long-term.
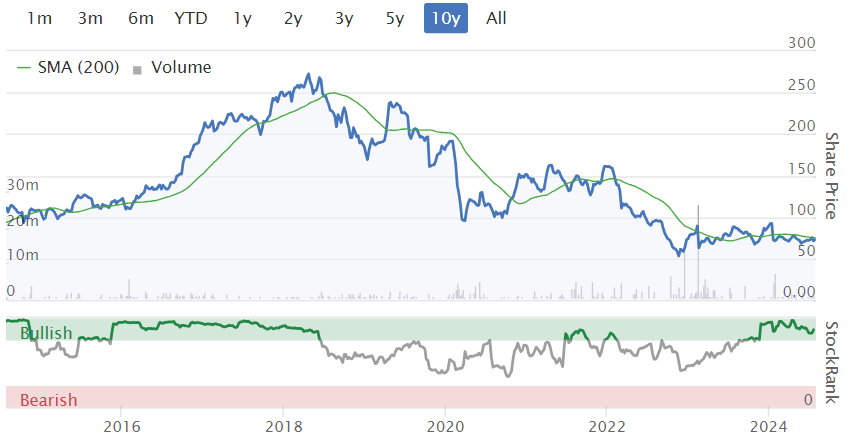
Zooming out to the 10 year chart below, a lot of shareholder value has been destroyed by TRI. Although it has paid decent divis along the way. It could be tougher than people think to turn this ship around, so for me, I’m not convinced at this stage. AMBER is the best I can get to, but that’s a notch up on last time, because trading hasn’t got any worse, it’s still profitable, and inventories/debt have both come down decently.
Just to remind everyone, I am not predicting what the future holds. My view is just an assessment of the facts, figures & forecasts, as of today. From today things start changing.
Notes from Zeus & Cavendish are available on Research Tree. Zeus leaves forecasts largely unchanged, just some minor tweaks.
Graham’s Section:
Quartix Technologies (LON:QTX)
Up 9% to 175p (£85m) - Interim Results - Graham - AMBER
Quartix Technologies plc (AIM:QTX), a leading supplier of subscription-based vehicle tracking systems, analytical software and services, is pleased to announce its unaudited results for the half year ended 30 June 2024.
It has been quite some time since I’ve covered this one, as Paul normally does it. He was “AMBER/GREEN” following the AGM update in March.
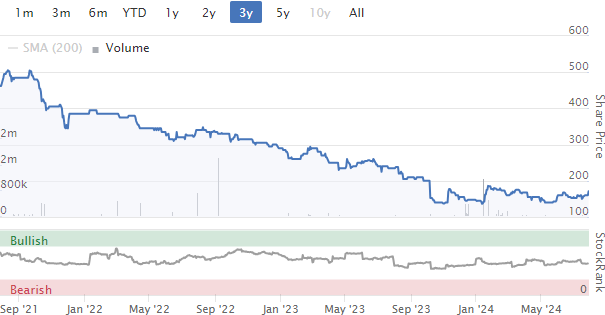
Its market cap has been demolished in recent years:
Today’s interim results show signs of progress:
Revenue +10% to £16.1m
Adj. EBITDA unch. at £2.7m
Operating profit +13% to £2.7m.
Annualised recurring revenue (ARR): often the key metric for subscription-based businesses, this is up 11% year-on-year to £30.94m.
Key performance indicators: aside from ARR, the other KPIs that stand out are the “fleet subscription base” (number of vehicle tracking units) up 12%, and the average subscription price down 1.3%.
I previously noted some softness in the pricing here, and was concerned that telematics products were getting cheaper so quickly that it negatively affected the investment case for companies in the sector. The average subscription price falling by 1.3% is hardly a good thing, but it fell by 4.6% a year ago!
According to the broker Cavendish, Quartix successfully implemented its first price increase across most of its customer base during H1. So while the average price charged did fall during the period, perhaps pricing has reached a bottom for now?
Executive Chairman comment by co-founder Andrew Walters:
"The Company made very substantial progress in the first half of the year: new subscriptions increased by 13% compared to 2023 and this led to record growth in annualised recurring revenues ("ARR"), which increased by 11% to £30.9m over the past year. Two thirds of this increase in ARR was achieved since January 1st…
The issues faced by the Company in 2023 have now been put behind it, enabling it to refocus strongly on its core business and to structure for further growth.
The Board is confident in the outlook for the remainder of the year and now believes that both revenue and profit will moderately exceed market expectations*
Estimates: Cavendish have upgraded the revenue forecasts for 2024 and 2025 by 2%. They also nudge up the gross margin forecast to 69%. With costs expected to remain under control, the adj. EBITDA forecasts for 2024 and 2025 are raised by 7% and 6% respectively.
Graham’s view
It has been some time since I’ve studied this one, but familiar themes are apparent.
1. Pricing power - does Quartix have it? If it doesn’t, that makes the long-term investment case so much harder to make. There are mixed signals on this front, with ASP falling despite the implementation of a rare price increase. My impression is that there are few barriers to entry in the telematics space, and that competition does keep a lid on prices.
2. Valuation - Quartix tends to trade at a rich earnings multiple, and that can also makes it harder to have a rosy outlook on the prospects for investors.
Last night’s earnings multiples:
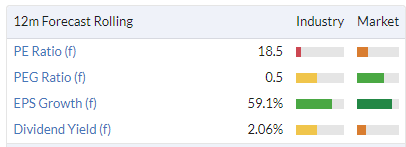
As readers will know, I am sometimes happy to look past earnings multiples and instead focus on cash-adjusted price to sales or price to ARR, depending on the circumstances.
For a true software-based business, I can use a cash-adjusted price/ARR multiple, instead of or in addition to the traditional earnings-based multiples.
Net cash at Quartix is modest at £2.7m, so the enterprise value is about the same as the market cap, £82m.
ARR is £31m, so the ARR multiple is less than 3x.
That would be considered very cheap in a US context for a subscription-based software business.
However, Quartix is both a hardware and a software provider. It does not earn close to 100% profits on incremental sales. For this reason, I’m not sure if I can apply NASDAQ-style valuation methods to it.
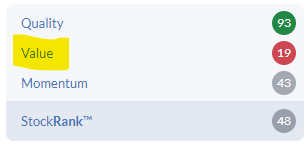
On traditional profit measures, it remains on the expensive end of the spectrum to my eyes. Stockopedia computers agree with me:
Hopefully there will be some operational leverage to boost profits in the years ahead - the company is doing its best on that front by controlling costs. Top-line revenue is growing at a good but not a rapid rate.
Management does win points for bulls here, as the company’s founder and largest shareholder is at the wheel again. The company is likely benefiting from highly motivated and passionate management at this time.
Overall, I’m more comfortable with a neutral stance here, as I think there are good arguments on both sides of the debate.
dotDigital (LON:DOTD)
Unch. at 93.2p (£286m) - Trading Update - Graham - AMBER/GREEN
This is a company providing online marketing tools, although it uses more impressive terminology than that:
Dotdigital Group plc (AIM: DOTD), the leading SaaS provider of an all-in-one customer experience and data platform (CXDP), announces a trading update for the year ended 30 June 2024 ("FY 2024"). The trading performance reported in this statement is based on unaudited management accounts.
Today’s full-year update is in line with expectations: here are some of the key points.
Revenue +14% to £79m
Organic revenue +9% at constant exchange rates.
Cash of £42m is ahead of expectations.
The adj. PBT estimate for the year is £16.4m (last year: adj. PBT of £15.4m)..
Last year, we covered the acquisition of a company called “Fresh Relevance” by Dotdigital (here), that provides complementary products to many of the same customers as Dotdigital. The integration of Fresh Relevance is “now complete and driving pipeline growth”.
Bigger clients are being attracted by the combined group, although the company notes that there have also been “elevated levels of churn” due to economic pressures on smaller customers.
Outlook is confident:
The Group enters the new financial year with continued positive momentum. Wider macro global conditions remain challenging, but due to the diversity of our revenue base and the low dependence we have on individual customers, the impact of this has been limited. We are seeing growing evidence that the investment we have made into our product offering is yielding results, particularly in respect of average new logo values and pricing power.
Graham’s view
I have generally taken a positive view on this one, citing its large net cash position, track record and quality.
It remains a company of exceptional quality, at least according to the numbers, although that is arguably priced in at these levels.
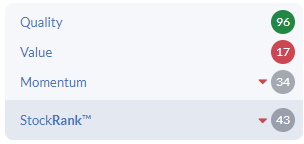
Admittedly, this sector does tend to trade at rich multiples:
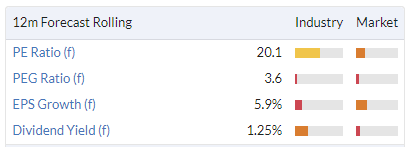
Overall, not much has changed since I covered this one last time. It continues to execute its plans and make progress.
However, growth in adj. PBT is perhaps a little more muted than I would like at this valuation. It has only grown profits according to this measure by about 6% in FY 2024, despite the acquisition made and despite revenue growth at a double-digit rate.
For FY 2025, broker estimates suggest growth in adj. PBT of c. 10%.
Therefore, despite the company’s impressive cash pile, I think I need to adjust my stance on this stock down by a touch. I’m going AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Trifast (LON:TRI) Did anyone watch the investor update this week? The question is whether the recovery plan is sensible, believable and whether management will deliver on the margin improvement targets. The goal is clear (ie. return to >10% net margin) and they have clearly put a lot of work into analysing the situation and defining an improvement plan. I thought the strategy seemed sound, so i't all down to execution now. The CFO seemed a bit nervous to me though, which made me a bit nervous too!
Ooh - after hours announcement from 4Basebio (LON:4BB) that they’ve had a £40m investment from 2 institutions (inc M&G) at a premium to existing share price = 1500p
Looks like a bit of a secondary share sale by founders too. That’s no bad thing given the amount the main holders own though isn’t going to add to liquidity as these will both be long term holders.
Very interesting - I had said I thought they would move away from debt funding to equity at these levels despite directors protestations but am pleased they did as I wanted to see them well funded given the opportunity.
Good to get some validation over valuation and opportunity too. Gives me increased confidence..
Wonder if it will have much effect on share price.
Watkin Jones (LON:WJG) Build to rent sector starting to pick up again..? Although this sale is already factored into Watkin's guidance admittedly.Hopefully signs of better trading conditions to come?And nice to see a decent big national bank's investment fund interested enough to invest.Wonder if it was set up especially for a Labour government's policies?Hopefully rates will start to be cut sometime this year.
A housing impact investment fund run out of Lloyds Banking Group has snapped up a new 397 bed purpose-built student accommodation (PBSA) development in Stratford in a deal worth nearly £300m.The Housing Growth Partnership,, which is a joint venture between Lloyds and Homes England and was set up increase the supply of affordable housing, made the forward purchase from London-listed Watkin Jones, one of the UK’s leading build-to-rent specialists.
I wonder if any future proposals on raising CGT rates will encourage users of platforms to go the Spread Betting/CFD routes to mitigate it.
Might be good for platforms offering those services?
Don't most serious cgt gains come from property and business sales annually as CMC Markets (LON:CMCX) and similar platforms always warn that the majority of punters lose money.It's not effecting isas, where naturally big cgt gains can be accrued over years, is it?
The £20k a year cap into a ISA means that some of us have spread investments between direct share accounts and ISAs.
My plan, when I retired, was to use both my ISA and my CGT allowance for retirement income. The reduction to CGT allowances over a relatively short period has left me with an island of investments that I’ll probably not be able to recover before death without incurring a substantial tax liability!
Many of these investments have been owned for 20 years or more and CGT is payable without consideration for inflation.
We used to have a system where capital gains were taxed on the same rates as income, but gains were index adjusted. A better system.
To be fair I didn't say use of Spread Betting platforms was good for punters.
Paul was a big user of such systems, I understand, until he saw the light.
i would imagine that serious players can mitigate tax by using spreadbetting - so i wouldnt pay too much attention to then obvious fact that most lose - there must be an eleemnt of sensible "losers". Note the reality is those simply paying acceptable margin are being classsed as losers here !
Would people rather lose 5% to the spreadbetting company or 20% in extra cgt - so i would say there is decent potential for increased use of spreadbetting if cgt rates go up - unless they arent specifically taxed extra - so perhaps there is the risk of these copmpanies being taxed more highly ?
Serica energy
Like most oil and gas explorer in the North Sea, this one has been left on the hook for the last few months. No one is interested in the sector , that is what I thought until I read this article in the FT. Carlyle is still investing in the sector
https://www.ft.com/content/bbb...
Recent government comments on not forcing homeowners to rip out their gas boilers and the tone of last week's parliamentary energy debate confirm gas will remain a key part of the UK's energy mix for the rest of this decade and beyond.
I hold and will keep banking the dividends unless there is an unexpected development on hydrogen costs or other base load fuel for the grid.
Interesting comments from you this morning Paul Scott on Trakm8 Holdings (LON:TRAK) where the biggest holder is either Microlise (LON:SAAS) or Mr Raza, the CEO of Microlise (LON:SAAS) depending on where you look on Stocko for the information.
He has held that stock holding of around 20% for some years and is a NED at Trakm8 Holdings (LON:TRAK) too.
Perhaps he will seek to integrate Trakm8 Holdings (LON:TRAK) into the much more successful Microlise (LON:SAAS) though why he would want to do that at this stage, I don't know.
I don't have the technical knowledge to know whether there is some overlap between the two companies, whether Trakm8 Holdings (LON:TRAK) has offered Microlise (LON:SAAS) some cheap cross over of sales to additional different customers etc.
I would be interested to know if any other readers here have anything to add, including yourself, Paul.
Loungers (LON:LGRS) – growth at a very reasonable price
Author reckons it is compellingly cheap relative to the growth path ahead. Full write-up:
https://sweetstocks.substack.c...
I just read this. Interesting read and quite compelling but I am struggling to reconcile his much higher ROCE to Stocko's figures.
Future (LON:FUTR) I see the CFSO - chief financial and strategy officer - has stepped down. Despite serving for 8 years she is not thanked. Should I take that as a red flag?
No, I don't think so. It was announced a while ago she was becoming CEO of Taylor and Francis
Thanks Rupert, I missed that amongst all the share buyback notices.
Reckitt Benckiser (LON:RKT) Fall looks rather overdone given it trades on a far lower p/e than Abbott. Abbott are appealing and it seems the payment is very high compared to analyst estimates. I hold- mainly because it is only time until the predators start moving in-that is my opinion anyway.
TT electronics (LON:TTG)
I have a modest holding. The shares are cheap and remain so.
It is difficult to know whether the weak share price reflects the company's performance or whether the second half weighting indicated in the AGM update has hung over the shares with the result that they are completely unloved. TT electronics (LON:TTG) operates in the field of 'electrification' and sophisticated sensing devices with an equally sophisticated manufacturing capacity.
Peter France, the new CEO has moved the company away from operating as three separate business units and it now operates on a geographical basis, e.g. USA, the potential benefits being increased collaboration between business units and cross selling opportunities.
The company has historically struggled to raise operating margins, but this is beginning to improve. Debt is higher than one would wish, but is starting to reduce.
All views welcome.
10 May AGM update:
TT Electronics plc ("TT", "the Group"), a global engineer and manufacturer of electronic solutions for critical applications, publishes the following trading update on the Group's performance for the four months to 30 April 2024 (the "period"), ahead of the AGM taking place later today.
Trading update
Group revenue in the period was 2 per cent lower than the previous year on an organic1 basis, but 1 per cent higher excluding the impact of pass-through revenues which continue to reduce.
Book to bill in the period was positive at 102 per cent with good performance in the Europe and Asian regions however, de-stocking continues and is now expected to normalise during H2. This is impacting our shorter cycle component products, primarily in North America. We have taken cost action to offset the lower demand and as a consequence expect the H2 profit weighting to be more pronounced than normal.
We also continue to unlock significant value through our self-help programme, Project Dynamo, as outlined at our recent Capital Markets Event.
The Board's expectations for the year remain unchanged and the business remains on track to deliver 10 per cent adjusted operating margin in 2024.
Commenting Peter France, Chief Executive Officer said:
"Whilst there is continuing global macro-economic uncertainty, the outlook for our markets remains good. The significant orderbook coverage and our prompt actions across the business underpin the Board's confidence in an unchanged outlook for the year and the delivery of the 10 per cent operating margin target.
Project Dynamo is progressing at pace and the new organisational structure is already helping to optimise resources, drive operational standards and increase customer intimacy as we remain laser focused on efficiency, growth and innovation."
Hi Jonno - like you I also have a small holding and wondering why it appears unloved, although there are a good mix of institutional holders. Stocko mentions 1st half TU on 1st August so lets hope that brings good news.
Trifast (LON:TRI) For those that haven't seen it - there was an excellent interview that Paul Hill did with Christopher and Nick Mills from Harwood Capital, who own 15%. See here: https://www.youtube.com/live/6... (16:50).
And even better, this one with Richard Staveley - see here (17:32) ...
An interesting turnaround case ... there have have been significant changes to the management team.
Both Mills & Staveley describe the strategy to improve margins from 5% to 10%, renegotiate contracts amongst large accounts, reduce costs, improve efficiency etc. Key thing then is to watch the profitability margin. Very insightful.
"FY2025 will be a significant turning point for the Group - clear ambition to deliver measurable progress in profitability, cash generation and ROCE. The Board is confident in the future outlook for the business over the medium term"
Good value at the moment too.
I like Trifast (LON:TRI) and have held off so far. Main reasons are I feel there is better value elsewhere for what is likely to be another 2 years at least to improve margins which is the basis for investing. Where as at least with Reach (LON:RCH) , for example there's a massive div to fallback on and I can see the turnaround starting to happen (end of pension problems and moving to a digital age). The other issue I wondered (possibly wrongly) was actual growth as opposed to cost cutting etc... That said, on balance when I get more funds this might get an opening position.
Card Factory (LON:CARD) - looks like Cockney's followers are piling in today.
"Will CARD get a bid? Well I’m due one in my holdings - the last was Menzies nearly 2 years ago! If I were a retailer on the acquisition trail I’d personally be looking for great cashflow and on that basis CARD has always been a bid target imo."
https://cockneyrebel.substack....
Card Factory (LON:CARD)
Unsurprising that investors are buying. We all make mistakes as does Richard Crow, but one has to admit that he is an excellent stock picker with a very good success rate, The shares are cheap even after the recent rise and the removal of Telios from the register in favour of a successful retail entrepreneur is a significant positive.
It is a furhter positive in my opinion that Card Factory (LON:CARD) already has a partnership relationship in Australia, which I suspect Mr Blundy will look to build on. As to a bid this seems unlikely until such time as the value in the company becomes apparent, after all why would Brett Blundy buy close to a 9% stake and then accept a bid, unless the offer was very favourable.
As you may assume, I hold the shares having purchased at under 100p, so am somewhat biased, but the risk/reward does from my lens look very favourable.
On Card Factory (LON:CARD) (I hold too) yes some of Mr Crows friends may be piling in now but I think they mostly bought at sub 100 some time ago. This is a profitable co on a low per (7.6) paying divis that are well covered (4.9% 5x cover) and broker eps estimates are trending up.
What I see is a decent 400m mkt cap company re-rating. What it will rerate to I don't know.
It is a lesson to me that good news travels fast but not as fast as I may think. Certainly slower than bad news.
Mr Crow did the same with Chapel Down (LON:CDGP) about 1y ago (long term hold for me) to greater profit. You could almost see them exit their trade (fast 25% fall from memory) but the market cap was about 40m in a different illiquid market. I wouldnt count on a similar pullback for card.
Agree Andrew.
If I have my Andrews right, I was wondering if you still retain an interest in Jet2 (LON:JET2) ? In my view an excellent company with a very good management team whose shares continue to be available on modest investment metrics that fail to reflect its performance.
All the best
Yes that andrew. Now get ready for all of those stocks to crater :)
Card Factory
Feels a bit frothy right now with a lot of PI jumping in .
Maybe follow the money is a smart move but Im not a fan when something pops up every single day and every post is pretty much positive .
Its a simple business , I met dean hoyle once the founder his stock and replen system was genius in its simplicity .
Three on the shelf , three in the drawer below , check the drawer below every week to see if empty . If ermpty replen .
Anyway feels like everyone loves it right now so momentum with it .
Card Factory (LON:CARD)
must admit i resisted the temptation to jump in here - but i must say the shareprice still doesnt look ridiculously or even particularly frothy - one thing that time does is here is allow debt to come down so even not doing much other than promised should be decent progress ref moving towards sound balance sheet - so i would say well done to holders for getting this one right.
Jupiter Asset Management hunts for acquisitions
https://archive.ph/KIFhq
Thanks
This is why stocko is so useful. I would never have noticed this article about Jupiter Fund Management (LON:JUP)
Thanks again
Following buying Merian, the Liontrust model of M&A that has proven so successful...
It appears that Litigation Capital Management (LON:LIT) have finally received payment for a large and long-standing case against Tanzania. I don't think the news is generally known as the company has not issued an RNS as yet.
Paul covered them last in Feb 2023 I believe. It has done reasonably well since then though I believe still very well priced. Also a business which is generally uncorrelated to the rest of the market other than to have more business when times are difficult perhaps due to higher number of disputes and insolvencies so it has been a good period for them and continues to be.
They have been shifting their business model to using part own balance sheet and part third party funds (25%/75% split) so have been able to diversify cases by sector and geography further with enhanced return. It has been and remains one of my larger holdings as I do appreciate the uncorrelated nature. I encourage other investors to take a look; as this business/mkt cap grows it will become more interesting to funds that could not or would not purchase a holding in such a small company. There are few listed alternatives, the largest and most well known is Burford Capital (LON:BUR).
This link looks relevant:
https://data-api.marketindex.c...
Yes this shows the settlement amount and some details - thanks for posting the link
Another contract win for Journeo (LON:JNEO). I know Paul and others have said they have previously missed an opportunity to update on trading, however, last year they released a trading update on 1 August so I think it's reasonable for them to wait until their trading update at this stage. That said, they haven't talked about any contract wins not budgeted for this year so the best we can hope for is 'in line'.
Of all the shares I own I am most nervous about Journeo (LON:JNEO) as it has very little recurring revenue so it does feel like a bit of a punt on its ability to constantly generate new business.
Today's expected announcement from Rachel Reeves that she's cutting some rail infrastructure projects is not great news either - not sure if that affects the company directly but it's not the macro environment they want.
Sorry Tortoise - Journeo (LON:JNEO) has a rapidly growing SaaS type recurring business. That was part of their business model switch 2 or 3 years back and has been doing well. They will always need to generate new business but that’s no different to any business but they have regular repeat cycles as assets are refreshed and renewed.
Rachel Reeves cutting rail infrastructure projects is irrelevant. Journeo (LON:JNEO) don’t service infrastructure that the government might cut - they manage displays, cameras/monitoring etc.
I’m surprised you own Journeo (LON:JNEO) as it doesn’t seem like a stock you appear comfortable you understand the business model of or how it wins business.
In-line is perfectly fine - I expect that to be the case. If they are not in-line then they should already have said so under MAR rules. Not every management obeys the spirit of the rules but my experience of Journeo (LON:JNEO) management is that they do not play fast and loose with rhetoric. We don’t know what the outlook is and that might change things but they are expanding into the Nordics and Europe so there is plenty to go for.
JNEO. Thank you David. I have long experience of JNEO and the management team there are absolute exemplars in transparency. People seem to think that stocks have to be in excess of 'in line' when 'in line' is exactly what they should be and given appropriate credit for. As for the SaaS issue it is an area JNEO are conscious of and moving to a stronger and growing recurring revenue paradigm is what they are doing.
Journeo (LON:JNEO) has a rapidly growing SaaS type recurring business.
For FY23 they said recurring revenue accounted for 10% of total revenue. It'll be great if they can boost that.
They - Journeo (LON:JNEO) - stated at a recent webinar that they are awaiting regulatory approval in EU. Likewise I have been waiting for news on this front - an enormous rail market
I hold
Journeo (LON:JNEO)
If they are not in-line then they should already have said so under MAR rules.
surely though you must concede the point that with such large "new" chunky contracts there is execution risk getting the value of work recently signed complete to the extent that it passes year end audit? we do see many companies spin this yarn again and again as a convenient excusenear the end of the year not delivering on promises. I wont blame anyone for being cautious with such lumpy stuff clearly needing to be sorted before year end.
In that regard good mangement with clear updates and hopefully transparent figures for next year massively helps. In that regard the lack of forecasts ref next year and the "silence" ref current trading does imho create some uncertainty that probably doesnt need to be there. I would also say the following doesnt exactly roll of the tongue will imho - if they are trying to exude confidence it doesnt exude confidence to me
It is anticipated that the majority of the work will be completed by Journeo by December 2024 which is included in management's expectations of performance for the current financial
Journeo (LON:JNEO)
You’re conflating risks here rmillaree
This isn’t a particularly large contract - management generally announce all multi-million pound contracts. They also usually tell us how much is in this years forecasts versus future years. The format is almost exactly the same - go back and look at them side by side and you will see what I mean. This approach of announcing is not everyone cup of tea. Some people say why announce it at all if it is in forecasts, which is perfectly valid. I personally quite like it as I get to see a lot of the contracts come through and who they are with and it gives me better visibility than just waiting for the next trading update.
There is no “silence” over current trading - they do a trading update every year at the same time. If forecasts are in line why would they keep informing the market they are in line? What is it with investors these days that they constantly want management to reassure every time the price moves a few %? I expect good communication around contract wins and if expectations change I expect to be told as soon as management know.
Journeo (LON:JNEO) have no history in inflating numbers or not being transparent over what falls into an accounting year or not, so I’m not sure why you are insinuating they are about to change that.
I’d recommend you go back and have a look through the last couple of years announcements and tell me where they have been inconsistent in approach or where they have missed forecasts or been unclear in communicating.
Journeo (LON:JNEO)
i dont think i am conflating risks here - these new contracts have to have risks they may not be delivered and the value to me suggests any slippage could be unfortunate for current year forecasts. Note i am not predicting this will happen - i would take comfort if managment have good prior track record of delivery but lets not pretend there is no inherent risk here ref lumpy new contracts signed - i would agree that if company has previously delivered at promised that shouldnt necessarily make us panic and think the worst.
Ref 2025 projections - when did this company first release 2024 forecasts - it looks like the 2024 forecasts were in place last this time this year? was that the case ?
ref quiet on current trading - ok i am probably being very melodramatic here - absolutely no NEED to say trading is on track you are correct when they are on track - that doesnt mean that it wouldnt have been nice to get an update bearing in mind the shareprice has declined getting on 20% from peak - perhaps price previously market was expecting some more ahead of updates that didnt materialise.
You are probably correct much ado about nothing if thats how the company always does it.
well let's see how things play out rmillaree.
I'd be very disappointed in management if it was anything different not least because they have announced two new contract wins in the last couple of weeks so plenty of opportunity to say if there was anything other than in-line. Of course you are right that we cannot take anything on blind faith though. It certainly never harms to question and a sceptical eye is probably a healthy dynamic too.
rmillaree - clearly JNEO is not a stock for you.
Journeo (LON:JNEO)
i dont mind being slightly downbeat in tone on stocks i hold - whether it is a stock for me for the long term is another matter. To me at present despite my comments i am more positive on this stock than negative overall so its wrong to say its clearly not a stock for me when i hold.
Noses in the trough at Nexteq (LON:NXQ)?
The Board therefore intends to utilise up to its full authority to purchase up to 10% of the Group's Issued Share Capital, equating to the purchase of up to a further 6,475,634 ordinary shares of 0.1 pence each in the capital of the Group, taking into account the 178,272 Ordinary Shares purchased to date. The Extended Buy Back will return up to £6.5 million to shareholders (the "Maximum Amount").
They could have issued a special divi for long suffering shareholders after the disastrous events recently. Instead they'll no doubt award directors for failure with cheap options in due course.
https://newsfile.refinitiv.com...
Nexteq (LON:NXQ) - from a capital allocation perspective, the buy-back has to make sense even if being used for share option schemes in the future. Buying 10% of the shares back when they have excess capital and the share price has halved is a no brainer. A special dividend won't generate the same value. They haven't increased the share count over the last few years.
Nexteq (LON:NXQ)
Terrible company governance here. They knew their numbers were bad and by far to miss market expectations BUT they kept buying back their shares even a day before the profit warning ; this is a classic case of waisting shareholders funds.
Same is happening now with the new buyback announced.
All the best
Nexteq (LON:NXQ) buyback was executed on an arms length non-discretionary basis by Cavendish and could not have been cancelled during a closed period . This buyback will be considerably larger , perhaps a sign that the board who own a large chunk of the shares between them see better value than when they initiated the last buyback
It does not work like that. The board knows at least 3 months before that the revenues will be lower than estimates.
All the best
Agree with Yiannos Nexteq (LON:NXQ) on buyback. Complete waste of money, only person happy will be the large holder/s who've been selling for months, unable to get out, and future director options. Only 66m shares so its illiquid.
28 March announce a 10% buyback. Shares to be either cancelled or held in treasury
16th April -. In line with forecasts. Expect improving 2nd half orders.
25th April - buyback cut to 1%. To be held in treasury.
25th July - FY24 revenues 15%-20% below market expectations. Director resignations.
Today - 10% buyback. Held in Treasury. Shareholders cash being used to clear an overhang (The Directors also believe that the Extended Buyback will provide shareholders with the flexibility, but without any compulsion, to realise value in respect of all or some of their shareholdings)
Also worth noting Everi Holdings (NYQ:EVRI) one of their big 2 customers received a bid from Apollo on Friday.
Nexteq (LON:NXQ) has always been a lumpy and volatile business prone to a big profit warning . The concert party , with strong board representation own around a third of the shares outstanding, and it’s a big part of their personal worth , so I’m pretty sure they are well aligned with shareholders . As far as the current buyback goes if you exclude the balance sheet cash and the interest received you’ve got at year end a roughly £20 million enteprise value with $95 million revenue , and $8 million PBT . And that’s without forecasting any recovery to previous years levels . It’s a disappointment the board isn’t willing to buyback even more shares IMO
Nice one Wolfie!
So many Companies, their advisers, commentators and analysts, including in Investment Magazines and National newspapers and on Investment websites, and investors (who swallow all the bullish commentary) do not understand buybacks, beyond the fact that they increase eps and reduce the number of shares in issue. And if Director bonus pay is based on eps that they can be rewarding for Directors too.
It’s wrongly taken for granted that buybacks “return cash to shareholders” and “reward shareholders.” That’s in the teeth of evidence staring them in the face that often they do the opposite!
Nexteq (LON:NXQ) is a classic example. They started buying back at the end of April at 150p. From that day onwards, as they continued buying back, the share price drifted lower to around 120p ahead of the big fall to 80p on the day of the recent profits warning.
How on earth was that “rewarding shareholders?”
It’s nonsense. Those who’ve held Nexteq (LON:NXQ) since they started buying back haven’t received a single penny. They’ve seen the value of their stake fall by over 40%.
The investors “rewarded” were not those who stayed invested during the subsequent 45% share price fall, but those who got out at the start of the buyback programme at the end of April, Those selling had a willing buyer of their shares in Nexteq (LON:NXQ).
That’s what buybacks so often do; they “reward” investors who want out and not the investors the “reward” is intended for. The supposed “reward” is too often a very costly punishment for those continuing to hold.
Have Nexteq (LON:NXQ) got the message now?
No way!
Having already thrown money away on buybacks, today they’ve announced a new buyback programme to throw away even more money, including this comment:-
“We therefore believe it is appropriate to return a proportion of the company's significant net cash balance, which stood at $36.9m at 30 June 2024, to shareholders.”
And this bit:-
The Extended Buy Back will return up to £6.5 million to shareholders (the "Maximum Amount.”
Unless a buyback looks sensible (e.g Next (LON:NXT) ) DO know how to buyback successfully) I use the day the buyback is announced as THE day to sell.
Why?
Because the lack of understanding about buybacks means that they are often greeted with a big share price gain on the day a buyback is announced. And sure enough that’s happened with Nexteq (LON:NXQ) today, with the share up over 5% just now to 84p.
Hi Ken,
Buybacks do work and do miracles for the shareholders and enhancing EPS. Have a proper look over in the US but the companies there are cash machines growing their revenues year after year. Unfortunately here , and I do agree with you , in many cases it is used just to keep the share price steady for a couple of months. The problem in the UK is that most companies are not really growing their revenues.
Nexteq (LON:NXQ) buyback should not have be executed.
All the best
Hi yiannos
Though I much prefer the certainty of the cash from dividends and specials to buybacks, that’s just a personal preference. , I agree (hence my Next (LON:NXT) example) that buybacks can work well, especially so it seems in the US. I didn’t make that point in my previous reply because of wanting to focus on the folly of so many UK buybacks too often resulting in big losses for shareholders, and the failure of so many to realise about that folly of the non existent “reward” they have supposedly received.
I’ve had a great run twice from £1 from , Marks and Spencer (LON:MKS) but when I held years ago (when I should have sold as they were so obviously struggling) it was infuriating when time and again then CE Stuart Rose bragged about how he had “rewarded shareholders” with a £2 BILLION buyback starting at £4. It was no reward at all as the share has never again reached £4. And what happened with MARKS happens time and again in the UK.
I 100% agree with you, Ken. The overwhelming issue with share buybacks for me is that they are undertaken by the very people who won't be objective about whether the shares are currently undervalued or not. It will always be in the company's interest to buy back shares (good for eps which is often linked to directors bonuses) and the directors will nearly always claim that their shares are 'undervalued'. Even when trading is just a little soft there is a huge temptation to do a buyback and soak up some of the loose holdings that come onto the market. All that does is delay the inevitable fall in the shares if and when things get worse!
Nexteq (LON:NXQ)
Ken, et al.,
Re: Nexteq’s buy backs
NXQ’s planned buy back announced in March was only for 1 million. There are/were obligations for share-based payments to be made. I presume that the company didn’t want to issue shares so decided to buy back shares to have on hand. It seems a reasonable thing to do with cash, especially if the board was aware that the CEO was considering a departure (implied in RNS 24.vii.24) which would, unsurprisingly, cause delays with acquisition decisions.
The share price at the time was c. 150p. In hindsight, this was bad timing, but the company only has c 5 months of visibility in its order book. It may not have been clear in March/April that there was anything more happening other than a slight temporary contraction in orders. There is a possibility that the contraction had yet to begin.
On the other hand, the company had gone to the trouble of ensuring that any buy back wouldn’t trigger the obligation for the concert party to make a cash bid for the whole of the company.
The Company has historically sought authority and received approval from its shareholders to make market purchases of its own shares, with the most recent authority being granted at the Company's AGM on 27 April 2023, permitting the Company to repurchase up to 6,647,506 Ordinary Shares, equal to 10 per cent. of the Company's issued ordinary share capital at the time of the 2023 AGM. However, despite this authority having already been granted (to expire at the conclusion of the 2024 AGM), the Company has been restricted from using it owing to the Concert Party being interested in more than 30 per cent. but holding less than 50 per cent. of the total voting rights of the Company (and therefore, any repurchases of shares under such buyback authority being liable to trigger an obligation for the Concert Party to make an offer, in cash, for the entire issued and to be issued share capital of the Company, pursuant to Rule 9 of the City Code, if the repurchase would cause the aggregate number of shares of which the Concert Party was interested to increase).
RNS 28.iii.24
A similar wording has been used in connection with both sets of buy backs:
The Directors have confirmed that none of them (or any persons connected with them) will, nor do they have any current intention to, sell any of the Ordinary Shares which they beneficially own to the Company should the Company utilise the Proposed Buy-Back Authority.
My general view on Nexteq is that it is a cyclical company prone to lumpy revenues. It makes real cash. The market is not kept updated on the company’s forecasts for earnings. This has led to many happy surprises (…in the past). I haven’t noticed any governance issues. As of yesterday, it had a market cap of £53 million with cash of c. £28.6 million. Stripping out the cash, we have a company the market has decided is worth £24.5 million that is forecast to make £7ish million this year. Last year it made around £16 million in free cash flow. The trajectory of EPS from 2010 to 2018 was more than satisfying: .9p, 1.7, 5.6, 7.6, 9.2, 9.7, 14, 19.7, 21.3…followed by a blip down in 2019 before COVID completely shut down their customers. It had looked like orders had recovered from COVID, but the profit warning has indicated otherwise.
I like the trajectory of historic eps so much that I bought some on the 24th. I already had some picked up in December.
I think that buy backs at this point make perfect sense for the company; assuming that earnings will recover in the next year or two, there probably isn’t a better use of company cash available.
As to buy backs in general, I can see the truths behind several viewpoints on this. I shall leave it to others to debate.
Nexteq (LON:NXQ)
Listed companies have more than 5 months visibility in their order books. They wouldn’t be able otherwise to guide for future earnings and budget appropriately. There are brokers estimates to 2025 year end.
As to corporate governance issue the main aspect of it is who makes decisions and accounts for them.
I shall leave it as well to others to decide if there was any wrongdoing there. Issuing a statement only in January claiming expectations above estimates to come up only in July to miss estimates is unacceptable.
Good luck to all holders but not for me.
All the best
Nexteq (LON:NXQ)
The Group enters 2024 with good visibility of demand with the order book representing a more typical five months' revenue cover
From the CEO’s report in the Final Results (FY23), RNS 13.iii.24
You’re right, Yiannos, my cryptic notes have led me astray again. It isn’t five months’ visibility, but five months' revenue cover that was mentioned. They are usually, but not necessarily similar.
Some businesses don’t have the visibility or repeatability that one can expect from diversified giants or companies with recurring revenues. I’m happy with the opportunities this can present, but sometimes I’m caught holding when the bad news comes.
I hold Nexteq (LON:NXQ) and recentlty doubled down so I'm hoping you are right topvest (and eParo wrong?). But it's good to have these discussions so keep it up!
Can't see that this article about Zotefoams (LON:ZTF) has been mentioned here but it might be of interest to holders (I hold) and could have been responsible for the upwards blip on Friday:
https://packagingscotland.com/...
Interesting article, thanks for linking. Love this company description “Zotefoams is not a packaging company; it is a science-based disrupter intent on delivering innovation and solutions. Previous work has included the creation of ZoomX foam used in Nike running shoes, that helped propel athletes to world records and first place finishes.” I hold.
Thanks Q - really interesting article and a great opportunity for Zotefoams (LON:ZTF) to make major inroads into a market/area that has been stagnant for a very long time. Here's hoping their trials are successful and it marks a major transformation. I hold.
Thanks for sharing Quilleron. Despite being my largest holding I hadn't seen this article. Most of what is mentioned happened a few months back when the price spiked up on 15th March following the media launch so is not new news, however, the article is a nice summary of the product. Since then the price has pulled back a bit and stabilised, trading around 480p. The uptick on Friday was just due to a big drop of 7% the day before and then reverting to the mean, with the share being so illiquid, 4-5% daily swings are all too common unfortunately. I believe the stock has formed a new base and is ready to break out when the result of these trials is announced and/or information on the the funding partners is shared. Hopefully that comes sooner rather than later, but I am happy to be patient.
Huge thanks for sharing this article. The chemistry is fascinating and the market opportunity huge. I hope they pull it off and don't end up having to give too much of the opportunity away in "strategic" partnerships. I hold.
Quiz (LON:QUIZ) delays their audited results...
Wondering if the Going Concern statement is holding it up...!
ME International (LON:MEGP)
I missed this on my initial RNS scan
Up to 300 new sites for the laundry machines on the largest UK motor fuel retailer .
https://www.voxmarkets.co.uk/r...
This is a relatively new holding in my daughters ISA ME International (LON:MEGP) - I was attracted to some new opportunities (i.e. food vending) and the continuing growth. We were discussing we else to roll out this weekend and the thought of petrol stations didn't actually cross my mind. That said, it seems to make sense - clean some duvets and order some pizzas at the time? I know despite spending a small fortune on a Miele washing machine, my missus still insists on going to the launderette for bigger items, so rather than view this as a business used by people who don't have a washing machine, the opposite may also be true.
My impression is that they are finding the food vending much more difficult than the washing machine offer, which is going very well.
By coincidence - I just did a very rough and ready discounted cashflow analysis on each washing machine - assuming a 5% discount (they are spending their own cash rather than borrowing), 2% annual price rises, 10 year lifespan, £22,000 cost per machine and £8,000 EBITDA (both figures my calculations rather than stated by the company) I get a PBT for each machine of circa £48,000 over 10 years.
PSI Software - Dr. Uwe Hack is the new Chairman of the Supervisory Board
You couldn't make it up!