Small Cap Value Report (Mon 29 Oct 2018) - W7L, GMAA, VCP

Good morning, it's Paul here!
I've finally managed to work out how to put up my Bournemouth sunset picture from last week! Shrinking the file size dramatically seems to have done it - anyway, I hope you like the colours.

Preamble
Volatile stock market conditions remain, driven mainly by the USA (rising interest rates, trade war with China/EU), but also factors closer to home such as Italy/Eurozone crisis, Brexit & Corbyn worries.
I recall that, a couple of years ago, the Fed tried to start raising interest rates, but it triggered a stock market plunge, so they back-tracked. Maybe we've had QE & ultra low interest rates for so long, that our economies are now addicted to cheap credit?
I don't see any particular reason why there would be a continued bear market (based on the information we have as of now). In my view things got very frothy, and this is a sensible (and long overdue) correction.
I'm also starting to see some genuine bargains crop up - companies that are reporting decent trading, but are on fairly bombed out valuations. Last week, Flowtech Fluidpower (LON:FLO) and Photo-Me International (LON:PHTM) struck me as good value (I don't hold either, but they're both on my watchlist). There are some attractive (and sustainable) dividend yields out there, which make some high yielding equities look rather attractive now.
I'm thinking about running some stock screens, to look for bargains, much like I did in 2016 after the Brexit vote. Over the weekend, I revisited a video I made just after the Brexit vote. I was correct at the time that it was a one-off plunge, which would recover. Although looking back at the stocks that came up on my "Brexit bargains" screen, it's amazing now how far some of the low PER + high dividend yield retailers shares have more recently collapsed (e.g. Debenhams (LON:DEB) ). So I might use different criteria this time around, more focused on quality measures.
The speed of the decline in some conventional retailer shares has really surprised me - operational gearing in reverse. It's made me realise that chasing the lowest PER & highest yielding shares is a dangerous strategy - as that could end up steering us towards the lowest quality companies that are in structural decline.
The internet really has changed everything. In the past, when I first started investing, in the 1990s, you could rely much more on "reversion to the mean". So oversold, low PER, high yielding, strong balance sheet companies, would usually recover quite well, after a downturn. These days, we cannot rely on reversion to the mean, because the internet is disrupting so many sectors, on a permanent basis. This seems to be accelerating the death of weaker players in many sectors.
This is why evidence of a successful internet strategy should be a key item on everyone's investing checklists.
What am I doing with my own portfolio, in current volatile conditions? Nothing! I'm an investor, not a trader these days. So my portfolio is a concentrated group of high conviction positions, which I've researched thoroughly, and have the confidence to hold through any market volatility, providing there is no negative newsflow. I see indiscriminate falls in share prices as providing potential buying opportunities.
It's a stock-pickers market now. We can't rely on buying anything & it automatically going up, as we could in 2016-17 to some extent.
I don't believe in buying low to middle conviction things, because what's the point? You only end up throwing them out when they drop. So why buy them in the first place? Several years ago, I did some analysis of one of my main spread bet accounts. It showed that hundreds of transactions in low conviction trades, netted off to about nil, over the whole year! Yet I had a very good year overall. How come? Because I had 2 or 3 really big winners, which I had backed in size. Therefore, practically everything I did that year was a waste of time, I could have been lying in my hammock, reading books, rather than glued to the computer screen all the time! Therefore my approach now is to ignore almost everything, and just focus on my top handful of share picks.
Still, there are lots of different ways to make money in the market. As my mentor once said to me, "Just do more of whatever works".
Budget
I've double-checked, and it is definitely today! Coverage starts at 3pm today, on BBC2, and no doubt other media channels too.
The Chancellor has plenty of headroom to be generous. We're constantly being told how terrible everything is, but the reality is that tax receipts are doing very well, and the Govt's spending deficit has been largely eliminated - at least in real terms - i.e. inflation is scrubbing off about £40bn p.a. (my rough calculations, of £1.8trn National Debt, and 2.4% inflation). New debt is now being added at less than £40bn p.a. So the National Debt as a share of GDP should actually start shrinking slightly now.
The OBR website has useful updates, and tons of data. This shows the deficit rapidly reducing, which suggests to me that the economy could be stronger than official estimates.
We also have full employment, rising real wages, and consumer confidence is positive at the household level - people just have a negative view of the economy as a whole - hardly surprising considering the blanket daily doom & gloom in the media, and the political chaos.
Overall then I think perhaps the gloom is overdone? Time will tell.
Anyway, on to some companies reporting today.
Warpaint London (W7L)
Share price: 112.5p (down 45% today)
No. shares: 76.7m
Market cap: £86.3m
Trading update (profit warning)
Warpaint London plc (AIM: W7L), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands, provides a trading update for the year ending 31 December 2018.
Bad luck to holders here. I will just get up to speed by re-reading our previous coverage of Warpaint in the archive, here. I quite liked it at the interim results stage, noting the high quality scores & strong balance sheet. Although I also flagged that the H2 weighting looked like a "steep increase" - to double sales from H1 actual.
As "Wimbledonsprinter" notes in comment no.4 below, it was only 42 days ago that Warpaint said this (on 17 Sept 2018);
The emphasis on Christmas gifting of our own brands across the Group has resulted in an order book that was significantly ahead at 30 June 2018 compared to the same point in 2017 on a comparable basis (including the own brand orders of Retra in H1 2017), allowing us Based on current expectations the Company's board anticipates that revenue for the year ending 31 December 2018 will be in the range of £48 million to £52 million. Consequently, the Company's board currently expects profit before tax for the year ending 31 December 2018 (excluding amortisation in connection with acquisitions and exceptional items, which total approximately £2.5 million) will be in the range of £8.5 million to £10 million..
Compare that with what the company says today (29 Oct 2018);
However, the UK market, as highlighted in our interim results, remains challenging. The UK market, which accounted for 44% of Group sales in the first half of the year, has seen further softening recently, with retailers reducing stock levels and Christmas orders.
This reduction in previously anticipated UK sales will have an impact on Group performance for the full year that will not be completely offset by better than anticipated performance in our major overseas sales territories.
Bit of a difference. It sounds to me as if the tone in the 17 Sep 2018 announcement was over-optimistic. That inevitably dents management credibility, and I won't be placing much credibility on outlook statements from now on. Outlook comments should be cautious. It's far better to under-promise & over-deliver, rather than hoping for the best and then disappointing.
I'm not surprised that UK retailers are reducing orders, because so much business is moving online in the UK. I understand that we have the highest (or almost the highest) proportion of sales carried out online, of any major economy. Therefore, this shortfall for H2 orders at Warpaint would make me want to look more closely at where its product is selling online, and why that hasn't offset declines from physical retailers?
Quantifying the damage - this bit is excellent - the company has provided us with revised numbers, in a range. I wish all companies would do this, it means investors can make informed decisions better;
Based on current expectations the Company's board anticipates that revenue for the year ending 31 December 2018 will be in the range of £48 million to £52 million.
Consequently, the Company's board currently expects profit before tax for the year ending 31 December 2018 (excluding amortisation in connection with acquisitions and exceptional items, which total approximately £2.5 million) will be in the range of £8.5 million to £10 million.
It makes a lot more sense to provide a range, rather than a specific figure, so this is at least good reporting, of a disappointing situation.
There is still uncertainty;
The reported level of profitability for the full year will be crucially dependent on the precise product and geographic mix of sales for the remainder of the year, the busiest period of the year for the Group.
This makes me worry that the company doesn't seem to have a lot of visibility on sales orders. We're almost into November, so I would have thought that retailers would have all their Xmas stock in stores by now. Maybe it doesn't work like that in make-up? I've noted before that Warpaint holds rather large inventories, so perhaps retailers are able to re-order fast-selling lines, and pull the stock from Warpaint's warehouse? That could help explain why visibility is poor, but I'm guessing there.
Retailers might have cancelled some existing orders too, perhaps? Even though they're contractually obliged to take delivery of goods which they've ordered, many retailers ride roughshod over this, and cancel orders at the last minute. If suppliers protects, then they're routinely told that they won't get any future orders from the retailer, if they don't accommodate the cancellation. These are just generic comments about the retail sector, by the way.
Valuation - there's a note on Research Tree, which gives an immediate update to forecasts, suggesting that this is a conservative initial view.
Forecast EPS for 2018 is reduced from 9.6p (flat vs last year, and down 23% on previous forecast). That gives a PER of 11.7 - which probably looks about right, for a company that has just disappointed, and may now even be ex-growth?
Due to the strong balance sheet, the previous dividend forecast of 5.5p is maintained. If that's correct, then the yield of 4.9% is beginning to look attractive - providing you are confident that divis won't be cut.
My opinion - if this is just a blip, then this could be an attractive entry point.
My concern is that the products should be selling well online, so overall UK demand should not be reducing. Unless the product has perhaps been surpassed by other brands with better products & more effective marketing budgets? Maybe we should all be asking wives/girlfirends & femals friends & colleagues what they think of Warpaint's products? If they rave about how great it is, then the shares could be a buy at this level. If they're lukewarm or negative about it, then there could be a bigger problem. Is demand too fickle in this sector, I wonder, to be able to reliably forecast?
In more normal market conditions, the share probably would have fallen 30%, not 40%, bu that's not a big enough profit opportunity to make me want to catch the falling knife. I'll put it on my watchlist though, as potentially interesting.
A similar situation arose recently with QUIZ (LON:QUIZ). It fell sharply on a profit warning, and was looking tempting at 80-100p. However, it carried on falling, and bottomed out (possibly) around 45p. So it just shows, that diving in immediately after a profit warning can be very high risk. Many recently floated small caps, like Quiz & W7L don't have a fully developed private shareholder base. Brokers just place lumps of shares with institutions, because that's the easiest way to earn their fees. No thought is given to the after-market.
So, when a profit warning comes along, there's not enough liquidity from retail investors, to soak up any selling from institutions. I think that's why the share price can collapse far more than might seem reasonable. Maybe some fund managers also want to ditch lousy performers before year end, to clean up their portfolios before the end of year report on holdings?
These are the considerations which make it impossible to predict where a profit warning is likely to lead the share price. Hence why I tend to stay away. There's a lot to be said for selling on the opening bell, if you're a small shareholder, when profit warnings come out. You can always buy back later.
Gama Aviation (LON:GMAA)
Share price: 121.5p (down 20% today, at 13:01)
No. shares: 63.6m
Market cap: £77.3m
Trading update (profit warning)
Gama Aviation Plc, one of the world's largest business aviation service providers, today announces a trading update for the full year to 31st December 2018.
That's quite a bold self-description, for a £77m mkt cap business!
As above with Warpaint, the dreaded H2-weighting to profits strikes again;
At the time of the H1/18 interim results substantial growth was anticipated in the 2nd half of the year.
However, with Q3 delivered and with better visibility for the full year, trading in certain divisions has not improved sufficiently to deliver the full year expectations.
Quantifying the shortfall is always helpful, although there isn't any footnote to say what the original expectations were, so job only half-done here;
As a result, whilst no individual division is significantly weaker, in aggregate there is a material impact, and accordingly the board now expects the full year underlying operating profit to be $3m below its original expectations.
Valuation - the house broker has joined up the dots, and issued a flash note (on Research Tree). Its 2018 forecast is lowered by 19.3% to 21.3 US cents (note that the company reports in US dollars).
Converting that at £1 = $1.28, gives us 2018 EPS forecast of 16.6p, a PER of 7.3
Balance sheet - the most recently reported (interim) balance sheet seems fairly solid to me. Receivables look a bit high.
It did a big equity fundraising in Feb 2018. There seems to have been an unusual acquisition, with Gama buying something from its major shareholders. I'm generally not keen on deals like that.
My opinion - neutral. I don't recall having looked at this company before, as these days generally I try to avoid anything aviation related, because historically I've usually lost money when delving into that sector.
The more detailed commentary today sounds as if the problems affecting 2018 may be fixable, and hence perhaps 2019 might improve? If you understand the sector, then it might be worth a closer look, given the low PER. It doesn't interest me though.
2018 Budget
I listened carefully to the Chancellor's speech today, and it strikes me as a sensible package. It reminded me of the crowd-pleasing, giveaway budgets that Chancellors in the past have tended to do shortly before general elections. So I wonder if the Tories are gearing up to hold a snap election after announcing some kind of Brexit deal?
I don't see any need to adjust my portfolio in light of the Budget. The tax cuts from April 2019, through an accelerated increase in the personal tax allowance & higher rate threshold, are clearly going to give household incomes a boost next year.
As mentioned above, the economic data at the moment is remarkably good. There seems a total disconnect between the figures (rising real wages, low unemployment, strong Govt finances, etc) and the general perception.
Extra Govt departmental spending announced, plus more money for Universal Credit, etc, is all good for stimulating consumer spending.
The business rates cuts (for retail/pub/restaurant/cafes) with rateable value under £51k, giving them a third off, for 2 years from April 2019 - this probably won't benefit many listed retailers, as most will have sites with rateable values well above that level. It's more designed to help smaller businesses.
Victoria (LON:VCP)
Share price: 455p (down 25% today)
No. shares: 125.4m
Market cap: £570.6m
Victoria PLC (LSE: VCP) the international designers, manufacturers and distributors of innovative floor coverings...
There are 3 announcements today, which I'll try to cover below, although it looks fiendishly complex;
Trading update - LFL sales growth continues;
... for the six months ended 29 September 2018, the Group has continued to grow sales in a challenging market and Group like-for-like ("LFL") revenue growth(1) has continued to exceed 3% compared with the equivalent period during the prior year.
Operating margins have fallen - which is buried in this section of PR puff below! Note to PRs - this stuff doesn't fool anyone. There is no such thing as "investment in operating margin". In reality, it is just lowering your prices & accepting a lower profit margin, in order to avoid losing sales to competitors.
Overall, as previously stated, the Board firmly believes that it should capitalise on the strength of the Group by driving sales and market share at this time, although this comes with a short-term investment in operating margin.
Based on year-to-date performance and taking into account seasonality, this is impacting the Group's overall margin by approximately 1 - 1.5 percentage points versus consensus market forecasts, although margins are still expected to significantly exceed the prior year due to organic growth and product mix effects from previous acquisitions.
That doesn't sound much, but if your operating margin is 10%, and it's going to be 1.5 % points lower, then that's a 15% fall in operating profit. Again, the clever wording doesn't fool people.
To be fair, the previous trading update on 10 Sep 2018 did also mention that the strategy was to drive market share through competitive pricing. Although that announcement did not quantify the reduction in operating margin.
Broker updates - I can't find anything, so we're in the dark. Reading between the lines, if I had to guess, I'd say that earnings are probably heading 10-15% lower than forecasted. The operating margin comment above suggests that, and I'm assuming that sales growth is probably similar to forecast.
Stockopedia shows a forecast PER of 47.8p for this year (driven by large acquisitions made this year - ending 03/2019). At a guess, it sounds to me as if we might be heading for something nearer to 40-44p? That's just my estimate, with little information available.
A PER of 10-11 maybe? That would be OK if the group had net cash, but it doesn't. Its taken on a ton of debt to fund acquisitions.
Outlook - I don't like this at all, it seems disingenuous - glossing over the profit shortfall, and instead talking about revenue growth;
The Board believes that seeking to increase market share is the correct strategy for the Group at this time as, even with current market conditions, the Group's year-to-date revenues are on track to exceed consensus market forecasts, and the Group plans to recover the margin investment in stages over the next twelve months.
Reminder - there's no such thing as margin investment. It's doublespeak for lack of pricing power, and competitive pressures.
Intention to offer 450m Euro senior secured notes - this separate RNS strikes me as very peculiar indeed. The group is trying to raise E450m in 2023 loan notes, with the interest rate & pricing as yet unknown.
Why is this happening? All we are told is that the net proceeds from the bond issue is to repay existing bank borrowings!
This rings loud alarm bells to me. Why replace bank borrowings suddenly, with what sounds like a junk bond offering? This suggests to me that the banking relationship may have broken down in some way. I don't want to speculate, but in the absence of any explanation from the company as to why it's doing this unexpected & very large refinancing, then I wouldn't want to be holding the equity at all.
Pro forma & interim financial information - again, a very unusual announcement, with reams of figures which look like an IPO document. Pro forma figures are used to show how acquisitive groups would have looked, if the acquisitions had occurred earlier. The purpose of this, is to enable investors to assess how the group would look at a steady state going forwards.
In this case, the pro forma numbers are not audited. Not that audits make much difference anyway, as they're certainly not, and never have been, the rigorous assessment of the numbers that many investors imagine them to be.
Adjusted pro forma EBITDA is £111.7m for the year ended 30 June 2018.
Balance sheet - looking at the pro forma balance sheet as at 30 June 2018, the following figures look quite shaky to me;
NAV: £331.9m, of which 500.9m are intangibles. Deducting those, gives;
NTAV: negative at £-169m. That's bad.
Working capital: Current assets of £330.8m, less current liabilities of £163.2m, giving a healthy current ratio of 2.03
Elephant in the room: £405.8m in long term creditors, called "other non-current financial liabilities" - which I assume is bank debt, or similar.
Net debt: this term is not used in the pro forma announcement, so working it out myself, I get to £349.4m (being cash, less current & non-current financial liabilities). This is 3.12 times adjusted EBITDA, and 3.36 times unadjusted EBITDA. That's quite high. It reinforced my hunch that something might have gone wrong with the banking relationship.
My opinion - obviously, I have incomplete facts. The company has not told us why it's seeking to raise a large bond offering, in order to pay off the bank. I'm inclined to draw my own conclusions - which are very negative.
I would not want to hold this share until its refinancing has been completed. You can't value the equity, if you don't know what terms the large debt pile is going to be refinanced on. It could be much more expensive than the bank debt. Or it might not be able to refinance at all, who knows?
I don't like this at all. The risk with acquisitive groups, is that they get carried away, and take on too much debt. That seems to have happened here. I'd give it a very wide berth, unless & until the financing position is sorted out.
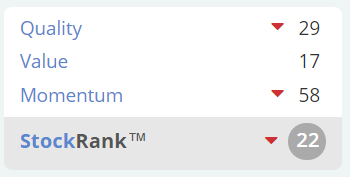
Stockopedia computers don't like it either - a very low StockRank of 22, and negative "Momentum Trap" description before today's 25% share price fall. As always, a reminder that the Stockopedia rankings are not infallible. But are statistically proven to out-perform the market, for a portfolio of shares.
UPDATE 31 Oct 2018 - Victoria (LON:VCP) has issued an update regarding its possible bond issue, here;
Credit rating and response to speculation
This carpet maker has given more details about its proposed bond issue, to replace the exiting bank borrowings. Summarising it, with my comments;
Credit rating - Fitch has given the rating BB(stable) for the intended bond issue. Using a table shown here on Wikipedia, this doesn't look very good - it's in the bracket described as non-investment grade, and speculative. "Higher degree of default risk, speculative" are the description provided by Google for BB credit rating bonds. So not something to brag about, I would suggest. The interest rate would therefore tend to be higher than better quality bonds.
"Misleading rumour & speculation" - what does the company expect, if it drops a bombshell on the market, with no explanation? At the same time as issuing a profit warning, which is what happened here.
Banking relationships (with HSBC and Barclays) - Victoria says;
Firstly, the Company continues to have a close and positive relationship with its lending banks, HSBC and Barclays, and continues to operate with significant headroom with respect to its covenants under the existing 2-year facilities put in place in August 2018.
Our lending banks are acting as joint global coordinators and bookrunners on the potential Bond issue and have been working with us on the project since April of this year.
That's reassuring on the banking covenants.
What I don't understand is this. If the banks are happy with their existing lending to Victoria, then why have they been working with the company to get their lending repaid through a bond issue? That just doesn't make sense to me!
More detail is given about why the company thinks a bond issue makes sense for Victoria;
Long term (5 year) funding of a bond - but this could also be done via a term loan from the banks. Maybe the banks don't have the appetite for long term lending to Victoria?
Fixed rate funding - again, this could also be achieved through conventional bank borrowings, adding an interest rate swap or cap if needed.
Flexibility - but not specified why a bond is seen as more flexible than bank borrowings. I would have thought the opposite is the case. Bank borrowings can be easily amended, whereas bonds are usually set in stone.
Depth of the bond market - suggests perhaps that the banks are at or near the limit that they want, in terms of exposure to Victoria.
Discretionary nature of this bond exercise;
The potential Bond issue is an entirely discretionary exercise, and a final decision will be made at the Company's discretion in the coming days on whether to move ahead or retain the existing facilities;
The potential Bond issue is an entirely discretionary exercise, and a final decision will be made at the Company's discretion in the coming days on whether to move ahead or retain the existing facilities.
My opinion - the proof of the pudding is in the eating. So let's see what terms (if any) are agreed for the bond issue. I cannot see the logic for replacing cheap bank borrowings with a (probably more expensive) junk bond. Whatever the company says, this suggests that the banks may not want continued exposure to Victoria. Why else would they be o-operating with the company to get all their debt repaid? I could understand if the banks wanted to lower their exposure, but it's perplexing as to why they are happy to see it all repaid.
The share price has fallen because of the profit warning a few days ago, and the bombshell announcement (with no explanation or detail) as to the bank borrowings being repaid through a bond issue.
Maybe the share price would go up again, once the refinancing has happened? That would depend on the terms of the refinancing. If the bonds are expensive, then that would reduce profits available to pay out in dividends.
I shall monitor things closely, but personally I remain of the view that this share looks too risky to hold unless/until the refinancing has completed.
That's all I have time for today. I didn't get round to looking at Wey Education (LON:WEY) in the end - sorry about that - but Victoria looked much more interesting, so I focused on that instead.
Graham will be looking after you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
The Victoria (LON:VCP) RNS reminded me of this latest video from Howard Marks and colleagues at Oaktree. They anticipate many businesses needing to refinance and having to pay more than they have become used to as the cycle turns.
https://www.oaktreecapital.com/insights/videos/conversations-with-portfolio-managers/cycles-with-howard-marks
You captured a lovely sky in your photo, Paul!
Victoria (LON:VCP) always seemed too good to be true..almost based on an acquisition policy that seemed flawless..as though the vendors were mugs. Alot of obfuscation in that statement I think.
Hi Paul and Graham. Thanks for all your comments As a novice reading VCP I would be easily fooled.Keep up the good work.
Victoria (LON:VCP)
I think as an ex investment banker, I suspect the CEO Gordon Gecko view of companies, namely that they are merely an accumulation of financial data that can be manipulated to unlock value. However, that mindset only seems to work if you pass the parcel asap to the next mug after squeezing your own value out of it.
I was impressed by the way he secured his significant holding- via a call option I think? Never seen that done before or since in a public company. But it struck me as too clever by half, and relies on the accumulation by an acquisition strategy to get the price up to activate the option. A fast acquisition strategy usually excites the market, when its animal spirits are up, but can all too easily follow the route of over-leveraging when the financials start to look less rosy. So in a way, its a bit of cliche when you look under the surface of the superficial cleverness.
Of course I am a bit of staid so-and-so. However, some of these things seem to follow a natural dynamic. I also thought the lack of any commentary by the CEO when posting the unaudited reports was odd, unless I somehow missed it. Of course a good way of obscuring a truth is by giving so much information that it bemuses the reader.
So a good job done by Paul, and I think he is right to start hauling up the red flag on this one.
Re Victoria (LON:VCP) This has got to be one of the worst financial information presentation that I have seen of late.
The big red flag for me is the weak balance sheet. Looking at the debt position, a ratio favoured by the Naked Trader is net debt/ adj. operating profit. By my calculations, this ratio comes to 4.9. NT thinks anything above 3.5 is a good reason to move on.
IMO that combined with no moat, weak operating margin and a wobbly stock market is enough to look for better investment opportunities elsewhere.
Thanks for the write up on Victoria (LON:VCP) . Never a holder, but interested watching its financially engineered rise and current fall in recent years under ex-City banker Geoff Wilding. Could never understand the attraction of gearing up an operationally leveraged business such as carpet retail with massive financial leverage to fund repeat acquisitions thereby compounding the risk that when the music stops ther whole edifice comes tumbling down.
A high yield bond issue might prove to be the rabbit from the hat (one of its few selling points is that its usually covenant lite and it may be the banks are getting nervous/starting to rein in the company’s activities), but such issues tend to come with strings attached (not least usurious PIK interest roll ups) that further ramp up the risks for equity holders. A particularly sharp falling knife for those inclined to try and catch it.
Gus.
Hi Gus,
Thanks for your comment re Victoria (LON:VCP) .
I note that the head man at VCP banked £41.35m, selling shares in Aug 2018, at 827p/share. This is on top of £18.4m banked at 460p in April 2017, and £11.175m banked on 7 Aug 2015, at 1117.5p/share. Not bad going! Although he still holds a substantial stake of 18.16%, reduced from over 40% in 2015 - so he's more than halved his personal shareholding, which was amassed from a bonus scheme linked to share price, if my memory serves me correctly.
I met him in late 2016, and was very impressed with the strategy - to strip out working capital, and synergies/efficiencies, after buying up sleepy, family-owned carpet makers. Although I remember him being a bit too gung-ho about debt. I cautioned him on not taking on too much debt, and that under 2 times EBITDA struck me as a prudent level. He dismissed that, saying he could push it higher than 2 times, safely. I wasn't convinced.
Anyway, we'll have to see what the outcome of this bond issue is. Maybe they already have investors lined up to fund a bond? Although very little information was given in yesterday's announcements about why they are doing this. That's what makes me nervous.
Regards, Paul.
EDIT: I see from the RNS of 6 August 2018, that new banking facilities had been arranged. It's very odd that the group has now decided to repay these borrowings from a bond issue, less than 3 months later;
Footnote, to the discussion on Victoria (LON:VCP). The company issued an RNS this morning “setting the record straight” on the background to the proposed bond issue. I note the comment 3 about one of the benefits of the bond is the “flexibility” (read loose or no covenants) it offers is a vis bank debt. Just because the lending banks are leading the bond issue (to repay themselves from the proceeds) shouldn’t necessarily prove they’re fully comfortable with their exposure and in any melt down debt holders will rank ahead of shareholders.
https://www.investegate.co.uk/victoria-plc--vcp-/rns/credit-rating-and-response-to-speculation/201810310701047907F/
Glad that’s all sorted it then. Still think there’s a good chance the wheels might be working themselves loose on this one ....
Gus.
Great stuff Paul on Victoria (LON:VCP) - Much appreciated
Quite agree with Paul's assessment that you need to assess the success of an internet sales based strategy before buying a retailer or retail related company. This is why I avoided Warpaint as their web site looks gaudy, cheap and cheerful to me and not at all distinctive. This also the reason I sold Walker Greenbank a while ago as they continued to deny that people would buy many of their products, such as wallpaper, on the internet, apparently failing to realise the value of digital/internet marketing. However, I think things are improving there now, although I worry about their sales in department stores.
The Chancellor has said there will be a digital sales tax on profitable companies making over £500m online revenue from UK consumers. The Treasury twitter channel says this will be a 2% tax. Details coming out soon but sounds like it might hit more than just "internet giants" like Amazon. Could be quite a big deal for low margin online businesses like AO World (LON:AO.) and maybe affect Boohoo (LON:BOO) perhaps? Need to see detail...
I'm getting old so short term memory not what it once was but didn't he say that this wouldn't apply to sales of consumer goods as that would effectively hurt the consumer??
The Chancellor said the digital services tax would not apply to online shopping as that would be a tax paid by consumers.
It's aimed at Facebook, Google, Netflix etc. Which is why he said he expects to receive a phone call from the former Deputy Prime Minister.
.
More detail now published: https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/752172/DST_web.pdf
It sounds like it will just apply to search engines, social media sites, and online marketplaces (which is about user-to-user transactions so maybe sites like AirBnB?). AO World (LON:AO.) and Boohoo (LON:BOO) are probably safe for now. Although it does set a precedent that could be later extended.
Ranting! - thought better of it and removed
Paul
have you given much thought to the impact of IFRS 16 on retailers? looking at DEBS, this will bring about £2.5bn more 'debt' on balance sheet, operating profit will increase hugely as the rental expense is accounted for mainly as interest expense but leverage will be reported at about 7 times and interest cover will only be about 1.1 times. the impact is understood by sellside analysts and many fund managers but I wonder how many retail investors have grasped the impact.
Hi Hornblower,
The accounting changes, to bring retailers lease obligations onto the balance sheet, are completely nonsensical. I will just adjust them out.
If a store is profitable, then the future rents are not a liability. You should be looking at that store as an asset - because it's profitable. Why bring its future rents onto the balance sheet as a liability? It makes no sense at all. There will be future sales which will pay the future rents, and if it's an overall profit, then that is not a liability, it's an asset.
The accounting proposals are total nonsense, and are likely to be binned quite quickly, in my view.
What we REALLY need to know is this - a table, which gives every store, anonymised for commercial reasons, together with revenue, profit, length of lease, current rent, date of next rent review, expected rental increase at next rent review, any break clause, etc.
Then below it, we need a total of store contributions, and below that, the central costs.
This information is the bare minimum we need to assess future profits of retailers. The accounting standards do not get anywhere near this, so they're utterly useless.
Next (LON:NXT) is the only company which has provided any meaningful information on this subject. It's probably the only one worth investing in too, for reasons explained previously - more than 50% of profits are now online - God knows how though! I bought 2 suit jackets & several shirts from Next Online recently. They turned up in 3 parcels over 3 WEEKS, and ever since they've been sending me marketing emails about womens bras & such like! They don't seem to be able to identify the gender of the customer. How ridiculous! I've heard about all this gender fluid business, but it's not for me! I like being male, and certainly don't want to swish around in a bra! So NEXT can take a running, swinging, double-D jump as far as I'm concerned!!
Regards, Paul.
Paul - "They turned up in 3 parcels over 3 WEEKS, and ever since they've been sending me marketing emails about womens bras & such like! They don't seem to be able to identify the gender of the customer. How ridiculous! I've heard about all this gender fluid business, but it's not for me! I like being male, and certainly don't want to swish around in a bra! So NEXT can take a running, swinging, double-D jump as far as I'm concerned!!"
It MAY be that their marketing is more clever than you're making out. As a Sosandar (LON:SOS) holder, I presume you check out their website occasionally, and the cookie information from this could be used by Next (LON:NXT) - I've had numerous occasions where Facebook adverts have been quite specific (and irrelevant to me). I then realised someone else using the same router, had been researching things similar to the adverts I received - Train tickets and hotels in Liverpool (I think) - quite eerie/worrying that 'data' from their laptop was picked up by my laptop/browser.
Paul, I share your aversion to aviation shares generally, but there is a case for GMAA imho. Recurring revenues, driven by compulsory maintenance schedules, and with growth underpinned by the growth in private aviation. And hard to see it being disrupted by the Internet!
I look forward to hearing from GMAA at Mello, and feel the current price offers real value.
Jon
If you're interested in the Tech sector, here's an interview with Gareth Evans, founder of Progressive Equity Research, and ex Head of Research at Investec, discussing tech: valuations, where we're at in the cycle, winners and losers, and his views on the sector going forward.
We recorded this last week, it was informative and heartening amongst crashing tech (and other) stocks.
https://www.piworld.co.uk/2018/10/29/tamzin-talks-tech-with-gareth-evans-from-progressive-equity-research/
We're really grateful to Gareth for so generously sharing his insight and knowledge.
Ref Hydrogen (LON:HYDG) (LON:HYDG) a sell alert was issued by a tip sheet just before 11.30 this morning
Interesting. This only came on my horizon yesterday reading the latest copy of Shares. It is Jeroen Bos’s largest holding in his Deeo Value Fund:
“Hydrogen Group continued with its good run to such an extent that the holding hit the 10% limit and we had to sell a few shares.” - http://www.ch-investments.co.uk/sites/default/files/downloads/ch-deep-value-investment-factsheet-october-2018.pdf
I was certainly going investigate further with book value above mkt cap.
Stockopedia algorithm liked it (Super Stock and SR of 92) so does the market no something we don’t? Did the tip sheet say why? Which one was it?
Thanks for that Dickshorty - a poster on ADVFN said something similar so it seems plausible.
Totally bonkers it seems to me - although the current shareprice only reflects a low about 4 months ago.
So did the "tip" from these people create a spike that is now bust or is their sell recommendation genuinely bearish?
I actually don't know, but I'm tempted to think is is a buy opportunity.
Did they get wind of IR35 being extended to the private sector? I'm not sure how problematic, in general, this is going to be to the recruitment sector, but had a significant impact when introduced into the public sector going from memory.
Phil
( Hydrogen (LON:HYDG) )
The poster over on ADVFN said that the tipsheet cited industry headwinds so that could have included a view on IR35.
Meanwhile, the company thought it was a buying opportunity too and bought back 98,000 shares at 45.6p.
Clearly opportunistic as they do not have an active buyback programme AFAIK. Or perhaps just a novel way to tell us that they have no unpublished share price impacting information.
I joined them in a small way.
An astonishing fall today of around 30% for Hydrogen (LON:HYDG) on no news (as yet). Seems to have kicked off from about 11:30 with a large number of relatively small trades. Is anyone aware of any news I have missed?
Paul, I would be interested in your take on Victoria (LON:VCP) (Victoria) margin fall and bond issue. Following its 22% price fall this morning it now qualifies as a small cap. Unfortunately I hold.
Richard
Hi RichardK,
Yes, Victoria (LON:VCP) does look interesting. Providing there's nothing catastrophic in the Budget, I'll have a look at it later!
Regards, Paul.
Not a small cap, but I was wondering if there was any useful read-through from the good HSBC Holdings (LON:HSBA) results for some of the smaller "challenger" banks.
My reading is that a lot of the positive performance at HSBC Holdings (LON:HSBA) is down to strength in Asian markets, so may not directly read across to "challenger" banks in the UK.
For what it's worth, I do think at least one or two of the challengers will end up making great investments. However I'm also convinced that it's a hugely competitive sector and there will certainly be casualties along the way.
Metro Bank (LON:MTRO) has bounced nicely today after almost halving in the year to date. Valuation still looks rich even after the falls though!!
I was wondering to what extent £HSBC, and others, are starting to benefit from a changing interest rate environment. I agree about the rich valuations for the "challengers". How many of them are going to be able to compete successfully for deposits when the going gets a bit rougher?
Paul has said that he prefers Malvern International (LON:MLVN) to Wey Education (LON:WEY) though I can't recall whether he said why.
EDIT It was the strength of the management team. (SCVR Oct 1st, in the section on WEY).
I'd be really interested in Gama Aviation (LON:GMAA) please, Paul, should you have time.
Thanks,
IG
Strange times. Some prices seem to be discounting Armageddon. Marshall Motor Holdings (LON:MMH) (which I hold) now has a SR of 90, a decent balance sheet, and a dividend yield higher than its PER.
Warpaint London £W7L please
Disappointing to say the least, but international expansion very encouraging for the long term and today's drop - although consistent with profit warnings today, seems overdone
The Warpaint (W7L) downward revision is disappointing. While it is true, as mentioned in the trading statement, that the full year Is heavily dependent on H2 and Christmas gifting; the outlook statement at the half year stage (only released on 17 September - 42 days ago) stated that the increased order book gave “visibility and confidence in the full-year outcome”.
Good morning all. I would appreciate reading opinions from any quarter on the following (no positions): ITM Power (LON:ITM) £27m in the bank (apparently), everything seems to be going well except the mention of actual profit,
Wey Education (LON:WEY) pretty strange accounts, seem to be emphasising doubling of EPS as long as you exclude exceptional spending, spending which, if they continue to attempt to expand into Nigeria and China, would be set to continue. I sold out but seems that if they give up on foreign escapades they might actually be in profit again, though how much of their increased EBITDA is due to the acquisition of Academy 21, 'provider of online secondary teaching to pupils in the state school and other public-sector bodies.' Still think the sector has potential but like Paul I've learnt there's more competition than I thought (no position).
£W7L sounds like a coded warning for a slow UK festive period.Edit: Down 40% Yoinks. Commiserations to holders in what I still think is a good company. No wonder so many others are seeking to diversify out of Britain.
Wey Education (LON:WEY)
Revenue beat: £4.2m vs forecast of £4.1m.
EBITDA miss: £0.45m vs £0.53m
FD Adj EPS miss: 0.33p vs 0.39p
Statutory EPS: loss of 0.16p vs profit of 0.02p for FY2017.
Cash: Arguably contradictory, stating >£4.0m in the headline results and >£4.2m later vs £4.0m forecast.
The forecasts are from WH Ireland (house broker) issued on 23th August and were restated recently with a hint that revenue might be beaten. Prior to May 2018 the revenue forecast was for £4.8m. The FY2017 profit figures now claimed by the company differ from the broker's historical figures, but regardless of the basis they still seem to be a clear miss.
Presumably WH Ireland is in the process of releasing updated (lowered) FY2019 estimates to reflect this. These are not yet on Research Tree and in the past private investors have generally been required to pay for it (i.e. a second time, given that WEY pay for it).
On the plus side organic revenue growth is confirmed to be growing at well over 20% which (on the assumption this can be converted into profits...) is my main reason for investing.
There are many red flags here but then they have sold off significantly into the run up to these results. I'm still reading and won't be able to form a firm conclusion before 8:00.
Thanks @leoleo73 . I dislike the presentation of the accounts at Wey Education (LON:WEY) with their emphasis on "Adjusted EBITDA" - which translates as "profit before bad stuff": exceptional costs, share awards, as well as depreciation and amortisation. I can't see any detail on the exceptional costs, or why they won't recur in following years. This business should be scalable and have attractive economics now that it's got going, but the investment case is harmed by the presentation of accounts.
Also thanks for pointing of the difference between headline cash number "over £4 million" whereas later in the commentary it says "over £4.2m" which agrees with the cashflow statement. Seems odd.
Wey Education (LON:WEY)
Whilst agreeing on the accounts presentation (they do seem almost apologetic in their presentation of adjusted profit following the grief they got on the interim accounts) , I'm more forcused on the outlook.
They have stated their "prudent" expectation of 66% turnover growth and this is without any froth from international expansion. Consider this makes Wey Education (LON:WEY) quite interesting from a growth perspective.
WH Ireland have intially gone for a 79% increase in their forecasts for 2019 - whilst this is down from their last forecast of @100% I always thought that too aggressive.
As always, time will tell.
Phil
Wey Education (LON:WEY) - WH Ireland have reportedly cut FY2019 revenue forecast from £9.6m to £7.5m and updated their FY2020 guess from £14.5m to £12m.
Credibility of forecasts is a major concern here. If the pattern of downgrades matches last year's then the outturn will be approx. £6m for FY2019 with FY2020 being well under £10m.
My morning smallcap tweet: Pursed lips for Warpaint holders.
Gama Aviation (LON:GMAA), £W7L, Gordon Dadds (LON:GOR), Lok'n Store (LON:LOK), Ten Entertainment (LON:TEG)
Gama Aviation (GMAA) curse of H2 weighting. Guides FY $3m op profit below its original expectations.
Warpaint London (W7L) guides FY rev only £48 to £52m. F/C was for £55.2m. Guides pretax £8.5m to £10m. F/C was £10.6m. IPO 2 years ago.
Gordon Dadds Group (GOR) confirms merger. Buys Ince & Co International for £34m (adjusted for 3 year rev). Shares will remain suspended.
Lok'n'store Group (LOK) FY rev in line, adj EPS beat (I think) at 12.83p (dil) vf F/C 11.9p. Adj NAV/sh up 15% to 480p. SP was 374p.
Ten Entertainment (TEG) CFO off to Prendragon. The shocking news is he'll serve his notice period of 6 months. He is thanked.