Small Cap Value Report (Mon 3 August 2020) - HMSO, DISH, TGP, PURP, SEE, BYOT, INCE

Good morning, it's Paul here with Monday's SCVR.
Please see the article header for the companies I'll be reviewing today, which have issued trading updates or results.
Estimated timings - I lost the section on PURP, so had a re-create it from memory. Hence running a bit late. Should be finished by 3pm. Update at 15:42 - today's report is now finished.
.
Hammerson (LON:HMSO)
Share price: 58.3p (down 9% today, at 10:45)
No. shares: 766.3m
Market cap: £446.8m
- Considering a rights issue.
- In advanced discussions to sell its 50% stake in VIA Outlets.
- Approved for£300m loan from Bank of England (CCFF scheme)
- Q3 rent collection improved to over 30% (still sounds awful)
My opinion - this share looks finely balanced, so I'm watching from the sidelines. I held it recently, but sold out once it became clear that the economics of its shopping centres don't work unless footfall returns to normal, and tenants can pay rents that are far too high for market conditions. Nobody knows what the new normal will be though. Hence I feel it's almost impossible to value this share at the moment.
Bigdish (LON:DISH)
(I'm long)
Another day, another operational update!
TGI Fridays has joined its ordering app, as have 500 more M&B sites. Therefore the 1250 new sites announced recently, has become 1850. Seems to be gaining traction in terms of restaurant recruiting. The platform is free at present. Needs to raise more funds this autumn.
Tekmar (LON:TGP)
Share price: 110p (down 3.5% today, at 10:56)
No. shares: 51.3m
Market cap: £56.4m
(I'm long)
Tekmar Group (AIM: TGP), a leading provider of technology and services for the global offshore energy markets, announces its final results for the year ended 31 March 2020 ("FY20" or the "Period").
I did some research on this company earlier this year, and like the look of it. It's a profitable supplier of niche products mainly for the offshore wind farm sector - cable protectors. It's also diversified into other subsea markets (oil & gas, less than 20% of revenues), and growth is both organic and by acquisition. This is a good growth area. Performance was dented by covid, but the figures overall look quite decent to me in the circumstances.
Our trading update stated we expected our results to be broadly in line with those achieved in FY19, and I am pleased to report this was achieved.
Actual adj EPS is 5.8p (LY: 6.2p). PER isn't very useful at the moment, because earnings would have been higher, had it not been for disruption from covid. But for the record, PER is 19.0 - if we were to normalise earnings to exclude the impact of covid (which is reasonable in my view), then the PER would come down to probably the low teens.
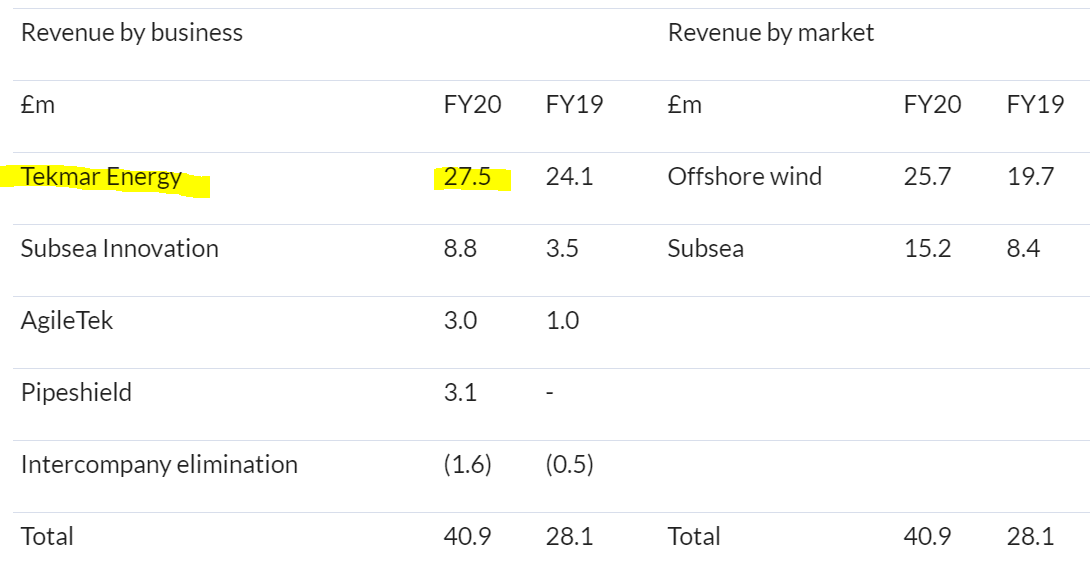
This is a useful table, as you can work out that the organic growth is a lot lower than the total growth, but still not bad;
.
.
Balance sheet - NAV: £46.0m, less intangibles of £26.3m, giving NTAV: £19.7, which looks solid for the size of the group.
Receivables stands out as looking high, at £26.8m. Note 10 gives a breakdown, with trade receivables looking more sensible at £9.9m (around the level I would expect, relative to revenues). There's also £15.0m of contract assets, which seems a lot. An explanatory note says;
Trade and other receivables
We closed the year with trade debtors of £9.9m and contract assets of £15m. The majority of the latter sits within Tekmar Energy and relates to offshore wind projects that have large project milestones towards the end of the project that are not yet due for invoicing.
I'm not terribly keen on that. It introduces risk, that customers might challenge costs. Also why is a small UK company effectively bankrolling its larger overseas clients, by funding the work-in-progress? It would be better to negotiate payment plans with customers which better reflect the actual costs being incurred by Tekmar.
.
.
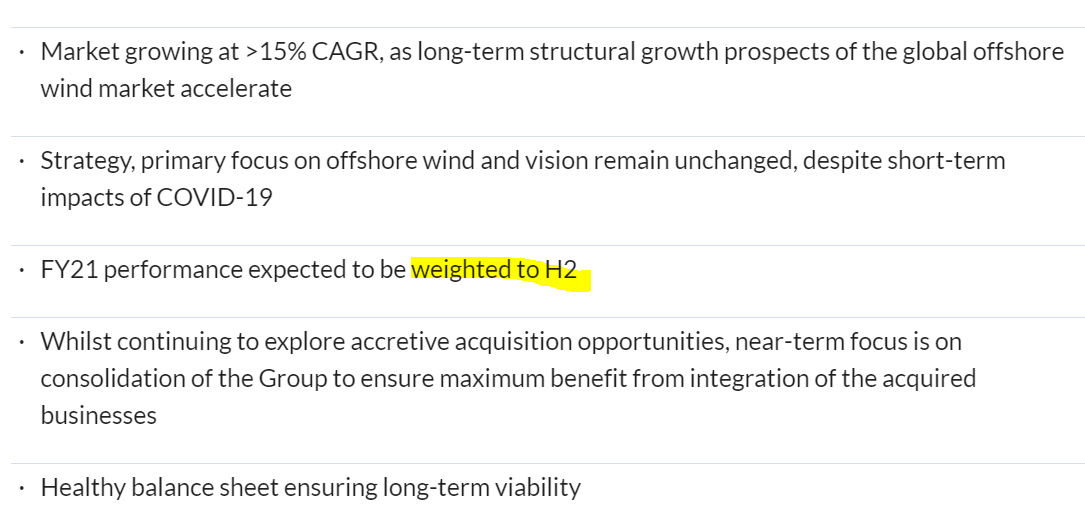
The Chairman sounds upbeat about the future;
"Whilst the level of growth in profitability in FY20 was inevitably affected by COVID-19 and the shutdown in China, our strong market position and track record in offshore wind cable protection projects remain unrivalled globally.
Our overall confidence in the prospects for the business should not be understated. I now see a Group which has truly been transformed and, with a much wider portfolio of complementary technologies, is able to offer an international customer base a unique customer-value proposition.
Coupled with a robust balance sheet, the Group is well positioned with a solid platform for growth over the next decade, which is supported by a positive market outlook, despite some short-term uncertainty as we transition through the COVID-19 recovery, which the Group has somewhat mitigated by receipt of a CBILS loan of £3m post year end."
My opinion - an interesting collection of niche businesses.
A while back, I found it very difficult to buy this share, as the market is so thin, so after 2 days trying, and only getting a scrap of shares I gave up. Perhaps management could work on a strategy to improve market liquidity, otherwise what's the point in having a listing?
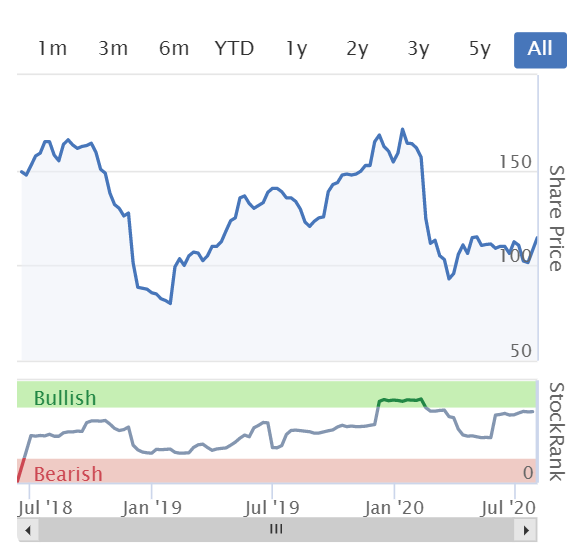
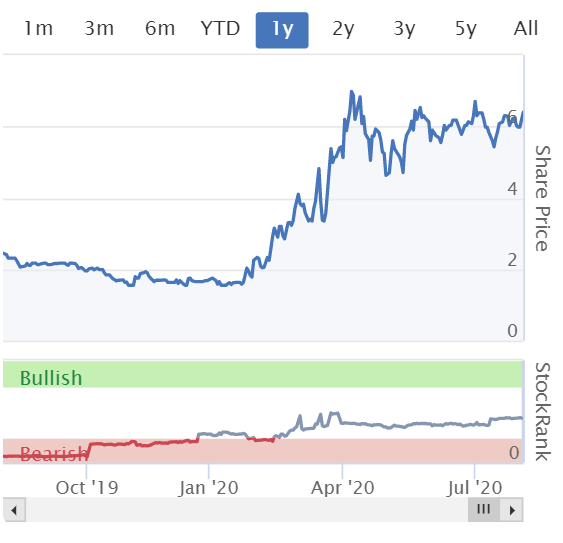
Note that the StockRank has been good since it floated in June 2018.
.
.
Nightmare, I've just lost the whole section on PURP, so will have re-create it from scratch. Apologies for the delay.
Purplebricks (LON:PURP)
Share price: 50.6p (up c.8% today, at 13:17)
No. shares: 306.8m
Market cap: £155.2m
Purplebricks Group plc (AIM: PURP), a leading UK estate agency business, announces its results for the year ended 30 April 2020 ("FY 2020") and provides an update on strategy and current trading.
Results for FY 04/2020 are of limited use, because they include Canadian operations, which were sold post year end. This has resulted in a very healthy cash pile of £66m, and UK operations trading at around breakeven. Being on online only business, it can dial marketing spend up or down, so profits are more a policy decision than a measure of performance. There's also a JV in Germany.
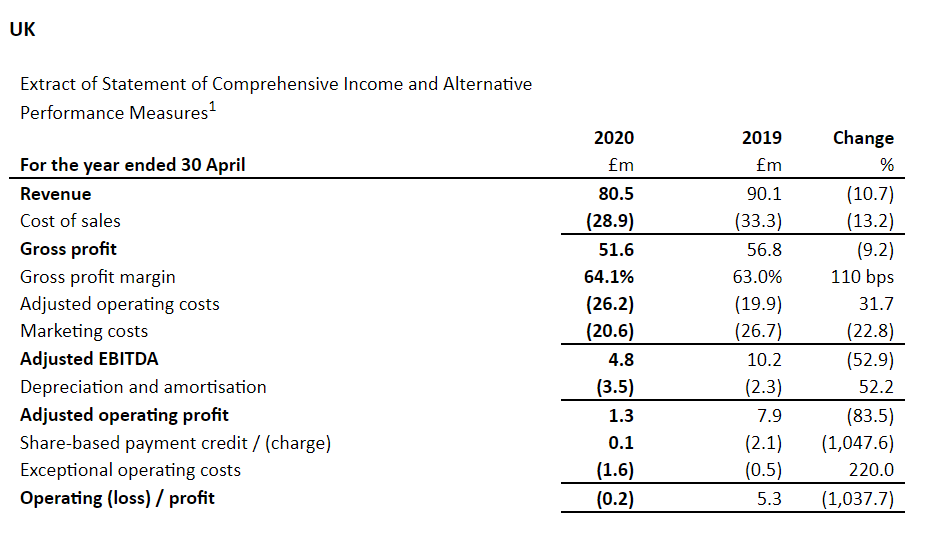
Here's how the UK performed;
.
Not great, with revenues down vs LY. Note how marketing spend was reduced, to arrive at a roughly breakeven result.
Current trading/outlook - market recovering well since mid-May. Record month for instructions in July 2020. Uncertain outlook. Stamp Duty holiday helping demand.
Pricing model - this is an important point. PURP has been criticised for its up-front charging model, leaving a long trail of dissatisfied customers whose properties fail to sell. As PURP collects its fees up-front, then it has no incentive to push sales through to completion. It sounds like this point is at last being addressed;
Evolving our pricing model
We have a business model that is based on value. It's unrivalled in the marketplace and offers consumers the opportunity to sell their homes for a fair, fixed fee. This single-minded proposition has got us to where we are today and created a business model that has resulted in Purplebricks becoming the largest estate agency brand in the UK. However, we also recognise that, to extend our market leadership, we'll need to evolve our pricing. That means looking at different pricing strategies to reduce the up-front fee and splitting the payment between listing and completion.
Following an in-depth pricing study in the first half of the year, we had hoped to pilot a new pricing structure in early 2020, but the lockdown has delayed this to the autumn. I believe reducing the level of the upfront fee will widen the market opportunity significantly, although a fixed fee element will remain a critical part of our success, as hybrid adopters remain more motivated to sell their homes. Reducing the upfront fee will reduce the barrier for many customers in instructing us - while higher fees on completion will allow our LPEs to earn more from each sale, ensuring our self-employed model will not only remain sustainable but become more attractive to the best talent in the industry.
My opinion - with most overseas operations now out of the way, this is a more focused UK operation. I haven't looked into the Germany JV, but note PURP has gone over 50%, so it should now be consolidated into future group results.
Valued at £155m, I think PURP is starting to look interesting again. With £66m in the bank, it can continue to out-spend the competition on marketing. There used to be lots of online estate agents, running TV ads. I wonder how many have since gone under? PURP has emerged the clear market leader. This, combined with its very well known brand name, means there could be interesting value here. If that cash pile is spent wisely, then it could broaden its lead. Speculative, but gets a thumbs up from me at 50p per share.
.
Seeing Machines (LON:SEE)
Share price: 3.33p (up 7.3% today, at 14:00)
No. shares: 3,365.2m
Market cap: £111.1m
Seeing Machines Limited (AIM: SEE, "Seeing Machines" or the "Company"), the advanced computer vision technology company that designs AI-powered operator monitoring systems to improve transport safety, provides a trading update for the period ended 30 June 2020 ("FY2020").
As you can see from the Stockopedia graphs below, performance of this company has been very disappointing historically. Look at the share count too, it's increased about 5-fold since 2014, with repeat fundraisings.
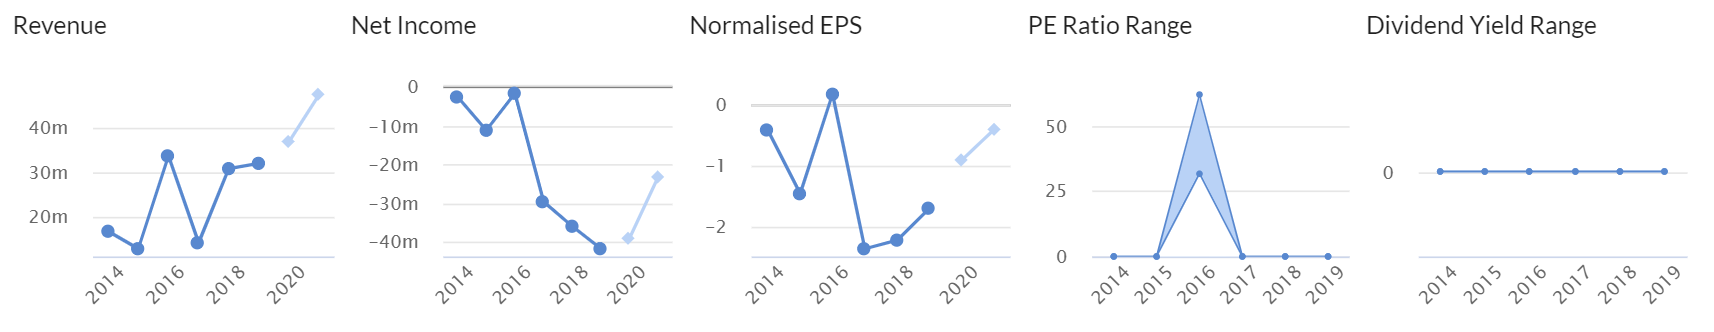
The numbers above are reported in Australian dollars. Current rate: £1 = A$1.84
Today it reports limited info re FY 06/2020 results;
- Revenues A$42.6m (up 30%)
- Cash A$38.7m
- No mention made of losses (which are still substantial)
- Transport sector impacted by covid
- Launch of 2 vehicles incorporating SEE technology in coming months
- Expecting connections to accelerate
My opinion - I've followed this company for years, and it constantly disappoints with continuing, large losses. Nevertheless, the technology is important, as it prevents accidents (monitoring the driver's eyeballs). The big hope for this share was always that it would achieve mass market adoption. That's been painfully slow to date.
Maybe it might make a big breakthrough? Given the poor track record, I'd take a lot of persuading to pay £111m market cap for things as they stand now. Mass market adoption of the product could however be a game-changer, so who knows what the future holds?
.
Byotrol (LON:BYOT)
Share price: 6.4p (up 7% today, at 14:38)
No. shares: 442.8m
Market cap: £28.3m
Byotrol plc (BYOT.L), quoted on AIM, is a specialist infection prevention and control company, operating globally in the Healthcare, Industrial, Food and Consumer sectors, providing low toxicity products with a broad-based and targeted efficacy across all microbial classes; bacteria, viruses (including coronavirus), fungi, moulds, mycobacteria and algae.
Today's update relates to FY 03/2021.
Trading for the current financial year to 31 March 2021 remains strong across the whole Group and multiple opportunities continue to be available, across both product sales and IP licensing.
Product sales for the first quarter to 30 June exceeded £3.4m and orders for July and August continue to look encouraging. Our order book at the end of June stood at approximately £2m. Our current net cash position is healthy at £1.8m.
Whilst it is early in the year, assuming continued easing in supply chains and a relatively orderly Brexit, the Board would expect revenue and EBITDA for the current financial year to be significantly ahead of current market expectations.
We could have used a footnote, to tell us what market expectations are. FinnCap to the rescue, with an update today which is available direct from FinnCap or via Research Tree. Adj PBT is raised to £1.2m, and adj EPS 0.3p - a PER of 21.3 - quite a punchy rating for a tiddler.
My opinion - clearly Byotrol is in a good space, specialising in infection control. So the burning question is whether this is a one-off bonanza year due to covid, or whether stronger performance has longevity? I don't know the answer to that, so have to say I'm neutral. The share price has already tripled due to covid. I've seen other companies launching sanitiser products, so wonder if there could be downward pricing pressure, as supply matches or exceeds increased demand, perhaps?
.
.
Ince (LON:INCE)
Share price: 26.5p (down 7%, today at 14:58)
No. shares: 68.5m
Market cap: £18.2m
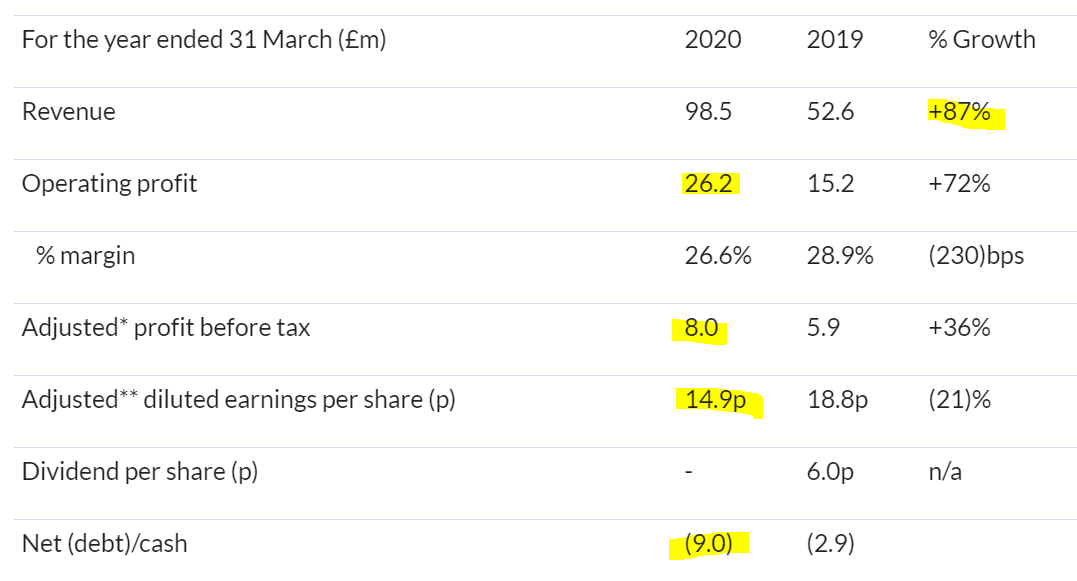
Subscriber fwyburd flagged these results first thing, as the share does indeed look incredibly cheap from the highlights section. Why would a company producing these figures be so cheap? There has to be a catch!
.
.
Note the large difference between £26.2m operating profit, and the much lower £8.0m adjusted PBT.
Also, given that adj PBT is up 36%, why would adj EPS be down 21%? That implies a large issuance of new shares, perhaps? Or a large tax charge, or a combination of the two. Note that it raised £14m in fresh equity in Deb 2020.
Net debt of £9.0m doesn't look excessive, which would have been another reason why the market cap would be so low.
Re-reading my notes previously, it's coming back to me. This is the company that did a terrible fundraising at a 50% discount, in Jan 2020 (before covid), which I was pretty scathing about here.
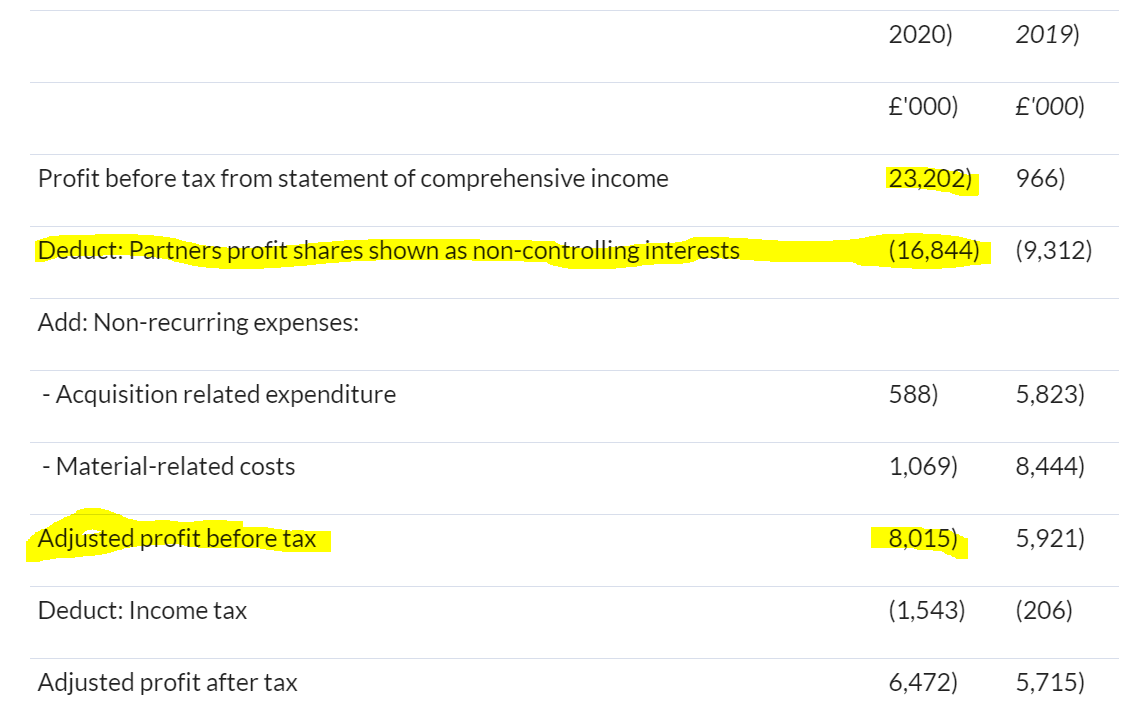
Non-controlling interests - used to be called minority interests. This shows what proportion of profits are attributed to minority shareholders within group subsidiary companies. I can't recall ever seeing a number as large as this, below (note 11 to today's accounts);
.
.
Hence the operating profit number is of no relevance, we should be focused on the adjusted figures.
The cashflow statement shows a cash outflow of £15.5m, called "Transactions with non-controlling interests". Therefore, the minority shareholders seem to be extracting most of the cash for themselves. How come? Does anyone know more detail re this strange structure. It doesn't strike me as a very good deal for ordinary shareholders!
Balance sheet - this is also a can of worms.
NAV: £51.3m, but of that £9.1m is non-controlling interests (minority shareholders in subsidiaries), so NAV owned by INCE shareholders is £42.2m.
Intangibles are £80.8, hence NTAV is heavily negative, at -£38.6m - or in common parlance, shot to bits!
Receivables look very high, so there could be some write-offs needed there.
Anyone interested in this share should look at the liabilities side of things, shown in note 21. Liabilities include £14.6m in deferred consideration (for previous acquisitions) payable in the next year, and £21.1m long term deferred consideration. Where is the money coming from, to settle these liabilities? It's almost twice the current market cap!
My opinion - this looks a real mess. Uninvestable as far as I'm concerned.
.
All done for today, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
#INCE there is an explanation here (if this link works) Ince Group: Explainer Note – Partner Remuneration (research-tree.com)
very useful analysis - thank you
Hi Paul - re. your question on Ince (LON:INCE) minority interests - I haven't looked at this for their specific case at all, but I suspect the clue is in the description: "Partner profit share shown as non-controlling interests". Looks likely that this has been structured so that the partners in the firm take out their profit share (or at least the bulk of it) as a fixed share (non-equity) drawing rather than as shareholder profit/dividends. Law firms as listed entities are an odd phenomenon and are probably much better suited to the traditional partnership model. Essentially, the entire valuable business of a law firm is the Partners (unlike a company where the management team steward the company but they are not also the entire substance of what the company is selling as well) so the Partners (fair enough) expect to take most of the profit for themselves as compensation for that - but that arrangement fits much more neatly with an LLP than a listed company in my view. I think professional services of this nature are all uninvestable - shareholders are always going to get a raw deal when you have a business run by Partners who start with the perspective that this is their business and they deserve all the profit and the listing is just another way of capitalising that business. If you were considering an investment you would want to know (i) that there was a truly independent board (not comprised of lawyers/partners of the firm) controlling things and having full control over partner remuneration, (ii) that the partners remuneration is very heavily based on shareholder return/dividends and not by way of fixed share or salary and (iii) that there are very robust lock-ins for the key rainmaking partners so they can't just resign and set up their own firm competing with the business (the listed firm would collapse overnight if the key partners left). I've yet to find any listed law firm that looks like a good bet for an outside investor.
BIACS
£XLM Stocko has upgraded XL Media from Neutral to Turn Around.
Paul
re Byotrol (LON:BYOT) the CEO gives a really good summary of why sanitisers are under regulatory pressure in video in below link, so you are actually likely to see supply dropping rather than increasing. They are fully reg compliant so benefit from this effect. I haven't spent too much time on the Tristel (LON:TSTL) tie up and in my own numbers have discounted that revenue stream to zero, though from Tristels latest update I think that's highly unlikely and could be very material in time. I have looked at the eps in the brokers forecasts and suspect they are light. I think there may need to be considerable upgrades over the next 6-12 months.
https://www.proactiveinvestors...
Tekmar
Founder & CEO has resigned:
https://www.investegate.co.uk/...
Holding quite a large position in Purplebricks (LON:PURP) I thought it would be worth sharing some of my thoughts from today's results.
As I scanned the results first thing, my initial reaction was actually disappointment , but the more I look into it, the more optimistic I am.
Note that the results published today include the Canada business, which is now sold off, so all the comments below relate to the UK business only.
If there was 1 negative to take away it was the Year-on-Year decrease in H1 (so up to October 2019). This was a relatively long time ago now, and it's not clear what happened here (Brexit-related uncertainty perhaps? - I saw a comment saying UK listings were extremely low in this time period), so the revenue growth at the start of H2 is one to keep an eye on.
VALUATION
It's probably also worth noting that the first 10 months of the year generated EBITDA of £5.7m and the last 2 months of last year generated £1.9m EBITDA. Combine these together gives a pre-covid Last 12 Months EBITDA of £7.6m.
Underlying capital expenditure (including capitalised development costs) have been <£3m for the last 2 years, so an underlying positive cash flow of c £5m.
The current EV of the company is £77m.
Given the operational leverage a company like this will have, this still looks cheap to me.
If only the share price knew that.
A
I agree this should be a winner in this space. The key for me is two things. One, having enough good local property experts and two, offering top notch customer service throughout the transaction. If they can do this then the model should be able to disrupt the space to a huge extent. I guess the trouble is there is not much evidence of good management in the business so far so they could probably do with some more talent at the top!
abtan - thanks for sharing your analysis and thoughts. The UK estate agent market always felt ripe for disruption with it's combination of high fees and generally poor service. The Purplebricks (LON:PURP) challenger business model intuitively appeals.
Looking through their numbers it's disappointing to see their costs growing broadly in line with sales and gross profit. This morning's announcement states that "Improved UK marketing spend efficiency at 25.6% of revenue, down 400bps" so perhaps the divestments of the Canadian business and focus on the UK will reduce costs and lead to positive operating margins.
I guess the real question here is one of scale - their low cost business model requires a significant volume of business to cover their costs. Hard to know how much of these costs are fixed and how much variable. They currently have around 5% of the UK market by volume, so there's clearly plenty of market still to go at. If they can grow share and manage costs then the business model looks attractive. So far they've struggled to contain costs and growth has been more sluggish than perhaps expected. For me they've yet to prove the viability of the business model. One to watch...
Purplebricks (LON:PURP)
Agreed costs have risen with sales, though I don't see it as concerning at this stage, especially as the company is cash flow positive (unless I've missed something).
Fingers crossed!
A
EDITED POST
Shirley some mistake abtan?
Cost up by more than Gross Profit and EBITDA goes through the roof?
Not sure it is a dream, it might just be an hallucination?
Haha, indeed a mistake. Thanks for pointing out.
Sorry, rushing around, "dream scenario" has (sadly) been edited from the previous post.
Definitely cashflow negative! Burnt through £90m last financial year, which to be fair does include £27m on acquisitions, but even so... Prior year (2018) was £20m outflow once the equity raise is removed.
Purplebricks (LON:PURP)
Hi Man of Steel
The company has certainly been cash flow negative in the past, but a lot has changed in the last 12 months eg they've closed down or sold ALL their loss-making businesses (i.e. US/Canada/Australia).
Plus they had all that Woodford cash to use.
The UK operation by itself, which is all that remains, is cash flow positive from everything that I can see. I'm sure this will be clearer in the next results, which will exclude the Canada business.
This from today's Annual Report:
Adj EBITDA is positive, there's £1.6m exceptional item relating to a legal ruling that went against them (and certainly appears exceptional) and Capex each year is well below this (as mentioned <£3.0 in each of the last 2 years).
In the presentation today the company even said they were cash flow neutral in Q1 (and this includes setting up a £2.2m fund for their contract estate agents; I think only about £0.5m had been paid out of it at year end, but need to double check).
They have used the furlough scheme, but don't plan to claim the £1k furlough bonus scheme.
Happy to be corrected if I've misunderstood anything.
Cheers
A
Abat - you're correct. I had a dig through the Annual Report and the UK business is now cashflow positive. The company is making sensible strategic decisions by divesting it's loss making overseas businesses and focusing on the UK. It will be interesting to see how many of the exceptional items and consolidating adjustments disappear from the future numbers. In theory they should all do so, meaning that the UK numbers become the Group numbers, but experience suggests that isn't always the case. Not withstanding this, it looks like the company is now on a better path than it was in the past, so positive progress.
Hi
With my sample size of me (1) I had a very painful experience of using Purplebricks (LON:PURP) trying to rent a flat whilst I was working away from the family home. What was a nice 2 bed flat in a great location, but basically the landlord was trying to do everything very cheap. There numerous mistakes made on contracts and timings etcetera and I ended up walking away after constantly checking, correcting and having to chase myself to both the "local expert" he just showed people around due to the owner living out of the UK, and the back office who were doing the paperwork.
Similarly when there were issues with buying the current family, thankfully all resolved, we looked at a couple of other houses one with £PURP. As a family we were not shown round by a "local property expert" but by the owner, who admitted they were only using Purplebricks (LON:PURP) to save money. We noted that the photographs on the website were basic, and the owner basically said the person came and shot them in about 10 minutes. I talked to them about the house we were selling the agent took a first set, and had us moving things, tidying up and removing kids things, and turning on all the lights etcetera, the agent then came back on a sunny day to take further pictures of specific rooms and outside the house, they said they had got none off that advice. Maybe just a poor person in our area?
I would add the owner was doing all the showing around, and again could really have done with watching some of the Property shows that abound, on how to prepare ahead of a viewing and also how to act.
So overall conclusions, yes Purplebricks (LON:PURP) definitely have a place in the market for easy to sell and standard houses but the service side needed a lot of work, the question is how large a % of the UK market can they get and can they get enough freelance staff to work with them?
Tommy
Just noticed, and a major mistake of mine costing me -21%.
Stagecoach (LON:SGC) has now been downgraded to Value Trap and shows a 5% drop on today alone, StockRank downgraded to 53.
Had the Lock Down gone the other way, Stagecoach shareholders would not be feeling so miserable today, but its clearly obvious that buses and passenger trains are not going be profitable businesses for the short to medium term, with their revenue coming from Government grants principally.
I'm selling my corporate holding and using the loss to neutralise some tax. Yuck. Personal holding also gone.
Hi Paul, thanks for the great updates, so helpful to a novice like me.
Considering the new operational update from Big Dish it would be interesting to hear your views on how this differs from another company that releases regular operational updates Optibiotix Health (LON:OPTI) as I know you're a big fan. (Jokes) Both companies have small revenues and are pre-profit so on the surface quite similar from that perspective.
Haha, nice try, but you're not going to suck me into that particular black hole!
Haha, it was a genuine question, the fireworks that would have resulted would have been a cherry on top.
Thanks for the reply though, keep up the great, informative work
Byotrol (LON:BYOT) trading statement looks interesting this morning. Surprised not to see it up considerably more to be honest.
they are doing £1.2m p/m at present. order book is same as it was in April at circa £2m so that implies to me that demand is consistent. Brokers have significantly upgraded targets and now have 2021 at revenues of £11.5m but that still looks light to me and I expect the earnings upgrade cycle to continue. At present run rates are closer to £15m so there is a lot of margin for error factored into forecasts. Somehow I can't see demand being the problem given the products they are selling and the obvious advantages. you'd expect it to be more a function of how much they can grow/capacity.
Argentex (LON:AGFX)
Hi Paul, could you take a look here, the update looks very good to me (and a slightly gushing chairman statement for lord digny jones), but its down 10%. Is it a miss, i cant see it stated if they are inline or not?
I hold AlphaFX instead of this as Alpha FX (LON:AFX) had much more focus on technology but Argentex (LON:AGFX) state they have launched an online system too, it was an obvious question to me of why no online trade booking, now they have it.
This market they are both in is wide open as the banks are terrible at corp fx. They both seem good growth businesses.
Thankyou
BTW - Investor's Chronicle today gave Argentex (LON:AGFX) the thumbs up -a "buy"
I do not hold this
Just published Ig Design (LON:IGR) FY20 results presentation with Paul Fineman, CEO & Giles Willits, CFO. They outline the highlights, financials and strategy & outlook going forward.
Video and podcast.
Separately, we have two piworld webinars this week:
1. Imimobile (LON:IMO) FY20 results webinar: Wednesday 5th August, 10.30am. Jay Patel, CEO & Mike Jefferies, CFO will present the FY20 results, followed by a Q&A. Register here.
2. piworld Thursday webinar: Thursday 6th August, 1pm. Investor & Trader: Life in a Family Office. Richard Leonard (ex City) discusses how he manages money in a Family Office. Including, what he's learned from his mentors of the years. How it formed his investment philosophy. What he looks for. curret markets. What he's buying. Where to spot red flags, and much more. Register here.
Paul,
We be interested to read your views on X P Power - I hold. Looks to be a v strong performance for H1 2020 with a healthy outlook too. And the dividend has been restored. One of the better UK small cap shares trading internationally in my opinion, but I may be biased as an existing holder of course. Do you see any downsides?
Rfcg1
XP Power (LON:XPP) - as a long term holder I agree that it has done very well. However, that means it is hardly small cap now - it is in the 250 index.
Re Hammerson (LON:HMSO)
Apple wants up to 50% off rents
This sort of thing won't help generally. I believe Next (LON:NXT) have agreements in place where their rent is reduced if competitors around them receive CVA's
With Apples level of profits they are probably one of the least deserving of a 50% reduction. As it seems to be a suggestion for the future, the landlords need make no decision now and by the time the leases are coming up for renewal the situation with a successful vaccine may have completely changed. It is just a wait and see for landlords.
Apple have done fine with their stores shut. Microsoft decided not to re-open theirs at all.
So no business justification for paying premium rents.
Retail has changed forever unfortunately. And why shouldn't Apple try and lower their rents? Others are too. Footfall in shopping malls is way down.
Because The Apple model is service.
Granny/Grandpa goes to Apple because they get customer service in a store from a nice young person who is paid to help them read or delete an email or open a web link.
If you don't want customer service, go to Samsung (market leader) or Carphone Whorehouse (last man standing in consumer electricals).
Of course service is their model. But they are as entitled as anyone else to challenge the rent if footfall goes down.
There is responsibility within the freedoms of capitalism.
Do the the right things:-
Report clearly and fairly.
Pay your suppliers on time.
Pay your fair share of taxes on time.
Spread risk fairly and equally, not disproportionately against certain demographics, sectors and parties.
* You being corporates of course.
Because if they don't, eventually a counter-political party (Labour/Democrats) gets power and they then try to arbitrarily impose this through legalise which rarely works well.
"Granny/Grandpa goes to Apple because they get customer service in a store from a nice young person who is paid to help them read or delete an email or open a web link."
LOL
"And why shouldn't Apple try and lower their rents?" - because Apple have more cash on their balance sheet than the GDP of smaller European countries! It is utter greed to ask for such reductions in rent when so many individuals and companies are already struggling due to the Covid crisis.
I suppose that people are bringing their political ideas into this. Some believe that companies and individuals who haven’t run their finances prudently should be subsidised by those who have.
An interesting philosophical point, andrea 34. If rents are down across the board, the question becomes: why should Apple pay a premium on their rent compared to their retail neighbours? Should means-testing for companies apply? I suspect probably not.
Means testing already exists ...stronger covenants pay lower rent as they’re less risky
All we are seeing is an acceleration in trends where the number of flagship retail locations where landlords are in the driving seat has declined....massively...only Q is how temporary/permanent this shift is
It has changed until we have a vaccine. I think I was one of the first people in the country to use the internet when it took about ten minutes to dial in and subsequently we have bought almost everything that way. However, a lot of people like to go shopping and Apple are presumably in prime locations. The one I know is at the Trafford Centre and their shop and the whole centre was always heaving and often difficult to park despite having over 10,000 parking spaces. It is a destination that people want to visit. I know people who go just to walk around even if they don't intend buying. Once we have a vaccine this will come back quickly. So it depends on where the stores are. I am confident that in 5 years time there will be no 50% off rents in the Trafford Centre.
Hi billytk,
I remember Lord Wolfson of Next (LON:NXT) saying that he wanted leases which would reduce rent if shops nearby got reduced rents on CVAs, pre-packs, etc. However, I'm not sure he actually got what he wanted! In practice, the only time to negotiate such a deal would be when leases expire, or a break clause is available. Otherwise, landlords would just say no to such a request.
It would be interesting to find out if Next actually persuaded any landlords to agree to such a CVA/pre-pack clause? I could see it being workable where a landlord owns a whole shopping centre, but would be very difficult to work out in a High Street, where individual properties usually have different landlords.
New lettings from now on, will need completely different lease agreements. I think landlords will have to switch to turnover rents, as the only way to find new tenants. I'm a big fan of turnover rent deals. In my FD days, we had about 50 shops on turnover rents (nearly all in factory outlet centres), and the tenants/landlord have genuinely aligned interests. They're simple to administer, I remember my team drawing up the monthly rent statement - you disclose your revenue from the EPoS system, then pay the higher of agreed percentage (typically 8-12%) * revenue, or the base rent. Then at the end of the year, the auditors quickly check the figures, and sign off an audit statement. That used to be an add-on to the usual audit, so only cost about £1k per shop (that was about 20 years ago, so probably double or triple that now).
Practically every shop on a turnover rent deal was profitable, because the rent settled at a level where profits were almost guaranteed. The only problem was a shop in West Calder, where the outlet centre was dying a death, and we only took about £2k per week (less than a tenth of the more successful shops).
Regards, Paul.
From anecdote I think this is how Cabot circus in Bristol works for some of its shops.
But the min was set at a v.v.v. high level - that put of the freind of a friend who was running a magic trick stall off.
Be interested in your thoughts on Tekmar Paul. I appreciate they are hard to trade, but equally reckon sector going to grow 15% year on year and they are well placed globally. No debt although what are these CBILs??
Ive posted the M Winkworth (LON:WINK) update here, very upbeat/busy but will it last (as they say), either way a very downbeat update for such a key indicator would have been, well, a bit depressing.
Since 8 July 2020, when the Chancellor announced an easing of the stamp duty threshold from £125,000 to £500,000 until 31 March 2021, the Winkworth network has seen a significant recovery in sales interest, with sales applicants registering on the day after the announcement up 64 per cent. on the previous week. Website traffic hit the highest ever level on the day of the announcement. There has also been a material rise in the number of instructions and viewings since 8 July 2020, up 17 per cent. and 14 per cent., respectively, on the same period last year and by 13 per cent. and 22 per cent. compared to early June 2020.
Although the significant rise in activity is welcomed, it is too early to predict to what extent this will translate into completed sales and how sustained this increased activity level will be across the network. Accordingly, and although encouraging, it is not yet possible to predict the extent of any impact on Winkworth's financial performance.
Dominic Agace, Chief Executive of Winkworth, commented: "Post-lockdown, we had already seen a sharp uptick in activity, the result of the pent-up demand caused by several years of political uncertainty, the disruption caused by the market being effectively closed for several weeks and buyers re-evaluating their future lifestyle choices.
"This has now been our busiest July in at least the past five years. The changes in stamp duty have turbo-charged the market. Our network is reporting a significant uplift in activity at all price levels, with a focus not only on London and the commuter belt, but also on towns and cities with a longer commute, reflecting the move to a more flexible working landscape.
How interesting. I'm really surprised that Foxtons (LON:FOXT) shares remain stubbornly low. It's below the recent placing price still. (I hold)
Hi, yes i also hold Foxtons (LON:FOXT) and i thought this might move them but no
Not much change in macro corner...bond market on life support, US 10 Year Yield drifting slightly lower at 54bp not caring much about anything... the Dollar stabilised for now at key breakdown levels. A lot of Gold chat, it was up 1.6% meanwhile copper and oil were weak. So macro stuff took a back seat and markets focussed on earnings, where banks dominated with high provisions and big misses. Big tech posted big gains... and value suffered. The random 5, BP, BT, Barclays, IMB and Rio were all very weak - and are now off 10.9% which compares to a fall of 7.5% for Tesla (unch on week) and 5% for the All share index. Kind of interesting to tell the truth, since Tesla were blow out by all accounts and Barclays and BT were awful yet overall not much to choose so far in share price performance. So whilst value hasn't been punished too much... the nos did nothing to support the investment case.
#K3C.
Large complementary acquisition of Quantuma for £27m
Rev £24m immediately earnings enhancing
Follows hot on heels of Rannd acq of £9.29m
Recent placing of £30m at £1.50p
Transformational period
I hold
Do you have time to comment Paul?
Michael
Argentex (LON:AGFX) operating profit up 28%, revenue up tad under 33%, has started paying a dividend, some concentration risk as top 20 clients represent 41% of revenue and spread can sometimes be wide.
Also has cash and cash equivalents of £49 million.
Morning Paul, Metro Bank (LON:MTRO) acquired Ratesetter, the UK's most popular peer to peer lender with £750k customers, for an initial £2.5m and upto £9m. The biz was valued at £220m at last fund raise so potentially a real bargain. Would be interested in your thoughts if you have time. thanks
Hi YA
I have historically had money invested through Zopa, I had looked at Ratesetter and even though I get a monthly email from them with a £0 account which I could not delete ever, I felt that Zopa had the better offering to me as a lender.
I think the big issue here is though whilst the rates are better than you get elsewhere they are dropping and the customer defaults are growing. I know that there used to be a loan protection offering but that seems to have been withdrawn now and the risk put on the lender.
I felt that they were a good alternate product, but there were also a lot of companies coming into this space and then wiping out and taking a lot of money with it due to risk control on the loans.
Tommy
My morning smallcap tweet: FCA sniffs around NSF
£K3C Yourgene Health (LON:YGEN) Zoetic International (LON:ZOE) Journeo (LON:JNEO) Byotrol (LON:BYOT) Non-Standard Finance (LON:NSF) M Winkworth (LON:WINK) Seeing Machines (LON:SEE) Oxford BioMedica (LON:OXB) Dialight (LON:DIA), Crossword Cybersecurity (LON:CCS)
K3 Capital (K3C) makes £27m (+£15m earn out) acquisition which is expected to be immediately earnings enhancing.
Yourgene Health (YGEN) get CE mark for Clarigene, a covid in vitro diagnostic kit, for diagnostic use. Claims >99.9% accuracy with no false positive or false negative results. The test kit has an internal control that detects poor-quality samples to give an invalid result.
Zoetic (ZOE) DTU and its Kansas nitrogen assets delayed due to matters beyond the Company's and seller's control.
Journeo (JNEO) 3-year renewal of a framework contract with Abellio bus London. Worth c.£2m over 3 years with an additional £1.2m possible.
Byotrol (BYOT) guides FY(Mar21) EBITDA and rev significantly ahead of market expectations. Q1 product sales over £3.4m.
Non-Standard Finance (NSF) FCA "has raised a number of concerns regarding certain aspects of the operating procedures and processes at Guarantor Loans Division...NSF is now conducting an in-depth review, working closely with the FCA, to clarify the scope and scale of its concerns and to develop a possible redress methodology." Plans for possible placing on hold.
Winkworth (WINK) significant recovery in sales interest after stamp duty easing. Applicants registering on the day after the announcement up 64% on the previous week. Instructions and viewings since 8 July up 17% and 14, resp.
Seeing Machines (SEE) guides FY(June) rev $39.7m, 8.5% better than consensus, income A$42.6m, up 30%, also ahead of consensus. Net cash significantly ahead. Does income include grants?
Oxford Biomedica (OXB) new Development, Manufacture & License Agreement with Beam Therapeutics for the LentiVector® platform for its application in cancer. OXB gets undisclosed upfront payment and payments for development and manufacturing of lentiviral vectors for use in clinical trials.
Direshite (DIA) H1(June) rev down 26% but loss cut to £3.1m (£3.3m loss). Is this worse than expected? "We have adopted an agile approach balancing risk mitigation and business continuity with a primary focus on cash and ensuring we have sufficient liquidity to weather this crisis. We have undertaken measures to reinforce our financial position and ongoing performance by implementing cost reductions across the Group."
In line: Crossword Cybersecurity (LON:CCS)
whoops there on DIA...
Good morning Paul, hope you had a good weekend?
I'd be interested in your views of Ince (LON:INCE) final results announced today. Divi cancelled but revenues robust and up 87% to £98.5m, £8m PBT up 36%, net debt £9m. £19.53 mkt cap seems cheap to me but what do I know.
I hold
Cheers
Francis
Sounds interesting. The issue seems to be the balance sheet - very weak, and has a ton of deferred considerations liabilities, hence likely to be significant dilution in future to pay off those liabilities. Also note the non-controlling interests on P&L is large. Receivables very high, which could contain write-offs, legal businesses often have to write off some receivables, if the fee earner has been over-eager in invoicing.
RE: Ince (LON:INCE)
Many thanks Paul for your comment and later review of their results. You helped me understand how bad the balance sheet was first thing this morning so I dumped all my holdings around 31p which preserved my profit. Worth the Stocko subscription fee many times over.
I owe you (another) beer
cheers
Francis
Just don't mention China, I hold with fingers crossed.
Silver
I see Bigdish (LON:DISH) have furnished us with another operational update, here comes TGI Fridays.
Proof in the pudding will come in a few months time... will the restaurants start paying for Bigdish services?
Good Morning!
FTSE looks like it’s catching a bid this morning. Will be interesting to see who the advancers are.
Did you mean the LSE?
Silver