Small Cap Value Report (Mon 3 Oct 2022) - MEX, SRT, AGFX, PEEL, SPSY, RNWH

Good morning from Paul & Graham.
Paul's Podcast - Episode 14 went out on Saturday, although I didn't get round to recording part 2 (macro comments), so will try to catch up on that maybe tomorrow or Weds. Hence episode 14 is purely comments on individual companies which we covered in the SCVRs last week. The "mystery shares" are my best ideas each week, which I'm holding back specifically for Stockopedia readers (since you're paying for me to do the research!). Last week's mystery shares were £LOAD and £REDD .
Come hell or high water, I'll keep these podcasts going, because it's the current awful market conditions that are throwing up the big long-term buying opportunities, and we mustn't get swamped by the negativity. Bad patches happen, and they're deeply unpleasant, but then a new bull market starts and we make a fresh fortune! That's what 's happened in the past, and will happen again. The only unknown question is timing.
Agenda -
Paul's Section:
Tortilla Mexican Grill (LON:MEX) - interim results show this expanding casual dining /takeaway burrito chain operating just above breakeven. A profit warning for H2 is only just perceptible in the outlook statement. Yet broker forecasts have been drastically reduced for 2022 & 2023, to just above breakeven. This completely changes the investment proposition, which was for rapid profit growth due to expansion, and is now barely profitable despite the growth. So I'm rapidly losing interest in this share.
Spectra Systems (LON:SPSY) [no section below] - I wrote very positively about SPSY recently, see the archive. Today there's a positive contract amendment announced, and broker WH Ireland (see Reearch Tree) has increased forecasts. It's now expected to make 12.8 US cents EPS in FY 12/2023 (previous forecast ws 12.3c). Note that nearly all earnings are paid out in divis. So this share offers a reasonable PER, very good yield, and interesting growth potential. So I want to reiterate my positive opinion of this share. [no section below].
Renew Holdings (LON:RNWH) - a positive trading update. Renew has established such a good track record, in the 10 years we've been following it here. It's managed to grow hugely, through acquisitions, whilst paying growing divis, and gradually improving what at times looked like a dangerously stretched balance sheet. Also it's safely navigated the considerable risks that contracts in this sector often fall foul of. Very impressive. The price now looks attractive to me, for a long-term investment. That's assuming nothing serious goes wrong in future, which it hasn't in the past.
Graham's Section:
SRT Marine Systems (LON:SRT) (£54m) - this H1 2023 update has been received positively as SRT delivers spectacular growth in revenues and a swing to pre-tax profits. Much has been promised over many years at this company, and results are finally delivered with H1 revenues of £18.8m and a pre-tax profit of not less than £1.5m. As disclosed in the full-year 2022 results, SRT’s systems division has a new coast guard customer and is also carrying out major works in the Philippines. I would continue to treat this one cautiously as revenue recognition is inherently lumpy and unpredictable. But management has gained credibility by finally hitting some big revenue numbers. Long may it continue.
Argentex (LON:AGFX) (£119m) - a terrific update from this FX broker. Revenues are up 75% compared to H1 last year, while costs remain in line with management expectations. The success is attributed to the company’s “core UK proposition” but also to the exceptional trading conditions in Sterling recently. I remain impressed by several features of this company which is probably my top pick in the FX brokerage space. It recently won an electronic money licence in the Netherlands as it seeks to internationalise and further diversify its customer base. The valuation here has looked low relative to its growth achievements and I reckon that it deserves a re-rating.
Peel Hunt (LON:PEEL) (82p) (-7%) (£101m) [no section below] - many of you will be familiar with this investment bank that caters for small and medium-sized businesses. The corporate client base currently sits at 164 companies, with an average market cap of £600m.
It is yet another example of a 2021 IPO that has gone terribly for investors so far. That’s partly because the small-cap market has been decimated over the past year, but also undoubtedly because IPO valuations were overcooked. This listed at 228p and so nearly two-thirds of its IPO valuation has been written off in a year. Today’s outlook statement warns of the effects of uncertain capital market conditions, geopolitical/macroeconomic factors and tightening monetary policy, but says that the company will be prepared for when market activity levels “normalise”. Trading in small-cap and AIM companies is currently “much lower” than before, though larger companies and investment trusts are in line with expectations. Peel Hunt is also leading the charge for more retail participation with “REX” (giving retail investors easier access to fundraisings) and plans to launch Peel Hunt Europe during the current financial year. While Peel Hunt is a very successful broker, it lacks a track record for external shareholders to rely on in terms of bottom-line profitability - apart from FY March 2022, the year in which it listed. I would therefore treat these shares very cautiously.
(Paul adds: Peel Hunt is also known for its outstanding research notes, many on small to mid caps. But the company jealously guards them, and private investors don't get access to them, unless we're prepared to pay a substantial annual fee which most people can't afford or justify. I appreciate that it costs a lot of money to produce quality research, and the MiFiD rules have made it difficult, but even so I question whether it is fair or right that research analysts get privileged access to, and inside information/guidance from companies, but then restrict who can see that research? That doesn't seem consistent with the rules. Maybe Peel Hunt should do what other brokers (e.g. Singers, Liberum) do, and put out short notes on Research Tree, holding back the deeper research for fee paying clients? The danger is that, by withholding research from private investors, Peel Hunt is actually harming its clients - because private investors create the market liquidity in small caps. If we can't get broker research, many of us won't buy the shares. So when I talk to small cap management, I always urge them to use a broker which publishes research for everyone to see).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Tortilla Mexican Grill (LON:MEX)
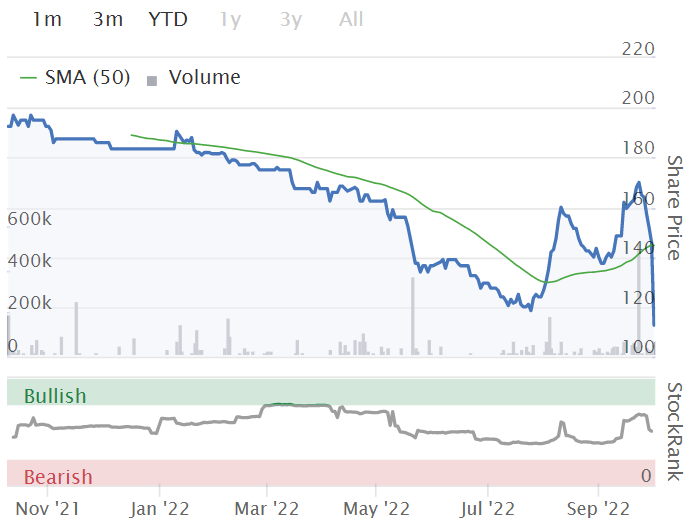
112p (down 22% at 09:11)
Market cap £44m
Tortilla Mexican Grill plc, the largest and most successful fast-casual Mexican restaurant business in the UK, today announces its unaudited interim results for the 26 weeks ended 3 July 2022 ("H1 FY22", "the Period"). All numbers are shown on a IFRS basis unless otherwise stated.
Tortilla demand and market conditions lead to acceleration in pipeline
H1 numbers seem OK, although it’s not yet reached any meaningful level of profitability.
Key figures for H1 are -
Revenues £26.9m (up 30%vs H1 LY) - helped by 5 new sites, and acquisition of smaller rival Chilango near the end of H1, but being up 30% suggests that there’s good growth from the existing sites too.
Like-for-like (LFL) revenue growth (a key measure, as it strips out the effect of new site openings & any site closures) is an impressive +19% - footnote 2 says the comparative is H1 2019, pre-pandemic. Revenues need to be strongly up against a comp that is now 3 years old, because many costs (esp. wages) will have risen a lot over that time.
Adj EBITDA (quite a useful measure in this sector, as it does approximate to cashflow) is £2.5m in H1, but PBT is only £0.3m - so taking into account all costs, the business is effectively trading just above breakeven - not very exciting for investors.
Site expansion (roll out) - now has 84 sites, including 5 new Tortillas, 1 delivery kitchen, and 8 acquired Chilango sites (5 of which have been re-branded as Tortilla). 5 more new sites are planned for H2 this year. Then expansion is to accelerate to 12-15 new sites p.a. - I like this a lot. Now is the perfect time to be rolling out a good format, that is popular with customers, because the deals available from landlords are currently so good, it’s completely unprecedented actually. I’ve heard of sites being offered at only a third of the pre-pandemic rents, and often come with a large capital contribution from the landlord towards fitting out costs.
London - very interesting, with read-across to other companies - Tortilla’s central London sites are now trading at 98% of pre-pandemic revenues. That’s still well below its overall +19% performance, but gives confidence that London is returning to normal, gradually. That’s certainly my perception too, subjectively, having been in London for the last month, it feels busy & buoyant here.
Current trading - LFLs (vs pre-pandemic remember) slipped back a bit in the summer (July: +13.2%, Aug: +12.3%, but improved in Sept to +16.6%).
Cost inflation - mentions higher meat costs, and utilities. Combined this will take £1.8m off the gross margin for FY 12/2022. I can’t find any information on cost hedging. We do need guidance on this, so a bit of a gap there.
Outlook - sounds like a profit warning for H2, due to increasing costs. Let’s see if broker downgrades have happened.
Broker update - many thanks to Liberum for updating us with revised numbers. It’s a big drop to forecast profitability in both 2022 (£0.7m new, vs £3.9m old), and 2023 (£1.1m new, vs £4.3m old), with the main cause being (as the company explained), slower trading over the summer, but increased meat & utilities costs being the main culprits.
Note also that the tail end of Pandemic support measures boosted Q1 (business rates relief, and reduced VAT for hospitality).
Can’t they just raise prices? The commentary indicates that Tortilla wants to stick with a value-for-money offering, eschewing both price rises, and discounting, both of which are (I think correctly) viewed as damaging in the long-term. Therefore I think investors will just have to accept that, for now anyway, profitability is not really happening, they’re just building the business at or just above breakeven, rolling out new sites, with (hopefully) profits coming longer-term. That’s a big change in the investment proposition though, and might put off some investors.
Balance sheet - looks OK, I wouldn’t call it strong, more adequate. NAV is £4.2m, less £2.6m intangibles (mainly arising from the acquisition of Chilango), gives NTAV of a rather modest £1.6m. However, the IFRS 16 lease entries have a deficit of £5.3m (liabilities exceed RoUA). I am happy to remove all these items, which puts NTAV up to a better £6.9m. Although note that a deficit on the IFRS 16 entries suggests that Tortilla has several loss-making sites, where it can’t get out of the lease.
Cashflow - positive EBITDA has been spent on acquiring Chilango, and funding the capex for new sites. It’s still got £6.1m in net cash though (ignoring leases). Plus an unused £7m RCF as back up. Although I imagine the bank might want to reduce that facility, given that profit guidance has now been slashed.
Should it do a placing, to give more cash headroom? I don’t think that’s necessary actually, and the timing is certainly not right to be asking investors for more cash. The existing cash, and the £7m bank facility looks perfectly adequate for the current expansion plans. Remember that each new site costs c.£0.5m, but landlords will probably be covering a fair chunk of that, with reverse premiums negotiated as part of agreeing lease terms. So the cash requirement for new sites doesn’t look onerous: 12-15 news sites per year could probably be funded from existing resources.
My opinion - this is a big drop in expectations today. Instead of profitability building nicely as the business scales up, revised forecasts are now saying little more than breakeven in 2022 and 2023. So the economics of the business can now only really be viewed as unproven. That has to impact valuation heavily. I’m not convinced that this morning’s 22% drop in share price in the first hour of trading, is the last of the fall.
It depends how much investors are prepared to look to the longer-term growth potential? Current trading at around breakeven, is certainly not enough to justify the £44m market cap. It really should be profitable now, with 84 sites. Which suggests to me that the format isn’t quite right at the moment. What are the issues? I think pricing is too low, and needs to be increased. Also, the menu is too complicated, which slows down the production line I’ve noticed when mystery shopping. Also, it’s annoying to customers when delivery orders are being prepared as a priority, and I have to stand there waiting whilst a delivery order is prepared. I think a much faster, simplified menu, is needed. Not giving customers dozens of different options - do you want this, or that? (half the time you can’t understand what they’re saying, due to accents/mumbling, and loud background music).
Despite these issues, I think the business has good long-term potential. Maybe management should focus more on getting the format right, and operating profitably, before doing a rapid roll-out of new sites, which is likely to take up most of their attention?
Overall, given this major downgrade of forecast profits, I think the shares have gone from appealing, to unappealing.
Also, I have to question why it’s taken so long to guide down profit expectations? Cost increases should have been obvious months ago, which makes me question the strength of the finance team here, who don’t seem to have been on the ball in terms of accurate forecasting. After all broker research effectively comes from the company, which guide them.
Once macro conditions stabilise, then there could be upside for future profits, but it feels too early to start anticipating that.
MEX shares floated in Dec 2021, so it's been a rip-roaring success compared with many other 2021 floats!
.
Renew Holdings (LON:RNWH)
589p (up 3% at 11:59)
Market cap £464m
Renew (AIM: RNWH), the leading Engineering Services Group supporting the maintenance and renewal of critical UK infrastructure, provides the following trading update for the financial year ended 30 September 2022.
Strong trading with results expected to be marginally ahead of market consensus
Here’s the update in full, as it’s all relevant (as usual, I’ve added bolding) -
The Group continues to successfully manage the well documented inflationary pressures and supply chain challenges in the wider economy.
As such, there has been no material impact on trading, once again demonstrating the resilient and differentiated nature of Renew.
As a result, the Board expects the Group to report results for the year marginally ahead of market consensus1.
1Company derived consensus adjusted operating profit is £54.0m and pre-IFRS 16 net cash of £8.9m.
The Company's balance sheet continues to be strong with net cash, at 30 September 2022, anticipated to be ahead of market consensus1 due to lower capital expenditure and pension costs combined with higher operating profit in the period.
The Group's Engineering Services order book remains strong and we continue to see good demand across our core markets which continue to trade well. Despite the uncertain economic outlook, the Board looks to the year ahead with confidence with the Group well positioned to continue to benefit from the UK Government's committed infrastructure spend.
That sounds very good indeed. I’m so impressed with Renew - having followed it for many years. Management seem to have executed flawlessly, growing the group by acquisitions, whilst also paying growing divis, all whilst gradually improving what was at times a dangerously stretched balance sheet.
It also seems to have avoided the widespread risks of contracts going wrong, which bedevils the sector. And they’ve steadily improved margins over time, which was exactly what was originally planned.
Valuation - Stockopedia is showing a forward PER of 10.3, and a 3.2% dividend yield. Companies in this sector tend to attract fairly low valuations, so the current valuation, in a tough market, looks about right to me.
My opinion - given the outstanding track record, I can see a lot of merit in this share, as something to just hold long-term, and watch management hopefully continue to execute very well.
It seems to have good inflation protection built in, clearly being able to pass on cost increases to customers. There’s a good order book too.
Lots to like here, for a long-term hold I think, assuming nothing serious goes wrong along the way. It hasn’t so far, so it looks as if management are safe hands, and seem adept at setting up contracts so that the downside risks are anticipated & allowed for - that’s really the crux of things for this sector - getting the original contract terms right to allow for all eventualities.
.

Graham’s Section:
SRT Marine Systems (LON:SRT)
Share price: 29.87p (+11.7%)
Market cap: £54m
A brief update from this “global provider of maritime surveillance, monitoring and management systems”.
H1 revenues are up 300% to £18.8m, and pre-tax profit is expected to be “not less than £1.5m” (financial year ending March 2023).
I have felt that this company over-promised and under-delivered to its shareholders over a long period of time, so I’m glad to see that it might finally be coming through with some decent financial results.
Let’s review its H1 revenues and PBT over the years:
- H1 2022: revenues £4.7m, loss before tax £3.1m
- H1 2021: revenues £3.8m, loss before tax £2.7m
- H1 2020: revenues £3.5m, loss before tax £1.5m
- H1 2019: revenues £3.2m, loss before tax £1.3m
- H1 2018: revenues £2.9m, loss before tax £3.3m
As you can see, the track record is grim.
On top of the losses, shareholders have been diluted with 180 million shares currently outstanding versus 128 million, five years ago.
But something has changed. From today’s RNS (emphasis added):
Despite continuing production constraints, our transceivers business revenue grew by approximately 20% to £5.2m (H1 2021/22: £4.2m). Our systems business delivered multiple operational and several revenue milestones, and thus generated approximately £13.6m (H1 2021/22: £0.5m) of revenue.
At the final results, CEO Simon Tucker talked of a “£600m systems division validated sales pipeline”, which I thought had very little credibility.
This is how the systems division performed back in FY March 2022:
The systems business did not complete any revenue milestones and thus only generated £0.6m of revenues during the period from the ongoing sale of data services to system customers. Cash payments amounting to £6.1m were received during the year from existing system customers.
These “revenue milestones” (points when revenues can be recognised in the financial statements from ongoing contract work) are clearly very lumpy! And like buses, after a 12-month period in which none of them were achieved, SRT has delivered several of them in just a six-month period.
Under IFRS 15, revenue is recognised only when a company satisfies an accounting requirement called a “performance obligation”. Sometimes, this means that companies can carry out lots of work before revenue is eventually recognised.
The work that SRT is doing in its system division includes the following:
- For the Philippines: a fisheries monitoring and management centre, and “further follow-on data sustainability and system expansion contracts to follow”.
- For “a new national coast guard agency”: an SRT-MDA System, which uses SRT’s inhouse technology to create “a national scale integrated system solution that delivers a full range of sophisticated maritime surveillance, command, control and management functionality.”
With respect to this new coast guard customer, SRT said: We consider this new customer to be of considerable long-term value to SRT and likely to generate further contracts as they build up their maritime surveillance capabilities.
My view
I would continue to take a cautious approach here: one swallow doesn’t make a summer, and all that. It’s possible that things will change from now on, but the long-term track record is extremely patchy.
As you can see from the fact that total revenues quadrupled compared to last year - and went from almost nothing to £13.6m in the systems division - the results here are lumpy in the extreme, making them very difficult or impossible to predict. This is a consequence of both the small size of the business (reliant on a small number of contracts) and the complex nature of its contracts.
There is also precious little asset backing - close to zero net tangible assets at March 2022, despite raising £4.9m in an equity placing.
Therefore, these shares continue to strike me as high-risk, although I have to acknowledge that management has much more credibility now that their promises of contracts coming through in FY 2023 have materialised. Hopefully we will see more consistency from this company in future.
Argentex (LON:AGFX)
Share price: 105.5p (+16.6%)
Market cap: £119m
This FX company provides an H1 update for the six-month period ending September 2022.
It is confident it will “exceed expectations for the period ended 31 December 2022” (it recently changed its year-end from March to December).
Argentex expects to report six month revenues of £27.4m, a 75% increase compared to the same period last year (H1 2022: £15.7m)* with costs remaining in line with management expectations. There has been continued strong client demand with the number of corporate clients trading growing to 1,393 (H1 2022: 1,241)*.
The company attributes this successful performance to its “core UK proposition” but also to “more favourable market dynamics, with the recent historic lows in Sterling presenting exceptional short-term trading conditions”.
That’s an interesting feature of the recent volatility that I had overlooked: the additional demand for FX services to manage these conditions. Also, the additional value that firms like Argentex can arguably provide for their clients by timing the purchase of Sterling in recent days and weeks.
Let’s remind ourselves of what Argentex does:
Our clients use us for bespoke advice, tailored hedging strategies, spot, forward and structured products. We also offer payment services and an online portal should you want to manage your own trades.
We operate like a private bank, giving our clients a bespoke service every time they deal with us. Our clients range from institutions, corporates and private clients of varying sizes.
It’s easy to imagine the demand picking up for currency management, as high net worth individuals try to figure out what to do with their currency exposures. And the number of corporate clients is up by 12%, too.
My view
I flagged this company as offering high growth at a single-digit PE ratio back in July.
My main difficulty with the FX brokerage space is (and perhaps it’s my own fault) I find it difficult to distinguish between the different players in the sectors. How to choose one over another?
That being said, there are a few things about Argentex that caught my attention:
- Working hard to build out an international presence (it recently won a Dutch electronic money licence).
- Growth appears to be fully organic and customer diversification is improving (the top 20 customers generated 36% of revenues last year).
- Its online platform enables customers to efficiently make their own trades, if they wish.
See my commentary in July for more detail (link).
After today’s positive trading update, I’m clearly going to retain my positive impression of the company and even bolster it with added excitement around the rate of growth it’s achieving.
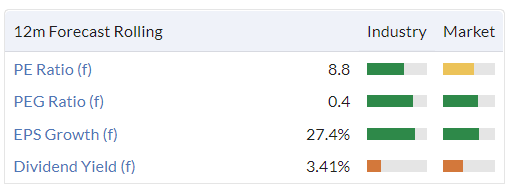
See the PEG Ratio below, as calculated by Stockopedia. Anything less than 1x has traditionally been considered to represent good-value growth.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
update from Telecom Plus:
● We expect full year profits will be materially ahead of current market expectations, due primarily to (i) stronger customer growth, and (ii) a reduction in the previously expected cost of multi-service discounts during H2 and an improved outlook for energy affordability, resulting from the recently announced price guarantee which will cap average energy bills at £2,500 per household for the next two years.
I have heard on the news and read on Twitter that it’s the rate that is fixed, so the more you use, the more you pay and it is not capped @ £2,500.
https://www.investegate.co.uk/...
Stegga 1000000,
You are correct. It is not capped a£2,500. That is only the average bill per household. apparently British Gas put a big advert in the papers over the weekend stating "the more you use the more you pay"
Martin Lewis was making this clear on his programme this morning .
There is a standard charge per day for both electricity and gas for being connected.
For Electric this will be 42.83p.
for gas this will be 26.22p (both new figures from Utility Warehouse.)
The new prices from 1 October are Electric 34.225p per kwh.
Gas 26.622p per kwh.
They give an example of your bill being £168, you pay £100 & the Government pays £68 for the next 6 mths.
Can we have some ideas about what the mystery share jingle should be in the podcasts? I was thinking the x-files theme music
The truth is out there...
Paul , I'm certain that you're podcasts are excellent , but I get my insights from the printed word and data. So secret squirrel broadcasting of Redde Northgate (LON:REDD) (I hold ) misses this long term subscriber (and non chatterbox ). Can't be the only one?
alanshares
Stockopedia | Small Cap Value Report (Weds 28 Sept 2022) - CARD, REDD, FIF, PRES, BOO, GLAN, CML, K3C | By Paul Scott
You won't miss it if you read the above.
Thanks Dicktrade , thought there was something that I was not party to . Have done the post, so
I'm now a happy bunny!Hi alanshares,
Yes, just to confirm what Dicktrade says above, my podcasts are just a weekly summary of these written reports. Plus some general market/macro chat.
So in terms of my podcast "mystery shares", they're my best ideas from the week's SCVR, already published here.
I feel it's only fair that Stockopedia subscribers get the best share ideas to research yourselves, rather than giving away all my work (which you pay for via subs) to non-subscribers out there on the internet.
Anyway, glad your query is resolved, and you're happy now :-)
Best wishes, Paul.
Hi all. There was an investor event for Surface Transforms (LON:SCE) this morning. Did anyone catch it?
Added more £SAGA. Now <£120m cap. Wonder if an opportunistic buyer would pounce?
Remember that the founder's son, and himself a long-serving CEO, came back and refinanced SAGA during the pandemic, and now owns close to 30% I think. Sir Roger de Haan. So he could block any buyer, but maybe could decide to buy SAGA himself? Distinctly credible, especially as there are no solvency issues, so why bother with a stock market listing, if there's no benefit from it?
Haan has 26%. Some of the other major institutions won't let him get on the cheap imo. Valuation is well on the floor now.
More broadly the Sterling/US$ rate means more and more modestly valued small caps with sound businesses may attract offers.
Recently listening to Paul’s excellent interview with the CEO of Renold (Renold (LON:RNO)) where their acquisition records was discussed I wondered how attractive they might be to a larger acquiring group, despite their pension issue?
Hi eParo ,
I think by looking at Saga’s 21/26 5.5% bond trading at 71 cents ( thus yielding about 13% ) , one can only assume that the company has serious solvency issues.
From previous experiences if this falls below 50 cents then the existing shareholders are left with nothing as the current bond holders will become the major shareholders.
DYOR.
Thanks
Meant to say 8%.
Hi yiannos1,
Just FYI, you can edit a post within an hour of posting it. So if there's a typo like above, you can edit the original post. Hope that helps.
Given that interest rates have risen sharply, then I would expect the SAGA bond (issued when interest rates were ultra low) to be below par value of 100. Although as you say, 71 cents is quite a significant discount. A valid point, backed up with facts & figures, good to see!
Regards, Paul.
My points are always backed by facts and figures. It’s not what I feel , it’s not what I think , but especially it’s not what I currently hold.
Interesting. Maybe the bonds are due a bounce. There are some very good institutions holding equity here. I would think they would have dumped by now if they thought there were solvency issues.
Their cruise demographic would be mortgage free and the increase in savings rates would mean more disposable income to spend on leisure imo. It's an insurance business with a couple of cruise ships. I feel we've reached a bottom here. Time will tell.
Can you explain what you mean by "if this falls below 50 cents then the existing shareholders are left with nothing as the current bond holders will become the major shareholders." please? Are you assuming that Saga default on the bonds?
Yes this is exactly what I am saying if the price of these bonds goes below 50.
DYOR
Thanks
Can anyone please explain why the share price of Rosslyn Data Technologies (LON:RDT) (I hold), having announced the sale of a loss making division for a profit, has dropped by 12.8%?!
Hi Roger Baron,
RDT is a loss making business that is burning cash on a daily basis. Most of its employees ( top sellers ) that used to generate good revenue for the company have left and sooner or later it will need a fundraise to survive.
Thanks
Seeing some great rebounds off of low sell offs last week...but can they hold?
Airtel Africa (LON:AAF) Henry Boot (LON:BOOT) CentralNic (LON:CNIC) Equals (LON:EQLS) K3 Capital (LON:K3C) Norcros (LON:NXR) Coats (LON:COA) Warpaint London (LON:W7L)
These are good companies over sold last week IMO.
I hold all but WarPaint
IMO - I quite agree with you that some of these stocks are oversold, but certainly right to question whether or not rebound will last, albeit relatively small to be honest in terms, given the savage substantial decrease in share price for some. I still consider the market prices are being manipulated, Warpaint is up and down like a fiddlers elbow, appears that any increase one day is superseded by a similar decrease following or following days. regardless of trading position or fundamentals. Although I am a long term holder of most stocks I find current trading price fluctuations very frustrating (market conditions factored/appreciated) and I am firmly of the opinion that shorting and hedge funds are largely responsible in creating/exacerbating these movements. It didn't use to occur as dramatically as this when I first started investing back in the day. During periods of market turmoil should these practices be banned?
Proffittpar, I agree there does seem to be some manipulation going on to the point where I am now manually stop losing as I have noticed being stopped out on sudden dips a couple of times recently and when going back through the Bid and Offers makes no sense.
Low volumes general are not helping with this. I am treating this as a dead cat bounce so maybe sell out if we have some decent gains...time will tell.
Ok, so there are two good things in my portfolio this morning.
Has Warpaint London (LON:W7L) been tipped at the weekend? Or is the some news out there in a similar company that is being read across?
Again starter position, FOMO of should of got more, but a 10% up day.
Thank you
Tommy
I hold Warpaint London (LON:W7L)
Paul, thank you for the Saturday Podcast, it's always a good listen. One consideration which stops me buying Redde Northgate (LON:REDD) is that they previously announced that they were switching their fleet to contract hire rather than outright purchase / internal finance. This means that they will have de fleeted their owned fleet and sold these vehicles when used prices are artificially high so massively bumping up todays profits. Going forwards, using contract hire, they won't make any profit (or loss) from these fleets; the vehicle will simply go back to the finance company. With this I'm cautious that £REDD's current profitability is being artificially inflated and won't be repeated, so profits in 2023/24 will be significantly lower . Any thoughts?
Redde Northgate (LON:REDD) I think profits were clearly boosted by higher rental prices as a result of van shortages - would expect this to normalise at some point, although surely partly priced in given this is on PE of 6 - similar situation to Vertu Motors (LON:VTU) in some ways. If they do move to a contract hire, capital light model in future then this is arguably lower risk - they would simply collect the spread between the price they can hire at and the price the customers pay. They wouldn't be exposed to movements in the value of the fleet in the way they are now.
Hi 55555,
Yes that's a very good point about favourable residual values on vehicles benefiting REDD. I looked into that a bit, and the forecasts do already factor in a fall in forecast EPS next year.
Also, I reasonableness checked profit/EPS against pre-pandemic levels, and assumed it might drop to say 40p. Which would still leave the shares v cheap. There's also the issue that the Redde side of the business saw reduced business during the pandemic, which should now be returning to normal maybe. So there could be a bit of an offset there maybe?
Remember too the great balance sheet support - this thing is fully backed by NTAV. That could dip a bit, as vehicle depreciation resumes, but it's a great starting point.
.
Regards, Paul.
“I've been to the mountaintop and I have seen the promised jam.”
Very nice MrContrarian, thank you for this (and all your contributions).
Boohoo (LON:BOO), I wonder if anyone can comment about the share options delivered to the CFO, Shaun McCabe. nil cost. personally held 110,627, and has been awarded 3,073,778 ordinary shares:
1,253,109 options to vest in May 2023;
· 1,575,812 options to vest in May 2024; and
· 244,857 options to vest in May 2025.
not a bad number.. Are shareholders happy with this type of arrangement. Does anyone have any care or hope for BOO any more
For those that like a blue-sky gamble, this one has just become more tangible.
Oxford Biodynamics (LON:OBD) has secured an insurer reimbursement code in the USA for their new CiRT cancer test. This test shows the likelihood of a (very expensive, very painful) cancer treatment succeeding, patient by patient.
The announcement sounds boring - just another administrative issue - but it now unlocks the door for CiRT to be automatically included by insurers on their lists of diagnostic tests they allow, which then allow oncologists to prescribe it, knowing that insurers will approve and pay for it.
The big problem with OBD though, is that they are rapidly running out of cash, and the market for new fundraising is not ideal... the likely outcome is probably a convertible bond issue by their largest shareholder, Vulpes, or another third party. But at a current market cap of £11m, this dramatically undervalues the IP that this company has, especially as its now jumped through all the hoops to get their CiRT test into the market, and just need 3-6 months runway for the sales to build up.
(I hold in the Boon Fund)
I commented on SRT Marine Systems (LON:SRT) recently as a bit of a bear !! - so hey to those holding - good news for you, and perhaps I was wrong. I still wont buy in at the moment, but at least things look like they might be turning around.
Hi cheeky_minnows,
Indeed, I've also been bearish on SRT Marine Systems (LON:SRT) in the past, because it's promised so much, but repeatedly missed forecasts, over many years. Which did make me wonder if all the talk of a huge pipeline, and unfeasibly large numbers, could just be hot air?
Today's figures, as reviewed above by Graham, certainly improve the company's credibility. Although I agree with Graham's conclusion, that one good year doesn't necessarily mean it's turned a corner. There have been false dawns before, remember - with a surge in sales/profits, then a reversal the following year.
With such poor visibility, I don't think SRT would appeal to me. But good luck to holders, and if it really has cracked its markets now, then it could get exciting. That's what people have been saying for many years! The CEO is so likeable & enthusiastic, that I want him to succeed. When I berated him in person for repeatedly missing forecasts, at an investor show years ago, he disarmingly agreed with me, and said that yes it was so frustrating that performance had been so poor, and he had to do better. You don't find that very often, and it impressed me.
Regards, Paul.
Smart work by Spectra Systems (LON:SPSY) reported today. (I hold)
Contract Amendment for Supply Chain Protection for Materials to a Central Bank
...
The effect of this amendment is to increase the price of specified materials
supplied thereunder by approximately 21% relative to the current price. The
price increase will begin with the next order and reflects Spectra's proactive
efforts to mitigate supply chain issues for the customer, by bringing more
processing in-house. The price increase portion under the amended contract
also has a built-in annual price escalator of approximately 3%.
In the year ended 31 December 2021, Spectra generated revenue of approximately
US$5.9m from sales of the specified materials under the earlier procurement
contract
In addition, Spectra will receive a $1.3m onetime payment for the development
effort undertaken to be able to provide this capability.
Ireland have done a good doc on Research Tree today on Spectra Systems.
The tight/cosy relationship they have with their largest central bank customer astounds me.
What other client will agree, after the R&D has been done, to reward their supplier for the good work and say "here's $1.3m, our appreciation for proactively thinking of supply chain issues and creating a robust solution for us".
One could argue Spectra Systems (LON:SPSY) should have gotten the central bank to agree to funding the R&D before starting in the first place, rather than spend their own money and then wait for the discretionary tip at the end.
Along with putting through a 21% price rise increase, this goes to show the strong client relationship they have.
On the other hand... I'm worried that this one materials supply contract represented 35% of FY21 revenues... eek! Talk about a single customer risk.
(I hold in the Boon Fund)
Spectra Systems (LON:SPSY)
What other client will agree, after the R&D has been done, to reward their supplier for the good work and say "here's $1.3m, our appreciation for proactively thinking of supply chain issues and creating a robust solution for us".
One could argue Spectra Systems (LON:SPSY) should have gotten the central bank to agree to funding the R&D before starting in the first place, rather than spend their own money and then wait for the discretionary tip at the end.
What makes you so sure these costs were not agreed or discussed (on some sort of contingency basis perhaps) upfront ? - it sees clear that they proactively flaged up the issues in advance.
We identified the potential supply chain problem well in advance of any ramifications to the program and initiated an internal development and capability which our customer greatly appreciated.
Spectra Systems (LON:SPSY) (I hold)
Hi Boon
Spot on with the comment on customer concentration risk.
Given the concentration of USA based revenues I have assumed that this is the FED.
I would usually avoid any company reliant on 1 main customer, however, I am comforted by the fact that contracts are in place until 2034. One would hope that, if it is the FED, then these are contracts that won't be reneged upon.
I think it's also worth adding the diversification currently taking place. K-cups is the obvious example, for which I believe there will be c$2m of revenues in FY22. For context revenue were $0 prior to 2020.
At the moment, there might be a long term risk from customer concentration, but my hope is that these recede; the company certainly seems to be moving in the right direction.
I remain a happy holder.
A
Abtan, re £SPSY (I hold), it is possible that America refers to the continent of America (cf sales to Europe). In which case it could be anywhere between Argentina and Chile and Canada.
Good luck with our holdings.
Richard
Spectra Systems. The ticker didn't translate into the name.
Spectra Systems (LON:SPSY)
It does on my ipad but it does not always work, temperamental.
I hold also, but looking to sell.
Spectra Systems (LON:SPSY) (I hold)
Hi RichardK
The Annual Report specifically says revenues are from the United States of America and that there is a direct relationship with a G7 bank.
There was also a video - made by the company - that implied it was the FED, but I'm afraid I can't find it.
I once thought it could be the Bank of Canada too, but that doesn't really tie in with the above.
I could be wrong of course. Maybe there are some accounting funnies going on, with intra-company sales masking the true end user. In any case if that end user is a G7 bank then the revenues should be okay.
A
Just a note of thanks to all contributors to these threads during these challenging times. I am usually a reader rather than a contributor. Like most (if not all) of you my portfolio has had a hard time in the last 12 months, but with the balanced comments over the long term outlook I have felt confident riding out the storm, whereas in the past I would have had a lot less confidence in my position. I am currently -30% (1 year), -2.5% (2 year) and +13% (3 year), despite these figures my shares portfolio has done better than my funds and IT portfolio. That long term perspective is what I am looking towards. I do appreciate that things can get a lot worse before they get better, but I have confidence that we'll be in a better place in 3 years time.
Thanks again for all your contributions (although some of you need to stop getting irritated with each other!)
Nicely put, thanks Ted Striker!
You sound like a sensible person, so I hope we hear more from you in future, here in the SCVR comments. And you can keep the naughty boys in line too LOL! ;-D
Best wishes, Paul.
Results from Tortilla £MEX today - be interested in your view Paul/ Graham. Certainly, the market doesn't like the numbers. I hold
Renew Holdings (LON:RNWH) Year End Trading Update: Strong trading with results expected to be marginally ahead of market consensus… continues to successfully manage the well documented inflationary pressures and supply chain challenges… well positioned to continue to benefit from the UK Government's committed infrastructure spend.
(I don’t currently hold)
How are directors allowed to buy so close to a trading update? I really don’t get the rules.
Brickability (LON:BRCK) buys ET Clay products, “funded from the Group's existing cash resources and is expected to be immediately earnings accretive post completion.”
(I hold)
Very strong update from Argentex (LON:AGFX) for the first half; revenue up 75% - not reflected in the share price (even though it has recently reflected some strength).
I was just about to say the same thing Shipofrogs. Results look very good and Argentex (LON:AGFX) looks a good investment to me especially at this time of currency volatility. Would appreciate Paul/Grahams view if possible please chaps. Many thanks.
Hi ShipofFrogs
This is probably my only highlight in a challenging 13 months, now obviously why did I take and hold a starter position only is the question for my FOMO to deal with today???
I think that this is one of the beneficiaries of the volatility in the last week with Sterling, the question is will this continue and be a structural change so that the revenue rise will continue and hold for the rest of the year, or will this be a Covid-esque bump and hence we see the massive jump in profit and SP which is then lost in a few days as people get bored again?
So my question for today is more thoughts on whether this is a long term structural change, and do I continue to hold, or do decide to bank the profit and buy back again in a couple of weeks, which is not my normal approach but just looking at the behaviour of many of my holdings after a positive update, goes up and then drops even lower than before.
Tommy
I hold Argentex (LON:AGFX)
Yes very strong update from £AGFX.
HOWEVER, at their FY22 results they did indicate that profitability may be impacted in the short-term noting 'Continued investment into people and technology expected' which they said 'is expected to generate a strong return on investment in the medium term' and further: 'The Board remains confident that the level of revenue growth will continue as expected in FY23 with associated enhanced quality of earnings over the medium term.'
This led Singer at the time to downgrade their EPS estimates to 6.4p for the current year and 10.1p next year (still not reflected in the Stockopedia data I am afraid*). Of course, this year's EPS estimate will likely be beaten now - how much by we don't yet know. But I'd be careful about getting *too* excited on Argentex (LON:AGFX) just yet.
*I did raise a ticket about this a while ago but I know the issue was at the data provider end.
re Argentex (LON:AGFX)
Yes, a good update but I’d caution that the TU notes the recent exceptional opportunities afforded by the recent volatility in FX markets, ie this HY has been boosted in a manner that should not be expected to persist, once this hump is cleared. I think the market has recognised this, as the earnings would otherwise justify a near 30% hike this morning, and the early 20%+ uplift has moderated to a more rational gain.
Well, the currency volatility really took hold in the last couple of weeks - after their 1H. We are in more volatile times as the Fed ramps up interest rates, so I don't see volatility disappearing anytime soon.
Even if it does ease off customers and potential customers have been reminded to pay more attention to this area. Plus the business isn't just about volatility, it's about paying a lower margin on fx transactions. The level of those transactions are more likely to be impacted by broader economic conditions, e.g. less trade - fewer fx transactions.
It was notable though that the update referenced revenue and not the bottom line. Nevertheless, it was trading at a significant discount to its peers.
As usual, the pre 9am exuberance wore off some.