Small Cap Value Report (Mon 31 Jan 2022) - STAF, CBOX, BLV, STU, TND, PURP, STEM, SLP

Good morning, Paul & Jack here.
Agenda -
Paul's Section:
Staffline (LON:STAF) - a reader request from last week. The latest trading update shows a greatly improved position, with better trading, and an equity raise having fixed the balance sheet debt overhang. So it's now a regular investment, rather than a distressed situation. Despite these improvement, it wouldn't be my sector pick.
Cake Box Holdings (LON:CBOX) - I've been through Maynard Paton's damning report again, in a fair bit of depth. Most of the accounting issues he's unearthed don't seem too important. However, the CFO selling 5% of the company 2 days before the auditor resigned with a critical departure letter, is outrageous. Entrepreneurial management was previously a strong attraction of this share. I don't trust them now, so am steering clear, despite the steep fall in price.
Studio Retail (LON:STU) (I hold) - oh dear, another problem. STU has warned on profits again - not a big deal given supply chain problems. However, far more concerning is that a working capital shortfall has emerged, due to over-stocking. This is such a basic lack of financial control, that I have no confidence in management, so have decided to sell. It's not a very good business, and now we know it's not very well run too. Although this is all reflected in a now ultra-low PER, so it could be a recovery share once working capital has been sorted, maybe?
Purplebricks (LON:PURP) - a catalogie of problems has smashed the share price here. I take a quick look at interim results. Bad - but mainly due to one-off charges. The key point is, it still has £58m cash in the bank, and the market cap is £64m. Could be an interesting one for special situation investors maybe?
Sthree (LON:STEM) - I quickly review the FY 11/2021 results, and am impressed. This looks a good company, performing well, with a decent outlook, and priced sensibly. Also a sound balance sheet. Very good! This is the type of thing we like best here at the SCVR - a decent company, reasonably priced.
Jack's section:
Belvoir (LON:BLV) - full year profit before tax to be comfortably ahead of expectations thanks to a strong sales market. While this has since shown signs of normalising post-stamp duty holiday, the outlook for lettings remains positive. A quality company on an undemanding valuation.
Tandem (LON:TND) - I hold - profit before tax expected to be slightly ahead of current market expectations. The current financial year has started off more slowly, but there’s good momentum in eMobility and the new warehouse should be complete by Q4 2022, which is a significant development. The valuation remains undemanding.
Sylvania Platinum (LON:SLP) - I hold - FY production target brought down from 70koz to 66-68koz as the group grapples with a couple of short term operational issues. Cash generation remains excellent. The critical factor remains PGM basket prices. These are hard to anticipate and it means models / forecasts are very sensitive to inputs, but the general outlook remains positive.
Friday's podcast
Jack & I are now recording a weekly podcast summary of the SCVRs on Spotify.
The sound quality at my end was poor, sorry about that. I've re-recorded my bits as a video here:
It's the same content as the podcast, but a bit more detailed, and better quality sound.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Staffline (LON:STAF)
56p - mkt cap £93m
(this announcement was from last week)
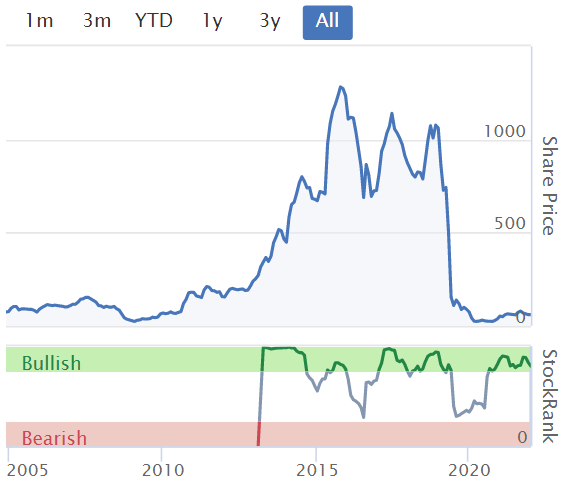
Staffing companies generally are doing well at the moment, as there’s plenty of demand for labour, and near full employment. Staffline has had a very chequered past though, and came close to going bust when lots of problems emerged. So I’m wary of this share.
There’s been massive dilution, from 34m shares in 2018, to 165.8m shares now, which was required to keep the company afloat. So realistically, the share price is never likely to return to anywhere near previous highs.
Note that the former CEO, Andy Hogarth, banked £10.3m in Jan 2018, at 1020p per share, which was 16 months before the share price collapsed (pre-covid) in July 2019.
There are so many examples of £multi-million Director sales preceding bad news, that it’s a big sell signal when the people who know the company best are bailing out - whatever the reasons given.
.
.
Trading Update (issued 25 Jan 2022)
Staffline, the recruitment and training group, is pleased to provide the following trading update for the year ended 31 December 2021.
The company’s summary says this -
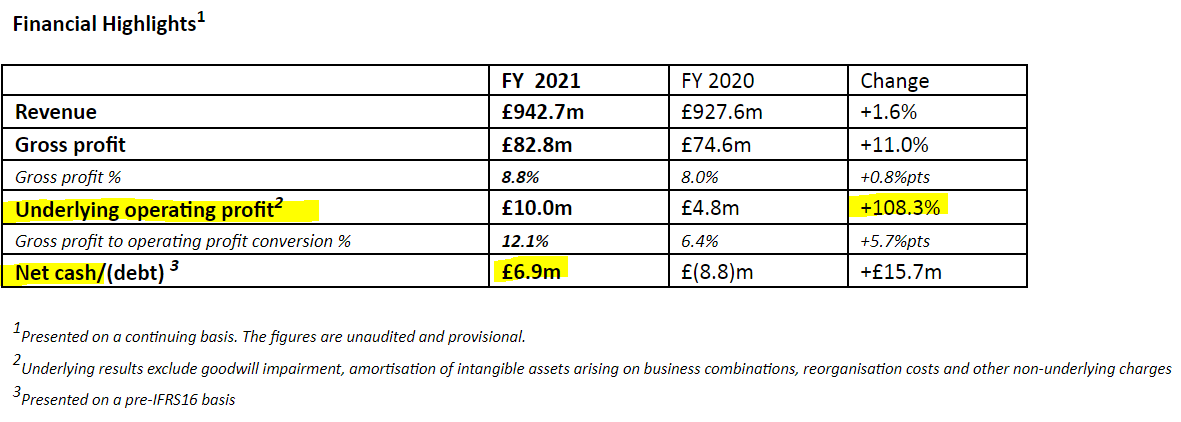
- 2021 Underlying Operating Profit doubles year-on-year; c. 11% ahead of market expectations
- Strong FY 2021 performance underpins increased confidence for FY 2022
The highlights table below also looks good, although the footnotes show quite a lot of adjustments are made, so I need to dig deeper to get the full picture when the full results are published.
.
I tend to ignore the revenue line for staffing companies, as it includes the pass-through wages of the contract staff. So gross profit is better seen as revenue for the staffing company itself.
Summarising the rest of the announcement -
Strong trading in H2.
Revenue up slightly, despite exiting low margin contracts.
U/l operating profit (not my preferred profit measure) is said to be 11% ahead of market expectations for FY 12/2021, which seems pretty good.
Note that it made £4.6m in H1, so H2 is £5.4m adj operating profit.
Cash & liquidity - looks to be dramatically improved from when I last looked, when STAF was mired in debt & surviving due to deferring a large VAT bill, which now looks sorted. Adjusting for the temporary benefits mentioned below, STAF is really in an underlying net debt position of £8.9m.
Staffline's balance sheet was significantly strengthened during the year with the Group expected to report an increase in pre-IFRS16 net cash of £15.7m to £6.9m at 31 December 2021 (2020: net debt of £(8.8)m), despite repaying the majority (£40.7m) of its Deferred VAT Relief, with the remaining balance of £5.8m to be repaid on 31 January 2022. This substantial improvement was achieved through a successful equity raise of £46.4m (net of costs), and includes c. £10m of timing benefits, which are expected to unwind, alongside further improvements in trading cash flow and cash collections. The Group's financing headroom, relative to available committed banking facilities at 31 December 2021, was in excess of £75m.
Outlook - sounds generally positive, although note at the end it refers to medium & long-term. Which tends to suggest by omission, that the short term outlook may not be quite so rosy perhaps?
The Group has delivered an excellent performance in 2021, exceeding expectations in both profitability and cashflows, with upgrades to market expectations during 2021 against a backdrop of continued macroeconomic headwinds.
This momentum is expected to continue into 2022, supported by a strong new business pipeline, a lower overhead cost base and the expected post-Covid recovery of historically strong Staffline recruitment sectors, such as automotive, manufacturing, aerospace and travel.
The Board remains confident in the growth prospects for the Group in the medium-to-long-term…
The pipeline for 2022 is encouraging, underpinning the Board's increased confidence in the current financial year and beyond."
Diary date - 22 March for FY 12/2021 results.
My opinion - I’m also looking through the last interim results, and the figures look quite clean, with all the restructuring & exceptional costs looking to have been kitchen-sinked previously in 2019.
The refinancings have improved the balance sheet considerably, but it still had negative NTAV of £(11.3)m at 30 June 2021 - not strong, but not threatening solvency either.
Overall it’s gone from a basket case, to a reasonable position now. Hence risk has dramatically reduced, and STAF shares now look investable again. Would I want to invest though? Not really. It’s a low margin business, eking out a tiny margin from large revenues, but as we’ve seen before, with plenty of risks that accounting and regulatory issues can go wrong.
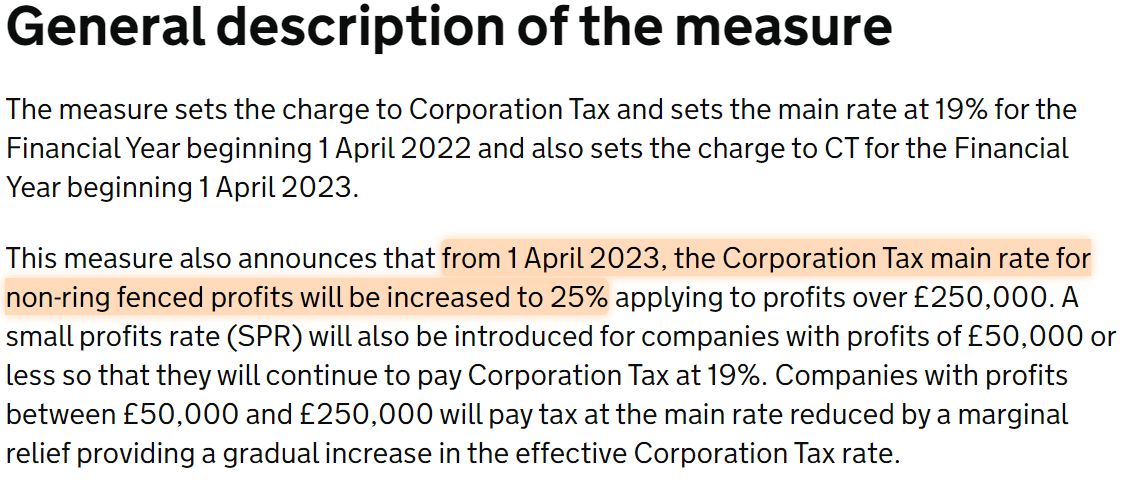
Many thanks to Liberum for making its forecasts available on Research Tree. EPS is forecast to reduce in 2022 to 4.71p, then rise to 5.84p in 2023, a PER of about 10 times 2023 forecasts. Note that tax rates rise, swallowing up a lot of the improved profit - that's a headwind for most companies, as corporation tax is set to rise significantly, from 19% to 25%.
If I wanted to buy a staffing company, then I’d be more inclined to look at Robert Walters (LON:RWA) or Sthree (LON:STEM) which are not much more expensive (fwd PERs of about 13), but with none of the historic problems which dogged STAF.
From the Govt's website (click below for link)
.
Cake Box Holdings (LON:CBOX)
236p - mkt cap £94.4m
This has been a fascinating situation. This is a very long section, so feel free to skip to the next item if it doesn't interest you.
It’s a franchise business, selling egg-free cakes, which floated on AIM in 2018. The shares traded sideways, until going on a tear in 2021, doubling from c.200p to peak just above 400p.
The founder & largest shareholder sold a quarter of his holding in a secondary placing on 25 Nov 2021, at 350p, a significant discount at the time, trousering £10.5m.
I reviewed the situation here on 25 Nov 2021, concluding that the founder remained the largest shareholder, so it didn’t look a cause for alarm that he wanted to bank some profit. However, I did feel at the time that this large Director sale put a cap on the share price, and limited the upside, hence concluding that CBOX shares looked fully valued for now, and I would only be interested in buying on any dips, to c.300p.
The next event was when respected shares analyst Maynard Paton issued a bombshell report here, on 21 Jan 2022. This is what has triggered a large sell-off in the shares of CBOX, coinciding with a nasty market sell-off in many shares. It reads a bit like a shorting dossier, but more concise, and I don’t think Maynard has shorted the shares. His motives appear completely genuine, revealing inconsistencies and concerns in the Annual Report, that everyone else seemed to miss.
I think Maynard deserves a hearty pat on the back, for doing such detailed work scrutinising the accounts, and finding a catalogue of oddities in the annual report. This must have been a huge job, and I reckon it’s at least a week’s work, putting together such a detailed report.
Maynard’s description of the company reminded me of Mrs Doyle, so here’s a gratuitous comedy link.
The business operates as a franchisor. It manufactures a “high end, secret recipe” egg-free sponge that is sold to numerous franchisees who in turn use the sponge to make the cakes. The franchisees presently sell the cakes from 200 outlets.
Going through Maynard’s report for the third time, I’m finding most of his queries on the accounts fairly trivial. It’s also quite normal for any errors which are discovered after the accounts are published, to be put through as prior year adjustments. However, the cumulative effect of lots of errors & inconsistencies, is that reading his report, I’m beginning to lose confidence in the company & its management.
It’s looking as if financial controls are not up to scratch, at best. At worst, there could be something a lot more worrying going on.
It’s the relationship with the auditor that is the most worrying aspect of this. CBOX issued an RNS on 20 Sept 2021, “Change of Auditor”, which gives the impression that the auditor is being changed due to a competitive tendering process, which is usually nothing to worry about -
Cake Box, the specialist retailer of fresh cream cakes, is pleased to announce that following a competitive and comprehensive tender process, overseen by the Audit Committee, it has appointed MacIntyre Hudson LLP ("MacIntyre Hudson") as the Company's auditor with immediate effect. The Company intends to put the appointment to a vote of shareholders at the Company's next Annual General Meeting.
The Company's previous auditor, RSM UK Audit LLP, submitted its letter of resignation to the Board of Directors on 16 September 2021. In accordance with the relevant Companies Act 2006 requirements, a copy of the resignation letter and statement of reasons will be sent to shareholders of the Company.
The stock market didn’t flinch at this, and why would it? It sounds perfectly normal. But as it turns out, things were not normal at all. CBOX did not issue an RNS of the letter of resignation from its outgoing auditor, which turns out to be damning. It is on CBOX’s investor relations website, but it seems few people noticed it, or read the letter (if they received it at all, because so many shares are held via nominee accounts). Also, auditor resignation letters hardly ever contain anything of note, so nobody reads them.
This is what RSM’s resignation letter said -
Statement of reasons relating to the resignation of RSM UK Audit LLP as auditors to Cake Box Holdings Plc – Company Number 08777765 (“the Company”) In accordance with section 519 of the Companies Act 2006, we consider that the following matter connected with our ceasing to hold office should be brought to the attention of the company’s members and creditors: During the course of the audit engagement, we became concerned about the robustness of the Company’s control and governance frameworks due to delays in the provision to us of audit evidence, which was not provided on a timely basis. Such delays did not, however, prevent us from issuing an unqualified audit opinion on the Company’s financial statements for the year ended 31 March 2021.
That’s as close as an auditor will get to saying that they don’t trust management. Outgoing auditors generally don’t rock the boat unless there is something seriously wrong.
What shocks me, is that there were worrying things published in CBOX’s annual report’s audit report, which nobody seems to have spotted, until Maynard flagged it in his report last week.
How many of us can truthfully say that we read the audit reports in company annual reports? I should, but in truth, I look at so many companies, that I tend to rely on the preliminary results statements, and only dip into the annual reports online when I need to look up specific details that are not usually published in the preliminary results statements (e.g. breakdown of trade receivables & creditors, bank facility details/covenants, freehold property disclosures, share options detail, etc). Only sometimes will I glance at the audit report. That needs to change. Anyone who did read the audit report, probably would have sold out near the top.
Part of the problem is that audit reports are written in such complex, legalistic language, that even people like me (I trained as an auditor for 3 years, for Price Waterhouse, from 1990-93) find the reports very difficult to understand. There’s surely an urgent need for auditors to make their reports more accessible, and write them in plain English, which would greatly enhance their use. Being cynical, a lot of it seems to be written in complex legal language, so that the auditor can wriggle out of any legal liability when things go wrong. Plus a fundamental question as to what audits are for? If they're not designed to detect fraud (as auditors claim when they fail to detect fraud), then they're largely pointless in my view.
The bottom line in this case, is that the auditor seems to have resigned because of their concerns about management & disclosures, not due to a competitive tender process. It’s quite obvious that CBOX management have not been open & honest with the auditor, e.g. by hiding the data breach it suffered, for about a year.
The big question is this - has CBOX fiddled the figures to any material extent? I think the jury is out on that. It’s not always easy to identify dodgy accounts. Look at Patisserie Valerie - unfortunately another vendor of cakes, which it turned out was a massive fraud - where management were hiding liabilities (undisclosed overdrafts & other creditors) off balance sheet, by running 2 sets of books. That’s almost impossible to identify from the accounts, because the auditor and investors, are only shown the dodgy accounts.
I must remember to check my change, next time I buy a cake from anyone.
With hindsight, the signs were there with Patisserie Valerie - mainly that it made an implausibly high profit margin, in a sector where nobody else seemed to be able to make a 10% profit margin. Also, the numbers looked too perfect - too consistent, with a smooth steady upward progression of revenues & profits. Liabilities on the balance sheet also, with hindsight, looked too low.
Could CAKE’s accounts be a similar work of fiction? We don’t know, it’s possible at any company - not just small caps, plenty of large caps also fiddle the figures, e.g. remember Tesco getting itself into hot water a few years ago, when they were cooking the books with creative accounting for supplier discounts, or something like that.
People take bizarre risks when pressurised to deliver results that the city, and investors, want to see. Plus hardly anyone ever goes to prison over this sort of thing, as investigations seem to take years, and usually fall apart, letting off the culprits.
Going back to frauds that I did identify in the past, the signs were usually very obvious, and it’s the balance sheet where the bodies are buried - usually obviously large & unusual assets, such as excessive receivables, bloated intangible assets, etc. Understated creditors are also a feature of frauds, but are harder to spot.
There were dozens of frauds on AIM, particularly from Chinese companies which listed on AIM a few years ago, almost all of which turned out to be frauds - which we spotted here, and put out a blanket avoid opinion on all Chinese AIM stocks, which turned out to be very sensible.
Also we picked up on Globo and Quindell, both of those frauds were blindingly obvious from the balance sheets, and dripping with other red flags. Gullible investors just chose to ignore the warnings, so tough luck if they lost money - hopefully they learned from the experience, and I have zero sympathy for people who shoot the messengers (like me) who explained all the detail about why these were obvious frauds, for a long time before they blew up. I don’t like his personal style, but Tom Winnifrith has done excellent work on many frauds - most of them very obvious things to avoid though, that we wouldn’t even bother to mention at all here because they're so bad - e.g. zero revenues jam tomorrow rubbish.
Going back to CBOX, I’m not concerned about it revaluing its freehold property upwards. I actually think freehold property should be revalued to market value, not kept at historic cost, as that way we get more accurate, real world ROCE calculations. A company which e.g. bought some freehold property just after WWII ended, and still has it shown in the accounts at cost, is arguably deceiving us about its returns on assets that are now seriously under-valued on the balance sheet.
Going through CBOX’s balance sheet, “Other financial assets” look unusual, but is not huge at £1.0m (see note 17 in the prelims) and this seems to be loans receivable from franchisees. Not unusual, or large, for a franchise business.
Inventories & receivables look fine to me, they’re not large, for the size of business, although note the auditor wasn’t happy with controls over inventories. But they did issue a clean audit opinion, so any queries must have been resolved.
The £5.1m cash pile must be real - as cash is the easiest thing of all to audit. Mind you, Chinese frauds got round that by pumping cash into the company just before year end from an undisclosed lender, then whipping it back out again shortly afterwards. You would hope that RSM would be smart enough to have checked the cash balances throughout the year, not just at year end.
Current liabilities as at 31 March 2021 rose a lot compared with the prior year. That doesn’t shout out to me that liabilities are being hidden.
Overall, I can’t see anything obviously odd or worrying about this balance sheet. That doesn’t rule out any problems later emerging, just that I can’t see anything untoward.
Response from CBOX - this statement was issued on 24 Jan 2022, and I find it rather unsatisfactory.
The initial sentence strikes me as haughty, and intended to belittle Maynard Paton’s meticulous report:
Cake Box notes the movement in its share price this morning and also notes recent commentary from a retail investor blogger.
CBOX describes the issues as “transcription errors”, which strikes me as odd -
The Company acknowledges some transcription errors between its 2021 Full Year Results announcement published on 30 June 2021 (the "Results Announcement") and the 2021 Annual Report and Accounts (the "Annual Report"). It also notes inconsistencies in prior period inventory reporting and comparative period disclosures relating to director interests in franchise stores. Where such discrepancies exist between the Annual Report and the Results Announcement, investors should refer to the Results Announcement.
It does however make this following valid point, so are we getting steamed up about things that don’t really matter? I can’t make up my mind on this point.
The errors noted have no impact on the Group's reported profits, cash flows or balance sheet and the Company received a clean audit opinion for the year.
It tacitly admits here that internal financial controls (and hence finance management) are not up to scratch -
As previously announced and as we continue to grow the business, a key priority for the Board remains underpinning growth with the appropriate level of experience and expertise for the Group's central functions, internal controls and processes. BDO has also been appointed to assist with implementing improved internal audit practices.
I think the CFO has to go, after presiding over clearly sloppy (and maybe worse) financial controls.
Also looking at the Director trades, the CFO banked £1.3m personally in share sales 2 days before the auditor resigned! That’s outrageous, and it makes him look dishonest. He has to go.
.

.
Going back to Maynard’s report, he questions the unusual disclosure of ageing of payables (as opposed to the more usual disclosure of ageing of receivables). He says he can’t remember seeing this before. Purely from memory, I think I have seen this disclosure before, and it’s not important, unless it shows stretched creditors, which this doesn’t. Getting too much information is not a problem.
Similarly, Maynard questions trade receivables, which are meant to be on 7-day terms, but look higher. I don’t think this is a concern, as during the pandemic, it’s entirely possible & reasonable, that CBOX may have given some leniency to franchisees which might have had cashflow problems, due to lockdowns, and given them more time to pay. So this doesn’t worry me.
Current trading - sounds OK. A reminder that this does seem to be a decent business, if we take announcements at face value (which inevitably now has a question mark dangling over it) -
The Board confirms that, since the Company updated the market with its half year results in November, trading in H2 has continued strongly and in line with expectations for the full year.
My opinion - what a fascinating situation, and big thanks to Maynard Paton for this superb report.
I’ve only reviewed it, Maynard is much closer to the detail than me, most of the details he raises are fairly minor.
However, the resignation of the auditor, with a damning resignation letter, and the CEO/CFO selling millions of pounds worth of shares when they knew there was a big problem over the accounts, puts too big a question mark over this company and the trustworthiness of its top Directors.
For that reason, I’m not prepared to take a risk by giving them the benefit of the doubt, at this stage.
I’ve changed my mind on that, having had a few days to think about this. Initially, thought it all looked a bit of a storm in a teacup, but now I’ve decided to play it safe. This could cast a cloud over the share for a long time.
To reflect the risk, I’d want a much cheaper share price, with a big discount. What level would tempt me to buy? Right now, it would have to be really low, maybe 100p or less?
Having said that, CBOX does look like a decent business. There hasn’t been any dilution since it listed almost 4 years ago, despite strong growth. Franchisees are lining up to open new shops, and pay hefty fees for doing so. I remain of the view, from the published numbers, that this is fundamentally a decent business. But can we trust management? That’s for you to decide.
The outgoing auditor clearly doesn’t trust them, so why would I?
Pity, as management came across so well on previous webinars. So I’d like to hear more from management. Ideally, a new webinar, where they openly ‘fess up to what they did wrong, apologise, launch a new range called “humble pie” maybe, bring in a new CFO, and draw a line under these issues. It seems a fundamentally decent business, but lots of investors are probably now worried that it could be a can of worms.
As a former CFO myself, there’s no excuse for sloppy financial controls. Everything should be pinned down, and reconciled to the penny. In my CFO days, I used to reconcile everything, every month, so the end of year procedures were a doddle. So I really baulk at CFOs that don’t know what they’re doing, or are in a muddle, or even worse maybe fiddling the figures. We all have a bottom drawer account, to smooth over any nasty surprises, but the basic accounting has to be accurate.
That said, Maynard hasn’t found a smoking gun, or anything seriously incorrect with the accounts, and despite disapproving of the financial controls, the auditor did sign off the last accounts as being accurate.
Follow the money, as they say. The main 2 Director/shareholders have banked millions, just before, or even after, these problems surfaced (but only Maynard noticed, to his credit).
They know the company best, and have taken millions off the table, so overall, I think I’ll avoid this share. Why take the risk?
.
Studio Retail (LON:STU) (I hold)
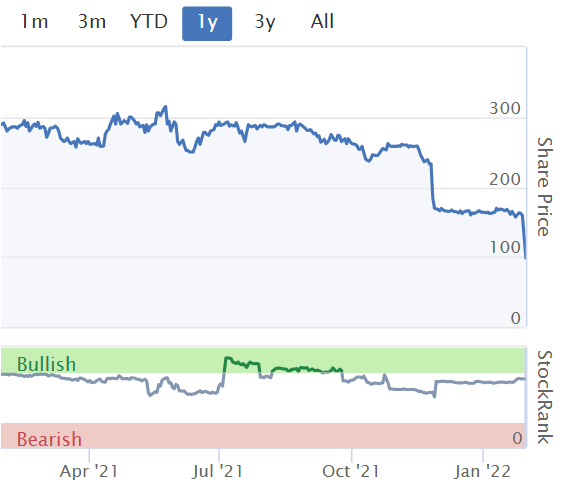
92p (down 42% at 09:46) - mkt cap £80m
I was half-expecting another profit warning from this online retail/ instalment credit business.
Previously STU issued a mild profit warning which I reviewed here on 26 Nov 2021. It wasn’t unreasonable, given supply chain problems that are affecting everyone - delays, and additional costs, so to be expected that profit expectations were trimmed a little. I concluded that it wasn’t serious, and the business looked adequately funded.
That’s changed for the worse today, with another profit warning (not in itself particularly surprising), but I’m more concerned that the company tells us today that it has run into a working capital shortfall -
… in addition to advising it is exploring a range of options to meet a short-term working capital funding requirement…including discussing the current level of our working capital facilities with our long-standing UK lenders.
It is also likely that some of the actions to improve short-term working capital discussed below will further reduce margin in the remaining weeks of the year…
What has gone wrong with working capital? It looks very basic to me - they’re just ordered too much stock -
… This has led to a higher level of inventory than normal at this time of the year. This is further compounded by commitments to current and future season stock needing to be made earlier than normal due to ongoing nervousness in supply chains.
Supply chain - still causing additional costs, as I would expect. Today's headwinds will eventually turn into tailwinds, once supply chains ease. But not any time soon -
We have also incurred some further costs linked to the shipping delays and port congestion…
We anticipate that the disruption to supply chains will continue throughout calendar 2022…
Profit guidance - has been reduced again, but is still healthy for a business that now only has a market cap of £80m.
As a result, our current expectations for Adjusted PBT(1) for the full year are now likely to be in a range of £28m to £30m.
My opinion - I’m disgusted at this. Trimming profit guidance is fine, and to be expected given the ongoing supply chain issues. But over-ordering stock, then apparently being surprised when you run out of liquidity, is appalling. It demonstrates to me that the CFO doesn’t have proper control over the business, and buyers perhaps operating independently of the finance department, and not having proper budgets, or controls. There's clearly inadequate forecasting & control going on. The whole point is that problems like this should have been anticipated, and avoided.
A good CFO would have prevented this happening, and would have lined up additional borrowing facilities in advance. Not drop a bombshell on shareholders, who now have to hope the bank decide to be helpful & flexible.
There’s now a chance the bank might dig in, and tell the company to raise additional money from shareholders. Hence a risk of a placing, and the trouble with those, is the institutions can just name their price. They might be supportive, and want to protect the value of their existing shares, or they might be brutal and demand a deep discount for putting in fresh capital. It’s an almost random risk factor where private shareholders don’t know the outcome. It could be fine (e.g. Card Factory (LON:CARD) somehow muddled through without diluting shareholders, despite looking quite precarious for a while, but better now). However Revolution Bars (LON:RBG) (I hold) shareholders got stuffed twice, with 2 deeply discounted fundraises. You just can’t tell how things are going to go, in situations where more equity is needed.
I’m seriously unimpressed with mgt at STU, and didn’t think it was a very good company to start with. Now we know it’s badly run, without effective financial controls over the buying & stock holdings, with the uncertainty of whether the bank will extend support, which might include a requirement to do a placing, I think this share has become very unattractive for the time being.
It was never a high conviction holding for me, and now I’ve lost confidence in management, am not prepared to sit around and wait for it to fix the funding shortfall, as that introduces a lot more risk than I originally planned.
So I’ve decided to ditch this share, and move on.
Bull case - at some point it could recover of course (probably just after I sell!). The update note from Liberum today (many thanks for this) reduces EPS for FY 3/2022 to 25.8p. At 92p, that’s a PER of just 3.6 times. So once the dust has settled and the all-important working capital crunch has been dealt with, I’ll take a fresh look at the share.
Although I’m not likely to buy back in until the CFO has been replaced. Preventing a company running out of cash is the absolute core duty of all CFOs. Having someone asleep at the wheel, and then telling the stock market that you’re exploring options to get hold of more working capital, is totally unacceptable.
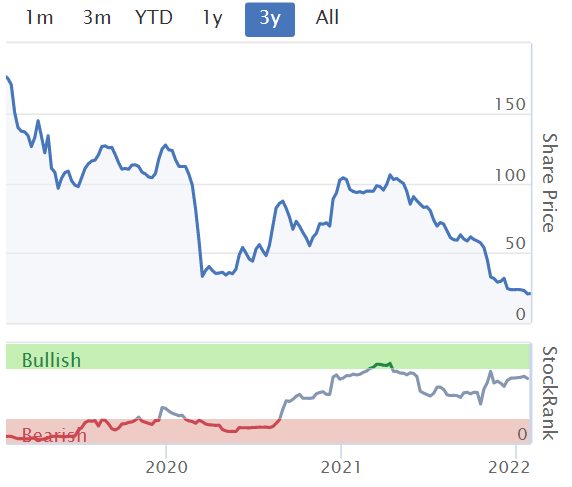
There are plenty of charts that look like this at the moment. Some of them could be great buys, for a recovery. The jury's out on whether STU is one of those or not.
.
Purplebricks (LON:PURP)
20.9p (up 4% at 11:26) - mkt cap £64m
This is on my list of potential turnarounds. The share price has been smashed downwards by a catalogue of expensive problems that need sorting out. On the upside, PURP had plenty of cash in the bank, and a well-known brand name.
Purplebricks Group plc (AIM: PURP), the UK's leading tech-led estate agency business, announces its half year results for the six months ended 31 October 2021
H1 trading has been very poor, with a big increase in exceptional costs (of £8.3m) causing an operating loss of £(11.1)m.
Note that revenues was flattered by instructions from the prior period, so the underlying picture from instructions is a lot worse than the reported revenues.
Clearly the business is in trouble, and they say it’s been restructured, but crucially it still benefits from a big cash pile, of £58.3m. There’s a very healthy £50.7m of net current assets, so PURP looks financially strong enough to survive, as other online estate agents risk withering away as their funding dries up.
Provision for problems at its lettings division have been made at £3.6m, which is less than some press reports suggested.
Outlook comments - don’t have a lot of credibility in my eyes, given previous mis-steps, and this first bit sounds negative -
Since the period-end, we have continued to see a significant imbalance between the strong demand for housing and a very limited supply of stock, which has driven house prices higher. Although housing supply has increased in January, we expect these market dynamics to continue through the second half of our financial year, which will continue to impact instructions and gross margins. In addition, the comparable performance will also be impacted by the expected increase in costs associated with our transition to a fully employed model.
Set against these market challenges, we are greatly encouraged by the positive signs we are seeing in our operational performance since we implemented our new operating model. We are confident that the steps we have taken to improve the business will drive a return to growth and market share gains in 2023.
My opinion - this share looks a potentially interesting special situation. The key point is that it’s got pots of cash, so should hopefully be able to get through the various issues which have arisen.
Anyone buying this share needs to properly research it, and be fully aware of the various problems, and risks.
At £64m, the market cap looks cheap, given there is not far off that amount of cash in the bank, of £58m.
Does the cash deplete, from continued trading losses, and settling old liabilities? Or does the business stabilise, and return to growth? No idea! With the shares down at this lowly level, I think risk:reward could be coming into interesting territory, for special situations investors.
I'm wondering if there might be an opportunity for a trade here - targeting say a 50% gain, then moving on? The bad news is probably in the price now, but you never can tell for sure.
.
.
Sthree (LON:STEM)
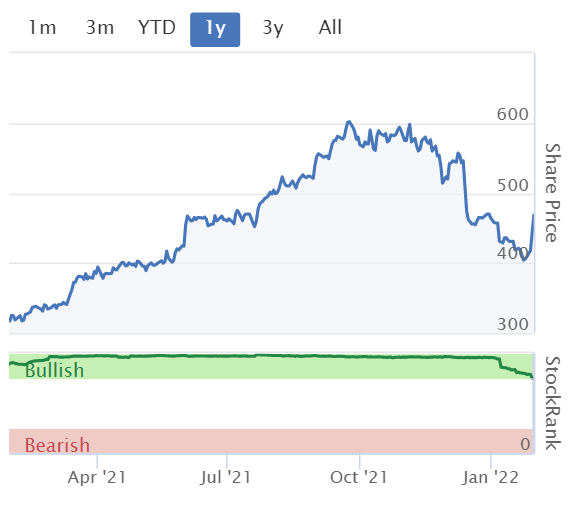
467p (up 12% at 11:53) - mkt cap £625m
This share has cropped up in the reader comments before, with our resident sector expert BnB previously flagging this as a good staffing company, reasonably priced. Jack has also written about Robert Walters (LON:RWA) several times, following positive trading updates. We prefer these shares to say Staffline (LON:STAF) (see above) or Gattaca (LON:GATC) .
Looking at the accounts today from STEM, it immediately strikes me how much better quality the business is than STAF. STEM makes a much stronger profit margin, which shot up from 10.1% in FY 11/2020, to 17.1% in FY 11/2021 - this measure is calculated as operating profit divided by net fees. Actually STAF is behind, but not horrendously so, at 12.1%
I’m wondering if STEM is getting a one-off return to normal margins, after weak margins during the pandemic? So maybe we shouldn’t be expecting profit growth to continue at the same rapid rate in future?
Basic EPS is 31.8p, up 129% on LY - excellent.
The PER is now 14.7, taking into account today’s 12% rise in share price. Seems reasonable still.
Outlook comments -
Our year started with strong forward momentum. We will continue to build sustainable growth and will resume our plans for internal investment during the year, particularly in the infrastructure that will allow us to expertly harness data and efficiencies, for example in further enhanced CRM and ERP platforms. We expect to deliver double-digit growth in net fees and profits in 2022, maintaining our operating conversion ratio at similar levels to 2021 to allow for the impact from investment of between 1% and 2% of net fees to further strengthen our operational and sales platforms. We anticipate payback on the investment, delivering an acceleration of margins from 2023.
I believe we have good reason to be confident: we are in the right markets, we are focused on the right sectors, and we have a team that is flexible and resilient enough to seize the opportunities ahead of us.
Balance sheet - looks fine to me, it’s ungeared, with £57.5m net cash.
No issues here at all, that I can see.
My opinion - just a quick, superficial look at the key numbers, but I’ve come away impressed. This looks a decent business, reasonably priced, and financially strong.
This looks a good place to park your money, so a thumbs up from me.
.
.
Jack’s section
Belvoir (LON:BLV)
Share price: 257.44p (+6.82%)
Shares in issue: 37,292,113
Market cap: £96m
This is a leading UK property franchise and financial services group. Along with M Winkworth (LON:WINK) and Property Franchise (LON:TPFG) (I hold), these stocks offer good profitability, financial health, and growth prospects at reasonable valuations.

I’m a fan of the business model here. Franchise income is high margin and the companies are cash generative. There is cyclicality risk if we see a downturn in the property market, which would hit share prices, but enterprises such as Belvoir would ultimately survive and continue to grow longer term, in my opinion.
Trading update for the year to 31 December 2021
Comfortably Ahead of Expectations
Revenue is up 36% in the year to a record £29.6m, meaning profit before tax will be comfortably ahead of management expectations.
2021 was one of the busiest years in recent times for the estate agency, with residential property sales transactions up 41% on 2020 and 22% ahead of the six-year average to 2019.
Against this strong backdrop, the group expanded both its property and financial services networks with the acquisitions of Nicholas Humphreys (a specialist student lettings franchise), and Nottingham Mortgage Services (the mortgage arm of The Nottingham Building Society).
Revenue from the financial services division increased significantly by 49% to £14.4m, having grown the network of financial advisers by 20% to 243. Conditions were buoyant in the residential property sales market throughout most of 2021, and towards the end of the year experienced a strong period for remortgage activity.
Revenue from the property division was up 27% to £15.2m. The acquisition of the Nicholas Humphreys network added £2.2m.
Management service fees ("MSF"), the key underlying return from franchisees, was up 18% for the year to £10.7m.
Sales MSF jumped by 56% to £2.5m, with the extension of the stamp duty holiday ensuring that the residential sales market remained highly active until September. After that, the market returned to more normal transaction levels but unfulfilled demand has continued to fuel house price inflation.
Lettings MSF increased by 10% to £8.2m* (2020: £7.5m) of which £0.3m related to the Nicholas Humphreys acquisition and newly franchised Lovelle offices. The underlying lettings MSF increase of 6% reflected a strong lettings market.
The demand for more space and a return of young people to UK cities as offices re-opened post lockdown resulted in insufficient supply of available properties to rent and as such rents on new tenancies were seen to rise by around 8%.
Net debt has fallen by almost two thirds to £1.3m (2020: £3.7m), despite £4.7m of cash spent on corporate acquisitions.
Dorian Gonsalves, CEO, commented:
With our significant recurring lettings revenue stream and our substantial financial services client base to draw upon during what is currently a strong market for remortgages, we believe the Group is well insulated from what could be a more challenging market in 2022. Given the resilience and diversity of our business model, we remain confident that we will continue to perform well relative to the market as a whole. Meanwhile, the Board continues to identify suitable acquisition targets to support continued growth and enhance shareholder value still further.
Diary date - The audited results for the financial year ended 31 December 2021 will be announced on Monday, 4 April 2022.
There’s also a 20 minute presentation, including Q&A from participants, at Mello on Monday 7 February, starting at 6pm. If you want to attend as a shareholder, you can register here for the event using code SHVIP for 75% off tickets.
Conclusion
Belvoir has grown its revenue at a compound annual growth rate of more than 25% over the past five years, with operating margins consistently around 30%.
The group has proven itself over the past couple of years as a well run company, one of the best in its space. It has done a particularly good job in growing its financial services division and seems to be ahead of competition here. I think the stock is probably too cheap at these levels and warrants a higher valuation multiple.
There are perhaps general concerns around the long term health of the property market, particularly as the Bank looks to nudge up interest rates. And the CEO does touch on this in his comment, with signs that 2022 might be more challenging.
Everything I’ve seen so far suggests a pretty buoyant rental market though. The group notes the return of workers to cities and ‘insufficient properties to rent’. Perhaps Gonsalves’s comment refers to the sales market then, which has contributed a higher-than-usual amount to gross profit this year.
Ultimately I continue to think the shares offer good value at 12.8x forecast earnings (likely less) and a forecast yield of 3.61%.
Tandem (LON:TND)
Share price: 509.6p (+1.92%)
Shares in issue: 5,284,116
Market cap: £26.9m
(I hold)
Trading update for the year to 31 December 2021
The Group expects to report FY21 revenue of £40.9m, with FY21 profit before tax expected to be well ahead of the prior year and slightly ahead of the current market expectations.
It looks like the current market expectation is for profit before tax of £4.6m.
The Christmas trading period saw continued robust performance from the group's toys, sports & leisure business and, whilst H2 growth rates did not match H1, turnover was still over 7% ahead of the same period in the prior year.
Revenue in the first half of the year was approximately 14% ahead.
Toys, sports & leisure - Revenue from the toy, sports and leisure business was ahead of the prior year. The Ben Sayers golf range continued to perform well, with revenue growth of 33%.
The group recently exhibited at London Toy Fair with positive feedback, especially on new licences including Bluey, CoComelon and Rainbow High. There was also general excitement about the new Disney Pixar Lightyear range, with the movie being released in June this year.
Bicycles - Revenue approximately 3% ahead of last year, with the lightweight Squish branded children's range performing strongly, (+31% turnover on the prior period). The challenge here remains stock availability, although this pressure has been easing in recent months and the group starts the current year with better availability.
Home & garden - Revenue was approximately 9% ahead of the prior period, with solid growth in outdoor ranges. These are mostly sold from Tandem’s online platforms.
eMobility - Revenue increased by over 70% compared to the prior year comparative, with our Li-Fe and Wired range of eScooters performing particularly well. Sales of eBikes under the Dawes, Falcon and Claud Butler brands also saw significant double digit growth.
Outlook - 2022 has begun more slowly, with some customers delaying orders into future months.
Tandem does expect its eMobility business to continue to expand in 2022 though and is investing further here. This includes a refurbishment of the group’s onsite shop at Castle Bromwich, planned for completion in Q2 2022.
Work has begun on a new B2C (business to consumer) website which will focus on all of Tandem’s eMobility products.
Formal planning permission was granted on 23 December 2021 for the new warehouse project with no pre-commencement conditions attached. Construction work has now begun and is anticipated to be completed in Q4 2022. This warehouse will provide the group with additional capacity, helping to grow its domestic business and enhance efficiency due to centralised operations. This should be a big step forward, operationally speaking.
The business continues to experience global logistical challenges, which are still impacting upon the supply of goods from the Far East to the UK. Despite this, our order book remains materially ahead of the comparative position in the prior year.
Diary date - FY21 results to be published on 28 March 2022.
Conclusion
Tandem has a habit of releasing updates that sound slightly mixed. Positives:
- FY21 profit before tax expected to be well ahead of the prior year and slightly ahead of the current market expectations,
- Stock availability is improving,
- The new warehouse is in construction and will bring extra capacity and cost savings from Q4 2022,
- Home and garden sales are up 9% year-on-year,
- eMobility is +70% yoy,
- Order book is 10% higher than last year’s, which was a record at the time.
Negatives:
- Global logistics issues remain,
- 2022 has begun more slowly.
On balance, there is more good than bad here and with the company’s current valuation (c6.4x forecast PER) there is probably upside. I think the valuation is an important consideration here. This is not a racey software multiple demanding high levels of growth. It is a £29.7m market cap company racking up £40.7m in annual revenue, with operating margins recently in excess of 10%.
All that’s required in order to lift the shares is steady progress, which is still on the cards. Tandem is well positioned to benefit from growth in eMobility, while its renewed focus on websites and online trading is good news. The group’s net asset value should continue to grow as well, and the new warehouse is a significant development for the enterprise.
Overall, I’m positive at these levels. It’s not in the company’s character to ‘wow’ the market with the tone of its updates, so the investment requires patience. But I do think several initiatives are moving in the right direction and it’s entirely possible for Tandem to grow over time given its brands, expertise, routes to markets, and cash generation.
Sylvania Platinum (LON:SLP)
Share price: 95.82p (-3.21%)
Shares in issue: 272,985,435
Market cap: £261.6m
(I hold)
Stockopedia’s own Investment Club has a holding here - in fact it is the club’s best-performing current investment, although the past six months or so have been less stellar.
Q2 update to 31 December 2021
- Sylvania Dump Operations ("SDO") achieved 16,605 4E PGM ounces in Q2 (Q1: 15,771 ounces),
- SDO Q2 net revenue up from $29.8m to $37.9m,
- Cash costs per 4E PGM ounce down from $862 to $772,
- Group EBITDA up from $13.6m to $22.3m,
- Net profit up from $8.6m to $15.5m,
- Cash balance of $110.1m (Q1: $132.7m).
It sounds as though there are a few short term challenges.
The Western operations have faced continuing challenges due to water shortages at the plant and water shortages at Lesedi were exacerbated by the temporary tailings deposition strategy. Another challenge is lower PGM feed grades in ROM at Mooinooi operation.
Full year production guidance has been pulled back to 66-68koz from 70koz as a result.
Production should lift in H2 as new projects begin to make an impact and Samancor restarts.
Offsetting some of this is an improvement in PGM recovery efficiency, up 5% in the quarter and resulting in reduced costs. There are signs of an improving PGM basket price, too, which is what led to SLP’s initial dramatic share price gains a couple of years ago.
The Grasvally sale is back on, with the $6.4m purchase price for SLP’s 74% stake to be paid over 15 instalments.
Commenting on the Q2 results, Sylvania's CEO, Jaco Prinsloo said:
Net revenue increased 27% to $37.9 million and net profit increased 80% to $15.5 million, with the PGM basket price realised from our smelters of $2,892/ounce remaining at similar levels as Q1. Our capital projects remain fully funded from current cash reserves and we are making significant progress in terms of access to additional chrome tailings resources at both the Eastern and Western Operations.
Conclusion
There has been quite a lot of share price turbulence here recently, but the underlying rationale remains the same: if the PGM basket price has reached a new equilibrium and the outlook is positive, then SLP is set to generate a lot of cash in the coming years.
The shares have risen from 20p to 96p over the past three years but still trade on a forecast PER of just 3.9x. It’s worth viewing the past 12 months’ share price performance in that context.

Still, the share price volatility is a consideration and I feel as though it might have caught a few investors out over the past six to eight months. There are some short term operational challenges which could mean that volatility continues now it has rerated from 2020 levels.
These operational challenges, assuming they can be handled by the experienced management team, pale in significance compared to views on medium term PGM prices. That is the critical factor here. Liberum is forecasting net cash flow from operating activities of $66.3m and $127.1m for FY22 and FY23 respectively, which are big numbers for a £270m company. Net cash is forecast to grow from $106m in FY21 to $217m by FY23.
The share price is at times noisy and a lot depends on the future PGM basket, which is a dynamic that Sylvania itself acknowledges is difficult to forecast. Recent trends have been positive though and the shares continue to look cheap at the current levels of cash generation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
paul loved the chat on the podcast, please do again. Half an hour of golden nuggets! (Wasn’t that a sweet breakfast cereal??!)
Hi Paul, Really like the new podcast format you are doing :)
Great stuff!
All the best
re Cake Box Holdings (LON:CBOX)
I was invested in it for about a year. Rode the share price all the way from £200 to £400+ just to see all profits wiped out. Sold my shares today before going on to negative, don’t plan to buy back anytime soon (never try to catch a falling knife). If and only If goes about 50% discount from here and CFO is replaced I could consider once again buying this share as I think the business is terrific. Such a shame, promising business and management, I’m truly sad.
A large increase with microcap Digitalbox (LON:DBOX) today. There is a fair amount to like about this share. Jack covered it on the 6th Jan 2022 https://www.stockopedia.com/co...
And a great interview with the management today; on Martin Flitton's blog https://martinflitton1.wixsite...
I am tempted to build a larger position after reading this, but nervous as it is likely to be highly volatile.
Am I missing something or is the Unbound (LON:UBG) AIM admission document not on the website as it is supposed to be? Anyone know where I can find it?
Yes, you are missing something. (I am too polite to say what). The Unbound (LON:UBG) AIM admission document is there. Go to the website, then investors admission information and you can download all 188 pages of it.
Is it really necessary to be so rude??? Maybe just don't bother responding next time.
It isn't then at the location that was specified in the Schedule One that was RNS'd, which is actually why I didn't find it...
Regarding $PURP they may an advantage if the market gets squeezed as they operate a fixed price model. I have, last week, put my home up for sale with Purple Bricks. The service so far has been excellent, photos taken within 2 days, schedule next day and on the market within the week from start to finish. I had a couple quotes from local estate agents, who were all charging a % of sale, plus marketing, photos etc. In fact the closest price I had for selling was average £5500 from 2 other agents (this could change depending on house sale value) and £999 all in from Purple Bricks. That's a difference of £4500 just for selling fees. Purple Bricks were definitely the best option and I love that everything is online - Potential buyers can book viewings, put in noted interests and offers. Sellers can amend the schedule, photos etc. Very flexible service.
The key for Purplebricks (LON:PURP) would seem to be that they are only going to be effective where the property is low or tightly priced (a lot of similar houses on an estate where other sales are recent).
Where the traditional agents win is in realising a better price that more than eliminates the fee difference. My experience has been that the good ones can do this for fees, that on any international scale, are relatively low.
“our resident sector expert BnB”
Paul, you are too kind. Or perhaps I have just been fortunate with my estimates. In any case, thanks for the coverage of Sthree (LON:STEM) in response to my request.
The point I would add is for investors to stop looking at this name as cyclical. Like Staffline, demand for its specialisms may wax and wane, but, unlike Staffline (or Gattaca, or Empresaria, or even Page and Hays), the level of demand for STEM skills remains above the level of supply in all but the most extreme circumstances. In other words there is a structural shortage of skills which keeps the phone ringing at SThree when the tumbleweed is blowing through the offices of its listed equivalents. To be clear, we are nowhere near this point today despite the downward trajectory of the sector shares of late.
That’s not to say that the market understands the extent to which SThree is a gilded outlier and any perusal of the chart and revenues over a long period will show a steadily increasing top line but a cyclically performing share price. There is a possibility, however, that the market eventually gets its head around the fundamentally different revenue profile of SThree, based as it is predominantly (75%) on contract revenues. The extra certainty and visibility that this provides of future revenues ought to be valued at a premium in the same way as SaaS revenues carry a premium valuation, all the more so since the average contract placement is worth three times as much as the average permie! I certainly can’t be sure that the market will ever wise up, but it at least provides a bedrock of confidence when the share price dips in concert with its more vulnerable sector bedfellows.
Thx Jack for the review of Sylvania Platinum (LON:SLP) which I hold.
Falling Paul’s recommendation of Dr. John Campbell’s YouTube channel, I now watch this almost daily as reasoned and a non hysterical take on where we are with Covid.
From his presentation yesterday :
“We are at the end stage of this pandemic”
I post here for people to make of it what they will.
The source documents that he has used to come to his conclusions are linked to in the descriptions on the video. I have not read them.
Regards
Michael
The problem with Purplebricks (LON:PURP) is that there is nothing being shown that shows their new operating model can return them back to prior market share levels (5%+?) or higher, and also deliver profits. They have conveniently omitted any stats regarding recent trading, as one might expect, if recent performance since the restructuring has been bearing fruit. Last 8 weeks trading performance of the HY. First few weeks of trading in H2.
So with this silence, one has to assume that their new operating model isn't performing yet? They are expecting still cash outflows for H2. Given that H1 was about £14m I believe, then we really should take another £5-10m at least for H2, and its also uncertain if the new FY will be cashflow negative too, given they only expect to get back to profit in 2023 (calendar or financial year, uncertain).
So yes, lots of cash on the balance sheet. But also will be lower in the next 6-12 months.
On top of that, mortgage rates have already started rising quickly, and this macro headwind will slow down the property market too. So they don't have macro tailwinds to benefit them either.
Completely and it was easily copied, which is what Yopa did and undercut them.
It is a big market but easy to replicate so valuations should reflect the lack of a moat.
Brief article here on Purplebricks (LON:PURP) and their possible breaches of the tenancy deposit scheme. I've not held for 3-4 years but the move to make agents 'employees' must surely increase operational gearing. Still, seems there's no shortage of new agents signing up. Strikes me that they had a tremendous 1st mover advantage initially but they've hit so many bumps in the road.... https://www.cityam.com/purpleb...
Here's today's agenda. As you can see, there were way too many things for us to cover, sorry about that.
Good afternoon. May I ask, what is the source for what you are going to cover on the agenda for the said day?
thanks
Lee,
Almost always the SCVR ( Jack,Paul and sometimes Roland) write about some of the small cap companies that have issued RNS's on that morning, as you can see by the above agenda for today it is normally the ones that are reporting figures that are not in-line, if that makes sense.
Hope this helps.
Richard
Hi Lee,
Good afternoon. May I ask, what is the source for what you are going to cover on the agenda for the said day?
Jack & I make a list of the trading updates & results statements of companies in our remit (typically up to £700m mkt cap, excluding some specialist sectors like oil & gas, biotech, blue sky).
So we just read the RNS, and compile a manual list. We try to focus first on shares reporting earnings beats or misses against expectations.
Source info comes from the RNS own website, or investegate, I also use the list on Research Tree because it puts the mkt cap & sector next to each results statement or trading update. Then we also refer to MrContrarian's brilliant morning snapshots, to see if we've missed anything important.
Paul.
Re Cakebox (CBOX) I was really interested in Pauls comments on audit reports and believe there is a far larger issue here.
It seems to me as an ex FD (and Big Four auditor for 4 years in the 80s -urgh !) that the whole auditing/accounting world is not fit for purpose. The world the ICAEW in particular inhabits is an out of date anachronism :
I have therefore concluded to pretty well ignore audit reports/auditors/accounting firms as being irrelevant. And start from a position of healthy scepticism when looking at any business in detail, with in-depth research necessary to prove that trust and confidence in it is deserved.
Sylvania Platinum (LON:SLP) : do you guys have any thoughts on the Sylvania Platinum trading update? The market seems unimpressed.
sorry - I jumped the gun! Loving your work!
A fantastic report on Cake Box Holdings (LON:CBOX) Paul. Thank you. When I saw Maynard Paton's article I sent a link to a mutual acquaintance who featured it in his podcast that day (kindly namechecking me). I saw the management present at an investor seminar some years ago and they quuckly went on my bargepole list I'm afraid. After a while one does get a 'nose' for these things I think.
Hi Steve,
It's funny I saw Cake Box Holdings (LON:CBOX) management as being excellent, on webinars online. They seem really good entrepreneurs, and I still like CBOX as a company.
But I don't trust management following the auditor resignation & their negative comments. So it's annoying - what seems a really good company, but now uninvestable for me due to these revelations.
Out of interest, what did you see as negative about CBOX management in the investor presentation you saw from them?
Regards, Paul.
Amala Foods (LON:DISH) - a blast from the past if anyone cares - (I still hold a few) in todays RNS - said they have been approached for their stock market listing...which given the mkt cap vs the cost and time to list I think would be a great outcome.
"These approaches have indicated that should a deal be completed it would result in a 'see through' valuation for shareholders that is materially in excess of the Company's current market capitalization."
yes - its a tiddler now at just over £1m market cap. I bought some at 0.4p a while back for precisely the reason that appears to have come to pass, ie a reverse takeover. I am speculating that management will only do a deal at something north of 1p so could be a nice return but at this sort of microcap level will be completely illiquid so probably not one for most people, and for that reason I'm not in there for any real size.
Still amazes how you guys manage to get so much commentary out all before 11am. Bravo!
Still amazes how you guys manage to get so much commentary out all before 11am. Bravo!
Thanks! I did the first 2 sections last night ;-)
Thanks for another epic start to the day's SCVR Paul - the quality and depth of your output so far this year is just incredible. I wonder if dry January might be coincident?
Since you may already be planning to celebrate tomorrow (or at midnight tonight), I hope you don't mind if I share my experience of dry January from several years ago. I had read an article explaining that the full benefits of abstinence are really only felt after 3 months and so I decided to extend to a Dry 100 days.
During this period, I happened across an excellent book called "The Unexpected Joy of Being Sober" by Catherine Gray which was fascinating and entertaining as well as proving to be motivational (it's a fun read and not in any way preachy or intentionally motivational I might add).
Approaching the end of my 100 days, it occurred to me that in common with most Brits, I had not ever gone an entire year of my adult life without some alcohol and so I really had very little perspective on what life was supposed to be like unfiltered by this pernicious substance.
I resolved to go beyond the 100 and do an entire dry year and to be honest, after the first 100 days, it became harder to stomach the idea of drinking than it did to continue with sobriety. I gained so many valuable new perspectives on my own and society's strange relationship with this drug.
In the end my dry January lasted for almost 2 years and when I did start drinking again (a beautiful bottle of Italian Brunello to celebrate a significant anniversary) my perspective and relationship with alcohol had changed forever. I now enjoy the odd beer and a good wine with a meal but the allure of "getting on one" has gone for good and I haven't drunk to the point of being drunk in the 7 years since my initial dry January.
I hope this anecdote provides some inspiration for Paul or anybody else out there who is thinking of ending their dry January tonight with a bender. It would be like doing a month of piano lessons, and then smashing the piano up on the 1st February!
To bring it back to the subject of investing, it's no surprise that Diageo (LON:DGE) are one of the best investments the FTSE has to offer!
Re Cake Box Holdings (LON:CBOX)
I have some experience of franchising from both sides and I have noted here before that Cake Box do not appear to be members of the British Franchise Association
That immediately ruled out any further involvement for me. It is the first thing I would look for before engaging with a franchise business in any way.
Membership of the association indicates at least a decent level of knowledge of and compliance with the proper conduct of a franchise business.
Edit: Today's other franchise business Belvoir (LON:BLV) are listed as members.
I thought given the prevailing supply and cost inflation issues, the update today from Tandem (LON:TND) was impressive. I assume the focus will be on the outlook, where it is stated that 2022 has begun "more slowly", but the order book is also said to be "materially ahead of the comparative position in the prior year". With the warehouse expansion finally going ahead, bicycle supply gradually improving and other positive tailwinds, you would think in the not too distant future - general market sentiment permitting - this should move closer to a PER between 9-11 (i.e. 50% from here).
Historical issues were raised about prior management, but I've been impressed in the last few years by the changes, especially the shareholder engagement. It is genuinely one of the very few companies where my queries over email - several over the last two years - have been answered each and every time. Talking my own book, of course, as I hold.
Tandem Group (TND) out with some ok results (I hold) .
Just looks just too cheap on a long term basis .
I had 30 years in the bike industry founding Planet X bikes before doing an EOT 2 years ago .
Tandem are for sure a bit slow and steady, we even acquired the brand Holdsworth from them which was a pretty poor deal for tandem we thought but they seem to have improved greatly since then .
My chairman had even discussed trying to buy them when they were valued at a measly 6 million but the pension deficit put him off .
Never going to set the world alight but its just far too cheap, balance sheet is strong, has cash , makes 4-5 million a year, building a new warehouse will improve running costs , they own some good brands and have good license deals, plus importantly well diversified into several areas ..
Cycling industry is getting tough this year so that will knock them a touch, but ultimately it is a "rising tide" sector .
I have topped up at 507p this morning having just missed 502p , its highly unlikely to be at those levels in 3 years .
I love my PlanetX bike, thank you Sir/Madam.
Good to hear ! Great bikes at great prices and now employee owned .
Good morning Paul and Jack. If you can, please, could you have a look at MJH?
Belvoir - based on the above review, I expected Belvoir to come out at a fair price based on my own assessment, and that pretty much turned out to be the case.
Net tangible equity has grown at an average annual rate over the past 4 years which equates to c1.7% of the MCap. Some intangibles growth from acquisitions. I am not opposed to this, when a business is acquired for more than the sum of its net tangibles, which, for this sector, will always be the case, the the excess paid over the net tangible will be shown on the balance sheet as intangibles, which is the correct accounting treatment.
But of course every business must ultimately generate tangible wealth for its shareholders, this being the sum of the dividend and the growth in net tangible equity. Net tangible equity growth is by far the most imprtant growth figure for any business, and yet it gets so little attention.
So putting the tangible equity growth and the dividend together gives a tangible surplus of just over 5% of the current MCap, before share issuing is assessed.
Shares haver been issued, at an average rate of over 2% pa over the past 4 years. But, there has been no share issuing since 2017. In 2017 the jump in intangibles indicates a larger acqusition around that time. The subsequent growth in intangibles suggests the acqusition was sound and, the not having issued shares in 2020 due to Covid, when they had an excuse to do so, suggests that the business does not intend to issue any more shares other than for a very clear cut acqisition perhaps.
Overall - not going to lose your shirt here. But is Belvoir a buy at this price? Not really, the price is just too high, if the price was 50% lower I would be interested. Doug you may ask, how do you ever find anything to buy? Well, looking for the best quality bargains takes a lot of work, but ultimately if you can buy stocks whose share price would have to increase by 50% to 100% to reach a fair price, you are than giving yourself an enormous long term edge over the market.
Hello, Doug, thanks for that and always interested to hear your views. Just post your short list of buys at the moment IYHO, even if it is likely to be very short. I for one am all ears.
In order of size: Fort, ScS, LGEN, Boot, CAML, Plus500 and Bellway. Note, Bellway is a very strong business selling cheaply. I took the decision to sell most of my Bellway holdings the week before last while the negative noise on house builders continues. I will build back in to BWY, RDW and Berkeley Group in time, but I just think that the cladding issue might hold them back a little, for no reason other than the negative noise, the cladding issue does not threaten these businesses at all.
Other investors that I know with a similar approach to me and similar long term returns, do not agree with me here, they feel that to sell Bellway when it is so cheap is daft. They may be proven right, but the outlook for Fort and ScS, where I moved the money into, is just so strong at the moment and they do not face the same negative noise over the next few months. At the end of the day, all of the above are all very strong businesses selling far too cheaply.
Hi Jack - Looks like Venture Life (LON:VLG) making a come back with todays results... after all the flak over a year ago when the Chair sold before the storm - worth a look and some comment maybe ?
(I sold out)
Thanks
I Held Cake Box Holdings (LON:CBOX) for a while and turned a small profit. But there were too many reports of management being either defensive or arrogant in presentations, and the reviews of the product were generally poor. (And have got worse). Didn't feel like a management team that I wanted in charge of my money and I sold. I watched the price continue upwards for quite a while afterwards.
Re Cake Box Holdings (LON:CBOX), there is a simple rule of thumb to be applied here. If you don't trust the directors and their accounts, then avoid the company. Clearly the former auditors did not so that's good enough for me.
Morning Roger,
Re Cake Box Holdings (LON:CBOX), there is a simple rule of thumb to be applied here. If you don't trust the directors and their accounts, then avoid the company. Clearly the former auditors did not so that's good enough for me.
Absolutely, same conclusion I've come to.
Regards, Paul.
Van Elle (LON: VANL) interims
Decent update from an unloved and lowly rated UK market leader
New management team who seem good to me
Trading ahead of expectations and reinstating dividend
The higher margin work is the electrification of the railways which has been lacking but now seems to be returning.
Outlook
· The positive trading momentum from the first six months has carried into H2 of FY2022
· The improved levels of demand across the core markets are expected to remain strong for the remainder of the financial year and into FY2023
· Investment in infrastructure, including the decarbonisation/electrification of the rail network, where the Group has established a market-leading position, is expected to continue in the longer term
· The Board now anticipates trading for the full year to be ahead of market expectations
· The Board confirms its intention to reinstate dividend payments, commencing with a final, full year dividend for FY2022
I hold
Investegate |Van Elle HoldingsPLC Announcements | Van Elle HoldingsPLC: Interim Results & Investor Presentation
Thanks Paul for drawing attention to Cake Box Holdings (LON:CBOX) reporting and providing useful links. The two references mentioned "Patisserie Valerie" and "Quindell" reminded me about the book by Tim Steer "The signs were there" (https://www.amazon.co.uk/Signs...) which I think should be read and re-read by anyone who is interested in analysing the companies financial shenanigans at least as a primer...
A second hand copy of Tim Steer's book was the best value investment advice I got; after my Stockopedia subscription. Obviously. I am away from home today, so can't check but I think Quindell's had the ignominy of a whole chapter devoted to them... It would have been written pre Pat Valerie and the case studies used were all LSE or AIM listings and all recent to the publication date- so as to demonstrate issues with contemporary accounting standards- hence he didn't dissect Enron or Polly Peck for example, but plenty of others have put them under the microscope.
Copies on Ebay are much cheaper than Terry Smiths "Accounting for growth", which I haven't read but I suspect it is more relevant to the modern investor as "Accounting for growth" is now 30 years old or more.
Morses Club (LON:MCL) appear to be in freefall at the moment. From a profit situation some months ago to sitting on a 40% loss.
Any thought on this please?
Morses Club (LON:MCL) seemed unduly low, so I bought in about 10 days ago, having held previously at a higher share price. I discovered, however, that their marketing and communications director offloaded all their shares at the end of last week for just short of £100000. That is hardly confidence-inspiring, so I have sold out again...
Re £MCL and its recent “freefall” to a point where it offers a 12% yield next year! Clearly something is up. The current position is unsustainable. However, I share your lack of understanding as to why the fall. (FWIW – Stockrank is now 77– (Q90, V90, M22).
After recovering to a +/-80p range last summer, it fell to +/- 60p in Q4. Maybe that was a fair fear that the emerging, energy led cost of living crisis would lead to higher impairments or that the Omnicron COVID spike would mess things up again.
However, the further fall to 45p in the last 2-3 weeks is against no news. Have fundamentals got worse? On its home lending side, they now have the pick of the market with Provident (and many others) having withdrawn and shrunk their book to the highest quality customers. There is no new regulatory pressure.
I can only presume that the newer digital lending side, whose move into profit had already been delayed 6M, is facing further issues and news is leaking out. But I have seen no evidence for this.
Demand for unsecured credit remains high and there are loads of jobs for the young and poorly paid who take the predominantly 9 month loans they offer (not great for them but nothing to cause a spike in defaults nor any sign of claims exploding).
The failure to re-organize the business structure as planned might be the canary on this; perhaps they chose to keep the businesses at more arms length from each other if one looked in trouble. The RNS explaining this was not credible.
An extra 1Mn share were traded last week, including the complete sell out of nearly £96K’s worth of shares from the Mkting & Comms Director but there has been no RNS from a big player.
I am hoping – always an uncomfortable place to be – that it is retail investors selling, spooked by April's bad news coming into focus (NI tax rise, energy bills, etc) and the 2nd tier mgr’s sell
I’ve liked Mgt’s steady approach since IPO to widening their non-standard credit offer from Home Collect to a much wider suite of products and would add to my holdings if they were not already so large. Their strategy seems very sound and the regulatory risks are addressed
As it is, after a review, I intend to hold on to what I have.
Hello Johnmhughes. Regarding your request for comments on Morses Club (LON:MCL), I can think of quite a few anecdotal influences, including concerns about the worsening plight of low income households going forward in 2022, especially in the short term. Attitudes of investors can range from 'I d ont want to be associated with this kind of business' to the concerns about much higher levels of bad debts going forward. Looking at the 'facts', as per the Stocko page I am looking at, for some reason earnings and profits for the year just about to end and the next year look very poor versus most earlier years (though much better than last year, a horrible one) and free cash flow looks poor too. There as been no dilution fortunately. Other than that, I look forward to hearing comments from others.
The new Chair seems to be a very well qualified and appropriate appointment and will certainly add some 'quality' to what is a pretty sordid business, depending on how you look at it.
Of course, the other way to view it is to say better to have a Morses Club (LON:MCL) than to have unregulated loan sharks demanding even higher interest rates.
Thank you for your insight and also to Zipmanpeter, for taking the time to comment. It is much appreciated.
Good morning Paul,
On Friday you mentioned in the comments section about doing a shares social in Revs Bournemouth later this year.
I just looked back at your comment and noticed that you already have 13 private investors interested in attending ! I very much hope you are able to organise this event.
Best regards Neville
£CBOX
However, the cumulative effect of lots of errors & inconsistencies, is that reading his report, I’m beginning to lose confidence in the company & its management. It’s looking as if financial controls are not up to scratch, at best. At worst, there could be something a lot more worrying going on.
Exactly, and as you say, why take the risk? I sold out the second I read that - shame because it looks to be a great underlying business.
(NB Don't forget last year's data breach on the website).
Would welcome your views on Studio Retail (LON:STU) this morning. It was a small holding for me but companies warning about working capital is a bit of a red line for me so I plan to ditch the shares - if I can find a buyer!
I thought it was a very mixed trading update, some positives but equally some negatives. I do think its a double whammy drop and a bit over the top given that much of the bad news was already priced in.
I am not sure potentially running out of money was already priced in.
Will there be coverage for Sylvania Platinum (LON:SLP) ?
RNS looks really positive if comparing to Q1 2021, However, when looking at Q2 2020 it is still below. Positives are more favourable USD/ZAR rates and dividend payment. Cash sheet remains at $110M after dividend etc. Positives moving forward are PGM basket prices appear to be increasing over the last month; Rhodium currently at $16,850oz up 19.08% on the month. Palladium is at $2,372oz up 29.97% on the month and platinum is trading around $1009 an oz, up 5.71% on the month.
A concern regarding the temporary suspension of Lesedi operation…
I remain a long-term holder here as value, quality and liquidity metrics are very strong. However, I notice Liberum have dropped buy recommendation from 170p to 150p. With that being said, the SP has been trading very close to its book value per share of around 89.5p recently; a slight increase of around 11% throughout January, likely on expectations of Q2 results.
Hopefully operations can continue to run smoothly, alongside a rally in PGMS price increasing the overall basket price of Q3/Q4 - Good news that direct-associated covid-19 cases have remained low, despite omirocn emergence in South Africa alongside no deaths from operations; there is always a silver lining and life trumps everything.
All the best,
GI
I'd second a look at Sylvania Platinum (LON:SLP) if Jack is around today.
All the metrics are good, mega cash in the bank but no real view on what they are going to do with it may be holding the price back.
A really valid point, GloucesterBob, one I had not actually considered; I.e why hold on to huge proportions of cash (around 30% of MCAP) if not planning to reinvest it to reduce operating costs or actively looking for acquisitions; after all, it is shareholders money so buybacks or increased special dividend should be an option. Does seem rather pessimistic or slightly stuck in terms of expansion/growth…
What are your views on what a reasonable proportion of cash would be?
The RNS addressed this "The Group maintains strong cash reserves to allow funding of capital expansion and process optimisation projects, upgrading the Group's exploration and evaluation assets and returning value to all stakeholders."
Yes please to Sylvania Platinum (LON:SLP) review
Lookers (LON:LOOK) have come out with a very interesting statement this morning. It is not often that a large holding of shares by a former shareholder has been transacted at a significant premium to the current SP. 102p - the price received for most of the shares - in a company with an SP of 89p at the end of last week must be interesting.
I am reminded of several things Paul has said about the unusual motor trade situation in recent months.
The first is that the exceptional profits have transformed the balance sheets of the various beneficiary companies.
The second is that the structure of the motor trade is likely to see a transformation. That was before the Marshalls sale, and now we have another not dissimilar situation. Constellation is mentioned as the purchaser of the near 20% shareholding. Looking behind the share purchase in more detail, TDR Capital come up - a major hedge fund with fingers in lots of pies (including Constellation) - and Cinch - one of the significant players in the direct to home consumer car market.
The plot thickens. Although only 20% of the shares are involved, the SP should move further in the right direction?
I suggest anyone following car dealer shares reads the damning report on online American used car dealers issued on the 29th by wolfstreet.com . The dynamics are the same here for Cazoo. The franchised dealers are in a stronger position hence the Marshsalls takeover and the stake building in Lookers.
Agree Ridavies, all very interesting. Constellation building a holding in Lookers Constellation own webuyanycar and Cinch.
Any holders of Tissue Regenix (LON:TRX) (I hold) might be interested in the recently announced purchase of Triad Life Sciences Inc by Convatec (LON:CTEC) for an initial consideration of $125m and up to £275m. Triad produce pig-placenta-derived wound dressings https://www.triadls.com/innova... .
TRX currently valued at £34m recently announced results https://www.investegate.co.uk/...
and is on the verge of profitability with a wider range of products on the back of expanded production facilities in Texas.
A Proactive interview is available here:
The market is valued at $1.8bn pa and set to grow at a high single digit rate.
TRX products are already sold "white labeled" through partners and so a buyout seems a distinct possibility.
An ex Woodford holding that might at last be coming good with Covid having held back recent progress.
Thhank you Paul for your reports on Staffline (LON:STAF) and Cake Box Holdings (LON:CBOX) respectively. I have been involved in both, and certainly am not a happy person with the Cake Box Holdings (LON:CBOX) situation. I would also refer readers to the relatively recent Mello presentation (pre the major sale by CEO of shares at 350p, a 50p discount to the SP at the time) where the management were bullish, though they did say that a significant ingredient price increase would be passed on to the franchisees in the New Year, 2022. That will be an inflationary hit for the franchisees, and presumably for sales.
Thanks Mr Contrarian for delivering this on a very busy morning! please note that Studio retail group's ticker is Studio Retail (LON:STU)
Many thanks from me as well. I really don't know how you do it!
Blood, toil, tears and swearwords.
Paul, I wholeheartedly agree that Sthree (LON:STEM) and Robert Walters (LON:RWA) make better long term investments than Staffline. As it happens, the former has a TU out this morning which matches my expectations expressed during the recent Gattaca discussions. Sthree (LON:STEM) has a strong growth runway and looks good value even after this morning’s decent spike. Perhaps one to look at, thanks?
Deleted
Decent update from Xpediator (LON:XPD) on the face of it. However, net margin is wafer thin as is typical in logistics, which suggests they don’t have any special pricing power. Additionally, despite the growth the book value per share is still very similar to what it was in 2018. Perhaps these latest figures will change that. They had a good story but it’s still not clear to me that it is translating into a more valuable company.
No position.
A staggering report on Cakebox Paul, luckily my wife bakes all our cakes and her financial controls are great.
Director selling shares is a signal that I can understand. A Moonpig director (Niall Wass) and chairman of the board (Kate Swann) have bought about £300K of shares in the last six months but the share price is still bumping along the bottom. Any comment on why they would have bought and generally what insider share buying signals - is it always a positive sign?