Small Cap Value Report (Mon 4 April 2022) - BLV, MGP, FUL, TED, THRU

Good morning, it's Paul & Jack here with the SCVR for Monday.
Agenda -
Paul's Section:
Ted Baker (LON:TED) - takeover approaches. Sycamore has raised its cash offer (was previously 137.5p) but we're not told how much. Other third parties have expressed interest too. So a formal sales process has been launched. I'm sceptical whether any bids are likely to be high enough to persuade the big 4 shareholders (including the founder Ray Kelvin) to sell up, but everything has a price, so who knows?!
Thruvision (LON:THRU) - a serial disappointer in the past, with never-ending losses each year. However, today's trading update shows signs of decent growth, and a positive outlook. Breakeven beckons possibly for 2023? Might be worth doing some digging on this one, the products look interesting, and have attracted big name clients. Valuation looks warm though.
Jack's section:
Belvoir (LON:BLV) - a 25th year of profit growth, stretching back through cycles. Belvoir has organic growth opportunities and smaller acquisition candidates. Meanwhile, the shares trade on 13.6x forecast rolling earnings with an FY21 yield of 3.24%, which hardly seems demanding given the track record and prospects.
Medica (LON:MGP) - elective scanning is now back to pre-pandemic levels, while Nighthawk continues to trade strongly. Recent acquisitions see it enter Ireland and the US. I’m curious to see how the group fares in these markets, which are quite different to UK Healthcare. There is some potential here and the current year will benefit from softer comps, but more research is needed.
Fulham Shore (LON:FUL) - EBITDA to be well ahead of last year and ahead of market expectations. There are cost pressures, but the group’s businesses are relatively low cost and it has a greater ability to increase its own prices compared to competitors. Meanwhile, cheaper new sites fundamentally improve the economics and I think management has a good chance to continue successfully growing the company.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Ted Baker (LON:TED)
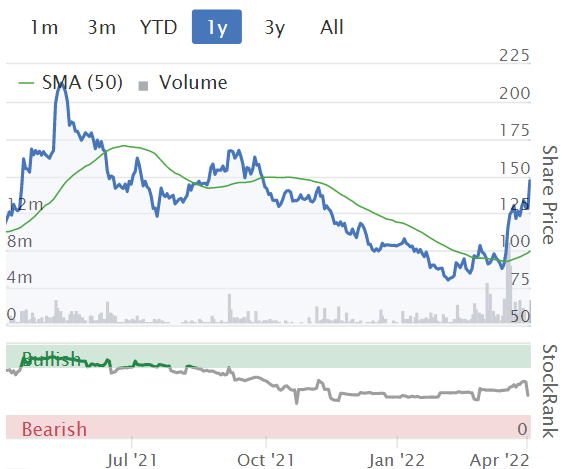
146p (up 14% at 14:16)
Market cap £270m
The story so far
18 March -
Sycamore Partners Mgt issued an RNS confirming press speculation that it was “in the early stages of considering making a possible cash offer for Ted Baker”
TED responded on the same day, denying that it had received any approach, and urging shareholders to take no action.
28 March -
TED rejects a bid approach from Sycamore at 137.5p cash.
4 April (today) -
TED says Sycamore has improved its offer, but doesn’t say by how much.
Other third party bid interest has been received.
A brief trading update is provided -
The Board believes the business is well positioned to create significant value for shareholders. Ted Baker is a leading global lifestyle brand and the Company continues to make good progress with its transformation. Despite the impact of Omicron on the fourth quarter of the year to 29 January 2022, Ted Baker delivered group sales growth of 35 per cent. compared with last year, and trading margin improved strongly demonstrating the progress the Company is making in re-establishing its premium brand positioning. Ted Baker has a strong balance sheet, with a net cash position at year end, and ample liquidity headroom to continue to grow.
Formal sales process has been launched, in agreement with the Takeover Code - under note 2 of rule 2.6, a crystal clear (!) explanation is given here in the Takeover Code -
2. Formal sale process Where, prior to an offeror having announced a firm intention to make an offer, the board of the offeree company announces that it is seeking one or more potential offerors for the offeree company by means of a formal sale process, the Panel will normally grant a dispensation from the requirements of Rules 2.4(a) and (b) (but see Note 12 on Rule 8) and Rule 2.6(a), such that any potential offeror which agrees with the offeree company to participate in that process would not be required to be publicly identified under Rule 2.4(a) or (b) and would not be subject to the 28 day deadline referred to in Rule 2.6(a), for so long as it is participating in that process. The Panel should be consulted at the earliest opportunity in all cases where such a dispensation is sought.
What happens next? This is from TED’s announcement today -
The Company intends to conduct a targeted process, focused on those parties who understand and value the full potential of this unique brand. The first phase of the process is expected to be based on public information only and interested parties will be invited to submit non-binding indicative offers to Evercore and Blackdown Partners. It is currently expected that a select number of parties will be invited to participate in a second phase. Those parties will be required, at the appropriate time, to enter into a non-disclosure agreement and standstill arrangement with Ted Baker on terms satisfactory to the Board of Ted Baker and on the same terms, in all material respects, as other selected parties. Further announcements regarding timings for the formal sale process will be made when appropriate.
The Board of Ted Baker has not yet had any discussions with Sycamore as to whether it wishes to participate in the formal sale process. If Sycamore does not confirm an intention to participate in this process, it will continue to be subject to a deadline of 5.00pm on 15 April 2022 by which it must announce either a firm intention to make an offer for the Company in accordance with Rule 2.7 of the Code or to announce that it does not intend to make an offer.
The Board of Ted Baker reserves the right to alter or terminate the process at any time and in such cases will make an announcement as appropriate. The Board of Ted Baker also reserves the right to reject any approach or terminate discussions with any interested party at any time.
This announcement is being made without the consent of Sycamore. There can be no certainty that an offer will be made, nor as to the terms on which any offer will be made.
My opinion - I don’t really have a lot to add, as it would just be speculation.
As mentioned before, TED has a concentrated shareholder register, so the big 4 will decide what happens next (Toscafund, Schroders, Ray Kelvin, and Columbia Threadneedle). If an offer is attractively priced, then they may be prepared to sell up. Or, if they really believe the turnaround potential is as good as they make out in the RNSs, then I imagine they would reject takeover bids, and continue as a standalone company.
I imagine it would take a very high price to persuade the founder Ray Kelvin to sell up. Hence a successful bid seems unlikely to me, but anything could happen.
The bid interest is shining a light on value in the fashion brands sector. I've been buying Superdry (LON:SDRY) (I hold) recently, as I think it could be emerging as a credible turnaround. Similarly Joules (LON:JOUL) (I hold) looks staggeringly cheap, if it can recover from supply chain problems which caused 2 profit warnings, and if it can avoid dilution from a possible placing? So JOUL is not without risk. I think a lot of fashion retailers are oversold now, even allowing for a likely soft patch as inflation bites harder later this year. Bottom line, is that if they get the product designs & pricing right, then they'll do well, largely irrespective of the macro situation. Also a tougher macro situation weeds out the competition, leaving greater market share for the survivors.
.
.
Thruvision (LON:THRU)
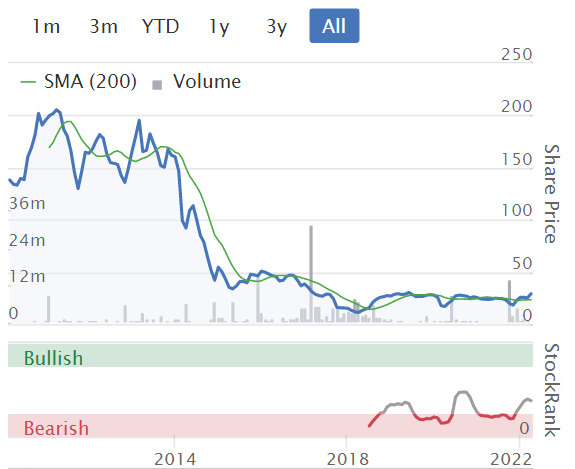
31p (up 14% at 13:52)
Market cap £45m
We’ve not looked at this company for several years, it used to be called Digital Barriers. The StockReport is literally a sea of red, with the only black numbers in the profitability section being revenues. It did a big equity raise in 2018, and has burned through most of that cash gradually over the last 4 years. So it’s not clear whether there is a viable business here or not, let’s have a fresh look.
Thruvision (AIM:THRU), the leading provider of "safe distance" people-screening technology to the international security market, is pleased to provide an update on trading for the financial year ended 31 March 2022.
Company’s overview -
As expected, the second half of our financial year showed a significant improvement over the first, driven by a considerable increase in our Profit Protection revenues and further orderflow for US Customs and Border Protection (CBP). Full year revenue is expected to be around £8.4 million (FY21: £6.7 million) and our cash balance has increased since the half year to £5.5 million on 31 March 2022 (30 September 2021: £4.1 million; 31 March 2021: £7.3 million).
Outlook - sounds upbeat -
Our markets have now substantially recovered from the negative effects of COVID, and we believe we are now firmly back on a growth trajectory. The pandemic has strengthened the need for contactless people security screening and this is most evident in Profit Protection where increasing traction in the US and Europe means we are very positive about the Group's prospects. With operational successes and front-line demand, we are also increasingly confident about significant growth with CBP. As a result of this positive momentum in our two main markets, we are confident of good growth in FY23 and beyond.
Valuation - there’s an update note from Progressive today. This shows a forecast adj loss before tax of £(1.7)m for FY 3/2022, improving to a smaller loss of £(0.5)m for FY 3/2023, on revenues of only £10.1m.
I’m struggling to see any justification for the £45m market cap, based on small revenues, continuing losses, and a poor historic track record.
My opinion - it might be worth looking into the company’s products, and its competitive situation. There are some big name clients mentioned in the commentary today, e.g. Tesco & Asos. It operates internationally too.
The main product seems to be a scanner, that looks through peoples’ clothing, to reveal any concealed items. This is useful at airports, and in warehouses - to detect and hence deter employee theft of small items that are easy to conceal under clothing. Short video is here.
Overall, I think the products look interesting, and big name clients are ordering more. I wonder what the business model is, i.e. are sales one-offs, or is there any recurring revenue?
This share could be worth further investigation possibly, but the valuation seems rather warm, considering it has been loss-making for many years.
.
.
Jack's section
Belvoir (LON:BLV)
Share price: 262.66p (+3%)
Shares in issue: 37,292,113
Market cap: £98m
Final results for the year to 31 December 2021
This is a UK property franchise and financial services group with a well-earned reputation for consistently good performance. Revenue and profit were both up in FY21, meaning 25 years of unbroken profit growth.
- Revenue +37% to a record £29.6m, some 25% of which is like-for-like with the remainder from acquired businesses,
- Management service fees (MSF - key underlying return from franchisees) +18% to £10.7m,
- Profit before tax +39% to £9.3m,
- Net debt down by 65% to £1.3m despite £4.4m spent on two acquisitions,
- Total dividend per share +18% to 8.5p.
Belvoir is more than just a lettings business (although that continues to dominate), with other segments making up an enlarged proportion of gross profit: 56% lettings, 19% sales, 20% financial services, and 5% other (2020: 60%, 17%, 19%, 4%).
This group is a serial outperformer and a bit of a hidden gem for those that have not heard of it. Performance over Covid and lockdowns has been far better than some might have initially feared, and the group has grown in all its three key markets in FY21.
UK residential property sales transactions rose by 41% year-on-year and were 22% ahead of the six-year average to 2019. The financial services division achieved revenue growth of 49% to £14.4m (2020: £9.7m), 44% of which arose from the underlying business. Revenue from property was up 49% to £3.7m and revenue from lettings increased 21% to £10.7m.
A number of operational metrics back up the financial growth. Two companies acquired (Nichals Humphreys, 20 offices with a focus on student lettings in March 2021, and the mortgage advisory arm of NBS in July 2021), the mortgage advisor network up 20% to 243 advisors, number of offices up 11% to 463, managed properties up 12% to 72,900, written mortgages up 37% to 16,585, and house sales up 54% to 12,320.
An additional acquisition was completed post period end: the personal agent network, Mr and Mrs Clarke Limited, for £0.2m net cash. This opens up a ‘new home-based agency option for franchisees’.
Outlook
The majority of our mortgage business is currently being introduced from non-Group sources, i.e. national contracts serviced in partnership with MAB and independent estate agency businesses, and leads generated by our online marketing activities or from our extensive client database. A key focus for 2022 is to drive further collaboration between our property and our financial services networks, so that we can maximise the earnings potential for our franchisees and advisers from offering financial services through all Group offices.
Further bolt-on acquisitions can be expected in order to expand both franchise and financial services. Belvoir has made acquisitions of this kind every year since 2015, with one already completed for FY22.
Meanwhile, the Nicholas Humphreys acquisition provides an entry into university towns, which should help drive organic growth.
The effective rate of corporation tax for the year was 20.6% (2020: 20.3%) - this could increase due to the 2021’s Budget commitment to increase corporation tax to 25% with effect from April 2023.
Balance sheet - negative net tangible asset value, but net assets of £33.6m after taking into account £34.8m of intangibles. It’s much harder to place a value on intangibles, but the resilience and recurring nature of the group’s lettings division goes some way to justifying this. It’s a capital light business model, so it is what it is. Debt is manageable and interest is well covered by earnings.
Conclusion
The property market is a curious beast. Average transaction prices are at pretty toppy multiples of earnings, but the market is so important, and the supply/demand imbalance so steep, that it’s actually in rude health. It got a lot of help from the government during lockdowns, and now we are seeing ‘the strongest residential sales market since 2007’.
This has the benefit of driving performance in Belvoir’s estate agency and financial services businesses. There is the specter of rising interest rates to consider though.
The market returned to more traditional transaction levels towards the end of 2021 and the challenge at the start of 2022 is a lack of stock in both the lettings and sales markets. This is anticipated to ease as we move into spring, which is traditionally the most active time of the year for homeowners starting to look to move.
Meanwhile, in financial services:
The financial services sector anticipates increased remortgage activity by both home-owners and buy-to-let (BTL) landlords whose mortgages, fixed amid robust property markets in 2017 and at the start of 2020, are coming to an end of their two and five-year deals. With further stimulus stemming from predicted interest rate rises in 2022, transfers and remortgages are forecast to increase. As a result, our financial services division will benefit from having a substantial client bank to service, and this will mitigate some of the fall in the house purchase mortgage activity.
And then there’s the higher quality, annuity-type revenue derived from Belvoir’s lettings division. This, unfortunately for those suffering from a cost of living squeeze, should be able to keep pace with inflation. This focus on a franchised lettings estate gives the business model real resilience and suggests the company should be able to weather downturns.
All in all, a well-managed, profitable company (with high levels of cash conversion) that is growing in a large market. There could be bumps in the road in future but the group’s track record on profit growth is encouraging and there’s a good long term opportunity to create meaningful shareholder value.
Medica (LON:MGP)
Share price: 160.07p
Shares in issue: 122,428,836
Market cap: £196m
Final results for the year to 31 December 2021
UK market leader by revenue in the provision of teleradiology services. It provides some FY19 comps, which removes Covid distortion.
- Revenue +33% to £61.9m,
- Gross profit +41% to £31.4m,
- Gross margin up from 47.8% to 50.7%,
- Underlying profit before tax +6.9% to £12.1m (margin down from 24.2% to 19.5%).
The rest is year-on-year: underlying EPS +126% to 7.83p, basic EPS +277% to 4.56p, final dividend +5% to 1.79p, net cash up from -£3.9m to positive £3.9m.
Underlying results are before exceptional items and one-off costs relating to the GDI acquisition, associated debt facility, share based payments, and amortisation of acquired intangibles. Here’s the note for non-underlying items:

That seems fine at first glance.
UK revenue grew by 33% to £47.1m, with Nighthawk strong and a full recovery in Elective scanning by year end. Medica Ireland contributed £9.7m in its first full year since acquisition in November 2020. This is in line with expectations. RadMD (Philadelphia) contributed £5.2m for the nine months since acquisition in March 2021, ‘broadly in line’.
Gross profit up due to mix effect, cost management, and positive impact of acquisitions.
That seems positive. Nighthawk continues to win contracts and renewals, while Elective is coming back and the group has expanded radiology reporting capacity in the UK by 5%. Medica has also restructured ‘to create additional management bandwidth’, with new group functions to support growth.
MedX was also established, a joint venture with Integral Diagnostics Pty in Australia.
Current trading
Launch of a new enterprise imaging and reporting software platform for Medica’s radiologists ‘as first major milestone of the future tech programme’. Nighthawk trading remains robust, a new service with a leading health insurer in Dublin has been launched, and a general manager has been appointed for MedX.
Conclusion
It seems like the peak risk has passed for Medica - as a teleradiologist service, business could have been hit catastrophically by Covid, depending on how hospitalisations played out.
Valuation is not the cheapest, but neither is it overly expensive. The trailing twelve month figures still bear some scars from lockdowns, and the flipside of that is that those comps should be a tailwind over the next year. We’ve already seen this in H2, with Elective activity a notable growth driver.

It all depends on the group’s growth prospects really. Clearly, Medica has international ambitions and Healthcare is a huge market, so if it can find a way to replicate its UK success in overseas markets then it could grow substantially. These markets vary greatly in their complexity and makeup though, from country to country and culture to culture. Not all have an NHS equivalent, so it’s probably not the same as somebody looking to expand branded cakes or some other consumer good for example.
Still, the group is targeting in excess of 15% annual revenue growth over the medium term in both its Ireland and US markets at an underlying net operating profit margin of 20%, so management must be confident of its ability to service multiple markets.
It’s an interesting prospect with some promising signs of a quality business, and it remains on my watchlist of stocks to look at in more detail. The shares dipped recently but have since recovered, so a bit of a missed opportunity there.

Fulham Shore (LON:FUL)
Share price: 16.5p (+6.45%)
Shares in issue: 634,820,577
Market cap: £104.7m
The Fulham Shore is one of the better casual dining operators out there, ably helmed by the experienced David Page and co, who have worked together on several other successful roll outs in the space before.
Following the removal of all restrictions in February 2022, customers have continued to return to the Group's restaurants in increasing numbers, reflecting the fantastic quality and value of the Franco Manca and The Real Greek propositions.
Despite periods of disruption, H2 has been strong and ten new restaurants have been opened in the year. Two franchised Franco Manca restaurants were also opened in Athens, Greece. That could be an important development: proving that the Franco Manca pizzeria chain has international potential would materially improve the valuation should management look to sell.
Input costs rose throughout the year due to increased transportation costs, raw materials and the impact of Covid-19 disruption.
However these were mitigated through small price increases and generated better results than the Board had previously anticipated at the half year.
The group’s restaurant businesses have been structured to be able to provide very affordable price points compared to more established competitors, so the ability to increase prices has been built in from the start.
This strong trading momentum and expansion drove a significant increase in revenue, comparable with the levels seen pre COVID-19. As a result, the Board expects to report that revenue, EBITDA and Adjusted Headline EBITDA for the financial year ended 27 March 2022 will be ahead of last year's figures and comfortably ahead of market expectations.
With those expectations helpfully flagged as revenue of £73.4m, EBITDA of £16.5m and Adjusted Headline EBITDA of £9.5m.
The pre-IFRS 16 net cash position as at 25 March 2022 had improved to £4.0m from net debt of £3.6m, with undrawn bank facilities of £15.9m. That’s despite opening 10 restaurants, and the company intends to continue funding new sites via internal cash generation.
Current trading and outlook
The 24th The Real Greek is soon to open up in Newcastle (with another five in legal negotiations) and there are five upcoming Franco Manca sites in places like Edinburgh, Manchester, Canterbury and Didsbury, so the group is proving the scalability of its concepts.
The group plans to open around 18 new restaurants across both brands in the financial year ending March 2023 and will review this opening programme at the half year.
The outlook for costs, be they utilities, raw ingredients or labour presents challenges for all operators within the sector. In addition, the reduced VAT rate and hospitality business rates relief both ended on 1 April 2022. Thanks to its brands' affordable, value-for-money proposition, the Group is well placed to offset these increased costs through increased menu pricing, which, when they occur, will be implemented to cover costs rather than increase margin.
Conclusion
Tricky market periods, once concluded, present enhanced opportunities for quality operators. I think that’s the situation The Fulham Shore is currently in. It’s not all sunny skies now, with higher costs an increasing issue, but hospitality has survived worse and good companies will find a way to manage those pressures.
An important point to consider here as well is that the market for new sites is far more favourable for operators than it has been for many years. That will provide a strong tailwind, and fundamentally changes the economics for those operators experienced enough to capitalise.
The group’s shares have held up well recently, but then I would argue that its prospects have improved materially over the past year or so and management will be confident of further growing the company. I think it’s proving to the market that it’s a cut above other operators in the space and, if I had to pick a sector winner over the medium to long term, this would be it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
£XPD - No coverage or comments to date - would it be possible for either Jack or Paul to cover please. Another small cap whose share price has been hammered despite positive trading statements, indeed figures seem to be okay and trading statement to date okay despite the current instability in the region. The share price decline from 80p high to 40p last year - slight recovery since but down 6p to date today. £AQS provided results above expectations last week and again prior to this share price has been hammered. Share price recovered/rose 25p on the day but since then has given up this and lost more ground, PE, fundamentals really good former forecast to decrease. I am having difficulty in fathoming some of the share movements in Small Caps appreciating that current market conditions inflation, instability are impacting but a lot of the decline took place before this.
Sorry meant for below
Hostmore (LON:MORE)
Just read this quote in the Telegraph.
“Lots of people haven’t had a holiday in the sun for the past couple of years, and so maybe that takes precedence over eating out as much as they have over the past year,” says Robert Cook, chief executive of TGI Fridays owner Hostmore
Does this imply that Hostmore are seeing reduced footfall? Or is it a classic reporting miss quote?
Maybe OTB be a good holiday investment. Very cheap and on a dip ATM.
brilliant announcement from Saietta (LON:SED) just now. So they've basically brought forward their own production capabilities by 2 years, taking on an electric drive manufacturing facility (along with staff) in Sunderland. I am very impressed so far with the management of Saietta (LON:SED) they seem to have a very commercial eye. They bought the EV unit off Evergrande for an absolute snip and brought forward the business plan 2 or 3 years. Now they've done this deal bringing their own manufacturing forward by 2 years at significantly less cost.
Whilst I was very excited by the opportunity the one thing that concerned me when I bought shares was whether the ex Cosworth engineers would be able to manage costs whilst maintaining the business plan as we have too often seen boards with good innovation woefully underestimate costs and time to commerciality. However, it seems these guys can, so that ticks another box for me.
Excellent news from Saietta (LON:SED) and great for the 39 workers who are being kept on. The plant previously made steering column motors. Now Saietta are transferring production in from China.
https://www.business-live.co.u...
Saietta (LON:SED) had always said they wanted a plant capable of 100,000 unit production in the UK and were in negotiations on potential sites etc with government schemes. The idea behind the 100k production is that they win a customer, configure and produce the early units for them as PoC whilst the customer then readies their own manufacturing capability for mass production. Customer then makes their own units with a royalty fee to Saietta (LON:SED) for each unit.
This news now means that they can also bring forward their manufacturing of the marine outboard motor division which is also brilliant news. They were sold out almost immediately when they soft launched their outboard motor and this market can easily be £100m in its own right for Saietta (LON:SED)
All looks very promising at the moment. Long term position for me as I anticipate it could be worth billions in the future if executed well. Clearly thats not going to happen overnight and is full of risk and uncertainty so I don't want it to sound rampy..... my point really is that I need to remain diligent to news flow and tick off my check boxes of successful strategy execution as time goes along (ie be careful not to ignore any warning signs). Anything that brings forward the timelines by 2 years has a meaningful impact on the DCF of earnings. I am looking forward to the trading update this month, so fingers crossed!!
Saietta (LON:SED)
https://www.voxmarkets.co.uk/a...
Worth a watch from last September '21. I do not hold as I spent funds else where but would of been happy buying when they were 150p. If I remember correctly, broker has a target of 275p.
Re Saietta (LON:SED) why are there no rankings on the Stockreport and no prints available at all?
Sorry Rustbucket, I have no idea. I'm just a regular punter!
Saietta (LON:SED)
It joined AIM on 7 July 2021 so presumably there's not enough data available for Stocko to work on.
£SED I don’t think that is the case, I’ve seen stocks that are only a few months old that have the information and July is now 9 months ago but maybe some information is missing. But prints should be available every few weeks. I will report it to the support team.
Saietta (LON:SED) update, the interim data which was back in December is missing, support will get this info. and update the Stockreport. I think Stocko should be checking when there are rankings on a stock, it would fairly easy to do.
Saietta (LON:SED) Stockopedia have now update the data and the rankings are all there now.
Good update from Belvoir (LON:BLV) I hold, curious why Property Franchise (LON:TPFG) is up 50% compared to Belvoir (LON:BLV) only 15% despite BLV having higher profits. I thought they were. Very similar companies.
House sales in my area certainly much slower than last year, houses are selling quickly and some prices have been reduced to try to sell them, last year they were selling like hot cakes, even before they were marketed. So surprised they say house sales are highest since 2007 but different parts of the country are seeing different things.
Hi
I notice Ig Design (LON:IGR) rising sharply. Up +14.66% today (as I type), +37.80% over past 5 days (using Goggle chart).
I don't hold.
Regards
Howard
Gosh how far Ig Design (LON:IGR) have fallen. The market cap seems to be about six weeks of their sales value so I can understand some bargain hunting. I may be tempted myself.
Medica (LON:MGP)
Hi Jack - I like these. Not going to necessarily multi bag but operate in a growth area of the healthcare market and have successfully expanded globally so good diversification of revenues.
Whilst I expect UK/Ireland and Australian businesses to benefit as they get back to, and exceed, pre covid levels (particularly given multi year backlogs) I think the one to watch is the newly purchased RadMD business in the US. This business has performed well since purchase and in the 9 months since it was bought has grown its order book 35% to $54m and has the best gross margins of all the businesses at around 55%. Given the size of the US market if this trend continues then it should be very valuable.
FCF yield exceeding 5% expected for this year. Pays 2% divi and growing net cash. My models suggest trad at a PE around 15 or 16 which given a 15% anticipated group annualised growth rate looks inexpensive. I'm targeting north of 225p
Fundamentals for Medica (LON:MGP) look good as you say and no share dilution (that I can see) during the pandemic to boot. A word of caution would be that the process of teleradiology is undergoing disruption by AI - startlingly accurate and MUCH faster than a human expert. Fine if Medica is already heavily invested in that tech, otherwise a risk to consider.
yep - per their report.......
"Medica is also focussed on continuing to improve our reporting systems as part of the FutureTech programme, rolling out further Augmented Intelligence ("AI") solutions"
As a radiologist I am always interested to read peoples take on Medica. Medica is not much more than a medical staffing agency IMO and deserves to be on the typical low PER of such a company. Medica has been around for over 15 years - was a private company in the early stages.
I can assure anyone that AI does not have any real role today in radiology. Its an interesting area for development but is more likely to be an assistant to the radiologist than replacement. There is no risk to Medica from AI in the next 5-10 yrs IMO.
Very helpful thanks. I see Medica as more akin to an offshore software house however, which comparison the operating margins also justify. On that basis a PER nudging 20x is not outrageous.
Thanks and nice to get your take. The reality though is that Medica (LON:MGP) isn't a staffing agency. It is nothing like. It is more like a business process outsourcing and these will trade in the 15-20 PE range.
A staffing agency is where a company will put staff into an organisation usually at a low margin. An outsource is different and has very different margins.
I agree AI has little risk to Medica (LON:MGP) over the next few years but they need to invest to be ahead of the game, so it is good to see that they have spotted this as a potential risk to the business in future and counter that through investment.
the RadMD business is the US is growing very fast, in excess of 35% pa and with gross margins of 55%. That isn't a business that will be on a low PER.
Thanks for your insight on £MGP maillotàpoisrouges
I've just gone through the results and as a holder I remain quite impressed.
Some plus points:
It's a shame that these figures have only just been published, so cannot be compared pre-2020, but at the very least, 41% does not seem too bad.
There's lots to like here for a lay person such as myself, so I'm surprised by the apparent caution in your comment.
If you have time to respond it would certainly be interesting to hear your take on the future of such companies. Is it simply the current valuation that would put you off investing here? Or is there something fundamentally wrong with the business model?
Thanks in advance
A
If you have time to respond it would certainly be interesting to hear your take on the future of such companies.
I second that thought. Valuation looks quite reasonable for the growth envisaged if one compares Medica (LON:MGP) to a skilled IT outsourcing enterprise or indeed to pure play CROs. Is the recent diversification a sign that the core tele-radiology product is fading? Or does the original application form a solid cash-generating hub to support multiple related spokes?
Ted Baker, Ted Baker (LON:TED), has put itself up for sale after receiving a third takeover move by US private equity firm Sycamore Partners.
Hi everyone, Why is my portfolio going up in value at the moment? This doesn't usually happen! Do you think it will be back to normal again when everyone has finished topping up their ISA's?
Would value Paul or Jack's views on Fulham Shore (LON:FUL) following the trading update today. Ahead of expectations and growing quickly, taking advantage of a lot of cheap deals from landlords. Seems to suggest the consumer is still excited to be eating out, and this company aims for the value end of the market so in theory it should be a more affordable option if belts are tightened. Views welcomed.....
Paul, many thanks for the update on Belvoir (LON:BLV) whose results look great. The one things that makes me really cautious is how the directors have done nothing but sell the shares over the last three years and the main director owns less than 2%. If the prospects were looking good, why haven’t they been buying? Any ideas please?
I've avoided Belvoir (LON:BLV) as I don't feel comfortable with the level of options the board have awarded themselves. This might be entirely within the "normal" range of award for this type of company and accumulated over many years, but it's over 5% of the shares in issue if the Stockopedia numbers are correct. To be fair, they don't sell every share bought in most cases (over the last two years). This for a share price that hasn't really gone anywhere for ten years and then shot up about a year ago? I'd welcome any comment from someone more knowledgable than I.
As a 50 something male who hates shopping with a passion I nevertheless have to comment on my observations at the weekend. Norwich city centre was absolutely heaving, I am talking the weeks up to xmas busy!
Next and M&S were packed, Wagamama even had a queue of 20-30 people waiting outside!
Okay, it was a nice sunny day but maybe write off the consumer at your peril!
Agreed,
Our local High Road and its shops have been very busy lately, cafes and pubs heaving and unless you book a couple of weeks in advance getting a decent restaurant table is impossible. So no short term shortage of disposable income it would appear. On the other hand my sister volunteers in a well known charity shop in an affluent southern town and they have never been as busy as the last month ! Not sure if that carries the same signal.
Richard
Hi Tiswas
I am a 50 something male who for 25 years has owned a retail business in Norwich City Centre selling a high quality furnishing product (handmade rugs, not sure i'm allowed to mention name?) and let me say that the last 2 months have been very poor, trade wise.
I think the cafe's restaurants etc have definitely been busy, not so with consumer high value and discretionary purchases though, from what I am seeing and hearing.
There has been a rotation of spending from goods to services from lockdown to "normalish" times. Some big winners of lockdown , things you could still do eg. fishing, golf, cycling are now experiencing not only a lack of demand, as people now can do other things, but supply chain problems as well because they simply sold all the stock there was. I am not sure where your business falls in this scenario, i suppose it depends on whether you sold on-line during lockdown or not.
I hope business picks up for you.
Richard
Thanks Richard
Anyone else in the Norwich area?
Would tiswas and grumpy5 like to get together over a coffee in Norwich and swap some investment ideas?
Happy to do so - it's an hour's drive for me, but I can make a day out of it.
Well I'm down on the east coast from Norwich, so count me in in any potential plans
Hi Norfolk. Yes, I would be interested. How do we take the discussion off board so as not to clutter things up? No private messaging facility as I understand it?
I was in Norwich city centre 2 weeks ago, midweek, and I thought the bars and cafes were desperately quiet! (eg I was the last customer in Harriet's at 3pm).
I was in Reading town centre last Tuesday and it was really quiet apart from the Apple store and Pret. I bought a burrito in Tortilla to take a look at it and there were three staff just for me. Perhaps people are getting out more to socialise at the weekends than make big purchases?
Glad to hear the pedestrianisation of Norwich city centre is going well ;-)
Apart from the curse of empty retail units, which do nothing for the ambience, it is actually a very pleasant city centre to walk around!
I too am a 50 something male who hates shopping. I have lived in Paddington for over seven years, and most weekdays pop into the station to pick up a Metro. I don't think I have ever seen it as busy as it has been over the past few weeks. Consumers really seem to be getting the appetite back for travel and shopping. I dislike both, but there could be some good share opportunities out there.
Consumers really seem to be getting the appetite back for travel and shopping. I dislike both, but there could be some good share opportunities out there.
The best estimate I've seen is that the effect of fuel rises, tax rises, inflation etc will leave the average household £1,000 worse off this year. Which doesn't sound too bad but it's of a scale only previously seen in recessions of the 1970's, early 1980's and during the problems in 2008/2009.
The average household has about £31,000 disposable income but the real issue is discretionary income - what's left after the basics have been paid for. Finding a number for that is ticky but it looks like it's about £21,000, although I'm excluding things some people won't regard as optional like insurance, pet bills and the various small vices like alcohol and cigarettes.
So we're looking at a 10% hit to discretionary spending before wage rises. And we probably have yet higher energy bills to come again later in the year along with higher interest rates.
It's significant, but it hasn't hit yet and it won't impact higher income families as much, which probably includes most people on here. The bond markets aren't quite signalling recession yet, but I don't think it would be a surprise if it happens later this year or next.
timarr
Any thoughts on bonds Tim most commentators are saying avoid but although the yields at the short end are rising they dropped at the long end last week. Anything other than bonds you would view as defensive for part of the portfolio obviously cash is an option but with inflation rpi at near 10% you don't want to much in cash either.
Thanks Andy
Any thoughts on bonds Tim most commentators are saying avoid but although the yields at the short end are rising they dropped at the long end last week
Hi Andy
I don't really know. If interest rates are rising then bond prices will fall. There's a theory that if recession strikes Central Banks will have to reverse interest rate increases - but with inflatiion running hot that seems an unlikely course of action to me, barring some other crisis.
I have some cash and some gold, a bunch of commodity and oil producing stocks and a selection of shares with little debt (including Belvoir (LON:BLV) and Medica (LON:MGP) who both updated positively today) which I hope can continue to grow through any downturn. If we get a crash that won't make any difference - everything will be crushed in the rush for the exit, so I want to make sure I'm invested in companies that can live to fight another day.
Cash does give optionality in the event of a downturn but, as you point out, it's also a guaranteed 10% fall in real terms at the moment.
timarr
£1,000 per household looks a bit light, energy bills have doubled, so £1,000 maybe just for energy before you add on petrol, food prices and everything else. Some of its hit already as many bills went up in October 21 and petrol has already gone up. Food prices are definitely going up.
Average gas/electric bill, September 2021 was £1,138.
It does really matter about the few people on here, many people are going be affected by these rises, especially those on low or fixed incomes.
Some food producers have already decided not to plant crops such as tomatoes and cucumbers because of gas prices, so we will have be importing even more food.
Shortages of fertiliser has pushed up prices by x3, so will also add to the costs or lead to a reduced yield.
Although higher income families are more conscious and cautious of the financial impact of inflation and i wonder if the old saying ' council house tenants spend £101 of every £100 they earn' is still relevant for lower income households ?
Richard
Re hit to discretionary incomes at +/- 10% "It's significant, but it hasn't hit yet and it won't impact higher income families as much"
I agree especially as the backdrop over the P2Yr is (choose you preferred demographic descriptors) higher income/white collar families/rich pensioners, have saved and built cash from forced reductions in consumption (holidays, eating out etc) plus seeing their property prices surge whilst the bottom half of society, the poor, the young and renters, have struggled. NI increases, fuel charges, etc will only exacerbate this 2 speed Britain.
Politically and socially, it's a disgrace but stickling to investing, I think in the consumer space that means companies like Saga l (the old are cash rich and desperate to travel) and Hostmore (premium priced bars) will do well, more mainstream offers will struggle unless geared for it ( Fulham Shore (LON:FUL) ). I hold these 3 but have got out of others even at a loss eg Revolution Bars (LON:RBG) where even though they recovered well to date and are a kind of 'last man standing', in some places, I think there core target market will be forced to draw their horns in.
I do chuckle at the idea of the comfortably off old people congregating at TGIF! We had enough of that place 25 years ago for children’s birthday parties.
The ladies I know who lunch during the week go for the cafes at the garden centres or farm shops - somewhere to park easily and do a bit of shopping before or after lunch. At the weekend it’s more likely to be a country gastro pub than the smell of TGIF food.
Interesting I live near Norwich also still love living in Norfolk but Norwich is looking tired compared to what it was ten plus years ago with a lot of empty shops it does seem busy when I go into the city but a lot of the people mulling around seem to be youngsters/students.
Thoughts on finals today from Surface Transforms (LON:SCE) please. Seems all on track; Finncap raised their TP to 80p, given the increase in order book, most of which, I think, was already annoucned in the last TU.
Belvoir (LON:BLV)
Another year of increasing real profits and dividends for this growing property management , sales and financial services franchise company. Cautiously optimistic for this to continue organically and by acquisition.
Belvoir (LON:BLV) has been a reliable long-term winner for me and FY21 was a cracking year.
One thing I struggle to understand is how the broker arrives at a significantly different EPS figure to the company. The company says this morning basic EPS including the dilutive effect of share options is 20.3p but the broker has 22.7p... Does anyone understand the difference?
Hi Patrick.
LON:BLV Are presenting on Investor Meets Company this afternoon at 4.30. I have always found them good at answering questions.
Mark