Small Cap Value Report (Mon 4 Sept 2023) - BLV, AMS, ERGO, CRU

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries
Belvoir (LON:BLV) - up 2% to 225p (£84m) - Interim Results (forecasts upgraded) - Graham - GREEN
I’m surprised these are only up by 2% as brokers upgrade EPS forecasts by 7-8%. As usual, lettings income has come to the rescue for Belvoir as the sales market stalls. I’d like faster revenue growth but in these tough conditions I think BLV has demonstrated resilience.
Advanced Medical Solutions (LON:AMS) - down 25% to 185p (£407m) - Trading Statement - Paul - AMBER
This high quality business loses a quarter of its market cap today, with a profit warning. I'm lacking information on it, but have a stab at quantifying the damage below. It looks pricey, but when you adjust out the £82m cash pile (20% of the market cap), things look more interesting. Could be worth a closer look possibly.
Ergomed (LON:ERGO) - up 27% to 1336p (£679m) - Recommended cash offer - Paul - GREEN
Ergomed receives a recommended (by management) 1350p cash offer from private equity firm Permira. I think this looks a fair deal on quite a punchy valuation. The 18% shareholder, founder, Chairman agrees, having accepted the deal. A nice outcome for shareholders, well done to any holders here!
Paul’s Section:
Advanced Medical Solutions (LON:AMS)
Down 25% to 185p (£407m) - Trading Statement - Paul - AMBER
Winsford, UK: Advanced Medical Solutions Group plc (AIM: AMS), the world-leading specialist in tissue-healing technologies, today announces a trading update following recent events that have impacted financial expectations for the year ending 31 December 2023.
Reduced royalty revenues now expected from Organogenesis in USA.
Not able to estimate impact, so have prudently removed all royalties from this customer from forecasts.
Financial impact is a £2m aPBT (adj profit before tax) impact to FY 12/2023 guidance, and £4m aPBT impact in FY 12/2024 and FY 12/2025.
Customer de-stocking will impact 2023 only, for Liquiband. Explanation provided seems muddled to me - I don’t understand why a growth product would see de-stocking?
Revised guidance - clear guidance here, but as with many companies, it doesn’t say what the previous guidance was, which wastes everyone’s time in having to look it up.
Unfortunately, there are no broker notes available on Research Tree, so I’m working with limited information here.
The combined effect of these factors is expected to impact the Group's FY23 financial performance with revenues now anticipated to be approximately £124 - £127 million and adjusted pre-tax profit of approximately £25 - £27 million. Reflecting the Board's confidence, with the exception of the adjustment to the Organogenesis royalty, guidance for future years remains unchanged.
CEO comments suggest this might just be a current year glitch, which if true, could mean we’re getting a buying opportunity maybe? -
Chris Meredith, Chief Executive Officer of AMS, commented: "While the uncertainty in the Organogenesis royalty stream and the higher de-stocking of US LiquiBand® is clearly disappointing, my confidence in AMS's long term growth prospects is stronger than ever. We remain convinced that our new US LiquiBand® partner strategy will drive accelerated growth from early 2024 and that this, in conjunction with other initiatives such as the imminent launch of LiquiBand® Fix8 in the US, will enable AMS to return to strong growth in 2024 and beyond."
Valuation - this is only rough, as I don’t have proper numbers.
An H1 trading update on 11 July indicated that H1 would be revenue of c.£63m, and aPBT c.£13.6m.
Today’s FY guidance says £124-127m revenues, and aPBT £25-27m.
Therefore H2 is implied at £61-64m revenues (very similar to H1’s £63m), and £11.4-13.4m aPBT for H2, a bit below H1.
That doesn’t sound a disaster to me.
Broker consensus is 10.7p adj EPS (from the StockReport here), so my rough figures suggest this might be revised down to c.8-9p EPS (we should see updated broker consensus numbers on the StockReport quite quickly).
AMS shares are currently down 25% to 185p today. That gives a PER of between about 20-23x, based on my guess of 8-9p EPS this year. Is that cheap? No, it’s not. The problem is, AMS is now looking ex-growth, in profit terms. It’s been producing around 9-10p EPS for the last 6 years, excluding a one-off bad year in the pandemic. So why would we value a company with static profits on a PER in the twenties? The risk is that today’s profit warning might be triggering a permanent de-rating of the shares from growth, to value. Which would mean it could have a good bit further to fall.
Or, a more bullish take would be that today is a glitch due to one-off factors, and profit growth might resume in 2024.
Balance sheet - I’ve checked the last one, as at 31 Dec 2022, and can say that it’s a glorious thing to behold. There’s obvious excess capital on the balance sheet, which gives management options re increasing shareholder returns, or making acquisitions. The £82m net cash looks surplus to requirements - given its strong profit margin, and cash generation, I think AMS could operate with a modest overdraft to dip into from time to time, hence it doesn’t need the cash pile at all really. Cash constitutes about 20% of the market cap now, which might catch the eye of a bidder, who could buy the company, using its own cash to part-fund the deal, and then load it up with debt.
Paul’s opinion - if we adjust out the cash, the PER falls to a more palatable level.
It’s undoubtedly a high quality business.
This sector is often attractive for generously priced takeover bids.
Overall then, despite a disappointment today (both factors had already been mentioned in the July update), I’d say this share is now looking potentially interesting, and could be worth a closer look. I’ll go with AMBER, as I can see both bull and bear points here.
Ergomed (LON:ERGO)
Up 27% to 1336p (£679m) - Recommended cash offer - Paul - GREEN
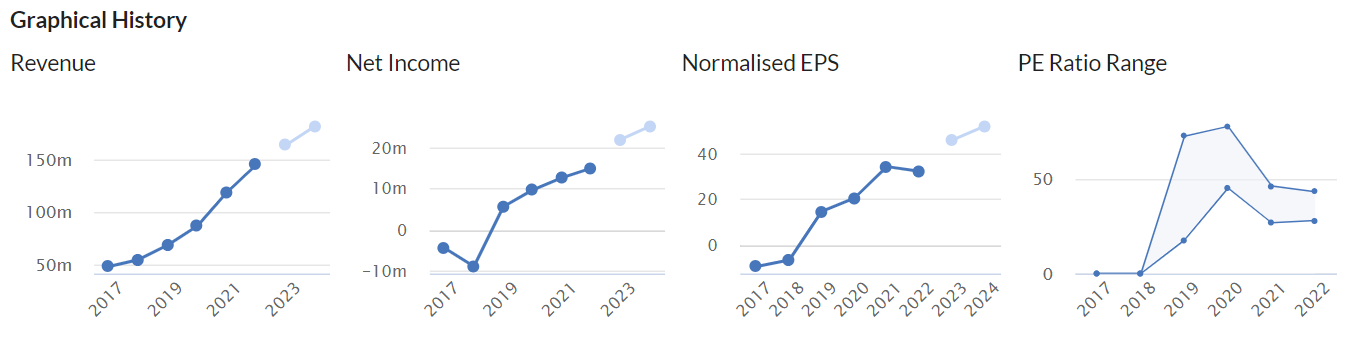
I’m not familiar with this company, as Jack always used to cover it here, and we’ve not looked at it in 2023. Although I have a generally favourable impression of the company, who wouldn’t with a track record like this?! -
Management has agreed it, so the deal should now go to a shareholder vote.
The offer is 1350p in cash, a 28% premium to Friday’s closing price, from Permira, a well-known private equity firm.
Valuation looks quite punchy to me, so I’d say this is a favourable deal for shareholders, eg. -
...implied Ergomed enterprise value multiple of approximately 21.0x its forecast Adjusted EBITDA of £32.4 million (on an IFRS 16 basis) for the year ending 31 December 2023, which the directors of Ergomed believe is highly attractive and at the high end compared to relevant public precedent transactions.
Unusually, there’s an alternative of less cash, 451p, and the balance in (unlisted) shares - which might have been quite a nice option for shareholders who want to remain partially invested in Ergomed, although without the protections of it being a listed company. However, the 5-year lock-in condition makes this less appealing. I'm not sure why this option is being provided, when it seems to have been structured to repel investors, and the advisers decline to say whether it is fair & reasonable!
Note that the founder, who still owns 18%, has agreed to the deal, so I think that confirms the price is fair, and that it’s likely to go through. Although only Amati with 2% has given an undertaking to support the deal. Maybe other institutions are waiting to see if a higher competing offer might appear?
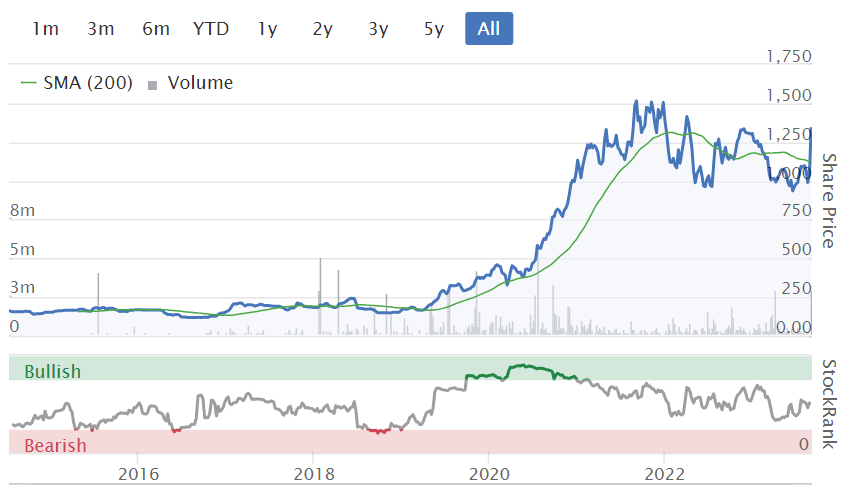
Paul’s opinion - this deal doesn’t look particularly generous when considering the previous share price did peak at more than 1350p previously. Although maybe that valuation was too aggressive in the last bull market? If the founder/major shareholder has agreed it, then I think that tells us it’s a sensible deal. Well done to holders!
There seems a clear trend that private equity buyers are going for structural growth companies, often in medical or software type of sectors, and they’re paying punchy valuations for them. We’re not really seeing much in the way of deals towards the value end of the market.
I see ERGO shares 10-bagged from 2019 to the peak in 2021, so I'm wishing I'd paid some attention to it, this largely slipped through the net here unfortunately. Jack reported positively on ERGO several times, but baulked at the high valuation each time.
Graham’s Section:
Belvoir (LON:BLV)
Share price: 225p (+2%)
Market cap: £84m
Belvoir Group PLC (AIM: BLV), a leading UK property franchise and financial services Group, is pleased to announce its Interim Results for the six months ended 30 June 2023.
This property franchising group tends to get positive reviews at the SCVR. These interim results are as follows:
Revenues +3% to £15.9m. Some moving parts here: acquisitions increased revenues, while the successful franchising out of offices reduced revenues (this is a good thing).
Management service fee (i.e. franchise-related royalty income) +4% to £5.5m, with lettings down and sales up.
Financial services income +11% to £8.6m
Only 4,177 house sales were managed (H1 last year: 4,889) but the lettings portfolio increased to 75,000 (H1 last year: 73,300).
The net result for the period is that PBT gets a 10% increase to £4.4m.
The results are “comfortably in line with management’s expectations”.
Checking the latest note from broker finnCap, I see that full-year forecasts are upgraded: they now expect 2023 EPS of 19.9p (previously 18.4p) and 2024 EPS of 20.8p (previously 19.5p). They also increase the dividend forecast.
Comment by CEO Dorian Gonsalves (emphasis added):
"With 58% of their revenue derived from a strong recurring lettings market, our property franchisees have been able to offset the impact of the reduction in UK housing transactions. Meanwhile our financial advisers are mitigating the lower level of new purchase mortgages by servicing demand for remortgages and other related products from their substantial client banks.
Comment on the housing market: “Whilst the headlines continued to predict doom and gloom for the property sector, the market actually proved to be fairly resilient in the face of the dual headwinds of high inflation and rising interest rates.” He notes that house prices are “fairly stable” (2.3% down on December 2022) and rents continue rising.
But still, there are some bearish factors that can’t be ignored, in my view. In particular, there is the 18% reduction in sale transactions, and the 26% reduction in gross new mortgage lending (both noted by Belvoir today). With the sales market frozen up, it’s a great relief for companies like Belvoir that they can fall back on their lettings income.
Dividend: Belvoir “has reviewed the Group’s dividend policy and intends to increase the proportion of earnings paid to shareholders in future”. Interesting! The interim dividend this year will be 5p (interim dividend last year: 4p).
Outlook statement foresees only another 2% fall in house prices, notes that mortgage interest rates have reduced from their recent highs, and sees continued strong demand from tenants for rental properties. I suppose that estate agents aren’t known for their doom-and-gloom views on real estate!
Balance sheet doesn’t offer much tangible support to the valuation here but the cash position is fine with a small net cash position of £0.4m. A large bank loan has been paid off.
Graham’s view
I liked this company before today, and the valuation hasn’t moved much this year:
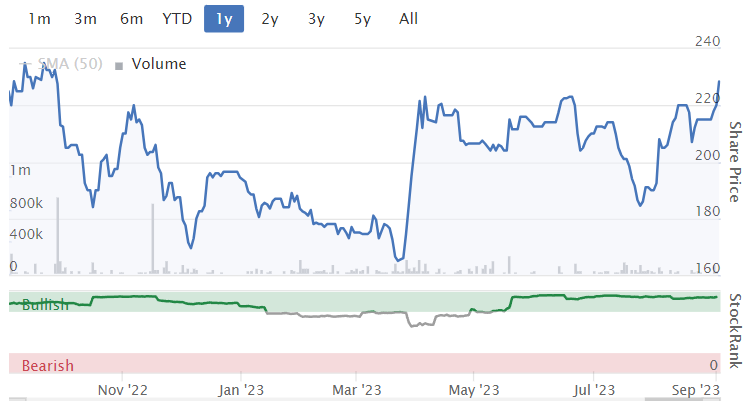
So clearly I’ll be inclined to stay positive on it today, after it issues a “comfortably in line” update and its forecasts are raised by the broker!
Its key feature is that it earns high-quality, royalty-like profits from franchisees - a highly lucrative investment theme. The franchisees themselves earn reliable, recurring lettings income and also have the opportunity, when conditions allow them, to earn substantial sales-related income. Financial services revenues should also pick up when bank lending recovers.
Cash flow is excellent, the company’s debts have been paid off, and valuation remains reasonable:
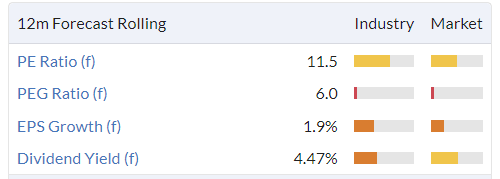
I’m not surprised to see that this share currently enjoys a very high StockRank of 92.
What could go wrong? Belvoir points to increasing regulation of the property market being a reason for landlords to use agents such as themselves. True, but perhaps there is a risk that increasing regulation could ultimately reduce the size of the rental market? And I’m not sure that this would boost the sales market very much, e.g. if owners of second and third homes simply allowed their extended family to live in them instead.
The bottom line is that property is now a more regulated sector; and who knows what regulations might be in 5-10 years, and how this might affect companies like Belvoir?
There are more obvious risk factors too, i.e. interest rates (when will BoE stop raising rates?) and other economic factors.
However, my own investment style is to try to own good companies and to accept that there will be regulatory and economic dangers. Sometimes this pays off, and sometimes it doesn’t. But equities are inherently risky and I don’t think it’s possible to eliminate this entirely. So for me, Belvoir shares definitely get the thumbs up!
Coral Products (LON:CRU)
Share price: 16.5p (+3%)
Market cap: £15m
Coral Products PLC, a specialist in the design, manufacture and supply of injection moulded plastic products based in Wythenshawe, Manchester, announces its audited final results for the year ended 30 April 2023.
We discussed this one in May and last December. It’s a tiny nano-cap, but it has impressed me with the successful (so far) digestion of four acquisitions.
Here are its full-year results to April:
Sales +144% to £35m (in line)
PBT +53% to £2.3m
Basic EPS +87% to 2.6p (ahead of broker forecasts of 2.3p).
April feels like a long time ago, as we are already in September, so I won’t dwell for too long on these historic results.
I have to go into the footnotes to find the net debt position. A key point is that the company finished the year with net debt of £7m (previous year: net cash of nearly £5m). The largest element here is an invoice discounting facility.
After the year-end, it paid out another £1.3m in an acquisition earn-out.
Its liquidity headroom is probably still fine: it has £4.8m of gross cash and perhaps another couple of million in headroom on its banking facility. But I think it’s important to point out the changed position. Reducing its net debt could be an important priority now.
Chairman comment mentions the strong gross cash position, not the net debt:
The four acquisitions completed during the first half of the financial year delivered a significant sales uplift and, have integrated well, adding complementary expertise and products lines. Despite investment in acquisitions and our ongoing capex programme, the Group continues to be highly cash generative and has retained a strong gross cash position. Our objective remains focused on capitalising on our position in the specialists' plastics market where we see significant further opportunity.
The plan is to become “a UK plastics business of scale”
Dividend for the full-year is 1.1p (0.5p interim, 0.6p final), costing around £1m.
Here’s an excerpt from the Outlook statement:
We have planned our business to be flexible, in all areas, to meet fluctuating levels of demand. We have robust financial controls that will ensure we maintain our working capital requirements whilst meeting all our agreed parameters with our financial partners and due to contracts already negotiated all operations will remain relatively unaffected by the current turmoil in energy prices…
We have enjoyed a strong start to our current financial year, and we look forward to a satisfactory outturn for the year given the prevailing conditions.
Graham’s view
I still think that this is an impressive nano-cap, showing decent profitability and shareholder orientation in the form of the dividend. The Chairman owns 7% which I view as a positive sign.
But there are some other important features to be aware of:
Average or low profit margins (gross/profit/net, take your pick!)
In line with most manufacturing companies, the “quality metrics” have never been particularly high.
The company is now significantly indebted and doesn’t acknowledge this in today’s RNS, only in the footnotes.
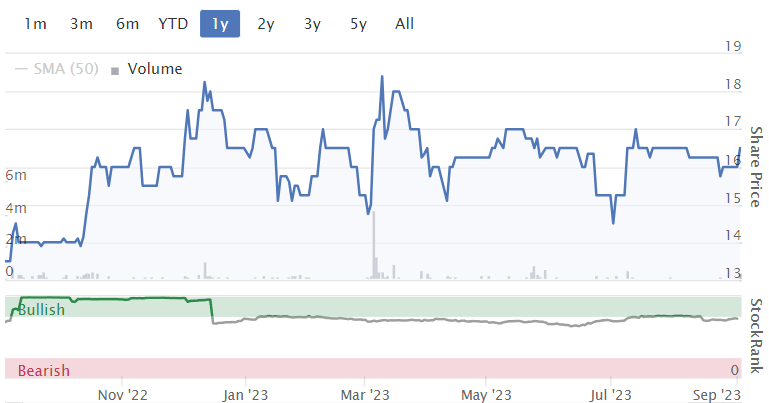
I won’t be making any changes to my “Amber” view on this share. On balance, the current earnings multiple of 9x seems fair enough to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
I was reading the news about Jimmy Buffett who died recently
He popularised beach bum soft rock scene with the escapist Caribbean-flavored song ‘Margaritaville’,
So it turns out Jimmy died a billionaire, he invested heavily in a fledgling holdings group called Berkshire Hathaway (NYQ:BRK.A) many moons ago.
No relation!
Funny old game isn't it?
Sad news. but I'd rather be alive, and moderately affluent.
I'm sure everyone will have seen the news about crumbling aerated concrete in schools and other buildings and initially I thought this might prove to be favourable for contractors (some of which do of course fall into the smallcap universe) as there will surely be a huge amount of re-building and repairing to do. Then I thought about the cladding scandal and how the government imposed a levy on housebuilders to help pay the cost of remedial work so perhaps a similar levy will be imposed on those contractors who have built schools and other affected buildings, so not sure if this is positive or negative news for contractors? Any comments?
Not sure how this will play out. Kier (LON:KIE) shares are down slightly today, they are the largest schoolbuilder.
Pretty hard to impose a levy on product technology that was used to build in the 50, 60, 70’s predominantly.
I very much doubt any contractor at that time gave a lifetime guarantee so the fact these panels are some 50+ years old would make that type of levy entirely unreasonable and would land the government in some serious litigation if they tried it. Not least because most of those contractors will not be in existence.
This bit of the law can get a bit complicated, but I agree with DJH, that there is likely to be zero exposure here, assuming these things were built more than 12 years ago.
Looks like Guy Stenhouse, Non-Executive Chairman bought the dip in Eneraqua Technologies (LON:ETP) on Friday, 50k's worth of shares.
Be interesting to see what you thought of the profit warning if you get time Paul?
Litigation Capital Management (LON:LIT) really surprised not to see this motoring ahead based on todays announcement of a class action litigation favourable settlement in Aus. The numbers are material.
Wasn't this just confirmation of settlement, and the figures already known? If not, then yes it should have gone a lot higher.
The figures were not known. They said at the time of the win they couldn’t quantify it so although the share price went up a couple of pence it didn’t really move. Today shows the impact which I’d have expected to result in some interest but hasn’t seemingly.
I haven’t followed the share price movements but I would expect that the recent Supreme Court judgement on the legal status of litigation funding agreements would have a negative effect.
Dear FREng,
Can you recall the name of the recent case about litigation funding agreements?
Thanks
Ricardo
Crikey, by your own admission you clearly haven’t been following the stock. The Supreme Court judgement does not impact Litigation Capital Management (LON:LIT) business model at all although it is probably net slightly favourable to them as small non compliant companies in the UK fall away. It’s all in a recent rns.
Crikey, by your own admission you clearly haven’t been following the stock
If people on the SCVR only wrote about stocks they follow or understood it would be a barren wasteland populated only by a few stylites preaching to the faithful from their lofty perches ...
The Litigation Capital Management (LON:LIT) RNS in question is this one:
https://www.investegate.co.uk/...
The bigger question I have over litigation funders (other than the hoary perennial of when is earnings actually cashflow) is how long litigation funders will be allowed to go unregulated, particularly as they seem very keen to fund cases against governments.
For instance, it'd be interesting to see what our government did if someone mounted something like the Malaysian Sulu suit against it for past colonial misdeeds: https://www.funds-europe.com/o...
The EU has draft regulation under consideration: https://www.europarl.europa.eu...
timarr
Litigation Capital Management (LON:LIT) have been explicit in an RNS that they are not impacted by the case.
Manolete Partners (LON:MANO) has 5% is assets impacted though
Franchise Brands (LON:FRAN) (I hold) have announced a restructuring of their board, reducing it to just 5 members exec chair, Stephen Hemsley, and CFO, Mark Fryer - and three non-executive directors. Many of the existing execs moved to second level Management Board which will comprise the divisional Managing Directors, together with the directors of the key central support functions. Nigel Wray and Stephen Hemsley are the largest shareholders, with just under 12% each.
Obvious concerns as this concentrates the top level decision making, compounded by having exec chair.
Any thoughts?
Pimlico, as you know Franchise Brands (LON:FRAN) has effectively been run by Messrs Hemsley and Wray since they bought in. The slimmed down Board seems a sensible move to make strategic decision making more efficient. Perhaps there is more M&A on the way?
And this way the operational and divisional leads can keep their focus on their areas of expertise. Given the nature of the team they are probably quite happy with this arrangement. Generally a focused, no nonsense bunch IMO.
For what it's worth Pimlico, I sold Franchise Brands after their Pirtek "transformational" acquisition as I prefer serial acquirers that make smaller acquisitions rather than betting the farm. Perhaps there would not be any need to restructure the board if things are going well, but just my speculation.
Belvoir (LON:BLV)
Heard a radio conversation with someone with someone operating in the market on property/mortgages etc. They said there may be pressure from renters seeing rents go up to acquire properties rather than continue to rent. With pricing coming down, and perhaps mortgage rates stabilising there could be further demand coming from this section of the property market.
Too early for doom and gloom, I would say.
A simplistic view is that property rental and sales go in opposite directions - people have to live somewhere, they either have to rent or buy. Ok, this is a very broad brush view but I have found over the years that this tends to be the case.
Ergomed (LON:ERGO) has been my most successful investment ever and to say that I’m disappointed with this bid would be an understatement. As AstonGirl points out it was only this year that it was at £13 and this bid strikes me as opportunistic. Relijanovic should have held out for a much higher bid. But if you are going to cop £125m you are probably not fussed whether you get £125m or £200m. After all how much can you spend.
Oh well at least it’s a tax free gain. But where to redeploy.
Would be interested in other peoples views on this.
Regards
Michael.
I'm a long-term holder bur rolled half of my holding (plus some) into hVIVO (LON:HVO) which seemed like a similar business at an earlier stage of its evolution. I was getting a vibe that whilst Ergomed (LON:ERGO) is undoubtedly a great business it might have gone a little x growth short-term.
Jim
Yes the offer and sale for Ergomed (LON:ERGO) highlights one of the reasons I like hVIVO (LON:HVO) long term. It has excellent growth opportunities short/medium term and a very strong net cash position. I heavily suspect the board intends for it to also get taken out eventually but some considerable way above current share price. Patience will be key with it though.
Ashtead Technology Holdings (LON:AT.) half year - adjusted eps up over 70% (statuatory eps even more), other metrics in line with that. Organic growth 41%. Gross profit margin 78.8%. Net debt up a bit, due to M&A.
"The Board is very encouraged by the Group's performance in HY23 and expects FY23 to be comfortably ahead of its previous expectations"
https://www.investegate.co.uk/...
Belvoir (LON:BLV) half year - eps up 3%, dividend up 25%. I'd note that over half the revenue is coming from Financial Services, as opposed to franchise fees.
https://www.investegate.co.uk/...
Presumably the shares of both will fall off a cliff today.
timarr
As a holder I am glad Ashtead Technology Holdings (LON:AT.) have decided against an interim dividend for 23, as WeSubSea and HireTtech seem to have integrated well and are performing 'ahead of expectations' I would back the management to find more profitable acquisitions with the potential divi money.
Yes great revenue increases from £AT. Also striking is that H1 ROIC is up from 19% to 25%, so they are their utilizing their subsea equipment better. More growth and upgrades are likely going forward.
My morning smallcap tweet: Blazing Twaddles
Ergomed (LON:ERGO) Home Reit (LON:HOME) Narf Industries (LON:NARF) Litigation Capital Management (LON:LIT) Graft Polymer (UK) (LON:GPL) Intercede (LON:IGP) Cordel (LON:CRDL) ReNeuron (LON:RENE) £CNIC
◄Ergomed (ERGO)► rec offer of 1350p, a 32% premium. [SP=1052 Cap=535m]
◄Home REIT (HOME)► monthly update. Co doesn't expect to publish its outstanding accounts until late 2023 at the earliest. [SP=38.7 Cap=301m]
◄Narf Industries (NARF)► gets $1.2m of orders under its exclusive US Government Omnibus contract. [SP=0.79 Cap=13m]
◄Litigation Capital Management (LIT)► settlement in Australian class action re contaminated land. Gov't will pay $132.7m. [SP=105 Cap=126m]
◄Graft Polymer (GPL)► R&D and Supply agreement with FORPET BALTIC. No £££. [SP=2.28 Cap=2m]
◄Intercede (IGP)► $2m of orders and renewals over 3 years. [SP=48.06 Cap=29m]
◄Cordel (CRDL)► trial contract for technology to automate rail level crossing safety assessments in Australia. If successful it will be followed by further stages leading to adoption across the rail network. [SP=6.5 Cap=12m]
◄ReNeuron (RENE)► generates "in vivo data to exemplify the cellular and tissue targeting capabilities of exosomes produced from its multiple conditionally immortalised producer cell lines". [SP=9.3 Cap=5m]
◄CentralNic (CNIC)► to becomes Team Internet. Ticker is TIG from tomorrow. CEO coughs up a fur ball of guff: "Our tier-one businesses, cutting-edge technologies, and the boundless potential of our team will continue to fuel the Company's growth...With our refreshed identity, we remain anchored in our core values." It just sells Internet domains FFS. [SP=123.67 Cap=341m]
TIG, the new ticker for CNIC feels familiar. Was it used before by a smallcap company?
The Innovation Group rings a bell..
CentralNic (LON:TIG) - I think they've got the ticker wrong here, it's TIG.L according to the news feed. (I hold CNIC/ TIG.L) Have reported TIG to Stockopedia.
Hi FREng.
I think it must have. Stockopedia TIG takes you to a company worth 40p last trade in November 2015. Got a bit of a shock. As mentioned by TEIN it should be TIG.L. Stockopedia needs to change it as the announcement has the wrong ticker now for CentralNIC.
TIG - the November 2015 last trade would have been the Innovation Group - last day was 17/11/15 before scheme of arrangement became effective. This is not the first time that codes have been reused.
Think I've got that wrong, the RNS reports both this morning, (TIG and TIG.L), however the company update reports TIG, so that has to be right, and presumably all the data will catch up in time. Apologies!
Stockopedia replied to me very quick this morning to say they're investigating the pricing errors for CentralNic (LON:TIG)
“ a fur ball of guff “. Love this description which can be applied to so much commentary in todays over hyped world. It is Roy Keanesque.
Mr Contrarian is normally spot on but he is a bit out of date on CentralNic. Selling Internet domains ('Online presence") is now only a minority of the business which is mainly online marketing and has been growing fast. Sadly, not only is Stockopedia confused by the change in ticker, but the group's own websites seem to have had a seizure so I can't check the accounts for the precise figures. Hope they sort that out quickly.
Ergomed (LON:ERGO) Another Day Another Takeover, this time a 1350p bid from Eden Acquisitions
Whilst the shares closed at 1052p on Friday they were above the bid price in December so it doesn’t seem particularly generous to me. I do note that M Reljanovic has been selling down since 2015 and is now at 17.98% which may have driven the recommendation bid if he’s wanting to fully exit (I don’t hold)
Starting to get mildly bemused none of my shares have caught a takeover in recent times, feels like there have been quite a few. Looking at some of the more recent ones, I'm coming to the conclusion they don't happen so much with a StockRank much higher than 80 (the day before the announcement), although my rapid data set is thwarted slightly by fact Stocko seems to delete the rankings once the takeover has gone through. Feels like 50-80 might be the sweetspot, but don't feel I have enough data to back this up. Wondering if anyone has actually ever tracked this? Or rationalised it?
You can still look at the prints before the bid. Just looked at a few and they range from around SR 27 Dechra Pharmaceuticals (LON:DPH) to around 97 Sureserve. Gresham House (LON:GHE) and EMIS (LON:EMIS) both about 50. Crestchic was about 65 SR. K3 about 82 SR.
Thanks Rusty. I couldn't find ones for Crestchic or K3C, are you quoting those from memory, or am I being thick in not finding the no longer listed ones. Maybe it doesn't matter and there's no pattern. I also looked at Instem (LON:INS) 69, Network International Holdings (LON:NETW) 74, DWF (LON:DWF) 81.
They are in my folios, so I can see them, but not sure if you can find them by searching. Here is K3C: https://www.stockopedia.com/sh...
and Load: https://www.stockopedia.com/sh...
I don't think stockranks are going to be any use in spotting takeover targets, since they have a heavy bias towards value at a time when private equity is looking for secular growth at recently reduced valuations. I've had a whole bunch of takeovers in my portfolio this year. Those I can quickly recall are Network International, K3 Capital, Dechra, Instem (impatiently sold before the bid came through), Sailpoint, Proofpoint, VMWare, Activision Blizzard and of which Ergomed is just the most recent. What they all have in common is a strong niche in attractive growth markets, minimal to no debt, rapid revenue growth, reduced but still "growthy" valuations. I think you would do better screening for these characteristics.
BnB, to have so many you either have a very diversified portfolio or are just brilliant at spotting the right ones. Either way, what you say makes sense. Just thought it was interesting to pose the question as to how the targets often score in terms of StockRanks.
To be perfectly honest, I am feeling a bit p**sed off. I have seen Instem, Ergomed and Abcam disappear from my portfolio over a relatively short time period. Long term, this is not good for UK PLC.