Small Cap Value Report (Mon 5 Aug 2024) - HVO, CKN, SNR, WG., RLE

Good morning from Paul & Graham!
It looks as if we're in for a bumpy ride, as Bloomberg reports this morning,
"Global Rout Deepens With US Stock Futures, Asia Stocks Plunging"
The Japanese market has fallen around 11% today, and almost 20% in the last 5 days. Bloomberg reckons it's due to high levels of margin trading in Japan, reaching an 18 year high recently. There's also been a sell-off in many other global markets, as I touched on in this weekend's podcast. I'll leave it to others to analyse the reasons, I'm just flagging that we could be in for a bumpy ride here. Personally I'll be ignoring this volatility, as I'm in good stocks, and don't use margin any more, so I can ride out any market volatility.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Very quiet for news today, so we'll have plenty of time to watch our portfolios dropping in real time!
Summaries
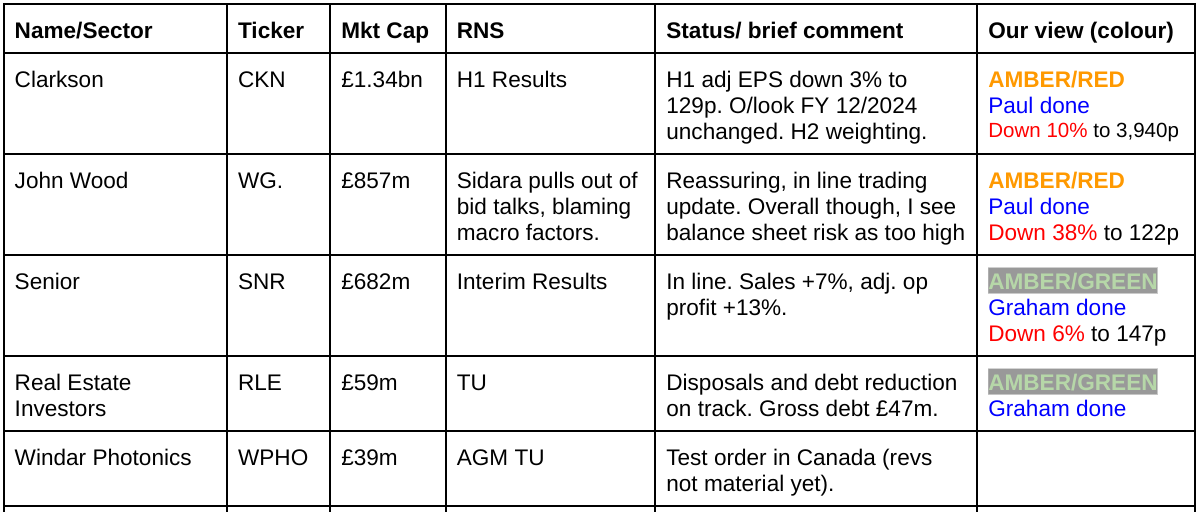
Clarkson (LON:CKN) - 4,370p (pre-market) £1.34bn - Interim Results - Paul - AMBER/RED
H1 numbers are in line, and the outlook sounds confident about hitting the FY 12/2024 forecasts. However, on doing some digging, I refresh my memory on the outrageously generous management and staff remuneration here. This puts me off, so I'm flagging that there are issues here, with a drop to AMBER/RED. The shares could still do well of course, other investors might not be so bothered about this as I am.
Senior (LON:SNR) - down 5% to 150p (£654m) - Interim results - Graham - AMBER/GREEN
Decent results here and full-year expectations are unchanged, although it must be said the outlook is a little cloudy, e.g. due to ongoing 737 MAX difficulties. I’ve upgraded from a neutral stance as the valuation for new investors has improved substantially over the past 18 months. It does remain unclear how the medium-term ROCE target of 13.5% will be achieved.
John Wood (LON:WG.) - down 38% to 122p (£857m) - Bid talks off & trading update - Paul - AMBER/RED
Bid talks are called off by Sidara, which blames macro factors. Whatever the reasons, it's done DD and walked away. Reassuring mini trading update today is in line. I have a recap on the numbers, and dislike the stretched balance sheet, with some nasties in there. So I have to flag the higher risk, but will happily move up once it's de-geared the balance sheet in future, if the turnaround gains traction.
Real Estate Investors (LON:RLE) - up 2% to 34.7p (£58m) - Trading Update - Graham - AMBER/GREEN
This Midlands-focused commercial property investor is pleased with its progress as it seeks to sell down its property portfolio and reduce its debt burden. A sale of the entire portfolio is also possible, according to the most recent full-year results statement in March. I’m intrigued by the discount to NAV on offer here.
Paul's Section:
John Wood (LON:WG.)
Down 38% to 122p (£857m) - Bid talks off & trading update - Paul - AMBER/RED
We’ve been following the bid approach (from Sidara) for Wood, with the timeline so far being -
16/5/2024 - Wood rejects 212p approach from Sidara as undervaluing it.
6/6/2024 - after pressure from shareholders, Wood management agree to allow due diligence on a fresh 230p indicative potential bid from Sidara.
Today’s update -
5/8/2024 - Sidara issues a rule 2.8 statement that it does not intend to bid for Wood. Reason given is -
“Sidara confirms that in light of rising geopolitical risks and financial market uncertainty at this time, Sidara does not intend to make a firm offer for Wood.”
Obviously we don’t know if that’s the real underlying reason, it could just be a face-saving type of announcement, who knows? Maybe they did their due diligence (detailed analysis of the financials & commercials, legals, etc) and decided 230p was too high?
Wood issues its response here - which echoes the Sidara announcement.
It adds the following detail -
“The Board remains confident in Wood's strategic direction and fundamental prospects. As set out in the HY24 trading update on 11 July, the growth strategy continues to deliver, with further growth in EBITDA, margins and order book in the first half.
As we look ahead, we remain focused on delivering our potential, including generating significant free cash flow next year.
We are pleased to reconfirm our outlooks for both this year and 2025.
The Board is grateful for the substantial engagement of its shareholders and the support of its clients and employees throughout this process. The management team looks forward to continuing to deliver against the strategy set out in November 2022.
Wood will publish its half year results on 20 August 2024.”
I find that mini trading update reassuring.
How to value Wood shares? This is the tricky bit! As you can see, performance has been volatile in recent years -
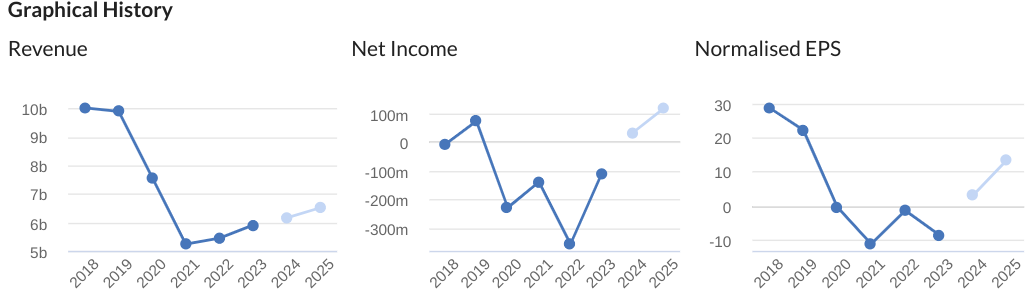
(note the figures above are in US dollars)
Valuing it on a PER basis is tricky, as forecast for FY 12/2024 is 3.1 cents, and FY 12/2025 is a large rise to 13.5 cents. With massive revenues of >$6bn, and low margins, there’s a wide range of potential outcomes re profits. Hence valuation is really tricky.
I don’t have access to any broker notes, so am largely in the dark here.
2023 accounts - I’m having a rummage through last year’s numbers, to get a better feel for things. It’s a very big business, and the accounts look complicated, with large adjustments in 2022 and 2023. Profit all comes from adjustments. There’s also worryingly negative cashflow, leading to debt looking uncomfortably high. Although the position with its unsecured loan notes looks OK, with a big chunk having been repaid from disposal proceeds, and remaining expiries into 2025 and beyond, which looks OK.
The balance sheet puts me off. NTAV was negative $(677)m at 31/12/2023. There are some nasties in there too, eg a $307m liability called “asbestos related litigation” dates from the 1970s or earlier, and is in the US. Remember that liabilities are (usually) estimates of cash outgoings in future. So Wood will need to generate tons of cash in future, just to pay down debt, and clear these onerous legal costs, before it can even think about paying divis. The last divi seems to have been paid in 2018, so this looks like a multi-year problem company.
Paul’s opinion - there’s too much risk here, with a lousy, overly geared balance sheet, and the hefty legal claims provision. So for me, it has to be AMBER/RED, due to elevated risks. However, I can also see that, if the turnaround actions gather pace and cause an operationally geared increase in profits, then this share could fly.
Since I don’t know what the outcome will be, I don’t want to get involved. One for sector specialists I suspect, rather than generalists like me.
Sidara walking away doesn't help.
Clarkson (LON:CKN)
4,370p (pre-market) £1.34bn - Interim Results - Paul - AMBER/RED
Clarkson PLC ('Clarksons') is the world's leading provider of integrated shipping services. From offices in 24 countries on six continents, we play a vital intermediary role in the movement of the majority of commodities around the world.
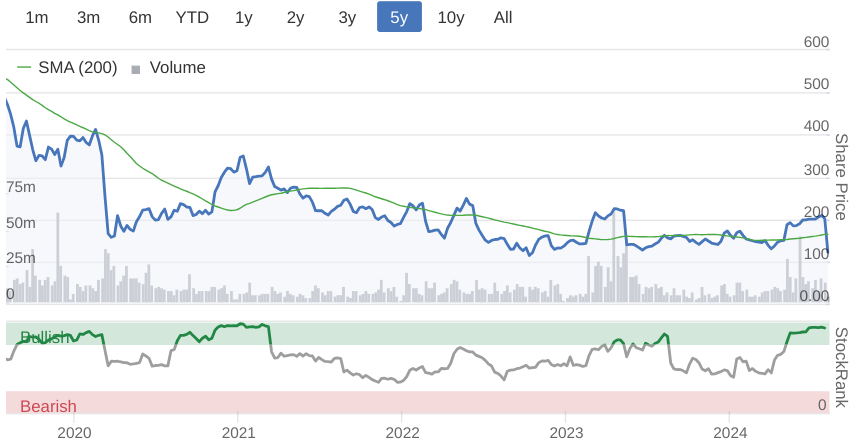
Shares have had a very good bull run this year, but I suspect we’re likely to see a sharp sell-off this week, due to adverse stock market conditions, and results that are only in line.
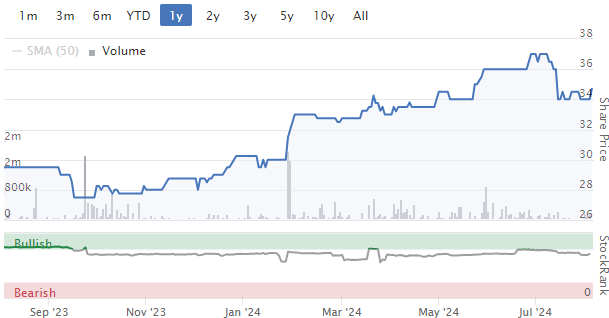
Shares had a fantastic run from Oct 2023 to last week - is this sustainable though?
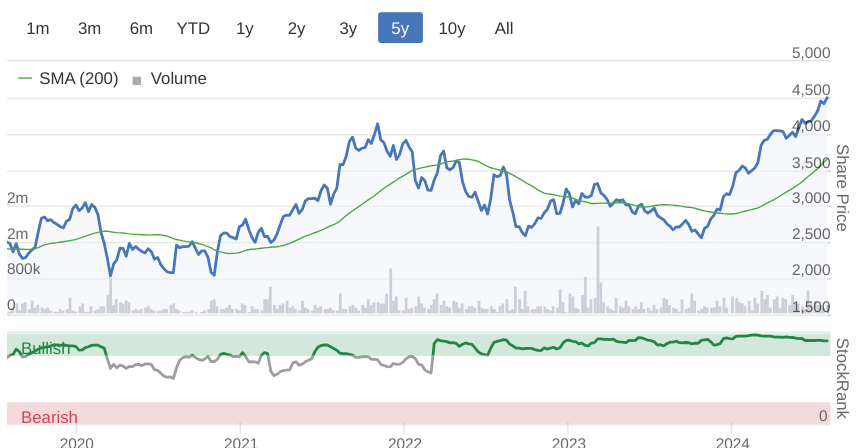
My main worry with Clarkson is that its performance dramatically improved when the pandemic kicked in. The big question being, how much of this (and why?) is a permanent improvement in business performance, or is it temporary due to all the disruption to supply chains, which is still ongoing (lots of companies we cover are mentioning delays and extra costs linked to the Red Sea) -
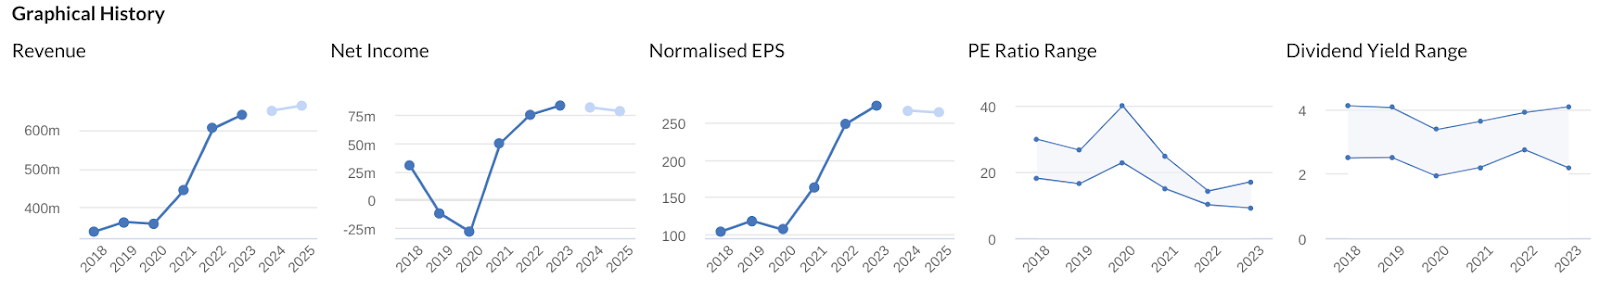
Hence the only question that needs answering with Clarkson, is whether higher profits are sustainable?
The company’s summary shows H1 profits slightly down on LY, but FY 12/2024 outlook unchanged -
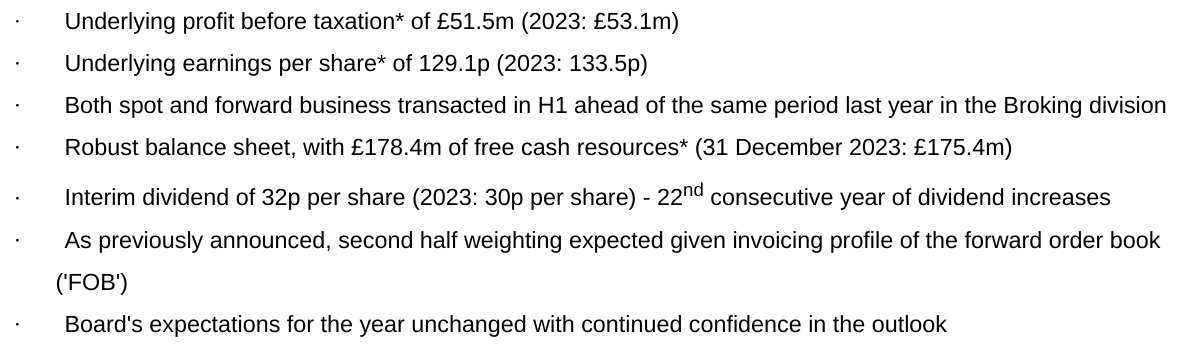
Note that adjustments to profitability are only small in both this year, and last year comparative.
Broker update - thanks go to Panmure Liberum for an update this morning. It sounds pretty upbeat, and emphasises that an H2 weighting is normal seasonality for Clarkson.
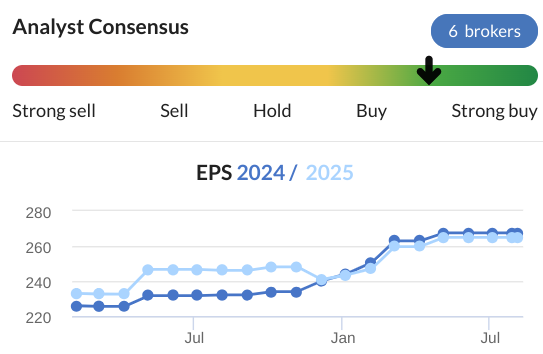
Forecast is 277p for FY 12/2024, barely changed from the previous year. 2025 and 2026 are in a similar ballpark, so there doesn’t seem to be any expectation of further earnings growth.
I see that shares are down c.10% to 3,930p at the time of writing (08:32), which makes sense to me, giving a PER of 14.2x - I can’t see any reason to pay more than that, given that it seems to have gone ex-growth. With possibly a risk that earnings might actually fall eventually, once global shipping returns to normal?
That said, shares were rated at roughly 16.5x on Friday, and are now usefully cheaper, so some might see this as a buying opportunity. Also note that the trajectory of broker consensus has been upwards -
Dividends - nothing to write home about, with a forecast yield c.2.5%.
Although the message that this is the 22nd consecutive year of divi increases is a powerful one.
Outlook - nice and clear, and sounds confident -
Andi Case, Chief Executive Officer, commented:
"I am immensely proud of everyone within the Clarksons team for delivering this strong set of results for the first half of 2024. The profile and further development of the forward order book, level of new business being transacted and pipeline for the second half, means that we have confidence that we will be second half weighted and deliver full year results in line with the Board's expectations. This confidence has enabled the Board to increase the interim dividend by 2p to 32p, continuing the progressive dividend policy into the 22nd year.
Balance sheet - is strong with NAV at £468m. This includes £180m intangible assets, so NTAV is £288m. That supports about 21% of the market cap, so useful, but this share is mainly about earnings, not assets.
Director & employee pay - I think we’ve discussed here before - for whose benefit is Clarkson run?
It seems to me that the answer is very clear - it’s run mainly to benefit Directors and staff. See this table below for the Directors remuneration from the 2023 annual report - they take astronomical remuneration, similar to the entire dividends paid out (hence the low divi yield) -
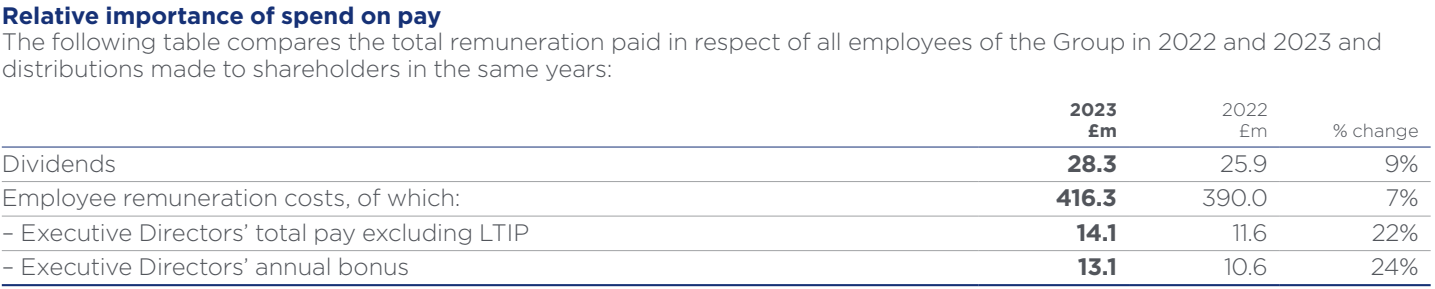
I also flag up last year’s cashflow statement, which shows £28.3m total divis paid to shareholders, which is dwarfed by the £49.5m cash spent on buying shares for the ESOP!
Note that higher up the cashflow statement it reveals that £58.7m was expensed through the P&L in 2023 for staff bonuses. The figure was even higher in 2022, at £88.8m!
These figures are absolutely outrageous in my opinion, and rule out this share as an investment for me.
I suppose a more bullish view would say that the business is far more profitable and cash generative than the headline numbers suggest, but the money is being diverted to employees rather than shareholders.
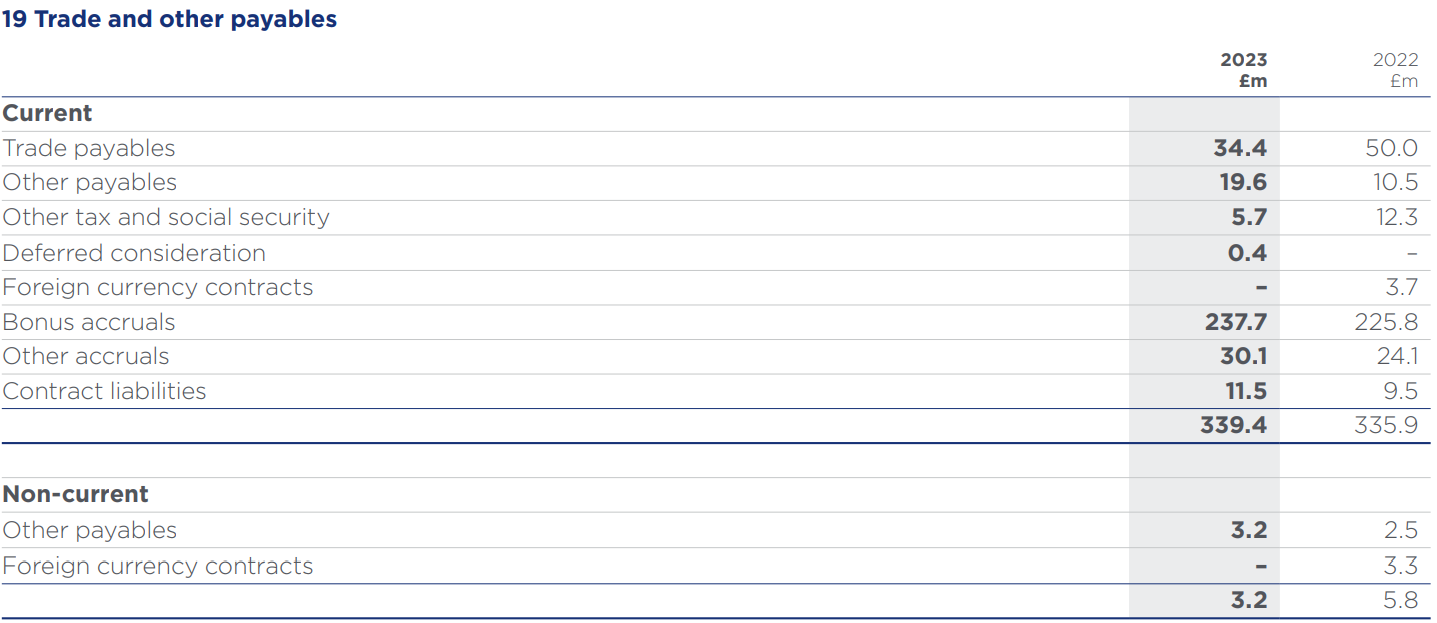
Another eye-opener from the 2023 annual report is note 19, where it gives the breakdown of trade creditors - look below at the money owed to employees in unpaid bonuses of £237.7m! If these are bonuses which have been accrued for, then a good question to ask management is when this £237m is going to be paid out?
The key point here being that the cash pile of £276m at 30/6/2024 would presumably largely disappear if the accrued bonuses were paid out in cash. Hence if you’re valuing CKN on an enterprise value basis, you’re probably significantly over-valuing the shares.
Paul’s opinion - I’ve previously been positive about CKN shares, because it has performed so well in the last few years.
However, refreshing my memory about its outrageously generous employee remuneration has really put me off.
In reality most of the profit made ends up with the employees, not the shareholders. The cash pile effectively belongs to employees too. On top of that, I don’t know if it can keep growing profits, or if it’s been boosted by the disruption to global shipping.
Putting it all together, I need to flag that there are significant issues here, hence I’m lowering it to AMBER/RED.
You might not be concerned about the issues I’ve flagged, and look how well the shares have done, so it doesn’t necessarily follow that these issues will harm the share price. It’s my job to flag up accounting issues, and you can then decide how you view them, armed with the facts.
These numbers do look crazy to me though, in terms of the rewards flowing to staff, and very little to shareholders.
hVIVO (LON:HVO)
It will be interesting to see if the mainstream media report on this, because it doesn't fit their doom & gloom agenda about how awful the UK is.
"HVO has announced the proposed cancellation of its shares on the Euronext Growth market. The company has noted that its primary operations, majority of employees and main investor base are in the UK and it makes sense to consolidate trading of its stock via the primary AIM listing. There are associated costs and duplication of activities involved with maintaining dual listings, and these will be removed."
(excerpt of a note from Cavendish)
Graham’s Section:
Real Estate Investors (LON:RLE)
Up 2% to 34.7p (£58m) - Trading Update - Graham - AMBER/GREEN
On a quiet day for company news, let’s cover this one for the first time:
Real Estate Investors Plc (AIM:RLE), the UK's only Midlands-focused Real Estate Investment Trust (REIT), with a portfolio of commercial property across all sectors, is pleased to provide the following trading update, ahead of the announcement of its Interim Results on 23 September 2024.
Key points:
£12m of planned disposals year-to-date, either completed or conditionally exchanged.
Further strong sales pipeline expected to complete in H2.
Debt: £7m of debt repaid year-to-date. Strategy is to prioritise debt repayment. Total drawn debt reduced to £47m (year-end 2023: £54m).
Average cost of debt 6.5%.
Rents: annualised rental income reduces to £10m (year end 2023: £11m) due to disposals and vacant possession needed to sell assets.
Occupancy at 84% could improve with new lettings and the disposal of vacant assets.
Q1 dividend reduces to 0.5p (Q1 2023: 0.625p)/
CEO comment extracts:
"We are pleased with the performance of the business year-to-date and remain on track with our strategy to make targeted sales to private investors and special purchasers during 2024, repaying debt with the proceeds…
Sentiment so far in the second half of the year has been positive with business confidence in our region growing by 15 points since the result of the election in July. We believe the recent 0.25% interest rate reduction, announced by the Bank of England last week, will further enhance confidence and support a return to more normalised investment market conditions that will allow us to start to sell our larger assets, utilising funds more rapidly to eliminate our debt with a view to then returning surplus capital to our shareholders.
Graham’s view
I’m not sure what to make of this one yet. The Dec 2023 balance sheet showed total assets of £156m (including properties of £143m) and net assets, after all liabilities, of £96m. That’s a significant premium to the current market cap of £58m.
Recent asset disposals have been slightly above their balance sheet values, which tends to give some reassurance that balance sheet values may be accurate.
Strategically, the Board has decided that paying down the debt should be the priority, and are “open to a corporate transaction that is in the best interest of shareholders”, which could include selling the whole portfolio.
This is a very small company by REIT standards and I’m inclined to think that a disposal of the entire portfolio to a larger REIT could make sense.
That transaction would hopefully be closer to NAV than to the current market cap, giving shareholders an uplift.
On the other hand, if RLE succeeds in selling down its portfolio and reducing debt, without taking any large discounts to balance sheet values, then perhaps it can prove that it deserves to trade closer to par without needing to sell the entire portfolio?
Net tangible assets per share, according to the Dec 2023 results, were 54.9p. If that number is still approximately right, it provides an opportunity of well over 50% from the current share price.
And with interest rates moving in a more favourable direction, maybe it won’t be so difficult to offload more properties?
I’ll tentatively go AMBER/GREEN on this one, but more research is needed.
Senior (LON:SNR)
Down 5% to 150p (£654m) - Interim results - Graham - AMBER/GREEN
A reassuring headline for Senior’s investors:
Robust results, full-year expectations unchanged
Key bullet points from the results table (all growth figures are given at constant exchange rates)::
Revenue +7% to £501m
Adj. operating profit +13% to £25m
Adj. PBT +8% to £18m
Other key points:
Return on Capital Employed (as calculated by the company) increases from 6.3% to 7.3%.
“Book-to bill” ratio is 1.15, meaning that orders are coming in faster than they are being fulfilled.
Interim Dividend is increased by 25%.
Net debt increases by £24m to £156m (excluding leases). Free cash flow was held back by growth in inventories and receivables, and higher capex. On top of that, Senior then had to fund deferred consideration (defcon) for a prior acquisition, £7m of dividends and £3m of share purchases for employees.
Net debt to EBITDA is 1.8x, up from 1.6x six months earlier.
CEO comment snippets:
Our Aerospace revenue and profits have grown strongly notwithstanding 737 MAX volumes being subdued as a consequence of the ongoing situation at Boeing.
Our Flexonics Division continued to perform well, maintaining double digit margins, albeit revenues and profits were lower as land vehicle markets started to normalise and upstream oil & gas customers reduced inventory levels.
For the full-year we still expect to maintain good performance in Flexonics with H1 slightly higher than H2 due to a return to more typical levels of land vehicle demand.
Some additional commentary on the 737 MAX follows later. In short, businesses within Senior were planning for higher build rates of this aircraft and are awaiting clarity on levels of future production, but they do have production schedules agreed for the time being.
Adjustments to the results: while there is nice growth in H1 adj. operating profit, this is only possible with the help of adjustments. In particular, there are £2.6m of “site relocation costs” that are adjusted out. Without the adjustments, H1 operating profit slightly decreased.
Outlook: Aerospace performance in H2 should be higher than H1, thanks to “sensible schedules” agreed with Boeing and other customers. Flexonics is the opposite, with H1 slightly higher than H2. “Overall, the Board’s expectations of good growth for the Group in 2024 are unchanged”.
Graham’s view
It’s been a while since I covered this stock (see last year’s report). The main difference since then is that the forward PE multiple has improved for prospective investors:
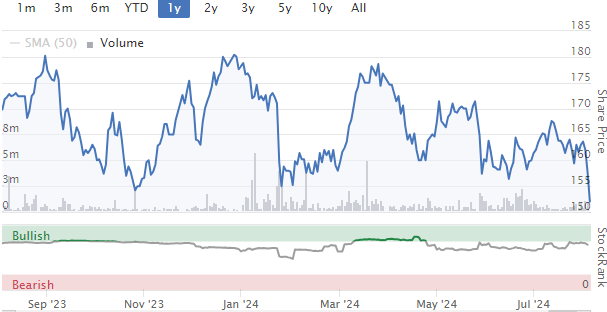
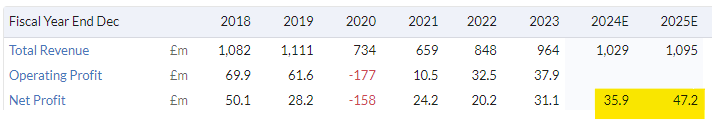
The forward PE multiple is now about 15x, versus 25x when I covered it last! While protracted weakness in the share price has played a part in this, the main reason is higher forecast profits over the next year:
I was neutral on Senior early last year. One major gripe I’ve had with the company has been its low ROCE over the years: it had in general failed to achieve a ROCE of over 10%, even in good times. It has a target ROCE of 13.5% that it has been working towards “over the medium term”.
As noted above, the latest ROCE measurement from the company is 7.3%.
Here is today’s update on its progress with this metric.
We understand the importance of considered and effective capital deployment towards maximising shareholder value creation. The Group has a medium-term pre-tax ROCE target of at least 13.5% on a post IFRS 16 basis. Our strategy of expanding Senior's high-quality fluid conveyance and thermal management businesses remains a priority. We have a rigorous appraisal process to evaluate the business case of all significant investments.
The Group actively reviews its overall portfolio of operating businesses and evaluates them in terms of their strategic fit in order to grow returns, maximise Group operating efficiency and optimise value for shareholders.
We continue to progress strategic options for our Aerostructures business including the potential divestment of the business. Within the period, revenue in Aerostructures grew strongly by 16% from £121.9m to £141.2m on a constant currency basis. We have secured notable new contract awards and important contract renewals bringing pricing up-to-date from various customers, with multiple ongoing discussions regarding attractive new business opportunities.
So perhaps a disposal or even a set of disposals is how the company will achieve higher ROCE?
I’m happy to upgrade my stance on this one to AMBER/GREEN as the valuation has become more interesting and at the end of the day, I still view this as a high-class aerospace & defence group. But it seems that it does still need to figure out how it can achieve sustainably high returns for investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

124 comments
Just in case anyone is interested. Here is the podcast I mentioned. If you want to ignore all the fluff, the most interesting section is from around 20 to 40 minutes: https://behindthebalancesheet....
All the best, Si
Great podcast on the weekend Paul many thanks, I now use these as an incentive to get out the house and go for a walk so I'm often straight out the door when they turn up and an hour is perfect for financial pondering while shuffling around the local park.
And thank you to Paul & Graham, for today's coverage - I've read it & I own one of them, even if my comments have been on other matters.
It's not much fun being an analyst when the market moves this much as people get distracted.
Easier said than done but at least a bullet in the head, or a stab in the guts is not the most serious risk we face in our age, (well hope not as writing! - seems the inevitable civil disruption is reaching its nadir.
Dead cat bounce is what I want and into cash - sorry the optimists.
Don't panic! Agreed Harry. As long as you are not in the bubble areas (mostly US mag-7) or are leveraged!
I'm a dividend investor. What counts for me is my annual dividends which are doing very nicely. I only really get worried if a dividend cut is coming. In the meantime, if you have cash in your portfolio its time to start buying more dividend stocks. Gradually though, as we don't know whether this is a correction or full on bear market starting.
Alternatives are very interesting today. They are following the market down, but the 10 yr bond yield has reduced down to 3.9% in a matter of days which is a positive for valuations. With 7-8% yield on offer and high discounts, that's quite a nice proposition. Returns must be c10% per annum from here on the quality operators, which is good enough for me!
Financials that are not likely to cut their dividends are also very tempting such as Legal & General (LON:LGEN). It will probably go down further, but did very well in the GFC and is unlikely to blow-up this time around...it's not a bank!
As always in such situations, there are too many opportunities and you can panic into not buying anything as you watch the red screens. Purchased 2 holdings this morning and will start adding modestly on down days from here.....provided the dividends on offer are good enough!
And I guess I should respond on the bond market....(broadly, not today's moves).
Maybe it is just that familiarity breeds contempt (I spent a decade in fixed income), but I was never entirely persuaded that the bond market had a more accurate crystal ball than the equity market.
Yes, yield curve inversions precede recessions, but they've also reliably preceded something like 10 of the last 2 recessions....(the spikes/signals tend to drop out of the long term charts because they didn't last long). Also QE has brought in to question whether yield curves today are comparable to the yield curve analysis of decades gone by.
What is different is that fixed income investors have a very different perception of risk/reward - credit investors especially are much more concerned about downside. They don't get bailed out by the odd multi-bagger.
It’s days like today, when the whole market takes a bath that a few of my stop losses kick in and it makes me reevaluate if I should be using these on all shares I buy - my option on the shares I’ve been stopped out of remain the same.. I usually set these at. 10% of the price I buy at - and move the price up when / if prices increase. What are people’s views on stop losses?
Stop Losses are OK if you are invested in a company that isn't doing well and it preserves some of your capital, preventing a further loss. What about a strategic trailing stop loss to lock in your profits if the shares have risen over time?
If you believe in the company and its prospects, then I wouldn't use them myself.
The VIX today was at a 4 year-high (since Covid), and this isn't another Covid, so I think a lot of shares will recover.
I am in two minds, but 10% on days like today, you would expect some to hit. I believe the best range is 15-20%, and I had mine set at 15%, but turned them all off yesterday. I felt it was just going to be market behaviour and not the individual stock. A couple would have been hit today, but bounced back a little. Last time I got all stressed when to buy back in, so I have decided to chill out. Hope it works out for you either way.
PayPoint (LON:PAY)
Added a few today. Looks good value to me. The company has a dominant position in a niche market.
Well I have just done some end of day catching up on emails, I put small orders in on my Vanguard SIPP on Friday and today, purchase of various ETFs to get specific market exposure, and prices on Friday were not dissimilar to those I got today, and some cases lower...no specific discussion point but sometimes it pays to put orders in on days that everyone else is selling maybe? These purchases are at their specific automated trade points rather than calling Vanguard.
I know that I am drip feeding in, so this is not a wow I am amazing look how much I made from a trade, rather I am trying to have the behavior that is the reverse of my past - yes I am trying not to follow my patented "buy high, sell low, buy even higher, sell even lower" strategy.
Yes in some cases the market was a lot cheaper on previous purchases if you go back in time but I do have some cash, and I will be honest that is through nervousness rather than a wonderful insight, but also trying to modify past behaviors on days like today.
To those worrying Friday and Today, this is about trying to learn a different behavior of not to log in and sell everything and watch the world bounce back up again, get FOMO and buy back at a higher price, watch it bounce lower, panic again and sell...and basically manage to lose x% of your portfolio in a few days due to "over trading in total Fear and Panic". If you are a genius trader yes there is a lot of money to make from those ins and outs, but that is not me. Now if you need a major construction project that is in a total mess rescuing different conversation :)
Yes there has been a pull back on a lot of things, and a lot of fundamental pricing alerts from Stocko Thursday/Friday/Today coming into my inbox, but that is another hour to clear that and set things up again. I am happy with the companies I have bought, there is nothing I would describe as racy or highly speculative. So somethings show as green, and some as red, but my good thing for me is I managed to sell nothing today.
Instead I bought some more ETFs to add to existing holdings.
It may all bounce up tomorrow, it might go down, I do not know.
Now it is time to go make tea as I have switched off the work laptop, and will do the same with the home one now and then go take the kids to swim training and go for a walk round the park next to the pool - not the glamourous high life for me :)
Make your plan, and stick to your plan... unless it is not working in which case sit back and think again carefully and update your plan, or modify your behaviors.
Good luck for tomorrow!
Tommy
Panic on the streets of London .
So said Morrissey.
How many actual business owners that are in their business day in day out hopefully working to a plan and budgets have actually drawn their curtains this morning and tried to sell their business by lunchtime
Not once in 30 years when owning a business would I ever have even considered “what the market was doing” as a factor ,
So if as a shareholder by definition you are a business owner, then why sell your business today just because a manic depressive Mr Market who is nothing more than a face at the window passing by every day telling you what he thinks your business is wortn based on his emotion .
Strikes me a lot of “shareholders” are actually traders that do not realise they own a business of long term .
When the tide goes out you can see who has their pants down, traders are panicking esoecially if leveraged, business owners are unaffected.
Interesting book, worth a plug i think, about the global carry trades/leverage by an englishman, Tim Lee, and his son and a US professor no less 'The rise of the carry : The dangerous consequences of volatility supression and the new financial order of decaying growth and recurring crisis'.
So glad i didn't sell puts on the indices yesterday.Vix was around the pandemic levels today... Is the global economy going to shut down again?!Everyone was watching the yen slowly start to reverse and go up the last tiny while though....
“Is the global economy going to shut down again”
I just dont understand how this affects UK small caps ?
Cant think of a single company I own that gives s rats ass about “global economic shutdown”
We sold exacy the same number of saddles today as we have done for previous 10 weeks.
Same staff
Same overhead
Same collection at 1pm
Nothimg changes
Same matket denand, same run rate.
Even “recession” well what in reality is the diffetence between plus 1% growth and -1% growth , just 2%.
In my opinion 99% of businesses are no diffetent today than a week ago .
USA ISM services PMI 51.4 forcast 51 previous 48.8
Markets fall most before the event it fears!
In my 30 years of investing, the market falls most before the actual event. It fell before the Gulf war (it actually bounced when the war started), it fell before the lock downs and it fell before entering recessions. This time is no different.
I look at my holdings and I am aghast of how much it has fallen. It will bounce back; at least it has since 1987. long enough.
I am going through my watch lists and selectively adding. financials and banks rose strongly and have fallen back sharply. I only look at those with the biggest falls. Today is not the time to pick up those who have fallen.
I am eagerly watching the afternoon opening of the US market. JPM, BLK and Berkshire are on my list.
No cash? wait for the divi to arrive. We probably have a few weeks of this mayhem.
"I am going through my watch lists and selectively adding .... I am eagerly watching the afternoon opening of the US market. JPM, BLK and Berkshire are on my list."
Sounds like a good plan, perhaps others could suggest which stock is on their list. I may top up GDWN, and am looking at JUST, RCH, and ALTYN
I have gone to the mattresses!!!!
What you are logged in on your phone whilst at Linthorpe Beds???
Hope you find what you want at a good price!
I’m dreading logging into my trading account, in anticipation of a sudden 5-10% drop of my holdings. It would be great to hear how others are coping with this kind of stress of investing. I’m working on facing market shocks head-on instead of avoiding them, although I'm tempted to switch off for a few days. If only I had full confidence in the quality of my holdings, this course of action would help me weather the storm. The fear index must be off the charts right now. Despite this, I’m trying to resist the urge to become a forced seller and maintain trust in the quality of my shares. In the past I've usually buried my head in the sand in hope of a market recovery!
Stress isn't kicking in for me yet. The best thing to do if you feel like that is to switch off for a few days.
When the market falls this fast it will usually stage a quick rebound, too. It's impossible to know if a bear market is on the way, or if it's just a temporary market blip.
A forced seller is someone who has to sell for liquidity reasons, which I assume is not the case for most folks here. If you're not using margin or leverage, nothing is forcing you to sell other than fear.
Anyway, best of luck. We're all feeling your pain right now.Well Turbo, the old adage of if you're going to panic then panic early, still runs true today. Although, depending on your size, you might find the liquidity is just not there to sell into.
I think your point in having confidence in the quality of your holdings is a good one and depending on their balance sheets they might even benefit from the multiple rate cuts now forecast to come our way.
Either way, good luck, nobody ever said this game was easy!
I'm more of a planned seller than a forced seller. There is a price I will sell at and be done with it. I won't hold telling myself a story that it will eventually come back. I have a plan for buying if and when my system tells me to. That means I'm not having to take decisions under stress... too many biases otherwise.
If you have good companies then you should be ok.
Feeling nervous is natural, I feel nervous too but not too worried. Interest cuts are coming which is normally good for stocks.
this is my portfolio today and will get worse as US opens as I hold Nvidia
Thanks for all the replies, it helps to feel part of a 'team'. On a slightly more positive note, Nvidia seems to be bouncing back up (I hold), and Goodwin (LON:GDWN) seems to be holding up well without going into negative territory (I hold). I may decide to log on to my share account at some point....
It’s stressful, but I hope I’ve learned my lesson this time. Previously, I kept switching in and out of investments, driven by fear of losing everything during drops and fear of missing out on rebounds. The brokers were the only ones making money, and my timing was a tad off. Now, I’m staying invested in companies I believe are solid, and I’m still showing positive numbers year-to-date. Good luck with whatever decision you make; talking it through really helped me last time.
Hi Turbo
I’ve been through (and guess many others here have too) the “dread” stage you’re in today. There’s no solution if the falls continue as it’s too late and if the falls continue you’ll probably worry even more!
There are though investment methods that reduce the worry so that next time it’s less worrying. My method (it’s just one approach possibly not used by a lot of investors) is quite simple,
1. Always have plenty in cash ready to invest at bargain prices after big market falls.
2. I’ve a portfolio stuffed full of quality big dividend paying shares and Investment Trusts. This ensures regular big income which provides some relief (and more cash for new investments) during big market falls.
3. I’ve a portfolio I’m very happy with (aside from around 10% in iffy shares, fun punts etc) that can ride out the big falls. If having doubts about any of my holdings, I sell. I don’t wait to panic sell after the share price has crashed in a crashing market.
4. Having a portfolio we’re happy with even on days like today, means it’s a must to sell at once on bad news and profits warnings. It’s a big mistake to hang on and hope or make excuses. That leads to a portfolio with too many shares that should have been sold and already losing even ahead of days like today. And these failing shares can take bigger hits on big down days and weeks than quality shares that under promise and over perform. I also tend to sell on dividend cuts if a key reason I bought that share or Investment Trust was for that big dividend.
What to do now?
That’s the really hard bit if very worried about further market falls and not happy with the portfolio. Perhaps do some selling or top slicing to reduce the worry?
We can’t predict markets though many of us think we can.
So it’s guesswork whether this is an overdue correction after a very good run that will soon be followed by a big bounce, or whether there’s much worse to come, and specially so for some arguably overvalued US tech shares.
It’s infuriating to sell just ahead of a big bounce. It reduces investing to gambling too if we have to resort to that just because we’re scared.
So to the final key points.
I use the tried and tested method of buy low and do some selling and top slicing in the good times. Then big market falls provide the next buy opportunities instead of a reason to panic.
And to end on a positive. A lot of UK shares and a wide range of Investment Trusts investing worldwide were already at bargain prices. They are cheaper still now. e.g UK shares like Legal & General (LON:LGEN) now paying a near 10% dividend and M&G (LON:MNG) also paying 10% a year. There are plenty more like those two too. E.g…..the Commercial Property REITs where sector consolidation is taking place and where the yields are up to 9%. AND they are holding up well so far today.
If the market falls continue then these UK bargains will get cheaper still …………..to provide a bargain buy opportunity that means the next time there are big falls it’s far less frightening.
Good luck.
Legal & General (LON:LGEN)
i think i would say with the black box companies like the insurers and the banks i think one needs to accept that when there can be risks of unknown / unplanned contageons coming back to bite these companies down the line for whatever reason. So in times of strife it might be the case that now is the time to load up - but if i was offering advise to others i would say think twice before investing in finance related companies s in times of strife - unless you have done your resarch or are happy with the fact its nigh on impossible to predict what the next banana skin may be for companies like this.
Hi Ken,
Always have cash is something that few can manage just because of the FOMO factor. That’s the difference of professional experienced investors with the rest.
Interesting and correct points you have there but the CASH factor is the one that makes the difference and the one that helps beat the market.
An understanding of how the bond market works is crucial as well.
Perhaps the next Stockopedia workshop should be about the bond market!
All the best
Yiannos1 is in mischief mode....
Stocko will need to work out how to accommodate dirty pricing, durations and DV01s into the Stocko schematics first.
You can usually accommodate equities on a platform designed for fixed income because equities are a bit like deeply subordinated, variable coupon, perpetual bonds with voting rights attached.
Adding bonds to systems designed for equities is extremely difficult - it doesn't take long to realise it is easier to start from scratch.
Monty
That’s very deep things that few understand (especially in practice).
I am talking though about Stockopedia educating its subscribers about the US bond market and how it works. Maybe they have done it in the past. I don’t know. I think it is a good idea though.
For example today this massive stock decline was not accompanied by a bond rally. You and I know very well the meaning of this movement………
All the best
All jesting aside - I'll settle for Stocko being able to handle dividends in their "performance" charts & return stats before they turn their attention to the nuances of semi-annual and annual yields, let alone z-spreads.
Stocko can't yet show equity income investors what they need to see to assess their performance, let alone teach subscribers about fixed income.
Hi Yiannos1. I was puzzled why bonds didn't rally today. They started to rally hard but then gave back all their gains. Are you interpreting today's equity movements as a prelude to recession and today's bond non-rally as a prelude to inflation? I would have thought that recessions were generally disinflationary as demand falls and supply remains too high. I'd also guess that commodity input prices generally fall during/ahead of recessions (which they have) and that this would also tend to reduce inflation. Finally, I'd expect central banks to reduce interest rates, which should increase bond prices on at least the short/medium end of the yield curve. So I'm surprised at the sideways movement in treasuries today (although tbf they rallied hard last week, so perhaps some profit taking into the rise?)
The only logical explanation is that this is just a deleveraging/overpriced valuation correction with further to go. If it was a growth issue the bonds would have rallied despite going up last week.
I wish I knew but usually at the end the logic prevails.
All the best
I listened to a podcast earlier this year with a specialist in Japan being interviewed and I found it interesting that Japan is the largest outside holder of US Treasuries with north of $1 trillion. So, apart from the unwinding of the carry trade and issues with the leveraging of it, which is scary enough, what happens if the US reduces interest rates as you have mentioned and the Japanese banks decides to sell down their Treasuries and buy their own domestic bonds?
Just curious as it’s beyond my pay grade.
It’s the most secure asset in the world.
I realise that, and that’s why Japanese exporters to the US have ended up owning so many Treasuries. I know $1 trillion is a relatively piddling amount in terms of the size of the market but as interest rates decline in the US and increase further in Japan as they seek to tame inflation, it makes less sense for the Japanese to hold them.
Anyway, looks like the Japanese market has bounced back hard overnight. Nikkei up 10%. Could all be a storm in a tea cup.
They are not investing
They are looking for safe heaven assets
The highest the rate the highest the probability of default
I think you maybe need to understand it more from the Japanese perspective. I know it’s smaller than the US but it’s still the world’s third largest economy. The podcast I linked below is at least worth 20 minutes of your time.
It’s above your pay grade-you said it
No need to continue this conversation
Thanks for the put down, nicely dismissive. And you have the cheek to complain about Paul.
Maybe I understand more about what’s happening in Japan than you as it’s something I’ve followed closely for the past 18 months. What I don’t understand is the effect on the US bond market if Japan starts repatriating capital, hence my question. Even after yesterday my Japanese investments have done extremely well in that time. Here’s another podcast which discusses the changes in Japan. It’s a more interesting overall discussion from the turn of the year, main discussion of Japan started around 30 minutes in: https://behindthebalancesheet....
You are trying all the time to pick fights.
I have worked in the industry and I understand who is what and the knowledge they have in different financial instruments.
You asked a question saying that is above your pay grade. I answer to you at a time that I am very busy. You come back with something that it’s no interest to me trying to teach me whatever you think you can teach me??
But then you bring Paul in the conversation.
It was only on Friday that you were fully invested but suddenly on a crash on Monday you had cash!!
I’m not trying to pick fights. I asked you a genuine question as I do with others in these comments from time to time, but for some reason you felt the need for a put down. I used to work in the semiconductor industry with a particular emphasis on intellectual property, and when anyone asks about it I try and help them out and explain things. It seems that’s is beyond you other than to display your self importance and superiority over others. If you’re busy then there is no need to respond at all and certainly no need for put downs which are every bit as bad as the post Paul made on Friday.
As for your last cryptic comment: It was only on Friday that you were fully invested but suddenly on a crash on Monday you had cash!! I have no idea what you’re talking about. I did no such thing.
A possible answer (although we're in the weeds now) is perhaps the US Service industry PMI coming in hot today - leading bond investors to conclude that the economy may in fact be chuntering along quite nicely so that interest rates will not be slashed quite so dramatically after all.
There's little doubt that both the equity and bond markets are very jumpy, hence the recent volatility.
I'm buying a few things already in the US markets.Maybe too soon but who knows.I wonder if Powell will say anything soon or not......?Nice sunny day in the garden though.So turning off after any buying sounds great.
VIX is over 50 now and will be close to pandemic and 2008 FC levels if this continues in the next two days. To understand the seriousness of what is going on the VIX record was at 89 during the 2008 FC.
All the times the VIX was over 50 there was a market crash. I believe the FED will have to make a series of rate cut interventions.
All the best
Dear Stockopedia
Please can you do something with the tech or moderation so we don't have to suffer the 'one letter per line' posts. I never see this anywhere else. It's so annoying to have to scroll for ages when it's entirely unnecessary.
Thanks.
Michael - you need to specify what browser/OS/machine you are viewing the website with and send your request via chat to Stocko - not as a comment to the reader community on the SCVR?
I'm not seeing what you refer to on a PC with Win11 using Firefox.
Thanks Monty Carlo
They problem is on my phone. I think many users will have the same problem so I think it is sensible to raise this openly. It is not a one- off but a regular problem
Sigh - iphone or android? Which OS version? What browser? Which brand & model?
It is very challenging to design a website to cope with thousands of different mobile phones (let alone multiple browsers per OS), each with a slightly different screen size across 10 different versions of each operating system.
Not something the SCVR can handle.
Contact Stocko on the support button. Never get that issue on my device. Get plenty of other issues that are unique to this site.
I get this problem on my iPhone when in portrait mode. If I turn my phone to landscape it solves it. Maybe that is of some help?
Thanks MattH.
That worked on my phone.
Really helpful, possibly for others too.
Will check my laptop later.
ymmv. I have a big screen phone. I get the same issue holding in portrait.
If i hold the phone in landscape i see
(or go unthreaded but i lose too much context doing that)
Hi Michael, this happens when there are multiple replies and you view on a phone, it's always been like this, the longer the thread, the less letters per line. Best head for a laptop if you wish to view the long threads.
In my case android mobile phone.
Tom
Michael
When this happens I skip to the next normal post and miss the one letter per line posts.
Always the potential for missing some 'nugget'.
Most annoying and glad someone has complained.
Tom
Thanks Tom Stokes
These 'one letter' situations are often when posters have moved beyond a discussion and into some kind of argument, so not worth reading except for a laugh. It is annoying to have to scroll for ages because a couple of people decide to have an argument and we all have to watch.
Clarkson (LON:CKN) - 13 years in my portfolio and no concerns here. Management renumeration package really is old news dredged up and there was a substantial shareholder vote against at the last AGM. Increasing Divis have long since paid me back my initial position. Amber / Red seems harsh to me Paul - perhaps another we can agree to disagree on!
Clarkson (LON:CKN) - Harsh it may be but we have to face the facts And bear in mind - if you have a look at Director share dealing - its all sales, no buys. Ok I'm still in profit and its only a small holding but I won't be topping up and definitely on the Watch list.
As a 22 year holder of Clarkson (LON:CKN, I also feel amber/red is harsh. It's a cyclical business but mostly swings between profitable and highly profitable. It maintains a cash rich balance sheet which sees it through the economic downturns and sensible dividend cover, hence able to increase dividends 22 years in a row. It's a City people business and you need the best, who might otherwise be in hedge funds or private equity, so high pay is to be expected. The amount in (genuinely performance related) bonuses is a good thing and provides a profit stabiliser when revenue falls cyclically. Their reporting of year end net cash has always made clear how much will go out in bonus payments in the following half year. The sentiment towards the shares also swings around so I've been able to enhance an already multibagging return by trimming the holding when the share price is ahead of events and topping up when it's out of favour. But the bulk of the holding is long term buy and hold. Having said all that, there will probably be better entry points than now because over £40 a share was looking toppy. I wish I'd trimmed last week but, if I had, I would not have been looking to add back until they dropped below £30.
22 years! and I thought I was a long term holder! Nicely put.
Uk services PMI joins manufacturing PMI showing strong expansion at 52.5 today, whilst the yield on the 10 year gilt continues to fall. UK valuations remain close to lows relative to their own history and to other developed economies. Once the Uk begins to outperform the US, the flows will come roaring back
Well, well, what a pickle! I have no idea where this is going. Will the Fed intervene, I doubt it unless the crockery really does hit the floor.
I have sold a few positions at a modest profit where the price looks up with events, e.g. Porvair (LON:PRV). A lovely company but Ben Stocks, the long standing CEO is stepping down and the shares are trading at a high teens multiple. But otherwise will watch and wait.
On another note, I thought that the update from Newriver Reit (LON:NRR) looked good. I recently bought Aew UK Reit (LON:AEWU) and the former does look interesting.
On a bad day in the markets I wanted to thank the numerous subscribers who responded over the weekend to the rather testy reply I received on Friday from Paul Scott following my post on 'National World (LON:NWOR). Particular thanks to Yiannos1, Callum Cowan and Tein.
I am still puzzled why I provoked such irritation from Paul who I greatly respect particularly because I have never sold a single share in National World since my first purchase in Sepetember 2021.
Hi portugull, I believe you were a bit of a escape goat. The week before last week, Paul complained on the podcast about some people starting to post their trades on this forum. I respect him but I think he's slipped this time as your post was in line with the discussion and could be adding a bit of value. In the other hand I agree with Paul about not filling the forum with empty post that don't add any value at all, and if I come out of the blue saying I've bought X stock at Y price without going any deeper that's just doesn't belong here
Hi Portugull, I don't think you did much wrong but neither did Paul. It was just a reminder to keep the discussion to things that others might find useful. Nobody else is interested in your buying prices and dates, but why you still think the stock might be good value now could be value adding. The whole 'dangers of averaging down' thing looks like a red herring to me because I don't think you were making this point when you first posted.
Anyway, we had better get you tethered up if Abel thinks you are an 'escape goat!!!'
Half way through my cycle ride, having a coffee and inspecting the damage.
I notice there is no serious volume behind any of the selling in any of my small caps.
I am deploying some cash (wish has more) today as several small caps look like they are doing a perfect retest of resistance. I expect a lower open in US followed by a bounce.
I am always interested in the psychology behind the market. The UK index is back to where it was on 23rd April. A time not so long ago that i remember posters on this board noting how great the market was.
It seems to me that perception / the current frame always dominates the 'facts'. What are others opinions on this.?
I think its clear that back in April there were decent prospects for many companies returning to higher profits quite soon - roll forward till now and it seems like most companies and now saying recovery will take longer than expected. This being the case it seems clear to me that arpil was perhaps a false dawn in that regard. Hopefuly there are still some gren shoots around now but i really dont think there is the general optimism there was back then - dont know if that data backs that up or not - ref companies upgrading compared to downgrading the last 4 months or so
Prices often retest breakouts. This applies to small caps and markets alike. If a price successfully bounces off the retest then it’s a solid sign that the market believes this is a good price to buy.
Obviously if the retest fails then the market is saying the breakout was false optimism. Personally I am buying here.
Great review of CKN excessive remuneration deserves to under the spotlight
Can anyone point a (feeling very this morning) amateur investor towards a good website/book as to how the stock market actually works mechanically? For example, I'd like to know how Buffet can sell such a big stake in Apple? Is there someone buying such a big amount somewhere?
There are many books (and I'm not trying to be be funny) including Stock Investing for Dummies and a Beginners Guide to the Stock Market). They will be very basic and I suggest you look at Amazon and read the reviews. My own personal favourite which I wish I'd have read before I got into all this, and which would have saved me a lot of money) is Robbie Burns' Naked Trader but maybe read a basics book first
as of berkshire's latest Q2 report (released on saturday), they now hold roughly ~400m (again, it's acktualy 390m) shares, or 2.5%/2.6% of the business
berkshire overall sold ~$73B of equities in the quarter which: doing some simple maths, means that the big run up in apple shares to over $200 a share occurred AFTER buffett/berkshire sold! (as $200 per apple share x 390m shares would = $78B in apple etc.)
berkshire sold 390m shares, ~$65B worth
for some context: the daily liquidity (i.e buying and selling) in apple is the best part of 50m shares i.e $10B a DAY
with that much liquidity, even he could have sold in a week or so!
hope that clears things up a bit!
How are the bond markets responding to today's equity bloodbath?
Well fixed income traders are now pricing in five 0.25% interest rate cuts by the Fed in H2'24 - compared to 1 or 2 in May.
In fact, bond markets have been shifting toward a more recessionary view over the past month vs soft landing before.
Nonetheless from Friday's US payrolls report - the employment situation is still one about weaker new hiring, as opposed to mass lay-offs.
Firms have been hoarding labour up to this point. But how long would this last in the face of sub-trend GDP?
The 'Fed Put' seems again to be well & truly back.
AJ Bell website is not working at the moment. IG seems fine as is X-O (Jarvis).
Not sure if a global meltdown and panic is going to affect
- how many people a are buying harry potter (bloomsbury)
- how many locks croma sell today
- how many tyre measuting devices transense sell
- how much fertiliser wynnstay sell
Sometimes boring asset backed small cap companies are a good place to be .
Personally I hope the magnificient seven get slaughtered and there is an outgoing of funds from these robber barons forever .. its been a long time coming ..
Only problem is planetx Elon Musk has just paid himself $54bn!!!!
Only problem is planetx Elon Musk has just paid himself $54bn!!!!
If thats the amount relating to near tenfold? (estimated) increase in shareprice then its not as if he didnt deliver well for shareholders to earn that bonus - as ever often the time to sell out in situations like this is the exact price at which those rewards become payable.
I dont remember any shareholders kicking up a fuss ref that future payout when that setup agreed and the price was much lower. Obviously now he has delivered it being the us they wil all no doubt be suing saying he is doing something sketchy - when he aint.
The Fed have been keeping interest rates high and waited a long time for the effects to show in the numbers. The Fed print on Friday finally showed it is starting to work. This is what they wanted. But it is only one month's figures. Next month might be different. The Fed are always behind the curve. Hopefully they do cut interest rates soon. Can't quite believe Bailey cut our rates before the Fed cut but I think he got this right.
Spot on planetX!
Will we see central banks be conflicted if markets keep declining?
On the one hand there will be huge calls for emergency rate cuts to prop up the markets. On the other hand, their mandate for inflation... of which they need to see hard data (ie very delayed).
John Wood (LON:WG.) Sidara has droped plans for takeover, looks like a hefty drop at the open (-35%+)
Their reasons seem to be centered around global markets instability rather than company specific. Could be a good buying opportunity after a big drop.
Possibly a time to add to Japanese investment trusts like JPMorgan Japanese Investment Trust (LON:JFJ) - need to take a look today. Major strengthening of the Yen also needs to be taken into account. Global weakness due to Japanese invetors taking money home and fears of US recession. Could be an interesting week, just as traders are trying to enjoy sitting on a beach somewhere!
EDIT - Some Japanese investment trusts are down big time this morning. They are not down as much as the Nikkei due to the £ effect. Took a position in Schroder Japan Trust (LON:SJG) but others look equally of interest. Depends on whether you want a dividend or not. My biggest position is JPMorgan Japanese Investment Trust (LON:JFJ) which is merging with JPMorgan Japan Small Cap Growth & Income (LON:JSGI) - it was down 10% at the open, but seems to have recovered a bit already so missed the max drawdown for now. Lots of Japanese investment trusts on a discount to choose from!
Topvest I sold out of Japan Friday- suspect a bit further to fall . I have also sold out of my favouirite markets-India and Vietnam. India has- like Japan- a lot of local investors who are relatively new to investing. They might panic . Vietnam is always a bit volatile, but historically August has not been great for the market according to Vietnam newspaper.
CC Japan Income and Growth Trust (LON:CCJI) is a pretty solid performer in the Japan IT sector and down around 10% this morning - temped to have a nibble. Also pays a decent yield.
I would agree but it is timing
Yes it does feel a bit early to be rushing in - I have a bit of cash on the sidelines but will probably wait a few more days before making any additions. Also in the IT space Pershing Square Holdings (LON:PSH) looks quite interesting after a sharp fall, probably not helped by the news that Ackman has pulled the launch of his new US funds and a big fall in his biggest position UMG which makes up around 25% of the portfolio.
I will take Pauls Lead and avoid trying to say I know what's going on or how it will end. However Im sure I have managed to miss out on some nice stock situations... mainly fearing they had run too far. I can think of 5 or 6 off the top of my head.... so I will be drawing up the shopping list.
This all seems to have happened rather quickly, and VIX is already trading at mid 20s, maybe higher... normally a sign of extreme stress and therefore a buying op. On the negative, Crypto losses look extreme. I have no idea if this feeds into other assets but normally large losses in one thing spread to another.
Anyway, it's August, everyone's away, and not much has changed IMO. Hard hats on and good luck all.
I will update myself that VIX appears to be in the 40s already this morning. VIX can do weird things.... a lot of funds have been selling options and collecting premium. This has an effect on VIX... which for most of this year has been very low against a backdrop of elevated Geopolitical risk. Buying stuff you like when it's on offer esp with VIX above 30 "normally" works out quite well. It looks like a VIX shock....and that means positioning ...which will blow over... but not till the funds in trouble close their positions. Anyway, on the single measure VIX it looks to me like we are already at a five year high....ie not seen since the Covid collapse.
Any more macro from you throughout the day would be appreciated your one of the best on Stocko with the geo political stuff imho
Massive carry trade unwind upon the beginning of Fed and BOJ policy divergence. Very weak economic data in the US (initial jobless claims and nonfarm payrolls last week) mean the Fed are now expected to cut 6 times by January. Meanwhile the BOJ hiked by more than expected last week. Yen has strengthened from 161 to 142 USD in one month (+2.5% today which is huge for a major currency). The Nikkei has just had its worst day since 1987. The ripple effects are being felt across the globe. I just hope it doesn't trigger a LTCM moment from some major institution.
Absolutely. Sharp rise in JPY/USD causing a massive unwind of Yen carry trade positions. Expect massive US sell off to continue.
That’s what happens all the time in over leveraged markets. I agree with Paul that if you hold good stocks and do not use margin then you have nothing to worry about. I expect the FED to intervene with providing liquidity and/or emergency rate cuts this week if this continues at the current pace.
Nikkei lost all the 27% year’s gains in just few weeks and is down for the year!
All the best
With the increase of the £ recently, and the talk over the past month of Japan finally becoming more investable, is this an opportunity to open a global and/or Japan heavy ETF?
Unfortunately Gbp Jpy has actually gone the other way... 208 down to 182 in just 3 weeks .... not as large a move as the fall in the Nikkei, but unhelpful nonetheless
Personally as already stated here last week that I am 75% cash I will be looking across the pond at some US growth companies (with healthy balance sheets and no debt) if they get battered over 15-20% during the opening. Have in mind that they have already lost 20-25%.
All the best
Companies with healthy balance sheets and no debts, eg: magnificent seven!!
Except Tesla (NSQ:TSLA) !
Amazon.com (NSQ:AMZN) and NVIDIA (NSQ:NVDA) on the radar.
All the best
I was topping up some Amazon.com (NSQ:AMZN) on Friday evening. May prove to have been very rash & premature (a small nibble, I have plenty of dry powder).
We are looking at something like 28x earnings a year out, for around 20% earnings growth? (I'm aware of the drawbacks of P/E ratios, but they remain a useful shorthand).
These are not the sort of numbers I recall from the dot.com bubble. Of course the earnings forecasts may well be brought back and regulators may intervene more aggressively. But on an initial glance the likes of Alphabet (NSQ:GOOG) are not on outrageous valuations - you pay more for Walmart (NYQ:WMT) .
Yes, the market has taken fright at AI related capex, but just look what happened when Meta Platforms (NSQ:META) rowed back on the metaverse.
NVIDIA (NSQ:NVDA) a stretch too far for me..but I've been too cautious on that one for a long time!
Amazon.com
These are not the sort of numbers I recall from the dot.com bubble.
You shouldnt expect that they should be - you always have much more potential for exponential growth at an early stage company worth $1 bill/$10 bill or $50 bill than you would do for a company valued at $1.6 trillion. I am not saying amazon is expensive just thats its ridiculous comparing expected pe's now to 20 years ago - as growth in numbers for Amazon next 5 years will be vastly different from 20 years ago - when they reach marketplace saturation i know not but its reasonable they will do some day . On the plus side back in the day their was probably risk of total failure - i think they have at least put that to bed now. Back then it was also clear for example that amazon were reinvesting profits it could have been made into new income streams so the p/e numbers back then didnt reflect the realities of how strong the company was trading in some areas of its business.
In response the rmillarree regarding valuations....
I'm not talking Amazon.com (NSQ:AMZN) now vs amazon a decade back, nor am I thinking Amazon now vs early stage companies.
The appropriate comparison is perhaps Amazon now vs Cisco Systems (NSQ:CSCO) in about the year 2000. There was nothing early stage about Cisco, or indeed all the telcos.
Of course, things didn't end happily for Cisco Systems (NSQ:CSCO), Nortel Networks or Vodafone (LON:VOD) investors, but that is a different debate.
Getting hold of reliable P/Es from decades ago is tricky (you tend to get the historic number, not the fwd looking P/E investors we considering at the time) so I'm not going to quote numbers.
I just sense that if we are in a bubble for the likes of Alphabet (NSQ:GOOG) and Amazon.com (NSQ:AMZN) , then we have an earnings bubble as much as a valuation bubble - which may indeed prove to be the case, but it is very different to two decades ago.
Nobody was comparing Cisco Systems (NSQ:CSCO) to Walmart (NYQ:WMT) !
The appropriate comparison is perhaps Amazon now vs Cisco Systems (NSQ:CSCO) in about the year 2000. There was nothing early stage about Cisco, or indeed all the telcos.
Apologies i got the wrong end of teh stick ref your post,
I would agree that there was more excessive over valuations in the dotcom space back in 2000 that is generally the case now - deffo less froth in the market now than back then for sure thats easy to agree on. Being frank with the benefit of hindsight prices back then were crazy for a while - that should have been fairly clear from the ridiculously quick appreciation of valuations in 1999 and 2000 - albeit no one knew how good the future might be with the reapid adoptance of tech/it at that time
First single share i bough was sage when it had subsided 2/3 from its peak valuation - i though yep that as decent price to pay 1/3 of peak price - shareprice went down another 60% from my buying price so my falling knife strategy failed miserably at the back end of 2000 - albeit having picked a decent company sage eventually exceeded its dotcom peak 23 years later ! - nice 8 bagger from the low point albeit 23 years is a long wait !
Being a tight wad i mostly missed out on most of the boom in tech as i refused back then to pay a pe's of 100. pe's now deffo much more reasonable than back then - that has been the case for some time if you can time it right - i seem to remember apple being on pe of closer to 10 than 15 a few years back - thats probbaly when buffet loaded up.
yes it really ought to be classified as The Magnificent Six now but obviously that title doesn't appeal so much
Famous 5 / Fantastic 4... More seriously, this is not 2000 over again.
The AMZN P/S ratio is currently 3.27. Perhaps a bit high (NXT is 2.11 from the same source) but not insane. (I held in the early 10s before cloud was a thing )
There is a quote on the .com bubble i keep (https://www.bloomberg.com/news...)
At 10 times revenues, to give you a 10-year payback, I have to pay you 100% of revenues for 10 straight years in dividends. That assumes I can get that by my shareholders. That assumes I have zero cost of goods sold, which is very hard for a computer company. That assumes zero expenses, which is really hard with 39,000 employees. That assumes I pay no taxes, which is very hard. And that assumes you pay no taxes on your dividends, which is kind of illegal. And that assumes with zero R&D for the next 10 years, I can maintain the current revenue run rate. Now, having done that, would any of you like to buy my stock at $64? Do you realise how ridiculous those basic assumptions are? You don’t need any transparency. You don’t need any footnotes. What were you thinking?
P/S = 10 was a thing then.
The last time I looked and gasped was the Autonomy trial a few years ago. I worked out HP paid a P/S ratio of *13* for Autonomy.
All ratios have their place. Hope this reduces your stress a bit.
Oof. Don’t you just love irrational price moves in good companies. This time last week I triggered the 25% TFLS in my SIPP. Incredibly lucky timing.
I have two pensions, and did the same because I don't trust the Government and wanted certainty before any budget.
AJBell paid out within days, Scottish Widows still waiting, so a bit Ying and Yang for me. At least I have some cash but is today a good day to catch falling knives of good companies?
I have two pensions, and did the same because I don't trust the Government and wanted certainty before any budget.
Same reasoning, but very fortuitous timing to be cashing in at near maximum SIPP valuation before a market sell off. Will buy some Gilts, recycle some into the market, and buy a new kitchen!
Generally in pensions, if the govt says "no more TFCS from a-day", any rights you had at a-day are protected.
(Hoping that past performance is a guide to the future)
Generally in pensions, if the govt says "no more TFCS from a-day", any rights you had at a-day are protected.
Yes, but I needed the funds, and most importantly, I don’t trust governments. But let’s not get into that here. Meanwhile, some interesting stuff selling off. Spectra Systems (LON:SPSY) may be getting a top up later.
I took a TFLS from my SIPP at Hargreaves Lansdown earlier this year. They took over 4 weeks to pay up despite chasing them. False promises and missed deadlines. The highest fees in the industry and the worst service. Not a good policy to preserve AuM.
Nice one and you may have beaten Rachel to it well
Could it be a buying opportunity in Japanese trusts or stocks soon? Buy at the bottom or is there more lows to come??
Graham.
I am afraid the only thing I know about Japan is its food and I love it!
All the best
(((Shudders!))) I remember this well (margin calls) from a previous life!
Another point to remember for margin traders, is that when markets go haywire, the spread bet/CFD companies often hike the margin percentages required to keep positions open.
I vividly remember cutting positions on my spread bet accounts during the various market meltdowns in 2008, only to wake up the next day and find some of my small cap positions had been increased from 20% to 40% margin. So one broker rang me up and demanded £500k be transferred immediately. That was an interesting day.
As I have proven many times, it's no good trying to tough it out with geared positions, they need to be cut immediately unless you're only using a small amount of gearing. That's if you can sell at all. The bid often dries up, and it's not possible to sell illiquid positions held in spread bet accounts.
As I've mentioned here many times, over many years, gearing is an absolute killer when markets take a dive.
Regards, Paul.
P.S. I should also add that forced margin sellers can hand superb bargains on a plate to patient, ungeared investors sitting on cash.
Agreed Paul - wise words
This is probably one of the reasons why Warren Buffett (re Berkshire Hathaway (NYQ:BRK.A) sold a net $75.5bn of stocks in Q2'24 - mostly coming from the disposal of shares in Apple (NSQ:AAPL) ($50bn+) and Bank of America..
In turn boosting BRK's June cash reserves to a colossal $276.94bn - or 30% of its market cap. Meaning he's now perfectly placed to mop up any distressed sellers in quality firms at attractive prices - & even perhaps act as the 'bank of last resort' which occurred during the 2008-10 GFC (eg Goldmans)
My morning smallcap tweet: Back with a whimper
Cordel (LON:CRDL) Guild Esports (LON:GILD) hVIVO (LON:HVO)
◄Cordel (CRDL)► wins contract to provide a comprehensive assessment of Amtrak's Metro-North corridor. It will "leveraging state-of-the-art LiDAR technology". Is it disruptive AI though? No $$$. [SP=4.5 Cap=10m]
◄Guild Esports (GILD)► LoI with DCB Sports for latter will acquire 100% of the assets of Guild Esports as well as assuming all disclosed liabilities. [SP=0.14 Cap=1m]
◄hVIVO (HVO)► intends to cancel trading on Euronext Growth. [SP=29.7 Cap=202m]
Buy on the sound of cannons?
After more sabre rattling between Iran & Israel over the weekend - coming of course on top of US slowdown fears & a tech rout - then (not surprisingly) the major equity indices are all flashing 'bright red' again this morning (see below).
VIX jumps to 34. In particular it's been another tough 24 hours in Japan for the Nikkei 225, down >12% today. Unwinding of the Yen carry trade is having an impact too. Definitely risk off!
Nikkei is now most oversold since Covid and back to major support so I suspect a bounce from here.
Personally I’m sitting tight and going cycling (not looking at my screen for a few hours!).
Morning All,
Paul, what's your thoughts on current macro situation?
Nasdaq futures down 6% as I type!
Hi JohnDoe2378,
Paul, what's your thoughts on current macro situation?
No specific view on the macro conditions. The UK economy seems to be in slow recovery mode, and data seems quite reassuring to me. Although we're not yet seeing any recovery in some key sectors that we follow here, like staffing companies, or building supplies. I would have expected them to be reporting green shoots, but they're not so far, at least at the small caps end of the UK market.
As regards market volatility overseas, we've had a somewhat frenzied tech bubble again recently, so a correction to wash out the excesses there looks a good thing. I see the bitcoin nonsense is also plunging.
We've had a lot of momentum stocks rise probably too far, so if I held any of those, I'd be selling on the opening bell today.
Good luck!
Regards, Paul.