Small Cap Value Report (Mon 5 Feb 2024) - PRV, CMCX, BIDS

Good morning from Paul & Graham!
Did we miss anything good in the frenzy of trading updates in January? We've got a bit of spare time this week, as newsflow is quietening down, so I've come up with an idea! If you would like us to look at a small to mid cap share, and you can make a good case for it that engages our interest, we'll review it here! Reader suggestions in the comments below, with the most thumbs ups, we'll review the top 3 this week.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Other morning movers -
t42 IoT Tracking Solutions (LON:TRAC) - Nanocap. Up 45% on agreement - potential revenue of $7.5m, but “no guarantee” of quantity, timing, or revenues! Desperately weak bal sheet, needs a fundraise. Still hasn’t reached agreement with holders of CLNs.
Superdry (LON:SDRY) - continues rising, up 12% to 52p, on hopes that Dunkerton might bid for it with private equity backers. It’s possible, but why would they be generous to minority shareholders, when the company’s in such a mess?
Summaries
Porvair (LON:PRV) - 660p (pre-market) £305m - FY 11/2023 Results - Paul - GREEN
One of my favourite shares - quality at reasonable price probably sums it up best. As expected, results have come in ahead of modestly set forecasts. Lovely balance sheet. Cashflows mainly being used for bolt on acquisitions. Modest divis. Outlook sounds fairly confident. I continue to view this share positively as a long-term investment idea.
CMC Markets (LON:CMCX) - 149.6p (+13%) (£419m) - Cost Reduction and Efficiency Plans - Graham - GREEN
CMC appears to have caught the market by surprise with the announcement of a 200-person reduction in headcount, leading to £21m of annualised savings from next year (FY March 2025). Revenues have surprised to the upside and now costs to the downside.
Bidstack (LON:BIDS) - 0.19p (-65%) (£2.5m) - Cost Reduction and Efficiency Plans - Graham - RED
Ominous news here, looks like it's heading for disaster.
Paul’s Section:
Porvair (LON:PRV)
660p (pre-market) £305m - FY 11/2023 Results - Paul - GREEN
Porvair plc ("Porvair" or the "Group"), the specialist filtration, laboratory and environmental technology group, announces its results for the year ended 30 November 2023.
Record revenues and profits.
Background - Porvair has been on my radar for years, and I added it to my top 20 list of ideas for 2024, being impressed with its multi-year performance, and the valuation had come into reasonable range (after previously being over-priced). Our previous 3 comments here -
3/7/2023 - AMBER - pricey at 664p (PER 19x), good H1 results & outlook.
15/9/2023 - GREEN - 598p good entry point? Likely to beat forecasts.
5/12/2023 - GREEN - 624p - trading ahead of expectations. Acquisition.
FY 11/2023 results -
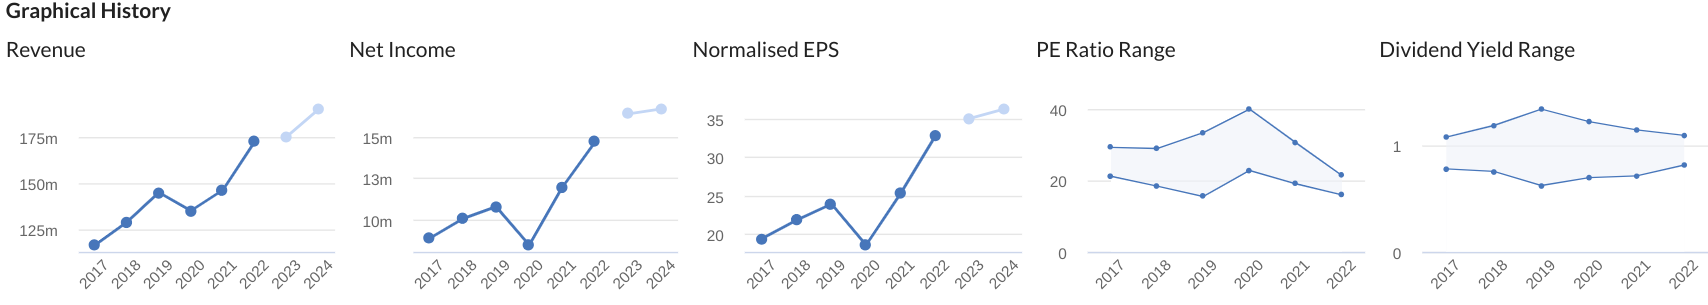
Revenue up 2% to £176m
Adj PBT up 10% to £21.4m - attractive 12.2% PBT margin
Adjustments are small, and relate to acquisitions (costs and amortisation), which is OK.
Adj EPS is 37.2p both basic & diluted (no share options?) PER 17.7x
This looks an earnings beat, with 37.2p being ahead of 35.0p consensus.
Dividends small, but well-covered at 6.0p (full year). The dividend-paying capacity would be a lot higher, but cashflow is prioritised to fund acquisitions instead.
Strong balance sheet NAV £140m, less £83m goodwill = NTAV £57m.
Net cash (excl leases) £14.1m
Cashflow is healthy, and is used in this order - acquisitions, capex, dividends.
Outlook -
After a record 2023 the Board is optimistic for 2024 and beyond. There is much to look forward to as the year unfolds: opportunities afforded by acquisitions; strong order books in aerospace and petrochemical; demand recovery in Laboratory; and new products in Seal Analytical and elsewhere. In the first half of 2024 these should offset near-term headwinds of adverse foreign exchange and de-stocking in US industrial consumables, which seems to have a few more months to run.
The Group's fundamental demand drivers have not changed. Porvair remains well positioned to take advantage of tightening environmental regulation; the growth of analytical science; the need for clean water; the development of carbon-efficient transportation; the replacement of plastic and steel by aluminium; and the drive for manufacturing process quality and efficiency. It is these trends that drive the Group's consistent longer-term trading record and enables the Board to look ahead with confidence.
No broker updates available.
Paul’s opinion - good results, very much as I was expecting. We’ve been pointing out here for a while that forecasts looked beatable, because strong H1 results and a positive Q3 TU were already in the bag.
I remain of the view that this looks a high quality business, with a conservative balance sheet providing safety, that recycles most of its cashflows into making complementary acquisitions within its areas of expertise (hence less likely to make mistakes).
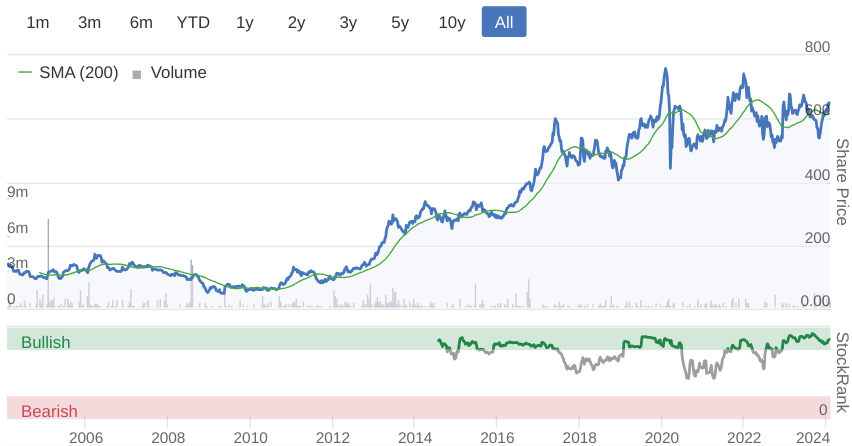
It’s not the cheapest share out there, but given the fairly upbeat outlook, it really should manage 40p+ EPS in FY 11/2024, so at 660p it’s now valued at about 16.5x current year earnings, which I see as an attractive price for a good business, with a hold forever type of investment strategy. Shares have 10-bagged in the last 14 years, so patience has been a real virtue here.
I’m happy to stay at GREEN.
Graham’s Section:
CMC Markets (LON:CMCX)
Share price: 132.8p (pre-market)
Market cap: £372m
This is another positive update from a share which found itself on both Paul and my favourite ideas lists for 2024.
The key point about CMC’s current situation is that it’s trading at a point of extreme operational leverage: small incremental revenues can drop down to the bottom line and make all the difference between a profit and a loss. (This stands in contrast to companies who already have high operating margins, so that small increases in revenues don’t have a large percentage impact on their profitability.)
At the interim results (covered in November) CMC reported a £2m loss on net operating income of £123m.
In January, as covered by Paul, net operating income guidance for FY March 2024 was upgraded from £250-280m to £290-310m.
And today we have news on the cost front. Unfortunately it’s not good news for staff, as CMC are planning a 17% reduction in headcount:
In its interim results announcement on 16 November 2023, CMC indicated that the business was reaching the peak of its investment cycle and a cost review was planned for H2 focused on driving efficiency through its global operations. The review has been successfully completed and as a result the Group will be reducing global headcount by approximately 200 positions, representing circa 17% of existing headcount.
Financial impact: a one-off cost of c. £2.5m in the current year, but annualised savings of £21m in FY 2025.
This news was not yet priced into forecasts, as it represents “an 18% reduction against consensus staff costs”.
Today’s update also confirms that a variety of other cost-saving/efficiency measures have been taken and continue to be targeted, in addition to staff reduction.
Trading remains in line with the previous update.
Graham’s view
Analysing shares can be simple sometimes (maybe analysis is best when it’s simple?).
The investment thesis here has consisted of three simple ideas: revenues can improve, costs can stabilise, and then the operational leverage will see profits pick back up again.
First, revenues can improve cyclically when volatility picks up off its current low levels. Here is the VIX volatility sentiment, which as you can see has been quite depressed of late:
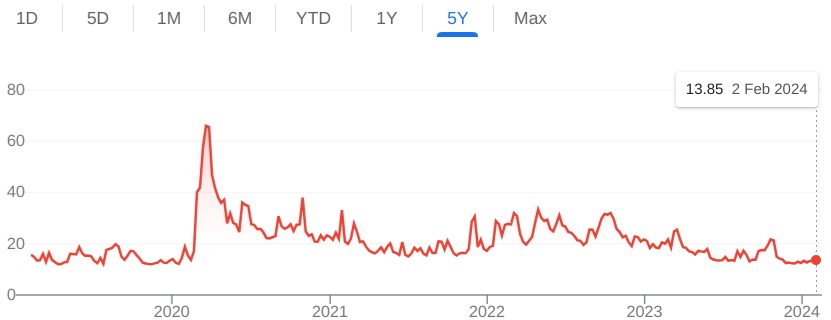
The recent trading update hinted at sentiment recovering to some extent, with higher levels of interest in trading, even without much volatility in the market.
On the cost front, it was flagged by Lord Cruddas, and we were reminded in today’s update, that CMC’s investment cycle had “peaked” as it rolled out new products both at home and internationally.
However, I must admit that while I was optimistic that costs could be reduced, I did not expect such a radical change as a 200-person reduction in headcount. That £21m annual saving could transform results, if it’s true that this labour is surplus to requirements now that the company’s pace of product roll-out is slowing down.
Both forces (rising revenues and falling costs) appear to be moving in the right direction, so clearly I’m going to keep my positive stance on this share. Hopefully FY March 2025 will be the year when we see CMC returning back to healthy profitability as it was before.
Bidstack (LON:BIDS)
0.19p (-65%) (£2.5m) - Cost Reduction and Efficiency Plans - Graham - RED
The wheels may be coming off this video game advertising company for the final time, as the company notes procedural difficulties in relation to planned funding from its largest shareholder, Irdeto. Irdeto has thus far failed to provide documents needed in order to facilitate a legally required vote on their proposed £2.4m convertible loan note. Oddly, Bidstack has already drawn down £0.6m under the facility, but will not draw down any more tranches given the circumstances. I wonder if they are planning to use the £0.6m they’ve drawn?
They have also received EUR €3m from commercial partner Azerion to settle a long-running dispute and set up a new collaboration between the two companies.
Despite these cash inflows, Bidstack’s working capital position “remains tight”. The cash balance is only £1.4m which is thought to be sufficient to last until the end of March. Restructuring advisors have been appointed and asset sales are possible. I wouldn’t bet on anything being left for shareholders when all is said and done. This much talked-about stock appears to be heading for a sad end.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
Anyone else noticed that things are getting really bad in China? SZSE Component Index is down 33% in a year, 16% in 2024 and now at 5-yr lows. Trading halted earlier on today. It's a bit surprising that UK and US markets seem to shrug-off a melt-down in the No. 2 world economy. This looks serious.
What's happening in China is net positive for the West economically...financial market contagion very unlikely as the links were never that strong and they have been made more tenuous in recent years with all that has followed post HK policy shift
MPAC (LON:MPAC) anyone know why they jumped today? Was there a tip I missed over the weekend per chance or a.n.other rumour?
Sunday times
Thanks Yiannos - much appreciated.
Only an 80% rise late by the sunday times….but better late than never :-)
Paul getting bored maybe?? Plexus Holdings (LON:POS)
Paul getting bored maybe??
Being frank what Paul does next here and when is his business - i kinda feel is kinda bad form to over speculate in that regard. Its time consuming enough to write up these daily reports without having to answer what could very well be idle speculation.
It's entirely idle speculation, and Paul has absolutely no obligation to reply, that isn't what I sought.
When you have a prominent commentator build a good position, plus lots of followers invest, when news flow dries up people get bored and start selling for fresh opportunities.
Just part of the cycle that should be discussed
Of course people drift away in between news. That's what provides opportunities to transfer money from the impatient to the patient!
I'll update on Plexus Holdings (LON:POS) [I hold] when there's some fresh news, same as with anything else.
Take the good with the bad. On the same day by large holding in CMC Markets (LON:CMCX) went up 18% , my significant position in Plexus Holdings (LON:POS) is down about 12%.
Many thanks to the individual who shared insights on Goodwin (LON:GDWN) recently. Despite my efforts to locate the post in various discussion forums, I've been unable to find it again. I had never come across Goodwin before reading the post, and was prompted to delve into the company. Goodwin's latest report I came across was really impressive – its contents were clear, precise, and easy to understand. Reading the report left me with the conviction that Goodwin could be a solid long-term investment. It's not often one comes away with a feeling of conviction after reading a company report. About the company
“Goodwin PLC is a mechanical and refractory engineering company. The Company specializes in the design, manufacture and supply of products and solutions. The Company’s segments include Mechanical and Refractory Engineering. The Mechanical Engineering segment is engaged in casting, machining and general engineering. “
Some extracts from the latest report:
“After due consideration, from listening to shareholder enquiries at the AGM, we recognise the importance of providing more frequent updates. Considering our Group's diverse and complex operations, we have decided to introduce quarterly trading updates to keep our investors more informed.”
“The new Calciner at Hoben International Limited has proved to be approximately 15% more efficient than the original Calciner due to the strategic design modifications that were incorporated into the initial design. This efficiency improvement has translated into enhanced productivity and energy cost savings. Hoben's sales of Soluform concrete bags continue to grow and there is wider adoption amongst some project engineers who are increasingly favouring it as their product of choice.”
“Keeping one eye on the future, our patent pending polyimide resin production company, Duvelco Limited, remains on track to have its production plant commissioned and operational by June 2024. All the major capital expenditure has been completed with the majority of any spend left being labour to finish off the wiring, pipework and commissioning. All initial chemicals to make up to 30 tonnes of polymer resin are on site, so there should not be any large increases in working capital affecting the Group's future cash position, as it should become self-funding once operational.”
Searching the Stocko forum I also came across
“However, for investors looking for businesses with the ability to deliver long-term compound growth, I think Goodwin could be worth further investigation.” Roland, 22 Dec 2022
“...personally I wouldn’t want to chase the share price any higher, without having much more detailed, and reliable knowledge about what level of profits we should expect to see in the coming few years. If any readers have more detail on that future outlook, do please share it, and what your share price targets are? I believe we have some very knowledgeable members here on GDWN.” Paul, 11 Aug 2023
“The UK steel industry has been under pressure for decades, hit by rising costs, falling demand and intense competition. Goodwin runs one of the oldest foundries in the country but this robust family business shows what can be done with ingenuity, clear sight and true grit. At £50.40, these shares are a long-term buy.” Midas Verdict, 11 Dec 2023
I was also highly impressed by the detailed plans drawn up by the company in setting up Develco.
Roland's gave a neutral stance on 22 Dec 2023 but noted "With Goodwin, I do see mention of intellectural property and interesting patents. Along with the track record and the positive culture, I'm inclined to think that it's worth a considerably more expensive rating than the average engineering stock."
Bear points mentioned by Roland include possible order delays from Goodwin's customers, net debt position making share price more sensitive to doubts on trading performance, modest capex (imminent cash performance improvement indicated by company).
I think the decision to introduce quarterly trading updates to keep investors more informed will help bring the company to a larger number of investors attention. Also worth mentioning a comment by rhomboid1 on 20 Dec 2023:
"…it’s important to note that they are now at most 6 months away from the launch of a new polyimide range of products designed for extreme applications where it’s unparalleled thermal range & self lubricant characteristics will command a very high price…they’ve designed it to slot straight into use cases such as aero engine components, semi conductor manufacturing, & glass bottle manufacturing where a chemically identical competitor is now out of patent. They are already in communication with prospective customers & today we learnt that they’ve raw materials for 30 tonnes of output..if their aspirations are realistic this 30tonnes alone will in itself be by far the largest part of the business in valuation terms….the costs of developing this have largely been absorbed…the benefits will accrue over future years."
I have bought Goodwin (LON:GDWN) today as a conviction share.
Not sure which piece you mean exactly but Rhomboid is than man to follow on all things #GDWN also on Twitter as Rhomboid1 (Rhomboid1MF) - would highly recommend following (as well as his other RNS etc coverage)
and his tweets are hilarious!
Thanks Adam
Anyone know why Plexus Holdings (LON:POS) is falling off a cliff today?
Reverse FOMO?
I sold mine a few days ago following the strategy explanation from Plexus Holdings (LON:POS) which made it seem that they were investing to strengthen their rental offerings. That didn't feel like the growth company I had thought I was investing in. Maybe others have a similar opinion
Plexus Holdings (LON:POS)
is the opaqueness with regard to ability of company to churn out profits not a very obvious reason for the reversal of fortunes here - particulalry if the reason for the spike upwards was that higher profits were expected before the deal to improve the balance sheet was announced. The reasons for where they are now seem sensible nore i am not knocking the decisions they have made to improve the balance sheet but why should anyone expect shareprice to remain bouyant in absence of concrete news ref decent profits particularly for ye 30/6/2025.
Ignoring the spike of enthusiasm the shareprice is still above levels it was at 6 months ago - so its not as if the company has shown no porgress. Easy come easy go with shares like this when they are steaming in one direction or the other.
Tim Martin having to reply to another lie from the media. Time Out accusing J D Wetherspoon (LON:JDW) of "During the pandemic, (Mr Martin) also initially refused to offer staff furlough payments, before public outrage caused him to backtrack" as well as other fabrications.
I dont hold shares in Wetherspoons but good to see him push back against this, every company should do it.
"This statement is entirely fictitious. Mr Martin at no stage said that the company would not pay its furlough payments. All staff were paid weekly/monthly throughout the pandemic - not one payment to employees was missed or delayed."
Wetherspoon chairman Tim Martin said:
"Even though Wetherspoon has received enough corrections and apologies from the media to fill a magazine (''Does Truth Matter?'') in respect of the sort of misrepresentations contained in the TimeOut article, they continue to be repeated- and to be believed, as a result, by a percentage of the public. By this process "the lie becomes the truth". However, there is no doubt that articles such as the one in TimeOut gradually undermine the integrity and reputation of the press."
I have an issue with the comment "gradually undermine the integrity and reputation of the press"
I think we are well past that and the press generally have little integrity and zero reputation.
I am sure there will be one or two honest members of the press, but you will be hard pressed to find many.
Over my many years of working there have been numerous industries that have become the target of peoples ire; 2nd had cars salesmen, estate agents, utility suppliers etc etc. I now feel that the press themselves, by compromising on their own standards of integrity and instead looking for a quick sensational story have failed live up to the standards set by their predecessors.
Truth, facts and validation have all been sacrificed in a search for a quick story. There will be a few decent journalists left, but on the whole, whenever I speak to the press in my job I know that I will never get a decent hearing.
Wetherspoon chairman Tim Martin said:
"Even though Wetherspoon has received enough corrections and apologies from the media to fill a magazine (''Does Truth Matter?'') in respect of the sort of misrepresentations contained in the TimeOut article, they continue to be repeated- and to be believed, as a result, by a percentage of the public. By this process "the lie becomes the truth". However, there is no doubt that articles such as the one in TimeOut gradually undermine the integrity and reputation of the press."
I am sorry WoSS but the statement made me chuckle - the irony.
My sister in law works for Wetherspoons. She is very happy there as are her work mates. Tim Martin visits venues each week and the staff always look forward to seeing their boss.
Vertu Motors (LON:VTU) down nearly 4% today so have bitten the bullet, given the negative news flow on car market, financing, etc, and sold at small loss. Given my recent investment efforts that will guarantee that an acquisition at a significant premium will happen in the next few weeks!!
Vertu Motors (LON:VTU) Used car prices are key and they stabilised in January so hoping no further nasty profit warnings, but certainly not ruling it out. Will continue to hold on the basis that strong bid interest and asset backing should (in theory) put a floor on the share price. I also like to remind myself that all the other dealers have been snapped up at far higher valuations than their current market cap, and would like to think the various acquirers know a lot more about the sector than the average investor (who ultimately determine the share price). Either way will be interesting to see how it plays out this year.
Agreed Vertu Motors (LON:VTU) is a quality company that is a long term hold for me . Expect the share price to stay in the same range for a while but pick up steam again, once the negative sentiment re used car prices changes .
Paul. One small co share I’d be interested in your views on would be Incanthera (OFEX:INC).
It’s pre revenue, and the directors have behaved honourably by suspending remuneration to conserve funds.
In December it announced a potentially transformational deal to sell its skin care product in the stores of major retailer AS Watson. The RNS Implies profitable H2 for 2024 and the treat overall. Run rate for 2025 will clearly be better. This interview with the Chairman doesn’t give figures but he comes over very well and his enthusiasm is obvious.
&pp=ygUOSW5jYW50aGVyYSBwbGM%3DI bought too early at 13p in 2021 but topped up at 6p after the December RNS. it seems hugely de risked now and could have multi bagger potential. I’d liv you to listen to the short interview and give your thoughts. It might appeal to you.
Incanthera (OFEX:INC)
Thanks Poker111. I nearly skipped over this as pre-rev is not my thing. However I am glad that I read your intro and watched the video.
The chairman comes over well. I have a personal interest as I am a multiple sufferer of skin cancers over some years and take B3 tablets on a daily basis on orders of my dermatologist. The new product could be a big seller and the production farm out and the retail outlets now agreed sound very realistic plans.
Mark
Hi Cricketfan
If I was you I will have a proper and detailed researched on Incanthera (OFEX:INC) -where it is listed , the number of shares traded every day and its previous history!
Thanks yiannos1.
Incanthera (OFEX:INC) will certainly get the due diligence treatment before it gets my money!
Cheers, Mark
Could perennially cash burning Kromek (LON:KMK) be about to change spots?
Looks to me like they are very close to hitting cash flow break even with recent slew of take up on the CTZ side including RNS this morning. Brokers have a seemingly fanciful 27p target or 4* current price. I would say that appears to be the trade sale value of the IPR rather than earnings/PER based. The key for this business is to be cash self sufficient (ie after R&D). If it does that then the value is clearly wrong as it has high strategic importance but it has to get house in order and achieve cash profits for that ever to be realised.
Starting to look investable again if my maths is correct and that b/e cash frontier is about to get breached for the first time. Interesting one to watch if you can get over the history.
I thought this was an interesting article that helps explain the performance of the stock market over the last 10+ years
Having worked for the fund manager of an occupational pension scheme, I saw this sleight of hand by Gordon Brown would have huge consequences, as the amounts involved covered a substantial proportion of management fees. Little wonder that it accelerated the decline of defined benefit pension schemes.
I put forward Venture Life (LON:VLG) as one of those that was overlooked in last week's blizzard of results so vote this comment up if you would like it reviewed in today's 'top 3' offer.
Although the preclose statement was inline the fact that this morning the sp is 20% above close the day before the rns suggests there is something interesting here.
On the day I wrote:
"Inline update from Venture Life (LON:VLG) this morning. The best feature is the reduction in debt which had increased due to aquisitions. A note from Cavendish https://www.cavendish.com/rese... points out that that revenue growth was delivered completely organically, a first since 2019. Free cash yield is estimated at 15.8%
Graham gave this an amber last July saying "I am cautious when it comes to my interpretation of the company’s EBITDA and cash flow claims" but perhaps the balance sheet is in better shape now".
Later in the day the CEO was interviewed here and it sounded as if the potential of some of the brands acquired may not have been fully reflected in the sp.
Venture Life (LON:VLG) was highly priced in the early pandemic on the potential of mouthwash Dentyl to deal with the virus but came back down and has drifted since:
I think they also achieved a very high margin during 2020 which is why it peaked then - I assume due to anti bacterial handwash. I haven't looked at Venture Life (LON:VLG) since January 2022 but my previous concerns were
Director sells at the top (90p) in Dec 20 at same time as placing
It raised funds but then no acquisitions for ages (maybe raised funds at the top though but seems to have been to support an exit for directors?)
Shipping problems to China 2019
Chair and CFO left the company in December 21 following more warnings.
Also, looking at the Stocko data the debt isn't insignificant - are you happy this is manageable?
Venture Life (LON:VLG)
Tortoise - yes, the pre 22 concerns you list were bad. Downing held a stake and you can hear Judith McKenzie on 11/1/22 echoing that by listening here (probably as forthright as she dare in public!). She wanted better "checks and balances" so when the new Chair was announced on 17/5/22 and one of the non-execs was replaced on 10/10/22 I could sense her hand at work!
The raft of acquisitions was paused after that of Earol in Dec. 22 and Cavendish expects net debt to come down from £16.6m at the end of 22 to 11.7m for 23 and 5.3m for this year. Of course, there will be more aquisitions at some stage and one attraction of this company is the spare capacity in their existing factories so that if anything new is brought in then margins are increased as overheads are spread.
Re Venture Life (LON:VLG)
What investors need to weigh against any perceived value is:
So go ahead punks....do you feel lucky? ;)
Maybe the sp is going to go up a lot. I don't like the company due to its history so I won't play (at least until mgt goes). High odds they have the same 'character' so this run at cashing out share incentives you at least want to make sure that investors get the same benefit.
PS There's a pre history on their Italian production capabilities and what the deal for that was and the implications for the business but can't be bothered to delve further into that right now.
Isn't this the share that was sold by Directors at 90p shortly before crashing to 30p. There is a lot of risk out there right now and this is one I would rather miss - no FOMO here!
Venture Life (LON:VLG) bohenie - yes certainly no need for a FOMO rush here yet. See my reply to Tortoise here.
Knights group (LON:KGH) has just broken out of a year long base/cup and handle formation. Stock rank 99.
Luceco (LON:LUCE) has formed a year long base, and appears to be in the handle phase of the outer cup, having broken out of the inner cup two weeks ago. Stock rank 90.
Luce is in Mark's Potential Multibagger screen and also a "green" from Paul. I hold both, and think they both have multi-bagger potential based on the charts.
Hi Paul & Graham, KGH was reviewed here months ago- another update would be nice. Thanks!
In reply to stay humble Serica Energy (LON:SQZ) is one of my largest holdings so like you I am not happy. I assume you are a holder.
They have released a detailed RNS this morning which is well worth reading.
Recently the Company announced the forthcoming retirement of the CEO Mitch Flegg which may have unsettled the market.
In December they bought a 30% stake in Jersey Oil & Gas's Great Buchan Area.
I am sitting tight remembering how both Shell and BP fell dramatically in recent years and then recovered strongly.
We are going to need Oil and certainly Gas for a long time.
Absolutely, oil and gas will not significantly be replaced for another 100 years, CO2 is not our enemy. Very sad to see Mitch retire a very capable CEO, hope he becomes a Non Exe his experience is needed
"CO2 is not our enemy" is a bit misleading. It is certainly an extraordinary fact that all life is built from carbon based molecules that were originally CO2 molecules, fixed into organic form by the mind-boggling process of photosynthesis - all the more extraordinary given what a tiny fraction of the atmosphere is made up of CO2 (it's over 20x less abundant than Argon, which no-one even notices). It's also true that without CO2 the Earth would be roughly 30 degrees cooler - so life is absolutely dependent on carbon dioxide being present in our atmosphere. But you can have too much of a good thing. CO2 is also astonishingly effective at absorbing infra-red radiation (hence the useful keep us warm effect) - to the extent that if our eyes could detect IR light, the world around us would appear black, as none of that light would reach our retinas. That means that even what seems to be a tiny increase in percentage terms has a massive effect on the greenhouse effect. That might not seem a big deal in temperate UK - hotter summers, milder winters and lots more storms (more energy in the system has to go somewhere) isn't an obvious disaster. But the global effect of rising temperatures will inevitably lead to, among many other things, a massive rise in human migration as people move to escape the droughts and famines. None of this is disputed by anyone who understands the science. If we're not prepared/willing to reduce CO2 emissions, then we need to make contingency plans for the alternative, which will be far far more costly.
CO2 is also astonishingly effective at absorbing infra-red radiation
(hence the useful keep us warm effect) - to the extent that if our eyes
could detect IR light, the world around us would appear black, as none
of that light would reach our retinas.
Not quite.
https://www.flir.co.uk/discove...
Ah, quite right, sorry, I was over-simplifying. I should have said that if our eyes could detect wavelengths at 15 microns, which is in the infra red range and is the most strongly absorbed by CO2, then the air around us would appear opaque. But the IR range is much more than this, hence thermal imaging works.
Ok, but 15 micrometres is not at the peak of intensity of blackbody radiation from an object at about the temperature of the earth surface. I have to admit I've never seen a satisfactory explanation of greenhouse gas absorbtion and haven't had the time to dig into it properly myself - maybe when I'm retired - but the clearly unscientific statements I see being made and repeated by gramophone minds don't give much confidence. I'm sure if the real science was wrong it would've been challenged by now, but I think you can understand why there's a lot of sceptics.
It's easy enough to demonstrate the greenhouse effect in a school laboratory - so there's empirical evidence that CO2 absorbs heat and prevents it radiating back into space. As I said, this is good, otherwise the Earth would be 30 degrees Celsius cooler and the oceans would be frozen solid. Pretty bleak. But are you asking for an explanation as to why carbon dioxide molecules absorb infra red so effectively? It's something to do with the molecular bonds but I'm not enough of a physicist to explain how this works!
The problem is its all based on computer modelling, which usually turns out to be wrong.
Not really. The models are retrospectively tested with real data to compare the predictions with what actually happens. Turns out they're remarkably accurate.
I'll never forget a young teacher called Mrs O'Hara earnestly telling me & a class of 9 year-old kids in 1977, that all the world's oil would run out by the year 2000, and life as we knew it would collapse.
That was the universally accepted scientific wisdom at the time.
So when I see crying brainwashed youngsters today saying "I haven't got a future", I hope they direct their energies more towards technological research, rather than "raising awareness" and "activism".
Serica Energy (LON:SQZ) Must be getting close to being a takeover target at these depressed levels.
Portugall,
The UK energy sector currently has the lowest average Quality rank of 33, of all the sectors, this rank includes profitablity, cashflow and margins figures. The highest is industrials(62) then consumer defensives(62). I used to be obsessed with trading oil and gas shares to my detriment but now I am trading shares in all sectors. Follow the money I'd say, I've recently exited almost all my oil and gas shares, and switched to better performing sectors such as the two above.
Anyone know why Serica Energy (LON:SQZ) valuation is so low? Strong financials
The Energy profits levy (EPL) is such a drag on these North Sea names. A shockingly ill thought out tax. Sentiment awful. Unfortunately it’s an avoid for me until this is scrubbed.
Beeks Financial Cloud (LON:BKS) - big volumes again.
Yes, as per my trade on Superdry (LON:SDRY) last week and Shoe Zone (LON:SHOE) in 2021, sometimes doing research is a complete waste of time, if the market doesn't follow your train of thought and it can be as good just following where the money is. If I wasn't already holding Beeks Financial Cloud (LON:BKS) at a loss, I'd be putting money in from last Friday.
Beeks Financial Cloud (LON:BKS) now up 10% on no news at all following that huge surge in volume. Very strange.
Beeks Financial Cloud (LON:BKS) interim results are due in 3 weeks, according to Stocko. Might there be a TU in preparation?
Beeks Financial Cloud (LON:BKS) " interim results are due in 3 weeks, according to Stocko. Might there be a TU in preparation?" ...and if they could throw in a nice contract win like they did this time last year that would be good.
Also, thanks to those on here alerting us to the volume increase over the past week or so. I hadn't spotted it but took advantage, averaging down and currently now in (small) profit. Sterling work, thank-you.
One of Paul's GARP ideas for 2024 of course and one he holds himself. Any thoughts on the current activity Paul?
Are transactions in round numbers more likely to be instutions than PIs (or to put it another way, are transactions of odd-looking numbers of shares more likely to be PIs trading a cash amount rather than a share amount)?
I think opposite
As a PI I like to buy round numbers of shares and equate that to a £ per penny position (like a spread bet)
Institutions may buy to a set % of shares or £ value so more likely to be odd amounts. TR1 notifications nearly always have odd amounts in them
Interesting........I guess we are all different and there is no way of telling. I always buy in round numbers of ££££ ie. to the nearest £1000, whether that be £1k, £5k or £10k etc.
However, if selling (top-slicing) I normally do a quick bit of mental maths, work out roughly what % of the holding I want to slice and then divide that by the share number............so I sell a set number of shares that I normally round up or down to a round number.
I reckon everyone does something slightly different so I am not sure if there is anything you can read here.
I thought institutions used iceberg trading programs and similar, which are designed to appear random, to try to disguise bigger volume purchases, so other traders and algorithms wouldn't front run them or similar.
Yes but what do you think this means?
Hi Paul - I was very sorry to hear on your podcast about your dog Paddy. As someone who has had cats all my life I know all too well how painful the loss of a pet can be. Take care of yourself today and this week - there are things more important in life than shares sometimes and both you and Graham have definitely earned your keep already this year!
That's kind, thanks Tortoise! It had to be done unfortunately, as Paddy was too disabled to keep going. We used a "palliVet" who comes to the house and puts down the dog in their favourite place, which I recommend, it was nice and peaceful. Just part of the deal with pets isn't it, saying goodbye to them when their time comes. Anyway, sorry for off topic!
Losing a dog is the saddest thing: unlike many people they're reliably loyal; are pleased to see you and love you for just being there for them; and they never let you down.
Pets are given Nembutal which is painless and in my view should be permitted for humans. Fortunately I have obtained a supply from a vet overseas and thus when it’s my time to kick the bucket it will at least be painless .
Saying goodbye to a dog is so painful ... sorry to hear your news Paul
Porvair (LON:PRV)
I hold.
One has to admire the consistency of the company in delivering earnings growth in the face of challenging economic headwinds. The experienced management team under Ben Stocks is not given to hyperbole or 'flannel' it just does what it does very well, focussing on essential life limited filtration components across aerospace, metallurgy, water and life science.
Marginal increase in revenue, but this should increase going forward as a result of recent acquisitions. As Paul said adjustments relate to acquisitions, other than these adjusted and statutory earnings are on par. Confident outlook statement. The shares are inexpensive compared to historical standards and have the potential to mean revert once the economic backdrop improves and rates start to decline.
Beeks Financial Cloud (LON:BKS) Unusually high volume on Friday, from Stocko - 1,273,251 shares (3.7% of free float) versus average volume of 83,837
My morning smallcap tweet: Do you believe in the truth fairy?
Bidstack (LON:BIDS) Aptamer (LON:APTA) Sondrel (Holdings) (LON:SND) Kromek (LON:KMK) East Imperial (LON:EISB) Esken (LON:ESKN) t42 IoT Tracking Solutions (LON:TRAC) Ethernity Networks (LON:ENET) Avon Protection (LON:AVON) Duke Royalty (LON:DUKE) Revolution Beauty (LON:REVB) CVC Income & Growth (LON:CVCE) Vector Capital (LON:VCAP) Gore Street Energy Storage Fund (LON:GSF), Ceps (LON:CEPS), Gaming Realms (LON:GMR)
◄Bidstack (BIDS)► delay on convertibles agreement with Irdeto so doesn't currently expect to make any further draw down. Therefor needs further working capital in the short term. Gets €3m from Azerion in settlement of all outstanding claims and disputes and for the establishment and activation of a new technical and commercial collaboration with BIDS. Strategic review. [SP=0.6 Cap=7m]
◄Aptamer (APTA)► guides H1-Dec rev only £0.3m (£1m). Co expects to progesss £1.4m of signed work and a proportion of the £1.5m of advanced stage sales pipeline in H2. [SP=0.94 Cap=4m]
◄Sondrel (SND)► has received £1.5m of payments from an automotive Tier 1 supplier. "Negotiations remain ongoing with suppliers to improve the terms of existing supply arrangements but the Group continues to need to secure additional capital prior to the end of March." [SP=5 Cap=4m]
◄Kromek (KMK)► gets £1.3m grant to participate in the Intelligent Radiation Sensor Readout System. [SP=7.1 Cap=43m]
◄East Imperial (EISB)► to supply Macau's Galaxy Entertainment Group. [SP=0.95 Cap=3m]
◄Esken (ESKN)► gets legal advice that London Southend Airport Co has not defaulted on a loan. However Esken will be submitting a proposal to lender with a view to reaching a negotiated settlement. The dispute has disrupted talks on other matters including a potential £20 million funding facility. [SP=0.65 Cap=7m]. I hold.
◄t42 IoT Tracking Solutions (TRAC)► wins c.$7.5m three yr follow up order. Legals on extension of 2021 convertibles taking longer than expected. [SP=2.42 Cap=1m]
◄Ethernity Networks (ENET)► some relief as the Court in Lod has approved the proposed creditor settlement plan. [SP=1.24 Cap=5m]
◄Avon Protection (AVON)► gets another order worth $36m from the U.S. Army under the Next Generation Integrated Head Protection System. [SP=974 Cap=293m]
◄Duke Royalty (DUKE)► review outcome. To reframe product as 'hybrid capital' to more easily convey the attributes of its financing solution to business owners and investors. Will be able to take equity ownership of inveseees over 30%. Will change name to Duke Capital . [SP=32.11 Cap=136m]
◄Revolution Beauty (REVB)► settles dispute with Adam Minto, the Group's co-founder. He will pay £2.9m over 5 years. [SP=29.5 Cap=94m]
◄CVC Income & Growth (CVCE)► hikes annual dividend targets to 8.25p plus 7.25c (Euro). [SP=0.99 Cap=208m]
◄Vector Capital (VCAP)► guides FY-Dec rev £5.7m+, above mkt exp. "Since the year end, the Group has begun to see a softening in the interest rates offered by some lenders in the wholesale market, and a willingness in some cases to loosen loan to value requirements. Whilst this is encouraging, these are early days in the hoped for reduction in UK interest rates." [SP=29.7 Cap=13m]
◄Gore Street Energy Storage Fund (GSF)► reassures on liquidity, cash and divs. "Reconfirms its commitment to a diversification strategy, which has insulated it from the current dynamics of the GB market." [SP=68.3 Cap=338m]. I hold.
In line: CEPS, GMR
CMC Markets (LON:CMCX) to reduce headcount by 17% (around 200 posts).
One off cost of 2.5M but will have annual savings of 21M.
Very sad for those concerned, though having been involved in the odd redundancy myself, it can be a silver lining for some.
Quite a cost saving going forward.
Personally suspicious of these types of announcements. Why were 200 staff employed that were not needed? And why wasn't headcount reduced by natural wastage?
CMC Markets (LON:CMCX) Don't think necessarily suspicious - the staff were required for the rollout of new projects and products which appear to have now concluded. I suspect some of these staff would have been on short-term contracts, which would explain the relatively low one-off costs (£2.5m for 200 staff is £12,500 each, which suggests there won't be a huge volume of large redundancy pay-outs)
I remember viewing a CMC Markets (LON:CMCX) webinar a few years ago and selling immediately after. The management team were (just my impression from watching and listening) very far from impressive. Wish I could find the webinar. Maybe somewhere on PI World or Investor Meet Company?
Gaming Realms (LON:GMR)
The Company is pleased to confirm that it expects to report FY23 revenue of c.£23 million and adjusted EBITDA* of not less than £10.0 million, up 23% and 28% respectively year-on-year, in line with Board's expectations. The Company ended the year with £7.5 million of net cash.
Gaming Realms (LON:GMR) - Canaccord target price remains at 50p although I see a slight drop on the StockReport estimates today. A large blocking order at 36.5p was cleared on Friday - timely!
Porvair (LON:PRV) Nice results. Adjusted EPS 6% ahead of consensus. Based on 15-year (!) CAGR adjusted EPS increase could do around 41p of adjusted earnings this year putting them on 16x future earnings which looks way too cheap. If they can get re-rated to the 23x earnings they have more normally traded at, the SP could be closer to GBP10. Plus, the possibility of a bid, good cash generation and an experienced and impressive track record from Ben Stocks means this is a core holding for me.
Porvair (LON:PRV)
I agree. Good results and confident outlook with a sensible note of short term caution (continued industrial consumables destocking). While I think previous multiples at 23x look more challenging in a higher interest rate environment, net cash keeps EV/EBITDA more than a third below that of serial acquiring compounders in the industrial space, rendering the company an attractive acquisition target, and giving upside to current valuation. Question is: can PORV break out of this narrow trading band that it has been in for nearly 5 years?