Small Cap Value Report (Mon 6 July 2020) - BOO, UPGS, MACF, DISH

Good morning, it's Paul here.
This is initially a placeholder article, for subscribers to leave your early comments on anything interesting on the RNS. I'll write up the main article throughout the morning, section by section.
Estimated timing - I'm aiming to finish before 3pm today.
Update at 14:45 - today's report is now finished.
.
Pubs re-opening
I ventured out into Bournemouth on Super Saturday , expecting to witness chaotic scenes of drunken Brits defying social distancing, and being rowdy. However, it was all rather calm & civilised from about 6-9pm when I was out & about.
Starting off in Holdenhurst Road (near the station), which is usually busy at that time, only 1 cafe was open - Sprinkles Gelato, a large, new ice cream parlour. It was almost empty. None of the other restaurants, or independent bars had opened. A reminder that whilst there are no business rates, and staff can be paid on furlough, the financial incentive is to remain closed, having a call option on whether to re-open at all. Hence the general approach by independents, seems to be wait & see, before deciding whether to struggle to re-open, or throw in the towel & hand back the keys to the landlord.
One pub was open, The Christopher Creek, which is a popular Wetherspoons. On arrival, I was greeted by a friendly staff member, who invited me to use the hand sanitiser, then explained that all service is now at table. So find a table, then order the drinks & food via the Wetherspoons app, which also takes payment by card through the app It worked great, and I sat outside, enjoying a couple of pints & a panini with chips, all good quality & cheap. Not having to rub shoulders with smelly people, which is an issue with some Wetherspoons, was a pleasing improvement.
Inside the pub, they had installed clear plastic screens between the tables, and I'm pretty sure there were fewer tables than before. It wasn't that busy. I talked to the security lady, and commented that it didn't seem very busy. Oh we've only just opened, there was a gas leak on the boiler, so that had to be fixed before we could re-open. A reminder that a lot of re-opening pubs are likely to have maintenance issues due to being closed for a while. The bar area is not to be used by customers at all. Customers walking into the pub looked delighted to be able to have a freshly poured pint again, and many seemed to be regulars, greeting the staff warmly.
Overall capacity of customer numbers must be way down (below half, I'd guess) on what would normally be allowed at peak times. Plus the number of staff is up, because they need extra people to meet & greet, control numbers coming in, and serve food/drinks to the tables. There was almost no "atmosphere" in the pub, just small groups of people sitting at tables, talking quietly.
Next stop was Old Christchurch Road, which is a tatty-looking, but busy road, full of takeaways, vaping shops, hairdressers & tattoo parlours. You can probably visualise the type of thing. I noticed that the takeaways were all open, but have been for some time, and are clearly busy, with groups of Deliveroo mopeds lined up. Restaurants have had to adapt, and the ones that have embraced takeaways are likely to survive, in my opinion. Others, probably not. One or two independent restaurants had opened, but in each case only had a handful of customers were inside, as I peered in the windows.
Revolution Bars, and all its nearby competitors are still shut for now. More maintenance issues, with minor vandalism evident on several shopfronts, and peeling paint, etc.
Next stop was a large pub called the George Tapps, or the George Tapas as I always read the sign. They don't serve tapas, which is a good thing, as I reckon that's a con - splitting the food into smaller plates, and then charging you more for it, as you have to order at least 5 plates to feel full. This pub is run by Stonegate. It also seemed very well organised, with a reception team of 2 staff also asking me to use the hand sanitiser, and then register my personal details through their app, called My Pub. They helped me navigate the app, and register my visit (for tracing purposes if an outbreak occurs), then allocated me a table - right in front of a huge screen with football showing, oh dear! Most tables were full of men in their 20s & 30s, bellowing at each other. Why is it that when people have had a few pints, they shout instead of speaking normally? Anyway, it was so noisy, I left after one pint. They had taped off half the urinals, for social distancing, which is marvellous - I hate having someone right next to me when relieving myself, so let's hope they keep this innovation permanently.
Everything seemed very well organised in both pubs visited so far. This must have taken a lot of organising, I commented to the slightly brusque security lady. "It's been like a military operation over the last fortnight", she confirmed.
Next up I headed further into town, to The Mary Shelley, a larger Wetherspoons. Same thing there - staff seemed on the ball, and were managing things very well. There was a short queue outside, then when tables became free, they were let in. I had a table of 4 for myself, which seems wasteful & damaging to revenues. I had a couple of pints & a cooked breakfast, which was OK, but cheap. The clientelle generally seemed quite tipsy (this was about 8pm), and I overhead doormen discussing people they had just thrown out. Also groups of screeching young women were completely flouting distancing rules, by hugging each other, etc.. Most people seemed to observe social distancing well, but if people see some friends out, then social distancing seems to go out of the window. Therefore, I imagine we're likely to see some new outbreaks linked to bars & restaurants. You can't completely socially distance indoors, especially when passing in corridors, or going to the loo.
In the centre of Bournemouth, the main drag for bars, called The Square (which is actually circular), was quiet, with just the usual skateboarders & tramps hanging around. Hardly any bars were open, just another Wetherspoons! That looked busy, with lots of people standing outside at the front, under a canopy, smoking & drinking.
I then tried to get into a Slug & Lettuce, but was turned away by 2 rather smug doormen. "Have you got a buggy?" they shouted to me from a distance, as I halted at the halt sign, halfway up an outside stepped pathway. How strange. They must think I'm a single Dad, and need some help with my pushchair. Why on earth would they think that? Where do they think I've left my baby? "No, I haven't got a buggy with me today", I replied. "A booking! Have you got a booking?!" Oh no, sorry I don't. Then you can't come in I'm afraid. That was that.
A similar thing happened at another large bar, an O'Neills. The burly but affable doorman explained to me very politely that his total capacity was now just 100 people, when it had previously been 800. "But your beer garden is practically empty, I just wanted to stand outside there". I know, but 100 capacity is for the whole pub. Again, with maximum capacity at peak times down from 800 to 100, and with more staff needed, I don't see how this pub could possibly be profitable until these restrictions are removed completely.
Overall here are my key impressions;
- Very much a soft start, with only a few pub/restaurant chains re-opening, independents generally not
- Wetherspoons & Stonegate seem to be managing their pubs very well, from my small sample, observing the Govt rules thoroughly.
- The beer tasted good, so they seem to have surmounted the supply chain issues well
- Limited customer numbers mean pubs won't now have busy, profitable, peak times any more. Therefore I don't see how the sector can be profitable at all in the current circumstances, especially with increased costs too
- You have to book a table beforehand, to be sure of gaining entry to popular pubs/restaurants (opportunity for booking apps?), which may improve loyalty to particular pubs where you get used to using their app
- Customer experience is fine - I actually much preferred having fewer people in pubs, and ordering/paying from the table.
- If you can't interact with other people, then why go to a pub at all? Sitting at home with beer from the supermarket makes a lot more sense to me
How long before things return to normal? - Who knows, but if we have a vaccine/treatment in 2021, as seems possible, then the hospitality businesses that survive this crisis should become more profitable again, and with less competition. Hence I think this sector is attractive for investors who are willing to look beyond the current crisis. But don't expect pubs to be profitable any time soon - which begs the question whether their balance sheets are strong enough? There might need to be more dilutive fundraisings for some, possibly?
.
Boohoo (LON:BOO)
331p (down 15% today) - mkt cap £4.1bn
Allegations have resurfaced in the Sunday Times about a third party BooHoo supplier apparently operating unsafe sweatshops in Leicester, flouting social distancing rules, and paying below minimum wage. This issue was flagged up some time ago, and it all blew over, but the same thing has cropped up again.
Garment making almost completely disappeared in the UK in the 1980-90s. However, it has come back in recent years, e.g. in Leicester, with authorities turning a blind eye to sweatshop conditions & illegally low pay, probably through fear of being accused of racism - which seems to dominate the PC world of local councils. Whereas applying the law evenly & fairly, to everyone, is what we actually need. Why bother having rules, if they're not going to be enforced?
BooHoo has responded. It claims to not have had knowledge that some of its products were being made in a sweatshop. Whilst people might be cynical about this, there is actually some credibility to this. My experience in the sector is that orders placed with one supplier are very often outsourced to another factory, usually via family connections. Sometimes retailers are unaware of even what country their products are made in. Audit trails are a waste of time, because I found that suppliers will just sign anything. The only way to properly audit where & how garments are made, is to have physical boots on the ground, inspecting factories in person. With hundreds of suppliers, scattered around in multiple countries, that's complex & very expensive, hence why so many retailers don't do it.
BooHoo says it's working to raise standards, and details what is going to be done. The danger is that these repeated allegations may damage its brands, and lead to customer boycotts. Although in the past, the public have shown a very short attention span, with boycotts quickly fizzling out.
A dose of reality here - if you buy a garment at a remarkably cheap price, then the person making it is being paid very little - whether that's in the UK, or abroad. However, the person making it clearly needs the money, or they wouldn't be working for a low wage, and doesn't have an alternative, better paid, source of work. Therefore I always tell everyone who virtue signals about boycotting a particular shop, to make sure they donate money to a charity which will feed & house the people who are now unemployed because of their boycott.
Clearly BooHoo has to deny these allegations, and also has to take decisive action to sort out its supply chain. That's bound to hit its margins somewhat. Social media means that bad news travels further, and faster, than in the past. But with such a short attention span, the public quickly forget. Is this likely to damage BOO badly? I doubt it, once the dust has settled. It really is long overdue for sweatshops, and breaches of minimum wage regulations, to be properly punished. That is going to be tricky though, as sweatshops are adept at disappearing, then popping up again somewhere else, with the same people, but a new limited company. Sometimes retailers turn a blind eye, but sometimes they're unaware that orders have been subcontracted out to an unknown factory, that's the way this sector works. The rules have to be enforced, otherwise nothing will ever change. I expect customers might forward some outraged opinions, sign a petition online, and then carry on an usual after a few weeks. Hence I'd be more inclined to buy on today's drop, than to sell.
EDIT: I'm quite surprised to see BOO shares continue falling today, now down c.23% at c.300p. This is looking increasingly tempting as a buying opportunity. Unless there's been some further negative news out? End of edit.
.
Up Global Sourcing Holdings (LON:UPGS)
76p (up 13% today) - market cap £62.5m
Trading Update - the previous trading update from 8 June was surprisingly good, for background here is my article on that - with underlying EBITDA (not my measure of choice) would be above market expectations. Although a soft order book was mentioned.
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces the following unscheduled trading update.
Today's update - this reads very positively to me, and it's good to have some specific figures;
Since the Group provided its previous update on 8 June, the invoicing and delivery of its order book has continued to progress at a good pace, driven in particular by a strong performance in Online.
As a result, we now anticipate that revenue for the year ending 31 July 2020 will be above £111.0m, Underlying EBITDA* will be above £9.6m, and Underlying PBT will be above £7.4m - all of which are above the market's current expectations.
Those figures are way above the (possibly old) forecasts shown on the StockReport.
My opinion - I'm very impressed indeed with how UPGS has managed to trade so well through such a difficult period. These results are tremendously impressive. I'm not looking to open any new positions at the moment, but UPGS is certainly going on my watch list of possible future purchases. There could be further upside on the share price, given this strong performance, maybe?
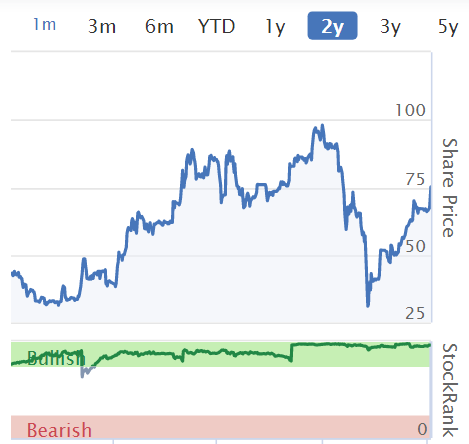
Divis may be back on the cards soon too. Overall, I like this share, it gets a thumbs up from me. Note the high StockRank over the last 2 years;
.
.
Macfarlane (LON:MACF)
76p (up 8% today) - mkt cap £120m
I last looked at this packaging group here on 27 Feb 2020, when it published quite good results for 2019.
Trading Update - summarising it;
- Previous guidance was that Q1 was good, and Q2 sales expected to be down 20-25% below 2019, due to lockdown
- Actual Q2 performance has been better than expected, with sales down only 7%
- Weak sectors partly offset by growth in others (e.g. online, medical, food, etc)
- H1 sales will be down 3% on LY, but includes benefit of acquisitions. Organic growth not stated, but will obviously be worse than 3% down
- All sites continued operating throughout lockdown
- Furlough - bringing back staff (30% furloughed originally), and will seek to repay sums already claimed. Not explained why
- Liquidity - tons of headroom (£30m facility), net bank debt reduced to only £2.0m - helped by Govt schemes
Guidance - still too uncertain to give specific guidance (a bit lame, as we're now in H2), but this reassures;
... based on ongoing actions and current levels of trading, we expect the business to remain profitable in 2020 and to operate well within the current borrowing facility
Divis - intention to reinstate them once there is more clarity
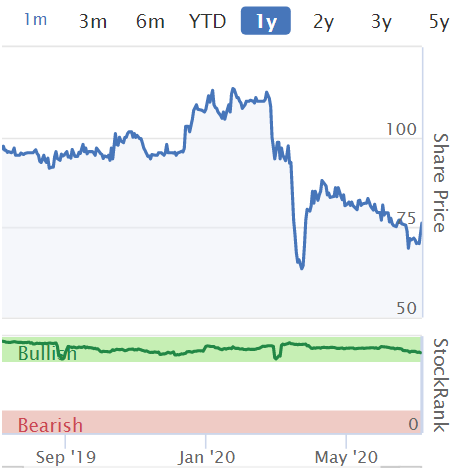
My opinion - this is clearly a good update. Shareholders can sleep more soundly now. Given that it's had a fairly good crisis, then this chart looks as if there could be some more recovery potential maybe? Note the consistently high (green) StockRank in the last year.
I think we could see nice upside from companies which reinstate divis, and this might be one that applies to.
.
.
Bigdish (LON:DISH)
2.3p (down 14% today) - mkt cap £8.0m
(I have a long position)
This is a tiny, highly speculative company that operates a dining app which allows restaurants to use dynamic pricing (i.e. discounts with half hour slots) to attract more business at times when they would otherwise be empty/quiet. Clearly this is highly relevant to the situation now restaurants are re-opening.
There's a rather long-winded strategic update out today. It doesn't seem to have impressed the market, with the share price down 14% today, but it's a highly volatile share, and had been rising in anticipation of a resumption of trading.
It's a big change to the business model, with the company expanding its offering to become a SaaS provider for restaurants, to replace the current small fee per transaction. I really like the concept of disrupting the deliveries market (basically by undercutting Deliveroo), and encouraging restaurants to promote BigDish, which removes the need for a huge marketing budget.
The Manchester based telesales team proved highly effective just before lockdown brought down the shutters.
DISH needs to raise more money, which is already known. I'm relaxed about that, as there's pots of money swilling about for dining tech companies. The last fundraise was from a US family office, at 7.2p. I imagine the next funding round is likely to come from something similar, rather than a stock markt fundraise (it's fully listed by the way, not on AIM, so more expensive to raise money from the stock market).
This share will not appeal to anyone here, so I'm not really interested in discussing it. I'm fully aware of all the negatives, but think it has interesting speculative upside. Very high risk.
My RNS - it's a long time since I've had to issue one of these, but my total DISH holding has gone over 3%. Because most of the position is on a spread bet through Spreadex, I didn't think it needed an RNS (because spread bets don't usually include voting rights). But the company told me that they wanted a TR-1 to be issued, which they have now released, after I filled it in over the weekend. Section 11 Additional Information - this explains things in full. Since my economic interest in the company is 11,529,620 shares (3.166% of the company) we thought it best to publicly declare it, as I don't want to fall foul of the FCA. Better to err on the side of declaring too much, than too little, in my view.
.
That's me done for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

127 comments
So I get home and see Paul has mentioned BigDish (LON:DISH) in today's SCVR, brill I thought, he is going to explain why BIGDISH-toGo has not gone anywhere, but alas no, someone has decided to go "willy waving" in public.
In the Blue corner we have Paul (who I do not know) who raises money for the poor of Zimbabwe, doesn't sound to racist to me.
In the Red corner we have someone who found issue in a single paragraph when it appeared no-one else did. But did he decide to email Paul on the quiet explaining why he felt that way, no he decided to go straight to the Boss and complain, and let everyone on here know what a hero he is.
When he got his reply, did he decide to congratulate himself and pour himself a J2O, no he again decided to go public to prove what a super hero he is.
There is only one person in this scenario "wiping up hate" and it isn't Paul.
Apologies for the rant, and I very rarely post, but this is what is so wrong with society and it certainly isn't helping race relations
What an embarrassing complaint. No wonder you are still awaiting a response!
You mentioned in your complaint that many people would find Paul's comments offensive but I suspect that actually you are wrong. Perhaps the 41 down votes might give you some indication in that regard. Paul simply expressed his opinion on the matter which he is entitled to (albeit arguably not suitable on this forum). Paul actually called for laws to be applied evenly and fairly for all. Surely you would agree that this is a call for equality, which I assume you are supportive of? For the record, I don't actually agree with Paul's opinion on the subject but to claim a 'deeply racist narrative' is completely ridiculous. There are too many people in the world right now that try to muzzle alternative opinions if it doesnt confirm to the narrative they are trying to push. Paul's comments were not racist he has just expressed an opinion you didnt agree with. That's ok, debate it all you want but to throw out accusations of racism like you did is appalling and extremely unfair. I'm sure everyone on here agrees that racism has no place in the world but it's getting to the point where behaviour like this is going to do more harm than good to the cause you are fighting for. It's getting to the point now where people are frightened to offer an alternative opinion on issues involving race due to the risk of being castigated and labelled a racist, just like you have done here.
Dear harvs19,
I thought it is only fair to Stockpedia to let people know that Stockopedia has taken the complaint seriously and I have received an official response. Any delay in responding was explained as the desire for Edward Croft to deal with the complaint personally.
Edward has thanked me for taking a ‘proactive stance on the matter.’
Let me thank Stockopedia for a response that is woke (alert to injustice in society), politically correct, and progressive. Stockopedia recognized that inaccurate stereotypes of race that have been propagated and that the specific narrative has a racist subtext that was not recognisable by the majority of readers on the platform.
Stockopedia has committed to take a number of positive steps in order to protect the Stockopedia community and employees. Stockopedia will communicate some of their initiatives in due course.
Thank you again Stockopedia.
BSV
I've read the BigDish strategic update (I'm long), and I have to say it seems a very smart move to me. Moving to SAAS should be more appealing to restaurants, and focusing on a tech strategy rather than purely an introductory discount transaction model plus delivery service should make this a tech service the restaurant retains for the long term, particularly if they keep the customer relationship, data etc. The integration with Wia's environment sensing tech looks a particularly smart move, given the post covid new normal. More importantly creating a scalable tech solution means this can easily spread beyond the UK and penetrate markets worldwide. I can imagine a tie-in with a company like Amex, restaurant lounges helping this to explode globally. I should think the market drop is linked to the delay to profit realisation driven by the strategy change. However I think Dish should be applauded for innovating through the pandemic and incorporating the change in the market they see happening around them.
Re pub openings, From the experience here in spain, the first day every bar was offering to douse you head to foot in bleach, near realtime measuring your 2 meter distance, with a claxton sounding, if your lazy leg strayed too far. Now its much more relaxed, rightly or wrongly, it’s human nature. The government over time also relaxed the rules so 25% capacity and now mostly 100%, but masks if you cant social distance.
So Paul, I'm sure this will be a bind, and i know a sacrifice but regular attendance at the pubs will show if people relax over the weeks, staff and customers & it starts to get back to normal. Tough i know but thorough research is just so important, i had to endure it here too, but a worthwhile sacrifice I'm sure you'll warm too!
Paul..I like a punt so please could you present your case again for Bigdish£Dish....I know it’s speculative but from what I have read , there is just a chance that it just might get its new business model off the ground , as the technology now available to its restaurant customers on a monthly fee is surely going to be a no brainier, provided the monthly fee is reasonable...After all, most restaurants would not have the capability or know how, to set up, promote and use a modern bit of technology to get more business...As someone in business I would love a slice of new technology for a monthly fee...even if I had my doubts, I would give it a go as what have I got to lose? ..Moreover, every business has a marketing budget and this might just be the best bit of marketing for any hospitality business where margins and sales are under pressure ..
Give it to us Paul , as I for one am keen to hear your side, even if proves a total duffer....it’s not like i would put my life savings into Dish...but it’s worth say 1% of a portfolio on a risk reward basis ...Thanks.Tony
Hi Tony,
I'm just not interested in trying to sell DISH shares to anyone. People can make up their own minds.
I think it's an interesting risk:reward punt, very high risk, but potentially high reward.
Management are ambitious, and creative, and have changed the business model several times, learning & making mistakes as they go along.
I just think it looks potentially interesting, and is in the perfect space for current market conditions in hospitality.
It probably won't work, but if it does, then I could do well on my position. I do like to have the occasional big punt on something speculative. Very occasionally it works, but usually doesn't. Going into it with that preconception is a good starting point I think.
Regards, Paul.
Regarding £Boo, I think as soon as a "police investigation" was reported to be launched regarding the Leicester factories, the SP fell with increased momentum. Once the 300p support was broken, the SP plummeted to around 282p and then rebounded where for around 1 hour it was around 295-300.
Us humans love round figures, the SP was at 299.90 for around 2 minutes at 4.28pm. Why 299.90 out of all numbers... Will it or won't it go over 300p? Alas, not to be.
Similarly to the tragedy in Bangledesh in 2013 with Associated British Foods (LON:ABF), the fall in SP is very likely to be a blip and the 16-30 year olds carry on buying what they usually buy!
But the Home Secretary announced a National Crime Agency investigation last week. I guess the news took a while to filter through.
I have seen that BOO is part of some ethical ESG funds, e.g. Standard Life. That might have to be reviewed. Always slippery defining what ethical investment means.
Hi Paul,
I object to the hearsay comment;
'e.g. in Leicester, with authorities turning a blind eye to sweatshop conditions & illegally low pay, probably through fear of being accused of racism - which seems to dominate the PC world.'
It is difficult to believe in the UK today people in power worry too much about being PC or racism perceived and real. We can't have Windrush or a Prime Minister deliberately using racist language to gain the racist vote if everyone is to PC. The above language is more of a trope I'd expect from EDL members.
This sort exploitation has been known for years and I suspect the blind eye is more the result of general approval of exploitation of labour for fatter profits to shareholders/business owners, cheap prices for consumers and low taxes by government cuts to enforcement agencies. After all, this is how you gain donations and win elections.
Kind regards,
BSV
Codswollop!
I reckon the real reason illegal sweatshop practices being ignored for years is that no one gains from stopping it. The workers are either illegal migrants or claiming benefits and have no options for better employment. Catching, detaining and deporting illegal workers is massively expensive. Garment Manufacturing would just move offshore with loss of jobs and profits for UK businesses and less tax for HMRC. Nobody wins, not even the people being exploited. Only coronavirus has forced the government to act, in the interest of public health and safety. I can’t see how things can go back to business as usual.
Hi Momoko,
Thanks for not blaming political correctness.
BSV
Blue sky venturer ..I am sure there is a message in your words but you should be engaged to write RNS for companies with bad news to report but want to show it in a positive spin.
Try rewriting your words , so a thicko like me can understand what you are trying to say...is that possible please BSV .Tony
Hi Tony,
I think what I'm trying to say, is that the EDL wipe up hate by explaining authorities are too worried about being PC to deal with ethnic minority criminal activity. Unfortunately, rather than addressing the incompetence of the authority, ethnic minorities scapegoated as the problem. Unfortunately, this has been picked by normal people and repeated.
I think the share price of Boohoo (LON:BOO) reflects what might happen to their business model if the government actually enforce the law. I suspect Boohoo (LON:BOO) and other firm are very aware of how they make fat margins.
Kind regards,
BSV
How dare you associate anyone here with the EDL - shame on you.
How Dare you!
Your language is the same used by the EDL. I advise you to stop using it whether you believe it or not. I will be writing a letter of complaint about your some of you racial undertones lacking facts.
BSV
The complaint raised with Stockopedia. Still waiting for a response.
https://drive.google.com/file/...
That is truly pathetic.
Hi Blueskyadventurer,
When I read Paul's comments on councils not enforcing regulations I was pleased as there seemed to be a trend of blaming Booboo and not those responsible for enforcing legal standards.
i assumed the lack of enforcement is because of lack of resources rather than misplaced political correctness.
Reading your complaint and thinking again, it does seem that PCness is being made the scapegoat instead of other more likely possibilities and this seems unfortunate.
I would have preferred to see a serious discussion on this rather than your talk of the EDL and a complaint.
I also feel a professional organisation, like Stockopedia, should answer a complaint from a customer within 3 weeks.
Best wishes Paul
You mentioned in your complaint that many people would find Paul's comments offensive but I suspect that actually you are wrong. Perhaps the 41 down votes might give you some indication in that regard. Paul simply expressed his opinion on the matter which he is entitled to (albeit arguably not suitable on this forum). Paul actually called for laws to be applied evenly and fairly for all. Surely you would agree that this is a call for equality, which I assume you are supportive of? For the record, I don't actually agree with Paul's opinion on the subject but to claim a 'deeply racist narrative' is completely ridiculous. There are too many people in the world right now that try to muzzle alternative opinions if it doesnt confirm to the narrative they are trying to push. Paul's comments were not racist he has just expressed an opinion you didnt agree with. That's ok, debate it all you want but to throw out accusations of racism like you did is appalling and extremely unfair. I'm sure everyone on here agrees that racism has no place in the world but it's getting to the point where behaviour like this is going to do more harm than good to the cause you are fighting for. It's getting to the point now where people are frightened to offer an alternative opinion on issues involving race due to the risk of being castigated and labelled a racist, just like you have done here.
If stops people from blaming minorities and immigrates for all problems, and stop my brother from being attacked after the same narrative was raised by the EDL in Rochdale. I'm all for it.
I thought it is only fair to Stockpedia to let people know that Stockopedia has taken the complaint seriously and I have received an official response. Any delay in responding was explained as the desire for Edward Croft to deal with the complaint personally.
Edward has thanked me for taking a ‘proactive stance on the matter.’
Let me thank Stockopedia for a response that is woke (alert to injustice in society), politically correct, and progressive. Stockopedia recognized that inaccurate stereotypes of race that have been propagated and that the specific narrative has a racist subtext that was not recognisable by the majority of readers on the platform.
Stockopedia has committed to take a number of positive steps in order to protect the Stockopedia community and employees. Stockopedia will communicate some of their initiatives in due course.
Thank you again Stockopedia.
BSV
blueskyventurer,
Please be so kind as to share with the Stockopedia community the response in full to your complaint. We need to know the detail of the positive steps that will be taken to protect the Stockopedia community where we are considered inadequately woke, politically incorrect and generally reactionary.
It would be useful to know from whom and what we are to be protected - ourselves - each other - Covid-19?
Will this added protection cause my subscription cost to be increased?
Bonitabeach
P.S. only kidding about the Covid-19.
Clearly there's a lot of people feeling oppressed by political correctness.
Suggest you look at the following video to look for alternative expression.
Is There an Alternative to Political Correctness?
https://www.youtube.com/watch?time_continue=56&v=uWM2E9oHlhA&feature=emb_logo
BSV
I think Paul is reluctant to write more about BigDish (LON:DISH) as he knows it would all be over-baked waffle - right Paul?
I mean they are frantic pivoting (somewhere, anywhere) they've made themselves so dizzy that they think they should give up their current business model and try and disrupt and disintermediate the rather new and disruptive delivery/order companies like Deliveroo, JustEat, etc.
(Read this. Good laugh and interesting on 'cutting edge' delivery and restaurant tech -> https://themargins.substack.com/p/doordash-and-pizza-arbitrage )
Isn't it a bit mad for tiny shallow pocketed Big DIsh to take on the deep SV VC pockets behind foodtech who will just keep throwing money at any old crap? That Dish has to face the scrutiny of public markets is against it. Plus Dish clearly do not have tech that these guys want to buy...and they haven't shown any operational or sales prowess that would entice a bid either looking to consolidate a bit of space.
Rainbow chasing is fun though. And it might work....but this is clearly a long odds punt....longer and less discernible than rather dodgy Tasty (LON:TAST) ;)
I'm interested and open minded so I'd welcome the detailed case for it still...I'm happy to change my mind and do it often.
Best wishes
mojo
One interesting thing I noticed from Paul's BigDish (LON:DISH) RNS is that their "Digital Communications Officer" (whatever that is) is one Zak Mir. Not a common name so I assume it is that Zak Mir.
Nothing personal against Zak and probably not very rational of me; but the idea of someone whose investing style (Technical Analysis) relies on investor sentiment being involved in a pre profitability story stock doesn't really attract me.
He has to earn a crust I suppose. I agree that there are better ways to do it. Personally I have always prioritised my reputation over fees. Nobody can buy my opinion on anything, for any price.
Why would I give a damn what you think about anything? Obnoxious comments don't get any future replies from me. So talk to yourself.
Okay...we all hear you...
There's clearly no answer from you as BigDish (LON:DISH) is an outright howler....you're a bit annoyed as you've managed to get yourself neck deep in a piece of hokum on a total whimsical flight of fantasy re foodtech and platforms or some other nonsense.
It makes Tasty (LON:TAST) look like a quality safe company...obvs its not and I didn't tip it, just discussed some facts about as I hold it in full knowledge it could prove to be a piece of trash...but hey, you said i was clueless...
If you're gonna dish it, you got to take it.
Anyway, no hard feelings. I've screwed up plenty too...and may have a decent chunk of whoopass ahead of me in H2 2020 as I hold plenty things many sages would tell me is a but junky...and I'm quite nervous they are right...but got to play it as I see it.
Best wishes
Your mojo
PS you may be right on Big Dish but we won't know that's from insight rather than luck unless you lay it out for us....Whatever...in that alt reality let me be the first to congratulate you
Haha...I see that cancel culture has arrived in Stocko too.
Whoever you are...know you are a muppet
Great write up as usual Paul. You have sold me on Big Dish but not Rev Bars :). You can’t win them all
I'm not trying to sell anything to anyone. Just giving my opinions, which you're free to accept or reject.
Paul - you are clearly going to lose your investment or make more than most people on here will make in a lifetime of investment so best of luck. I would say they should put you on the board because your expertise may make the difference.
Loved the description of Bournemouth! Doesn't sound very different to my own home turf of Manchester,Stockport and its satellite towns. Somehow I'd an image of Bournemouth as a genteel congregation of pensioners.
Somehow I'd an image of Bournemouth as a genteel congregation of pensioners.
50 years ago maybe, but definitely not now! It's full of pretty ghastly chavs now, and junkies.
These "chavs" seems to spread everywhere with their tattoos, potty mouths, loud cars, ridiculous drag-strip and stop driving, pants showing, "rollies".
Why are they breeding so rapidly and what can be done to reduce their population? Some Tebbit / Thatcherism? National Service? Natural Selection? Capitalism?...
I saw one the other day wearing a facemask AND smoking at the same time.
Such a shame Paul had it on my list to visit in the future I think Brighton has gone the same way remember some great nights out there in the late 90's early noughties but last time I went to Brighton 6-7 years ago it was over ridden with aggressive beggars and Gangster looking types hanging around all over the place.
Despite the 23% drop Boohoo (LON:BOO) is still on a forward p/e of 38. I would need something stronger than beer to buy in!
It grows at 40-50% per year. 38 puts it PEG below 1.
Thanks Paul for another report full of thought provoking reflections. Mark
"This share will not appeal to anyone here, so I'm not really interested in discussing it. I'm fully aware of all the negatives, but think it has interesting speculative upside. Very high risk."
Not sure that's quite right Paul. I think there are a few of us on board Bigdish (LON:DISH), So very interested in what you have to say about it :-)
OK, I might expand on DISH in future reports then.
Paul - any thoughts on Bigdish (LON:DISH) announcement on strategy this morning? Seems market wasn't particularly impressed though I can see some sense in what they are trying to do. I hate the current Uber Eats type model. They charge the restaurant, then they hike the price of the dish by at least £1, then they add a delivery charge and finally a service fee. Now they ask you to add a tip to the driver too so clearly little of the extra fees goes to the poor delivery guy! I reckon a delivery for 4 people costs me at least £10-15 more than if I went and got it myself, so I either use restaurants with their own delivery or get it myself now. I will only use something like Uber if there's a big discount and that doesn't feel like a sustainable business model. I know several others who now do the same. I may be able to easily afford the extra £10 but I have little desire to give it away.
Therefore a model whereby Bigdish (LON:DISH) look after the logistics and marketing and someone else does the last mile delivery resulting in less price gouging is attractive to me as a consumer as well as the restaurant, so I can see both demand and supply. If it gets any traction at all the valuation multiples could rocket given how hot the food tech space is. I recognise that is highly speculative but I think the core business should also remain attractive as there is little else out there like it and spreading traffic across the day is clearly now a big focus. Revolution Bars (LON:RBG) pretty much said that exact thing in their recent commentary.
I notice your 3%+ holding RNS this afternoon too, so given the vested interest your thoughts on it most welcome.
Re Bigdish (LON:DISH) - The consumer problem for restaurants is that there is a consumer reason why there are "naturally" a few very high trading periods (eg Fri/Sat 7-9pm) but mostly low periods (hence often closed on Mon/Tues).
Consumers going to restaurants casually WANT to have a crowd for "atmosphere" and as proof the food is good. A second group are those who have to eat at a certain time (eg after work but not too late in the week (7.30-9.30pm).
In the remainder, of those who will "shift time" based on a price reduction will be quite small and mostly young/poor people - who are going to be attracted by ever better takeaway and home delivery options
How many does that leave and how much margin will be offer after you have given a big price discount to the consumer and paid DISH - especially if fixed costs like rent are pushed done further.
All conjecture but going against the grain I think.
don’t agree or at least I am one of the older generation who likes to avoid crowds and favours great service over atmosphere. Suspect many like me,especially among my generation
Hi Caper4,
I'm a card carrying miserable git, despite being only 52.
I'd much rather go to Crabs (my favourite fish restaurant) when it's empty at noon, and get a 25-50% discount through DISH, than pay full price with a load of noisy, selfish, plebs surrounding me & making me have to strain to hear what my lunch guest is saying, some time later that day.
As someone else said, with restaurants now seeming to like minimalist decor, with no curtains, carpets, or cushions, the noise just reverberates around into a deafening din.
Friends with hearing aids cannot abide this. I find it difficult too, even though my hearing is only slightly impaired.
So I'm all for quieter dining options, at off-peak times.
Best wishes, Paul.
Hi Zipmanpeter,
You should try out the BigDish app (if it operates in your area, and once they get the restaurants re-started again). All will become clear once you use it - the app is fantastic. Why do you think I bought 3% of the company?! The answer is because I used the app a lot, found it absolutely wonderful, and could see the kernel of something really good here. I think mgt is fumbling its way towards the right business model, and trying out different ideas.
Regards, Paul.
I always like good service and also prefer when a place is less crowded as I feel that the kitchen staff are giving attention to my meal, rather than rushing like mad as they are chasing their tails to keep up with the massive table of 20 that just rocked up without a booking and yet still seem to be served ahead of you...
Or maybe that is just my memory of my youth working in such places and always seeming to be the only cook on when a coachload turn up and they are on quick turnaround to make a football match or show.
Is it just a coincidence that the first area to be shut down again due to a Corona surge was Leicester?
Amusing
On other issues that are sometimes discussed here - there is a great Motley Fool US podcast featuring Bethany Mclean, the author of a famous book about Enron, talking about £Tesla. Scottish Mortgage IT has 12% in Tesla......
Tesla is just crazy. That is one share I would never buy at the crazy prices now. Guess it’s loads of the Robin Hood idiots happily chasing it up.
Tesla is just crazy. That is one share I would never buy at the crazy prices now. Guess it’s loads of the Robin Hood idiots happily chasing it up.
Tesla's a $250 billion company - I don't think the Robin Hood idiots are going to move the price at that level :-)
Whether Tesla is worth this or not is impossible to know, but there are clearly signs that we're going through a third industrial revolution. That that makes it hard to assign a value to the companies that are riding the wave. Personally I wouldn't hold Tesla at these prices but I'm very happy that Scottish Mortgage Investment Trust (LON:SMT) - which I do hold - does. It's well worth reading the commentary from James Anderson, the SMT portfolio manager:
https://www.bailliegifford.com...
Anderson quotes Charlie Munger:
As ... Charlie Munger, puts it with the clarity of a 96 year old, too many investors are ‘like a bunch of cod fishermen after all the cod’s been overfished...that’s what happened to all these value investors. Maybe they should move to where the fish are’
timarr
You need to listen to the podcast. Scottish Mortgage Investment Trust (LON:SMT) holding is surely too large. It’s £300m.
You need to listen to the podcast.
No I don't.
timarr
Tesla is now 3x all the other US motor manufacturers combined. Stark raving bonkers.
Noisy places, where people lean into each other to hear and raise their voices expelling more particulants, slowly losing their inhibitions over the course of the time ....
What could possibly go wrong?
Must complement Paul's memory after (at least) five pints too.
As a Bournemouth University graduate, this has made me feel somewhat nostalgic. Nice read. Extra points for ordering a cooked breakfast at 8pm :)
Likewise, although some of the pubs have changed names.
Presumably, if someone tested positive for COVID-19 and it could be traced back to a Wetherspoon’s pub then everyone at the same table and on neighbouring tables to that person in the bar at the same time would be required to self-isolate for two weeks. For a self-employed person that would mean two weeks loss of earnings. That seems like a big risk for a couple of pints of beer. The potential disruption to livelihoods as a result of having to self-isolate strikes me as a major disincentive to visit bars and restaurants that require pre-booking and the use of an app. It may make sense from a public health perspective but I suspect that many people will not be willing to take the risk of having to self-isolate.
It might be useful for the pub sector if independent statisticians were appointed to analyse the odds of having to self-isolate after visiting a pub. At least, customers could then make a judgement based upon facts rather than conjecture.
Good points. Although self-isolating seems largely voluntary, how many people are actually going to obey, or rather flout the rules? As you say, self-employed people can't afford to self-isolate.
We're pretty sure that a self-employed builder who was re-fitting 2 bathrooms in my London house, and seemed very unwell but carried on working, almost certainly brought covid into our house back in March, resulting in a death.
Talking of voluntary self isolation - This weekend also bought news that cleaners and porters in NHS Hospitals now statistically show very high anti body levels
Had it and couldn't afford to be off sick? Suggests similar issues in Care Homes?
How much lower could our fatalities have been with hindsight?
It might be useful for the pub sector if independent statisticians were appointed to analyse the odds of having to self-isolate after visiting a pub. At least, customers could then make a judgement based upon facts rather than conjecture.
It's a well known fact that nothing good has ever been achieved in the history of mankind by asking a statistician! Whilst I completely agree with you that it's a disincentive to visiting a pub or restaurant that you may have to self-isolate as a result of your visit, I don't see how on earth anyone can come up with any meaningful probability that you may need to do so. It would just be a guess, wouldn't it?
All the best, Si
It wouldn't necessarily be a guess. Statisticians and economists regularly use micro-morts (or a one in a million chance of death) to weigh the risk of all sorts of activities. For example, driving 330 miles in the UK in a car is roughly 1 micro-mort, whereas doing the same on a motorcycle is 47 micro-morts.
In about a months time it will likely be possible to work out the micro-mort associated with going to a pub (in the time of corona- remember to subtract the micro-mort of a pub visit pre-corona) to get to some probability of death per pub visit.
Almost certainly it will be a miniscule number vs. a miniscule number, and given that every drink after 2 per day reduces life expectancy by about 15 minutes (whereas 1 drink actually has a protective effect in terms of micro-lives) I don't think COVID is the big problem at the pub.
Almost certainly it will be a miniscule number vs. a miniscule number...
That's what I call a guess! I wish I'd never trained as an engineer. Over-exposure to the real world has obviously done me no good; I might have more time for economists and statisticians were it not for engineering.
All the best, Si
Wow!
Did you never use statistical techniques for quality management in your engineering Si?
Simoan
I don't see how on earth anyone can come up with any meaningful probability that you may need to do so. It would just be a guess, wouldn't it?
Thats the point though probability by definition is simply guessing the % chances an event will happen - so i would say its entirely possible to estimate the odds and present them with the caveat they may not be accurate.
If one believes the bookies there is nearly a 1% probability that Kayne West will be the next US President - interesting - not sure how accurate that probability is though. i am kind of guessing he was just having a laugh when he said he was running - could upset the applecart though if he were to run and split the vote slightly.
Great to read about your weekend experiences, Paul. I also went to a number of pubs in West London and was expecting it to be a bit busier. I found the locations where younger people usually go were quite busy, but those with older clientele not so much. This is probably linked to the risks associated between the virus and age. I ended up spending far too much on booze and interacted with very few people. While we had a great time, it's not quite the same with minimal entertainment (quiet music, etc.). For me, I'm not sure the cost is worth it and would suggest this is a risk for Revolution Bars. I'm predicting pubs/restaurants will have a strong few weeks of sales, but the novelty will wear off, and people will start to save their cash until things become more interesting. As you note, who knows how long this might be?
Just published, the Retail Charity Bonds webinar, here, from last week. These bonds offer a yield of between 2.7% to 4.8%. Mark goes through each issue in detail. There's a helpful summary slide on price and yields, towards the end. The Q&A is also very interesting.
Looking forward, we are thrilled to be joined by Andy Brough, for the next educational piworld Thursday webinar. This is a week on Thursday, 16th July, 1pm. We will draw on Andy's experience, to talk us through some of the tricks of the trade. An Amazing Hour with Andy Brough, including time for your Q&A. Register here.
I have met Andy , he is one smart cookie and a very nice guy. Thanks Tamzin I am looking forward to this webinar !
A truly brilliant read !
Thanks very much for this Paul, insightful and very, very entertaining.
Can we look forward to a Christmas publication of “2020 - The Bournemouth Diaries” ?
Paul, after reading your preamble I've come to the conclusion you went on a pub crawl - in the name of research of course ;-)
Yup, that's the one!
"from about 6-9pm when I was out & about"
Woah! - So, in that time you managed a "panini & chips" plus "a cooked breakfast"?
I'm not sure everyone on here fully appreciates the lengths you go to in the cause of research Paul ;)
But, I think you're right - with all these additional costs, particularly extra staff, and much reduced capacities, how are these places going to manage to turn a profit, or even break even?
Yes that's how I read it but thought I was missing something ! I mean I can eat for England but this sounds a lot !!
I think there will be a new normal as far as pubs go. Very few have reopened in Deal Kent. We are blessed with many micro brewers and the invention of the micro pub, which started off with a one armed landlord converting a tiny Butchers shop in Herne about ten years ago. With various witty or homely names like The Potting Shed, The Firkin Arms, The Freed Man, The Wrong Turn, Time and Tides, they are now they're all over Kent, but not seen many outside the county. The beers are truly amazing. I can't beer (apologies) to waste money on the big breweries rubbish beer and their pathetic attempts at 'craft beer.' They just don't get it. All they see is bandwagon. The micro brewers, who have some dedicated ground breaking master brewers, and micro pubs have been doing good takeaway business during lockdown too. I welcome this is the new norm. The other benefit is pricing, anywhere from £2.50 -£3.50 a pint for real beer!
Bath's micro brewers charge the Earth but that may be changing.
I wonder if UP Global Sourcing Holdings (LON:UPGS) will resume its dividends now that there seems to be light at the end of the tunnel? They suspended their interim dividend as a precautionary measure for Covid issues.
Could it be that they will declare a larger final dividend with an element of a special dividend?
I am holder, and would be interested in Paul's view of the trading statement, which on the whole seemed pretty positive
Trident, Up Global Sourcing Holdings (LON:UPGS) must be one of many companies which cancelled dividends. I hold shares in a few of them but don't hold out much hope as directors may decide to award themselves bonuses for navigating the quirks of LockDown rather than reward investors for their patience.
On UP Global Sourcing Holdings (LON:UPGS) ...just about the best way directors can reward themselves is through dividends as they own a big chunk of stock (c.40%).
My most significant negative for this business is that I would like them to pay less dividends ((they target a 50% payout pa). They have decent long term growth prospects. I like that they are cautious and prudent on how and where they invest (good job historically) but I think they have the scope to risk a bit more investing for the future and making sure they are max ready and able to grow revenue.
Silver Moon. I think the management of UP Global Sourcing Holdings (LON:UPGS) are fairly decent, as far as I can gather, and also a member of their non-exec board bought a fair slug of it to put in his pension previously, so I am reasonably confident they will be thinking about dividends. But no guarantee of course!
Hi Paul, could i get your thought on Macfarlane (LON:MACF), Up Global Sourcing Holdings (LON:UPGS) and Cohort (LON:CHRT)?
Cheers
Anything else at all?!
Hi,
Does anyone know what has triggered the rise in Diaceutics (LON:DXRX)
It's obvious that this is going to be a multi-bagger with final results reporting revenue up 30%, gross profit up 52% and gross margin of 77% (LY: 66%). Is this the type of company that just rises because of a very strong final results published 3 months ago, or is it down to this article published over the weekend?
https://www.thisismoney.co.uk/money/investing/article-8489989/MIDAS-SHARE-TIPS-High-tech-drugs-firm-Diaceutics-really-hits-spot.html
Anyone else following this?
Cheers
Think it was tipped in Daily Mail over the weekend
Thank you mickyd33 for letting me know that Diaceutics (LON:DXRX) has been tipped :)
"It's obvious that this is going to be a multi-bagger..."
Is it? It's on a PE multiple of over 100.
Hi Paul, an evaluation of United Oil & Gas (LSE: UOG) would be appreciated at some point.... Not sure if junior oilers is something you dabble in though,
Sorry no, I don't cover the resources sector at all. It's too specialised, and there are too many companies (many of which are complete rubbish). So not a good use of my time, hence why I completely ignore this sector.
BOO has dropped 9% this morning on the news that they have breached the Government's coronavirus guidelines in their UK factory and have helped cause a local spike in coronavirus.
Correction: Boo don’t have any factories.
Agreed. It is a UK factory that supplies them. The market has gone into a tizz over it this morning.
I expect the sp will recover.
From older conversations I think Boohoo (LON:BOO) subcontract.
This is what I think.
Short term:
a) they knew that those factories were below min wage and not safe
- they are in really big trouble
b) they did not know that those factories were below min wage and not safe
- they are in some trouble
Long term
a) they can maintain margins
- all is well
b) they cannot maintain margins
- they are in trouble
(was a holder, sold @~240, regret now, think this is an excellent business)
They have to ensure the supply chain conforms to the Modern Slavery Act. This could be an issue for them.
Any ideas on BOO?
A storm in a teacup? The world is its oyster.
I have seen several Panorama style exposes of Leicester based 'sub-contractors' over the years. It fairly obvious that there is a continuing problem in that area, and I further suspect even if some were closed down, they would arise from the flames fairly quickly unless as issue it is continually monitored, which evidently is not the case.
I should think the whole issue is fraught given the weighting of the Asian population in the area, leaving it wide open to exploitation. Cultural biases that should have remained in the 'homeland' are often imported, and often with those who are exploited having poor English and perhaps being poorly educated, and some perhaps being here illegally, makes it all the easier to occur.
My morning smallcap tweet: Part 2/2
Macfarlane (LON:MACF) £N4P UAE Oil Services (LON:UOS)
Macfarlane (MACF) Q2 better than expected with rev down only 7%. Guides FY profit and staying well within the current borrowing facility.
N4 Pharma (N4P) optimisation programme progress slower than originally hoped. Also Evotec remains on track with the in vitro testing of Nuvec loaded with the Covid plasmid. Also "recent research on Nuvec indicates that its unique spiky structure could give it a significant competitive advantage as a potential delivery system for use in oral vaccines."
UAE Oil Services (UOS) exec chmn scarpers 'in order to focus on other projects'. He is not thanked.
Rockrose Energy (LON:RRE) please
Rockrose Energy (LON:RRE) seems pretty sensible, anyone who holds or bought, well done! Choose to cash out today with the market spike, or hold on until the formal offer comes through for a few pence more.
The only question you have to ask in your mind is there likely to be another company come in and offer a higher bid? With the premium paid and the number of companies around in the OG&C sector maybe but slim given the price rise to what it could have been bought at a couple of months back and the future uncertainty and obvious downstream liabilities.
Pretty disappointed myself. I bought around the 1880p level so I am going to nurse a loss on the takeover, even if marginal. That's worse when net cash exceeds 2200p.
I get the future decommissioning liabilities but even at current oil prices that should be more than covered. Feels like Directors/original founders have decided to cash out given their massive gains and 33% ownership, which you can understand from a personal level. But also feel as though this is a low ball bid from an opportunistic bidder that I don't believe represents the true value in the assets. So for me a big thumbs down but I guess I will nurse the small loss and move on.
Tommy - you couldn't have bought Rockrose Energy (LON:RRE) at prices seen in the market a couple of months ago. It is too tightly held so there was zero opportunity to buy the company at those levels. This is about as cheap as another company would get it.
That said I don't think there will be a counter bidder imo. It's a trade sale of a market listed vehicle.
I'd be interested in thoughts on Macfarlane. Announced positive results regarding trading this morning, seems to be have a track record of growth, but has mostly traded sideways(ish) for a couple of years prior to COVID.
Re Macfarlane (LON:MACF) I thought the intro to the trading update might be setting us up for something nasty but agreed it sounds pretty positive. Q2 was down 7% not 25% (as had been expected in the May update), and net debt has reduced further. So all good, albeit there is continued weakness in a few divisions. The disappointing bit to me is that in May they (understandably) concluded that they couldn't give guidance but expected the business to remain profitable both in Q2 and the year overall. Now 2 months on and with better trading than anticipated they still say only that they 'expect the business to remain profitable in 2020'. Sounds a little bit vague/ conservative, especially when they've been consistently very profitable (c£10-12m PBT p.a. for the last few years). Though I guess they don't want to say more with the outlook generally still very uncertain.
Re Macfarlane (LON:MACF) There was also what I thought was a rather strange paragraph concerning furlough payments in the update.
"In line with the UK Government's aim to preserve employment levels, we furloughed approximately 30% of staff through the Coronavirus Job Retention Scheme in the second quarter to protect employment during the period of uncertainty. However, in the light of the better than expected trading performance, and as we gradually bring employees back from furlough, we do not intend to make any further claims under the Scheme and in the second half of the year we will seek to repay sums already received."
(My bold). They clearly seem to be suggesting that they will seek to repay furlough already received for staff who were not working at the time. AFAIK, there is nothing in the furlough scheme to mandate this, and I am not aware of any prohibition on furlough recipients to not pay dividends, so this seems like seeking to make a voluntary repayment to me, unless anyone can suggest a reason? It's almost like they are embarrassed to receive it given the better than expected performance.I am confused by companies wanting to pay back the Furlough money. Many seem to be either doing this or plan to. Although this is honourable I do not see the financial sense in doing so.
eltorero - me too. Hopefully someone far cleverer than I can explain the thinking. Games Workshop (LON:GAW) is a big holding for me and they are one of the companies saying they are going to pay back furlough money. In a way I'm happy to be supporting a company with such high moral standards but would still like to understand the logic behind handing back free "income".
I don't think companies handing back furlough payments are demonstrating high moral standards at all. Far from it. Instead they are giving themselves greater flexibility in the future with regard making mass redundancies, paying dividends etc.
Although it may not account for the companies mentioned above, keen eyed observers have apparently noticed different Government wording now appearing as part of the furlough scheme.
It’s been interpreted that there might be some further financial penalties to receiving money via the furlough scheme and being able to shed jobs in the future.
"Free" meaning that we tax payers paid for it? Well done GAW.
It's called mitigate reputational risk as opposed to financial risk. Something, where I work, is regularly commented on.
Another example, it made no sense for Admiral to give back £50 customers' insurance premiums but it perfect sense in terms of PR. The very act gives the impression to wider public the company is ethical and trustworthy.
My morning smallcap tweet: Part 1/2.
Gunsynd (LON:GUN) Boohoo (LON:BOO) BigDish (LON:DISH) ValiRx (LON:VAL) Urban Logistics Reit (LON:SHED) Gresham Technologies (LON:GHT) Dev Clever Holdings (LON:DEV) Zoetic International (LON:ZOE) Filtronic (LON:FTC) UP Global Sourcing Holdings (LON:UPGS) Collagen Solutions (LON:COS) Cohort (LON:CHRT) Concepta (LON:CPT) Mobile Streams (LON:MOS) Fusion Antibodies (LON:FAB) Sabien Technology (LON:SNT)
Gunsynd (GUN) £465k placing at 0.65p, a 7% disc.
boohoo (BOO) strong response to Sunday Times exposure of alleged supplier malpractices.
BigDish (DISH) expands scope of business from discount app to 'a complete dining solution for restaurants and consumers', as if that was possible. Will scrap commission and charge monthly fee. There is probably a reason no other co does this. Good luck to them. Will offer food delivery app and a Super App - many apps within an umbrella app.
ValiRx (VAL) new corporate strategy for tinpot co - "will build on its existing portfolio of drug candidates and grow a pipeline of innovative, early-stage projects in the areas of oncology and women's health..."We've shifted the development paradigm for ValiRx to earlier in the drug discovery process. This is intended to maximise the impact that our intellectual and financial contribution can make."
Urban Logistics (SHED) 98% of Q rent has been collected.
Gresham Technologies (GHT) guides H1 rev down 2%. Recent orders mean mgmt confident will hit FY guidance for adj EBITDA and 'Cash' EBITDA.
Dev Clever, (DEV) partnership agreement with Veative Labs, a leading provider of online and immersive learning modules within the EdTech sector. Will "creates a fully comprehensive remote e-learning solution."
Zoetic (ZOE) first international distributor for its Chill brand of tobacco alternative CBD products, for Czech Republic and Slovakia. JV with former COE ended, co claims transitional period has now concluded. UK operations will remain uninterrupted with no change to the fulfilment of online sales of the 21 existing product lines.
Filtronic (FTC) wins 2 year £4.9m order, delivery starting Aug.
UP Global Sourcing (UPGS) guides FY above mkt expectations with rev over £111m and U/L pretax above £7.4m.
Collagen Solutions (COS) a euphemistic 'Realignment of Bond Repayments' - a reduction in capital repayments and a delay to the final repayments.
Cohort (CHRT) wins 2 year £20m order, delivery starts in FY21 H2.
Concepta (CPT) relaunches MyLotus fertility fertility tracking and pregnancy self-testing system. Renames it and will sell online. Marketing campaign. Has it bombed? Claims 5k app downloads but no fig for paying users. Also 30% cost reduction to the current operating overhead with more to come.
Mobile Streams (MOS) in an RNS that misspells its own name, launches an SaaS Insight platform. Over 30 launch partners signed up. "SaaS Platform has been designed to provide ease of use, simple access, and price points that focus on small/medium business and individuals looking to gain insight for their digital marketing strategies."
Fusion Antibodies (FAB) has commenced its proof-of-concept work on the Mammalian Antibody Library Discovery Platform. Also hits first milestone in covid associated project, with the synthesis of the antibody library DNA. CEO trumpets "excellent progress on the launch of the proof-of-concept for the Mammalian Library and have generated a panel of SARS-CoV-2 S antigens." Antigens? Is that in addition to the antibody library?
Sabien Technology (SNT) H2 rev 2x H1 but FY still down due to covid and an exceptional order last year. "Board believes that first half sales represent a "low watermark" after several years of diminishing performance by the previous Board...Sabien is planning a strong start to the new financial period with a backlog of more than 300 M2G units to install and a confirmed order book of approximately £140k."
Re BigDish (LON:DISH)
Even if they get some initial success, I cannot see how they can defend their ideas against other companies in the restaurant space copying them. e.g. what’s to stop Opentable eating their lunch, if you’ll forgive the pun?
Changing the business model right now looks like an act of desperation.
(I hold) I suspect they are trying to capitalise on the current trends (valuation and takeovers) going on in the space. I do think it probably makes sense to offer additional services to their existing customer base given the current climate.
According to their web site Big Dish seem to have a maximum of 54 restaurants signed up in Birmingham, Brighton, Bournemouth and London. I would have thought that if this were an idea that appealed to restaurant owners they could have had these signed up in a few weeks. I know that when my son, who is involved in web design, looked at this perhaps a year ago he thought it was one of the worst designed web sites he had seen. Where they have taken the business at present looks more appropriate for someone working from home and not a public company. When you look at food delivery there are well established companies doing this although in our area even they feature few of the better quality restaurants.
R.e BigDish,
I have a small sized punt esque holding in these but not sure how to take their latest update. Seems a bit muddled. If they can gain traction and make a success of the SaaS model then it could do well but they've definitely got a lot of work to do.
I'm on the fence tbh and don't feel inclined to add to the position currently until they can show some signs of good progress.
Rockrose Energy (LON:RRE) - 1850p all cash bid. Not to be sniffed at pre-second wave.
Should I hold or sell?
Depends! If you want the money for something else then sell now, if not the hold and get the full 1850p. I'm holding.
Paul/Graham don’t cover resource stocks but as this was one of the Stocko subscribers picks for 2020 so is worth a comment here. For all the talk about premiums to current closing price (64%) and average closing price for last 3 months (91 %), all of which was in oil price collapse and Covid-19 lockdown period, this looks a very opportunistic bid to me. The price offered is about the same as the share was trading at in mid-Feb before the pandemic and during the ongoing spat between the Saudis and Russia. Also at start of year it was trading above £20. The Rockrose management must be taking a pessimistic view of future oil prices and demand - consistent I guess with recent major writedowns seen from £BP and £RDSB. - and have decided to cash in. I can’t see anyone coming in with a counter bid in the current climate so the question for holders is will the deal go through? Any doubts about it completing at agreed price then it is probably a good time to sell. As a my case this would be at a small loss vs. my buy price of £19.22 which is a lot better than the last few weeks with share well below the £10 mark. For the proposed acquirer it would seem to be a ‘bet’ on the oil price recovering significantly. If they are right then they will be the beneficiaries not the existing shareholders.
Royal Dutch Shell (LON:RDSB) was over £20 at the beginning of the year too. Personal view is that oil has had it.
Up Global Sourcing Holdings (LON:UPGS) has issued an unscheduled trading update with quantified revenue and profits ahead of expectations.
UP Global Sourcing Holdings (LON:UPGS) you can take a look at our upgraded numbers here:
https://research.equitydevelopment.co.uk/research/brisk-growth-rate-supports-higher-valuation
Obviously not a small cap, but an honourable mention for Barratt Developments (LON:BDEV) for their remedial work at Citiscape and other buildings, which they decided to undertake after Grenfell, as per https://www.investegate.co.uk/barratt-developments--bdev-/rns/trading-update/202007060700070607S/.
Very good reputationally and quite probably life changing for those living in these buildings.