Small Cap Value Report (Mon 6 Mar 2023) - WAND, CPI, SEE, FOXT, CRW, CKN

Good morning from Paul & Graham!
Weekend podcast - went up on Sunday. I was pleased with this one, some interesting stuff in it, even if I say so myself! See Friday's SCVR here for the mystery shares (3 of them last week). I'll also add a reader comment below to list the mystery shares (my best ideas from the week).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
WANdisco (LON:WAND) (Paul holds)
1318p (pre market open)
Market cap £911m
This is self-explanatory -
As a dual UK and US headquartered technology company, WANdisco has long-stated its intention to consider an additional listing of its ordinary shares in the United States. The company can confirm that it is in the early stages of proactively exploring this option.
The Company also confirms that it remains committed to London's Alternative Investment Market ("AIM") and to maintaining its current UK AIM listing.
My opinion - I met management last week, with the overall picture being the same as my previous comments here on the company. The story is that it’s won a series of big contracts (which take time to convert into revenue) over the last c.9 months. WAND has special software for handling & moving large amounts of data, and it claims to be the only software capable of doing so accurately. With the proliferation of data caused by 5G, WAND says its software is now in big demand, initially from telecoms and car manufacturers.
If even part of what the super-bullish CEO claims for the company actually happens, then this company could become an important player in the infrastructure of the internet.
As the RNS says today, it’s been an open secret that WAND was considering a US listing.
Ironically, the UK has attributed a lofty valuation to WAND, whereas usually the complaint is that the UK markets are not liquid enough & don’t match the sky high tech company valuations that the far deeper liquidity of the US markets enable.
It will be interesting to see if WAND shares continue rising on this news. It’s interesting how private investors seem generally sceptical about WAND, and it is far from being a bulletin board favourite. Will that change I wonder?
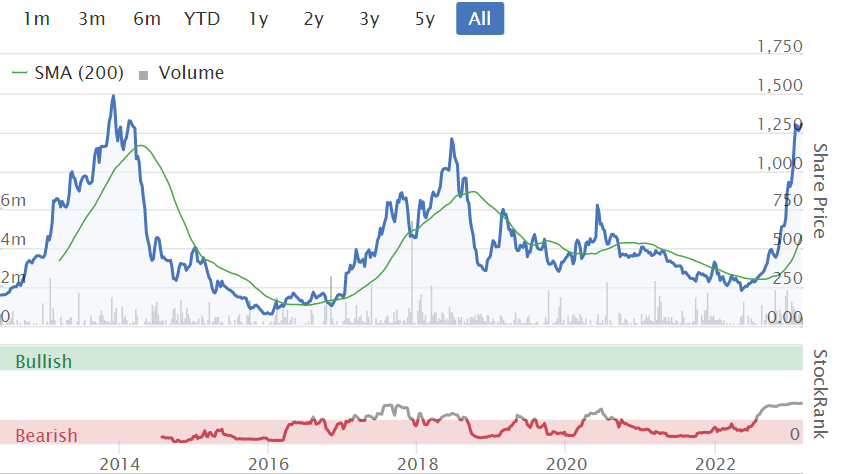
I remain intrigued by this share, with the contract wins having convinced me to buy. I’m sitting tight, and see this as a fairly speculative position, because it has had false dawns in the past. A value share, this is very much not! Past performance has been diabolical, so it's the future that investors are buying into.
It's been a 5-bagger in the last 12 months. Looking at the longer-term chart below, you can see where it promised the world, and failed to deliver before. Hence why I'm holding on to some scepticism, and not going in too big with my position sizing for my personal holding in WAND -
Capita (LON:CPI) (Paul holds)
39p (Friday’s close)
Market cap £659m
I flagged this share on Friday as looking like a potentially interesting recovery share. This weekend I did a bit more digging, but am still only part way through my research process. Previously I rejected Capita as way too high risk. Indeed, re-reading my notes here from Nov 2020, Capita looked insolvent, with a balance sheet that had negative NTAV of a staggering £(1.6)bn.
Since then, the group has been transformed, with loads of disposals, and only small dilution from new share issuance. The balance sheet at end 2022 was still quite weak, but NTAV was £(360)m, a dramatic improvement.
Net debt has also been almost eliminated, and is expected to move into net cash by mid-2023, with further smaller disposals.
The financial risk has almost gone, so it’s a completely different investment proposition now, and it looks quite appealing to me.
I made the following notes of the main points whilst watching the recording of this webinar, for FY 12/2022 results -
Moved into profit
Positive free cashflow
Big disposals almost eliminated net financial debt down to £85m, with remaining disposals expected to at least wipe out this remaining debt later in 2023
Resilient business, with long-term contracts & very high renewals rate of 97% - which it says proves the quality services provided
CEO describes his 7 years at the helm thus - 2018-21: transformation, 2022: stabilisation, 2023: acceleration
Good pipeline of new contracts
Capita Public Service division: £1,445m revenues, £91.5m operating profit, a decent enough 6.3% margin
Capita Experience (which seems to be private sector clients): £1,151m revenues, £38.5m operating profit, a lower margin of 3.3%
Pension deficit funding - now £30m pa, due to fall to £15m pa. Now in accounting surplus, and the CFO reckons the 2023 actuarial valuation is likely to also be in surplus. So it looks as if the pension deficit should be permanently resolved in perhaps 2024.
Capex - being spent better now, “capex goes a lot further now” (CEO)
Cost reductions continuing, including making more use of its outsourcing (IT, etc) operations in Poland, S.Africa, and India
EBIT margin of 2.9% expected to “at least double in medium term”, CFO warned not to expect too great a step change in 2023, so this will be gradual
Revenue growth guidance in next few years, is c.5% pa
Cash generation in 2023 likely to be similar to 2022’s £99m
Embraced hybrid working for staff, lowers office costs, and reduced absenteeism
CEO - key phrase used, “We’re NOT going to repeat the mistakes made in the past”
UK public sector - Capita has 10% market share, with strong growth potential
All contract renewals saw improved terms, and two thirds of contracts already have in-built protection against higher inflation. CEO reckons they can be more aggressive on pricing in future
Experience division - large, growing market. Book to bill was 1.2 in 2022
AI based innovation is important & growing. Gave example of Scottish Power new contract, using chat bots, customer “delighted” with the service
Going concern - auditors “material uncertainty” view was eliminated in latest results. CEO praised CFO, who rebutted this, saying it’s the strong cash generation (mainly from disposal of Pay 360) which caused this to no longer be required - seems a good dynamic between the CEO & CFO
Dividends - not yet committed to anything definite, but it seems obvious that divis will resume in 2023, since it should reach a net cash position
Summary - I think this looks very interesting, with possibly a lot more scope for this share to re-rate further (if I had to guess, 70p strikes me as possible, with patience, versus the current 39p)
Plan to double EBIT margin from 2.9% to c.6% would itself drive share price a lot higher, I reckon
“De minimis” financial debt now expected by mid-2023, maybe even net cash - that’s totally transformed from a couple of years ago, and it seems to me this could now be driving a re-rating of Capita shares
Pension deficit - pretty much sorted, on both accounting (already in surplus £40m), and soon to also be actuarial basis, probably
Inflation protection already in most contracts
Upbeat outlook comments
Dividends due to resume this year, probably
Put that lot together, and I suspect we’re seeing a sustainable re-rating in this share, and it still looks cheap. Whereas just over 2 years ago, it looked like a complete basket case.
Overall then, it gets a thumbs up from me, but I do want to reiterate that it’s a large complex business, so I’m a little out of my comfort zone analysing this.
Note the StockRank is quite high, at 84.
I am ignoring the weak Z-score, because recent disposals have resolved the previously over-geared balance sheet.
Clarkson (LON:CKN)
3475p (up 5% at 09:22)
Market cap £1.06bn
Tremendous figures announced today for this shipping services group, for FY 12/2022 -

At 3475p per share, that makes the PER on FY 12/2022 earnings 13.9x which seems reasonable.
Are earnings sustainable though? Or has this been a boost from all the pandemic-related disruption to shipping? That’s the key question.
Outlook - this is encouraging, with Clarkson suggesting it has favourable market conditions for some time to come -
"Whilst the global geo-political outlook for 2023 and beyond remains uncertain, the green transition is driving significant activity in our industry. This, coupled with a supply and demand balance that will create meaningful supply-side constraints supporting the market, and our strong forward order book, gives us confidence in the outlook for Clarksons."...
Whilst there are considerable uncertainties in the geo-political landscape, we are confident that supply-side constraints brought about by years of underinvestment and the pressure on shipowners and charterers to decarbonise, will provide significant opportunities for Clarksons long into the future.
Balance sheet - my obligatory check of the finances. This looks very good at first sight.
NAV is £413m, take off £189m intangibles (so it’s done some hefty acquisitions to accumulate a figure this big), and NTAV is still decent at £224m.
There’s a big cash pile of £384m gross, although given the large trade creditors, it looks like a fair bit of that will be client cash - does the company earn interest on that now, I wonder?
There’s a small accounting surplus of £15.8m for the pension scheme.
On digging a bit deeper, I’ve found something rather alarming in the notes, right at the end, it says that most of the cash pile is due to be paid out in bonuses, a colossal amount!
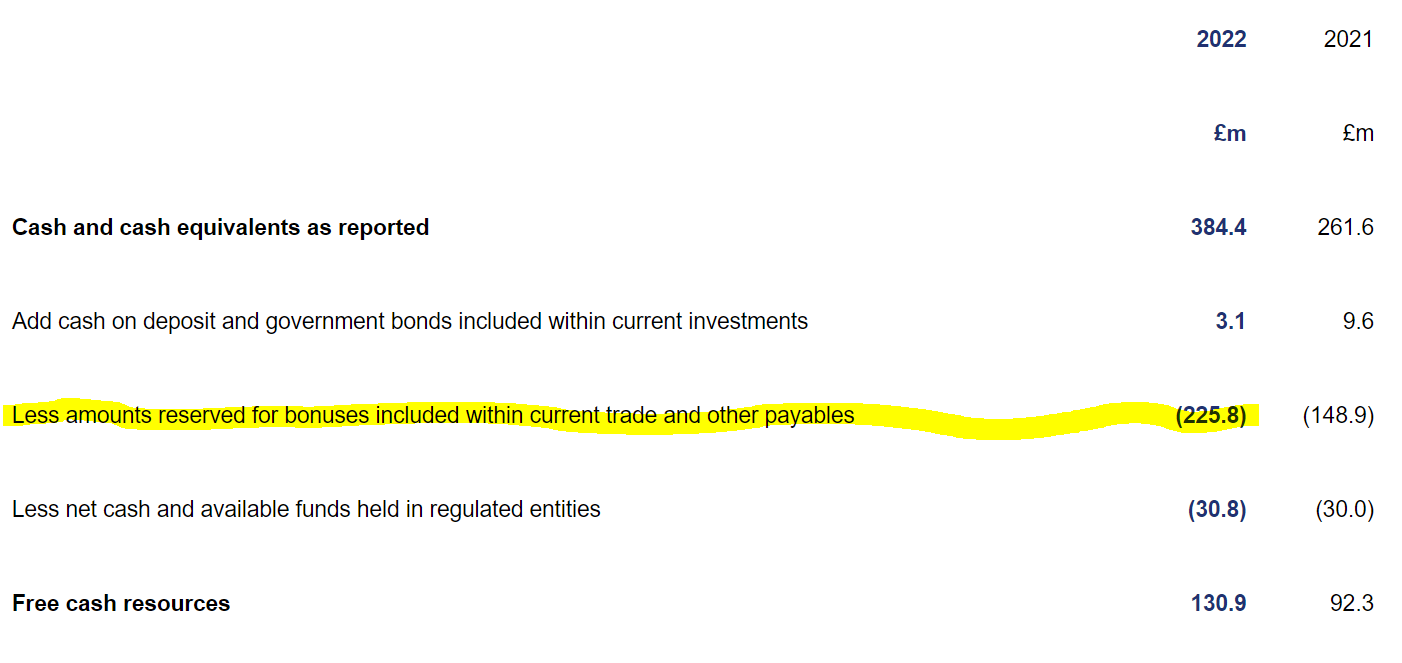
I also note from the cashflow statement that £20.4m was spent buying shares for the employees’ ESOP. Plus an £88.8m increase in the “bonus accrual”. This dwarfs the cash paid to shareholders, divis of £25.9m.
My opinion - I was going to conclude positively, until I found those massive bonus numbers, which does make me wonder for whose benefit this company is run?
If more than half the cash pile is to be paid out in bonuses, dwarfing divis, I would find this very challenging to invest in.
Hence I’m obliged to raise the questions about Clarkson, and hence can only mark it as amber.
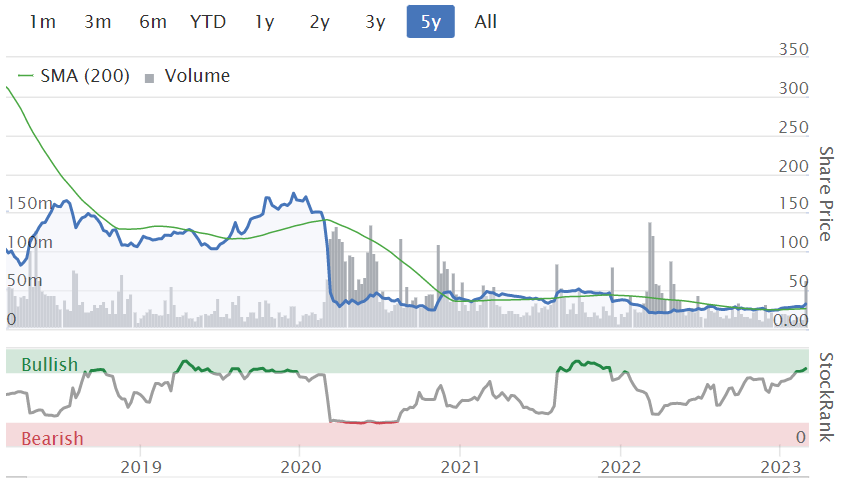
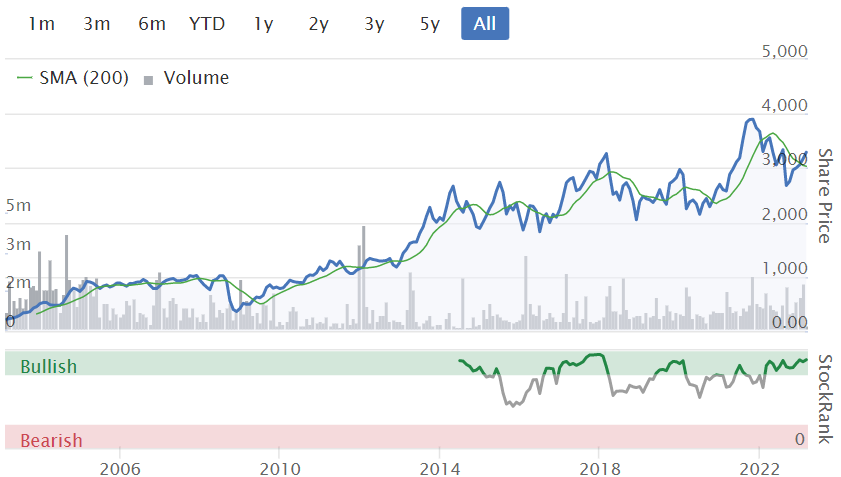
Shares have zig-zagged sideways for the last 5 years, but the longer term trend is good.
Also note that Stockopedia likes it, with a strong StockRank-
Graham’s Section:
Seeing Machines (LON:SEE)
Share price: 7.44p (pre-market)
Market cap: £310m ($373m)
This describes itself as “the advanced computer vision technology company that designs AI-powered operator monitoring systems to improve transport safety”. We last covered it in October.
I don’t normally spend too much time covering cash-burning, blue-sky type companies, but this one has a market cap of over £300m and so it has clearly captured the imaginations of some investors.
Today’s interim results are presented in US dollars for the first time (previously Australian dollars - the company is headquartered in Canberra).
Highlights:
Revenue up 54% to $24.4m, led by strong growth in the “Automotive and Aviation” category. Revenue in the “Aftermarket” category declined.
Gross profit more than doubled to $15.5m
Net loss halved to $5.4m.
The cash balance finished H1 at $52.2m.
Convertible note: Seeing Machines has borrowed $30m under the facility I previously discussed (a convertible note that charges 8% and can be converted to equity at 11p). The company says it is “fully funded to deliver on its current business plan for the foreseeable future”.
Deals: the company now has “15 automotive programs spanning 10 individual OEMs, covering more than 160 distinct vehicle models”. The initial lifetime value of all of these deals is $321m.
The company’s technology is currently monitoring 46,000 individual vehicles.
Outlook for FY June 2023: in line with expectations (revenue $53.9m, EBITDA of minus $12.7m).
My view
I’m impressed by some aspects of this report. The net less halving to $5.4m is a big one: if losses and cash burn slowed down considerably, then I might have to review my negative stance on this stock.
But then I remembered that Seeing Machines capitalises lots of development costs, i.e. it keeps them off the income statement by turning them into balance sheet assets instead.
Today’s cash flow statement shows $11m of capitalised development costs, up from $8.6m in H1 last year.

Indeed, if I simply add the operating cash outflow and the investing cash outflows together, I find a cash burn (before financing activities) of $18.5m in H1, up from $16.9m in H1 last year.
So even though the net loss halved, the cash burn was the same for the six-month period.
Also, while the $52m gross cash balance is impressive, net cash is only $22m when you deduct the face value of the outstanding convertible note. This note is not due for repayment until 2026, which does at least give the company time. And there is always the possibility of conversion at 11p, which will negate the challenge of repaying it.
The progress on deals with automotive OEMs is undeniably impressive. However, based on the financial numbers, I’m going to have to retain my negative stance on this one. The cash burn is still too strong for me to do otherwise.
Foxtons (LON:FOXT)
Share price: 40.95p (+2%)
Market cap: £123m
This London estate agent announces the £7m acquisition of an agent with four branches in Central East London - Atkinson McLeod.
It’s not immediately obvious from their website, but Atkinson McLeod is very heavily weighted towards lettings with 90% of their revenues coming from that side of the business.
The strategic rationale:
The acquisition of Atkinson McLeod represents further progress against our strategy of acquiring lettings businesses that deliver an attractive return on invested capital, enhance earnings and improve the resilience of the Group's earnings, whilst also reinforcing Foxtons as London's largest lettings brand.
As we’ve discussed many times before, lettings management provides a very dependable source of income.
Foxtons remind us of their performance in 2022: “non-cyclical and recurring revenues, primarily delivered by lettings, represented c.65% of Group revenue, significantly enhancing the earnings resilience of the Group.”
The acquired business generated an operating profit of £0.9m on revenues of £3m in FY March 2022. Strip out some costs to increase profitability and the earnings multiple on this deal should be very reasonable. It has c. 1,100 tenancies under management (Foxtons has 27,500).
My view
While I like this acquisition, I haven’t got a strong view on the merits of Foxtons shares. It has had a difficult few years and can still be classified as a turnaround stock:
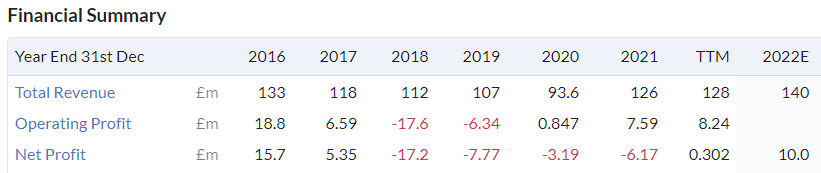
In “normal” property market conditions it should do very well, and maybe those conditions aren’t too far away. Revenue stability is also much better now, given the heavy focus on lettings. And it passes some of Stockopedia’s bullish stock screens:
So it could be worth researching in greater detail.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
Well sniffed
Interesting results out from Batm Advanced Communications (LON:BVC) today, growth prospects look excellent. Admittedly hard to get a handle on this company though as I don’t really understand all the IT jargon! Partnerships and contract wins look encouraging. Worth a look at current price imo (I hold).
Terrible results from BATM Advanced Communications burning about $25m. I think there is also a criminal investigation involving one of its subsidiaries in Italy.
Thanks for your response yiannos1. R&D spend it looked like, which does seem to be a theme. Although the balance sheet was reported as strong and revenue growth looked pretty good, but admittedly, I’m no accountant.
This was a recent entry for me with trade plan defined, so will wait and see what happens. Do you have a link to the Italy story?
I am afraid I do not have a link but I do remember that it involved Adaltis , its subsidiary in Italy.
BATM is one of those companies that borrow money every year , but at the same time claim that they have 3 times that amount as cash in their balance sheet. Maybe they do , but it is always a red flag for me.
Good luck though.
Paul,
I have moved two chunks of SIPP to HL, including one a couple of weeks ago. One transfer took two weeks, one transfer took one week. You may find you are surprised to the upside.
If you haven’t heard back from HL within a week of submitting your transfer, chase them via secure message.
Thanks GavSmith!
I'll report back once my SIPP has transferred to HL. Hopefully my experience might mirror yours, of only 1-2 weeks, I'd be very pleased if that is the case. Although I suppose it depends on the counter-party.
Regards, Paul.
My experience of HL and their efficiency and customer experience has always been very positive.
Their transaction charges are lower than you suggested earlier as they fall with only modest transaction levels.
The only downside is that sometimes - in volatile market conditions and particularly for smaller cap stocks - it can be hard to transact, even to buy.
Hi Jayman
"The only downside is that sometimes - in volatile market conditions and particularly for smaller cap stocks - it can be hard to transact, even to buy."
I've found the same issue when using the HL website on my laptop, however, even in the most volatile times, I'm able to continue trading on their (Android) app.
A
Hi abtan,
Interesting. I've been on their app for about a year and found it an excellent tool and soooo convenient but its doesn't quite have all the functionality of the website.
Not sure about "market access/execution" issues. Certainly in volatile conditions for small caps there have been issues and not just the 2nd/3rd weeks of March 2020, as an extreme example. I'm sure they would have, even then, have been trading in FTSE250 stock just fine, but the community interest here is in the much smaller caps.
I'm defo paying only about £9 per trade which makes even small, incremental purchases/sales (say only £1.5k) economic.
Helpful to get others' perspectives of the respective offerings of all of the competing platforms.
The idea of paying commission of hundreds of pounds as Paul was suggesting is ludicrous.
Regards
Coral Products (LON:CRU) I have held for many years. Anyone know why such large trading volume today? 4 mil shares traded. There's only been one month in last 12 that the Monthly volume has been over 4 mil!
Tipped today by Simon Thompson in Investors Chronicle
Thanks Westway001
Thank you Roger and Westway001, just looking today and seeing it had a big rise and big volume, obviously here is me looking at 21:18 so not a lot I can do, but nice to see it bounce back...
As always should have bought more a while back :)
Tommy
ps. I hold Coral Products (LON:CRU)
As a novice investor, I wonder whether wiser heads here can help me ?
I sold my holding in Craneware (LON:CRW) this afternoon (at pretty much breakeven, so this is a learning exercise for me, more than anything else).
The results today state that their H1 23 profit before tax is $5.2m(as opposed to $6.2 H1 22), so the outlook for the full year one would expect to be slightly less net profit than last year $9.41m.
The interim statement claims 'we are confident in delivering results for the year in line with consensus and look to the future with confidence'
The current consensus for me is the 86.3c EPS and $30.7m net profit - does this mean that they intend to make 5x the profits in H2 than they made in H1 ? In my calculations the current PE should be about 70x assuming that they do about as well as last year..
What am I getting wrong ? !
Small cap liquidity seems low and bouncing prices .
Good to see Avingtrans bouncing up from the lows, it slid on just a bit of selling and has bounced on a bit of buying.
Small cap market seems to have very low liquidity at the moment and quick 15-20% slides are then accompanied by equally quick 15-20% rises.
Guess until there is a sustained influx of "sitting on the fence funds" this will be modus operandi for the foreseeable future .
Best tactic is probably to keep checking on the reason you invested and asking yourself if anything has changed other than price.
Stock market is a voting machine, value a business using a weighing machine.
Hard to keep a clear head sometimes.
Example I was buying Watkin Jones quite happily at 103 level (after dividend) but now its 93/94 I am not buying .
Hard to think and act like Warrenn Buffet ("we like it when prices go down we can buy more" )
Yes I noticed this quite a bit recently, big falls then recover, even some US mid caps are doing it, one of mine fell 15% in early trading but finished only 3% down, on no news. I do hold Watkin Jones (LON:WJG) , considering topping up. Also hold Avingtrans (LON:AVG).
Don't forget Warren always keeps $10 billion in cash
I've also been thinking of this "volatility" in the markets recently, where it looks like we do have wild swings in prices. I wrote about it more in my Feb commentary yesterday.
My thinking is that to mitigate being "unlucky" with your buy or sell pricing, the way to do it would be to break down your buys and sells to take place over multiple days. This also gets over the problem of low liquidity, by tapping multiple days.
Big investors do this all the time when buying or selling big chunks; but it looks like we might need to start doing this too, as smaller investors.
Hi Paul
Just wanted to say a big thank you for your very insightful review and comments on Clarkson. much appreciated.
It also shows the degree of interaction between the community here and you and Graham. CKN was not on your list in the early edition but you kindly added it later.
Thank you again
Hello Paul, I think the tags have fallen off today's report, there were some earlier.
Brilliant, thank you Rusty2, I hadn't spotted that the tags had disappeared again. I've put them back in now.
Graham I'm going to disagree with you on Seeing Machines (LON:SEE) .
Although you do make some valid points about cash burn we are now approaching the period where all the previous investment by the company will start to pay off.
Whilst cash burn is high the Magna deal which was incredible considering the markets means they have more than enough to become cash flow positive.
Won contracts together with regulatory taikwinds mean that the company is expecting sales of around 3 million units in 2024, 6 million units in 2025 and 11.5million units in 2026. This is just based on the contracts they've won to date. At over $10 a unit you can see revenue increasing significantly in this division.
The aftermarket division has seen some taikwinds with stock issues. That looks like it's now been resolved. They are also due to launch a low cost generation 3 product that will significantly increase the addressable market. They are working with Mobileye to bring together a driver facing and outward facing product that should appeal to major fleet operators.
Within fleet annual recurring revenues are growing steadily and contract renewal rates are above 97%
Finally nothing is really added for aviation. I'm expecting a license deal and significant contacts in that division over the next few years.
All in all I'm very optimistic for the future.
I forgot to say that the automotive revenue per car is at over 90% margin.
Seeing Machines (LON:SEE)
Thanks for the comment Boonboon. I seriously considered switching to an "Amber" rating today, given the revenue that's coming up, but couldn't quite force myself to do it! Best of luck. G
Bango (LON:BGO) published an RNS this morning titled "Change of Advisor".
Although this type of RNS is usually pretty factual regarding the change, this RNS was more interesting:
Bango (AIM:BGO), the global platform for data-driven commerce, today announces the appointment of Singer Capital Markets as the Company's Nominated Advisor and Broker, and the appointment of Stifel Nicolaus Europe Limited as Joint Broker, effective immediately.
Bango CEO, Paul Larbey, said: "Bango is on an incredibly strong growth trajectory, which is attracting interest from institutional investors internationally. To serve our growing investor base we believe the appointment of a new Nomad and a joint broker will inject fresh energy and expanded reach through our investor engagement activities. We look forward to working with both Singers and Stifel as we embark on this next phase of our growth journey."
I think this type of very bullish commentary is uncommon. Bango has a CAGR of 42% since 2016 according to Stockopedia numbers and has been growing very strongly recently. Growth appears to be accelerating. They are attracting very large clients such as the Verizon and Apple which have only just begun to produce revenue. There are many potential growth drivers.
Bango is a company I know well. I have confidence in the directors and the strategy.
I have a large position in Bango.
Investegate |Bango PLC Announcements | Bango PLC: Change of Advisor
Crapita (after Private Eye) Capita (LON:CPI) , once the darling of HMG for contracting out services. What went wrong? Well, plenty of their contracts, but what does it do now?
Hi Paul, thanks for your comments and work on Capita (LON:CPI) today and on Friday. i think a lot of investors previously saw this as uninvestable due to concerns about the levels of debt and possible equity issuance. The significant disposals over the last couple of years should allay those concerns for most investors. At the very least more people will be prepared to give it proper consideration now and make their judgement on whether the low margins can improve to something more palatable. If they can the share price should continue to improve. I see that your write up today now has the " I hold" comment attached. I suspect quite a few more will be adding that comment too.
Morning Yellowstone!
Yes indeed, I picked up a tiny scrap of Capita (LON:CPI) on Friday, very much just dipping my toe in the water, to motivate me to do more research! Unfortunately I haven't got any spare cash to speak of, and my SIPP is locked down for several weeks, as I'm moving provider to save on fees.
But when I've got some available cash, I'd like to buy more Capita, it looks pretty good I think. As you say, a huge turnaround from its desperately weak financial position just a couple of years ago, and it's done that without much dilution too, even more impressive. The CEO and CFO came across well on the webinar I thought, focusing on the business basics of margins, operational delivery, etc, not fancy growth plans.
Regards, Paul.
Scrapita
Hi Paul,
You just mentioned something briefly about the transfer of SIPP which takes several weeks. This is a disgrace . Bank transfers and moving money in their system used to be like that. Thankfully , for the bank customers the money transfer is now instantaneous and changing banks have become much easier too.
I think the Share Society should make a strong representatives regarding this with the brokers. It seems getting divorce is easier than changing your broker if you have a large porto and trade frequently. It becomes a lifetime connection you never imagined when you joined!
Hi Lucky dip,
Yes indeed. I didn't really bother much with my SIPP, and it was largely dormant, so fees didn't really bother me. But now I've discontinued spread betting, which used to be my main activity & where most of my money was, my SIPP is back in focus, and I did more transactions recently, and found I was paying something crazy like £200-300 in broker fees per transaction! So I've decided to move it to one of the cheaper, online brokers (Hargreaves Lansdown), where each trade will be about £12 instead!
Given market gyrations over covid, then inflation/energy crisis, I've decided to be more active with my portfolio positions, rather than leaving the SIPP dormant effectively.
It is rather worrying that my positions are now locked down for what might be 6-8 weeks, so I won't be able to react to any newsflow. But I deliberately (mostly) picked things that I'm happy to hold long-term anyway, even if some bad news came out, with this in mind.
I also question why pension transfers take so long? Maybe the regulators could do something useful, and impose time limits of say a fortnight to get these done? It should be straightforward in most cases.
Despite not really giving it any attention, my SIPP has still managed to do about +17% pa compound since I created it (with some old, dormant, managed pensions with Prudential & HSBC) back in 2012. Hopefully I can improve on that, now that I'm taking it in hand & focusing a bit more!
Regards, Paul.
I have been using Barclays for a SIPP for years and they became rubbish when becoming Smart (hahaha) Investor. The time to transfer out has put me off doing so. Now considering setting up a new SIPP with Interactive Investor who have been fine in my experience for ISA and GIA. Has anyone any experience of ii SIPP please?
The only thing stopping me transferring out of Barclays is the time it takes. I joined Charles Schwab decades ago, who were great, but sold out to Barclays Stockbrokers, who were OK, but then the transfer to "Smart" Investor has increaed charges and lowered service. Someone finally rang about a complaint I made months ago the other day and effecively admited that the whole system was based around Barclays Bank Acc holders and those of us who bank elsewhere are effectively 2nd class citizens. Not sure where I'd go. II are fine, but I already have an account there, so I'd want to go somewhere else.
Hi Roger
II SIPP - I've had one since Alliance Trust were taken over by them. Pretty good - altough the recent "upgrade" of their site is far from that. It's become (laptop / Chrome) clunky with needless clicking needed.
It seems pretty cheap & there are quick replies to messages sent. And it's possible to speak to a human!
I recently went through probate for mum - Iweb were much slicker & responsive than II.
Overall though, I'm happy & see no reason to move. However, it's fairly early days as part of abrdn...........
Hope this helps
Andy
It’s a shame WANdisco (LON:WAND) company profile summary is so full of BS. This is a description that’s supposed to be for laymen and yet it’s full of Hadoop data, Hive meta data(treated with antibiotics), and ‘deep integration’ - not had that for a while.... Does your Vendor lock-in scales horizontally – mine don’t. I’d be more interested if they just said "We have data good compression technology". Kinda big scale JPEG or pkZIP? I’m in IT and skeptical at this valuation!
(Car diagnostic data is not really time critical. Your phone already gives speed and location data over its network for traffic apps and the billions of existing phones seem to manage fine on 4G with existing compression tech)
Sigmaroc (LON:SRC) Director purchase: Emmanuel Maes, West MD and Group Head of M&A, purchased 320,301 ordinary shares at 56.8p and now owns 1,835,995 Shares.
UK banking observation
UK banking sector seems somewhat uninterested in real businesses.
Seems Barclays in Yorkshire have a blanket policy of “we’re not accepting any new business accounts at the moment “
I am somewhat staggered, you would have thought it is the equivalent of my local fruit and veg shop putting a sign u “we’re only selling to the regulars”
Getting similar total lack of interest from other banks .
Has anyone any good experiences with one of the new online banks for business or do we have to wait for the corporates to do us the honour of allowing us to be a customer .
Scratching my head, probably some banks see their profit and turnover in other areas than supporting UK businesses .
That is very sad to read planetx, I hope you soon find a bank wiling to do business! I'm also staggered having been been with Barclays through thick and thin for 63 years, relationship banking disappeared a long time ago, we no longer hold.
When I setup a new company recently, I came across the same issues, even though Barclays and HSBC had been my business banking accounts for years prior to the pandemic. Step forward Starling, who have been excellent and I'm now thinking of moving my family banking to them.
In my experience probably not a good idea to have personal and business banking with the same bank. If they have a tech meltdown you're up the creek completely.
I’m with starling personally they are good, recently moved to Chase who are very good and give 3% interest and 1% cashback .
Never was a fan of Barclays anyway ever since we had a 70k fraud attempt which they caused inadvertently then said “that’s just the way it is”
For anyone in business watch out for this
- customer pays in larger amount than expecting
- calls up saying “sorry we sent 70k too much please send back “
- our FC correctiy waits 5 days expecting funds to evaporate
- day 6 returns funds
- day 7 Barclays bounce the initial 70 k payment
Turns out that supplier had posted ! A uk stolen cheque to a local branch of Barclays , Barclays have a policy of “cashing” all cheques no matter what the amount and no Checking .
So I sent a cheque to Paul scott via a Barclays branch for 1 billion pounds for 4 days his account would show 1 billion even if signed by Donald Duck .
Most companies believe it is a 4 day clearance , but for cheques paid in by local branches it is longer - this is the area of weaknesss
We did end up getting our 70k back as fortunately it was national holiday in Dubai for those few days after sent .
Anyway glad I’m not with Barclays .
Re banking indifference
I find it astonishing that banks should be so uninterested in someone with a successful entrepreneurial history. Clueless. Reminds me of the time NatWest called me in to discuss my £500 overdraft after I finished my degree. The manager took a sadistic pleasure in demanding my credit cards be returned with no thought to the likely economic prospects of an Oxbridge graduate. I walked straight next door into, ironically, Barclays to start a relationship that lasted well past several business sales and a full LSE listing. Eventually I moved on but the relationship was very fruitful until the bank became more and more difficult to deal with - which I guess is what led to your frustrations today. Good luck finding a banking partner.
Metro Bank (LON:MTRO) are a good choice if you see yourself needing branch services. They pride themselves on offering branches you actually want to visit, and open hours you want to (weekends, evenings). They run a fairly large business current account base.
Otherwise for the online only banks, I've had good results with Starling, who I've had a business account for years. No hassle, app works well. Never had to contact customer services (so far!).
(I hold Metro in the Boon Fund)
planetx - I sympathise re Barclays. I have been with them for some 50 years - both business and private accounts. To unlock my account I spent some 2 hours with a helpful young lady going through my KYC details (they have known me so long I would have thought they had all the information they needed). I finally realised that the young lady was not even born when I started using Barclays. My interview culminated with them photographing me with my passport held open alongside my face. Seemed to me to equate to Police procedure. Personal relationships are over with Barclays.
I am staggered to hear the difficulties being faced in trying to open a new business bank account. What is the cause of this reluctance by banks? How are businesses meant to operate without a bank account?
I am retired so it doesn't directly affect me but I have great sympathy for those who are having their business plans hijacked by this unwelcome roadblock.
Snazzy
Having dealt with various Banks as a supplier I think you will find its death by compliance process mostly. Barclays I have never dealt with for my own sake, but fines in the US for accounts for trading with sanctioned entities and the growth of cyber fraud generally have probably caused a ripple throughout the organisation to tighten the KYC aspects. The one area I did deal with them on behalf of others, they did not impress.
Here's my banking rant. When my wife and I retired we sold half the shares in our business to our manager. He has improved its performance which is galling but profitable. The business has been running for 27 years and never had any solvency issues. Last year he had the chance to buy an identical business which has been running a similar length of time. He asked me to look at the books and I could see it was a good deal. He needed to borrow about £300k, all asset backed, on a 5 year payback plan He could not raise the money. I would have invested but he wanted something to call his own and I didn't want to risk souring the relationship by lending. Rejections from banks were:- (1) we don't lend to your kind of business (visitor attractions); (2) the deal is too small; (3) the deal is too big... and the people dealing with this were all nincompoops who seemed inadequate for their roles. He might as well have been dealing with software as people, in fact I think he was. He has given up and is doing something else equally profitable which he can finance from his own resources.
I am currently going through a horrendous experience with my Santander business account. I have a personal account and 2 business accounts, one for my current business and the other for an old business that’s not trading and have been winding it down over last few years.
It’s the old business account that they wrote looking more information on, had to phone them (or all accounts will be frozen) and put through a series of questions, most about personal finances, earnings, savings, investments and asset ownership. As a result they requested I send them documents - annual return of old company, annual return of current company, my personal tax return and a copy of the deeds to house.
All this for an account that only has about £4000 in it and activity of less than £15000 for the year.
Have asked them why this is needed, to be told its for compliance and all customers will be put through it, all other questions were met with 'computer says no' answers.
I find this very intrusive and unnecessary.
Just wondering has anyone else being put through this ?
Have lodged a compliant with the Financial Ombudsman.
They have now frozen my account.
just gone through exactly the same with santander there excuse was i was drawing the same amount every month to pay a bill it was my wages!!!!!!!!!!!!!
All this was prompted by FCA's fine of ever £100 million on Santander in December.
Did they want you to provide any documents ?
Question is what information can a bank legitimately ask of its customers
Podcast mystery shares (my best ideas for the week, held back for Stockopedia subscribers) -
Mystery shares in this weekend's (5 March) podcast are -
ME International (LON:MEGP) - see Wednesday's report. I'm really impressed with performance, and the future looks bright, with higher margins from raising prices, and the fast-growing laundry division is catching up with the core business, so it's no longer a one-trick pony. Shares have risen a lot of late, so it may need to consolidate, but valuation still looks good value, and I like the longer term outlook.
National Express (LON:NEX) - briefly covered in Friday's report. I think this looks a good recovery share, but need to do more work on it.
Capita (LON:CPI) (I hold) - also briefly covered in Friday's report. Strong recovery in earnings, and previous concerns about excessive debt have now been fixed. Could be interesting, but again, I need to do more work on it, so more than ever, please make sure you DYOR.
Great podcast - much thanks Paul
Not small cap, Clarkson (LON:CKN) put out some pretty impressive results today. Eps increased by 51%
I am a long term holder of Clarkson (CKN). Today result was indeed impressive and more so that the better section was the brokering one.
It has other sections , Advisory and financial which together makes a diversified company in a growing sector. It is a shame that this company does not get much attention here.
My morning smallcap tweet: Enought bluff! Stuff that guff up your chuff
ADVFN (LON:AFN) WANdisco (LON:WAND) James Fisher And Sons (LON:FSJ) Trellus Health (LON:TRLS) Home Reit (LON:HOME) Capital (LON:CAPD) 1Spatial (LON:SPA) Kingswood Holdings (LON:KWG) Galliford Try Holdings (LON:GFRD) Ethernity Networks (LON:ENET) Plexus Holdings (LON:POS) Fusion Antibodies (LON:FAB)
◄ADVFN (AFN)► H1-Dec in line. "Our R&D team is working tirelessly to identify emerging trends and technologies that will enable us to stay ahead of the curve and deliver the next generation of products and services." And PR team working lazily to produce the same old cliches. [SP=40 Cap=15m]
◄WANdisco (WAND)► confirms report that it's considering a second listing in the US. [SP=1320.65 Cap=880m]
◄James Fisher (FSJ)► sells the lossmaking James Fisher Nuclear Holdings for a nominal sum. Guides FY-Dec rev-cont up 7% and U/L profit-cont flat. The Specialist Technical division experienced a disappointing year. [SP=392.3 Cap=198m]
◄Trellus Health (TRLS)► FY-Dec trading: "In line with expectations [it] expects to report an EBITDA loss...and revenues of c.$30k". Does that mean the loss is in line though? [SP=6.68 Cap=11m]
◄Home REIT (HOME)► two tenants making up c.18% of rent roll have entered creditors' voluntary liquidation. HOME in discussions with prospective tenants to take on new leases of the portfolios. [SP=38.05 Cap=301m]
◄Capital (CAPD)► MSALABS subsidiary has a strong start in 2023. [SP=106 Cap=204m]
◄1Spatial (SPA)► guides FY-Jan rev up 10% or more and pretax £0.9m+. In line? Confident. [SP=50.48 Cap=58m]
◄Kingswood (KWG)► conforms report that it is exploring a potential sale or third party investment. [SP=27.97 Cap=57m]
◄Galliford Try (GFRD)► get place Southern Water's 39 month £600m framework. [SP=175.4 Cap=189m]
◄Ethernity Networks (ENET)► update on its fibre controller contracts. Co will "will target sales of licensing fees for its PON fibre controller SoC and sales of its PON fibre controller OLT system in various configurations". [SP=7.3 Cap=7m]
◄Plexus (POS)► £5m 12 months contract. Half of cash will come in FY but be booked next FY. [SP=2.72 Cap=3m]
◄Fusion Antibodies (FAB)► warns FY-Mar rev and earnings significantly behind market expectations with rev £2.8m+. Blames a number of valuable projects being suspended by clients due to delayed investment. "There continues to be uncertainty over the timing of commencement of several such anticipated orders." Also "negotiations concerning a significant order for an integrated service contract have progressed but have not concluded". [SP=45 Cap=12m]
Your comment on ADVFN - PR Team made me chuckle!
OK Caduceus, if Paul and Graham are caffeinated up and ready to go I offer 4 interesting UP's for comments this morning which we hold. Centralic directors buying lifts total held to 23% , Capital is achieving success and expanding in Canada with their new Lab process, Macfarlane makes an accretive acquisition and finally possibly quite exciting for such a small cap, Getech announces a new chair for H2Green Dr. Graham Pooley ex-ITM power.
WANdisco (LON:WAND) RNS about listing in the US chimed with Jeremy Mckeown's blog that arrived also this morning in my email https://hypernormaltimes.com/f... about UK companies being passed over in favour of US stocks. A bit too negative perhaps, but maybe highlighting a longer term trend.
"Rise and shine, investors! It's a new day full of opportunities and potential profits. Let's caffeinate our portfolios and make some smart moves together. Good morning!"
I like together bit, years ago dont remember how but a group of us used to share what we found were interesting finds, we'd share our opinions then others would add theirs - it could work well here if allowed and the experts who I follow daily could correct or avoid as wished?