Small Cap Value Report (Mon 6 Sep 2021) - HEAD, WJG, BLV, SPSY, PCIP

Good morning, it's Paul & Roland here with the SCVR for Monday.
In between exploring the Senglea and Burgu areas of Malta over the weekend, I also took a look at interim results from Headlam (LON:HEAD) - not a current holding of mine, but something I would like to buy back into, when funds permit. So there's a section on that below, to get you started today.
Mello Monday is back today, at 6pm - details here.
Agenda -
Paul's Section:
Headlam (LON:HEAD) - my review of the recent interim results, to supplement Roland's review last week. I'm impressed with the recovery to pre-pandemic levels, plus the very strong balance sheet (with net cash, and freehold property) could attract a bidder maybe? Still seems good value to me. Although the commercial sector remains subdued, and there is a new competitor Likewise, set up by former HEAD leaders.
Watkin Jones (LON:WJG) (I hold) - a frustrating trading update that sounds reassuring, and gives lots of detail on developments, but says nothing specific about performance versus market expectations. A research update from Progressive says that today's update reinforces confidence in forecasts.
Pci- Pal (LON:PCIP) (I hold) - very strong organic growth in mainly recurring revenues. However, all the additional gross profit has been consumed by considerably higher admin costs - although this was flagged as a deliberate policy to help accelerate growth. I ponder the bull & bear points.
Roland's Section:
Belvoir (LON:BLV): an excellent set of figures from this estate agency group, boosted by rapid growth in revenue from sales and mortgage broking.
Spectra Systems (LON:SPSY): strong numbers and excellent cash generation from the banknote authentication specialist. But I’m struggling to get a clear picture on growth.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Headlam (LON:HEAD)
(I do not currently hold)
480p - mkt cap £409m
Headlam Group plc (LSE: HEAD), Europe's leading floorcoverings distributor, today announces its interim results for the six months ended 30 June 2021 (the 'Period') and an update on current trading.
Strong recovery to 2019 levels
There’s a deck of presentation slides here, which I find a much more user friendly way of reviewing results. Although you always must keep in mind that presentations give the most positive picture of events, and negatives can sometimes be harder to spot, or glossed over.
H1 Revenues - impressively, have returned almost to pre-pandemic levels (continuing operations - they’ve stripped out the Swiss subsidiary, because it’s been sold) -
Strong recovery to 2019 levels, with total revenue of £329.9 million being in-line with H1 2019 (£335.0 million), and 45.2% ahead of H1 2020 (£227.2 million)
Note that 68.5% of revenues are for residential floorcoverings, with the balance being commercial - which is still under pressure due to working from home causing an understandable slowdown.
Profit margin - cost increases are being offset by operational improvements, and the aspiration is to achieve a 7.5% margin over the next few years -
Underlying² operating margin in-line with H1 2019 at 5.3%
Therefore we should be able to extrapolate increased profits, if all goes according to plan. A rise from 5.3% margin to 7.5% margin is a 42% rise in profits, which should feed through to a similar rise in future EPS, looking 2 years ahead - that’s a key point supporting the investment case for HEAD shares.
Underlying profit before tax (PBT) of £17.4m in H1
Underlying diluted EPS is 14.4p for H1.
Therefore the current forecast of c.32p for FY 12/2021 should be comfortably achieved, in my opinion, due to the seasonally stronger H2.
Seasonality - using this handy feature here, you can quickly check the H1/H2 seasonality for any company. Ignoring 2020, due to pandemic distortions, you can see that HEAD previously had a seasonal bias, with stronger profits in H2. I would expect that to occur this year too, hence full year EPS should be considerably more than just doubling H1 profits.
Balance sheet - I particularly like that HEAD also reports average daily net debt/cash. This is a far more realistic measure of liquidity than the usual snapshot on a period end date (which is often window-dressed by many companies) -
· Average net funds³ of £30.5 million, representing a strong reversal of the £35.3 million and £8.6 million average net debt³ position for H1 2020 and full-year 2020 respectively
· Net funds at Period-end, excluding impact of IFRS 16 'Leases', of £53.9 million (as at 30 June 2020: £22.4 million net debt; 31 December 2020: £51.6 million net funds)
Cash has been piling up in the group’s bank account, helped by a pause in dividends, and working capital returning to normal (trade creditors were unusually low a year earlier at the height of the pandemic)
Overall, a key point with HEAD is that the balance sheet is significantly over-capitalised. This makes the company attractive to bidders, who could do a sale & leaseback on the c.£100m freehold property, strip out all the cash, and load it up with debt. That could easily fund about three quarters (or more) of the current market cap! So don’t be surprised if this business attracts takeover approaches.
NAV is £226.1m, with only £19.0m intangibles to deduct - giving NTAV of £207.1m.
Therefore shareholders are not only sitting on a low PER business, performing well, but you’re getting a bulletproof balance sheet with surplus assets thrown in for free. What’s not to like about that?!
Dividends - with the coffers brimming full of cash, I think we can look forward to generous divis in future. The company says -
Resumption of normalised level of dividend payments with 2021 interim ordinary dividend of 5.8 pence per share
Forecast divis are about 15p, which is too low in my view. I reckon a return to peak divis of c.25p is more realistic, which means buying now could lock in a future divi yield of c. 5.2% - appealing for income seekers. Plus the divis should be protected against inflation, because HEAD is the type of business which can pass on inflationary pressures to its customers.
We also know it has proven resilient in the pandemic, so risk is low.
The more I look at this share, the more I like it.
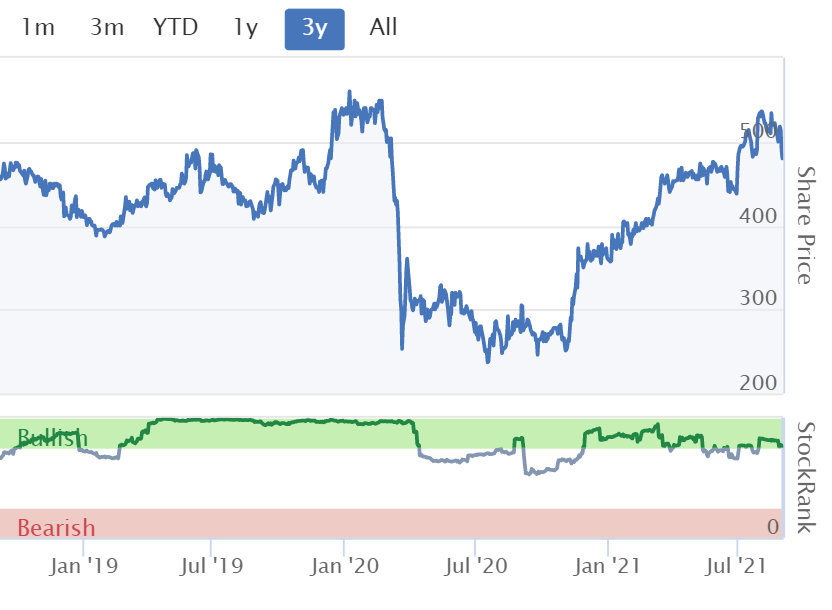
Why did the share price ease off last week then, when these numbers were published? I think it might be the cautious outlook remarks about the (smaller) commercial sector -
Post Period-End and Current Trading
· Subdued commercial sector activity, although with regional variations, and residential sector performance pleasing
· Continuing to trade in-line with market expectations4 which were significantly upgraded in July 2021
4 Company-compiled consensus market expectations for 2021 revenue and underlying profit before tax are £684.8 million and £35.0 million respectively (on a mean and post IFRS 16 adoption basis).
There’s also the issue of smaller competitor Likewise plc, which recently floated at 25p, valuing it at £48m (see here for its AIM admission document). The CEO is formerly from Headlam, which does raise the question of how fair it is to take all that knowhow & trade secrets with you, and set up in competition? Although as Headlam’s slide deck points out, HEAD has the advantage of scale, being >6x the size of its nearest competitor. Nevertheless, with all his knowhow of the sector, the former HEAD CEO could prove a thorn in HEAD’s side, and maybe curtail its ability to increase margins, if it has to discount to retain customers maybe?
My opinion - I reckon HEAD should be moving towards EPS of 40-50p over the next couple of years, so at 480p it looks attractively cheap.
Generous divis are on the cards, as it has a bulging & growing bank balance.
The balance sheet provides immense financial strength, and could attract a private equity bid - fine, if they pay a 30%+ premium then they’re welcome to it.
On the downside, the commercial sector could continue to be a drag, and there is a risk of increased competition.
The recent Capital Markets Day (CMD) was interesting, and gave many detailed examples of where the company has under-performed, and sees upside. Although it did leave me questioning why it has allowed so many operational areas to go quite badly wrong & become so inefficient in the first place?!
On balance, I have decided to buy back into HEAD shares, when funds permit (which they don’t at present). It looks an attractive value share, with decent potential upside, providing nothing goes wrong. Let’s hope Likewise doesn’t eat its lunch, so that would need careful monitoring.
I’ve just re-read Roland’s review of the interim results last Thursday (when I was travelling), and it’s interesting to see he picks up on a couple of points that I missed. There’s a lot of duplication obviously, but I thought it would be interesting nonetheless to do my own separate review of the interims, and compare my view with Roland’s. It looks like we both see this as a good value share.
Since writing the above, I’ve had a rummage through the Admission Document of recently floated Likewise. It’s small, but growing fast, and still loss-making. Even after the c.£9m raised in its transfer to AIM (from a Guernsey listing), the balance sheet will still be a sliver of HEAD’s bulletproof financial clout.
So I think it’s likely to take Likewise 5-years+ to get anywhere near the size of Headlam. So it’s a simple choice - buy the relatively cheap (on PER, divi yield, and balance sheet metrics) larger player. Or gamble on the growth of a loss-making small competitor. I’ll go for the value investment. It’s a capital-intensive business, with lots of premises & capex needed, in order to expand, so Likewise may not find it easy, and is almost certainly going to need follow-on funding, to drive expansion.
.
.
Watkin Jones (LON:WJG) (I hold)
240p (Friday’s close) - mkt cap £614m
Watkin Jones plc (AIM:WJG), the UK's leading developer and manager of residential for rent homes, provides the following update on developments since the Group issued its half-year results on 18 May 2021 (the 'period').
The current financial year ends 30 Sept 2021.
This doesn’t seem to be a scheduled update, so it’s not clear why the company has updated us today. The heading sounds positive -
Strong momentum continuing in H2; development pipeline enhanced
Continued delivery of developments on time despite COVID-19
All remaining FY21 developments (one BtR scheme for 184 apartments in Leicester and two PBSA schemes for 1,121 beds in Glasgow and Wembley) on track for completion in September.
Institutional demand across asset classes driving forward sales
The problem with this update, is that whilst it gives granular detail on each development’s progress, which I haven’t copied here, but it doesn’t give us any detail on the overview! Are they trading in line with expectations, or ahead? We’re not told.
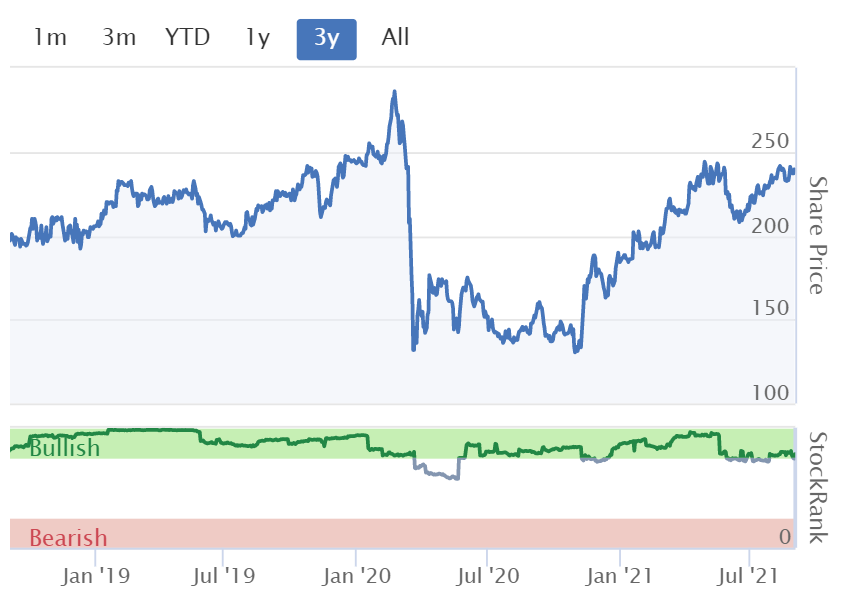
Research update - I’ve checked to see if Progressive Equity Research has updated, which it has here. It’s commissioned research, so in effect is coming from WJG, which is fine. Forecasts for FY 09/2021 are left unchanged, but today’s update “reinforces confidence” in the forecasts.
Adj EPS is forecast at 15.8p for FY 09/2021, giving a PER of 15.2 - that looks about right to me.
Dividends are useful here, forecast at 7.8p this year, a yield of 3.3% - the business model at WJG is unusual, in that it recycles capital quickly by forward-selling developments to institutions. Therefore it has good dividend paying capacity, which in my view is more important than the actual dividend yield. I.e. I’d rather have a 3% yield that is well-covered, from a company that holds & generates plenty of cash, than a say 6% yield from an indebted company that is struggling to maintain that level of payout, and is probably heading for problems.
My opinion - I very much like the business model at WJG, and the company has executed so well in recent years. The main downside risk is that the whole business rests on the expertise of the management/staff, and the relationships they have built with institutions. So it’s a know-how company, the actual construction work is outsourced I think. Therefore the danger is that the key people might decide to up sticks & set up in competition.
Hopefully that won’t happen, however note that the family have been part-selling in secondary placings.
The main attraction of this share, as I’ve pointed out before, is the planned growth in pipeline particularly for build to rent. Therefore, assuming nothing goes wrong, the next couple of years should see a decent rise in revenues & profits, from the projects already in the pipeline at various stages of development.
For that reason, I’m planning on sitting tight for a while, with a standard position size - i.e. not something I would want too much exposure to.
.
.
Pci- Pal (LON:PCIP)
93.5p (up 1%, at 09:52) - mkt cap £61.0m
Final Results & Investor Presentation
PCI-PAL PLC (AIM: PCIP), the global provider of secure payment solutions, is pleased to announce full year results for the year ended 30 June 2021 (the "Period").
Substantial increase in revenues and continued strong new business momentum
There’s an results webinar at 4.00pm (UK time) on Wednesday 8 September 2021 on InvestorMeetCompany - worth a watch I think, as this is an interesting growth company.
Key numbers for FY 06/2021 -
Revenues small, but growing fast, at £7.4m (67% growth - all organic)
Recurring revenues are 88% of the total - so the company is building a sticky, long-term revenue stream
Heavily loss-making still, with a loss after tax of £(4.04)m, similar to last year’s £(4.13)m
Gross profit rose strongly, from £3.0m LY to £5.56m this year, but the increase was consumed by a big increase in costs - admin exps rose from £7.25m to £9.52m. This shouldn’t come as a surprise to anyone paying attention, as the company’s stated intention was to ramp up the growth rate into new markets, which involves cash expenditure up-front. This was explained at the time of the last placing.
Even so, I do cringe a bit at the numbers, and personally I would have preferred the company to focus on its existing markets (which include the huge USA), and make faster progress towards breakeven.
The bull argument is that if you have a remarkable growth opportunity, then you should maximise it, even if that involves prolonging the short term losses.
There’s no right or wrong about this - it’s up to each investor to weigh things up for ourselves, and form our own view on the share, same with everything.
In the current environment, bull markets do prefer rapid growth, and are often impervious to short term losses. So on balance the more rapid growth strategy is probably likely to create more shareholder value than a more cautious, lower cash burning strategy.
Is there enough cash? Yes - since a placing raised £5.5m before expenses in April 2021 at 95p per share. Dilution was just under 10%, so it’s not a big deal. More money could be raised if needs be, so I don’t worry about liquidity, it’s fine.
Development spending - note that £920k was capitalised in the year.
Current trading - is in line - several new contract wins are noted -
Strong start to new financial year with new ACV in line with management expectations...
Outlook -
After a strong year I believe that the business is set to take another sizeable step forward in the next financial year. Whilst we do continue to be mindful of the pandemic, we believe that the momentum we have built, together with our ability to deliver new customer deployments, and our near-term sales pipelines means we are well-positioned to have another year of substantial progress…
There are 2 more paragraphs in a similar vein.
I don’t think there’s anything to be gained from going through the numbers, because historic figures are not what this investment is about, it’s a growth company. Let’s summarise the bull & bear points -
Bull points
- Very rapid organic growth - the market is currently happy to pay high valuation multiples for software companies achieving rapid growth
- 88% recurring revenues, very sticky
- Operational gearing is high, with gross margins rising further
- Huge markets, global
- Little competition for the niche that PCIP operates in
- Sold via resellers, so doesn’t need a large central overhead
- Cloud-based software, so cheaper & easier to implement
Bear points
- Still loss-making, with rising costs
- Breakeven has been deferred by policy to increase the rate of expansion, so shareholders need to be patient - several years yet until profitability
- Risk of a de-rating if bull market in tech fizzles out
- How to value it? £60m could be expensive, or cheap, depending on your point of view
- What short-term catalyst is there for further share price rises?
My opinion - overall, I’m happy to keep a standard position sized holding in my personal portfolio. I don’t want to go big into PCIP, because it’s probably valued about right for now, and it requires several years of patience for the company to grow into the valuation. Anything could happen in that time.
On the more bullish side of things, the company clearly has a great product, that is attracting many new clients, who sign up for long-term, high margin recurring revenues. As that builds, the company becomes more valuable.
I’d prefer the company to be more profit-focused though. The problem with this type of growth company, is that management always seem to find ways to increase costs, thus breakeven can sometimes feel like a mirage in the distance.
On balance though, the very rapid organic growth excites me more than the downside risks, so I’m broadly positive on PCIP. What do you think? All views are of interest.
Note that the StockRank system really doesn't like permanently loss-making companies, as you can see below -

Roland’s section
Belvoir (LON:BLV)
Share price: 280p (pre-open)
Shares in issue:36.4m
Market cap: £102m
This estate agency group has triple-bagged since the market crashed in March 2020.

These half-year results are flagged as “significantly ahead of management’s expectations as at the start of the year”. This is a reminder that Belvoir put out a trading update at the start of August, upgrading its guidance.
Today’s numbers are in line with last months’ update, but nevertheless appear to be very strong indeed. Earnings are significantly ahead of both last year and the same period in 2019.
Financial highlights: Belvoir acquired the Nicholas Humphreys network of agencies (which specialises in student lettings) for £4.4m in March. This deal has added to both revenue and profits. Happily, the company has split out the contribution from this deal so we can see the split between acquired profits and organic growth.
- Revenue +41% to £13.8m (H1 2020: £9.8m)
- 33% of revenue growth from underlying business, 8% came from the NH network
- Pre-tax profit +51% to £4.8m (H1 2020: £3.2m)
- 42% of profit growth from underlying business, 9% from acquired NH network)
- Earnings per share: +36% to 9.9p (H1 2020: 7.3p)
- Interim dividend:+18% to 4p (H1 2020: 3.4p)
- Net debt: £4.0m (H1 2020: £5.7m)
Belvoir has 467 branches and 242 financial advisors, operating under a number of brands. The majority of branches are franchised, which helps to keep costs low and margins high.
Using today’s figures, I calculate a trailing 12-month operating margin of 32% and a TTM return on capital employed of 21%.
These excellent figures are consistent with, but slightly ahead of, the group’s performance in recent years:

The franchise model also lends itself to strong cash generation, which is evident here:
- H1 21 operating cash conversion: 119% (H1 2020: 113%) - percentage of operating profit converted into operating cash flow
Results boosted by sales growth: Like most large estate agency groups these days, Belvoir’s revenue comes from a mix of lettings, sales and financial services.
Helpfully, the company has split out the revenue growth, allowing us to see how the gains during the half year were driven by a sharp increase in sales:
- Lettings revenue +21% (56% of gross profit)
- Sales revenue +78% (21% of gross profit)
- Financial services +51% (18% of gross profit)
We can see that lettings generated the majority of gross profit, but was the slowest growing area during the first half of this year.
Belvoir’s strong growth in financial services and sales isn’t a surprise, given current booming housing market conditions, super-cheap mortgages and strong employment. How much longer will this continue? I really don’t know. But I’d argue there is some cyclical risk for investors at this point in the cycle.
Incidentally, financial services growth may continue to run ahead of previous trends, as Belvoir acquired The Nottingham Building Society’s mortgage business during July. This added 21 financial advisers who will work in Nottingham branches, servicing the society’s customers.
Outlook: Belvoir’s house broker, FinnCap, has issued an updated note this morning which is available on Research Tree. The note makes the interesting point that Belvoir’s growth strategy has supported “24 years of unbroken profit growth”. I have to admit I haven’t looked that far back - that’s an impressive achievement in a cyclical sector, in my view.
However, this record may be broken in 2022, if current forecasts are correct. FinnCap suggests earnings of 19.8p per share this year, falling to 18.8p in 2022. Stockopedia’s consensus figures (not yet updated) suggest a similar trend, with adjusted eps of 20.6p in 2021, falling to 19.8p in 2022.
Today’s outlook statement indicates the board is confident of “a strong trading performance for the full year”, but Belvoir has stopped short of another guidance upgrade.
My view: Belvoir appears to be operating well and delivering strong financial results. Profitability and cash generation are excellent and the balance sheet looks sound to me.
Based on the group’s record of profitability and growth, the stock’s forecast P/E of 14 and 2.6% dividend yield don’t look overly expensive.
However, I can’t shake off the feeling that we may be getting close to the top of the market. If I held Belvoir shares I would continue to do so, but this probably isn’t a stock I’d rush to buy at current levels. Despite my favourable view of the business, I’d prefer to wait for the next market correction to begin building a position.
Spectra Systems (LON:SPSY)
Share price: 163p (+6% at 9am)
Shares in issue: 45.3m
Market cap: £62m
Interim results + New contract win
Spectra Systems specialises in machine-readable high speed banknote authentication, brand protection technologies and gaming security software.
This company’s high margins, strong cash generation and useful dividend yield have caught my eye over the last year, but I’ve been unsure about the long-term growth potential of businesses reliant on banknote technology.
Financial highlights: Today’s results strike a bullish tone that’s supported by a strong financial performance:
- Revenue +23% to $8.0m
- Pre-tax profit +53% to $3.0m
- Earnings per share +50% to $0.06
- Net cash $12.9m (H1 2020: $10.9m)
- Free cash flow: $4.3m (H1 2020: $1.8m)
Spectra’s operating margin for the half year was 38%, giving a trailing 12-month figure of 40%. This appears to continue the trend of improving margins seen in recent years:

High margins and strong cash generation are paired with a dividend payout ratio of around 90% - unusually high for a growth stock.

These payouts appear to be affordable and give Spectra shares an attractive 4.5% yield. But I am a little puzzled that more money isn’t required for R&D. Today’s accounts show R&D spending running at around 10% of TTM revenue. Is that a little low?
Too reliant on legacy sectors? Nearly 90% of Spectra’s revenue comes from its Authentication Systems business. This sells the materials, equipment and services needed to create and authenticate security features in customer products.
The largest market is banknotes. Spectra has a number of central bank customers who purchase “covert materials” and equipment from them. The company’s main growth opportunity in this area appears to be facilitating a switch from paper to polymer banknotes.
Interestingly, Spectra says it has now upgraded its print-ready polymer substrate so that it is able to compete directly with other suppliers in the industry, including £DLAR.
The company’s second-largest business appears to be providing brand authentication for consumer goods with its TruBrand product. The main client industry mentioned is tobacco. New opportunities cited include “a European tax stamp”, “motor vehicle registrations” and “foodstuffs in a large Asian country”.
I don’t have any way of putting a value on these opportunities. But the conclusion I draw is that most of Spectra’s current revenue derives from what I’d view as legacy industries - banknotes and tobacco. I wonder if this accounts for the relatively modest valuation of this business, given its profitability.
Security software: In 2012 Spectra acquired some gaming technology businesses. These provide security software services for gaming groups, mostly lotteries, as far as I can tell. This business generated $920k of revenue in H1, up from $693k last year. However, adjusted EBITDA fell from $156k to $112k. The company says this is due to investment in a new software platform that will cut future development costs.
Again, I’m not sure lotteries are really a growth sector.
Contract win: Today’s results are supplemented by a contract win RNS which reports a major new contract to provide the materials needed for a security feature in K-Cups for Keurig brewers (a US alternative to Nespresso).
The new customer is expected to spend more than $500k per annum and sales for this business are expected to reach $1m in 2022. Management describe it as “high margin” and say that additional sales will not require new staff, providing attractive operating leverage.
This seems to be good news, but again I’d argue that it’s not necessarily a growth sector. The coffee pods market is pretty mature now. I suspect demand for authentication is being driven by Keurig and its licensees trying to protect their margins in the face of cheaper generic competition.
Outlook: CEO Nabil Lawandy strikes a bullish note in today’s results and there’s a lot more information about new opportunities, mostly in banknotes.
The outlook statement is brief but confident:
"The Board therefore believes that the Company is on track to achieve record earnings and meet market expectations for the full year."
My view: Current broker forecasts in Stockopedia show adjusted earnings of 11.8 cents per share for 2021. That’s in line with the adjusted earnings of 11.9 cents reported by the company in 2020, so I’m unsure how much earnings growth is expected this year. I’ve not been able to access an updated broker note yet.
These forecasts put Spectra shares on 18 times forecast earnings, with a dividend yield of 4.9%. That seems cheap to me for such a profitable business, unless the market is pricing in a risk that profits will stagnate in future years.
I’m concerned about the growth prospects in banknotes, but from a global perspective, perhaps that view is too cautious? I don’t have any insight into this.
I’m impressed by Spectra and want to like the shares. But I’m a little concerned that the majority of the group’s profits come from what might be described as legacy businesses.
However, I suppose the other way of looking at this is that authentication often only becomes a major concern when a product or brand is well-established. Hence it’s natural that Spectra will get involved with mature businesses.
On balance, I’m afraid I’m undecided. Spectra Systems is performing well financially, but I’d need to do more research to understand the growth opportunity here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Spectra Systems (LON:SPSY) (I hold)
Thanks for the write-up Roland and to all those who made interesting Spectra contributions today.
One of the things that originally put me off buying Spectra Systems (LON:SPSY) was the promise of revenues many years in the future.
So I decided to go and read annual reports several years prior and (most) things did indeed turn out as the company predicted they would.
So when I read announcements such as today's:
a) I believe them, and b) it gives me optimism for the future.
---
Further observations from today include:
I remain wary about the share price reaction when revenues eventually don't grow for a period, but overall I remain reasonably optimistic.
Here are some more granular details for any interested, though please note the H2 numbers are my own.
Cheers
A
Thanks for your thoughts Roland.
I have held Spectra for several years now.
I still am not sure how they have managed to regularly increase their profits each year since I invested at well below £1! In terms of products they sell, advantges they have, and so on they are very secretive. Not many turn up to their meetings!
What I am sure of is that Spectra possesses considerable IP which they use to generate much of their growing profits and do not employ many people, smart scientists aside. Brown University (from where the MD qualified) is where they seem to be sourced from.
I surmise that much of their banknote authentification know how, may be developed using the very strong relationship they have with one central bank with whom they appear to have an externally funded continuing research contract.
I surmise that they hope to profit from the move to the use of longer life bank notes, using the IP they hava developed, to increase their market share by selling bank note substrates.
The subsidiary mentioned in the RNS was (I believe) spawned by the MD a couple of years ago. It is developing a product in the entirely different field of medical instrumentation. Since it is majority owned by Spectra one assumes that should it produce a commercially successful product (a blood plasma viscometer) much of the returns will be shared in some way by Spectra shareholders.
I like the fact that the Company holds a considerable cash pile, generates lots of cash and has been paying a consistently rising strong dividend for several years.
SM
Timarr is correct regarding the globai increase in bank notes as afar as I am aware. While electronic payment is increasingly popular in the USA and Europe, in particular, this is not the case for the majority of the population of less industrialised nations. In large parts of Africa, South America and India for example, cash and even bartering still hold sway. Counter intuitive perhaps, but that appears to be the case.
This point was made by Clive Vacher, CEO of De La Rue (LON:DLAR) in a presentation earlier this year.
Spectra Systems (LON:SPSY)
Roland
I’m concerned about the growth prospects in banknotes, but from a global perspective, perhaps that view is too cautious? I don’t have any insight into this.I’m impressed by Spectra and want to like the shares. But I’m a little concerned that the majority of the group’s profits come from what might be described as legacy businesses.
I have similar "worries" and not pushed the buy button up to now (somewhat annoyed at myself looking at todays numbers) - however i am coming moe to the "uninformed" viewpoint that authentication is only going to become more important even if the main established market may show reduced volumes ?? (perhaps their product will be equally relevant even if there is material decline in banknote production volumes?) eg if its core infratructure in that regard - the more i look at the numbers being delivered the more i like it and i think given a chance (shareprice drift back down to 150p??) i think i may take the plunge here despite the slight niggles. At the end of the day they seem to be delivering exactly what customer want and K-kups , lottery and ICS stuff seem to suggest that they have enough strings to their bow that long term it looks like they may perhaps be able to fully manage with "managed decline" in banknote stuff? .
Would be interested to hear what other think ref the future prospects for their individual income streams and whether other bods have similar "worries" that this could be a one trick pony and whether that pony many be getting old.
RE: Spectra Systems (LON:SPSY)
Bizarrely the number of banknotes in circulation is still going up, not down. That's not just true globally but also in the UK:
And although this can't go on forever as electronic payments grow and grow, it'll be a very long time before banknotes disappear and Spectra will have lots of time to grow adjacent product lines.
timarr
Spectra Systems (LON:SPSY) I believe part of the reason is because of the switch to the new polymer type, so there are both in circulation at the moment but the old notes will disappear over the next few years. Actually it only until 30/9/2022 that you can use the old £20 and £50s.
I used to use notes all the time but have not been to an ATM for over a year now, I'm sure I'm not alone.
Hi herbie
I used to use notes all the time but have not been to an ATM for over a year now, I'm sure I'm not alone.
Me too but sadly for us I suspect our ATM based contributions to the UK's banknote circulation have never been that significant.
The same trend is evident elsewhere. Eurozone for instance:
It's a general trend, not something specific to the UK. The reasons for it are complex, but regardless banknotes will be around for a lot longer than I'm likely to be a shareholder in £SSPY.
timarr
Interesting chart! Puzzled that the blue line shows steady annual growth yet the yellow lines show huge fluctuations, down and up, in 'notes in circulation'. Eg the fall from €1400bn to €200bn over 2008-12 with steady increase thereafter. Anecdotally, my friend in Ibiza always told me that pre-GFC, Germans would turn up on the island with suitcases stuffed with notes to buy second homes, until this tax evasion was stopped. But it's hard to understand who would be hoarding currency now - most public-facing businesses surely will hold just enough for immediate needs. I remember vaguely considering in March 2020 withdrawing a daily £200 for several months and burying in the garden, but this was driven by imminent talk of meltdown and authorities imposing -ve interest rates on bank deposits (which I thought applies in a couple of countries?).
Back to Spectra Systems (LON:SPSY) and £DLAR surely what is more important is the velocity of circulation of notes? Hoarded notes shouldn't deteriorate but money passing between grubby hands does eventually. With businesses in Western countries accepting no-surcharge card payments for just a £2 cup of coffee, and many Eastern nations having leapfrogged the card system altogether in favour of mobile payments, I don't understand who is spending/circulating so much cash. Long-term, plastic notes should need replacing far less frequently than paper, so I'm rather negative on Spectra Systems (LON:SPSY) prospects once their target markets have completed the switch to plastic. Not to mention the threatened central bank digital currencies, which I thought are already being trialled in some China cities.
I've looked in Euro notes and it seems a lot is either outside Europe or is in store. Retail transactions using cash is falling, up to 2019 it was around 6% fall per year, I expect 2020 it fell even more as many switched to card payments. So if there is less money going through the banks then does that not effect £SSPY ?
I'm also have read that the BoE is counting old notes such as £5 and £10s which are no longer legal tender, in it's figures for banknotes. Europe has issues new notes in the last year so it could be an issue there as well. I can see there will be some doubling up until all the old notes are out of the system.
I've looked in Euro notes and it seems a lot is either outside Europe or is in store. Retail transactions using cash is falling, up to 2019 it was around 6% fall per year, I expect 2020 it fell even more as many switched to card payments.
I work in electronic payments so, sadly, I know far too much about this.
There are multiple reasons for the increase in cash in circulation. For the dollar and the euro a lot of it is dollarization effects where they're used as hard currencies in countries with unstable governments and high inflation. There's also a movement for people to hoard cash - with interest rates at zero then it's not a major issue to do so. And, of course, for person to person payments cash is still king (although in Sweden and Denmark even that has been largely replaced by electronic payments).
Outside the major currency zones the amount of cash used in transactions is still increasing, although the total number of transactions is increasing faster - the difference being the increase in electronic transactions. Also, of course, banknotes get lost and destroyed - although polymer notes decrease the latter effect.
Beyond that you have the potential rise of CBDCs - essentially fiat cryptocurrency - which will also start to eat into banknote useage. That's a long story in its own right.
So overall there's no question at all that the production and usage of banknotes globally will start to decline soon. But "soon" is hard to define and the idea that the world will suddenly stop using banknotes in the next few years is just wrong. £SSPY will have plenty of time to develop its business and, for all we know, could end up with a larger share of a shrinking market.
timarr
Hi Tim, I never said banknotes will stop in the next few years. But it is certainly declining in the west. Even in less advanced countries the switch to cards or mobiles is gaining ground. Yes less advanced countries are still using cash. Apparently money withdrawn from ATMs in the UK last year was down 30%.
My understanding is that £SSPY deals mainly with retail money, so if the money is abroad or in store then it will not go near a SSPY system. So yes they are in a declining market, especially as they are based in western countries. It's good they are branching out into other areas away from banknotes.
My understanding is that £SSPY deals mainly with retail money, so if the money is abroad or in store then it will not go near a SSPY system.
I haven't looked at this recently but a lot of SSPY's business is based around banknote security features - which are used in central bank production processes and are then used in checking when they're circulated back through the banks. Mostly that looks like Central Bank customers rather than retail ones.
I think the main risk here is customer concentration, rather than banknote decline.
timarr
Indeed! bank note circulation is increasing.
Also in Europe (data up until first week of 2021): https://www.statista.com/stati...
The statement about breakthrough in polymer tech, being able to compete against the likes of De La Rue (LON:DLAR) is interesting; not quite sure I understand it fully, so will read more about it later today.
Overall, I am expecting FY21 EPS to probably come in 12-13c instead of the 11.8c forecasted currently.
It has a stronger pipeline of "new tech" than any time in the last few years, so historical multiple range (17-27x) doesn't really apply, this should trade at 25-35x, IMO.
Solid moat of tech, good revenue visibility, exciting portfolio of growth opportunities, good balance sheet.
I therefore see potential for the shares to realistically re-rate up to around 280-300p, and that's why I'm happy to hold; a good 75% potential uplift. In the meantime, getting 4%+ dividends that is secure due to the long-term revenue visibility of the company and its decent balance sheet.
(I hold)
Fairly unusual for any company, £spsy in this case, to highlight that it has a product which is better than its two main competitors. If this is not what they really meant, i cannot see why they mentioned them in the RNS.
Just to mark out:-
This is the last week of the old Stockopedia web site / application / server. I'm holding out on the old trusted way until the very end.
It will all be very different next week after "execution" day.
It would be as well to tell those who never had it that they will never miss it.
Silver
I have taken the plunge in the last week - i do seem to be having random issues with ticker symbols not showing up on posts automatically- nothing 4 or 5 edits wont sort though :)
I would say i have mostly been assimilated now - lets hope i am not Borg (Not Bjorn! )
Going from a update software on your PC/MAC to a cloud or internet based system is the way to go for the service providers. I use Evernote which did the same thing and functionality dropped - but have not found an alternative yet. Change is hard to assimilate to the best computer on planet earth (inside your skull).
Belvoir BLV. Purely by chance I watched this very brief interview (from 3rd August post trading update) over the week-end - sad I know but watching the Indians pile on the runs became a little tedious. It is useful for a flavour of what looks like an excellent small company.
https://www.proactiveinvestors...
Headlam (LON:HEAD) (I hold)
Thanks Paul for your excellent resumee. The points made by the company re areas of disappointment/opportunity to improve are interesting. I can’t help but wonder how many of these relate back to the management group who left.
Hi Cricketfan,
Re Headlam (LON:HEAD) - you said -
The points made by the company re areas of disappointment/opportunity to improve are interesting. I can’t help but wonder how many of these relate back to the management group who left.
I was thinking the same thing. The Likewise website says that its CEO was previously CEO of Headlam from about 2000 to 2016 (from memory). Yet Headlam is now saying it has all sorts of historic problems & inefficiencies, from doing loads of acquisitions, and not integrating them, not exploiting obvious sales opportunities, having hopelessly inefficient distribution, etc..
Which does make me wonder how competent the previous team were? Maybe we shouldn't worry too much about Likewise?!
Regards, Paul.
Hi Paul,
Are you taking a look at Pci- Pal (LON:PCIP) today?
Many thanks
Yup, the section on Pci- Pal (LON:PCIP) is up now.
very informative and interesting write-up, thank you.
The most interesting revelation was the increase in gross margin to 76%. It's a good rule of thumb in the USA, where such growth companies abound and I do the majority of my research, that margins in excess of 75% are considered healthy. I am with you on a preference for positive earnings or cashflows. That deficit (and a less sexy sector than cybersecurity) is what is holding the valuation back from matching the likes of Darktrace (LON:DARK) and its US counterparts. But my estimation is that positive earnings or cashflows for the same growth and margin profile would probably double the valuation, or even triple it with a Nasdaq dual-listing. I plan to attend the Investor Meet on Wednesday pm.
Was watching an interesting interview with the theranos whistleblower at the weekened where he was told in no uncertain terms by the hedge funds et al who they were pitching to get money from that any forecasts with regard to sales should really be double what they actually expected to achieve as all the dishers out of funding that matter simply take company estimates for sales and use half the figure as a starting point - seems like everything is on steriods when it comes the good ol US of A. Note this one bods comments may not reflect reality he may just have been telling a good story in this regard
There's a difference with forecasts in a fundraising or IPO of a private company - which can and will pitch heat to get your much-needed injection of cash - as opposed to quarterly guidance from a market-listed firm. In the latter example, you can spot a missed forecast or disappointing guidance on any growth stock chart from a mile away - just look for the big drops. These are a regular event, even for the likes of Amazon, which disappointed only last month. And for that reason, guidance has to be prudent and achievable as much as it is ambitious and attention-grabbing. It's a fine balance.
I would endorse Gloucester Bob's post on Sylvania Platinum (LON:SLP) if Jack is available today. I hold.
Regarding Headlam (LON:HEAD)
I’m really surprised that residential was only +4.7% compared with H1 2019
The housing market, a big driver of new floor covering sales, has been going along at a terrific pace for the first half of 2021 encouraged by the WFH and stamp duty reduction factors. Even people staying put have been spending at least some of the money saved on commuting and holidays into refurbishment of their existing property.
Strange, I would have expected double digit growth in H1 followed by a more moderate pace in H2.
Belvoir (LON:BLV): It's worth noting that the house broker Finncap has lowered its target EPS for FY21 today from 20.6p in its June note to 19.8p today. I am assuming this is because of the corporation tax charge - am I right in reading Belvoir (LON:BLV) have brought forward the 2023 corporation tax increase? If so, maybe this will (deliberately) give the company a chance to extend its unbroken profit growth record of 24 years by avoiding this cost in 2023?
Hi Patrick, good point re. £BLV. I have to confess I don't quite understand the rationale for bringing forward the corporation tax increase.
I'm sure there's a compelling (and correct) accounting explanation for this decision. But your explanation does seem to have a certain logic!
Regards,
Roland
Belvoir (LON:BLV)
Roland
"Hi Patrick, good point re. £BLV. I have to confess I don't quite understand the rationale for bringing forward the corporation tax increase. "
What Patrick says makes sense - indeed the company have semi confirmed this situation today when they advised the following.
· 36% increase in basic earnings per share to 9.9p (2020: 7.3p), having reflected the impact of the 2023 corporation tax increase on deferred tax
Note the important bit here is that this relates to deferred tax - practicably speaking deferred tax does not normally need paying "anytime soon" - so it's standard to use the currently known in the future tax rates that are likely to apply. So its seems "reasonable" to me that despite the fact that even the next year end being before the introduction of the new corporation tax - it's likely deferred tax will not be crytstalised before 1/4/2023 therefore it gets provided for at the future higher rate that applies from 1/4/23. Note i can't comment on whether this provision is technically correct but it seems to be logical to my untrained eye.
Deferred tax is just a provision to recognise the likely CT payable in the future, based on tax balances now. If the tax rate in the future has been enacted then that rate can be used. Hence the 23% rate sounds fine in this case.
Belvoir (LON:BLV) (I hold)
"Deferred tax is just a provision to recognise the likely CT payable in the future"
I must admit to being confused by this.
I was under the impression that deferred tax is literally a past tax expense on the P&L that hasn't been paid yet.
So the current £1.9m deferred tax on the balance sheet is the cash the taxman is expecting to receive in the near future on profits generated over the last 12-18 months.
What has this got to do with 2023 tax rates?
The Belvoir's CFO seems quite competent so I don't doubt that she knows what she's doing, but I don't really understand it.
Any further help on this - from any tax experts out there - would be most appreciated.
A
Thankyou for your time in putting together your report on HEAD Paul, also to the rest of the team for your continuing great work...
DH2.
Does anyone have news on Tclarke (LON:CTO) which has opened up 10% up ? No announcements - was it tipped over the weekend ?
Yes it was tipped in SCSW.
ah cheers.
20% up now. (I hold hence excited)
Hi Paul, thanks for your write up of Headlam (LON:HEAD) to compliment Roland's. I was just slightly concerned by the section of the RNS towards the end under post period end and current trading that said "Trading post the Period-end in July and August 2021 has been below the same months in 2019, although not materially". This is driven by the commercial side as you set out but if residential eases off even slightly then the business won't grow revenues. I am a holder and happy to hold.
£BLV. Strong results as expected. Worth a look Paul or Jack?
Hi Robert, I've covered Belvoir (LON:BLV) now.
Roland
Belvoir (LON:BLV) (I hold)
Thanks for your write-up today Roland.
I remain a big fan of this company (probably because I hold) and am quite surprised by the drop in share price today.
The biggest takeaway for me was the underlying progress of the Nicholas Humphreys (NH) acquisition (completed end of March 2021):
Unless I'm missing something that seems quite a poor return from so many franchised offices. I am hoping that it's just a timing issue.
---
On the point of extending the 24 years of profit growth, I have a feeling that the company will either:
The company currently generates c £8-£8.5m in free cash flow per year, which should be more than enough to keep the acquisitions flowing and profits rising.
To be honest given the highly recurring revenues, and what I see as pretty secure c.£5.5m operating profit, which should trade at a high multiple (this estimates excludes any Sales gross profit, which was £2.5m in FY20), I'm quite surprised the share price isn't higher than the current c£93m.
But of course, I am biased and I imagine that I am probably being overly optimistic. Nonetheless I do hope that the growth continues.
Thanks again.
A
Spectra Systems (LON:SPSY) interims out today. Highlights:
Plus new customer order for K-cups @$500K pa
Love to get your views on this.
cheers
Francis
The only thing that I take issue with in these results is the fact that the company only bought back 500k shares while clearly undervalued.
Other than that a happier holder than I was on Friday.
Regards,
Dave.
Hi Francis,
I've completed a section on Spectra Systems (LON:SPSY) now.
Regards,
Roland
My morning smallcap tweet: Dribbling into the cup of opportunity
Spectra Systems (LON:SPSY) Checkit (LON:CKT) Science (LON:SAG) Omega Diagnostics (LON:ODX) Watkin Jones (LON:WJG) Powerhouse Energy (LON:PHE), Totally (LON:TLY), Pelatro (LON:PTRO)
Spectra Systems (SPSY) H1(june). Guides FY in line. Wins first orders from a new customer for materials in K-cups for Keurig brewers. Expects over $500k PA. [SP=152.65 Cap=69m]. I hold.
Checkit (CKT) CFO scarpers. She is thanked. [SP=56 Cap=35m]. I hold.
Science Group (SAG) trading sounds in line. "Considering a new debt facility in order to increase capital efficiency and enable Science Group shareholders to benefit from an increase in leverage." Also may do a fundraise. [SP=430.2 Cap=177m]
Omega Diagnostics (ODX) submits to EU all of the information required for self-test use approval for VISITECT COVID test. [SP=53 Cap=97m]
Watkin Jones (WJG) positive sounding op update. Institutional demand across asset classes driving forward sales. [SP=239.5 Cap=614m]
Powerhouse Energy (PHE) speculation re "potential agreement between DMG licensee Hydrogen Utopia International (“HUI”) and Linde...Linde has finalised a technical feasibility evaluation to deploy the syngas clean-up and hydrogen extraction of DMG technology". May develop a plant in Poland. [SP=5.08 Cap=200m]
In line: Totally (LON:TLY) Pelatro (LON:PTRO)
If Jack is around Sylvania Platinum (LON:SLP) please.
Every up circa 100%, 4% plus dividend announced and potential special dividend the follow next year, what's not to like, probably drop 10%
my reading of it is, it should be over 115-120p and it's clearly demonstrated expansion plans with cash to spare, so it should be much higher next year. So yes, probably drop 10%
Hi Bob, sorry to sound like an amateur here, but you are expecting SLP to drop 10%? I presume due to paying out such a high dividend and potential special dividend in the future.
I was up around 76% on them until recently and I think the sell off is well over done now. Very bullish on them for the long term and if they do drop further after both dividends I'll likely pick up some more shares.
Cheers :)
Doozy, I was being Facetious, good news always tends to send the shares I hold down.
They will probably drop by 4% on ex divi day, but do most shares, so I wouldnt worry about that.
Still an excellent company, but just so volatile. I bought some for my daughter and keep telling her, forget them and come back in 5 years, unlike me, who checks them most days.
£SLP
Couple of points that I found interesting from the presentation just now:
- agreements with source mines for tailings are life of mine - 25 years plus
- Rhodium was circa 60% of profits last year.
what is said here really is that the market is irrational at times! some it for sure is due to market makers actions.
Haha I see! Yep, I know that feeling all too well.
Appreciate the response buddy!
Looking further out; I don't expect the chip shortage which is holding back car production, to last for ever. This would be good news for platinum group metals.
Jack's back tomorrow, so I'll flag up that readers are interested in Sylvania Platinum (LON:SLP) to him.
P.
Many thanks Paul for asking Jack if he will do a write up because I bought back into Sylvania Platinum (LON:SLP) towards the end of August based on its technicals.
ie, 78% retracement in its share price.
Stochastic had dipped below 20 and was starting to rise.
MACD blue reference line was about to cross over the red signal line.