Small Cap Value Report (Mon 7 Nov 2022) - JOUL, LGRS, APP, DWF

Good morning from Paul & Graham! It's a very quiet news day today. Today's report is now finished.
Weekend podcast - was published here (and on podcast platforms) around Saturday lunchtime. I've typed up the written summary, for Stockopedia subscribers only, which is here. Lots of ground covered, as usual!
Mello Monday - is this evening, starting at 17:00. Fund manager Judith MacKenzie is being interviewed, and one of my favourite companies Sanderson Design (LON:SDG) is also presenting.
Agenda
Paul's Section:
Joules (LON:JOUL) - financially distressed special situation. Its update today includes yet another profit warning, and indications that it's going to run out of headroom at end Nov 2022, hence is seeking bridging finance. More detail below, this share looks increasingly precarious, so I'm steering clear.
Loungers (LON:LGRS) [no section below] Quite an interesting development here. This lounge/bars operator thanks it has spotted a gap in the market, and is creating a third format, called “Brightside” - roadside cafes, which evokes Little Chef, focused on comfort food, including all-day breakfasts. Sounds great to me! LGRS management is respected as being best in class operators, so I imagine they’ll probably do well with this new format too. Three sites in the South West have been lined up for spring 2023 opening.
Graham's Section:
Appreciate (LON:APP) (£48m pre-open) - two of my favourite financial stocks are set to combine forces. PayPoint (LON:PAY) has offered 44p for each Appreciate share, in the form of 33p plus a fraction of a PayPoint share. Even though it’s a premium of nearly 70% to the existing Appreciate share price, I suspect that Paypoint will do extremely well out of this. The Appreciate valuation was extraordinarily low, and they are about to start benefiting from higher interest rates. My attention now turns to Paypoint. It’s not quite as cheap as Appreciate was, but I expect it to benefit from this acquisition. As was the case with Appreciate, I suspect that stock market investors also underrate it and undervalue it.
DWF (LON:DWF) (£221m) (-2%) [no section below] - this large professional services company announces an acquisition worth up to £27.7m (including debt). It’s buying a Canadian law firm that earned revenues of £20m (translated from CAD) last year, and adjusted EBITDA of £3m. The deal “marks the next step in DWF's North American strategy and will result in an integrated legal and business services offering in Canada”, while also tying in with DWF’s Chicago operations. The two firms appear to share some of the same clients, and referrals can flow from one to the other.
DWF’s net debt (excluding lease liabilities) was £72m as of April 2022. However, a big chunk of today’s deal will be paid for in the form of newly-issued DWF shares, so the impact on overall leverage should be limited. DWF also reassure shareholders that they expect “deleveraging beyond the current financial year to be driven by profitable growth and strong cash generation”. DWF’s value metrics are extremely cheap at present, but listed law firms can be a bit of a minefield. These shares might be best left to sector specialists. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Joules (LON:JOUL)
13.7p (pre market open)
Market cap £15m
Joules, the premium British lifestyle group, provides an update in regard to its turnaround plan, and current trading and financial position.
The current year is FY 5/2022.
As we already know, this is now a financially distressed special situation, so high risk.
Today’s update says -
Trading behind expectations (11 weeks to 30 Oct 2022)
Blames macro factors & mild weather (which didn’t seem to hurt larger competitor Next (LON:NXT) which recently reported solid trading)
Advanced discussions with a number of strategic investors (including Tom Joule) re equity raise.
Possible CVA also being planned (a solvent form of restructuring, to get rid of lease liabilities and potentially other liabilities)
Ominous sounding “other options” also being considered, which I suspect might be a pre-pack administration, should they be required - which would wipe out existing equity.
Discussions with bank lender over easing of covenants.
Net debt was £25.7m at end Oct. £11.4m headroom, but £5.6m of this is “trapped cash” with payment providers (which I assume means merchant card processing?)
Bank facility (RCF) set to reduce by £5m at end Nov, which can’t be paid without some bridging finance.
My opinion - this sounds grim. It sounds to me as if the risks have worsened, and there’s an increased chance of existing equity holders being wiped out through heavy dilution, or insolvency. I’d steer clear for now, until it’s either done a refinancing or gone bust.
Graham’s Section:
Appreciate (LON:APP)
Share price: 26.05p (pre-market)
Market cap: £48m
I noted in September that Appreciate, the Liverpool-based gift voucher company, was a potential value investment with a StockRank of 93, and a ValueRank of 87 at the time.
This is a share I owned quite a few years ago (first purchasing it in 2017), but did not hold onto it. It was hit badly by Covid and has been looking to replace senior leadership roles - it does not currently have either a permanent CEO or a permanent CFO.
Investors have had little interest in owning a business that sells High Street vouchers, which has resulted in the following metrics showing up:
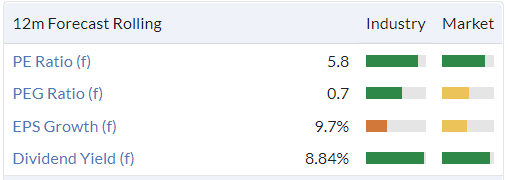
However, trading has been good: the September update was encouraging with the Group reporting that it was set up “strongly” for the Christmas period, and the outlook remained in line with prior expectations.
The value on offer has been spotted by another financial stock that I’m a fan of, namely Paypoint (PAY).
Therefore, this is the offer for each Appreciate share:
- 33 pence in cash and
- 0.019 New PayPoint Shares
If the deal goes through, Appreciate’s shareholders will wind up owning 5% of PayPoint.
A PayPoint share was worth 580p last night, and therefore the offer is worth 44p for each Appreciate share.
As pointed out in the RNS, this is a major premium to the existing Appreciate share price, whether measured by last night’s price (68.9% premium) or by the average price over the last three months (63.8% premium).
The deal has to be put to a vote, of course, but already it has been indicated that 23% of shares will vote in favour of the deal.
The Appreciate shareholder base consists mostly of professionally-managed funds who I’m guessing will be glad to see the back of a company with a sub-£50 million market cap:
Comment from Exec Chairman of Appreciate:
"PayPoint's offer represents an attractive premium for Appreciate Group Shareholders providing an opportunity to exit the majority of their shareholdings for cash, whilst participating in the potential upside of the combined Appreciate Group and PayPoint businesses over the long-term.
Comment from Chief Executive of PayPoint:
…the proposed acquisition would jointly target growth in three broad areas: prepayment saving through Park Christmas Savings to support customers with budgeting tools for Christmas and other events; an enlarged full-service offering for gifting, employee rewards and benefits to Appreciate Group's corporate clients; and an extended consumer gifting network for the Love2shop brand.
My view
Even at a premium of nearly 70% to the prevailing Appreciate share price, I suspect that PayPoint is getting a bargain here.
The offer is valued at £83m. As announced in today’s RNS, they are paying 6.2x adjusted EBITDA for the year ended March 2022.
For the current year - FY March 2023 - forecasts suggest that Appreciate’s adjusted pre-tax profit is going to be over £9m. So they are paying barely over nine times that.
They are also buying a bullet-proof balance sheet: Appreciate’s year-end cash was last seen at £20m. Including cash held in trust, average funds held during the year were £179m.
As I was saying back in 2018, when Appreciate was still called “Park Group”, there is an implicit interest rate hedge at this company, since it benefits from higher rates.
PayPoint will know this, and have timed their purchase very nicely as interest rates rise.
There is also the possibility of some valuable synergies, although I’m not sure exactly how it will work. I suppose that consumers who use PayPoint’s terminals might benefit from the traditional Christmas saving scheme offered by Appreciate.
And perhaps it makes sense for Appreciate’s gift voucher business to plug into PayPoint’s existing retail network of convenience stores. It will be interesting to see how the two businesses might cooperate.
However it might work, I believe that the deal will get voted through, because Appreciate’s fund manager shareholders will want to see the back of a holding that has been an awkward one to sit on for the past five years.
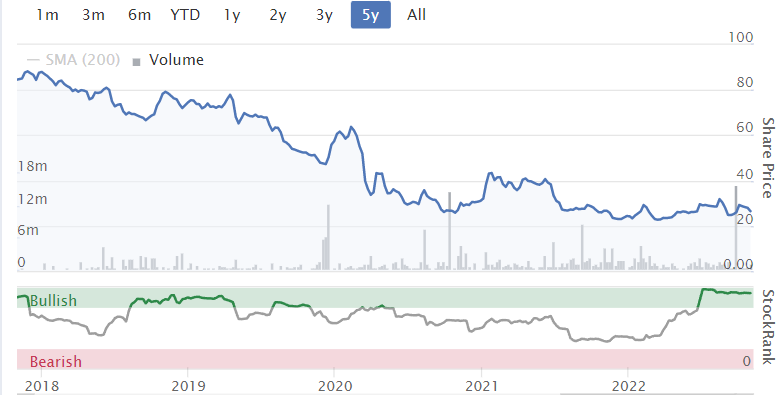
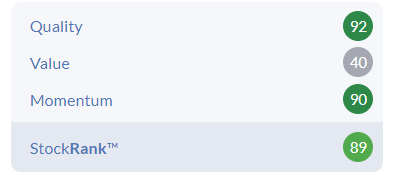
Looking forward, I think this deal adds to the attractiveness of PayPoint shares, which already have a very high StockRank and (from my point of view) a cheap valuation:
I was a fan of Appreciate, and a fan of PayPoint, so I’m certainly going to be a fan of the combined business! My most recent PayPoint commentary can be found here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Does anyone know where Stockopedia get the 'upcoming events' dates from?
Anybody know why the price of Natural Gas has jumped up 11% today?
No idea but the sooner we detach the price of energy from a traded commodity the better in my humble opinion.
delays on French nuclear plants going online but that was late last week
The gas price rise seems to be a delayed reaction to Friday's news of lower nuclear output in France plus an expectation that the unseasonably warm weather can't last, according to this article. Also on Bloomberg if you have an account. It needs to be seen in the context of a significant drop in price since the September peak. Chart here.
Here is the full info on the Mello Monday show tonight. All are welcome
I see the SRT Marine Systems (LON:SRT) share price has increased 15% today on the back of a tip from MIDAS in This is Money. Volatile times.
I see the SRT Marine Systems (LON:SRT) share price has increased 15% today on the back of a tip from MIDAS in This is Money. Volatile times.
It's pretty standard. The smart money will flow somewhere else in a week or so after it's rinced the hot dumb punters. Situation normal.
timarr
I hold £APP and welcome the takeover. I thought its 'voucher' had long term potential and agree that Paypoint are buying at a good time. Most of the complexity has gone from Appreciate (hampers, paper vouchers) and the digital business has been largely weathered in (new HO/staff, updated ERP/systems). However, as a small group it was always going to struggle to convert that latent opportunity.
In truth, the timing on my buy means I will only get my money back from when I bought but that is better that waiting another 3 years for Appreciate's value to (maybe) out and Paypoint is more liquid so I have a few months to see if I like it there.
FWIW, I think we will see more deals come through at current valuations - at lot of consuming facing stocks look cheap on a long term buy and hold basis something the cautious folks in cash may miss out on. Who's strategy is right? Ask me in 2 years.
I hold PayPoint (LON:PAY) (sadly not Appreciate (LON:APP)) and this morning it triggered a stop-loss. In the past this would have meant an automatic sale. But I no longer use automatic stop-losses and always make a conscious decision when I receive an alert. On this occasion I have done something I have never done before - I averaged down. So now PayPoint (LON:PAY) is heavily overweight in my portfolio. The reason I did this is that I am comfortable that I understand PayPoint (LON:PAY) and if I was not a holder today's fall would have triggered a buy. I think my decision will prove right or wrong within a week because my tentacles are telling me the market as a whole is no longer falling and the enormous dividend yields we have seen recently will soon be gone.
I guess better to listen to what you tentacles say, rather than your testicles (unless you are Bull for shares). Guess you are in a for few extra squid now.
Georgia capital
Update of Fridays posts saying Georgia capital looks a good entry point .
Bank of Georgia up yet again .
The huge discount to NAV appeared to be based on potential regional issues with Ukraine
However looks like Georgian economy is actually getting a big boost with Russian in flow of money .
Article out on Reuters .
https://www.reuters.com/world/...
Good spot and even better Georgia Capital (LON:CGEO) looks very very cheap - less than 50% of NAV based on last results with the next set on Wed? Really not good on knowing Georgia and the political risks but just on the bank of georgia valuation and the recent exchange rate moves the discount must have increased even more. Looks like a good entry from a quick glance - thoughts?
Many banks in the UK trade a discount to NAV/book value. Why take extra geopolitical risk?
yep good point and explains why discount is more like 65%+ from further research. Do any UK banks trade at such a discount? And when a big chunk of that NAV is a premium listed FTSE plc (albeit a georgian bank) that also helps derisk it
Metro Bank (LON:MTRO) is the extreme case, trading at 0.15 Price / Book Value.
But even if we take Lloyds Banking (LON:LLOY) one of the biggest, it is at 0.58 Price / Book Value. Natwest (LON:NWG) at 0.66
Back in the days of 4%+ interest rates, which was pre-2008, retail banks were trading at premium to book value I believe (caveat: someone please step in with better knowledge, as I wasn't even trading shares pre-2008! So this is based on foggy memories of articles read since 2008)
Don't think it will ever go back to that, with huge regulatory restrictions on banks and therefore their ROCE power much diminished. But it shows potentially the scope of opportunity. Lloyds potentially re-rating to 0.8x P/B maybe?
(I hold Metro in the Boon Fund)
Edit: Just had a look at Bank of Georgia - P/B of 1x! Wow. Maybe that is a good example of what banks could be worth in a high interest rate environment (it looks like Georgia central bank rate is 11% currently?)
Thanks! v useful. So implies Bank of Georgia itself may be a bit overvalued.
of course my example of Georgia Capital (LON:CGEO) is essentially a fund (well, asset manager) holding lots of assets mainly utilities/property/financial etc of which this bank is only a proportion, so the discount to NAV needs to be looked at compared to other similar funds in other territories. But those examples above are great and i'll go away and look more closely at Metro Bank (LON:MTRO) and Lloyds Banking (LON:LLOY) now based on this as you'd imagine some normalisation may happen. I was trading back in 2000 so do remember bank valuations particularly RBS!
For those who might be interested there's was a mention of SRT Marine Systems (LON:SRT) (I hold) in the Mail yesterday that's pushed the share price up 15% up this morning - a good explanation of what they are all about and the potential size of their market. If they come anywhere close to becoming the providers of the air-traffic-control of the seas they should do well for investors who've waited a long while for this to come about.
Hi Quilleron,
I hope they do but they have been saying the same story for years and the share price hasn’t gone anywhere.
Why is it different this time?
SRT Marine Systems (LON:SRT)
Why is it different this time?
As a long term investor in SRT (since 2011), I understand the scepticism. There have been many false dawns but despite this SRT have won some impressive contracts in the Middle East and in Asia where the Philippines BFAR agency has the largest fishing vessel monitoring system up and running and it is confidently expected to be expanded to cover thousands more vessels. At some point, the national CoastGuard may also define its requirements.
The other recent contract win in a very large ME country is operational and additional project phases originally required to be completed in three years are now planned to overlap to satisfy the customer requirement to complete in two years.
Both of these major contracts have a recurring revenue element for system upgrades and data collection and are not just one offs..
The current excitement is the potential to land a large contract with Indonesia. Those who have followed to SRT story will know that a contract was won here before but due to high level personnel changes it was aborted. Now with a new president keen to improve the lives of their fishermen and protect their national interests, SRT are once again bidding for the work. Why this is looking particularly promising is down to the Indo Defence Expo which took place last week in Jakarta. SRT were one of the UK companies here but rather than occupying the UK Government stand, they were featured by Bakamla (Indonesia's Maritime Security Agency) with a large. scale live demonstration of the SRT system. You can see photos here https://srt-marine.com/gallery...
To some it may appear odd that a system for which a contract has not yet been tendered would be being demonstrated by the prospective customer. Those more aware of the long process by which SRT builds a relationship with the client and confidence in its system and implementation ability will see this as a sign that the ground work has been well prepared. Having already achieved a reference site in neighbouring Philippines can only be helpful.
There is little doubt that SRT have a world class set of products and a system to analyse the masses of data collected so that operators can home in on the unusual activities which need human scrutiny.
So far, I've only talked about the systems side of the business but the transceivers side is also making good revenue growth. This is being watched by investors who know that a new product called Nexus is due for commercial launch next year having been a couple of years in development. SRT regard it as a potential game changer which combines AIS and VHF radio in a way which they believe is superior to anything on the market. Talks have been held with all the major brands to ensure they have the opportunity to include Nexus in their product line up.
So, it may just be different this time.
What do these new contracts and/or new products mean in relation to net profit and free cash flows?
Give us some meaningful numbers please?
Thanks
SRT Marine Systems (LON:SRT)
"Give us some meaningful numbers please?"
I'm not prepared to be a hostage to fortune so close to the date when SRT's half year results will be announced (14th November). More relevant to the question asked will be the publication of an updated broker note which I'm assuming will address the subject having access to more insight than a mere shareholder can muster. Suffice to say, I believe the next couple of years will see a significant improvement in revenue, post tax profit and cash flow.
If it was easy to predict before the event, there would not be any advantage in being an investor. DYOR sounds glib but it helps build some confidence in one's choices. Despite the travails of owning SRT shares over the years, my personal investment is thankfully well above the water line and I remain optimistic.
Let me help you with the numbers then as there is a brokerage note out.
The revenues will be around £55m and the free cash flows about £2.5m , the dividends will still be 0 and the share buybacks nowhere to be seen. Therefore on a market cap of £75m this is not even close to any meaningful investment case.
If you really want to investigate the case for SRT Marine Systems (LON:SRT) look no further than their news page - a more full and frank evaluation of their prospects and obstacles to progress I've rarely seen. ST's webcasts are at the bottom of the page. And striking to me was this screen that I captured from the most recent AGM
As I said before forget all these colourful stories.
Concentrate on the numbers.
The numbers do not add up here for an investment case scenario.
Thanks and good luck
Paul I agree totally with your opinion on Joules however have you or Stockopedia members noticed the recent presence of one Richard Teatum on the shareholder list. He's a very shrewd ex car dealer not known for throwing his money about, I would think with Tom Joule they have a cunning plan. We do not hold but I did notice after RT's 11 miilion share purchase the shares started to show signs of life.
Hi JASVFS,
Yes I saw the RNSs about Richard Teatum taking a stake in Joules (LON:JOUL)
I've just looked at his company's accounts (Stoneacre Ltd) and it's a substantial business, with nearly £1bn in revenues, £26m profit in FY 4/2021, and NTAV of £133m. So he looks deep-pocketed enough to refinance JOUL, as you say, maybe in conjunction with Tom Joule.
So I hope a solvent solution might happen for JOUL. It also owns the freehold of its HQ building (currently acting as security for bank debt).
The question is, whether they will be greedy, and buy it from an administrator for peanuts, which would allow them to ditch all the loss-making shops, stuff all the suppliers, and the bank, and start afresh with no debt? Doing a pre-pack administration would then mean they own 100% of the business, and wipe out existing equity. That's what a hard-nosed new investor would probably want to do.
This type of situation is just too risky for me. Also if it is refinanced, you've then got the issue of it not trading well, being terrible at logistics, and having damaged the brand by being in permanent discounting mode. So lots to sort out. But still a fundamentally very good brand, just badly managed for years.
I bought a beautiful duvet set from Joules recently, at a very good price, in the (permanent) sale. I just waited for the (daily) email offering discounts, and when a 40%-off one came through, I grabbed this item below. It's gorgeous, although I find that nonchalantly leaving a gold tray of coffee and croissants on any bed would make it look more appealing (until you climb in, and knock it over!!)
P.S. Best to pay with a credit card, when companies are having solvency issues, so you have protection in the event of it going bust.
Fun fact : Paul's butler was just out of shot on this photo ;)
Sorry Paul, I'm confused. Why would someone who hopes to buy from an administrator bother buying shares? Is it because they would get first shot at a pre-pack simply by virtue of being a shareholder?
Thanks Mr. C for brightening up a dull and wet Monday morning with your "said Sir Humphrey Appleby" note. Brilliant.
This led me to look at the Atome Energy (LON:ATOM) page to discover the even more bizarre. Only Stockopedia could put a Leeds UK postcode into googlemaps and come up with Akjoujt in Mauritania!
I see PayPoint (LON:PAY) are acquiring Appreciate (LON:APP) for 33p plus 0.190 new PayPoint (LON:PAY) shares - plus an Appreciate (LON:APP) divi of 0.8p declared in Sept.
This is approx 44p per share vs last closing price of 26.05p last week - approx 66% gain
I am a holder of Appreciate (LON:APP) and TBH I feel this isn't a great deal - I had high hopes for Appreciate (LON:APP) and it was an excellent dividend payer as well.
It has been recommended by the Board, but TBH they don't have a lot of skin in the game and I question if this is driven more by their personal gain than in the best interest of shareholders.
Morning KEvinS1,
I wouldn't quibble, this looks a decent offer for Appreciate (LON:APP)
(Graham's doing a write up of it now), given that the company has been under-performing, although Graham covered the last update here in Sept 2022, which wasn't bad.
I always wondered with APP why it exists, and if it's just a relic from the past? Also there are competitors, so margins are tight. It seemed to be in semi-permanent restructuring, turnaround measures.
Hence an agreed bid at 44p (33p cash, 11p Paypoint shares) is a 69% premium. The beauty of that, is that it gives you a decent payday, at a nice premium, which you can then deploy to buy some other undervalued company (there are plenty to choose from!)
Whereas if the bid falls through, then the share price would go back down again, probably most of the way.
It could put downward pressure on PayPoint (LON:PAY) shares, if APP shareholders don't want to hold their new PAY shares. Although it looks a decent business, and PAY currently has a generous 7.0% dividend yield, so quite a nice income stock in tough conditions.
Anyway, well done to holders in APP! People always say they're disappointed by a takeover bid, whilst actually being quietly delighted LOL! ;-)
Regards, Paul.
Sorry Paul, I can't agree with you in my own and probably a few other PI's circumstances. Incidentally I also hold PayPoint (LON:PAY) and am underwater there as well.
Your thoughts are more than likely correct Kev, as for myself being a long term holder of Appreciate (LON:APP) I see the vultures as having landed and causing a personal loss of 14.9 percent against who knows what in gains for the Appreciate (LON:APP) board of Directors.
I'm also a holder of Appreciate (LON:APP) and I'm actually very pleased with the c44p offer. Granted, of course I wish it was a stupid high price that Paypoint were offering, but it came in near my sell target price. So excited, as this is my first offer of 2022 and I'd thought I would end the year without any!
The ironic thing is that I did a personal review of my position on Saturday, and concluded:
I'm ruing what could have been in another universe; a refresh of my Appreciate analysis was on my To-do list since last weekend. And also if I was more lax about my liquidity rules, I would have had a bigger position, as Appreciate was one of my top 5 convictions in my portfolio. As it stands, it was 4% of my portfolio (pre-acquisition) so it is only going to contribute a small 2%-ish net increase in my overall portfolio returns for the year.
Also, ironically, I had a look at Paypoint on Sunday, refreshing my internal analysis. Paypoint has been on my watchlist for a while now. And concluded that it was worth buying, but only below 500p. So I won't be looking to keep my Paypoint shares after the acquisition completes; and if the Appreciate share price gets to around 43p or more, I'd happily cash out leaving some money on the table to avoid taking delivery of the Paypoint shares at 560p.
(I hold Appreciate in the Boon Fund)
Also it seems like this one really flew under the radar on Stockopedia, looking at the Community Activity over the last 12 months.
I'd say 10-15% Buy is about average for most shares. The ones with lots of Stockopedia subscriber interest tend to go to 30%, 40% or more? And very few shares get below 8%. So this had some interest, but not huge, which in hindsight you would have thought so with a 60% premium takeover.
Investor Activity rating scores for Appreciate (LON:APP)
(I hold in the Boon Fund)