Small Cap Value Report (Mon 8 July 2024) - KGH, PLUS, MACF. Movers: CRL, ZIN

Good morning from Paul & Graham!
I updated my SCVR summary spreadsheet over the weekend, and we are now up to 552 unique companies covered here (including brief comments) 2024 YTD.
"Profitable Growth"
This phrase seems to be appearing with greater frequency in trading updates. It strikes me as being vague, and not really telling us much, if anything. Do you share that view, or is it just me over-thinking things, and/or being neurotic? Let's find out! I've set up a quick & simple online poll here. Please don't share this link, as I'm just trying to gauge opinion amongst Stockopedia subscribers. Then I can share the results with the PR/broking community, to give them some feedback. There's also a comment field where you can leave any additional views (up to 100 characters, the max allowed). Just a bit of fun, and if people like this, we can do some more polls!
Tell us your opinion here!
Apologies, the survey is now full, as they start charging after just 25 responses, so I'll have to find some better survey system (I might set up my own on Google Forms, leave that with me for later).
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
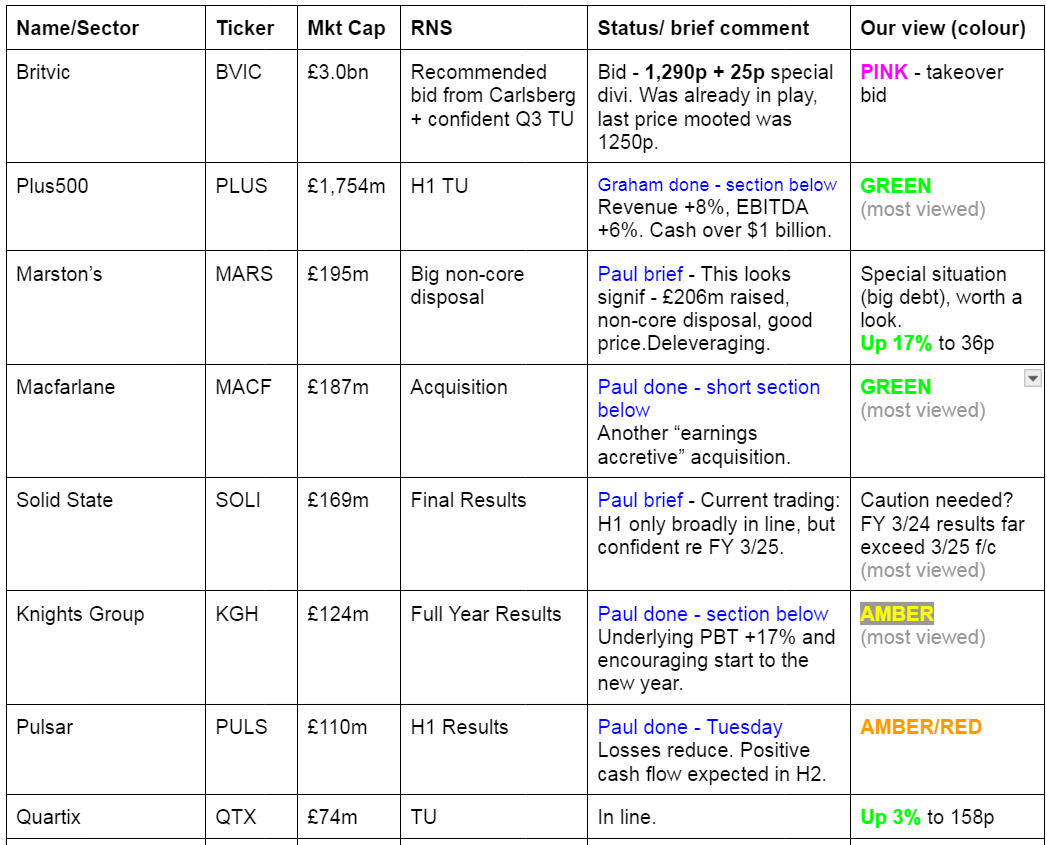
Other mid-morning movers (with news)
Creightons (LON:CRL) - down 10% to 19.0p (£13m) - Update on Asset Impairment - Paul - AMBER
Creightons plc (LSE: CRL), the product developer, brand owner and manufacturer of personal care, beauty, and fragrance products, today announces an update on its annual impairment review of goodwill and brand values…
Interesting, it looks as if some small shareholders panicked first thing, with trades printed as low as 14.5p. Since then it’s been steadily recovering to only down 10% at the time of writing (11:08).
My summary -
Audit for FY 3/2024 still underway.
Impairment of the Emma Hardie brand/goodwill will be a non-cash, post tax write off of £4.62m.
No impairments required on any other brands.
Underlying trading -
“The operational performance of the Group in the year to 31 March 2024, will show improved underlying profit and cash generation in the second half of the year in comparison to the first half.”
Results due out 18/7/2024, webinar at 11:00, 24/7/2024.
Paul’s view - storm in a teacup. I nearly always write off intangible assets anyway, so it doesn’t really matter to me when these are impaired. Also it's a process driven by the auditors, so often may not be anticipated earlier in the year. It’s not a cash cost now, although as others have pointed out, impairments are usually a historical cash cost from when the acquisition was originally made. My understanding is that CRL was already known to have a patchy track record in the brands and companies it has previously purchased.
For me all that matters is current, and future trading, which sounds OK in the bit I’ve highlighted above.
What is missing from the announcement? I think it needed a clear statement of performance vs expectations for the underlying business. Also since I can’t see any forecasts, then it needed a footnote saying what market expectations are. Finally, I would have liked confirmation of the current net cash/debt and liquidity position.
CRL has been through some turmoil, I don’t cover it often here, but I see from 4/12/2023 I noted that the long-serving CEO seemed to have been booted out.
The Emma Hardie brand only delivered £1.5m revenues in H1, so CRL clearly made a bad buy there. Overpriced anyway, but presumably investors would have already worked that out from its modest sales?
Is CRL at risk from insolvency? I think not. Its last balance sheet looks pretty solid, with c.£12m NTAV (which of course has already written off all intangibles, so won’t change after today’s news).
Overall then, I’m happy to stick at AMBER, and keep an open mind, since I don’t know how it’s likely to trade in future. But there are no alarm signals either in today’s update, not in the historical accounts, so nothing for me to warn you about.
The obvious questions to ask management are what went wrong with this acquisition, and how will they avoid making a similar mistake again?
Zinc Media (LON:ZIN) - down 16% to 70p (£16m) - Trading Update - Paul - RED
Zinc Media Group plc (AIM: ZIN), the award-winning television and content production group, today announces a trading update for the six months ended 30 June 2024 ("H1 FY24").
Customers taking longer to sign contracts, and £2m revenues have slipped from FY 12/2024 into next year.
Cash at 6/2024 was £4.0m. What this RNS omits to say, is that it also has £3.5m of debt (propped up by Herald Inv Trust, and another shareholder). So net cash will only be c.£0.5m - highly misleading to only mention gross cash and ignore debt, in a trading update - a pet hate of mine - it's deliberate deception, simple as that.
Outlook - despite various problems, it says cost-cutting has been done. This comment has rattled my cage -
“which provides the Board with confidence in the Group's ability to deliver continued profitable growth in FY24 and FY25."”
It’s not profitable! So how can it deliver “profitable growth”, let alone “continued” profitable growth, when I don’t think it’s ever made a genuine profit (PBT)?
Paul’s view - I find the investor communications from ZIN to be one of the most dishonest out there. I've learned to completely disregard everything management say. Check out the recordings of its webinars to see what I mean. I remember seeing one on Mello and thinking this sounds great. Then I looked at the historical numbers, and there was almost no correlation between what its CEO said, and the actual numbers! He talks as if this is a profitable, successful company. Reality is that it’s on its knees financially, having only avoided insolvency from shareholder loans, and has been consistently loss-making. I worry that naive investors are being sucked into buying something pretty rubbish at an inflated price. Hence the warnings here, one of the few places out there that tell you the unvarnished truth as we see it, because we don't take any fees from companies to lie for them - unlike city advisers.
Creditors look stretched, and I suspect this share is a strong candidate for ending up at zero, so a complete bargepole stock for me. Harsh? Not really - have a look at the figures, they’re dreadful.
Summaries
Knights group (LON:KGH) - unch 145p (at 08:21) £124m - FY 4/2024 Results - Paul - AMBER
Headline numbers look great, but the deeper I got into the detail below, the less keen I became. Cashflow in particular don't look up to scratch. So I've come down a notch from amber/green to just AMBER. There's nothing particularly bad here, it's just not the great bargain that it initially looks, in my view.
Plus500 (LON:PLUS) - down 4% to £22.28 (£1.7 billion / $2.2 billion) - Half Year 2024 Trading Update - Graham - GREEN
The outlook is in line with expectations for the full year after this H1 update shows good progress in revenue and EBITDA despite the impact of Euro 2024. I think the company has a great chance of beating consensus expectations this year, and perhaps investors were expecting it to say as much today.
Macfarlane (LON:MACF) - up 3% to 121p (£192m) - Acquisition - Paul - GREEN
Quick comment [no section below] - the latest acquisition in this packaging group’s buy & build strategy is called Polyformes. Funded through existing debt facility. Says it’s earnings accretive. In FY 12/2023 Polyformes made £1.4m PBT on £9.3m revenues. Initial consideration c.£6.7m, plus potential 2-year earnout of £4.8m maximum - seems a reasonable price.
Paul’s view - I remain of the view that MACF seems a decent business, with a good strategy to self-fund lots of bolt on acquisitions. Shares always seem cheap, and the fwd PER is now only 9.4x.
There was a wobble on 7/5/2024, when it revealed soft Q1 performance, hoping to be made up in H2, which can be a deferred profit warning sometimes. Although given a good long-term track record, personally I’d see temporarily softer trading as more of a buying than selling opportunity. [
Paul’s Section:
Knights group (LON:KGH)
Unch 145p (at 08:21) £124m - FY 4/2024 Results - Paul - AMBER
Knights, the legal and professional services business, today announces its full year results for the year ended 30 April 2024.
A good performance, reflecting resilience, scale and financial discipline
Plan to double the business in medium term
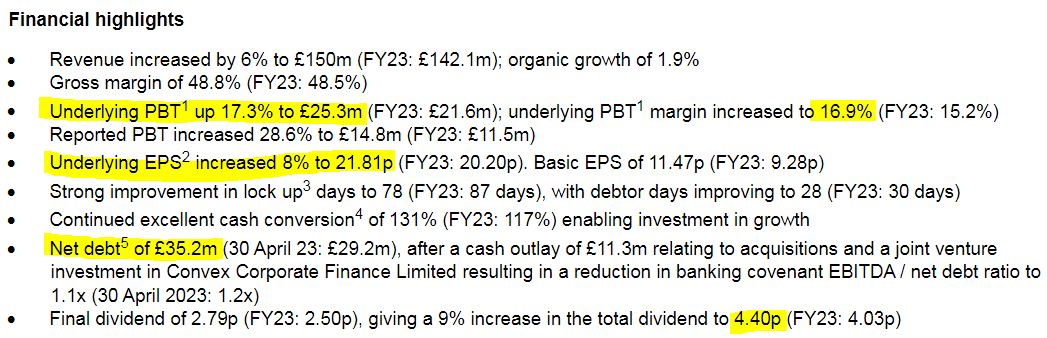
I’m drawn to the numbers I’ve highlighted below - showing nice profit growth vs LY, a good PBT margin, and the PER is only 6.6x adj EPS of 21.81p - more than enough to make me want to dig deeper.
Although using statutory diluted EPS of 11.1p, the PER is 13.1x - about the valuation I would expect. So the key question for investors in this share, is whether or not you accept the profit adjustments. If you do, it’s cheap. If you don’t, then it’s probably priced about right.
The Chairman’s statement says -
“… the Group's financial performance was in line with the Board's and market expectations, with a significant rise in profitability.”
Adjustments are large - with adj PBT £25.3m enhanced by 71% from statutory PBT of £14.8m. Are adjustments reasonable? I’m not entirely sure, as I’ve never really got my head around the issue of contingent acquisition payments treated as remuneration. Note also the size & repeat nature of “other non-underlying costs”, which suggests some of these are regular things. It strikes me as a fairly aggressive level of adjustments overall, hence I can see why some investors wouldn’t want to chase up the PER multiple very high -
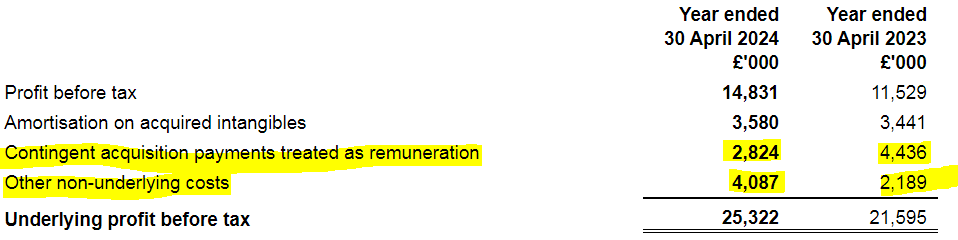
“Underlying profit before tax excludes amortisation of acquired intangibles, transaction, and onerous lease expenses in relation to acquisitions, contingent acquisition payments, disposals of acquired assets, one-off restructuring and professional costs mainly incurred in the streamlining of support functions or strategic reorganisations. “
Acquisitions - two completed in the year, with both performing ahead of expectations, per the CEO review.
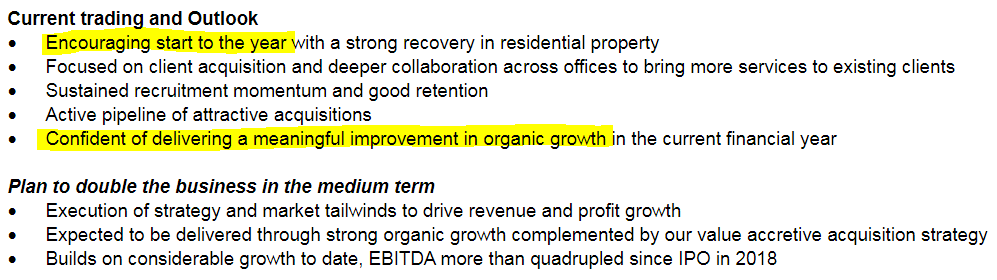
Outlook - this sounds positive, but it’s somewhat vague, and doesn’t directly confirm market expectations, thus introducing doubt -
Balance sheet - NAV of £100m is dominated by goodwill & similar of £87m, so only £13m of NTAV.
Lease entries are quite high too, so it’s obviously got a lot of office space - hence its policy on working from home, and any issues with surplus property would be good questions to ask. The commentary mentions “rightsizing” its property portfolio. Remember that it’s one thing to make a provision for onerous leases, and adjust it out of profit, but the rents still have to be paid in cash! Note 33 shows £4.8m of property provisions (dilapidations), but only £244k in onerous leases, the latter being less than I was expecting.
A drawback with solicitors’ accounts is the working capital tied up in both billed, and unbilled fees which have been booked to revenue & profit, but not yet received in cash. These are £32.8m + £40.2m here, total £73.0m. That’s almost half the full year’s revenue of £150m. Billed of £32.8m probably includes VAT, so taking that down to pre-VAT would reduce the total to £67.5m. Still 164 days revenues. That includes prepayments and amounts due from a JV, so if I adjust those out, trade debtors (exc VAT) comes down to £58m, or 141 days. My figure is way higher than the company’s “lock up” figure of 78 days shown in the financial highlights, so this area needs some more work, as I’m not convinced the company’s reporting number of 78 days is realistic of the reality of how much customers owe.
Bank net debt is £35.2m, which is towards the top end of what I’m comfortable with. I’m not keen on Knights doing more acquisitions funded with debt.
Cashflow statement - these usually reveal what’s really going on! This looks quite poor to me. In particular, capex cash outflows of £8.2m look high, and seem to relate to property (note 23). Yet the large disposal number doesn’t come through into cash, suggesting to me that capex is a cash cost, but disposals look to be losses (ie not cash coming in).
The way I look at it, the acquisitions and dividends look to have been funded from increased bank debt.
Lease and other finance costs are hefty cash outflows of £5.1m and £4.5m.
Overall then, I’m raising an amber/red flag over poor cash generation. Well, almost no cash generation actually.
Paul’s opinion - the headline low PER and good profit growth look great at first sight.
Although the deeper I dig, particularly into the cashflows, the less enthusiastic I’ve become.
For that reason I’m moving it down a notch from amber/green, to just AMBER.
I prefer simpler, more obviously cash generative companies, which this isn’t.
Cheap on a PER basis, but for good reasons, is my view. Just an opinion as always, so feel free to disagree & post your reasons why.
EDIT: Many thanks to Brothersinarms, who points out below in the reader comments that interest on client monies is a huge number, which is mainly what has driven the profit increase. I didn't spot that on my initial review, so appreciate this important point being thrown into the discussion. The company's commentary confirms this -
"Other operating income has increased to £10.4m from £6.7m driven by an increase in interest earned on client monies held due to higher interest rates in FY24 than the previous year."
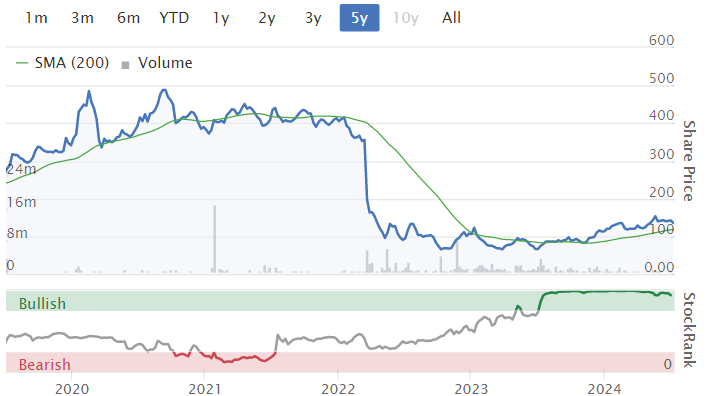
Graham’s Section:
Plus500 (LON:PLUS)
Down 4% to £22.28 (£1.7 billion / $2.2 billion) - Half Year 2024 Trading Update - Graham - GREEN
Plus500, a global multi-asset fintech group operating proprietary technology-based trading platforms, announces its trading update for the six months ended 30 June 2024.
Over time, I’ve turned more positive on this CFD provider as it built a lengthy track record of profitability, cash generation and shareholder rewards.
I am also a long-term shareholder in IG group (LON:IGG) and I’ve included CMC Markets (LON:CMCX) in my best ideas list for 2024, so this is a sector I tend to be very positive on!
It has been a fabulous time to be a PLUS shareholder:
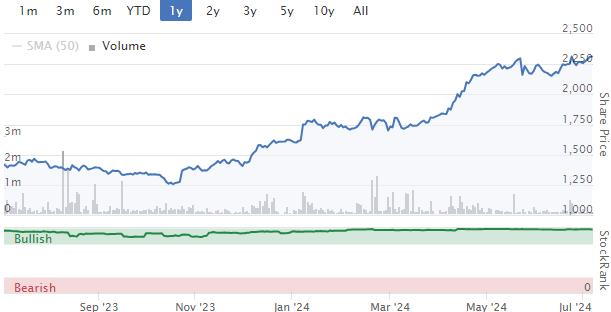
Today’s H1 trading update has the following key info:
H1 revenue +8% to $398m. Q2 revenue +14%.
H1 EBITDA +6% to $184m. Q2 EBITDA +11%.
CEO comment describes “excellent financial and operational performance despite difficult market conditions”.
There were “lower levels of activity across financial markets” towards the end of the period due to the UEFA Euro 2024 tournament - so customers are betting on/watching the footie instead of trading.
Cash was over $1 billion by the end of H1.
Customers: 56.8k new customers were onboarded in H1, and the total base of active customers was 175.9k. The total number of active customers in H1 is about the same as last year.
Shareholder returns: $81m of PLUS stock was bought back in H1. In total, $175m of dividends and buybacks were announced in H1. New shareholder returns will be announced with the H1 results:
Outlook: in line with current market expectations.
Expectations are shown on the company’s website, with a small dip in revenues and EBITDA expected this year:
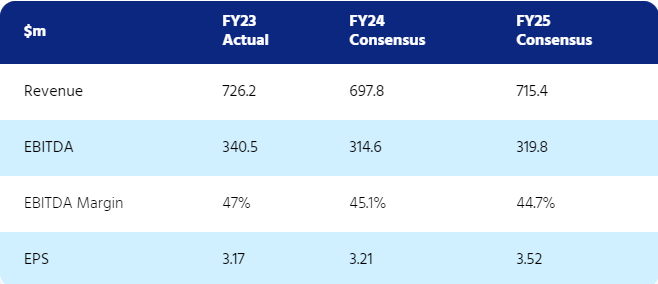
Graham’s view
I’m comfortable with my positive stance here, as I think that Plus500 has proven itself as a consistent generator of cash.
Some of the old arguments against the stock are still valid, in my view, but have been overtaken in importance by the fact that the company has generated mountains of cash - and returned large amounts of that cash to shareholders.
For example, there is the claim that Plus500 profits directly from customers’ trading losses. The company still insists that the contribution of customers’ trading losses is expected to be “broadly neutral over time”. It calls this item Customer Trading Performance.
In 2023, it benefited to the tune of $74m from Customer Trading Performance.
In 2022, Customer Trading Performance contributed $193m.
In 2021, it contributed $16m.
The right way to analyse the stock is probably to value it first excluding Customer Trading Performance, and then try to value the contributions from Customer Trading Performance separately
The volatile and sometimes large impact of Customer Trading Performance adds a degree of uncertainty to all financial forecasts for PLUS - e.g. I think the company could easily beat its consensus forecasts this year, but it’s too soon for anyone to predict this with confidence. But PLUS has already earned 57% of its full-year revenue forecast and 58% of its full-year EBITDA forecast.
Being a cash-rich company, it is also sensitive to interest rates: interest income last year was over $50m and this figure is included in top-line revenue.
The other old argument from bears like myself relates to customer churn. We can see from the H1 figures that new customers in H1 (56.8k) account for a high proportion of total active customers (175.9k). My impression is that the company has made some progress when it comes to increasing the longevity of the average customer, but a high degree of churn is still indicated to me by these numbers.
So when it comes to the quality of the business, I still have a preference for IGG and CMCX, which I believe have higher-quality customers along with more sophisticated and robust hedging policies.
While PLUS would probably deny it, my impression is that PLUS are happy to book their clients because a) their clients are more likely than not to lose, in aggregate and over time; and b) PLUS is happy to carry an extraordinarily large cash balance. So it can afford to pay out in the event that customers don’t lose.
Ultimately, the bearish arguments here don’t matter if the company continues to execute with a combination of successful marketing and a platform that customers enjoy using. The regulators have gone quiet in this sector for now. Traders are trading and the platforms are making money. It’s a nice time to be a shareholder.
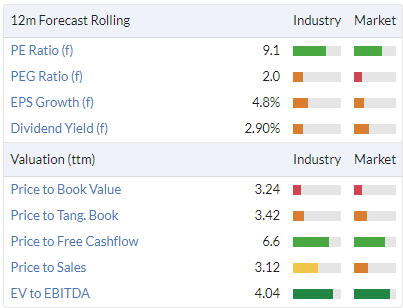
With a $1 billion cushion to be deducted from the PLUS market cap, the enterprise value here is only $1.2 billion. So you can count the EV/EBITDA multiple on the fingers of one hand. Even allowing for the issues raised above, I still see value here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Thanks for Plus500 (LON:PLUS)
Chart wise it busted through 1800 Apr 24 and now breaking resistance of 2300 so another "staircasing" up. How do people try to increase their wealth. Pensions/ISAs etc are under the eye of Sauron aka government and buy-to-let a risky business.
But they will come for spread betters at some point and its tax free advantage, so the inevitable levelling down to the gulag.
First time post here but long term private investor. Any thoughts anyone on David Stirling, long time CEO of Zotefoams (LON:ZTF), retiring and joining Macfarlane (LON:MACF) as a Non-Executive Director? Very successful of course and massive shoes to fill at Zotefoams (LON:ZTF)
Hello ChrisR,
and welcome to the boards I hope you will post more frequently. I posted my thoughts on 16th of July - I don't normally post on the appointment of a NED , but occasionally it can signify something of the aims of the management and I think it does in this case. Subsequently Shore Capital (house broker) posted similar thinking and also connecting with the recent acquisition of Polyformes.
Here's my note from 16th July:
illiswilgig Joined 2010 343 posts Jul 16, 2024
Macfarlane (LON:MACF) Appoint of Non-executive Director
Not normally riveting news. But in this case?
David Stirling, recently retired long time CEO of Zotefoams (LON:ZTF) has just been appointed NED at Macfarlane.
Intriguing? I had already sensed a strategic shift at Macfarlane (LON:MACF).
Sales at the largest division, distribution, have been falling . My assumption has been that the company is choosing not to compete upon price in low margin general packaging sales while increasing their focus upon higher margin specialist protective packaging.
Their rapidly growing manufacturing division both organically and through acquisitions has higher margins. Last week they acquired Polyformes a leading supplier of custom foam packaging and engineered parts to the aerospace and industrial markets - where Zotefoams is one of their main suppliers. In 2023 they acquired Barum and Dewar, a bespoke protective packaging maker (including engineered foam products) for the aerospace and defence markets.
The bespoke packaging industry supporting aerospace, defence and industrial sectors in the UK is very fragmented. It's much higher margin than corrugated cardboard and bubblewrap and tends to work on long term relationships. esp for shipping high value fragile items. This supports my view that Macfarlane (LON:MACF) is aiming to build a leading position in this specialist long term growth market?
I shall watch with interest. Long term I expect this to increase margins and rate of earnings growth,
cheers
Mark (liong term holder of Macfarlane (LON:MACF)
Thanks for your reply Mark. I have been researching Macfarlane (LON:MACF) recently and note the share price has remained pretty stagnant for a while so a shift in direction may help it rerate and stay above 145p, then push on. I do also hold Zotefoams (LON:ZTF) and look forward to their trading update on the 6th August, the first under the new CEO.
Knights group (LON:KGH) FY24 results presentation by management may provide some light on details flagged by Paul above video & podcast. A buy-and-build is always a more complicated picture. We know some of the acquisitions came with property leases, which are being restructured and cost synergies achieved. Clinical negligence has provided good revenue at strong margins when property and M&A were quiet but it has a longer cash conversion period (can take 2 yrs). Otherwise, Debtor days and WIP days are a key focus for KGH, where they are industry-leading. Management are highly commercial. They target to double revenue and profit in 3-5 years: 1/3rd organically, 2/3rds through acquisitions. For now, organic growth is a priority. Outlook: Residential property is up 30% since the start of the new financial year, and they expect M&A to start to return. Capex guidance for FY25: £11m.
You imply 750MW of wind generation costs arounf £45bn, i.e. around £60m per MW. Those figures are nonsense. A modern wind turbine costs around £1m per MW, less if you go bigger as is increasingly the case.
I'm not totally against nuclear, it has a role, for now at least, in being able to provide consistent power generation, but our powe for some time to come (decades?) is going to come from a mix of HCs, nuclear and sustainable (such as wind, solar and possibly tide). But it's no at the moment an either or, and as is crystal clear the costs of solar and wind generation have fall, and continue to fall, continually. Perhaps modular nuclear will cut costs there, but up till now massive cost overruns has been the norm. Storage will reduce in cost too, but we don't need to, and certainly won't, plan a power system that is based on 100% wind backed entirely by storage.
Hi Paul, thanks for Macfarlane’s short section
Apropos my post about Gordon "Robber" Brown's stealing from pension funds, coincidentally this article was on the Telegraph site. Lists manifesto pledges versus reality for Bliar and Brown. It's unlocked and archived here.
Does anyone know what has initiated the spike down at Ashtead Technology Holdings (LON:AT.) today. It's clearly been triggered by something at around 3.30pm but I'm not sure what!
Beeks Financial Cloud (LON:BKS) have announced a Trading Update this morning for July 22nd. Last year the TU was 6th September some 45 days later. Could this be a case of Beeks management being keen to announce further good news? In March they stated....
"With our proven offering and growing tier 1 customer base, which includes some of the largest financial organisations in the world, as well as our increasing profit margins and cash generation, we have never been better placed to seize the opportunity".
The SP is up almost 5% today so its looking promising. I hold
Thanks for the comments from members on MBH, added 5000 before the close at 100p also added 5000 Macfarlane at 121p before the slight rally, we had decent holdings in both companies prior to today, they are at 3rd and 5th (MBH) by value in our portfolio. Also added a few Wynnstay which is number 2 and needs patience.
Court judgement on water company pollution.
I have not noticed this in the newspapers etc. It looks like water companies may be sued for putting sewage in the water.
Yes very interesting, action brought by the Manchester Ship Canal Company against United Utilities. Just the kind of loony lefty reporting I'd expect from the Guardian :-)
https://www.theguardian.com/en...
cheers
Mark
PS - Sold the UU shares in a 'family' portfolio in advance of this
MBH (DUS:M8H0)
With the funds from the sale of Marston's (LON:MARS) this morning, I added a few Michelmersh Brick Holdings (LON:MBH). Admittedly much smaller than Forterra (LON:FORT) and Ibstock (LON:IBST) and a manufacturer of specialist bricks, but despite this the valuation disparity looks anomalous.
From AGM Statement of 16th May:
"Since reporting our full-year 2023 results in March, we have continued to experience positive momentum in our order intake, reflecting the benefits of our product portfolio's broad reach and the strong customer loyalty and distributor relationships we have across our end markets.
"We remain mindful of the higher interest rate environment and its impact on demand across the wider construction industry, and as such continue to focus on appropriate portfolio pricing to maintain diversity in our forward order book, which is drawn from social and specification housing, RMI, new build and commercial sectors.
"While delivery schedules have been impacted in the first quarter, as a result of more challenging seasonal conditions, production volumes continue in line with our expectations. With order intake momentum at levels not seen since the end of 2022 driving improved volume and quality of the forward order book, we anticipate increased despatch volumes for the remainder of the financial year, which when combined with the strength of our balance sheet, positions the Company well for delivering full-year expectations."
Rachel Reeves speech : 'Speaking about pensions Ms Reeves said: "We will turn our attention to the pensions system to drive investment in homegrown British business and to deliver greater returns to pensions savers." Here's hoping some of our more laggard UK based and focused fund managers end up finally getting rewarded and seeing some of that pension money.
Hopefully a positive and maybe they could do something to stem the tide of companies quiting the London Stock Exchange.
Regarding pensions etc my only fear is the new Government meddles by mandating certain types of investment such as 'green' and other forms of picking 'winners'.
Reeves has also announced an increased investment in wind power as though it was something good. Right now wind power, after £45 billion of investment is giving us 750mw, while nuclear is as usual providing a reliable 4500mw.
The cost of wind produced electricity is not helped by taking 30,000 people to deliver it. The basis of a modern economy is the cost of energy, we are allowing ourselves to be crushed by it and no amount of “open for business” rhetoric will make any difference. As investors do we have to follow where our tax pounds are (pointlessly) wasted or go where, eventually, reality will force the government’s hand if we are to prosper? Very disappointing that we have to make this choice.
Right now wind power, after £45 billion of investment is giving us 750mw, while nuclear is as usual providing a reliable 4500mw.
Those wind power figures don't look right to me?
https://www.gridwatch.templar....
Currently wind is supplying 8.57GW(29.76%)
Nuclear 4.68GW(16.25%)
The latest available quarterly figures Q1 2024 are
Wind generation 26.1 Twh
Nuclear generation 8.3 Twh (lowest recorded due to outages)
data from https://assets.publishing.serv...
just sayin'....
Mark
Currently wind is supplying 8.57GW(29.76%)
How reliable are these "gridwatch" sites?
According to gridwatch.co.uk wind is currently 0.73 GW only 2% not the 29% you are quoting.
How reliable are these "gridwatch" sites?
per the link i provided it was 29.4% over the whole year last year - is that not enough proof of the pudding?
is that not enough proof of the pudding?
I'm not disputing the annual average. The issue with wind is that it is intermittent, only contributing about 2% of total demand today. Something else is needed to fill the void. I think this is the point Aislabie is making.
all energy generation is intermittent thats the nature of the beast - obviously wind is more variable than most other stuff but we are managing ok with wind already at 1/3 of the mix most of the doom and gloom mongers would have said that was impossible 10 years ago. we have hardly started on battery investment (battey and wind is a pefect combo) we have made zero investment in tidal little investment in hydro and need to invest more in ability to transmit between the countries. the falacy that we need 2 coal power station on standby for every 1 wind equivalent is just that nonsense.
The problem is not that we cannot manage it is that this management is gruesomely uneconomic - before we even discuss batteries which do nothing at all to lower energy costs.
Despite the bleating, the Government takes over an economy with historically modest and declining inflation, full employment (for those able and willing to work) and a government debt pattern that, while higher than historically experienced, is well managed to long dated maturities. So what is wrong? The cost of energy; which affects everything we do and which is kept artificially high to “manage” the wildly ineffective £45 billion investment (so far)in wind power and thus put both our government and industrial costs at uncompetitive levels. Tidal power (see Simec ) is hopeless even when applied to the Pentland Firth, which is about as good as it gets for favourable conditions. To give our economy the shove it needs to afford all the aspirational spending this government wants, requires us to lower energy costs. The carbon footprint has been declining mainly because of the move to gas and we should be seeking to build our own gas and oil over the decade or so while every other pound gets put into replacing it with a reliable nuclear base for increased electrical usage. The biomass number seems to be largely based on clear cutting South Carolina for Drax and this should also be stopped as soon as possible. We need to get a position in the mid 2030s where our fossil fuel needs starts to drop fast, this is affordable and realistic and (will coincide with the expensive and necessary decommissioning of masses of uneconomic wind farms).
With enough electricity electrolysis should allow cheap hydrogen production for fuelling the gas turbines for handling peak loads above the nuclear base.
You do raise some valid points Aislabie agree gas if the cheapest is then most obvious practical stopgap solution - should our government have gone so gung ho on freebies for renewable providers probably not. I am trying to be balanced here and you seem to ignore the fact seems clear to me offshore wind prices are coming down and onshore is surely cheaper than nuclear and we are so far of getting any new nuclear up and running at reasonable costs perhaps its best left on the drawing board - perhaps Tidal power via the severn eastuary may not turn out viable . I for one though feel we have made some decent progress to be where we are and to me the future is brigght with options - renewable do all need to stand on their own to feet though so i for one am happy if future subsidies will be be cut back. It appears to me that the stupidity of the government more than anything has caused some of the high energy prices we have - eg by locking in fixed prices at the peak a couple of years back and not boxing clever to ensure we are not having our eyes gouged out by excessive profiteering - and not plannig for more gas storage Must admit i have none of the answers - i only came on here to back up the real i am fact that wind did generate 29% of our electric last year however much you diss it with suggestions that nuclear provides more when that is clearly not the case.
How reliable are these "gridwatch" sites?
According to gridwatch.co.uk wind is currently 0.73 GW only 2% not the 29% you are quoting.
Whooops!
My apologies!
you are quite right. These sites are normally reliable. Not today. There seems to be a data feed problem affecting some data on some or all sites. I should have noticed that! My bad.
That doesn't affect the governments Quarterly update for 2024 Q1
Wind generation 26.1 Twh
Nuclear generation 8.3 Twh (lowest recorded due to outages)
data from https://assets.publishing.serv...
sorry for any confusion caused,
Mark
Reeves has also announced an increased investment in wind power as though it was something good. Right now wind power, after £45 billion of investment is giving us 750mw, while nuclear is as usual providing a reliable 4500mw.
where on earth have you got your stats from Aislabie?
facts are in 2023 29.4% of the electricity grid generation came from Wind and 14.2% from Nuclear?
https://www.nationalgrideso.co...
personally i would be surprised if onshore wind power costs more than nuclear now - happy to be convinced otherwise if you can provide a non biased link. Note i would say the net is probably full of bias on both sides ref that debate.
I find this site useful and generally accurate regarding electricity generation. I believe the data is sourced directly from the National Grid https://grid.iamkate.com/
She could start by reversing the decision by Prudence Brown to tax pension funds' dividend income which, together with his quantitative easing scheme of virtually zero interest , has had the effect of reducing the ability to maintain payments against inflation plus reducing the investment capital available. Increments to pre 1997 benefits are discretional and this has resulted in some companies making no adjustments for those contributions. Final salary scheme indeed.
Creightons (LON:CRL) ( I held historically)
Emma Hardie acquisition and impairments, my recollection is that shares were used as a significant part of the purchase but they guaranteed the value of the shares issued which was above 100p !!
The long serving MD went abruptly and I do not recall any thanks for years of service
The Chair /CEO retired in March and switched to Non exec ( he is largest shareholder 23.7% )
To my knowledge they never had any broker coverage but they used to give guidance of a type at the end of their webinars on PI World, they called it aspirations and what I recall was revenue target of £100m and margin target of 10% ( can’t remember timeline)
I will continue to avoid but will watch presentation on July 24th as announced today
Michelmersh Brick Holdings (LON:MBH) I bought 5000 on Friday using HL , no problem dealing .
if you have time, it would be good to have some thoughts on Solid State (I hold). @soli The results seem to be good; but clearly not quite good enough for the market. With a market cap of about £170 million it seems a good size for the SCVR, and to my amateur eye, it appears to have a good niche
No problem in buying Michelmersh Brick Holdings (LON:MBH) on HL. Just tried 20000 and it came back with buy price of 100p.
Michelmersh Brick Holdings (LON:MBH) Can buy on IG group (LON:IGG) now at 99.8p but could not buy earlier.
I've just tried to add to our MBH holding through Barclays Smart Investor, It wouldn't give a price for 5000 twice, then 2500, and finally 1000. I got an immediate price above the current 98/99 to sell a lot more, which we didn't of course. Any comments from members?
Can't even get a quote to buy 100 Michelmersh Brick Holdings (LON:MBH) shares on IG platform. This sort of thing has been going on for about year now.
Michelmersh Brick Holdings (LON:MBH) just tried on AJ Bell and 1000 shares seems to be the most that can be purchased - surprisingly illiquid for some reason.
I managed to buy 1000 about a month ago - No issues (Via HL)
Can buy Michelmersh Brick Holdings (LON:MBH) now price has gone up to 99.8p.
Bought 2163 late June via HL.
When the sell price exceeds the mid price or the buying price or you can't buy but you can sell, it tells you there are lots of buyers in the market. This is a bullish sign. Don't sell. The price is likely to continue to climb.
These guys need to realise they can’t keep shareholders in the dark! Better comms and broker coverage wouldn’t go amiss. PS: I hold
Who are you referring to? Please add a ticker or name at least!
Ironic that you are talking about better communication but don't say who you are talking about. :) You would help to give us a clue if you used the reply button then we could see who you are replying to.
He did.
But you were replying to Shopping365 though, not Oilinvestor85.
Shopping365 replied to Oilinvestor85.
Rusty, are you trying to draw me into another pointless argument, obvious who I was talking too. Over and out.
You replied to the wrong person then.
Surely it is Michelmersh Brick Holdings (LON:MBH) ?
Morning all. Firstly thank you to Paul & Graham for the continued excellent coverage & the rest of the regular posters. I don't think there's a better place out there for analysis & discussion of UK small caps. Especially useful in the confusing & opaque system we have in the UK.
I haven't posted one of these in a while as I've been transitioning into more of a trading focussed strategy recently & have been trying to nail my process down.
My new system, for those that haven't seen elsewhere, is momentum based. Trying to buy a stock as its entering a new up trend, or in a continuing one. As such I've adapted my snapshot to focus more on the factors that should lead to that new, or continuing up trend. These factors being recent earnings growth, forward growth expectations & some elements of historic growth. With the new score being out of 50 & a score of 36 or higher required to go on my watchlist. All based on excellent investors / traders like William O'Neil, Stan Weinstein & Mark Minervini. Basically I want to see accelerating earnings & revenue for current results & forward guidance (green boxes). Green everywhere is a very good sign!
I know there's a fair few people here that follow very similar strategies so hopefully these snapshots will still be of interest to many.
Anyway, here's my snapshot for Solid State (LON:SOLI) . Excellent results for the year with exceptional growth in their Systems segment. However FY25 is set to see a pull back in top & bottom line due to exceptional comparisons. The long term growth story appears to be still very much in tact. It previously scored a 36 on my checklist so was on the watchlist, however these results drop it off for now.
Music to my ears as a momentum trader. Phil.Loved the focus and set-up.Whats the highest score in the current watchlist
For the UK the top three are currently Warpaint London (LON:W7L) (48), Cairn Homes (LON:CRN) (44) & Gaming Realms (LON:GMR) (44).
For the USA its NVIDIA (NSQ:NVDA) (50), Wingstop (NSQ:WING) (48) & Applovin (NSQ:APP) (48).
The scores will change whenever new earnings come out so these aren't guaranteed to still be the best in a few months. I am finding the USA has far more options at the moment, though I fully expect this will change over time. Currently there's 18 UK stocks on my watchlist & 55 US ones. Of course I haven't gone through every single available stock though, so I'm bound to have missed some that haven't come up on screens or aren't well known.
Interesting (although slightly secretive) announcement from ITM Power (LON:ITM) this morning:
ITM is pleased to announce that it has signed a 500MW capacity reservation with a global industrial customer. This reservation secures future production capacity for the manufacturing of our state-of-the-art electrolyser stacks.
The agreement covers the period until the end of the 2028 calendar year and foresees call-offs against future projects in Europe and the US.
The two companies have agreed not to disclose further contract details at this stage.
Dennis Schulz, CEO ITM, said: "Today's announcement is a great example of how close collaboration will unlock competitive and successful green hydrogen projects. Following the already announced capacity reservation for 100MW from Shell, this agreement with yet another large-scale industrial customer is a validation of our technology and credibility to deliver."
Looking forward to hearing more when their final results are out in August.
I'm a fan of ITM Power (LON:ITM) . They have a lot of capital investment from Linde, the industrial gases owner of British Oxygen and also from Lord Bamford of JCB. New CEO has worked hard to throw the losing parts of the business overboard and prioritise the profitable. I would recommend anyone interested in the use of off-peak renewable electricity to produce hydrogen as an alternative fuel to watch this presentation on IMC from last year. An impressive CEO.
Thanks Samsgrandad, re ITM Power (LON:ITM) but the link to the presentation generates an error. I will find it some other way.
Sorry, too late to edit but InvestorMeet Company still have it, they moved it here.
Macfarlane (LON:MACF) earnings accretive acquisition of Polyformes Limited ("Polyformes") for up to a maximum cash consideration of £11.5 million, including an earn-out of up to £4.8 million over two years.
Note that Macfarlane has a habit of putting the price including earnout at the front - price paid today is £6.7m plus an expected £0.2m adjustment for the anticipated 0.7m net cash with the business. The three directors stay with the business and the £4.8m earnout is dependent upon achieving profit growth targets over the next two years.
Another excellent acquisition from Macfarlane. Shore capital (house broker) have released an updated note on research tree (free) this morning - upgrading FY25 - but not FY24.
Most likely because the market was spooked by MACF's AGM trading update which revealed a 9.5% fall in sales in Q1.
The AGM TU also revealed that net cash had risen to £4.7m at end Q1 after paying for the Allpack acquisition - so this acquisition will also be mainly paid from strong cashflow being generated.
The buy and build acquisition strategy continues apace - important to note that Macfarlane continues to buy highly profitable businesses at good prices in niche specialist protective packaging markets serving growth sectors of aerospace, medical, defence and industrial - rather than FMCG and ecommerce where pricing and demand are currently challenging. When demand in the economy does improve - Marfarlane will be well prepared to benefit strongly.
Macfarlane (LON:MACF) has long been one of my top holdings and I see no reason to change that - if anything I am more encouraged by the work the company is doing to improve its future position in protective packaging manufacture and distribution. Now my third largest holding at around 9% following the ascent of MS International (LON:MSI) (now 42% of my folio) and recently the seemingly unstoppable upwards move of Vianet (LON:VNET)
cheers
Mark
Marston's (LON:MARS)
Further to my post last Thursday I have sold my modest holding that I bought at 30.5p for 36.5p; clever no. lucky yes! We all need a little luck from time to time.
It may be that the shares will recover further in time, but a 20% rise in the share price appears to reflect this morning's news.
Look solid results from #KGH, eps and profit ahead a bit, turnover less a bit but against good growth numbers. PE looks very cheap vs where its sat historically
Yes, not going to shoot the lights out but a market cap of 125M against PBT of 25M looks plain wrong to me!
Knights group (LON:KGH)
Not if you dig deep into the results and include capital expenditure etc etc etc.
All the best
Agree. Knights group (LON:KGH) some smoke and mirrors results so I am out after a fair run.
Maybe it's naïve of me, but I didn't realise that booking billed/unbilled fees/invoices to the accounts as revenue and profits was allowed until the bills had actually been paid. What if some companies don't pay or go bust? smacks of creative accounting. Anyway net gearing >50% way too high for my liking
Simon, you are being unnecessarily alarmed by the billing receivables. It is absolutely normal for companies that sell on credit (ie most companies) to record a sale when the work is done or product delivered and to then record a “Trade Receivable”. As you point out not everyone pays up but most do, and based on experience the company will take a reserve against bad debts.
In the case of Knights, as a law firm, they have an additional more complicated (and larger!) piece called Contract Receivables. This contains work that is being done where the billing does not necessarily follow the work cycle. So this might include work being done on a monthly retainer basis, or even on a contingent basis where the amount and timing of any cash received is not certain. Where cash is received but no work has yet been done a liability - “Contract Payables” - is recorded.
For all companies the recognition of revenue is an increasingly complex area but , if you can bear it, the notes in the accounts will explain what is happening ( and probably put you a jump ahead of many analysts!)
Thanks Aislabie. Maybe I am a bit over cautious at times, but I always recall a few of us at a previous employer had been approached by another company (Quindell) with job offers and they were doing something similar and buying up companies. I didn’t like what I read online and in the accounts, plus odd as it may sound, the salaries were too generous as well. Sadly it didn’t end well and those who jumped ship got made redundant 18 months later when things went belly-up
Although 10.4mm of the 25.3mm PBT is interest income on client balances. That will reduce when rates are cut.
Great analysis on this Paul, thanks. Like many others I was drawn by the apparent cheapness especially in comparison to Keystone, but your earlier comments had me checking the cash flow and I exited at a reasonable profit intending to buy back in if they became a lot cheaper. Right now I’m more dubious so holding off for the time being.
Anyone else puzzled by the market reaction to the Creightons (LON:CRL) writedown of Emma Hardy? It was known that buying Emma Hardy was a mistake. After all they sacked the CEO because of it. So why the mark down, when we have confirmation that the recovery is in progress?
It's a hefty write-off. I am never sure how to treat these things - it's a non-cash and one-off impairment so my view is it can probably be adjusted out although it does also point to lack of performance from the Emma Hardie brand. I'd welcome different views. Although note that Creightons (LON:CRL) does not tend to use adjusted figures which might make the results look pretty bad.
Presumably the last of the "kitchen sinking" before publishing the finals.
One of those companies that don't make much effort at investor communication. I hold
Britvic (LON:BVIC) - another quality UK company gets taken out by an overseas buyer. I hold and its a fair price. There won't be much of a UK stock market left if this carries on much further!
Its been "Tango'ed"
Thanks for another great podcast Paul, it has become part of my weekend now. I wonder if the people in the gym think I'm I'm listening to workout motivation music :p
Thanks Nanotrader09 for the nice feedback on my podcast.
Apologies for there being too much politics in the latest one, I am a total hypocrite after asking people not to talk politics here!
Also my friend Jon points out that I'm a hypocrite for talking about my portfolio (top 2024 share ideas) performance every week, having previously criticised everyone on X for doing the very same thing LOL!
Jon is the same chap who moved to Malta for lower tax, and I berated him about that being unpatriotic apparently. He politely replied that he'd got the idea in the first place from one of my podcasts!! :-D So we met up for lunch next time I was in Malta, and had a good laugh about it over some sushi and beer!
Thanks for the podcast Paul. You could hardly not mention the election. I thought you got it right. One point I'd make about the NHS is that the sales pitch to introduce it was that the average health of the nation would improve so that running costs would reduce over time. How wrong could they be, only Labour can sort it now as they apparently own it and no one else can interfere.
Marston's (LON:MARS)
Disposal of brewing joint venture for cash to pay down debt. Hard to judge how good a deal this is certainly at present the £200 mill to pay down debt is perhaps necessary boost in generally higher interest rate environment. No more future divis from this venture though do clearly selling of some of the jewels that are left. Debt will still be £950 mill ish so while £200 mill is great boost it’s not as if they still don’t have large debt pile. I probably expect temporary boost in shareprice today - how long this will last will I know not - it’s obviously good now but they no longer have the 50% share in the what should be cash cow beer business. Perhaps long term not being tired to any beer brands might actually be good news perhaps ?
I saw this, further to my comments last week Marston's (LON:MARS) . It's a good trade, bad for business.
My morning smallcap tweet: L'Oreal: I'm Worth it. Creightons: Emma Hardly worth it.
Creightons (LON:CRL) Marston's (LON:MARS) Aptamer (LON:APTA) Biome Technologies (LON:BIOM) Seeing Machines (LON:SEE) Macfarlane (LON:MACF), Zinc Media (LON:ZIN), Quartix Technologies (LON:QTX), Pulsar (LON:PULS)
◄Creightons (CRL)► writes down the Emma Hardie brand it overpaid for by £4.45m to only £0.66m. FY-Mar results will show improved underlying profit and cash generation in H2 in comparison to H1. [SP=20 Cap=14m]
◄Marston's (MARS)► sells remaining non-core brewing assets for £206m. That's 14.5x EBITDA. [SP=30.7 Cap=195m]
◄Aptamer (APTA)► guides FY-June rev £0.85m. £0.98m in orders were won in Q4. The pipeline of advanced sales negotiations is £2.1m. Bullish. [SP=0.69 Cap=3m]
◄Biome Technologies (BIOM)► warns FY-Dec24 rev materially below market expectations with profit partially offset by higher margins and lower overheads. Expects small -ve U/L EBITDA. Blames various technical validations are finalised by come customers. Some signs of weak coffee packaging market in North America. Co examining ways to ensure that the Group has sufficient working capital ahead of anticipated customer ramp-ups in North America. [SP=69.88 Cap=3m]
◄Seeing Machines (SEE)► buys Asaphus Vision, a highly specialised development group with leading Machine Learning and AI capability, for $6m. [SP=4.68 Cap=194m]
◄Macfarlane (MACF)► buys protective packaging manufacturer, Polyformes, for £11.5m, including an earn-out of up to £4.8m. It is earnings accretive. [SP=117.5 Cap=188m]
In line: ZIN, QTX, PULS
◄Notes► SP & cap are 20m delayed
Croma security
Received 1.76 million of its deferred payment for selling off its security division .
Assuming all this continues to get paid Croma is the wrong price .
The market seems to have applied a big risk factor to non payment but the cheques keep coming so that risk factor may be over stated .
A nice little company and possibly a bit of uplift with increased building etc .
Big spread if you catch it wrong and not easy to buy and microcap .
Management possibly a bit too well paid .
Can you remind us how much they're due and what that will mean for the cash balance vs market cap?
Whenever I look at Croma Security Solutions (LON:CSSG) it looks pretty low growth and low margin. It's already trading at a high p/e according to Stockopedia so it looks to me like quite a lot is factored in already.
Regarding Croma Security Solutions (LON:CSSG) :
- Current market cap c. £10m
- Current net cash c. £4m (including today's payment)
- Future receivables iro Vigilent c. £3.3m (receivable over next two years)
- Market cap net of 'cash' c. £2.7m
- 2023/24 revenue forecast c. £8.8m
- 2023/24 PTP forecast c. £0.6m
Assuming the £3.3m is paid as scheduled (and today's payment was probably the riskiest), the maths looks pretty compelling to me.
Thanks, very helpful Effortless Cool. So it feels like a judgement on their ability to use their cash well. Most recent operating margin looks a bit better than I thought. Cheers.