Small Cap Value Report (Part 2 - 24 Jan 2017) - XLM, LAKE, MUR, KLBT, AVO, PRSM

Good evening!
Many thanks to Graham for publishing excellent reports today & yesterday. I took a long weekend break to visit friends & extended family in Warsaw. Unfortunately my flight back yesterday was cancelled, so we had an extra day there. No hardship though, I love visiting Warsaw at any time of year - it's a really up & coming city. Also they extend Christmas until the end of January, so all the decorations are still up, and there's skating & mulled wine in the (rebuilt) old town square. Better still, it only cost £173 per person, for BA flights & a 5-star hotel. Service is a little morose, but that's just their way.
I've just got time to briefly report on a few more small caps that Graham didn't get time to cover today.
XLMedia (LON:XLM)
Share price: 110.5p (down 1.8% today)
No. shares: 200.4m
Market cap: £221.4m
Trading update - for the financial year ended 31 Dec 2016.
The key bit says;
XLMedia continued its strong performance in 2016, with revenues up 15% to $103 million (2015: $89.2 million) and adjusted EBITDA1 up 21% to at least $34.5 million (2015: $28.4 million).
The company doesn't say whether this is above, in line, or below expectations, which is a little unhelpful. From the upbeat tone of the commentary though, it sounds as if the company is pleased with its performance.
Outlook - Directorspeak sounds positive;
The Board believes that the Group is well positioned for further growth and the current financial year has started positively. The Board looks forward to continuing to execute on its strategic plan and looks to the future with confidence.
The Company expects to announce full year results for the year ended 31 December 2016 in March.
Ory Weihs, Chief Executive Officer, commented: "During 2016 we made significant progress having now established ourselves as a dominant player in the performance marketing arena. We continue to execute our strategic plan whilst implementing our know-how, expertise and technology in new business verticals and key end markets. We are very proud to have delivered another record year of performance in 2016 and look forward to reporting our full year results in March."
My opinion - this is a tricky one, as based on the figures alone, everything looks fantastic.
The Stockopedia computers love it, with a StockRank of 97, and the usual graphics below point to a cheap, high quality company;
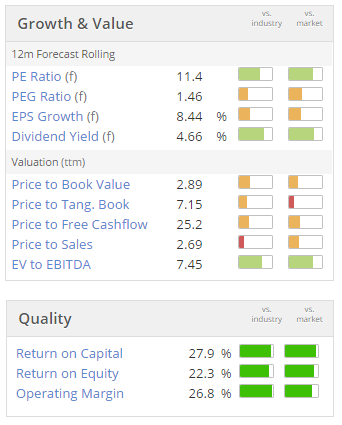
The balance sheet also looks good, and it pays lovely divis.
However, I'm still not comfortable about specifically how these bumper profits are actually generated. I'd need to better understand the business model by looking at the company's highly profitable marketing websites, and understanding how they work.
We've seen before how online gambling can spring nasty, potentially devastating regulatory surprises on investors. There's no doubt that XLM is a golden goose. The question is, how long will it last? Also how precisely, does it work?
Lakehouse (LON:LAKE)
Share price: 37.9p (up 11.4% today)
No. shares: 157.5m
Market cap: £59.7m
Results for year ended 30 Sep 2016 - I won't revisit the troubled history of this group, but for anyone interested, here is a link to my previous articles covering profit warnings, and a battle for control of the company.
It's really now just a question of whether things are turning around under new management, led by Bob Holt?
A few key points;
- Underlying EPS of 5.2p sounds alright, but the exceptional & other adjusting items are so large, that I'm not minded to rely on this EPS number.
- Kitchen-sinking, with £42.6m of exceptional & other items.
- Ropey balance sheet, with negative net tangible assets, and net debt of £20.6m.
- Surprisingly, it's paying a 0.5p divi, making 1.5p divis for the full year. Is this wise, given the weak financial position? I think not.
My opinion - I'm not fully up to speed on this company, and having had a bad experience with it in the past, catching the falling knife, it's not something that interests me to revisit.
This sector is so problematic, and so prone to things going (often badly) wrong, that I can't see any reason to want to get involved at all. That said, there might be a good turnaround here, possibly? The CFO impressed me at a meeting some time ago. He sounded genuine, when he said that there are some really good businesses within this group.
It's not for me, but readers who understand the sector might want to take a closer look, and maybe report back if you like it!
Murgitroyd (LON:MUR)
Share price: 407p (down 19.7% today)
No. shares: 9.0m
Market cap: £36.6m
Trading update (profit warning) - this group has a 31 May year end, and today warns that a variety of factors mean that H1 has under-performed;
The Board, cognisant of current macro-economic uncertainty, has also concluded that the implied improvement in operating performance during the remainder of the financial year necessary to meet current market forecasts is unlikely to be delivered and, as a result, that the outcome for the full year will fall short of market forecasts, and likely see reduced full-year 2017 earnings.
This is typical of the type of RNS which I dislike. It drops a bombshell, but doesn't quantify anything. So investors are left in the dark about how serious this profit warning is.
What the company should have said, is something like this:
We believe market expectations are for x pence EPS for year ending 31 May 2017. Due to the factors mentioned above, current indications are that our performance is likely to be 15-20% below this. We will update the market further if this situation subsequently changes.
I'm sure most readers would agree that my suggested replacement wording is far better than the original version.
Due to the lack of clarity in the company's announcement, we now have to rummage around to find broker forecast updates. Personally, I can't be bothered, so the company has lost a potential (small) buyer of its shares, due to putting out a poor RNS.
My opinion - this looks a mature business, that makes a decent profit margin, and pays nice divis. Also its balance sheet seems sound.
Therefore, if you like the business, I think today might offer a decent entry point perhaps? It strikes me as the type of business that is likely to recover from short term problems, if that's what these are. Overall then, I'd say it might be worth a closer look. Although I don't really properly understand what it does.
A couple of quick comments to round off with;
Kalibrate Technologies (LON:KLBT)
Trading update (profit warning) - it has a 30 June year end, and puts out a pretty nasty profit warning today, although kudos for giving us some actual numbers to work on;
As a result, the Group now expects its revenue and EBITDA for the current financial year to be materially lower than market expectations with first half revenues of approximately $14.0m (H1 2016: $15.9m) and EBITDA of approximately £0.1m (H1 2016: $1.4m).
Going into the second half contracted year to date revenue is $26 million (which includes the revenue of $14.0m recognised in H1) and the Group enters the second half of the financial year with a strong pipeline.
However the range of outcomes for the full year will depend on the closing of further business the timing of which is difficult to predict. The Board has therefore taken prudent action to reduce the Group's cost base in order to protect profitability and cash flow.
The balance sheet remains robust, with a net cash balance standing at $3.1m at 31 December 2016, up $0.7m from 30 June 2016.
My opinion - I see too many red flags in the accounts. In particular debtors is way too high, and the cashflow statement seems to involve capitalising a lot of costs into intangible assets. Both classic signs of things to avoid. It doesn't pay any divis.
So lots of reasons to avoid this share. Why get involved in low quality stuff, when you don't have to? There are plenty of decent companies out there to invest in. Please do correct me, if I've missed something, but on a brief review of the figures & commentary, I really cannot see any reason to invest here.
Advanced Oncotherapy (LON:AVO) - apologies, formatting problems.
this share is a great example of why I don't touch blue sky crap on AIM any more. They nearly always fail. Back in 2015 this share looked potentially interesting, because it seemed to have a Chinese customer lined up to fund some serious-sounding kit for curing certain types of cancer.
Anyway, in an announcement today, the wheels are clearly coming off, with the Chinese customer cancelling its orders.
If anyone is daft enough to still hold this share, you need your head examining. IF the facts change for the better, then fine, it would be worth revisiting. However, for now, it looks a mess.
In this type of situation before, I've found that it pays to be early to break the spell that a story stock has on you. Most, or at least many punters may continue to delude themselves that everything is fine. This provides a vital gap for the more shrewd to exit stage left, with at least some of your capital preserved.
Also, I suspect short sellers may converge on this stock, as it ticks a lot of the boxes they look for. You have been warned! Personally I'm not going to get involved. Stuff like this just wastes mental energy that can be better deployed elsewhere.
Blue Prism (LON:PRSM) - I cannot resist a brief comment on full year results to 31 Oct 2016 from this sexy growth stock.
Looking at the numbers alone, I am struggling to justify a valuation of more than about, well nothing. It's loss-making, and the losses are increasing rapidly. So if the cash is going to be spent, then it's surely worth nothing?
Amazingly though, this share has achieved a valuation of about £300m, at c.500p right now, despite reporting only £9.6m revenue for y/e 31 Oct 2016, and an operating loss that has gone up from £753k to £5.3m. Am I going mad?! This really does remind me of Medisys, right at the peak of the TMT boom in 2000, when I thought its retractable syringe was the best thing since sliced bread.
Some of my best investing friends really like Blue Prism, so they will be cursing me as they read this. However, I want to throw a massive, air-dropped multi-ton, forest-fire-quenching tsunami of cold water onto this share idea - to challenge the bull case, and make sure it makes sense. So comments in the comments please.
At this 500p valuation, it looks an accident waiting to happen. Smart IT people can do all sorts, why is this unique? Why is it worth £300m+, when it hasn't even got anywhere near to making a profit? To my mind, stories are often a lazy excuse for doing proper number-crunching! They often start with glamour, and sparkle. But end up scraping turds off your cheap trainers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
XLM does have a fair bunch of competitors and you can even find them on Stockopedia
Long term holder of XLM. enjoyed serious capital growth and dividends. In this technical age, it is hard for the layman to understand how companies make their profits. Therefore I welcome the comment, both for and agin. However, XLM seem to have the knack of producing exceptional results, after exceptional results, and like cg78riverside,I do expect this to be a 10 bagger.
Re PRSM, a holder at the moment from 320.
Re information on it, here are two pieces, one a detailed piece of research done by the LSE on RPA with PRSM at Telefonica 02
https://www.mwdadvisors.com/2016/11/24/on-the-radar-blue-prism/
http://eprints.lse.ac.uk/64516/
Amazed at the lack of knowledge on here about what the company does. Please have a read through the latest company presentation before passing comment. http://www.xlmedia.com/wp-content/uploads/2017/01/investor-presentation_JAN17.pdf
XLM I'm invested here but with a snap stop loss. I understand how they make their money, I just don't like companies who base themselves to avoid tax and then keep moving.
Lake, well barge poled. They need to show more turn-around and imporved strategic thinking before I go in.
Blue Prism (LON:PRSM)
For interest, when I have repetitive tasks at work or where the package I’m using doesn’t have the inbuilt feature I require, I’ve been using AUTOHOTKEY (its free off the internet). It takes about an hour (longer if you’re new) to set up and completely automates repetitive tasks across any software platform thats running on your PC. I’ve successfully used it to automate tens of thousands of mouse clicks and any other keyboard commands at the single click of a button. I’m sure it’s not as robust, powerful, easy or self-documenting as Blue bollocks offering but it’s free and simple to use.
I recommend it although it won’t ‘Drive meaningful BI and MI reporting’.....
Re: Blue Prism (LON:PRSM)
If we assume 50% revenue growth then the current price is 6 times sales in 2020, so they need to be going much faster than 50% to justify current market cap. Even a 30% year would see the share price crater.
Re XLM, while the valuation does look cheap by almost every metric, but the "beta" of the share is high, and the share price can be very volatile, which in turn justifies a lower valuation. A case in point was in the first week of December, when the share price suddenly and instantaneously dropped from 98p to 85p. The cause was an announcement that the FD had sold is shares to raise c£100k (I seem to remember the "Personal reasons" being mentioned, as per). I was outraged at the very thought that the FD's sale had cost us shareholders more than £20m so that he could have £100k. It was a bit of a bungled announcement from memory, middle of a Friday afternoon. I post on Boards only rarely, but was actively raging on a rival board and even writing to company...even sarcastically making the points that it would have been much cheaper for us beleaguered shareholders to have a "whip round" for his £100k rather than take a £20m hit to our holdings.
There are two points to my post. The first is to highlight that potential volatility, and you would expect to pay a lower percentage of earnings because of it, especially given the fast moving Regulatory environment.
The second point is to highlight that after taking two weeks to calm down in time for Christmas, I then checked my different portfolios and came to the stunning realisation that I didn't actually own any XLM!!
Over the Christmas holiday I read a great book by Guy Thomas called "Free Capital" about how 12 Private Investors had made Millions by investing in the Stock Market. I am sure the book is familiar to many subscribers. All 12 were interviewed, and many offered some real insights and helpful advice. For me, the most pertinent advice of all was to "mix attack and defence"...and to spend as must time constantly reviewing your existing portfolio with "would I still buy this stock today if I didn't already own it" as much as the time spent evaluating new ideas to add shares in. Time spent on existing shares is more efficient as you (in theory!) know a fair bit about it, compared to the blank sheet of paper of evaluating completely new ideas.
Blue Prism (LON:PRSM) Their financial model initially attracted me to look at them, as many other investors simply do not understand the mechanics of an enterprise software business, so they can be mis-priced. You get paid cash up front for something that is "delivered" over a long period of time. You stick the cash in the bank, put the Deferred Income on the Balance Sheet and send some it to your P&L as Revenue each month. Hence, there's very little immediate profit from each new contract, but you're storing up a nice foreseeable revenue stream for the future.
This type of software is also very "sticky" if it meets expectation, so the future revenue could be quite stable. The future contracted revenue includes licence fees (which have ~zero cost of delivery) and support fees (which have some cost, but should be profitable). The trick is to be able to manage the other expenses to continue to grow the company and start to make a profit from those contracted revenues.
At the moment they are increasing spending massively on sales activities. This is mainly staff (salaries, commission, incentives etc). It seems to be generating growth and I liked the fact that they are paying out the sales people fully in year one - that leaves more potential profit in each contract for the future. If sales keep growing ahead of sales costs then they should become profitable pretty quickly. The test will come if sales growth starts to slow - how will management react then? The nightmare will be if they reach a point where sales have slowed and they're not yet profitable. Their only real expense is people, and it's a downward spiral once you start cutting. The shares would be worthless in that scenario.
I agree with Paul that the valuation is crazy, although I note that Salesforce.com is currently on a p/e of 260! A reasonable P/E would be 30-40, and that implies £12-15m profit in the not too distant future at current prices. I suspect that's quite a few years away yet, so would expect this share to stagnate or decline until more good news comes out.
I agree with your comments here and am a bit confused by the sceptics.
The key factors which stood out for me with Blue Prism are: its partner and client base, its business model and how deeply its RPA software integrates into clients' existing systems. Plus if anyone is wondering where the excitement is coming from with the tech, I note that the processes it can implement include the recognition of content on documents. In my mind, if you want to save money on staff then software that can take 'read' information from documents and input it into an existing system would certainly appeal.
That's not to say not investing is a bad decision. As others have said already, it is loss making and the PE is high. But then a similar situation existed with ARM for a long time too. I've invested but am keeping an eye on price movements.
Blue Prism (LON:PRSM) A couple of months back I took some time to look at Blue Prism in detail.
Basically their premise is that they can automate tedious back office repetitive tasks in the same way that industrial robots have taken over repetitive tasks in, for example the automative industry.
Well I have retired from a lifetime in the financial services industry and back office automation has been going on for well over 30 years. Premium renewals, bonus statements, direct debit collections, etc are totally automated and involve tens of thousand of transactions every day. The common or garden spreadsheet has revolutionised finance, accounting and actuarial departments by fully automating extremely boring data collection and basic analysis work.
So I struggled to see what else Blue Prism could be doing to squeeze out manual tasks and let in software robots. I went to their website and clicked on 'case studies'. There was only one entry and it didn't read anything like a proper case study.
So far, to me this is hype. The lack of decent revenues is just proof of lot of hot air and little real substance.
You might want to also look at Automation Anywhere.
https://www.automationanywhere.com/customers
They are the major competitor and already have more than 500 large clients so are ahead of Blue Prism in this regard. It seems unlikely that so many reputable large companies would get caught out buying into a solution that is nothing more than "hype" but it is possible I suppose.
Yes, I agree with comments on Blue Prism. All they need on their website is some screen shots of their package or the user/programming interface so that we can get an idea of what it is they are flogging.
Any company that describes its software as a fleet of robots is just trying to mislead investors/customers. Robotic process automation is what you have in production lines, oil refineries or factory’s. If your were distributing an Access database query around your workforce you wouldn’t describe it a digital workforce or software robot.
Their website reads like an explosion at a IT Thesaurus printers;
‘addressing potential significant seasonal variations in operational demand’
‘on-premise enterprise deployment’
‘Process excellence engineers’
'identifies both inline process statistics and real-time operational analytics'
‘Drive meaningful BI and MI reporting’ anyone?
I agree with your sentiment regarding the hype on their website. However, the vast majority of sales come through channel partners which include many impressive names so perhaps their website is not so important from a customer acquisition point of view.
My understanding is that the software simply automates repetitive computer based tasks that typically involve transferring information from one system to another. The best solution would obviously be to upgrade software to take away these manual elements but due to the complexity and customisation inherent in IT systems in large organisations, this is often not an effective use IT resources. There are lots of people currently employed doing this type of work either as direct employees or through outsourcing and so there are large cost savings to be realised if you can replace each one with a software license. Blue Prism's very well known and rapidly growing list of clients is testimony to this.
I agree that there doesn't seem to be much that is that groundbreaking about the technology but its simplicity may in fact be its strength. The solution is quick and cheap to implement and it doesn't require IT specialists to maintain and operate it. It is therefore highly scalable and whilst there is a risk that over time all software will be able to integrate seamlessly together (another reason that I sold out), this will take a long time in the case of specialist enterprise software solutions which are often one of a kind.
I work for one of the afore mentioned channel partners and based on personal experience I would not invest in Blue Prism (LON:PRSM) .
The software is clever enough but to my mind it's software looking for a use case not A use case looking for software.
Any time someone brings me a use case for RPA I work out that I could achieve the same result for a fracton of the cost with a SOAP or RESTful API integration between the two systems in question.
In other words its integration software for people who don't know better. It's the technical equivalent of getting a robot to write and post a letter for you when actually the right answer is to send an email instead.
It may well be the next big hyped thing in the short term and people could make money trading the share but I can't see it being the next big long term thing that makes it worth investing in.
It's absolutely not Salesforce, invest in £NOW instead I would say.
Yes as I said before direct integration is a better solution but this often isn't as cost effective as you say. I do agree there are question marks about the longevity of this technology which is why I sold when the price started to factor in too much of the future. There are potentially interesting applications for using RPA as a platform for AI.
http://info.genfour.net/blog/robotic-process-automation-is-more-than-an-application-interface-tool
"However many companies, especially within financial services, have legacy systems (mainframe/green screen or custom built) in which these interfaces don’t exist. Building APIs into existing software can be costly, time consuming and can require a high level of expertise around the underlying system."
Potentially interesting but in reality too few and far between in reality to justify the current SP. feels more like a short than something I would go long on.
Even in a legacy situation a modern IT department is just using something like this as a stop gap while they pursue a legacy modernisation strategy. Its short termism encapsulated in software.
C
Yes it probably is a stop gap. It works well as such because of ease and speed of deployment and it sits over the top rather than being deeply embedded so can be easily removed when it is no longer needed.
However, it is very flexible and I am not convinced that all the potential uses for RPA will get solved with better solutions any time soon, if ever. Ultimately I simply see it as a tool that is available to an organisation looking for a quick fix and there is always a demand for these.
I agree that it is a mistake to think this is deeply embedded mission critical software say like Craneware makes. In contrast, RPA is easy to switch on and off and so revenues are probably not so sticky.
I also worry that the big tech companies will shortly launch enterprise level AI products that incorporate RPA into a more complete offering.
The other think to consider is that even though there might be relatively few of these legacy systems, they are concentrated in the largest organisations. These organisations currently employ a lot of people to operate them. My impression is Blue Prism is charged on a per seat basis so the number of legacy systems is not important in terms of the size of the market opportunity, rather the number of people required for them to function.
Also it shouldn't be underestimated how hard it is to upgrade these systems so a "stop gap" can be many years. For example where I live in Australia, there are government organisations that rely on software built decades ago and such systems are at the core of what they do. The fact they haven't yet got round to modernising these tells you something about how hard this is to do. RPA would be an attractive option in these settings and why wouldn't it last for a similar duration?
Regarding XL Media, I also owned XLMedia until this TU.
This RNS although factually correct is very, very misleading.
Revenues increased by 39% in H1 2016 & fell 2% H2 2016, there was absolutely no mention of this in the RNS, just a positive spin on 15% annual growth.
A company whose revenue growth goes from 39% to -2% in 6 months & does not mention it in its RNS is scary !!
Also FO sold a not insubstantial amount of shares late last year.
One thing I do not understand is why the share price has remained relatively resilient to this news, has no one else noticed this slight of hand ?
XLM
Steve Hill, not true regarding revenue.
they updated the forecasts in September and upped EPS number. Explanation was trimming activities in the partner network that account for 1-2% of EPS as a whole as well as change to a small sector they are active in (utilities), but please remember they upped EPS alongside that!
Maybe others were paying attention 4 months ago and you were not?
XLM in response to Tom stone I didn't mention EPS.
H2 2015 Revenue $52.4M
H2 2016 Revenue $51.8M
Coming from a revenue rise of 39% in H1 I was very surprised the slow down was not mentioned in the RNS.
It was mentioned in SEP, read the analyst reports,they mentioned specifically that the partner network revenue that was cut was an intentional move by them cutting very low margins REV that does not effect the operation to focus on the serious money makers.
Regarding the utilities sector, it was a small one, again with lower margins. The CORE high margin business is growing which I'm sure will be emphasized in March.
Having said that, Mr. Scott's comments are quite outrageous, claiming a company is breaking the law because he doesn't understand their model (he never spoke to them) or finds it out to believe is quite slanderous.
Re XLMedia
The September RNS did not lead me to believe that revenue growth was going to fall from 39% to -2% or that EBITDA growth was going to fall from 37% to 9.8%.
Having said that I'm sure we all have our own investing rules & that huge fall in revenue & profit growth, together with the fact that it was not even mentioned in Tuesdays TU & the CFO's share sale was enough for me to decide to sell, however they are still massively profitable & on a low PE so I can see how others could come to an alternative decision.
I used to hold PRSM but sold under 400p when I thought the price had gotten crazy so I half agree with you. What you are missing is that they get paid upfront and so although losses are growing, they are break even at the cash flow level. As you will be aware, launching a new technology in the software industry is all about grabbing market share. Yes, eventually the competition will catch up but changing suppliers is a hassle (even for an over the top solution like Blue Prism). Therefore, costs are front loaded but each new customer will (hopefully) generate high margin revenue for multiple years.
The other key number to look at here is future contracted revenue which soared from 11.5m to 35.2m. Note that this represents a floor, as many customers are likely to increase number of seats as they get comfortable with the software (as has been the case to date). To understand why, it is worth looking at a few of the case studies on their website. Essentially, unlike an excel spreadsheet, the software is robust, secure, compliant and highly flexible and therefore has a wide range of applications withing a single organisation.
PRSM
I looked hard(ish) to find out what their software approach is and why this might be some sort of a "moat". It's almost as if they are deliberately not saying what they do.
In principle I can see no reason why a decent spreadsheet cannot produce this functionality (although with a crap interface). So, I assume they produce some sort of rule-based program with a decent interface. I.e. nothing special.
If this assumption is correct then I can see nothing that would justify purchasing this company for any reason - I would not reach the stage of attempting a valuation.
Like you, people I respect are keen on the company - it is comforting to see a similar view to mine aired. I was beginning to wonder what I had missed, but can't be bothered to return to the issue.
apad
I think XLMedia (LON:XLM) has run out of steam and I sold a couple of days ago, but their business model seemed reasonable to me. They run a lot of 'independent' websites which appeal to poker players etc. and XLM gets a lifetime percentage of all bets placed at very decent rates (c. 50% even) from click-throughs that lead to account openings on other companies' gambling sites. They can be picking up streams of income for years at relativey low cost. It could all be a big fat lie, I've no idea so it's definitely a gamble. Their divis are usualy late being paid which was annoying and they never replied to my email either, again not reassuring. But as BT reminded us today... (I won't complete that sentence due to risk of libel proceedings).
"and XLM gets a lifetime percentage of all bets placed at very decent rates (c. 50% even) "
Shine - where did you get that from? Surely you mean "losses" not "bets placed".
I've been following XL Media since it listed but have never invested. I have emailed investor relations repeatedly asking what websites they own or if they could link me to an example of a website that generates revenue. Every single email I have sent to investor relations has been ignored. I find this quite concerning. Would you invest in N Brown if the brands they owned were a closely guarded secret?
The numbers look great and the dividends are attractive however. Investing here is really just gambling that the magic black box at XL Media will keep spitting out money somehow. I just can't get past the fear that maybe one day someone opens the black box and finds a Blinkx hiding inside.
Re XLM - Affiliate marketing businesses do tend to be secretive as I believe once you know what sort of sites are receiving significant revenue it is very easy to copy them and compete away the profit. Hence why I have no interest in investing in such a business. They have zero competitive advantage in their products alone. However if they have sufficiently talented individuals who are constantly seeking out new niches you could describe their workforce as generating a moat.
Connor, my tip to you is contact the CEO directly, I have been speaking to him as well to IR@ many times.
AVO - I agree more risk than one would like and there are more fish in the sea - so better away. That said according to their RNS's every stage in production testing has been met and all testing has worked. The science is from CERN so should have merit. The machine is being made in partnership with Thales a world class Company who I doubt would be there unless it was serious. They have planning permission from Westminster Council and have started site work to install first machine in Harley St whereas all the current machines need the size of 2 football pitches and have to be buried underground and cost at least 10 times more. Given that, together with the NHS are currently having to send their patients to USA at a cost of £20k each - if it works I'm sure it will sell and well. I doubt that the loss of that order is a dealbreaker if it works.