Small Cap Value Report (SCVR) - 14 Jul 2014 - CVR, PLA, TUNG, CSG, TMMG, HNT

Good morning!
Conviviality Retail (LON:CVR)
Preliminary results for the year ended 27 Apr 2014 have been issued this morning. In my opinion the shares look moderately interesting. It's not a great business, being budget off licences, but I do like their franchise model, since stock loss is always going to be a huge issue in this sector - therefore making the operators of the shops responsible for their own P&L is probably the best option. That removes all the headaches, and just means that CVR can sit at the centre, making a small but safe profit margin supplying the product.
The figures below are based on the current share price of 164p and 66.7m shares in issue = market cap £109.4m
Positives
- Very good dividend yield of 4.9% (8p for the year)
- 12.5p adj EPS came in ahead of expectations of 11.3p, for a reasonable PER of 13.1
- Sound balance sheet with £ 10m net cash
- Shrewd shareholders (HH, Henderson, Miton together own 32%)
- Debt now cleared, so finance charge should largely disappear in future
.
Negatives
- Probably limited growth opportunities?
- Low operating margin
- Competition - especially from supermarkets
- Possible threat from Govt - minimum price per unit?
- Wide bid/offer spread - 7p, or 4.3% quoted spread
- Rick of franchisees sourcing their own illicit supplies?
.
So overall I think it looks potentially interesting to buy for the divis perhaps? Although there are large caps available which pay 5% divis, so it might make more sense to go for them if it's income you're after?
Plastics Capital (LON:PLA)
This is a small group of niche plastics businesses. I like the business, but think management are stretching credibility somewhat by over-using the word "major" in today's announcement, e.g. "Major bearings projects update" is the heading, followed by "major design project", and "major commitment from a tier one automotive manufacturer", "this major project win..", "conversion of these major projects...".
Come off it chaps, the contract announced today is only £0.5m p.a.! Sorry, but that's not major at all, in the context of a group with forecast turnover of £36.1m this year. So perhaps the RNS writer should have a bucket of cold water thrown over them before they sit down to write these things!
Still, the company does talk of other similar sized projects in the pipeline, so that opens up the possibility that the company might beat forecasts. I saw one broker note which had much higher growth assumptions in it than are generally accepted. So this could possibly be an opportunity where a share that looks reasonably good value on forecasts turns out to be cheap because the forecasts were too low? We'll just have to wait and see.
As I reported here on 30 Jun 2014, the accounting adjustments look a bit too aggressive to me, so I'm rather sceptical about the reported EPS figures. Certainly I'd want to see a more clean number before investing. So for the time being it looks priced about right to me. Also perhaps less hyperbole, and more sober reporting of facts over the RNS might be a good idea.
Tungsten (LON:TUNG) & Mello Beckenham
This is a rapid growth company, supplying accounting systems online, particularly an e-invoicing system. I read some stuff about this company a while ago, and it has some major existing clients, so the bull case is that the suppliers of those major clients will have to use the Tungsten system, and that will then snowball further sales, and the hope is that it becomes the de facto standard electronic invoicing system.
That all sounds great, but the market cap is already factoring in a lot of upside in performance, as is often the case for growth stocks in a bull market. That's fine as long as nothing goes wrong, but it makes the shares very high risk, as this type of share can go spectacularly wrong (and most do at some point) when growth turns out to be less than expected. Occasionally things go the other way, and growth out-performs even optimistic assumptions, and you have a multi-bagger on your hands.
The other interesting angle with Tungsten is that they are trying to integrate invoice discounting into their system, which is a brilliant idea. However that will need funding, and today's announcement just says that the company is exploring funding options to roll out the invoice discounting offering.
I'm tempted to have a punt, in the more speculative part of my portfolio, but the market cap is £268m. The forecast figures to support that valuation require an 8-fold increase in turnover. It's a tricky one this. They do seem to have a remarkable opportunity, given the high calibre of the clients (e.g. GE, Caterpillar). Over time it will effectively turn into a bank, with its integrated invoice discounting offering - which makes such obvious sense, that providing they can get the funding, it could become something very big.
You can make up your own mind by seeing the company tonight, at the monthly Mello Beckenham investor evening. Booking details are here.
Sweett (LON:CSG)
There's an update this morning on the Wall Street Journal bribery allegations concerning a former employee of Sweett Group. It's got worse, with the Serious Fraud Office now investigating the matter, which sounds ominous to me.
Today's statement says that the former employee worked for its subsidiary company in Cyprus, with the possible implication that any penalties or other liabilities might be ring-fenced within that subsidiary? I don't know how it works with criminal allegations, can they lift the corporate veil and come after the group as a whole, or do the liabilities remain at subsidiary company level? If we have any corporate lawyers who read this, perhaps they could enlighten us on this issue in the comments section below.
I have a general rule that I don't hold shares in companies which have significant legal problems underway, on the basis that they can often turn out of be worse, last longer, and cost a lot more than management suggest. Therefore I maintain my bargepole rating on this stock.
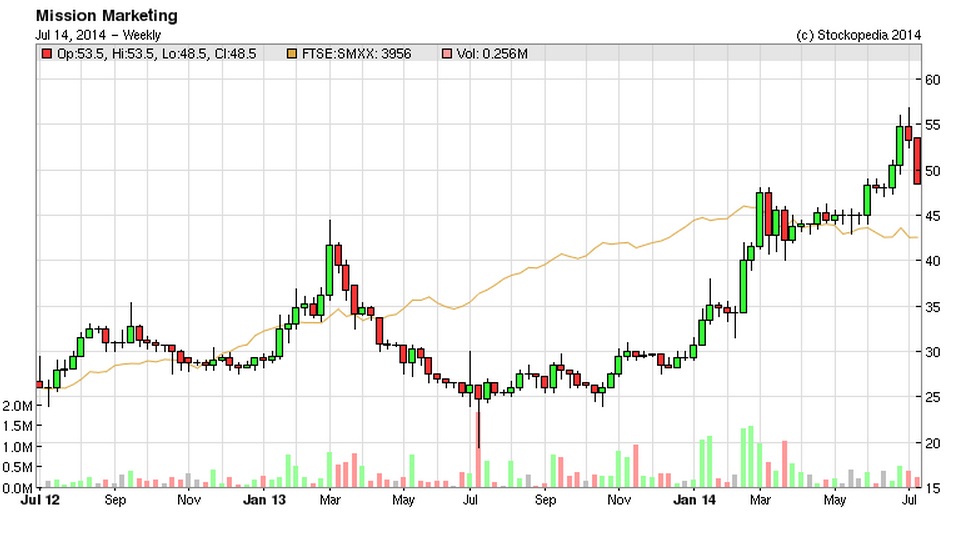
Mission Marketing (LON:TMMG)
Mr Market doesn't seem to have liked this group's trading update today. The shares dropped 9% to 48.5p.
Edmund Shing wrote an interesting article about it on Stockopedia recently.
I'm at a loss to work out why the shares fell. There's nothing I can see wrong with this update. It confirms that H1 performance is in line with expectations;
Trading for the first half of 2014 has been in line with management's expectations, with revenue and profit both expected to be ahead of the equivalent period last year.
The comments on debt & cashflow sound positive;
The group's net debt fell from £10.7m at 31 December 2013 to less than £8m as a result of strong cash flow which is typically experienced in the first half of the year, and the group's leverage ratio (ratio of net debt to EBITDA) continued its downward trend, falling below x1.25 at 30 June 2014, thereby triggering a further reduction in interest rates.
Perhaps the market didn't like the following comments about an H2 bias to trading, although this is stated as if it's the normal seasonal pattern;
Our results for the year to 31 December 2014 are again expected to have a bias towards the second half and the Board remains confident of further progress for the full year.
Overall that sounds fine to me. I suspect that the selling today was just some profit-taking, after all the shares have had a very good run since January, so perhaps a bit of a pullback is healthy?
Huntsworth (LON:HNT)
In a similar vein, this is a PR group that took a bath today - shares down 15% to 44p after a short and sour trading update that simply said;
The Board of Huntsworth plc, the public relations and healthcare communications Group, announces that first half results will be below market expectations. The Board is reviewing the second half year and, while there is work to do, we believe that the second half will show improvement over the first half year.
If I were a shareholder, I would find that totally unacceptable. The company has given no explanation whatsoever for why they have traded below expectations in H1. That's not good enough, so I certainly would not consider buying these shares until it has become clear why the group has under-performed.
It may or may not be connected with the separate announcement today that the COO & FD (one person, which is odd) is on sick leave, and is expected to return in the autumn (vague). It says that the AGM on 24 June disclosed that she was unwell.
There's something a bit peculiar about this company. I can't put my finger on it, perhaps it was the rather drawn out process last year whereby a Chinese party took a 20% stake in the group. The company has maintained a 3.5p dividend since 2010, so if that is continued (broker forecasts assume it will be), then at 44p per share you'd be locking in a whopping 8.0% yield! Although that's not well covered by earnings. Forecast is for 4.7p this year, so that's probably coming down to say 4p, which doesn't leave much headroom to maintain that 3.5p payout.
Personally I don't like chasing abnormally high dividend yields, as they usually end up being cut. It's more important to buy shares where the company has the capacity to pay big dividends, than companies which actually do pay big dividends but are stretching themselves to pay them.
This share is going onto the watch list as something that might be potentially interesting, once there is more clarity on performance.
That's it for today. I shall be very interested to hear back from Mello tonight about what people thought of Tungsten (LON:TUNG) - looks potentially interesting to me, so I bought a bit of stock today.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in TUNG, and no short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

21 comments
Tungsten's seems to be a funny kind of diagonal integration. If I was a user of an invoicing platform, I guess I'd rather see the platform become a broker where third-party invoice discounters compete for business (and charge transaction fees for that service) rather than them become a principal, with associated conflicts of interest.
http://boards.fool.co.uk/mello-monday-tung-13057765.aspx?sort=postdate
I worked in Tungsten 2 1/2 years ago and they were talking about rolling out invoice discounting then. Still hasn't happended
Tungsten only floated in October last year so not sure how you could have worked for them 2 1/2 years ago?
Webpax,
Just because they floated in October doesnt mean they didnt exist beforehand as a private (unlisted) company. Khaledfan cvoudl have worked from them from 2012 or indeed one of the companies they acquired such as OB10.
They were called OB10 in those days. Same management
Plastics Capital (LON:PLA). I think you are being very harsh on Plastics Capital (LON:PLA). I am invested in it and posted my meeting notes with management last week. For PLA this is a major announcement. The bearings division, its largest has been a bit of a drag recently because although it has been pitching for new business, frustratingly it has not been able to announce actual contract wins. These contracts are normally for the life of a new model, so 5-8 years and generate pretty good margins. It is also with a tier 1 manufacturer, I guess German, and I think bodes well for it securing more contracts in the coming months. I just would not be so dismissive of a well managed, cash generative, mainly UK based engineering company where the Chief Executive has a near 10% stake.
John,
Little bit puzzled by your comments. I'm not at all dismissive of Plastics Capital (LON:PLA), in fact I like the company & the management.
What I don't like is the tone of their RNSs (far too excitable/rampy) and their somewhat aggressive accounting. Apart from that, I think it's quite a nice business, and probably priced about right for the time being.
Also bear in mind that contract announcements tend to be a one-way street - i.e. as with many other companies, they tell the market about wins, but don't say anything about contracts coming to an end, for example. It all fits a pattern of share price pumping which I'm not keen on. They need to moderate that side of things and just let the numbers do the talking.
Regards, Paul.
Regards, Paul.
Hi Paul,
I think that John's comments were more an opportunity to publicise his own website - for which you need to pay £15 a month to get his pearls of wisdom. I don't think I'll bother.
Regards, Maddox
If I may respond in support of John Rosier, he surely is doing no more than many other commentators on this and other blogs, voicing his opinion about a certain company and, in this case, expressing a disagreement with something Paul wrote — which boils down to the interpretation of the word "major". It was hardly surprising, as a holder of shares in Plastics Capital (LON:PLA), that John was going to question Paul's relatively negative response to the contract win announcement. To see his comment as seeking publicity for his website is, I feel, a little cynical.
I am an avid follower of Paul's daily report, and feel that I benefit hugely from his observations and insight. I am delighted that these come free of charge. At the same time I also appreciate the research and thought that goes into John's investments, and I for one am very happy to shell out the price of one glass of wine a week to get the benefit thereof.
Hi Maddox,
I think that's a bit harsh! John's one of the good guys.
The website link comes up automatically I think, if you put it in your profile.
Regards, Paul.
Hi Paul, happy to be corrected - and apologise to John for my previous remark. Regards, Maddox
Hi Paul
Thanks for the write up re Tungsten (LON:TUNG)
What interested me was the CEO Edmund Truell is a seasoned operator and has a substantial personal stake in the business (circa 15%). Also NED Michael Spencer has a significant holding.
Thanks
Jon
Disclosure: Long Tungsten (LON:TUNG)
Neil Woodford has released a full list of holdings in his new Equity Income Fund:
www.telegraph.co.uk/finance/personalfinance/investing/funds/10965211/Neil-Woodfords-Equity-Income-fund-the-full-list-of-holdings.html
Bsharman
Got it..Stockopedia adding a .pdf link when I C&P yours. Annoying.
Cheers for the headsup
Hi Paul,
I'd appreciate your thoughts on the update from Sprue Aegis (LON:SPRP).
Record revenue again, strong demand in Germany, record order book for H2, new product launches in H2, but exchange rate headwinds and softening of demands for CO sensors in the UK.
Thanks Phil
(Long on £SPRP)
Morning Paul. Could you take a look at Huntsworth (LON:HNT) which could now be classified as a small cap....
Thanks.
Ironic isnt it, when a PR company puts out a Trading Update (Profit Warning) that is so lacking in any detail?
It doesn't give us much to go on does it! They are yielding almost 7% at these levels but i don't know how sustainable the dividend is, so may get cut? Perhaps there are better options out there such as Creston (LON:CRE) and Cello (LON:CLL) ?
Hi bsharman,
I've updated the article to include comments on Huntsworth (LON:HNT).
Regards, Paul.
Thanks Paul. They are on the watchlist, but agree that the dividend may get cut soon.
Cheers, Ben.