Small Cap Value Report (Thu 10 Sept 2020) - DNLM, SAGA, VCP, SDY, EPWN, ANP

Good morning, it's Paul here with the SCVR for Thursday.
Today's agenda;
Dunelm (LON:DNLM) - Results 52 weeks to 27 June 2020
Saga (LON:SAGA) (I hold) - Interims
Victoria (LON:VCP) - AGM Statement
Speedy Hire (LON:SDY) - Trading Update
Epwin (LON:EPWN) - Half year results
Estimated timings - I'm running a little late today, got distracted by something, sorry about that. I should be mostly done by 1pm, but might carry on adding sections after that.
Update at 14:21 - SAGA took much longer than expected, so I'm taking a lunch break now, and will resume later this afternoon to finish off the last 2 companies above, and hopefully look at Anpario (LON:ANP) from yesterday too. Thank you for your indulgence.
Update at 15:57 - I'm back, and working on an update to Saga, plus the rest on the list - should be done by 8pm.
Update at 21:02 - today's report is now finally finished!
Dunelm (LON:DNLM)
A quick mention of this homewares retailer, operating from large units in retail parks. Together with a strong online offering, retail parks are the best places to be operating from at the moment - the open spaces lend themselves well to social distancing, and plentiful free parking helps. People seem far more willing to visit these sites than town centres.
Results for the 52 weeks to 27 June 2020 are remarkably good, considering the stores were shut in most of Q4.
EPS is obviously down on LY, but not by much - it reports 42.9p EPS, vs. 49.9p LY. That's astonishingly good in the circumstances.
Online is key too these days, and Dunelm reports a big increase here too, with 27% of total sales online.
Current trading is strong, and management sound confident, but say there is too much uncertainty to be able to give guidance. The final divi is withheld, which seems overly cautious to me, given how well it has traded. Divis are set too resume at the interim stage.
My opinion - a fantastic company, but the shares are so expensive now, that I'm not interested in buying back in (this was one of the shares I bought about a week before the March low, as chronicled here at the time). Even allowing for a recovery to 50p EPS next year, the fwd PER is 28 times. If it out-performs against forecast by say 20%, to achieve 60p EPS next year, then the PER would still be nearly 24 times, which is just too much.
For a retail park homewares company, my pick (on valuation grounds, and strong current trading, and super-strong balance sheet) is Scs (LON:SCS) (I hold). I can buy that on a PER of about 10, so why would I want to buy DNLM on a PER of 28? OK, it's a better business than ScS, but not by that much! Plus ScS should pay much larger divis.
Interestingly, despite publishing remarkably good figures, Dunelm shares have gone down today by 3%, to 1420p, which tells me that the share price is up with, or ahead of, where it should be. Great business though, and it goes on the list of companies that have proven they can sail through a major crisis unscathed.
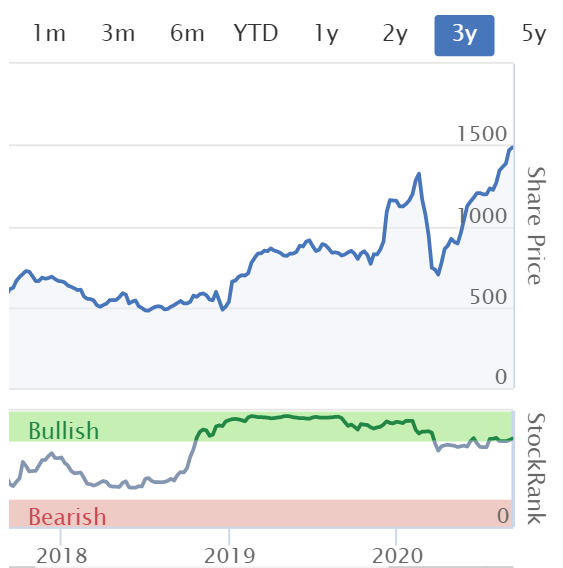
As you can see, it's had a big re-rating in the last 3 years, which again makes me feel that the price is up with or ahead of reality now.
.
.
Saga (LON:SAGA)
Share price: 15.4p (down 4%, at 11:15)
No. shares: 1,122.0m
Market cap: £172.8m
(I hold)
This well-known brand for the over-50s (that includes me, arrrgghh!! I'm still 25 in my head!) sells motor/home insurance, and has a travel division (tours, and cruise ships).
This £150m equity fundraising announced formally today, was pre-announced on 1 Sept, which I covered here. To summarise that announcement, the former CEO, Sir Roger De Haan is investing £100m as the bulk of a fresh equity raise totalling £150m. Amazingly, he has put in just over £60m of that £100m fresh equity at a premium share price of 27p - highly significant in my view, as a strong indication of his confidence in the company. Sir Roger is returning as the Non-Exec chairman, to oversee the turnaround. This has given me the confidence to buy some shares in the open market after digesting the previous announcement.
Another factor I very much like, is that Saga said it turned away a possible bid at 33p per share - double the current price. If the Chairman thinks it's worth 27p+, and backs that with over £60m, and a bidder offered 33p, then that's telling us very clearly that the share is too cheap at the current price of just over 15p. That's why I've been buying recently. It's now a medium-large holding in my personal portfolio, which I'm disclosing because it might mean I have unconscious bias. It's easy to accidentally gloss over the negatives, if you've decided the potential upside outweighs the negatives. So just to be clear, Saga is troubled, the shares have been a terrible performer, and it has far too much debt. Exposure to the travel sector is clearly another major negative at the moment, with the fixed costs of its cruise ships being a cash drain until cruising can resume in April 2021 hopefully. Over 65% of customers have kept their bookings, so demand is clearly there. When it's safe to cruise again, I reckon these ships will be mobbed, and margins likely to be very good. I see Saga as a nice way to profit from that pent-up demand, without the huge risks of the big cruise operators, that are on (expensive) debt-fuelled life support.
Although Saga's high debt is a worry, £150m of fresh equity considerably de-risks it. The turnaround potential here looks exciting - Saga has a very successful insurance business (mostly motor and home), plus a travel division (including a small cruise ships operation). Obviously that's struggling, but I see this as a nice way to play the (hopefully) covid recovery in 2021. The combination of a highly profitable insurance business, and a travel business that should recover in due course, looks enticing. This could be a 2-5 bagger if the turnaround works, I reckon. The brand has considerable untapped potential, and is very valuable, in my opinion. If it can become a trusted one stop shop for the over-50s, then all sorts of new products could be introduced.
Share consolidation - one new share will replace 15 existing shares, a cosmetic change which makes the shares look less mickey mouse at just 15p currently. So the new share price will be about 225p (effective from 12 October), but we'll have 1/15th of the number of shares, therefore the market cap and investor percentages of the total are unchanged.
Bank support - as if often the case, the equity fundraising is accompanied by improved banking arrangements;
Conditional on the successful completion of the Capital Raising, the Company has agreed with lending banks to extend the maturity of the £70 million term loan by a year to May 2023 and has also agreed certain covenant amendments that provide additional financial flexibility
... On a proforma basis post completion of the capital raise, the Group will have a strong financial position with significant available liquidity, with approximately £60m of available cash resources, together with £100m of available undrawn RCF that is available through to May 2023.
That looks a comfortable position for the time being, so I don't have any solvency concerns about Saga for now.
There's loads more detail in the full announcement, but I've covered the main points above, so see the RNS for more information.
.
Interim results - are in line with expectations. I don't intend to dwell on these numbers, as this share is all about the turnaround under new management. Obviously covid has had a big impact, which makes the figures unrepresentative of what future performance is likely to be.
There is a video webcast of the results available here. You only have to register via email, then confirm on the email, and login using your email address to watch it. I shall have a gander at this after lunch, and read the rest of the RNSs too.
A few key numbers;
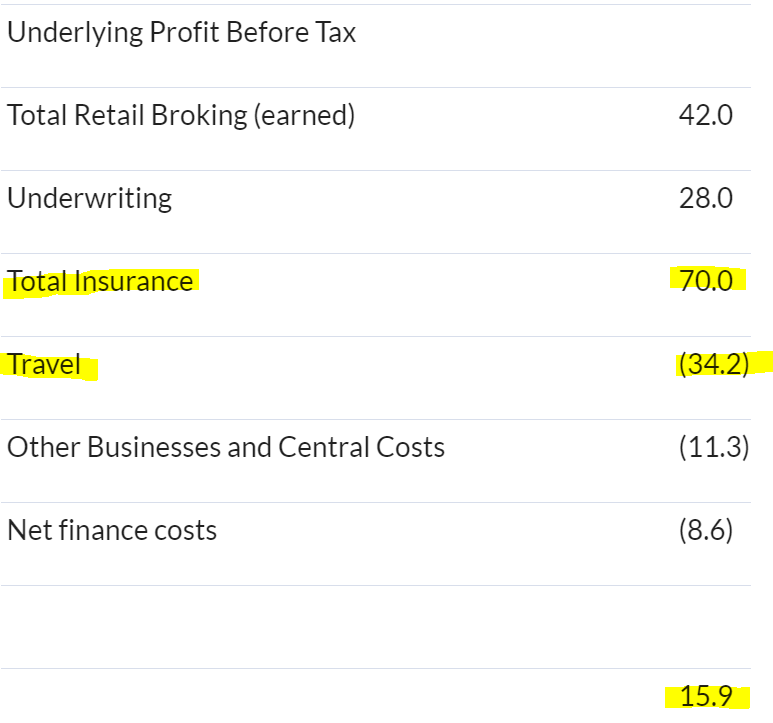
Underlying H1 profit of £15.9m, down 70% on LY
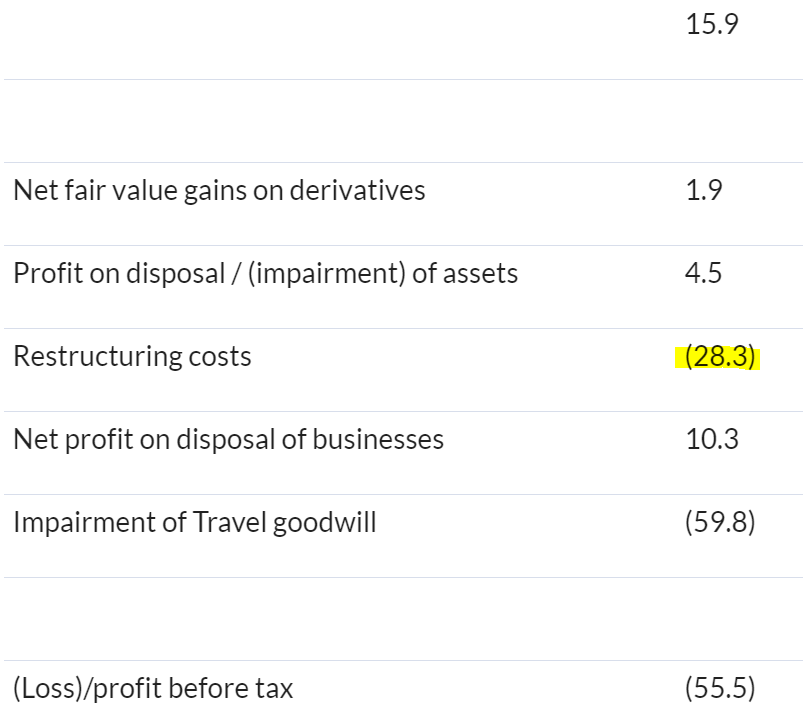
Statutory loss of £(55.5m), so a big difference from the underlying profit. £60m goodwill write-off makes up the bulk of the difference, which is fine I'm not bothered about goodwill, as I ignore it anyway.
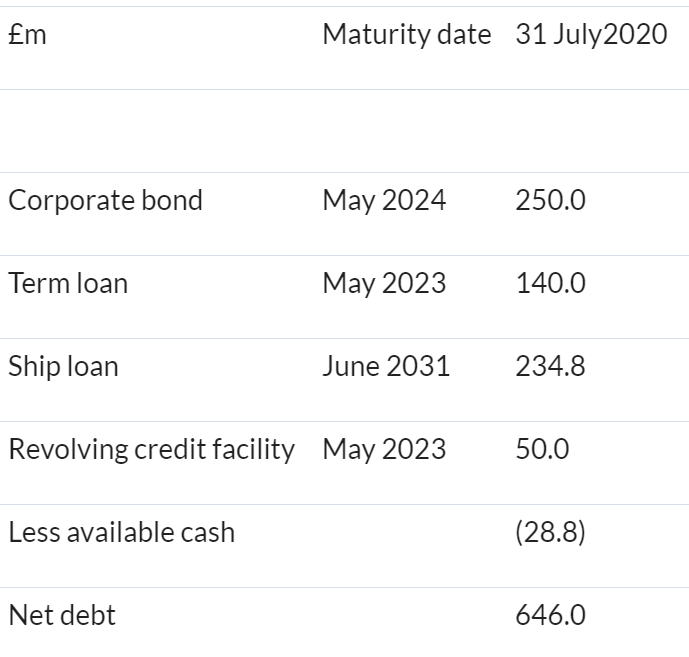
Net debt (adjusted) of £410.7m, not including the debt funding of its cruise ships. Clearly it is over-indebted, hence the equity fundraising being done.
Travel division is expected to burn cash of £6-8m per month in H2. That's an important disclosure, and I see that as a manageable level of losses for now. Remember the insurance division should generate cash, to fund or part-fund travel losses.
There's a nice table here, giving the breakdown of the £15.9m underlying profit, which demonstrates that the profitable insurance division is nicely supporting the losses in travel. It doesn't take a genius to work out that when travel returns to profitability, this should be a very strongly profitable group. Remember these are only half-year numbers too;
.
.
What I like about this, is that investors don't have to worry about Saga going bust. Whereas if we invest in a pure play cruise line, or airlines, etc, then insolvency is a serious threat. Plus with airlines, the lucrative business travel market might have been permanently damaged, because people are now working around long haul business trips, using Zoom, Teams, etc. instead.
Where adjustments to profit are large, as in this case, I like to check what they are, and consider how reasonable they are. Generally speaking I'm happy with adjustments which strip out genuine one-offs, in order to show the underlying performance of the business. If you prefer to value the business on the statutory numbers, then that's your prerogative. We're presented with both figures and the breakdown of it, so everyone should be happy.
.
.
Of the above, I'm happy with everything, although have highlighted the very large restructuring costs. There can be a temptation for excessive provisions to be made, and then benefit future profits as they are released. That's a general point, I'm not saying Saga has done that. It's a generic risk though, hence it's always sensible to ask the company what these costs are, as £28.3m is a lot, and that's cash going out of the door, I imagine.
Total debt is a bit scary, but has long maturities, so shouldn't be a problem to refinance, and reduce from cashflows, once the travel business is operating again (in my opinion). Note that bonds are an important part of the financing. It could be worth a look at the bonds as a potential, safer investment, if you don't fancy the higher risk equity;
.
.
Pension scheme - is in a small accounting surplus. Triennial valuation in progress, so the actuarial valuation could result in recovery payments, I haven't looked into this in any detail yet.
Going concern note - interesting reading. There's a "material uncertainty" conclusion, but only because the fundraising hasn't completed yet. Therefore barring some unexpected calamity with the fundraising (highly unlikely as the newswire is saying that it's a done deal - the company should update us later today), this material uncertainty would disappear. It's fine then overall, I don't have any concerns over solvency for the next couple of years.
Balance sheet - is quite complicated, given that both insurance and travel companies have lots of debits & credits all over the place. I like to keep it simple - NTAV is negative, at £(218.6m) - clearly a weak balance sheet, as everyone (including the company) acknowledges. The equity raise will boost NTAV by £140m (after insanely high £10m of fees for the suits - daylight robbery!), taking pro forma NTAV to a less poor £(78.6m). Overall, I think the equity fundraising makes this share investable now, whereas I wouldn't have touched it otherwise.
My opinion - I've covered this in a fair bit of detail, because I think it could potentially be a very good turnaround from here. This is a fundamentally very good business, with a very valuable brand. If new management can sort it out, with the founder's son now a major shareholder & the new Chairman, then I see this possibly doubling or more from the current level.
The downside risks are covered above, but personally I don't think it's anywhere near as risky as the market is currently assuming with such a low market cap. Covid is not likely to last forever, and with probable vaccines & continued improvements in testing (which could see every passenger being screened before embarking), then I think it's reasonable to believe that the cruise & holidays businesses could begin recovering in 2021. That's not guaranteed though, hence why the shares are low.
The equity fundraising shores up the balance sheet for now, so personally, I see risk:reward here as potentially good - i.e. more upside than downside, hence why I've bought the shares after the fundraising was announced earlier this month.
UPDATE at 15:58 - Results of Conditional Placing
The deal has gone through as expected, although the unexpected (at least by me) bit is the price - it's been done at just 12p, a 20% discount. Why?! This is ludicrous, since 2/3rds of the £150m fundraising is being bankrolled by the incoming Chairman (son of the founder, and a former CEO). So only £50m was needed from external investors, which should have been a quick & easy fundraise, at a premium even (since Sir Roger is paying 27p for £60.5m of his new shares).
I think the advisers have done a shockingly bad job here, and they're taking £10m in fees as well, which is 20% of the money not pledged by Sir Roger. This also reflects very badly on SAGA's CEO & CFO, who've been fleeced by the suits I'm afraid, ultimately costing shareholders money.
I know it's a lot of time & effort to produce a prospectus (out tomorrow morning), but £10m fees, really?!
This doesn't really affect existing shareholders, because the Record Date is close of play last night, so anyone holding then is eligible for Open Offer shares at 12p. That applies to spread bets too, which mirror the underlying market position. Although since the announcement of the 12p placing/open offer, the share price has actually firmed up a little, and is about 15.4p at the time of writing, so anyone who did buy today can sell at around breakeven now, if they want to. So overall, no harm done.
Although on reflection, I should have more heavily emphasised that the price of the deal wasn't firmly set. Apologies for that. I did point out here on 1 Sept that the fundraising price was to be "15p or less", but should have emphasised that today. It didn't occur to me that the company & its advisers would offer a discount on the fundraising, when they clearly didn't need to. Anyway, there we go.
Open Offer - is 5 new shares for every 9 existing shares, priced at 12p. Maybe they discounted the deal in order to motivate people to take up the open offer?
.
Victoria (LON:VCP)
Share price: 327p (down <1% at 13:29)
No. shares: 125.4m
Market cap: £410.1m
AGM Statement (trading update)
Victoria PLC (LSE: VCP) the international designers, manufacturers and distributors of innovative flooring, is pleased to announce the following trading statement ahead of its AGM to be held later today.
Trading is going well;
Trading has continued to be resilient since it last updated the market in July and demand has recovered in all its principal markets. This is reflected in the Board's view that consumers are prioritising spending on improving and refreshing their homes following the lockdown. The Group continues to carefully manage expenses and cash flow to ensure it maintains its strong balance sheet given the current economic conditions.
No figures are given, but the above is encouraging. I like the whole area of home improvements, as a good & resilient place to invest. Being stuck up at home, and with plenty of homeowners benefiting from low mortgage rates, and surplus cash from not going abroad, not commuting, etc, it makes sense that people are revamping their homes. I think that also provides an important psychological boost, in improving well-being, in what has been a harrowing year for all of us. My parents generation used to talk about where they were when President Kennedy was shot. Their parents swapped war stories. For us, I think covid & lockdown could be the big topic for discussion for years to come. People & businesses have proven remarkably adaptable, and generally I think we have pulled together. Massive Govt support when needed is also a strong indication for potential future problems also being fixable, in my view. So strangely, I actually have less anxiety about the future now, having been through (or rather, still in) covid.
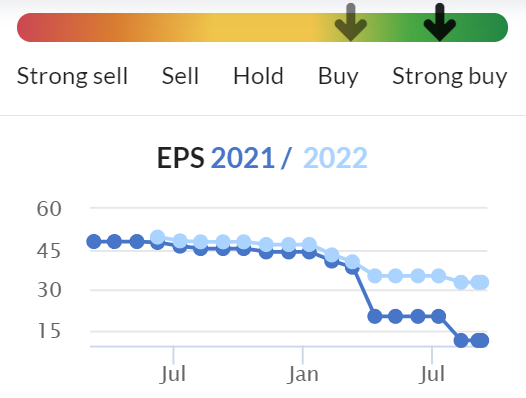
Victoria has a end March 2021 year end. It's a pity today's update doesn't give us any guidance on how the company is performing versus market expectations. As you can see, forecasts have come down a lot, so it looks like they have been adjusted for covid impact, enough, or too much, we don't know.
.
.
With businesses generally recovering, I'm increasingly coming round to the view that we should be valuing shares on normalised earnings in future years, rather than current year forecasts. In this case, looking at the above graph, if I were considering making a long-term investment in Victoria, then I'd base it on the company probably getting back to 50p EPS at some stage in the next year or two. Hence on that basis, the PER looks quite low, at 6.5
However VCP carries a heavy debt load, although this is nice secure debt, in bonds with medium maturity, and no covenants. Hence no bank manager whims to worry about there. Hence I'm not worried about solvency, but am just pointing out that the net debt needs to be taken into account in valuation.
When last reported net debt was £365.9m - that's a lot, and not far behind the market cap of £410m - hence why the PER is low. Debt of that size is expensive too, costing c.£25m last year in interest, or about a quarter of operating cashflow.
My opinion - this is a very cash generative group, and with trading recovering, I'm more inclined to have a dabble here than previously. Debt is high, but it's secure - being bonds - therefore before maturity, the company should be able to build up cash for repayment of at least some of it, but in practice would probably refinance the debt in due course. The only worry is if credit conditions are bad (e.g. another credit crunch) when the bonds need to be refinanced. Overall, I'm not too worried about this.
Overall, I think it looks potentially interesting.
.
Lunchtime now, I'll be back later this afternoon to look at 3 more companies on the list, EPWN, SDY, and ANP.
Epwin (LON:EPWN)
Share price: 75p (down <1% at market close)
No. shares: 142.9m
Market cap: £107.2m
Resilient performance ahead of earlier expectations; optimistic for prospects in H2
Epwin Group Plc (AIM: EPWN) ("Epwin" or the "Group"), the leading manufacturer of low maintenance building products, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors, announces its half year results for the six months to 30 June 2020.
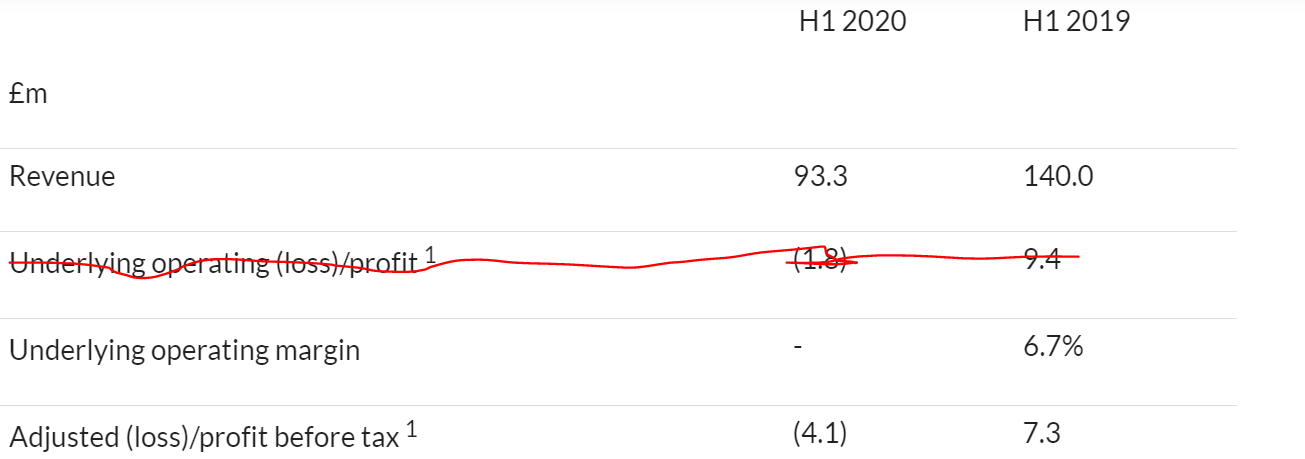
Epwin has taken a hard knock from covid, as you can see below. I've crossed out operating profit, because since IFRS 16 has messed up company accounts, it's now largely meaningless, in my opinion - because some of the rental costs for properties now (wrongly I feel) have to be included further down the P&L, within finance costs (or shown as a separate line in this case, on the P&L, which is a good way of presenting it)
.
.
I'm not sure that's a "resilient performance" as trumpeted in the RNS summary above. Revenues are down 33%, and it's swung from a healthy profit, into a loss. Is that resilient? Not really, in my view, but that's subjective. I'd say Dunelm's performance is resilient (as mentioned above - profits taking a small dip due to covid.
It's been a bad, but not disastrous half year, due to covid. Fair enough, let's move on.
Current trading - positive commentary, but July & August 2020 are only marginally up, at 2-3% LFL. Not really any sign of pent-up demand there. One division is up more, but that therefore means everything else must be down more than the 2-3% improvement on LY revenues.
Outlook - the key bit says;
As previously stated, the impact of COVID-19 will inevitably have a material impact on trading for the current year as a whole, however, at this stage the effect is anticipated to be less than the initially expected, with the Board expecting significantly improved performance in H2.
That's OK I suppose, but I'm getting the feeling that this announcement has been over-PR'd.
H1 was pretty awful, so I would expect a significant improvement in H2, because the economy has opened back up again.
Divis - suspended for now, but positive noises made about resuming in future.
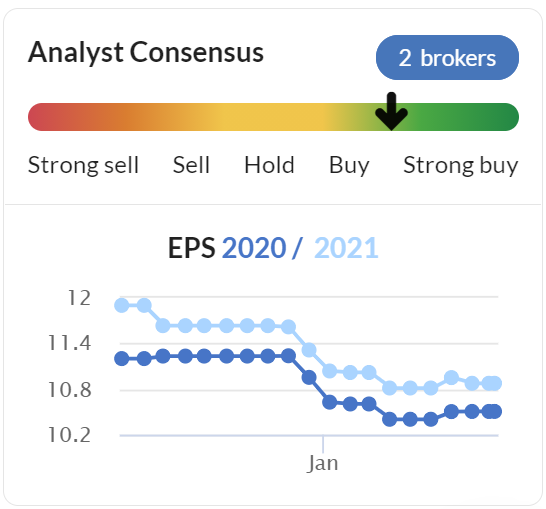
Forecasts - the broker consensus has come down, but nowhere near enough, given that H1 was loss-making, therefore I am ignoring these figures;
.
Balance sheet - looks reasonably OK, but not strong, with NTAV of £9.4m.
Bank debt is very high at £65.3m in long term creditors, but that's because the company seems to have drawn down borrowings, as an insurance policy, and is sitting on a cash pile of £48.0m.
Receivables are down 39%, which I would expect from the reduced H1 revenues. But trade creditors are almost identical to 12 months ago, at £61.6m. That suggests to me some creditor stretch - maybe deferral of VAT? Doing a quick CTRL+F search for "VAT", the narrative confirms that the March 2020 VAT liability was indeed deferred, but doesn't give us the amount - a glaring omission, investors should be told what important one-off gains have been made, because that VAT has to be paid in March 2021. We don't know if it's £1m or £10m, or somewhere in between? Similarly, the company says it took advantage of the furlough scheme, but doesn't provide the number. This is an annoying lack of transparency. Do let me know if the figures are given, as I might have missed them.
My opinion - I can't get excited about this. It seems as if the recovery is underway, but seems a little anaemic. I'd rather concentrate on companies where trading is roaring back, and pent-up demand is taking current trading way above last year. That's not the case here.
I imagine that this share might recover next year, but I can't see much of a catalyst for it recovering this year. Therefore, I'd rather concentrate my money into other shares with more obvious recovery potential.
Don't get me wrong, I cannot see any particular reason to avoid EPWN shares, it's just not clear that the upside is enough, or imminent enough, to make me want to put money here, and miss better opportunities elsewhere.
.
.
Speedy Hire (LON:SDY)
Share price: 54p (up 3%, at market close)
No. shares: 527.0m
Market cap: £284.6m
Trading Update (AGM)
Speedy, the UK's leading provider of tools and equipment hire, and services to the construction, infrastructure and industrial markets, provides an update in advance of its Annual General Meeting later today.
As I would expect, business is recovering as the economy opens up again;
Revenue has continued to improve over recent months as customers have returned to work and activity levels have increased... UK and Ireland core hire revenues for September to date are c.8% lower than the prior year.
Group revenues, pre disposals, for the year to date are c.23% lower than the prior year.
SDY has a 31 March year end, and I think lockdown started in late March, therefore almost all the covid impact would have hit the current year, FY 03/2021. Therefore, that YTD figure should steadily improve later this year, but it sounds like they're not likely to recoup lost sales, so a poor overall result seems likely for FY 03/2021.
Cost-cutting has seen 13 depots permanently closed, and staffing reduced, costs will be booked as exceptional.
Liquidity - details given, sounds fine to me. Tax deferred will be paid by 30 Sept 2020.
Guidance - remains suspended due to uncertainty. Boo, hiss!
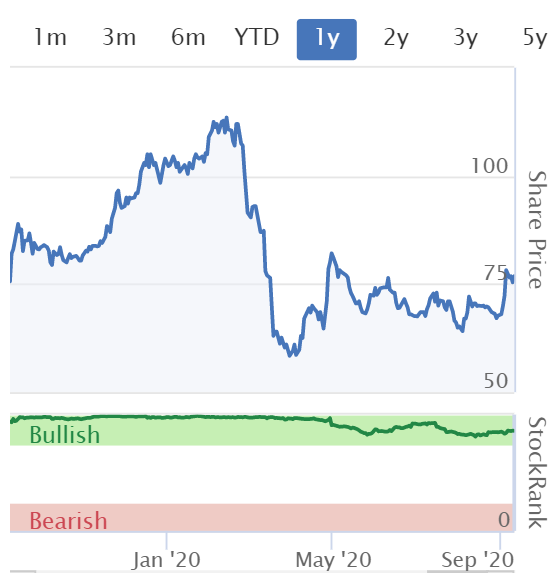
Graphical history - as you can see from the Stockopedia graphics below, the broker consensus is that the current year is basically a write-off, then next year FY 03/2022 rebounds fully to historic levels of earnings. That's possible, and the PER would then be about 11, if that scenario pans out.
.
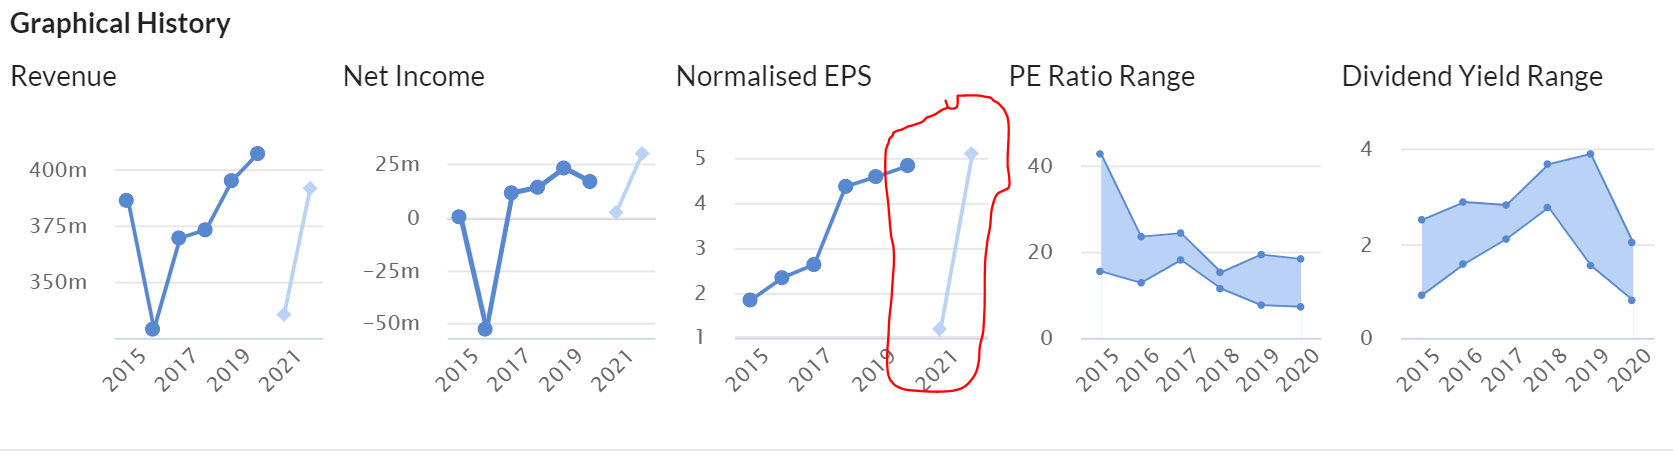
.
My opinion - I can't see enough upside potential here to get me interested. It might do alright, and recover more, but hire companies don't tend to attract high PERs at the best of times. There could be better opportunities elsewhere maybe?
.
Anpario (LON:ANP)
Share price: 420p
No. shares: 23.1m
Market cap: £97.0m
Anpario plc (AIM:ANP), the international producer and distributor of natural animal feed additives for animal health, nutrition and biosecurity, is pleased to announce its interim results for the six months to 30 June 2020.
I've looked at this company several times over the years, admiring its cash-rich balance sheet, and decent profit margins. However, the lacklustre growth made me question why it was valued like a growth company. That might be about to change, as H1 results are showing good profit growth.
H1 main points;
Revenue up 13% to £16.17m - I think that's all organic growth, I can't see any mention of acquisitions.
Gross margin is also up, leading to a rise in gross profit by 20%, to £8.5m
Profit before tax is only up 6% to £2.4m, due to adverse forex movements, which are stripped out of the adjusted profit numbers - that's OK I think, as forex movements are swings & roundabouts to me, so adjusting them out does show a smoother, more underlying view of profitability.
Adj EBITDA is up 24% to £3.4m
Adj EPS is up 34% to 11.74p. It looks as if there might be a slight bias to H2 seasonally, so I'm guessing full year adj EPS might be something like 25p perhaps? At 420p per share, that makes the PER about 16.8 - which seems quite reasonable, given that the company is now demonstrating some decent organic growth.
Balance sheet - is just stunning! I get joy from seeing a balance sheet like this.
NAV is £36.5m. Deduct £11.6m intangibles, and NTAV is £24.9m -which is a lot, for a relatively small company.
Working capital is really strong: current assets of £25.4m, includes cash of £13.2m. Current liabilities are only £4.0m, and long-term liabilities only £1.7m.
There's therefore stacks of surplus capital in the business, and it could easily make acquisitions of say £10-20m without breaking into a sweat. Not bad for a company valued at £97m, the cash is material to the valuation, and is hidden upside I think.
Acquisitions? It sounds like something might be brewing on this front;
Our strong balance sheet provides Anpario with the resources to expand our global reach and to undertake earnings enhancing and complementary acquisitions which may arise in these uncertain times.”
Outlook - I particularly like the bit about online & direct marketing - that could be a precursor for further growth, which is what I'm looking for;
Looking forward, we will continue the on-line and direct marketing tactics that produced such a strong first half performance. Additionally, we will be able to build upon new business gained from those competitors unable to supply during lock-down. As a result, we remain confident of continuing the profitable development of the Group.
.
My opinion - this looks good. The broker consensus forecasts look too low, so there might be an opportunity here to buy at a multiple that is quite reasonable, if you adjust the forecasts to something more realistic.
I only review the numbers here. The clever bit is for you to do - i.e. looking at the products, and understanding its markets, and what the growth potential is. I haven't got a clue on that side of things, but it's ultimately what drives the share price in the long-term.
From my review of the numbers, it gets a thumbs up. Many thanks to the readers who so politely nagged me to look at this, it was worth it!
Phew, bit of a mammoth session today, but I finally got through the list.
See you in the morning!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
Paul -Glad you optimistically reviewed . One of my significant favourites . Ticks all boxes . Leaving aside any acquisitions growth should from three areas - population growth needing feeding , new developed ,products , and particularly countries are increasingly outlawing toxic ,chemical growth stimulants - Anpario’s are all natural . A tightly ,conservatively managed business with big potential . Warrants a higher rating I believe .
Wow, are you working round the clock now Paul? Thanks so much for sticking with it to the end. Glad you enjoyed ANP. I went to a shareholder meeting when they were Kiotech and only about 2p! We were outnumbered about 2 to 1, but very much welcomed and thanked for attending. I think they were astonished at our presence. Must have been a first. They consolidated the sp to bring it up to around £1 I think to try and help reduce the spread, which is still ridiculous at 4 quid. It has been slow progress I guess, but they pay a decent and growing divi too. They got flooded when their base was near Reading I seem to remember so had a few early difficulties. The CO Richard, very nice down to earth guy, told me he had been project manager on the channel tunnel after uni. Absolutely fascinating little company of natural animal feed supplements for which they have numerous patents. Many of their products are produced in conjunction with research from universities around the world. So I would say they are of major importance in our food chain. A small company with an enormous world role to play. By and large I would say the strategy they drew at the meeting has gone exactly to plan so far. It is well worth looking at their website to appreciate what they do. BW and thanks
Thanks Simon, I've copied your post into my "interesting background" file on Anpario.
I've had Games Workshop (LON:GAW) on my watchlist for years but unfortunately never bought any. You know when Patisserie Holdings went bust and lots of people were being very wise after the event, saying that it was obviously not making anywhere near the profits that it claimed because they had visited the shops and always saw very few customers. Well every time that I've considered investing in Games Workshop I've taken a look at one of their shops and I don't think that I ever saw a single customer inside! So much for DYOR! Maybe I just went at the wrong time of day...
Every time I look at the share I cant get past the large p/e and think that it cant go up much more... oohh how wrong. Maybe there will be another dip (wish I bought in March 2020)... and I will have cash doing nothing that needs a home.
Best to stick with Paul Scott and find the next Games Workshop (LON:GAW) and jump in at the begining.
I use to subscribe to Analyst magazine back in late 1990's I remember GAW was tipped by them - but never bought, thinking "this will never take off".
Little did I know - I finally succumbed 6 weeks ago. Took me 20 years to buy them.
Who plays with little figures and paints them right? A LOT of people it seems... good luck with your share purchase!
Lyndhurst, I had the exact same experience with GW. I’ve always loved the company (had a misspent childhood where D&D played a big part). They have had several storefronts in Belfast - over the years I would see bearded employees (before beards were cool) playing games with each other and customers surrounded by high priced stock that never seemed to actually sell. I wanted to invest because I loved the company and products but the evidence of my own eyes always put me off.
I missed that the value in this company isn’t really in the sale of beautifully crafted miniatures and overpriced games - it’s in the asset value of the community (those bearded employees and customers that didn’t then have any cash) and IP that they have built over the years. Now we live in an age where everyone is crying out for new IP and GW is sitting on a mountain of it - the only question to my mind now is whether they continue to develop it successfully themselves or if Netflix/ Disney/ Apple (the list goes on and on) comes in and pays big money for the business.
Sadly, still can’t force myself to buy any at these valuations even with above rationale - I’m an awful investor still stuck with the old fashioned metrics that I can’t get over...
Games Workshop (LON:GAW) hasn't all been one way over 20 years. There was a big rise on the back of the Lord of the Rings films. The a multi year fall, restructure of retail and doubts over the future.
CEOs didn't seem to last long.
Then it all came right.
I owned it during one of the less successful phases so don't beat yourself up too much.
Although I enjoyed reading Paul's thoughts on Saga (LON:SAGA), I could not help feeling that many were reminiscent of the reasons I bought into the IPO in the first place back in 2014 and have since watched my (small) investment effectively disappear. One of the few things I have learned (but forget to practice) is that putting good money after bad is risky.
Saga (LON:SAGA)
xerxes
I could not help feeling that many were reminiscent of the reasons I bought into the IPO in the first place back in 2014 and have since watched my (small) investment effectively disappear. One of the few things I have learned (but forget to practice) is that putting good money after bad is risky.
Is this not a completely different situation though - if we say Saga returns to decent profits in two years time (and continues to trade well) what p/e do we think the company will be on based on shareprice now - possibly pe of 4 perhaps maybe even less. Whereas when it ipo'd i would be guessing it would be bog standard p/e of 10+. If it does return to profit and gets 16*pe rating back then that would suggest it could be 4 times return on investment from current position.
I would doubt that kind of return would have been expected at ipo? i would have had this down as a dependable plodder of the business way back when at a guess - take your divi and get a bit on increase in shareprice as profits rise.
The downside though is porbably worse than when it floated - if things to go wrong from here its probably almost a given that one should be expected that this would be 100% loss due to the debt.
So binary play now v dependable plodder back than - completely different plan of attack- not that the description dependable plodder seems aprt now with the benefit of hindsight.
Wise words rmillaree, I was with you right up until this :
In that event anyone who bought in at IPO will also lose 100%.
The risk of that is obviously more apparent now, but I don't think it is necessarily less avoidable, there is still imho a reasonable chance that any total loss may come with some advanced warning, potentially enabling an exit.
No position at the moment, although about a month ago I was preparing an article on Saga (LON:SAGA) that I never got around to publishing, so I'm reasonably au-fait with the business and may well be a buyer tomorrow.
Gromley, I have only looked at very shallow level, really as I own the ugly sister Aa (LON:AA.)
Why do you like it? What do you think is misunderstood, under appreciated, too easily hated, etc about it?
Thanks
To be perfectly honest, mostly because it is cheap!
It's far from a conviction holding (I do now hold), but it is with the realms of plausibility that it will multi-bag over the next 3 years or so.
The insurance business is clearly not broken and according to their latest statement has 'returned to growth' (obviously means something different than a year of year decline in revenues). Neither is their holidays business broken - the cruise bit is clearly damaged for a good while but that 70% of their bookings have just been moved into the future rather than refunded, suggests if they last long enough future prospects are okay.
The fund-raise reduces the downside risk of running out of cash (although that is still not an insignificant risk given the cash drain in H1) and if then can return to near to their previous earnings they are on a PE c. 2x.
There's more to it than that, but I'll save that for another time.
Saga (LON:SAGA)
gromley
The risk of that is obviously more apparent now, but I don't think it is necessarily less avoidable, there is still imho a reasonable chance that any total loss may come with some advanced warning, potentially enabling an exit.
I think my point was that previously there was a very nice comfort blanket that the company was making decent profits - had a divi it could cancel to save cash and had a much higher market cap that meant it could raise £100 mill at will without undue dilution.
Now the company has such a small market capitlisation compared to its debt that the main backup plan of a nice rights issued without undue dilution is not really there - there is currently also no cast iron profits coming along anytime soon - so holding for any length of time has risk in that bad news could come along any day. Often with companies like this its an ever decreasing circle that the share price drifts down on no specific bad news , making the problem worse so that if bad news does come along material dilution can be on the cards or the holders of teh debt can force through somethig that is really bad for shareholders. Hopefully saga has raised enough cash to see it back to profitability and put oit in a position where it can service and debt rollover - if that is the case things go right i would be positive about teh future. I haven't looked closely enough at saga to form an opinion either way at present.
From an overall point of view if one is comfortable that the busines will make enough profits to service its debt from here on in then i think the upside prospects will look very nice potentially.
I do get what you are saying, but it is a question of perspective. From my point of view the comfort blanket you describe was the risk (or perhaps the trap).
It is now close to been priced to fail and whilst the visibility of a potential 100% loss is now much more apparent the actual likelihood hasn't increased by quite so much.
I think I would rather invest 20% of a position in 5 uncorrelated situations like this than I would 100% of a position in the previous investment prospect.
The market doesn't know, or care, about our history with any share.
The more digging I'm doing with SAGA, the more reassured I'm becoming that this looks a potentially interesting turnaround. Some really good stuff here;
https://www.corporate.saga.co....
It looks like a fantastic brand, that's been damaged badly by the curse of Private Equity, and corporate suits mismanaging it thereafter. Now the founder's son is coming back, refinancing it himself, this looks potentially really exciting to me.
I'm reading through the Prospectus, it looks solvent through 2021 to me (post fundraise). Love the move to ring-fenced cash in Oct. Just 2 cruise ships, cash burn £6-8m per month, which I think might include cash returned to customers, not sure. Most are re-booking. Demand is like a coiled spring, note from the webinar that mgt keep saying things like "demand will not be a problem" with the brand new cruise ships.
I suspect the stock market might look at this share dramatically differently this time next year.
Cashflow & debt are fine, post fundraise.
DYOR obviously. Post covid, I reckon this could be a 3+ bagger, without much risk. Just my personal opinion, am only on about page 57 of the Prospectus, so reserve the right to change my view.
Regards, Paul.
FWLIW, we had a Headlam (LON:HEAD) carpet fitted just before lockdown, sold via a Headlam (LON:HEAD) distributor, and which a few days later proved to a have a fault. Despite lots of statements by the company that they are back operating as normal, we have yet to receive a replacement carpet... ...its now due to be delivered to our fitter this Friday. Said distributor put its reps on furlough when lockdown started, gradually brought them back so that the rep our fitter was dealing with was working half his hours. Now he's back on full furlough.
Apparently any newly ordered carpets, across the sector are quoting delivery in November and actually getting hold off what was ordered months ago is a complete nightmare involving masses of chasing.
I am struggling to reconcile the above with all the positive commentary from Headlam (LON:HEAD) and other carpet companies. Personally I see it as a huge red flag that Victoria (LON:VCP) are not prepared to give any solid numbers and limit their RNS to vague positive platitudes.
Would like to be proved wrong. No position in the sector.
Let the total figures (and cash) do the talking, not a mystery shopper sample of one.
Usual stuff of, shop seems empty, etc.
If they're busy & can't supply you until November, what does that tell you? Lack of demand?!! As an investor that's a buying signal isn't it? You're usually very sensible shanklin! I think you need some smelling salts! ;-)
Paul, your write up, especially the line "What I like about this, is that investors don't have to worry about Saga going bust." spurred me on to take a position in Saga. Good luck to me and all other holders!
Oh dear. I hope you've done your own research. Remember this isn't a tipping site, it's just me giving my personal opinions on shares. I definitely don't want readers following me blindly into things, as then I get the blame when things go wrong! (as inevitably some shares do, since we cannot predict the future with any certainty).
You are right to remind readers that this is not a tipping site (which it is not) and that it is important to do your own research. I felt there were too many pointers in your research that suggested that this company has good potential for upside whilst at the same time being a less risky proposition, coupled with the low entry point. I take responsibility for my decisions, so no worries there. On a positive note, the share price is ticking up even as I write....
Looks like I made a good call and my decision is bearing fruit :)
I also bought more Saga at 18p because of the many plus points so well covered by Paul in his (as usual) excellent update on Saga today, and also so as to get more shares in the open offer.
I’m now confused about the Open Offer as the maximum price is 15p. Yet with the share now down to about 14p and down a lot so far today, it is cheaper to buy more shares in the open market. So will the offer price now be reduced to keep the offer attractive? And was it a mistake giving a maximum 15p price as possibly a temptation then is for the market to drive the price below that? It just seems odd bearing in mind that Roger De Haan is happy to pay 27p that the share price has now been driven so low. Unless I’m missing something Saga’s current share price looks a real bargain bearing in mind recovery prospects and that they are now on a much firmer financial footing.
Another thing I don’t get is why we shareholders were not informed about that 33p offer. Why not? That imo was a better alternative for those of us holding than coughing up new money. And who knows there might have been more than one bidder too.
Saga came to the market loaded with debt and at far too high a price too. But the 90%+ fall does look extreme! They tempted a lot of their customers to buy the shares then, and for many it may well have been their first foray in to share investing and so it’s been a bruising experience. Their excellent magazine has hardly mentioned their shares since!
Paul mentioned their cruises starting up again next April. The good news is that they hope to start again in January with a succession of cruises to the Canary Islands. I’ve checked availability and sales seem to be going well so far. Hope the new restrictions announced by the Government yesterday don’t change that.
Note that their 2 new ships are superb and unique and the first small ships to have 100% balcony cabins with no inside or just portholes. Saga prices are good for the high quality, with a lot included that other Companies charge for. And customer service for their cruises is very high. As Paul says cruisers love cruising and when covid is history the sector will thrive. And a BIG BIG plus for Saga is that cruises are just a part of their business, unlike huge rival Carnival where lockdowns are losing them £billions.
A possible negative pointed out in posts here today is that CE Euan Sutherland has a not very impressive past history, leaving the Co-op after a row and then Julian Dunkerton, founder of Superdry, was so unimpressed with his performance there that he came back again and Euan Sutherland had to resign again. BUT Companies can thrive despite the CE just as Belgium managed very well without a Government a while ago. And anyway Euan doesn’t seem to be doing a bad job at Saga and the return of Roger De Haan is a huge plus.
Maybe I’m missing the reasons why the share price is in free fall?
Saga (LON:SAGA) - Hi Ken, news out a few minutes ago - the Bookbuild is at 12p -
Thanks Albm7.
And in case anyone hasn’t seen it, Paul has added to his Saga write up today with his thoughts on that 12p discount price.
This well-known brand for the over-50s (that includes me, arrrgghh!! I'm still 25 in my head!)
I have recently started my 53rd year of experience of life and one thing I have learnt in that time is that you are as old as you behave, so I'm only 12!
Epwin is on the rise and housebuilding is beginning to wake up. A good little company in the right spot.
Any chance of looking at Prime People (LON:PRP) Paul?
I'm afraid not Prime People (LON:PRP) is only £5m mkt cap, so too small - lots of tiddlers that sort of size end up de-listing, as spending £100-200k p.a. on a stock market listing makes absolutely no sense, plus all the hassle of a listing. I think a small staffing company announced a de-listing recently, but cannot remember the name. Also the recruitment sector is something I'm steering clear of at the moment - too many regulatory risks.
That said, a quick look at PRP's StockReport shows a nicely profitable little company, so it could be worth looking at, if you're prepared to take the risk of holding something that tiny. And of course, if you can actually deal in the shares at all - often the liquidity is next-to-nothing, and bid/offer spread very wide, at that microcap level.
But by all means post your thoughts on the company here.
Regards, Paul.
I haven't paid close attention to Saga (LON:SAGA) ...however £150m at 27p (ie near 100% premium) is quite remarkable...ex CEO and son of founder coughing up maybe as much as £100m of it (for sure £60m)
The share price today implies the company is zombie and/or the extra £50m+ wont be taken up by others. But it seems unlikely this exercise would be underway without pretty strong commitments at 27p.
Interesting also that the notorious and hard nosed Elliott Mgt took a stake in April....they see some value in the assets and the brand.
Complex game going down. Interested in what happens. What are the views? (beyond Saga is rubbish etc)...starting with...why is anyone selling today? (i'm pretty ignorant on the company so it may be obvious)
RNS says:
BLOCK TRADE: SAGA CONDITIONAL PLACING - BOOKRUNNER SAYS
BOOKS ARE COVERED. INDICATED DEMAND EXCEEDS DEAL SIZE, FURTHER
GUIDANCE TO FOLLOW
Haha. I think my original comment was out of date when I posted if I'd updated on RNS!
I'm being a bit dumb here but why is the share price falling on this?
Placing is at 15p Mojo. Yes, the old CEO is putting in a big chunk at 27p but the rest is being done at 15p, so the share price is just reflecting this I think.
I didn’t read carefully enough
Saga (LON:SAGA) I bought more this morning - averaging down for my sins! But at circa 15p and as you say the former CEO paying close on double plus the fact that they rejected a 33p bid tells me people see value in their insurance arm and the brand itself. I think they mentioned the cruise bookings had also held up quite well but that was back in June.
Elliot according to filings is now below 5% . They held their positions via 3 equity swaps, 1 of which expired 14th April 2020, (0.82% of voting rights) another expired 28th August 2020 have also expired (4% of voting rights) and their last one expires 2022 (0.24% of voting rights).
I think the 1:15 share consolidation is also good as it makes it an easier for institutional fund managers to own as they tend to shy away from penny shares.
The current CEO at Saga (LON:SAGA) doesn't have a great record as far as adding shareholder value is concerned... https://en.wikipedia.org/wiki/...
Superdry (LON:SDRY), Kingfisher (LON:KGF), Co-op
no position
I guess he has some experience when it comes to negotiating his exit packages.
To be fair to this individual if my basic research is right Kingfisher shareprice did alright while he was there - superdry increased sales nicely for 4 years whilst he was there before it all went its up (and fashion retail probably is smee stuff) and it looks like he walked away from the co-op on a point of principle. If nothing else he will have good life experience in probably just about everything that can go wrong with regards to big companies - so perhaps in that regard he may be a suitable fit for saga perhaps?
Definitely not a small cap (but as a retailer, it's in Paul's specialist field), the Hut Group announces its pricing this morning: 500p equates to a mkt cap of £5.4bn, which is 4.9x 2019 revenues! Bonkers.
is the ipo open to anyone, if so hoe do you sign up?
*how
I would appraoch one of the sponsoring banks.
Any thoughts on property reit Hammerson (LON:HMSO)? Gone ex rights today and the nil paid can be bought and sold under ticker HMON for a few pence. Just option money and will fly around. Takes me back a while. I remember buying the "Polly Peck" rights many years ago for a penny; lost the lot.
Amazing really. Not that long ago that the directors turned down a £5 billion offer for HMSO having themselves offered £11 billion for the now ill fated Intu. As one poster elsewhere asks...who are these directors paid fortunes a year and how can they have destroyed so much in so short a time?
I've updated the valuation on the below link for Hammerson (LON:HMSO)
https://www.stockopedia.com/co...
If HMSO closes below 15p then the nil paid rights will be worthless. If not taken up they will expire for zero. The underwriters will end up with a huge amount of stock. The stock opened up today at around 28p and closed at just 23p so it will be close I think. Personally I could see the current HMSO price at around 12p to 14p and many investors refusing to throw more money in.
yep, I see this ending close to 15p.
BSV
Am hoping I am correct on this, but it seems quite interesting. The RNS from Scs (LON:SCS) this morning (I hold and doubled up in early April lows after some discussion here re. cash holdings) shows a new disclosure of a 5.07% holding in the name of Scion Asset Management LLC. A quick Google of this name shows it as the investing vehicle of Dr Michael "Big Short" Burry - if my quick search is right I am encouraged... time to get my headphones on and crank up that rock music (those who've seen the film will get this)
Perhaps I'm right, as it would help explain why the SP is up >5% on IG.
Master of Puppets time.....
Could the shorting guy possibly be hedging a short in DFS with a ,long in SCS? Just a hypophesis.
Tt Electronics (LON:TTG) seems a very bullishly worded TU from this reliable if dull manufacturer. In fairness they also give good specifics. the £280m sales opportunity i assume if over multi - years. i have gone for £70m next year which at a simple pro-rata basis adds 60p to the previous share price - but i'd have though the ne product is
(1) at higher margin
(2) de-gears the business
(3) warrants a higher rating b/c of CV19 possibilities.
disc - not a holder as too risky for me to calculate underlying value at the mo
I think that the speed to market of the Virolens kit will also serve as a a great shop window for the group's ability to bring something like this to market quickly. The TU also hints that there are several other (presumably mainly airport) operators watching the Heathrow trial keenly.
Hi regarding TT electronics (LON:TTG)
Two comments:
TT talk of £280m in possible revenue but this testing space is/must become very crowed soon as there are probably 1000’s companies round the world charging to the same solution, a rapid swab test, so is £280m likely given the huge competition they are soon to face?
Related topic, on Mad Boris’s Moonshite, make your own mind up on the madness that there are at least 3 ‘experts’ saying the technology for rapid tests does not exist.
Related topic, on Mad Boris’s Moonshite, make your own mind up on the madness that there are at least 3 ‘experts’ saying the technology for rapid tests does not exist.
It will be interesting to see the Salford trial results. I'm sceptical about the behavioural science: hundreds of people with tickets turn up to an event. They queue at the required social distance for testing and each wait 20 - 90 minutes for a result (socially distanced - maybe in the rain?). Then those who tested positive obediently go away to self isolate (with or without a ticket refund? On public transport?) and those who tested negative trust that all those who tested positive have not been admitted.
Those assumptions don't feel they would lead me personally to want to attend a theatre performance or a football match - or to buy shares in companies on the assumption that this will succeed.
Surely there's a better use for £100B?
Surely proof of a negative test result would be a condition of admission, so I don't see where trust comes into it. The scheme has problems, as you point out, but a saliva test with a 20-minute turn-round, assuming that is available, might be less onerous than the consequences of the theatre, cinema and nightclub industries totally collapsing, and it might be cheaper than financial support for them all.
A "proof of a negative test" would have a market value. The touts at the entry to the Oval cricket ground stretch for a hundred yards ...
In order for such a system to work, it is likely that the Oval would administer the test - such a test should be cheap, mobile, quick turnaround and not requiring high skill to conduct, and of course reliable. In absence of deployed vaccines such a test would have huge utility and economic and social value.
Hi Thirty Fifty Twenty
I have held Tt Electronics (LON:TTG) for a few years or more, since they divested their automotive division and started to focus on improving margins and the development of complex electrical and internet related components. It commits annually to its R&D budget. It is not dissimilar to Volex (LON:VLX), which I also hold. Darren Morris, the CFO of Volex described Tt Electronics (LON:TTG) as its closest contemporary at a presentation organised by Yellowstone Advisory, which I attended, from memory in November 2018.
Richard Tyson, the CEO is not given to hyperbole in my view, having seen him present on a couple of occasions. He is very much matter of fact and tells it how it is. If Virolens achieves medical certification, it will be transformative for the company. Not only Virolens itself, but showcasing the company's engineering skillset. Conversely if Virolens fails to gain traction, it will not be a disaster. To my mind Virolens is a potential and unexpected cherry on the cake for what is a company operating in an exciting growth area.
My views of course and I am talking my own book. Each has to come to their own conclusion.
All the best
Here is the Luceco (LON:LUCE) interim results analyst presentation from Tuesday. Poor John Hornby, CEO, had a power cut, shortly after he began! Matt Webb CFO took over very smoothly, and John did come in on 4G after the financials. A good set of results, things seem to be going very well for them. Video & podcast
Today, 10.9.20, 1pm, we have a piworld interview with Castleford Tiger. We will cover CT's stock selection, current picks, thoughts on Dart/Jet2; with hopefully time for the pros & cons of bulletin board posting. Following our chat yesterday, I know we're in for a treat.
Castleford Tiger was mentioned by Andy Brough, for his encyclopaedic knowledge of Dart Group. Andrew Robinson (Castleford Tiger) is a accountant, runs a family food & drinks business and has interests in retail property. Andrew has invested since winning an investing competition whilst at University. (Latterly he went back and taught investing to under grads at his university, but sadly no longer has time for this.)
Register here.
Later today, we'll have the recording of the analyst presentation for £EMIS.
I had a brief look at Fuller Smith & Turner (LON:FSTA), not strictly a small cap at £700m market cap. Trading seems ok, 80% of the estate open trading at 80% of previous levels. It requires a bit of work from me but I am always told how much amazing real estate they have. I was in London for a few days last week and had the pleasure of a Guinness or two in the Hereford Arms. I have no idea what that pub is worth as a conversion to residential but would wager its more than its in the books for. Although of course it could never be replaced either. Balance sheet looks debt light and the share price has halved.... looks worthy of a closer look to me.
Reported that the freeholds are worth more than the company.
And the last property valuation was done about twenty years ago.
Hi Paul. Is ANP still on the agenda? I guess its all in the update but would be grateful for your financial opinion. Many thanks
Have just worked out Stockopedia doesn't accept comments using a VPN's. Thought I'd been barred! Which leads me onto another question. Does anyone else here use them?
I'm currently signed in over a VPN using a laptop and using the new S'pedia site and can post with no probs.
hi Simon. I use a vpn all the time and it works for me, I'm using Nord and have very limited issues with certain websites but the security on line it gives me far outweigh the irritations, Stockopedia isn't one I have any issues with btw
cheers
David
Thanks both of you for the replies. I have PIA and AVst or Hidemyass which I'm trialing and they both block Netflix, Iplayer. and other sites. Interpol seem to be suggesting VPN's were a problem because it hid criminal activity and was beginning wonder who they are trying to protect! I've heard Nord and Express are 2 of the best of about 700. BW
Simon, has always worked for me using ProtonVPN.
Incidentally, I will not use Nord as the ownership is clouded and highly suspect. Proton was developed for CERN
Thanks Parsley. Thats the strange thing. Pia (Kape)always worked for me. Just recently its seems to be blocked by more and more sites. When I started researching it, it seems there is some strange ongoing cat and mouse battle, as VPN's update to get around the blocks. The beeb obviously block them because they want to protect people from other countries getting free access to their service, which means I have to disconnect VPN to listen to Test match special because they can't see my concealed IP address. I'm glad to see a few more of you think its worth using VPN. So far all the people I talk to face to face have never even heard of VPN except for one of my sons who's company use it as he works from home. Even an IT guy I know said he doesn't see the point. I would have thought share dealing and bank transfers make them fairly essential even if not full proof
Mirriad Advertising (LON:MIRI) another request for this one please, looks very interesting & the CEO who is running the show now has a good background.
Hi Yellowstone, do you know if they have competition in this space?
Hi John, im not aware of any company doing exactly what they do.
HI John, my reply further up the forum might be useful in terms of context.
Thankyou Richard.
Investegate is very slow this morning, so Ill do a quick macro update. My main interest is a shift to value which would benefit many UK sectors incl retail and although it has small cap implications it is far from their only driver. Hopefully it is therefore of interest.
The above chart would suggest things are changing. I have looked at 30-5s because the 10s are thought, perhaps, to be held down by the fed action whilst the 30s aren't. The recessionary mood of the bond market in 2018 has passed and the spread is picking up. There is little follow through to equities yet.
In the last week we have had a tantrum in tech but that is all. We took a look at 50 day MA and now hover over trend lines drawn since the covid correction in March. The dollar made a base but hasn't been doing much... 10 year yields are moving up but slowly. Month to date Oil shows most weakness, -10%. Gold and silver are off slightly less but the industrial metals, copper and Iron Ore are positive. VIX has being doing strange things, rising ahead of the tech wobble, remains elevated but actually fell on Tuesday. This could be interpreted as nothing at all, or that the problems are in the market not with the market.
So there is a little evidence that some change is a foot but that is all. In my random list of 5 value stocks the same trends are also evident. The weak links are BP and Barclays, whilst Rio, BT and IMB are flattish. Tobacco has been strong the last few days. Overall the darling of the last decade, Tesla is still out in front but its 40% rise has halved to 18% whilst the All share is down 3% and the value basket down 7.
Its a clear pair of heels to Tesla and co but normally.... rising volatility brings change. This doesn't have to be bad for the market overall... in the period 2001 - 2003 I have read but don't have the chart, an equally weighted S&P 500 rose. Hence my interest in value versus growth.
Happy hunting.
let's hope LOOP recovers today after a NASDAQ caused sell off of tech on the FTSE, nice update.
My morning smallcap tweet: WJA believe it.
Wameja (LON:WJA) EPE Special Opportunities (LON:ESO) John Menzies (LON:MNZS) Supply@Me Capital (LON:SYME) City of London (LON:CIN) ReNeuron (LON:RENE) Prime People (LON:PRP) LoopUp (LON:LOOP) Speedy Hire (LON:SDY) Iconic Labs (LON:ICON) Science (LON:SAG) U and I (LON:UAI) TT electronics (LON:TTG) Saga (LON:SAGA) Epwin (LON:EPWN), Dev Clever Holdings (LON:DEV)
Wameja (WJA) rec offer at 8p, a 39% premium. Many holders hoped for more from partner Mastercard. [SP=5.75 Cap=167m]
EPE Special Opps (ESO) NAV 345.7p/sh. [SP=208 Cap=65m]
Menzies(J) (MNZS) bank agrees revised covenants. Guides H1 rev down 33%. Co "re-starting operations and seeing a partial return of flight schedules. Cargo volumes continue to be more resilient and our AMI business, a cargo brokerage, is trading ahead of expectations given the current lack of available capacity." Some contract wins. [SP=113.8 Cap=96m]
Supply@Me Capital (SYME) claims to habve offers of funding to monetise more than €300m of inventory. Plus region updates. [SP=0.57 Cap=187m]
City of London Group (CIN) £30m placing at 80p, a 25% premium, for SME lending and to boost capital for banking license. [SP=64 Cap=26m]
ReNeuron (RENE) AGM stmt: patient dosing started in the expanded Phase 2a trial of hRPC cell therapy candidate for retinitis pigmentosa. Also "signed a further research evaluation agreement with a leading biotechnology company [for] Company's proprietary exosomes for the delivery of novel therapeutics." [SP=91.45 Cap=29m]
Prime People (PRP) guides FY(March) rev down 3%, pretax at least £1.8m (£2.47m). ""Since June there has been a modest increase in activity. However, half and full year profitability will be severely impacted. As a result of challenging trading, we expect to take a material reduction in the value of goodwill." [SP=42.04 Cap=5m]
LoopUp (LOOP) significant new contract with one of the world's top-5 law firms. Expands partnership with C&W Communications to 2022. Starts free plan for 10 people max "aimed at individual users within target market professional services firms, who experience the product as guests of existing customers." [SP=200 Cap=111m]
Speedy Hire (SDY) UK and Ireland core hire revenues for September to date down c.8%. Utilisation 52.9% (2019: 54.6%). Expects no staff on furlough beyond end Sept and other tax payments deferred as part of COVID-19 support measures will have been paid. [SP=52.4 Cap=276m]
Iconic Labs (ICON) has successfully completed a contract to produce research, data and insights for a multinational consumer goods company. Expects to extend JOE Media's contract to its newly acquired Irish operations. [SP=0.01 Cap=1m]
Science Group (SAG) guides FY adj op profit in line or slightly ahead of mgmt original expectations. Will pay interim div of 2p. [SP=242.9 Cap=101m]
U and I (UAI) gets £23m grant for first phase of delivery at Mayfield in Manchester which is expected to deliver c.£80-100m of profit and c.£40m in fees to U+I over its lifespan to c.2034. Other updates. [SP=62 Cap=78m]
TT Electronics (TTG) has been appointed exclusive manufacturing partner for the commercial launch of Virolens, a COVID-19 screening device using microscopic holographic imaging and AI to detect the virus from a saliva swab test within 20 seconds. Initial order worth £2m in Sept and Oct. iAbra has indicated its intent to purchase further devices and cartridges with associated revenue to TT of circa £280m. [SP=190 Cap=312m]
SAGA (SAGA) [edit] proposed £150m rescue placing. £60.6m at 27p from the ex CEO and the rest at a discount [SP=16.03 Cap=180m]
Epwin Group (EPWN) H1 ahead of earlier expectations;,optimistic for H2. [SP=76.12 Cap=108m]
In line: Dev Clever Holdings (LON:DEV)
Hi Paul. Is ANP still on the agenda? Would be grateful for your thoughts on that. I guess its all in the update but would still be good to get your financial wisdom on their numbers. many thanks
Hi Simon,
Yes, Anpario (LON:ANP) is on my list, but it won't be until late afternoon, as I have a few other companies to do first, and need to rest my eyes for a bit over lunch.
Regards, Paul.
Much appreciated, Paul! (But please don't overdo it today if you're tired; I think we Anpario shareholders are a patient bunch who would be grateful whenever).
Loopup (LON:LOOP) have announced some major contract wins prior to their results on 23rd September. They already provide communication services to 20 of the World's Top 100 Law Firms and 20 of the world's top 100 Private Equity firms. Today they announce (potentially) their biggest ever client and have added 3 more top law firms (i'm not sure if this makes them market leader?)
My analysis has H2 operating profit at 7m verses 9m in H1 to give 16m for the full year. this would be EPS of 22p with (very probably) a net CASH position.
My analysis is simplistic but gives an indication of value on offer (IMHO). I have a lower H2 op profit than H1 as i have assumed some level of increased expenditures to facilitate growth. This might turn out to be conservative because in H1 the additional 'lockdown' revenue very much went straight through to the bottom line.
I think before some investors were put off because they reported EBITDA but of course had development expenditure. My analysis expenses this expenditure. But to put t in context Gross Profit will be c.45m and Development Expenditure this year estimated to be 6m.
disc holder. I am risk adverse investor type.
Hi, thanks for the recap on Loopup (LON:LOOP) (I hold)
Today's news on contract wins was good, but it didn't say anything about market expectations, so presumably the new orders haven't made much difference to expected performance. Remember that companies don't RNS attrition rates of the clients they lose! (unless it's a major customer material to profits).
I like the try before you buy marketing approach. It makes sense to get a few individuals trialling the product, who could then become advocates of it for their whole organisation.
LOOP does seem to be becoming a strong niche player - particularly with legal & other professional services firms, who want something more secure than e.g. Zoom.
The last trading update from LOOP was stunning I thought, so am eagerly awaiting the next results. Looks good value to me.
Regards, Paul.
Fabulous update from Games Workshop (LON:GAW), wish I had continued to hold. Potentially transformative announcement from Tt Electronics (LON:TTG) (TT Electronics) regarding the development of new technology, a screening device for the detection of Covid-19 in partnership with iArbra, a British technology company and Intel. The device 'Virolens' has successfully completed the first round of testing Heathrow Airport and is about to start clinical trials, hopefully leading to certificate for medical use.
I'd just like to leave a note of thanks to Paul and Mr Contrarian who first highlighted Games Workshop (LON:GAW) to me in 2017, when it was £22 a share. It touched £104 at the open today, so far too big to be a small-cap these days. Just shows what can happen when you find a good one. What a fantastic resource Stockopedia is, and especially the SCVR. Thanks again Paul!
Hi bluecurve,
I remember that MrC flagged Games Workshop (LON:GAW) to me at just £8 per share. I agreed it was good value, and bought some. Sold them at about £10 a few months later, when nothing much seemed to be happening LOL!
It wasn't obvious from the figures that it would go on to be a multibagger at the time. It needed a proper understanding of the products & upside potential from the new games & characters it was developing.
Never mind, there are always "ones that get away"!
Glad it worked out better for you :-)
Regards, Paul.
I beat that! Bought at £4.60 and sold around £6. What an opportunity missed.
Hi Paul, I don’t think you’ve covered Mirriad Advertising (LON:MIRI) before but I think this is the sort of stock that would appeal to you. Their ground breaking tech enables ads to be inserted into video content post production. The Algorithms and AI enable advertising opportunities within videos to be identified automatically. Market research indicates they generate superior returns for brands.
HY results this morning show good momentum despite the difficult advertising backdrop. Their financial characteristics, business model and operating momentum look attractive. Gross Profit margins 90%, relatively fixed cost base and rapidly growing sales. Together this translates to shrinking cash burn - £825k first four months of the year, £700k in May/June and down to £550k in July/August. Total cash at end August was £13.3m, so a decent runway.
Majority of sales currently come from their contract with Tencent which is expected to annualise revenues of $2m this year. The US ad market is so much bigger though and they are in advanced discussions with the major streaming platforms. It sounds like Covid had slowed progress but that these negotiations are now back on track. If you believe the twin pulls that these streamers need ad revenue without the adverts and that the Kantor data shows the effectiveness of the platform to brands then multiple deals makes sense for all concerned. And each is likely to a multiple of the Tencent deal given the respective size of the ad markets.
Clearly a stock not without risk, but rewards could be quite large if they crack the US.
They are presenting at a webinar for PI’s next Monday at 12. Register here
Thanks @Yellowstone Advisory. £miri was VC owned for many years. Oxford Tech VCT 4 had a significant stake but were eventually diluted. The proposition seems an obvious winner so why hasn't it already taken off and with this in mind why it will take off now?
The description below from the Oxford Tech VCT 4 website is a lot of "could" and "can" and not a lot of "do"!
"MirriAd was spun out from another Oxford Technology 4 VCT investee, Imagineer Systems, in 2006. In May 2015 MirriAd's assets were purchased by Broadwall Acquisitions Ltd, subsequently renamed MirriAd Advertising Ltd. OT4 recieved shares in MirriAd Advertising as part of the acquisition. Mirriad Advertising listed on AIM in December 2017 and OT4 received shares in Mirriad Advertising Plc.
MirriAd is able to deliver Embedded Advertising into video streams, ranging from user generated content, such as on YouTube and MySpace, to studio and broadcast quality productions, such as Casino Royale or Pop Idol. This capability allows real time ‘In-Video Advertising’, where branded products for instance, Coke cans, advertising hoardings, or even cars can be placed into video streams, appearing to the viewer as if they were there on the original film set. This means, for example, television game shows could be regionalised by inserting different branded products into multiple variations of a single show for example, Pepsi into one version of Pop Idol, for broadcast in the US, and 7 Up into another, for transmission in Europe. Popular clips on YouTube could be monetised by inserting branded objects or images into the background with the particular brand automatically selected according to the demographic of the individual downloader."
Overcoming this perception is Yellowstone's big task!
I'd need to look more closely but this sounds very similar to Sky's Adsmart product which I imagine Comcast are now touting in the US. If I am correct then the product is not unique which perhaps is why the price is not doing very much,
Hi Robert,
Sky Adsmart supplies a traditional advert based your subscriber information. Mirriad Advertising (LON:MIRI) uses software to identify where to place an advert, ie a bill boarding the actual video, so creating a digital image inside the programme. Sky's solution is quite quaint almost :) If it works seamlessly brilliant tech.
A one minute video on the homepage here.... https://www.mirriad.com
id never heard of them but they look interesting. Bidstack (LON:BIDS) do something similar for video games but they have never really taken off, I dont know why, great idea, maybe the big gaming companies want to do it themselves.
Thanks. I stand happily corrected.
That was exactly my thought when I looked at Bidstack a while back - if you for example have a billboard in a game that shows a coca-cola advert, you have a piece of code to display that advert. it's the simplest thing to make that code interactive, so you can switch the ad to pepsi if coke won't pay the royalties. - Why pay someone to do that for you? They say "stick to the knitting" but that is imho part of the knitting!
There might be more scope for such an offering with films (if they are not heavily CGI already) but I seem to recall that there is another listed company in this space as well as Mirriad Advertising (LON:MIRI) . Anyone remember who?
You're right Richard its certainly taken a lot longer than a lot of people hoped to commercialise. You could say that about a lot of new technologies . There is much clearer appetite now for the Mirriad offering from all concerned: broadcasters, ad agencies and brands which should help to make the difference now.
Team17's results are absolutely outstanding. But was it ever in doubt? It's a model quality company with an awesome boss at the helm.
Are you the boss...?
haha no way I just really admire how this company is ran. Its balance sheet. Its IP (economic moat). Its growth with acquisitions etc. It really is a model company.
Agreed. I'm a big fan. And there in lies the danger. I still want to be objective but they just keep on producing stunning results!
I doubt it. But but his performance in "Get him to the Greek" in 2010 was outstanding.
Yes very good results BUT this is a highly valued company with market cap' at £981M and only makes circa £13M for this half.....so there needs to be a lot of growth to maintain this high valuation. I hold currently and have done well from this stock for the last 2 years but suspect I will be reducing my stake over the next 6 months as there is a lot of risk in the valuation.
can definitely see your point but time and time again this company powers through it. Increases its IP and digital content. 8x% of revenue came from back dated titles. With loads in the pipeline. Combined with PS5 & New Xbox released this year with COVID keeping people in it's going to be a bumper year for TM17.
Trading at 51 times versus last years earnings. PEG is over 2 at current growth rate of 25% increase in earnings per the interims. Great company but does not look great value at these levels.