Small Cap Value Report (Thu 12 May 2022) - BLV, JD., CNC, CCT, SDRY, EMR

Good morning! It's Paul & Jack with you today.
Agenda -
Paul's Section:
Belvoir (LON:BLV) announces it will be attending Mello in Chiswick on 25 May. Do come along too!
JD Sports Fashion (LON:JD.) - a mid-cap, but interesting because its trading update today mentions supply chains improving.
Concurrent Technologies (LON:CNC) - good results for 2021, blunted by an increased tax charge. Fantastic balance sheet, very strong indeed. Component shortages seem likely to delay product deliveries, impacting H1 2022 results. Overall therefore, I'm happy to sit on the sidelines.
Superdry (LON:SDRY) - (I hold) a not very helpful trading update, but I found the IMC webinar this morning much more informative. It sounds like the company is near enough to market expectations, so no profit warning. Subjectively, I discuss the reasons why I think the turnaround here could be working. Obviously macro headwinds are a sector-wide worry.
Quick comments (no sections below) -
Empresaria (LON:EMR) (I hold) - Unchanged at 69p - mkt cap £34m
A solid update today for FY 12/2022 today -
The Group has had an encouraging start to 2022, continuing the progress made in 2021 by delivering strong growth in net fee income. The Group remains on track to meet market expectations for the full year.
Singers has 8.8p forecast EPS for this year, so that’s a PER of 7.8 - cheap, but the whole sector has sold off (again) recently.
I think we tend to prefer Robert Walters (LON:RWA) and SThree (LON:STEM) here at the SCVR. But EMR is also worth considering - performing well, and cheap.
Jack's section:
Character (LON:CCT) - revenue up 22% but the mix (more FOB and US sales) means gross margin has fallen. Profit is down year on year but is up if you strip out last year’s property sale. The company is buying back stock and paying out dividends, so it has its attractions for investors, but there are also a few headwinds in the short term.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Belvoir (LON:BLV)
241p
Market cap £90m
Presenting at Mello 2022 Investor Conference
This is a non-regulatory (“RNS Reach”) announcement, which I want to flag -
Belvoir Group PLC (AIM: BLV), a leading UK property franchise and financial services Group, is pleased to announce that the Company will be presenting and exhibiting at the Mello2022 Investor Conference on Wednesday, 25 May 2022. Dorian Gonsalves, CEO, will be presenting to delegates.
The event will take place at Clayton Hotel Chiswick, Chiswick High Road, London W4 5RY. For further information on the Mello2022 conference, please visit the event website: https://melloevents.com/mello2022/
The Company is committed to ensuring that there are appropriate communication structures for all of its shareholder base so that its strategy, business model and performance are clearly available and understood.
David and the team at Mello have taken a risk, in organising a live physical investor event, following a long gap due to the pandemic. Tickets are selling well, David tells me, but he is finding reluctance from some companies to attend, because they prefer doing online presentations.
Online webinars are fantastic, and long may they continue, but there’s no substitute for meeting management in person, and have a live presentation, and face-to-face Q&A.
I’m looking forward to meeting Belvoir’s management in person for the first time. I’ve really admired the way this lettings business has steadily grown, improved its finances, and demonstrated resilience in downturns. BLV shares have held up very well in the current bear market.
We're hoping to meet some SCVR readers at Mello too - even people who are occasionally prickly in the comments sections here, are always absolutely charming in real life. Something strange can happen when we get behind a keyboard! (guilty as charged).
Anyway, at every previous Mello I’ve met some lovely people from all backgrounds, which is the nice thing about investing - nobody cares who you are, or where you’re from, the only thing that matters is whether you come up with good investment ideas!
We definitely need more women to get involved in investing too. Investing shouldn’t just be a boys club.
.
.
JD Sports Fashion (LON:JD.)
119.4p
Mkt cap £6.1bn
Trading update, interesting for possible read-across to other retailers & re supply chains more generally.
14 weeks to 7 May 2022 - FY 1/2023 - trading well. “At least” in line with expectations.
Profit guidance is £940m, at least equal to last year.
Like-for-like sales (LFL) up >5%.
Global supply chains expected to improve gradually this year (important point!).
My opinion - JD's share price has halved this year. That seems bonkers to me. The fwd PER is now only 10.1, which is irresistible, so I’ll buy a few. The fundamental value of the business has not halved, has it? Even if demand softens due to cost of living squeeze, that’s a temporary factor, so we’re being given an opportunity to buy a great business at a bargain price, in my view.
Bombed out retail shares are looking increasingly interesting to value investors. Remember that supply chain & expensive freight really kicked in last autumn. Hence we're coming up to annualising those problems, with companies having taken action to get stock in earlier, freight rates coming down, etc. So I think we could see less supply chain disruption as this year progresses, who knows? These factors could soften the blow from consumer spending coming under pressure.
.
Concurrent Technologies (LON:CNC)
76p (down c.12% at 08:55)
Market cap £56m
It seems very late to be publishing 2021 results.
There was a reassuring trading update on 5 Jan 2022, which said -
Based on its unaudited management accounts for 2021, the Company expects to report revenues and profitability slightly ahead of market expectations despite the ongoing challenges that the worldwide component supply chain is experiencing.
Whilst the component issues are ongoing, the Company enters 2022 with a robust order book and an exciting pipeline of innovative product releases to grow our customer base and revenues in 2022 and beyond…. [RNS from 5 Jan 2022]
FY 12/2021 Results
Concurrent Technologies Plc (AIM: CNC), a world leading specialist in high-end embedded computer products for critical applications, announces results for the year to 31 December 2021.
Key numbers & my comments -
Revenue £20.5m (down 3% on LY), “slightly ahead of market expectations”
Profit before tax up 22% to £3.5m - note the decent profit margin of 17%
EPS up 3.5% to 3.88p - PER of 19.6, at 76p per share
Dividend flat at 2.55p (yield of 3.4%, not bad)
Cash pile of £11.8m - impressive
New CEO & management
Restricted supply of components - particularly affecting the IT sector at present
Outlook - a bit mixed -
Outlook
· The Group is targeting eight new product releases in 2022. Delivery on this objective has begun, with a Position, Navigation and Timing plug in card announced in January 2022 and a 100 Gigabit Ethernet Processor Plug in Card announced in February 2022, simultaneously with the new Intel chip on which it is based.
· Strong bookings with order book increased to £16.2m as 31 March 2022 from £13.2m at 31 December 2021.
· Component shortage represents challenge to ship product in 2022, particularly in H1 with order delivery expected to be delayed and revenues recognised over a longer period than during normal market conditions….
"Despite growing demand for our products and an increased order book, we do expect short-term supply challenges will result in delivery of it being more protracted than is normal for the Group.
However, we are robustly managing this issue and have a very strong balance sheet and so, rather than damage the business through cost cutting exercises, we will focus on continuing to grow the order book and on creating an even stronger business capable of taking advantage of a number of identified, exciting prospects. We are already seeing increased market interest in our renewed product portfolio, and I am confident in our mid-to-long term profitable growth."
That last point seems to be indicating that H1 figures are not likely to be good, which puts me off buying the shares now, because the stock market is so short-term focused at the moment, and is punishing companies twice - in advance, with a mark down on caution, then again when the expected negative impact on results comes out.
Taxation - note that a much higher tax charge vs LY (£638k vs £98k) is the reason why EPS only grew 3.5%, when PBT rose 22%.
Balance sheet - very strong. There’s a big surplus in working capital, with current assets of £21.6m (includes £11.8m cash), and current liabilities of only £4.2m. Hence the company is bulletproof, and has scope to do something with the cash pile - e.g. an acquisition, or a special divi. I’d like to know what new management plan to do with the cash, instead of just sitting on it. Although with interest rates now moving up, at least the company should be able to generate c.£200k p.a. in interest receivable, something we’ve not seen for many years!
Cashflow statement - note that £2.1m of development costs was capitalised, hence rendering EBITDA meaningless. Working capital increased, absorbing about £1.2m in cash. The other big item is £1.9m in dividends paid (in both 2021 and 2020). The cash pile barely changed, so the group’s cash generation was effectively all paid out to shareholders in 2021.
Note 2 - re auditing 2021 accounts. I don’t know what this means, but it sounds worrying, so I need clarification of this point -
The auditors have reported on 2021 accounts; their report includes a disclaimer of opinion
I’ve googled this bit, and it’s positive -
… did not contain statements under section 498(2) or (3) of the Companies Act 2006.
Taken from the Companies Act -
Statements under those sections of the companies act are only required in these negative circumstances (below). Therefore their absence is a good thing -
(2) If the auditor is of the opinion—
(a) that adequate accounting records have not been kept, or that returns adequate for their audit have not been received from branches not visited by him, or
(b) that the company's individual accounts are not in agreement with the accounting records and returns, or
(c) in the case of a quoted company [F2or unquoted traded company], that the auditable part of its directors' remuneration report is not in agreement with the accounting records and returns, the auditor shall state that fact in his report.
(3) If the auditor fails to obtain all the information and explanations which, to the best of his knowledge and belief, are necessary for the purposes of his audit, he shall state that fact in his report.
[Source: https://www.legislation.gov.uk/ukpga/2006/46/section/498 ]
My opinion - sorry if this upsets the bulls here, but I can’t see anything particularly exciting about the business, or the valuation. A PER of nearly 20, when there are ongoing supply chain shortages, hence raised risk of a profit warning, strikes me as too high.
Long term holders might be happy to look through the supply chain issues, but personally it puts me off wanting to make a new purchase here. If the PER was say 10, then I would take the risk possibly, which would imply a target buy price of around 38p.
On the upside, I like the new CEO’s plan to accelerate new product launches, the strong order book appeals, and there could be upside from the cash pile being used to do something that releases shareholder value.
Overall, it’s not cheap, so doesn’t interest me at this stage, although the business looks quite good, and we’ll keep an eye on how things progress. Once the supply chain issues are smoothing out, then I can see this share could do well, with strong demand, and new product launches happening.
.
Superdry (LON:SDRY) (I hold)
149p (down c.4% at 09:41)
Market cap £123m
This relates to FY 4/2022.
SDRY trading updates are frustrating, because they contain probably too much detail on sales, with complicated tables, but no indication is given on what we actually need to know - which is whether the company is trading (i.e. profitability) above, in line with, or below market expectations (with a footnote saying what expectations are). That information is completely ignored, so how on earth are private investors meant to judge how the company is performing?! It’s ridiculous really, and I’ve already lodged a complaint with the company, via the InvestorMeetCompany platform, where there’s been a really interesting webinar, that it needs to simplify its trading updates, and focus primarily on profit vs expectations.
Performing in line? I didn’t quite catch the wording, but the CFO gave the impression in the webinar a moment ago that trading is broadly in line, but in a different shape - i.e. lower sales, but higher gross margin, due to focusing on full price sales. Hence no profit warning, which has to be seen as a positive right now, and especially with the share price so bombed out.
Looking at the various sales channels, and trying to make sense of today’s update -
Sales by channel for FY 4/2022 -
Stores (220 run by the company) - £224.5m revenues, 37% of total group revenues. Up very strongly (+60%) on LY, but down 22% on largely pre-pandemic FY 4/2020. The CFO indicated they’re expecting continued, gradual improvement in store sales, settling at 10% below pre-pandemic levels. This is OK, because the company is securing large rent reductions averaging 50% (70 sites done already, 70 more being done in next year, so that will be about two thirds of the store portfolio on 50% lower rents) - a big cost-saving, that was heavily emphasised in the webinar today.
New store fit-outs, and layouts for product, have been very successful, so this will be rolled out, but capex limited in next 2 years.
Gross margin in stores - dramatically improved, up 590bps for the year (or possibly Q4, it’s not clear which). This is key to the strategy - moving from permanently discounting, to getting the product designs right, and only selling for full price.
eCommerce - revenues £155.7m for FY 4/2022, 26% of total revenues - hence an important channel. It’s a concern that this fell 23% vs LY, and is only slightly ahead (3%) of the pre-pandemic year.
Reasons given for this poor eCommerce performance are - some sales moved back into the physical stores, as they re-opened. Prior year growth came from lockdowns and discounting online, which has now been curtailed. Although a quick look at SDRY website shows that there’s still plenty of discounted product, at up to 50% off, but it’s not given prominence, instead being under a separate heading “Outlet”.
The webinar heavily emphasised improvements to the online offering as it transitions imminently to a new platform called “Micro services”. This is supposed to be more flexible, and will enable SDRY to catch up with the competition, doing things that are proven to work, which the current platform can’t do.
Therefore, the reality seems to be that SDRY’s existing online offering hasn’t been good enough, but they’re putting that right shortly. So hopefully we might see online growth resuming?
Wholesale - revenues £226.3m (37% of group total) - so another very important channel. Obviously wholesaling is lower gross margin, but with much lower operational costs for SDRY. I think this would also include the sales going to franchise partners, operating 475 sites in over 50 countries.
This channel saw revenues up 6% vs LY, but is still 15% below pre-pandemic levels.
Debt/liquidity - frustratingly, nothing is said about this in today’s update. Information that was provided in the year end update last year. Do they think it doesn’t matter, or are they hiding bad news? We’ll have to wait for the full accounts to be published, but when important information is omitted, it naturally makes some investors wary, especially in a bear market when people are in paranoid mode, and seeing the glass half empty.
Outlook - fairly generic stuff really -
“We continue to execute our strategy of returning the Superdry brand to a premium position and I am excited by the progress we are making. Despite the ongoing tough trading conditions and turmoil in the market, our focus on full price trading will deliver a strong gross margin improvement for FY22.
We are conscious of the cost-of-living pressures on consumers, meaning that now, more than ever, we must continue to deliver product that stands for what is important to them: quality, style and sustainability at great value.
As we head into FY23 we remain cautious on the macroeconomic outlook and the impact of inflation but are confident that our strategy is positioning the brand for future success.”
I would love to sit down with management, and explain to them what investors need to be told in trading updates, as they’re missing the mark at the moment. But the openness in the webinars is great, and I think management enjoy talking directly to investors on webinars. It gives a great feel for the people behind the business too. In particular I like Julian Dunkerton a lot, he reminds me a bit of my old boss at Pilot in the 1990s - full of energy & flair, and very focused. That type of leader tends to motivate the people around them very well, and I sense that’s the case at SDRY.
Key points from the webinar Q&A -
Dividends? Dunkerton: Not on the table. I want to build up a cash pile before divis are paid.
Where are you with turnaround progress? Dunkerton: pandemic put a brake on things. Just at the start I’d say, lots of positive things happening now (e.g. micro services launch - new web platform). Building the brand again, we’re at an inflexion point. So much opportunity everywhere - esp. USA, but also Germany, and China. This will be a big, international business in future. Targeting a broad range of customers now (i.e. not just yoof - my description not his!)
Has customer behaviour changed re cost of living squeeze? It’s too early to say.
Inflation? It’s being managed. Some prices rising “slightly” this autumn, more for spring 2023. We remain the best value brand out there (really?! I don’t agree! But I think he’s comparing SDRY product with fashion brands, as opposed to normal retailers, which are much cheaper in some cases).
What do you think about the bombed out share price? (sighs) it’s sector-wide, and macro worries are weighing on it, we can’t control share price. We just have to accept this, I don’t worry too much about external events. I’m a long-term investor, and we’re feeling really positive here.
Why is Singers forecast showing negative cashflow? CFO - we think Singers are wrong! Need to go through the figures with the analyst to see why his model is giving this result.
My opinion - I need to see the full figures, as there are gaps in today’s update.
Also bear in mind that Dunkerton is always super-bullish on everything! It’s great to have that enthusiasm & dynamism, and lots of areas within the business are clearly being improved.
I’ve already dipped my toe in, with a small initial purchase, which I subsequently added to, averaging down. Not that it matters, but my average buy price is about 170p. It’s now 146p, which looks attractive to me.
Above all, I think Dunkerton is hugely motivated to turn this thing around, being the founder, and having run the business for many years, then inexplicably handing it over to the clueless Euan Sutherland. Why put someone who knows nothing about brands, fashion & retail, in charge? He did a lot of damage I think, but that’s being put right. So I’m a cheerful member of Team Dunkerton, I think he’s doing the right things, but you never really know as an outsider.
I have no idea what the share price likely to do, but today’s update & webinar give me a generally positive feeling, that the business seems to be under control, and mgt are doing the right things.
Obviously we know about the disposable income squeeze, and inflation, that’s why the share price has collapsed already. The big question is whether profitability can be restored, against such headwinds.
It seems to me this is a lot of business for a market cap of £123m. If things work out well, then we could be on to a multibagger. The downside risk has reduced, because physical stores are now only 37% of total revenues, and the big fixed cost (rent) is falling by 50% as leases re renegotiated, a big cost saving. Other parts of the business (online and wholesale) have lower fixed costs, so there’s downside protection there compared with other retailers.
Overall, I think risk:reward could be attractive with SDRY shares, as the turnaround develops. In the short-term though, anyone buying now needs to have a strong constitution, as it’s entirely possible the share price could continue in a downtrend. I don’t know what the future holds, as always investing is educated guesswork!
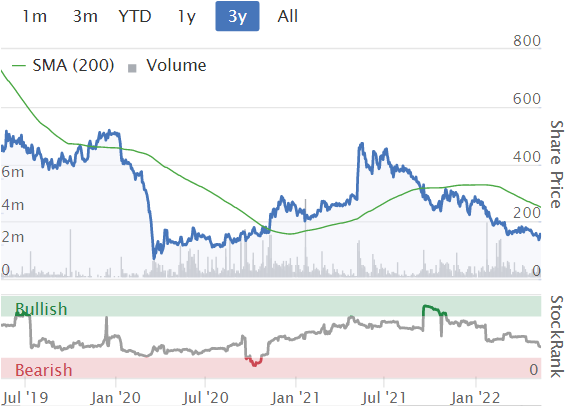
If I can get more confident about the turnaround, and the macro picture, then I could see this share becoming one of my top positions. I’m not sure if that’s a good thing. As one friend recently quipped to me, rather unkindly I thought, but during an argument, “Given how badly you’re doing at the moment, every time you get an urge to do something in the markets, then just do the opposite!” He’s got a point, to be fair.
.
.
Character (LON:CCT)
Share price: 594 (+2.06%)
Shares in issue: 19,300,352
Market cap: £114.6m
Half-Yearly Report for the six months to 28 February 2022
Character designs, develops and distributes of toys. It appears be a well managed small cap, but there have been a couple of setbacks and currently there are some headwinds.

Results:
- Revenue +22% to £90.9m,
- Operating profit before highlighted items +6.6% to £6.5m,
- Diluted earnings per share +7.4%,
- Cash and equivalents down from £34.9m to £21.5m following £13.6m share buyback.
Statutory profit has fallen year-on-year due to last year’s £2.02m sale of property, but is up if you strip that out.
Like many others across the industry, we also continue to experience inbound shipping delays and other operational adversities due to continuing COVID-19 concerns, particularly in China. Despite these challenges, we expect the profit before tax and highlighted items for the full financial year ending 31 August 2022 to be in line with market expectations.
Character and others that operate along similar lines find themselves in a difficult operational environment right now.
Although the majority of countries where we sell or distribute our products relaxed or even eliminated COVID-19 restrictions, the strict controls applied in China, where almost all of the Group's manufacturing takes place, resulted in delays in production at factories and shipping exports to our global markets. Consequently, this led to extended lead times, uncertainty over delivery dates and significant cost increases. In the UK, the shortage of HGV driver capacity and delays at ports added to the convolutions that all these factors have presented to the business.
Quite a few headwinds, but these results are therefore reassuring. There is scope for supply chain lead times and HGV driver shortages to worsen though.
Revenue is up c22% thanks to a strong performance from FOB sales (freight on board), although this mix has negatively impacted gross margin, which has fallen from 29.2% to 24.8%. Cost increases in the Far East have also affected margin.
Balance sheet - is good, with net assets at 28 February 2022 of £35.2m after a share buyback of £13.6m. That’s substantial. There is no debt and cash of £21.5m, along with £50m of headroom in its banking facilities.
Inventory is materially higher (up from £9.1m to £17.9m) after difficulties in meeting demand in the run up to Christmas
Outlook
As we indicated earlier in this report, the momentum seen in sales in the first half is continuing, particularly in the strong performance from our international FOB business. We remain mindful, however, of the current difficult macro-economic conditions and the recent weakness of Sterling.
Conclusion
Character looks like it is on course to meet full year expectations (underlying profit before tax of £11.3m) assuming trading conditions do not worsen. But that is not certain.
It’s quite possible that material and labour costs continue to increase and, while US and FOB sales are driving growth, these are lower margin. The dividend history here is interesting - a business that looks to return cash to shareholders, but this has stopped or reduced at several points.

As such, I don’t think it warrants a particularly high valuation multiple and there are headwinds, but there are also signs of a well managed business.
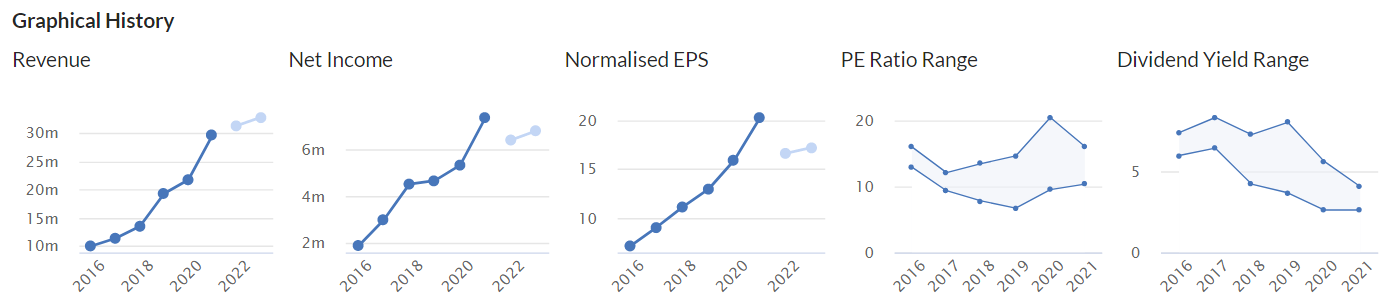
Management does tend to maintain a net cash position, and shares in issue have come down over time. Unfortunately, this chart does not capture the most recent buyback, which sees shares in issue fall to 19.3m.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Can I ask a general question ?
Why are Stockos share price information so behind the market ?
How do you mean? Stocko prices are usually 20 minutes behind, sometimes more, the other morning was over 30 minutes before yesterday's prices were updated.
Exactly . Wonder why .
Real time pricing is expensive and as Stocko is not a trading platform and I guess they don't consider it worthwhile. However, and amazingly, Google finance, which allows you to set up any number of lists of shares, is as near real time as you can get for FREE.
HL and IGG are free and live prices but need to register and sign in. Stockopedia prices are misleading because they based on the last trade, which could be a buy or sell trade, I find this really annoying.
Yes it is because of cost which is understandable.
If you look at the CNN Fear Index it is currently at "Extreme Fear" rating and on a value of just 7 !
That matches the financial crash of 2008 and any subsequent event. On every occasion the fear index has gone to 9 or lower it has acted as a very strong contrarian buy signal with 100% success I believe.
Now I'm not dismissing current events or the prospect of continuing volatility but if anyone is looking for a chink of light the fear index is often one to watch.
Hallowed are the Ori - i believe in this one
And how many times has the fear index gone below 9?
£VTU
Just circling back to yesterday's SCVR and in particular Glen Keedy's comment,
Glen KeedyYesterday 10:25 am
Great results from Vertu Motors (LON:VTU) I believe car prices will be higher for longer than the market thinks so still more good news to come.
I agree that due to supply constraint, there will still be disruption to the supply chain of new vehicles - and more importantly so does Robert Forrester, CEO of Vertu. What this means in real terms is (at least) two fold for Vertu, 1. New cars don't need to be discounted, 2. Lack of supply of new vehicles supports second hand prices. This should help support gross margins in both cases.
Looking at broker forecasts, Liberum are forecasting £35M PBT for FY/E 2/23. Vertu are saying they have managed net profit of £19.1M for first two months of this financial year!! Yes March and April are traditionally strong months for car sale and of course increasing costs are going to play a part but Vertu have an excellent track record in managing those costs. Surely this PBT forecast is conservative at best?
In summary I agree with Paul that this company simply shouldn't be trading below NTAV (currently 66.8p p/share).
Hi NF&G,
With regards to Vertu Motors (LON:VTU) the risk for me is that the market simply dries up and total sales drops off and therefore they don't make the profit they forecast.
With the economy on such a shaky peg there will be millions of people who suddenly become fearful around the future prospects, maintaining their jobs and increasing costs related to inflation on everything we use.
The purchase of a new car will therefore drop very quickly down the priority list and people will "sweat" their current model.
I appreciate those on PCP's who have no option but to hand it back will need an alternative - a new replacement PCP at a much higher price or a more expensive 2nd hand model (also at a higher price). But the big unknown is the sweating of those people who own their cars outright.
Personally I have just cancelled an order for a new car as its delivery date remains unknown (not before Sep/Oct 22, having first ordered it in Oct 21). I've found a 2nd hand model instead and am now trying to offload my old car - I am sure I am losing out all over the place with higher 2nd hand prices and lower offers from the internet types like M/Way or We-Buy-AC.
Time will tell, but Vertu Motors (LON:VTU) seem quite cyclic to me and therefore I'll stay away for the present. I was previously in it but felt the long-term may not be as rosy as everyone kept saying.
Hi Kevin
Thanks for replying. Strangely enough, despite forecast doom and gloom everywhere there is a general shortage of labour, at present - there are literally thousands of vacancies in all sorts of industries/trades that remain unfilled at the moment, not usual for a recession, although of course technically we are not as yet in a recession. Indeed Robert Forrester CEO of Vertu was bemoaning the very fact as a major headache for them currently.
Secondly, Vertu have a very strong relationship with a number of vehicle manufacturers and have said that whilst the sourcing of new vehicles is improving it isn't back to 'normal' as yet, thereby enabling manufacturers to pass through price increases. Of course anyone keeping hold of existing vehicles will still need repairs, servicing and MOT's - most of which is more lucrative than actual vehicle sales in any event.
I take your point re new car sales - I am currently waiting a delivery date on an EV ordered late last year and as yet have no build/delivery date - very frustrating. From my experience I think there is enough pent up demand for new and nearly new vehicles for demand itself not to be the problem - I feel supply will still be the dominant issue for the next 6-12 months, thereby helping to support these 'bumper margins'.
Pistonheads is an excellent website to off-load your old car. Highly recommended.
Thanks Piers!
Volex (LON:VLX) dropping like a stone again, even after the very positive update last month. Now on a forward PE of sub 10. Unbelievable
Volex (VLX) Any thoughts on why JD, I’m also perplexed ?
China supply concerns, general smaller cap sell off, worsening economic outlook ?
I wonder if some of their products are too ‘commodity like’ and interchangeable for competitors’
Or is it a good time to top up ?
Hi John
I had sold Volex (LON:VLX) just before the results came out, and an obvious kicker watching them bounce back up to what would have been green again. This was manual stop loss (>10% down from purchase) and I had bought again because I felt they were a very good price.
Whilst I am not a "trader" I am trying to learn more about the whole chart approach currently, and when you look at Volex (LON:VLX) it is showing as a classic "Stage 4" now from some of the texts that I have been reading.
Ok for my simple mind there is a lot of this within the Smaller Caps world, and come to that Mid and Large Caps too, nothing materially changed about the company doing what it does, still making stuff, making a profit, buying more companies and all that. But for me personally right now (might have changed my mind again due to FOMO by 16:28) I am not trying to fight Ze (or pronoun of your choice) Market when the price is declining. You have to make your personal choice that either you are happy to ignore and figure in the long term it will be all right, or you cash in and draw up the list of companies you want to buy and some will be cheaper, some will be more expensive, but when you are comfortable you hit the button to start the buying.
Sometimes no matter what you personally thing, or the rationality of it all, the Ze Market goes against you... or with you just after you press the button so sell in my case
Tommy
Yep thanks Paul for flagging JD Sports Fashion (LON:JD.) Having a quick look at their previous updates this year in terms of pre tax profit and exceptional items, they were as follows: Jan £875m, Feb £900m and today it’s now increased further to £940m. Could the variances be down to accountancy “tweaks” hence the delay in the final results?
I note analysts consensus in Jan was £810m, a 16% uplift is a significant beat is it not but they are are saying it’s “in line” with their expectations, presume analysts are behind the curve on this one?.
Interested what people think. Why is it that women don't seem very interested in investing / the stock market?
As a female investor who has been to several Mello’s, I’ll reiterate Pauls comments on encouraging more women to attend
I’ve had a warm welcome and found my fellow investors (of both genders) to be knowledgeable and keen to chat shares. The presentations and speakers are excellent with the majority of companies being profitable (or close to). In particular, it’s an excellent opportunity to meet some pin ups of the investing world over a beer or gin & tonic, including our very own Paul so do please consider coming
*and mines a gin & FeverTree thanks Paul
Pink gin is the best gin.
Agree with the physical presence. Zoom is great but sometimes you want to know if someone acts or looks dodgy when they answer questions. Harder to do via video!
Michael, I totally disagree with you. (But that's ok no hard feelings I hope.) I spent some years travelling all over Europe and the Middle East having meetings and in my mind unless you want to put them in a headlock and force them to sign on the dotted line, I can see no disadvantages at all to a Zoom meeting over a physical meeting. Oh except of course I got to stay in some nice hotels.
No hard feelings! It's also possible I overestimate the value I think I find on physical.
That said, Mello is fun, so it would be a shame if companies didn't pay to attend.
I was worried you were going to disagree with me on the pink gin at first, as that would've been a problem.
Zoom is fine if there is a pre-existing relationship to build on.
Otherwise not.
Having said that I have noticed that younger people who grew up with facetime / zoom are pretty relaxed using that all the time and they often prefer online chat.
Personally I think it is a bit like a colourblind person not seeing the point of anything more that B&W tv.
My prior life was travelling around the world analysing and interviewing asset managers with a view to allocating significant sums to them sometimes inc seeding. Phone or zoom fine for some info but when a soft capability is involved (ie taking risk as individual and unit) the meat of assessment needs to be in person. What is not said, by whom and when is always the most important information...as is any other incoherence that can be observed of whatever sort. People always reveal most in what they don't do or say...or what they flinch at (which you don't see online). Also, observing power relationships tells you a lot...
...the receptionists have info and how they deal with you etc. I decided not to pursue a Brazilian investment any further after being met from the lift in Sao Paulo by two very large men with hands on weapons (not pointed at me thankfully). Turns out the macro fund manager I was meeting had a lot of land in the NW area ("personal account"...not client accounts)...where cartels had interests too....
Thanks Paul for the piece on JD Sports. Agree there is a lot of value in bombed out retailers, many having crashed around 50%. Petrel Resources (LON:PET) is another one that I've got my eye on - this one has the advantage of being somewhat less cyclical and would imagine more resilient in a downturn.
Sorry, I meant Pets at Home (LON:PETS) in my previous post!
On another tough day it's always nice to get the 'Dividend added to your account' email ( Somero Enterprises (LON:SOM) ).
Nice update today from H&T H & T (LON:HAT) (I hold). Pledge book strong, gold purchase, FX and jewellery sales all back to pre-pandemic levels. Improved digital strategy and modest increase in store numbers planned. Looking forward, the counter-cyclical nature of the business seems likely to provide some degree of insurance in turbulent markets and with a squeeze on incomes. They have confirmed their exit from short-term lending and their liabilities there have already been accounted for. Decent divi, undemanding p/e and well financed. I've got a full position but am still tempted to buy a few more.
I'd decided to buy Ramsdens James which also seems to be trading well, I agree about the counter-cyclical nature of these businesses.
Good morning Paul. Yesterday I posted a reference to Vertu Motors (LON:VTU) and your side-ways comment to Cinch (via the white teeth reference, I presume). I asked the following question yesterday of you and any other reader. I didn't get an answer, but I found my own by accident this morning by reading some thing on Citywire.
Yesterday's comment was this. Good morning Paul, and thanks for great write up on Vertu Motors (LON:VTU)
which seems really undervalued. On your comment on Cinch and white
teeth, I seem to remember that I saw that Cinch had bought around a 10%
share in one of the big ones like Vertu Motors (LON:VTU) and for the life of me I cant remember which! Do you or any readers have any idea. I also have Pendragon (LON:PDG) and Lookers (LON:LOOK) so may have been one of the three.
My answer this morning is this. Cinch bought into Looker.
'Artemis UK Select fund manager Ed Leggett says the mismatch between supply and demand in the car market is good for Lookers (LOOK). In a quarterly update on the fund, the Citywire AA-rated manager of the £1.3bn fund said Lookers’ shares had rallied after Constellation Automotive – the owner of Cinch, as well as We Buy Any Car and BCA – acquired a 20% stake in the group at a 45% premium to the prevailing share price.
‘The logic in gaining access to more used stock – in the form of trade-in vehicles – to feed the Cinch brand looks clear,’ said Leggett.
‘Furthermore, by buying a potential blocking stake it has significantly reduced the options for rival Cazoo to pursue a similar strategy.’
Do you or any other reader have any further comment about the interplay - current and likely future - between the new boys on the block like Cinch and the old guys like Vertu Motors (LON:VTU) and Lookers (LON:LOOK)? Have any of the new guys the muscle or likely desire to buy into the old, either separately or in a joint deal with a PE operator, in your or anyone else's humble opinion? Possibly attracted by the real estate you frequently mention on the balance sheets of the old guys? Sell and lease back, releasing a lot of funds for greater advertising etc to fund greater market penetration? Thanks as always to you and other readers for your comments.
Very interesting, thanks ridavies.
I wonder if the new online only car dealers have missed their chance? Looking at Cazoo, it listed via a SPAC at a laughable, bonkers high valuation. I tried to find a way of shorting it, but was unsuccessful. Pity, as the share price is now down almost 90% at only $1.21, having started at $10 in autumn 2021.
I reckon Cazoo probably goes to zero, as it has an unworkable business model, and spending like crazy on advertising, whilst selling cars for negligible gross profit.
Meanwhile the conventional car dealers are also offering exactly the same internet-only car buying service as an alternative, so Cinch/Cazoo and others haven't actually disrupted anything!
It could be nice upside for Vertu Motors (LON:VTU) and others, if we see the new entrants go bust, freeing up market share for the more canny, traditional operators like VTU.
Regards, Paul.
During the second lockdown I was wasting time browsing ebay and spotted a classified ad advertising a car I really liked and in normal times would have traveled to look at. The dealer was a very long established small family firm. I emailed saying I liked the car but could not get down to see it. We ended up speaking on the phone and I decided to buy the car. I paid by bank transfer and booked a car transporter to deliver the car. The transporter dropped the car on the driveway and put the keys through the letter box, all Covid safe.
My point is the Cazoos of the world are not doing anything different except perhaps i got more human contact from the seller end which a lot of customers appreciate. The dealer that supplied me was doing exactly what Cazzoo et al is doing and any other dealer even small independents can do.
I can see no barrier to entry and that means a flawed business model.
i
I did some work for BCA a while back and was amazed at the amount of online (unseen) transactions carried out. The ratings of cars is highly trusted by dealers and if BCA wanted to push it, could be Joe Public if wanted it that way. They absolutely dominate the B2B space and could raise barrier into B2C very easily. The only thing holding them back would be the damage to the B2B business if they started to eat the dealers lunch.
Just thinking that Cinch might be more successful than you expect Paul. I believe it is the B2C online portal for the old BCA Group who were taken private. Wasn't that by Constellation who have also taken a stake in Lookers?
Wish I'd kept the last BCA Annual Report as I think that is where I'm remembering it from. Should be some reference on the trading website too but I haven't checked. Will probably get a slew of car ads on my screen for the next 6 months if I do!
Agree on Cazoo. They are spending a lot of cash marketing to the horseracing fraternity at the moment too, including sponsoring the Derby/Oaks at Epsom next month. Reminds me of when Orange launched with a blitz including covering Wembley for an FA Cup final. Awareness campaigns can work of there is something in the product or service to support it. Like posters here I'm not sure the Moment of Truth delivers for Cazoo. At least not in an economical and sufficiently differentiated way.
Apologies somewhat OT
Crypto warning
Coinbase one of the largest listed (us) crypto wallet providers sunmitted the folowing information in one of their latest sec filings
“Because custodially held crypto assets may be considered to be the property of a bankruptcy estate, in the event of a bankruptcy, the crypto assets we hold in custody on behalf of our customers could be subject to bankruptcy proceedings and such customers could be treated as our general unsecured creditors,” the filing said.
So if you park your crypto with them your funds are not in any sort of seggregated account - note their prior earning releases alwasy showed "Customer custodial funds". If i was holding crypto i would at a minimum damn well be demanding that the bitcoin i had been in a seperate seggregated acount for very obvious reasons - now sure how the sec let them get away with this. Although if they have only just filed this info to the sec this may not be the end of the story - i simply cant see how they can be allowed to do such busines slong term without being forced to keep customer held funds "secure"
Note company is reasonably well capitalised - but they lost $430 mill dollars qe march and will probably lose more qe june unless bitcoin picks up . To me the risk here is more along the lines of cybertheft or insider fraud rather than the obvious one of simply running out of cash - presuming they arent the next northern rock (look up that one on google young uns) operationally speaking they should be able to dial down expenses if needs be.
Note in addition to the above the FCA has also explicitly warned if you invest in crypto even if that is with an FCA regulated firm you are not covered for crypto losses as you would be ifd you held your funds in an FCA regulated bank acount. Foir this reason any overseas firm could simply pocket uk investors cash whilst looking after non uk investors if thye so choose and did fall out with the uk regulator - i think some companies in this arena have already fallen out with uk regulator in which case there could be block put on future trading cash out possibilities.
We are talking about a Crypto app that does not even show position P&L to its customers (you can't tell whether you are up or down on a crypto holding!). Coinbase do not care about their customers, that much is evident!
WidsomTree Physical Gold ETF moved up this morning so if the crypto bubble is bursting gold may benefit? Caledonia Mining (LON:CMCL) noted earlier but I've never been able to pick small miners and been burnt often Centamin, Shanta etc etc.
Yes I find investing in individual gold miners far too risky and frankly don't have the specialist knowledge. I get my gold exposure through Golden Prospect Precious Metals (LON:GPM) which is an investment trust focusing on the sector. Good track record and trading at a c13% discount (has been wider, but could see this going to a premium if gold really comes back into favour).
I’m a recent investor in Golden Prospect Precious Metals (LON:GPM) and I’d just echo your comments- it’s a great way to get a spread of gold miners without the stress of trying to pick (and hold!) winners. Also it’s only one purchase fee as opposed to multiples.
min my research on them I thought the investment trust fee and payments to directors etc were on the high side, but as a 3-5 year investment I thought the benefits outweighed this.
I also picked up £GDX and £GDXJ, two etf’s that seem to be the standard miner etf’s that are referenced a lot.
Also i ran the holdings of all 3 through stockopedia UK, US and Australia to get a handle on the stockopedia metrics for all company’s in those jurisdictions and was happy with the results. (I subscribed to US and Australia just for this purpose). This covered most company’s, the major exception being the Canadians.
Hi
Golden Prospect Precious Metals (LON:GPM)
Used in the past for gold exposure. Problem is that at the moment the market seems to have gone seriously off gold/silver miners - monoliths Newmont and Barrick both off @4.5% and GDXJ off over 5% as I type -following and more the drop in the gold price. Since mid-April this seem to have been the story.
Which is a pity since I like Goldies.
Phil
We are recent holders of Concurrent Technology. The results seem satisfactory with cautious statements on supplying an increased order book on time due to supply line difficulties. Paul or Jack -- your comments on the results and explained (minor) qualification on the accounts would be much appreciated. I'm tempted to increase our holding.
I think there is one more negative(ish) trading statement to come from Concurrent (as highlighted by the CEO), and providing he puts his money where his mouth is, there is real upside from there. It looks oversold to me, so I just bought a second stake (75p). I am looking to buy a third stake sometime in the future....perhaps after the next set of results.....depends where the market goes next 6 months.
I like the fact this seems to be going more defence based, he has bought in a number of ex QQ. guys in, and he has a long track record in defence...so I think there is real growth potential.
Likewise just increased my stake this morning. Interesting comment on the dividend. Sounds like the Company may be looking to reduce in future to free up capital for further R&D/M&A? Personally I wouldnt have an issue with this.
Thanks Paul, we'll be topping up too. I'm bearish on market direction so expecting further falls in many shares, and opportunities. I should mention my stockbroker in the eighties used to say "You're a good barometer for doing the opposite to your decisions!" He's still a friend.
Hi JASVFS & Camtab,
OK, I'll take a look at Concurrent Technologies (LON:CNC) next.
Regards, Paul.
I posted yesterday evening that £NXR had announced a major acquisition (EV £80Mn, 2021 EBITDA £10Mn) of a highly related bathroom UK panel maker Grant Westfield (brand Multipanel) - although I missed mentioning the additional potential £12mn performance element. This was part-funded by a placement of £18Mn.
The deal offers further scale in a specific niche (bathrooms), entry into new growing markets with a leading brand, access to new customers and further dilutes the historic pension overhang. No doubt over time, genuine cross selling and expansion opportunities through the Norcross network can be found. In short it looks exactly like the sort of medium sized deal I hoped they would make from their position of increasing financial strength. Nothing is certain but a way above average chance, it will bed in well like other recent acquisitions.
Today, we learn the Placing was done at 230p - roughly the market price yesterday so no dilution. Mgt have a pretty simple plan and are steadily executing it. Bit dull but it has been nicely rewarding over several years - a lesson to re-learn. Very tempting to bank some more cash and wait 2 years but I have been burnt by over-concentration previously.
The key risk I see for £NXR these days is a supply chain one with so much sourced from China. But even here they managed Covid related shortages well and the new business has a UK manufacturing footprint I read so they are acting even on this. South Africa is a permanent low level risk but they have good opportunities to grow there as well.
I'm surprised it's only up 3.5% this morning. I hold at the maximum position for me else I would buy more. Very tempting to bank some more cash here and wait 2 years but I have been burnt by over-concentration previously. How do others see the deal and risk for the company generally.
Norcros (LON:NXR)
Very tempting to bank some more cash and wait 2 years but I have been burnt by over-concentration previously.
I would agree this for plenty of reasons is probably not a share to recommend going overweight in - there are plenty of real risks here. It certainly is one my larger holding though i must admit , mostly due to me buying at lower levels than today. Ref rights issues if i see the price at which shares as being issued as below my intrinsic valuation i am much more likely to participate that is the case here - i highly suspect my thought process here is highly biased as there is an element of me not wanting to look back in 12 months time and miss out on the potential gains that those that have been brave enough to stump up cash for will get if share is well back above £3
I'm surprised it's only up 3.5% this morning. I hold at the maximum position for me else I would buy more.
I think as fans of the buisness we are probably somewhat biased - they are paying 8 * ebitda so they are buying a busines that aint exactly cheap in the current enviroment - when you compare profits being made and curent valuation of the two businesses its clear the company they are buying is more highly rated by them - as norcos has miserly rating at present the paper they are issuing is actually quite expensive - i am happy though that at present cashflow is so sound that overall the useage of the available finance facility should see a good end result - that is probably 4 surplus years cashflow(+) acounted for though on the downside to get back to where they are now - and thats presuming profits dont drop off a cliff and that new unit does provide double digit earnings growth as promised.
So i perhaps do see then argument this is not as great an acquisition as it might have been had dilution been less (shareprice not depressed) and or p/e being paid had been less (harder bargain driven) - i would say its more important that they get the right brand/business than anything so if good aint cheap and it still adds up that is stil the right thing to do.
As ever with uncertainty the market is probably saying yesterday without this risk at present may have been a place i would rather have been.
Absolutely agree it would have been better if £NXR 's deal was concluded 3months ago.......although would multiple then have been 10? The frustrating thing as an outside small investor is you only get glimpses of the financials....and these are themselves only a presentation by the selling company.
Ultimately, we need to trust/not trust Mgt and vote on strategy/direction of travel which is why I am happy. This seems like a decent UK business in a closely related area - not a bigger jump to a Middle Eastern toilet bowl manufacturer or Chinese kitchen accessories maker.
And at least I can act at same price as the people in the Placing by buying (or selling) on the market at the same price. As ever, time will tell.
Re £NXR - Just seen much more detail on the acquisition on the website https://www.norcros.com/files/...
Be interested in your thoughts on Concurrent Technology CNC Paul. Results out today. Static in terms of profits and dividends. But talk of new products and opportunity for growth. Issues with components. Feels to me a 12% drop is overdone.
I know the resource sector is not typically covered here, but if anyone is interested in a gold producer with a decent dividend stream Caledonia Mining (LON:CMCL) provided a nice update this morning:
"Financial Highlights
· Gross revenues of $35.1 million (Q1 2021: $25.7 million). Higher revenues reflect a 40 per cent increase in production and a six per cent increase in the realised gold price. Revenues include the sale proceeds of 442 ounces (net) of gold in work-in-progress.
· EBITDA of $14.6 million (Q1 2021: $9.7 million).
· On-mine cost[1] of $698 per ounce (Q1 2021: $836 per ounce). Lower cost per ounce was primarily due to higher production, which means that fixed costs are spread across more ounces, improved grade and reduced use of diesel generators.
· All-in sustaining cost1 of $968 per ounce (Q1 2021: $1,044 per ounce).
· Adjusted earnings per share1 of 62.5 cents (Q1 2021: 51.6 cents).
· Net cash from operating activities of $10.2 million (Q1 2021: $2.0 million).
· Net cash and cash equivalents of $14.4 million (Q1 2021: $13.0 million).
· Dividend paid in the Quarter of 14 cents per share, a 27 per cent increase from 11 cents per share paid in Q1 2021. The quarterly dividend has been maintained since October 2021."
https://www.investegate.co.uk/...
Given the jurisdiction etc it is probably the antithesis of your typical "widows and orphans" stock, but I have held this for several years and the management have always delivered. With the newly commissioned central shaft, the economics should continue improving I think and as such am happy to continue holding Caledonia Mining (LON:CMCL) as part of a diversified portfolio.
Norcros (LON:NXR)
Ok Norcros have gone on on a spending spree again - the size of the acquisition is a biggie at £80 mill (+£12 mill add ons).
Norcross have pretty much paid down their debt - per latest prior update they had £7 mill net cash and £130 mill unused finance facility in place - so they were pretty much ready for this one. As with prior acquisitions there is a placing used to help fund a small % of the acquisition - timing is great here but one would "hope" that the value of the business they are acquiring hopefully "reflects current market sentiment" - it may not though if price was agreed and they felt duty bound to proceed (who knows?)
8.1 mil new shares issued (roughly at market price so current owners can simply top if if no upward spike today) - dilution looks it was done at pretty much close to straight 10%.
They have paid 8 times adjusted EBITDA for purchase (£10 mill 24% margin)- hopefully very good scope for efficiency gains here , norcros have done very decent job of bedding in prior acquisitions so this should be safe pair of hands.
They expect acquisition will be double digit earnings enhancing - with most of the cost of purchase being funded by "borrowings" we would damn well want to hope that the acquisition would want to be at least double digit earnings enhancing.
Ref return on capital - that will be positive in year 1 - no idea practicably spekaing if that news is materially good or not bad or may be somewhat irrelevant?
All looks ok - the only thing that may annoy some is the dilution when the shares are well off the prior highs !! - in that regard i would take this acquisition rather than not take it in the whole. Seems a solid god margin business that should fit very nicely within their current brand portfolio. Think if the price is right i may be tempted to top up my holding by 10% here to keep my same % ownership of the pie ? pe at present was 6.3 before what should be decent uplifts ref "double digit earninsg increase". Note the trend in expected earnings has been nothing but good the last 12-18 months - although thats not to say anythinmg about what the next update will be , can;t argue some slowdown in their markets should be expected with material slowdown a possibility. Note the obvious extra risk here is there will be very chunky debt again short term - so they really need not to have huge recession in te next 24 months.
Morning guys, hope you're both well! Can you take a look at $MJH this morning please? Not sure its been looked at here before? I posted the below after interims at start of April, I think it potentially one to keep an eye on (once/if the current mkt turmoil ends!)
"If either of you have time, is it possible to circle back to Mj Hudson (LON:MJH) interim results from the 12th April as I don't believe they were covered?
I think it ticks a lot of boxes- growth markets (inc being an ESG play), increasing margins, long term sticky recurring revenue, broad customer base inc some blue chip clients with decent cross selling opportunities, potential expansion to US, high % of equity in m'ment hands (around 40%- they didn't sell down in the IPO)
I think the question is whether its now close to reaching an inflection point? The share price had almost halved prior to these interims on earnings upgrades and PDMR purchases (albeit small compared to overall holdings). I'm wondering if this is the start of an upturn in fortunes as acquisitions start to bear fruit and a slight change in business mix (towards faster growing, higher margin data&analytics) takes hold. Financials appear a little messy and contain various adjustments- struggling with the adjustment primarily related to deferred consideration fair value loss :) (and the distinction between statutory and net revenue) but potentially not far away from producing a clean set of figures?"
MJH was on Mello 21 Feb 2022 (1hr 08m 45 secs in). Questions at 1:31:44. Management consultancy, keen on acquisitions, niche area. I felt I would have to put a lot of work into it to understand it. As you say, financials feel messy.