Small Cap Value Report (Thu 12 Nov 2020) - SNWS, VLX, NWF, NXR, IDEA, TTG, CLG

Good morning! It's Paul & Jack here with the SCVR for Thursday.
Agenda - this is what has caught our eyes today;
Smiths News (LON:SNWS) - Jack covering its preliminary results (Jack holds, done)
Volex (LON:VLX) - Half year report (Paul holds) - webinar today at 11am on IMC platform (Paul holds, done)
Nwf (LON:NWF) - shares unsuspended, update on cyber-attack (Paul, done)
Norcros (LON:NXR) - Interims (Paul, done)
Ideagen (LON:IDEA) - Trading update (Paul, done)
Tt Electronics (LON:TTG) - Trading update (Paul, done)
Clipper Logistics (LON:CLG) - Trading update (Paul, done)
.
Timing - looks like it will be an all day job, as lots of interesting stuff to cover. Today's report is now finished.
.
NB. Jack writing this section
A changing of the guard or too soon to call?
This has been another defining week in the markets, with Monday’s vaccine announcement flipping 2020’s winners and losers more or less on its head. Is this a changing of the guard in terms of stock market performers or just a premature celebration set to fade?
I’m thinking about this carefully and am curious to hear what others make of recent developments from an investing perspective.
For a month or so now I’ve been looking for a bit more Value-Momentum - the idea being that we will at some point return to normal life (say on a two year view), and so those companies with bombed out share prices, promising strategies, strong management, and good upside potential might offer attractive risk:reward.
But cheap companies are never perfect and do tend to come with higher risk such as large pension funds, so DYOR. The below are not recommendations but might spark a bit of conversation.
I’ve held one Leisure stock through thick and thin: Fulham Shore (LON:FUL) . I did hold Marston's (LON:MARS) but sold on the spike up to 65p or so after the Carlsberg JV announcement. Now, with tangible (albeit preliminary) news of a vaccine I would buy back in if we saw some selling pressure there in the weeks ahead. I’ve also repositioned into Reach (LON:RCH) , Redde Northgate (LON:REDD) , and Smiths News (LON:SNWS) (but a small amount in the latter) over the past few weeks.
I bought some Novacyt Sa (LON:NCYT) on the steep drop on Monday but it’s a volatile stock so you do need to be able to handle that volatility.
Below is from an equal-weighted Folio watchlist of turnaround situations. This Folio dramatically underperformed in March and for a long period thereafter but the past three months show an interesting trend.
The watchlist is the blue line and the FTSE All Share is the grey line:

I do think the real deal lockdown winners will continue to be longer term winners. But I’m also keeping a closer eye on what have been losers, because the stock market is forward looking.
If there are continued signs of ongoing investment into COVID recovery stocks, I’ll devote more time to opportunistically playing this theme. Buy and hold quality investing is a great strategy - but the fact is being a nimble and responsive investor has served me well so far in what is clearly an exceptional year.
Risks remain and we’re not out of the woods yet of course, so there’s plenty to ponder - but I’m as curious as ever to hear how others are positioned.
(to avoid any confusion, this section was written by Jack)
Paul replies - very interesting, thanks very much Jack. I've been on what can almost be described as a buying frenzy this week, so I'm planning on writing a similar piece, giving my current market thoughts, and what I've been buying. Looks like that will probably have to wait until tomorrow though, as there are lots of other things for me to look at today.
Volex (LON:VLX)
Share price: 254p (down 3.4%)
No. shares: 152.3m
Market cap: £368.8m
(I hold - Paul)
Board changes - abrupt departure of the CFO today, which sounds like there must have been some kind of disagreement. Hopefully nothing more to it than that - many investors get spooked by sudden departures of CFOs, as it can indicate something might be wrong.
Daren Morris, who initially joined the business in June 2014 as a Non-Executive Director before becoming Chief Financial Officer in September 2014, has today left the Board with immediate effect and will be leaving the business.
Jon Boaden, who joined the business in April 2019, as Deputy Chief Financial Officer, has been promoted to the role of CFO with immediate effect.
There’s a presentation on IMC at 11am this morning, so hopefully we’ll get to see the new CFO. At least he already works within the business so knows the ropes.
Robust H1 performance - resilient business model responding well to Covid-19
Volex plc ("Volex"), a global provider of integrated manufacturing services and power products, today announces its half year results for the 26 weeks ended 4 October 2020 ("H1 FY2021").
These financial highlights look outstanding, considering the backdrop of covid/lockdowns;
.

.
I’ve highlighted the most important numbers to me;
Revenues up 3.5%
I tend to ignore operating profit now, because IFRS 16 has rendered it unreliable. Hence underlying PBT and EPS are the figures I tend to work from, for valuation purposes, providing the adjustments are reasonable.
There’s a healthy cash pile too
Note the figures are all in US dollars, so EPS translates into about 10p for H1. Simplistically, if we double that to 20p for the full year, then the PER is only 12.7 - too cheap in my view.
Bank facilities - a big increase is announced, even though the group has a strong net cash position;
We have also signed a new, three-year $100 million multi-currency revolving credit facility to replace our current $30 million credit facility, increasing our capacity for investment in future growth. The facility consists of a $70 million committed facility with a $30m accordion feature and is effective from 12 November 2020
Acquisition - this is substantial, at Euros 61.8m, but only E37m initially, which Volex can easily afford from its cash pile, and borrowing facilities.
This looks an excellent acquisition, a strongly profitable, decent-sized, low cost producer based in Turkey. This should substantially increase EPS, and is a great use of the cash pile, which was otherwise sitting there doing nothing!
Outlook - sounds fine;
Having delivered a robust performance in the first half of the year, coupled with a strong forward order-book, the Board remains confident in delivering on full-year expectations, absent any material disruptions to our business that may be caused by Covid-19…
Balance sheet - is strong. NAV: $150.7m, less $40.6m intangibles = NTAV $110.1m. My only queries are what “Other receivables” of $4.59m and $9.158m pertain to? Also I wonder what $42.2m in “Other payables” are?
There’s a modest pension deficit.
Note that Volex does not capitalise development spend, which is good.
Share based payments - seem rather high. This was $4.0m in H1, or about 20% of adjusted profits. It was $8.7m last full year, so I’m not sure these should be adjusted out as one-offs?
There again, if we value the business on diluted EPS, then we’re taking into account all future planned dilution.
My opinion - on an initial, quick skim of the figures (I’ve not gone through all the commentary yet), I’m really impressed. The turnaround at Volex has been remarkable, with the operating profit margin now just above 10%.
I like the look of the acquisition announced today, which is going to considerably boost profitability and EPS, which the market doesn’t seem to have recognised yet.
Maybe the abrupt departure of the CFO today might have caused the share price to fall. On fundamentals, I think the share price should have risen considerably today, so for that reason I’m going to buy some more.
I’m becoming increasingly convinced that Volex is too cheap. The analyst at Small Company Share Watch, a long-standing tip sheet, which is often very good, came to a similar conclusion, with a very bullish write-up last weekend, suggesting c.400p is a sensible target. I completely agree. Once you add on the profits for the new acquisition, and that existing forecasts seem too low, then it could continue to rise to that sort of level, with a bit of patience, I reckon. Providing nothing goes wrong of course, as with everything.
I particularly like the impending boom in electric vehicles, as this plays right into Volex’s strengths. They need complex, critically important wiring looms, hence likely to be very much in demand, and at good margins, because manufacturers simply cannot risk using a cheap supplier that could render electric vehicles as write-offs if the wiring goes wrong.
Remember how Jaguar designed a beautiful vehicle, decades ahead of its time, the Jaguar XJS (disclosure: I hold), but they used cheap electrical connectors, which rendered the vehicles unusable after just 2-3 years. That and the rust of course. Such a pity.
I could see Volex becoming one of my largest positions at this rate, if progress continues to be this impressive.
.
Volex - additional points from today’s webinar
As usual, this was a very interesting webinar on the IMC platform, today from 11am for an hour. There should be a recording of it on IMC in due course, so very worth watching for anyone interested in this company. I jotted down a few key points;
- Electric vehicles wiring components are starting to grow “exponentially”, already 15% of the power products division’s sales
- Opening a factory in Indonesia, lower tariffs than China for e.g. US customers
- DEKA acquisition in Turkey is “terrific deal”, leading power components maker for European customers, “opportunity for huge revenue synergies”, as well as cost savings, excellent European customer base, 2-year stretch targets for contingent consideration to kick in. Don’t expect any problems at all from competition regulators.
- H1 results benefited from one-off factors not expected to continue in H2, e.g. favourable forex, low copper price in Q1 since reversed, low tax charge due to utilising UK tax losses which allows them to recognise tax asset on balance sheet
- Hard to quantify impact of copper prices on H2 performance, partially hedged
- Q2 performance “very strong”, continued into Q3 so far
- “Incredibly deep” acquisitions pipeline, but won’t overpay, 3 potential deals at advanced stage, expect deals in Jan-Mar 2021.
- CFO change - outgoing CFO had indicated his wish to retire, 2 years ago. Hence why they recruited his ultimate replacement. Board decided that replacement performing so well, it was time to make the change. Hence nothing untoward, assuming that’s the full picture!
- New NED - is a fluent Turking speaker, and knows Turkey very well having been ambassador there. Also previous ambassador to USA & France, so beings very relevant skills to Volex
- Closing remarks - with the benefit of the DEKA acquisition beginning to kick in, we should be able to report “cracking results” to you in June next year.
.
My opinion - that all sounds excellent, although I hadn’t picked up on the fact that H1 benefited from some one-offs. Written down, the content of management comments sound really positive, but the tone of the webinar was delivered in a rather sombre, downbeat style I thought. Maybe they were tired/stressed?
Anyway, I’m more comfortable with things now (especially reason for the CFO departure), so am ready to push the buy button, and increase my stake.
.
** This section written by Jack **
Smiths News (LON:SNWS)
Share price: 26.68p (-8%)
Shares in issue: 247,700,000
Market cap: £66m
(Jack writing - I hold)
Smiths News (LON:SNWS) has recently refinanced but the share price is still cheap - that’s probably because, even post-financing, it operates in a shrinking market as the UK’s largest news wholesaler.
It’s very cash generative but you can see the direction of travel in recent times is all wrong:

So there’s plenty to do and the jury is still out. That said, you would think this year is about as bad as it gets for a lot of companies, and Smith News has remained profitable and cash generative through it all.
Shares are down quite a lot on the full year results - perhaps some relieved long term shareholders are gratefully offloading their stock, having previously been contemplating permanent loss of capital?
There has been a rerating over the past month or two.

This is a long and involved update so keeping it short will be a challenge.
Headlines:
- Performance ahead of revised full year expectations
- Trading resilience throughout lockdown and good recovery in Q4
- All major publisher contracts now secured to at least 2024
- Robust cost control delivering sustainable operating efficiencies of £6.7m
- Disposal of Tuffnells removes a loss-making operation
- New £120m three year bank facility agreed in November 2020
- Bank net debt of £79.5m equivalent to leverage of 2 X EBITDA at the year end
There are some heavily adjusted results here - perhaps to be expected from a company with a distressed valuation but also a further confirmation that this is a risky turnaround.
- Revenue -10.7% to £1.16bn
- Adjusted PBT -25.8% to £27.9m; statutory PBT -51.2% to £14.8m
- Adjusted earnings per share -15.7% to 9.7p; statutory EPS -45.6% to 4.9p
- Free cash flow -67.2% to £10.9m
- Adjusted bank net debt +7.6% to £79.5m; statutory net debt +52.8% to £112.9m
So the adjusted EPS figure puts Smiths shares at 2.75x FY20 earnings.
Statutory PBT of £14.8m is impacted by a non-cash impairment charge relating to goodwill and assets in DMD of £5.7m and the impact of COVID-19 on trading of c£7.5m.
Continuing Free cash flow of £10.9m is after the temporary closure and return of unsold supplies from a significant number of retail outlets during the lockdown. It’s good, given what the company has had to cope with this year.
Refinancing
The Company's new banking arrangements provide facilities of £120m in three parts.
- Term loan A of £45m- amortising at £15m p.a. over three years
- Term loan B of £35m - non amortising but subject to agreed repayments from the deferred consideration due from the sale of Tuffnells and ‘any cash surplus arising from the proposed move to buy-out of the Company's defined benefit pension scheme’.
- A revolving credit facility of £40m
Bank Net Debt at year end was £79.5m (FY2019:£73.9m), up £5.6m but ahead of Smith’s revised expectations.
As of FY19, there were also two pension funds to account for: WH Smith (surplus of £24m) and Tuffnell’s (deficit of £2.9m).
Conclusion
These results should be judged in the context of a very cheap valuation and good forward revenue and cash flow visibility:

The company is still profitable in 2020 which I view as quite a feat but the results aren’t pretty and I view this as a high risk turnaround.
There’s no doubt that Smith News is in a structurally challenged industry characterised by declining revenue and market size.
This is a long and complex update, but some of the key points include:
- The group has high visibility of revenue and cash flows through to at least 2024.
- The sale of Tuffnells in May 2020 gets rid of a loss-making division and simplifies operations.
- Network restructuring and efficiencies in the supply chain should deliver ongoing savings
- A key focus on debt reduction
- The board expects to resume dividend payments in FY21
In terms of outlook, management thinks it can ‘continue to trade profitably with positive cash generation in all reasonably foreseeable scenarios.’
It will be a bumpy road though. The company is cheap for a reason and it anticipates core revenue decline in the range of 3% and 5% per annum. Not just that - it expects ‘year-on-year sales declines to be greater over the next 12 months’, as a consequence of the ongoing impacts of COVID-19.
It’s a mixed update for sure, but I don’t see anything here that is a surprise or makes me want to sell just now. On balance, I’m happy to keep the small position as a deep value stock given the good revenue visibility.
There’s been net director buying over the past year or so.
.
Nwf (LON:NWF)
Share price: 192p (down 4%, at 10:55)
No. shares: 49.0m
Market cap: £45.1m
Restoration of trading - this share had been suspended when a cyber attack was discovered. Very sensible, whenever there is a potentially material uncertainty, then I think shares should be temporarily suspended. Shareholders can breathe a sigh of relief, as it’s only down 4% today, on very low volumes.
NWF Group plc ('NWF' or the Group), the specialist distributor of fuel, food and feed across the UK, provides an update regarding the impact of the cyber incident announced on 2 November 2020.
Following extensive investigations, supported by cyber security experts, the Group is satisfied that the incident has been contained and additional security measures have been applied to all of the Group's IT systems.
Here’s the most important bit;
...the Group is pleased to report that each of its three divisions has continued to operate with minimal disruption and the Board does not expect that the incident is likely to result in any material impact on underlying trading…. It is expected that the costs associated with the Group's response to the incident will be approximately £0.5 million net of recoveries under the Group's existing cyber insurance and as such the overall financial impact on the Group is not expected to be material.
My opinion - something like this can hit almost any company, so I don’t think we should be too harsh on management at NWF. One hopes that, having suffered such an incursion once, they’ll make sure IT systems are as near to impregnable as they can be, in future.
Is it a buying (or selling) opportunity? Not really, because the price hasn’t moved much. It looks an OK company - ex-growth, and modestly priced on a PER of about 11.
.
Norcros (LON:NXR)
Share price: 185.5p (up c.1%, at 14:58)
No. shares: 73.6m
Market cap: £136.5m
Norcros, a market leading supplier of high quality and innovative bathroom and kitchen products, today announces its results for the six months ended 30 September 2020.
'Marked recovery and strong financial position.'
The results presentation slides are on its website here (scroll down to “latest downloads” on the right hand side). I really like the video of its various subsidiaries’ products which plays when you load the page. Some lovely, stylish products there. I'd love a shower cubicle like that, as opposed to my one at home, with doors caked in limescale, and hanging off their hinges!
H1 results key points;
Revenues down 25.3% to £135.3m (at constant currency, and adjusting for 27 week period LY, it’s a fall of 17.3%)
Underlying profit before tax down 31.4% to £10.7m - not bad considering the environment
Received £4.9m in Govt assistance (furlough) in UK, Ireland, and S.Africa
Net debt has fallen very strikingly, down to only £7.3m (was £41.1m a year earlier) - there must be some creditor stretch here, so I’ll look into that. Yes, here we are;
The Group generated an underlying operating cash flow of £37.6m (2019: £20.0m) driven largely by a £19.9m inflow from working capital (2019: £3.1m outflow) reflecting a significant reduction in inventory and the deferral of VAT, rates and rent in the period.
It’s a pity the company has not disclosed the actual amounts of creditor stretch, as this is important information, creating an abnormally and temporary boost to cashflow. Clearly the net debt is going to rise again, once the company has paid up the deferred taxation, and once working capital increases again as business normalises (note that inventories levels are unusually low).
No interim divi (LY: 3.1p)
Strong recovery in Q2 trading
Outlook - nothing meaningful, but generally sounds upbeat, e.g.
...the Group remains well positioned to sustain the strong progress and recovery of the second quarter.
Forecasts/valuation - as you can see from the broker forecasts below, they’re starting to pick up. I can’t see any reason why, once things get back to normal, that previous levels of EPS of perhaps 25-30p couldn’t be attained once more. Plus, the DIY & home improvement sectors have proven quite resilient, as many shops were allowed to remain open during lockdown.
.

.
Personally I wouldn’t want to pay more than a PER of about 8, given the huge pension schemes, and large exposure to S.Africa. That gets me to a valuation of 200-240p looking forward maybe a year or two. Given that the current price is 185p, then personally I don’t see enough upside to get me interested.
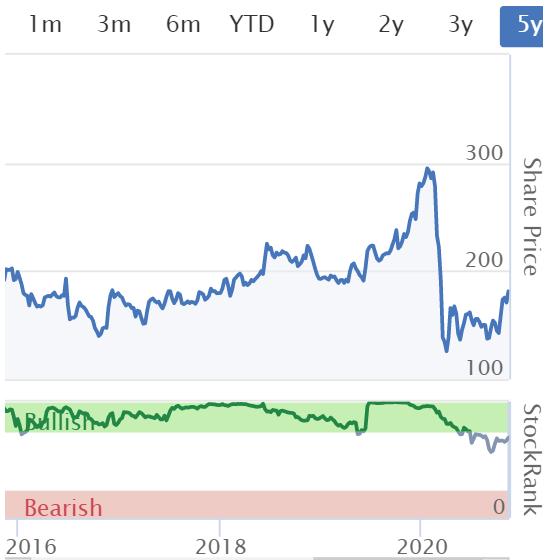
As you can see below, the share price hasn't really gone anywhere in 5 years, although reasonable divis have been paid. I think that's why this share has tended to have a revolving door type shareholder base. People buy because they think it's too cheap, sit and wait for a while, and nothing happens. Then eventually they sell up and move on.
.
.
Ideagen (LON:IDEA)
Share price: 229p (down c.2% today)
No. shares: 226.9m
Market cap: £519.6m
Trading update & Board changes
Ideagen PLC (AIM: IDEA), a leading supplier of regulatory and compliance software, is pleased to provide an update on trading for the six months ended 31st October 2020.
This is the key bit;
The Board is pleased to report that trading for the first half of the financial year has been ahead of the same period last year and comfortably in line with the Board's expectations.
These results underpin the Board's confidence in the Group's prospects for the second half of the financial year
Increasingly strong recurring revenues;
The Board considers ARR as the Group's primary growth metric and the driver for long term value. ARR recognised during the first half is expected to be £24.4m (H1 2019: £20.3m), representing 83% of total revenues, up from 74% in the comparative prior period. The ARR book (being contracted revenue to be recognised over the coming 12 months) has increased by 13% during the first six months to approximately £54.8m (April 2020: £48.7m), arising from both strong organic growth of approximately 7% (14% on an annualised basis) and 6% of acquired ARR from the acquisition of Qualsys in August 2020.
H1 guidance -
The Group expects to report total revenue up 7% at approximately £29.2m (H1 2019: £27.3m) and adjusted EBITDA* to have increased by 25% to approximately £10.0m (H1 2019: £8.0m).
Net debt -
Cash generated by operations during the first six months is expected to be in excess of 90% of adjusted EBITDA* resulting in a gross cash balance as at 31 October 2020 of £12.1m and gross bank borrowings of £40.0m. Net bank debt at the period end of £27.9m leaves the Group comfortably within banking covenants and on a robust financial footing.
My opinion - I’m not keen on the balance sheet, or the valuation (very high, in my opinion). So it’s not something I would want to buy at anything like the current price.
I reviewed the last full year accounts here in Sept.
Bulls point out that high recurring revenues software businesses do attract a premium price, which is a fair point.
Long term holders have done very well;
.

.
Tt Electronics (LON:TTG)
Share price: 213p (down c.5% today)
No. shares: 174.2m
Market cap: £371.0m
TT Electronics plc ("TT", "the Group"), a global provider of engineered electronics for performance critical applications, publishes the following Trading Update on the Group's performance in the four-month period ended 24 October 2020.
Like-for-like revenue is 11-12% down on last year for July,Aug,Sept, Oct - a slight improvement on the -17% reported for Q2 (Apr, May, June)
Book to bill is improving;
The trends previously seen in TT's end-markets have continued. Order intake has shown signs of recovery with bookings for the four months running at 104 per cent of revenue and, as a result, the Group's order book has now almost recovered to where it was this time last year. The recovery dynamics in organic revenue and order intake have come from across the Group.
Cost-cutting to improve margins - these are quite big numbers relative to historic profitability;
We are making good progress with the Group's extended self-help programme, which commenced in the second quarter, with initial headcount reductions completed and transfer activity on schedule to support the site closure timeline. The project is on schedule to deliver the expected £11-12 million of run-rate benefits in 2023.
Outlook -
...We are continuing our journey to double-digit margins and expect to see further improvement in trading this year."
Virolens - I’m still smarting from this. I got suckered in by a very rampy RNS issued on 10 Sept 2020, which trumpeted possible orders of £280m relating to a covid testing machine that TTG is involved with. This caused a big spike up in share price. I bought right at the top, and then almost immediately press reports began to pour cold water on the credibility of TTG’s partner.
Then within a week, TTG announced a placing at 200p for an acquisition.
Look at the market chaos this badly handled chain of events caused in Sept 2020. This cost me, and other investors, losses;
.

.
Today’s update on Virolens doesn’t mention any numbers;
In September we announced that TT had been appointed exclusive manufacturing partner for the commercial launch of Virolens®, a rapid COVID-19 screening device. There remains a wide range of possible outcomes but Virolens® is proceeding through regulatory approvals and devices have been shipped to initial launch customers for operational trials in a number of different jurisdictions.
We have also been working to prepare for volume production of Virolens® devices and testing cartridges at our facility in Hartlepool, UK.
Acquisition - of Torotel, for $43.4m, completed earlier this week.
My opinion - I’m steering well clear of this company for the foreseeable future, after the debacle re Virolens in Sept, just before a placing. That cost me a few grand, and has badly dented my willingness to trust management. That’s a pity, because I always thought this seemed a pretty good company.
.
Clipper Logistics (LON:CLG)
Share price: 480p (up 4% today)
No. shares: 101.7m
Market cap: £488.2m
Clipper Logistics plc ("Clipper", the "Group", or the "Company"), a leading provider of value-added logistics solutions, e-fulfilment and returns management services is pleased to announce a trading update for the six months ended 31 October 2020.
This sounds very good;
Clipper has continued to see strong trading across the business in the year to date, benefitting particularly from the continued structural shift to e-commerce that has been accelerated during the ongoing Covid-19 pandemic. The Group expects to report revenue for the period of at least £300m, an increase of almost 20% against the prior year comparative period, including e-fulfilment logistics growth of over 30% and non-e-fulfilment logistics growth of approximately 10%.
Nothing is said about performance vs expectations. Therefore I’m assuming this is in line with expectations. Stockopedia shows a +20% forecast for revenues this year.
If it achieves FY 04/2021 forecast EPS of 20.6p, then that gives a current year PER of 23.3 - rather a lot for a logistics company, but it does seem to be seen as a picks & shovel type share for eCommerce companies, and the growth rate is impressive.
Cashflow/net debt - have improved, but we’re not told how much of the gains are one-off, temporary effects from stretching creditors, eg. VAT/PAYE. Companies must report the numbers, otherwise they could be giving us a false impression.
Outlook - sounds reassuring;
This good momentum and the existing pipeline of new business opportunities is expected to give the Group continuing strong performance into the second half of the financial year.
My opinion - I’m not really interested in logistics companies, but if I had to buy one, it would probably be this one, due to how well it's doing with eCommerce clients.
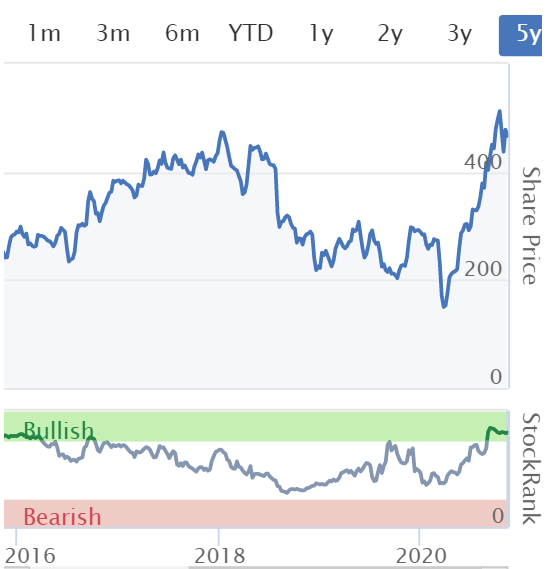
Note how Clipper shares are doing extremely well this year, but the longer term picture is more mixed.
.
.
I think we'll call it a day there. Thanks for tuning in!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

116 comments
Volex (LON:VLX) (no position)
Does anyone have a Investor Relations contact email address for this company (their website only has one for Link Asset Services)?
Or even better can anyone help me with the following:
Thanks in advance
A
My thanks to all contributors today. What a great read. Plenty of information and analysis.
Clipper Logistics (LON:CLG) are doing a lot of the Government/PHE/DHSC distribution for PPE supplies and I suspect that this has kept their results well up whilst the stores they normally supply have been depressed. Difficult to know if it was a well timed political donation or savy business or both
Anybody know why the big drop in Morgan Sindall (LON:MGNS) today? I've had a look but couldnt find anything.
gone xd today but not by amount of fall
Morgan Sindall (LON:MGNS) is ex dividend date is today (21p) i think - other than it does seem a slightly ott decline on no obvious news i can see - . Perhaps it one of those situations where bods have hung around for the divi then started selling en-mass to book their tidy recent gain? quick look at galliford try and they aren't down today so doesnt look like general sector slide.
Thank you FB and RM, it was puzzling me!!
re £MGNS. the fall may be down to profit taking. It has had a good run over the last week.
Jack, Thanks for your regular in depth thoughtful analysis of a broad range of companies, & topics; much appreciated.
Hi Jack, thank you for your thoughts on £VLX. This might sound like quite a novice question, but would appreciate some clarity on this.
You say "I tend to ignore operating profit now, because IFRS 16 has rendered it unreliable. Hence underlying PBT and EPS are the figures I tend to work from, for valuation purposes, providing the adjustments are reasonable."
Can you say more about the unreliability of OP, as I generally use this metric and why IFRS 16 affects it.
Additionally you comment on their OP margin being good, but is the OP margin not built from the stated OP, and therefore does the stated OP margin also become unreliable due to IFRS 16?
Many thanks,
MAx
Hi Max,
It was Paul writing about Volex (LON:VLX) and the presentation. I signed up to it too but haven't yet had the chance to watch it.
It is available on www.investormeetcompany.com as a replay I believe - you just need to sign up and add Volex as a company of interest.
Hi MAx,
I'm too tired to delve into a full explanation of this now, it's been a long day!
Let's discuss it another time. I'll try to give a clearer explanation when a suitable example crops up in the near future.
Best wishes, Paul.
Volex (LON:VLX)
Just finished listening to the presentation. Noted -
1) Departing CFO had indicated in 2018 that he wanted to leave in 2 years so today's news not as dramatic as sounded
2) margins benefited in H1 from copper prices and forex changing in favour but expect this to reverse in H2
3) eps flattered by a tax credit. This was explained as historic UK losses now available to a current UK subsid. to offset against profit.
Re 1): That was my impression at first hearing it, but why did it apparently come out of the blue and on a day when there was otherwise good news released ? I haven't seen any announcement of this planned retirement before, yet I have previously seen companies announce succession plans for BMs who were planning to leave in the near future. Maybe someone else has seen a previous announcement ? I hold.
My impression was that Daren Morris’s responsibilities were somewhat broader at £VLX that a standard CFO. This is logical as there was no CEO and Nat Rothschild as Exec Chair has his fingers in a number of pies.
I first chatted to Morris after a presentation at a Yellowstone Advisory (Alex Schlich) event in Nov 2019. From my recollection (I have checked my notes but had not written down this part) Morris and Rothchild went back a long way. So if (note the word “if”) the reason for Morris quitting was there was a “falling out”, it was probably quite a falling out.
Following that presentation I bought Volex, but have not held for a little while (definitely sold too soon), where I have got worried about the valuation given the growth was historically only through acquisitions - and the organic numbers had to be teased out of the reports. From a first read- through of today’s interims, I do not see a breakdown of how much of the 3.5% top line growth is non-organic.
re £VLX - I hold and, like Paul, think it’s a great and undervalued company.
I read too about the departure of the CFO this morning with some concern. Prior to Volex, Daren Morris had been a banker at Morgan Stanley and when I listened to the last Investor Meet presentation I concluded (my own view) that he was likely something of a deal maker and, as such, was great for the company, given its acquisition trail. It’s turnaround and trajectory has been great.
I also listened to this morning’s presentation and wasn’t altogether convinced with the explanation that he had given notice of his intent to retire 2 years’ ago. It’s plausible enough, given the new CFO’s hire 18 months’ ago as Deputy CFO, but interesting (and odd?) that Monday’s RNS announced that Nat Rothschild and Daren Morris would present the HY results together, this morning.
CFO departures can often preface bad news, which I hope this doesn’t. I’m holding on and may well buy some more on the current dip, but will watch closely.
I was only able to listen to the first part of the Volex presentation. But like Paul, I thought the tone (at least in the part I heard) was very downbeat. He started by saying something along the lines of being pleased or keen to get started on the presentation. You could have fooled me!
Results seem OK, but if there was a previous announcement of the CFO planning to leave I also missed it. The tone, and the lack of any advance warning of this, makes me suspect there was more to it.
The Volex (LON:VLX) recording is now available so you can listen to the rest. The CFO transition answer is 36m 20s in.
Be very careful of Ienergizer. Its main site is haunted.
https://www.holidify.com/pages...
JACK RECOVERY Reach (LON:RCH) REACH
Owner of Daily Mirror and 20+ regional newspapers. Big deal? Nah, not really... but read on.
That doesn't look good on the face of it but... as a result of this, they have HUGE readership.
If you add up all the readership of Reach (LON:RCH) it makes it the fifth largest source of readers in the UK behind Facebook, google etc.
People want to know what is happening in their local area.
So readership has went up during covid.
What's the big deal, I hear many of you ask.
Well as I alluded to initially, Reach was no big deal previously. Why? Because they weren't utilising their data. All that data of all those online readers. Not willing to pay for news but willing to give their data away for free.
You like golf? Good, Reach are now going to direct golf product ads to you after you look up the golf news. Etc. etc. etc.
Looking at the fashion section? Wait for that ad - and these are high margin ads, sports and fashion.
They've cut the cost of print and pivoted away form the cost intensiveness of print media onto online.
They are only just monetising the data and new CEO Jum Mullins is leading the charge and he has experience.
It's gone up a lot recently but still only a PE of c5.
Change is coming to REACH and change makes money.
A lot more to come. DYOR
Hi Greenhat2, I spent an evening reviewing Reach (LON:RCH) websites and annual report. I decided not to invest due to two factors; I struggled to buy into the strategy as the websites felt very much web2.0 (a very subjective opinion but I signed up to the picture memory site and the local news aggregator and I was left with questions over ability to execute. I expected them to be far more exciting and integrated for new initiatives ); and secondly I couldn’t find details on the reader number. They don’t seem to have a source or definition of metric used. Being the 5 largest might not mean a lot. More clarity on that number might change my opinion. Have I missed it?
I'm with you Jack. Have a look at their site and then go to the Top 50 internet sites - there's a couple of sites that do this. No way they are fifth.
Their top site is at No 39 - the truly gruesome Daily Express. They miss out the BBC, Daily Mail and one other one called Porn Hub that Ive heard of but never visited.
Their other problems is the print works and the pension fund.
yes it is difficult but a bit of digging round you can get the jigsaw
https://aboutmanchester.co.uk/...
“Reach has already surpassed its full year 2020 target in achieving over 2.5 million customer registrations. It is now increasing its 2022 target to 10 million by 2022 up from the 7 million announced in February. ”
KGB - it’s not one title which is 5th - it’s the amalgamation of all their titles which puts them in 5th place.
Put simply if you add up all these - you get 5th place in audience in UK... simples
National newspaper
Local and regional newspaper
(Macclesfield Express / Wilmslow Express / The Sentinel (Staffordshire))
Scottish and Universal Newspapers)
Digital online Brands
Reach has launched websites under the Live brand:
Thanks for digging Greenhat, but that is a hugely diverse portfolio. I think @Ed posted a link to Ben Thompson's 'Stratechery' a while ago and Ben has done a lot of work on the power of Aggregation Theory. The link is quite old (2015), but the right side of the paywall and still relevant.
Reach (LON:RCH) is not going to unseat Facebook or Google as things stand (IMHO), so they need to add something different; and ultimately that will lie in execution. They need to be able to execute a local, specialist, or perhaps UK wide internet presence better than Facebook or the others do. After trawling their sites I did not build that confidence. Being an also run doesn't really count in this space. Which is the 5th biggest auction site? I have no idea, but who is a player in used car sales, a specialist such as Autotrader. They carved a niche (I don't hold).
I’m sure there is money to be made, but unless they can control the space (become the aggregator) not for the long run.
Somewhat tangential, but my daughter lost her cashcard in town (sleepy old Nairn), and got it back the next day from the local police station all through the power of Facebook. Its already hyper local.....
I agree but it looks like they’re on it
change can take time you know
look at the jobs on offer https://jobs.reachplc.com/jobs all digital web type plus digital sales
change is a coming the next update will be interesting
RECOVERY RESPONSE TO JACK
Jack - I think you are bang on the money with your choices.
My opinions
Redd Redde Northgate (LON:REDD) - will make more money with the improving business environment. Covid has propelled online shopping by say 5 years? All of us who said to ourselves, 'no, I'm not into buying clothes + x + x or y online', have tried it now and think it's great.
So where does that lead?
It leads to the demand for deliveries which pushes up the demand for delivery vans.
Even small local businesses are having to deliver now. Having to get online and deliver... people are used to the convenience now.
Demand for used vans has soared as a result.
Supply chain issues caused a shortage of new vans, as well which has helped push the price of used up.
Remember, if you can teach a monkey supply and demand, you can teach him (or her) economics.
So what are REDD doing?
They are selling their used fleet into the spike in the market and paying down debt. They had planned to do this anyway but they've just ended up getting 15-25% more for the used fleet.
They are degrossing the fleet, removing risk and starting to lease vans, to let out on hire.
The new CEO Martin Ward knows his stuff too. He is going to turn the company around. And Avril Palmer, formerly BCA Marketplace - she's come on the board too... started her career at Northgate and knows how to make serious money.
And that's not even touching on the old REDDE side of the business, here, after the merger you are getting, vehicle hire:
+:
- Depots
- Maintenance
- Overhead economies of Scale
- Distribution network increased
- More sales
Still only a PE of 6.7
Looking at c7% div (and they have a history of paying divs)
Big funds starting to buy in (Norge Bank this week)
Redde Northgate (LON:REDD) going to be a big winner in the recovery.
If I have time, I'll post some on reach too... another top notch winner.
Redde Northgate (LON:REDD)
Thanks for that greenhat2 (was greenhat1 taken?)
This company has been on my watchlist too.
I've heard/read so many positives, that I'm wondering what I'm missing. What's the BIG risk with this one?
Thoughts from you, or anyone else, would be appreciated.
A
It's got a high M-Score which has put me off investing
I haven't looked at the details for Redde Northgate (LON:REDD) but the M-Score probably does not make much sense at the moment.
Redde & Northgate completed their merger towards the end of February and they have an April year end.
What this basically means is that the latest balance sheet - reflects the combined group, but the P&L / cashflows mostly just reflect Northgate. (As I believe it was the Northgate listing that was retained).
I don't think there is any way (other than waiting a year for the first combined results) to reliably calculate some of the M score components on as it stands.
have a look at Redde Northgate (LON:REDD) Gromley
it would be good to hear your thoughts
I can’t see any downside atm apart from high debt
But they are paying that off and degrossing the fleet
The value of the fleet on the balance sheet is undercooked because it’s not factoring in the 15-25% premium on price of used vans
Jack - any negatives from you ?
I suppose one risk is an integration risk due to the recent merger. They have also made a purchase of a nationwide repair business (out of administration) in the last few months. So lots going on at the moment (and therefore risk of not delivering on plans).
I'm quite comfortable from reading recent RNS about the work being done to drive down costs from the merger. So although this is a risk they do seem to be managing quite well post merger.
They’ve a seasoned management team now to be fair
I really admire what Avril Palmer did with BCA marketplace £BCA
Martin Ward knows the industry
And they are being very careful with the balance sheet by degreasing the fleet and removing risk
Redde Northgate (LON:REDD)
Apologies for replying to my own post asking whether there were any negatives for this company. It's 1am on a Sunday morning so naturally I thought of nothing better to do than read about fleet management in the UK.
I came across the below article (published on 5/11/20) on vehicle registrations in October and YTD. It doesn't really paint a very rosy picture of the industry so far this year.
Some snippets:
Now I'm not saying that there isn't value for this particular company, but I'm a tad more sceptical on the short term outlook, which I thought would have been booming.
Is:
What do others think? Have I misinterpreted what this article is saying?
https://www.fleetnews.co.uk/ne...
Thoughts as always appreciated.
A
ps - no position
Spirent Communications (LON:SPT) - trading update says still inline with guidance - which I already understood to be quite nice. Why the sell off?
Sector rotation maybe? Banking profits and moving on to the next big movers?
Spirent Communications (LON:SPT) (I hold) Perhaps because they just added one word too many in their RNS?
The word in question is “broadly”. Read the profit warnings survival guide book produced by stockopedia. https://www.stockopedia.com/bo...
Here are my heat maps for today (prices as at 9:45am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than the 20d EMA of ATR):
Big movers today (moving more than 20d ATR EMA against either yesterdays close, or today's open - not limited to small caps):
And finally the key to the instrument heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 80 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many as part of my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria ('T': profitable, low-debt, reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the individual instruments further using the Stockopedia Stock Report.
How (or indeed if) you use the heatmaps is up to you, I contribute them here in the hope that others may also find them interesting or useful.
greensiax
Thanks for this. Very interesting. I'm new to this. Could you explain what you use to measure trending or break out? I'm not to clear on how these work.
Thanks again
Hi eddifin,
Thanks. I can certainly tell you what I use, but it may not be a text book definition ;)
I define trending as the highs and lows of the days trading range are greater (trending up, or lower trending down) than the previous days for more than half of the trading days in the period I'm testing (7 trading days, and 21 trading days in the heatmaps).
Investopedia's dictionary defines a breakout as "the movement of the price of an asset through an identified level of support or resistance".
My definition of a breakout in the heatmaps is that the low price in todays trading range is higher than the previous high price in the period I'm testing. I use 1 month and 3 month breakouts in the heatmaps. For breakdowns the high price is lower than the previous low in the period.
Hope that helps.
greensiax
Smiths News (LON:SNWS) (previously Connect Group)
Despite this being one of my holdings, I would suggest as today is looking quite busy, this is probably not a priority to cover today.
The c. 7% fall in the share price thus far, should be taken in the context of a near 50% rise over the last month.
There is a useful presentation on the results from the CEO & CFO here. (I shall be having a moan at investor relations about the fact there is no recording of the Q&A)
There are not really any surprises in the numbers. If the market is disappointed about anything it may be the clear focus on debt reduction going forwards (at least £15m pa) – that should not have been a surprise however.
The refinancing included a provision precluding any dividend for FY20 and “capping” (no details given) of dividend for future years. However it seems clear that there will be a resumption in dividends from 2021 – a 1p (c. 3%) dividend for example would cost about £2m which is a pretty modest sum given the strength of cashflows.
All reassuringly boring.
One interesting snippet near the end of the presentation that may have read across elsewhere. During “lockdown one” more than 2,000 retail outlets that they service were closed; one week into “lockdown two” and only 110 outlets are closed, newspaper sales were down around 1% week on week.
More on Smiths News (LON:SNWS) .
Firstly a quick disclaimer - I sold more than half of my shares today - not because I think there was anything wrong with the results, but because as the reaction to the results was lukewarm - I don't see any short term catalyst for a rerating. I still think it is fantastic value and the shares I have kept are sort of an insurance policy against my total ineptitude at trying to "time the market".
I was interested though by the FCF progressions chart that Jack posted
(my childlike scribble squiggle)
From my perspective I think it is not quite right to suggest that the direction of travel is wrong (although objective correct).
Both the 2019 & TTM figures there were both a result of the Tufnells disaster. Taking that out of the picture I see about 13p FCF in 2019 (and probably similar TTM). So in fact I would say that the cashflows of the Smiths business have been robust (and that is the one of the key attractions).
However I think the 2020 FCF/share is 4.4p which looks horrible - "because Covid".
Also because their year end working capital flip flops outrageously because they collect from customer (the "newsagents" etc) on a weekly basis but pay their "suppliers" (the publishers) monthly. In the year just ended that was flipped on its head (I think) as they had passed on rebates (for unsold returns) to the customers before receiving the rebate from the suppliers.
So I do expect to see a bounce back in cashflow next year as covid (hopefully) has less impact on performance and the Working Capital resets.
Having written all of that I am now tempted to sell the remainder of my holding tomorrow - I think there is plenty of room for the market to become overly gloomy on the apparent poor cashflow. As I said at the top of this post though, I am hopeless at reading sentiment and timing like this.
First time poster so please be gentle ;-) It feels that the vaccine race may be a bit “tortoise v hare”. Good summary here of the 68 vaccines being progressed round the world currently from the New York Times - it’s a global race.
https://www.nytimes.com/intera...
excellent article and overview. thank you for sharing.
A search for the trial result of the Virolens machine TT electronics (LON:TTG) mfr does not throw up much.
"Heathrow boss John Holland-Kaye is urging the Government to fast track the test following a successful three-week trial at Heathrow Airport as part of the Government's Condor programme. He said today: 'Testing for Covid-19 is the lifeline that the UK economy needs to get back on its feet. 'I have experienced iAbra's test myself, alongside the PCR test - it is quicker and cheaper, and potentially more accurate.' "
https://www.dailymail.co.uk/news/article-8903075/Boris-Johnson-signals-immediate-prospect-10-minute-rapid-turnaround-Covid-tests.html
There's nothing on the inventor iAbra's website! That's pretty odd for a world-beating advance.
iAbra admitted in Sept the test had not had clinical trials, without which it won't be used. The co made false claims which it humiliatingly had to recant, saying a press release had been released in error.
I've had a good week so far, I'm up about 6%, but I'm surprised at the amount that stocks I bought partly to profit from the pandemic have gone down. Specifically Loopup (LON:LOOP) , N Brown (LON:BWNG) and Boohoo (LON:BOO) . I bought all of these thinking that they were good companies which should continue to prosper once life returns to normal, and I think this week's reaction is overdone.
I agree. It's not as if the shift to online is going to suddenly reverse. It's a long-term structural change, that lockdowns have accelerated. Maybe a bit of the gains might be given back though, as people return to offices in 2021?
Personally I do enjoy face-to-face meetings with company management, but it's vastly more efficient to have a Zoom meeting, as I can see so many more companies, and only spend maybe an hour on it, during the day, instead of having to set aside pretty much the whole day.
Re Loopup (LON:LOOP) , I was talking to a judge the other week. He said that the lockdown had resulted in a surprising amount of legal business being conducted over video links, and saw this as a gain in efficiency at least some of which would continue once we are free of the virus.
Re: Loopup (LON:LOOP)
I was talking to a friend of mine who works in one of the big law firms. They use LOOP but don't trust ZOOM which I gather is common for UK law firms. As a consequence, the use of LOOP will expand naturally amongst their clients, a network effect that should result in incremental growth. And whilst law firms may reduce WFH, all it needs is one person to be away from the office for such systems to still be used. So I've been buying more LOOP sub 170 and its now a very large position.
cheers
Francis
I'd never heard of Loopup (LON:LOOP) - working in the IT industry as a consultant for a big player. I've seen it being used a couple of times recently and am starting to think about taking a position. Could just be confirmation bias affecting my judgement though.
Agree Paul, if anything Covid will accelerate the change I would have thought as people who would have never (older demographic?) shop online realise it is an easy and a better experience than the high street.
I buy almost everything online and have done for years (living in the middle of nowhere in both France and England, I had no choice) and my last hold out had been food shopping, as I enjoyed choosing my fruit and veg but now we are used to online I am sure we will continue to do it that way.
This is of course with the proviso that the online ‘experience’ is good. I have just tried to order for delivery from B&Q (I’m in SI) and the web site won’t even let me checkout.
What it means for the likes of charity shops, coffee shops, banks and estate agents (and of course the property owners of the high street) etc I am not sure. Will the footfall be sufficient to justify all those places to eat in the high street? I always thought that estate agents would be the first to leave the high street but they are a hold out but it still surprises me. Why not get your shortlist together via Rightmove (LON:RMV), have a zoom discussion with the agent(s) in their cheaper out of town office and then meet them at the property.
I am long £boo
Sorry for the rambling email.
Regards
Michael
Im a customer of £LOOPUP and I know that their revenue is more than just their own product. They make a large % from managed services selling the other major collab vendor tools like MS Teams/Webex et al. (where we use them).
This is a growth sector and will continue to improve bottom lines even if LOOP becomes a smaller margin.
what this pandemic has done is bring forward our reliance on all things IT/web/AI etc etc by some years. i think the pull back has been indiscriminate in a lot of cases but some valuations were and probably still are ridiculous. for example i bought Zoom early on , made 200% and sold when it really spiked up. i bought back in when it pulled back because i think zoom will continue to be a winner post covid, although i have to admit i am not sure of the financials. others such as peloton for example have done ridiculously well but surely people would rather be out on the road or in the forest rather cycling indoors so that is one i would avoid. so there will be a rerating of both growth and value stocks. i am still bullish in the short term because i am sure there will be news on another vaccine or vaccines and hopefully ones that are easier to deal with. we are definitely in a two tier economy ATM , people still in a job have lots of pent up cash that will be looking for a home when we able to do things , i have had quite a lot of work done at home recently and everyone i have spoken to in all trades has never been busier, on the other hand many have or will be made redundant.
I think many of us might have topped on on Novacyt Sa (LON:NCYT) on Monday if our respective platforms hadn't (at best) ground to a near halt or (worse still) gone down completely. There were still opportunities on Tuesday but not as attractive as Monday's bottom.
What are your thoughts on Novacyt Sa (LON:NCYT) SA medium to long term? I'm concerned that the demand for testing could start to reduce after the launch of a vaccine - maybe not immediately, but over the next year or two.
I'm long Novacyt Sa (LON:NCYT) too from around the £4 area, sold a small amount at £10 to derisk and free up some funds but I expect it to go well above over the longer term. We need to begin to consider the company as a diagnostic services proposition instead of a pure play on Covid testing. The revenue already generated will be put to use to (try and) build a company with a significantly broader market, the recent acquisition only serves to further this goal.
How the acquisition and development strategy goes will determine whether they turn into a Global player to rival the likes of Roche, get taken over, or wither and wane due to mismanagement of the opportunity!
Novacyt Sa (LON:NCYT) I found this article interesting, although not sure how biased the writer is: https://novacytinsider.com/abcam-hutch/
You've identified the 'long' question James. The 'vaccine' announcement and no doubt more good and bad Covid news to follow in the coming weeks and months might mean that the meteoric share price rise for Novacyt Sa (LON:NCYT) with downward adjustment this week is a sign of more turbulent pricing to come. Novacyt is not only about Covid but having been in the right place at the right time it has then became suddenly fashionable and the share price has taken off, does it reflect the long term potential for the company or short term hype? There is a good piece in the Share Club articles that helps one consider that.
There are too many unknowns to predict where the virus and therefore where testing goes, but even the best scenario for tackling Covid means gradual suppression over the next 6 - 18 months, continued vigilance, a desperate roll out of vaccines which will take even longer, no adverse reactions, no mutations of the virus etc. I can also visualise organisations and companies wanting to get back to normal working undertaking their own testing (for who knows how long?), as is the case now in some sectors - the beauty in that for Novacyt being that tests are regular, my daughter (care sector) is tested every two weeks.
I'm off to find a crystal ball...
Like John Doe below I would appreciate you having a look at the interims from iEnergiser Ienergizer (LON:IBPO) , it seems to have slipped through the net of our early morning reviewers. On reduced turnover from $96.5 mill to $90.5 mill (6.5%) they have managed to increase operating margin from 27.8% to 30.9%, PBT has gone up from $25 mill to $26.9 mill , net cash is up from $1.6 to $5.6 mill and they are paying a divi as well. All of this on a stocko score of 93 , a PE of 14 , ROCE of 29.9% and ROE of 32.1% . The broker forecast is profit of $44.5 mill for the year and they have achieved $26.9 mill in the first half so they are 60% there already and this has been achieved in a period dominated by covid . Hope this is enough to wet your appetite!!!!
Summed up very well fred9566. This share is totally below the radar unfortunately...
Seems that the illiquidity / low free float is possibly holding this one back ? The co-founder Anil Aggarwal appears to hold >80% .
Yes, good and bad. Small selling will drop the price
i'd imagine it would support the dividend though. At 58 maybe there isn't a pressing need to look for a sale either.
Yes, small buying will cause a rise!
yes I looked at this today after the post by Fred9566 and was immediately put off by the small free float and the %amount owned by the founder.....I may be wrong as the numbers look impressive YOY.
Hi fred9566,
Thanks for flagging Ienergizer (LON:IBPO) - I've never looked at this company before, possibly because it falls into the overseas/AIM category, which I usually keep well away from, as so many of them go wrong.
However, in this case, it's been around on AIM for 10 years, and seems to have an excellent track record.
Thanks also to Teast17 who flags up the important point that the biggest shareholder holds almost 83% of the shares! That would probably rule it out for me, or I would only take a small position in it anyway, due to concerns over that level of dominance.
I haven't got time to delve into the detail today, but on a quick skim of the figures, and the StockReport, I can see why you think it's interesting. Looks a pretty good GARP share, worthy of a closer look when time permits.
Regards, Paul.
I must confess that I found this particular share through one of your contemporaries Robbie Burns at Naked Trader who has been in it since July of this year and generally speaking he normally does ok . Like you I did not like the free float % but Mr Burns normally makes some good choices and all the metrics are good particularly the ROCE and ROE ( this might even impress Mr Buffet) We shall see.
Ienergizer (LON:IBPO) Whilst being put off by the free float, I did notice that its bigger rivals, i.e Infosys and TCS on the Indian stock exchange - were touching all time highs. So was tempted. Looked into their quarterly reports briefly. Given Indian's extended lockdown, both of these relative big boys on the NSE performed resiliently. Thus, likely to be extended growth after pandemic for all outsourcing companies.
Looks like there are negative shares available?!
Ienergizer (LON:IBPO)
Here are two RNS from several years ago which I found interesting.
I do not hold.
17 August 2015
iEnergizer Limited
("iEnergizer" or the "Company")
Placing and Director dealing
Result of AGM
iEnergizer Limited (AIM: IBPO.L), an international and full service business process outsourcing business, is pleased to announce that it has raised 1.1 million by way of a placing of 22,000,008 new ordinary shares of 1 pence each ("New Ordinary Shares") with EICR Cyprus Limited ("EICR") a company of which Mr Anil Aggarwal, Non-executive Director of the Company, is the ultimate shareholder (the "Placing") at a price of 5 pence per Ordinary Share (the "Placing Price").
The Placing Price represents a discount of approximately 78.72 per cent. to the closing price of 23.5 pence per share on 14 August 2015, (being the last practical date prior to the announcement of the Placing).
RNS Number : 3061S
iEnergizer Limited
07 July 2015
7 July 2015
iEnergizer Limited
("iEnergizer" or the "Company")
Placing and Director dealing
iEnergizer Limited (AIM: IBPO.L), an international and full service business process outsourcing business, is pleased to announce that it has raised GBP2.12 million by way of a placing of 15,120,000 new ordinary shares of 1 pence each ("New Ordinary Shares") with EICR Cyprus Limited ("EICR") a company of which Mr Anil Aggarwal, Non-executive Director of the Company, is the ultimate shareholder (the "Placing") at a price of 14 pence per Ordinary Share (the "Placing Price").
The Placing Price represents a discount of approximately 49 per cent. to the closing price of 27.5 pence per share on 6 July 2015, (being the last practical date prior to the announcement of the Placing).
Anil Aggarwal, a Non-executive Director of the Company, is the ultimate shareholder of EICR and as such is a related party for the purposes of AIM Rule 13. The independent directors of the Company consider that, having consulted with the Company's nominated adviser in relation to the Placing that the terms of the Placing are fair and reasonable insofar as the Company's shareholders are concerned.
Further progress from Bango (LON:BGO) with a deal to support Telco billing for the new Microsoft XBOX/SBOX launch this week - this should drive significantly increased throughput through their billing /payment platform but it is not clear how much.........I still hold this one and think it has a long way to go yet hopefully upwards.....
Interesting results from Duke Royalty (LON:DUKE) this morning - covered well in MrContrarian (s) update this morning - I hold, and kept holding, after the March sell off. I have bought more this morning as the update seems very positive; and with the returning dividend they seem very good value for an income stock (dividend at least 7% and perhaps a lot higher if they get to the pre Covid levels).
They were unlucky with some of their royalty investments being in a river cruise firm (DUKE now own three river cruise boats!) and the company that owns Pearl and Dean cinema advertising.
Anyone have any thoughts?
Hi Nick
I think that the detailed update demonstrates the strength of the royalty model. The efforts Duke Royalty (LON:DUKE) have made to negotiate with, guide and support their (investment) companies that were/are having difficulties will it appears ensure the businesses remain solvent for when business returns to normal. This in turn means that the investments will possibly all make good returns, eventually. And of course the COVID success companies continue to grow with investment and support from £DUKE.
As well as the return of Divs it looks as if the market is pricing in reversing of COVID write downs.
I hold, and on the basis of this company update am looking forward to see what this company can achieve over the next few years....though I’m not expecting it to be a long term river cruise boat owner!
David Smyly
Totally agree with Nick and Martin on Duke Royalty (LON:DUKE). I have been determined not to be panicked out by the fall in the share price since March. I regard it as a very well managed company with excellent medium- to long-term recovery prospects. It would be interesting to know Paul's view.
Biz idea for Duke Royalty (LON:DUKE) - River cruises on the Rhine with the non-stop Pearl and Dean advertising music. Wunderbar!!! Baa Baa Baa Baa ...
Hi Nick
Duke Royalty (LON:DUKE) used to be one of the shares that Graham covered and held, I think that it was one of the ones he sold to fund the house purchase/wedding but would need to go to Cube to check.
I think that Graham had some concerns over the nature of the business being invested in and the long term implications of these e.g. recruitment companies from memory.
I think there is opportunities, but no longer hold.
Tommy
Graham was pre-empting a recession. At the time he was reviewing it - SP I presume was in its mid-40s. However, SP at close of day was 26.5p - so much of the bad news of a recession already factored in at this discounted SP
Re market view: I am petty sceptical about the sudden surge in markets, especially in financials, who trusts a bank still ? Very sceptical about Pfizer. CEO sells shares day of announcement. Doesnt he pay himself enough as it is? Looks a rush to market to beat the competition. The logistics of it 's distribution, extreme temperature control, 2 part injection etc all make it to me a less desirable option than AZN. I'll wait to see what the competition come up with thanks even if that includes missing out altogether. Its great that competition has brought about such determination to beat the bug but am mighty relieved that the health authority seem to be taking a very cautious view on COVID inoculation including Pfizer.
There are still good bargains to be had, particularly the ones that didn't surge with the injection rush, but keeping back plenty of fire power, and hoping that one or two surprises may yet confound the market. Which is another way of saying I hold at least 2 dodgy positions!
Norcros (LON:NXR)
Interims out today - all of the tickover variety as imporant numbers mostly flagged up earlier.. They will obviously be hit further by the current lockdown but they have proved remarkably resilient generally speaking so thats no biggie.
No reduction in pension deficit :( as RPI (is future RPI really gonna be 2.9%?) and bond yields going in wrong direction.
No intermin dividend but hoping for final one at year end - thats fine by me.
Exceptional costs of £2.1 mill are nonenity items thankfully only being intangible amorisation and £0.2 mill deferred remuneration. So very clean bill of health through a tough 6 month period.Fair play to them for not hiding anything below the line (or to the right of the column as some choose to do)
Finance costs significantly up - again no biggie here debt is well under control and they have a warchest available now should they so need it (distressed sellers form an orderly queue please). Invariably the hit with regard to financial derivatives being the biggest line item - nice earner for whoever programmed that (orange?) black box.
Share price shows very little sign of returning to pre covid peaks - main thing to me is they have survived intact shown some glimmers of potential for ogranic growth here and have reduced debt and kept the share count pretty much intact - so job will done.
Two of the biggest concerns with Norcros (LON:NXR) in the past have seemed to be the debt and the pension scheme. I would say those concerns are fading and in time would expect the share price to catch up.
Debt has reduced significantly, as highlighted in this release. The pension deficit is unchanged over the 6 months, but unless you look at Note 12 (and referencing Note 24 in the most recent annual accounts) you won't spot the progress here. In the 6 month period there have been "negative" moves in inflation and bond yields and yet no worsening of the position. It should be noted that this "snapshot" is Sep 2020, and since then we have had significant news re Covid. Bond Yields are now higher, as will the net asset investments be. Despite the quantum of excess deaths since March 2020 (the comparative "snapshot") no assumption changes were made with respect to mortality/longevity either.
The next actuarial review is due April 2021 (although this will take some time) so the funding commitments, and the cash flows associated with it that are unavailable to shareholders currently, could well drop. This news will take time to filter down to the share price I'm sure as few properly analyse the pension issue, and the market isn't wholly rational. So long as the underlying business remains good (and it appears to be the case), I am happy to hold longer term to capture this "reevaluation".
In addition to the debt and pension scheme, other concerns with Norcros (LON:NXR) are the large South Africa exposure, their acquisitive strategy, and the cyclical nature of their market. All of these represent risk factors IMO.
They are of course cheap, but not cheap enough to tempt me back in at this level, given the plethora of other cheap stocks in the UK to choose from at the moment.
which cheap stocks do you have in mind isallowance? Would you care to share some of them?
Sure. In the last few months I've bought Natwest (LON:NWG), Lloyds Banking (LON:LLOY), 1pm (LON:OPM), Newriver Reit (LON:NRR), Redde Northgate (LON:REDD), Just (LON:JUST) & Hargreaves Services (LON:HSP) in the value catagory. The unifying feature of all of these was (and still is I believe) a discount to tangible book value, in some cases really significant (< 0.5 TNAV). I recognise that most of them are leveraged to some degree or other, and hence that TNAV can be impaired more greatly than the actual capital impairment, but personally I think the discounts are overdone...
The banks: Apart from the insurers, these are the most leveraged, but so far COVID impairments at the UK banks have been covered by operating profit for the period and the lack of dividend, leaving tangible book values unchanged. COVID impairments made already have been greater than actual COVID defaults, so there is scope for upside surprise in future (and downside of course if it all really goes to sh%t!). My thesis is that if we get through this with TNAV largely unscathed than the banks will re-rate to close to TNAV, even in a lower interest rate environment.
Just (LON:JUST) - this is a life insurer, and a bit of a special case, they've been out of favour even prior to COVID due to scrapping the dividend due to regulator intervention over capital requirements for their equity release mortgages. I don't pretend to understand life insurance companies, but if Just (LON:JUST) are on 0.2 x TNAV whilst LGEN are on 1.4x ish then I see some possibility of convergence.
1pm (LON:OPM) - less leveraged from the banks.
Newriver Reit (LON:NRR) - Already have very cheap rents, so don't see them as affected as other shopping center REITs. Alternative use possibilities. Less leveraged than the banks.
Redde Northgate (LON:REDD) - Second hand vans are going at a premium at the moment. Even I've finally bought a van this year!
Hargreaves Services (LON:HSP) - Land. Probably all horrible contaminated brownfield so could take a while for the value to out.
I don't have anything against Norcros (LON:NXR) and have held it in the past, but I don't see any real catalyst for a re-rating, whereas for some of the above I see exit from COVID as a catalyst to re-rate back closer to tangible book value.
Sorry, probably written far too much. Obvs all IMHO, DYOR etc.
I used to hold Hargreaves Services (LON:HSP) a few years ago and sold out, when I sold everything to fund the family house.
It would be worth listening the the Castleford Tiger interview on PIWorld as it is one of his holdings from memory.
https://www.piworld.co.uk/2020...
thanks
i have looked at (LON:MAB) for a little while and as a COVID recovery play there range
of strong brands looked an ideal candidate. The financials also look strong .
i was lucky enough to get in an hour before the 'vaccine announcement' on Monday
which gave an SP lift of 20%, but i would still look at buying more on any weakness.
here is some info on Mitchells & Butlers (LON:MAB) - I dont hold
https://thecollective.finance/2020/10/mitchells-butlers-100-upside/
Hi Jack (now that I know it was you who read the market piece above)
So much depends on the true effectiveness of vaccine(s) and the length of the rollout. in the UK, even with 1m doses administered per week, and assuming 2 doses required per person, its going to be a long time before we are back closer to normal, with, for example, most people happy to fly. Those roll-out numbers need to be a lot higher for us all to have been vaccinated by the Spring, which seems like a complete BS suggestion.
Albeit I am nearly 4% down this week, I still feel happier invested in shares that are covid-agnostic or slight covid beneficiaries, with generally good business progres. The alternative is bombed out companies that may well struggle, with more fund raisings, for at least the next year, albeit they have had a great few days perhaps largely based on short closing.
All IMHO.
Cheers, Martin
Morning Paul
An awful lot happening this morning, not sure if Jack is about to lend a hand, but results and updates have come thick and fast.
Impressive results from Volex (LON:VLX), although have only skim read the interims. The Turkish acquisition looks very interesting and to my mind positive. Reading between the lines there appears to have been a 'fall out', with Daren Morris the CFO leaving somewhat abruptly to be succeeded by his deputy, Jon Boaden. A pity I think, but at least Mr Boaden succession provides continuity. Daren Morris is thanked somewhat tersely.
Also still trying to get to grip with the details of Smiths News (LON:SNWS) prelims, but the stock is just too cheap in my view and the business is at last starting to sort itself out. Finally Tt Electronics (LON:TTG) provides a steady as she goes update, with reference to Virolens, which may still 'have legs'.
I hold all of the above.
Best wishes
Hi Paul and Jack, £OWH Ocean Wilson Holding have updated the market today. They are resuming dividends of 40c per share cut off 20/11 and their invest portfolio alone is worth £6.11 per share so the port services are pretty much thrown in at the moment. The share price bombed out with Covid as it became impossible to assess, Jupiter have been reducing their holding keeping the price at around £6.20 but now seeming finished selling, allowing it to creep up. I sold out of this when the market turned in March and brought back in yesterday. The reasons I like this share are, they report in extensive detail and disclose the good the bad and the ugly very carefully and simply. They are old money and have plenty of skin in the game and experience. They pay good dividends, I can’t see too much downside but plenty of upside potential. I just wanted to flag this as it’s not normally covered here but might be if interest to folks. I’m no expert at balance sheet analysis I’d like to add, so please all dyor hopefully Jack or Paul might take a look if they have time. Any counter comments would be very much welcome.
sorry that should be £OCN
@TStubbs
The Ocean Wilsons Holdings (LON:OCN) intestment portfolio includes "cash under management" according to the RNS. How much of the NAV of the investment protfolio actually belongs to OCN?
Morning,
Good results from IBPO this morning. Revenue down due to Covid, but increased profits, margins and divi!
Will you cover?
Regards.
Promising update from Volex (LON:VLX) this morning with news of the purchase of a similar Turkish power cord company DEKA:
· Acquisition multiple represents 6.9x DEKA's expected 2021 EBITDA
· Acquisition is expected to be earnings enhancing after the 1st full year of ownership
· Following the Acquisition, Volex's ROCE is expected to exceed 25% (StockReport today 12% ROCE)
Sounds transformal to me - (I hold) Ian
Just topped up this morning.
yes so I’m surprised by the fall today. I’m a LTHer.
CFO leaving has created uncertainty and spoke a few. Looks like a fallout with Nat.
I still hold but will be wait to see today presentation
The CEO of Novacyt has bought 60,875 shares in his company at a price of £8.17 per share, i.e. a total cost of £497,349:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-directorpdmr-shareholding-urn:newsml:reuters.com:20201112:nRSL0564Fa/
I hold.
Morning pka - I believe the word used is acquired, bought to me mean means money changed hands. Aquired does not necessarily suggest any monies changes hands Yes I'm a pedant
Morning ezlifeme,
This tweet suggests it was bought:
https://mobile.twitter.com/E16343676/status/1326531406227533826
Perfect and thanks for the clarification - Only Q is why can't a NOMAD call a spade a domestic agricultural hand operated tool usually manufactured from steel and wood
Excellent (I hold too)!
I saw this this morning (I hold Novacyt Sa (LON:NCYT), was largest now third largest position) and was wondering whether a genuine purchase or some sort of option reward or something so did not tweet it out.
I assume that it is a genuine purchase at £8.17? If so that is a serious chunk of money, for somebody one assumes is not independently wealthy and relies on his income from Novacyt?
Thx.
Regards
Michael
Hi MichaelFBS,
I understand that Novacyt's CEO received a large cash bonus in recent days and he may have used some of that money to "acquire" the £497k worth of Novacyt shares yesterday. But I don't think he had to do that, so it seems to indicate that he believed the shares at yesterday's price are good value.
Thank you.
My morning smallcap tweet:
Bango (LON:BGO) TT electronics (LON:TTG) Redcentric (LON:RCN) Manolete Partners (LON:MANO) Anexo (LON:ANX) NWF (LON:NWF) Duke Royalty (LON:DUKE) LPA (LON:LPA) Powerhouse Energy (LON:PHE) Mediazest (LON:MDZ) Brickability (LON:BRCK) Norcros (LON:NXR)
Bango (BGO) has expanded its partnership with Microsoft to open-up access to Xbox subscriptions and consoles sales. "Unique Bango data insights optimize the targeting of product bundles to boost consumer engagement. " No £££. [SP=155.99 Cap=116m]
TT Electronics (TTG) trading: seems in line. Re mfr of too-good-to-be-true covid ultra-rapid screener invented by a 4 man band: "There remains a wide range of possible outcomes but Virolens® is proceeding through regulatory approvals and devices have been shipped to initial launch customers for operational trials in a number of different jurisdictions." [SP=224 Cap=390m]
Redcentric (RCN) For Sale flag lowered because "discussions did not materialise into any fully funded offers". H1(Sept) rev up 7% and adj EPS 3.61p up 50%. [SP=129 Cap=201m]
Manolete Partners (MANO) gets £2.8m net cash from case end, in line with book value. Payable over 3 years. [SP=302.5 Cap=132m]
Anexo (ANX) in line. DBAY Advisors buys 29%, co seem excited by this. [SP=134 Cap=155m]
NWF (NWF) hacking ('cyber incident') - incident has been contained and unlikely to result in any material impact on underlying trading. Cost c. £0.5m net of insurance claims. [SP=194.4 Cap=98m]
Duke Royalty (DUKE) 7 of the 12 royalty partners maintained cash payments throughout. "In addition, the Company delivered additional capital to its Royalty Partners which experienced growth opportunities during the pandemic. Furthermore, Duke's first partner exit was achieved with a successful cash-on-cash return in excess of 1.5x." Resumes 0.5p/Q divs. [SP=25.2 Cap=65m]
LPA (LPA) H2 rev slowed slightly but has since increased. Rev still slower than normal some parts of the Group. Guides H2 profit up vs H1. Plans to restart divs. [SP=91.3 Cap=12m]
Powerhouse Energy (PHE) non-binding Heads of Terms with Hydrogen Utopia International in Poland for a potential licence. [SP=2.65 Cap=98m]
MediaZest (MDZ) trading has continued to be encouraging. Ongoing roll out projects have restarted and are continuing during Nov. [SP=0.04 Cap=1m]
Brickability Group (BRCK) H1. The strong recovery continue into H2. [SP=49.6 Cap=114m]
Norcros (NXR) H1(Sep) rev down 25% or 17% in const FX. U/L pretax down 31%. Div passed. Q2 rev up 4.5% though. [SP=184 Cap=148m]. I hold.
Good morning Paul, I wondered if you might want to revisit Brickability (LON:BRCK) Brickability after their HY results today which read pretty well. I saw you looked at it after the FY figures and although had no strong view wondered whether it might be an interesting sector to revisit.
The numbers reported today suggest the company has recovered strongly from tough months in April/May and that the strong improvement in trading has continued into the second half (Oct/Nov).
Performance in the six months to end Sep reported a 23% decline in sales but only a 17% declines in gross profit after implementing measures to reduce costs. The declines were mainly due to the lockdown and although unprofitable in April, the company returned to profitability in May and in each month since. There is a small amount of net debt on the balance sheet, £2.7m, but the board is sufficiently confident in the prospects to be paying an interim dividend.
Chair John Richards is particularly bullish, talking of a V shaped recovery which continues to improve, and CEO Alan Simpson talks of rapidly increasing demand from the housebuilding sector.
If you want to hear more on the company and its prospects there is a webinar on Monday 16th at 12pm. Register https://us02web.zoom.us/webinar/register/6316037876681/WN_LM_pR6tXRlyLL5DU40d4aQ
TTG possibly on the cards? I did have communications with certain parties about the FT article on IABRA. It seems they are not in agreement about the content of that article. How does HollandSmith gather all that info so quickly? Deserves a gong
Super fast fingers! :)
I use strategic automation to present decisions that we as humans are positioned to fully understand. I have fully automated my trading selection from this, and just publishing a part of the process here. If there is interest - I could also broadcast my upcoming trades selection here, but I believe I already take up to much digital real estate at the moment.
The future of financial advice will be where human use artificial intelligence and automation to become smarter and more efficient at doing their jobs, so jump on board! :)
Cheers HS . I think I know what you mean. fine by me.
Good morning HS. Your contribution to this platform is hugely impressive, thank you. I can’t say I understand how you use “strategic automation “ or how you fully automate your trades. I am not sure that any written explanation would help me to understand so this is a request to you and Ed to present your methodology and use of AI tools via a video presentation.
I would welcome seeing your picks Holland, as well as hearing a podcast too
// Half-year Report
// Total return of £1,142 million or 15% on opening shareholders' funds (September 2019: £767 million, 10%) and NAV per share of 905 pence (March 2020: 804 pence)
// Burberry Interim Results
// H1 FY2021 saw a 31% revenue fall with adjusted operating profit down 75% and adjusted diluted EPS down 88% (reported diluted EPS down 66%).
// Half-year Report
// Group revenues increased by +25.3% to £2,242.1m, +25.3% on a constant currency basis.
// ITV plc - Q3 Trading Update
//
Total external revenue was down 16% at £1,860m (2019: £2,209m)
Total ITV Studios revenue was down 19% at £902m (2019: £1,116m)
Broadcast revenue was down 13% at £1,270m (2019: £1,464m)
// Half-year Results
// The Group's 1H21 revenue was down 7% at £1 411m (1H20: £1 515m) and down 5% in constant currency terms.Group adjusted EBITDA at £171m was down 32% (1H20: £252m) in both reported and constant currency terms.
// Preliminary Results
// Covid-19 has had a significant impact on the Group, particularly in the second half of the financial year. Total Group revenue was down 27% compared to last year at £1,021m (2019: £1,397m) with Group LFL revenue down 33% (down 64% in the second half).
// Trading Update
// Revenue and profitability in the four months to 31 October 2020 ahead of expectations· Adjusted operating profit1 guidance for second half increased to £130 - £140 million range· Net cash position before lease liabilities increased to £150.0 million at 31 October 2020 (30 June 2020: £58.6 million)
// Half Year results for period ended 30 Sept 2020
// Underlying operating profit down 12% to £1.1bn Statutory operating profit up 13% to £1.1bn
// Third Quarter 2020 Trading Update
// We are pleased to see continued strategic momentum and the Board remains confident that the Group will show progress in 2020. Our expectations for the full year remain unchanged.
// Trading Statement
// Housebuilding has secured 3,237 plots across 16 developments totalling £179.2m and has a strong land pipeline, with 100% of land required for forecast FY21 completions secured.Partnerships is investing in its owned land bank to support its targeted step-up in mixed tenure completions to 3,000 units by 2022.
// Trading Statement
// For the 4-month period ended 31 October 2020, sales to the Domestic end market were up 10 per cent on a like for like basis compared with the prior year
// Trading Statement
// The trend of improving revenue performance has continued, with around 70% of last year's revenue secured in October compared to around 60% in August. We continue to generate positive EBITDA, with October delivering the highest monthly total in 2020 to date. We retain significant liquidity and expect to close the year with around £1.5 billion in cash and undrawn committed facilities.
// Trading Update
// On a constant currency basis, our sales in Q3 were up 7.0% quarter on quarter and although down 14.3% year on year, this is an improvement on the sales decline of 26.2% in Q2 compared to Q2 2019.
// Trading Update
// The Group has seen an encouraging recovery in trading during the period, with revenue of £235.2m, 3% lower than the same period last year (2019: £243.6m).
// Pre-Close Trading Update and Board Changes
// The Board considers ARR as the Group's primary growth metric and the driver for long term value. ARR recognised during the first half is expected to be £24.4m (H1 2019: £20.3m), representing 83% of total revenues, up from 74% in the comparative prior period.
// Half-year Report
// The lengthy 16 weeks' closure has had a significant impact on our results, and the business had an initial cash burn between £4.0 million to £5.0 million a month. It was the closure period that solely contributed to an operating loss of £16.9 million, and a loss before tax of £21.8 million. When excluding our £2.6 million of adjusting items, we recognised an adjusted operating loss of £14.3 million and an adjusted loss before tax of £19.2 million.
// Interim Results
// Revenue reduced by 7.6% to $54.9m in H1 2021 (H1 2020: $59.4m), due to reduced business from some clients in India.
// Trading Update and Notice of Interim Results
// Clipper has continued to see strong trading across the business in the year to date, benefitting particularly from the continued structural shift to e-commerce that has been accelerated during the ongoing Covid-19 pandemic. The Group expects to report revenue for the period of at least £300m, an increase of almost 20% against the prior year comparative period, including e-fulfilment logistics growth of over 30% and non-e-fulfilment logistics growth of approximately 10%.
// Trading Update and CMD
// Restore is consistently number 1 or number 2 in the markets we serve, with very good customer retention and highly predictable recurring revenues. The total market size across all our end markets is estimated to be c£1.9bn and with only c11% market share in these highly fragmented markets, there remains significant opportunity to expand our market share.
// Half-year Report of Volex plc
// Revenue for the first half of the year is up by 3.5% on the comparable period in FY2020. We have seen some variations in customer demand due to the pandemic.
// Half Year Results
// We have delivered a positive total return of 0.7% over the six months and our net assets have dipped only slightly to £506 million, still reflecting a net asset value of 93 pence per share.
// Trading Update
// Momentum in the Group's trading performance has continued as expected, with the trends in like-for-like revenue improving in the four months to October. Revenue in the period was 11 per cent lower than the previous year on a constant currency basis and 12 per cent lower on an organic basis.
// Interim Results
// "Urban Logistics is extremely well placed to benefit from this market backdrop. We have a unique investment strategy based on management's considerable industrial and logistics experience. Over 90% of our assets are purchased off-market and we take a stringent approach to tenant selection. We have collected over 99% of rent demanded for the March, June and September quarters in 2020.Despite Covid-19, Urban Logistics has made significant progress over the last six months.
// Q3 Trading update, Dividend & Strategic Review
// The Group also completed a number of lease renewals during the quarter, achieving rental uplifts of 12.2% versus previous rent. Retention of occupancy by area remains high at 90.2% as 83.9% of units with lease renewals remain occupied1.Further to the announcement made on the 17 September 2020, the Board will pay a dividend of 6.4pps for the full year 2020, which it is expected will be fully covered from EPRA earnings, and equates to an annualised dividend yield of 8.3% at the close of 11 November 2020.
// Results for nine months ended 30 September 2020
// Total income
£85.0m - last year £256.9m
// Results for the quarter ended September 30, 2020
// Gross revenues of $25.4 million, a 27 per cent increase on the $20.0 million achieved in the third quarter of 2019 ("Q3 2019").·
// Half Year Results
// Total revenue increased by 7% to £46.2m
// Trading and Operational Update
// Premier's production averaged 62.5 kboepd for the 10 month period.
// Interim Results
// Half year revenue of £135.3m (2019: £181.2m), 75% of prior year revenue on a reported basis and 83% on a constant currency like for like basis,
// Brickability Group plc - Interim Results
// The Group delivered revenue of £75.3m in the first six months of 2020 (H1 2019: £97.9m), representing a total decrease of 23.2% (£22.6m).
// Quarterly Financial Results
// The contingent consideration payable to Xstrata Brasil Mineração Ltda has a carrying value of £3,176,017 at 30 September 2020 (30 September 2019: £4,640,847).
// Audited Preliminary Results
// Adjusted profit before tax from continuing operations of £27.9m is down by 25.8% (FY2019: £37.6m) and Adjusted Earnings per Share of 9.7p is down 15.7% (FY2019:11.5p).
// Trading Update and Reinstatement of Cash Dividend
// The Company's cash position has increased by 122% to £6.0m as at 30 October 2020, from £2.7m in April 2020.
// Unaudited results ended 30 September 2020
// Acquired 85% of the land within the permitted La India open pit mine site infrastructure, including the key areas of the location of the processing plant, tailings storage facility, open pit, waste dump area, explosives magazine.
// Results for the six months to 30 September 2020
// Turnover was down 26% to £14.4 million and losses in the six month period to 30 September were restricted to a pre-tax loss of £0.2 million//
// Trading Update
// Activity in the second half of FY20 slowed slightly as some customers temporarily closed sites due to worldwide lockdown restrictions. However, whilst activity has since increased, we are still experiencing slower than normal revenues in some parts of the Group, particularly around the aviation sector.
// Interim results for the six months
// International revenue (sales outside North America), at $1.9m, represents 74% of total revenue, compared to approximately 30% in the previous full year period ($3.2m) and 42% in equivalent period ending September 2019 ($2.8m). New customers in China represent 70% of the period's international sales.
// Half-year Report
// Our trading performance for the six months until September 30th was quite a lot better than feared but still only produced a small profit of £6k before exceptional items (2019: £363k), on sales of £4.850m (2019: £6.920m).
// Trading Update
// Ongoing contractual income remains robust and the renewal rate of such recurring revenue streams has been strong.The differing terms of the second "lockdown" mean that many projects continue to be delivered, with additional safety and social distancing measures.
// Financial results for the third quarter of 2020
// Revenue for the third quarter 2020 totalled $1,454 million, up 26% compared to the previous quarter.
// Interim Results
// We grew orders by 37% (17% on an organic basis) and delivered revenue growth of 24% (8% on an organic basis), with operating profit margins within our short-term target range at 11.4% growing operating profit by 16% (flat on an organic basis).
-----------------------------------------------------------------------------------------------------------------
Also, heres a map of PLC companies which is a visual way to discover
listed PLC companies in your location, and question how many degrees of
separation there is between you and the knowledgable people within them.
Click here to view the map
-----------------------------------------------------------------------------------------------------------------
Thanks
Dan
Also, heres a map of PLC companies which is a visual way to discover
listed PLC companies in your location, and question how many degrees of
separation there is between you and the knowledgable people within them.
Click here to view the map
Dan - I think this is a facinating idea. If this could be used to encourage more local investor days, for instance, that would be interesting (post covid of course).
Unfortunately for me, being up on the Moray coast there is only one company within a couple of hundred miles, but you have got me thinking about drawing up a list of PLCs in the central belt for closer inspection.
Thanks for the great work.
Jonny
Map is a fantastic idea. Thank you.