Small Cap Value Report (Thu 13 April 2023) - TET, INCE, WJG, SIS, PZC, LINV, MRK

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
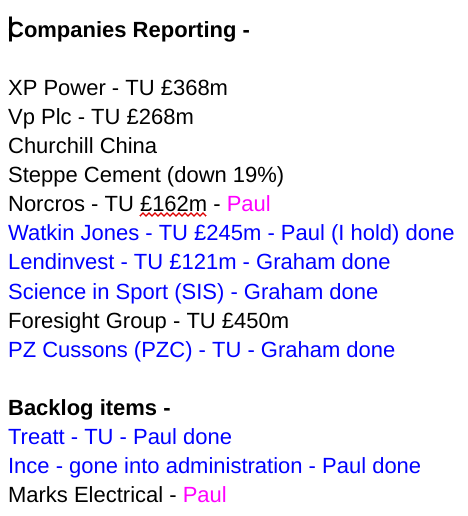
This is what we're going to attempt to cover today - making good progress at 09:00, so time for a tea break before tackling some more on the list. I'll also check the top % movers table, to see if there's anything interesting going on that is not on ze list -
Summaries of main sections
(more detail below)
Treatt (LON:TET) - H1 TU - up 6% to 622p y’day (£375m) - Paul - AMBER
H1 trading is strong, in line with expectations. Outlook section hints at possible upgrades later this year. I like the company, but my main concern remains the lofty valuation, discussed in more detail below.
Watkin Jones (LON:WJG) - H1 TU - down 3% to 93p (£239m) - Paul (I hold) - GREEN
Seems reassuring about H1 and the outlook. Although a project in Exeter has been hit by unexpected costs, due to a contractor going bust - it would have been helpful to give some idea of the size of this impact, which is missing. Heavy H2 weighting, as previously indicated. It's good value, I think, with a nice lower risk business model (forward selling developments before construction starts).
Science in Sport (LON:SIS) - Strategic review concludes / TU - up 6% to 9p (market cap £16m) - Graham - AMBER
The strategic review is over; The growth plan will continue with emphasis on profitability. Margins should improve but quality shareholder returns are far from certain.
PZ Cussons (LON:PZC) - TU - up 4% to 195.4p (market cap £838m) - Graham - AMBER
I’m on the fence between Green and Amber with this. Full-year profits are trending at least in line with expectations, helped by currencies, as inflation continues to get passed onto customers.
Lendinvest (LON:LINV) - full-year TU in line with expectations - up 1% to 87.5p (market cap £122m) - Graham - AMBER
Reassuring update that this property platform and investor is on track to report expected profitability. Superficially cheap but highly leveraged property play.
Marks Electrical (LON:MRK) - FY 3/2023 TU -
Quick comments
(no additional detail below)
Ince (LON:INCE) - a wipe-out for shareholders of this legal/accountancy group. It announced yesterday afternoon that a major creditor was withdrawing support, so it has no choice but to appoint an administrator. Hence shares suspended, and almost certainly worth nothing. We’ve been strenuously warning SCVR readers away from this share for years, so I very much hope nobody here was caught on this one. It’s staggering how inept many accountants seem to be at managing their own affairs - this being the latest in a series of disastrous listed firms of this type. I remember joking with Ric Traynor, the boss of Begbies Traynor (LON:BEG) a few years ago, that his firm seemed to be (at the time) the only one that hadn’t gone bust, and he agreed, calling BEG the last man standing in its field of listed rivals. That was before FRP listed, which has done OK so far.
INCE going under reinforces my resolve to completely avoid all of these people businesses where there’s an inherent conflict between fee earners and outside shareholders. INCE seems to have been staggeringly badly run - see our archive here for the whole sorry INCE tale.
Paul’s Section:
Treatt (LON:TET)
622p (up 6% yesterday)
Market cap £375m
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, announces the following trading update for the half year ended 31 March 2023 (the "Period").
The current financial year is FY 9/2023.
I keep a close eye on this company, as it’s always intrigued me. Our last review was here in Jan 2023, when it said Q1 (Oct-Dec 2022) was trading in line with expectations.
This share always looks expensive, but the bull argument is that all its larger competitors are also expensive (on high PERs). Plus TET has built a new factory, which will double capacity once it’s fully online - I’m more convinced by the second point, but not the first! Just because other investors are overpaying for an asset, doesn’t convince me to follow their lead. Although it could make TET a takeover target from a highly rated industry giant.
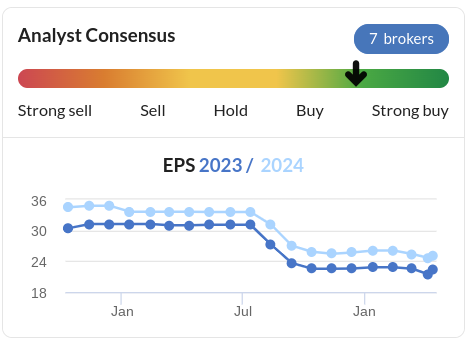
So to be bullish on TET, I think by implication you’re expecting it to out-perform broker forecasts, which so far it hasn’t. Indeed forecasts have come down a fair bit -
Turning to yesterday’s H1 trading update, this all looks reassuring -
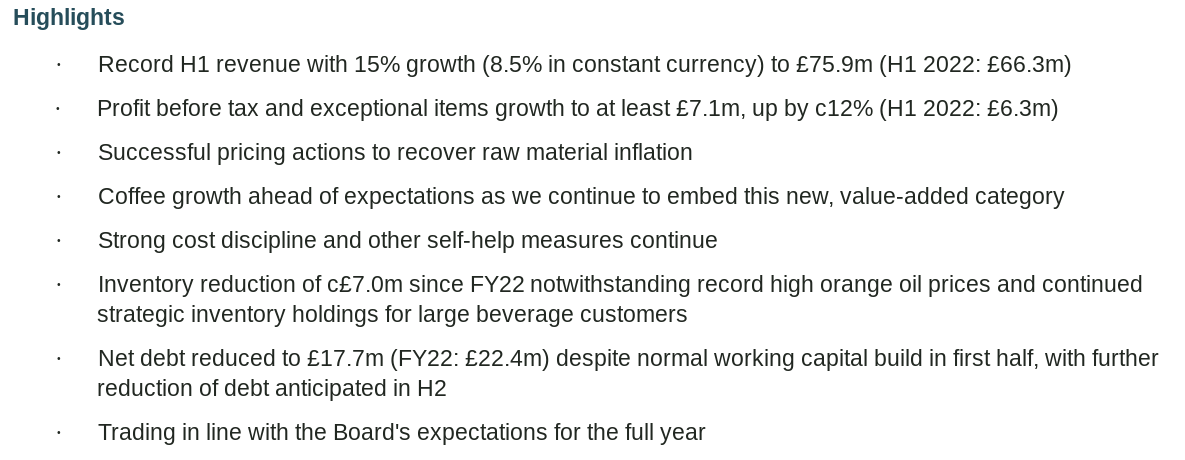
Nothing of concern there, but only in line with expectations again, which I don’t think is good enough, considering the shares are rated at 28x broker consensus earnings estimate for FY 9/2023. But the market was happy with it, as the share price rose 6% yesterday.
There’s lots more detail in the announcement, but nothing of any earth-shattering importance.
I’m particularly keen to learn more about expansion plans, with the new factory now up & running. It says this -
After substantial investment in our people and production facilities in the past 18 months to support the Group's next phase of expansion, we do not anticipate any significant increase in administrative expenses in the short to medium term, above the normal rate of inflation. The group headcount has reduced by 6% since September 2022 with the benefits of relocating to our new UK facility beginning to show the expected efficiencies.
Debt - isn’t a problem anyway, but it’s set to reduce further -
The Group has decades of experience managing raw material price movements which are impacted, not only by general inflation, but also by specific supply and demand factors such as climatic conditions. We anticipate a further reduction in net debt in H2 in line with market expectations.
I wonder if the widely reported recent falls in food prices will help boost TET’s future profit margins, or if customers will seek discounts to reflect lower costs?
Outlook - this is the best bit, and the way I read this, it sounds as if they’re warming us up ("at this stage") for a possible beat against expectations in Q3 or Q4 -
The Group has started FY23 strongly and we have good confidence in Treatt's proposition and its ability to deliver top line growth, supported by positive market dynamics.
Q2 momentum was particularly encouraging and we enter H2 with a strong order book and conversion of sales pipeline.
At this stage, we expect to report full year profit before tax and exceptional items in line with the Board's expectations.
Diary date - 9 May for H1 results to 31 March. That’s a prompt reporting schedule, which I like - it usually means the financial controls are good, if the accounts department can report promptly. Or they’re just winging it, with estimates ;-)
Paul’s opinion - much the same as I always say for this company - it’s a nice business, and improving now that it has a spangly new factory. H1 figures and outlook both seem pretty good.
However, that solid performance seems priced-in to the shares already. I could cope with PERs over 20 in the zero-interest rate world, but not any more. This share should probably be on a PER of 15-20 in my opinion. So at 28x current year, and only an in line update yesterday, it’s difficult to see any immediate upside here.
With raw ingredients now falling in price apparently, and good demand, then the real PER could be much lower of course, once it’s put out an ahead of expectations update later this year, which is slightly hinted at, in the outlook section. Trouble is again, the share price is already anticipating that.
Longer term, it seems to be in a nice sector, and if TET can drive up utilisation of the new factory (potentially doubling volumes) then I can see a nice long-term story developing.
In conclusion then, I’m positive about the company, but the high valuation means on balance it has to be a neutral overall view, AMBER.
There's been a fair bit of progress made in the last 5-years, but the share price hasn't really achieved that much at this point overall, and dividends have been paltry, since there's not been any free cashflow as the heavy capex programme (now largely complete) has consumed the cash generated. I do wonder, is this company really as high quality as everyone seems to think? I'm only asking the question, don't shoot the messenger! It's not obvious from the historic numbers anyway.
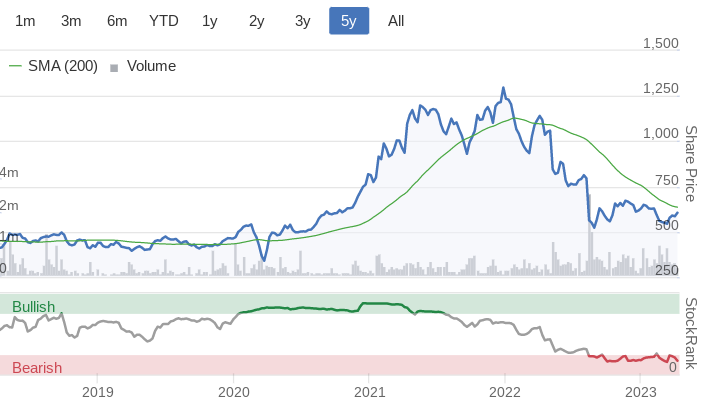
Also note the StockRank has plunged, and is now low - with Stocko's algorithms currently viewing this as expensive, and not very good quality -
Watkin Jones (LON:WJG) (Paul holds)
93.2p (down 3% at 08:20)
Market cap £239m
This covers the 6 months to end March 2023, being H1 of FY 9/2023.
Watkin Jones has an interesting, differentiated business model. It builds mainly student accommodation (but also build to let is increasing), but crucially these developments are forward-sold to institutional buyers, before they’ve been built. So WJG has very little risk, other than cost over-runs, which have tended not to be an issue historically.
It gave detailed guidance at the start of 2023, saying that a softer H1 was expected as margins tighten. However, it seemed upbeat about the future, saying that institutional investors were coming back into the market, after a hiatus caused by the mini budget, and rising interest rates.
Rents to the end occupiers are rising strongly, hence there is still appeal to this niche, although building margins are likely to be trimmed somewhat from the days of zero interest rates.
I watched the company’s last investor webinar, and was impressed with how the very experienced team at WJG seemed to be on top of all the issues, and very open about softer margins expected in H1, so hopefully no surprises. That’s why I’ve continued to hold a small position in this share personally, for the recovery potential with little risk, and the nice divis are a bonus too.
Costs of remedying buildings following stricter rules after Grenfell are a downside risk though, and the provision has already been increased considerably. What’s the betting further increases happen? Quite high I’d say, but obviously safety comes first, but somebody (shareholders) have to pay for it.
Here’s the main body of today’s update for H1, which I think is self-explanatory.
I wish companies wouldn’t use abbreviations, or at least put an asterisk to a footnote explaining what they are.
PBSA is - purpose built student accommodation.
BTR - is build to rent.

My only other complaint is that I would have liked a rough indication of the financial cost of point 1, the contractor going bust.
Other than that, everything else looks fine, even encouraging.
Paul’s opinion - looks fine to me, so I’m happy to continue holding a small position with a medium term view, and might load up when the interims come out, as we could get a dip when relatively poor (expected) H1 figures are issued. So I’d like to keep some powder dry for that eventuality, to buy any dip.
Longer term, I think this share has lots of recovery potential, without all the risks that you have to take with other property investments.
So it gets a thumbs up from me, as good value - I think the share price has been overly beaten down with the sector generally, providing a buying opportunity for us, hopefully, if we’re patient.
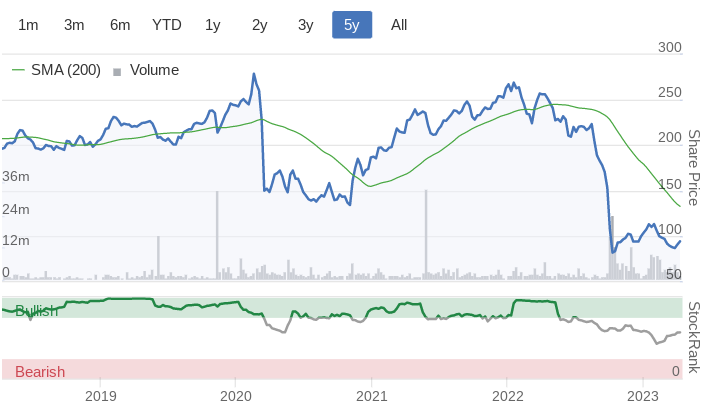
I'm generally now switching from 3-year to 5-year charts, because the 3-years are losing the initial covid impact, which is important for perspective (as the March 2020 lows show the key turning point price, where investors stopped selling, and became net buyers) - then of course the everything rally that started when the vaccines were authorised in Oct 2020 -
Marks Electrical (LON:MRK)
88p
Market cap £92m
I last looked at this online retailer of electrical products here in Jan 2023, when it issued an in line Q3 trading update, with YTD revenues up 22%. I baulked at the 98p share price suggesting it had got a bit ahead of itself at 19x forward earnings.
This update came out yesterday -
Marks Electrical Group plc ("Marks Electrical" or "the Group"), a fast-growing online electrical retailer, provides a trading update for its fourth quarter ended 31 March 2023 ("the period" or "Q4-23"), ahead of announcing its Full Year Results for the 12 months ended 31 March 2023 on 14 June 2023.
The company’s view of its own performance is -
Continued revenue growth, with margin expansion and strong cash conversion
Q4 revenue growth was very similar to previously, at +20% vs last year (LY).
The total revenue for FY 3/2023 is £97.8m, and growth for FY 3/2023 vs LY is an impressive +21.5% - that’s well above inflation, so indicates volume, as well as price growth.
Gained market share.
Gross margin rose in H2 (as expected).
Full year adj EBITDA: above £7.5m (Canaccord says consensus was £7.3m, so this is a modest beat)
Closing net cash of £10.0m, thanks to working capital improvements.
Quite a long way down the announcement, it seems to be saying that results are ahead of expectations - surely that good news should have been right at the top within highlights, and in the headline? -
After an improvement in profitability in the third quarter, we continued this trajectory with improvements in gross margin and operational leverage, allowing us to exceed our full year targets on profit and cash conversion, even as we grow market share.
Outlook - a “positive start to April”.
Valuation - many thanks to Canaccord for its update note on Research Tree. It increases FY 3/2023 to 4.7p - note this is still down on 5.0p LY, so we mustn’t get carried away here.
At 88p per share, that gives us a PER of 18.7x, which for me is still a bit too rich.
Investors have to weigh up whether you’re prepared to pay a highish price tag, to reflect the strong organic growth, and the fairly good profit margins in a highly competitive sector - which suggests to me that MRK is the most efficient operator in this sector as it’s beating margins made by £AO. and much larger Currys (LON:CURY) (which has a diabolical balance sheet, by the way). Actually, despite being the smallest of those 3 electrical retailers, I’d say that MRK is by far the lowest risk. CURY is dangerously reliant on credit from suppliers, and has a large, negative NTAV. AO has a lot of on balance sheet risk from extended warranties.
MRK is free of both those significant problems. I also like its one-site, own logistics & distribution model, which seems more efficient.
Paul’s opinion - a thumbs up for the business, but I’m not comfortable with the current valuation, which for me, is too high for this type of business.
Hence purely due to valuation, I’ll have to go for AMBER. Although I would be happy to snap up a few of these shares the next time the market throws a panic & people start selling. It looks a fundamentally good, growing, entrepreneurial business.
If you watch any of the webinars from MRK, you’ll get a master class from the founder on how to run an efficient business. Actually, I think I’m talking myself into buying some MRK shares!! This should do well long-term, I reckon.
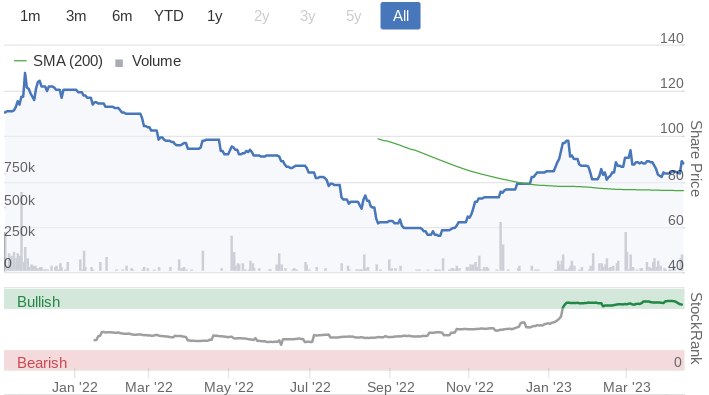
There's a lovely high StockRank too -
Graham’s Section:
Science in Sport (LON:SIS)
Share price: 9p (+6%)
Market cap: £16m
I reviewed the merits of this stock at the time of its February trading update here.
This morning, we have news that the strategic review announced last September is finally over. Here is the conclusion:
…the Board has concluded that shareholders' interests are best served by seeking to maximise value through focusing on accelerating the profitable growth of the business under an ambitious growth and efficiency plan that is currently delivering in line with management's expectations.
I interpret this as saying that there will be no major change in direction.
However, when we look at the “key drivers” for the decision, we find that three of the four bullet points emphasise the company’s prospects for improved profitability. Perhaps the company is getting serious about the need to stop bleeding money, year in and year out?

The company believes that its two brands - PhD and Science in Sport - have “significant differentiation and superiority”, and can “attract new users and retain loyalty”.
Its new manufacturing, distribution and warehousing facility in Blackburn is now complete: “The cost benefits of the facility, now being delivered, are expected to provide operational leverage and expansion capacity over the foreseeable future for continued operationally leveraged global growth.”
It says that it has a “comprehensive profitable growth plan”, but I don’t think it gives too much away about the specifics of this plan.
It points to growth in the overall sports nutrition market, it points to its distribution partner Flywheel Digital, and it points to its sponsorship of the Shanghai Marathon.
The most compelling argument it makes, in my view, is the argument that manufacturing its own bars in the Blackburn facility will improve its margins. Although I have more to say about that below.
In summary, the strategic review has concluded without any of the fireworks or dramatic decisions that may have seemed possible at the outset. The company will continue on its current path, but perhaps with a greater emphasis on bottom-line profitability?
Trading update - there is a “good start” to 2023. Q1 revenue is £15.6m, up 2.3%.
And some evidence of improved margins:
Q1 trading contribution margin was 20.9% (FY22 13.7%), delivering a significant improvement over the comparative period, because of the implementation of the growth plan. Overheads were in line with management expectations.
Graham’s view
I’m hopeful that this stock might finally come good and deliver on its promises. I also note that it remains very cheap on a price/sales basis. But we mustn’t get too carried away.
Actually, I can explain in a mathematical way why investors should not get overly excited by the fact that SIS has increased its margins by bringing its production in-house.
Here’s a well-known formula for return on equity::
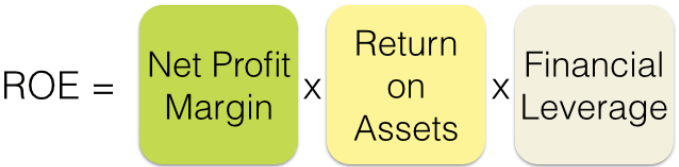
These are the three major levers for increasing a company’s ROE.
When a company starts doing manufacturing work that it previously outsourced, its margins will improve because it no longer has to pay the profit margin for the outsourced manufacturer that it’s no longer using.
However, this comes at a price in the form of a higher asset base. The company now has to own and maintain all of the necessary manufacturing equipment. All else being equal, we should assume that return on assets, the second lever of ROE, will decrease.
What this means is that we can’t say for certain that ROE will improve. We can reasonably expect that the profit margin will improve and that return on assets will deteriorate, but we don’t know for sure what will happen to ROE. It will depend on which factor outweighs the other.
In other words, SIS still has everything to prove when it comes to the profitability of its current strategic direction.
I do think that its brands are impressive and that the stock has potential, but I’m not ready to give it the thumbs up just yet.
Also, while this is unconfirmed, I expect that the company’s current cash position is quite weak. There has been no update on this but the amount raised in the most recent placing was not enough to settle its last-reported net debt position. Another factor to be aware of.
PZ Cussons (LON:PZC)
Share price: 195.4p (+4%)
Market cap: £838m
Let’s take another look at this FTSE-250 member. I also wrote a few words about it in February.
Here is today’s Q3 update, with expected full-year profits “at least in line with expectations”:
Like-for-like revenue growth 6.2% for the quarter (in line with expectations), or 6.1% year-to-date.
“Europe and the Americas region back to strong revenue growth and with significantly improved margin” - like-for-like revenue growth here was 9.9% for Q3, much improved on prior quarters.
Strategic progress with “Must Win” brands, including dishwasher products and baby lotions.
Once again, it is price/mix movements that are driving the revenue growth, rather than volumes. In an inflationary environment, we have to remember that successful companies are going to pass on input cost increases and that this doesn’t necessarily represent “real” growth.
Reading further down the report, to the outlook statement, I see that there is a 3-4% currency benefit from translating foreign operations, and this is boosting expected full-year profits. Perhaps the company isn’t really outperforming by much at all, if you exclude that tailwind?
Graham’s view
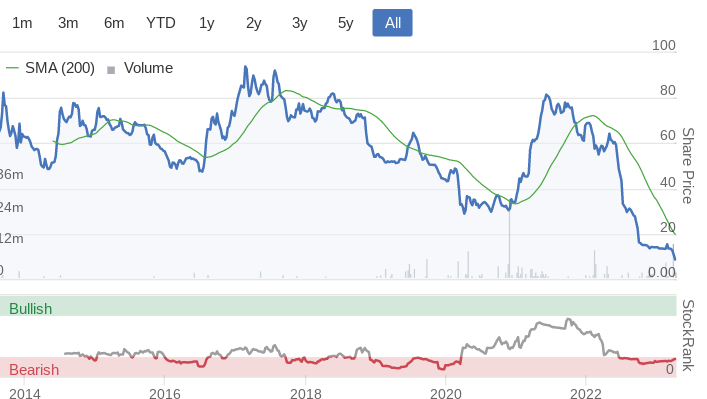
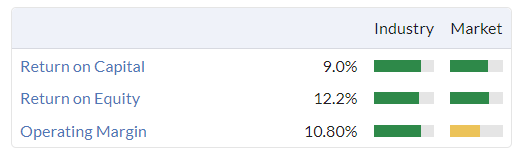
I don’t think this trading update changes things so I’ll wrap up my comments on it quickly. The bottom line is that I still consider this to be a fine company and I wouldn’t mind owning a few shares in it. Performance does need to tick up a little, so I’m on the fence between Green and Amber:
Lendinvest (LON:LINV)
Share price: 87.5p (+1%)
Market cap: £122m
This is a full-year update from Lendinvest, which describes itself as “the UK’s leading platform for mortgages”.
You may recall that it issued a profit warning back in October 2022, when it repriced its products and reduced its lending appetite, in the midst of rising interest rates, falling property prices and mortgage market disruption.
Today’s update is reassuringly in line with expectations, so the company should report PBT of c. £14.3m for FY March 2023.
The sharp slowdown in H2 (the period from September to March) is evident from the figures below:
Platform assets under management grew 6.4% in H2 and 20.5% in the year, and now stand at £2.6 billion.
Total funds under management grew 4.8% in H2 and 45.2% in the year, and now stand at £3.6 billion.
Headroom: the company has an additional £1 billion in headroom to lend to its borrowers, “when market conditions improve”.
New product: the company now has a Residential Mortgage product, supported by £300m from Lloyds Bank, for “borrowers with multiple sources of income, the self-employed and small-business owners”. Sounds great - I know that mortgage applications for self-employed people can be quite complicated!
Excerpt from the CEO comment:
Our technology enables us to continue developing disruptive new solutions in existing and new parts of the mortgage market, giving us a competitive edge with brokers and borrowers and helping us to continue to attract diverse sources of capital.
Current trading/outlook includes some important observations on the housing market:
More than 1.4 million households in the UK are facing the prospect of interest rate rises when they renew their fixed rate mortgages in 2023. We have seen a shift, with an increase in borrowers opting for tracker mortgages which provide greater flexibility to remortgage if rates reduce. Some of our commercial borrowers are seeing the weaker property market as a buying opportunity and in March we recorded our highest ever level of applications for bridging loans.
Estimates - a broker note from finnCap indicates that the FY 2023 revenue estimate has been revised lower, but all other estimates are unchanged (including FY 2024 estimates).
Graham’s view
This stock provides an easy way to bet on the housing market. If you think that buy-to-let, property development and other property projects will have a fair wind over the next few years, then Lendinvest might be a good way to express that view.
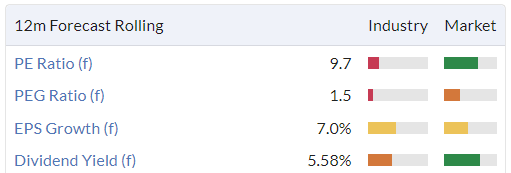
Personally, I can see that this stock is cheap relative to earnings, but I also see significant risks here:
Balance sheet net assets were only £60m in September 2022, after the fair value of buy-to-let loans saw a whopping £80m+ reduction in fair value.
The fair value of these loans will continue to fluctuate in accordance with interest rates, so hopefully you can see why I don’t think these shares are a slam-dunk buy at their current level. Leverage is very significant here and you really have to have a view on the direction of the property market - otherwise, this stock offers no margin of safety.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
Treatt- Last year Tea & FX were largely responsible for SP weakness. There is a huge opportunity in cold brew coffee. Difficult to produce authentic taste due to instability of coffee oxidisation although looks like Treatt have very interesting proven solution. Most of Treatt ingredients are 0.2% of finished product but coffee 25%. beverages are recession resilient- affordable impulse purchases. Mega trends, natural products, sugar reduction, provenance, RTD cocktails & seltzers, China( 6% sales & recent new order) & cold brew coffee( tea & coffee 10% sales). New UK facility has 2-3x capacity & there are joint development projects.
YouGov (LON:YOU) - a FANG delves into the SCVR land. Mr Shakespeare has transferred his holdings to Mrs S and to become a NED. Meta Platforms (NSQ:META) exec Mr Hatch to become CEO. Somebody from Deliveroo also in the mix.
I wish the SVCR would focus on some real stuff rather than Science in Sport (LON:SIS) - really just a scroll on the mouse. A £14m MC SR 24 (generous) micro value trap. Yes I will DYOR - not.
Just took example at random - when gold is exploding why do I want to hold whatever they do. LOL.
Not this again! We've discussed this topic to death in the past. We cover over 500 companies here, a large chunk of the UK market, much of which is not covered elsewhere. The idea is to build up an archive, where people can quickly check to see if any company looks interesting (from a value/GARP investing perspective) or not (steering people away from risky stuff is just as important as flagging the good things).
So whilst you may not be interested in SIS, there might be other people who read a positive article about it somewhere else online, and then want to check what Graham/Paul/Roland think about it. So they can look up our view here, and see within 1-2 minutes if it floats their boat, with us covering the main points, good and bad, that are often not covered properly elsewhere.
Turning to YouGov (LON:YOU) thank you for flagging the change of CEO, looks quite interesting. That in itself wouldn't trigger us writing about it here, as we focus on results & trading updates, and takeovers. But it's always useful when readers post comments flagging up this kind of development which might be significant.
We covered YOU for years, always concerned about its accounting policies of capitalising far too much in internal costs. I'll check it out & do a review here next time it reports some numbers.
Paul.
Dechra Pharmaceuticals (LON:DPH)
Blimey. You wait months for an offer and then two come along at once - see Network International Holdings (LON:NETW) earlier today. Looks an attractive bid at nearly 50% premium to the undisturbed closing price.
Marks Electrical (LON:MRK) does have a hi PE value as it is a growing company. It has proven it has a good business model compared to AO and Currys. The question would be can they continue to grow? Imo, yes, because as they are mainly an online competitor, they are largely unknown still by the public. From previous surveys I think only 6% of the public had heard about them. So this gives them the opportunity to increase yoy as more of the public become aware of them.
Because of the way their business model works it is very hard for their competition to under cut them without hurting themselves. They have the capacity to keep growing from their current warehouse and are looking to expand their warehouse to accommodate future growth.
Imo, what Paul said about buying any dips is the way to go.
VP (LON:VP.) On track to again grow profitably in FY'24 *** Today’s “in line” FY23 trading update from Vp reiterates that it had made “good progress within its core markets” since the interims in Nov’22. It has benefitted from strength in civil engineering (eg highways) and infrastructure (eg water, rail & energy), alongside successfully lifting prices to cover input inflation as well as rightsizing some parts of the group to further reduce costs.
Elsewhere, the international energy & testing divisions also performed well, while residential housing has stabilised at lower levels - partly supported by robust RMI activity where millions of properties need modernisation.
As such, we retain our projections and £11.30/share valuation. Based on forecasted FY’23 revenues, adjusted PBTA and EPS of £365.5m, £40.2m & 75.9p (+6.5% YoY) respectively - climbing to £376.5m, £43.3m and 81.3p (7.2%) in FY’24. This in turn puts the stock (at 670p) on attractive FY’24 EV/EBITDA, EV/EBIT & PE multiples of 4.2x, 8.2x and 8.2x – whilst paying a 6.0% dividend yield. We believe this is simply far too cheap for a best-in-class, economically resilient business with a proven track record through thick & thin.
Mooted offer for Network International Holdings (LON:NETW) from a consortium led by CVC capital partners. Looks a well timed bid to me as the takeout price would be 50% higher in a better market. Nevertheless my rule is sell on the bounce - based on the theory that the (usually) 10% you miss out on is nothing next to the drop if talks fail to reach agreement (see GB (LON:GBG) Darktrace (LON:DARK) etc).
Plenty of depressed prices into which to re-purpose the proceeds - today and likely for some time.
Congratulations!
Hi Graham,
Intersting comments re Science in Sport (LON:SIS.
I noticed an RNS last Thursday re a Mr Steven Granite picking up 2% of the company.
Granite is currently COO of Applied Nutrition who appear to be a fast growing UK competitor. Anyhow having looked up Applied Nutrition Limited at companies house they appear to be stunningly profitable (esp with ref to SIS) off a much smaller revenue base which I have to say, I wasn't expecting.
The products offered by SIS (PhD especially) and AN appear quite similar.
More interestingly from what I can garner they used to outsource production but moved it in house and they now operate from a 45,000 sq ft facility in Knowsley.
So maybe SIS are onto something putting all their efforts into their Blackburn facility?
I missed that RNS, thanks for the info Wolfy! Very interesting. Fingers crossed that their new facility leads to success for SIS. G
The latest full year results from Churchill China (CHH), whose main business is manufacturing tableware for the hospitality industry, might be worth a comment. Revenue and earnings have rebounded strongly with adjusted earnings per shares of 66.9p increasing by 77%, slightly ahead of Stockopedia’s forecasts, and the full year dividend is up by a similar amount to 31.5p.
With a market cap of £136m, Churchill is a classic example of a well managed UK small cap stock, generating 60% of its revenues overseas, growing strongly despite a slowdown in world trade and a sharp rise in energy costs for its kilns. Its pension plan is in surplus, it has net cash on its balance sheet, and it is optimistic about current year prospects.
However, the latest results also show that the company still has a way to go to match its 2019 pre-Covid performance. Although 2022 revenues are 22% higher than in 2019, operating profit and earnings per share are still around 18% below 2019 levels, primarily because the company’s operating margin of 11.1% is one third down on pre-Covid levels.
The company currently trade on a p/e of around 17 times current year’s earnings and yields close to 3%. It has always looked expensive compared to Portmeirion (PMP), its smaller competitor which trades on a p/e of 8 and yields around 4%.
Churchill has long benefited from a supportive family shareholder (the Ropers control around 15% and James Roper sits on the board as market director) and a management team which has been around for a long time. However, that is starting to change. David Taylor, who has been on the board for 30 years, has just retired as finance director, and Alan McWalter, who has been on the board for more than a decade, steps down as chairman next year. It would be surprising if David O’Connor, the current chief executive who has worked for the company for over 30 years, is not also contemplating retirement at some stage.
As a long-term shareholder, I like this company but my confidence is tempered by several things - the boardroom changes; the executives have tended to be net sellers of CHH shares over the long term; and the non-execs do not hold many shares. All this leads to my conclusion that the shares are unlikely to enjoy an early re-rating despite today's impressive results.
Apologies for filing this Churchill Comment comment twice. They are both the same but cannot find a way of deleting the second one. How does one contact someone at Stockopedia to delete the second piece?
DarwenLad - re deleting posts
They are not quite the same - the last 4 words only appear in the second.
Two ways to try to delete - report yourself using the flag (bottom R on the one you want to delete but there is not a suitable category) or (probably better) use the green button (bottom R of whole page).
Many thanks
The latest full year results from Churchill China (CHH), whose main business is manufacturing tableware for the hospitality industry, might be worth a comment. Revenue and earnings have rebounded strongly with adjusted earnings per shares of 66.9p increasing by 77%, slightly ahead of Stockopedia’s forecasts, and the full year dividend is up by a similar amount to 31.5p.
With a market cap of £136m, Churchill is a classic example of a well managed UK small cap stock, generating 60% of its revenues overseas, growing strongly despite a slowdown in world trade and a sharp rise in energy costs for its kilns. Its pension plan is in surplus, it has net cash on its balance sheet, and it is optimistic about current year prospects.
However, the latest results also show that the company still has a way to go to match its 2019 pre-Covid performance. Although 2022 revenues are 22% higher than in 2019, operating profit and earnings per share are still around 18% below 2019 levels, primarily because the company’s operating margin of 11.1% is one third down on pre-Covid levels.
The company currently trade on a p/e of around 17 times current year’s earnings and yields close to 3%. It has always looked expensive compared to Portmeirion (PMP), its smaller competitor which trades on a p/e of 8 and yields around 4%.
Churchill has long benefited from a supportive family shareholder (the Ropers control around 15% and James Roper sits on the board as market director) and a management team which has been around for a long time. However, that is starting to change. David Taylor, who has been on the board for 30 years, has just retired as finance director, and Alan McWalter, who has been on the board for more than a decade, steps down as chairman next year. It would be surprising if David O’Connor, the current chief executive who has worked for the company for over 30 years, is not also contemplating retirement at some stage.
As a long-term shareholder, I like this company but my confidence is tempered by several things - the boardroom changes; the executives have tended to be net sellers of CHH shares over the long term; and the non-execs do not hold many shares. All this leads to my conclusion that the shares are unlikely to enjoy an early re-rating .
Great point on switching 3 to 5 year charts Paul - You always drop lovely little (aside) nuggets into your reviews. AND you're away on your hols. Appreciated as always
Wonder if Begbies Traynor (LON:BEG) might be in the market to buy Ince (LON:INCE) from administration!
Certainly would be logical, since Begbies have the financial power plus the acumen and track record for M&A now...
Probably better if Begbies Traynor (LON:BEG) don't touch Ince (LON:INCE) . There's all sort of issues in the background. I believe a lot of the key staff from Arden left after the takeover, and the rump was sold off a few weeks ago. The original Ince went bankrupt before the reverse takeover. There's been problems with the relationship with the partners and they seem to have difficulty collecting receivables in the Far East. Not to mention there's still an onerous lease on unused office space in Aldgate. Better for Begbies to continue acquiring good businesses that they can easily integrate.
Treatt TET - this was one of my 5* investments but took a thrashing in the past two years, culminating in a very poor outturn magnified by a failed currency hedge. I bought it first because a 'much-respected' investor, Lord Lee, was very bullish in his FT column a few years ago. So bullish, ideed, that at one stage he confessed it had represented a staggering 40% of his entire equity portfolio. This was apparently much reduced, but even then seemed completely bonkers. So the share had a marvellous run, from around 170 when I bought in 2015, up to 1190 in early 2022. Earnings spiked in fy 9/22 helped by strong retail (helped by covid) , the company nearing completion of a big spending expansion not only in the UK but also the US (fixed assets doubled to £84mn in three years), health drinks were all the rage and Fevertree (notice the identical earnings spike and fall) was still boomin . I am still invested and whilst I accept it looks too dear on current earnings I remain hopefull that the massive capacity expansion may pay off, that the recovery in the hospitality sector continues (I think lower gas prices, if realised are key). But all said and done that is a sensible comment, Paul. The stockrank chart (on the Stockreport page under the price chart) tells its own cold tale. One of the very best fund managers I knew never fell in love with a company, not an easy quality to have. But the head must rule the heart.
'much-respected' investor, Lord Lee
Has anyone seen a verified performance figure for him in the last few years?
I know when he was writing regularly for the FT years ago, there was some published performance stats. Obviously he's cemented his status long ago as the ISA millionaire.
But what of his recent performance?
RE: John Lee
Has anyone seen a verified performance figure for him in the last few years?
Nope, but why should he?
Self-reported from his latest FT article:
"For the first 16 years I subscribed the maximum, £126,000 in total. I reinvested all dividends, such that by 2003 my Isa was worth £1mn — and I became known as the first Isa millionaire. I had no means of knowing whether this was true, although no one challenged me!"
And:
"Thankfully, the combination of more investment successes than failures — no one gets it right all the time — reinvested dividends and takeovers resulted in my current Isa being nicely north of its 2003 value in real terms. Holding established, profitable, dividend paying, niche small caps has served me well."
And:
"However, the past couple of years have been challenging — recent “all time highs” have passed me by and my Isa is well below its peak. When conditions are buoyant one looks for the “double whammy” of rising profits and an upward re-rating, but when global trading becomes more difficult and company forecasts and results fall short of expectations, the reverse happens. Thus a number of my favourites such as Anpario, Treatt and Videndum have fallen sharply. Since all are excellent businesses with a strong future, however, I have every intention of staying aboard."
Make of it what you will, his holdings are all listed on the Parliamentary register, so it's always possible to get some idea of how he's doing.
timarr
Hi Timarr
I agree. Lord Lee does not need to give performance figures, none of us do. It is a matter of choice.
His record speaks for itself and I think his strategy is a good one.
I saw him speak at an FT event in 2013. He displayed his ISA holdings and values.
At that time his ISA was worth £4.5milliion and Treatt was £1.5million of it.
I have seen him speak many times since and also spoken with him. I consider him an icon for the private investment community. Anyone who has not read his book: "How to make a million slowly" should take a look.
Michael
RE: John Lee
His record speaks for itself and I think his strategy is a good one.
Interestingly he has Aviva (LON:AV.), Phoenix group (LON:PHNX) .Legal & General (LON:LGEN) and M&G (LON:MNG) in his ISA now, none of them small cap. As he notes the inversion of small and large caps in terms of yield is quite striking.
timarr
Lord Lee has obviously been taking a sneaky peek at my ISA holdings.
Even lord lee has had better luck with large caps than the smaller ones.
Legal and General, Aviva and MNG have proved great investments with dividends and capital appreciation.
Anpario has been a disaster for anyone invested followed by Treatt and PZC.
Anpario has been a disaster for anyone invested followed by Treatt and PZC
Depends on your timescale. John Lee invested in Treatt (LON:TET) at under a £1 as I recall. But that was 20 years ago.
timarr
He still writes intermittently in the FT weekend which I buy (the print copy) but I cannot really access the archive. His latest was March 7th. He is still quite frank, including about his failures (don't we all have small cap failures in the past year? I certainly do) prefers companies with family management and investment. If you have a friend who gets the online edition he should be able to dig it up for you. I think if you register you can get one article a month yourself.
LVMH, the largest luxury company in the world updated the market with an excellent results. The small caps not a better investment in my mind. Compare the LVMH with TET : both highly rated but one has performed much superior.
As the old saying goes: Vanity and old age do not go out of fashion. LVMH and L'OREAL, are the proof if you need any!
Louis Vuitton is a multi-bagger….
Vanity and old age do not go out of fashion. LVMH and L'OREAL, are the proof if you need any!
Two of my biggest holdings. I was once asked by a female relative which share to buy if you could have only one. My reply was L'Oreal, perhaps swayed by her own preference for expensive brands, but it turns out to have been very sound advice that, for a change, I followed myself.
Is that because (drumroll please......) you were worth it......... :)
Is that because (drumroll please......) you were worth it......... :)
Well at my age, I could probably make better use of the product than the money :-)
Foresight group (LON:FSG) gave another positive update today. Looks like they are confident of 20-25% AUM growth/annum on a rolling average 3 year basis. I like this and Gresham House (LON:GHE, so would be good to cover today, if possible. I hold both.
Hi Topvest - You may well be onto two winners here - but there's a lot of Greenwashing going on at both these companies but hey - thats how things are going right now!
FSG looks good but why so many directors selling?
Cos they are clever - sold at the right time - 450 against todays much increased price of 414.
Could I kindly ask one of Paul or Graham whether they might review Churchill China (LON:CHH) . Announced very good finals this morning. Given the significant interest in Portmeirion (LON:PMP) on this board I think it makes for an interesting comparison, albeit that the former more focused on B2B
Thanks Phil117, we do usually cover Churchill China (LON:CHH) but for some unknown reason, it didn't come up on our list today. I'll aim to take a look a little later, or tomorrow, interesting company (but usually too expensive for what it is).
Many thanks Paul. Much appreciated! On my crude back of the envelope calcs it’s now trading below 20x PE, latest historics. Next year forecasts will hopefully see that fall further. Still a big premium to PMP. Very much looking forward to your view
Thank you for an interesting review on Science in Sport Graham, we do not hold but I do use their products and find them excellent, when/if you ever give it the thumbs up, we'll probably hold the shares too! Than you Paul for your observations on WJG, we do hold and are stake building again after success in the past with the company's shares.
Hi, you're very welcome JASVFS! Yes, their products are allegedly quite nice! G
Products from Science in Sport (LON:SIS) are great and have uesd for 15+ years (planning to use at Boston on Monday and have just packed a load of gels conincidently). That said, I don't see as particularly differentiated product (Gu, Maurten and loads of others work as well, it's just a preference thing) and a good product does not necessarily make a good investment (never been tempted to buy the shares).
Petrotal (LON:PTAL) The North Peruvian Pipeline (ONP) has been reactivated giving PTAL another route to ship oil from their wells in Peru. They have been using barges to Brazil whilst this pipeline was shut and this has limited production whilst river levels were low. Now debt free and committed to paying dividends, this share is worth a look, but does carry the risks of operating in Peru. DYOR. https://larepublica.pe/economi...
Petrotal (LON:PTAL) paying 11% dividend yield, and should have half its market cap in net cash over the next year at current oil prices. Is buying back 10% of the company shares too.
I think forecasts are deliberately on the low side due to getting caught out with low river levels last year but with pipeline reopening and better management of barging I suspect the production profile will go up as the year goes on too.
I've held these from around 17p and think they have much further to go - I'm comfortable with how they engage with the local Peruvian communities and think the fund they proposed was a super idea. Seems they are a bit of a trusted middleman between Government and indigenous community.
With System1 (LON:SYS1) share price up around 38 percent over this week it seems there could be some fireworks at the impending General Meeting. I hold and with the general public holding of the market cap being so small at 6.5 percent it hardly warrants my vote. On an aside I have finally been released from my holding in Ince (LON:INCE) with an irritating loss, I should have listened to Paul a long time before the share was suspended.
Unbound (LON:UBG) I see these guys put out a late announcement and following an approach by Marwyn to put in £10m at 10.5p as an investment rather than a takeover are leaning towards that. Marwyn are insisting on allowing shareholders to also participate in said fund raise, which will dilute shareholders by half !
Cynically I would point out there is incentive for management to favour this approach as it will keep them all in well paid jobs but unless shareholders put their hands in their pockets they will continue to bear the equity risk, but take significantly diluted upside and lose 50% of any insurance claim success which is a material amount!
hmmm - is this a better result for shareholders then? Im not so sure........
On the plus side Marwyn get seats on the board and I do rate them as investors so they might change some mgmt and right the ship. Equally the net debt would disappear into net cash.
I know Serica Energy (LON:SQZ) has upset quite a few.... after a controversial deal kiboshed a winter gas trade. Actually winter gas prices surprised to the downside.... falling from ridiculous levels 400+ to just high by normal standards 100+. That's by the by - taking a step back - and avoiding commenting on the deal - it strikes me this co has significant cash resources c£400m - and is paying a handsome final divi 14p...making a total 22p. The divi yield and earnings yield leave the co looking very cheap.... but commodity volatility renders such measures somewhat meaningless. Peel Hunt put out an NAV of 440....in January...but this no doubt needs to fall to reflect lower future gas prices.... never the less the shares will continue to look cheap on an NAV basis.
All this is known, eminently forecastable and not really price sensitive. The reason IMO companies with lots of cash often look optically cheap is the market doesn't trust the management to spend it wisely. So it's the cash the market discounts which may sound counter intuitive. Although they just did a rather controversial deal, Serica Energy (LON:SQZ) management have done rather well for all concerned so far. Im inclined to ride out my rubbish winter trade now....and actually think Mercuria will feed them further deals ....accretive to NAV... pushing the story on. I "guess" this might be behind the confidence reflected by the dividend. I don't think you need to be an expert in fossil fuels to invest here.... just size accordingly and see how this story develops. It is more about management credibility and investment opportunities than fossil fuel prices IMO. Obviously a labour govt may well present risks in the future but for next twelve months I suspect not too much to worry about.
I never really liked investment case drift ....the winter trade didn't work... but im happy in resources in the current world, and think in this case the upside is worth it if management deliver for you.
Hi - re Serica Energy (LON:SQZ) I think investors really misunderstood the investment case of buying Tailwind and adding a much great oil split. That diversification will hold them in good stead for much longer than the gas assets.
Nonetheless whilst gas prices have decreased to more normal levels, oil prices have increased, and Tailwind will be NAV accretive after year 1 of acquisition. Not only that but the resource base has increased materially - ie by 20%+ overall (and 3 to 4 * last years production) so a very strong reserve replacement. The 440p NAV was not based on 400p spot gas prices either - it was based on medium term forecasts and also remember the NAV includes circa 1/3rd of market cap in net cash.
So I think investors have got this one wrong. This year they will have circa £500-600m in net cash despite paying 10% dividends, which equates to 2/3rds of the market cap. So the market is attributing 1 more year of cashflow to this company and then nothing for ever more. That's utterly absurd given they are replacing reserves at 4* the rate they are depleting them and have production for well over a decade!
But at least I'm being paid 10% a year to wait for the market to recognise that value.
Agree mostly. For the record the gas price assumptions were 170 and 150 for 2023 and 24. Oil was more interesting at 75.... and the reserve replacement number you quote is just Tailwind.
hi - reserve replacement was both Serica and Tailwind
Serica went from 62mmboe to 75mmboe (whilst producing 8.3 during the year)
Tailwind went from 42mmboe to 55.5mmboe (whilst producing 4.2 during the year)
So total increase of 39mmboe with a production of 12.5 = average 3.1*
Technically NAV should rise 30% less gas price declines + oil price gains
Avation (LON:AVAP) another positive piece of news this morning. Disposed of one of the final two off lease aircraft that is 10 YO for a price above book value. With second hand values firm and numerous enquiries for the final off lease plane this bodes well.
For me though the fact that the plane was sold above book value and NAV was around 285p previously it should have a positive read across. Basically you can buy real assets at 35p in the £.
Treatt (LON:TET)
Thanks for covering Paul and I can’t argue that the name isn’t an outlier from SCVR norms on valuation grounds. It’s worth noting however that valuations have come down with rising interest rates in the ingredients sector as well, with all the main names taking a 30-40% hit from nosebleed levels. Still high multiples reflect extremely sticky and reliable revenues for ingredients of essential household products like tea, coffee, dairy etc and much stronger pricing power than enjoyed by the equally highly valued consumer staple companies for whom the individual ingredients form a minute proportion of their overall product cost. If you want to participate in these potentially very stable and growing revenues, you have to pay up.
Reassuring update from Watkin Jones (LON:WJG) , despite the glitch on the Exeter development where a contractor has gone into liquidation. Looks to me that Mr Market has thrown the baby out with bath water. Hopefully time will confirm my somewhat biased view. Again as with Portmeirion (LON:PMP) when it could be bought for 300p it just looks too cheap.
I hold having bought hopefully with foresight at 88p. Fingers X.
Norcros (LON:NXR)
Shareprice here is back in the doldrums that’s par for the course here. Ref todays update it’s all vey tick over not much sign of any organic growth this year closure of the adhesive unit is sad for peeps that will lose their jobs and exceptional costs probably take a bite of a shine of the end results which are vey decent otherwise. Tickover here is fine by me pay down debt (new) pension scheme is again more mature than the prior year - would love to see them buying back shares at current kevel to get share count back towards where it was pre latest acquisition.
Re Norcros (LON:NXR) - Agree steady results is fine. Debt is being rapidly paid down again which I prefer to buybacks for at least another year as I like the strategy of gradual expansion through very related acquisitions. I think more such bolts-ons can be done over time and they need headroom to do them. Closing the adhesives unit to avoid £3Mn pa losses with a 1 year payback is another material pick up to the bottom line (+10%) from 2024.
My only real fear is a new geo-political concern. They have managed the South African risk very well. However, pretty much their whole supply chain starts in China. A conflict over Taiwan might really disrupt that (although China would have a lot to lose to stop selling its goods). I think this is another reason for its short term price depression.
Otherwise, it is doing OK in a not good moment in a cyclical UK market. I am happy to hold, take my well covered divis and wait.
Brooks Macdonald (LON:BRK) "Impressive consistency in strength of net flows" (new note from Equity Development)
BM has recorded yet another quarter of positive net flows: +£373m in Q3 of FY23 (to 31 Mar 23), its eighth in succession. This is a hugely impressive achievement considering the last five of these quarters was a period characterised by market falls, economic uncertainty, and investor nervousness – an environment more typically associated with depressed flows. BM’s net flows have now been above peer group median levels since calendar Q4 of 2021. Our fundamental valuation remains at 3150p per share, 77% above the current share price. We also flag that BM’s P/E ratio of 11.9x is 30% below a peer group median of 17.0, despite its organic growth rate being higher than most peers. We see potential for a re-rating. See link with audio summary here: https://www.equitydevelopment.co.uk/research/impressive-consistency-in-strength-of-net-flows
My morning smallcap tweet: Cash gushers and flushers
System1 (LON:SYS1) Angle (LON:AGL) Science in Sport (LON:SIS) Distil (LON:DIS) Home Reit (LON:HOME) Synectics (LON:SNX) Watkin Jones (LON:WJG) Oxford Instruments (LON:OXIG) Avation (LON:AVAP), PZ Cussons (LON:PZC), Newriver Reit (LON:NRR), VP (LON:VP.), Norcros (LON:NXR), XP Power (LON:XPP)
◄System1 (SYS1)► details about activism by former CEO. Rebuttal to Maynard Paton's article. [SP=207 Cap=26m]
◄Angle (AGL)► contract to use Portrait Flex assay in prostate cancer study. No £££. [SP=17.55 Cap=46m]. I hold.
◄Science in Sport (SIS)► six month strategic review concludes with no change. Trading in line. [SP=8.75 Cap=15m]
◄Distil (DIS)► warns FY-Mar rev slightly below market expectations at £1.32m down 55% and pretax loss higher at £0.71m. Outlook "Despite this, the outlook for the coming financial year is positive. Q4 delivered the strongest revenues of the financial year." [SP=0.46 Cap=3m]
◄Home REIT (HOME)► extension of PUSU offer deadline to 11 May. [SP=NA Cap=NA]
◄Synectics (SNX)► wins £3.5m order for delivery this FY. [SP=114.75 Cap=20m]
◄Watkin Jones (WJG)► H1 trading. Project margins in line "with the exception of our scheme in Exeter where the Group has incurred certain additional costs following the liquidation of a contractor". Expects to close a number of transactions in H2. [SP=95.99 Cap=246m]
◄Oxford Instruments (OXIG)► guides FY-Mar rev up 22% or 14% at const FX. Adj op profit ahead of mgmt exp. [SP=2436.78 Cap=1406m]
◄Avation (AVAP)► sells an off-lease plane for above book value. [SP=114.5 Cap=82m]
In line: PZC, NRR, VP., NXR, XPP
Is anyone aware of when Volex (LON:VLX) is next expected to provide a trading update?
They released one in 3rd week of April 2022 but their corporate website (Investor Relations) doesn't, so far, provide a financial events calendar for 2023.
Long overdue whenever it comes!
Volex (LON:VLX)
There is a note from Singer on Research Tree dated 9th Nov 2022 confirming trading in line with expectations
Can’t help wondering if the delay is a red flag
Volex (LON:VLX) Looking at the known facts and trying to avoid speculation. The trading update hasn't been delayed. Historically it has been made in the second half of April. The webinar of the interims to 2 October is available on
www.investormeetcompany.com
is worth listening to. In it Nat Rothchild expressed confidence in the outcome for the year. Admittedly circumstances can change, but the electrification of the world, especially from an automotive perspective continues apace. 50% of debt is fixed at marginally above 3% for 4 years (Q and A from interims).
Nat Rothchild and the management team hold over 25% of the equity. There has been minimal director selling and Nat Rothchild has to my knowledge never sold any shares
There are as with any investment potential negatives.Stirling is comparatively strong at present which creates a potential headwind as 75% of Volex (LON:VLX) revenue is in dollars and euros. Also consumer electricals may experience some headwinds, hopefully offset by growth in EV, medical and data centres.
To end on a positive note, Volex (LON:VLX) global footprint is a valuable asset and should benefit from the trend towards localisation/on-shoring.
I don't know what the update will bring, but there is no reason to believe that the forthcoming prelims will not be in-line.
Volex (LON:VLX) is my third largest holding.