Small Cap Value Report (Thu 13 Aug 2020) - TPT, TRB, GDWN, CGS, PEN, DLAR, PVG

Good morning, it's Paul here with Thursday's SCVR.
Estimated timings - there's lots to cover in detail today, so I'm carrying on until about 4:30 pm.
Edit at 15:58 - today's report is now finished.
Please see the header above, for the announcements today which have caught my eye, in the small caps space.
.
Topps Tiles (LON:TPT)
Share price: 50p (up 16% today, at 09:21)
No. shares: 195.0m
Market cap: £97.5m
Topps Tiles Plc (the "Group"), the UK's leading tile specialist, announces a trading update for the six week period ended 8 August 2020.
Checking my previous notes, I reported here on 1 July 2020, on a positive Q3 (Apr-Jun) update, plus a good performance in the first week of re-opening stores (LFL sales down only 5.4%).
Today's update has a summary at the start (becoming increasingly popular, probably dreamed up by the PRs!), saying;
Robust like-for-like growth; modest pre-tax profits now expected for FY20; well-positioned to strengthen market position...
Remember that these summaries will be cherry-picking the best bits usually, so need to be initially treated with scepticism. EDIT: having looked through the whole update, I'm happy to withdraw this general point - in this case, the summary is accurate. End of edit.
LFL sales in Q4 (July-Sept 2020) to date - this looks excellent;
Retail trading over the first six weeks of our final quarter has been robust, with like for like retail revenues growing by 15.5% year-on-year.
It's not clear whether the above includes online sales, or not. So I queried this with the company's advisers, who have just called me back to confirm that the above LFL figure does include both stores and online sales.
Online sales have moderated once the stores re-opened;
While online sales have moderated from the peaks seen in April and May they remain above previous levels, leveraging the Group's recent online investments.
A reduction in online sales is to be expected, once stores re-open, so that's not a problem.
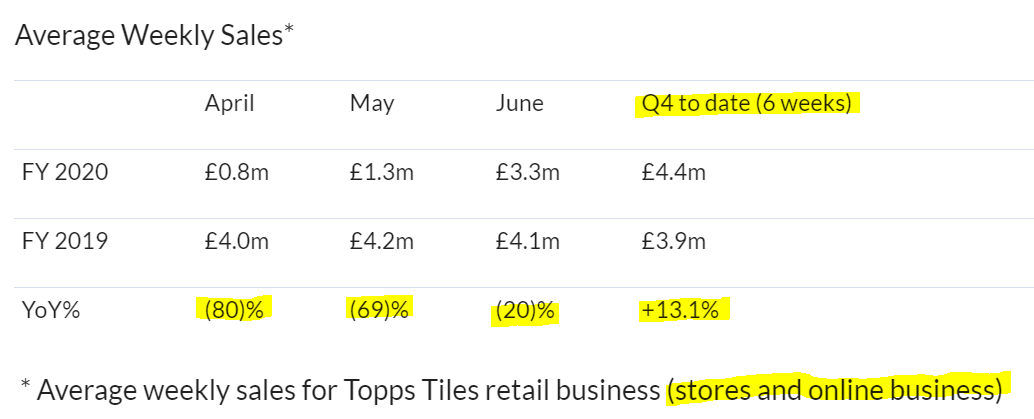
Average weekly sales - excellent transparency here, I wish all companies would present current trading information in such a clear format. The trend looks very good here, from a severe downturn when lockdown began, to now trading ahead of prior year with stores re-opened. There must be pent-up demand now being satisfied, which is good to see;
.
.
Note that the table above does combine stores, and online sales.
Stores now operating normally, staff returned from furlough.
Commercial division - subdued, but starting to improve. Subjectively, the tone sounds less enthusiastic about this division than previously.
Order book "significantly ahead of the prior year"
Guidance - good to see transparency here as well, instead of the usual it's too uncertain to give any guidance, which other companies are still trotting out;
... the Board now expects that the Group will generate a modest level of adjusted profit before tax2 for the 52 weeks ended 26 September 2020.
Given the unique conditions created by covid-19, I think to still be able to generate a small profit for the year, is pretty impressive. Bear in mind though, that this is only possible because of Govt support measures - particularly furlough, and business rates waiver. Without that taxpayer support, we'd probably be looking at a thumping loss for the year.
Liquidity - very good, but boosted by stretching creditors no doubt, plus the sale & leaseback which we already knew about. Times of crisis demonstrate so well how owning freeholds gives companies a get out of jail free card. Such property can be sold outright, or a sale & leaseback, thus generating significant cash when it's most needed. I'm a huge fan of companies with freehold property - it de-risks investments, and is often ignored in valuation, meaning investors get a substantial asset thrown in for free. It's also a signal of prudent management. You often find freeholds in family-run, or owner-managed listed companies, which is a theme we've been discussing here recently. A key lesson from this crisis is that prudently funded, owner-managed businesses, don't go bust, and probably don't have to raise any fresh equity at a low share price. Unlike many companies with hired hands running things, taking risks in order to achieve their share options targets.
The combination of strong trading and receipt of the proceeds from the sale and lease back of the Group's head office and warehouse buildings at Enderby in June, have had a material impact on the Group's liquidity position. The Group currently has c.£9 million of net cash and available cash headroom of £58 million within its financing facilities.
That's good, but it's disappointing to see that Topps has not disclosed what short term cashflow benefit it has received from stretching creditors, e.g. taxes in particular. It's misleading to trumpet lots of liquidity, but not tell us how much has occurred due to one-off & temporary measures, such as VAT deferral. This should be disclosed either way - whether companies have taken advantage of tax deferral, or not. This is the one key omission, in an otherwise excellent update.
My opinion - this looks a really good update, in tough times.
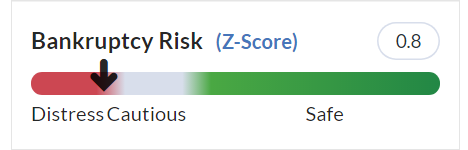
Note that the Z-score (a key thing to check, on every company's StockReport) is showing a poor result. However, the computers don't know about the large freehold property sale & leaseback, hence this should update to a more positive figure, next time results are published. Therefore, it's safe to ignore this warning.
.
There's an updated broker note available on Research Tree, which makes interesting reading. Note that previously the analyst had pencilled in a loss of £4m for FY 09/2020, but has today raised that to a profit of £2.2m - a big forecast improvement, which justifies a decent move up in the share price today. Future years forecasts are also raised significantly.
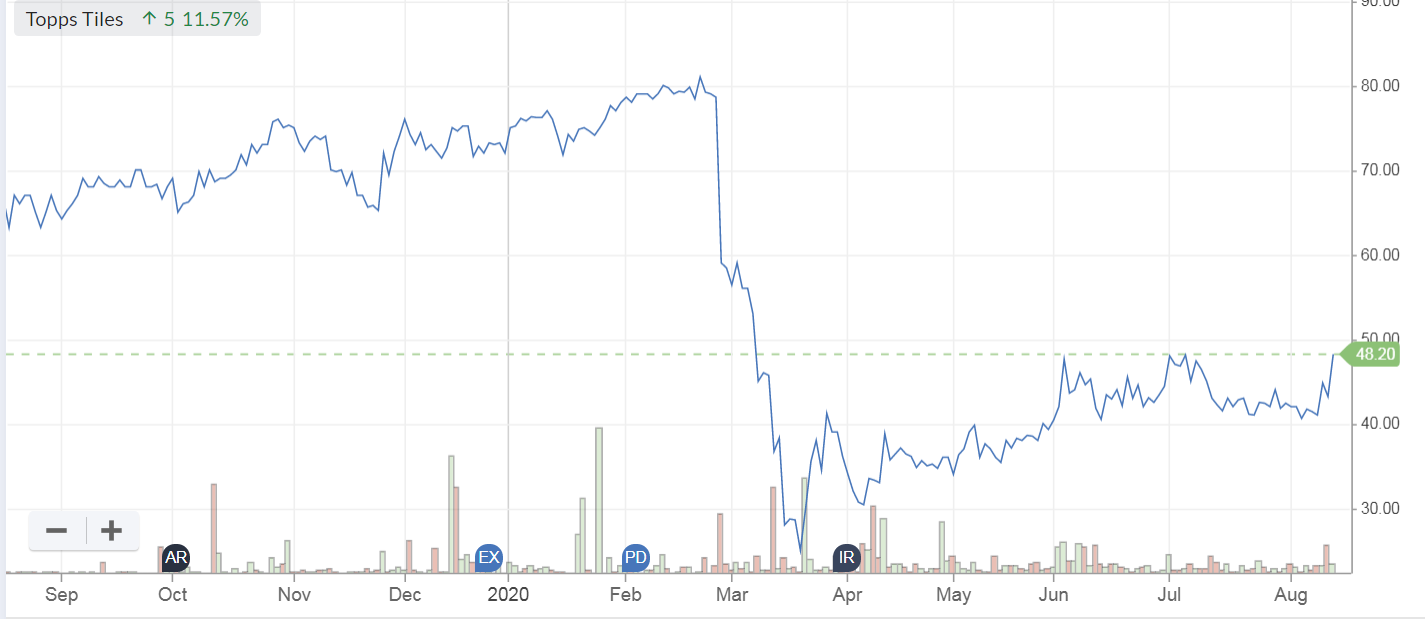
Overall then, this is a good day for TPT shareholders - an excellent update, and decently improved prospects. So it gets a thumbs up from me. Unfortunately, I had to ditch my spread bet on this share a little while ago, due to a margin call on something else, so I've missed out on this decent rise today. Am toying with the idea of buying back in.
Given strong current trading, risk:reward looks good to me. I doubt it would be likely to revisit previous lows. Although the big unknown is covid & a possible second wave. Based on what happened last time, DIY type businesses are one of the least likely to be closed down, so the risk here looks much lower than say for pubs/restaurants.
.
.
Tribal (LON:TRB)
Share price: 65.5p (up 15% today, at 09:20)
No. shares: 205.7m
Market cap: £134.7m
I've moved this announcement up the running order, because the share price has risen strongly this morning, so there might be something interesting going on.
This is an education-focused business, providing software & services for universities & schools, worldwide.
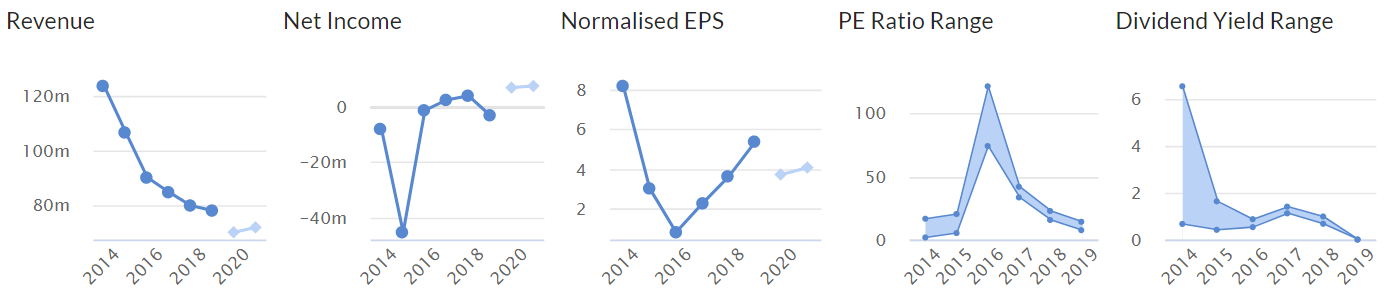
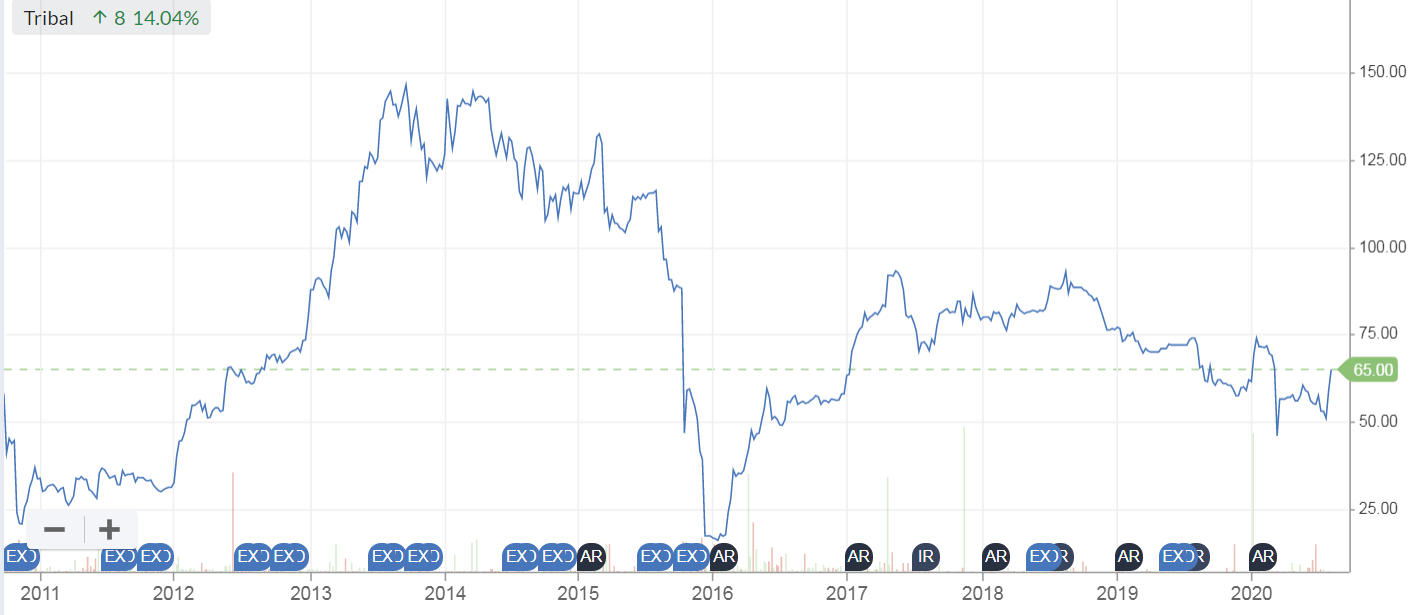
Historically its performance has been erratic, and unimpressive, as you can see from the Stockopedia graphical history (my starting point for looking at every company);
.
.
This has been reflected in a disappointing share price performance, over the last 10 years - it's pretty much back to where it was 10 years ago, and there have only been modest dividends over this period too.
.
.
Still, the way I look at things, the past doesn't matter, shares are all about the future. Therefore a company with a disappointing track record, could start off from a base price that is too cheap, if good things begin happening (e.g. restructuring under new mgt). That's why it's worth looking at everything with an open mind.
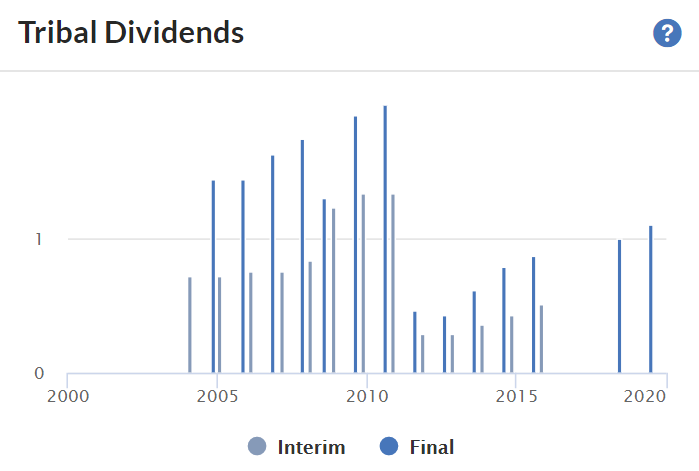
As you can see below, divis were reduced downwards in 2010, and have only been small since - not a good sign, as this seems to suggest a business which has struggled to generate cashflow over the long term;
.
.
The average number of shares, shown on the StockReport, sees an increase in several stages, from 131m, to 205.7m, since 2014. I seem to recall it got into a mess financially, possibly through making duff acquisitions, and came close to going bust at some stage.
Today's results - are for H1, being the 6 months to 30 June 2020.
H1 revenues £38.2m, down 5.4% on H1 LY
Adjusted profit before tax of £6.4m, is up a bit on H1 LY (£6.2m)
Adjustments are shown in note 5 - the company classifies quite a lot of things are adjustments, and these are material to profits, being £1.7m this time, and £1.9m last time (H1 figures), so a bit of scepticism needed here perhaps? If companies do a lot of adjustments to profits, then I tend to value the business on a lower PER than I would for completely clean accounts with no adjustments.
Balance sheet - is weak, but that doesn't always matter for software companies with strong, long-term recurring revenues, and up-front payments by customers. Hence I'm just reporting the facts, not ringing an alarm bell.
NAV: £37.0m, less intangibles of £48.0m = NTAV is negative, at £(11.0)m. I don't usually invest in companies with negative NTAV, unless they're exceptionally cash generative.
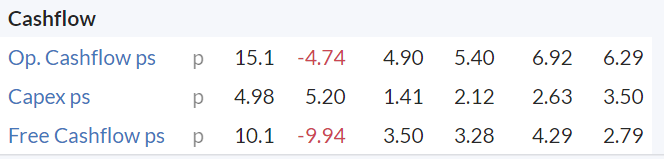
The Stockopedia summary shows that it has generated cash in the last 4 years (this table runs from 2014 to 2019 calendar years), with an increasing amount spent on capex. Capex is mainly capitalised development spending. The cashflow statements are quite complicated though, as they include acquisitions, drawing and paying down loans, etc.
.
Remember that Tribal had an expensive legal dispute with a software provider a year or two ago, which cost it close to £10m. So it seems a bit accident prone. I'm not convinced that acquisitions have added much value either.
Outlook - the figures look resilient, given the disruption caused by covid. Software businesses, with strong recurring revenues, serving mostly public sector bodies (less likelihood of bad debts) has been a good place to take cover during this crisis.
There's also a positive outlook comment (probably the main reason for people buying the share today);
The Group expects results in the current year to be slightly ahead of market expectations for Revenue and Adjusted EBITDA, and ahead for Adjusted EBITA.
Sales pipeline is positive - cloud, CRM, and mobile products are mentioned as generating customer interest.
Sales cycle lengthened - due to uncertainty over student numbers (covid impact/uncertainty)
My opinion - I'm neutral on this one.
Positives - resilient figures, good recurring revenues, sticky customer base, products sound relevant (cloud, etc), good current year outlook.
Negatives - weak balance sheet, poor long-term track record, customer budgets constrained, sales cycle lengthening.
.
Goodwin (LON:GDWN)
Share price: 3115p (down 2.4% today, at 10:26)
No. shares: 7.36m
Market cap: £229.3m
Goodwin PLC today announces its preliminary results for the year ended 30th April 2020.
BUSINESS MODEL
The Group's focus is on manufacturing within two sectors, mechanical engineering and refractory engineering, and through this division of our manufacturing activities, our overseas business facilities and our global sales and marketing activities, the Group benefits from market diversity. Further details of our business and products are shown on our website www.goodwin.co.uk
.
What an interesting share! I've gone through all the figures & narrative, and several general things strike me;
- No adjustments to the figures (so they're probably presented stated prudently)
- Balanced commentary, comes across as trustworthy, not rampy
- Obvious that this is a well-managed group
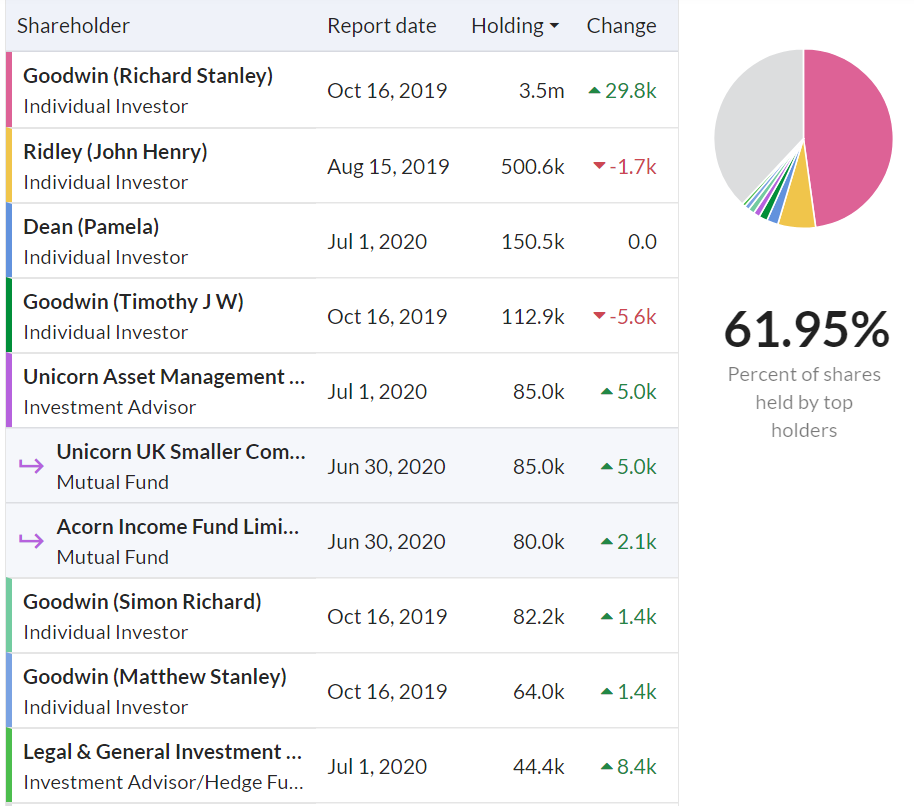
- Long-standing history - a family-managed/owned business that happens to have a listing, so external shareholders are along for the ride here, as you can see from the major shareholders & Directors info, with Richard Goodwin having a dominant stake;
.
.
Results FY 04/2020 - here are my notes covering the key points;
- Revenues up 14% to £145m
- Pre-tax profit down 26% to £12.1m - why profit is down is not explained in full, but negatives mentioned include: covid impact in Q4 ("stalled our progress"), USA/China trade frictions, customer disputes with 2 contracts
- EPS (diluted) of 103.3p (down from 149.6p LY) - PER of 30.2 - looks expensive, but remember Goodwin doesn't adjust its EPS, so on a comparable basis to other companies, the PER would probably be somewhat lower
- Dividend reduced 15% to 81.71p - yielding 2.6% (not bad, for a sustainable divi) - sends a strong signal that covid has not done serious damage to the business, and buoyed by strong order book
"Current workload" (similar to order book, presumably) is high, at £183m, up 11% on prior year end;
Armed with this workload, the Group retains a high degree of confidence in the future versus the looming uncertainty for many businesses this coming year.
Bank facilities tendered out, switched to Santandar, on better terms. Took out £30m Govt CCFF loan, as an "insurance policy". Borrowing facilities look ample to me, so no concerns here.
Changing auditor after using KPMG for 56 years!
Reduced previous dependence on oil & gas sector, more diversified now, both in sectors and internationally
Balance sheet - looks good. NAV: £109.6m, less intangibles of £24.7m, gives NTAV of a healthy £84.9m
Receivables look under good control, at £24.5m
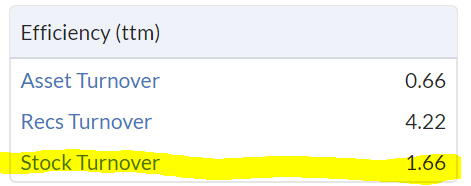
Inventories seem high at £44.9m. Jack recently pointed out that the StockReports here have some handy tools to check if receivables and inventories are reasonable. I'd never even noticed they were there! Here are the relevant figures for Goodwin, which confirms that inventories turn over very slowly indeed. Maybe they have to keep a high number of stock lines on hand? It just seems odd that a company which clearly keeps a tight rein on its receivables book, has so much inventories kicking about (NB these are historic numbers below now, which should update in a few days when these latest results feed through);
.
.
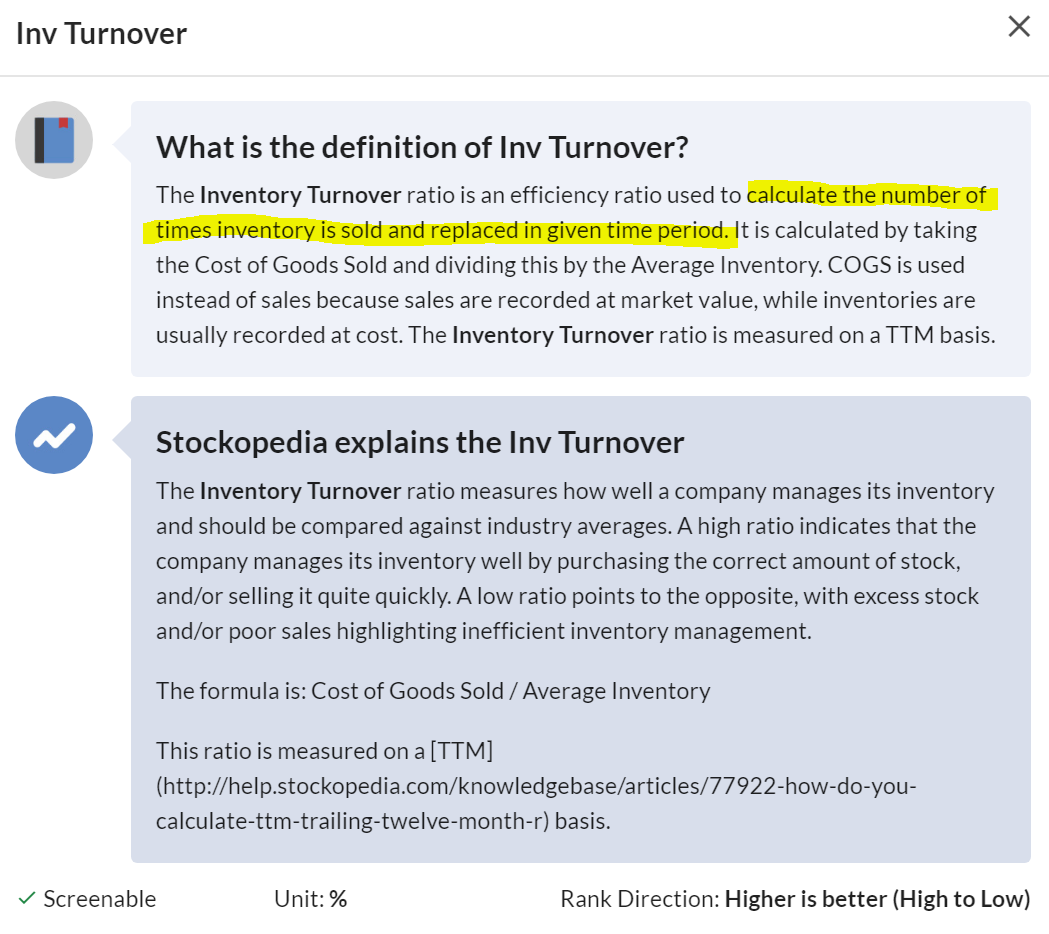
For anyone not familiar with this concept, here are the explanatory notes from Stockopedia;
.
.
Cashflow statement - I'm a great believer that cashflow statements should be really simple. Goodwin's is, as you would expect from what is clearly a conservatively run group, with prudent accounting.
It generates good operating cashflow, which is then spent on capex and dividends, and occasional acquisitions. That's it in a nutshell.
It all looks fine to me.
Outlook - as mentioned above, the strong order book means Goodwin is confident about the year ahead.
Other outlook comments are dispersed through the commentary, without a separate section.
Particularly upbeat comments about Goodwin Steel Castings, mentioning long term benefit from its nuclear waste containment boxes. Specialist alloys work for ships has few competitors.
Product development - sounds very interesting, with a number of new products ("major activities") launching this year,
My opinion - I very much like family-run/owned businesses like this. The valuation looks punchy, but probably isn't, if the figures were adjusted from super-conservative, to how everyone else presents them, with loads of adjustments!
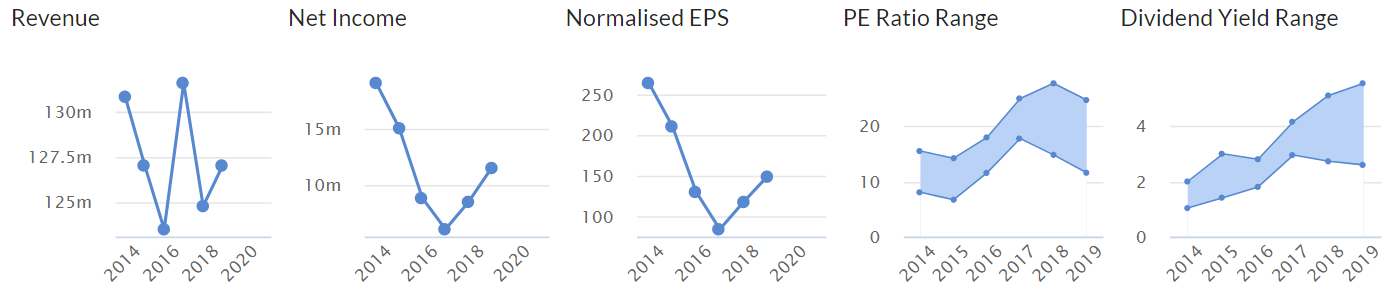
However, taking off my rose-tinted glasses for a moment, the track record in recent years has been quite lacklustre. Maybe that's because the group has had to ween itself off dependence on oil & gas? EPS this year is only 103p, so over several years has fallen a lot. Meanwhile the PER has been going up. That means investors must be factoring in & are paying up-front for a considerable rise in future profits.
.
.
Overall, I don't doubt that this share is likely to be usefully higher in 10 years time, with a dependable flow of divis along the way. But is that exciting enough for me? Probably not.
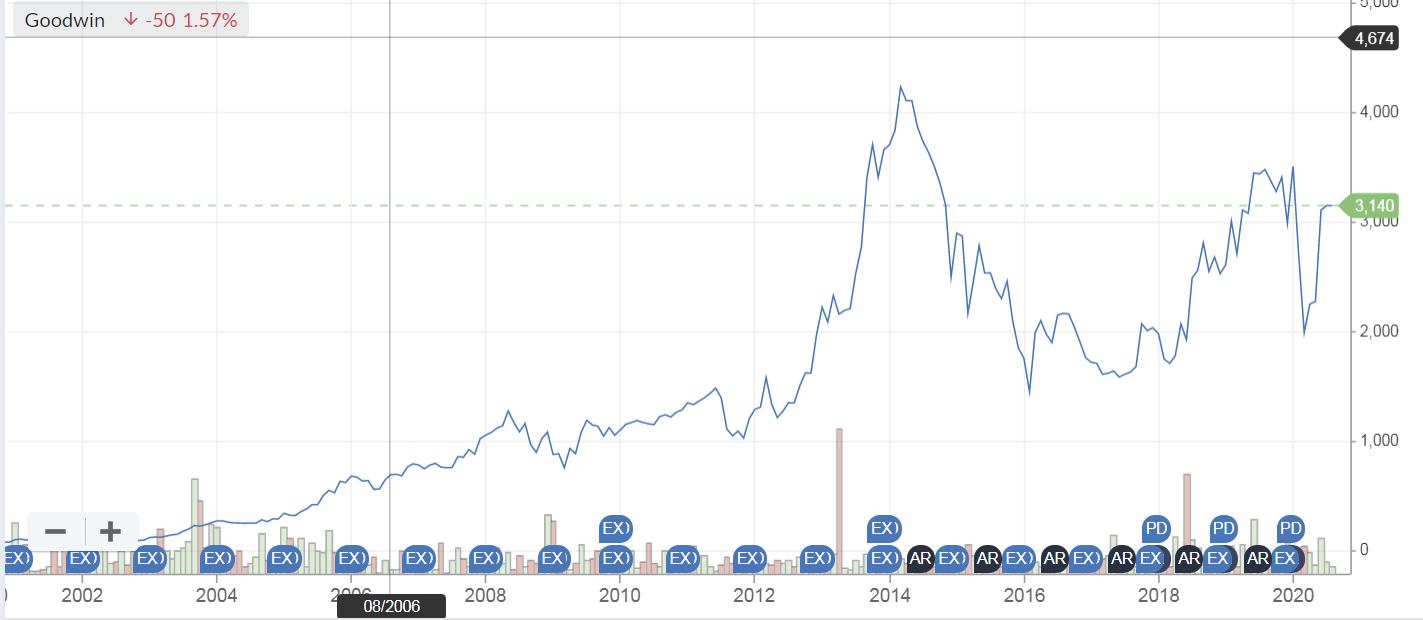
Looking at the long-term chart, buy and hold forever isn't necessarily the right strategy. This chart is saying to me, sell the big moves up, then buy back cheaper at a later date.
.
.
Castings (LON:CGS)
Share price: 349p (down 1% today, at 14:57)
No. shares: 43.6m
Market cap: £152.2m
This is another very traditional company, similar in some ways to Goodwin (LON:GDWN) above.
The share price has barely moved today, so there's probably nothing price sensitive in it, i.e. unchanged outlook.
This relates to the financial year ending 31 March 2021;
As previously reported, the group experienced a significant fall in demand at the start of the financial year with approximately 80% of our workforce being placed on furlough leave under the Coronavirus Job Retention Scheme.
Summary of other points;
- 70% of revenues are from commercial vehicles sector
- Customers closed factories from end March, resumed (limited) production in May 2020
- April & May - dispatches down 80% on pre-covid level
- Demand since recovering, now down 40% on pre-covid level
- Demand expected to recover further, to 15% down (based on forward schedules)
- Don't know whether demand is catch-up, or sustainable
- Focus - conserving cash (balance sheet remains strong), improving productivity & profits
My opinion - results for the current year are likely to be poor, but does that matter to long-term investors?
Brexit is a risk too, as are second-wave covid lockdowns. Are its customers seeing a sustainable recovery, with maybe pent up demand from end users, or will the commercial vehicles sector remain depressed? These are the key issues that would determine whether buying/holding this share is a good move or not.
The balance sheet is not just strong, it's ridiculously strong! So there's zero chance of this business going bust, even in a worst case scenario, in my opinion. For example, the last balance sheet showed £83.6m current assets (including £33.4m cash), and current liabilities of only £20.1m. The only long-term liability is £3.9m deferred tax, whic h is safe to ignore. Even the pension fund is in surplus.
Overall, I see this as a special situation, and worth keeping on my watch list. I'd be interested in buying some if it sells off when the next results come out, but not at the moment. Could be a good long-term income (divis) share, given that the balance sheet is so strong, it should be able to continue paying divis. Who knows, there could be some distressed acquisition opportunities too?
.
A few quick comments to finish off with, as I'm also out of time.
Pennant International (LON:PEN)
36p (down 8%) - mkt cap £13.1m
Trading update - for H1 to 06/2020.
Covid restrictions continued to impact delivery of contracts.
H1 revenues expected to be £6.3m, and a very hefty (for size of company) loss of £2m (EBITA) - that's enough to make a nasty dent in the balance sheet. Plus there is another £0.9m or £0.5m in exceptionals (not clear from wording which it is).
Cost savings of £1m p.a. implemented. Board taking 20% pay cuts for H2.
Liquidity looks OK - had cash of £2m at period end, plus £4m undrawn overdraft. Not stated how much taxation and other creditors have been stretched, a key omission.
Outlook - says H2 performance should "improve significantly" in H2, and be profitable.
Healthy 3 year order book of £36m.
My opinion - I think this is a fundamentally sound company, which I've followed for years. Its performance has historically been too lumpy to interest me any more. The shares are horribly illiquid too. It's not clear to me why the share is listed. At some point, I imagine it might be bought by a larger group.
.
De La Rue (LON:DLAR)
Appointment of joint broker
This usually happens when a company is considering a fundraising. Yet DLAR has already done one quite recently. Maybe there's a bit institutional overhang that needs a bookbuild to get rid of? We saw that recently with something else, I can't remember the company name now.
DLAR has appointed Numis, to work alongside Investec. Both of these brokers show not the slightest interest in private investors. In fact, Numis are notorious for aggressively trying to exclude all PIs from any company meetings!
Given that DLAR is now a small cap, the company really needs to recognise that it needs at least one broker that understands how important PIs are, in creating liquidity, and setting the share price (which the smaller trades do). Having 2 brokers that haughtily ignore, indeed actively work against the interests of PIs, in restricting access to companies, and research notes, is just no good at all.
A far better structure, in my view, is to have one broker that understands the market, and the importance of PIs. FinnCap are particularly good at this, but other decent brokers also make their research available on Research Tree, such as Liberum, and N+1 Singer. Then maybe the bigger brokers, are better at fundraisings & placings? So how about having 2 brokers, one to focus on institutional holders, and the other to nurture liquidity through a focus on PIs and HNW individuals?
.
Premier Veterinary (LON:PVG)
De-listing - another dire AIM minnow bites the dust. In this case, it's making an acquisition, and de-listing at the same time.
The £5m mkt cap, large Director holdings, and permanently loss-making performance, with an apparently unviable business model, means I'm glad to see the back of this one.
The only surprise is that the share price hasn't dropped 50% today, which usually happens when companies de-list.
Its last balance sheet looked insolvent, so nobody in their right mind would be holding this share.
I'm mentioning it to remind everyone of the bigger risk of companies de-listing in current tough economic conditions. There must be lots of financially stretched micro caps, wondering why they are wasting £100-200k p.a. on a stock market listing. So do be careful, you don't want to get caught out in something that decides to de-list.
.
That's it for today, see you in the morning!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
- [Paul thanks for the coverage on Goodwin (LON:GDWN) Goodwin, this is my second largest holding so my bias is off the chart
- The key aspect of these results is alluded to within the text of the Chairman’s remarks on numerous occasions. It is that the company has gone through a transformational period during which it has significantly increased and broadened its capabilities in order to reduce its historic dependence on the oil and gas and petrochemical industries
- It has taken some five or six years to reach an inflection point where the new business sectors are contributing orders on an unprecedented scale that more than offset the challenging conditions in oil and gas and petrochemicals. The key technological change underlying this broadening of capabilities is the ability to cast components vastly larger than they they have historically been able to undertake, this means they cast weights of up to 35 tons compared to say Castings plc (who coincidentally also reported today..but in considerably more downbeat fashion ) who typically cast weights of between 10 and 40 kg.
- The advantage of larger components is simply that they are technically more challenging and require very high-level metallurgical expertise possessed by very few competitors worldwide. As a result margins are typically higher and the level of design input by Goodwin is far greater and the limited range of competition is perhaps only four or five companies globally.
- The key advantage that Goodwin have is that they are fully integrated, by which I mean they start from the design collaboration, then the production of the complex casting, in some cases using patented Goodwin alloys that have very specific in use characteristics, then x-ray in their own recently installed underground x-ray chamber, then validate using Lloyds register or similar who are represented on site, then they machine the castings of up to 35 tons at their sister company ..Goodwin engineering ..to the ultimate finished component that is then utilised in typically mission-critical environments.
- For Goodwin the growth in order book is taking place in nuclear&defence, major multi year programmes ..that is vastly improving the quality of their earnings and the visibility thereof, only a fraction of this 2% is in current workload figure quoted
- Finally I would add that refractory products are virtually half the business and do not feature in the order bank at all, this part of the business has benefited considerably in recent years after the global number one competitor went out of business 2 yrs ago, they have global leadership as a result & again are fully integrated including a patented new silica free offering
- I’d suggest 14% turnover growth..& a record order book in the year of a pandemic are pretty good signs that future performance will reflect the scale of the physical changes that the have taken place throughout the business
In short Goodwin (LON:GDWN) has been transformed..but the transformation has been all but obscured to an extent by the decline in O&G ..but that’s s definitely coming to an end
I like it a lot ..a truly remarkable business
A very helpful contribution about £gdwn Rhomboid, many thanks. I am very new to them having bought in a couple of months ago because it seemed a compelling investment case at £24. They have a moat, the conservative characteristics of a long standing family run business and a growing market opportunity.
cheers
Francis
Paul sums up the investment case for Goodwin perfectly. “Overall, I don't doubt that this share is likely to be usefully higher in 10 years time, with a dependable flow of divis along the way. But is that exciting enough for me? Probably not. Looking at the long-term chart, buy and hold forever isn't necessarily the right strategy. This chart is saying to me, sell the big moves up, then buy back cheaper at a later date.” As a long term shareholder that is the way to make money in this share.
What is less obvious is that Goodwin has recently undergone a complete rejuvenation of its top management team which adds both potential and an element of uncertainty. Richard and John Goodwin, who had run the business as chairman and managing director respectively for 27 years, handed over the management to the next generation of Goodwins in April 2019.
Timothy Goodwin, the new chairman, has just turned 30, and Matthew and Simon Goodwin, who have been promoted to managing directors of the mechanical engineering and refractory businesses, are in their late 30’s.
As a family controlled business, Goodwin has always done its own thing. It does not have a designated chief executive or finance director, and just one non-executive director, Jennifer Kelly, 40, a local solicitor with no obvious experience as a non-executive of other quoted PLCs..
Although Goodwin has never ticked all the right corporate governance boxes, nor gone out of its way to court city analysts, it has always seemed able to refresh its top management team from within the family for more than a century. There can be very few successful family-controlled companies with that record.
Drat ..lost my 2 page post
The management team of Diversified Gas and Oil plc (Diversified Gas & Oil (LON:DGOC)) presented their HY results at one of our Yellowstone Advisory webinars on Wednesday and the more I hear them talk the more impressed I am.
There's a write up on the stockopedia discussion page and recording of the webinar can be found on the Yellowstone Advisory YouTube channel or by clicking here.
I hold DGOC and listened to the presentation and felt it sounded a little bit too good to be true.
Still holding for the forthcoming ex-dividend date to pass but then will sell as i believe the market is underrating just what strong favs Democrats are to win the Presidency and when the market realises then the USA Oil & Gas sector is likely to get marked down severly and then i will look to rebuy when i feel DGOC is oversold
Hi Paul,
Re Tribal (LON:TRB)
'NAV: £37.0m, less intangibles of £48.0m = NTAV is negative, at £(11.0)m. I don't usually invest in companies with negative NTAV, unless they're exceptionally cash generative'
Where do you see the NAV & Intangiables?
Manythanks John
"Where do you see the NAV & Intangiables?"
On the balance sheet in the Half Year results RNS,
You wont see those figures on Stockopedia until updated in a couple of days.
thanks Gromly,
I see that so Net assets - (goodwill & other intangibles)
why is DLAR on? Appointment of joint broker?!
Yes, I'm just building up to a little rant about brokers that disregard private investors!
Ok cool, thanks!! hehe
Paul - be interested to talk to you on this specific point
Quick note on Ra International (LON:RAI) (I used to hold. no longer do, remain sceptical):
End of Q1 order book $138.8m
Contract win today = $60m
Current order book (mid Q3) = $188m
Q2 + 1/2 of Q3 total revenue (balancing figure) = $10.8m (A)
Q1 revenue = $17.9m (B)
13th August YTD revenue = (A) + (B) = $28.7m
2020 Full Year Revenue forecast = $65.6m
RA International (LON:RAI)
Thanks for that Abtan - really helpful to have you doing your ongoing maths here despite having exited the bulidng so to speak.
I know per your calcs they pulled a rabbit out of the hat last year - and it appears they may have to do the same this year. It is one of the red flags large lump contracts where the booking of the sales may be out of alignment with cashflow.
With regard to using the order book as a direct measure to calculate sales how confint are you that this has any accuracy?
I could imagine the booking of revenue for accountancy purposes could be completely independent of the quoted order book in which case its use as a proxy for calculating sales could be very wide of the mark. Eg if oder book goes on billing but tuirnover is calculated on completion of contract date!
Also there is always the possibility/probability that there is additional income not reported via RNS. So if they only RNS large contracts - they might have picked up work in the beginning of July and completed the same month - that would result in higher turnover but would be misisng from your calcs. I woudl be surprised if they have zero adhoc billing but this could be the case.
I would say in the absence of direct confirmation from the company that the above methadoligy is wrong it is probably the best measure we have without up to date sales totals as to where we are. seems stupid though we need to donthe maths if the figure nis known and the company could tell us - i do understand here though the booking of revenue will be lumpy so posting numerous turnover updates might give more or wrong picture than a right one.
Another note here is that they have specifically advised that due to covid targets for this year may not be hit - so presumably the forecast being used is out of date practicably speaking if they have warned us already that they may not hit?
The momentum of the second half of 2019 continued into the start of 2020 with a heightened level of activity as we continued to deliver on a greater number of larger, long-term contracts. Whilst COVID-19 will have a material effect on our 2020 financial results, we believe the impact will be limited to project delays rather than cancellations.
Hi Rmillaree
Ra International (LON:RAI)
"With regard to using the order book as a direct measure to calculate sales how confident are you that this has any accuracy?"
Me: Very
There should be a direct connection between order book, new orders and revenue recognised on the P&L. The only thing that would make me less confident is if there has been another material order that has not been disclosed (unlikely) or if a contract has been lost and not declared...but even with this latter option that would mean booked revenue this year would be even lower than what I stated.
The only disconnect that might happen is between revenue booked to the P&L and cash actually received.
I didn't provide much insight to my last post, though I probably should have added that it looks like the company has only received one order this year (+ possibly a smaller one at the start of the year too) and revenue recognition so far this year looks pedestrian. It's a shame, as I was expecting more when I originally bought in, even with lumpy contract wins.
Worth noting as well that there was no update on performance so far this year. If things were going well, perhaps the company would have said something today.
A
RA International (LON:RAI)
Worth noting as well that there was no update on performance so far this year. If things were going well, perhaps the company would have said something today.
Agreed - the final paragraph i posted above per their prior update leads me to believe there is the possibility they could be well behind the prior expectations due to covid related contract delays - i am not writing off this year yet but if contracts stretch into next year due to covid related reasons it is what it is - in the scheme of things it doesnt really change the bigger picture - albeit generally contracts that take longer than expected normally come with associated extra costs so it does mean its likely that the delay will mean they end up with less profits. With what they do and the current covid issues worldwide - its possible that any or all of their contracts could be stopped with immediate efect anytime - no reason to belive that will happen but i do understand them not saying owt that may make them look stupid (or disingenuous) later.Hey ho at least they hopefully (unlike Globo and Patisserie Valerie) have the cash in the bank to see them through any issues.
Abtan,
Looking at previous years in 2018 Ra International (LON:RAI) rns'd $45m of $62m of total orders placed, in 2019 they rns'd $56.7m of $91m of total orders placed suggesting your calculations demonstrate a minimum revenue value for 2020 rather than an actual value. They do pick up ad-hoc orders.
Saying that they have already declared material effects from Covid in 2020 with projects moving from H1 to H2 and from H2 to 2021.
(It is possible I may have missed some declared orders, so happy to be corrected)
I’m not sure if I’m allowed to put this here, but it is topical (except that I should have posted it yesterday) and feel that as Paul and readers are some of the sharpest minds in the small cap universe it is worth asking ...
For better or for worse, I hold Craneware (LON:CRW) shares.
Two days ago they announced a Proposed Placing to Institutional Investors of what would be about 20% of Capital.
Yesterday they cancelled it, but that aside, I feel it is the same old story of the Private Investor being left out in the cold, with the price at a 9% discount to the share price when announced and with the 20% dilution.
I’m very happy to simply sharpen my pencil and drop a line to Keith Neilson, the CEO, pointing out how uncharitable this would have been, but just thought I would put it out here to see if anyone has any brighter ideas of who I should write to or what I should do/say.
The exercise will probably get me nowhere, but sometimes I think that these things have to be said and how is the company going to know if PI’s don’t point these things out now and again?
As always Paul, thank you for the wonderful write ups
Santa
As a P.S. and reading between the lines, it appears they pulled the placing because their main intended purchase was snatched up by someone else, so that may be why they went for institutions to raise the money very quickly, but even then, only a pity they didn’t think ahead a little more.
Hi Santa,
Craneware (LON:CRW)
Write to them, its really annoying, see what they have to say & if they get back to you & let us know...
I hold and it does seem a bit odd, poor show that they are to raise equity & then the deal disappears and they give very little information. Maybe they dont know, but I'd have expected a 'PE bought it for £50m more than we'd pay, etc etc'
I've been looking at Craneware though don't yet hold. Attractive ROCE but lofty forward PER over 37 according to Stockpedia. Maybe it's a rare situation where a rights issue is justified ahead of need? Also I wondered if the directors approved the (now abandonded) placing because even with a 9% discount, it represented a good deal to existing shareholders at the current share price rating.
Hi Santa,
Having just read the RNS I think Craneware (LON:CRW) have something to explain here , the RNS from a few days ago highlights that they want cash for 'opportunities', one being a sale process where they want to gain access to due diligence, & a strong balance sheet for Hospital confidence.
Then they cancel if but the reasons for it are still valid ie 'acquisition opportunities' plural & balance sheet strength. So for me it is odd to cancel it given they started the process. Maybe the last point below was reason enough to cancel but they should have stated that.
Sharpen that pencil!
RNS from 11th Aug
Overview
· Whilst growth of the Company since IPO has been primarily organic, the directors of the Company (the "Directors" or the "Board") believe there are specific potential acquisitions that offer the opportunity to accelerate the progress of the Company.
· In accordance with the Company's strict acquisition criteria, the Board has identified a small number of acquisition opportunities which it believes provide the Company with compelling synergistic benefits through a combination of: extending the Company's customer coverage across US healthcare providers; adding proprietary technologies, expert knowledge and application extensions; and increasing the Company's scale.
The net proceeds of the Placing are intended to be used to take advantage of these opportunities, whilst preserving a prudent balance sheet which is important to the Company's US hospital clients given the multi-year commitments they enter into for software solutions.
These potential opportunities vary in size and complexity and the Board does not expect to complete all of them. The Board believes that executing the Placing would position the Company to best be able to take advantage of the acquisition opportunities. In particular, one of the possible acquisition targets is in a sale process and the Placing is an important step to potentially gaining exclusivity and undertaking due diligence in that process.
The Board are strong proponents of a long-term efficient balance sheet and are committed to returning the balance sheet to a more efficient position within 18 months, either through completing the identified acquisitions or returning capital to shareholders.·
Thank you John for both your replies.
Will get a letter in the post and if I get a reply will try and be efficient and file it under Craneware (LON:CRW).
But please don't hold your breath! (That I get a reply that is, not whether I will file it).
Santa
Hi Santa,
'letter in the post' in that you'll email IR - just checking you never know :)
RA International (LON:RAI)
Also the move into O&G removes some of the ethical halo over Ra International (LON:RAI)
I think from an ethical point of view O&G brings good cash into areas that must provide people with jobs and food - which is probably priority number one in these regions?. So compared to the alternative that those jobs are not there (oil left in the ground) i would say i am more morally positive than negative ref this. IMHO the current trend of renewables is nicely going towards a point that the ethics of getting oil out the ground probably won't be a major issue enviornmentally in 30-50 years. So that simply leaves us with O&G companies respecting the local enviornment when they are working - that's 100% the responsibility of the bods who run the country to ensure that that is done correctly so sort of in their own hands other than probably not (if its a local dictator sat in his nice palace paid for by big oil) if you know what i mean.
Eckoh (LON:ECK)
For those of you that like recurring software revenue (and I do) Eckoh (LON:ECK) are worth a look. They mainly provide call centres and customer care teams with secure over the phone & chat bot payments - some of this with patent protection. So if you make an over the phone ( or chat) payment, the phone switches to system for the details, removing the opportunity for fraud. They have stated a number of times how positive C19 has been for the business due to much more home working by call centre staff & they seem to be building momentum having done nothing SP wise for years.
Totally agree with everything you say, john652. I have been in and out of Eckoh (LON:ECK) in the past and been disappointed with the lack of share price appreciation, which has remained largely flat-ish for 5 years now. One I keep on my watch list, and if this starts to gather any momentum then its likely to encourage closer attention, but currently too early for my liking.
TT
Hi TechnoTrousers,
Eckoh (LON:ECK) you could be right its too early. I'm very interested in all the tech charting chat about volume etc etc but I also like the Peter Lynch comment that historically it took 4 years before the shares he held rerated because the market saw what he did. Asked why he didn't just buy them much later he said he was not that clever. I'm just hoping its not 4 years & the news flow does seem to have improved recently.
Yes, I hope for you too that you are not waiting four years or more. I somehow think that won't be the case, as they do look interesting. However, until I see some confirmation, I am happy to keep these on the watchlist.
TT
Would be interested in your thoughts on Ra International (LON:RAI), who have announced a major contract win today. They have presented at the last 2 Mellos.
When Ra International (LON:RAI) IPOed 2 years ago - it was a primary issuance to build up the cash position of the company (which was already profitable and cash generative). The logic was that this additional cash would allow (in terms of funding working capital and credibility) RAI to bid for and win for larger contracts. The cash raised has largely sat unutilised on the balance sheet since IPO, as the company did not win major contracts - and brokers were forced to reduce earnings forecasts after the IPO, leading to a fall in the share price. As far as I am aware, this is the most significant contract ($60m), since IPO and perhaps starting to justify the vision of the IPO.
I hold - admittedly partly on ethical grounds - as I feel the company is providing much needed infrastructure in some of the most difficult parts of the world (eg Federal Government controlled Somalia).
RA International (LON:RAI)
very surprised by the 30%+ increase in shareprice today, i would have said very nice contract win $60 mill - but they need to keep those contracts ticking over anyway so spike seems OTT perhaps?
Always good when its a new client though and i am not aware they have done much work previously in the oil and gas field - so nice if they are expanding available customer offerings.
Does this change anything and justify 30%+ increase?
Order book is now $188 mill
Last confirmed order book was $141 mill - so its not 60 mill on top of where they were previously but still it seems to underpin the future business prospects nicely with potentially higher sales. One caveat being if the order book is spread more itno the future it might not materilaly increase sales.
Unfortunately with the shareproice increase it means they wont be able to buyback shares on the cheap anymore - so its a shame news wasnt delayed till sharebuyback was complete or more progressed.
Plenty of red flags with this share (look at comments on days of previous news) that i wont bother getting into today.!
Market cap showing as £79 mill (is this adjusted for todasy increase?) - pe showing as 8. Is this adjusted for todays increase?
Kinda tempted to take my profits here as i bought in as a speculative punt when the price was mid 30's but my gut feeling is there may be plenty of future potential work out there so i may hold on in the hope that the momentum can be continued - hmmmmm.
rmillaree. I agree with you and think this rise is excessive - and I have decided to try and sell. Also the move into O&G removes some of the ethical halo over Ra International (LON:RAI)
Re RA International (LON:RAI) (I hold), I think the jump in the share price today can possibly be attributed to relief that the order book has reached a new high when it did look as if it could be in decline. Here is a chart of their declared order book in US$m at various dates:
Given that the stock was on the cheap rather than expensive side previously, I am guessing relief rather than expectation is driving the rise.
Edit: I've added the statements and dates I took the values from below, apologies for the formatting, I can't figure out how to insert a decent table into the comments section.
HY 18 Outlook 31/08/2018 114
FY18 31/12/2018 119
FY18 Outlook 10/04/2019 130
TU 24/06/2019 150
HY19 30/06/2019 166
TU 18/12/2019 148
FY19 outlook 31/03/2020 138.8
Contract award 30/08/2020 188
Considering there was no live sport on and their shops were closed impressive that GVC numbers are only down 11% year on year. Thought it would be way higher.
1 CEO departed recently.
2. A few days later, GVC released news regarding HMRC investigation.
Hence the slide around 20th July
My morning smallcap tweet: Topps up, red ink for PEN.
Topps Tiles (LON:TPT) Yourgene Health (LON:YGEN) Pennant International (LON:PEN) Smartspace Software (LON:SMRT) RA International (LON:RAI) Panoply Holdings (LON:TPX) Immunodiagnostic Systems Holdings (LON:IDH) Directa Plus (LON:DCTA) International Personal Finance (LON:IPF) Eckoh (LON:ECK) Tribal (LON:TRB)
Topps Tiles (TPT) recent 6 weeks rev up 15.5%. "Performance of the business through the pandemic period has been significantly better than initial expectations." Now guides modest FY adj preax profit. [SP=43.2 Cap=84m]
Yourgene Health (YGEN) IONA, a non-invasive prenatal test, get Australian approval for sale. [SP=17.25 Cap=124m]
Pennant (PEN) guides H1 rev only £6.3m and underlying EBITA loss of £2m. Guides FY rev only £14m but with positive EBITA in H2. [SP=39.95 Cap=15m]
Smartspace Software (SMRT) has received the £4.6m, subject to adjustment, from the sale of Enterprise software business. Another £0.4m deferred expected. After the sale co will have £5.7m of (net?) cash, [SP=60.51 Cap=17m]. I hold.
RA International (RAI) wins 2 year contract worth c. $60m. [SP=45.94 Cap=79m]
The Panoply (TPX) wins 2 contracts from the Land Registry worth £3.2m and £1.6m. They are already in mgmt forecasts [SP=120 Cap=67m]
Immunodiagnostic Systems (IDH) the new automated covid IgM antibody test assay gets CE mark. [SP=251 Cap=72m]
Directa Plus (DCTA) its graphene enhanced facemask has been confirmed as having strong anti-viral properties by a university. The masks are washable at least 50 times. [SP=77.51 Cap=47m]
International Personal Finance (IPF) receives its £45m from the appeal against 2008 and 2009 tax audit findings after Polish court has formally confirmed decision is final. Collections reach 92% and credit issued reaches 43%, of pre-Covid expectations. [SP=59.5 Cap=133m]
Eckoh (ECK) wins six-year renewal of London Congestion Charge contract, worth £4m. [SP=63 Cap=160m]
Tribal Group (TRB) H1 rev down 4%. but EPS up 12%. Guides FY slightly ahead of market expectations for rev and adj EBITDA, and ahead for adj EBITA. [SP=58 Cap=119m]
Good morning Paul,
I'd love your views on Goodwin (LON:GDWN) FY results today. Profits down (£12.1m vs 16.4m prior year) and small cut in dividend (81.7p vs 96.2p) but current workload 11% ahead of prior year and focusing on higher margin products including their largest ever order announced a month or so ago. I hold
cheers
Francis
Francis. If you you don’t already you should look at @Rhomboid1MF on Twitter - he is a holder of Goodwin (LON:GDWN) and comments intelligently on the stock. As a holder, he is positive.
Thank you, I do follow him so I'll have a look at what he says.
cheers
Francis
GDWN is on the list now, I'll be looking at it next.
re Goodwin (LON:GDWN), there was some discussion at the beginning of the week with Jack about corporate governance and the value in family owned businesses. Goodwin (LON:GDWN) looks to be that rare beast in the modern world, an engineering business still run by the founding family (there are four family members on the board). I will be interested in your comments - not the easiest business to review in the space of a couple of hours - but it does look interesting.
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
Excellent stuff Holland Smith, this makes things so much easier, I hope Ed has offered you free subscription at the very least! And not forgetting MR C either, as reading this report with my coffee is now ever more cemented at the start of my day.
Hi HS , I look forward to this every morning - just sent you a virtual beer
excellent overview. Thank you :)
This is fantastic, thanks so much! Worth paying for I'd say.