Small Cap Value Report (Thu 13 May 2021) - ALU, BOTB, TTG, LUCE, DX., ECEL, TENG

Good morning, it's Paul & Jack here with the SCVR for Thursday.
Timing - update at 13:52 - I've got 2 more companies that I want to cover TTG, and LUCE, so estimated finish time 16:00.
Update at 16:32 - today's report is now finished.
Agenda -
Paul's Section:
Alumasc (LON:ALU) (I hold) - ahead of expectations update for this building products group. Looks good, but beware the pension scheme cash outflows, which partly explains why the PER is low. That said, the better the business performs, the less of an issue the pension scheme becomes.
Best Of The Best (LON:BOTB) (I hold) - an in line trading update for FY 04/2021. A stunning increase in EPS from 37.5p last year, to 125.2p forecast for the year just ended. The PER of 22 is either very cheap (if growth continues), fairly priced, or expensive (if growth goes into reverse). Get out your crystal balls!
Tt Electronics (LON:TTG) (I hold) - a solid trading update (towards upper end). Seems a decent business, at a reasonable valuation. Planning for double-digit operating margins with restructuring in the pipeline. Order book good. Cost pressures mentioned, as with many companies at the moment.
Luceco (LON:LUCE) - strong H1 trading update.
Jack's Section:
DX Group (LON:DX.) - stronger than expected trading and on track to significantly exceed adjusted PBT forecasts; 300 new vehicles recently acquired and 12 new depots announced
Eurocell (LON:ECEL) - improved full year expectations and market share gains, but cost inflation becoming a concern
Ten Lifestyle (LON:TENG) - Covid disruption hits these half year results and the outlook remains uncertain
.
Paul’s Section
Alumasc (LON:ALU)
(I hold)
218p (pre market open) - mkt cap £79m
Alumasc, the premium building products, systems, and solutions Group, today provides a trading update for the ten months ended 30 April 2021.
Strong last four months' performance
- All businesses performing well
- Cost-savings of £2.4m last year have improved margins this year
- Govt policies are helping support housing market
- Raw materials & shipping costs rising in recent months, being managed to maintain margins in the medium term (implies some short term margin impact maybe?)
CEO comment -
The great potential for the Group is starting to be realised with a strong continuation of the good performance seen in H1
Overall trading - is strong -
As a consequence of the continued strong momentum, the Board now expects that Alumasc's results for the year will be ahead of its previous expectations.
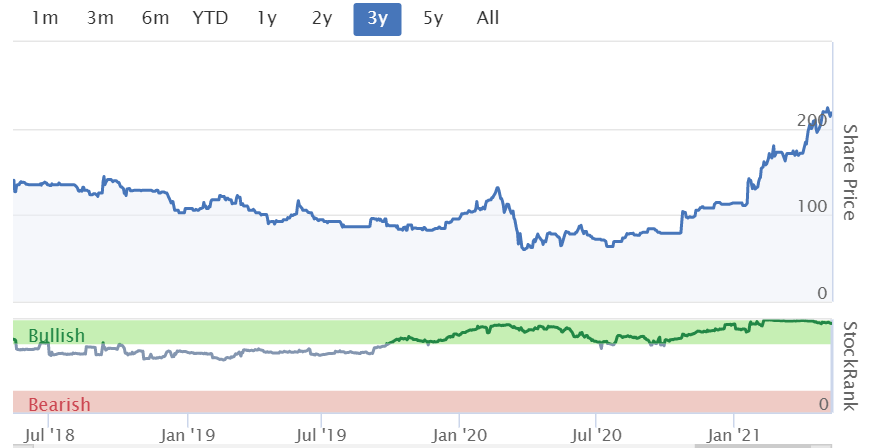
My opinion - I last reported here on 5 Feb 2021, on Alumasc’s very strong interim results. The share has gone up a lot since then (like most other shares in cyclical sectors). Hence an ahead of expectations update today justifies that price move up.
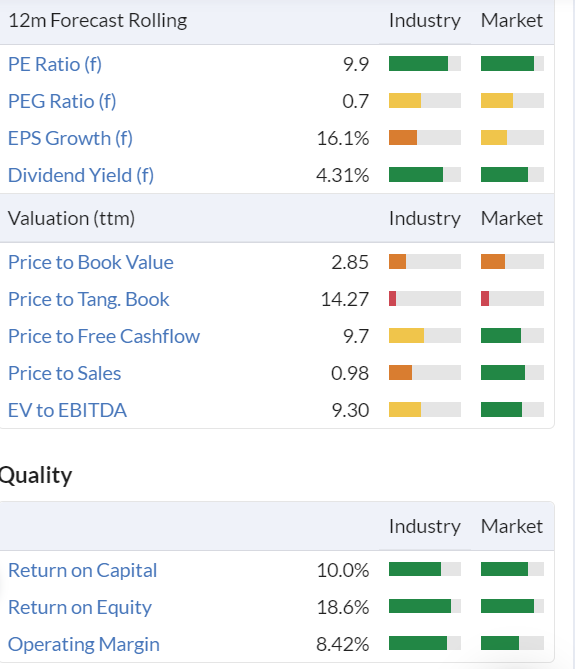
Many thanks to Finncap for an update this morning, it’s raising EPS by 9% to 21.7p, giving a PER of 10. That’s good value, but don’t forget to adjust for the pension scheme cash outflows, which will curtail the valuation somewhat.
Overall, this looks a very nice business, improving performance, generating decent margins, I like it.
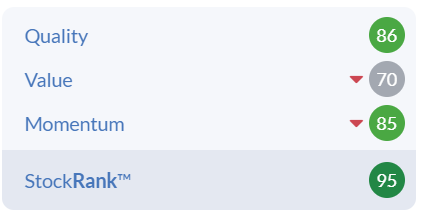
A nice combination of value, and quality here -
.
.
.
Best Of The Best (LON:BOTB)
(I hold)
2775p (down c.11%, at 11:42) - mkt cap £260m
Best of the Best PLC, (LSE: BOTB) the online organiser of weekly competitions to win cars and other lifestyle prizes, is pleased to provide the following trading update for the 12 months ended 30 April 2021 (the "Period").
I always laugh when I see an ordinary word in quote marks & brackets, because it means a lawyer has probably spent a few minutes lightly editing the statement, and probably charged a couple of grand for the privilege!
Today’s update is in line -
The Board is pleased to confirm that revenues and profits before tax delivered in the Period are expected to be in line with market expectations, which were most recently increased in March 2021.
It would have helped if the update had included a footnote, specifying what market expectations are. This saves time for all of us reading the update, and avoids any confusion, especially for people who don’t have access to the figures.
Many thanks to Finncap which has issued an update note today (available on Research Tree, or through Finncap’s own portal - although I think we should support RT because it’s such a useful service, and great to have everything in one place).
This reiterates forecasts as follows:
FY 04/2021: 125.2p (PER of 22.2)
FY 04/2022: 143.1p (PER of 19.4)
FY 04/2023: 165.5p (PER of 16.8)
Those PERs look strikingly cheap to me, given the track record of explosive profit growth this year, and last year:

.
Given that we’ve had an astonishing series of out-performance from BOTB, at some point the forecasts were going to be up with events.
So it shouldn’t come as a surprise that hugely upwardly revised forecasts have been achieved. Maybe some people hoped for further blow out out-performance? I must admit I was quietly hoping that the company might even smash the newly upped forecasts! But that's just being greedy.
Still, looking at the PERs above, the valuation is really very modest, if this year’s astonishingly good performance is sustainable. Imagine if it’s the start of a multi-year explosion in earnings?
My opinion - what the market seems to be telling us, is that it’s not sure whether the huge surge in EPS this year to 125.2p, from 37.5p last year, is permanent, structural growth, or whether it’s a one-off boost from lockdowns. Management have said that the growth began before the pandemic, and carried on when lockdowns were released last summer. So they believe this is the business taking off, irrespective of the pandemic/lockdowns.
The critical factor seems to be effective online marketing strategies, which are pulling in punters not just from the UK, but internationally. Customers are sticky too, as I know - I’ve recycled some of my special divis from BOTB into buying tickets for the weekly competitions! Even though I don’t really want a supercar (been there, done that, got the speeding tickets!), it’s just fun to play.
Another factor is that management sold a hefty slug of their own shares at £24 recently, which surprised a lot of us, giving quite a big discount to the then market price. I was very pleased to see that highly respected Slater Investments took a big slug of the secondary placing, and now owns 9.1%. Management still own about half the company, which is a ton of skin in the game still, so I have no problem at all with them wanting to take some money off the table. After all, what’s the point in being rich, if you can’t actually do anything with the money, because it’s all tied up in one share certificate? After 20 years of slogging away, they deserve to see the benefit of their hard work, in my opinion, and good luck to them. It might have been partly driven by worries about CGT rising in future too, possibly, but I’m guessing there.
If the growth continues, then this share is dirt cheap. If growth stalls, then the share is probably fairly priced. If growth turns negative, and FY 04/2021 turns out to be a one-off good year, then the stock is expensive.
I can’t predict the future, so can only make an educated guess. I think the stock is good value, and believe that further growth is likely.
It’s still extremely illiquid, so moves of c.10% should be seen as normal. It only takes a tiny amount of buying/selling to move the price. I usually keep a bit of cash on the sidelines to nip in on down days and buy more of the most illiquid stocks I hold, like this one.
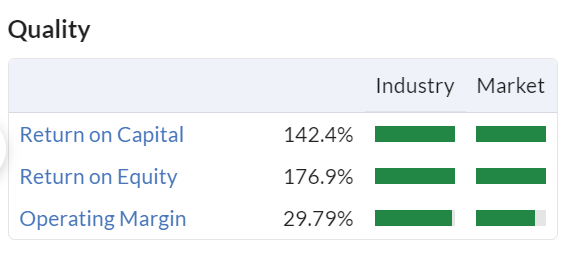
Just look at these quality scores - this is almost a unique business -
.
Tt Electronics (LON:TTG)
(I hold)
248p (up 2%, at 15:07) - mkt cap £433m
AGM vote - there was a significant (22.5%) vote against the remuneration report. I don’t know the specifics of the case, but generally am delighted to see that institutional shareholders are beginning to flex their muscles over ESG, including executive remuneration. This has been a long-running scandal, that passive shareholders have allowed management of many companies to absolutely plunder companies for their own personal benefit, often without any justification. Let’s hope times are (at long last) changing.
TTG says it will engage further with major shareholders to better understand their concerns. Good.
Trading Update -
TT Electronics (the "Group"), a global provider of engineered electronics for performance critical applications, publishes this trading update for the four months to the end of April 2021, ahead of the AGM taking place later today.
STRONG YEAR TO DATE TRADING
This sounds pleasing-
Trading in the first four months of the year has continued to strengthen with Group revenue 7% above last year on an organic¹ basis, building on the strong start made in the first two months of the year…
- Order book strong
- Mindful of supply chain shortages & logistics challenges
- Acquisition of Torotel in Nov 2020 is going well & expected to perform ahead of plan
- Site closures going ahead, to drive up margins
Overall trading -
… the Board now anticipates adjusted operating profit for the full year to be towards the upper end of market expectations2.
2Latest company compiled view of market expectations shows a consensus adjusted operating profit of £34.5m with a range of £33.6m to £35.4m
Thank you for the footnote, very helpful.
My opinion - looks a decent business, on a reasonable valuation. No mention of the covid-testing machines.
.
.
Luceco (LON:LUCE)
350p (up 6%, at 16:09) - mkt cap £562m
Luceco plc ("the Group" or "Luceco"), the manufacturer and distributor of wiring accessories, LED lighting and portable power products, is pleased to provide the following update on trading for the four months ended 30 April 2021…
Strong trading momentum continued into 2021
Strong demand, and soft prior year comparatives from lockdown 1
Cost inflation being dealt with well -
We have taken swift action to protect our margins from rapid, industry-wide inflation in raw material and freight prices and kept overheads under tight control.
H1 guidance - note the very strong profit margin, and profits doubled against the prior year soft comparative -
In light of the above, for the first half of 2021 ("H1 2021") we now expect revenue of approximately £105m and Adjusted Operating Profit of approximately £18m.
Order book good, but notes tougher H2 comparatives coming up
Broker update - many thanks to Liberum for crunching the numbers for us.
It forecasts 18.4p EPS for FY 12/2021, up 19% on last year. That’s a PER of 19 times - looks about right to me.
My opinion - this company has performed really well in the last year, with lots of positive updates. There’s talk of more M&A.
It’s particularly good to hear a company swat away cost inflation, saying they’ve taken swift action - which must mean raising selling prices. The high margins suggest it has pricing power.
All in all, everything looks very nice here, on fundamentals. The big rise in share price looks justified. Probably priced about right, in my opinion.
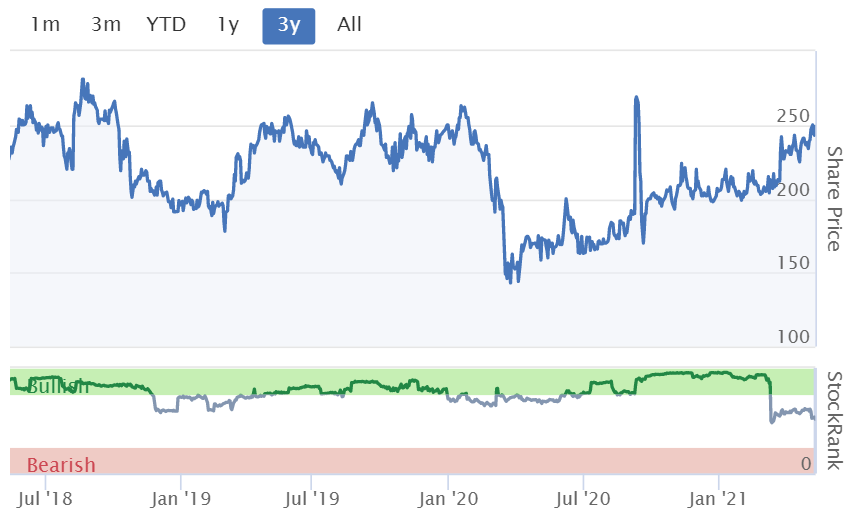
When a chart looks like this, further gains can sometimes be more difficult to come by.
.

.
Jack’s section
DX Group (LON:DX.)
Share price: 34.25p (pre-open)
Shares in issue: 573,682,000
Market cap: £196.49m
DX Group (LON:DX.) provides delivery services to business and residential addresses across the UK and Ireland.
The name comes from document exchange, which harks back to the group’s origins in 1975 as a Document Exchange service to the legal sector. Now, DX provides overnight delivery services of items like confidential documents, valuable packages, and large, awkward-to-handle freight, unsuitable for standard conveyors.
DX Freight comprises DX 1-Man, DX 2-Man and Logistics, and specialises in the delivery of irregular dimension and weight freight ("IDW").
DX Express comprises DX Secure Courier, DX Exchange and Mail, with a focus on the express delivery of parcels and documents.
The group has been loss-making for a few years now but the trailing twelve month (ttm) figures and broker forecasts suggest that DX is returning to profitability.

Even after a run up in the share price, DX generates annual revenue of £341.9m compared to a market cap of £196.5m, so depending on what sustainable profit margins look like there could be scope for a continued rerate. The forecast PEG is just 0.5x, and the company trades on 5x ttm free cash flow and 0.57x ttm sales.
Meanwhile, directors have been buying shares and the company has recently added another 300 new vehicles to its fleet, taking the total to 900, which suggests DX can see some growth opportunities ahead.
Lloyd Dunn (CEO) said at the time:
We have further investment planned across sites, technology and equipment, and with our aim to set market-leading customer service standards, DX is increasingly being recognised as the premier operator in its markets.
DX's trading performance has been stronger than expected.
Trading at DX Express has been in line with management expectations but revenue growth at DX Freight is now expected to be around £10m higher than previously anticipated.
This has been driven by significantly increased volumes, both from existing customers and through new customer wins.
As a result, the Board anticipates that DX will significantly exceed existing market expectations for adjusted profit before tax in the current financial year, with an associated improvement in operating cash flows. The board has consequently decided to repay government furlough payments totalling £0.6m.
Furthermore, the group is accelerating its plans to expand DX's delivery network by targeting the opening of 12 new depots over the next two years.
Conclusion
A further update is expected in mid-July 2021.
It’s hard to pick any holes in this update, brief as it is. Trading is ahead of expectations in Freight, momentum is strong, and the group is paying back what help it did receive over the lockdowns. The fleet has been expanded by 50% and the directors have been buying shares.
It all suggests to me that there is something worth investigating here.
The balance sheet is a concern, with the Z-Score flagging liquidity and liability issues.


Heading over to the balance sheet, it looks like the bulk of total ‘debt’ is in fact capital lease obligations.
Ideally the group would strengthen its finances further given the weak liquidity scores but, on balance, the financial health does not look to be as weak as the Z-Score might suggest.
The group can be very capital intensive, so that is worth bearing in mind.

Overall, given the operational momentum, the recently expanded fleet, and plans to open 12 new depots, I’d be a happy holder here.
Eurocell (LON:ECEL)
Share price: 274.2p (-4.79%)
Shares in issue: 111,498,522
Market cap: £305.7m
Eurocell (LON:ECEL) manufactures various PVC products, which it then distributes to a network of fabricators, small builders, and independent stockists. It also recycles customer factory offcuts (post-industrial waste) and old windows that have been replaced (post-consumer waste).
You can really see the Covid crash and recovery play out in Eurocell’s share price chart.

As with so many other stocks now, the question has shifted from ‘can it survive’ to ‘will it thrive’.
AGM trading update for the four months to 30 April
Highlights:
- Total group sales up 23% compared to the same period in 2019; up 75% on the same period in 2020,
- Life-for-like revenue up 20% on the same period 2019 and up 28% on 2020
The group says it is ‘continuing to take market share’ but has also had to increase prices slightly to mitigate raw material price inflation. Comparisons to 2020 are affected by lockdowns, when the business closed from 23 March to mid-May but growth on 2019 numbers is encouraging.
Strong demand in Eurocell’s markets has put sector supply chains under pressure and the group is experiencing an ‘increasingly inflationary environment’, with prices of certain raw materials, particularly PVC resin, rising significantly in 2021.
These rising input costs are being offset by a resin surcharge and the group’s own recycling plants, which supplied 25% of our raw material consumption in 2020.
Eurocell is also fitting out its new warehouse. This is already being used in the group’s Profiles and Building Plastics divisions and should increase capacity and operational efficiencies.
Conclusion
The short-term outlook for the first half has improved here and Eurocell says its markets are strengthening. Together this leads ‘to an improvement in our full year expectations’.
That said, raw material supply chain inflation will continue to be a concern.
Looking over the financial data, the company has managed to grow revenue in the past but has struggled to translate this into profit growth.
There’s no denying the improving outlook here and it could do well in the short term, but I’m not sure I’d want to hold this one through the economic cycles. Capex can be quite heavy and the group retains a net debt position.

Assuming the group gets back to FY19 levels of profitability, that would be a PE ratio of 14-15x. I’m not sure I’d want to pay much more than that.
Eurocell says it is taking market share but competition will always be a risk here, plus there is potential inflation to consider.
Ten Lifestyle (LON:TENG)
Share price: 99.5p (-0.5%)
Shares in issue: 81,530,891
Market cap: £81.7m
Ten Lifestyle (LON:TENG) partners with blue-chip corporate clients worldwide ‘to deliver technology-enabled travel and lifestyle services’. It’s a concierge service, basically.
I’m not sure about this one at first glance. Even though revenue has grown at a compound annual growth rate (CAGR) of 17.9%, the group has struggled to turn a profit.

Forecasts suggest this will change in FY22e, and Ten was free cash flow positive in FY20 (for the first time), so it is possible that an inflection point is approaching, but the track record of losses makes me cautious.
Highlights:
- Net revenue -28% to £17.2m,
- Adjusted EBITDA -19% to £2.1m,
- Loss before tax has increased from £3.3m to £3.6m,
- Cash of £9.2m, long-term debt of £1m.
The group continues to invest in its proprietary digital platforms - £5.5m of investment in the period compared to £5.9m in H1 2020. That’s a lot of money getting pumped into these platforms considering the small scale of revenue and losses.
These results have been affected by Covid but it looks like travel-related disruption could continue to impact results over the next few months despite a ‘strong pipeline of new contract opportunities’.
In terms of outlook and current trading, request volumes and the resulting net revenue since the end of the half year remain below prior year due to the effects of COVID-19 on Ten's core propositions in the dining, travel and live entertainment categories.
Conclusion
Ten references the fact that it has remained adjusted EBITDA positive, but I would attach greater weight to the fact that the company is loss-making on an absolute basis and has been for many years now.
FY20 did bring a much improved cash flow performance, so it’s worth keeping tabs on in the longer term.
For now though I’m not convinced of the opportunity here and the near term outlook is decidedly uncertain, with many important variables beyond the company’s control.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Best Of The Best (LON:BOTB) (I hold)
My own take on today's update is one of confusion.
I just can't see how the current forecast make sense, without it highlighting an underlying weakness somewhere.
GROSS MARGINS
The most important metric that I track is the value of prizes given away, which for 2020-21 came to c.£9.8m.
If full year revenues are indeed £44m, then this implies a H2 gross margin of 60%, a drop from H1 (63%).
It would have been nice if the company could have kept this gross margin going up.
MARKETING
Finncap's £14.0m PBT figure implies a drop in marketing spend to £4.9m, 22% of revenues, down from 27% in H1.
If my understanding of the accounts is correct, this implies either higher costs to advertise vs H1 (entirely possible) or less confidence in their marketing strategy (also possible.)
----
There's a little too much guess work to make from a 1 line trading update so I'll remain wary of the short-term share price and look forward to more clarity next month.
Cheers
A
I know this is out of left field at a mkt cap of £1.9bn but does anyone have a view on what's going on with the SP of £BEZ. This has been on the decline for a while now what with insurers having to payout over the pandemic, but life moves on and a super TU this morning and metrics of PE under 10 and PEG of 0.1 must make this one of the buys of the year. Got to be a takeover target at 300p ish.
Anyone got more knowledge about non life and special risks situation at the moment
Steve :
Can't help with any specific knowledge and am equally mystified by today's / recent price movement, particularly when other COVID affected stocks have managed to "see through" its temporary nature. My only consolation is that (respected investor) Leon Barros mentioned BEZ recently as an interesting value situation. Can't remember the forum unfortunately. Sometimes things take a long time to work themselves out - I held the insurer Amlin for 10 years before they were taken over at a decent premium......
Geoff
thanks Geoff.
I was trying to remember the names of a glut of non life insurers who were taken out in 2014 or so. Catlin, Amlin and another whose name still escapes me. I have listened to Leon Boros a number of times and always noted his sage comments. I have held £bez since 2013 and am debating whether to add. If 300p comes to pass the decision may be taken out of my hands
IML,
I'd agree that care is needed in interpreting survival data from screening studies. However, it certainly can make a difference - it's unlikely I'd be writing this now if my prostate tumour hadn't been spotted early by screening 16 years ago. But more significantly, and moving away from the anecdotal, even if screening currently does little or nothing to improve overall survival, screening generates data, raises profile, which in turn is likely to lead to more rapid development of treatments, and ultimately will allow such treatements to be applied early.
There have been several comments here about inflationary pressures this morning. The visual effects (i.e. assuming I don’t sell) on my portfolio have been significant. The first I heard of these in a striking way was recently when Mcbride (LON:MCB) said they had already anticipated rising raw material and plastic costs but the rate of increase had caught them out and they were having to react to much sharper rises. At the macro level, noises and real effects are coming through from the US and this is reverberating around the world stock markets.
When markets open up again after the pandemic eases such as now e.g. the UK, then immediate pent up demand presumably increases significantly as the flood gates are opened so to speak. Lots of sellers don’t keep stocks (e.g. UK car manufacturers and computer chips recently) On the other hand, the same factors that have led to pent up demand have presumably also led to hold ups in supply, as the pandemic is unable to discriminate between suppliers and receivers (demand).
What I am trying to get my head around is whether there is quite a significant short term effect until rate of supply catches up and rate of increase in demand eases off; or whether these are inflationary pressures that are going to be with us longer term, not least because of the actions of government printing money big time to protect their economy short term.
I don’t have the answers, but would be interested in comments form others, including Paul and Jack.
I am not so sure this is a supply/demand issue, I think it is a centralised plan by govs and central banks, seen as it would help governments tremendously if inflation rose and interest rates did not, as their various debt piles would evaporate away. The RBA in Australia has recently stated explicitly what I think other central banks are thinking:
https://www.bloomberg.com/news...
Essentially they are set to target wage growth of 3% YoY and all other inflation measures will be considered transitory.
Right now stock markets are shedding because they are expecting interest rate rises (or are taking advantage of bond yields possibly), but developed nations, particularly the US, simply cannot raise interest rates- it might even come to pass that as inflation hots up, the Fed lowers rates. I think they are telling themselves it will be fine because wage growth is the plan.
I am positioned almost exclusively for inflation (miners, commodities, uranium, gas). I don't see how you can own bonds in this environment, which I think bodes well for gold. Probably Bitcoin too but I can't wrap my head around it so won't go anywhere near.
Time will tell.
Hi Paul..I know you are busy but would appreciate your thoughts on the savage market reaction to today's news from BOTB.. This is a strong marker for me to buy more, as this company has got great metrics. Having said that so many quality companies are down this week, it's great for those with cash to add more. Tony
I suspect the 'market' overdosed on beats, even wants the beat to be beaten.
Not sure what some people were expecting, the company announces that its in line with what it said so in the last 6 weeks of trading from before nothing changed. This is by far my biggest holding having bought in at around 2.50 a few years back and whilst I top sliced last year I have no intention of selling anymore at the moment.
The key question will be in the June update what they expect next year to be and what is there strategy to grow either internationally or into other areas. I also expect a nice 40-50p dividend again.
Looks like a good opportunity for those who missed out on the recent placing. (I hold)
I'll admit as a holder I am slightly disappointed with 'in line with expectations' update. In H1 they made 59.84p EPS so comparing with upgraded expectations of 125p this suggests they might have only improved EPS by about 10% in H2 - I thought it might be even stronger building on the customer database that will have increased thanks to the spectacular growth in H1.
Does that mean I'm looking to sell? No. Even if EPS growth was "just" 10% per half from now on that would be amazing and I think a rating of 30x PE is deserved. However, I think some shareholders, myself included, are nervous about how much revenue was driven by lockdown. If they can sustain or increase revenue in H1 FY22 I can see the share price re-rating again in the autumn or winter.
Angle (LON:AGL)
No regulatory news from Angle but a headline news item in the press today regarding the ‘failure’ of a large scale ovarian cancer trial. No mention that the technology employed is now deemed limited and that new options have evolved which show great promise. Why spread optimism when you can spread gloom ?
Clinical Trials Arena published an interview with the head of Angle (LON:AGL) clinical labs which gives a view of what they are planning and what might be possible.
hTTps://www.clinicaltrialsarena.com/analysis/liquid-biopsy-tech-non-invasive-cancer-monitoring-in-clinical-trials/
Are you talking about the study on screening in ovarian cancer that concluded screening did not save lives? That's important, and backs up what was found previously in breast cancer screening studies, namely that patients only appeared to survive longer with the cancer because they were caught earlier. In effect, screening added years of diagnosed time, but no additional actual lifetime survival because treatments are no more effective.
Speaking as someone who works in Health Economics, this is really important public health finding, as screening has long being suspected as not really beneficial.
Heaven forbid the media cause this to become generally known and Angle (LON:AGL) stock price suffers.
£AGL It possibly depends on where you argue ‘screening’ stops and ongoing diagnosis continues. My understanding is that screening of the type used in this trial in itself won’t save lives but screening using a CTC gathering device will (eventually) save lives. As you say the earlier the detection the better chance of beneficial treatment. CTCs, esp clusters, can be detected very early and there is research being done to see if clusters can be broken up before they take root elsewhere. Also, if physically invasive biopsies can be avoided there can be benefits from avoiding secondary infections / problems. Also, in economic terms, benefits will accrue from patients being treated in the correct environment – ie not misrouted to specialist clinics when the mass is benign.
To me the biggest benefits / savings will be made analysing the CTCs in labs and finding which treatments will work and which won’t – and also which treatments stop working over the patient’s lifetime. Such ongoing lab work will no doubt lead to discoveries of new treatments.
Hello to all Angle (LON:AGL) supporters, and hanks JimMcLad for your initial comment and reference today.
I emailed the CEO this morning with the bbc.co.uk report, and asked whether they will respond, and what would they be saying to put the Angle (LON:AGL) process and opportunity into the correct context.
As you say the earlier the detection the better chance of beneficial treatment.
That's the opposite of what the study indicates. The 'extra' survival is a total artefact of early diagnosis. In effect, if you catch someone's cancer the day before they die then survival is 1 day, if catch it a year before then survival is 1 year. Fantastic right? No, they both died on the same day, it's just that 'survival with cancer' is increased, but not lifespan.
This has been the issue with screening for a while. Treatments don't work better the earlier they are used, and cancer aggressiveness is not changed.
Angle (LON:AGL) I have no issue with stating that ‘screening’ in itself doesn’t increase lifespan. However, if cancer is detected by any kind of screen, especially if detected early, and action is taken (eg primary tumour removal before it metastasizes ) and the patient survives then I’d suggest the ‘screening’ at least helped to increase lifespan.
Parsortix has not been suggested for mass screening (as yet) but the resulting treatment and ongoing monitoring of patients will increase lifespan – afaic that’s the important thing.
Re Angle (LON:AGL) : As I understand, a differentiating feature of the Parsotix system is that it captures the whole circulating cancer cells which can then be analysed and matched up to the most effective treatment. For example, a cancer drug might only be 10% effective on say breast cancers in general, but 100% effective if matched to the right type of breast cancer.
Having the correct 'companion diagnostic' (as I think the term is) can dramatically increase a drugs effectiveness and hence use and hence business case for it (from patients, paying party and developer/manufacturers perspective).
Here are my SCVR heat maps for today (prices as at ~9am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Just published Treatt (LON:TET) H1 results presentation to analysts. Daemmon Reeve, CEO and Richard Hope, CFO outlines H1 results where they have seen revenue up 13.5%, with gross profit margin up 880bps; very strong growth has been enjoyed from the ‘healthier living’ categories. Good trading momentum continues with encouraging order book levels and further growth opportunities. Profit before tax and exceptionals for the current year is expected to be at least £20m, exceeding the current consensus of £18m. Video & Podcast.
Also, don't miss the Stockopedia/piworld StockSlam next Wednesday 19th May at 6-7.15pm. Ten 'Slammers' present their best stock idea in 3 minutes, followed by 3 minutes questions. Slammers include Ed Crofts, Damian Cannon (of course) and other esteemed investors. Register here.
Finally, Cerillion (LON:CER) will present interim results on Thursday 27th may at 4pm. They've just reported they will exceed expectations for H1 with revenue c £12.8m (+25% pop) and adj EBITDA c£4.8m (+77% pop). To join the webinar register here.
Pension scheme deficits in general and ALU in particular. Suggest important to read the last tri-annual review to establish the pension scheme assets and liabilities as subsequent seemingly small changes in performance and assumptions can have appreciable effect.
Luceco (LON:LUCE) providing a shining green light in a sea of red this morning with SP currently up around 6% following a very upbeat TS finishing with this statement for the current year "Strong sales momentum and sustained profitability mean that we expect to double our profits for the first half against last year and retain this healthy combination as we enter the second half." Any chance of taking a look at this .
Sounds interesting. OK, I'll take a look at Luceco (LON:LUCE) next - it's a company we like here at the SCVR, and have reported positively about many times. Section should be up by about 14:30
Titon Holdings (LON:TON) reported relatively solid numbers this morning. (I hold). It is too illiquid and unsexy to be of general interest. But its comments on supply shortages in the construction industry even for the most basic commodities (cardboard, plastic and metal) , input cost increases and its own ability to increase prices, gives even greater credibility to the general economy inflation risk.
“we have experienced some procurement difficulties and an element of scarcity in recent months for basic materials, such as plastics, cardboard and metals, all of which are vital to our production. We are also seeing price increases imposed by our suppliers, which will impact on our margins but will be mitigated by our own pricing strategies. The shortages of building materials including components is industry wide and now being more widely reported.”
I know Paul does not like Morses Club (LON:MCL) on principle but very interesting and IMHO encouraging results today. The loan book has shrunk unsurprisingly and customer numbers too (255 to 180K) but the business remained profitable and the bigger bigger picture is transformed.
In the key Home Credit business it cites no of smaller competitors shrinking from around 400 to 262 whilst market leader Provident has announced it is pulling out and NSF is financially crippled. It has transitioned to a mostly digital execution (67% lending online, 80% of collections), closing 90 branch offices to WFH permanently. With a smaller, higher quality borrower base, impairment FELL to 21% from 27%. Once the economy opens up and its customers want to go on holiday to (wherever they can they will go !!), demand will boom and they should mop up lots of it, especially if they pick up lots of experienced good agents. Their customer satisfaction measure remains at 98%, having transitioned to a semi-digital service. The only fly on the ointment is potential regulation - and whilst this could be devastating, I think it more likely to cement them as the new market leader in a protected, regulated industry.
The digital side was slightly disappointing and behind where they said it would be at acquisition, with a big loss again this year of £11.3Mn on a statutory basis. Impairment was also at top of range at 55%. However, they promise "run rate profitability" by end of this fiscal year and now truly have a broad, digital offering from banking services on a transparent Ryan Air-style PAYG menu to long term high margin lending. My .back of the envelope calculations suggest a loss of no more than £2-4Mn and good profits thereafter
Financially they seem sound. Net equity despite everything and the investment in the digital business was unchanged at £70.7Mn. Renewed lending facilities. Dividends for the year were 3p (so a trailing yield of 5% on today's price).
The key to me is the massive change in their external market in their favour. The regulatory risk is a constant threat but if they can deal with that I think the future is very bright.
Clearly, I hold and plan to buy more. Would welcome comment by the community.
Yes Morses seem to be very well positioned for when the lending market picks up - solid performance in the circumstances and going forward they should largely have the home credit market to themselves as Provident have withdrawn, while a lot of the smaller peers will struggle to survive.
I hold Morses Club (LON:MCL) but i'm trying to decide if it's time to cut my current small loss or commit to holding the next couple of years. this is a tricky one because the share price certainly doesn't reflect it's normal (pre-pandemic) performance.
My main concern, which grows more and more in this sector, is that regulation is becoming extremely onerous. Its not just the financial impact of the fines that could be imposed. The negative news coverage is a killer these days, and the media love to put an evil spin on things. when evaluating shares i'm now actively trying to not underestimate the impact of cancel culture everyone seems to be embracing currently.
Im also a bit worried about the Loan book value decreasing by 26.5% and the loss of customers, decrease of 29.4%. With a lot of people having saved extra throughout the pandemic, how quickly can the company recoup these lost customers? (I know a few people who used to love a payday loan but because of covid, ended up saving a nice rainy day fund and no longer live pay cheque to pay cheque)
That said, a 2% dividend is welcomed. Outlook certainly sounds like they expect gain additional customer's from other lenders. I'm personally leaning towards selling. the more i think about it, the less confidence I have. will decide after another coffee.
i think the decision of Provident Financial (LON:PFG) to withdraw from the doorstep lending market is an ill omen for Morses Club (LON:MCL) . The regulatory landscape is becoming ever more hostile to this type of lending as lenders have to demonstrate "affordability" or face big fines. I think the pandemic has also changed long term behaviour which makes doorstep lending less socially acceptable. I don't think that the doorstep lending model lends itself to digital switching as it very much relies on the decision of the "man on the ground" and I would also suggest intimidation tactics to collect payments.
Coupled with the demise of payday lenders like Wonga and the woes of other lenders in the low quality credit sector like Amigo Holdings (LON:AMGO) it rather begs the question what will fill the gap. To my mind H & T (LON:HAT) (I hold) could be a beneficiary as pawn lawns are inherently affordable, a borrower cannot pay more than the loss off their physical collateral. Also most of the population own items of value that are easy to pawn e.g. smartphones, consoles, jewellery etc
Hi MM
I’m not sure Morses Club (LON:MCL) would get such stonking customer ratings if their business model was to strong arm their customers! I think the point about the demise of other providers in this highly regulated market means that Morses Club (LON:MCL) can be even more selective in their customers (than they already are). Remember, if regulation were such a bad thing for business why do so many companies actively lobby for more!?
The ability to provide credit without regular home visits seems to be something that they have demonstrated successfully during the last year, and now their move into online banking for underserved customers means that they are diversifying their offering.
I agree H & T (LON:HAT) are a competitor, but surely the big issue at present, for both companies, is the heavily suppressed demand for loans, based on vastly reduced consumer expenditure due to 15 months of Covid restrictions, and furlough payments to people who otherwise would be unemployed. Both of these factors will change significantly in the next six months.
I have shares in the former, and have regularly held shares in the latter.
I think you ask the right question : what will fill the gap (in lending to those with poor credit files). Old style door-step lending is going/gone (regulation but also social change now so many have online) but the value of personal F2F interview to establish the willingness to pay has not. I therefore see this as a benefit - fewer calls is cheaper but the 1st call is key and occassional check in v valuable when impairment can be so high. It is also a great way to demonstrate ongoing affordability checks and hard to set up - a potentially great moat. The social side I think is unchanged; in 18months we will be able to knock doors again and be happy to do so - I do local politics, so do a lot of this! Even now , it is OK.
On pawnbroking, I agree it has a future but I am less sanguine than you. Outside of immigrant families who often have community not branded lenders, I see fewer families with valuable jewelry and all the other items you mention attract little 2nd hand value/sell on ebay etc. So H&T will do OK but there was a reason it was trying (unsuccessfully) to get into online lending.
The key is really knowing your customer - which is the best protection in regulatory terms. Unless the whole industry is blitzed (when your original challenge applies - where will these people borrow? ), I see Morses doing very well. I think Provident are retreating because they spoiled their own network and have better fish to fry. I think they would have sold but this would have attracted regulatory hassle they do not want.
As ever, time will tell.
I have invested in Morses Club (LON:MCL) from September and remain to have a high degree of confidence in the company. The reduction in the Loan book value of 26.5% and the decrease in customers of 29.4% is only to be expected given the pandemic. The fact that they made a small statutory profit of £0.5mil (without government subsidies) is quite surprising if not amazing. I have seen it mentioned previously in the commentary that the pandemic has significantly accelerated the change in some companies strategies and I would say this is definitely the case with MCL. Their strategy in the move to digital seems sound and providing they can deal with the regulation side of things IMO they are well positioned to become a much bigger company than they were prior to the pandemic and should correspondingly have a much higher share price but only time will tell ....
BOTB issue an inline RNS shares fall 10%??!?! Who says the stock market is efficient.
That's why it is called Efficient Market Hypothesis
Atalaya Mining (LON:ATYM) (I hold) Q1 financial results clearly shows the influence of the copper price:
· Q1 2021 revenues of €97.4 million (Q1 2020: €61.2million). Higher revenues were the result of higher realised copper prices and slightly larger volumes of concentrate sold.
· Q1 2021 EBITDA of €47.4 million (Q1 2020: €9.3 million). The increase in EBITDA was driven by higher revenues and lower operating costs compared with Q1 2020.
· Q1 2021 profit after tax of €33.7 million or 24.5 cents basic earnings per share (Q1 2020: €2.9 million or 2.3 cents basic earnings per share).
So, revenues: +59%, EBITDA: +411%, Profit after tax: +1049% (Q1 21 vs. Q1 20) with only 5% higher copper production. Share price still down ~2% at the moment...
Q1 operating profit almost equal to all of 2020.
I've been buying this after Edmund Shing's stockslam pitch. (Thanks Ed! Thanks Stockslam!) The operational leverage across the mining space is quite something to behold. Gold, PGM, and Copper miners are going to have free cash flow coming out of their ears. Possible risk that inflation in oil and steel outstrips metal prices however, but even then you've got to like base and precious metals miners right now.
Issue with share price is that a lot of holders are using miners stocks as options on underlying metal (I am doing the same with some Canadian uranium miners) so can be highly sensitive to metal price as opposed to actual good news from company.
I hold. (about a dozen miners)
Big fall this morning in On The Beach (LON:OTB) due to outside trading hours announcement last night that they are pushing back the first departure date for bookings by two months to 31st August.
This is the concern I expressed earlier in the year coming to fruition. Even a relatively short delay in the business restarting potentially wrecks the forecasts as they are losing the major part of the lucrative summer season.
It continues to show that we bet against COVID at our peril. While the EU vaccination programme will probably have caught up by the autumn those high margin summer sales cannot be recouped. Hopefully, there won’t be a variant of concern that further derails progress, but we really don’t know.
I’m sure there are bargains to be had in this sector but this still shows that the potential rewards need to be pretty high to compensate for the elevated level of risk.
Re On The Beach (LON:OTB), but still the same SP that it was at in late summer 2019, even after the fall this morning. Can this really make sense?
What's the significance of late summer 2019 to use it as a comparison to the current share price?
Probably because August 2019 was the end of that summer season for On The Beach (LON:OTB) and the next one was 2020 and covid. A lot of other travel and hospitality shares seem to have priced in a strong recovery and OTB is a good example with the share at the same level as August 2019.
Summer 2019 was the last covid free summer (although On The Beach (LON:OTB) issued a below expectations in August of that year). Then there was a placing in May 2020 - "The Placing of 26,143,500 the Placing Shares, representing approximately 19.9 per cent. of the Company's existing issued share capital, will raise gross proceeds of approximately £67.3 million. The Placing Price is equal to the closing share price of 257.5 pence on 21 May 2020"
FTSE down again today.
Seems like the old adage 'sell in May and go away' is coming true this month.
My portfolio has taken a bit of a battering.
Yes, but I guess the World is going to be battered by waves of bad news and good news as the we come out of the many Covid impacts. I expect a bumpy ride along the way over the next couple of years, but I suspect still overall quite positive.
The thing that has struck me recently is how many companies have used this last year to make really productive improvements in many different ways to their businesses. I think we will continue to see benefits from that for quite a while.
Mark Minervini tweeted on Monday that he’d gone into 100% cash. If you can see past the annoying ego of the man, he does seem to have the knack of knowing exactly when to exit the markets!
Interesting! Thought has actually crossed my mind to dump my whole portfolio in the last 24 hours, take profits and come back in later in year...
That's my fear side taking hold, logically just hold. I need to re read 100 baggers again!!
If it's any consolation, mine too!
Got lucky with banking some profits earlier this week...
Decent update from Brewin Dolphin Holdings (LON:BRW): this morning record discretionary fund inflows, client retention rate increased to 98% so strong recurring revenue model, 5% increase in the dividend
De La Rue (LON:DLAR) Contract Renewal with Microsoft. Not very exciting but FY results due out 26 May.
https://www.londonstockexchang...
My morning smallcap tweet:
Kier (LON:KIE) Empresaria (LON:EMR) Checkit (LON:CKT) Nanoco (LON:NANO) SEEEN (LON:SEEN) Alumasc (LON:ALU) Ideagen (LON:IDEA) De La Rue (LON:DLAR) DX (Group) (LON:DX.) Luceco (LON:LUCE) Eurocell (LON:ECEL) TT electronics (LON:TTG) PHSC (LON:PHSC), One Media IP (LON:OMIP), Best Of The Best (LON:BOTB)
Kier (KIE) huge £241m placing and OO at 85p, a 17p discount, to strengthen the balance sheet. Trading in line. [SP=102.4 Cap=166m]
Empresaria (EMR) AGM stmt: "The Group now expects adjusted profit before tax for both the first half and full year 2021 to be ahead of 2020." [SP=69 Cap=34m]
Checkit (CKT) last 3 months rev up 15%. Recurring rev up 29%. Remains confident. In line? [SP=66.8 Cap=42m]. I hold.
Nanoco (NANO) project extension hikes FY21 revenue guidance by c. 40% with the balance of the project revenue to be earned in Q1 FY22. Extends cash runway to H2 of calendar 2022. Silent on customer and type of work. [SP=27.77 Cap=85m]
SEEEN (SEEN) launches new product, Dialog-To-Clip, for sale to Premiere Pro users on Adobe's app store. [SP=51.22 Cap=26m]
Alumasc (ALU) guides FY ahead of mgmt expectations due to continuing strong sales and improved margin. [SP=217.55 Cap=79m]
Ideagen (IDEA) guides FY(Apr) rev up 16% to £65.6m and adj EBITDA up 24%. In line? [SP=283 Cap=714m]
De La Rue (DLAR) five-year renewal of its contract with Microsoft to provide innovative authentication products. Also wins contracts for digital tax stamp schemes with two Tier 1 countries. In line with mgmt exp. [SP=174.8 Cap=341m]
DX (DX.) guides FY(July) rev £10m above mkt exp. Adj pretax significantly above market expectations. Plans to open 12 depots in next 2 years, above previous plan. [SP=34 Cap=195m]
Luceco (LUCE) guides H1(June) rev c.£105m and adj op profit c. £18m after continuing strong sales - last 4 months rev up 43%. [SP=329.5 Cap=530m]
Eurocell (ECEL) guides FY pretax ahead of market expectations of of £20.5m. [SP=288 Cap=321m]
TT Electronics (TTG) guides FY adj op profit towards the upper end of market expectations of £33.6m to £35.4m. [SP=243 Cap=425m]
PHSC (PHSC) guides FY(Mar) £3.29m and U/L EBITDA c. £0.52m as H2 rev up 39% on H1. In line? [SP=15 Cap=2m]
In line: One Media IP (LON:OMIP) Best Of The Best (LON:BOTB)
Mirriad Advertising (LON:MIRI) – published their FY results yesterday. Headline numbers looked impressive - Revenues +91% £.18m. net cash £35.4m, but the market reaction wasn’t so favourable with the shares falling 10%. Is this a buying opportunity?
If you have any burning questions about the prospects for Mirriads' in video advertising, the recently announced tie up with Pepsi or the current state of the Tencent contract put them to management at todays webinar at 5pm. The CEO and FD will talk through the numbers and prospects for the current year and answers your Q’s
Register here
Paul and Jack,
If you get the chance a view on Elementis (LON:ELM) would be appreciated. I hold. I saw that Rosemary Barnard (not sure of spelling) ex of Schoders and Buffetology funds had rated this as one of the most undervalued stocks in her new fund.
The share has also been subject to a couple of approaches at 130p and 160p, both rebuffed.
The update indicates they are trading above expectations with a good first qtr and good start to second quarter.
They have a bit more debt than i like although they flag they are planning to reduce leverage this year.
Best wishes.
Greyster
Not really small cap. Held this a long time, and still do - up about three times on fifteen years ago. They have always had quite a lot of debt. Price to sales ratio looks good, and will be improved when people start going on holiday again, but I would have thought the balance sheet weak - lot of goodwill.
Small cap Morses Club (LON:MCL) preliminary results out today. Lots of positive Operational Highlights. I dowonder about the Financial Highlights though. Lots of numbers to crunch through here.
I too would love some thought on Morses Club (LON:MCL) - From my initial review - a lack of breakdown between H1 and H2 figures (When H1 is being blamed for the reduction) is frustrating and makes it difficult to understand the trajectory.
I guess that the big issue for the last financial year is that lockdowns have in so many ways restricted expenditure, and hence for Morses Club (LON:MCL) demand. As we come back out of lockdown, the prospect is there for parties, weddings, funerals, holidays and all the other things people, usually, spend money on. Along with all of that, the Government handing our of free money (furlough) will come to an end this autumn.
I note that though they have also felt the effect of claims management companies drumming up business (ie complains) in this sector, Morses Club (LON:MCL) suggest that their liability is comparatively lower (with a £2m allowance for compensation, fees, etc) and that their customer satisfaction ratings are extremely high.
I hold as a potentially strong Covid recovery (ie as demand for credit expands as the economy opens up again), plus the digital transformation into an online bank for people with sub prime credit records and a home collect credit provider that now only occasionally collects from home.
Luceco (LON:LUCE) trading update looks promising.penny for your thoughts please Paul and Jack.im a long term holder