Small Cap Value Report (Thu 14 Dec 2023) - BEG, CPI, STEM, CURY, ENSI, MMAG

Good morning from Paul & Graham!
US interest rates - interesting news overnight, from the US central bank, indicating the likelihood of 3 interest rates cuts (of 0.25% each) in 2024, because inflation is now largely under control, albeit still above the arbitrary 2% target. This helped power the Dow to a new all-time high. It seems like a different world to UK small caps! Although looking at some of the early risers this morning here in the UK, I can see quite a few are interest-rate sensitive, highly geared companies like Mobico (LON:MCG) and S4 Capital (LON:SFOR) - maybe we'll see a dash for trash, as investors worry less about high gearing? Who knows.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries -
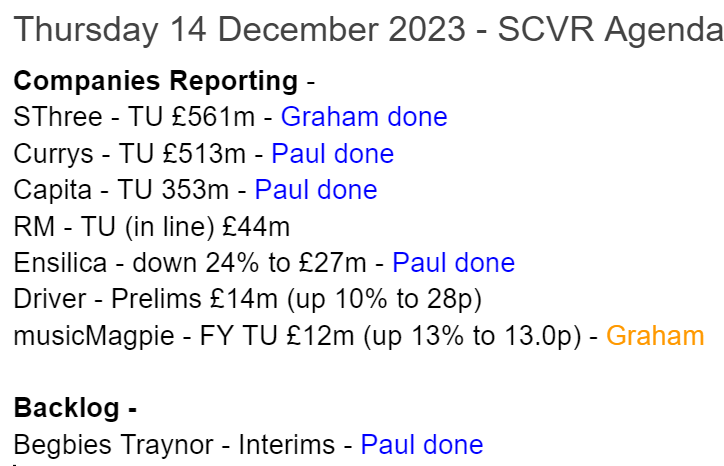
Begbies Traynor (LON:BEG) - up 2% to 115p (£182m) - Interim Results - Paul - AMBER
H1 results from earlier this week. If you accept the large adjustments, then this share looks good value. Nice outlook. Modest but OK balance sheet. The trouble is, I don't properly understand the adjustments, so can't form a firm view on this share.
Capita (LON:CPI) - 20.75p (pre-market) £353m - 11-month Trading Update - Paul - AMBER/GREEN
This update seems to mainly be a recap on previously announced news, and strategy. Shares have been a disaster over the last 10 years, but I wonder if seeds have been sown for a potential recovery, at least in part? Worth a look I think.
SThree (LON:STEM) - up 1% to 422p (£569m) - FY23 Full Year Trading Update - Graham - GREEN
This full-year update is in line with expectations. Fees from Contract recruitment are up slightly while Permanent fees are allowed to keep falling, consistent with their strategic focus. Demand is volatile and 2023 is weaker than 2022, but I remain a fan of this recruiter.
Currys (LON:CURY) - up 11% to 50.2p (£569m) - Interim Results - Paul - AMBER/RED
Another loss-making H1, but it's expected to eke out a small FY profit, with guidance unchanged. The weak balance sheet, and very cash-hungry pension deficit are further reasons to avoid this share. I've moderated my view from red to AMBER/RED, due to the favourable pending disposal of its Greek operation.
EnSilica (LON:ENSI) - down 24% to 35.5p (£27m) - Placing & New business update - Paul - AMBER/RED
My first look at this May 2022 float. Surprisingly, it has done a placing today, following a positive trading update just 2 weeks ago. Dilution is only 5-10% though, depending on whether warrants are exercised. I rummage through past accounts, and am a bit concerned about cash outflows. Doesn't look great at this stage, but it claims to have a massive sales pipeline.
Musicmagpie (LON:MMAG) - up 20% to 13.8p (£15m) - Full Year Pre-Close Trading Update - Graham - RED
The market has treated this update with relief: EBITDA in H2 was significantly higher than H1, and rental subscriber growth was impressive. However the big picture here continues to look ominous for shareholders and I would treat these shares with a great deal of caution.
Paul's Section:
Begbies Traynor (LON:BEG)
115p (£182m) - Interim Results - Paul - AMBER
Begbies Traynor Group plc (the 'company' or the 'group'), the professional services consultancy, today announces its half year results for the six months ended 31 October 2023.
Background - BEG’s core business is an insolvency practitioner - the specialist profession who manage administrations and liquidations. Begbies has made some seemingly good acquisitions over the years. So I have a favourable impression of this group, which still has the owner's eye of Exec Chairman Ric Traynor, with his 17.5% shareholding.
The theory is that this share should be a safe haven in softer economic conditions, but that hasn’t always played out as expected, due to the distortions caused by 14 years of zero interest rates, pandemic policies, etc. With interest rates now much higher, and credit conditions generally being tight (especially for smaller businesses), then I think it’s reasonable to assume BEG should have plenty of work over the next few years.
Despite this favourable backdrop, BEG shares are on a lowish forward PER of 10.6x, which strikes me as having scope to increase - although this share never seems to hold onto any re-ratings, for reasons unknown.
Interim results - for the 6 months to 31 Oct 2023.
The headline reassures -
"Strong first half performance and confidence in full year outlook"
By far the biggest issue with these accounts is getting our heads around the adjustments - which is where most of the profit comes from - I’ve highlighted adj profit, and statutory profit below - bear in mind these numbers are only for a half year - I can’t be the only investor who sometimes forgets that, and works out all the numbers wrong, thinking a half year was a full year! - thankfully I always realise in time before hitting the publish button!
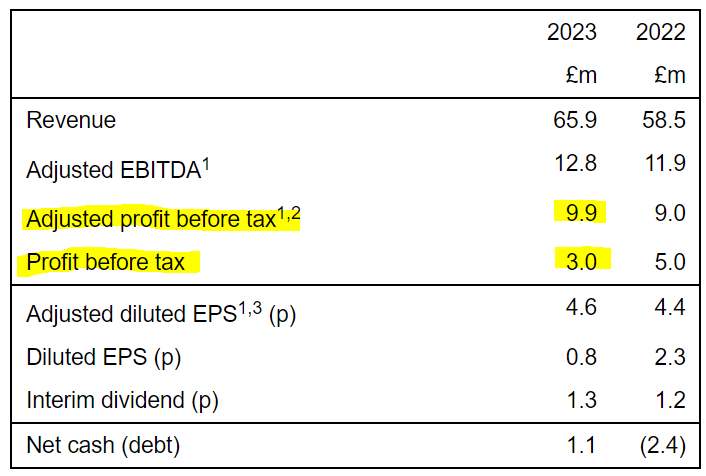
Note that of the 13% revenue growth, an impressive 8% is organic - which should be enough to absorb higher salaries (I’m told that accountancy firms are doing a roaring trade generally, and hence pay is rising strongly).
Acquisitions - “trading well and in line with expectations”.
Outlook - this strikes me as upbeat, considering the modest forward PER -
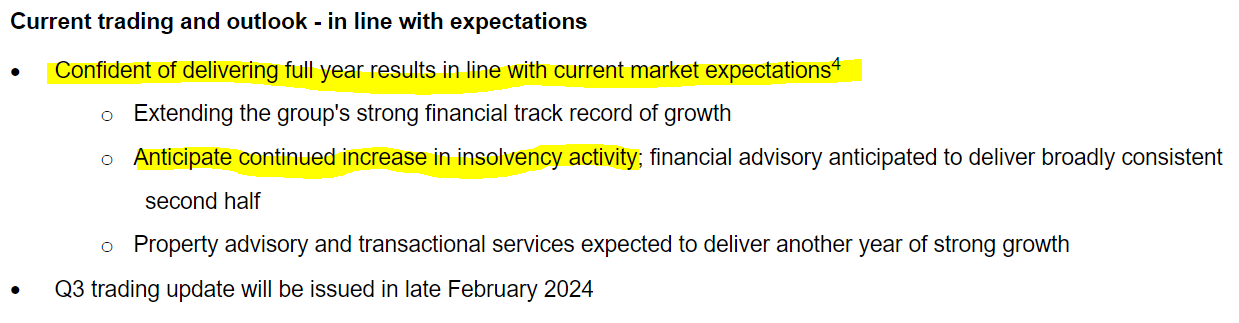
4. Current range of analyst forecasts for adjusted PBT of £21.9m-£22.5m (as compiled by the group)
Balance sheet - there’s little asset backing, so this share is all about profit & cashflows.
NAV is ££80m, with £71m of that being goodwill & similar, so only £9m NTAV. I’ll add back deferred tax (usually relates to goodwill) of £7m, giving adj NTAV of £16m. That’s only 9% of the market cap.
Receivables is the stand-out large number, which is inherent with insolvency practitioners, as they typically run up a fees account, then get paid when assets are disposed of, which can take a long time.
Overall then, I don’t have any balance sheet concerns, but bear in mind there isn’t much asset value to fall back on, if trading were to go badly wrong.
Cashflow statement - oh dear, this is the part where it becomes difficult.
I’m ashamed to admit that I simply don’t understand this accounting treatment, despite having had a zoom with the CFO a while back, where he tried to explain it to both Graham & I -
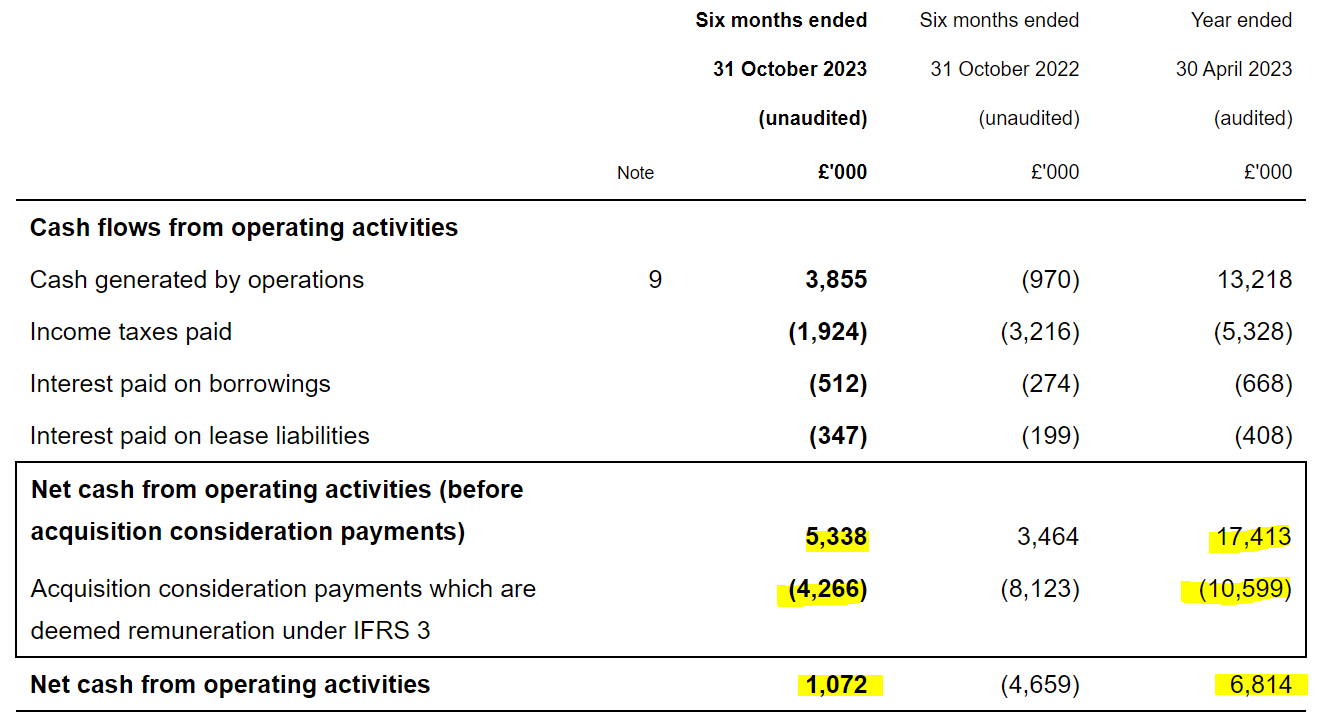
This same issue is the main area of adjustment in the P&L, as note 3 details -
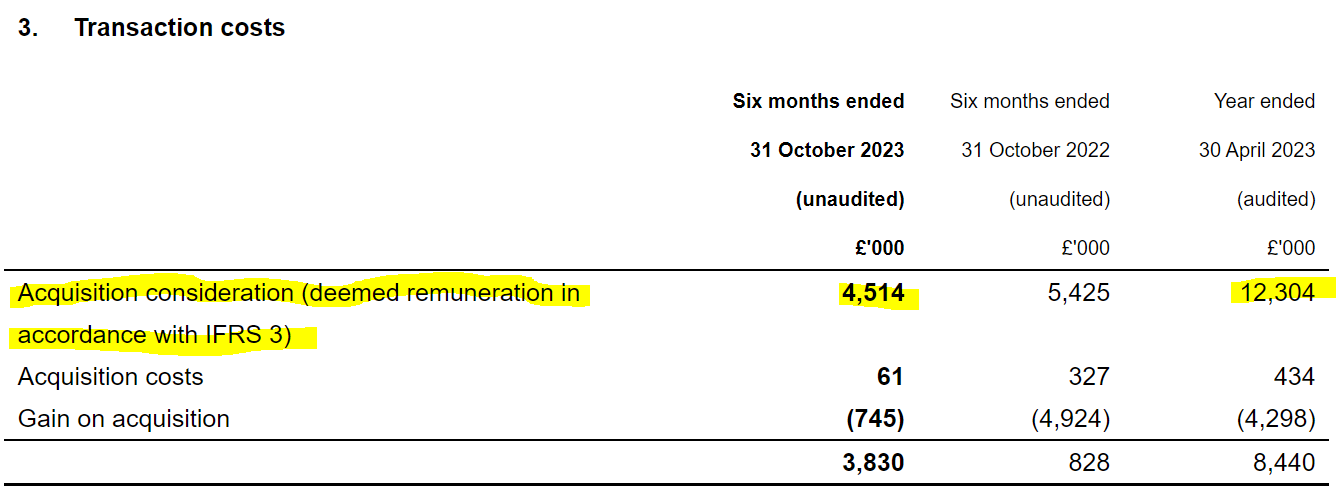
So what is the real profit and cashflow? I don’t know, it’s completely confused me.
Paul’s opinion - given that I spent 3 years training as an auditor with Price Waterhouse, and then 8 years as a CFO, I can usually breeze through almost any small-mid cap accounts in a few minutes and understand them, despite all that being 20-30 years ago now. So we might have to allow for a bit of age-related brain fog, and advances in accounting standards, where I barely know my IFRS from my elbow these days!
To be fair, it’s not just me who is confused by the adjustments in BEG accounts. Graham and I had zoom with the CFO, and were nodding along sagely, but afterwards I asked him - did you understand any of that?! I think we agreed that we thought we sort of understood it at the time, but cannot now give a coherent explanation. So that means no, we didn’t understand it.
The CFO did say that he’d had so many identical enquiries from fund managers, that he had prepared a slide deck to explain it. Maybe he needs some new, simpler slides?!
Part of me says just accept the adjustments, and value the shares on the adjusted numbers. In which case, BEG shares look attractively priced, particularly given the positive outlook for its core insolvency division.
However, given that I don’t really understand the adjustments, and they’re so material to profits, then I can’t go above AMBER again, which is Graham’s previous view too.
Capita (LON:CPI)
20.75p (pre-market) £353m - 11-month Trading Update - Paul - AMBER/GREEN
I’m not sure why this large outsourcing group has issued another trading update since its last, in line with expectations update, which I reviewed here on 21 Nov 2023?
Today’s update doesn’t tell us how the group is trading versus expectations, but is more a summary of things they’ve already told us.
Here are the most important points -
“Positive operational performance across both divisions”
(but nothing said about profitability, just a slight increase in revenues of 2.1%, less than inflation. There’s a slowdown in growth from H1 to H2 2023)
Increase in contract wins.
Cost savings (mostly people) of £60m from Q1 2024 - as announced on 21 Nov 2023.
Medium term target to “more than double” operating profit margin from 2.9% (implies 6%+ which would be a great catalyst for a share price rise, if it can be achieved).
Disposals almost complete.
Main pension scheme in actuarial surplus of £53m at Mar 2023. £30m paid in 2023. £21m payable in 2024. After 2024, no further cash required by the pension scheme - this sounds excellent, and obviously is a major benefit to cashflow from 2025 onwards. Assuming nothing goes wrong with the subsequent scheme valuations.
Negative overall cashflow expected to reverse in future years.
Broker updates - we don’t have access to anything, so we’re at a disadvantage here. So we have to fall back on the broker consensus graph on the StockReport here - which doesn’t seem to show much enthusiasm for the turnaround from 5 analysts - are they lagging behind reality, or is the company over-PR-ing its trading updates, I wonder? -
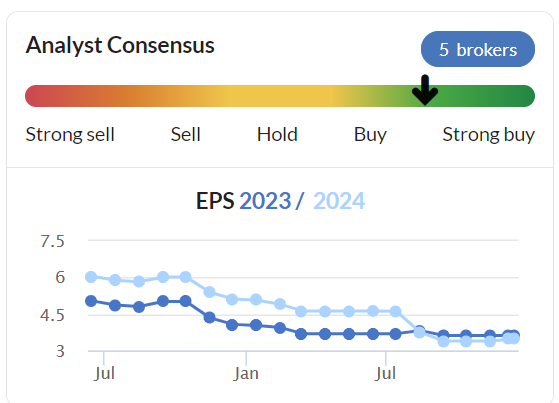
Paul’s opinion - there seems to be plenty of potential here for a turnaround, and the share price looks as if it might be finding a floor.
The key with this type of business is only taking on work where it can generate a decent return. Instead CPI seems to have got embroiled in problematic contracts in the past, and who knows whether its extensive disposals have sold off the best stuff or not?
I dislike the balance sheet, but it’s a lot better than it was.
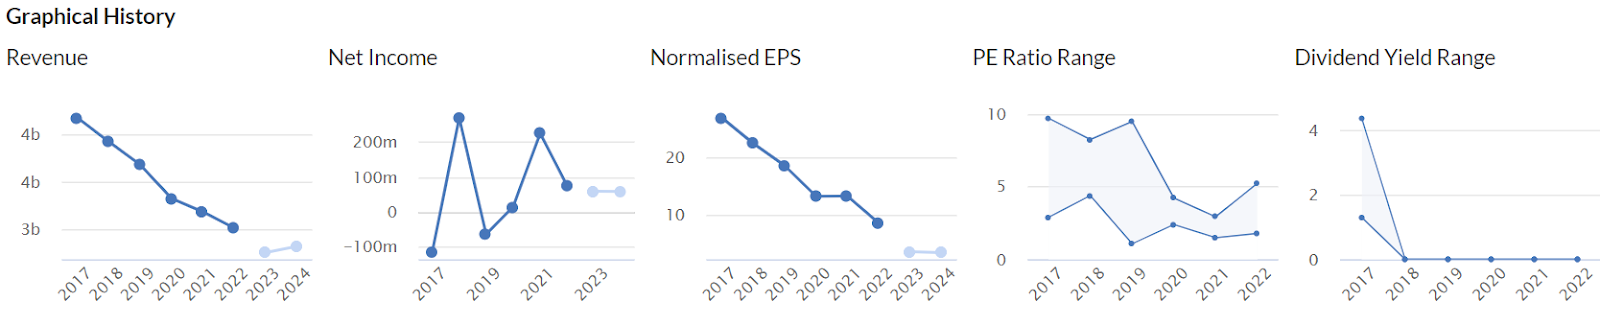
As you can see below, a horrible trend in EPS has driven the share price collapse in recent years -
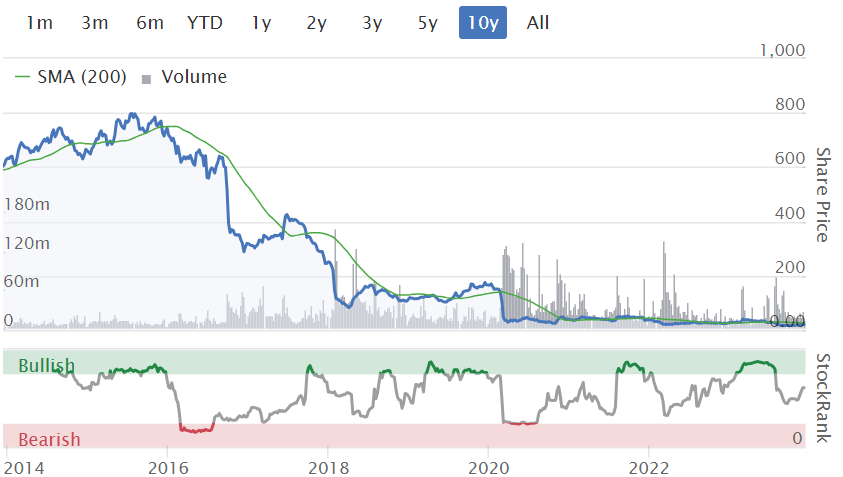
Staggering shareholder value destruction here over 10 years -
We're buying the future, not the past. So as a potential turnaround, I particularly like the ending of substantial pension scheme deficit recovery payments in 2024. That. combined with deep cost cutting, and a target to get the operating margin up from 3% to 6%, could (if it happens) fuel a rebound in share price maybe?
Overall then, not the type of business I would want to invest in, but as a trade for a partial recovery in share price, it’s looking tempting. So I’ll stick at AMBER/GREEN - mildly positive, but with some reservations.
Currys (LON:CURY)
Up 11% to 50.2p (£569m) - Interim Results - Paul - AMBER/RED
Currys actually uses the RNS title - “Solid performance in a tough environment” - instead of the more usual “Interim Results”, so I’ve changed it above to be more accurate.
As well as the heavily PR-d title, I think we also need to be cautious about share price movements on a big up day - small caps are up 2%, and mid caps 3%, on the back of the more dovish Fed stance re 2024. Hence big moves today might be somewhat exaggerated maybe, and may not stick?
I won’t spend much time on going through the figures, as they’re lacklustre - eg -
H1 revenue £4.16bn (down 7%)
Ignore EBITDA, as it excludes a huge amount of rent costs.
Loss before tax £(46)m, H1 LY was £(548)m but that included a £511m goodwill write-off, so a £(37)m loss H1 LY.
Adj loss before tax was £(16)m.
There’s an H2 bias to trading, I recall.
Disposal of Greek subsidiary happened post H1 period end, this does indeed look a good price achieved, and should help strengthen the group balance sheet -
After period closed, agreed sale of Greece for an enterprise value of £175m and net proceeds of £156m, representing an attractive return for shareholders. Greece will be included in continuing operations until transaction completes
Outlook - sounds OK -
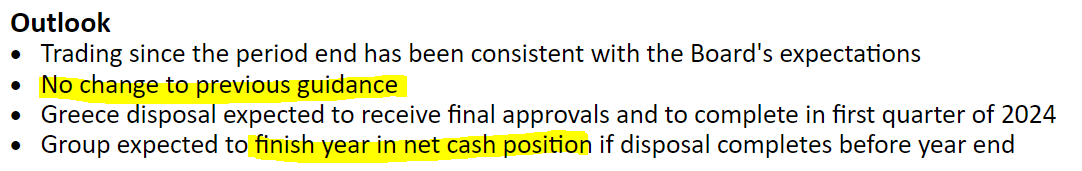
Balance sheet - is very weak still. NAV of £1,886m includes £2,569m of intangible assets, so NTAV is negative £(683)m. The main elements of this hole in the balance sheet are caused by £190m pension deficit, £230m deficit on the lease entries, and £129m of net borrowings. I suppose you could argue that these should be manageable things, and with the net borrowings about to be fully repaid by the Greek disposal, maybe I’ve been overly gloomy about this balance sheet in the past?
My main worry is still that the £2.52bn owed to trade creditors is gigantic, and could be dependent at least in part on trade credit insurance, which can be withdrawn at any time without notice.
However, there is £2.28bn of inventories + receivables, which supports most of the trade creditors.
So providing this state can be maintained indefinitely, then it might be just about OK?
Pension deficit - is a massive cash drain for the next few years -
Scheduled pension contributions will rise to £50m in 2024/25 and to £78m for the following three years before a final payment of £43m in 2028/29
Paul’s opinion - I think the pension deficit recovery payments are a deal-breaker for me. I was just starting to get a little more comfortable with the balance sheet until I came across the size of the pension deficit cash demands.
So as things stand, this business is operating to fuel the pension scheme. I see that brokers are forecasting a reintroduction of dividends, but that’s not sensible given its weak balance sheet.
Upside could come from a surge in consumer spending in 2024 and beyond, which is not as daft as it sounds, given that wages (and benefits/pensions) are set to rise way ahead of inflation from April 2024, plus the 2% NICs cut should kick in from Jan 2024, offsetting some of the stealth tax rises (such as frozen personal allowances). On c.£9bn revenues, and trading a little above breakeven currently, Currys could see a strong % increase in profits from such a low base. Offsetting that, will be a big increase in its own staff costs from April 2024, as everyone seeks to maintain their differentials above minimum wage. Lots to ponder there!
On balance, I think the Greek disposal reduces risk, so I’ll shift from red to AMBER/RED, to reflect that this really isn’t a very good business, operating on wafer-thin profit margins, with substantial fixed costs, totally dependent on trade creditors, and with a cash-hungry pension scheme. So why get involved?
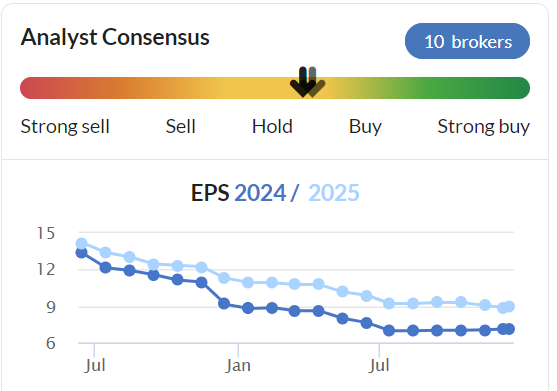
Also despite the best efforts of the PR team, reality is that broker forecasts are still in a downtrend -
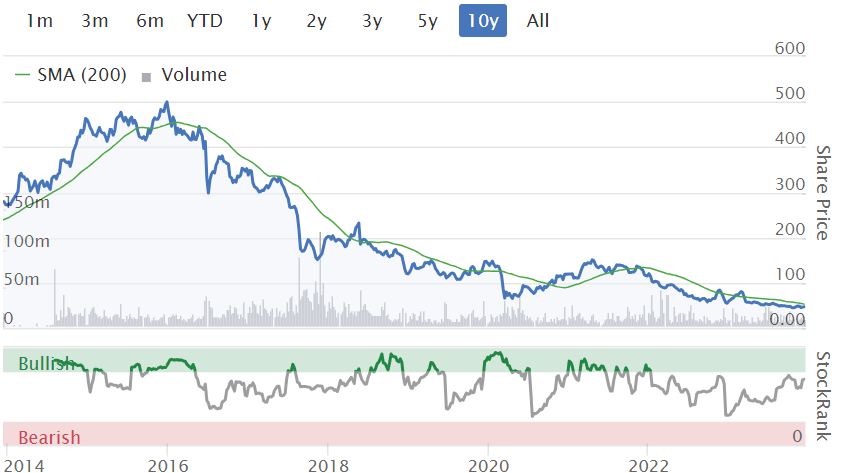
Long-term, this is a story of shareholder value destruction, which began long before the pandemic hit us.
Although note the share count hasn't risen significantly in the last 5 years, so theoretically that suggests upside could be considerable, if trading were to substantially improve -
EnSilica (LON:ENSI)
Down 24% to 35.5p (£27m) - Placing & New business update - Paul - AMBER/RED
This is our first look at Ensilica. It listed in May 2022, had a honeymoon period where it doubled, but has since come crashing down to a new low today.
EnSilica, a leading chip maker of mixed signal ASICs (Application Specific Integrated Circuits)...
Today announces it’s raising £1.56m in a 40p placing being done by Allenby.
Warrants are attached on a 1 for 1 basis, with an exercise price of 55p and a period of 18 months.
These are quite small numbers, so it’s about 3.9m new placing shares, plus 3.9m potential new shares from warrants (which would bring in £2.15m of fresh cash). Total dilution therefore up to 7.8m new shares, compared with 78.1m existing shares = 5% + 5% dilution, which isn’t a disaster by any means.
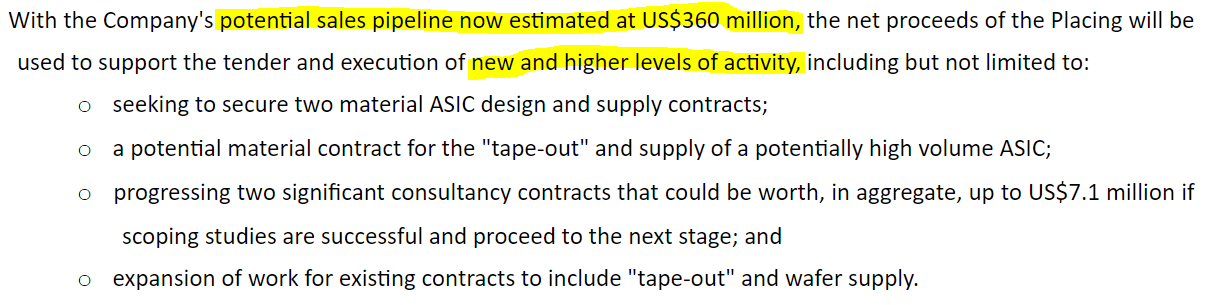
What’s the money for? There’s a nice story here -
It’s surprising that Ensilica has raised more money today, as just 2 weeks ago it issued an upbeat-sounding, in line with expectations trading update, that didn’t give an inkling that it needed more cash.
I’ve quickly reviewed its May 2023 accounts, with the cashflow statement being the most revealing - all its cashflow in both 5/2023 and 5/2022 came from tax credits. It then capitalised heavy development spending, having to plug the resulting cash shortfall with equity raises in both years. This year seems to be following a similar pattern.
Paul’s opinion - it’s never a good look for a fairly recent float to come back for more cash, especially when the share price is depressed. That said, the 5-10% dilution from today’s raise is not the end of the world.
From all the numbers to date, I’d say the jury is out on whether this is a decent business or not, it just hasn’t got enough of a financial track record for me to judge.
It would be useful to check out management - are they any good, what have they achieved in the past, etc?
The shareholder list is nearly all individuals (management maybe?), with Amati Global Investors holding 6.4% - they seem to crop up at a lot of more speculative micro caps that have been hammered in price over the last 2 years.
Anyway, we can keep an open mind about Ensilica - if a decent amount of the huge pipeline turns into sales & profits, then it could do well, who knows?
For now, I see it as AMBER/RED - so no strong opinion either way, but nothing much to convince me there’s a good business here based on its record to date.
Graham’s Section:
SThree (LON:STEM)
Share price: 422p (+1%)
Market cap: £569m
SThree plc ("SThree" or the "Group"), the only global specialist talent partner focused on roles in Science, Technology, Engineering and Mathematics ('STEM'), today issues a trading update for the financial year ended 30 November 2023.
This is my favourite recruitment sector stock, and I always look forward to its updates. Today’s update is in line with expectations.
Key points:
Net fees down 4% “against a record prior year performance and challenging global macroeconomic backdrop”.
Contract fees up 1% and now 82% of total.
Permanent fees down 22% and now 18% of total.
SThree has been shifting its business away from Permanent hiring and into Contract hiring for years, and the declining fees from Permanent recruitment have been a drag on total growth.
Average headcount in Permanent recruitment is down 17% year-on-year, so we should see reduced costs offsetting most of the reduced revenues.
Sectors: the Covid-boom in Life Sciences continues to retreat and Life Sciences fees are down 21% year-on-year. In contrast, Engineering is up 17%.
Order book is £184m, down 3%, but SThree argues that this is “sector-leading visibility with the equivalent of c. 4 months’ net fees”.
Net cash of £83m.
CEO comment: describes this as a “consistently robust performance”.
As we enter the start of the new financial year, we haven't yet seen an easing of the macro-economic environment, which continues to drive soft trading conditions. Our strategic focus, exposure to long-term megatrends, and progress to date delivering operational enhancements provide us with a strong platform for sustained growth. We remain excited by the opportunities ahead.
Graham’s view
In September, commenting on the Q3 update, I gave SThree credit for tightly managing its costs in a year with lower demand than the boom conditions of previous years.
I also pointed to the long-term trajectory of revenues, which remains encouraging despite the current hiccup:
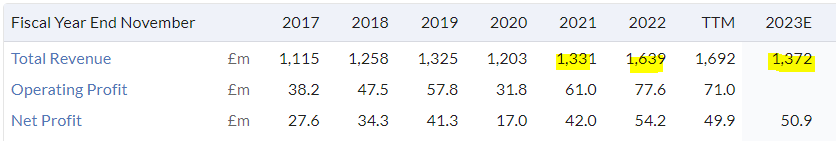
Today’s full-year update confirms that Contract fees are approximately flat - as this is now effectively the company’s “core” activity, I think investors should be focusing on this now, rather than the aggregate revenue performance.
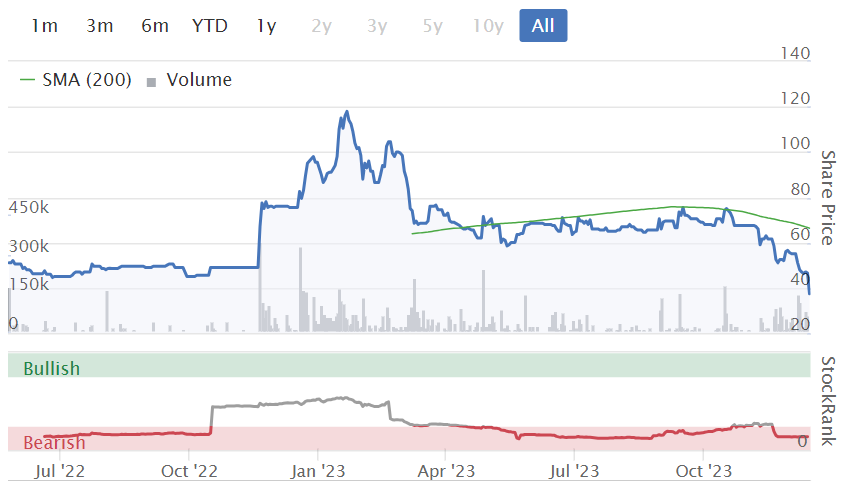
The company’s cash balance keeps rising (note that there is a 4% dividend yield here, too) and the share enjoys a StockRank of 98, also passing three bullish stock screens, including the Ben Graham Deep Value Checklist.
If I wanted to build a bear case here, I would start by pointing to the lack of recent top-line growth and the competitive nature of the recruitment sector. However, I’ve been following SThree for quite some time and have been consistently impressed by the quality of its results, which suggest to me that it’s a leader in the space. The focus on contract recruitment in STEM fields seems to be a winning strategy, and the cash balance provides comfort.
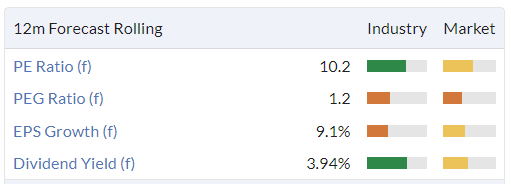
So I’m keeping my positive stance on these shares, as I struggle to find reasons to think that this valuation is overcooked:
Musicmagpie (LON:MMAG)
Share price: 13.8p (+20%)
Market cap: £15m
Takeover possibilities are in the air here, although potential bidders Aurelius and BT have said they do not intend to make an offer for this reseller of refurbished phones, tables, games consoles, and laptops, and second-hand films, books, and box-sets.
The company said on 27th November that it “continues to seek potential buyers”.
Let’s see if today’s full-year trading update (for FY November 2023) offers any light at the end of the tunnel:
Revenues £136.6m (2022: £143.3m)
Gross margin 27.7% (2022: 26.2%) was prioritised over revenue growth.
EBITDA £7.5m (2022: £6.5m)
At the interim results, adjusted EBITDA of £2.8m translated to a pre-tax loss of £3.2m, so I would assume there will be a full-year statutory loss.
Active rental subscribers are up 21% to 37,100 year-on-year, and rental revenues are up 57% to £8.3m. But this is just a fraction of MMAG’s total revenue base.
Estimates: there is no reference in today’s announcement to performance versus prior market expectations. Broker Shore Capital has withdrawn its forecasts, due to the company being in an offer period.
Previously (in August) it forecast revenues for this year of £140.6m, and an adjusted pre-tax loss of £2.2m
Net debt has reduced by £0.5m over the past six months to £13.1m.
Since the net debt position is nearly the same size as the company’s market cap, let’s focus on it for a moment:
Leverage at 30 November 2023, being EBITDA to net debt, was 1.7x (31 May 2023: 2.0x). Net debt is mitigated by future contracted rental revenue of £3.6m and Rental assets on the balance sheet with a net book value of £7.7m. It also continues to be supported by the £30m committed RCF facility provided by HSBC and Natwest, due for renewal in July 2026.
So let’s make a few points on this.
Firstly, the leverage multiple of 1.7x would usually be considered moderate. However, for a company that struggles to turn a profit, we need stricter criteria and so I do not consider this to be a comfortable position.
The company points to rental assets on its balance sheet of £7.7m. In isolation, that’s a reasonable argument but look at the entire balance sheet and it’s less reassuring: as of May 2023, the company had tangible net assets of only £3m. So it could not sell its rental assets to balance out its debt position. Firstly, because the rental assets are only £7.7m and the net debt is £13.1m. Secondly, because it’s very close to having negative tangible book value. So liquidation would be a risky strategy.
CEO comment:
We are pleased with the performance of the Group in the second half of the year, and are delighted that our focus on profits and cash has delivered significant EBITDA growth. Our strategy of proactively managing the number of active Rental subscribers has also helped in this regard and will support our short-term objectives on profits and cash into 2024, bolstered by an enhanced Buy Now Pay Later offering. I remain confident in the business and our ability to navigate the difficult external market conditions, especially given the outstanding level of trust that consumers continue to have in our brand, as demonstrated by our excellent 4.4* Trustpilot rating based on over 277,000 reviews.
Graham’s view
Share price gains today suggest that shareholders are pleasantly surprised with the update: H2 EBITDA is up significantly vs. H1 EBITDA.
However, I’m going to continue the negative stance on this one that Paul has suggested in his recent coverage. Reasons for this include:
Lack of profitability.
The combination of unprofitability and financial leverage.
No real balance sheet support.
The attempted sale of the company - is this a search for a bailout?
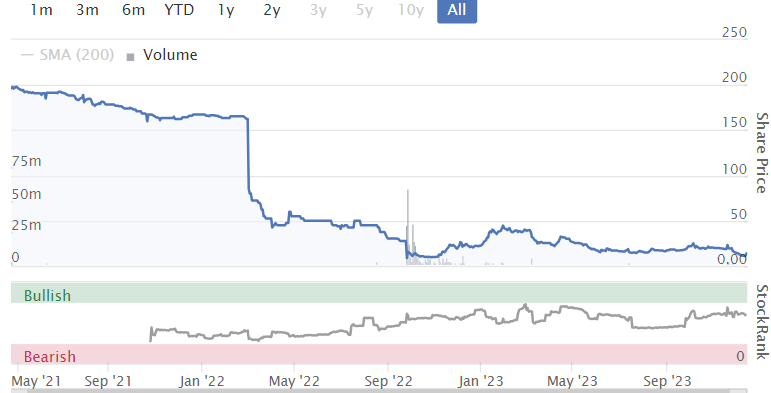
Looking at the historic financials, I see that the company was briefly profitable in 2020, just prior to the 2021 IPO. It’s difficult to blame investors for being wary of any fresh IPOs, given what they’ve experienced over the past two years with all of these 2021 IPOs:
Of course you can never tell what will happen in an attempted sale, and perhaps Music Magpie will find the buyer it is looking for, at a premium to the current share price.
Price to sales is only about 0.1x. If somebody thinks that this can be turned into a sustainable business, who knows what they might be willing to pay for it? But another strategy for possible buyers might be to let the company continue on its current course, and hope to start discussions with the bank at a later date.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
SThree (LON:STEM) Graham thanks for your comments on the FY23 TU . Here is their analysts' meeting recording video & podcast. Main points:
Nibbling at MPAC (LON:MPAC) today. FY24 forecast at 39p EPS with net cash position so 220p feels anomalous particularly if interest rates are moving down. New CEO and old CFO both bought some though very small to be fair so not sure I will be reading too much into that.
Has been hanging around 210-220p level for a while so I am hoping it’s formed a base and a bowl, staying above 50MA. This was a top up today for me.
Re Begbies Traynor (LON:BEG) they are doing an investor meet company presentation next week so I am going to ask them about what they exactly mean on deemed remuneration as I have not been clear on this for some time. I hope it is simply performance-related payout acquisition costs.
Brickability (LON:BRCK)
Further to my earlier post I have added to my holding at a little over 50p. To do so I trimmed my holding in Howden Joinery (LON:HWDN) at a moderate profit, an excellent company where I still retain a reasonable position but felt that the value on offer at Brickability (LON:BRCK) was too difficult to ignore and where I consider the potential for a re-rating as interest rates fall is much greater.
As Andy Brough has often said shares are for buying and selling. Hopefully this sell and buy will go to plan over the next 12 months. Fingers crossed!
Agree with you on Brickability (LON:BRCK) looks very good value and long term prospects should be good. You seem to have also sparked a bit of interest in the stock - I see it features number 2 on the most viewed in Stockopedia and perhaps even helped finally push the share price a bit!
Brickability (LON:BRCK) has popped up in the multi bagger chat too, so it’s on the radar.
(I hold)
Hi Bouden54
Brickability (LON:BRCK) Hopefully my reading of the runes is correct. I believe that they are, but ultimately each individual has to take responsibility for his or her investment decisions. I think that we will have to wait a little for a more benign announcement on interest rates before the share price starts to move more decisively. Although Andrew Bailey and his colleagues at the Bank of England don't exactly fill me with confidence.
Impellam (LON:IPEL) Another one gone.Aim listed too.Tory peer Lord Ashcroft will be taking home circa £300 million from the sale.In the recruiting business like SThree (LON:STEM),although i'd never really looked at them.They're being taken out for for a pretty decent premium, especially compared to their valuation 3-6 months pre-covid.
EnSilica (LON:ENSI)
That placing is a shocker, trash the share price for £1.5m and put a lid on the share price for next two years by having to hand out warrants like confetti. Nothing says “keeping the lights on”louder than that to me. Feels like the company left it way too late to raise working capital when it must have been obvious the company needed it months ago. The FD must have been asleep at the wheel, but so must the other directors… feel sorry for holders, this looked a really exciting uk technology company. Fingers crossed that’s enough money and it survives (but I struggle to believe £1.5m is enough if they had to issue in this market, at this time and with those warrants…!).
EnSilica (LON:ENSI)
The FD ain't at the wheel - the CFO resigned on 11 April, a temporary CFO appointed, and there's no RNS announcing a new appointment - 8 months on. Their website has a awful lot of non Board Directors of technical areas but none of the 18 person Directors / Leadership team is said to be looking after finance.......
The Exec Chairman, Mark Hodgkins, was the FD at Trackwise - who had the opportunity to raise a serious buffer when the shares shot up to 300p+ on the back of optimism over their contract with Arrival. But they didn't - and subsequently ran out of cash. To be fair to MH, I believe the CEO's reluctance to be diluted was the driver - but MH had a ringside learning opportunity.......
Are there any holders of Northern Bear (LON:NTBR) here still?
Following the completion of the tender offer (to let the departing Chairman exit his position) over 30% of the shares are now held in treasury. Is there any indication what the company intends to do with these? Why haven''t they just cancelled them?
NTBR looks very cheap, unless the very high number of treasury shares is likely to be a problem.
Northern Bear (LON:NTBR)
still here for the long haul ,
Is there any indication what the company intends to do with these? Why haven''t they just cancelled them?
I wouldnt presume they would need to be cancelled in any hurry that being the case i would read zilch into the fact they havent been cancelled at present. I think they would look pretty silly if they dished those shares out (other than what they would have done in normal course of business anyway - one benfit of having shares in treasury) or sold them at anything below the 62p buyback value - so i would say doing nowt or cancellation is still the most likely scenario unless they have someone/something turning up who wants to pay above 62p. There is an element of trust here i must admit - this board have been very straight laced over the years though. I think the main "excuse" to go down this route was so as not to create an overhang in share price if Jeff would have exited anyway - overall the result has pretty much acheived , with other shareholders benefitting from then uplift in shareprice since the buyback news. Wish i had had the kahunas to top up here when it dipped to the 40p level - but i had bought twice previosly here and its not a company i would want to go overweight in (plus i had no spare cash).
good news for holders who are left is that £2 mill pa profits turns into eps of 14.5p - so with pe of under 4.2 there looks scope for further gains if they can keep churning out £2 mil pa + clean profits. I would say the balance sheet is more stretched than it was and it has always been a slightly sketchy balance sheet anyway - albeit over the years its become less sketchy than it used to be. Note i would say when i say sketchy it looks fine from cashflow + net debt situation - what always worried me was the size of the receivables + payables , although more than 100% matched (receivables > payables) and they have plenty of customers they are probably slightly more vulnerable to bad debt than some with so much being owed in.
Heyho still a solid company overall - ignoring intangible w/offs i think this company has returned profit every year since 2008 - no mean feet with the industry they work in and having had covid come along and supply chain issues!
Also, the option for management to use the treasury shares to fund acquisitions with no additional borrowing costs for the share element.
Two comments on SThree (LON:STEM), one on competition the other investor hygiene.
Competition. Pagegroup (LON:PAGE) has identified technology as a target area. If AI reduces the number of clerical positions, I'd expect more recruiters to reallocate resources into STEM roles. How will STEM do against intensified competition?
Investor hygiene. Their TUs say that there's a call for "investors". I tried to join the Q2 call and was told it was for institutions only. It's STEM's call: if they'd like to limit to institutional investors, that's their prerogative, but IMO they should be transparent and say so on the face of the RNS. From my perspective, excluding private investors from the Q&A (the presentation itself is on PI World) creates an asymmetry of information and is a factor (not decisive) against investing as I'm not keen on buying from someone who's selling with better information given out by the company.
SThree (LON:STEM)
Competition. Pagegroup (LON:PAGE) has identified technology as a target area. If AI reduces the number of clerical positions, I'd expect more recruiters to reallocate resources into STEM roles. How will STEM do against intensified competition?
Not something I would give a moment’s worry to. Often as a result of the listed names’ publicity, outsiders labour under the mistaken impression that they form a big part of the market. Claiming to be a major force in tech hiring, STEM is not even 1% of the market for tech! The sector is absolutely jam-packed with smaller but better focused, better incentivised rivals, many of whom deliver far superior margins and profitability. It’s the listed names that are the plodding performers sustained only by scale and branding. The threat of Page doing more tech recruitment is tame - Page has been trying to crack tech since the last century. Meanwhile, barriers to entry for new participants are extremely high - tech recruitment is hard!
I’d be more concerned about changes to employment patterns in the technology field, resulting from the replacement of programming effort with artificial intelligence. Changes that might cause the company to alter its targeting of roles.
For the time being, I’m content that AI disruption will only cause a shift into adjacent skill areas and, for all that I’m being scornful of STEM’s boasts, it’s a decent and well positioned company and I own a good sized position.
The story I hear is that business for recruiters generally is dropping vertically at the moment. I believe SThree (LON:STEM) with its contract focus is better positioned than most, but I would still be avoiding the sector as a whole. No position.
The story I hear is that business for recruiters generally is dropping vertically at the moment.
Yes, perm is in deep doldrums, I could be wrong but I'm reminded of that saying of Warren B's. Note that recruiters are already 25% off the lows of the year. It could be bear rally of course. But market participants are asking the question.
MS International
Proper battle going on trading this in past day with all gains given up despite the great update
Seems to be have been a big seller taking price briefly back to 860-870 , at one point could buy 70k which is very high for MS I .
Bought chunks at 862, 877, 878
Stock now seems to have all gone apart from few hundred shares
Tight spread
Should have really committed , sometimes when you get moments of high liquidity and tight spreads in these thinly traded companies you have to make the move to get to a decent holding .
Very interesting trying to time an entry point pre and post news in this unusual market we have right now
I agree Planetx - that’s good insight re selling pressure as I wondered why MS International (LON:MSI) was struggling given the stomping results out and forward outlook. Well undervalued compared to peers though it may always trade at a discount given the conglomerate nature of the business, which hasn’t been in favour since the 1980’s !!
I’m happy to be patient but given UK 10Y is now almost back to 3.6%, the US has gone under 4% and mortgage rates are being persistently brought down, helping the housing market and associated trade, I suspect there will be a demand rush for interest rate sensitive stocks which may hold back value such as this.
I own the stock from below 200p but am kicking myself for not buying more on the way up. I need to get better at averaging up is my lesson!!
DAVID
Not sure if you do this but once you have a reasonable holding I always check
- price I can sell at and qty I can sell
- price I can buy at and qty I can buy
This will give an indication of the appetite / need of the market to buy or sell shares and the likely short term direction.
When buyers are exhausted and lots of stocks still available its heading lower .
When sellers are exhausted, and no stock available to buy its heading higher.
To do this effectively you have to have a decent holding ,.
Most mornings over a cup of coffee Ill dummy buy and dummy sell 20k each of my holdings to test the liquidity and get the likely direction of play.
I did this with Crestchic when a persistent seller took the price from 200-210 touching down to 170 level, lots of stock available at 170 so I put on my big boy shoes and cleared that overhang which promptly spiked the price to 210 as theres was no stock and the market was caught understocked.
At the moment its very easy to spike the prices in microcaps , last week I cleared the stock on Transense and it shot from 99p to 110 in a few days before settling back at 103./4.
Funny really I could have sold the holding for 106 2 days after buying for 99 which would have pushed the price down again and repeat ,
Market is really not functioning at all , though generally the large spreads rule out any chance of playing this game successfully.
Missed the chance on MS International this morning as couldn't find the big boy shoes in time .
Hi PlanetX,
I might be getting incorrect information from them, but if you use the IG platform you can put in dummy buy and sells at almost any value, regardless of the size of your holding at the time.
This is an example of a dummy buy for Zotefoams (LON:ZTF) , far below my actual holding which is only about 5% of what I have inputted. It works for sells beyond current holding as well.
As I say, I am not sure as to the accuracy, but thought I would flag it!
You can put in a sell on shares, you don't even hold, sometimes there is a message about shorting. Quotes don't always go through though, if price changes, in the seconds after the quote.
planetx - Why don't you use level 2?
Interesting RNS from Zanaga Iron Ore (LON:ZIOC) today, appointing its first CEO, an industry 'heavyweight' for a £ 50m cap mini resource co.
This step and the recent corporate restructuring with major shareholder Glencore (LON:GLEN) suggests that things may finally be moving on this major 'green iron' ore resource in Congo-Brazzaville.
'When the causes and conditions are right..."
I hold.
Serco (LON:SRP) up 5.54% at time of writing on news of improved financials and an acquisition.
Edit: I hold
Brickability (LON:BRCK)
Researched this after it was referred to by Paul Jourdan in his recent Vox market interview with Paul Hill. Watched the presentation of the recent interims on investor meet company and went through the accounts.
Whichever way I look at it, it just seems too cheap and that is despite the fact that UK small caps are cheap across the the board. It operates a capex light model and unless one thinks that the housing market is never going to recover the shares appear to be a steal.
I naively thought that the company's product range was confined to bricks but this is far from the truth. With the recent acquisition of Topek, a cladding specialist to add to the other two cladding businesses within the group, roughly 50% of revenue is now derived from bricks, down from 80% at the time of listing. After the terrible disaster that was Grenfell there will be a long term demand for cladding remediation works.
Brickability (LON:BRCK) operates 4 divisions:
The acquisition of Topek is forecast to offset the current revenue decline in bricks and building products going forward. The current and forward PE is around 5 for earnings of around 9.5p/10p. The dividend was increased at the interims to give a yield close to 7%. Management have plenty of skin in the game and as far as I can see the balance sheet is in decent shape and to cap it all the shares trade at less than book value. Seems like a no brainer. There is a broker note freely available from Finncap or Cavendish as they are now known.
What could go wrong? Two obvious potential banana skins, although there are no doubt more that don't come to mind as I write
I have bought a starter position in one of the family portfolios and would have bought more but am currently fully invested.
I could could go. These are just my views and will leave others to make their minds up.
All the best.
Nice note here Jonno, I bought in recently based on sheer valuation and also the fact I believe that the market is now being too pessimistic on construction overall. The share price has chance to double and even then could be viewed as too cheap. Chance to be buying here in a more difficult macro picture and once that eases (2024? once BoE reduces rates…) share price IMO will re-rate before the construction market has actually returned to a more normalised environment.
I’m currently reviewing all construction related businesses and looking at putting my money in shares that have the potential to re-rate the most.
I've been invested in the brick manufacturers in the past & keep an eye on the sector with a view to buying back in.
I have to say the recent Berkeley group (LON:BKG) results concerned me a little. Whilst I suspect they were playing to the gallery to make a political point, they pretty much threatened not to commence any further major schemes:
"it has become increasingly difficult to progress this form of development as changes to planning, tax and regulatory regimes have created an increasingly uncertain, unpredictable and burdensome environment. This is driving investment away from urban areas"
New builds aren't just about developer supply and buyer demand - councils seeking to grab a chunk of the planning gain and demanding more affordable housing can stop the market from functioning at all.
SThree (LON:STEM)
I am not particulary fan of recruitment groups after a sour experience with staffline (very poor management) and other flakey companies in the secttor have tended to have poor balance sheets.
I do hold some SThree (LON:STEM) though haveing picked up in the last 18 months or so. My experience so far is they they seem a very reliable plodder. They seem incredibly on then ball about the detail of their business and the balance sheet here seems incredibly robust for a firm in their sector. I would say trading isnt brilliant at the moment - even if the next 12 months forecasts are missed by 10% then they would probably still only be on p/e of under 12 or so per stock current pe is a tad over 10.
Companies in this sector tend not to comand a premium to the market ref pe - infact probably exactly the opposite. I dont think i would be adding to my holding right now (shares have appreciated 25% since i bought) outlook isnt exactly briliant but i am more and happy to keep holding this one as management seem to be doing very decent job.
Despite the outlook not being brilliant stocky expects decnt increase in EPS and net profit for new year (before update today) - no idea how todays update may have changed things. They say performance inlione but comments mentiong things being subdued so i kinda expect there could be downgrades perhaps by brokers or the reality that times are toughish.
Comptoir .
Quite interested here as I do like a good kebab .
Freed up a bit of cash a week ago just to start a few more positions, probably boredom as much as anything .
Anyway Comptoir looked a fun albeit micro cap value trap with a delist risk net .
But on the plus loads of cash and a CEO who looks good and sone smart new shareholder who is ex Rockwood Lawrence Hulse trying to prove himself .
Anyway thought “the proof is in the pudding” though in reality “the proof is in the starter and mains” as I’m on a diet so headed out in London Bridge to test it out.
Place was packed - good
Service - on arrival was rubbish stood there for 5 minute whilst staff dodged me despite having tables
Decor - in a Turkish kitsch way absolutely terrible but equally in a crap 1990s Turkish disco fet hat wearing charicature almost cultural misappropriation bonkers way quite brilliant . Branding is somewhere between terrible and genius .
Service - excellent server really engaged and positive, might be a one off but he loved it . “you’ve got to have the mixed grill “
Starter - some haloumi thing with pomegranate and rose water.
cane out very quick was very good , tick in the box
main - mixed grill
I’m very used to Turkish mixed grill courtesy of Zeugma on London road Sheffield . Spent many nights in there and it’s a benchmark in sheffield .
Comptoir mixed grill - woeful in comparison, came out very quickly which is a bad sign and just average pretty disappointed but what do I expect from a mass market chain ?
Investment theses thoughts ?
- place was packed and the guy said DEcember had been nuts so probably making good money
- my grill was pretty crap so profit margin will as offensively high as the food was bad .
Feels like a frankie and bennys standard Turkish chain run by a good CEO who can roll it out and make money for investors which makes it a good investment .
Didn’t hear any negative comments from other customers
Be nice if they made a better mixed grill .
Bit torn
Brilliant mystery shopping planetx. I hope you go there again.
Planetx
Love the report, could have done with prices though and your view of value for money. Restaurant experiences are not always just food related, the 'vibe' is important.
Keep up the posting.
mixed grill I think 17.99
starter 7.99
lemonade hime made 4.99
OK prices average quality really, might get caught out long term not good enough,
But Frachise rollout especially at airports would work well, for airport food probably good, for central London with some of the best restaurants in the world no chance .
Issue is a founder owned Turkish family restaurant with a motivated owner is always going to beat a chain of Turkish restaurants .
Hi Planetx
Nice post. Anecdotally I was at Berry Bros last night in St. James’ and the west end looked packed. Could not get a taxi home at 10:45 despite several attempts. Bars are all busy.
I have a feeling that Revolution Bars (LON:RBG) will do well this Christmas from low expectations so I see them as a leveraged recovery play. If they have a strong cash flow from the Christmas period and pay down some debt the enterprise value will rocket. A risky play given recent history of course but at these levels look interesting. Forming a distinct bowl as Cockney rebel would say too. Nice momentum.
Revolution Bars (LON:RBG) numerous 200000 share buys going through today. Maybe Eldose Babu from Dubai buying more. (I hold)
looks like an increase from 10% to 12%
https://newsfile.refinitiv.com...
Oh yes! It's like a 5 year old went mad with a plastic flower set.
Looks like RM (LON:RM) is finally back on an even keel. They've ditched the under performing business and no mention of the disastrous IT project that I assume was associated with the business. Would appreciate a view now we have cleaner numbers. Would also love to know what they tried to implement and who implemented it - so I can avoid their shares if listed!
FWIW, RM is the biggest holding of Rockwood Strategic (LON:RKW) , who actively try to engage with management. I don't remember the full story, off the top of my head but I'm pretty sure new management has been instated that are in possession of a cluestick.
https://www.stockopedia.com/co...
Paul gave RM a Red not all that long ago: https://www.stockopedia.com/co... but I think they're actually going to pull a rabbit out of a hat. The potential here is recovery in operating margin.
Just skimming through the RNS cold, they seem to be closing a naff division, their Assessment division continues to grow in revenue and profitability, and they've decreased net debt.
I don't hold, but it's on my ISA top-up list. I'm actually pretty bullish on this one.
REACT GROUP
New holding for me .
Good to see Father Christmas arriving on the scene at React
Nice present for Mark Braund chairman who exercises 10 million shares at 0.3p thereby getting circa 100k value stuffed into his Christmas stocking .
Don’t know much about the management team yet but I’m sure he’s amazing and fully deserving of his award .
Happy Christmas Mark .
React (LON:REAT) Hi planetx. Re your comment "Don’t know much about the management team yet" I phoned Mark a couple of weeks ago (after contacting him via email (mark.braund@reactsc.co.uk) to discuss a few queries I had. Contacted him on a Sunday afternoon and he responded later that day.
He was very generous with his time so I'm sure if you have any queries he would be happy If you contact him I'd be interested in what comes out .
I'm dithering on this one but intrigued at Dowgate increasing their stake and Harwood buying some (albeit Chris Mills referred to it in an interview with Paul Hill as going from the sublime to the ridiculous when going from discussing Conduit Holdings (LON:CRE) to talking about React (LON:REAT)
Driver (LON:DRV) - "New strategic plan to further improve margins" (report & audio summary here: https://www.equitydevelopment....)
FY23 preliminary results delivered a strong turnaround in profitability on modestly lower revenues, highlighting action taken on costs and improved levels of utilisation. With a solid foundation now in place, we expect the new strategic plan to deliver an uplift in gross margins of c. 20% by the end of FY27. With plans in place to expand top line revenues plus a focus on added value expert services and related sectors, the outlook is bright and not yet reflected in the company’s current valuation in our view.
Year-end cash made up 42% of the Group’s market capitalisation and 37% of the NAV. This values the underlying business on modest ratings. We retain our 40p fair value / share which will be re-assessed as earnings momentum feeds through.
Capita (LON:CPI)(I own) look good enough to me.... very much on top of balance sheet now, no bad news re cyber costs and confirm 2024 +ve FCF guidance ... interestingly Serco (LON:SRP) results also today and point the way in terms of less than 1x net debt EBITDA, mid single digit growth and decent FCF.
This is the target for Capita (LON:CPI) but first it needs to deliver on much improved margins ... the rating leaves significant scope for improved share price and in March this year they traded above 40... before the cyber incident dented sentiment, with the exceptional costs impacting results at the half year. Of course there is plenty of hardwork ahead but the new CEO who takes over in January with an extended handover might get this one going.... Not that cyclical but not immune, certainly less so than previously .. steady as she goes will win the race with this one.
Don't get a more bullish looking chart than the S&P. Could well be on course for a new high by year end, not many would have predicted this a year ago. October 2022 almost everyone was mega bearish.
Will be interesting to see if a convincing breakout follows, lots of money sitting on the sidelines could come flooding back in and cause a really sharp move to the upside. Flip side is the effects of rapid rate rises come home to roost next year and something big breaks.
I'm expecting a "pop" today.
My vibe is that the mood music changed in November and the outlook for 2024 looks positive.
Indeed there was a ‘pop’ this morning but Andrew Bailey at the BoE soon put paid to much of that! Does the man know what he is doing?
Pound is up against the dollar. Maybe time to let Megan talk me into adding the USA to my Stocko regions when my subscription renews tomorrow - Pain Point 1 in her Four myths on US stock market investing (and how to overcome them) was 'Foreign exchange costs eat into my returns'. Is it worth the £110 extra? Hmmm, decisions.
Hi Indie, FWIW, I think it's worth the extra. You don't need to wait for renewal either, the cost will be pro-rata for the remainder of the year. I'm wondering if to add Europe...
Regards, Jon
Thanks, Jon. Hope our outcomes are good, whatever we decide.
My morning smallcap tweet: The death-watch beetle of bulletins
EnSilica (LON:ENSI) Microsaic Systems (LON:MSYS) abrdn Diversified Income and Growth (LON:ADIG) Musicmagpie (LON:MMAG) Aptamer (LON:APTA) Driver (LON:DRV), RM (LON:RM.)
◄EnSilica (ENSI)► £1.56m placing at 40p, a 16% discount, to finance sales opps (or keep the lights on by the sound of it). Warrants at 55p. [SP=47 Cap=37m]
◄Microsaic Systems (MSYS)► the cash crash disaster is evaluating a significant acquisition which would need a placing. No other real info. Remains suspended. [SP=0.01 Cap=m]
◄abrdn Diversified Income and Growth (ADIG)► proposes managed wind-down. expects that approximately £115 million would be returned to shareholders in H1 2024, at, or close to NAV. Further returns to follow from private markets portfolio. [SP=76.2 Cap=230m]
◄musicMagpie (MMAG)► guides FY-Nov rev down 4%. Consumer technology rev in H2 up 7.5%. EBITDA up 15% at £7.5m. Co "remains confident in the Group's strategy and in its medium-term prospects". Hmm. Opinions vary. [SP=11.5 Cap=12m]
◄Aptamer (APTA)► wins £553k max order to supply optimer binders. [SP=1.16 Cap=5m]
◄Driver (DRV)► FY-Sep rev down 5%, pretax-cont £0.13m (-£2.2m). U/L pretax -£0.02m. Sept trading stmt guided underlying pretax "at a slightly lower level than the £0.7m reported in H1". Didn't say continuing. Either a miss or presentation is confusing. [SP=26.94 Cap=15m]
Santa Rally is on, last 10 trading days of year.
A rally against the backdrop of macro uncertainty, with monetary tightening baked into the system having a progressively negative impact.
Lets see and as MrContrarian suggests above "opinions vary".
There's always a bad macro backdrop at the start of a new bull market... When investors don't trust the rallies, then we have an extremely bullish signal.
Always? The old adage is certainly that they climb a wall of worry. It more true that markets generally turn before the good news consistently starts arriving . . . . .
Yes, always! Every bear market in stock market history was caused by some "doom or gloom" in the media or the wider economy. And every subsequent bull market bottomed out and emerged when the doom & gloom was still in the news. The pandemic crash of 2020 was a perfect example, the market bottomed and raged forward despite the global economy in lockdown. There is always something to be concerned about, which is why investors need to switch off the news and focus on the price action or the company fundamentals (depending on how you invest).
The markets are very sensitive to interest rates and are pricing in a return to lower interest rates and the subsequent economic recovery. Every time central banks keep interest rates on hold, it strengthens the case that QT has peaked and that QE will commence next year in order to strengthen our economy and avoid a potential recession.
Tandem Group
Looks like bit of a horror story unfolding but equally valuation is starting to get silly given the asset backing.
Tried to dig a bit deeper yesterday on train back from London and quick fagpacket analysis mix of what I know , what I am guessing .
- massive asset backing with a supposedly lovely new warehouse well located
- cash pile has evaporated sunken into new building
- now has sone debt and was hopeless enough to “technically breach” which is somewhat alarming and not good to brush off as such
- bicycle industry is in meltdown yet statement says “ahead of last year”, this sounds waffle as last year was rubbish also. Where are they in relation to covid boom year and pre covid
- very worrying that the others sectors are under performing, you would have hoped that some of the other areas (outdoor / golf / toys etc) would have at least have one strong sector. All look weak. Very bad news
- dividend cancelled now loss making, arguably when new warehouse kicks in and they exit the leases etc of previous rented warehouses will be big cost savings, not clear when these kick in and there will be significant dilaps / exit costs so more short term pain
- CEO and management look woeful, constantly blaming external factors which they do continuously
. Really stupid strategy with their new flagship store to stock 3rd party brands (no commercial advantage just a retailer) for the likes of Whyte. Shows a company and its management so devoid of confidence and love for their own brands and product that they fill their lovely new retail outlet with other brands. Just a disgrace .
- Bit of history, few years ago I “bought” the Holdsworth brand from tandem group .
For me it was a prized asset and in the 50s / 60s / 70s holdsworth was the iconic British racing brand and it was sold in a silly deal (I’ll not divulge too much)
- stock levels look good, stock looks quite lean bit that should have generated cash, but cash has been absorbed by new warehouse
So summary
- clueless management
- brutal market with all cylinders not firing
- cash has evaporated
- cash savings not going to kick in for 12 months
- new warehouse and showroom now fully paid for and owned with large extra capacity they don’t need
- cash pile evaporated so bank will start to have more control
- zero interest from private equity right now as they have had very bad burned fingers in bicycle market boom and bust (wiggle / PBK)
- pension deficit not been boxed off , Couid have surely used the cash to square that off .
Prediction
More pain to come, if and when the valuation drops to sub 5 M gets into such deep value territory has to be of interest .
Possible Mike Ashley who is buying up the bike industry, if he pockets Wiggle in the next week or so to add to Evans / muddy fox etc .
Pension deficit complication for buyer
BUT
When it slips below 5 million would enter serious deep value territory
FiNALLY
Ask myself the Christopher mills question
“Would I buy the entire company”
At 5 million absolutely especially if I had a currebt pick pack warehouse operation that needed a retail space,
The logistics support and value of state of the art warehouse is worth 2 times market cap say 10 million
Stock is worth 4 million which I couid trade
Rest is break even / loss making but reverse in my existing staff saves the costs absorbs the overhead so there is value there .
So maybe a bid of 10 million.?
But deluded management and shareholder base might not accept until there is real blood on the streets .
I’m waiting to see if it drops sub 5 million market cap that’s going to be a real sweet spot .
Very interesting to hear Powell so open and dovish compared to what we are used to hearing yesterday. Worth sharing what the reaction in the Russell 2000 was following him talk:
A 4% upswing once he started speaking. Let's hope we see something similar in our Small caps today! Could be a good day if it does!
Since October lows the S&P500 has rebounded c15% and is now at 4,707 after yesterday's rally: not far off its early January 2022 peak of 4,815 which was an all-time high.
On the other hand the FTSE-All Share Index has rebounded just c5% since the end of October low and is range bound. This is what is killing the UK markets at the moment in my view: wealth managers and other investors just seem to be chasing the main constituents of the MSCI World Index ever higher.
Hi Paul and Graham
If you get the chance I would welcome your thoughts on Capita (LON:CPI) trading update. I hold this as a recovery play and see potential for a doubling of value if they deliver. Positives appear to be forecasting £60m free cashflow by 2025, as pension deficit payments cease and cost savings kick in. However, they are a big contract low margin business and susceptible to financial accidents. New CEO coming in next year should also help revitalise. Good momentum in winning contracts, but hope margin discipline was good in negotiations.
On balance I remain happy to hold and let this play out.
Greyster
Capita (LON:CPI) RNS reads to me as a random mix of comments about stuff that’s going on without any neat overall wrapper in terms of what this means for profits, dividends etc. Maybe they are waiting for the new CEO to deliver that clarity, until then it just feels like guesswork.
On the positive side, here’s another company that seems to have put an end (or have one in clear sight) to its DB pension contributions. There’s a fair list of them now. Kind of puts a light on those that haven’t been able to (e.g. Renold (LON:RNO)) and with interest rates potentially now falling the boat may have sailed for them.
Sobering results from Miton UK Microcap Trust (LON:MINI) today, showing how poor the UK market for smaller companies is. However this may well be the ultimate low point. It is notable that the FED is running off it's bond portfolios as they mature, without difficulty, (unlike the staggeringly incompetent Bank of England, which gets every call wrong), and that interest rates are about to start falling. Also that politicians are beginning to realise that Brexit and the FSA have holed our biggest industry under the waterline, and that we need money to flow back into UK equities of all sizes. Stuffing pension funds with bonds has been a bad strategy for growth in funds and companies.
I'm moderately hopeful that the recovery is about to begin.....and that higher yielding investments will bounce.
I’m pretty neutral on the sector. In the write up the manager says that a lot of funds now buy unquoted companies and the liquidity in micro caps is better than in unquoted. That’s debatable. If you build up a £1m position in a £50m company - and I can’t imagine an institution being bothered with a smaller stake - the only way you can sell it is if either the market has a bull phase or to a single buyer in a negotiated sale. And you are likely having to pay a MM 5-10% in spread to get in, so the marginal cost is huge. In fact, for a £1m investment I’d expect the investor to be down at least 10% straight away if they decided to sell immediately after. So I don’t see any difference really.
The lack of liquidity in small and micro caps puts off any sizeable investor. Once you’re in, there”s no easy way out. And unlike unquoted companies, you can’t base the valuation on the performance of the underlying business. Also, those problems have led to better companies remaining private, so the pool of listed small companies gets worse and worse. It’s hard to see a way out of this spiral tbh.
Absolute classic Paul throw away. Begbies Traynor (LON:BEG) write up.
I barely know my IFRS from my elbow these days!
I thought nodding along sagely was even better. I envy Paul's writing prowess - especially at such an early hour!
Morning ezlifeme & Berksbee,
Glad to hear you appreciated my quips! The subject matter is rather dry, so I like to spice it up a bit sometimes :-)
Regards, Paul.
Hi Paul,
I dont hold, but I think that yesterday PROCOOK (LON:PROC) was marked in your report as in-line. I chanced across the forecast EPS figure this morning - down 70%ish - maybe more in line now ?
edit: in fact the 2024 forecast EPS seems to have dropped off the report mid november, which was convenient, so maybe it was inline after all.
edit +1: in even more of a rant, it's no wonder that Watkin Jones (LON:WJG) cant project manage their construction contracts, from this mornings RNS
'Watkin Jones plc confirms that the registered office for the Company has been
changed to 50 Jermyn Street, London SW1Y 6LX. The Company will move its
registered office to 12 Soho Square, London W1D 3QF, with effect from 4
January 2024'
No, haven't got up the wrong side of the bed :o)