Small Cap Value Report (Thu 14 July 2022) - JDW, APP, LGRS, FCAP, TRST, JIM, XAR, MCB, CTO

Good morning! We're back up to full strength today, with Paul & Graham. Yesterday's report was a bit weak, sorry about that, we'll try to catch up today & tomorrow.
All done for today, I can't process any more numbers!
Agenda -
Paul's Section:
J D Wetherspoon (LON:JDW) - pubcos have been battered in the current bear market, for fairly obvious reasons - discretionary spending, when incomes are being squeezed by inflation. JDW's latest update is weak, with higher costs (some discretionary though) reducing profit guidance into a £30m loss. I think mgt can pull levers to restore profits, so this is starting to look like a potentially interesting entry point. Lots of costs are fixed, but not wages of course, a heavy drag on profits. Pubs are mostly freeholds, not revalued since 1999.
Appreciate (LON:APP) [No section below] - The CEO is stepping down, with the Chairman covering until a replacement is found. I listened to a recent webinar from APP, and can’t make my mind up about the shares. The upside case does sound interesting, but overall it left me flat. The outgoing CEO is most noteworthy for being a weak presenter on webinars (sounding robotic) - raising the question, does that really matter? I think it does to an extent - anyone running a company should be excited about it, and able to communicate that, and inspire staff. Although stellar numbers matter more than presentational style. Numbers at APP seem OK, but not stellar by any means. Let’s see what the next CEO plans to do with the company. I'll keep it on the watch list. [No section below].
Loungers (LON:LGRS) - a strikingly better performance than JDW, from this rapidly expanding chain of bar/cafe/restaurants. I skim through the results for y/e April 2022, which look great, albeit boosted by Govt support measures that have since gone. Forecasts for the new year look soft, so little risk of a profit warning. Much more upbeat current trading & outlook than JDW, which makes me ponder how different customer groups are behaving.
McBride (LON:MCB) (£28m) [No section below] - an in line update, but the company remains financially distressed, and is exploring options. Very high risk of dilution/insolvency. Two daft mistakes in the RNS - (1) a pointless footnote re market expectations, that doesn’t give any numbers! (2) quotes net debt of £168m including leases, likely to scare investors, without mentioning the lower bank debt figure! Who writes/reviews these things, scoring such obvious own goals?
On the upside, MCB is “predominantly” passing on cost inflation now, with price rises, hence H2 revs up 13%.
£30m liquidity headroom above minimum stipulated by bank, at end June.
It’s obviously going to need a placing, to refinance. With such a low market cap, a deeply discounted raise looks likely to me, so why get involved now when you face big dilution risk? Institutions can’t get out, we can! [No section below]
Tclarke (LON:CTO) [No section below] - we reviewed the strikingly positive trading update here in May 2022, from this complex electrical/IT contracting group.
Readers have been discussing today's interim numbers. H1 PBT is 5.5m, on revenues of £206m, so a tiny profit margin, with a lot of contract risk. The outlook sounds positive, and revenue expectations for FY 12/2022 are upped to £450m. Order book has grown further to an impressive £586m, plus over £1bn of bid pipeline (only some of which will turn into contracts obviously). There’s not much asset backing, only c.£10m NTAV. Note the £16m pension deficit.
This share has held up very well in the current bear market. It sounds as if the outlook is positive for the time being too. However, investors need to be very careful about buying into cyclical businesses that look cheap, at what could be the top of the earnings cycle. Look back to see what the share price did in 2008 for example, when investment dried up. Remember that big construction projects have long lead times, so a drying up of orders might not manifest itself until well into an economic downturn (if there is one). So it can be a mistake to assume that a company you like is somehow immune from macro factors.
Graham's Section:
finnCap (LON:FCAP) (£32m) - Results for FY March 2022 are good, as expected, from this AIM broker and Nomad with an increasingly diversified range of services. M&A is still of fundamental importance to its results and while FY March 2022 was a great year, and the company achieved record revenues, FY March 2023 is now said to be “very quiet”. That’s the problem with this sector: the good times are good, and the bad times are awful! I argue that P/E multiples should not be applied to these companies, and that value investors should instead try to buy them at a discount to their balance sheet values.
Trustpilot (LON:TRST) (£369m) (-5.5%) [no section below] - this floated at 265p in March 2021. At 89p, this is the sort of discount to the IPO price that gets me interested! Today’s H1 update shows revenues +18% to $73m (+25% at constant currency). The company is still targeting EBITDA breakeven in FY 2024. Unfortunately, the market has become rather impatient with companies so far away from making real earnings (and positive EBITDA would not represent real earnings).
As someone who regularly researches company reputations and looks for consumer perspectives, I find Trustpilot a useful tool, so I would love to find an argument that the shares are cheap. The price/sales multiple using next year’s sales forecast is around 2x, so maybe we are getting there (accepting the great uncertainty around future monetisation and profitability of the platform).
Jarvis Securities (LON:JIM) (£68m) (-22%) [no section below] - a dramatic fall in the share price at this discount stockbroker on the back of weak H1 results. Revenues are down 23% as UK investors are trading less and there are fewer IPOs giving Jarvis the chance to earn commission fee income. The share price decline is not matched by the decline in earnings estimates at the company’s broker, who has only slightly reduced the full-year PBT estimate from £7.3m to £7.0m.
Jarvis has a wonderful historic track record of cash generation, high ROCE and shareholder dividends, and I’m always interested to see it trading cheaply. The company has an opportunity to earn higher interest on cash deposits as rates rise, although this is offset by the likelihood that high interest rates will keep share prices depressed and trading volumes very low. In the short-term, it might be a case of swings and roundabouts!
Xaar (LON:XAR) (£149m) (+2%) [no section below] - this company produces advanced printing technologies. It was a high-flying midcap at one point, but has had an extremely volatile share price performance over the years. H1 revenues are £37m, up by 14% organically and 41% in total. Full-year adjusted profits are expected to be in line with expectations (these expectations are minimal: only around £1m). The cash balance has sadly reduced to £12.6m, and this is in line with expectations. Xaar could turn out to be an exciting growth story again; it’s on the racier and more speculative end of the spectrum.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
J D Wetherspoon (LON:JDW)
577p (close last night)
Market cap £744m
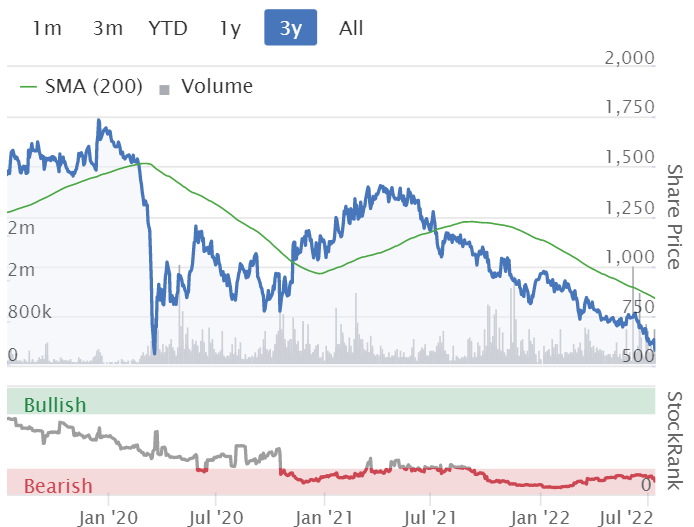
I’m staggered that the market cap of this large pubs chain has now fallen to within a whisker of our usual (flexible & arbitrary) £700m upper limit. As you can see from the 3-year chart below, the current share price is now similar to the low point in the original pandemic crash in March 2020. Although note that the market cap is still higher, because the share count went up - it’s now 128.8m versus 107m pre-pandemic.
.
Looking back on the RNS, I see JDW raised £141m (at 900p per share) early on in the pandemic, in April 2020.
When companies need money, they should always do it quickly, rather than hope for the best, and do it at a deep discount once a problem has become an emergency. We’ll be seeing more emergency fundraisings in the near future I believe, so the issue of balance sheet strength, and bank arrangements, should be top of our agenda right now.
This is a pub group, specialising in a simple, value for money offering. So it’s nearly always the place with the cheapest pints, and everything else that entails.
Higher costs mean a larger loss for FY 8/2022 than anticipated. Although some of these cost increases do seem discretionary -
Wetherspoon has invested heavily in labour, repairs and marketing, following the ending of restrictions in February in order to strengthen our position for the financial year beginning 1 August 2022.
Losses for the current financial year (FY22) will therefore be higher than expected at approximately minus £30m on a post-IFRS 16 basis (approximately minus £23m on a pre-IFRS 16 basis).
That’s clearly a poor result, since there have not been any lockdowns in that period. It should be profitable again by now, in my view.
It’s a fairly big profit miss, as the StockReport shows a net profit (after tax remember) of £11.9m, so that would be c.£15m pre-tax. Hence it looks about a £45m profit miss - that’s a lot, especially coming right at the end of the year, when management should have had a more accurate idea of profit, and communicated it to the market via brokers. Hence I am wondering if there’s possibly inadequate financial control/budgeting here?
Current trading comments are interesting for wider read-across -
Q4 (May, Jun, July to date) sales are almost level (minus 0.4%) with pre-pandemic.
Improving trend from Q3 which was minus 4.0%.
Recovery from pandemic slower than expected.
Biggest category (draught beer/cider) is the problem, with sales down 8%. Other categories are up. Best is cocktails, up 19% on pre-pandemic.
“Lloyds” branded pubs are up 6% - they play music (other ‘Spoons pubs don’t) - is this hinting that a change of policy re music might be on the cards?
Outside of London, major city centres are doing better than expected, and are up on pre-pandemic sales - quite surprising to me, and should be encouraging for my sector pick, Revolution Bars (LON:RBG) (I hold).
Labour costs are much higher than pre-pandemic - no surprises there.
JDW is noteworthy for having very good staff retention - managers are long-serving on average, because they are treated well with a generous profit share scheme.
Repairs costs are substantial -
Although repairs were reduced to minimal levels during lockdowns, there has been an element of "catch-up", so repair costs in FY22 will be around £99m compared to £76.9m in FY19.
Most pubs are freeholds - a key, and very positive point -
Wetherspoon has invested £128m in the acquisition of freehold reversions of 48 pubs since FY19, of which it was previously the tenant, bringing the number of freehold pubs to 582, 68.3% of the estate.
Leased pubs - I also like the sensible changes made here -
In addition, the company has also "regeared" the leases of 15 pubs in this period, usually at lower rents than previously applied, with fixed, five-yearly rent reviews, which are significantly below current inflation rates. Of the company's 270 leasehold pubs, 116 now have fixed rental increases.
Inflation - good arrangements have previously been put in place -
Wetherspoon has contracts for energy supplies until the end of FY23 at fixed prices which predate the current spike in energy costs.
As previously indicated, Wetherspoon has long-term contracts for many bar and food purchases, which will moderate the highly inflationary cost increases which have been widely reported.
Wetherspoon believes that its overall costs will increase by less than the current rate of inflation in FY23.
Interest on borrowings - this looks a stroke of genius, locking in long-term low rates long-term-
As has also been previously indicated, Wetherspoon has fixed the floating rate interest cost of £770m of its bank loans, using swaps, at between 1.02% and 1.61% until November 2031.
That sounds amazing, but I don’t think it’s the total cost of the borrowings, because the last interim report says -
The total cost of the company’s debt, including the banks’ margin was 4.28%.
Tim Martin’s rant - he can’t help himself, can he?! This time, it’s a re-hashed previous rant about unfair tax treatment of pubs vs. supermarkets. He also takes a swipe at competitors boards -
However, surveys by Wetherspoon in the past have demonstrated great fervour for tax equality among individual tenants and free traders.
The lack of vocal support for equality is probably an example of board rooms being out of touch with those on the front line, always a bad sign for any industry.Until there is tax equality between different types of businesses on the High Street, pubs will always be fighting with one hand tied behind their back - and will provide less in the way of jobs or taxes than they otherwise might.
Outlook - is mainly a rant about Govt covid policies, but also includes this -
"Wetherspoon has tried to take a long-term approach to these issues, investing heavily in the workforce, in buildings, in marketing and in contracts with landlords and suppliers, which will hopefully create a solid base for future growth. The company remains cautiously optimistic about future prospects."
Balance sheet - nothing is said about cash or liquidity.
Looking at the last balance sheet, at 23 Jan 2022, it’s adequate, but NTAV is only £296m, a long way short of the current market cap.
Key items to research in more depth are -
Freeholds - in books at £1.1bn (includes long leases), have not been revalued since 1999. So what is current market value compared with book value? We can't assume they've all gone up in value, some might have gone down maybe?
Bank debt - substantial, at £963m, although the freehold assets are more than this. What are the bank covenants, and is there enough headroom? I see from the interim report that banks have been very supportive, and covenants waived until Oct 2022 (for a £1m fee). What happens after that?
I think another placing is a possibility at some stage.
My opinion - I’m in London at the moment, and am pretty shocked at the price of a pint, £5.50 seems to be the new starting point. £6.50 for premium lager, and this is outside the centre, in ordinary pubs.
So in good weather, plenty of people prefer to gather with friends in the parks, and buy supermarket drinks. No wonder Tim Martin is unhappy with that, and he does have a point. Multibuys cost little more than £1 a pint at the supermarket, although you usually have to chill them at home first. Sometimes I find that draught pints are not very good (not fizzy, or cold enough), which certainly makes you wonder why you’re paying 5 or 6 times what a supermarket charges, often combined with surly & indifferent service in London.
I’ll have to mystery shop a ‘Spoons whilst I’m in London, and report back.
It does make me question the overall business model though - in British pubs, people are generally too stand-offish to mingle, and all too often you see people sitting on their own, looking miserable. You can do that on a park bench much cheaper, if you don’t mind being mistaken for a tramp. So why pay £6.50 for a pint?
It also begs the question whether the cost of living squeeze is harming ‘Spoons customers disproportionately? Given that they’re already probably challenged for money (hence seeking out the cheapest, no frills pubs), then it’s safe to assume that JDW’s customers are more likely to be impacted by food & energy inflation, than the middle classes, who don’t tend to drink in JDW pubs. Offsetting that, others might trade down from more expensive pubs, possibly?
It seems clear from this update that JDW needs to raise its prices, to restore profitability. Logically, the cheapest pubs should find it easier to raise prices, and will still be the cheapest in the market, as everyone else is raising prices too.
Cutting to the chase, is this a good time to buy JDW shares? Looking through the sector, other pubcos have also seen plummeting share prices of late. The way I see it, JDW does have a unique market niche, at the affordable end, and its long-term track record is excellent. Therefore, one way or another, profitability is likely to improve, and it looks well set up to withstand inflation & higher interest rates.
Hence for long-term investors, I reckon it might be one to add to the potential buys list, after having done more thorough research yourselves - particularly on the bank borrowings & covenants. Another placing can’t be ruled out.
Note that Tim Martin sold £60m of shares in 2020 & early 2021. Although he still owns c.22%. He could buy them back now at half the price he sold at.
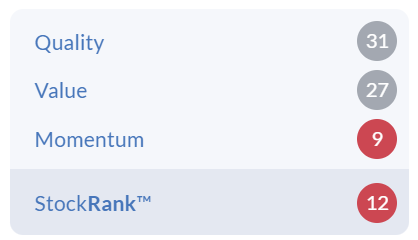
I'm surprised the StockRank is so low, but I suppose the computers don't realise there's been a pandemic, so just focus on the move from profit into losses.
.
Loungers (LON:LGRS)
188p
Market cap £194m
This is for an unusual 52 week year end of 17 April 2022.
We’ve covered Loungers here before, it’s an impressive self-funding roll-out of all-day bar/cafe/restaurants. My sector expert tells me that management are top notch.
Loungers is opening about 30 new sites per year. No doubt landlords will be offering them excellent property deals, so this is paradoxically a great time to be expanding, when others are struggling, and good sites are available. Although the CEO of Revolution Bars (LON:RBG) (I hold) recently said there is now more competition for good sites.
We’re pushed for time today, so I will just give some abbreviated notes from my skim of the results statement issued yesterday -
Revenues £237.3m
Lots of different EBITDA measures presented, which I’m ignoring, as they don’t reflect reality for me.
Profit before tax of £21.6m looks good - especially compared with JDW above, which is reporting a loss for a year end that is only 3 months different from LGRS.
17.0p diluted EPS - a PER of about 11, which looks superficially cheap.
Profit boosted by £4.5m Govt support measures. Plus there was reduced VAT on food, and reduced business rates (benefit not quantified).
Broker forecasts are for much lower profits in FY as Govt support measures have ended - good, we want soft targets, as there’s less risk of a profit warning. EPS falling to 9.4p is broker consensus. That’s a PER of about 20 - but I think it’s likely to beat this earnings forecast, so the actual PER could end up being lower.
Roll-out of 32 sites per annum is planned - an ambitious, expanding business. Self-funding too, so shouldn’t be any more dilution from share issues.
Share-based payments to mgt are possibly over-generous, at £3.2m this year, and £2.0m last year.
Current trading - in stark contrast to Wetherspoons above, LGRS says it has seen “no change in customer behaviour”, and its LFL sales are strongly up, +14.2% excluding the reduced VAT benefit, against pre-pandemic comps.
Wetherspoons is only just level with pre-pandemic, so as LGRS says, LGRS is out-performing the industry by +15%. I would just temper that by saying that, as many of its sites are newish, they’re probably still on the gradual build up of trade that I would expect from a new site, as it builds the customer base. Then that would expect to level off, once a site is mature, then go into decline, as it becomes tatty & requires an expensive refurb. It’s important to remember that (typically 5-year) cycle, which flatters performance in the first half, and drags on performance in the second half.
Also, different bar/restaurant formats come in & out of fashion over time.
JDW’s more mature estate is possibly struggling because of this factor, maybe?
Balance sheet - is pretty thin, because LGRS operates using leasehold properties.
NAV is £134m, but it’s mostly intangibles of £113m, so removing them gives NTAV of £21m.
So no asset backing, and increased risk from rent reviews in future eroding profits, but also little to no bank lending to worry about in a downturn, which is probably more important right now.
Cashflow - distorted by IFRS 16, but also there seems an unusual & large rise in trade creditors, that looks a one-off benefit, which might even unwind next year?
So I wouldn’t assume that the exceptionally good cashflow is necessarily going to continue at that level. Still, it’s wiped out the bank debt, so is rather nice.
My opinion - comparing JDW’s weak performance, with LGRS strength, confirms my view that current macro conditions at the moment are not the usual “squeezed middle”, which we hear the press go on about. Inflation tends to hurt lower income people the most.
It seems to me that people in work, are getting pay rises + bonuses which enable them to keep up with the cost of living - recent ONS data put it at c.7%. That’s enough, once you make a few downward tweaks to spending, to maintain pace with inflation, and continue the discretionary spending which you enjoy the most. That’s where I think we are right now, which could change in future of course. Recent GDP data was a bit better than expected too. So people are still spending, if goods/services are value for money, and enjoyable.
Where things are really starting to hurt, are for the “squeezed bottom” (very topical, given recent events in Westminster!). Low income people - that’s where inflation is hitting the hardest, already in double digits for people who spend a high percentage of income on food, and utilities. They’re more likely to be JDW customers, than LGRS customers, I suggest.
Overall then, I think LGRS looks a very good long-term investment, providing management can cope with opening so many new sites each year, without losing control.
Although in valuation terms, it’s not looking cheap, even after a big downward move. The forward PER of 20 certainly requires an earnings beat, to be justified.
It’s going on my possible buys list though, but maybe no immediate rush to dive in?
.
Graham’s Section:
finnCap (LON:FCAP)
Share price: 18p (pre-market)
Market cap: £32m
Many of you are familiar with this one - it claims to be the largest Nomad (nominated advisor) and No. 1 broker on AIM.
Its share price has approximately halved this year, in advance of today’s full-year results.
The problem with these small investment banks is that they have some of the lowest-quality earnings that any company can have:
- Lumpy revenues, from corporate clients. Sometimes one or two big deals can make or break the results for a year.
- Labour-intensive. If the chief rainmakers leave the company, it loses most or least much of its value. If they leave and set up a rival company, it’s a disaster!
- Economically cyclical. In bad years, both equity trading volumes and M&A opportunities dry up, and only skilled management can prevent these companies from making a loss - usually by cancelling bonuses and letting people go.
Personally, I would hesitate before even assigning a P/E multiple to these companies. When earnings are so volatile and unpredictable, I think it becomes a meaningless statistic.
If you look back at my Cenkos Securities (LON:CNKS) commentary in 2019, for example, you’ll find that I was mostly interested in that company’s net asset value (which was mostly cash and liquid assets). If I can buy one of these companies at a discount to cash and easily liquidated assets, then I think it has the potential to be a value investment. But I’m not willing to value them based on their earnings for any given year.
That’s enough of a preamble. Let’s see what Finncap achieved in FY March 2022, and quickly move on to a conclusion:
- Revenues +13% to £52.5m
- Cavendish (private M&A) revenues +101% to £24.3m
- Capital Markets revenue minus 18% to £28.3m
- Net income £6.5m (previous year: £7.0m)
Market share for AIM deals greater than £5m was 11% - excellent.
Finncap is now very active in private M&A, and has ambitions to build a professional services division (it recently bought 50% of a “sustainability” consultancy).
The diversification strategy does arguably reduce some aspects of risk for shareholders, but it also increases complexity for anyone analysing Finncap.
Furthermore, I think it’s hard to argue that the addition of these new businesses brings any radical improvement to the quality of earnings. But I’ll try to keep an open mind in this regard, and see how the strategy evolves.
Unfortunately, despite the record revenue performance in FY 2022, profits did not improve. The company comments on higher employee costs:
Administrative costs increased by 17% over FY21 reflecting higher employee compensation arising from the Group's strong financial performance in particular in the M&A division where competition for professionals remains intense. Staff costs (excluding share based payments) as a percentage of revenue were 61% - broadly in line with FY21 and within our 58-62% guidance range. Our staff costs percentage remains in line with or below much of our peer group.
Non-staff costs rose too, as the company invested in a new office, giving “substantial scope for expansion”.
It’s hard to imagine much further expansion in the short-term, however, in the current conditions. Finncap says that it will “selectively” invest in people, for the medium-term, but there is little doubt that short-term prospects in the current financial year are poor:
The current financial year has been complicated by the tragic conflict in Ukraine and rising macro risk including rising inflation, high energy prices, concerns over food prices and the consequent impact on consumer confidence in key markets. This has significantly impacted the level of ECM activity, IPOs and equity issuance across all market participants.
Equity issuance through our Capital Markets division has been very low but we continue to execute plc M&A mandates. Sales and trading activity has remained broadly stable.
In contrast, the private M&A market and our team's M&A performance has been strong and we have closed several private M&A transactions post year end…
As a result of market conditions, we expect revenue and financial performance to be substantially lower than in FY22.
Balance sheet - for March 2022, before a £2m acquisition, we get the following:
- Net assets £33.1m
- Net tangible assets £19.1m
- Net current assets (NCAV) £4.8m
My view: Below net tangible assets (c. £19m), I think this is a value investment.
That may seem ludicrous, given £6.5m in net profits just reported. Surely the company is worth more than three times trailing net income?
However, I would point to the lack of repeatability of trailing net income, how long it will take Finncap to pay out its market cap in dividends, and the possible changes in the M&A/capital market landscape by the time that happens.
Shareholders might still do extremely well from current levels, but I think it’s best to have a cushion in tangible assets (ideally liquid tangible assets) before getting involved in this sector.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
re Paul/Graham's write ups - I like both short and long! Personally, I think the current balance is excellent. Bit wider with a few short sections now but deep dives into something they find interesting and feel they can add value on. I am happy to trust their judgment.
Just as an aside, we've got so many companies to cover, that we have to somehow try to pick things that are relevant, interesting, and that we can write about reasonably quickly (i.e. not complicated).
I know that sometimes people moan about, why haven't you looked at this, etc, and I do sympathise. So thanks to everyone who put up your own summaries here for stocks you like & own, it's very helpful, and often gets us interested (e.g. JDW & LGRS yesterday, which I wrote about today).
Sorry we don't have sector specialism in resources stocks. I know a bit about the sector, but not enough, and really don't want to start blagging it, and trying to sound informed, when I'm not. I did follow up the query though, and have floated the idea at HQ that Stockopedia could try to find some decent sector coverage. I think that was tried before, but didn't work out.
Anyway, here is today's GoogleDoc, where Graham & I tried to cover as much as we could, and to give you a flavour for things, which might be of interest - they go blue when published. Orange are want to do. There'a rarely enough time to cover everything, but we try.
Do people like the shorter sections? Or would you rather we just focus on more in-depth reviews? We're not sure what to do, as not much feedback on that.
In my view (fwiw) what you jointly do at the moment is just dandy. I like the short sections at the top and the difference in focus between the 2 of you. I don't see the point in trying to cover businesses where you don't have much relevant experience (or alternatively a keen interest in digging in and learning, because we should all be doing some of that).
I say: good job, keep it going, thank you.
BattleOf Brit,
In case the message was lost in translation as some seem to think. Atalaya Mining (LON:ATYM) is a superb company, paying an excellent dividend with a rock-solid balance sheet which is net cash, selling at a good valuation. So is the other company that was discussed yesterday.
Well, as far as I can see Atalaya Mining (LON:ATYM) has only ever paid one dividend - that's not much of a record to start using the dividend yield as a solid case for investing! Cyclical sectors always look cheap when they are at the top of the cycle. The theory goes that you should only buy cyclicals when they look expensive at the bottom of the cycle. You say, it's a superb company and yet I now see this is what used to be EMED mining, a company I recall that struggled to get a license to mine its resource for many years from the local government even though it was in a "friendly" developed country like Spain.
And that is the point I am making against the risk/reward for small cap resource companies. They are often exposed to a single resource in a single country (like Atalaya), if you're lucky, maybe multiple deposits in two countries. This requires direct governmental approval for their operations. In less developed or developing countries the government nearly always wants some of the pie. When times get tough, they might want all the pie e.g. Argentina. If this isn't just a few million $$ paid into an offshore bank account, then that normally means they are looking for other ways to eat the pie. The point I am making, is that no matter how good the fundamentals, no matter how good the quality of resource, there is the exogent risk of direct government intervention. And you'll never see it coming...
It is my personal preference to remove the potential impact of direct government appropriation as far as possible from my investments. Who wants to invest in a company that has to declare its payments to governments every year? And what was the most recent case of threatened government appropriation?... Ah, yes, Hochschild Mining (LON:HOC) That looks very cheap too!
Hi Paul,
The SCVR is excellent and improving with your podcasts and summaries.
If you cant fit everything in, then I like the short "no section below' comments.
Your detailed analysis is awesome but I skip it if the company doesn't appeal to me. Obviously, if you review one of my holdings I read every word. Some of my holdings are purely from finding out about a company in SCVR.
Investing can be very lonely (especially if you are a contrarian). Its sometimes reassuring to find that other investors have the same thoughts.
Keep up the good work.
PS. Renold (LON:RNO) is a company that appears to be doing a proper turnaround focused on the basics of running a good engineering business. Repeated good news doesn't seem to be getting the SP reward it deserves. I expect this one to rise in the long run. I'm looking forward to your thoughts.
Shorter views for me Paul-just key headlines and more about what you and Graham think of the information provided by the companies update.
Hi Paul
I love the short sections, usually under a little time pressure so those are the sections that work for me.
If I get chance I do sometimes read the in-depth sections for companies I have an interest in and also look for ideas
Keep doing what you are doing it's appreciated, and aren't we overdue another Paul Scott ramble :-)
Hi Paul & Graham,
Great work from both of you. I like the short comments (no section below) - and would rather have these sections than nothing as all, as often they cover interesting companies for me.
Like the others below I don't always read the long write-ups if the companies aren't of any interest, but appreciate that many others do.
Keep doing what you are doing - your macro overviews are always of interest as are any views on your own holdings.
All the best. K
Paul
I find your insights and analysis really valuable. From some of your posts, it appears that you make notes as you go through a set of results or an update and then write them up into a detailed explanation of what you have noted. I'm greedy - I want both the breadth and depth of coverage! Would it save you significant effort to just publish your notes and your opinion but to omit the detailed write up? If there were things that subscribers found unclear, they could ask a question in the SCVR comments section.
Car insurers getting hammered on the back of Sabre Insurance (LON:SBRE) warning about very high claims inflation (due to more costly repairs). Saga (LON:SAGA) are big on 3 year fixed deals so could be particularly badly placed to mitigate inflation, although actually holding up reasonably well today.
Thanks Bouden54, for flagging this.
I'm not familiar with Sabre Insurance (LON:SBRE) but have just been reading its update, and it seems to have dragged down other mid/large cap insurance companies too. Not my sector, so not sure I want to comment on it though, but I'd certainly be interested in hearing reader comments.
I'm not sure how much SAGA reinsures its policies? I should know, but tend to focus more on the travel division.
Regards, Paul.
Hi Paul,
Anecdotally; my son has just got a summer job progressing insurance claims ( I won't name the company). He tells me waiting times for repairs are already long and getting longer. The earliest date for any Tesla repair is September! Its not good for customers waiting for repairs.
I suppose the hit to the insurer will depend on the flexibility of agreements in place and underwriting etc. I'm sure we can expect our policy renewals to rise to add to the inflation spiral.
Re Loungers (LON:LGRS) hank you for your review this morning. As usual, your quick look through highlights elements that I would have trouble finding and your overall review is so well balanced. That's what I pay my subscription for and why your section is compulsory daily reading for me. Sorry if that sounds like 'over praise' but its a fact for me.
For the sake of others who won't give the results and commentary from management much of a look because they are concentrating on their other favourites, I was particularly interested in the reference back to the 2008 situation and how they not only got through it but took advantage of it. No two situations are ever exactly alike but there seem to be lots of similarities about headwinds facing sectors like hospitality going forward.
Management Comment (in full - apologies for length!)
'The reason for this confidence is that as a business we have experience of dealing with a seismic economic shock before, having traded successfully through the 2008 financial crisis. In 2005/06 the economy was buoyant and consumer spending was elastic, which was exploited by the sector, and specifically by casual dining operators who confidently increased their prices. As a small management team at the time, we took the view then that we should minimise any price increases and hold on to our value for money credentials. We resisted making short-term gains in exchange for being fully prepared should a recession happen. Ultimately this approach paid dividends, and when recession hit in the autumn of 2008 we didn't need to alter our proposition or change our pricing as the consumer recognised that we already offered great value for money.
By contrast, many of our peers found they had driven price increases too strongly and resorted to discounting in a desperate attempt to drive volume, which ultimately ended up undermining their offer for years afterwards.
By early 2009 we were confident that we would not only continue to trade well - and ahead of our peers - but also that we should continue to accelerate our rate of growth. As our peers retrenched we expanded, taking advantage of an uncompetitive landscape for new sites and attracting talent to a business that was recognised to be winning. In September 2008 we had nine sites and by the end of 2011 we had 20 sites, with a further nine new sites planned for 2012. We were brave, ambitious, creative, and believed that we could build something special, and these same attributes have never been more alive in the business as they are today.
In my view, there are similar trends at play as we sit here 14 years on. Following the end of the third lockdown in 2021 we have seen prices in the hospitality sector surge. While some of these increases have been driven by a degree of necessity as supplier prices increased, some have also been driven by businesses trying to make up for months of lockdown. We have had to increase our prices in a targeted way, but by nowhere near as much as our peers. We have deliberately held back from doing so because we remember our experience in 2008 and how offering great value for money in an environment where the consumer is squeezed puts you at a distinct advantage. We are also extremely well placed to meet the challenges of incoming cost pressures to the business, as detailed in the CEO report.'
If I am looking for an investment in this sector at all, then it is one which will have the right balance of experience satisfaction (whatever that is!) and value for money/affordability.
This company seems o be on the right road here, though as Paul says the forward PE of 20 will take some earning.
Graham: "When earnings are so volatile and unpredictable, I think it becomes a meaningless statistic."
Yes, this is a problem with cyclical companies, but stock markets as a whole are cyclical too and perfectly acceptable ways of addressing that have been around for a long time. I would highlight the Cyclically Adjusted P/E (CAPE or PE 10). There is absolutely no reason this could not be calculated for individual companies too, so why isn't it done?
Using something like that would be a step forward for stocko, because just as the P/E is misleading for cyclical companies, so is the stockrank. With a company like finnCap (LON:FCAP) we would be better off buying it when the stockrank is 10, rather than when it is 90, because then we would be buying it at the bottom of the cycle, not the top.
Stockranks work on average, but not for highly cyclical companies. Developing some cyclically smoothed measures would be a step forward.
Hi cmpeckham, I have seen CAPE applied to individual companies and it has some merit, but great care is needed. Finncap (for example) has made important acquisitions recently, and is likely to make more acquisitions soon. It's not the same company as it was five years ago.
It's possible to account for this and build a margin of safety into the analysis, but I think you'd agree that there are complications! It works best for very stable (perhaps very large) companies that are unlikely to experience fundamental change.
Best wishes, G.
Hi Graham. Thanks for the reply. I'd agree that there are complications, but in my opinion that doesn't invalidate the analysis. The S&P 500 is a very different "company" to 10 years ago, but that doesn't invalidate comparisons using the CAPE.
Regardless of any changes to our example of Finncap, the CAPE measure would still impart key information. Looking at Finncap at the top of the cycle, the TTM and Fwd P/Es would be very low, but the CAPE would be high or middling. It's that difference that's key. It prompts the question: is this a bargain, or just a highly cyclical share at the top? Other analysis would be needed to tell you the answer.
Equally at the bottom (maybe in a years time?) looking at Finncap would show terrible TTM and Fwd P/Es, but the CAPE might suggest a bargain that is waiting to multi-bag in the next bull market. Again, it's the difference between the 2 measures that is key. It doesn't give you an immediate answer but throws up questions for further analysis.
I would also say that CAPE is just one way of cyclically smoothing, and that the idea is also useful for other measures including quality, not just value, but all that is a longer story ...
Re Appreciate (LON:APP) part of the attraction for me is it is a hedge against interest rate rises. In the last financial year they said in the notes section of the results that a 0.5% rise in interest rates equates to an extra £846k PBT (about a 10% uplift in profits when annualised) due to the levels of cash they hold at any one time. If the BoE rate rises to 3% as predicted then you could be looking at a c.30%+ increase in profits alone if rates remain at that level. The share is also on a low p/e and high divi. Lots to like, although the quality of the business is low so it's not a long-term hold for me, and it has gone up this year unlike most shares!
But what else would a rise in inflation and interest rates mean for Appreciate (LON:APP) ? Wouldn't inflation squeeze margins? Wouldn't the ensuing economic slow down hit both corporate and consumer gifting? If there is a benefit, wouldn't Appreciate's competitors be gaining the same benefit and see the opportunity to gain market share by reducing prices?
I wouldn't take a statement like their's at face value. It wont be that simple. I can see the basic logic of what you suggest, but at the same time, why go for something cyclical like Appreciate, when the same logic (interest income from cash advances) would apply equally to something less cyclical like an insurance company? I guess you'll stick with Appreciate anyway, so I hope it works out for you.
"It does make me question the overall business model though - in British pubs, people are generally too stand-offish to mingle, and all too often you see people sitting on their own, looking miserable. You can do that on a park bench much cheaper, if you don’t mind being mistaken for a tramp. So why pay £6.50 for a pint?"
I loved this comment in your report Paul. I have found myself thinking about this a lot this year as I quit my job in April and travelled over to Portugal to walk the Camino de Santiago and have had to be frugal! The culture in Portugal, Spain, France and Italy is much more social, inclusive and revolves around good quality (seasonal and locally sourced) food at a very good price. I am often surprised in Europe that food is so reasonably priced - for example, a real coffee is €1 in Portugal (not the soup sized latte's we have here in the UK!) and quite often you will be given a free cake to go with it. A cold beer or glass of wine is about €1.50 and again you may be given some olives or nuts as a side (for free!) - People don't need to be completely hammered to talk to each other and the bars and cafe's have a real community spirit. I was going into regular supermarkets (both in Portugal and Spain) buying incredible fresh bread (not reheated and sold as freshly baked as in the UK) and then walking over to the cheese and meat counter and asking if they could slice me a selection of cheeses and meats - cut open the bread and make me a baguette sandwich. Not one time was I told that they couldn't do this and in one supermarket they even recommended me a certain wine to match the cheeses that they had selected! All of this cost less than about €2.50!! Can you imagine if I asked them to do this in my local Tesco!? The quality of the food is off the scale and people seem to be a lot more knowledgeable and passionate about it. The same baguette here in the UK would be sold as a "gourmet sandwich" and would cost three times the price! I believe that our food and drink culture has become closer to the USA than continental Europe. i.e. we want fast, easy to prepare food and are not bothered about the quality but essentially we have got used to being completely ripped off and paying extortionate prices for sub standard (and measly portions) - When I have been in the countries mentioned, I don't think twice about having food out because I know it won't cost a fortune and I will get a good friendly and welcoming service and fresh, simple but delicious food. Why would I buy a G&T in a pub for £7 when I can buy a can of G&T in the supermarket for £1.50 and enjoy it in the local park or by the river? Something has to change!
Great post .... I totally agree. I miss my days travelling Europe selling Scottish seafood to European Supermarkets. Happy days.
Hi Graham
Jarvis Securities (LON:JIM) provide two interest related numbers in their FY reports, Gross Interest, and Cash Under Administration. The former is expressed in £, the latter on a scale that the company keeps to itself.
In 2012, GI was £2.8m and CuA was 0.8, giving a ratio of 3.5. This has dwindled progressively in subsequent years such that in 2021, GI was £4.5m and CuA was 3.6 giving a ratio of 1.25, reflecting the fact they are now achieving a much lower interest rate nmargin.
In 2012 the base rate was 0.5%, as per https://www.bankofengland.co.u...
Obviously the multi-year splurge of QE has not helped, but with rising interest rates and quantative tightening (at the margins), were this ratio to increase slightly, say to 2, then GI would increase quite sharply to say £7.2m.
Any thoughts how GI/CuA might progress going forward would certainly be of interest.
Cheers, Martin
Jarvis Securities (LON:JIM) (no position)
Hi Martin
I'm flagging so will attempt to keep this short.
I've been doing a lot of work on Jarvis Securities (LON:JIM) today and thought I'd find a lot to like.
However, I'm more cautious now and feel that there's more short-term risk than I expected.
Some thoughts:
https://www.stockopedia.com/co...
The Year End CAU figures below won't be 100% exact, but they'll be pretty accurate.
The interim CAU numbers are completely accurate.
Check out the concerning CAU drop from £382m (end of 2021) to £330m (end of June 2022).
For many years now that was all we needed to be aware of; there was no money to pass onto the client.
But I think 2022 is the year that changes.
I found this snippet in the x-o.co.uk T&C's:
"Interest accrued on sterling Account Money not immediately committed for investment shall be calculated monthly at 1% below the published HSBC standard current account rate."
The current HSBC rate for their Standard account is 1%.
So the client currently gets 0% on their cash held by the Jarvis.
But I imagine this will go up soon and I don't think the analysts are accounting for it.
I'm personally assuming HSBC increase their Standard Account interest to 2.0% by the end of the year, which I roughly equate to 1.5% on average for H2.
This means 0.5% will be paid out to clients = an additional cost of £800k in the Jarvis Securities (LON:JIM) accounts.
Note that the interest payment for clients is included within Administration Expenses, i.e. it is not netted off from the Interest Income within revenue, which is what Hargreaves Lansdown (LON:HL.) do.
---
I personally think the share price is far too low as I'm modelling a PBT of £6.7m for FY22 (a "weak year"), which seems like excellent value for a company with an EV of c£65m.
But I fear that if I'm correct on the client interest fees not being accounted for by the analysts, then there's more damage to come in these fragile markets.
Cheers
A
Spanish copper miner LON:ATYM is falling heavily today after a Q2 production update (3 months to 30 June 2022) and a FY profit warning. I think the drivers provide some useful insights as to the nuances and dynamics (best not call it transitory) nature of inflation.
Realised copper selling price fell to $4.32lb in Q2 from $4.42lb in Q1. Slightly above $4.27lb realised in Q2 2021 but starting to reflect a huge round trip with copper now trading at around $3.30lb having fallen 30% in 3 months. It begs the question, when will these commodity price falls be reflected in the inflation numbers?
The second part of the profit warning comes from cost increases (revised upwards by 5% to 10%) driven by “..electricity, explosives, diesel, grinding media and lime, as well as ocean freight rate”.
Interesting to hear ocean freight rates still elevated, is there a read across?
A lesson here for UK energy markets?
Electricity costs fell from EUR500/MWh in March to EUR180/MWh in Q2 but compared to EUR50/MWh in 2021. Driving the drop is Government changes to the price setting mechanism which like the UK sets the price based on the highest cost producer. This supported investments in renewables with hydro the marginal provider, however, this switched to gas due to the Ukraine war. Spain’s electricity generation capacity is dominated by renewables (only 10% from natural gas/coal) so it didn’t make sense to cripple the economy by exacerbating the impact of imported European gas.
Given the UK relies on gas imports for only a portion of its energy needs, it strikes me as odd that the Government is unable to protect our economy more by changing how prices are set in the UK ie away from marginal provider costs – maybe I’ve missed something.
Thirdly, FY22 production targets have fallen from 54,000-56,000 tonnes from 52,000-54,000. This is largely a consequence of local transport sector workers striking over the cost of living crisis….sound familiar?
Finally, the impact of FX, could this be a profit saviour? ATYM sells in USD but mostly incurs costs and reports profits in EUR. With EUR/USD around 1.00 this could both boost margins and cash flows, albeit on reduced output.
Critical for me though is that management has little control over many of these profit drivers. In summary, I’ve relearned a lesson from Warren Buffett about investing in miners…investing success is largely at the whim of market pricing and the nuances of a volatile inflation environment. Management and operational capability seems almost secondary.
I find it amusing that there was somebody commenting here yesterday that mining & resource companies such as this are too risky even for 'experienced' investors.
It's useful to keep in mind the performance of some of the popular retail stocks, including Joules (LON:JOUL) (from 300p to 22p in just 1y), Boohoo (LON:BOO), ASOS (LON:ASC),...
All stocks are risky...
I chuckled this morning because even the brokers can't seem to get the mining stocks right, last week or so they were raising them on mass, today they are cutting them....will stick with what I know, understand, and can work out for myself.
In case the message was lost in translation as some seem to think. Atalaya Mining (LON:ATYM) is a superb company, paying an excellent dividend with a rock-solid balance sheet which is net cash, selling at a good valuation. So is the other company that was discussed yesterday.
It should be blindingly obvious that these are cyclical companies. So if the underlying commodity starts dropping fast, it might be a good time to review your investment instead of mindlessly averaging down a losing position.
It is wrong to tar every company in a sector with the same brush and to ignore them just because there are other companies in the same sector that have (historically) had a bad reputation. You will find highly speculative, junk companies in almost every sector. They're not restricted to the resource sector. I'm definitely not suggesting that Stocko start to review every resource company. But perhaps, it is worth considering whether or not some resource companies, fitting a tight set of rules might warrant an occasional mention, considering that there are some of us paying close to a thousand pounds annually for our subscription...
Somebody forgot to tell the market! Atalaya Mining (LON:ATYM) down 13.7% today!
Unbound (LON:UBG) should I stay or should I go now?
Unbound (LON:UBG) SP is on a continuous slide with no bottom in sight. The SP has reached my stop loss but I have reservations about selling. The market cap is now just £10M. According to Stockopedia, sales are forecast to be £60M and EPS of 3.95p for 2023 but how reliable are these figures?
Looking back at 2022 figures the Stockopedia figures don't make sense to me. An EPS of 111p from total revenue of £55.4M dropping to 3.95p from £60.6M.
*** Whilst writing this I've looked at the balance sheet and found that there is a decimal place missing from all of the past EPS shown on the main stock-report screen. The EPS for 2022 was 1.11p 2021 was 1.73p and so on. This now makes sense. ***
Looking at the balance sheet it does appear that the Book value for 2022 is correct so currently trading at 0.43 price to tang book (which is a reason to hold or average down)
Looking forward. An EPS of 3.95 for 2023 and 8.7 for 2024 would be good but are these realistic? It would help if the management would tell us some recent sales figures rather than simply saying in-line with expectations. What expectations? Why not just give some sales figures? If they are talking about the above forecast then it's another reason to hold or buy more.
We also know that Shoe Zone (LON:SHOE) sales are going well but is the same true at Unbound (LON:UBG) ? It would be so refreshing to know!
I don't see the point in Unbound (LON:UBG) repeatedly telling us that the market is big and they have lots of email addresses. In fact, the more often I read this pitch (without any supporting sales figures) the more suspicious I become. I don't mind investing for jam tomorrow but it needs to be backed up by some real sales data today.
I'm at the point where I feel I might be throwing in the towel at the bottom so I am reluctant to sell and yet I've reached a stop loss and the management aren't giving me anything to work with. I invested in an established brand with a strong customer base, good sales and growth potential. It would be good to read something that confirms I haven't got this wrong.
I have a lot of sympathy with you as I find myself in the same place and without answers it is a rock and a hard place at the moment. To try and ease my concerns I needed some casual shoes so I ordered a couple of pairs from them off their website. The little solace I can give is they are good shoes and they arrived next day. It seems to be a robust offering. I too have decided that it is too late to sell.
Wetherspoon is one I am looking at too at the moment. I live in Cambridge and went for a drink with a friend the other evening. First pint £6.50, as I am both middle class and from Yorkshire I found myself conflicted. A decision to frequent Wetherspoons was made and I got a pint of Doom Bar (my personal favourite) and a packet of Cheese and Onion crisps (Walkers) for £2.04!!!! Amazing. Not particularly the quality (which was ok) but the price. It seems to me it wouldn't be unreasonable to raise the price by a £1 which would more than cover inflation (thats the middle class bit) and I would be amazed if that damaged many of their clientele who seemed to be shovelling it down their necks. I then went into Revolution which for a 58 year old was a humbling thing to do. It was heaving with lots of young ladies shovelling cocktails down at a tenner a time. As I hold some that made me very happy but I won't be going back although I doubt Rob Pitcher cares too much about that. Decided I am more of a Tim Martin sort of a guy. A good moan never hurt anyone!!
Hi Camtab. I'm a bit surprised that you won't be going back to Revolution. If I went there and held some young ladies that made me very happy, then I would probably be there every night! (Yes I do know what you really meant, but I was unable to stop myself)
I took my two lads to the Wetherspoons in Tonbridge early yesterday evening for a cheap and quick post-school pre-rugby training dinner. The place was packed - not just with old men but youngsters too, male and female, well dressed, meeting for dinner and drinks. Lots of people were eating. It was well-staffed and the outdoor space (recently renovated) was very nice. The food was decent (2x paninis and chips, scampi and chips and a curry with 3 large drinks came to £20) and arrived quickly.
My feeling is that this Wetherspoon (at least) nowadays appears to have a new clientele: younger, employed, both sexes - it occurred to me that people who would've otherwise gone elsewhere are now looking to save a few quid but still go out and socialise. When I last visited, pre-covid, I'd say that 80%+ of the clientele were men over the age of 60. If Wetherspoons can emulate this 'experience' countrywide, then they may well be on to something.
I don't hold but am considering after last night's experience. I'll check out the Sevenoak's site next.
I really like JDW and how they have revived many old buildings as interesting pubs. But I have to say they are their own worst enemies...
Pricing: it's great to be cheap but when your beer is over £2 cheaper per pint than local competition, I would suggest you are leaving a chunk of profit on the table.
Table service for drinks - the Spoons app probably helped them during covid, but having table service with rock bottom pricing makes no sense.
Drinks product range is huge - our smallish local Spoons offers 6 draught ales - before you get to all the draught lagers, ciders etc - this is too many and the beer quality suffers as a result.
Our local further suffers from having no one who really likes or understands ale so the beer choice and quality are highly variable. But I do go in because I am a cheapskate who loves winding up his London dwelling offspring that I only pay £2.10 a pint....
Jack Hughes, I am surprised at your comment about Wetherspoons' beer quality. Real Ale obviously needs the most care and attention and there always seem to be plenty of Wetherspoon pub entries in every edition of the CAMRA Real Ale Guide (the ale drinker's equivalent of the Michelin Guide).
Hi Camtab, re £JDW Wetherspoon, seems you have stolen my identity! I agree with everything you say. I live in Tameside, Grtr Manchester. Wetherspoon prices are ridiculously low, and the quality of both food and drink perfectly acceptable to me - making exceptional value for money. But I will not buy any shares until they increase their prices by AT LEAST 20%. For just £1.20 you can spend as long as you want sipping (or even guzzling) coffee or hot chocolate. Cheaper than staying at home, heating (or cooling) the house. Can't fault the beers - drinks for every palate!
Sorry Camtab, I should have said Jack Hughes!
Not being a fan of Tim Martin I feel conflicted going into a Wetherspoons, never mind investing. That said, I went for a couple of beers and meal in the one in St Pancras on way to the Champions League Final debacle (but that's another story).
Real Ale was excellent and incredibly cheap for London and the meal was very good for what it was and what it cost. The place was very busy but what I really liked was my son ordering drinks and food on his mobile so not even needing to queue at the bar.
Hello Revs. Yes re Unbound (LON:UBG) it is really painful isnt it? I baled out in the 30s because the forward figures are just unrealistic IMHO.
I have just posted to Stocko asking how can the StockRank be in the 80s which is just implausible!!!
mt is not as if My wife and I arent fans and long term supporters of Hotter - both bought some more just before Christmas...but the Unbound (LON:UBG) concept which was rolled out to us recently is not IMHO gong to cut the mustard. OK, it doesn't have some of the issues which have contributed to bringing Joules (LON:JOUL) to its knees, but I have my doubts about how the offering from say Rohan which is one the best additions to the 'UBG range' will be handled.
Rohan has its own website and also can be bought through other sites via eg Amazon. On the Rohan site they are offering 40% discounts. Will they follow through onto the Unbound (LON:UBG) site? I think not. Other brands quoted in the 'new range' also have their own websites. Ditto re follow through. An administrative nightmare, and how to make enemies by comparisons without trying!
No, reluctantly I have bowed out. I wish them well but .....If anyone an provide the answers that will take them back to when I first added them to a watchlist (as it happens 2.2.22) the SP has fallen over 60%. That's serious.
The same data for Joules (LON:JOUL) was 28.11.21 and he SP % drop is 89%. As we know, that's disastrous.
Oh dear, oh dear, dear, dear,
Every time in the last 12 months I have lowered a stop loss for one reason or another, it has still ended up stopping out.
With so many bombed out shares of late I have set a tight max 10% stop loss on the basis that if it goes, its in freefall in recent history and I will gladly wave it goodbye, sleep easy, and buy back in when it settles down.
On the swing side if its showing any sort of upward momentum (even not going down on down days) then am averaging up pretty early, and selling out as it rises to levels that meet the current market conditions (up between 10 and maybe 25%). For now this seems to serve me pretty well, recent examples including Volex (LON:VLX) Photo-Me International (LON:PHTM) Concurrent Technologies (LON:CNC) Argentex (LON:AGFX) CMC Markets (LON:CMCX) Oakley Capital Investments (LON:OCI) H & T (LON:HAT) Tyman (LON:TYMN) Capital (LON:CAPD) . If and when the companies come down again (which they pretty much seem to) am back in again for another go.
I know its more like trading (and frankly its a ball ache) but for now am just trying to get a few gains here and there and preserve my cash and capital for when things settle down, and if this is the bottom then these are all companies i want to hold anyway.
Just my take on the whole thing, for what its worth (not much I would say ;-)
The question that Unbound dodged when Paul asked it is an acid test question
“How many customers on the 4.5 million !!! Claimed database have purchased in the past 12 months “
What is outrageous is the fact they frequently quote the number of 4.5 million database which is clearly ludicrous yet don’t provide a number that is relevant which is active customers .
Any idiot can buy a database and then give a “we have s database of x million” but only active customers are relevant .
Management have shown their true colours by refusing to answer a straightforward question.
Hi planetx,
To be fair to Unbound (LON:UBG) management, they're new to being a listed company, and seem paranoid about not breaching the listing rules by revealing any new information - which is a good thing.
They wracked their brains, then said something like: what we've stated previously is that the database has c.1 million customers on it - i.e. people who have bought something. They didn't say "active customers" though. They elaborated by saying that some are lapsed customers, related to stores which had closed, but are hoped to be re-engaged at the garden centres, if that (successful so far) concept is rolled out, which I think seems likely.
A small placing wouldn't surprise me, to fund the garden centre roll-out, but it wouldn't be much, because they're quite cheap to set up.
Personally I'm happy to stick with UBG. Valuations right now don't necessarily make sense. UBG became a listed company with a completely inappropriate shareholder base, and it seems to be a slow and painful process to switch over to mainly private investors - who generally are put off by a falling share price, understandably, especially for a company that is not known by most investors.
I think there's a bit too much bank debt too which doesn't help.
It'll be interesting to see how this pans out.
Management were far better 1:1 than on webinars, I thought.
I'm inclined to give them a chance, and see what happens, rather than condemn now.
Regards, Paul.
One thought I had Paul which can be used across several companies, e.g. Saga, UNB and any other companys where we have previously argued that the older more affluent market is a safer place to be. I am slightly changing my view on this. With inflation powering away, wages rising I am thinking the older generation not in employ will find their nest eggs being destroyed and therefore they will be more cautious. I recall my Uncle retiring in 1971 on £4000 a year, that didn't last long by 1975. Perhaps. Just a thought.
Yes, good point Camtab. I had a similar experience seeing my Gran's savings from selling her big house in Essex, disappearing to almost nothing, thanks to the ravages of inflation in the mid 70's to late 1980s.
Although there are some signs that inflation might be peaking fairly soon. That's what the Bank of England has said recently apparently, and falling commodities prices reinforce that view.
Regards, Paul.
Enjoying the discussion on todays SCVR. It’s better when there are more comments.
The debate re £UBG highlights why the SP is falling Which may or may not be an opportunity (isn’t it always the case? Potential returns have risk or uncertainty.)
Re Portmeirion (LON:PMP) - Harsh reaction to a decent trading update this morning (price down 13% at 358p as I write). Sales are better than I expected in H1 at +5% vs LY. So effectively flat in volume/real value terms despite a big slug of orders coming in at the very end of last year and talk of retailers de-stocking in H1 - hardly a surprise!
Self help measures already in place like margin enhancing factory automation and critically, much improved digital DTC selling of its stable of lon-established brands. This offers better margins AND a stronger consumer offers - exclusives, gift set extensions etc. The ultimate consumer base is likely a bit older/richer than average and so will have likely have savings/rising equity?
Certainly, improving operations in key dollar-denominated markets of the US/Candada & S Korea will be fully in place for H2, container costs are now falling and energy is fully hedged (for this year).
So forecast three times covered dividend of nearly 5% is well protected and debt is modest with declared CAPEX peaking. Discretionary consumer companies are not fashionable at the moment - hence 35% price drop since before Christmas but, on a 1-2 year basis and with 'blood on the streets', some are looking very cheap now.
IMHO, this is one. (I hold)
Portmeirion (LON:PMP) (I hold) H1 trading update
Mcap £58m SP 410p
Reasonably robust trading update from Portmeirion this morning with H1 Revenues expected to be at least £45m - 5% up on last years £43.1m which was itself a record.
No other figures and all the usual warnings on materials prices, cost pressures, supply disruption in the brief statement.
Revenue seem to have accelerated since May when the first 4 months were +2% - which may reflect the increase in prices rather than an increase in volume. Particularly since the commentary refers to retailers 'de-stocking'.
No comment on gross margin which at 4 months was +0.5% indicating that Portmeirion's brands have an element of price-setting ability? With significant H2 seasonal weighting in both revenue and margins its a mistake to attempt to draw any conclusions from H1 - and in this year just about anything could happen and probably will - the H2 outlook statement in the interims (normally September) will be the first glimpse into order levels for H2, though these were said to be 'healthy' at the AGM.
In H2 Portmerion may benefit from its increasing international presence. The UK is now less than 1/3 of revenue and North America is larger by over 40% in sales with South Korea (traditionally a strong market) and the rest of the world also growing much more strongly than the UK.
Portmeirion has also been investing heavily in the UK in manufacturing efficiencies, reducing energy usage, logistics and distribution and in its direct on-line sales channel. The addition of drop-ship capability to their warehousing is an interesting move - allowing them to support on-line etailers alongside their own direct sales channel whilst Portmeirion gain margin and will be interesting to see how it progresses. Margin gains from these investments will be offset against the cost pressures - but with price setting ability Portmeirion is in a better position than many UK based manufacturers in the next few months?
Management have started to get a reputation for being conservative in their forecasting. Anything might well happen in the next few months - but likely most likely Portmeirion is well set for H2. The shareprice seems to have found a floor recently and trading at 6.6x forecast profits it looks cheap - but then I thought that when it was at 8x and before that at 9x.
I'd love to buy a few more - if only I wasn't surrounded by so many opportunities. And if only they weren't all going to be cheaper tomorrow!
cheers
Mark
Yes, Portmeirion (LON:PMP) sales at +5% is an improvement on the 2% reported at the AGM only a few weeks ago...and then they said margins had also improved...unlike MPAC (LON:MPAC) where sales improved but margins decreased, hence a profits warning...so Portmeirion (LON:PMP) looking good (I also hold)...
Too high a sound level coming from speech in Bath's King of Wessex for piped music to be of any worth. People go there for a good old natter.
Hi Paul,
Excellent write up on Spoons. Very topical. Thanks
Good Morning Paul & Graham
I was hoping you might be looking at Totally (LON:TLY) this week following year end preliminary results announced on Tuesday. Seemingly a miss on both profit and EPS but on closer inspection I note that the amortisation of acquired contracts reduced the figures by c£2.3M. These relate to Greenbrook (c£2M) and Vocare (c£0.3M). I'm guessing this is another IFRS requirement?
Once adjusted the results look like a tiny miss against Allenby forecasts and a small beat of Canaccord estimates. Revenue increase of 12% and recent contract renewals/extensions of £19.4m are further good news. Cash pile has increased to £15m although this is a bit misleading due to advantageous working capital movements.
Very good presentation yesterday on Investor Meets Company. New £5m facility with NatWest, as yet unused, points to futher aquisitions following the successful purchase of the excellent looking Pioneer during the year for £6.1M.
All in all company tracking in the right direct and, by my reckoning, looking good value. I HOLD
Hi Norfolk,
Yes, I also quite like
Totally (LON:TLY)
Not sure if we'll get time to look at it, there are so many companies reporting at the moment, it's a struggle to keep on top of them, and we do need to prioritise big price movers, up and down.
Regards, Paul.
Ok, thanks for the reply, that's understandable, there's plenty of big movers at the moment! But I am really more interested in your's (or Graham's) understanding of why acquired contracts even need to be amortised? Is this another IFRS clanger?
Wil you cover Tclarke (LON:CTO) please Paul (I hold), I guess this isn't a stock for you though due to low margins, but still, great interims, nice and cheap, forward p/e 6.5x now, net cash, divs 3.5% and well covered, guidance (well, revenue) raised...
Cenkos on Tclarke (LON:CTO):
"The stock has outperformed its peers’ growth over the past 12-18 months but the rating remains very undemanding indeed; on our conservatively estimated FY23E an EV/EBITDA of 3.5x, a PE of 6.5x, yield 3.5% (over 4x covered), FCF yield over 10% and a net ROIC of 16.5% with zero debt/gearing."
Cracking numbers. Technology sector now the biggest revenue generator and should be the main focus on growth going forwards. Very pleased with events here.
DSW Capital (LON:DSW) might be worth one of you looking at with FY results out today and an investor presentation at 1pm. It was an IPO in December 2021 so these are the maiden listed results of this franchised professional services company. They are profitable excluding IPO costs, have a strong balance sheet and have announced a final dividend of 4.22p (~3.5%) - I believe the dividend policy is one third interims and two thirds final. It is a micro cap though with low liquidity most days, so care needed.
[edit] McBride (LON:MCB) says exploring funding options.
Morning all,
Record first half numbers from £TM17. Acquisitions have bedded in well, a solid in line update. Fairly happy with that in these volatile times!
I hold.
Agreed, and still buying and could be for a few years while the market disagrees with my valuation. Fear appears to be the very dominant market sentiment at the moment and yet everyone knows that when this is the case, this is the right time to buy. There are those that understand that they cannot time the market and there are those that don't know they cannot time the market. https://edition.cnn.com/market...
Yes good update from Team17 (LON:TM17) (I hold).
Any thoughts on tinyBuild (LON:TBLD) , which I also think looks a good business at a knock down price?
If that's a question for me, I have no knowledge of this company so I have no answer.
Who wrote the Stockopedia profile text for tinyBuild (LON:TBLD) I wonder?
"It secures access to Internet protocol (IP) and partners with developers
to establish a platform on which to build multi-game and multimedia
franchises"
I think that must have started just saying IP, meaning intellectual property, and someone 'helpfully' expanded the acronym without realising that they had created nonsense.
Jarvis Securities (LON:JIM)
No surprise that their results are down on last year. I've been sitting on my hands a lot. Do you have any comment to add Graham?
RE: Jarvis Securities (LON:JIM)
EPS roughly matched the second half of last year, so this is about what I'd have expected.
They earned £4.5 million interest on deposits last full FY. Annoyingly they don't break this out in the interims (they never do), but short term interest rates have gone up about a perecent since last year so there will be a boost in the second half as funds are moved onto higher yields.
I'd be happy to add at lower levels here, there's no solvency risk, but in this market I really want cheap, another warning at the FY is entirely possible as activity drops off a cliff (it always does in the latter stages of bear markets).
timarr
Yes, I have a short section added. Best wishes. G
Polar Capital Holdings (LON:POLR) announce AUM down 14% over the last quarter. It's grim out there
Polar Capital Holdings (LON:POLR) That was fully expected given market sell off, especially in tech where they are heavy. Unfortunately a 14% fall in AUM will lead to a much higher than 14% in earnings because of operational gearing. Prefer alternative asset managers where AUM less correlated to markets, see excellent update yesterday from Gresham House (LON:GHE)