Small Cap Value Report (Thu 17 Aug 2023) - ITM, KCT, RNK, TRMR, ESP

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Quick Comments/Summaries
ITM Power (LON:ITM) - 87p (pre market) £537m - FY 4/2023 Prelims - Paul - RED
Not suitable for a value report, as this is a very ambitious blue sky project, burning prodigious amounts of cash, and massively loss-making.
Just for the record though, FY 4/2023 revenues were £5.2m (significantly ahead of £2m guidance LOL!), with an EBITDA loss of £(94)m (£85-95m range guided).
When’s it going to run out of cash then? Actually, not any time soon, it looks well-funded. There was £283m cash left at 4/2023 (down from £366m a year earlier).
Guidance for FY 4/2024 is: revenues £10-18m, reduced EBITDA loss of £(45)m to £(55)m. Cash remaining at 4/2024 forecast to be £175-200m.
Balance sheet - note that inventories are very high at £59m, several years’ revenues. NTAV looks healthy at £285m.
Paul’s opinion - I just wanted to get some basic info into the system here. It’s clearly a speculative project, not a viable business at this stage. ITM claims to be “state of the art”, and “globally leading” in developing green hydrogen fuel. I wish them well, but it’s not something we can possibly assess here.
All I would say is that in the 25 years I’ve been investing, practically all blue sky shares like this fail to deliver what they set out to deliver. So unless you’re an expert in the tech, why get involved? That said, with plenty of cash in the bank, who knows what might happen, investors might get lucky if the tech really is globally leading, and manages to remain so.
Kin and Carta (LON:KCT) - up 14% to 72.5p - £129m - Trading Update - Paul - AMBER/RED
A surprisingly positive trading update today for FY 7/2023, given that it had previously warned on profit. Cost-cutting seems to have driven a revival in H2 profits, a seemingly positive development. Although there are such huge adjustments in KCT accounts, it's difficult to know what's really going on. I note that it spends multiple millions buying shares for the employee trust, but doesn't pay shareholders anything in divis! Weak balance sheet with negative NTAV.
Rank (LON:RNK) - up 2% to 91p (£426m) - Final Results (in line) - Graham - GREEN
I’ve decided to give this casino/bingo hall stock the green light as it reports improving trends in cost stabilisation. Customers gradually return although high net worth travellers to London remain scarce. Whenever boom times return, Rank should once again do extremely well.
Tremor International (LON:TRMR) - Down 30% to 178p (£255m) - Q2 & H1 Results - Paul - RED
A nasty profit warning today, with guidance lowered a lot. Accounts are so over-complicated that it's difficult to decide whether it's profitable at all! Strange balance sheet with a large cash pile, half offset by borrowings. Overly generous share-based payments for management (mopped up by share buybacks), and repeat Director selling are further red flags. I gave it the benefit of the doubt when the PER looked really cheap, but that support has now gone. So it has to be RED I'm afraid.
Empiric Student Property (LON:ESP) - up 4% to 89.1p (£537m) - Interim Results (in line) - Graham - GREEN
This REIT provides purpose-built student accommodation. The Board is “comfortable with all earlier guidance” after posting strong H1 numbers. I give it the thumbs up at this discounted valuation thanks to its strong financial position, full occupancy and 9% rent increases
Paul's Section:
Kin and Carta (LON:KCT)
Up 14% to 72.5p (£129m) - Trading Update - Paul - AMBER/RED
Kin and Carta plc ("Kin + Carta" or the "Company"), the global digital transformation ("DX") consultancy, provides a trading update covering the year ending 31 July 2023 ("FY23").
Revenue - Q4 in line with exps, and FY 7/2023 also in line, at £192m, flat vs LY.
H1 results show revenue of £98.7m, so H2 is lower, at £93.3m.
Profitability sounds ahead of expectations, due to cost-cutting, that’s how I interpret this bit -
FY23 adjusted operating profit is expected to be £17.9 - £18.4 million, 10.5% - 14.0% ahead of market expectations, reflecting a realigned operating model with a lower cost base and improved operational efficiencies.
The resulting adjusted operating profit margin is expected to be 9.3% - 9.6% and adjusted EBITDA margins are expected to be 11.7% - 12.0%.
Net debt remains modest relative to adjusted EBITDA and is expected to be c. £20 million at 31 July 2023.
H1 saw adj operating profit of £7.5m, so by implication H2 was at least £10.4m, a big improvement, despite revenues being down. Clearly there must have been a lot of costs stripped out, but that’s a good H2 performance - strange, considering it warned on profit on 26 May.
Outlook - sounds mixed, I’d say -
The Company enters FY24 with a healthy backlog and expects further sequential net revenue growth in Q1. Although client engagement levels are strong, it is clear that market headwinds remain across the sector and we continue to manage the business with the necessary caution…
While macro challenges remain across the sector, I am encouraged by the start to Q1 underpinned by a solid foundation of enterprise clients."
Broker updates - there aren’t any available, which limits what I can achieve interpreting today’s update. The only indication is the StockReport disclosing that broker consensus EPS forecast for FY 7/2023 fell from about 8.3p, to 6.1p in June, after the 26 May profit warning.
H1 actual was 3.06p, so the forecast of 6.1p assumes H2 is roughly flat vs H1. Yet as I calculated above, it seems that cost-cutting caused H2 to be well ahead of H1 profits. Hence I’m deducing that maybe the full year might be something like 7.0p to 7.5p? That’s looking a favourable move, and would put the PER on an undemanding c.8.8x (at 64p per share). Updating that for today's +14% share price rise to 72.5p, we now get a PER of 10.0x - which is probably high enough I'd say.
That said, based on its past performance, loads of adjustments in the accounts, and a weak balance sheet, personally I wouldn’t be willing to pay anything more than a mid-single digit PER anyway.
Net debt of c.£20m indicated for 31 July 2023 is called “modest”, but seems to be up from £11.8m net bank debt reported in the H1 results, as at 31 Jan 2023. But it’s not clear if today’s £20m figure is calculated on the same basis (excl. leases). If we assume it is probably reported on the same basis, then net debt is up c.£8m in 6 months. That might be due to paying the £12m contingent consideration shown within current liabilities on the last balance sheet, at a guess? I need to see the full figures, which are out in Oct 2023. Snapshots in trading updates can be misleading I find, for some companies.
Balance sheet - when last reported, was weak. NAV of £84m is more than all intangibles, so taking off that £93m, gives a negative NTAV of £(9)m. Also a pension surplus of £14m would need to come off too, taking NTAV further into the red.
Paul’s opinion - we don’t think much of this share. However, today’s update has seemingly sprung a positive surprise, with H2 being better than expected apparently (but I’d want to see the full numbers in Oct to be sure, as KCT puts through large adjustments).
There are all sorts of funnies in the previous accounts, and I’ve just spotted very large purchases of own shares for the employee benefit trust in previous cashflow statements - £8.4m was spent buying KCT shares just in H1 of this year! That is highly material, so needs careful scrutiny. Bear in mind shareholders don’t get any divis, yet there seems to be plenty of cash available to buy shares for the employee trust (presumably to be given away in awards?) .I recall spotting a similar thing with one of the recruitment companies, and it was a form of hidden employee remuneration, so it's well worth checking every company's cashflow statement for this type of thing that might not appear on the P&L. After all, it's more important where the cash is going, than what a theoretical profit is!
For now I’ll stick with my RED view on this share, although maybe AMBER/RED would be fairer, given a positive surprise today? Yes, let’s go with AMBER/RED - denoting that I don’t like the company fundamentals (the RED bit), but it has issued better than expected news today (AMBER bit).
It would be so much easier if KCT would arrange to use a broker that gets some research notes out to private investors. We create market liquidity, and thereby set the share price, so ignoring us is such an own goal for any small cap, and it makes my job much harder, trying to make sense of the snippets of information they put into trading updates.
I see the market has reacted positively so far, with the share price up 13% to 72p at 08:52, but only 340k shares printed as traded so far. It will be interesting to see if that rise sticks, or whether sellers might snuff it out at a later stage, which is happening quite a lot at the moment, due to institutions needing to sell small caps widely (except the ones that are performing the best), to meet redemptions.
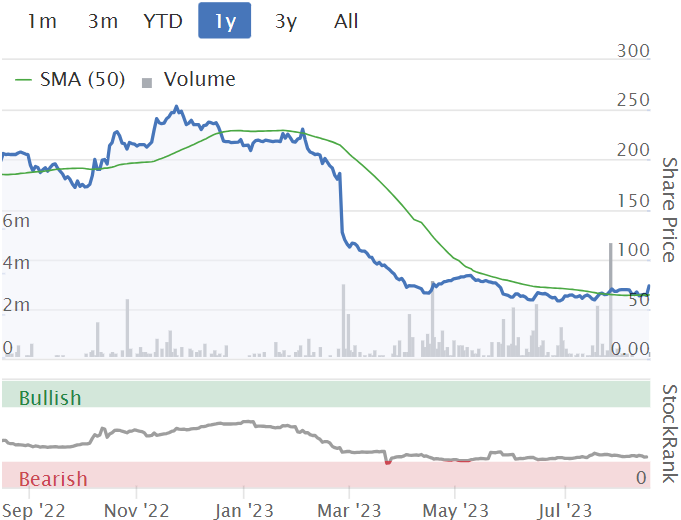
Looking at the chart, I imagine some chart followers might be sniffing around here, as it seems to have formed a base, and with a positive update today, could build on this, for traders anyway -
.
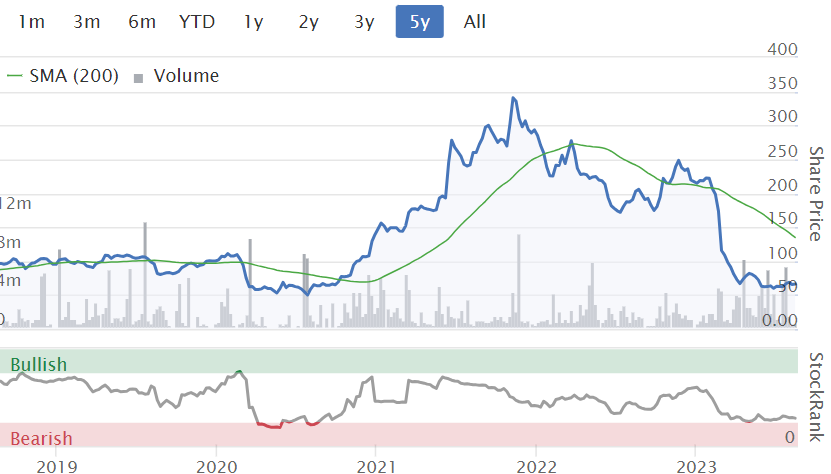
Zooming further out, KCT has been a boom & bust share over the last 5 years - is it just a bad company that has squandered money on poor acquisitions, or could the tide be turning? I don't know, but don't yet see enough evidence to want to take an interest, but will keep an open mind, and we have moved from RED to AMBER/RED today, so that's a step in the right direction!
Tremor International (LON:TRMR)
Down 30% to 178p (£255m) - Q2 & H1 Results - Paul - RED
Commiserations to shareholders in this digital advertising group, who have collectively lost £109m this morning, very painful.
To get me up to speed, looking back at our previous notes this year -
21/2/2023 - 323p - AMBER - SKY reported that TRMR was putting itself up for sale. Paul’s view: very low valuation, but difficult to assess, I don’t like the sector, and excess share options & repeat Director selling further put me off.
31/5/2023 - 280p - AMBER - Q1 results. Again looks very cheap on low PER. OK Bal Sht. Big buybacks. Could be cheap if profits are sustainable. I dislike sector, as online marketing companies often disappoint.
So I can see why people bought this share, as it looked cheap on a fwd PER basis all the way down. Although it was also dripping with bear points as noted above, and also that divis stopped in 2018. Why also have pots of cash on the balance sheet, combined with borrowings?
Tremor International Ltd. (AIM/NASDAQ: TRMR) ("Tremor" or the "Company"), a global leader in data-driven video and Connected TV ("CTV") advertising technology, offering a unified platform that enables advertisers to optimize campaigns and media companies to maximize inventory yield, announced today its financial and operating results for the three and six months ended June 30, 2023.
What a nightmare this statement is! I’d be surprised if many investors in this really understand what it does, and how it (supposedly) makes money. Does it make money at all? The figures are so confusing, with an emphasis on EBITDA. Good quality companies have simple, clear accounts, where you can obviously see how they make money and pay divis. This is the opposite.
Cutting through all the background noise, on any measure, profits have sharply deteriorated in H1 - adj EBITDA is down from $78m H1 LY, to $30m H1 this year.
There are so many adjustments, that this $30m EBITDA turns into a loss of $(21)m at the total comprehensive level. That includes a large $13.5m stock-based compensation charge in H1, which was even worse last year H1 at $31m - so I think it’s pretty clear that this company is not being run for the benefit of outside shareholders!
Cash/debt - this bit below looks peculiar to me. Debt is a lot more expensive now, so surely in uncertain times, the company should be paying off the debt with the cash pile? That’s assuming the cash is real of course -
Liquidity Resources: As of June 30, 2023, the Company had net cash of $94.2 million, consisting of cash and cash equivalents of $195.0 million, offset by $100.0 million in principal long-term debt and $0.8 million of capital leases (consisting entirely of the Company's server leases), as well as $80 million undrawn on its revolving credit facility. The Company intends to leverage its considerable net cash reserves to fund its existing operations and to support future strategic investments and initiatives, including potential future share repurchase programs and acquisitions.
Outlook - a large reduction in guidance, for various reasons, boiling down to: advertisers are spending less -
Full year 2023 Adjusted EBITDA in a range of approximately $85 - $90 million compared to previous expectations for a range of approximately $140 - $145 million
Paul’s opinion - I’ve given TRMR the benefit of the doubt in the past, seeing it as AMBER, mainly because of the low PER. Now that support has gone, with deep cuts to broker forecasts today, all I can see is really over-complicated accounts, and lots of red flags. So it’s got to be RED from now on I’m afraid, and probably should have been RED a while ago, as we’ve never liked it here.
This sector is full of companies that find clever ways of exploiting online advertising to make big profits for a while, but then the golden goose can just vanish overnight, when the online giants change the way things work. Maybe TRMR’s goose has flown to pastures new? Mind you, they might find some other way of making money, they’ve reinvented the company in the past, after previous disappointments. Anything could happen in the future, I have no view on that either way.
This share just has almost zero appeal to me, after reading these results. Good luck with it though, to those that decide to persevere with it. Bull points might include - some impressive major shareholders on the list, someone might bid for it in the USA, and trading might recover.
Graham’s Section:
Rank (LON:RNK)
Share price: 91p (+2%)
Market cap: £426 million
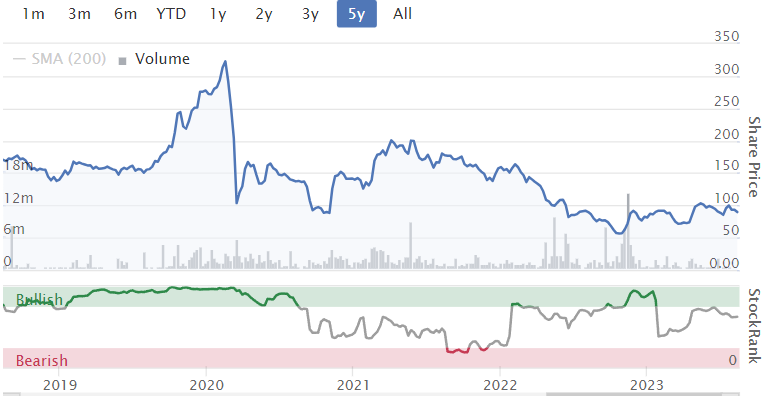
We have full-year results from this casino and bingo hall operator, whose share price (and financial performance) have been greatly affected by the twin challenges of Covid and then the subsequent inflation.
Here are the key points from the results for FY June 2023, which are in line with guidance that was upgraded back in April.
Like-for-like underlying revenues (“net gaming revenues” or NGR) up 7% to £680m.
Like-for-like underlying operating profit £20.3m (last year: £42.5m)
The main reason given for the decline in underlying operating profit is cost inflation. We knew that the cost of keeping the lights on and heating their playing venues, and everything else that goes into running large properties, had increased considerably and would take their toll on these results.
I am however encouraged by the resurgence in revenues seen in H2. At Grosvenor casinos, NGR was up by 4% for the year with a decline in H1 followed by a 15% year-on-year surge in H2.
The Digital products continue to show decent performance, with NGR up 10%.
The statutory results are terrible:
Actual operating loss £110m (last year: operating profit £81m)
Actual pre-tax loss £123m (last year: actual PBT £73m).
The difference between actual operating profit and underlying operating profit is a staggering £130m. This is due to almost £120m of impairment charges, and £8m of closure costs for 16 venues.
Net debt excluding leases is thankfully very low, at just £4m. It has a £100m RCF which it’s hoping to replace with a “longer-term financing package” this year, “when it anticipates securing better financing terms, driven by additional consecutive months of improved trading”.
However, the balance sheet does not offer any tangible asset backing.
Outlook
The outlook statement is very promising: in the opening six weeks of the new financial year, group NGR is up 16%, with the venues (Grosvenor/Mecca) outperforming Digital:
Despite the generally challenging trading conditions, with inflation still running high and the increase in interest rates impacting consumer discretionary expenditure, we expect to see good levels of revenue increase year-on-year and to grow our profitability in 2023/24.
Dividend - no dividend yet, but the Board “expects to recommence dividend payments as soon as circumstances permit”.
CEO comment lays out the long list of external problems faced by the company in recent years, and adds some positivity that they may finally be receding:
"The return of customers to our Grosvenor and Mecca venues continues to pick up and our second half numbers give cause for optimism after a very challenging couple of years. During that time, our UK venues have faced a surge in energy costs, high wage inflation, a tightening in the regulatory environment, the slow return of overseas visitors to London's casinos and the more general pressures on the consumer's discretionary expenditure. However, energy costs have stabilised, inflation appears to now be easing, customers continue to slowly return to both our Grosvenor and our Mecca venues and we now expect to deliver good levels of revenue and profit growth.
Graham’s view
As I’ve noted previously for this stock, it has always priced in some sort of recovery, so it never fell to what I would consider truly “bargain” territory.
At the current £426m valuation, investors clearly expect better days ahead - and I think they are right to.
As noted by the company today, Grosvenor accounts for a significant percentage (43%, they suggest) of the UK’s total casino industry. It can only be a matter of time before Middle Eastern/Asian tourists come back to London again in significant numbers, costs stabilise (the inflation data yesterday was interesting in this regard), and local customers start to feel more confident to spend again.
I’m going to turn positive on this stock today, as I think there is now enough evidence to say that the worst is probably behind it. That’s just a hunch, though - it might be premature. Costs might pick up again. High net worth tourists might be very slow to come back. An unexpected regulatory hurdle might show up. There are many things that can go wrong with a gambling business with physical venues.
However, I think Grosvenor is a trusted name in casinos and that it will thrive again as soon as conditions permit. Rank’s other assets have also performed reasonably well over the years. So I think for patient investors, this could be an interesting stock to hold.
Empiric Student Property (LON:ESP)
Share price: 89.1p (+4%)
Market cap: £537m
Empiric Student Property plc (ticker: ESP), the owner and operator of premium, studio-led student accommodation across the UK, is pleased to report its interim results for the six months ended 30 June 2023.
We last covered this one back in October 2022. The share price hasn’t moved too far since then:
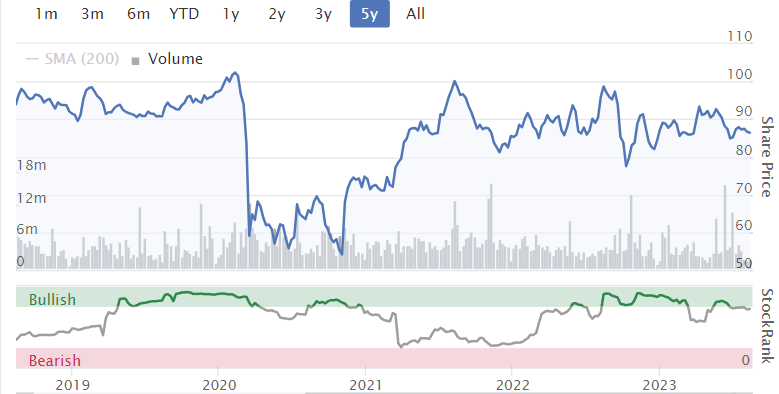
Back then, the company was performing well and was effectively full with 98% occupancy.
That remains the case today - in fact the booking cycle is “significantly ahead” of last year, as its rooms have been booked out faster than ever.
The company has significantly raised rental prices in the face of this very strong demand:
Our accommodation is now effectively full for the forthcoming academic year with occupancy at 98 per cent, a level achieved earlier than ever before. We are confident that like-for-like rental growth of around 9 per cent will now be achieved, significantly ahead of previous guidance.
Few would argue with the claim that there is an “acute undersupply of high quality student accommodation”. As I’ve said before when discussing ESP, I think this might be a sweet spot for investors in the property market, as the supply/demand forces are unique - lots of US, Chinese, Indian and other overseas students. For the coming academic year, 32% of rooms have been sold to Chinese students.
Market outlook - ESP says that purpose-built student accommodation “has continued to defy market trends”, with very large transactions going ahead in 2022 and a growing level of investor appetite in the sector. 2023 has seen less activity so far, but more deals are expected in H2. The student population continues to grow and there is particular growth in the post-graduate sector. ESP has recently started to develop sites exclusively for post-grads.
Financial results
The financial highlights for the first six months of the year are all positive:
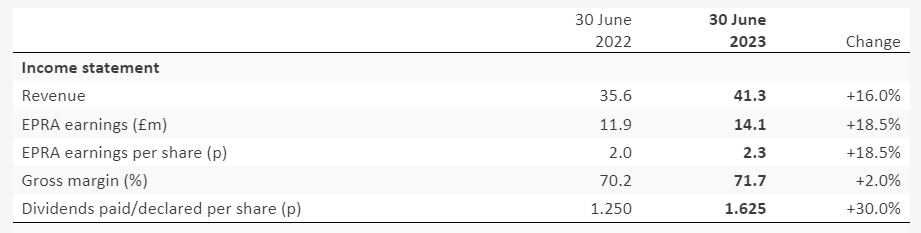
“EPRA earnings” excludes gains in the value of properties, profits on disposals, and other non-core sources of income. It is considered “recurring” and comes in at £14.1m for the latest six-month period.
Balance sheet: The portfolio valuation increased 1% like-for-like, and EPRA net tangible assets per share have risen to 117.3p - a nice premium over the current share price.
Loan to value remains cautious at 30% (the company has a long-term target of 35%), and the cost of debt remains low at 4.3%. Most debt is at fixed rates, and the fixed rate debt has an average term remaining of over 5 years.
Energy hedging is also in place until the end of 2024.
Outlook
The Board remains comfortable with all earlier guidance, including dividend guidance. The Company continues to expect to pay a minimum dividend of 3.25 pence per share for 2023. This will be revisited in the fourth quarter, following the start of the 2023/24 academic year.
Graham’s view
Balance sheet net assets here are £715m (vs. market cap £537m). Net tangible assets are nearly 30p higher than the share price. Why the discount? The company is achieving perfect occupancy and inflation-beating rent increases. Leverage is low and its debt is cheap. And it’s in a niche that protects it from some of the wider issues in the property market. I’m struggling to find any reasons to dislike this share.
We don’t talk about REITs all that often in this report but if I was going to invest in a REIT, this would be at the top of my list for further research. So I’m giving this stock the thumbs up.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Odd reaction to Entain (LON:ENT) today. Basically MGM said they are rolling out their new online platform into the UK and the market seems to have taken fright to that for some bizarre reason. Interestingly Flutter Entertainment (LON:FLTR) hasn’t had the same reaction at all despite facing the same competition.
It’s odd because firstly the BetMGM US and Canada JV between Entain and MGM is for 25 years and is exclusive so it changes nothing there. It’s also a 50/50 so neither party can control events to the detriment of the other. Secondly MGM entering the UK market with their newly acquired tech platform is unlikely to create massive competition anyway as the likes of flutter and Entain have such strong brand presence here I doubt MGM will make much of an inroad. Thirdly Entain is global with many growth opportunities across other entertainment sectors too.
Odd market reaction - could understand it maybe if other sector operators hit the same way as a knee jerk reaction but seems it is stock specific for no reason.
US 10 year and UK 10 year gilts hit a high again today at c4.3% and c4.75% respectively - that's higher than the late October 2022 peaks. That's not a bullish indicator for equities!
In the US July spending was US$497bn versus income of only US$276bn (i.e. 180c spent for every 100c of income) - totally unsustainable. The UK actually looks really good in comparison to that.
Puzzled why Empiric Student Property (LON:ESP) is at such a high valuation.
They're seeing abnormally high occupancy (98%?) so higher than historic average. Good rents too.
But all this only gives an EPRA earnings of 2.3p per share for the half year. x2, and that's 4.6p for the full year.
At an 88.5p share price, that's barely a 5% "net yield" on what is a property investment play. On what is a a cyclical high in terms of occupancy rate.
Why wouldn't I just take my money and stick it in the bank on a one year fixed for 6% instead?
Granted, on an EPRA NAV basis it is trading at a discount. But EPRA NAV is not the same as current market value (if it were to be sold). Granted, they have confirmed that their recent disposals were in line with book value (ie EPRA NAV).
Puzzled.
I hear this comparison a lot now, but cash in bank versus equities give you completely different things. The 6% you get in the bank is fixed and may not last beyond 1 year if rates fall back. The 5% earnings yield you get on Empiric Student Property (LON:ESP) is growing at 9% a year (based on current rental growth) and you also have upside potential, eg from property sales or discount tightening, not to mention the possibility of a bid (there's been quite an fewer in the property space recently).
But the 6% rate is fixed, it won't go down. You can fix for 1 to 3 years at around 6%. Empiric Student Property (LON:ESP) is down 10% in the last year. Yes it could go up but could also go down, if there is a recession or property crash. Look what happened to Watkin Jones (LON:WJG), down 78% over last year.
Watkin Jones (LON:WJG) are a developer and funding has dried up - effectively killing the business model for now. Empiric Student Property (LON:ESP) are essentially a landlord and much lower risk. Same sector but very different risk profile.
Tories have been a disaster as 'austerity' isn't a viable strategy for a developed econ. We're 15 years into this failed meme...it sounds good as its what individuals must do (cut their cloth to their means etc)...but its suicide for countries. See UK AND Europe (ie set aside brexit beef bs)
I'm a fan of high immigration...but want economic migrants not asylum seekers (pity for them for sure but former preferred). I've read that UK may 10-15% more people in it than officially stated as a result of poor recording ability. This sort of mismatch would lead to pressure on services funded for less. It probably would also mean that UK has much larger 'black economy' than is thought.
Sorry, this is not the right place for this kind of post. Try Twitter maybe?
Agreed - no specific look-across to sectors or small cap companies
Ok. No worries. I perhaps misread (skimming) the conversations of the day as seemed one of those days...
Thanks mojo, I appreciate your reply.
Best wishes, Paul.
Always easy to say what you don’t like “benefit of hindsight makes a fool a a wise man “ sort of thing
What government would you have proffered ?
if cutting spending was wrong what would you have done ?
How much more immigration would you consider too much another 10 million 20 ?
Would you be worried about social cohesion ?
Don’t think anyone really knows how many people are here illegally would be surprised if it was 10-15% though what was your source for this estimate
Politics instead of being a beauty contest seems to end up picking the least worse option
In recent times has only been one real choice
I've got knock you dead answers obvs...but I couldn't possibly say them now as been hushed ;)
You'll need to fight me on the hellscape that is Twitter
Yeah obvs lol
Have a good day
Thanks mojo for reminding us on the SCVR as although signed up to Twitter (who hasn't?) I never go there, for myself it's any port in a storm.
Ummm, I don't mind being red flagged having carried that shame many times :) ...but Mr/Mrs Post Police should get busy on a lot more of today's comments...and I suggest that my comments have more economic content than many of the other 'political' points (eg a bigger black market has many investment consequences)
Tremor International (LON:TRMR) First things first and the pw this morning was very unwelcome, but not 100% surprising for two reasons:
1. I believe I am right in saying that they had forecast an upswing in business through the year, so they already had an almighty 2H weighting. Any impact on this (as has happened) would knock forecasts more than might otherwise be the case.
2. Industry peers in the US had been guiding of poorer results in recent weeks, signalling that it would have been a surprise if TRMR were still on track with prior forecasts.
What is a pain is that they could not have told us sooner. It is very irritating that listing rules in the US, where the company has a secondary listing seem to wag the tail of how it discloses updates in its primary listing market. That just isn’t right and the U.K. rules should take precedence in my opinion.
I do take issue with Paul’s comments on share sales. Most recent sales have been for tax and are down to a lop-sided remuneration structure that over compensates via stock, making it hard for the directors not to need to (partially) sell to pay tax obligations. Most recent RNS’s have emphasised that sales are for tax.
Lastly, finnCap mention that when the market turns, TRMR have oodles of operation gearing, meaning a rapid reversal of form. For long-suffering /patient holders, this cannot come soon enough!
Paul - comments on Tremor International (LON:TRMR) share sales are a bit misplaced.
In the US in order to comply with insider rules a lot of compensation schemes paid in vesting shares are put into this kind of mandatory sale scheme. The directors don’t decide when and what to sell the intermediary does. Directors can also elect to cover tax liabilities in this way.
The compensation level and whether it is fair or just enriching directors ahead of shareholders is a different debate and there are merits to both sides of the argument there but it’s pretty common in the US if not here in the UK.
Tremor International (LON:TRMR) Israeli-based. No divvie. Share count keeps going up. ⇒ Classic bargepole stock. I did hear that a few experienced investors made a lot of money from a bit of in-out trading, though.
A note about cheapness: so was Quindell and a whole bunch of Chinese and Indian stocks before they collapsed. Sometimes Mr. Market isn't as stupid as he looks.
You seem to be inferring that Tremor International (LON:TRMR) is a fraud which it clearly isn’t.
None of the competitors in this space are doing well.
I’m not defending them but your inference is disconcerting.
Note the business is almost completely run out of the US.
Israeli company, generally run to benefit the directors not shareholders, look at the share options.
CEO, COO and CFO might originally be Israeli but are US residents and run the entire business out of the US. Yes, it was originally set up in Israel but it is effectively a U.S. company these days.
I don’t disagree about director pay but it is consistent with US market tho I also personally find that excessive.
How do you know it isn’t a fraud?
I have stated here about 6-9 months ago that their listing in the US and the need for raising millions of cash while claiming that they had millions of cash was rather strange.
Why do they carry all this debt in their accounts (probably expensive nowadays), when they claim they have about $90m in cash.
This company was named Taptica 4-5 years ago!
This has constantly been levelled at the business for the last 7 years. But the lawyers have been through DD on several acquisitions. The last one a lot of the price was paid in cash with some debt. The sharebuy backs in size were taken on by an independent broker that executed them with company cash.
None of that over several years points to the company not having the cash it says it does. They’ve answered the debt plus cash balance numerous times too.
If the cash wasn’t real and given the transactional events that have happened since which dwarf the gross debt then had it been an out and out fraud it would have unravelled a while ago.
Also worth pointing out that the CEO Druker has previously run and sold a similar agency for several hundred million and there was no scandal associated with that transaction. It would seem odd for a guy with that sort of wealth to take over the reigns at Tremor International (LON:TRMR) and then be complicit in huge fraud. note Druker arrived after people started this cash is real debate. So he would have to have joined, discovered the fraud and decided to be complicit with it rather than report it. I suppose you can never rule anything out 100% but that would also be seriously odd.
Also worth pointing out that the CEO Druker has previously run and sold a similar agency for several hundred million and there was no scandal associated with that transaction. It would seem odd for a guy with that sort of wealth to take over the reigns at Tremor International (LON:TRMR) and then be complicit in huge fraud. note Druker arrived after people started this cash is real debate. So he would have to have joined, discovered the fraud and decided to be complicit with it rather than report it. I suppose you can never rule anything out 100% but that would also be seriously odd.
The person you are referring to was thrown out in his previous role after the activist hedge fund ‘Brosh Capital’ requested this due to his mismanagement of Matomy Media Group.
I can’t imagine a well run decent and honest small company ( cause we are taking about a small company ) paying for this expensive debt while at the same time claiming that they have this in cash.
This company was called Taptica 4-5 years ago! Unfortunately, I haven’t got the time to discuss the issues they had with Uber technologies , and , although cleared , they opted to change their name.
Anyway you haven’t answered my concerns.
Thanks
the problem is you don't listen to any answers but never mind.
The problem is that you do not have the knowhow to properly research , but instead you just choose to write different unreliable stories based on your personal holdings.
Some interesting comments on inflation and its causes two of the biggest would be mass migration and it’s effects on demand for housing and on infrastructure and the result of the response to Covid lock downs on a country and worldwide level
Uk population growth 20% since 97
https://www.ons.gov.uk/peoplep...
stress on infrastructure and where population is growing leading to pressure on housing and infrastructure
https://nic.org.uk/app/uploads...
Excess spending on covid 20/21 £5,600-£6,,067 per uk resident
https://commonslibrary.parliam...
On top of that the response to the financial crisis of 07-08 which resulted in years of negative rates and bond buying by central banks that when unwound had the inevitable effect of high inflation like pouring petrol on a fire
I also think high energy costs have fed through into everything, from transporting goods to companies having to pay extortionate costs in their factory etc that have to be passed on to someone.
Tremor International (LON:TRMR)
In the space of 10 weeks FinnCap have gone from (EPS) 45.4c/63.4c 23E/24E to 18.9c/38.4c - And from 1300p to 1000p.
What type of info are they being fed by TRMR? Are TRMR providing wrong info to them or are FinnCap making the numbers up (from 10 weeks ago) with TRMR just ignoring it?
That's really poor imo - In the space of 10 weeks.
Even on it's own perhaps makes TRMR uninvestible!
I can't remmber the last time Tremor hit, or actually got anywhere near, its own guidance. Thinking about the millions of £s spent on the Amobee purchase, share buybacks (all out of the money) and share based compensation is eye watering. Finncap always says it trades at a hefty discount to its peers. It seems there is good reason.
Yes, I see that my holding of Tremor International (LON:TRMR) has just taken fright, down an instant 26.8 percent.
Tremor International (LON:TRMR) Looks a textbook example of Stan Weinstein's stage analysis. Its looked fundamentally cheap most of the way down after it rolled over in 2021 but brokers are way behind the market. It'll look expensive at the bottom too when it eventually breaks out and starts a new stage 2 but that could be months or years off.
Can you tell me where that chart is from?
Just a weekly chart. 10+30 week ma
Should have been clearer that green vertical bar chart on the left - frequency of sp ant that level (?) It sort of helps to tell a story.
Green bar is volume by price. ie. highest volume before the base breakout ~100-150p
By the way if anyone is interested you can see the old boy talk about stages on youtube. I love his enthusiasm and they way he keeps things very simple.
Thank you.
Very interested in your ideas around moving averages, particularly as I always find it difficult to time my sales. I have spent my 40 year investing life, generally focused around financial fundamentals; p/e, FCF multiple, etc. This method has worked fairly well, but I usually sell too early into a rise in price, when to my mind the value is no longer there. I see that there are you tube videos on Stan Weinstein's method. Would you suggest this is a good place to start. I'm also intrigued that in the past you have said a 10 day ma is your metric. I'm interested to look at some of the shares I have sold, eg Sage and Card Factory and understand whether this would have led to different decisions.
I am on the same page as with moving averages so please indulge me whilst I give my two pennies worth.
Stan Weinstein videos on youtube are a good place to start. The book is pretty dated now, and like most investment books contains a fair amount of repetition. The financial wisdom channel has a good summary, and there are some interviews with the man himself as well.
He recommends a 30 week MA in the book, but I think since that was written in the 80s things have sped up a little bit. Personally, I keep a close eye on 100 and 200 day moving averages. If the price breaks below one of those and then moves below the break or fails to regain it pretty quickly, I am out. Obviously, the moving average to use will have somewhat to do with your time horizon for holding shares. If you are a swing trader who wants to hold for days or weeks, then a 10 or 20 day moving average works well, but if you are more of a long-term investor, it may be the 100 and 200dma.
In the book "trade like an O'neil disciple" the authors recommend, looking at the stock's characteristics and see what moving average it tends to obey. They recommend it is usually the 10 day or the 50 day, and if the price closes below that and then moves to below that close, that is their sell signal. Again, they are more traders rather than investors, so you could maybe use a similar rule on a longer term average.
One suggestion, I saw that I find really helpful is that if you would show the chart to a complete novice or a child, which way would they tell you the price is trending. Personally, I make exceptions if the entire market is tanking, but other people might not. Obviously this is all caveated by the fact I am not an expert, often get it wrong, and other opinions are available.
I've never had much success investing just based on opinions -- either my own or others (such as analysts). And that's despite spending years learning all I could about fundamental analysis. In the past, I had many big winners and many balancing losers! However, this thread and others like it are asking for info regarding trading strategies. And that's when things changed for me -- when I overlaid my investing/fundamental strategies with traders' techniques. And stage analysis is one such of many useful concepts that I embraced. To me, trading strategies offer the potential of being more precise with equity operations. And they can be modified to work alongside a long-term investing mindset. Each to their own, though. All strategies are unique to the individual
Matt, I really like the suggestion of showing a child a picture of the share price. So much overcomplication of something which is essentially simple.
Tradingview lets you remove the price, but keep the moving averages. Ask a child which way Audioboom (LON:BOOM) is trending, and they'll be able to tell you easily.
Martin, I dont want to post too much on this as most people wont be interested, but a couple of quick thoughts.
I think everyone would benefit from at least understanding the basics of stage analysis. Its a simple method, easy to understand.
I basically have two ways to trade. 1. price reversals 2. uptrends. Hardly ever just buy based on the chart alone, 90% of the time its something that looks good fundamentally too.
Price reversals I tend to use 10d ma for most. Its a short enough period to give me time to get in early but long enough to not jump the gun too often. I like trend reversals because you tend to get an answer quickly ..if im wrong im quickly stopped out. If im correct the price tends to move up fast, good ones will have 3-5 up days in a row. Money isnt tied up long and when its the correct market they work great (its not right now) Usually short term unless earning upgraded. Wouldnt hold something with falling earnings long.
Main trades are looking for EPS upgrades (or potential upgrades) which will normally move the price up. These are longer term holds. 2-3x cash compared to trend reversals. Theyre safer as not many will report ahead of forecasts then next update a profit warning. Want up trending price/50+200d moving averages. Want to know typical news release dates so can time buys better.
You mentioned Card Factory (LON:CARD) Its one I hold, hopefully for a longer term hold as its earnings are rising. Its potentially about to start a stage 2 I would say.
Thanks Wolf, Matt and Kevin for your thoughts, I appreciate you taking the time to reply - very interesting.
Hi Matylda - I think the disconnect is down to the US listing rules for Tremor International (LON:TRMR)
The company updates quarterly and provides forward guidance each quarter but have basically been walking down expectations each quarter for the last year unfortunately. So I believe FinnCap just updates it’s forecasts after each quarterly forward guidance.
I was both surprised and not by todays profit warning because at the last quarter update they sounded much more bullish than I’d heard for a while. Reading between the lines not only were they confident of expectations but hinted at a beat.
Advertising market has clearly changed this quarter quite negatively though.
If you look at some of the US competitors they usually report ahead of Tremor and earnings have been dire. A number of 30% falls out in the States as guidance from them has been lowered. So the market was clearly horrible and Q2 an abberation. So based on the industry I wasn’t overly surprised but had expected better from Tremor given previous commentary.
I was mainly making the point that in 10 weeks EPS has been cut ~60% - To me that is a huge correction for any analyst to be making in such a short period of time
Tremor International (LON:TRMR) is 1) highly operationally geared, 2) in middle of relatively large acquisition and 3) the acquisition has raised the bite point of operational gearing.
So there is nothing underhand/unexplained going on (I'm not saying you said that...but its often the innuendo on Tremor). But they have deepened their cyclicality into a downturn.
The bigger issue to work out from the Q2 update IMO is whether the direction of movement of the biz is correct or they have made a strategic mistake with Amobee acquisition:
"We are also experiencing longer, and more complex, sales cycles related to our strategic focus on driving larger enterprise deals with major advertisers, agencies, and CTV players, while our enhanced focus on driving growth in our core programmatic and enterprise businesses has contributed to a changed revenue mix shift and lower overall take rates for the Company."
The above statement doesn't reference Amobee but it talks to the rationale behind the acquisition being a sort of full service solution for clients as opposed to getting into a 'demand side' tech, platform and volume war with Trade Desk (NMQ:TTD) or 'walled garden' bear hug from likes of Alphabet (NSQ:GOOG)
Some interesting discussions yesterday re inflation, government policy and BOE interest rate policy.
The UK has the highest 10 year Govt Bond yield when compared to Europe, Japan and US. It's only marginally higher than the US ....4.6%... Vs 4.3%. Arguably the US govt should be funding at 10 years taking advantage of the inversion.....yet it doesn't...choosing to fund ultra short for now. The media likes to comment on interest rate policy as a central bank choice.....yet the Truss affair showed there is actually less choice than we believe... if we wish to maintain market stability. The fact the BOE only raised rates 25bp days before the Truss announcement is overlooked.
If we view monetary policy as the rate required to maintain stability in bond markets then this explains why they have risen quickly. This brings pressure on governments to also tighten fiscally .... why? Well the higher cost of borrowing increases the government deficit...which is inflationary! As debt approaches 100% of GDP this becomes a problem and risks causing a currency crisis. In the extreme, the choice becomes rather simple, higher rates to maintain currency stability and/or reduce the government deficit.
If we look to Ireland we can see that it is possible to raise tax revenue without raising taxes....by attracting overseas companies. This policy has its own problems, never the less....it does show that it's possible to move to a balanced budget or surplus in a positive way. So all is not lost.
Rather than all options lead to bust the challenge all governments currently face is to come up with coherent market friendly fiscal policies. This will alleviate upwards pressure on interest rates. Tax breaks, to encourage long term infrastructure investment, would appear an obvious place to start to the benefit of all.
All good points, thanks. Surely the main reason that Gilt yields have shot up, is that the Bank of England stopped buying pretty much all of the newly issued Gilts, which they did throughout the pandemic. Indeed, they've even reversed a small amount of QE into QT. So it's just supply and demand, not really market sentiment. Or rather the artificial, and enormous buying of Gilts by the BoE completely distorted Gilt yields, and that huge distorting factor has now gone. So once again market sentiment decides these things. Plus of course the groupthink of the central banks, who all did QE and zero (or even negative) interest rates together, and are now frantically back-peddling with rapidly rising interest rates all in lockstep. It's all just bizarre!
More than a decade of manipulating the bond market by central banks.
The BoE decides the overnight (base) rate and uses its balance sheet to achieve it, buying and selling bonds as necessary using repo etc to add / drain bank reserves. It can perform yield curve control doing similar (selling short end buying long end etc). It isn't using the rate to control bonds. It is using bonds to control the rate.
When the government sells bonds it is functionally draining the reserves that it creates by spending... essentially a monetary operation that maintains the target overnight rate. That's what most people view as the government "borrowing".
This all makes sense if you have a gold standard or fixed exchange rates, or perhaps if you want to maintain the policy tool to have those options in the future.
Personally I think when inflation goes into reverse (ie near their target rate) the government / BoE will be bragging how right their policies are (seen a bit of that already by the government) but they will be faced with the opposite problem by chasing those rates down to zero trying to create inflation (avoiding deflation) which is where this started a few years ago. I can't prove it, but I think they are just chasing the rate rather than controlling it.
If my memory serves me right, the initial QE of the central banks and close to zero interest rates was not groupthink in 2009/10, but concerted action to prevent economies being hit by what was limbering up to be a sovereign debt crisis. Having stabilised economies, then central banks could start easing back, but fears of deflation kept QE going and low interests low for longer than anyone expected whilst they waited for sparks of growth. So not groupthink, but policies dictated by common circumstances. As growth began to return (beyond the UK) the central banks actions began to diverge.
Bizarre but not boring.... and keeps us all on out toes.
I would look at this a little differently.
Since the late 1970s until 2016 Britain has been run fairly consistently. There have not been any big changes and all govts had at least one eye on the markets.
Then we left the eu, clearly had no plan, incompetant (at best) govt, with a topping of truss fantasy economics.
This country has gone from enjoying a stability discount on debt to suffering an instability premium.
We are now seen as that bloke on a park bench with a bottle of cheap cider who is shouting at the ducks on the pond / the clouds in the sky / the passers by.
We need to get a shower, clean our clothes, sit down and concentrate on solving our own real problems (high house prices, adult education, public transport outside london) for the next 20 to 30 years.
The problems I listed are the ones that I think are important and are holding back this country's long term growth. Your list may be different. That is politics.
The only definitely wrong answer is to be inconsistent.
Back to share prices - the only way share values will grow as a whole over time is if the economy does. Which is what has not been happening for the last few years.
Hi Andrewdb
Re your final para. Spot on!
Very good summary.
We need grown up, proper politicians in charge, willing to make difficult decisions for the benefit of the country, and not to line their own pockets.
Hopefully, the era of the populist grifter politician will shortly come to an end.
Love this
"We are now seen as that bloke on a park bench with a bottle of cheap cider who is shouting at the ducks on the pond / the clouds in the sky / the passers by"
Oh dear, you've set off a political argument. I think we try to avoid that here, although it can be difficult at times, as the line does blur between politics & economics.
Unfortunately Paul politics and all our financial futures are inexplicably linked
What did Ronald Reagan say “most terrifying words in the English language are I’m from the government I’m here to help “
We are going to be getting lots of help from government in future and I find that more than a little worrying
"If we look to Ireland we can see that it is possible to raise tax revenue without raising taxes....by attracting overseas companies."
Surely in this regard one country is getting the benefit by stealing from other countries !!! - we in then uk seem happy to let all the us tech companies get away with something akin to homicide while we twiddle out thumb. Simple example being uber pretending they wree nota transport company for many years and vat office didnt actively investigae (or enusre rules were changed). Lo and behold when uber do go vat registered they almost immediately start sayingb tehir sales may be within the tour operator magbin scheme - so again miniomal vat being paid.
Ditto for facebook and google who can charge small uk businesses no vat when uk based companies do need to charge small companies vat.
In some respects overseas companies should be paying extra if we are not getting full payroll taxes coproration tax (oh so easy not to make a profit under current rules) - reality is we let them get away with murder with companies like Ireland getting some minimal benefit (even then your doubel dutch sandwich type stuff will have been in full effect no doubt.
Its all plainly ludicrous when they are forcing small business to do everything mtd for every transaction they do (if vat registered)
IMHO there is no free lunch overall - however if some can get free lunch its our stupidity for not raising extra taxes here. All we have done is upped standard rate copr tax uk based companies pay addinging insult to injury
RD do you see rates having to higher in the US and UK (more than the next two shoe in UK rate rises) due to the sheer number of gilts/treasuries they need to shift to keep the massive debts running. Also given Fed & B of E can't QE at the moment like they did previously to mop up hundreds of millions worth of bonds will rates have to go higher than thought to attract buyers.
My morning smallcap tweet: Profit earthquake at Tremor
Tremor International (LON:TRMR) ITM Power (LON:ITM) Gresham Technologies (LON:GHT) Kin and Carta (LON:KCT) Aptamer (LON:APTA) EQTEC (LON:EQT) Tanfield (LON:TAN) Arecor Therapeutics (LON:AREC) Watkin Jones (LON:WJG) Empiric Student Property (LON:ESP)
◄Tremor (TRMR)► warns FY-Dec ajd EBITDA $85-90m vs $140-145m guided due to “longer and more complex sales cycles..and continued expected declines in its non-core performance business". [SP=254.33 Cap=364m]
◄ITM Power (ITM)► launches "cutting-edge 20MW core electrolysis process module...based on state-of-the-art stack technology". [SP=87.12 Cap=537m]
◄Gresham Technologies (GHT)► wins 3 year $1.6m with Tier 1 global asset manager. [SP=140 Cap=117m]
◄Kin and Carta (KCT)► guides FY-July rev in line and adj op profit £17.9-18.4m, 10.5-14% ahead of market expectations. Cites a lower cost base and improved operational efficiencies. [SP=63.5 Cap=113m]
◄Aptamer (APTA)► wins 2 contracts worth up to £219k. They are further conversion of the sales pipeline announced previously. [SP=2 Cap=2m]
◄EQTEC (EQT)► wins €440k contract from Idex for Front End Engineering Design. To complete by Dec 23. "Assuming final investment decision based on the current configuration, EQTEC will be the core technology supplier for France MDC, receiving fees for engineering services, equipment, commissioning and licensing over the period Q4 2023 - Q1 2025, estimated to total c. €15m." [SP=0.17 Cap=20m]
◄Tanfield (TAN)► better figures from its troublesome 49% owned JV Snorkel: Q2 positive EBITDA. TAN "continues to be unaware of the reason behind the gross profit margin improvement from 2022 to 2023 but hopes that its ongoing work to try and investigate the current and historic gross profit margins may provide some further clarification". [SP=2.62 Cap=5m]
◄Arecor Therapeutic (AREC)► collaboration with a top 10 pharma to develop an enhanced antibody formulation. [SP=190.1 Cap=58m]
◄Watkin Jones (WJG)► sells its three non-core Private Rented Sector operational assets for £9m net and £2m deferred. Will make a book loss which is fully reflected in the expected impairment charge for FY23. [SP=47.95 Cap=123m]
◄Empiric Student Property (ESP)► H1-June. Booked occupancy a record 98% at this stage. Guides FY LFL rental growth c.9%, significantly ahead of previous guidance. [SP=85.6 Cap=517m]. I hold.
welcome back mr contrarian, hope you had a lovely holiday!
Georgia on my mind !
Bank of Georgia / Georgian economy
Wow
7% growth in economy and inflation below 1%.
Georgian investors on stockogeorgia are probably discussing the “geopolitical risk” investing in the UK with its cretinous government and policy makers .
I have to say Georgia looks to be in a sweet spot right now in terms of Growth and inflation and I am much more confident in Georgias ability to perform in the next 2-3 years as opposed to the UK.
The geo political issues seem our side not theirs .
Morning planetx
Georgia’s GDP grew by about 1000% in the last 20 years. The UK’s never even doubled. In fact, it merely grew prior to the 2008-2009 financial crisis.
Thanks
Good luck to any holders but political risk in Georgia is real imo. Their govt is in the pocket of Russia and, because of the current conflict in Ukraine, the EU & US govt's are talking about drawing up a list of sanctions to impose on the Georgian govt because of their close ties to Russia.
Spot on planetx. Close run thing between the UK and Argentina. Banana anyone?
Haha Planetx
I’m pleased with Bank of Georgia (LON:BGEO) results this morning. Performing well in a good economy with low inflation and strong inward investment.
Now looks like it will pay circa 10% divis this year which is great and trades around book value (maybe 1.1* today) but on a PER of only 3 with strong capital generation.
With the kind of ROTE it generates it should trade much higher in my view. Share but back shouldn’t hurt either.
NIM is probably around peak and whilst rates are coming down there the currency is still strengthening which obviously helps translate earnings into GBP.
At some point I am hoping BGEO will be large enough to enter the FTSE 100. Stock’s ranks sometimes don’t work well for banks, but in BGEO case I think they do represent the upside.
just wish I'd put all this year's ISA allowance into this
Contemplating this market I have moments of clarity but then become baffled in equal measure when I see conflicting trends.
Some share prices are being pushed up on modest buying and others drifting down with little discernible difference between the news flow of the underlying corporates.
I agree, money seems to shuffle between different names on a daily basis. Perhaps its poor liquidity, a lack of new investor money and traders reading too much into charts then closing short term positions when share prices lose momentum.
There was a bit of interest in the potential superconductor LK-99 a while back. Sadly the research shows it’s not a superconductor after all - which is a shame as it was pretty exciting for a while.
https://www.nature.com/article...