Small Cap Value Report (Thu 18 Feb 2021) - RNO, TRI, WIL, OPTI

Good morning, it's Paul here with the SCVR for Thursday.
Thanks to everyone who attended the StockSlam (via PIWorld, 3 minute pitches for people's favourite shares, with 10 shares covered) last night, an amazing turnout of about 1,000 people. My stock idea was Renold (LON:RNO) (I hold) - where a big pension deficit seems to be obscuring strong fundamentals, and a turnaround plan that's working. Here are my notes from Renold's most recent trading update. There's a persistent seller in the market, so hopefully my comments don't trigger a spike up in price, it's awkward when that happens.
The next StockSlam is on 7 April.
Agenda -
Trifast (LON:TRI) - Q3 trading update sounds reassuring. Although worrying comments about raw materials inflation
Wilmington (LON:WIL) - Impressive interim results, but the weak balance sheet rules it out for me
Optibiotix Health (LON:OPTI) - trading update for 2020. Signs of progress, at last!
.
Trifast (LON:TRI)
139p (flat, at 08:22) - mkt cap £188m
Leading international specialist in the design, engineering, manufacture, and distribution of high quality industrial and Category 'C' components principally to major global assembly industries … Trifast plc (Main market LSE Symbol: TRI) issues the following unaudited Trading Update covering the Q3 financial period and up to the date of this announcement.
Trifast has a 31 March 2021 year end.
Trading continuing to strengthen
H2 revenues up 5% for the four months to 31 Jan 2021
FY 03/2021 revenues expected to be slightly ahead of market expectations
1. Company compiled consensus shows market revenue expectations of c.£172m
Particularly noteworthy points are -
- Border issues (logistical challenges) re Brexit
- Well-known problems with transport costs & container freight are mentioned
- Global shortage of steel is causing price rises, and delays - leading to “additional margin pressure which we are working hard to mitigate”
Dividends - will be reinstated.
Outlook - sounds reassuring -
The Group's continued recovery, in addition to a strong pipeline and high activity levels, provides a solid base for the business to move forward…
My opinion - I find that Trifast tends to focus too much on revenue, and not enough on profitability, in its trading updates.
As you can see below, earnings expectations for this year and next year, are still way below (about half) of pre-covid forecasts. Note that forecasts were reducing before covid struck, so it looks as if there were existing issues.
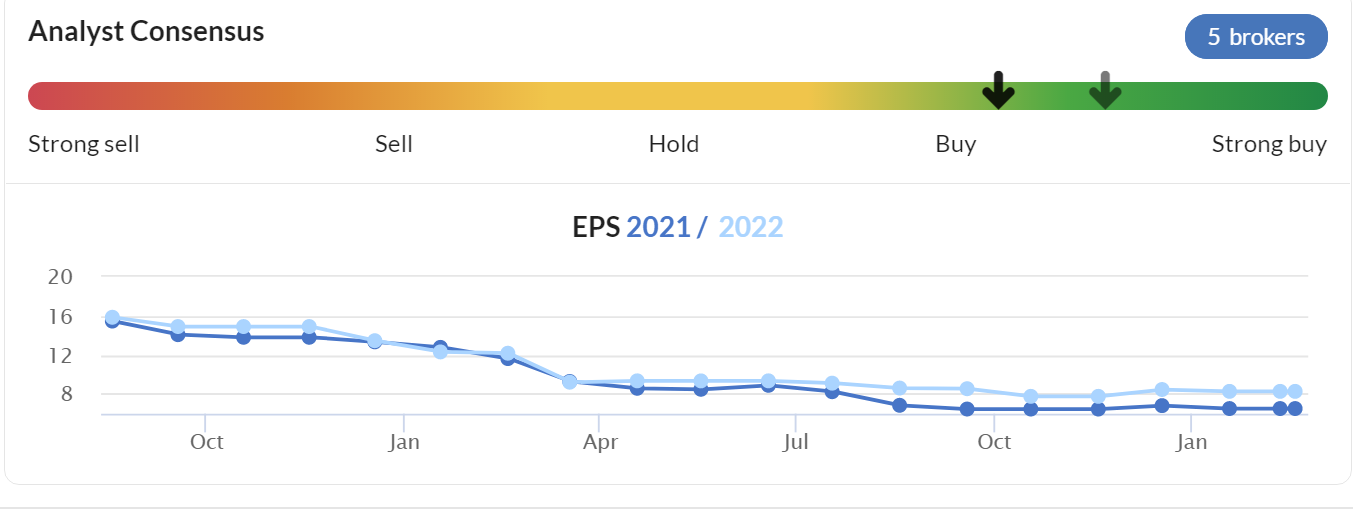
I suppose the opportunity here is that, over time, earnings could recover back to pre-covid forecasts, which would provide good upside on the current share price.
The comments about raw materials price rises, and a shortage of steel, plus freight issues, are similar to what we’re hearing from lots of companies at the moment. This worries me, that we could be entering an era of persistently higher inflation, and possibly interest rates rising? That could hurt earnings (margins under pressure from higher costs), and hit high PERs in particular, if interest rates rise. All this new money sloshing around from massive QE, has to logically end up in higher inflation, eventually.
There do seem to be some macro warning lights beginning to illuminate.
Overall, TRI shares look priced about right to me.
.

.
Wilmington (LON:WIL)
175p (up 4%, at 12:00) - mkt cap £154m
Here are my notes from 4 Nov 2020, where I saw potential in this education company’s move to online delivery.
Interim results today are for the 6 months to 31 Dec 2020.
Wilmington plc, the provider of data, information, education and networking services in Risk & Compliance, Healthcare and Professional knowledge areas, today announces its half year results for the six months ended 31 December 2020.
The financial highlights look really good, I’m impressed.
Revenue held up very well, considering no face-to-face events or training, down 7.4% to £55.1m
Adjusted profit before tax actually up slightly, to £7.0m - that’s a decent profit margin at 12.7% of revenues
This stands out as impressive too -
Cost savings from the move to virtual were greater than the fall in revenue
Dividend reinstated at 2.1p, and furlough monies (no figure given) to be repaid.
Balance sheet - this is a concern, it’s very weak.
NAV of £47.4m, less intangible assets of £94.4m, gives NTAV of negative £(47.0)m. It seems to me that reinstating the divis, when the balance sheet is really weak, seems reckless.
The working capital position looks unusually weak. Current assets are £33.5m, but current liabilities are £57.2m, giving a very weak current ratio of 0.59. Normally I consider anything under 1.0 as being weak. Trade creditors seems unusually high, at £54.5m (which includes £8.0m deferred VAT).
Perhaps this business has a negative working capital setup, where it receives money up-front from customers, but even so, I feel this looks a dangerously stretched balance sheet.
Long term creditors includes £30.4m in borrowings too. So the business is totally reliant on debt funding, rather than equity. That’s fine in the good times, but leaves the business dangerously exposed, if the bank decides it wants its money back.
My opinion - if you’re not bothered about balance sheets, then this might be an interesting share to look at. The trading performance looks strong, and very resilient given the sector it operates in. Switching to entirely online, is very impressive.
Management doesn’t seem to have received the memo that, post-covid, companies need to be building up their financial reserves, not resuming divis prematurely, funded effectively from debt.
For me, the very weak balance sheet, and too much debt, rules it out, but I can also see why other investors might put more focus on the positive performance & resilience re covid, which are good.
.
Optibiotix Health (LON:OPTI)
55.6p (down 9%, at 14:37) - mkt cap £48.8m
OptiBiotix Health plc (OptiBiotix), a life sciences business developing compounds to tackle obesity, cardiovascular disease and diabetes, provides the following strategic and financial update ahead of the Group's final results for the year ended 31 December 2020.
Functional Fibres division -
- Sales of £558k (up 150% on 2019)
- EBITDA of £66k (loss of £(433)K in 2019)
- 18 commercial agreements signed in the year
ProBiotix Health
- Sales of £818k (up 106% on 2019)
- EBITDA of £76k (loss of £(474)k in 2019)
- 7 commercial agreements signed in the year
Consumer Health Division
- Sales of £137k (up 12% on 2019)
- Loss of £25k
Total sales up 103% to £1.51m
Cash overheads £1.59m, down 28% on 2019)
Gross margin of 58% in 2020 (53% in 2019)
That seems to give gross profit of £876k, and an operating loss of £(714)k
Cash - tight, at £866k at 31 Dec 2020. £262k of tax credits & VAT refund are due.
Investment of 24.5% in separately listed Skinbiotherapeutics (LON:SBTX) a holding which is on paper worth £14.3m at the latest share price of 37.35p. That’s almost 30% of OPTI’s market cap, so it’s a significant consideration, especially if OPTI is able to place the shares, to turn it into cash. Bear in mind SBTX is a jam tomorrow, speculative share, even more so than OPTI, so its value on paper may not necessarily to into real money. But who knows, we’re in a euphoric late stage bull market, so anything can happen to story stocks.
A £7.0m profit will be booked in 2020 for the increase in value of SBTX shares owned by OPTI.
There’s loads more commentary in the announcement, which I won’t rehash here, because I’m only interested in facts & figures, not jam tomorrow.
My opinion - I’ve been highly critical of this company in the past, because management are so promotional - over-promising & under-delivering repeatedly. I wasn’t impressed with an abusive email I received a while back from the CEO, which seemed very much a shoot the messenger response. It goes with the territory though, so it doesn’t bother me.
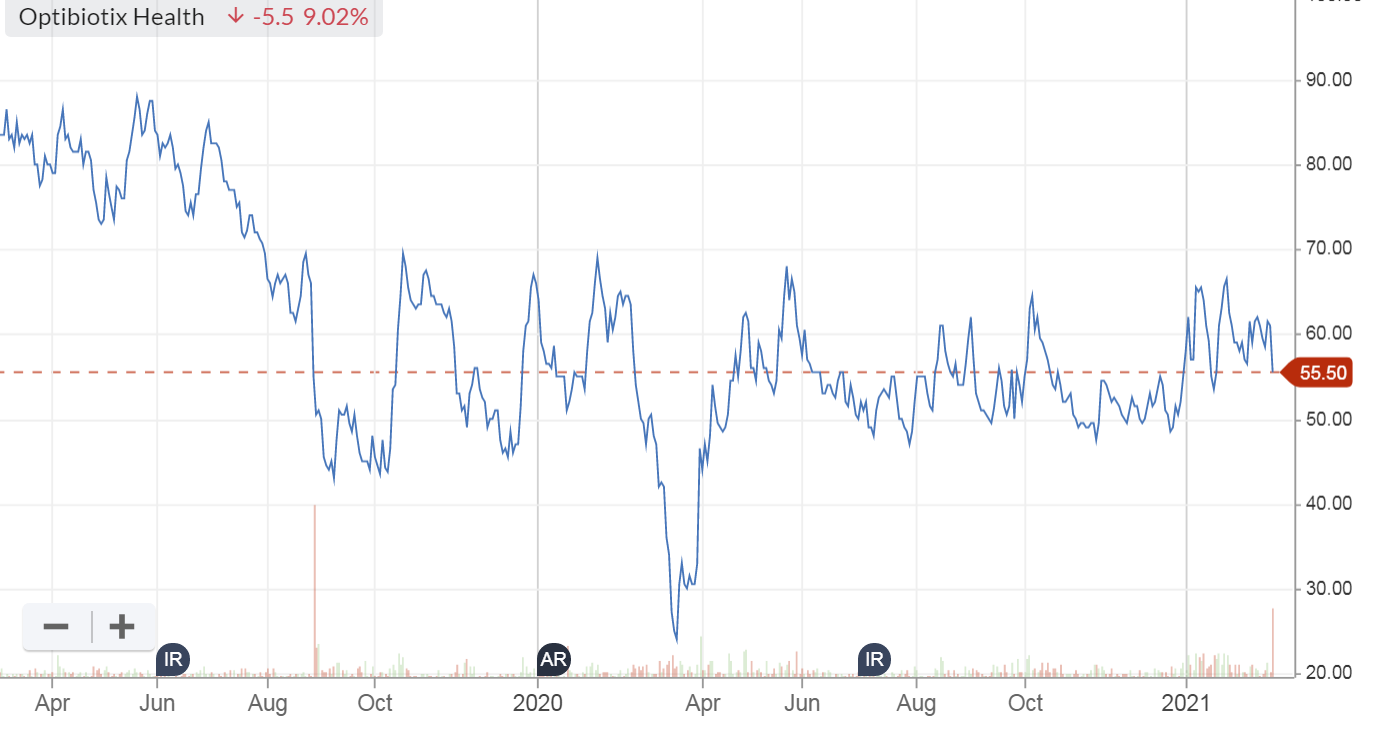
However, if the facts change, I change my mind. In this update today, I’m seeing the first signs that OPTI might be making some commercial progress. The numbers are small, but growing strongly, and a 58% gross margin creates really good operational gearing. Low overheads mean that it’s now not far from breakeven, and if growth were to accelerate, then it might move into profit at long last?
If the company could turn some of the SBTX shareholding into cash, then it could avoid another placing.
Overall, this is not a basket case any more! Some progress seems to have been made. The story had become very stale, but maybe it could be reinvigorated? Markets are very receptive to story stocks at the moment, after all.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
#AAA late post but the options from Nick Candy and David Rosen’e vehicles if exercised are a game changer, this share could easily go to £1, I have held since 2p and added at various times but it a play on AI with some products that have real traction. I also think #PIRI could double within 2 months essentially a VC for Crypto and other Tec, Low6 is a mega soon to be viral gaming app which will float in Q2, Pluto a VC for Crypto, YOP adds to the mix plus others - DYOR but plenty to get excited about - I am long
One other point about Renold (LON:RNO) (from memory!) ..it was two divisions chains and torque conversion. It seems as though if one is doing well the other not so. The Holy Grail is I guess to have both firing at the same time. It struck me that it might make it more difficult to be bid for...someone wants chain but not the other, and vice versa.
Ah yes that reminds me, the torque transmission division of Renold (LON:RNO) is smaller, but some quite interesting products. I am told that it might involve couplings e.g. for a warship driveshaft, so it cannot break. Or rather, if it breaks, it has to be capable of still working, but at lower revs. These things can cost £1m+ per coupling. Sounds really specialised.
Moneysupermarket.com (LON:MONY) (I hold)
Sharing my notes for any interested:
2020 AR:
-ve's
"The rest of the decline was mainly due to volatility in SEO positions for key insurance terms, with SEO positions in H1 weaker on average than in H1 2019. This means a lower proportion of customers came to us via natural search, leading to a fall in gross margin."
Is this partly to offset lower SEO (note 1)? Will it keep going up?
Why? Isn't 2021 going to be a shit year too?
The proposals to end 'price walking' within car and home insurance are likely to dampen switching levels in the medium to long term..."
Bad for business. Insurance companies pay referral fee in anticipation of little/no/negative profit in year 1, and much greater returns in subsequent years. Why would they keep paying Moneysupermarket.com (LON:MONY) the same referral fee? Could be quite impactful.
+ve
I know we're focused on shares here, but keep an eye out on bond yields.
Gilts rising steeply, especially further along the curve. Higher inflation or rate rises are being priced in. Still low levels compared to historic. But given how high valuation multiples of tech shares are based on low discount rates based on bond yields, this is worrying for the sustaining of high valuation multiples in shares.
Don't you mean gilts are falling ? gilt yields are rising.
Yes, my bad! Gilt prices falling, gilt yields rising.
Could the data not also be interpretted as a positive reaction to Covid Vaccine roll out success? Reflecting optimism that rather than prolongued economic depression, there is financial light over the horizon.
Re inflation
The argument that QE didn’t cause runaway inflation in terms of CPI after the global financial crisis so why should it do so now is a good one but it does feel a bit like saying, I was going 50 miles an hour and didn’t crash so I can go 100 miles an hour and not crash.
Is the productive capacity of the economy still the same as before? There’s been plenty of talk on here about companies going bust during the crisis or consolidation taking place reducing the competitive intensity and giving the survivors more pricing power, which sounds inflationary to me. Companies also need to raise prices to pay off those loans they were given to get them through the crisis.
So, if the massive government stimulus does create additional demand then it’s far from clear to me that the economy can respond to that without the side effect of inflation.
At the same time, I expect that the currency will start to devalue against commodities and other currencies that are not subject to increasing money supply on the same scale. So, that creates a further pressure for prices of products to increase. Combined I suspect that the effect will start to snowball. And by the time the central banks and governments step in it will be too late (we’ve seen how difficult it is for government to take preemptive action during the crisis because as soon as you try to do that there’s a chorus of people who insist that the figures don’t yet show that there is a problem).
Thus, I’m warming to the idea of having some investments in commodities, after a period of next to nothing, but not sure that small cap commodities are the place to be. So, as this is predominantly a place for small cap companies to be discussed I’ll leave it there.
Good event last night thanks. Already had Renold (LON:RNO) and bought some more on your pitch. Thanks.
On another note. There is a huge spread on £AIRA today. Is something up?
£AIRA I can't find. Which share do you mean?
Suspect he means Airea (LON:AIEA), quoted spread around 10%
Is that unusual for Airea (LON:AIEA) ? I checked in December 2020 and it was around 12% then.
I don't think it is. I was really thinking he probably meant Airea as AIRA doesn't exist and it's so close! But 10-11% is on the large side in general these days, thankfully!
These spreads are crazy IMO. I have been looking at US shares, the largest spread in my watchlist is 0.5%, most are around 0.1%.
hi. I meant Air Partner Air Partner (LON:AIR) on here. It’s AIRA on Investing.com I should have checked. Spread was 5 to 6% earlier today. Not usually anywhere near that.
Just wondering if anyone knows why £4bb - 4basebio UK which listed yesterday, has a spread of 25% - 40% !? is this because of the lack of free float ? Will this eventually reduce in time? Thanks.
Your comment is right that this company £TRI is too focused on Revenue and not Profitability. The EPS chart is downhill. I was in it and left very quickly in 2020. It amazes me that 5 Brokers have it as a buy or strong buy. They must not look too much under the bonnet. One can invest in US stocks and see much more progress on relatively modest sized companies in a short time frame. There is in fact a shortage of good stocks in the US with the result that some are very frothy because there is no alternative.
Did anyone mention cannabis or the new "cannabinoid-derived medicines" companies at the Stock Slam? MGC (MXC) pharma was floated last week at a penny and a bit and crashed through 9p today. Kanabo (KNB) floated at 6.5p this Tuesday and hit 52p today. Some of the market caps are bonkers; are investors sampling the products and then buying?
So if you have kids and they ask "what do you think about buying cannabis "......you can truthfully answer "it is making me a fortune", "I cannot get enough of them" or similar. Surely the ticker should be "WEED" or "POT"? What are the "fastest growing" stocks in this field? As kids, didn't we all watch the vietnam film Platoon? James Bond 007 sent to destroy such crops.....Mr Big I vaguely remember with the beautiful Solitaire? I admit I made a few quid this morning on MGC. Will the police knock on my door and accuse me of "dealing"?
Getting old I guess....
Why do people enjoy cannabis? It turns them into boring zombies. Waste of time if u ask me. Leave them in the corner, give me some dance music & some E & we'll partay! :-D
is there a recording of last nights event available?
Ben told me there would be one later.
They said it should be available by Friday.
Once again we have talk of "dastardly" MMs as if they were lurking behind a curtain in dark glasses listening to what Paul said last night. Well, they are actually called RSPs now (Retail Service Providers) because in all but the smallest caps it is the order book, not them, that make the market.
So look at Renold (LON:RNO) - the open was the result of an auction in which 50,000 shares changed hands at 15.1p.There was then some trading at 14.9p before buyers pushed it up to peak at 16.4p between 08 14 and 08 37.
True enough, the MMs can only do what the market will allow price-wise. One of the clues is to check if the stock is traded SETS or SETSqx. If the latter then the MMs do tend to control the pricing - but again can only do what the market will accept, if SETS then the order book controls the pricing. If in doubt check the volume - no volume doesn't really confirm strange price action. However, the MMs are definitely not stupid, are in business to turn a profit and read all the market news concerning their sector of the market, exactly as we do. There are plenty of other manoeuvres that abound in the market to confuse the unwary - iceberg orders, dark pools and that's just for starters.
Interesting post. One thing overlooked in talk of MMs is that in theory they are supposed to be in competition with each other which would appear to mitigate against them acting in concert to drive prices up or down. From my experience certain MMs got on better with some rival MMs and not with others. They would more likely help out those they liked. They used to use private chat boxes to talk to each other..but that was a few years ago. I'm sure compliance have knocked that on the head. One can't simply follow everything. If you were short Renold yesterday you would probably thank your mate who tipped you early doors it was recommended yesterday evening by an influential stock picker!
Paul: "All this new money sloshing around from massive QE, has to logically end up in higher inflation, eventually"
I don't know why so many people keep saying this kind of thing, it's simply not true. It's possible that we will see higher inflation, but it's not a given, and if it happens it's not necessarily a problem. To people who see this as a problem I would say:
- Massive amounts of QE (and government deficits etc) have been sloshing around since 2009. Why haven't we seen inflation in the 12 years since? What's changed now? Why is it "different this time"?
- Higher levels of inflation are exactly what central banks want now, as they keep saying, so if it materialises it doesn't mean they will slam on the brakes as they would have done in the old days. We should expect to see some rise in inflation, the bigger problem would be if we dont.
- Higher inflation driven by increases in demand would be a good thing. If, on the other hand, it's to be driven by a reduction in supply, then what is going to be in short supply (outside of a few rare minerals)? How will there be inflation if it isn't driven by an increase in demand or a shortage of supply?
- The same massive deflationary forces that have been in place for the past 20 years are still going strong and in some cases increasing. There need to be significant inflationary forces just to stop deflation.
I can see macro problems, and I can see inflation blips (demand might temporarily increase faster than supply), but I find it hard to see a significant inflation problem if it isn't caused by military conflict, social revolution or ecological disaster.
I agree, isn't it weird that the western central banks have created bucket loads of QE money yet there is no inflation. It would be good to hear from knowedgeable economists who could shed some light.
Perhaps what has happened is that the new money has indeed created inflation, but only in asset prices. It's as if the money, first injected 2008/2009 is like a static injection into the economy's balance sheet, repairing an unstable situation following the great financial crash. QE could equally be applied, say, by giving every UK resident £1000 cash. Then that would be like circulating additional money and probably give rise to RPI increases.
Well that's my guesswork, but who knows!
As investors, our job is to think what would happen if inflation does take off somewhat. What would happen? Doesn't theory say that with higher inflation and interest rates, the discount rate increases on future earnings? Hence all share prices logically fall, but growth shares whose earnings are more in the future, would fall more, and value share would find favour.
I keep wondering if this scenario unfolds, how Fundsmith's stellar performance might change. So far Terry Smith has played a blinder investing in stable but high priced quality shares. I suspect it's a good permanent stategy but there'd be a big step change reversal in conditions where value shares get back into favour.
If you look at the money supply in the UK (or anywhere) there has been huge inflation in the money.
Anything that is scarce has seen its price bid up and up (stocks, collectibles, gold, Bitcoin)
Why does this not show up in higher prices of everyday goods..... because technology is deflationary and is making everything cheaper. Central bank money inflation is pushing in the opposite direction, seeking to inflate prices. These two opposing forces are showing up as negligible CPI. Prices should be falling (if left to the free market), distributing the gains from technology broadly.
This book is an excellent overview of whats going on https://www.amazon.com/Price-Tomorrow-Deflation-Abundant-Future-ebook/dp/B08334WFSQ
If you read about periods of very high inflation eg Weimar Germany, Venezuela recently - government money printing was unhinged, but people were oblivious, seeing only that the stock market was continuoulsy rising, setting new all time highs regularly. I see the same thing playing out today.
I did a post on this a couple of days ago directing attention to that day's Big Read in the FT.
There are many ideas, but the truth is nobody knows. Money supply itself is imprecisely defined - or rather there are many precise definitions but the underlying reality changes over time; maybe we're missing something important here. Asset price inflation doesn't explain it. The chosen QE methods would inflate some financial asset prices but it would be expected to spill over into other prices, and it hasn't. And the correlation between the two isn't great anyway whatever MS definitions are used. Nor does technology explain price stability.
The relevant economic theories will be right - they're largely mechanistic - but the detail of the relationships with real world behaviour have clearly changed. This leaves economists stuck because all models are based on a relative stability of behavioural relationships measured through long observation. The examples we have of recent QE type stimulus have not produced inflation either in the west over the last decade or in Japan. Governments running huge deficits haven't either. I don't remember a large, sustained attempt at helicopter money, smaller trials haven't been effective.
What you can observe is a build up of tensions within and between societies both short-term (visible now) and long-term (eg ageing demographics). Sooner or later they will be resolved with the equivalent of an earthquake(s). Given the difficulties with firm predictions, I'd advise maintaining flexibility and freedom of action as well as spreading risks.
I see the point regarding QE, it cannot be read across directly as causing an uplift in inflation. I think one issue is people are talking about inflation in general terms when in reality there multiple types of inflation, I think what people broadly mean when they talk about it is CPI.
It is true that CPI levels have run very low since the financial crisis, in the face of significant QE, the banks would have had to lend sustantially more to impact CPI, which hasn't been the case. However I don't think the situation we have today is quite the same as the aftermath of the financial crisis, where liquidity supply was mainly made to shore up bank balance sheets.
There is unprecedented levels of fiscal spending coming through, particularly in the US with cash payments being made to the population directly from the government as well as discussions about student loan debt jubilees etc. If you pair this with some examples of basic materials / commodity supply issues caused by covid (or due to underdevelopment of production of certain materials due to prolonged slumps in prices) it could lead to higher CPI in the medium term. Just my opinion, but much still depends on future central bank and government actions, particularly any action to stem the rise in treasury yields.
At the end of the day central banks / governments have significant debts to tackle in the coming years, higher inflation will maybe be welcomed as a means of reducing the burden, similar to what happened in the decades after WW2.
Massive amounts of QE (and government deficits etc) have been sloshing around since 2009. Why haven't we seen inflation in the 12 years since? What's changed now? Why is it "different this time"?
Well, we have, it's just not been in consumer prices, it's been in assets.
But the point you're making is correct. No amount of QE can trigger persistent consumer inflation unless demand outstrips supply. There's absolutely no sign of that. The pool of educated workers continues to rise, labour movements are moribund and wage demands are subdued.
We may see some localised inflation - especially in the UK, where you'd expect Brexit to drive up the cost of some goods, border controls to trigger wage increases in some sectors and for some companies to take advantage of the confusion by pushing through price rises, much as they did after decimalisation. We may also see spikes in inflation if demand rises post-CV-19 while commodity supplies are restricted. But the vast amount of capital sloshing about will find its way into natural resource projects and that will wash out eventually.
A lot of this to me feels like people brought up in the 70's and 80's who are unable to shake the experience of inflation in their formative years. Much the same thing happened with people that experienced the Great Depression - they spent their lives expecting it to recoccur. But it never did and they sat on the sides during one of the greatest stockmarket rises in history.
Mostly the issue now is in asset inflation - we're seeing a lot of cheap capital finding its way into speculative investments. At some point it becomes clear which of those will succeed and which of those will fail - and if the majority are in the latter camp we'll see an extremely entertaining bust ensue.
Every boom and bust has it's own story but human nature remains the same. Greed on the way up, fear on the way down.
timarr
Hi Tim,
Do you not think this time it might happen I agree we saw inflation post 08/09 in stocks and residential housing, this time the central banks have unleashed QE on a scale that makes 08/09 look like getting a round of beers in.
I do just wonder with covid and global goods supply restriction being an issue that when we open up all the money people have saved plus the qe trillions will be chasing goods and services that won't be there due to problems in the supply chain and b and b's being able to up prices due to people taking stay-cations.
I agree the central banks want some inflation to get rid of the mega debts incurred (most is being written off behind the scenes by the bank of england) but it does worry me that if it takes off they won't be able to use the usual QE trick to get us out of that kind of jam that would follow if interest rates had to be cranked up to combat it.
The other side of the coin is Japan have been trying to create inflation for years with no luck but then again they didn't have the supply chain issues at that point or electrification where the current worlds annual copper supply would be needed to build Tesla target of 20 million cars per year.
The rise in the value of sterling suggests that import price inflation is more likely to be deflation.
The rise in the value of sterling suggests that import price inflation is more likely to be deflation.
Agreed. We have specific challenges in the UK due to well, you know, that Brexit thing.
But more generally, it's hard to see inflation getting out of control globally.
timarr
I never quite understand the criticism MMs get nor the shorters criticism. In the end our job is to make money in the environment we are given. MMs mark up the price because they know Paul has a lot of followers, as does Ed etc. Totally reasonable to do that, given the private investors attention has been brought to the share by the very same source. We, the PI could be criticised because we are taking Paul's word for it. Our goal is to get there before Paul so when he mentions it we can sell into the rise. Sorry Paul but thats how I see it.
Here are my SCVR heat maps for today (prices as at ~8:50am).
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents:
https://www.stockopedia.com/co...
RA International (LON:RAI)
For any holders or interetsed parties here cannacord (recently appoointed?) have issued a broker note on RA (golddust!) - this can be viewes on the RA thread on the "other place" at present.
Over there they seem to say that new brokers are normally cautious ref prospects for companies they have new notes for (no idea if this is the case or not).
I am hoping this is the case as they have pencilled in a very low EPS of 3.7p for 2021 (5.3p for 2020 and 8.3p for 2021) - so if we take the viewpoint these numbers reflect reality it looks like there may be no jam for this year ref this company. As ever with "lumpy start and delivery date" contracts it always seem to be the case that the jam is just over the horizon sigh - i had slightly higher hopes for 2021 as there was some overuns from 2020 that i hoped would give thme a flying strat to 2021 - it appears that this is not really the case based on these projections - to be fair to the company they have flagged up "covid related" uncertanties exist as the same time as being positive ref 2021 prospects so they have kinda covered their own back in this regard. Hopefully they/brokers are just moving to uber cautious so as not to not have overuns two years in a row - however when a broker goes to the toruble of saying this year will be worse than last i always take note as i am presuming some spefic info must have led to this conclusion ! (its not like we didnt have covid in 2020!) - as ever i would presume that to be a nod and a wink - hopefully they are just being uber cautious as new broker - their spefic wording ref the issues the company is facing is as follows
"In the short term there remain significant barriers to executing work due to COVID-19 related effects"
paul, not your “ fault” at all, but made me laugh with Renold up 13% this morning. Perhaps we should have a contest to see which of the shares discussed at the slam does the best , the day/ week/month after. Might be fun! No criticism meant at, all love your and jacks work.
Hi Tanglands,
Re Renold (LON:RNO) (I hold) - I know it's infuriating when prices go up after someone has mentioned them. But that's a symptom of a frothy market. This market feels exactly the same as 1998-99 to me, in terms of investor sentiment & behaviour. Frenzied speculation, hot tips, IPOs soaring to crazy valuations, an influx of inexperienced mug punters who are making tons of money speculating on junk, short sellers getting burned, etc. There's no point in fighting it, in fact a lot of money can be made in the final euphoric stage of a bull market. You've just got to sell up before it crashes!
With the StockSlam last night, I deliberately chose a stock where there are sellers in the market (several institutions seem to be offloading gradually), in the hope that this wouldn't cause a spike in price. It looks like the seller is feeding RNO stock into the market now, as it's only up 7%. Also I deliberately chose a 2 year turnaround/re-rating, rather than picking some speculative rubbish.
I don't think there's any particular rush with Renold. I'm hoping the turnaround continues, and sellers gradually exit, then possibly clearing the way for the share to re-rate over the next couple of years. It depends what the financial results are like.
Regards, Paul.
Ed Crofts pitched Cake Box Holdings (LON:CBOX) at the ShareSlam last night, and that's only up 4-5%.
Hi Paul, would be interested to hear your thoughts on £Kr1 . One of the reasons I'd not invested in cryptocurrencies coins is the inability to hold in my ISA, especially with possible tax changes incoming on investment gains in the budget.
KR1 is essentially a blockchain ETF/fund supporting early stage blockchain and DeFi projects. I trade with ii and had to call them to buy. The day after I bought, it listed in the US and the price shot up. Today HL have started to accept fill or kill orders online or app. Really interesting prospect.
Good morning Paul,
Interesting idea Renold (LON:RNO) as it looks quite cheap and on the way up. But what caused the business to decline from 2017?
Morning R--G,
Interesting idea Renold (LON:RNO) as it looks quite cheap and on the way up. But what caused the business to decline from 2017?
I'm not sure. Looking at the Stockopedia figures, it seemed to fairly consistently make c.£12m profit each year, then had a bad year where profit halved in FY 03/2018.
Talking to the CEO, it does sound like he took on an absolute can of worms, with multiple deep-seated operational & cultural problems that he's been steadily fixing over the last few years, but it sounds like it's been a painful experience for him. That's why I think he would happily sell to anyone who approaches with a sensible takeover bid at a decent premium. It's a lot of company for the money, and there's also an interesting angle on the pension deficit - namely that if a larger business buys Renold, then it would instantly reduce the pension deficit because a lower risk discount rate could be applied. Then you can factor in stripping out duplicated costs, costs of the listing, etc, and quickly build a compelling case for someone to buy Renold.
The downside risk is that it just trundles along, with nothing much changing, and the pension scheme sucking out the cash generated, leaving nothing for shareholders.
Personally I'm happy to give it a year, and see what happens. The key thing for me is the latest round of restructuring, which involves shedding a lot of labour, according to a broker note. If the CEO can get the operating margin up into the mid teens, as he believes possible, then the shares would definitely re-rate from the current PER which I reckon is about 3.5 (based on 4.0p EPS by my calculations for FY 03/2021) - the consensus forecasts don't look right. The post-tax earnings of £9m looks right, but then if you divide that by the number of shares in issue, it comes out at 4p, not less than 1p as shown on the StockReport.
Hence I think when the FY 03/2021 numbers are published, people might then see that the PER is ridiculously low. Sure, the pension deficit should result in a low PER, but I would say maybe 7-8 would be about right, implying upside of more than 2x on the current price, if my figures are right.
The pension deficit is the big issue, and with seemingly zero interest rates forever looking possible, then maybe investors have run away from Renold shares, not being able to see any end to the cash outflows relating to the pension scheme? I don't know. Unfortunately people don't fill in a form to explain their reasons for selling any share!
Regards, Paul.
Thanks for your reply Paul. Are you not concerned that Renold (LON:RNO) has a large negative NAV, not to mention even larger negative NTAV? Time and time again your advise us to be wary of companies with negative book value. Please comment if you have time. Thanks
R-G Paul did indirectly touch on the reason the negative NAV & TNAV at Renold (LON:RNO) , namely the pension deficit which stands at around £125m. (Compared with Book Value o -£11m, Market Cap of £33m and Enterprise value of £76m.
The very archetype of a Pension Fund with a small company attached to it.
Make of that what you will, but a key consideration is that these are long term commitments, the agreed recovery payments whilst large, do not seem fatally onerous at this stage and they appear to have a good working relationship with the funds.
It does of course increase the risk and I think very much puts the dampener on any likelihood of them being bid for.
No position currently.
Thanks Gromley, yes I see now. But I also see -£53.7m of accumulated losses in their balance sheet, and I am trying to undertand why this is not a huge red flag.
OptiBiotix Health (LON:OPTI)
I recall talking to them at the UK Investor show around five years ago. TW was very bullish on them then I believe. Unfortunately, despite the positive sounding updates, they’ve just gone sideways since and I had reached the conclusion over recent years that this is a lifestyle company for the management rather than an outfit that’s going to enter a rapid expansion.
Today it sounds like they have a good increase in sales revenue, but it’s from such a low base that the percentage increase is not very useful. In absolute terms, the peanuts are bigger but it’s still peanuts. Seems like they’ve still not got a great deal of traction in the market.
For goodness sake, OPTI is still transitioning from an R&D in late 2018 and didn't accelerate this until 2019. Of course, the was the small matter of Covid-19 in 2020, WHICH must have put off some partners developing products. Even so, there were 2 significant product launches in 2020, Alfasigma and Optipharm, which will not show royalties until H1 2021.
That said, I am still disappointed sales have not grown as fast as I hoped for, more so with the home online store sale. These will be near zero had it not been for OPTI investors.
Angle (LON:AGL) released an RCS to say that researchers using their Parsortix system have harvested circulating tumour cells that uncover a novel bio marker for breast cancer.
It reads as very promising for new treatment options to be developed in the future and as Angle say bodes well for the forthcoming launch of their pharmaceutical services business.
Hi Paul,
Thanks for your efforts on Renold (LON:RNO) last night. It def. looks interesting. I suspect however though, that those dastardly MM's will spot this and gap it up at opening. It is surprising how their tentacles stretch to every place that shares seem to be discussed and manage to spot every opportunity to move the market price up in nanoseconds.
Rookie question... What's an MM?
Hi Inde - Everyone starts out as a rookie - re What is an MM?
Every question is a good one (Just need to understand the tools to use in every walk of life)
https://www.investopedia.com/t...
Indie,
I strongly recommend you buy Anna Coulling's book, Volume and Price Analysis.
Published in 2013. I read it again and again........
My morning smallcap tweet:
KKV Secured Loan Fund (LON:KKVL) Mycelx Technologies (LON:MYX) Trifast (LON:TRI) Arbuthnot Banking (LON:ARBB) OptiBiotix Health (LON:OPTI) ADVFN (LON:AFN), Essensys (LON:ESYS)
KKV Secured Loan Fund (KKVL) Buy-back of investment boost NAV by 4.91p, based off the last published NAV of 36.19p. [SP=15.21 Cap=103m]
MYCELX (MYX) sells US office for $2.78 net of debt, a $2.53m book gain. [SP=27.03 Cap=5m]
Trifast (TRI) guides FY rev slightly ahead of market expectations of c.£172m. Rev up 5% in recent 4 months. "Pre-Brexit stock piling, in our other distributor business, led to a strong December in the UK region. However, border issues have created logistical challenges since 1 January on the EU distributor side (c.5% of Group revenues)...The current container freight issues are increasing transport costs around the world. Furthermore, a global shortage of steel as manufacturing volumes recover, is causing raw material pricing and lead time pressures for both our internal and third party manufacturers. This is creating additional margin pressure which we are working hard to mitigate." [SP=135 Cap=184m]
Arbuthnot Banking (ARBB) guides FY(Dec) pre-tax loss better than market expectations. Q4 loan enquiries improved. "The return to pre-pandemic credit appetites enabled the business to develop new lending pipelines that we expect to draw in 2021." [SP=909.75 Cap=137m]
OptiBiotix Health (OPTI) guides FY(Dec) rev £1.5m up 103% and admin costs £1.6m down 28%. £7m gain on holding in SkinBioTherapeutics. Holding reduced to <25% and will now be treated as an investment. "Investor and consumer interest in health and wellbeing and the microbiome is a growing trend and, as a result, the Company's market opportunity is large and expanding." [SP=61 Cap=54m]
ADVFN (AFN) H1(Dec) rev up 28%, pretax £264k (-£402k). "While we expect growth at a similar pace in the coming half, our strategy is to be very conservative and we will expend our energies growing our platform's capacity rather than looking to broaden our audience." [SP=38 Cap=10m]
In line: Essensys (LON:ESYS)
Morning Paul, well done on Your Stock Slam pitch, I really enjoyed everyone’s presentations.
Money Super Market releases their results this morning if you have chance to take a look? A really credible performance all things considered and a covid recovery play as things start to open up and people require travel insurance. Cash in the bank and div unchanged which yields circa 4%.
Many thanks, Phil
It isn't really a small cap, however I would second the request for a brief look at £MONY - they do appear to have weathered the storm fairly well and the next set of results will have an easy comparator.
People still want to get a good deal on house insurance, car insurance etc even if in a pandemic so I'm hopeful for a bounce back once travel picks up later this year.