Small Cap Value Report (Thu 2 July 2020) - AIR, macro, APP

Good evening/morning, it's Paul here with the SCVR for Thursday.
Estimated timing - should be done by 1pm
Update at 11:26 - I've got to pop out for a while, so will add a couple more sections after lunch. Hence revised finish time is 3pm.
Update at 15:52 - I've conked out now, so today's report is now finished.
I'm preparing this first bit on Weds evening, because I have to take some time out on Thursday to get the XJS fixed, ready for its 3rd attempt at this year's MoT. Nothing serious, just a weak handbrake (not needed on automatic transmission cars anyway), and slightly excessive emissions, so she needs an engine tuneup.
Let's start with short comments on some open tabs on my browser that got left behind earlier this week;
Portmeirion (LON:PMP) (I'm long) - a small number of shares in this decorative pottery, candles, etc, group appeared in my Spreadex account yesterday. That must mean the placing went ahead. I somehow got involved in this placing, but was more interested in meeting management and hearing their story. It's a share I previously liked a lot, but it's gone distinctly off the boil in recent years. This is all ringing a bell, have just remembered I wrote it all up here on 10 June. The more I think about it, the more I like its new strategy, to focus on eCommerce sales. This must be one of many companies that is now kicking itself for paying out generous divis in the past, and now needed to raise fresh equity at a low price. Overall, I'm not excited about the upside here, but think risk:reward could be OK, with patience (several years, is my intended holding period).
Comptoir (LON:COM) - a very small E.Mediterranean themed casual dining chain. Only £5m market cap at 4.2p. Although as with so many hospitality companies, you have to ask yourself, is it worth anything now? Its update this week (30 June) couldn't be more blunt in its message to landlords: start re-opening some restaurants from 4 July .... not completed its review as to which restaurants it may decide never to re-open.... support it receives from landlords to influence how many restaurants the company operates going forwards". It's probably easiest to do a pre-pack administration. There might be some value in the shares, if it is able to jettison all the problem leases via a pre-pack. As an investor, I'm mainly interested in buying shares in completely clean hospitality or retailing groups. A good recent example was Quiz (LON:QUIZ) (I'm long), which has done a pre-pack on its physical stores, thus getting rid of all the lease problems at a stroke.
Driver (LON:DRV) - I wrote about this small cap consultancy business here on Tuesday.
Many thanks to sharw who flagged up this link to the results presentation from Driver.
I can only embed video links here if they are in YouTube or Vimeo format.
See you in the morning :-)
Primark
Owned by Associated British Foods (LON:ABF) updates the market today. On re-opening of Primark stores, it says;
Trading in our reopened stores has in aggregate been reassuring and encouraging....
As indicated in our update of 1 June, most of our regional stores are performing well, especially in retail parks.
Our stores in the centre of big cities are suffering from the current absence of tourism and much lower commuter footfall.
Sales have been held back to some extent by a number of operating restrictions which vary by country but continue to evolve.
Primark gives full year profit guidance as follows;
Nearly all Primark stores are now trading again and we estimate that, absent a significant number of further store closures, adjusted operating profit for Primark, excluding exceptional charges, will be in the range £300-350m for the full year compared to £913m reported for the last financial year.
That's a savage drop in profitability, but it should bounce back next year, some or all of the way back to previous levels of profitability. The read-across for other garment retailers, is that if the best in the sector is seeing profits down by two thirds this year, then the weaker sector players are likely to report thumping great losses. I wouldn't touch any of the retailers that were struggling before covid-19 started, e.g. Ted Baker (LON:TED) and Superdry (LON:SDRY) spring to mind. The shutdown is likely to have caused further, serious damage to their profitability.
Primark doesn't sell online, which is a decision it might regret. Other retailers could at least keep business ticking over with online sales during the lockdown.
Recent sales performance strikes me as good;
Since the reopening of the first stores on 4 May, cumulative sales for the seven-week period to 20 June were £322m and were 12% lower than last year on a like-for-like1 basis.
Sales in the week ended 20 June, with over 90% of our selling space reopened, were £133m and trading in England and Ireland were ahead of the same week last year.
We have continued our policy of offering the best prices, and markdowns for the period since reopening have been minimal.
My opinion - Primark's announcement today seems reassuring to me, and should have good read-across for other retailers, and other shares which are part of the "re-opening trade".
Note that the most recent week's trading is above the equivalent week last year. That's fantastic news. Given that city centre stores are sluggish, then the rest of the estate must be doing a roaring trade, to bring the overall total to a positive LFL result.
When bars & restaurants open this Saturday on 4 July, combined with reassuring news on declining new covid cases, I'm coming round to the view that the re-opening trade is back on!
I wonder if the public will figure out that, with so many stores closing from the devastating impact of the lockdown, if we don't get out there and spend money in High Streets, and shopping centres, then they could disappear forever, and with it goes shopping as a leisure activity. Use it or lose it, springs to mind.
Other news
Reports from Germany are positive for retail spending on easing of lockdown, which beat forecasts apparently. That could have read-across for other consumer-driven economies like the UK.
American markets have also been strong, possibly propelled by encouraging news from Pfizer about a successful vaccine trial . This comes with all the usual caveats, that it's early stage, hasn't been peer reviewed yet, etc.. But as Jim Cramer pointed out on CNBC, Pfizer is not some promotional, rampy small cap. It's a highly credible major company, and just would not put out this news unless it were true.
For now anyway, all the above (encouraging re-opening figures, and hopes for a vaccine/treatment) seem to be outweighing the rising clusters of cases in the USA. It is starting to feel as if mankind may be beginning to control this thing. That's certainly what US markets are pricing-in. US markets seem to be looking beyond covid, whereas in the UK, small cap investors still seem mired in gloom. They can't both be right.
Is the V-shaped recovery back on? Recent comments from the respected Andy Haldane, from the Bank of England, made surprisingly bullish comments this week about a V-shaped recovery. He's got all the numbers to hand, so knows what he's talking about.
Broker research notes are starting to re-appear, with new forecasts that take into account the impact of covid. These are nearly always behind the curve. Going into a crisis, the forecasts are months behind reality, so we have to slash, or completely ignore broker forecasts going into and during a crisis. On the way out of a crisis, brokers tend to be overly pessimistic about how earnings are likely to recover. Therefore we need to anticipate this, and adjust forecasts accordingly. Recent research I've seen forecasts a sluggish recovery in earnings in 2021. If the economic recovery is good, then there could be an opportunity here, to buy stuff which is likely to beat 2021 forecasts. As always, we have to delve into the detail, and not take any forecasts at face value. They have to be assessed for either excessive optimism, or it now seems some are showing excessive pessimism. But it depends on the sector.
Overall, I think this could be a good time to be buying overlooked UK small caps - selectively, as always, as a lot of them are rubbish.
.
Air Partner (LON:AIR)
Share price: 89.5p (up 6.4% today, at 08:35)
No. shares: 63.6m
Market cap: £56.9m
Sorry for the slight delay, I nodded off.
Air Partner, the global aviation services group, is today providing an update on trading to 30 June 2020. This is the fifth update released during the COVID-19 pandemic and we anticipate communicating our next update to shareholders at the Group's Annual General Meeting (AGM) on 15 July 2020.
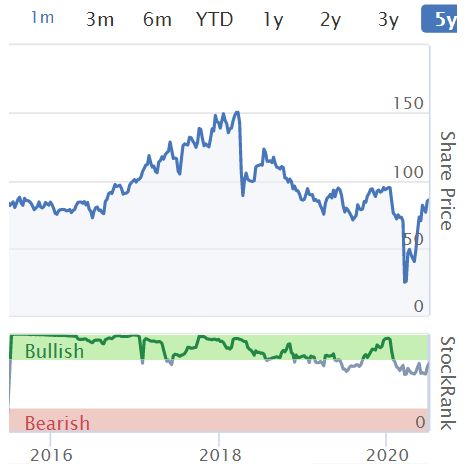
This is an interesting aviation services company, which charters planes, and acts as a broker for freight and private jets. Conventional wisdom might be that anything to do with aviation has had a terrible year, but this little company is a stand-out exception. So well done to shareholders who stuck with it, or bought at the bottom, look at this for a spectacular rebound;
.

.
As you can see above, the panic sellers in late March actually as it turns out, handed a wonderful gift on a plate, to people who had the balls to buy at that time of extreme crisis.
Today's update - another good one, but with a cautious outlook for H2;
Current trading overview
The business continued to perform significantly ahead of budget in June and the unaudited management accounts show an expected underlying profit before tax of at least £10.0m for the first five months of the year to 30 June 2020.
As has been the case throughout the COVID-19 crisis, this performance has been driven by strong activity in our Freight and Group Charter divisions. Early indications for July are showing an adjustment in our business mix to pre COVID-19 levels, with a recovery in both Private Jets and Safety & Security.... However, visibility for the second half of the year remains limited
Liquidity - looks fine to me;
June 2020 placing - raised £7.5m (before fees), which significantly reduced debt, and provided good working capital. Normalised cash of £16.0m at end June (doesn't include client cash). Access to £14.5m bank facilities, only £3.0m drawn down at end June. Seems very good overall, I have no solvency worries here.
Helpfully, there is a brief (6m30s) video update today from our AIR, via our friends at PIWorld;
.
My opinion - the update today doesn't give me much in the way of specifics, other than the underlying profit of £10.0m in the first 5 months of this sound, sounds really impressive. But the narrative indicates there are some one-offs in there (e.g. repatriation flights) without quantifying how much of the profit is one-off in nature. Could it be that AIR has benefited from the covid crisis, and business could return to normal? I don't know.
Checking back to last year's interim results to 31 July 2019, it made an underlying profit of £3.0m in H1, which compares with £10.0m this year (in just 5 months)! Therefore there's been a huge benefit this year from covid-related issues. I'd therefore be cautious and not value the business on a high multiple of a bumper year's profits.
I've just had a chat with Lord Lee, who has announced a 4.72% disclosable stake in the company today. He likes it a lot, and has obviously been buying recently. He points out that demand for private jets should remain strong, as those that can afford it would rather charter their own jet, than hang around in airports with masks on, and end up getting sick. Plus, sporting fixtures are now resuming, and private jets are widely used by sports teams, to avoid hotels & airports before flights, which could potentially make the whole team ill. Lots of things to like about AIR, it looks good to me.
.
.
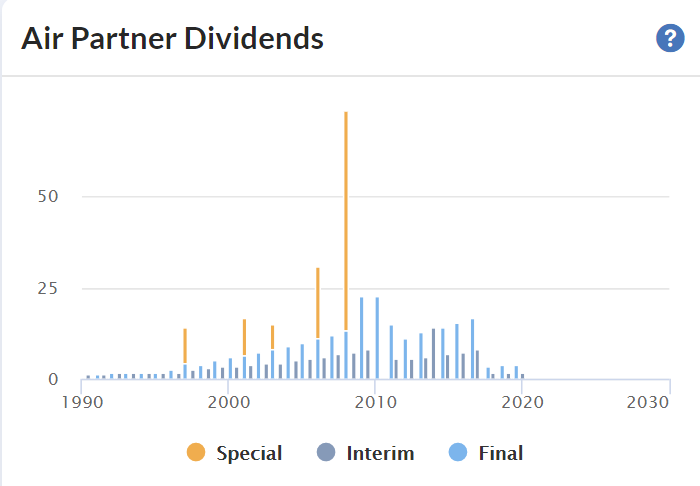
Looking at the 5-year chart above, it's basically traded sideways overall. Although dividends have been generous over that time period, totalling a remarkable 64.2p since 2015. Although that was dominated by 47.7p paid in 2015 & 2016, with the payouts from 2017 onwards have been much lower, as you can see from the Stockopedia divis chart below (which has been future-proofed with space up to 2030!);
EDIT: Many thanks to Geoff, who comments as follows about AIR's dividends;
Paul - thanks for the write up on AIR and indeed all your recent writings - both company specific and MACRO.
Just on the high dividends in 2015 & 2016 & apologies for being a pedant - looking at my records (having held since 2013 - it's been very bumpy on 2 occasions now !), these were before a 5 for 1 split in Feb'17 and therefore need a similar adjustment when comparing with today's shareprice ?
That sounds a very valid point, and explains why the divis were so huge prior to 2017. Many thanks for pointing out this useful information, much appreciated. End of edit.
.
Overall, AIR gets a thumbs up from me.
US Jobs data
US futures are up strongly again, on better-than-expected jobs data.
Nearly 5m new jobs were created in June, with the unemployment rate falling from roughly 13% to 11%. This is a big deal, and shows recovery is happening faster than expected.
More mounting evidence that major economies are over the worst. Stock markets look forwards, hence why some share prices are anticipating recovery. Maybe the market has been right to look beyond covid? It's starting to look as if that might indeed be the case, although I can't help feeling the market has overshot on the upside on recovery hopes, but what do I know?!
I like this comment from one commentator on CNBC on the US economy;
A return to normalcy is is on the horizon
The pockets of irrational exuberance continue to be fuelled by retail buying, e.g. Tesla is now valued at more than Toyota!
It's anybody's guess how long it is before the inevitable correction occurs. This reminds me so much of late 1999, early 2000, just before the TMT boom turned to bust.
I'm not saying the entire market, or the quality mega caps, should necessarily fall in price, we can justify high valuations on quality companies like Apple, Microsoft, etc. But Tesla being valued at $226bn (at $1219 per share) is just utter madness. I think we could be getting close to a big correction on the bubble stocks like this. Once shares detach from reality, and can no longer be valued rationally, then there's nothing to stop them going even higher, in a self-fuelling bubble. All it needs is a good story.
Castlepoint Shopping Centre
This is a large outdoors shopping centre (retail park) on the outskirts of Bournemouth. It happened to be on my way back from the Jaguar garage, so I stopped off at about 12:30 today, to check it out. Primark (as noted above) said the retail parks are trading well. This is backed up (admittedly only a sample size of one!) with my impression of Castlepoint. The car park was close to full, although about a quarter of it was fenced off for building work.
I bought some sale items in Next, which only had a few rails of reduced price clothes. Most of it was full price. The (large) shop looked immaculate, and there was a steady stream of customers, keeping apart well. A few wore masks, but not many. Some staff had perspex visors, and there was prominent sanitising gel on the door.
Then I went to M&S, and it's a similar story there. Subjectively, both stores looked as if footfall was close to normal for a Thursday lunchtime. I'd say older people were more likely to be wearing masks, and a few younger people were too.
The very large ASDA looked busy.
My trip today was not scientific in any way, but it reinforced to me what Primark is saying, that shoppers are indeed coming back, and are keen to spend. So for me, the re-opening trade is definitely back on now. I think when cafes, bars & restaurants are able to re-open too, then this could give town centres a nice boost too. Tourism is just starting to resume too.
Hospitality sector expert Mark Brumby of Langton Capital (sign up here free for Langton's brilliant daily email), has just emailed to point out that data from Germany is looking good for bars re-opening - this is what Mitchells & Butlers (LON:MAB) reported today;
- The experience in Germany. Signage, 1.5m distancing and the requirement to wear masks was common across the Federal states. The businesses were not allowed to operate buffets. Sales are now c70% of pre-Covid.
- This varies between city centre (40% to 45%) and suburban (some at 100%). A repeat of this in the UK would ‘delight’ the company and exceed expectations.
Therefore, I think this could be a good point for risk-tolerant investors to buy some shares in pubcos. If the re-opening goes well in the UK too, then I think these shares could rally nicely from next week.
.
Appreciate (LON:APP)
Share price: 30p (up 9% today, at 14:52)
No. shares: 186.3m
Market cap: £55.9m
Appreciate Group plc (the 'Group'), the UK's leading multi-retailer redemption product provider to corporate and consumer markets, today provides an update on current trading and financing and notice of its final results.
Appreciate (used to be called Park Group) has a 31 March year end.
Sales are on an improving trend, but still well down on last year;
YTD: 48% down on LY, split out monthly as follows;
- April: 70% below last year
- May: 47% down on LY
- June: 35% down on LY
There's no change in the position of the Christmas Savings part of the business, which is 10% below LY.
Outlook - sounds reasonably positive;
... we anticipate improved trading in the coming months and as lockdown is further eased.
Liquidity - this is self-explanatory, and reads well;
Update on bank financing
As stated in the 30 April trading update, the Board has reviewed several financial scenarios of the potential impact of COVID-19 on the business and, in each of those scenarios, the Group retains positive free cash this financial year.
Total billings are currently marginally ahead of our mid-range scenario and as at the end of June free cash stood at £18.8m.
If the company currently has £18.8m free cash, then retaining positive free cash this year doesn't sound much of a challenge. Although I would have to look into the seasonality of the business - e.g. a Xmas savings club would build up cash during the year, and then see it spent by customers just before Xmas, presumably. Does free cash include customer cash, I wonder?
My opinion - I'm not getting enough of a positive feel from the trading update, to want to delve any deeper. With only limited time, and so many companies to look at, I have to prioritise things that really grab me in terms of potential upside.
Lord Lee also likes this company, we discussed it today, and thinks its move to digital products is promising. It could be an interesting turnaround under its new CEO.
It certainly looks cheap on a low PER basis, and high divi yield, if it is able to recover to pre-covid earnings maybe next year?
.
All done for today, see you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Paul if you don't already have an expert for the XJS, I'm not that far away in Andover and can thoroughly recommend a Jaag specialist.
Thanks phillirp! There's a place near to me called Hollygrove, who seem accomplished Jag specialists, so the car's with them at the moment, but thanks for the kind thought!
Had the joy of a visit to Trafford Centre today (including queuing up to get in Claire's with my daughter; what a time to be alive). General observations, probably as busy as any other Thursday pre-covid. Next, Zara, Apple Store and Greggs all busy with queues to get in. Busiest store and longest queue (by some distance) was Primark. It is a new store at Trafford Centre but a fair walk from Main centre so was surprised at how busy it actually was. Most electrical retailers apart from Apple were not busy. Most people unable to follow one way signs. Generally very encouraged and backs up Paul's observations at Castlepoint. Superdry and Ted Baker were also doing ok and comparable to pre covid activity. Wouldn't put anyone off ABF (Primark) based on this morning's update and what I saw at Trafford Centre.
Interesting, thanks for that 2ShedSam.
I'm wondering whether I should buy back into my Hammerson (LON:HMSO) (where my downside scenario might be too gloomy?) and Newriver Reit (LON:NRR) ? Both could be good trades, if as we both seem to think, that customers are indeed coming back to retail.
Must admit, I found the social distancing stuff absolutely fine today, at Castlepoint. It didn't stress me, and there were no significant queues anywhere. But, it's a newish, and very spacious retail park. All the units are a decent size, so not a problem to socially distance.
The problems might occur in town centres though, with smaller shops. I'll be venturing out into B'mth town centre this weekend, partly to get p@ssed again in a pub (!), and also to see what footfall & general interest from the public is like, now hospitality is opening up. Also I want to dine at Wildwood in Bou'mth, where I've got friendly with all the lovely ladies who work there - all E.European, and absolutely charming & welcoming I've really missed them actually!
Best wishes, Paul.
Somewhat tangential perhaps with regards Newriver Reit (LON:NRR) but I noticed an article in the Kent Messenger a few days ago, concerning the Whitefriars centre in Canterbury.
The gist of the article is that NewRiver are expecting a number of retail failures and believe that the answer might be to convert their voids into food outlets. In light of the grim news from the casual dining sector it makes no sense to me and would give me pause for thought if considering investing in NewRiver.
That said, I guess it comes down to whether there is an exploitable valuation anomaly. It reminds me that I was chatting in over the fence to a neighbour a couple of weeks ago and the topic moved on to working from home through Zoom and Teams etc, and the fact that it might become the new normal. This prompted him to say that he should check with his pension manager that he is not too exposed to office real estate. I didn't take it any further becauase (a) I know very little about commercial property and (b) because I don't really think he's an active investor; but my initial thought was that it was probably a little late to be thinking about that and maybe there was even a contrian play.
Apparently the Gov't is going to lift quarantine restrictions to EU + Turkey. Announcement tomorrow:
https://www.theguardian.com/world/2020/jul/02/uk-to-lift-ban-on-non-essential-travel-to-up-to-90-countries
Good news for... Dart (LON:DTG) and the point to point airlines?
Boohoo (LON:BOO)
Some discussion on Modern Slavery issues in Leicester factories. BOO is referenced
https://labourbehindthelabel.org/report-boohoo-covid-19-the-people-behind-the-profit/
Afternoon. Paul. Re NEXT (Consumer observation sample size of 1)
My wife had an appointed internet sale access time the other night to see NEXT's seasonal bargains - I Assume that the better on line buyers got the earliest slots
After a whole evening of "frustration" she couldn't get access and had given up. (Perhaps social Internet distancing was being followed!)
Following day having not bought anything NEXT offered her a £10 credit to her account as an apology. Good Business? Signs of CV-19 WFH By the IT department?
Onthemarket (LON:OTMP) good update today. Extra £1.8 mio in revenue signed up since the new contract offer was introduced.
Re : Air Partner (LON:AIR) :
Paul - thanks for the write up on AIR and indeed all your recent writings - both company specific and MACRO.
Just on the high dividends in 2015 & 2016 & apologies for being a pedant - looking at my records (having held since 2013 - it's been very bumpy on 2 occasions now !), these were before a 5 for 1 split in Feb'17 and therefore need a similar adjustment when comparing with today's shareprice ?
All the best
Geoff
Thanks Geoff, that's very useful, I will amend the article to point this out.
I thought it looked rather odd that those massive divis were being paid.
Thanks for AIR update. I must say I was a little concerned when I got into this in March, but it was more one of those dont look a gift horse in the mouth situations than plain balls. Air was founded in 1961. So you could question what the hell have they been doing all his time? They started out retraining ex Air Force pilots to fly as commercial pilots. So it was really interesting to hear more about the Redline purchase which takes them back to their training roots in a way although more to do with security now. I think that purchase, just before Christmas rocked investors a bit, saying it was bad timing etc. So good to hear more of their reasons and potential behind that. It does look like the baby got slung out with the bath water, having felt the need to explain they are not an airline more an air taxi service. Whilst they don't deny some benefits from Covid to their business as many others have, the talk about the 'new normal' is what gives me the confidence to stay invested here, and the fact that they are still away off their all-time high.
I'm also sticking with my holding. I won't get too carried away with these one-offs in Charter, but who is to say this environment won't throw up many more Charter opportunities? In terms of private aviation recovery - surely it will be a huge theme once quarantine restrictions end. The rich will be avoiding airports like mad and the rich always want to travel, rarely are they hermits.
Air Partner (LON:AIR)
I agree with the sentiment that private aviation is where the medium-term potential lies for Air Partner (LON:AIR)
The company themselves indicated that Private Jet enquiries rose >200% coming into June.
I have assumed +150% Private Jet activity vs normal levels for the next 1.5 years, so Gross Transaction Value rising from £70m in FY20 to £100m in FY22.
Underlying Operating Profit for Private Jets was £2.8m in FY20, so the rise I am expecting in this division alone probably justifies the current EV of £36m, with the rest of the business just adding to what still looks like a very cheap valuation.
One note of caution, however, was the lower cash generation in June.
By my estimates it was only +£1m vs £3m generated in June and £8.4m generated across February and March.
Perhaps there are timing issues and differences in when the company recognises its "normalised" cash balance. I imagine this will all become clearer when the interim results are published.
Happy holder for now
Nothing serious, just a weak handbrake (not needed on automatic transmission cars anyway),
Paul, the handbrake is to stop the car in the event of the main foot brakes failing.
Paul, the handbrake is to stop the car in the event of the main foot brakes failing.
Surely this is wrong? The handbrake is for doing donuts in supermarket car parks!
All the best, Si
Ha ha of course!
Jeffvshep - you had me worried for a while. How could I not know that my Jag which I have had for 4 years had a handbreak that I was not aware of! I did a search on Auto Express and this is what they say.
The manual handbrake is becoming an endangered species on the new-car market, with 70 per cent of current models coming only with an electronic parking brake with no manual option, new research has revealed.
And some manufacturers - namely Jaguar, Land Rover, Lexus, Mercedes and Porsche - have ditched the mechanical handbrake across their entire model lineup, meaning it’s electronic or nothing if you want a car from these brands.
Yep, I came across electronic handbrakes 3 and a bit years ago when I worked in a garage assisting with MOTs. As far as we were concerned it is an over reliance on electronics.
Anyway, the point I was making to Paul is that as the handbrake exists to stop the car if the main brakes fail it is still necessary for automatics to have them.
Jeffvshep, I can only imagine what would happen if an auto gearbox was rammed into Park in an emergency or other. I've owned a 59 reg Passat from new and am entirely comfortable withe the electronic handbrake button The brake is much more effective than any mechanical one, and needs a little more throttle applied to release it and pull away insofar that when I (rarely) get behind the wheel of a conventional hand-braked car I motor off with the hand brake still on.....
My Merc and BMW (both less than 4 years old) - you can't ram it into Park. You select park electronically, just like Drive, Neutral and Reverse
Hi Jeffvshep, yes, fair point!
Hi
For those looking at economic trends/indicators for UK for Covid period, this link has interesting stats from footfalls, to capex, to job adverts, to shipping and much more. Good graphs as well.
https://www.ons.gov.uk/peoplepopulationandcommunity/healthandsocialcare/conditionsanddiseases/bulletins/coronavirustheukeconomyandsocietyfasterindicators/2july2020
Regards
Howard
As we approach the re-opening of bars at the weekend I thought it might be timely to reproduce the following comments from a healthcare professionsal in the US where bars were re-opened some time ago.
Dr Amesh Adalja, an infectious disease doctor and a senior scholar at Johns Hopkins Centre for Health Security, said bars are “coming up in multiple case investigations”.
“Because of the very nature of being at a bar is a social function, it’s much less likely that you’re going to see social distancing be observed there and people, as they drink alcohol, they may talk louder, they may yell, cheer, sing and scream.
“It does pose a higher risk for transmission. And most bars are indoors as well.”
After stay-at-home orders were lifted, he said many people wrongly took it as a “green light that things were safe”.
Notwithstanding the economic pain, I think that the wisdom of re-opening of bars in the UK is, at best, questionable and I hope the above underlines the risk for those participating. Unfortunately, I think this provides a negative investment perspective for bars as I think it is likely that indoor bars and perhaps restaurants will need to be re-closed at some stage in the future as, like in the US, ever more young people become infected and end up in hospital.
I think people will look at the risk factors based on age + health conditions and probably assume that if they're not overweight and under 40 that their chances of getting seriously ill are very slim. They're more likely to get an STD than a severe case of Covid
Hi peterthegreat,
Fair points, but I think some investors in bars (including myself) are looking beyond the immediate covid risk. There seems to be good progress being made on treatment/vaccines, and buying shares in hospitality companies is basically just a bet on things returning to normal before they run out of cash.
A general shutdown of bars nationally, seems to me fairly unlikely. Targeted local shutdowns in areas with a spike in cases, seems to be the way things are going in many countries.
As time goes on, more people have immunity or resistance to covid.
I think it's increasingly looking as if people are making up their own minds based on their own circumstances.
Thing to remember about Londonmetric Property (LON:LMP) is that it functions more like an old fashioned property company than a REIT. Some development, some asset management; always buying and selling. A few years ago they were heavily in shopping centres, but made the decision to transition to logistics - that was when I bought in.
Paul, re the XJS, are you familiar with the concept of the Italian tune-up? It is popular with older cars before MOT checks. In essence, get onto the dual carriageway out of Bournemouth and override the auto to get into a much lower gear than speed requires, forcing the engine to rev harder for a sustained period. It's popular because it works.
Good Luck with the MOT.
Jon (used to run an old Mercedes SL as my daily driver)
But only do it when the engine (oil not water) has warmed up - after 15 minutes . Owner of an XJ 4.0 of similar vintage to your girl.
Is this true ?????
Morning Paul
Any chance of comment please on Forterra (LON:FORT) - yet another overnight placing - small discount which I can see has now been lost as share price now below the placing price.
Hipgnosis Songs Fund (LON:SONG) announce today yet another placing (this time at what looks to be a significant discount for some reason - or maybe I'm reading it wrong).
Additional money to be raised by a retail offer (no offer price mentioned for this at present) via the Primary Bid platform. As I understand it, this means it's not possible to apply using funds with an existing ISA (please tell me if I've got this wrong).
If I have understood all this correctly then, as an existing holder who would have quite liked to take advantage at this price, I'm not too happy.
Hipgnosis Songs Fund (LON:SONG) has previously disclosed an intention to raise capital to fund the purchase of more song catalogues. From what I can gather from the RNS, the shares to be issued are new "C" shares.
In the last annual report and accounts (page 18), this appears:
Share Capital
The Company has two classes of share capital: (i) Ordinary
Shares; and (ii) C Shares. The issued Ordinary Shares
currently represents 100% of the total issued share capital,
as no C Shares have been issued. C Shares constitute a
temporary and separate class of shares which can be
issued at a fixed price determined by the Company. These
are subsequently converted into Ordinary Shares, at NAV,
once the proceeds of each C Share issue have been
invested or substantially invested in accordance with the
Company’s investment policies.
This explains why they are raising the capital and that the placing is not of ordinary shares but of new C shares. Quite what that means for existing shareholders, I have no idea! I hold so would be interested if anyone could enlighten?
Ah yes, thanks Westway001. They have issued C shares in the past and converted to ordinaries based on the NAV.
If you want to see how this worked last time you can at:-
https://www.lse.co.uk/rns/SONG/navs-c-share-conversion-and-total-voting-rights-cjr9xugf99ppkr5.html
I don't feel so bad now. But it would be helpful if Primary Bid could work out some way for ISA and pension accounts to be included in offerings.
I don't feel so bad now. But it would be helpful if Primary Bid could work out some way for ISA and pension accounts to be included in offerings.
Yes, I agree it's a big restriction not being able to use cash available in tax wrappers. It's a real pain having to use a Debit card.
I managed to take part in the Hipgnosis Songs Fund (LON:SONG) placing and got a bigger chunk than I did for the Air Partner (LON:AIR) placing given that my current account balance is higher currently. I got my order in before I received notification of the placing from Primary Bid having read the 7am RNS.
BTW I've had to switch to the old site to correct a spelling mistake. Why on earth does the new site not let you edit a post? Yet another black mark against the new site.
All the best, Si
There is an interesting comparison to Paul's detailed discussion on Hammerson (LON:HMSO) yesterday.
Londonmetric Property Londonmetric Property (LON:LMP) which is all about the none exciting world of grey crinkly tin sheds (aka out of town warehouses) announced there rental collection this morning, see link below, that 95% has been collected or is collected monthly.
https://www.stockopedia.com/share-prices/londonmetric-property-LON:LMP/news/london-metric-rent-collection-update-urn:newsml:reuters.com:20200702:nRSB7830Ra
Air Partner (LON:AIR)
Interesting that Lord Lee has appreared as a 4.7% holder.
(Wonder if it's in one of his ISA's.)
Also an encouraging statement from the company today (Tamzin's video is well worth a watch) - seems to be developing nicely - next news 15/7 pre AGM.
(I hold)
Hi just an fyi Lord Lee, he has been an owner for quite a while, (spoke about it during the video interview with Tamzin PI world last year) good to see he has been increasing his holding.
Can we have the link please
Air Partner (LON:AIR)
https://www.investegate.co.uk/air-partner-plc/rns/tr-1--notification-of-major-holdings/202007020700047796R/
Looks like it dropped to 18 odd p during March, there were some serious bargains out there in hindsight.
The comment from Primark that retail parks are outperforming city center shops is interesting. I assume that is because people are comfortable driving to these sites, being able to park near the shops they want to go into and not having to walk through a high street or take public transport. I hold Newriver Reit (LON:NRR) and think this is helpful for the bull case. But perhaps I am too optimistic!
The comment from Primark that retail parks are outperforming city center shops is interesting. I assume that is because people are comfortable driving to these sites, being able to park near the shops they want to go into and not having to walk through a high street or take public transport.
What Associated British Foods (LON:ABF) say is:
Our stores in the centre of big cities are suffering from the current absence of tourism and much lower commuter footfall.
So less tourism and more people working from home, both trends that correlate with everything else that we're seeing.
As we're on a slow small cap news day the other interesting report today was from Londonmetric Property (LON:LMP) who expect to collect 99% of rent due this quarter. The contrast between them - essentially serving ecommerce logistics - and more traditional REITS serving the retail space is striking. Almost no one is trying to renegotiate with them because that's where the revenue is.
They're increasing their dividend payout too.
timarr
Hi Timarr - Interesting about Associated British Foods (LON:ABF) - Primark. I was in Colchester Town Centre just the other day- all very quiet - with one exception - a long queue for Primark.
Primark also say this, which is why I made my comment. "As indicated in our update of 1 June, most of our regional stores are performing well, especially in retail parks."
hi Tristan - I'd recommend the recent presentation by management as I think you're looking at Newriver Reit (LON:NRR) the wrong way and it was particularly enlightening for me at least.
Newriver Reit (LON:NRR) own smaller local centres because they think this is more future proof. Their demographic is someone that walks to the shopping centre twice a week and knows exactly which shops they want to visit. So if you believe that out of town driving is the way to go then Newriver Reit (LON:NRR) possibly isn't that company. The bull case for Newriver Reit (LON:NRR) for me is threefold
1) Much of their space is leased to anchor tenants that are in the "essential" space such as supermarkets. Revenue collected even through this period has therefore been slightly better than I had expected.
2) The Alternate use valuation is strong, around a NAV of 180p I think from memory. That underpins the valuation for me as it means if retail disappeared tomorrow they could turn everything into residential and including the costs of demolishing and rebuild would still have an asset value more than twice the current share price.
3) The pub portfolio is strong and was doing very well prior to covid. 70% have gardens and so pretty much all their pubs are re-opening next week and rent should then be collected.
Bit of a rushed post so sorry if not everything is clear but I do recommend the management presentation for significantly more clarity on both the bull and bear points.
Good Morning Paul,
Would be great if you could take a look at Gamma Communications (LON:GAMA) announcement on the purchase of the German company and how that may affect their growth in the coming years.
Looks very exciting to me and seems to be an excellently run business. Decided to pick up a long position this morning.
Gamma Communications (LON:GAMA) would normally be outside the SCVR's market cap limit for small caps. However, the acquisition looks like a good fit and the German expansion into a market where cloud telephony only has 6% penetration makes sense. There's risk with all acquisitions but they're buying current profits of €3.2m for between €20m and €38m which looks OK. Assuming they can use this to drive growth then it would be better than OK.
Mostly the drivers for growth in telecoms don't vary much between countries, but there's always a risk in entering somewhere new. But in relative terms it's a bolt on acquisition not something "transformational" and, therefore, looks low risk. Only slight worry is that they're trying to do this in Spain as well, so there's a risk that management attention drifts.
Gamma Communications (LON:GAMA) is an excellent company although, as with so many these days it looks expensive on old style valuation metrics. But what with QE and low interest rates it's probably fair value - and better than that if it can continue to drive earnings growth at 20%+.
timarr
Gamma Communications (LON:GAMA) would normally be outside the SCVR's market cap limit for small caps.
Given we've had a post entirely about commodities today, it seems you can post about pretty much anything, so ruling an equity out on market cap grounds seems a little churlish! BTW what is your opinion on the outlook for Lean Hogs?
All the best, Si
Given we've had a post entirely about commodities today, it seems you can post about pretty much anything, so ruling an equity out on market cap grounds seems a little churlish! BTW what is your opinion on the outlook for Lean Hogs?
Hi Si
I think commodities are in scope if small cap, just as long as you don't ask Paul or Graham to comment on them.
Personally I wouldn't go long on Lean Hogs as we're likely to see oversupply as slaughterhouses reopen.
:-)
timarr
"BTW what is your opinion on the outlook for Lean Hogs?"
Lean Hogs currently trade at around $0.45 per pound, and the price has been in a downtrend for the past eighteen months.
Technically the price is looking oversold, being 27.3% below its 200 day moving average, an extreme gap since 2006.
From a fundamental viewpoint, pricing will be driven by a number of factors, including:
Technically the price is looking oversold, being 27.3% below its 200 day moving average, an extreme gap since 2006.
Great! I'm going long Bacon sarnies.
Inflation & Commodities Year to 30/6
Oil -30%
Urannium +28%
Gold 25%
Silver 18%
Platinum -1.35%
Soy 1.9%
Wheat -1.2%
Cheese/Milk +40%
Rice +80%
Wool -35%
Sugar Coffee Palm oil -1-5%
Corn -16%
Beef 35%
Lean Hogs -39%
Copper 2.6%
Nickel 6%
Zinc -16%
Iron Ore -16%
Coal -25%
Whilst there are some interesting lines above.... hard to say much in conclusion. Inflation is the focus but we had a strong bull market in commodities between 2000 - 2012 without inflation. This trend coincided with outsourcing to China and other emerging low cost geographies plus a strong move on line. Although corporate profit margins rose, wages failed to keep pace. At the moment its difficult to argue we have a shortage of capacity since we have record unemployment. We also have record stimulus. So the reason to watch these things are twofold, as we saw with Covid the world can change pretty quickly and secondly, there may be interesting investment implications.
Copper and Silver/Gold are industrial strength measures and suggest little at the moment. In all commodities the return from lockdown throws the world into a temporary shortage akin to a cold snap effect on power. We simply don't have infrastructure to cope with the surging demand as everyone restarts. So its not a surprise demand and price can surge reflecting bottle necks...however just as a cold snap passes, these surges will also pass.
Net net this is just another difficult position companies find themselves in. They probably make less money unless fortunate enough to be a producer of the product with a rising price.
Its impossible to say whether the stimulus thus far...or measures that follow will be enough. Its impossible to know if its good or bad inflation. Stagflation or other. Markets won't wait for the corporate results though which is why i'm keeping an eye on bonds and commodities....
Perhaps the dollar is the ultimate barometer. If it remains around current levels ...this is most bullish, with the status quo continuing, pushing tech and growth stocks higher. If it strengthens, this is deflationary, Id assume copper falls, silver falls and other measures of growth tail off. Equities will fall. If it weakens its interesting. This is pretty bullish... should bond yields also move higher though it has implications for value/growth in favour of the former. Its hard to say whether indices move higher...certainly would be good for the UK over US. Probably be good but with the majority of portfolios positioned wrongly.
What I hope my macro ramble highlights is that right now we are at a cross road - we can of course muddle on as we have been, but the virus is a massive deflationary impulse being met with an equally large and potentially inflationary stimulus. Its another fascinating time.
My take is prepare for deflation because that could hurt. Almost certainly the catalyst for more policy. Let the dollar tell you where we are. I cant see inflation with a strong Dollar.
Some of these commodities are at or near 10 year lows such as Corn ,Lean Hogs and ones you do not mention such as Cotton and Soybeans.Obviously oil was in March and had a huge spike up.
The same was true of Lean Hogs but it has fallen back to its year low.
I am long Corn , Gold, and hold the Uranium share Yellowcake.
Air Partner (LON:AIR) Mark Briffa, CEO gives his comments in this video on trading in the first five months, which is signficantly ahead of this time last year, c£10m v £2.4m. He also comments on the placing, Redline and the outlook.
Separately, join us for the piworld Thursday webinar today 2nd July, at 1pm, with David Thornton, who writes the Growth Company Investor (GCI) magazine, (and was previously a fund manager). GCI is excellent, and not as well known as it should be. He will talk about Small is Beautiful. Why Small Caps? And What to Buy Now? Giving us some of his current favourite picks. Register via this link.
Morning Paul. Is ABF too big to mention? As it’s retail and on course to open all stores could it have a more interesting read across in retail?
My morning smallcap tweet:
Air Partner (LON:AIR) Total Produce (LON:TOT) Verditek (LON:VDTK) Appreciate (LON:APP) Omega Diagnostics (LON:ODX)
Air Partner (AIR) continues perform significantly ahead of budget in June, guides U/L pretax at least £10m in first 5 months.
Total Produce (TOT) says H1 'satisfactory' with rev broadly in line YoY. Guides 'satisfactory' FY.
Verditek (VDTK) new orders over the past two weeks in new geographical areas and new vertical markets.
Appreciate (APP) billings down 35% in June, recovering from a low of -70%.
Omega (ODX) antibody test has been approved for testing of COVID-19 in India.