Small Cap Value Report (Thu 2 Mar 2023) - VTU, HSS, PURP, BIDS, TLY, SAGA, ALFA

Good morning from Paul & Graham!
It's going to be an early report today as I have to go into the city for a company meeting, then an investor lunch - exciting! I'll let you know tomorrow if the company meeting was of any interest.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Vertu Motors (LON:VTU)
61.2p (pre market)
Market cap £214m
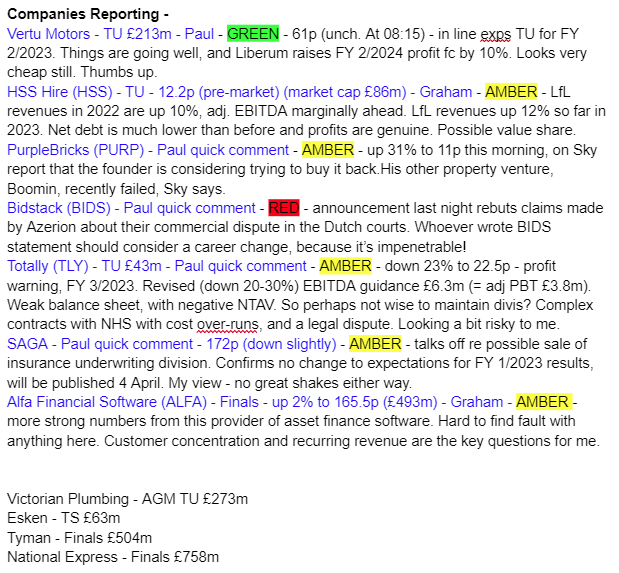
Vertu Motors, a leading UK automotive retailer with a network of 191 sales and aftersales outlets is pleased to announce the following update with regards to the five-month period to 31 January 2023 (the "Period") ahead of its preliminary results for the year ended 28 February 2023 to be announced on 10 May 2023. The Group continues to trade in line with management expectations.
Trading Update: Group trading in line, Helston integration on track, cash generation better than expected
That’s all straightforward, and not likely to move the share price, because it’s in line. Although forecasts for next year have been raised by 10%, so that should move the price up.
I won’t repeat all the other comments in today’s update, other than these 3 points below, which are interesting for general read-across -

The big question is whether new car supply easing is a good thing or not? As we’ve seen in the last couple of years, constrained supply has been very positive for car dealers, as it’s boosted their margins and overall profits considerably.
Further on in the announcement, the CEO sounds more cautious, talking of “tentative signs of improving new car supply”.
There must be pent-up demand for new cars, after several years of constricted supply, so maybe another profit boom is coming?
The service & repair division, which is nicely profitable, is described as trading strongly.
The recent big acquisition of Helston Motors is also progressing well.
Electric vehicle have plunged in price (as a stroke of luck, I sold my Taycan late last year, for more than I paid for it. Now it would be worth £20k less). I think the energy crisis has highlighted how vulnerable EV drivers are to spikes in electricity cost. Far more so than petrol/diesel drivers, where the % rise in price was much less pronounced, and has largely reversed now -
Within this overall benign picture, however, there has been recent much publicised weakness in the price of used electric vehicles in the UK, which saw average values decline by 17.0% on average over the Period.
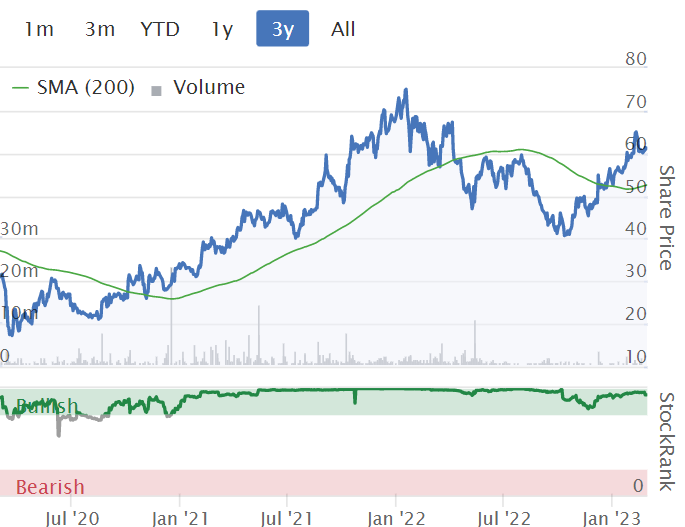
Valuation - despite a c.50% rise in share price from last autumn’s lows, the valuation metrics at VTU still look highly attractive. It remains a sector stand-out in being priced below its own NTAV, which doesn’t make sense to me - either the assets are over-valued, or the shares are too cheap -

Outlook - this is the key paragraph, and I read this as being quite positive -
As expected, trading conditions are normalising after a period of exceptional financial performance across the sector. New car supply is improving and should mean year-on-year volume growth of new and used car sales for the market in 2023. Used car supply remains tight given the lack of new car sales in recent years and this is likely to underpin pricing in the year ahead. Clearly consumer confidence is volatile and higher interest rates and high vehicle prices may influence demand patterns. The Group will remain agile and dynamic in adapting to this environment.
The important point with this share, is that broker forecasts already factor in a reduction in profitability from last year’s bonanza. Therefore, even if VTU only performs in line, the shares will remain cheap, as the forecasts are set low. That also means a good probability of out-perform trading updates as calendar 2023 unfolds, which I like.
My opinion - there’s loads more detail in the full announcement, which I didn’t see any point in repeating here. The key message is that trading is in line with expectations, and the outlook comments sound pretty solid.
Have a look at Liberum’s helpful update note today. It’s positive, and raises forecast profit by 10% for FY 2/2024.
I remain positive on this share - it’s still cheap. So a thumbs up from me.
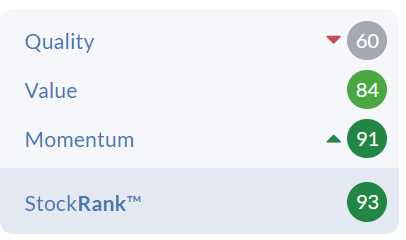
It's a thumbs up from the cold, completely unemotional analysis of Stockopedia's StockRank algorithms too, with a very high score -
Graham’s Section:
HSS Hire (LON:HSS)
Share price: 12.2p (pre-market)
Market cap: £86m
It’s a full-year trading update from this equipment hire company, for the financial year ended 1/1/2023 (I will refer to this financial year as 2022).
Like-for-like revenues +10%.
Adjusted EBITDA to be “marginally ahead” of expectations.
Leverage multiple less than 1x thanks to cash generation.
Operationally, four “large” customers have switched over to HSS’ self-service platform, HSS Pro:
This enables our customers to manage all their hire requirements in one place, therefore significantly improving efficiency for both customers and HSS. With positive results and strong customer feedback to date, we have a healthy pipeline of customers to roll this platform out to over the coming year.
Latest trading: like-for-like revenues up 12% in the first eight weeks of 2023, so that’s a slight acceleration on the average growth seen in 2022.
CEO comment:
"We are extremely pleased with the progress made in 2022, both in terms of financial performance and the implementation of our technology roadmap. Our strong focus on execution continues to underpin our momentum with a very positive start to the new financial year. While we remain mindful of the macroeconomic environment, HSS is well positioned for the year ahead."
Estimates - Stockopedia data suggest £332m of revenues and £16m of net profits for 2022, with further improvement expected in 2023.
In H1 2022, the company earned revenues of £160m and adjusted PBT of £8.4m.
My view
I haven’t got a strong view on HSS. Of course, everyone can see that it’s cheap:

And everyone knows that its balance sheet is much safer than it was before, thanks to equity fundraisings and business disposals.

At the end of H1 2022, net debt had fallen to £49m. Given the capital-intensive nature of the business, I think it’s understandable that companies in this sector will want to use some debt to juice returns for shareholders.
Also in reference to the H1 2022 numbers, balance sheet net assets at that time were £20 million.
If we are treating this as a possible “value” investment, I suppose we would ideally want to find more value on the balance sheet? Though I accept that things are much improved from the days when HSS had negative tangible assets.
Overall, I can see the bullish arguments for this one. Particularly if you are bullish on the economy and on the construction/maintenance sectors, you may feel that it is overdue a rebound:

Alfa Financial Software Holdings (LON:ALFA)
Share price: 165.5p (+2%)
Market cap: £493m
This is a B2B software company, serving the asset finance industry. They say that their “class-leading, cloud-native technology platform is at the heart of the world’s largest and most progressive asset finance companies”.
Much like HSS, this was an overpriced IPO that has been trading at more reasonable valuations in recent years:

Key points from these full-year results for FY December 2022:
Revenue +12% to £93m (+8% constant currency)
Operating profit +20% to £30m
Cash generated from operations £34m
Latest cash balance £19m, no debt.
The financial summary is brimming with positivity: nearly everything is moving in the right direction.
As promised (and as we discussed last year), Alfa has now returned £100m to shareholders since November 2020. Very impressive!
Additionally, the final (1.2p) and special (1.5p) dividends announced today are worth £8m.
Strategic highlights
75% of revenues are said to be “recurring”, but I’m not sure if I fully embrace the definition of recurring that is given: “subscription revenues or services and software revenues with existing customers”.
Surely revenue from an existing customer should not automatically be classified as recurring?
The subscription revenues are, in my view, truly recurring in nature. These account for 29% of total revenues at Alfa.
Customer concentration: top five customers are now 35% of revenues (they were 37% the previous year and 48% the year before that).
Employees: average headcount increased 10% to 420 with a retention rate of 90%.
A new version of their software was released in Q3 2022, with many improvements.
Outlook/CEO comment: there is “great confidence” in prospects for 2023 and beyond.
Pipeline - there is a “strong late-stage pipeline” and the company expects to convert most of these.
My view - as I said at the time of their interim results last year, I’ve warmed to this stock. The trend in customer concentration and concerns around how much of the revenues are really recurring would probably be my main two question marks over it. But it has evolved into a serious investment proposition, in my view.
Any company which returns material amounts of cash to shareholders, as Alfa has done, deserves to be taken seriously.
At its current valuation, my instincts are to keep reading about it and to keep it on the watchlist.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
I have received an email from my broker this afternoon, Hargreaves Lansdown, advising me that they will no longer provide research on Saga (LON:SAGA) which I hold.
I wonder if Paul or any subscriber has any views on the reason for the brokers decision.
I thought they were moving to Specialist Fund Segment of the Main Market (the “SFS”)?
Some brokers may not want to deal on that market, you should ask AJB.
Brokers don't deal with all listed companies and some are excluded from ISAs.
Metal Tiger (LON:MTR) has today announced intention to delist on AIM and move to ASX. This has led to a near 25% fall in the share price which exasperates an already large decrease in the share price over the last year. Could anybody please advise if the shares if held within ISA's with the likes of A J Bell, Interactive Investor are still eligible to be held, if not, maybe this is the reason for the drop with potential forced selling consequence?
As long as they are traded on a recognised stock exchange they should be eligible
Watkin Jones (LON:WJG) investor presentation today via IMC. I tried to watch/listen but my day job kept interrupting. It sounded positive overall and student accommodation development seems a strong growth area with little risk with their forward selling model. Paul I know that you've recently reinvested in this, as have I, so I look forward to any thoughts you may have on this. I'll view again and update when the presentation is accessible via the Investor Meet Company website.
Hi Bristolian,
I've been out & about, so missed the Watkin Jones (LON:WJG) (I hold) webinar, but see that it's already up in recorded video here: https://www.investormeetcompan...
I'll post here if anything of interest comes out from it.
Regards, Paul.
Thanks Paul, appreciated. Hope you're having a good day.
There is a nice little company called Plant Healthcare who just announced this morning their fungicidal treatment for plants has US Commercial approval. For transparency I have opened a position here and will build it over the next year. It holds few of the characteristics which would lead Paul to even comment on it, which I would agree with from his perspective. However it holds some characteristics that I like. It is related to the environment (increasingly important), it competes with a product which for geopolitical reasons is under pressure (fertilisers), it has a number of products (allowing some disappointment), the management team have been together for a few years, the company has been trying to develop the space since early 2000s (allowing it to learn and make contacts), it is using large established distribution companies to sell its produce and it covers a variety of different countries (recently adding India). Overall in my opinion a diversified BUT high risk opportunity. I like them for a small part of my portfolio. But as oft pointed out if it does hold any interest for you DYOR!!!!
hi Camtab
Plant Health Care (LON:PHC)
It would be useful if you put the company link in your comments.
This stock was given the bargepole treatment by Paul in 2015 at 98p and a big thumbs down from Graham in 2017 at 28p, since when the SP has continued its inexorable slide to 11p today.
Revenue has been stagnant for past 10 years, they have never made a profit and the share count has increased from 71m to 306m in 10 years.
Looks like a classic jam tomorrow share to me.
A big thumbs down.
Snazzy
Thanks Snazzytime
I was having difficult getting the ticker link up on a post I wrote yesterday - I insert £ before the name but it failed to work, but then remembered there being a new method introduced?
hi Jayman
You now use the @ symbol instead of £ and then select the stock in the pop up box.
Snazzy
Thanks for the helpful steer Snazzy
Sorry Snazzy Plant Health Care (LON:PHC) Paul was absolutely right in 2015 and Graham was absolutely right in 2017 as in the end the share price is the only true judgement. I am hoping I will be absolutely right in 2023. You are correct it definately is a jam tomorrow share but you know sometimes they become a jam today share. Another point I would add is I like shares like Beeks Financial Cloud (LON:BKS) and Cerillion (LON:CER) great companies but will they be good investments? They trade on sky high multiples and the world has just changed, could be argued they are also jam tomorrow shares. But i do understand what you mean. All the best.
I too have recently opened a position in Plant Health Care (LON:PHC) as having watched the presentations and done some research I do believe they address some of the future challenges of food production: increased drought or rainfall and the consequent increased suceptibility of plants to disease. If their products can address these problems and increase yields by 5-10% it's a win win for them and the farmers.
The have fully outsourced production, a very high margin product and extensive distribution arrangements so the operational gearing they'll enjoy is phenomenal. Do watch the most recent IMC presentation in which they answered my two questions.
As ever with these companies the timing is everything and I've been too soon in a number of cases recently but with these guys it does seem that it's upwards to their stated target of $30m of sales by 2025.
Plant Healthcare is indeed a little company , but I do not think it is a nice one.
Thanks yiannos1. Looks like my holding is going to be a disappointment. 1 for 2 against.
I see that Begbies Traynor (LON:BEG) did a tiny acquisition this morning. Add £1m of revenues only. To their existing £100m+ revenues.
I'm a bit mixed on what this says about Begbies. Part of the reason I bought in was because of their successful "acquire and build" strategy. They have done several acquisitions, successfully.
However, this one is so tiny, it might not even have warranted an RNS. It also doesn't add "new" capabilities or geographies. It is just a classic buy and roll-up, squeezing central costs, and maybe some cross-sell / up-sell synergies.
Have they run out of targets to acquire? Why have management wasted time on adding £1m of revenues, when they should be chasing £10m-£30m revenue acquisitions instead, that will meaningfully enhance the EPS?
(I hold in the Boon Fund)
Thank you for untangling the long Vertu TU Paul, we hold and the recent 3.1% stake held by the gorilla TDR Capital trading through Constellation, is in there for nothing.
Capita (LON:CPI) FY REPORTED PROFIT BEFORE TAX OF £61M today, shares are up 10%.
Beeks Financial Cloud (LON:BKS)
Hi Paul,
I have just watched their presentation and the business still perplexes me. What returns can they get on their hardware infrastructure? Not enough as far as I can see so far. Do you know if they have explained what returns mature clients provide across their platforms or what their spare capacity is to enable economies of scale to kick in. At present it seems that their ROCE is just too low and we've no idea what the potential is.
Nex, not a small cap but some in this group hold went up by 12% after a predicted good result. All travel related shares have done reasonably well recently.
It is also interesting that the Stocko rating on NEX is pretty poor at 17.
This shows how unreliable the ranking is in the turn around companies.
"Stocko rating on NEX is pretty poor at 17"
It is 37 on National Express (LON:NEX).
National Express (LON:NEX) showing 34 at 09:08, not 17 or 37. Is it jumping around today? And I agree with Lucky dip, the algorithms sometimes seem to be misleading when a business is in a period of rapid change.
Still 37 on my screen. Should not move during the day, from what I understood. Of course Stocko is based on the previous results, when these are updated then the scores will change. Value and momentum will change based on share price.
National Express (LON:NEX) is an interesting company
Alfa Financial Software Holdings (LON:ALFA) is a steady eddie but lots of positives in there and the market likes it - kind of!
Share buybacks, special divis, quiet Bulletin Board, reducing customer concentration, all metrics positive - what's not to like! Graham gave it a +ve review in DEc22 and they seem to have taken on his thoughts
Any chance of a review of the results by Hunting (LON:HTG) (I hold), think Graham has looked at this one before.
Initial thoughts are they look pretty good, return to profitability, order book up 124% with high visibility into 2025. Diversification into non oil and gas going well. Sub-sea revenues showing strong growth.
Happy to continue to hold.
Totally (LON:TLY) warning. Allenby cuts forecast eps from 3.0p to 1.95p (2022 was 1.92p). Not sure how much of this already in the market slide of sp from around 35p in mid January.
Have a nice day Paul, bring back gold!
Beeks Financial Cloud (LON:BKS) Hi Paul - appreciate you reviewed earlier in the week but any further thoughts after yesterdays IMC ?
I think I was reassured -
Bottom line focus as well as top line
If I got it right 3-5 rev target of £100m 4/5 exchanges times £20m rev
Risk = major dependency on getting mega exchange customers over the line
I thought it was interesting that until now BKS cloud has only been utilised within the Forex and Derivatives market, but not the large equities market. But the new Exchange Clous" will now give access to the equities market.
Not a small cap but reading the Vesuvius (LON:VSVS) announcement today, I'm unsure what " We will also be impacted in the first half by a negative fixed cost absorption related to the reduction of our inventory level" means. I wondered if anyone here could enlighten a non accountant
Hi, According to Chat GPT:
Inventory reduction impacts finances.
Based on the information provided, it appears that the UK company is experiencing a negative impact in the first half of the year due to a reduction in their inventory levels. Specifically, they mentioned a "negative fixed cost absorption," which suggests that the company's fixed costs (e.g. rent, utilities, etc.) are not being fully absorbed or covered by their reduced inventory levels.
In other words, the company's overhead costs are spread out over a smaller amount of inventory, resulting in a higher fixed cost per unit of inventory. This can lead to lower profit margins, as the company is not able to spread their fixed costs over as many units of inventory as before.
Overall, it seems that the company is facing some financial challenges related to their inventory management, which is negatively impacting their bottom line.
weird infact bizarre - surely the benchmark should be with regard to sales not inventory
i have business a sales 1 mill reduction in inventory from 200k to 100k this year
business b sales 1 mill inventory 200k this year as last year
clearly buisness a is the better run business if it has lower stocks or have managed to lower stocks - yet this linked nonsense seems to be saying a is struggling - back under the duvet for me.
What is missing in the space above this? Im intrigued!
When I posted, there was a huge white space underneath. I thought about trying to sort it out but had 15 mins left to sort myself and 2 children to be ready for school (they attend, I teach ) and get out of the house. Note to self, maybe leave reading and posting about RNS to weekends.
My morning smallcap tweet: Buy and forget or cash roulette
Hunting (LON:HTG) Poolbeg Pharma (LON:POLB) Verici Dx (LON:VRCI) Esken (LON:ESKN) Aukett Swanke (LON:AUK) Totally (LON:TLY) HSS Hire (LON:HSS) £LETS
◄Hunting (HTG)► launches 2030 Strategy. Targets 15% EBITDA margin. It will "leverage existing expertise". Fantastic! [SP=334 Cap=553m]
◄Poolbeg Pharma (POLB)► positive results from human trial of for POLB 001 treatment for severe influenza. Tested on 36 people. [SP=8.42 Cap=42m]
◄Verici Dx (VRCI)► gets Compliance Certification for commercial clinical operations to 45 US states. [SP=8 Cap=14m]
◄Esken (ESKN)► strategic review result: to sell its operating businesses. Sale of Renewables is currently in progress. Exploring sale of Aviation business, primarily London Southend Airport, Continues to seek buyers for its non-core assets (book value of £36m). Problems in wood biomass mkt means FY-Feb EBITDA guidance cut to c. £19m for this biz. Should normalise this FY. Cash headroom in line. [SP=6 Cap=62m]. I hold.
◄Aukett Swanke (AUK)► to buy Torpedo Factory, an audio, visual and stage technology provider, for £2.8m in paper. TFG shareholders will own 40% of the enlarged group. That's quite a step from architectural and interior design services. [SP=2.4 Cap=4m]
◄Totally (TLY)► guides FY-Mar in line but EBITDA c. £6.3m, below market expectations. Blames inflation, strikes, "delays in the conclusion of tender processes and continuing legal discussions with one commissioner on certain contracts". Div will be in line. [SP=28 Cap=55m]. I hold.
◄HSS Hire (HSS)► guides FY-Dec LFL rev up 10%, adj EBITDA marginally ahead of market expectations. Recent 8 weeks LFL up 12%. [SP=12.2 Cap=86m]
◄Let's Explore (LETS)► name change from Immotion (IMMO) effective. [SP=NA Cap=NA]
Metro bank please Paul £MTRO
Metro Bank (LON:MTRO) (Use an @ no longer a £)
Cheers, the results of Metro to my eyes are amazing! Look at that absolutely huge drop in losses on a massively increased revenue! This is not explained simply as 'profit from BoE base rate lift' as the mortgage portfolio is 90% fixed on a 2.1yr life span. Christ management have turned this around. Q4 profit to!!!
I've yet to fully digest the results at Metro Bank (LON:MTRO) . But it looks like H2 was breakeven on underlying PBT.
Net Interest Margin (NIM) increased from 1.73% (HY) to 2.11% (H2) to 2.22% (exit at Dec22).
Potentially small increase in NIM in 2023.
Assuming FY23 can deliver extra +0.3% NIM over H2 (which was roughly breakeven), and all else stays equal, including lending book (£13.1bn).
I make that an increase in PBT of potentially £39m. Market cap c£250m currently.
They did say they are capital constrained and would love to lend more, and if they could find more, or attract more deposits... That loan book could keep going up. They do see potential for growth this year - opening two new branches too.
It's a very interesting play because they have all the characteristics of the mega banks (Lloyd's, Natwest, Barclays, HSBC) in that they are mostly funded by current accounts. Which is sticky, and also very low cost of funding.
And while all other banks have been shortsighted and removing bank branches, Metro have carved a niche out with their branch strategy. Now paying off in a high interest rate environment, as they're the only player for customers and SMEs that prefer having a (very nice) branch to walk into. It will be interesting to see if this allows them to attract away a certain customer set from the major banks to themselves.
(I hold in the Boon Fund)
Metro Bank (LON:MTRO)
Is it not easier to add branches when you make no money. I can see the long game here that it could work out - but you are basically giving them credit for opening branches that are presumably losing money or not making any !!
You might be onto a winner here though - their market cap is a fraction of say virgin - so on sales multiple its looks alot cheaper - perhaps on sales multiple we should expect it to be more expensive if it doesnt have the legacy issues of virgin. Tricky one though i much prefer my banks to be making decent money to offer some downside protection - although i am always aware that profits can evapoarte in a heartbeat. If sales do keep growing rapidly and they morph into decent profits i do see good upside here which did surprise me somewhat.
As a whole industry, I think its inevitable that retail banking goes to a model with almost no branches. There are many successful retail banks that are purely digital, and their current account customers are happy. I am one of them.
However, there is always a niche in an industry as big as retail banking. I treat branches as a "customer value add service" rather than a P&L channel nowadays. Comparing it to things like free insurance, cashback, etc that banks are offering as goodies. I treat it as a cost, but one that brings in subset of the market.
However, my main investment case in Metro Bank (LON:MTRO) is not the branch strategy, but as you mention, their big discount to peers on P/B, P/S, etc. This was because they were unprofitable, and the market did not believe in a path to profitability. That is now moot - it is profitable, so the valuation gap should close. Albeit maybe always still at a discount, since in its sub-scale, branch-heavy strategy it will never make the same margins as the bigger banks.
Finally, I do see credible M&A potential. Either one of the PE houses that were circling, or even one of the USA banks that have dipped their toes in the UK - Chase, Marcus, etc. Or even one of the neobanks, flush with cash. One could buy into an established branch network, existing deposit base, a brand with value, and then strip out all the central overlap costs to justify the acquisition price. USA banks are flush with cash, having also seen their fortunes massively improve over the past year too.
Vertu Motors (LON:VTU) great update today. Some headwinds, but think that's priced in.
I agree, but given their consistent trading performance I don’t think they should be trading below book value. And it looks like TDR Capital are having a look as well having taken a 3% stake.
A possible substantial headwind for motor dealers will be the move to fixed pricing which is already in place at Tesla and will now seemingly be progressivelly rolled out by, at least, Ford, Mercedes-Benz, Volvo, Land Rover, and Jaguar: https://fordauthority.com/2023...
My summary spreadsheet is now up-to-date (please don't share this link) -
https://docs.google.com/spread...